7 Statement of Cash Flows and Related Matters
21 May 2026 Agenda Paper 7
OFFICIAL - PUBLIC
Executive Summary
| IASB | Research / Workplan | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Scope: Moderate
Purpose of the paper
In November 2024, the Board discussed the Project Initiation Plan for this UKEB research project and suggested that, if time and resources allow, the UKEB would consider undertaking research on the statement of cash flows for financial institutions, targeted towards banks and insurers.
The IASB plans to start its work on financial institutions in H2 2026.
This paper sets out a proposed draft of the UKEB’s sixth research paper related to this project at Appendix A.
Summary of the Issue
Stakeholders support a substantive reform to the statement of cash flow to improve reporting for banks and insurers, rather than incremental updates that are perceived as adding little value. A key priority for preparers is fixing the definition of cash and cash equivalents, so that it better reflects how financial institutions manage liquidity. Preparers also request clearer guidance on classification.
There is strong support for simplifying the statement of cash flows, given its limited relevance and high cost, while retaining some useful insights through a streamlined version supported by targeted disclosures. Any changes should be carefully scoped to avoid duplication, extra burden, or unintended consequences.
More broadly, stakeholders favour greater use of regulatory and alternative disclosures, bridging financial and regulatory information. This could be linked to other IFRS Accounting Standards that may already provide relevant disclosure, rather than IAS 7 alone.
Decisions for the Board
1 The Board is asked for general comments and observations on the UKEB research findings on the statement of cash flows for banks and insurers (Appendix A).
2 The Board is asked if there are any key areas of focus, or opportunities and solutions, that they would like the Secretariat to explore further and bring back an updated paper to the Board in June 2026 for approval to publish on the UKEB website??
Recommendation
N/A
Appendices
Appendix A: UKEB research paper 6 – Statement of Cash Flows and Related Matters: Further research – Banks and Insurers
Background: Statement of Cash Flows and Related Matters
The IASB added a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation (published March 2021).
In the Feedback Statement to the Request for Information (published July 2022) most respondents recommended the addition of a project on cash flows to the IASB’s workplan, rating it as high priority.
The IASB staff have performed initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB’s decision on the scope of the project and will also address possible ways of improving the perceived deficiencies.
The IASB discussed the initial research outcomes in March 2025, and in May 2025 discussed the topics to include in the project plan and a draft timeline for work on the project. The IASB plans to publish an Exposure Draft in 2027.
A UKEB research project on the Statement of Cash Flows and Related Matters supports meeting the UKEB’s responsibilities regarding thought leadership in accordance with the UKEB Terms of Reference. It will also help the Board to deliver the UKEB’s 2026-27 Regulatory Strategy, to influence the IASB early in its development cycle, by providing timely and effective input1. To date the UKEB has published five research reports on various aspects of the cash flow project.
The UKEB research has focused on gathering primary evidence on the improvements UK investors and creditors suggest for the statement of cash flows, and UK preparer views on those possible improvements. This has provided a foundation for the UKEB to propose potential solutions for the problems already identified by the IASB, as well as any other issues identified through UKEB outreach.
[APPENDIX A] Statement of Cash Flows and Related Matters: Further research – Financial Institutions
May 2026
DRAFT FOR DISCUSSION
- Executive Summary
- Decisions for the Board
- Recommendation
- Appendices
- Background: Statement of Cash Flows and Related Matters
- [APPENDIX A] Statement of Cash Flows and Related Matters: Further research – Financial Institutions
- Introduction
- Usefulness of the Statement of Cash Flows of Banks and Insurance companies
- Usefulness of Disclosures required by other IFRS Accounting Standards – capital and liquidity
- Suggestions for improvements
- Concluding observations
- Annex 1: Example of Regulatory capital and liquidity requirement disclosures by banks
- Annex 2: Examples of Regulatory capital requirement disclosures and other cash flow measures by insurance companies
Introduction
1 Building on earlier work in its Statement of Cash Flows and Related Matters project, the UKEB has undertaken further research on the usefulness of the statement of cash flows for certain financial institutions. The objective is to assess whether alternative or additional reporting could better meet investor needs.
2 In May 2025, the IASB tentatively decided to explore how its project might address financial institutions, focusing on:
- improvements to the statement of cash flows generally before deciding how any changes might apply to the requirements for financial institutions;
- exemptions for financial institutions from some or all of the requirements for presenting a statement of cash flows; and
- any presentation or supplementary disclosure requirements specific to financial institutions that might enhance the usefulness of information about cash flows for such entities.
3 The IASB decided not to consider alternatives to the statement of cash flows for financial institutions, given its limited priority among investors and the existing project’s scope.
Research approach
4 Following discussion of the draft Project Initiation Plan in November 2024, UKEB Board agreed to explore improvements specific to financial institutions, particularly banks and insurance companies, where value is driven more by capital generation than cash generation.
5 This paper incorporates findings from outreach conducted in early 2026 with the UKEB Advisory Groups, including the Investor Advisory Group, the Accounting Firms and Institutes Advisory Group, and interviews with members of the Financial Instruments Working Group2. Interviews were also undertaken with preparers from banks and insurance companies. Discussions focused on:
- the usefulness of cash flow statements for banks and insurance companies and reasons for limited relevance for users; and
- potential approaches the IASB could consider.
6 These findings were triangulated through other research which comprised:
- Financial statement analysis: reviewing IFRS annual reports of UK banks and insurance companies to identify useful voluntary disclosures, such as reconciliations of regulatory capital and liquidity metrics to IFRS figures.
- Review of other disclosures: examining cash flow and liquidity-related information presented outside the financial statements, including regulatory reporting.
7 This research will inform the UKEB’s engagement with the IASB as it considers the statement of cash flow requirements for financial institutions in the second half of 2026.
8 The IASB is expected to publish an Exposure Draft of proposed changes to IAS 7, and potentially other IFRS Accounting Standards, in 2027.
Background
Diversity of financial institutions
9 Financial institutions encompass a wide range of business models, including banks, insurance companies, investment firms, asset managers and other entities. This diversity means that solutions applicable to non-financial entities may not produce useful information for financial institutions, particularly banks and insurance companies.
10 For banks3, the statement of cash flows often provides limited insight into performance. Core activities such as lending and deposit-taking do not consistently result in movements in cash and cash equivalents. For example, loan issuance or repayment may only affect cash when funds are transferred between banks, rather than when balances are credited internally.
11 Similarly, interest income and expense frequently do not result in immediate cash movements, as they are often settled through internal account balances rather than external cash transfers.
12 As a result, the cash flow statement does not reflect the economic substance of a bank’s main activities. Value creation is instead driven by net interest margin, which has only an indirect relationship with cash flows. Consequently, cash flows may be misleading as a performance indicator: negative cash flows may reflect lending growth rather than poor performance.
13 Insurance companies4 typically receive premiums upfront and pay claims later, often over long periods. The cash flow statement reflects only premiums received and claims paid in the current period, without capturing expected future claims from current contracts. Reporting premiums received in the current period without an estimate of the likely timing and amount of resulting claims that will be paid in the future, provides an incomplete picture of the effects of contracts issued in the period, so that the resulting information in the statement of cash flows has limited value.
14 Investment funds5 generally recognise income and expenses close to cash receipts and payments, meaning cash flow statements provide limited additional information over the other primary financial statements. For open-ended funds, cash flows relating to subscriptions and redemptions largely duplicate information in the statement of changes in equity.
Existing requirements under IAS 7 Statement of Cash Flows
15 IAS 7 does not differentiate between financial and non-financial entities. It requires all entities to present a statement of cash flows, on the basis that users need information on how cash is generated and used, regardless of business model. Accordingly, no exemption is currently available for financial institutions.
Usefulness of the Statement of Cash Flows of Banks and Insurance companies
What is the issue?
16 As noted in the UKEB first research paper Statement of Cash Flows and Related Matters: Background and key issues6, it has been suggested that the statement of cash flows for financial institutions (in particular banks and insurance companies) is not seen to provide useful information to users of the financial statements. As noted in paragraph 9 above, the differences in the business models of banks and that of insurance companies results in differences in investors’ information needs.
17 Both banks and insurance companies are subject to regulatory capital and liquidity requirements. Investors seek information to understand how these requirements restrict the cash that can be distributed to shareholders. However, the underlying drivers of capital and liquidity management for banks and insurance companies differ. Therefore, the information needs of investors to assess the effect of regulatory capital and liquidity requirements might differ for banks and insurance companies7.
UKEB Stakeholders preliminary views
18 The findings included in the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives8, support the feedback also received by the IASB on the limited usefulness of the statement of cash flows for banks and insurance companies:
- Most users and preparers believe that the statement of cash flows for banks and insurance companies provides little to no significant incremental value –
- banks and insurance companies typically managing portfolios of liquid assets beyond what is included within ‘cash and cash equivalents’ (see paragraphs 39–50).
- the statement of cash flows only represents a subset of such portfolios and therefore does not align with how the overall business is managed.
- Preparers also expressed that it was rare to receive questions from users on cash flows.
- One user noted that for insurance companies, they cannot easily assess whether a company can distribute cash, so regulatory surplus is used as a proxy.
- When explicitly asked about the usefulness of the risk management disclosures required by IFRS 7 Financial Instruments: Disclosures, there were mixed views on the extent to which the required disclosures were useful. One preparer and one user expressed that the information provided was typically not cohesive, making it difficult to understand the impact of the risks to the business as a whole.
- Preparers and users place greater focus and reliance on information provided using non-GAAP measures and within regulatory reporting. Information contained within regulatory reporting was noted to be more standardised and disclosures around liquidity and capital management were noted to be more extensive, resulting in enhanced comparability and relevance.
- Moreover, regulatory capital requirements are a key factor when considering whether there is capacity to pay out dividends.
- An asset manager noted that the information provided by the statement of cash flows is more useful for their users than for banks and insurance companies, opting to include a condensed and simplified statement of cash flows within the Chief Financial Officer’s review in the Strategic Report. This is consistent with the feedback received from a private investor who had the same valuation model for both asset managers and non-financial institutions but had different valuation models for banks and insurance companies.
Further UKEB stakeholder views
19 There was widespread agreement from accounting firm representatives that the statement of cash flows for banks and insurance companies in its current form is often not useful to users, due to the nature of their business models, and that valuable information appears in existing notes to the financial statements and regulatory filings or liquidity disclosures, reducing the incremental value of the cash flow statement.
20 Investors commented that certain items, where available in the statement of cash flows, are useful for all entities, including for banks and insurance companies, such as dividends paid, capital issuance/repayment, share option exercises, interest paid/received, debt movements, and acquisitions and disposals. However, investors reaffirmed the notion that most of this information is already available elsewhere in the financial statements (e.g., equity statement, notes, regulatory capital disclosures), although sometimes difficult to find and is not cohesive.
21 Investors considered that the statement of cash flows is still useful for banks and insurance companies as it:
- Is valued as a tool to bridge the P&L and balance sheet, providing a sense check of liquidity, and explaining differences between accounting and cash movements.
- Contains useful information, although often “hidden” among very large, less meaningful cash movements.
22 However, investors also supported the views that the statement of cash flows had limited usefulness, noting the following key challenges:
- the statement of cash flows does not reflect how financial institutions manage cash or liquidity risk in practice;
- ‘operating’ and ‘financing’ activities are indistinguishable because financial institutions’ operating assets are financial assets (potentially breaking the usual operating–investing–financing model of IAS 7);
- the statement of cash flows does not differentiate between cash belonging to shareholders and customer/policyholder cash; and
- investors focus more on regulatory capital generation and constraints, not gross cash movements. For banks and insurance companies, large cash movements often reflect regulatory capital requirements rather than free cash available for distribution.
23 Investors suggested that the above issues apply similarly to banks and insurance companies. They also noted that the statement of cash flows may be more informative for smaller, simpler banks, financial service companies (leasing, microlending) or fintech/payment firms, where flows may be simpler or more customer cash driven, than larger, diversified conglomerates.
Other UKEB stakeholder interviews
24 During further stakeholder interviews there was broad support from preparers and accounting firm representatives for the view that the statement of cash flows has limited usefulness for banks and insurance companies.
25 One accounting firm representative agreed that liquidity in these sectors is primarily managed through regulatory frameworks, stress testing and ratios, rather than IAS 7 cash metrics. They concurred with investors that IAS 7 classifications (operating, investing and financing, and the definition of cash equivalents) do not align well with financial institution business models, where liquidity instruments exist along a spectrum, making the concept of “cash equivalents” somewhat artificial and leading to inconsistent practices.
26 Several accounting firm representatives and preparers supported investor views (paragraph 20) that much of the information presented in the cash flow statement is already disclosed elsewhere in financial statements.
27 Preparers, particularly banks, described the statement as backward-looking, produced for compliance purposes and not used internally for decision-making or liquidity management. They emphasised that banking is inherently liquidity-driven, with constant balance sheet movement, and that more relevant and decision-useful information is already provided through regulatory disclosures in the UK. These disclosures include liquidity coverage ratios and other risk metrics.
28 However, there was some acknowledgement of limited usefulness. A credit manager noted that while ‘operating’ cash flow is not a reliable indicator of performance—given it largely reflects balance sheet movements and can be misleading (e.g. strong banks showing negative cash flow when expanding lending)–the statement can still help explain period movements and highlight unusual items. Importantly, the ‘financing’ section is seen as valuable for understanding capital and funding actions, such as dividends, buybacks, and issuance or redemption of debt. While this information could theoretically be disclosed in notes, doing so may reduce prominence and comparability across banks.
Usefulness of Disclosures required by other IFRS Accounting Standards – capital and liquidity
29 As highlighted in stakeholder feedback, users of financial statements for banks and insurance companies place greater reliance on regulatory capital and liquidity disclosures–which can constrain dividend payouts–rather than on the statement of cash flows. While IFRS standards (outside IAS 7) include some liquidity-related disclosures and are considered useful, there is a notable gap in clearly linking financial statements with regulatory capital and liquidity or solvency information. This leads users to rely on publicly available regulatory data to attempt to create their own reconciliations.
30 IFRS 7 Financial Instruments: Disclosures provides requirements for preparing information on liquidity, which might be considered sufficient for some users:
- Paragraph B11E of IFRS 7 requires disclosure of maturity analysis of financial assets held for managing liquidity risk.
- IFRS 7 (paragraph 39, 42E(e) and B11B), and IAS 1 Presentation of Financial Statements (paragraph 65) (replaced by IFRS 18 Presentation and Disclosure in Financial Statements effective 1 January 2027) also require information for maturity analysis of financial liabilities.
- Information on liquidity gap disclosures showing whether there is an excess of assets or liabilities in specific time buckets might also be useful.
- Regarding information on encumbered assets, disclosures on financial assets pledged as collateral, as required by paragraph 14–15 of IFRS 7.
31 For insurance companies, in addition to the information required in IFRS 7, IFRS 17 Insurance Contracts includes the following disclosure requirements:
- Paragraph 132(b) of IFRS 17 requires maturity analyses of insurance and reinsurance contracts9.
- Paragraph 126 of IFRS 17 requires an entity to “disclose information about the effect of the regulatory frameworks in which it operates; for example, minimum capital requirements or required interest-rate guarantees”. This should lead to companies disclosing any constraints such as dividend payout capacity, but to ensure comparability, it may be necessary for this disclosure requirement to be more prescriptive.
32 In addition, paragraphs 134–136 of IAS 110 require an entity to “disclose information that enables users of its financial statements to evaluate the entity’s objectives, policies and processes for managing capital”. Some entities go beyond those capital disclosures, providing disclosures involving forward-looking information, such as dividend payout capacity (although insurance companies are expected to disclose this information under IFRS 17 requirements, as noted above).
33 Potentially, most information for capital flows could be derived from the statement of changes in equity and other disclosures.
34 Similarly, information about the collection and uses of cash resources could be derived from the statement of financial position and related breakdowns of the line items in the notes, which serve the purposes of showing the sources of funding and their uses. Some companies voluntarily provide such disclosures – see example in Annex 1.
35 Such IFRS requirements should be considered before requiring new liquidity information for banks and insurance companies. The valuable information for users is disclosures that link regulatory capital and liquidity information to the financial statements.
Suggestions for improvements
36 As noted in the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives11, there are a variety of views on how the statement of cash flows can be made more useful for banks and insurance companies.
37 Suggestions received during the outreach interviews ranged from retaining the current requirements to exempting certain financial institutions. Other interviewees suggested possibly replacing the statement of cash flows with regulatory disclosures provided by UK institutions, creating a bridge between the primary financial statements and regulatory requirements.
38 Preparer concerns related to improving the definition of cash and cash equivalents and the classification of cash flows.
Improving the definition of cash and cash equivalents
39 As set out in paragraphs 6–7 of IAS 7:
Cash equivalents are short-term, highly liquid investments that are readily convertible to known amounts of cash and which are subject to an insignificant risk of changes in value.
Cash equivalents are held for the purpose of meeting short‑term cash commitments rather than for investment or other purposes. For an investment to qualify as a cash equivalent it must be readily convertible to a known amount of cash and be subject to an insignificant risk of changes in value.
Therefore, an investment normally qualifies as a cash equivalent only when it has a short maturity of, say, three months or less from the date of acquisition.
(emphasis added)
40 Paragraphs A70–A79 of the UKEB first research paper Statement of Cash Flows and Related Matters: Background and key issues and paragraphs C147–C151 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives highlighted that there can be different interpretations of the definitions of cash and cash equivalents in applying the standard. This may cause diversity in practice, impacting comparability of the statement of cash flows between entities.
41 The previous UKEB research noted that specific concerns with the definitions of ‘cash’ and ‘cash equivalents’ include questions about the meaning of ‘short-term maturity’ and the emphasis to be placed on the reference to ‘say three months’.
42 Paragraph C170 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives also noted that for banks and insurance companies typically managing portfolios of liquid assets beyond those included within cash and cash equivalents, the statement of cash flows only represents a subset of such portfolios and therefore does not align with how the overall business is managed.
43 As noted in paragraph 128 of the UKEB fourth research paper Statement of Cash Flows and Related Matters: UK users’ views on ways forward, users interviewed understand ‘cash and cash equivalents’ to be readily available funds for a company’s day-to-day operations and therefore provide an indication of its ability to pay short‑term debts. In this context, it is important that amounts that companies include in cash equivalents reflect their cash management strategy.
UKEB Outreach
44 UKEB stakeholder outreach with accounting firm representatives and preparers identified significant concerns with the IAS 7 definition of ‘cash and cash equivalents’, particularly for banks. One preparer described the definition as counterintuitive and misaligned with banking practice, creating unnecessary complexity.
45 A key issue is IAS 7’s reliance on ‘original maturity’ rather than ‘remaining maturity’. This results in economically identical High Quality Liquid Assets–for more information see paragraph 94–being classified differently based solely on when they were acquired, despite having the same near-term liquidity profile. This approach conflicts with regulatory liquidity management, which focuses on ‘remaining maturity’, and often forces banks to maintain parallel data sets, increasing operational burden without clear benefit. It is also believed to drive management behaviour.
46 Similarly, mandatory central bank deposits—while economically equivalent to cash—are often restricted and therefore fall outside IAS 7 definitions, leading to imperfect workarounds such as ‘restricted cash’ classifications.
47 These definitional issues were described as a major “policy bugbear,” with stakeholders calling for solutions to address them to be prioritised by the IASB. However, even if resolved, concerns remain that the statement of cash flows would continue to provide limited incremental value, impose unnecessary costs, and risk producing confusing or misleading outputs for banks.
48 Operational risks were also noted, including potential reporting delays resulting from challenges in cash flow statement preparation. More broadly, stakeholders emphasised that banks operate across a continuum of liquidity instruments—from overnight to longer-dated maturities—making the binary concept of ‘cash equivalents’ inherently artificial.
49 Some users suggested improvements, such as tightening and standardising the reconciliation of ‘cash and cash equivalents’, noting that the measure currently lacks consistency and may include items such as required central bank deposits, collateral, restricted balances and short-dated instruments.
50 The IASB has begun exploring ways to improve consistency, including clarifying that cash equivalents should be held for short-term liquidity12 needs rather than investment purposes, and reconsidering the perceived rigid three-month maturity threshold. While such changes may address some concerns, stakeholders indicated that additional, sector-specific guidance—aligned more closely with regulatory concepts such as Basel13—may ultimately be required for financial institutions.
Improving the consistent classification of cash flows (operating, investing, financing)
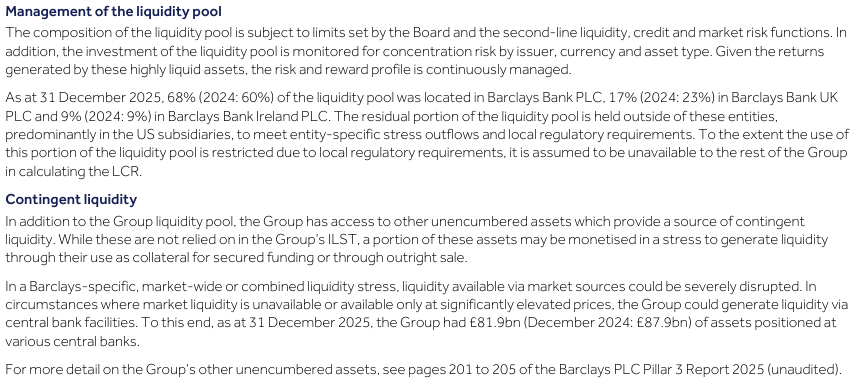
UKEB outreach
51 Another issue identified by stakeholders during UKEB interviews, is that the IAS 7 distinction between operating, investing and financing activities is of limited relevance for banks and insurance companies. One accounting firm representative noted that for financial institutions, these categories do not align well with business models, as activities typically classified as ‘investing’ or ‘financing’ are often core, revenue-generating operations.
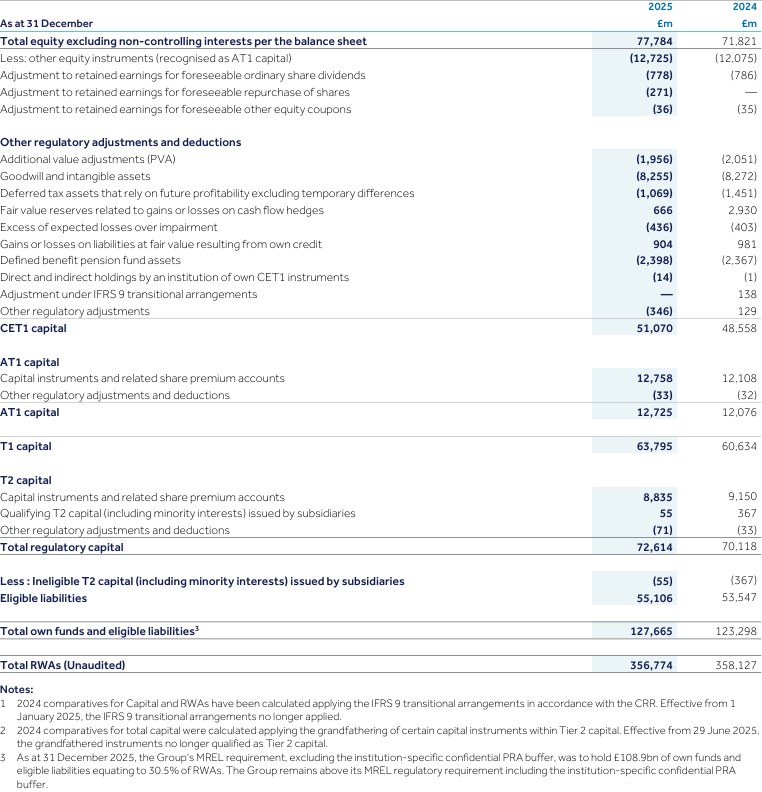
52 For example, raising funds through deposits, equity or debt issuance may be economically similar, while differences in loan maturities can significantly affect cash flow patterns between otherwise comparable banks. This makes classification outcomes inconsistent and reduces comparability.
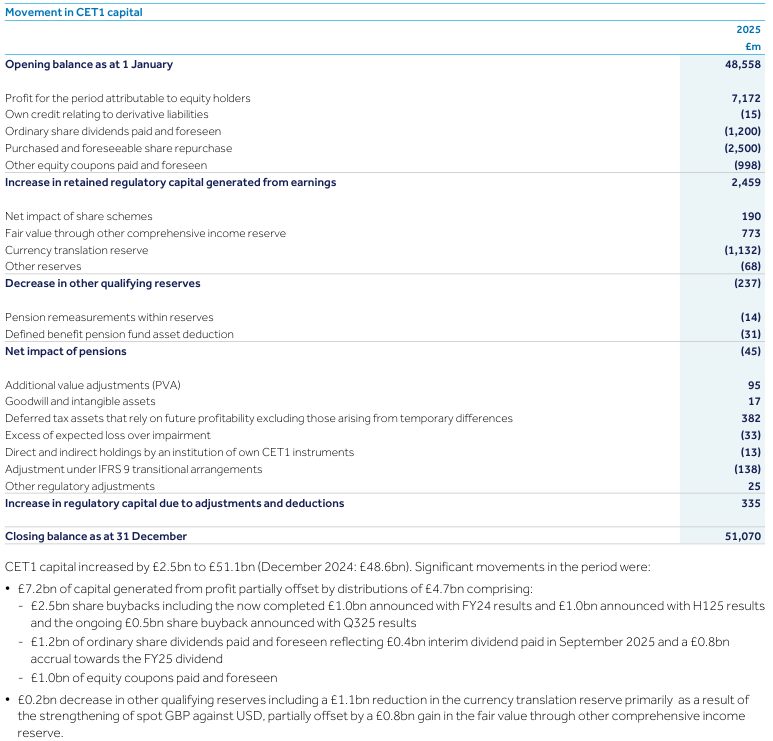
53 As noted in paragraph 45, challenges also arise in the treatment of High Quality Liquid Assets, which are variably classified as either ‘cash equivalents’ or ‘investing’ cash flows, reflecting the flexibility in IAS 7 but leading to divergence in practice.
54 A preparer from an insurance company raised similar concerns, noting that premiums received and subsequently invested to meet regulatory capital requirements are often classified as ‘investing’ rather than ‘operating’, despite being central to their business model. Stakeholders suggested redefining these categories for financial institutions, including a revised concept of ‘financing’ linked more directly to capital.
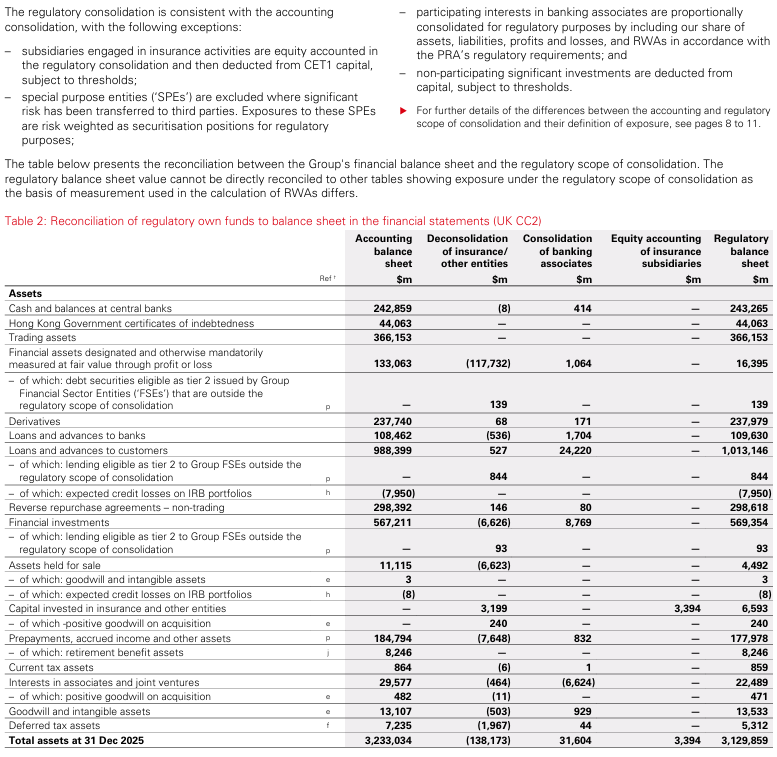
55 In the absence of clear guidance, diversity in practice persists. Although IFRS 18 introduces similar classification labels in the income statement, stakeholders do not expect it to resolve these issues, as the underlying mismatch with business activities of financial institutions remains.
Simplified Statement of Cash Flows
56 One way to solve the classification challenges that banks and insurance companies face might be to permit banks and insurance companies to provide a simplified statement of cash flows, without classification labels, but with sufficient disaggregated information (leaning into the disaggregation principles introduced in IFRS 1814).
57 Users noted that a simplified statement of cash flows might suffice, as long as relevant disaggregated information is provided in the notes to the accounts.
58 Accounting firm representatives suggested that rather than a full exemption, the IASB considers practical expedients, such as summarised cash flow disclosures, and approaches based on nature of transactions, rather than entity type. This might provide a proportionate approach given the low perceived usefulness to users of the statement of cash flow of financial institutions.
59 However, one insurance preparer interviewed, warned that removing the operating, investing, financing categories from the cash flow statement might reduce preparation effort, but would damage comparability, which they considered critical, especially among UK insurance companies, and more valuable than cost savings for preparers.
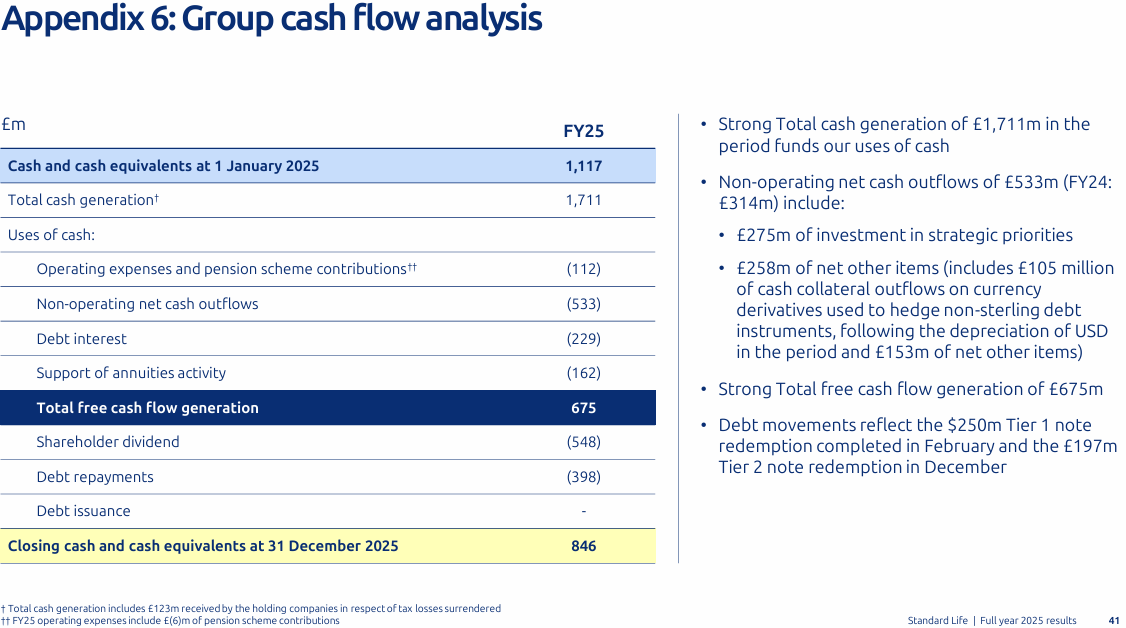
60 Another challenge is how the IASB might identify the entities for which it might be sufficient to provide a simplified statement of cash flows, instead of a full statement, or those that may be exempted from providing a statement of cash flows. The challenges with, and potential solutions to, scoping an exemption are considered later in this paper.
Investor demand for disaggregation
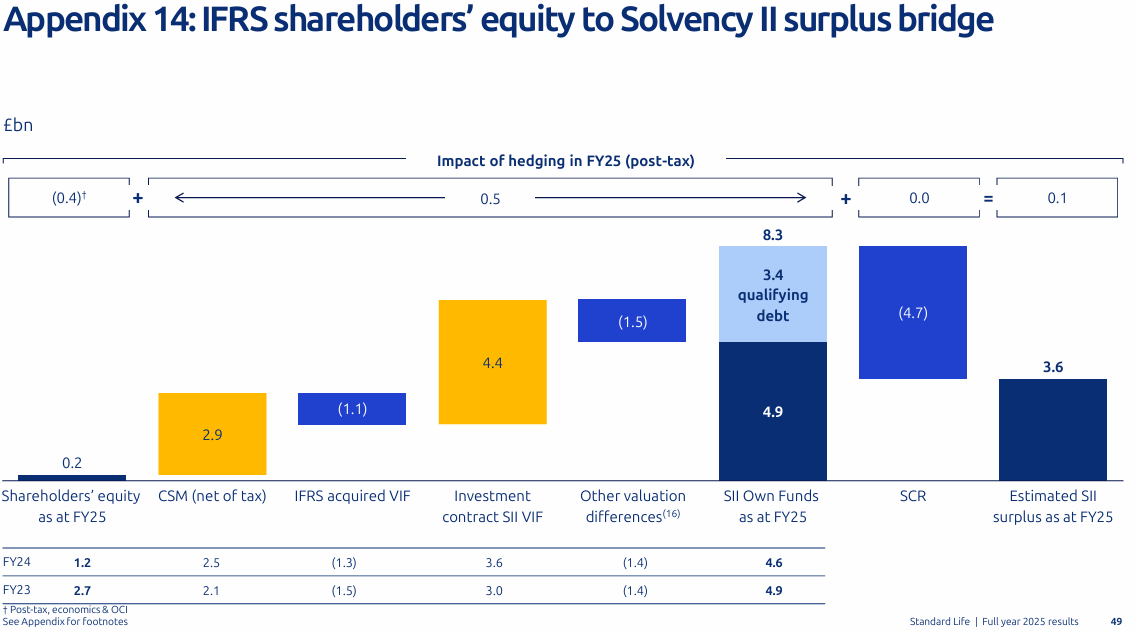
61 Investors strongly supported enhanced presentation and disaggregation, viewing it as the most practical solution, being the most useful to investors, the least burdensome to preparers, and capable of improving comparability without fully rewriting IAS 7.
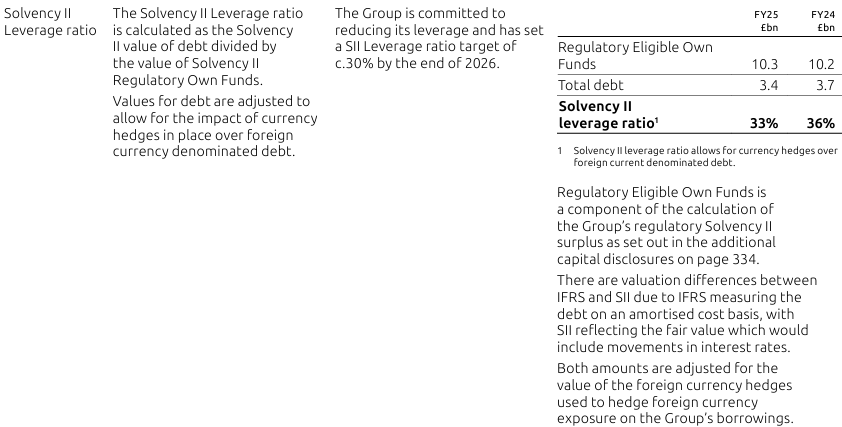
62 Similar to accounting firm representatives, investors suggested that, rather than removing the statement or creating a bespoke version for banks and insurance companies, targeted disaggregation by meaningful drivers is preferred, such as by nature or function, aligned with the principles in IFRS 18, as this would reflect diversified business models, and provide clearer presentation, which could be provided in the notes rather than on the face of the statement of cash flows.
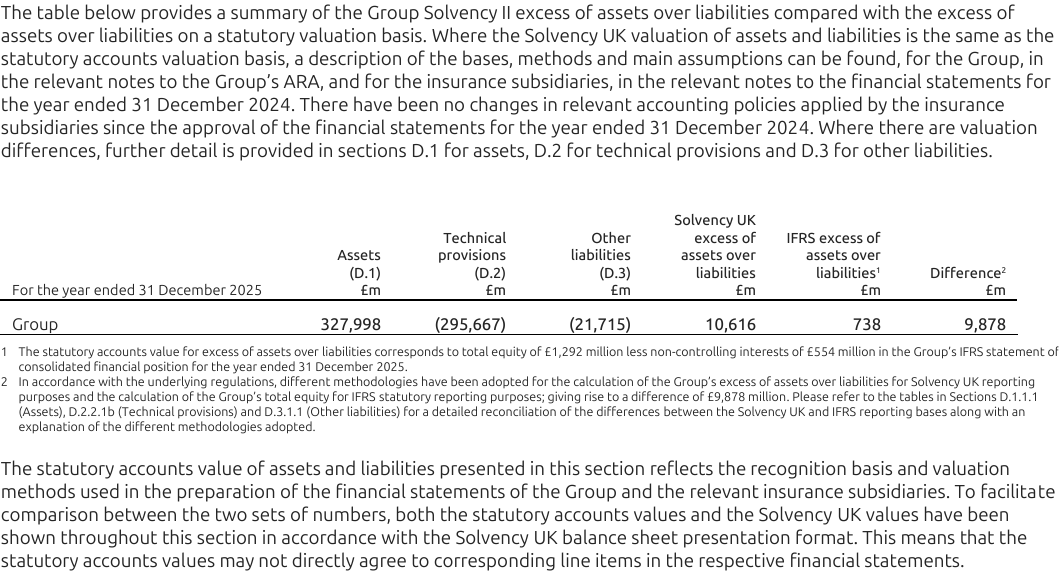
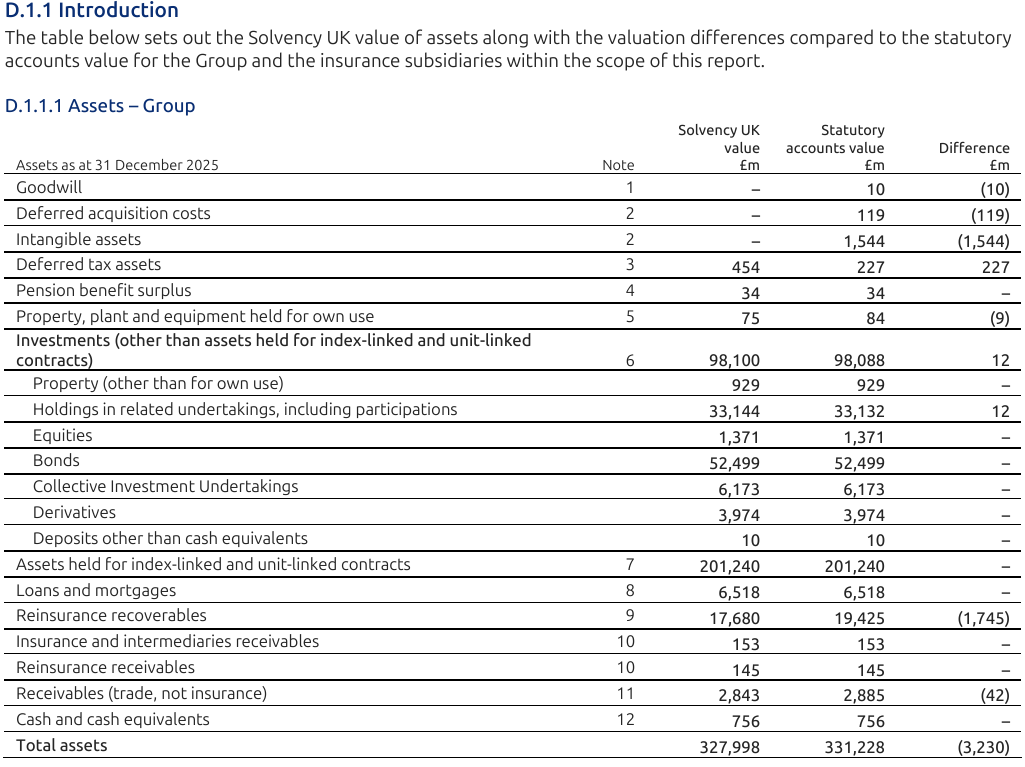
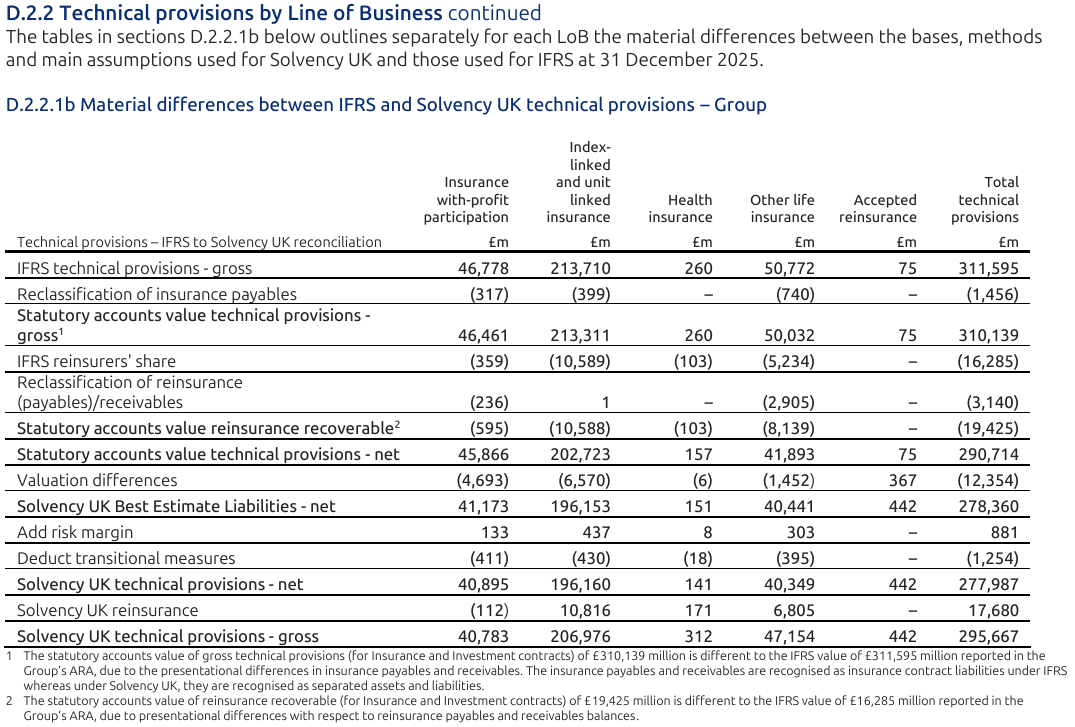
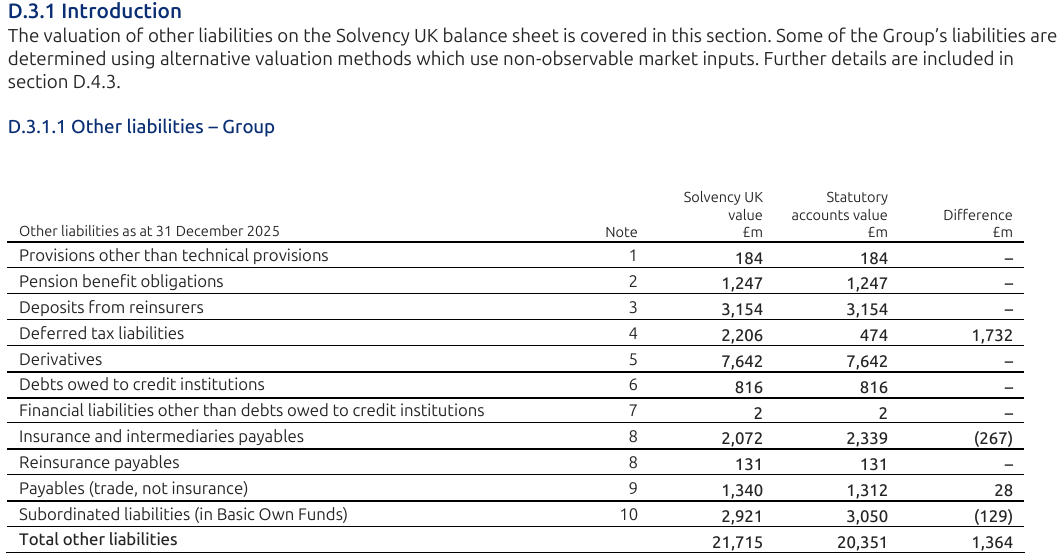
63 In further interviews, one credit manager at a UK bank suggested possible approaches to improving the statement of cash flows information for banks and insurance companies might include requiring a consistent minimum split of ‘operating’ cash flows for financial institutions, with sufficient disaggregation so users can separate the main drivers. Example of disaggregation provided were customer lending and deposits, trading activities, derivatives and related collateral or margin flows, and treasury liquidity management.
Pros and Cons
64 Providing an option for certain financial institutions to provide a simplified statement would reduce preparer burden and cost in preparing a full statement of cash flows, which may have limited usefulness.
65 The IASB would need to consider whether existing requirements are sufficient to ensure that users are still able to access cash flow information related to certain items that stakeholders have highlighted need to be transparent. These include dividend payments, capital issued and repaid, share options exercised, acquisitions and disposals, interest payments and receipts, and changes in debt.
Scoping an exemption
UKEB Preliminary feedback
66 As reported in the UKEB’s third research paper Statement of Cash Flows: UK User and Preparer Perspectives15, whilst alternative solutions should be explored before addressing the question of whether to exempt certain financial institutions from preparing a statement of cash flows, some preparers acknowledged that it was difficult to appropriately scope out banks and insurance companies, especially in the context of consolidated groups with diversified business activities.
67 It may also be difficult to specify the entities that are to be included in the scope of the alternative disclosure requirements on liquidity and solvency.
- One preparer from an insurer suggested that the IASB could refer to Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4)16, where the concept of activities predominantly connected with insurance was introduced.
- One preparer from a bank suggested scoping based on whether other regulatory reporting was required.
UKEB desk-based research
68 The IASB may be reluctant to exempt banks from preparing a cash flow statement for several reasons. Such an exemption would conflict with the principle in IFRS Accounting Standards that the cash flow statement is a primary financial statement for all entities. There would also be practical challenges in clearly defining the entities that should qualify for exemption, particularly for diversified groups that include both financial and non-financial activities17.
69 Rather than exempting banks (lenders and deposit takers) from preparing cash flow statements, there might be a middle ground. The reconciliation from ‘operating profit’ to ‘cash flows from operating activities’ could adjust for changes in loans, deposits and accrued interest in the style of a statement of changes in financial position, without disclosing separate adjustments for ‘amounts affecting customer accounts without affecting cash’.
70 At the time of writing this paper, the IASB is deliberating disclosures for non-cash information and it has tentatively decided to require all entities to provide a disclosure of ‘movements in operating assets and operating liabilities’ (‘working capital’ movements). This disclosure would reconcile the movements shown in the statement of cash flows to the balance sheet movements of the respective operating assets and liabilities. Such a disclosure might be useful for users of financial statements for banks and insurance companies.
UKEB Outreach
71 Investors acknowledged that while a scoped exemption from the requirement to prepare a statement of cash flows for financial institutions may be conceptually attractive, it would be difficult to implement in practice.
72 A key challenge identified by investors and accounting firm representatives is how to define the scope of such an exemption, particularly for conglomerates that combine financial and non-financial activities (e.g. manufacturing groups with financing arms). Some stakeholders suggested limiting any exemption to entities whose primary business is clearly banking and recognised as such by markets or regulators, thereby excluding mixed business models.
73 Others pointed to IAS 30 Disclosures in the Financial Statements of Banks and Similar Financial Institutions18 as a potential starting point, which defined banks based on core activities (deposit-taking and lending) rather than name. However, this approach may still be difficult to apply consistently across jurisdictions. Also, the nature of banking has changed since IAS 30 was developed, with the rise of ‘fin tech’ firms and challenger banks.
74 Definitional challenges are compounded by the global diversity of regulatory frameworks. Financial institutions are typically defined through legal and regulatory constructs that vary by jurisdiction, making it difficult to translate these into a consistent IFRS-based scope.
75 Stakeholders noted that users already view financial institutions differently from non‑financial entities, but translating this distinction into a robust and globally applicable exemption remains complex. As a result, some participants were cautious about exempting an entire industry from presenting a primary financial statement, given the implications for comparability and consistency.
76 Despite these challenges, some stakeholders believe a feasible path exists. They noted that precedents for scoped exemptions already exist in IFRS, such as IFRS 7’s reference to Value-at-Risk demonstrate that IFRS can incorporate externally developed methodologies. Similarly, past IASB work defining insurance companies based on liability ratios suggests that quantitative thresholds could be used to scope exemptions19. Definitions from sustainability standards (e.g. IFRS S2 Climate-related Disclosures) or regulatory frameworks (e.g. Basel III/Pillar III) could also provide a basis for scoping.
77 Preparers, particularly banks, strongly supported an exemption in principle, arguing that regulatory disclosures already provide comprehensive, decision-useful information on liquidity and capital, and that much of the content of the cash flow statement is duplicative.
78 However, they stressed that any exemption should not introduce new burdens, commercially sensitive disclosures, or additional reporting complexity; any alternative disclosures would need to rely on information already prepared and clearly add value for users.
79 Participants also emphasised that the IASB could not rely solely on jurisdiction‑specific regulatory definitions and would instead need a globally consistent, principle-based approach—potentially anchored to widely adopted frameworks like Basel III.
80 Ultimately, stakeholders noted that any reform would need to carefully assess whether the benefits of change outweigh the costs and consider more flexible, principle-based solutions, such as explicitly applying materiality to the presentation of the statement of cash flows.
Pros and Cons
81 The benefit of scoping an exemption for some financial institutions from preparing a full statement of cash flows is to reduce preparer burden and cost in preparing a statement that may have limited usefulness.
82 However, the IASB might be challenged in specifying which entities could apply a globally applicable exemption and how it would apply for diversified groups that include both financial and non-financial activities.
83 If such an exemption is optional, the IASB would still need to find ways of improving guidance on the classification of cash flows specific to banks and insurance companies. Stakeholders feedback suggests that the current guidance is insufficient and leads to diversity between financial institutions in practice classifying similar items.
Limited supplementary disclosures
84 Internationally, banks, insurance companies, and some other financial institutions operate in a highly regulated environment and are bound by a regime of capital, leverage and liquidity requirements and risk management, to ensure their financial stability and resilience. This includes provision of extensive reporting to regulators; some of this information may be publicly available. Investors use this information as part of their decision-making processes and attempt to reconcile some of the key metrics back to the financial statements.
85 For example, in the UK, day-to-day regulation and supervision of the UK financial services industry (including banks and insurance companies) is divided between the Prudential Regulation Authority (PRA), a division of the Bank of England (BoE), and the Financial Conduct Authority (FCA)20. In addition, the European Central Banks's policies hold relevance for banks operating internationally or within the EU. These policies influence banking regulations, impacting how banks function and comply with global standards.
86 For multi-national groups, operations, including overseas branches, subsidiaries and associates, can be subject to many rules and regulations applicable to the conduct of banking and other financial services business in each of the jurisdictions in which a group operates.
Reconciling to Regulatory Capital, Liquidity and Solvency information
Banks – Regulatory liquidity and capital disclosures
87 Banks are required to comply with capital, leverage and liquidity requirements and provide regular regulatory returns to the PRA21, including Liquidity Cover Ratio, High Quality Liquid Assets, Net Stable Funding Ratio and encumbered assets.
88 The Liquidity Cover Ratio requirement takes into account the relative stability of different sources of funding and potential incremental funding requirements in a stress situation22. The Liquidity Cover Ratio is designed to promote short-term resilience of a bank's liquidity risk profile by holding sufficient High Quality Liquid Assets to survive an acute stress scenario lasting for 30 days. The Net Stable Funding Ratio has been developed to promote a sustainable and stable structure of assets and liabilities.
89 Preparers told the UKEB that capital generation is more important than cash generation when it comes to banks, and to some extent insurance companies, stating that investors are looking for dividend returns. Given that dividend payouts are constrained by available capital, not available cash (as noted in paragraph 29), regulatory disclosures, such as Liquidity Cover Ratio and other solvency and capital adequacy information provides users with better insight.
90 Preparers therefore acknowledged that supplementary disclosures that ‘bridge the gap’ and reconcile regulatory capital reporting to the financial statements might provide users with better information. For example, if an entity provides capital and liquidity reporting to an external regulator, providing a reconciliation of that key performance metric (Alternative Performance Metric) to an IFRS measure would be helpful, and a simplified statement of cash flows could otherwise be sufficient.
91 Many preparer and accounting firm representatives suggested that investors and analysts tend to focus more on:
- Capital adequacy and risk-weighted assets (RWAs)23.
- Forward looking liquidity metrics, such as Liquidity Cover Ratio and Net Stable Funding Ratio.
92 Investors strongly supported enhanced presentation, viewing it as the most practical solution. They felt that this approach would be the most useful to investors, the least burdensome to preparers, and capable of improving comparability without fully rewriting IAS 7.
93 Investors suggested enhanced disclosures and better linkage of cash flow movements to regulatory capital requirements would significantly improve usefulness – several investors emphasised that users currently manually derive connections from multiple notes.
94 A credit manager at a UK bank noted that bank liquidity is assessed largely through the liquidity and funding stack, not through ‘cash from operating activities’, and since investors use this cash flow-related information, IFRS should require its inclusion. They noted that users lean on the size and quality of the liquidity buffer, i.e. High Quality Liquid Assets24, and how it maps to the Liquidity Cover Ratio eligible assets, and the degree of funding stability, through the Net Stable Funding Ratio25.
95 One accounting firm representative suggested that liquidity and expected cash flow disclosures are more relevant for banks and insurance companies than an IAS 7-style statement of cash flows:
- IFRS 7 liquidity tables currently show contractual maturities, which often paint an unrealistic picture – “all banks appear insolvent” if deposits are shown as on‑demand.
- Expected maturity profiles or disclosures aligned with regulatory liquidity metrics (e.g. Liquidity Cover Ratio-related insights) may be more meaningful.
- Some UK‑specific disclosures (e.g. DECL26 expected credit loss disclosures) provide helpful visibility into gross loan movements (net new money, portfolio changes), but these are not mandatory globally. The stakeholder noted this asymmetry could justify improved international disclosure requirements.
96 Some accounting firm representatives also stated that regulatory liquidity and capital disclosures are more relevant to investors than cash flows, raising questions about auditability and whether cash flow statements are the right tool.
97 Other legislation, such as Provision 31 of the 2024 UK Corporate Governance Code27 requires Directors to make a statement in the Annual Report regarding the viability of the Group, including an explanation of how they assessed the prospects of the Group, the period of time for which they have made the assessment and why they consider that period to be appropriate.
Insurance companies – Regulatory liquidity and capital disclosures
98 Insurance company regulatory reporting requirements are governed by the Solvency UK reporting part of the PRA Rulebook28, which includes a requirement for regulated firm to produce an annual Solvency and Financial Condition Report (SFCR) and provide regular information on the Solvency Capital Requirement, Solvency UK liquidity reporting and UK Solvency II Own Funds. These are also referred to as Pillar III or Pillar 3 disclosures.
99 The Solvency Capital Requirement29 is mandated by the Solvency II Directive issued by the European Union (EU) in 200930 and is a critical financial mandate for insurance and reinsurance companies in the EU, ensuring they maintain sufficient capital to cover all quantifiable risks, like underwriting and operational risks. Solvency II or Solvency UK requires a Solvency Capital Requirement annual recalculation for accurate risk management. If authorities find the requirement doesn't reflect the risk of a specific insurance type, they can raise the capital requirement. A Solvency Capital Requirement ensures these companies can meet their financial obligations to policyholders with a 99.5% probability over a 12-month period, meaning financial ruin is less than once in 200 cases. The formula uses a modular approach, assessing and then combining exposure to each risk category.
100 In addition to the Solvency Capital Requirement, a Minimum Capital Requirement must also be calculated. The Minimum Capital Requirement is a safety threshold below which national regulators would intervene, if breached. The Minimum Capital Requirement aims for an 85% probability of adequacy over a year. Understanding the Solvency Capital Requirement alongside the Minimum Capital Requirement helps firms avoid potential regulatory interventions and stabilize their operations in a competitive market.
101 The equivalent of equity in a Solvency UK balance sheet is the Solvency II Own Funds figure. Insurance companies tend to hold more own funds than the Solvency Capital Requirement. Insurance companies usually set a metric, the Solvency Ratio, being Total Own Funds divided by the Solvency Capital Requirement and set a ratio, e.g. say 140%–180% of the Solvency Capital Requirement, so that they hold a significant buffer for having the capacity to support the payout of dividends, the reinvestment of cash into its own activities, being organic growth of the business or inorganic growth (acquisitions).
102 One preparer (insurance) interviewed stated that anchoring cash flow reporting for insurance companies around capital would result in a stronger alignment between IAS 7 and capital disclosures currently in IAS 131 (replaced by IFRS 18).
103 The preparer suggested leveraging existing regulatory and capital frameworks rather than removing any existing requirements.
104 The preparer also advocates improving IAS 7, with more detailed guidance tailored to financial institutions, including a requirement to distinguish between cash attributable to shareholders and amounts belonging to policyholders.
105 The preparer suggested there should be clear reconciliation between:
- The IFRS balance sheet and IFRS P&L to the Solvency UK balance sheet and surplus generation.
- Cash generation and distributable capacity, given the constraints of regulatory capital for a financial institution business. Distributable reserves are also constrained by UK law (double test).
106 The preparer also suggested that bringing similar information into IFRS financial statements would not materially increase audit burden and could improve overall financial reporting quality, providing a link explicitly between cash flows and capital and other regulatory constraints, making information in the financial statements more decision-useful than relying on external disclosures.
107 Users suggested that it may not be necessary to require IFRS Accounting Standards to replicate regulatory templates, but IFRS Standards could close the gap with:
- a limited, auditable bridge, that requires financial institutions to provides a clear reconciliation from ‘cash and cash equivalents’ to liquidity resources and constraints; and
- a short commentary explaining the main drivers when the liquidity buffer moves materially.
Existing disclosures
108 Extensive disclosures are already provided by UK banks (see Annex 1) in publicly available regulatory information, or investor packs, or in the front half of the annual report, or voluntarily in financial statements, including example disclosures of Liquidity Cover Ratio, Net Stable Funding Ratio and High Quality Liquid Assets by UK banks. One UK bank included in the examples publishes its Pillar III disclosures on its website32.
109 Practical examples of disclosures provided by UK insurance companies that could inform standard setting are set out in Annex 2, including disclosures of:
- Cash generation and uses of cash.
- Capital and earnings reconciling between IFRS and Solvency UK (Solvency II (SII)) requirements.
- Publicly available audited solvency reports (Solvency and Financial Condition Report - SFCR33), showing the Solvency UK and IFRS metrics for excess of assets over liabilities and supporting tables showing the reconciliation and an explanation of the different methodologies adopted.
110 This is a useful source to determine what disclosures if referred to, and reconciled to IFRS amounts in the financial statements, would be more useful to users.
Pros and Cons
111 The main benefit of requiring certain financial institutions to provide additional limited disclosure of key metrics, defined by regulators, against which those financial institutions monitor the success of their businesses is to bridge the gap between those KPIs and IFRS defined measures, showing how they reconcile, improving transparency for users.
112 Users will benefit from not having to attempt their own reconciliation between the regulatory metrics and the audited financial statements, ensuring that reconciling items are transparent. In addition, this will allow for transparency on that information for the market as a whole.
113 This approach would be similar to how the IASB plans to bridge the gap between cash-flow related MPMs (defined by management, as opposed to regulators), by extending the income and expense MPM disclosure requirements in IFRS 18 to cash flow-related measures.
114 The challenge will be assessing which specific metrics provide the most useful information for users on a global basis, and how financial institutions might present required reconciliations without unnecessarily duplicating information required to be disclosed outside the financial statements.
Other cash flow measures
115 In addition to regulatory metrics, such as the Liquidity Cover Ratio, the Solvency Capital Requirement, etc, interviewees highlighted other key performance indicators used by insurance companies, e.g. Operating Cash Generation (OCG) and Total Cash Generation (TCG)34, which would be subject to disclosure requirements similar to income/expense MPMs covered under IFRS 18, should the IASB extend the MPM disclosure requirements to cash flow measures.
116 At the time of writing this paper, the IASB has started to deliberate extending the scope of income and expense management-defined performance measures (MPMs), introduced in IFRS 1835, to cash flow measures. Companies often use their own measures to track performance, including subtotals of income and expenses that they communicate in connection with financial performance. MPMs are currently defined as a subtotal of income and expenses that:
- is used in public communications outside financial statements;
- is used to communicate to investors management’s view of an aspect of the financial performance of the company as a whole; and
- is not listed in IFRS 18 or specifically required by IFRS Accounting Standards.
Pros and Cons
117 If the IASB decides to extend the scope to cash flow measures, it will need to further consider the wording if it intends to capture regulatory ratios in addition to cash-related MPMs, given that the former are key performance metrics are not defined by management but rather defined by regulation.
Commentary
UKEB outreach
118 Accounting firm representatives and preparers noted that such disclosures of quantitative liquidity metrics are far more informative than the statement of cash flows for understanding liquidity risk and suggested that aligning financial statements more closely with these existing Pillar III liquidity disclosures could improve usefulness for investors, along with clear commentary. However, they cautioned that commentary alone risks becoming boilerplate and uninformative.
Pros and cons
119 The IASB would need to consider whether it could require certain financial institutions to provide commentary without the risk of disclosures becoming boilerplate. Understanding what information would be useful to users and requiring commentary to be entity-specific will be key.
Restricted cash
UKEB outreach
120 A credit manager from a UK bank noted that users also need to understand what cash is genuinely available versus operationally required or encumbered. ‘Cash and cash equivalents’ can include items that are not freely deployable, and disclosure on encumbrance can be more or less explicit across banks in financial statements despite disclosure requirements in regulatory reporting36.
Existing disclosures
121 The reporting of encumbered assets is mandatory for all banks and is included in the Pillar 3 report (see example in Annex 1).
Pros and Cons
122 Linking cash and cash equivalents disclosed in the statement of cash flows to regulatory reporting would provide greater transparency for users over cash that is genuinely available, albeit cash is generally not the limiting factor for dividend payouts, but rather available capital.
Concluding observations
Challenges
123 UKEB evidence suggests that stakeholders think:
- For banks and insurance companies, the current statement of cash flows:
- does not fit the business models of banks and insurance companies;
- is widely considered to be not decision useful;
- is operationally burdensome and results in inconsistent application of cash and cash equivalents and classification of cash flows;
- is conceptually flawed; and
- should either be significantly reformed to improve the usefulness to users or removed altogether through a global scope exemption.
- Capital generation of banks and insurance companies is more important to users of their financial statements than their cash generation. Investors are looking for dividend returns and such payouts by banks and insurance companies are constrained by available capital, not cash.
- Existing disclosures required by IFRS 7, IFRS 9 (and IFRS 17 for insurance companies), are typically not cohesive, making it difficult to understand the impact of the risks to the business as a whole.
Opportunities
124 Stakeholder feedback suggests there are opportunities for the IASB to improve the usefulness of reporting by banks and insurance companies.
Fix the definition of “cash and cash equivalents”
125 UK preparers suggest that the top priority for reform is the definition of ‘cash and cash equivalents’, which currently produces counterintuitive and unhelpful results for financial institutions. Amendments are needed to:
- Address the arbitrary “original maturity” concept (three month ‘rule’);
- Align more closely with how banks assess liquidity (“remaining maturity”).
- Provide clearer guidance on whether mandatory central bank deposits should be classified as “investments” or “cash and cash equivalents”.
Consider a scope exemption for banks and insurance companies
126 There is strong preparer support for eliminating the statement of cash flows for banks and insurance companies.
127 However, users suggest that the statement of cash flows does provide some useful information as it:
- provides insights into the nature of a financial institution’s business activities e.g. identifies banks that are not fully active–no increase in working capital loans up to the expected level of utilisation
- links information about items between the other primary statements.
128 Therefore, a simplified statement of cash flows might be a useful compromise to reduce the cost to preparers, whilst still providing information that some users find helpful.
129 This assumes that there would be clear requirements to provide relevant disaggregated information that users need, in the notes to the accounts, such as dividend payments, capital issued and repaid, share options exercised, acquisitions and disposals, interest payments and receipts, and changes in debt.
130 Scoping an exemption might be challenging, but it is possible and worth exploring, provided the IASB carefully defines a global, principle-based scope definition.
Explore alternatives or replacement disclosures
131 Stakeholders suggest that regulatory disclosures, such as liquidity and other solvency and capital adequacy information provides users with better insight and more relevant information about banks and insurance companies than that currently in the statement of cash flows for those entities.
132 Therefore, there is an opportunity to require limited supplementary disclosures that ‘bridge the gap’ i.e. reconcile regulatory capital and liquidity reporting to the financial statements, to provide users with better, more cohesive information.
133 If an entity provides capital and liquidity reporting to an external regulator, such as the PRA in the UK, it could take advantage of a scope exemption from a full statement of cash flows and provide reconciliations of certain capital and liquidity performance measures to IFRS-defined sub-totals, alongside a simplified statement of cash flows.
134 Stakeholders suggest that the IASB consider whether any improvements to reporting requirements (i.e. disaggregation, new disclosures) could be more effectively made through IFRS 7 or IFRS 18, rather than IAS 7.
135 Stakeholders suggest that the IASB, when proposing new requirements and changes to current requirements, ensures careful scoping of any exemptions and avoids:
- duplicating regulatory information, unless users need it, though this may be challenging given the various regulatory regimes that operate internationally;
- additional reporting burden;
- disclosure of sensitive information; and
- unintended consequences (e.g. bringing regulatory information within audit scope).
Annex 1: Example of Regulatory capital and liquidity requirement disclosures by banks
136 Below are examples of Liquidity Cover Ratio and Net Stable Funding Ratio, including High Quality Liquid Assets disclosures, a reconciliation of equity to Regulatory capital, Own funds and Eligible liabilities, and a statement of sources and uses of funds, commonly seen in the risk management section of the annual report of banks.
Source: Barclays PLC Annual Report 2025, Risk Review (pages 318–320)
137 For other examples of Liquidity Cover Ratio, Net Stable Funding Ratio, High Quality Liquid Assets see: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – pages 22-25 (similar examples so not replicated here).
Liquidity Cover Ratio
Liquidity regulation Barclays Group monitors its position against both the LCR and NSFR according to the PRA regulatory requirements which include certain Basel III standards that were retained in the UK regulatory framework from 1 January 2022 as part of the UK’s withdrawal from the EU. The LCR requirement takes into account the relative stability of different sources of funding and potential incremental funding requirements in a stress. The LCR is designed to promote short-term resilience of a bank’s liquidity risk profile by holding sufficient High Quality Liquid Assets (HQLA) to survive an acute stress scenario lasting for 30 days. The NSFR has been developed to promote a sustainable and stable structure of assets and liabilities.
Liquidity Coverage Ratio (LCR) The external LCR requirement is designed to promote short-term resilience of a bank's liquidity risk profile by holding sufficient High Quality Liquid Assets (HQLA) to survive an acute stress scenario lasting for 30 days.
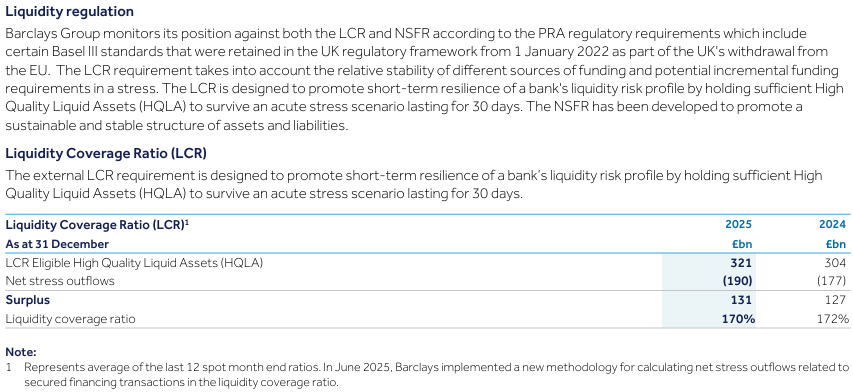
138 The Liquidity Cover Ratio could be supplemented by information on the breakdown and changes in the stock of highly liquid assets – see example in paragraph 142 below.
Net Stable Funding Ratio
Net Stable Funding Ratio (NSFR) The external NSFR metric requires banks to maintain a stable funding profile taking into account both on and certain off balance sheet exposures over a medium to long term period. The ratio is defined as the Available Stable Funding (capital and certain liabilities which are defined as stable sources of funding) relative to the Required Stable Funding (a measure of assets on the balance sheet and certain off balance sheet exposures which may require longer term funding). The NSFR was 135% at December 2025 (December 2024: 135%) (average of last four quarter ends) equivalent to a surplus of £166bn (2024: £163bn) above the regulatory requirement and demonstrates Barclays' stable balance sheet funding profile.
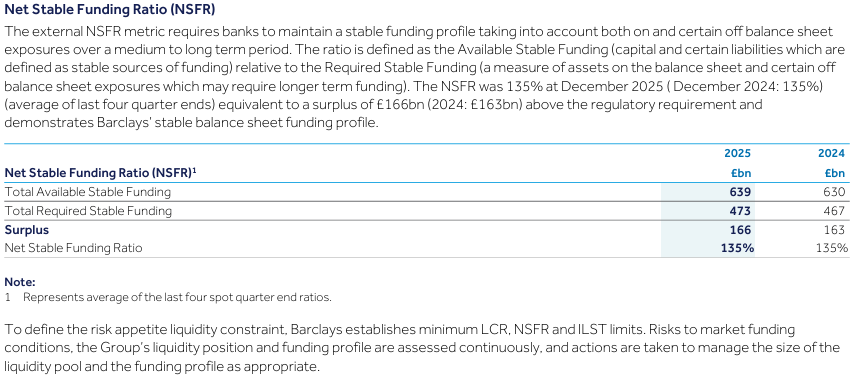
Note: 1. Represents average of the last four spot quarter end ratios.
To define the risk appetite liquidity constraint, Barclays establishes minimum LCR, NSFR and ILST limits. Risks to market funding conditions, the Group's liquidity position and funding profile are assessed continuously, and actions are taken to manage the size of the liquidity pool and the funding profile as appropriate.
139 The NFSR ratio could be supplemented by a breakdown of contractual and/or expected maturities of financial asset and liabilities prepared according to maturity buckets with sufficient sensitivity.
140 As shown in the Liquidity Cover Ratio and Net Stable Funding Ratio example disclosures below, instead of providing information on liquidity at a point in time, time-series information of a particular ratio could be provided and might better reflect significant fluctuations within short periods of time of banks’ liquidity – see also: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – pages 22-25.
Liquidity Cover Ratio eligible High Quality Liquid Assets
141 Assets which are potentially available for refinancing transactions by a bank (by pledging their assets as collateral) are referred to as unencumbered. Disclosures of encumbered and unencumbered assets by main categories provide additional insight into the liquidity position. IFRS 7 already requires disclosure of the carrying amount of financial assets placed as collateral for liabilities or contingent liabilities. Similar information is required in other IFRS Accounting Standards for non-financial assets.
142 In addition to the current information on maturity analyses based on contractual maturities, information on how liquidity needs are managed could also be provided, as well as a qualitative analysis of the components of the liquidity reserve/pool held to meet those needs. This would include maturity analysis considering behavioural assumptions (particularly on core deposits).
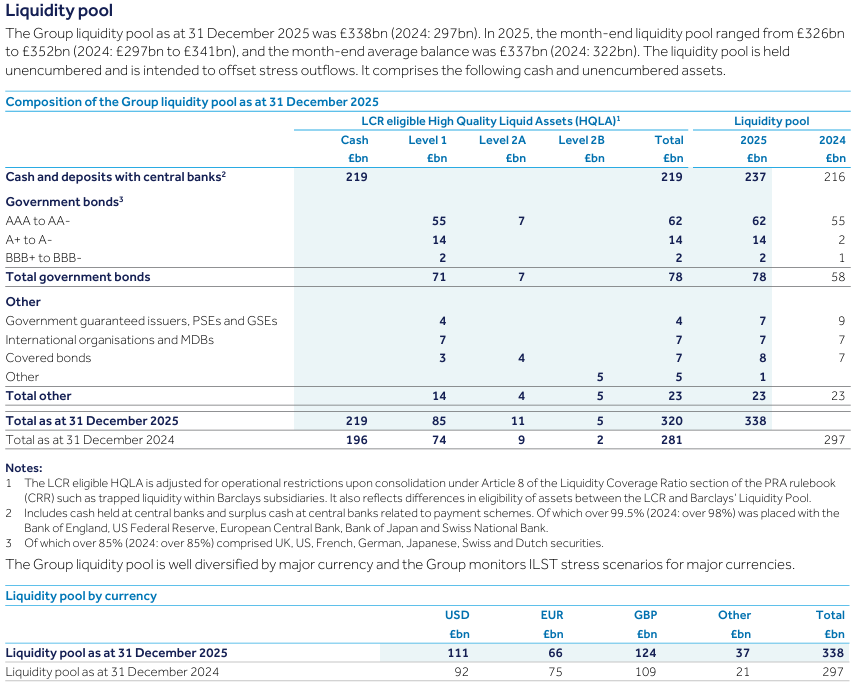
143 As shown in the Liquidity Pool example above, instead of providing information on liquidity at a point in time, time-series information of a particular ratio could be provided and might better reflect significant fluctuations within short periods of time of banks’ liquidity.
Reconciliation of equity to Regulatory Capital, Own funds and Eligible liabilities
144 Below are examples of reconciliations between the accounting balance sheets and regulatory balance sheets, commonly seen in the risk management section of the annual report of banks.
145 The CET1 ratio, among other metrics, is a measure of the capital strength and resilience of a bank, determined in accordance with regulatory requirements. [In this example CET1 is mentioned 94 times in the annual report, showing the significance of this metric for banks, but only once in the financial statements].
Example 1 - Source: Barclays PLC Annual Report 2025 – pages 57, 138, 329 (Risk review) and 405 (Basis of preparation).
146 Example 2 - See: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – page 15 (similar to Example 1 so not replicated here).
147 Example 3 - Source: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – page 8
The regulatory consolidation is consistent with the accounting consolidation, with the following exceptions: * subsidiaries engaged in insurance activities are equity accounted in the regulatory consolidation and then deducted from CET1 capital, subject to thresholds; * special purpose entities ('SPEs') are excluded where significant risk has been transferred to third parties. Exposures to these SPEs are risk weighted as securitisation positions for regulatory purposes; * participating interests in banking associates are proportionally consolidated for regulatory purposes by including our share of assets, liabilities, profits and losses, and RWAs in accordance with the PRA's regulatory requirements; and * non-participating significant investments are deducted from capital, subject to thresholds.
For further details of the differences between the accounting and regulatory scope of consolidation and their definition of exposure, see pages 8 to 11.
The table below presents the reconciliation between the Group's financial balance sheet and the regulatory scope of consolidation. The regulatory balance sheet value cannot be directly reconciled to other tables showing exposure under the regulatory scope of consolidation as the basis of measurement used in the calculation of RWAs differs.
Table 2: Reconciliation of regulatory own funds to balance sheet in the financial statements (UK CC2)
Movement in CET1 capital
148 Source: Barclays PLC Annual Report 2025, Risk Review – page 331
Asset encumbrance
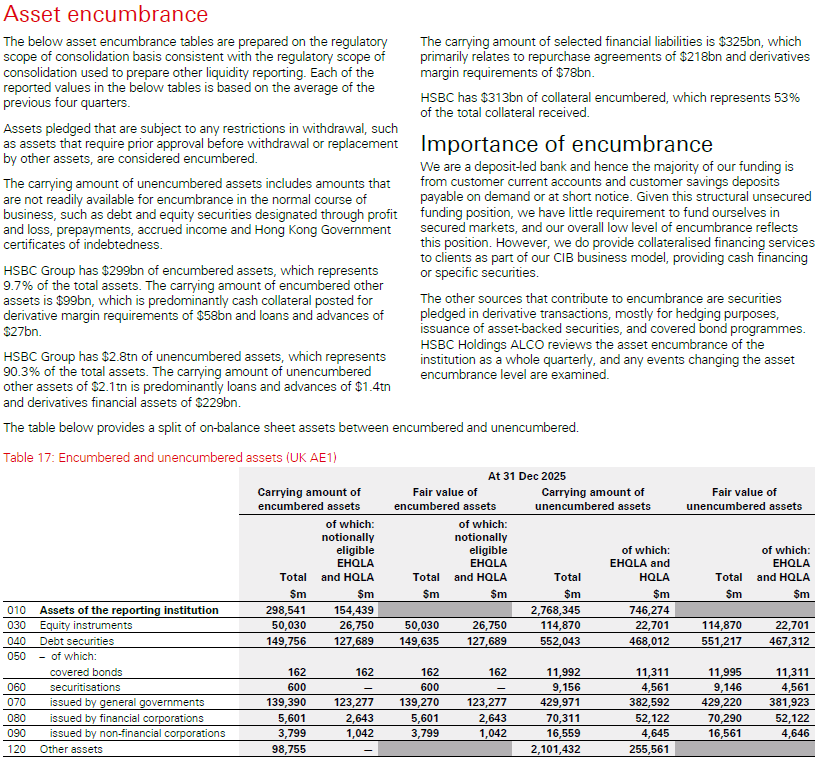
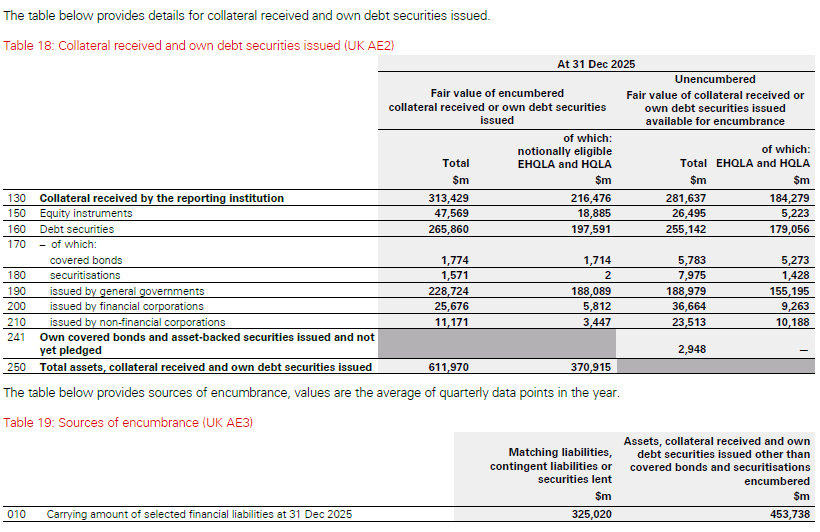
149 Source: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – page 27
Asset encumbrance The below asset encumbrance tables are prepared on the regulatory scope of consolidation basis consistent with the regulatory scope of consolidation used to prepare other liquidity reporting. Each of the reported values in the below tables is based on the average of the previous four quarters.
Assets pledged that are subject to any restrictions in withdrawal, such as assets that require prior approval before withdrawal or replacement by other assets, are considered encumbered.
The carrying amount of unencumbered assets includes assets that are not readily available for encumbrance in the normal course of business, such as debt and equity securities designated through profit and loss, prepayments, accrued income and Hong Kong Government certificates of indebtedness.
HSBC Group has $290bn of encumbered assets, which represents 9.7% of the total assets. The carrying amount of encumbered other assets is $99bn, which is predominantly cash collateral posted for derivative margin requirements of $58bn and loans and advances of $27bn.
HSBC Group has $2.8tn of unencumbered assets, which represents 90.3% of the total assets. The carrying amount of unencumbered other assets of $2.1tn is predominantly loans and advances of $1.4tn and derivatives financial assets of $229bn.
The table below provides a split of on-balance sheet assets between encumbered and unencumbered.
The carrying amount of selected financial liabilities is $325bn, which primarily relates to repurchase agreements of $218bn and derivatives margin requirements of $78bn.
HSBC has $313bn of collateral encumbered, which represents 53% of the total collateral received.
Importance of encumbrance We are a deposit-led bank and hence the majority of our funding is from customer current accounts and customer savings deposits payable on demand or at short notice. Given this structural unsecured funding position, we have little requirement to fund ourselves in secured markets, and our overall low level of encumbrance reflects this position. However, we do provide collateralised financing services to clients as part of our CIB business model, providing cash financing or specific securities.
The other sources that contribute to encumbrance are securities payable on directed transactions, mostly for hedging purposes, issuance of asset-backed securities, and covered bond programmes. HSBC Holdings ALCO reviews the asset encumbrance of the institution as a whole quarterly, and any events changing the asset encumbrance level are examined.
Leverage
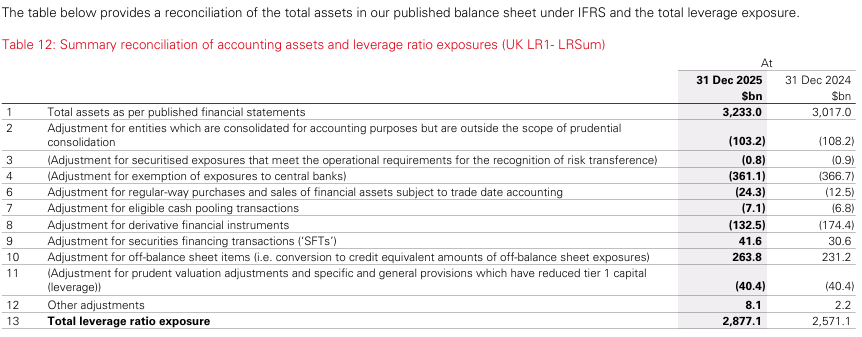
150 Source: HSBC Holdings plc Pillar 3 Disclosures at 31 December 2025 – page 21
The table below provides a reconciliation of the total assets in our published balance sheet under IFRS and the total leverage exposure.
Sources and uses of funding
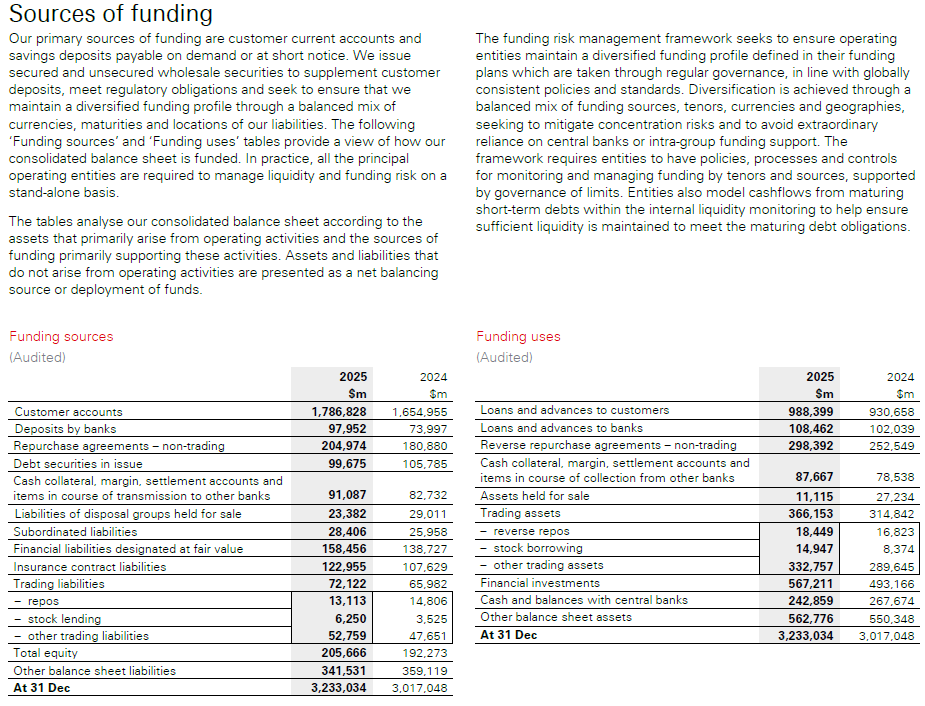
151 Source: HSBC Holdings plc Annual Report and Accounts 2025, Risk Review – page 162.
152 It is noted that this disclosure is audited.
Sources of funding Our primary sources of funding are customer current accounts and savings deposits payable on demand or at short notice. We issue secured and unsecured wholesale securities to supplement customer deposits, meet regulatory obligations and seek to ensure that we maintain a diversified funding profile through a balanced mix of currencies, maturities and sources of our liabilities. The following 'Funding sources' and 'Funding uses' tables provide a view of how our consolidated balance sheet is funded. In practice, all the principal operating entities are required to manage liquidity and funding risk on a stand-alone basis.
The tables analyse our consolidated balance sheet according to the assets that primarily arise from operating activities and the sources of funding primarily supporting these activities. Assets and liabilities that do not arise from operating activities are presented as a net balancing source or deployment of funds.
The funding risk management framework seeks to ensure operating entities maintain a diversified funding profile defined in their funding plans which are taken through regulatory governance, in line with globally consistent policies and standards. Diversification is achieved through a balanced mix of funding sources, tenors, currencies and geographies, seeking to mitigate concentration risks and to avoid extraordinary reliance on central banks or intra-group funding support. The framework requires entities to have policies, processes and controls for monitoring and managing funding by tenors and sources, supported by governance of limits. Entities also model cashflows from maturing short-term debts within the internal liquidity monitoring to help ensure sufficient liquidity is maintained to meet the maturing debt obligations.
Annex 2: Examples of Regulatory capital requirement disclosures and other cash flow measures by insurance companies
153 Below are examples of voluntary disclosures provided by insurer, Standard Life plc, that expanded capital reconciliation disclosures in its 2025 financial statements. Examples include:
- Cash generation and uses of cash.
- Capital and earnings reconciling between IFRS and Solvency UK (Solvency II) requirements.
- Operating Cash Generation (OCG) and Total Cash Generation (TCG) key performance metrics reconciled to IFRS results – these could potentially be captured as cash flow MPMs, should the IASB extend the scope of income and expense MPMs, introduced in IFRS 18, to cash flow measures.
- Publicly available audited solvency reports (Solvency and Financial Condition Report - SFCR).
Movement in cash and cash equivalents showing cash generated and uses of cash
154 The example below is a voluntary disclosure by an insurer of cash generation and uses of funds reconciled back to the movement in cash and cash equivalents.
Source: Standard Life plc (Formerly Phoenix Group Holdings plc) FY2025 Investor Presentation slides (page 41)
Capital and Earnings reconciliations between IFRS and Solvency II
155 The example below is a voluntary disclosure of capital reconciliation between IFRS and Solvency UK (Solvency II (SII)) requirements.
Source: Standard Life plc (Formerly Phoenix Group Holdings plc) FY2025 Investor Presentation slides (page 41)
156 The example below is a voluntary narrative disclosure of differences between IFRS and SII.
Source: Standard Life plc Formerly Phoenix Group Holdings plc Annual Report and Accounts 2025, Note 11 to the Parent Company Financial Statements (page 345)
Publicly available audited Solvency and Financial Condition Report (SFCR)
157 The example below from a publicly available audited Solvency and Financial Condition Report (SFCR), shows the Solvency UK and IFRS metrics for excess of assets over liabilities and supporting tables showing the reconciliation and an explanation of the different methodologies adopted.
The table below provides a summary of the Group Solvency II excess of assets over liabilities compared with the excess of assets over liabilities on a statutory valuation basis. Where the Solvency UK valuation of assets and liabilities is the same as the statutory accounts valuation basis, a description of the bases, methods and main assumptions can be found, for the Group, in the relevant notes to the Group’s ARA, and for the insurance subsidiaries, in the relevant notes to the financial statements for the year ended 31 December 2024. There have been no changes in relevant accounting policies applied by the insurance subsidiaries since the approval of the financial statements for the year ended 31 December 2024. Where there are valuation differences, further detail is provided in sections D.1 for assets, D.2 for technical provisions and D.3 for other liabilities.
The statutory accounts value of assets and liabilities presented in this section reflects the recognition basis and valuation methods used in the preparation of the financial statements of the Group and the relevant insurance subsidiaries. To facilitate comparison between the two sets of numbers, both the statutory accounts values and the Solvency UK values have been shown throughout this section in accordance with the Solvency UK balance sheet presentation format. This means that the statutory accounts values may not directly agree to corresponding line items in the respective financial statements.
D.1.1 Introduction The table below sets out the Solvency UK value of assets along with the valuation differences compared to the statutory accounts value for the Group and the insurance subsidiaries within the scope of this report.
D.1.1.1 Assets – Group
D.2.2 Technical provisions by Line of Business continued The tables in sections D.2.2.1b outline disclosures separately for each LoB the material differences between the bases, methods and main assumptions used for Solvency UK and those used for IFRS at 31 December 2025.
D.2.2.1b Material differences between IFRS and Solvency UK technical provisions – Group
D.3.1 Introduction The valuation of other liabilities on the Solvency UK balance sheet is covered in this section. Some of the Group's liabilities are determined using alternative valuation methods which use non-observable market inputs. Further details are included in section D.4.3.
D.3.1.1 Other liabilities – Group
E.1 Own Funds and analysis of solvency position continued E.1.3 Analysis of solvency position – Group continued E.1.3.6 Reconciliation of IFRS equity to excess of assets over liabilities The table below provides an analysis of the key differences between the Group's net assets under IFRS and the excess of assets over liabilities under Solvency UK rules.
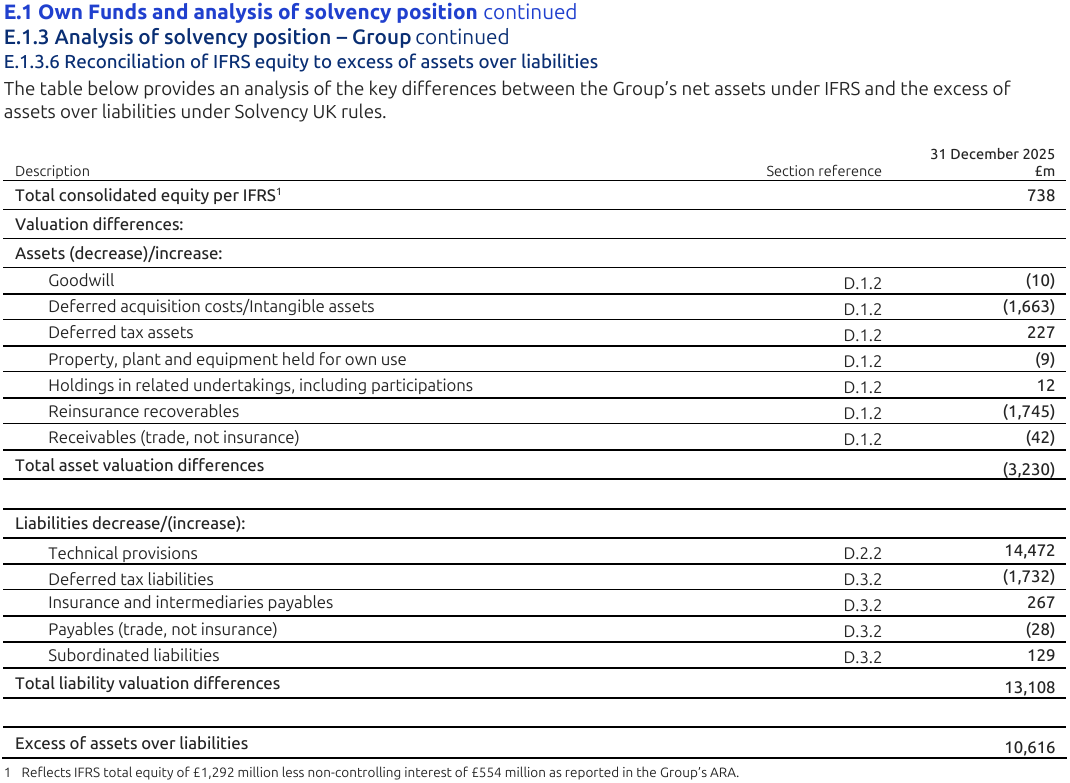
Source: Standard Life plc Formerly Phoenix Group Holdings plc Solvency and Financial Condition Report (SFCR) for the year ended 31 December 2025 (page 65) and tables in Sections D.1.1.1 (Assets), D.2.2.1b (Technical provisions) and D.3.1.1 (Other liabilities), E1.3.6 (Excess assets over liabilities)
Contact Us
UK Endorsement Board
13th Floor | 1 Harbour Exchange | Harbour Exchange Square | London | E14 9GE
www.endorsement-board.uk
- greater than 90 per cent; or
- less than or equal to 90 per cent but greater than 80 per cent, and the company does not engage in a significant activity unconnected with insurance.
Liabilities connected with insurance include investment contracts measured at FVPL, and liabilities that arise because the insurer issues, or fulfils obligations arising from, these contracts (such as deferred tax liabilities arising on its insurance contracts).
Footnotes
-
See paragraph 9 of the UKEB 2026/27 Regulatory Strategy, year 2 of the UKEB 2025/28 three-year Regulatory Strategy. ↩
-
The meeting summary for the UKEB Investor Advisory Group meeting on 2 February 2026 can be found on the UKEB website here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/investor-advisory-group/. The meeting summary for the UKEB Accounting Firms and Institutes Advisory Group meeting on 10 March 2026 can be found here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/accounting-firms-and-institutes-advisory-group/. Details of the UKEB Financial Instruments Working Group can be found on the UKEB website here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/financial-instruments-working-group/. ↩
-
For two example of statements of cash flows disclosed by banks, see Lloyds Banking Group plc Annual Report and Accounts 2025, Consolidated Cash Flows Statement (page 217) and related note 40 (pages 295-296) and Barclays PLC Annual Report 2025, Consolidated Cash Flows Statement (page 401). ↩
-
For an example of a statement of cash flows disclosed by an insurer, see Standard Life plc Formerly Phoenix Group Holdings plc Annual Report and Accounts 2025, Consolidated Cash Flow Statement (page 205) and related note 12 (page 311). Standard Life financial statements provide an example of effective cross-referencing, linking the primary financial statements to the notes - note I2 provides a more detailed breakdown of the operating cash flows, albeit the movement in operating asset and liabilities is not cross-referenced to the balance sheet notes, which users have informed us would be useful. ↩
-
For an example of a statement of cash flows disclosed by an investment fund see 3i Group Plc Annual Report 2025, page 158. ↩
-
See paragraphs A133–A138 of the UKEB first research paper Statement of Cash Flows and Related Matters: Background and key issues. ↩
-
Paragraphs 87 of the Staff Agenda Paper 20A for the IASB March 2025 meeting. ↩
-
See paragraphs C170–C178 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives. ↩
-
For an example see Standard Life plc Formerly Phoenix Group Holdings plc Annual Report and Accounts 2025, Note E6 Risk management (page 249) ↩
-
IAS 1 is replaced by IFRS 18 effective 1 January 2027. These specific paragraphs are replaced by paragraphs 126–129 of IFRS 18 which require an entity to “disclose in the notes information that enables users of financial statements to evaluate the entity’s objectives, policies and processes for managing capital”. ↩
-
See paragraphs C170–C178 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives. ↩
-
In June 2018, the Interpretations Committee issued Classification of short-term loans and credit facilities after receiving a request asking about short-term loans and credit facilities that have a short contractual notice period, and the balance does not often fluctuate from being negative to positive to include in its statement of cash flows as a component of cash and cash equivalents. The Committee concluded that the entity does not include the short-term arrangements as components of cash and cash equivalents. This is because these short-term arrangements are not repayable on demand. ↩
-
The Basel Committee on Banking Supervision (BCBS) is a global standard setter for banking regulation, aimed at enhancing financial stability through improved banking supervision and regulation. Its primary purpose is to provide a forum for regular cooperation on banking supervisory matters and to develop standards for the prudential regulation of banks (Source: https://www.bis.org/bcbs/index.htm). The Pillar III standard is part of the BCBS Consolidated Framework, which lays out a comprehensive set of public disclosure requirements that seek to provide investors, analysts, and other market participants with sufficient information to assess an internationally active bank's material risks, risk management practices and capital adequacy. The requirements aim to improve the ability of market participants to assess the risk profile of financial institutions and to make informed decisions regarding investment. In the UK, the Prudential Regulation Authority (PRA) regulatory requirements include certain Basel III standards that were retained in the UK regulatory framework from 1 January 2022 as part of the UK's withdrawal from the EU. Under the PRA requirements, banks are required to monitor their position against both the Liquidity Cover Ratio (LCR) and Net Stable Funding Ratio (NSFR). ↩
-
See Section 2.4 Grouping of Information of Effects Analysis–IFRS 18 Presentation and Disclosure in Financial Statements published by the IFRS Foundation in April 2024. ↩
-
See paragraphs C176–C178 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives ↩
-
The IASB issued “Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4)” on 12 September 2016. The amendments address concerns arising from implementing the financial instruments Standard, IFRS 9, before implementing IFRS 17 Insurance Contracts; the amendments also supplemented existing options in IFRS 4 to address those concerns. IFRS 9 Financial Instruments was issued on 24 July 2014 and became effective on 1 January 2018. IFRS 17 was issued on 18 May 2017 and became effective on 1 January 2023. ↩
-
These issues are explored in more detail in Accounting Miscellany blog: Cash flow statements for banks, insurance companies and investment funds (published 16 May 2025) ↩
-
IAS 30 Disclosures in the Financial Statements of Banks and Similar Financial Institutions was effective 1 January 1991 and superseded by IFRS 7 Financial Instruments: Disclosures, effective 1 Jan 2007. ↩
-
See slides 6–7 of September 2016 IFRS® Project Summary and Feedback Statement Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4). A company’s activities are predominantly connected with insurance, if, and only if:
- ↩
-
Both the PRA and the FCA apply standards that generally either anticipate or go beyond requirements established by global or European Union (EU) standards, whether in relation to capital, leverage and liquidity, resolvability and resolution or matters of conduct. The UK is in the process of reviewing, repealing and, where relevant, replacing the EU legislation that was on shored into UK law following the UK’s departure from the EU (known as “assimilated law”). The Financial Services and Markets Act 2023 (FSMA 2023) established a framework for the revocation of assimilated law relating to financial services. However, the Government is not expected to revoke assimilated law relating to financial services unless the FCA and/or PRA have drafted and consulted on rules in the relevant areas, where it is appropriate that the provisions are replaced. There is a significant volume of assimilated law for the UK Government to repeal and replace, so this process remains ongoing and the regulatory landscape continues to develop. There is potential for an increase in regulatory implementation costs to adapt systems and controls, as a result of these developments, although areas of divergence from assimilated law have been limited to date. [see pages 342–346 of the Barclays PLC Annual Report 2025]. ↩
-
See https://www.bankofengland.co.uk/prudential-regulation/regulatory-reporting/regulatory-reporting-banking-sector/banks-building-societies-and-investment-firms ↩
-
Market stress events such as the March 2020 ‘dash for cash’ at the onset of the Covid-19 pandemic, and the September 2022 liability-driven investment (LDI) crisis. ↩
-
Risk-weighted assets (RWAs) are used to link the minimum amount of capital that banks must hold, with the risk profile of the bank’s lending activities (and other assets). ↩
-
The liquidity cover ratio (LCR) determines if a bank holds sufficient High Quality Liquid Assets to survive a short-term liquidity stress for a period of 30 days. Banks are required to maintain LCR at a minimum of 100%. ↩
-
Net stable funding ratio (NSFR) determines if a bank holds sufficient long-term stable funding to cover the duration of their long-term assets. Banks are required to maintain minimum NSFR of 100% on standalone as well as consolidated level at all times, as assessed based on regulatory guidelines (Annex III of the Bank of England’s Prudential Regulation Authority covers instructions for reporting on stable funding). ↩
-
The Taskforce on Disclosures about Expected Credit Losses (DECL), sponsored by the Financial Conduct Authority (FCA), the Financial Reporting Council (FRC) and the Prudential Regulation Authority (PRA), published guidance on a complete set of high quality IFRS 9 Expected Credit Loss accounting (ECL) disclosures. Its third report comprises a comparison of preparers’ and users’ assessments of adoption of Taskforce recommendations and good practice disclosure examples – see https://www.frc.org.uk/news-and-events/news/2022/09/taskforce-on-disclosures-about-expected-credit-losses-decl-updated-guidance/. The guidance is aimed primarily at the biggest UK-headquartered banks and building societies but is also likely to be relevant to a much wider group of preparers. ↩
-
The 2018 Corporate Governance Code (the Code) was updated and published on 22 January 2024 following a consultation which concentrated on a limited number of changes. The 2024 Code can be found on the website of the UK Financial Reporting Council (FRC) here https://www.frc.org.uk/library/standards-codes-policy/corporate-governance/uk-corporate-governance-code/. The updated code has applied since 1 January 2025, with Provision 29 becoming applicable from 1 January 2026. Section 4 of the Code covers Audit, risk and internal control. ↩
-
See https://www.bankofengland.co.uk/prudential-regulation/regulatory-reporting/regulatory-reporting-insurance-sector ↩
-
https://www.investopedia.com/terms/s/solvency-capital-requirement.asp. The EU Solvency II directive designates three pillars or tiers for capital requirements. Pillar I covers the quantitative requirements; that is, the amount of capital an insurer should hold. Pillar II establishes requirements for the governance, effective supervision, and risk management of insurance companies. Pillar III details disclosure and transparency requirements. Solvency Capital Requirements (SCR) are critical to maintaining the financial stability of insurance and reinsurance companies within the EU. As a result, insurance companies are required to manage and disclose risks accurately, fostering reliability and trust in the sector. ↩
-
In the UK, the EU Solvency II regime was adapted by the PRA’s 2024 reforms and the phased implementation of ‘Solvency UK’ was completed on 31 December 2024, following the UK’s departure from the EU. Solvency UK is referenced except when referring to financial metrics, when Solvency II is referred to in line with the current PRA guidance and consistent with the prudential regime in the PRA policy manual. Solvency UK was designed to make the UK insurance market more competitive, dynamic, and capable of supporting domestic investment, while still ensuring financial stability and policyholder security under the PRA objectives. See https://www.pwc.co.uk/financial-services/assets/pdf/pra-finalises-new-solvency-uk-framework.pdf ↩
-
IAS 1 Presentation of Financial Statements (paragraphs 134–136) ↩
-
See HSBC Pillar 3 disclosures at 31 December 2025. ↩
-
The Solvency and Financial Condition Report (‘SFCR’) is a regulatory report required by the Reporting and Group parts of the Prudential Regulation Authority (‘PRA’) Rulebook. This report, including the accompanying Quantitative Reporting Templates (‘QRTs’), sets out aspects of a Group’s business and performance, system of governance, risk profile, valuation methods used for solvency purposes and capital management. ↩
-
OCG and TCG are defined in Standard Life’s 2025 Annual Report – see Glossary on pages 351 and 353. Operating Cash Generation (‘OCG’) is the emergence of cash as in-force business runs off over time and capital unwinds, plus day one surplus from writing new business (net of day 1 strain for fee-based business) plus group tax relief, plus the recurring management actions and the capitalised benefit from delivery of our cost savings programme. As a cash measure it is reported as the excess of their Board approved capital according to their CMPs. Cumulative OCG, being OCG over the 3-year LTIP performance period, is included in the 2025 and 2026 LTIP grant. On page 15 of its Strategic Report, says “Operating Cash Generation (‘OCG’) continues to be the metric which best demonstrates the long-term underlying value generation from our business” and is mentioned 42 times in that report. Segmental information on OCG is provided in note 3 to the financial statements (p339) and also in the APM section (p344-345). Total cash generation (‘TCG’) is cash remitted by the Group’s operating companies to the Group’s holding companies. No mention of TCG is made in the annual report, other than in the glossary. ↩
-
See Section 2.3 Management-defined performance measures (pages 20–23) of Effects Analysis–IFRS 18 Presentation and Disclosure in Financial Statements published by the IFRS Foundation in April 2024 ↩
-
The reporting of encumbered assets is mandatory for all banks and is included in the Pillar 3 report. See https://www.bankofengland.co.uk/-/media/boe/files/prudential-regulation/regulatory-reporting/banking/finrep-asset-encumbrance-instructions.pdf and https://handbook.fca.org.uk/technical-standards/provision/s54c474sn0p722 ↩
-