Project Initiation Plan - Exposure Draft - Amendments to IFRS 19
| Project Type | Influencing |
|---|---|
| Project Scope | Limited scope |
Purpose
1This paper sets out the plan to influence the forthcoming proposals for amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures to be set out in the catch-up Exposure Draft (the 'catch-up ED'), expected to be published by the IASB during late July 2024.
Background
2The IASB issued IFRS 19 Subsidiaries without Public Accountability: Disclosures1 in May 2024. The standard responds to stakeholders' feedback (mainly from preparers) to permit eligible subsidiaries to apply IFRS Accounting Standards with reduced disclosure requirements (a reduced disclosure framework) – those with a parent that applies IFRS Accounting Standards for its consolidated financial statements.
3In developing the reduced disclosure requirements in IFRS 19, the IASB considered the disclosure requirements in IFRS Accounting Standards issued before 28 February 2021.
4As an interim measure, disclosure requirements in new or amended IFRS Accounting Standards issued or exposed between 28 February 2021 and May 2024 were incorporated in IFRS 19 without reductions because the IASB did not consult on reducing these disclosures when developing IFRS 19. The catch-up ED will therefore consult on reducing these disclosures, applying the principles2 that the IASB used in developing IFRS 19.
5In future, each new or amended IFRS Accounting Standard will include consequential amendments to IFRS 19. This will ensure that IFRS 19 remains up-to-date and eligible subsidiaries have reduced disclosure requirements available to them by the time they are required to apply a new or amended IFRS Accounting Standard.
Forthcoming Catch-up ED proposals
6The IASB expects to issue the catch-up ED for this project during July 2024.
7From February to April 2024, the IASB has taken tentative decisions which suggest that the catch-up ED will include the following proposals:
- Supplier Finance Arrangements - it will remove the disclosure objective related to supplier finance (paragraph 167 of IFRS 19), consistent with the IASB's decision not to include disclosure objectives in IFRS 19 and will add the characteristics of supplier finance arrangements.
- International Tax Reform—Pillar Two Model Rules - it will remove the reference to a disclosure objective (paragraph 199 of IFRS 19) and will redraft the disclosure requirement related to an entity's exposure to Pillar Two income taxes.
- Lack of Exchangeability - it will remove the disclosure objective (paragraph 221 of IFRS 19) and disclosure guidance (paragraph 222 of IFRS 19) in relation to the impact of lack of exchangeability on an entity's financial statements.
- IFRS 18 Presentation and Disclosure in Financial Statements - it will replace the disclosure requirements in IFRS 19 relating to management-defined performance measures with a reference to those requirements in IFRS 18 and remove the disclosure objective (paragraph 137 of IFRS 19) from a disclosure requirement relating to non-current liabilities.
8Amendments to the Classification and Measurement of Financial Instruments (Amendments to IFRS 9 and IFRS 7) - the amendments were issued in May 2024 and included consequential amendments to IFRS 19 in relation to the disclosure requirements related to changes in contractual cash flows. These disclosure requirements were included in full in IFRS 19 and the catch-up ED is expected to include a question to seek views on the IASB's tentative decision not to propose any changes to these consequential amendments.
9Forthcoming IFRS Accounting Standard Regulatory Assets and Regulatory Liabilities (RARL standard) – the catch-up ED will seek views on the IASB’s tentative decision not to develop reduced disclosures at this stage.
Project plan rationale
10The following considerations have shaped the project plan.
The objective of the project is to make narrow-scope amendments to IFRS 19
11The objective of the catch-up ED is to reduce the disclosure requirements in new or amended IFRS Accounting Standards issued or exposed between 28 February 2021 and May 2024. As such, the catch-up ED is expected to propose few reductions in the disclosure requirements for the new and amended IFRS Accounting Standards within the scope of the project i.e., mainly removing the disclosure objectives.
12The Amendments are therefore expected to be narrow in scope with no significant reductions to the current disclosure requirements in IFRS 19.
13IFRS 19 is not yet part of UK-adopted IAS. Therefore, the catch-up ED will not change current practice in the UK until the standard is adopted for use in the UK.
Initial stakeholder feedback did not express significant concerns with the catch-up ED proposals
14The UKEB will need to assess whether the catch-up ED proposals achieve the objective of IFRS 19, in terms of cost savings for preparers (i.e., the disclosures are proportionate) whilst at the same time maintaining the usefulness of eligible subsidiaries' financial statements for users.
15Initial indications are that stakeholders do not have significant concerns with the catch-up ED proposals. At their June 2024 meetings, the Investor Advisory Group (IAG) and the Preparer Advisory Group (PAG) considered the five topics (paragraphs 7-8 above)3.
16IAG members indicated that they focus on the group accounts for the purpose of their analysis and only consider subsidiaries' financial statements on an exceptional basis, if they identify issues in the group accounts that require further analysis.
17PAG members indicated that UK Financial Reporting Standard 101 Reduced Disclosure Framework (FRS 101) is widely used in the UK. Some members considered that, companies currently using FRS 101 are unlikely to switch to IFRS 19 as the relevant subsidiaries are already providing reduced disclosures whilst complying with IFRS recognition and measurement requirements. In addition, systems are already designed to provide disclosures required by FRS 101. Therefore, for those subsidiaries the cost of transition from FRS 101 to IFRS 19 could be
18significant. Members also recognised that those groups with significant overseas subsidiaries would likely find an international standard on reduced disclosure helpful as it would help reduce cost by aligning all subsidiaries' reporting and reducing the disclosures for countries where no existing reduced disclosure frameworks are in place. Overall, PAG members were supportive of the adoption of IFRS 19 in the UK as an option available to eligible subsidiaries that conclude the benefits outweigh the costs.
Setting up an ad-hoc advisory group is not necessary
19Given the scope and nature of the project, it is not considered necessary to set up a separate, ad-hoc advisory group. The existing UKEB Advisory Groups are well placed to provide feedback on this project.
Project milestones
20A proportionate approach is proposed, incorporating mandatory milestones listed in paragraph 5.3 of the UKEB's Due Process Handbook (Handbook). The table below provides a brief description of the work we have done and that we intend to do as part of this project.
21Future dates are based on current expectations and are, therefore, subject to subsequent modification. The Board will be alerted to any significant changes.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30(b)i] | Added to UKEB technical work plan. | Completed. |
| Education session on IASB proposals in catch-up ED (optional) [Handbook 4.10(b)] | Not proposed in light of UKEB's influencing work on the ED on IFRS 19. However, updates on the catch-up ED were included in the agenda papers as part of the IASB General Updates for UKEB October and December 2023 and, February, March, April, and May 2024 Board meetings for noting. | Not applicable. |
| Desk-based research (optional) [Handbook 5.9] | The Secretariat has begun its programme of desk-based research, which comprises mainly a detailed review of IASB staff papers and the catch-up ED when published. To facilitate discussion with advisory group members and external stakeholders, we have developed detailed illustrative analyses of the disclosures that the catch-up ED is expected to propose removing from and adding to IFRS 19, including the IASB's rationale for doing so. | In progress. |
| Outreach activities (mandatory) [Handbook 5.10-5.12] | The Secretariat has already engaged with IAG and PAG at their June 2024 meetings. In addition, we plan to engage with the Rate-regulated Activities Technical Advisory Group (RRA TAG), the Accounting Firms & Institutes Advisory Group (AFIAG) at their upcoming meetings during June and July 2024. Additionally, we plan to undertake limited targeted outreach with potentially affected stakeholders, mainly preparers and users. The DCL will be published for stakeholder comment on the UKEB website. Outreach with users and preparers will continue whilst the DCL is out for comment. The Secretariat plans to promote our outreach activities and the DCL via the UKEB Advisory Groups and via the usual channels (LinkedIn, News Alerts to subscribers, UKEB/FRC website) to encourage responses. | In progress. |
| Project Initiation Plan (PIP) (mandatory) [Handbook 5.4 to 5.8] | This paper. | - |
| Draft comment letter (DCL) published for comment (generally mandatory) [Handbook paragraphs 5.13 to 5.17] | The Secretariat will publish the approved DCL for public comment for 45 days following the 19 September 2024 Board meeting. The exact duration of the comment period will be finalised following that Board meeting. | As soon as possible after the 19 September 2024 Board meeting. |
| UKEB submits final comment letter (FCL) to the IASB (mandatory) [Handbook paragraph 5.18] | The IASB comment period is expected to close at the end of November 2024. The Secretariat will submit the FCL to the IASB as soon as possible following approval at the 28 November 2024 UKEB meeting. This will result in late submission of the FCL to the IASB by a few days. | As soon as possible after the November 2024 Board meeting. |
| Feedback statement and due process compliance statement for influencing stage of project (mandatory) [Handbook 5.19 to 5.26] | Secretariat publishes Feedback Statement and Due Process Compliance Statement on the UKEB website. | To be completed. |
Resources allocated
22Based on this project plan, we consider a project team consisting of one Project Manager and one Assistant Project Manager with technical support and oversight from a Senior Project Director, should ensure the project milestones are achievable. Communications support will be obtained as appropriate.
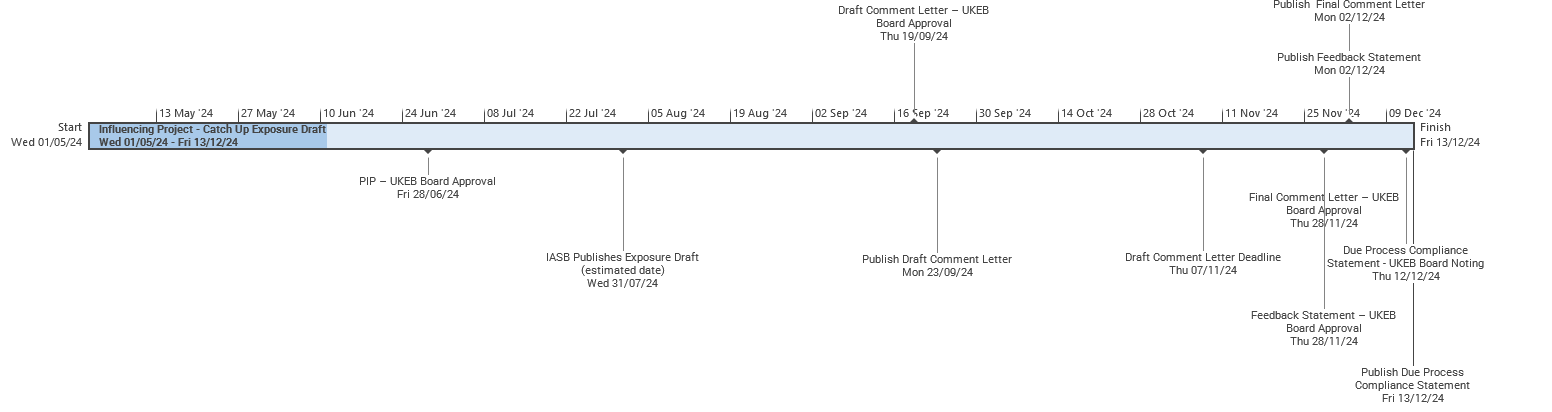
Detailed project timeline
| Expected Dates | Milestone |
|---|---|
| February to June 2024 | Preliminary analysis and outreach before publication of the catch-up ED. |
| 28 June 2024 | Board: Discusses and approves Project Initiation Plan (PIP). |
| June/July 2024 | Secretariat: Outreach with UKEB advisory groups. |
| Late July 2024 (expected) | IASB: Publishes catch-up ED with a 120-day comment period. |
| 19 September 2024 | Board: Consideration and approval of DCL. |
| 23 September 2024 (estimate) | Secretariat: Alerts key stakeholders to publication of DCL. |
| 23 September to 7 November 2024 | 45-day comment period for DCL. |
| 28 November 2024 | Board: Discusses and approves Final Comment Letter (FCL), Feedback Statement and draft Due Process Compliance Statement. |
| As soon as possible after Board discussion | Secretariat: Submits FCL to IASB and publishes FCL on website. |
| 12 December 2024 | Board: Notes completed Due Process Compliance Statement. |
Footnotes
-
Refer to IASB's news alert on the publication of IFRS 19 published in May 2024. ↩
-
These principles identify information users of financial statements of companies without public accountability are particularly interested in and include: i) liquidity and solvency; ii) short-term cash flows, obligations, commitments, and contingencies; iii) measurement uncertainty; iv) disaggregation of amounts; v) and accounting policy choices. ↩
-
At the time of writing, the Secretariat also plans to discuss the catch-up ED i.e., the proposal in paragraph 9 with the Rate-regulated Activities Technical Advisory Group (RRA TAG) on 27 June 2024 and the proposals in paragraphs 7-8 with the Accounting Firms and Institutes Advisory Group (AFIAG) on 1 July 2024. ↩