Updated Project Initiation Plan - Intangibles Project (October 2022)
As amended at 20 October 2022 UKEB Board Meeting
Overview
1 The UKEB delegated functions include responsibility for “participating in and contributing to the development of a single set of international accounting standards." Undertaking pro-active thought leadership activities is key to the UKEB's ability to effectively deliver this statutory function.
2 The UKEB's Terms of Reference (ToR) further explain that with regard to thought leadership, the UKEB shall:
- Lead the UK debate on international accounting standards and reporting.
- Represent UK views in international fora with the aim of influencing debate.
- Engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
- Proactively participate in the development of new global accounting standards, for example by undertaking research.
3 We believe that a project on intangibles, as described below, clearly supports the UKEB meeting these responsibilities.
4 The increasing importance of intangibles to the modern economy is ubiquitously acknowledged, as demonstrated by the numerous academic papers1 and books2 written on this topic. As noted by CPA Ontario “Today, intangible assets are recognized as the key source of innovation and growth, an economic golden goose"3.
5 At the same time there is significant discussion about the shortfalls of IFRS Standards4 in relation to accounting for intangibles. EFRAG has published a comprehensive report, outlining a range of concerns with current accounting for intangible assets and possible approaches to improving their reporting.5
6 Concerns about the accounting for and reporting of intangibles are not only confined to academic discussions and national standard setters. Steve Cooper, an independent analyst, co-author of The Footnotes Analyst blog, and former IASB Board Member, has stated that, “the current inconsistent and limited recognition of intangible assets causes analytical challenges for investors... We think that investors would greatly benefit from improvements to both the narrative reporting and financial statement data regarding intangibles."6
7 These concerns have been echoed in surveys of users. For example:
- In 2019 the FRC published a consultation “Business Reporting of Intangibles: Realistic Proposals”7. They noted when reporting the feedback received from UK investors that they “were unanimous in their support for improving the quality of reporting on intangibles” 8
- Research currently being funded by ICAS has noted that 93% of users surveyed thought that "financial reporting is lacking adequate information on intangible assets”, though they also note that this view was only shared by 61% of preparers surveyed.9
- A worldwide survey of 170 senior investment decision makers commissioned by Columbia Threadneedle Investments concluded that, “There is agreement that analysis of intangibles provides a competitive advantage to investors, and recognition that intangible research is increasingly important in analytical work. However, while investors find information about intangibles readily available, they believe that it is often unreliable, incomplete or inaccurate.”10
8 The IASB has acknowledged these concerns about intangibles. In one of his first public statements the new chair of the IASB, Dr Andreas Barckow, stated that "the rise of self-generated intellectual property and its non-addressal in the accounts" was one of the biggest challenges and opportunities facing the IASB.11
9 Staff papers presented to the IASB summarising the feedback it received on its Third Agenda Consultation12 indicated that most respondents rated intangible assets as a high priority area. 13 Respondents believed any review should:
- modernise IAS 38 Intangible Assets, to better reflect the ever-increasing importance of intangible assets in today's business models, particularly for unrecognised internally generated assets;
- address new types of intangible assets, which were not envisaged when IAS 38 was developed (such as cryptocurrencies and emission rights) to ensure it results in useful information to users of financial statements; and
- improve comparability between companies that grow organically and those that grow through acquisitions.
10 Based on that feedback we expect intangibles to form a key part of the IASB's agenda for the next five-year period.
11 A pro-active thought leadership project on intangibles will enable the UKEB to fulfil its responsibility to proactively participate in the development of high-quality accounting standards by leading the UK debate on accounting and reporting of intangibles as well as contributing to and actively participating in the international debate on a timely basis.
Objective of the project
12 Given the significance of intangibles to the UK and global economies in the twenty-first century, and the expectation that a project on accounting for such items will form a key part of the IASB's agenda in the future, it is important that the UKEB pro-actively contributes to this significant area of standard development.
13 "Intangibles” encompasses a wide range of possible topics and avenues for research. The UKEB believes that it is well placed to focus on elements of investor needs when it comes to accounting and reporting of intangibles. This will act as a useful starting point for, and input into, the accounting solutions to be devised by the IASB.
14 The context for the research is:
How could the accounting for, and reporting of, Intangible Items be improved to provide investors with more useful general purpose financial statements to assist them to make better informed decisions?
15 Key elements of this context are:
- Accounting and reporting14: The context for any research will be accounting and reporting in accordance with IFRS Accounting Standards, and the annual financial statements. Specifically, the research will consider elements of classification, recognition, measurement, and disclosure of intangible items. This does not necessarily mean that the current approach of the IFRS Accounting Standards should constrain possible solutions. It may be that new or expanded standards need to be developed to capture useful information.
- Intangible Items: This term is a placeholder for a broad range of non-physical items that are not within the scope of IFRS 9: Financial Instruments, and is not necessarily intended to be the same as defined in IAS 38: Intangible Assets. Part of the research would seek to identify what investors consider the most relevant intangible items, and whether current definitions adequately capture the extent and nature of these items.
- Investors: The Conceptual Framework for Financial Reporting15 identifies the primary users of financial reports as existing and potential investors, lenders and other creditors that cannot require reporting entities to provide information directly to them. We believe that a focus on investors who rely on General Purpose Financial Statements (GPFS) will provide useful information while helping limit the extent of research that will need to be undertaken. These users make key decisions that involve buying, selling or holding equity instruments; or exercising rights to vote on, or otherwise influence, management's actions that affect the use of the entity's economic resources.
16 Within this context we will focus on exploring with investors the areas they see as deficient in the current reporting for intangible items under IFRS Accounting Standards and possible solutions that they believe would address these concerns. This will include examining current reporting practices for intangibles in the UK.
17 The research could be extended later to engage with investors to explore new ways of thinking about the issue of accounting for and reporting on intangibles. A pre-requisite for this would be to consider with other stakeholders, such as academics and preparers (especially in sectors that have intangible items identified as particularly relevant by investors) possible alternative approaches that may not have been considered and which could meet investors' information needs. We would want to facilitate discussions between key stakeholders to develop solutions.
18 The research would be based on a bottom-up or inductive approach. In the initial phase, research would build from investors' needs and observations of practice to develop proposals. This can be contrasted with the top-down or deductive approach that would start with the conceptual framework and develop solutions rooted in accounting theory.
19 This approach will allow us to contribute to and reflect on the work being done by others in this area, such as EFRAG and the AASB. By building on our links with investors we believe we will be able to provide an important perspective on any solutions proposed by others.
20 It will also build on previous work in the UK by the FRC, for example, the FRC's 2019 consultation "Business Reporting of Intangibles: Realistic Proposals”.
Key planning assumptions, constraints and timeline
Project timeline and resource capacity
21 As noted below this project is split into two phases, each with a number of milestones, and an overall expected duration of up to 3 years. The immediate focus is on understanding the reporting landscape for intangible assets in the UK and investors' views. Later work could extend this research into developing more comprehensive proposals to address those findings.
22 This timeline would fit into the IASB's expected review of intangible assets, that is likely to be a long-term project commencing later in 2023. Therefore, we believe that the first phase of research could feed into the IASB's preliminary thinking by describing current reporting practice and investors' concerns. The second phase of the research could feed directly into an IASB project on Intangibles in 2024 or 2025.
23 We currently expect that the project would require input from the following technical staff:
- 40-50% of one accounting specialist project director on a consistent basis;
- up to 40% of a member of the economics team at various stages to support specific outputs; and
- 25% of a project manager on a consistent basis to support the project.
24 Production of regular outputs is important to retaining interest and momentum in the project over its lifetime, and is factored into the resource allocation. For example, one early output proposed is a paper addressing questions asked in EFRAG's Discussion Paper: Better Reporting on Intangibles. This will require significant activity in the first half of 2022.
25 It is also important to acknowledge that additional research opportunities and outputs could be identified or emerge while the project is underway. Any significant changes to the research outputs or timetable will be presented to the Board.
Assumptions
26 Once established, the UKEB's user and academic advisory groups will form a key part of any outreach. We may also be able to utilise the IASB's Investor contacts, along with the knowledge of our liaison IASB Board Member.
27 We do not plan on setting up an ad hoc external group at this point in time. However, a sub-group of UKEB Board members to provide ongoing advice would be useful. We believe a group of three or four Board members, including an investor and academic representative would be appropriate. They would be regularly consulted and appraised of progress on the project and would provide an important link back to the Board.
28 We will look to academics to support the research, in particular during Phase Two, to help identify alternative approaches to addressing the accounting for intangible assets. As noted, a future academic advisory group will play a key role in supporting engagement with academics. We would also look to bring academics and users together as part of some of the outputs discussed below and may consider commissioning empirical research, if appropriate.
29 It is expected that a number of the activities to be undertaken as part of this project will have synergistic opportunities to collaborate with and contribute to other UKEB projects. For example, there is overlap with the Goodwill and Impairment research currently being undertaken. We will actively look for ways to incorporate cross-sectional thinking and help ensure maximum impact for this thought leadership project.
30 We also see this project as an opportunity to engage with other NSS and international stakeholders (including the IASB). We will actively look to collaborate with others to enhance the research activities being undertaken and increase the impact of the work being done. Some of these opportunities are noted below, others will emerge over time.
Risks
31 Traditionally, it has been difficult to engage with investors. Though provision of information to investors is the focus of accounting information, the time scales involved in development of accounting standards makes it difficult to engage with this key stakeholder group as they are more focussed on what they are seeing today in financial statements.
32 Maintaining the momentum, consistency and quality of the project over a long period of time can be difficult. We intend to mitigate this by allocating a lead project director to the project with responsibility for coordinating the ongoing involvement of other members of the team at appropriate junctures.
33 The IASB's specific plans regarding the scope and timing of the intangibles project may not be known for some time. We are planning on the assumption we will be able to contribute to the early stages of the project. The UKEB project timelines and milestones will need to remain flexible in order to respond to developments at the IASB to ensure the UKEB outputs are timely and have maximum impact on the activities of the IASB.
Outputs
34 The research project is currently framed around two phases. Subsequent outputs are expected to build on preceding ones. Phase two would be subject to a review of the preceding research, and any expectations around the timing and nature of the IASB's plans with regards to Intangible Assets. This would be an opportunity to develop additional or alternative outputs.
35 The phase one outputs focus on evidence gathering, assisting the UKEB to understand the current state of reporting on intangibles in the UK through a review of the existing academic literature, considering the economic indicators and understanding stakeholder views on the extant accounting for Intangibles. Phase two will focus on the development of preliminary/final Board views. The nature and timing of the research will be affected by the IASB's plans with regards to Intangible Items.16
Phase One
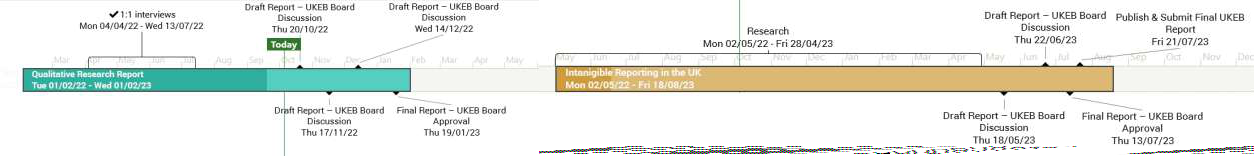
Major Output 1 - Qualitative Research Report: UK Stakeholder Views on Accounting for Intangibles {: #major-output-1-qualitative-research-report } (Q1 2022 – Q1 2023)
36 In 2022 we will develop a research paper drawing primarily on qualitative research based on in-depth interviews with a range of stakeholders, supported by a review of key literature. The research is explorative by design. It will provide a better understanding of UK stakeholders' perspectives on the accounting for, and reporting of, Intangibles in the UK, and the economic outcomes arising from the existing accounting framework.17
37 The work will be based primarily on qualitative research involving gathering feedback from a range of interested stakeholders. This is expected to include both detailed discussions with interested individuals and broader survey type research. However, we also expect it to be informed by the initial qualitative work being undertaken as part of output 3 discussed below.
38 The IASB have requested that the UKEB contribute to their research on making material judgements18. This project provides an ideal opportunity to contribute the views of UK stakeholders and there is a clear link between the accounting for intangible items and the role of materiality. By their nature intangibles necessitate greater consideration of qualitative factors when assessing their materiality. We have explored this issue with stakeholders in interviews and the IASB has already expressed interest in seeing our findings.19
39 We will seek to work with EFRAG on some outreach with stakeholders, including investors. For example, we are considering joint roundtables on specific elements of the EFRAG report.
40 We expect to discuss a draft report on the outreach with the Board in Q4 2022, with Board approval of the final report in January 2023. This is a research study that summarises the input received from a qualitative study ([Draft] Due Process Handbook, paragraph 7.11(e)). The report will summarise the feedback received as a result of the outreach undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.20
Major Output 2 – Analysis of Intangible Reporting in the UK {: #major-output-2-analysis-of-intangible-reporting-in-the-uk } (Q1 2022 —H2 2023)21
41 In parallel with the other major outputs we would also undertake an analysis of the reporting of intangible items in the annual financial statements of UK companies.
42 To better understand the current reporting on intangible items we will undertake a review of the nature and extent of current reporting in the UK. An analysis of current practices among listed UK companies using IFRS standards would allow examination of the accounting for intangibles (including capitalisation and expensing), along with associated disclosures. The analysis may also gather data that is useful for other projects being undertaken by the UKEB, including on goodwill and impairment.
43 This may also be an opportunity to engage with UK academics to support and enhance this research, for example by commissioning targeted empirical analysis. The UKEB may consider funding research through a competitive grant process to encourage and support appropriate research.
44 A multi-functional Secretariat team – including economist, academic and accounting technical – is likely to be needed for this work given the need to gather quantitative information which would then require comprehensive analysis.
45 We intend to publish a report in H2 2023 that summarises the findings of the research. This is a research study that summarises the input received from a quantitative study (Draft Due Process Handbook, paragraph 7.11(e)). The report will summarise the research findings as a result of the research undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.22
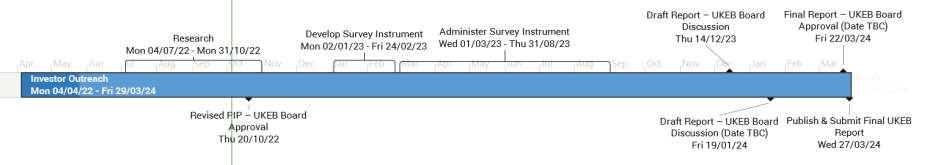
Major Output 3 - Investor Outreach {: #major-output-3-investor-outreach } (Q1 2022 - Q1 2024)
46 In 2022 a key focus will be engaging with investors to better understand their perspectives on the reporting of intangibles in the financial statements. This will take the form of a range of outreach activities including developing and administering an investor survey.
47 The focus of the outreach will be on understanding investors' information needs and practices. It will seek to examine:
- the intangibles investors consider as most important to their decision making;
- how well their information needs about intangibles are currently served; and
- investor views on the opportunities for improvement to the accounting for, and reporting of, intangibles in general purpose financial statements.
- some additional questions relevant to other UKEB projects that overlap with this work.
48 The survey development and analysis will be supported by the UKEB economics team and we will also explore opportunities to work with the FRC Financial Reporting Lab. We will also engage with the Academic Advisory Group and the Investor Advisory Group to advise on the survey instrument and engagement with users.23
49 We will take a proactive approach to engaging with investors in the UK as we consider this a great opportunity to build connections with them.
50 We plan to publish a report summarising the key findings from the outreach in early 2024. This is a research study that summarises the input received from a survey based study (Draft Due Process Handbook, paragraph 7.11(e)). The report will summarise the feedback received as a result of the survey undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.24
Phase Two
51 Phase Two would be subject to a new PIP to be presented to the Board in mid-2023. It is expected that additional outputs would be proposed, particularly in 2024 that would support the ongoing project, and any IASB activity in this area.
52 We also plan to engage directly with other National Standard Setters including EFRAG and the Australian Accounting Standards Board who are also planning to undertake extended research projects on the accounting for intangibles. This may provide the opportunity to develop collaborative research proposals.
53 Phase two research will build on the research studies undertaken as part of phase one of this research project. It is expected that some phase two outputs would include Board views, and therefore would include Invitation(s) to Comment.25
Other Minor Outputs
54 In addition to the primary outputs highlighted above, we expect to publish other minor outputs that utilise work already being undertaken. These will be of varying degrees of formality and size and will be intended to publicise and maintain interest in the research work. Examples could include:
- Short articles on the UKEB Website and in other media.
- Podcasts and videos highlighting aspects of research undertaken.
- Regular short posts on UKEB social media.
- Hosting and/or co-hosting topic specific events with a range of stakeholders.
- Participation in events run by others in both the academic and user communities.
- Contributions to research being undertaken by other National Standards Setters.
- Supporting and contributing to a special issue in an Academic Journal.
55 These outputs would be expected to involve to varying degrees both the Secretariat and UKEB Board members. We will continue to explore other opportunities to collaborate with interested parties. We are aware of a number of organisations that are currently undertaking research, or considering undertaking research, in this area. In addition to the NSS activities already discussed, work being undertaken by Professional Bodies and others will also be relevant avenues for collaboration.
Project closure
56 Each output will comply with the expected due process requirements appropriate to the nature of the output.
Project timeline
57 The proposed high-level project timeline is as follows (a graphical representation is included on the next page). Note that dates are indicative only, and subject to revision as the project develops26:
| Date | Milestones |
|---|---|
| 2022 | |
| PHASE 1 | |
| January | Project Initiation Plan |
| February | Commence Output 1 – Qualitative Research Report |
| Commence Output 3 - Investor Outreach | |
| March | Commence Output 2 - Analysis of Intangible Reporting in the UK |
| 2023 | |
| PHASE 1 - Cont. | |
| Jan Board | Approve Final Report – Output 1 |
| Q3 Board | Approve Final Paper – Output 2 |
| Q3 Board | Phase 2 Project Initiation Plan |
| 2024 | |
| PHASE 1 - Cont. | |
| Q1 Board | Approve Final Report – Output 3 |
Annex A
Work being undertaken by others
National Standard Setters
1 The Australian Accounting Standards Board (AASB) is looking at the current requirements of IAS 38, with a focus on improved disclosure27.
2 Given the focus of this research is on current requirements of IFRS Standards, and restricted to IAS 38, we expect limited overlap in any research project undertaken by the UKEB. While some of their findings may help inform our thinking, we expect to look much more widely at the issue.
3 EFRAG is undertaking a much larger project termed “Better Information on Intangibles”28. It has published a 70-page Discussion Paper outlining current issues and possible avenues for improvements of measurement and disclosure of intangible assets. The paper notes that the value relevance of financial statements is decreasing, which could be due to missing information about intangible assets. It considers three approaches for better information on intangibles:
- Recognition and measurement in the primary financial statements;
- Information on specific intangibles in the notes to the financial statements or in the management report; and
- Information on future-oriented expenses and risk/opportunity factors that may affect future performance in the notes to the financial statements or in the management report.
4 The scope of EFRAG's discussions goes beyond the existing definition of assets in financial reporting and also covers sources of possible economic benefits that would not be controlled by an entity.
5 The work being undertaken by EFRAG is likely to be directly relevant to any UKEB research project. Given their focus on better information on intangibles it would be expected that this work may help inform proposals for alternative accounting presented to stakeholders for discussion.
6 We will also be able to utilise some of the background work EFRAG have already undertaken, such as their literature review.
Academic and other research
7 There are a significant number of research papers looking at intangible assets. Presented here is a sample of a few of the studies that will contribute to this research project.
- Amir Amel-Zadeh, Martin Glaum & Thorsten Sellhorn (2021): Empirical Goodwill Research: Insights, Issues, and Implications for Standard Setting and Future Research, European Accounting Review. This paper reviews the empirical literature on the determinants and decision usefulness of goodwill reporting.
- Barker, Richard & Lennard, Andrew & Penman, Stephen & Teixeira, Alan. (2021). Accounting for intangible assets: suggested solutions. Accounting and Business Research. 1-30. 10.1080/00014788.2021.1938963. Drawing on relevant research, we evaluate solutions for intangible asset accounting that contrast with balance sheet recognition, and we compare these with current practice under IFRS.
- Chalmers, Keryn & Clinch, Greg & Godfrey, Jayne & Wei, Zi. (2010). Intangible Assets, IFRS, and Analysts' Earnings Forecasts. Accounting and Finance. 52. 10.1111/j.1467-629X.2011.00424.x. We investigate whether the adoption of IFRS in 2005 by Australian firms has been associated with a loss of potentially useful information about intangible assets.
- CPA Ontario (2021). You can't touch this: The intangible assets debate.
- EFRAG (2020). A Literature Review on the Reporting of Intangibles.
- Financial Reporting Council (2019). Business Reporting of Intangibles: Realistic Proposals.
- Financial Reporting Council (2021). Feedback Statement: Business Reporting of Intangibles: Realistic Proposals.
- ICAS (forthcoming). The Production and Consumption of Information on Intangibles: An Empirical Investigation of CFOs and Investors
- Nichita, Mirela. (2019). Intangible assets -insights from a literature review. Journal of Accounting and Management Information Systems. 18. 10.24818/jamis.2019.02004. Research Question: How do researchers address the definition, measurement, recognition and potential of intangible assets to generate future economic benefits when a formal structure for reporting them is highly controversial?
- Nwogugu, Michael. (2019). Intangibles Accounting Regulations and the “Global Intangibles Economy”: Belief-Revision, Enforcement Theory and Financial Stability. 10.1057/978-1-137-44704-3_5.
Footnotes
-
See appendix 2 for examples of publications on intangible assets. ↩
-
See for example Haskel and Westlake (2018), “Capitalism without Capital: The Rise of the Intangible Economy" Princeton University Press ↩
-
Ontario CPA Insight (2021), “You Can't Touch This: The Intangible Assets Debate", https://www.cpaontario.ca/intangibles ↩
-
See for example Barker, Richard & Lennard, Andrew & Penman, Stephen & Teixeira, Alan. (2021), "Accounting for intangible assets: suggested solutions”. Accounting and Business Research. ↩
-
EFRAG Discussion Paper: Better Reporting on Intangibles ↩
-
Missing intangible assets distorts return on capital | The Footnotes Analyst ↩
-
00 Intangibles-title 1..2 (frc.org.uk) ↩
-
Feedback-Statement-FINAL.pdf (frc.org.uk), para 6. ↩
-
The production and consumption of information on intangibles: an analysis of some preliminary results | ICAS ↩
-
Intangible Assets, note it is unclear whether this was exclusively in the context of GAAP requirements, though they are similar to IFRS in many ways. ↩
-
IFRS - Meet the new IASB Chair-Andreas Barckow ↩
-
https://www.ifrs.org/projects/work-plan/2020-agenda-consultation/ ↩
-
AP24D: Feedback summary-Potential projects (part 1) (ifrs.org) ↩
-
The remainder of this proposal will use the term "accounting for intangible assets" to include both accounting and reporting. ↩
-
See Chapter 2: Objective, usefulness and limitations of general purpose financial reporting ↩
-
[This paragraph was added in October 2022 to explicitly state the nature of the research in each phase] ↩
-
[Title amended in October 2022 to better reflect nature of research as had previously been agreed with Board] ↩
-
IFRS - IASB call for research on Making Materiality Judgements ↩
-
[Paragraph added in July 2022 to reflect discussion with the IASB] ↩
-
[Paragraph replaced in October 2022 to reflect Board's discussion and subsequent amendments to the [Draft] Due Process Handbook]. ↩
-
[In October 2022 the order of Major Output 2 and 3 were swapped to better reflect the relationship between the outputs and their timing] ↩
-
[Amended in July 2022 to reflect our understanding of the due process at that time. Amended in October 2023 to adjust publication date from early 2023 to H2 2023 and for subsequent amendments to the [Draft] Due Process Handbook]. ↩
-
[Amended in October 2022 to reflect the intended engagement with the Advisory Groups] ↩
-
[Added in July 2022 to reflect our understanding of the due process. Amended in October 2023 to adjust publication date from mid-2023 to early 2024 and for subsequent amendments to the [Draft] Due Process Handbook] ↩
-
[Added in October 2022 to reflect Board's discussion and subsequent amendments to the [Draft] Due Process Handbook]. ↩
-
[In both July and October 2022 the timeline was amended to reflect the proposed changes to the PIP] ↩
-
Intangible Assets: Reducing The Financial Statements Information Gap ↩
-
EFRAG research project on better information on intangibles - EFRAG ↩