Project Initiation Plan - Annual Improvements to IFRS Accounting Standards – Volume 11
Project Type: Influencing Project Scope: Narrow-scope
Purpose
1This paper sets out the plan to influence the International Accounting Standards Board (IASB) in relation to the Annual Improvements to IFRS Accounting Standards—Volume II Exposure Draft (the ED), which was published on 12 September 2023.
Background
2The IASB issues amendments to international accounting standards as part of its continuous effort to maintain and improve IFRS Standards and to support consistent application. Proposals for amendments often arise from questions submitted to the IFRS Interpretations Committee.
3At its February 2023 and May 2023 meetings, the IASB discussed the following eight proposed amendments that are included in the ED of Annual Improvements to IFRS Accounting Standards (Annual Improvements). The IASB’s Due Process Handbook (paragraph 6.10) notes that “Some proposed amendments to IFRS Standards that are sufficiently minor or narrow in scope can be packaged together and exposed in one document even though the amendments are unrelated.”1:
Paragraph 6.11 of the IASB and IFRS Interpretation Committee Due Process Handbook:
"The justification for exposing unrelated improvements in one package is that such amendments are limited to changes that either clarify the wording in an IFRS Standard or correct relatively minor unintended consequences, oversights or conflicts between existing requirements of the Standards.”
4A list of the proposed amendments in the Annual Improvements cycle is provided below, Annex A of this project initiation plan (PIP) provides additional detail2.
- Transaction price (IFRS 9 Financial Instruments)
The IASB was informed of a potential confusion arising from references to 'transaction price' in particular paragraphs of IFRS 9. The term is given a different meaning to that generally used in IFRS 9 when related to some trade receivables.
The proposal is to:
- Revise the wording in paragraph 5.1.3 of IFRS 9; and
- Delete the reference to ‘transaction price' and the associated references to IFRS 15 from Appendix A.
- Derecognition of lease liabilities (IFRS 9)
The IASB staff was informed that there is lack of clarity on lessee accounting for derecognition of a lease liability. The lessee could either recognise a gain or loss in profit or loss applying IFRS 9 or make a corresponding adjustment to the right of use asset applying IFRS 16.
The proposal is to:
- Add a cross-reference to paragraph 3.3.3 of IFRS 9 in paragraph 2.1(b)(ii) of IFRS 9.
- Gain or loss on derecognition (IFRS 7 Financial Instruments: Disclosures)
The IASB was informed about a lack of clarity from an obsolete cross-reference in IFRS 7 that was not removed upon the issuance of IFRS 13.
The proposal is to:
- Replace the reference to paragraph 27A of IFRS 7, which no longer exists, with a reference to paragraphs 72–73 of IFRS 13; and
- Replace the phrase 'inputs that were not based on observable market data' with 'unobservable inputs'.
- Disclosure of deferred difference between fair value and transaction price (Implementation Guidance3 accompanying IFRS 7)
The IASB was informed about an inconsistency that arose from the issuance of IFRS 13 resulting in consequential amendments to a paragraph in IFRS 7 but no corresponding amendments were made to the related paragraph in the implementation guidance.
The proposal is to:
- Propose an amendment to paragraph IG14 to improve its consistency with paragraph 28 of IFRS 7 which it illustrates.
- Introduction and credit risk disclosures (Implementation Guidance3 accompanying IFRS 7)
The IASB was informed of a potential confusion in the implementation guidance accompanying IFRS 7 because an example fails to state that it does not illustrate all the requirements of paragraph to which it relates.
The proposal is to:
- Add a statement that the implementation guidance accompanying IFRS 7 does not illustrate all the requirements in IFRS 7 in paragraph IG1 of IFRS 7; and
- Simplify the wording in paragraph IG20B of IFRS 7.
- Hedge accounting by a first-time adopter (IFRS 1 First-time Adoption of International Financial Reporting Standards)
The IASB was informed about a potential confusion arising from an inconsistency in wording between IFRS 1 and IFRS 9 as first-time adopters can only apply hedge accounting requirements in IFRS 9 rather than IAS 39.
The proposal is to:
- Add cross-references to paragraph 6.4.1 of IFRS 9 in paragraphs B5–B6 of IFRS 1; and
- Determination of a 'de facto agent' (IFRS 10 Consolidated Financial Statements)
The IASB was informed about a potential confusion arising from an inconsistency between two consecutive paragraphs of IFRS 10. The first paragraph indicates the requirement for judgement while the second paragraph has more conclusive language about the determination of a de facto agency relationship.
The proposal is to:
- Clarify the requirements in paragraph B74 of IFRS 10.
- Cost method (IAS 7 Statement of Cash Flows)
The IASB was informed about a potential confusion about a term 'cost method' that was originally defined in IAS 27 but was subsequently removed during the revision of IAS 27. However, no consequential amendment was made to the related reference in IAS 7.
The proposal is to:
- Replace the term 'cost method', which is no longer defined in IFRS Accounting Standards, with 'at cost'.
Scope of this project
6Two of the proposed amendments, 4d) Disclosure of deferred difference between fair value and transaction price and 4e) Introduction and credit risk disclosures, are to Implementation Guidance accompanying IFRS 7 and therefore are not included in the mandatory pronouncements of the IFRS Accounting Standards4.
7There is no impediment to the UKEB influencing all the proposed amendments including those to the Implementation Guidance. However, it should be noted that the proposed amendments to Implementation Guidance would be excluded from any UKEB endorsement and adoption assessment, if they are published by the IASB.
Desk-based research
8Our initial desk-based research suggested no significant concerns related to the proposed amendments. However we considered it appropriate to seek input from stakeholders on the application of the proposed amendments, particularly in the following areas of the ED:
- Transaction price; and
- Derecognition of lease liabilities.
Initial stakeholder feedback
9We have undertaken preliminary outreach and spoken informally to a small number of stakeholders including a regulator. To date, no stakeholder has raised significant concerns with the proposals.
Outreach
10We will discuss the draft comment letter (DCL) with the UKEB Accounting Firms and Institutes Advisory Group (AFIAG) and the Preparer Advisory Group (PAG). We also drew attention of the Financial Instruments Working Group (FIWG) to the ED and asked the FIWG members to contact the project team if they have any feedback.
Project plan rationale
11The following considerations have shaped the project plan.
The proposed amendments do not propose new principles or change existing principles
12The proposed amendments are limited to clarification of the wording in specific IFRS Accounting Standards or corrections of relatively minor unintended consequences, oversights or conflicts between existing requirements5. Therefore the proposed amendments are not expected to introduce any new principles or change existing principles in the IFRS Accounting Standards.
13Two of the proposed amendments touch on areas which have separately been identified in other projects as possibly needing more comprehensive review (included below for reference only). This kind of review would go beyond the scope of Annual Improvements and does not form part of this project:
- Derecognition of lease liabilities (proposed amendments to IFRS 9) Stakeholders raised concerns on the boundary between modification and derecognition in IFRS 96 and IFRS 16 requirements. We note that the IASB has included this topic in the project scope of a pipeline project, Amortised Cost Measurement7.
- Determination of a 'de facto agent' (proposed amendments to IFRS 10) The IASB has identified mixed views8 on the assessment of the de facto agency relationship and its interaction with the assessment of control. However, assessments of de facto control are infrequently needed in the UK9.
Change in practice or a material effect on entities' financial statements is not expected
14Given the proposed amendments are narrow scope in nature and merely clarify wording or correct minor oversights, we do not expect any change in practice or a material effect on entities’ financial statements.
Implication for project plan
15Based on the considerations described in paragraphs 12 to 14, we propose a proportionate project plan that involves public consultation on a draft comment letter and targeted outreach to the AFIAG, PAG and FIWG.
Setting up an ad-hoc advisory group is not necessary
16Given the narrow scope and nature of the project, it is not considered necessary to set up a separate, ad-hoc advisory group as the existing UKEB Advisory Groups are well placed to provide feedback on this project.
Project milestones
17A proportionate approach is proposed, incorporating the mandatory milestones listed in paragraph 5.3 of the UKEB’s Due Process Handbook (Handbook)10. The table below provides a brief description of the work we have done and what we intend to do as part of this project.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Influencing | ||
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30(b)i] | Added to UKEB technical work plan. | Completed. |
| Education session (optional) [Handbook 4.10(b)] | Updates on Annual Improvements were included in the agenda papers for UKEB March 2023 and June 2023 meetings for the Board’s noting. All but one of the final proposals in the ED are consistent with the proposals summarised in the agenda papers. In addition, educational material has been shared with the Board. | Not applicable |
| Desk-based research (optional) [Handbook 5.9] | - The IASB’s work on the ED (mainly staff papers); - The Basis for Conclusions; - Relevant material produced by other parties, including accounting firms; and - IFRS Interpretations Committee Agenda Decisions. |
Completed. |
| Project Initiation Plan (mandatory) [Handbook 5.4 to 5.8] | This paper. | - |
| Outreach activities (mandatory) [Handbook 5.10 to 5.12] | We will seek feedback on this project from the: 1. FIWG in September: Given most of the proposed amendments in the ED are to IFRS 7 and IFRS 9, we drew the FIWG members’ attention to Annual Improvements and asked them to contact the project team if they have any feedback. 2. PAG in October 2023 3. AFIAG in November 2023 In addition, we published a project page on the UKEB website which includes a request for stakeholders to contact the project team if they have feedback. The DCL will be published for stakeholder comment on the UKEB website. The Secretariat will also discuss the DCL with the UKEB Advisory Groups, as appropriate. Besides, we will draw attention to this with UKEB News Alerts and LinkedIn posts. |
To be completed. |
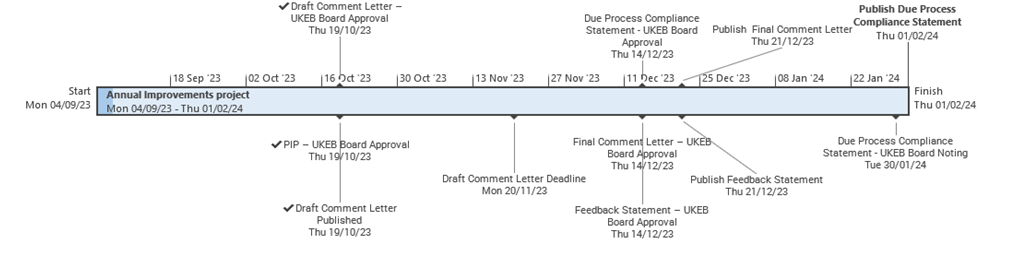
| DCL published for comment (generally mandatory) [Handbook 5.13 to 5.17] | A DCL is prepared for approval at the 19 October 2023 meeting. This will be issued for a consultation period of 30 days. | To take place following the October 2023 meeting |
| UKEB submission of FCL to the IASB (mandatory) [Handbook 5.18] | A final comment letter (FCL) will be presented to the board meeting on 14 December 2023. The FCL will be submitted to the IASB following the Board’s approval. | To be completed |
| Feedback statement and due process compliance statement for influencing stage of project (mandatory) [Handbook 5.19 to 5.26] | The Secretariat publishes Feedback Statement and Due Process Compliance Statement on the UKEB website. | To be completed |
Resources allocated
18On the basis of this project plan, we consider that a project team consisting of one Project Manager supported by one Assistant Project Manager, with technical support and oversight from a Project Director, should ensure the project milestones are achievable.
Project timeline
19The ED was published on 12 September 2023, with the IASB’s comment deadline on 11 December 2023.
20The consultation period for a UKEB’s DCL is generally not less than 30 days unless this period is shortened11. Given the IASB’s comment period ends on 11 December 2023 and the timing of the UKEB’s upcoming meetings, the Board decided to have a 30-day consultation period for the DCL, meaning the final comment letter (FCL) would be submitted to the IASB a week after its submission deadline, subject to approval at the 14 December 2023 Board meeting.
21A FCL will be presented to the Board for consideration and approval at the 14 December 2023 meeting.
22Further information on the proposed project timeline is presented in the table below.
Timeline
| Expected Date | Milestones |
|---|---|
| 19 October 2023 | Presentation of PIP and DCL for approval |
DCL consultation period: 30 days
| 14 December 2023 | Board’s review of comments received on the DCL and consideration of FCL, Feedback Statement and draft Due Process Compliance Statement | | 30 January 2024 | Final Due Process Compliance Statement for the Board’s noting |
Annex A: Summary of the Annual Improvements
1. Amendments to IFRS 9 – Transaction price
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion arising from a reference in Appendix A of IFRS 9 Financial Instruments to the definition of 'transaction price' in IFRS 15 Revenue from Contracts with Customers. The term 'transaction price' is used in particular paragraphs of IFRS 9 with a meaning that is not necessarily consistent with the definition of that term in IFRS 15. |
| Proposed amendments | The proposed amendments to IFRS 9 are to delete the reference to the IFRS 15’s definition of 'transaction price' in Appendix A of IFRS 9 and revise the wording around the term 'transaction price' in paragraph 5.1.3. of IFRS 9. |
| Outcome of the proposed amendments | 5.1 Initial measurement 5.1.1 Except for trade receivables within the scope of paragraph 5.1.3, at initial recognition, an entity shall measure a financial asset or financial liability at its fair value plus or minus, in the case of a financial asset or financial liability not at fair value through profit or loss, transaction costs that are directly attributable to the acquisition or issue of the financial asset or financial liability. 5.1.1A However, if the fair value of the financial asset or financial liability at initial recognition differs from the transaction price, an entity shall apply paragraph B5.1.2A. 5.1.2 When an entity uses settlement date accounting for an asset that is subsequently measured at amortised cost, the asset is recognised initially at its fair value on the trade date (see paragraphs B3.1.3–B3.1.6). 5.1.3 Despite the requirement in paragraph 5.1.1, at initial recognition, an entity shall measure trade receivables at the amount determined by applying |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraph 5.1.3 and Appendix A of IFRS 9 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | Paragraph 5.1.3 was added to IFRS 9 as a result of the issuance of IFRS 15. This resulted in the term 'transaction price' having two different meanings in IFRS 9: (i) “as defined in IFRS 15” (per paragraph 5.1.3 of IFRS 9) and (ii) “as the fair value of the consideration given or received” (elsewhere in IFRS 9). The deletion of the reference to the definition of ‘transaction price' in paragraph 5.1.3 of IFRS 9 is expected to remove potential confusion. |
| Proposed transition requirement | There is no specific transition requirement. |
| Note | The IASB acknowledges a broader issue about the application of the requirements of IFRS 9 to a trade receivable with a significant financing component, however this is beyond the scope of these amendments. Consideration within the scope of Annual Improvements12 The Secretariat performed a word search on the mandatory text of IFRS 9. The term “transaction price” only appears in four different paragraphs (5.1.1A, 5.1.3, B5.1.1 and B5.1.2A) in IFRS 9. When the “transaction price" is mentioned in IFRS 9, it is: - followed by a note as to what the term “transaction price” means (in accordance with IFRS 15 in paragraph 5.1.3 or in accordance with IFRS 13 in paragraphs B5.1.1 and B 5.1.2A); or - directed to another paragraph which has a note about what the term means (paragraph 5.1.1A is directed to paragraph B5.1.2A). In paragraphs B5.1.1 and B5.1.2A, the term “transaction price” is followed by a note “ie the fair value of the consideration given or received, see also IFRS 13”. Considering the scope of Annual Improvements does not include change of existing accounting principle, the Secretariat is of a view that this set of proposed amendments is within the scope and should not raise significant concern. |
2. Amendments to IFRS 9 – Derecognition of lease liabilities
| Header | Content |
|---|---|
| Origin | The IFRS Interpretation Committee received a request about a lessor's and a lessee's application of IFRS 9 Financial Instruments and IFRS 16 Leases when accounting for a rent concession in which the only change to the lease contract is the lessor's forgiveness of lease payments due from the lessee. The Interpretations Committee addressed a lessor's application of IFRS 9 and IFRS 16 in its Agenda Decision Lessor Forgiveness of Lease Payments (IFRS 9 and IFRS 16) published in October 2022. With regard to lessee accounting, there appeared to be more than one way to read the current requirements for a rent concession. |
| Proposed amendments | The proposed amendment to IFRS 9 is to add a cross-reference to paragraph 3.3.3 of IFRS 9 in paragraph 2.1(b)(ii) of IFRS 9. |
| Outcome of the proposed amendments | 2.1 This Standard shall be applied by all entities to all types of financial instruments except: (b) rights and obligations under leases to which IFRS 16 Leases applies. However: (i) finance lease receivables (ie net investments in finance leases) and operating lease receivables recognised by a lessor are subject to the derecognition and impairment requirements of this Standard; (ii) lease liabilities recognised by a lessee are subject to the derecognition requirements in paragraphs |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraph 2.1(b)(ii) of IFRS 9 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | There appears to be more than one way to read the current requirements of lessee accounting for a rent concession. The lessee could either: - recognise the gain or loss in profit or loss applying paragraph 3.3.3 of IFRS 9; or - make a corresponding adjustment to the right-of-use asset recognised applying IFRS 16. The IASB has noted it intended a lessee to apply paragraphs 3.3.1 and 3.3.3 of IFRS 9 in sequence, and the lack of a cross-reference to paragraph 3.3.3 in paragraph 2.1(b)(ii) of IFRS 9 was an oversight. Paragraph 3.3.1 of IFRS 9 provides requirements for derecognition of a financial liability when it is extinguished, and paragraph 3.3.3 of IFRS 9 requires the entities to recognise the gain or loss from lease liability extinguishment in profit or loss. |
| Proposed transition requirement | Prospective application of the amendments is required. That is, an entity would apply the amendment to lease liability extinguishments that occur after the beginning of the annual reporting period in which the entity first applies the amendment. |
| Note | There remains a broader issue regarding the boundary between modification and derecognition of a lease, as well as the requirements for the derecognition of financial assets following a contractual modification13. We note that the IASB pipeline project Amortised Cost Measurement includes this topic in its scope14. Consideration within the scope of Annual Improvements15 Paragraph 3.3.3 is a clear follow-on of the paragraph 3.3.1 in the context of the paragraph 2.1(b)(ii). Given the proposed amendment essentially removes the “option” of adjusting right-of-use asset upon lease liability extinguishment, the Secretariat considered there could be potential unintended consequences to the current application practice. Therefore the Secretariat has done desk-based research including reading accounting firm manuals and started targeted outreach, with a particular focus on the application. To date, no significant concern has been identified. |
3. Amendments to IFRS 7 – Gain or loss on derecognition
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion in paragraph B38 of IFRS 7 Financial Instruments: Disclosures arising from the reference to a paragraph that has been deleted from the IFRS Accounting Standard (paragraph 27A). |
| Proposed amendments | The proposed amendments to IFRS 7 are to replace the reference to paragraph 27A of IFRS 7, a paragraph that no longer exists, with a reference to paragraphs 72–73 of IFRS 13 Fair Value Measurement, and to replace the phrase 'inputs that were not based on observable market data' with ‘unobservable inputs' in paragraph B38 of IFRS 7. |
| Outcome of the proposed amendments | B38 Paragraph 42G(a) requires an entity to disclose the gain or loss on derecognition relating to financial assets in which the entity has continuing involvement. The entity shall disclose if a gain or loss on derecognition arose because the fair values of the components of the previously recognised asset (ie the interest in the asset derecognised and the interest retained by the entity) were different from the fair value of the previously recognised asset as a whole. In that situation, the entity shall also disclose whether the fair value measurements included significant unobservable inputs |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraph B38 of IFRS 7 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | The current reference to paragraph 27A is from an oversight during IFRS 13 issuance in May 2011 when no consequential amendment was made to paragraph B38 of IFRS 7. |
| Proposed transition requirement | There is no specific transition requirement. |
4. Amendments to Implementation Guidance accompanying IFRS 7 – Disclosure of deferred difference between fair value and transaction price
| Header | Content |
|---|---|
| Origin | The IASB was informed about an inconsistency between paragraph 28 of IFRS 7 Financial Instruments: Disclosures and its accompanying implementation guidance, paragraph IG14. The inconsistency arose when, after the issuance of IFRS 13 Fair Value Measurement, the IASB made a consequential amendment to paragraph 28 of IFRS 7 but did not make the corresponding amendments to paragraph IG14 of IFRS 7. |
| Proposed amendments | The proposed amendments to the Implementation Guidance accompanying IFRS 7 are to improve the consistency between paragraph IG14 of IFRS 7 and paragraph 28 of IFRS 7. |
| Outcome of the proposed amendments | The following text is extracted from the ED and reflects the outcome of the amendments. It should be noted that there are also minor editorial amendments to the rest of the illustrative example in paragraph IG 14 of IFRS 9. IG14 Fair value (paragraph 28) At initial recognition an entity measures the fair value of financial instruments that are not traded in active markets. However, when, after initial recognition, an entity will use a valuation technique that incorporates data not obtained from observable markets, there may be a difference between the transaction price at initial recognition and the amount determined at initial recognition using that valuation technique. In some cases, the transaction price of a financial instrument differs from its fair value at initial recognition, and that fair value is neither evidenced by a quoted price in an active market for an identical asset or liability (ie a Level 1 input) nor based on a valuation technique that uses only data from observable markets. In these circumstances, the difference will be recognised in profit or loss in subsequent periods in accordance with IFRS 9 Financial Instruments and the entity’s accounting policy. Such recognition reflects changes in factors (including time) that market participants would take into account when pricing the asset or liability (see paragraph B5.1.2A(b) of IFRS 9). Paragraph 28 requires disclosures in these circumstances. An entity might disclose the following to comply with some of the requirements in paragraph 28: |
| Mandatory or Non-Mandatory | The proposed amendments are to the Implementation Guidance accompanying IFRS 7 and therefore is not part of the mandatory text of the IFRS Accounting Standards and not included in UK-adopted international accounting standards. |
| Rationale for the proposed amendments | The current inconsistency arose when, upon the issuance of IFRS 13 Fair Value Measurement in May 2011, the IASB made a consequential amendment to paragraph 28 of IFRS 7 but made no corresponding amendments to paragraph IG14 of IFRS 7. |
| Proposed transition requirement | The proposed amendments are to the implementation guidance which is not a mandatory section of IFRS accounting standards16. Therefore, there is no need to consider transition. |
5. Amendments to Guidance on implementing IFRS 7 – Introduction and credit risk disclosures
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion in paragraph IG20C accompanying IFRS 7 because that paragraph fails to state that the example does not illustrate all the requirements in paragraph 35M of IFRS 7. |
| Proposed amendments | The proposed amendments to the Implementation Guidance accompanying IFRS 7 are - Paragraph IG 1: to add a statement that implementation guidance accompanying IFRS 7 does not illustrate all the requirements in IFRS 7; and - Paragraph IG20B: to streamline the paragraph by rewording the first sentence and deleting the second sentence. |
| Outcome of the proposed amendments | IG1 This guidance suggests possible ways to apply some of the disclosure requirements in IFRS 7. The guidance does not illustrate all the requirements in IFRS 7, nor does it create additional requirements. IG20B The following example illustrates one way of providing information about the changes in the loss allowance and the significant changes in the gross carrying amount of financial assets, other than financial assets that are purchased or originated credit-impaired, during the period that contributed to changes in the loss allowance as required by paragraphs 35H–35I. |
| Mandatory or Non-Mandatory | The proposed amendments are to the Implementation Guidance accompanying IFRS 7 and therefore is not part of the mandatory text of the IFRS Accounting Standards and not included in UK-adopted international accounting standards. |
| Rationale for the proposed amendments | Paragraph IG20B illustrates application of the requirements in paragraphs 35H–35I of IFRS 7 and states that 'this example does not illustrate the requirements for financial assets that are purchased or originated credit-impaired'. However, paragraph IG20C of IFRS 7 which illustrates the disclosure requirements in paragraphs 35M–35N of IFRS 7 also omits some disclosures required by those paragraphs but does not include any disclaimer. Therefore, the proposed amendments are expected to remove a potential inconsistency between paragraphs IG20B and IG20C. |
| Proposed transition requirement | The proposed amendments are to the implementation guidance which is not a mandatory section of IFRS accounting standards17. Therefore, there is no need to consider transition. |
6. Amendments to IFRS 1 – Hedge accounting by a first-time adopter
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion arising from an inconsistency in wording between paragraph B6 of IFRS 1 First-time Adoption of International Financial Reporting Standards and the requirements for hedge accounting in IFRS 9 Financial Instruments. |
| Proposed amendments | The proposed amendments to IFRS 1 are to: - replace the word 'conditions' with 'qualifying criteria' in paragraph B6 of IFRS 1; - add a cross-reference to paragraph 6.4.1(a) of IFRS 9 in paragraph B5 of IFRS 1; and - add a cross-reference to paragraphs 6.4.1(b)−(c) of IFRS 9 in paragraph B6 of IFRS 1. |
| Outcome of the proposed amendments | B5 An entity shall not reflect in its opening IFRS statement of financial position a hedging relationship of a type that does not qualify for hedge accounting in accordance with IFRS 9 (for example, many hedging relationships where the hedging instrument is a stand-alone written option or a net written option; or where the hedged item is a net position in a cash flow hedge for another risk than foreign currency risk) (see paragraph 6.4.1(a) of IFRS 9). However, if an entity designated a net position as a hedged item in accordance with previous GAAP, it may designate as a hedged item in accordance with IFRSs an individual item within that net position, or a net position if that meets the requirements in paragraph 6.6.1 of IFRS 9, provided that it does so no later than the date of transition to IFRSs. B6 If, before the date of transition to IFRSs, an entity had designated a transaction as a hedge but the hedge does not meet the qualifying criteria |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraphs B5–B6 of IFRS 1 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | Paragraphs B5–B6 of IFRS 1 were originally written to be consistent with the requirements for hedge accounting in IAS 39 Financial Instruments: Recognition and Measurement. In particular, the use of the word 'conditions' in paragraph B6 is consistent with paragraph 88 of IAS 39. First-time adopters of IFRS Accounting Standards do not have an option to apply the hedge accounting requirements in IAS 39 and therefore apply IFRS 9. Replacing the word 'conditions' with 'qualifying criteria' is expected to make the wording in paragraph B6 more consistent with paragraph 6.4.1 of IFRS 9 and improve understandability. The addition of the cross-references is expected to avoid unintended consequences by maintaining the focuses of the two paragraphs, ‘eligibility' in paragraph B5 and ‘conditions' (‘qualifying criteria' as proposed in the ED) in paragraph B6. |
| Proposed transition requirement | Transition requirements for the proposed amendments to IFRS 1 are not relevant for the entities that present their first IFRS financial statements because they would apply the requirements in IFRS 1 when transitioning from previous GAAP to IFRS Accounting Standards. Therefore, there is no specific transition requirement. |
7. Amendments to IFRS 10 – Determination of a 'de facto agent'
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion arising from an inconsistency between paragraphs B73 and B74 of IFRS 10 Consolidated Financial Statements related to an investor determining whether another party is acting on its behalf. |
| Proposed amendments | The proposed amendments to IFRS 10 are to address the inconsistency between paragraphs B73 and B74 by clarifying the requirements in paragraph B74 so that both paragraphs allow room for judgement on the determination of a 'de facto' agency relationship. |
| Outcome of the proposed amendments | B73 When assessing control, an investor shall consider the nature of its relationship with other parties and whether those other parties are acting on the investor’s behalf (ie they are 'de facto agents'). The determination of whether other parties are acting as de facto agents requires judgement, considering not only the nature of the relationship but also how those parties interact with each other and the investor. B74 Such a relationship need not involve a contractual arrangement. A party is a de facto agent when the investor has, or those that direct the activities of the investor have, the ability to direct that party to act on the investor’s behalf. A party might be a de facto agent when those that direct the activities of the investor have the ability to direct that party to act on the investor’s behalf. |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraph B74 of IFRS 10 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | Confusion may arise because paragraph B73 states that a de facto agent is a party that acts on the investor’s behalf— and that the determination of whether other parties are acting as de facto agents requires judgement. However, the second sentence of paragraph B74 includes more definitive language and states that “a party is a de facto agent when the investor has, or those that direct the activities of the investor have, the ability to direct that party to act on the investor’s behalf” [emphasis added]. |
| Proposed transition requirement | There is no specific transition requirement. |
| Note | There have been mixed views18 on the assessment of the de facto agency relationship and its interaction with the assessment of control however assessments of de facto control are infrequently needed in the UK19. Consideration within the scope of Annual Improvements20 During the development of the proposed amendments, the IASB was presented with a different proposal in its February 2023 meeting. The proposal was to replace “is” with “may act as” in the second sentence of paragraph B74 in IFRS 10. However this proposal may change the original meaning of the sentence – the first part of the sentence is the definition of a 'de facto agent' however the second part of the sentence is subject to the judgment of facts and circumstances in determining whether the party is a 'de facto agent'. Therefore, the IASB suggested splitting the sentence into two so that the original meanings can be retained – to keep the definition of a 'de facto agent' and to require judgment on other circumstances. |
8. Amendments to IAS 7 – Cost method
| Header | Content |
|---|---|
| Origin | The IASB was informed of potential confusion in applying paragraph 37 of IAS 7 Statement of Cash Flows arising from the use of the term 'cost method' that is no longer defined in IFRS Accounting Standards. |
| Proposed amendments | The proposed amendment to IAS 7 is to replace the term 'cost method', which is no longer defined in IFRS Accounting Standards, with the term 'at cost' in paragraph 37 of IAS 7. |
| Outcome of the proposed amendments | 37 When accounting for an investment in an associate, a joint venture or a subsidiary accounted for by use of the equity method or at cost |
| Mandatory or Non-Mandatory | The proposed amendments are to paragraph 37 of IAS 7 which forms part of the mandatory text of the IFRS Accounting Standards. |
| Rationale for the proposed amendments | The current use of the term 'cost method' results from an oversight during the issuance of Cost of an Investment in a Subsidiary, Jointly Controlled Entity or Associate (Amendments to IFRS 1 First-time Adoption of International Financial Reporting Standards and IAS 27 Separate Financial Statements) in May 2008 when no consequential amendment was made to paragraph 37 of IAS 7. |
| Proposed transition requirement | There is no specific transition requirement. |
Footnotes
-
The IASB and IFRS Interpretations Committee Due Process Handbook (paragraphs 6.10 to 6.15) – Exposing annual improvements, August 2020 ↩
-
The proposed amendments were also described in detail in the UKEB agenda papers for the March 2023 (paragraphs 122 - 142) and June 2023 (paragraphs G1 - G15) meetings. ↩
-
The proposed amendments are to the illustrative examples and implementation guidance to IFRS 7 and are not included in the mandatory sections of UK-adopted international accounting standards. Mandatory pronouncements are IFRS Standards, IAS Standards, Interpretations and mandatory application guidance. Non-mandatory guidance includes basis for conclusions, dissenting opinions, implementation guidance and illustrative examples, together with the IFRS practice statements. This categorisation is set out in the Introduction to the IASB yearly Bound Volumes. ↩
-
Mandatory pronouncements are IFRS Standards, IAS Standards, Interpretations and mandatory application guidance. Non-mandatory guidance includes basis for conclusions, dissenting opinions, implementation guidance and illustrative examples, together with the IFRS practice statements. This categorisation is set out in the Introduction to the IASB yearly Bound Volumes. ↩
-
The IASB and IFRS Interpretations Committee Due Process Handbook, August 2020 – Exposing annual improvements (paragraphs 6.10 to 6.15) ↩
-
This was also noted in the UKEB comment letter for Post-implementation Review of IFRS 9 Financial Instruments – Impairment (Paragraph 9). ↩
-
This is based on the IASB agenda paper 3C, July 2022 (Paragraph 6). ↩
-
This is based on the IASB agenda paper 7A, July 2021 (Paragraph 57). ↩
-
This was noted in the UKEB comment letter for Post-implementation Review of IFRS 10 Consolidated Financial Statements, IFRS 11 Joint Arrangements and IFRS 12 Disclosures of Interests in Other Entities. ↩
-
The UK Endorsement Board Due Process Handbook (paragraphs 5.3) – Milestones under Influencing process, December 2022 ↩
-
The UK Endorsement Board Due Process Handbook (paragraphs 5.15 to 5.17) – Draft comment letter, December 2022 ↩
-
The limitation to Annual Improvements is that they should not propose a new principle or change an existing principle. (The IASB and IFRS Interpretations Committee Due Process Handbook (paragraphs 6.10 to 6.15) – Exposing annual improvements, August 2020) ↩
-
This was also noted in the UKEB comment letter for Post-implementation Review of IFRS 9 Financial Instruments – Impairment (Paragraph 9). ↩
-
The IASB agenda paper 3C, July 2022 (Paragraph 6) ↩
-
The limitation to Annual Improvements is that they should not propose a new principle or change an existing principle. (The IASB and IFRS Interpretations Committee Due Process Handbook (paragraphs 6.10 to 6.15) – Exposing annual improvements, August 2020) ↩
-
Mandatory pronouncements are IFRS Standards, IAS Standards, Interpretations and mandatory application guidance. Non-mandatory guidance includes basis for conclusions, dissenting opinions, implementation guidance and illustrative examples, together with the IFRS practice statements. This categorisation is set out in the Introduction to the IASB yearly Bound Volumes. ↩
-
The IASB agenda paper 7A, July 2021 (Paragraph 57) and agenda paper 7, February 2022 (Paragraphs 77 to 82) ↩
-
This was noted in the UKEB comment letter for Post-implementation Review of IFRS 10 Consolidated Financial Statements, IFRS 11 Joint Arrangements and IFRS 12 Disclosures of Interests in Other Entities. ↩
-
The limitation to Annual Improvements is that they should not propose a new principle or change an existing principle. (The IASB and IFRS Interpretations Committee Due Process Handbook (paragraphs 6.10 to 6.15) – Exposing annual improvements, August 2020) ↩