Feedback Statement - ISSB Exposure Drafts IFRS S1 and IFRS S2
July 2022
Foreword
The UK Endorsement Board (UKEB) welcomes the opportunity to respond to the ISSB EDs IFRS S1 and S2 and contribute to the development of international sustainability disclosure standards.
Our response to the ISSB's consultation reflects the imperative to remain relevant in the face of these significant sustainability challenges for reporting entities around the world and to influence the development of robust standards that can be adopted globally.
The UKEB welcomed significant engagement with stakeholders during the outreach phase of the project. This included engaging with over 200 stakeholders representing over 90 organisations. This constructive and insightful feedback has been incorporated into the final comment letter to the ISSB.
We look forward to continuing to engage with ISSB as it redeliberates responses received and seeks to finalise proposals by the end of 2022.
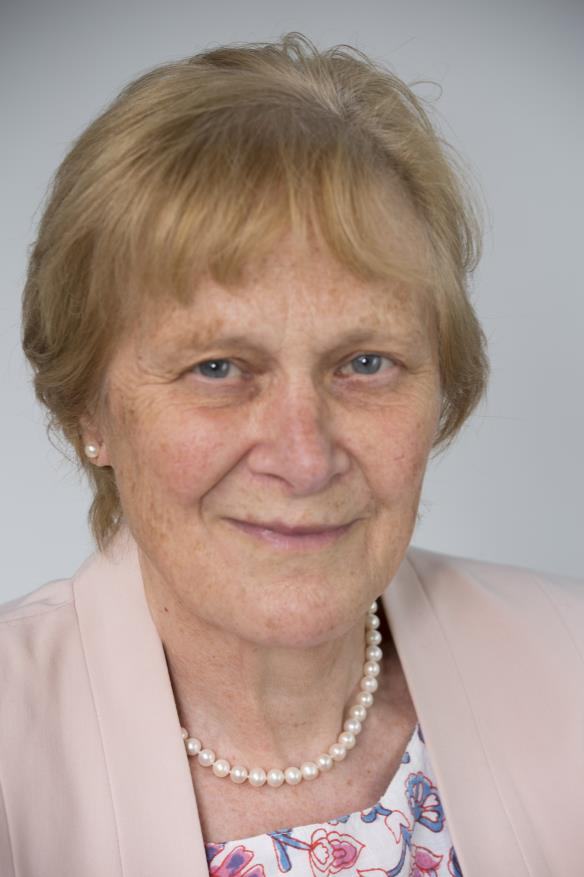
Pauline Wallace Chair, UKEB
Context and remit
-
The UKEB is responsible for endorsement and adoption of IFRS accounting standards for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new accounting standards, amendments and interpretations.
-
In November 2021, the Foundation announced the formation of a new International Sustainability Standards Board (ISSB) to develop a comprehensive global baseline of high-quality sustainability disclosure standards to meet investors' information needs. In March 2022, the ISSB issued its first exposure drafts: [draft] IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information and [draft] IFRS S2 Climate Related Disclosures.
-
The Department for Business, Energy and Industrial Strategy (BEIS) sets the reporting requirements, both financial and non-financial (ESG matters) for UK registered entities under Company Law. BEIS requested that the UKEB assist the UK Government by carrying out work to consider the overlap or impact of the proposed ISSB disclosure standards with accounting standards issued by the International Accounting Standards Board (IASB).
Purpose of Feedback Statement
The ISSB requested comments on [draft] IFRS S1 and [draft] IFRS S2 in March 2022 with a comment deadline of 29 July 2022. Their stated objective in undertaking the consultation was to obtain stakeholder feedback to shape the development and publication of final sustainability standards by December 2022.
[draft] IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information Requires a company to disclose information that enables investors to assess the effect of significant sustainability-related risks and opportunities on its enterprise value.
[draft] IFRS S2 Climate-related Disclosures Establishes disclosure requirements specific to climate-related risks and opportunities.
This feedback statement represents a summary of the views of UK stakeholders during the UKEB's outreach activities during May to July 2022. It also seeks to provide an explanation for the key changes between the initial views expressed in the UKEB draft and the final comment letters.
Outreach approach
All stakeholder feedback was considered in reaching the UKEB's final comment letter on the proposed standards.
More than 200 stakeholders representing over 90 organisations. Activities included:
- Multiple one to one engagements with stakeholders and stakeholder representative groups
- Hosting a webinar with the ISSB, FCA, preparers and users of financial statements to discuss the draft comment letter
- Observing a series of World Economic Forum and FRC hosted roundtables
- Discussions with other national standard setters
- Promotion through UKEB and stakeholder representative groups social media platforms
Stakeholder submissions received on the Draft Comment Letter (DCL) were made public on the project website.
During the consultation period, the UKEB and its Secretariat promoted awareness of the DCL and encouraged stakeholders to respond through News Alerts, a specific outreach event, outreach meetings and advertising.
| Stakeholder type | Stakeholders engaged | Organisations represented |
|---|---|---|
| Users of accounts | 15 | 11 |
| Representative bodies and industry groups[^1] | 60 | 5 |
| Preparers of accounts | 19 | 8 |
| Accounting firms | 11 | 4 |
| Regulatory Bodies | 5 | 2 |
| UKEB webinar | 95 | 64[^2] |
Executive Summary - [draft] IFRS S1
| Area | UKEB tentative assessment | Stakeholder views ``` July 2022
Foreword
The UK Endorsement Board (UKEB) welcomes the opportunity to respond to the ISSB EDs IFRS S1 and S2 and contribute to the development of international sustainability disclosure standards.
Our response to the ISSB's consultation reflects the imperative to remain relevant in the face of these significant sustainability challenges for reporting entities around the world and to influence the development of robust standards that can be adopted globally.
The UKEB welcomed significant engagement with stakeholders during the outreach phase of the project. This included engaging with over 200 stakeholders representing over 90 organisations. This constructive and insightful feedback has been incorporated into the final comment letter to the ISSB.
We look forward to continuing to engage with ISSB as it redeliberates responses received and seeks to finalise proposals by the end of 2022.
Pauline Wallace Chair, UKEB
Context and remit
-
The UKEB is responsible for endorsement and adoption of IFRS accounting standards for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new accounting standards, amendments and interpretations.
-
In November 2021, the Foundation announced the formation of a new International Sustainability Standards Board (ISSB) to develop a comprehensive global baseline of high-quality sustainability disclosure standards to meet investors' information needs. In March 2022, the ISSB issued its first exposure drafts: [draft] IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information and [draft] IFRS S2 Climate Related Disclosures.
-
The Department for Business, Energy and Industrial Strategy (BEIS) sets the reporting requirements, both financial and non-financial (ESG matters) for UK registered entities under Company Law. BEIS requested that the UKEB assist the UK Government by carrying out work to consider the overlap or impact of the proposed ISSB disclosure standards with accounting standards issued by the International Accounting Standards Board (IASB).
Purpose of Feedback Statement
The ISSB requested comments on [draft] IFRS S1 and [draft] IFRS S2 in March 2022 with a comment deadline of 29 July 2022. Their stated objective in undertaking the consultation was to obtain stakeholder feedback to shape the development and publication of final sustainability standards by December 2022.
[draft] IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information Requires a company to disclose information that enables investors to assess the effect of significant sustainability-related risks and opportunities on its enterprise value.
[draft] IFRS S2 Climate-related Disclosures Establishes disclosure requirements specific to climate-related risks and opportunities.
This feedback statement represents a summary of the views of UK stakeholders during the UKEB's outreach activities during May to July 2022. It also seeks to provide an explanation for the key changes between the initial views expressed in the UKEB draft and the final comment letters.
Outreach approach
All stakeholder feedback was considered in reaching the UKEB's final comment letter on the proposed standards.
More than 200 stakeholders representing over 90 organisations. Activities included:
- Multiple one to one engagements with stakeholders and stakeholder representative groups
- Hosting a webinar with the ISSB, FCA, preparers and users of financial statements to discuss the draft comment letter
- Observing a series of World Economic Forum and FRC hosted roundtables
- Discussions with other national standard setters
- Promotion through UKEB and stakeholder representative groups social media platforms
Stakeholder submissions received on the Draft Comment Letter (DCL) were made public on the project website.
During the consultation period, the UKEB and its Secretariat promoted awareness of the DCL and encouraged stakeholders to respond through News Alerts, a specific outreach event, outreach meetings and advertising.
| Stakeholder type | Stakeholders engaged | Organisations represented |
|---|---|---|
| Users of accounts | 15 | 11 |
| Representative bodies and industry groups[^1] | 60 | 5 |
| Preparers of accounts | 19 | 8 |
| Accounting firms | 11 | 4 |
| Regulatory Bodies | 5 | 2 |
| UKEB webinar | 95 | 64[^2] |
Executive Summary - [draft] IFRS S1
| Area | UKEB tentative assessment | Stakeholder views U
UKEB
```