UKEB Governance & Due Process Annual Report 2022-23
1. Introduction
The UK Accounting Standards Endorsement Board (‘UKEB') was established to perform certain functions relating to the adoption of International Financial Reporting Standards ('IFRS') as developed by the International Accounting Standards Board (‘IASB'), for use in the UK, and to contribute, on behalf of the UK, to the development of a single set of international accounting standards.
Chapter 3 of The International Accounting Standards and European Public Limited Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685) confers on the Secretary of State for Business, Energy and Industrial Strategy (‘BEIS') functions relating to the adoption of IFRS for application in the UK. The Secretary of State exercised the power conferred by Chapter 4 of those Regulations to delegate to the UKEB the functions specified in SI 2021/609, ('the Delegation Regulations') ('the Functions'). This delegation of powers came into force on 22 May 2021.
Underpinning the performance of the functions, UKEB has certain governance and due process duties and responsibilities which are incorporated primarily within the following:
- Memorandum of Understanding (‘MoU') between UKEB, BEIS1 and FRC
- UKEB Terms of Reference (‘ToR')
- UKEB Due Process Handbook ('the Handbook')
The MoU (s4.1) states that the FRC has oversight responsibility in respect of the effective governance of UKEB whilst recognising the fundamental importance of UKEB's independence by confirming (in s4.3) that the FRC does not have the power to direct the UKEB in relation to the determination of its programme of work or the outcome of its technical decision-making.
The MoU (s9.2) requires UKEB to report annually to the FRC Board setting out how it has complied with the procedures in the Handbook. The ToR (s10.3(b)) supports this by requiring that UKEB report, at least annually, to the FRC in relation to its governance and due process.
This report fulfils the above stated annual reporting requirement, covering the period from 1 April 2022 to 31 March 2023.
The UKEB Board is satisfied that it has fulfilled its governance and due process duties and responsibilities throughout the reporting period. The Board has maintained its focus on reinforcing and building on the strong foundations laid during UKEB's initial set-up phase, underpinned by a continuous improvement ethos.
2. Reporting Period 2022/23
The reporting period 1 April 2022 to 31 March 2023 saw UKEB continue to implement and embed the constituent parts of its governance and due process framework which underpin its day-to-day operations and the Board's decision-making. Particular highlights of the period included UKEB welcoming two new Board members, approving its first IFRS standard (IFRS 17 Insurance Contracts) and finalising the Handbook.
2.1 Core Values & Guiding Principles
The UKEB's mission is to serve the UK public good by leading the development and synthesis of UK views on financial reporting and representing them in the international arena, ensuring that the UK's voice is influential in the development of high-quality international accounting standards that are suitable for adoption in the UK. The UKEB is committed to performing its functions, and acting at all times, in accordance with its four guiding principles and the seven principles of public life. These core values are intrinsic to all of UKEB's governance and due process activities.
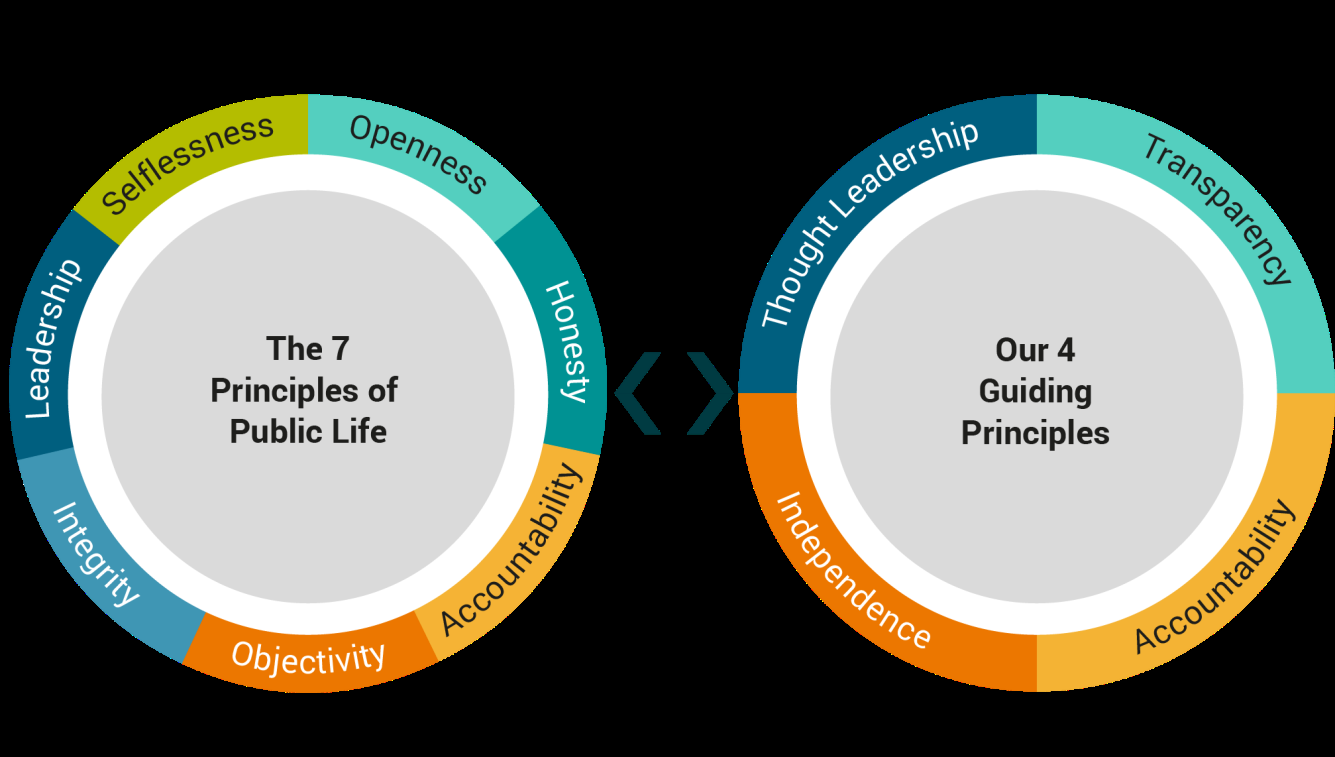
UKEB's approach to ensuring robust governance and due process, in pursuit of its strategic objectives, includes the following core activities:
1. Public Board Meetings
- The Board's technical decision-making is carried out in a fully transparent manner, in accordance with the ToR. Members of the public can choose to observe the discussions live or watch an online recording.
- The meetings are attended by Official Observers from the Department for Business and Trade ('DBT'), Bank of England, FRC, HMRC and FCA, all of whom have speaking rights.
- Meeting agenda and Board papers are published on the UKEB website in advance and a summary of decisions and minutes are published afterwards.
- In addition, the agenda and summary minutes of UKEB's private Board meetings are published on the UKEB website.
- UKEB has a Board Meetings Transparency Policy which sets out the key principles the Board considers when deciding which matters it discusses in public Board meetings and which matters are discussed in private.
2. Managing Conflicts of Interest
The Board complies with a Conflicts of Interest Policy and a Gifts and Hospitality Policy. A Transparency Register and Gifts and Hospitality Register are published on the UKEB website and regularly updated.
3. Stakeholder Engagement
- The UKEB has developed a Stakeholder Engagement and Communications Strategy to support the influencing and thought leadership responsibilities which form part of its Regulatory Strategy. It considers the high level of stakeholder engagement activities that UKEB is already performing and those areas where, at this stage in UKEB's maturity, resource should be focused in order to continue enhancing that engagement in the most effective and efficient manner.
- Five Advisory Groups, chaired by Board members, have been set up as follows: 1. Academics 2. Accounting Firms and Institutes 3. Investors 4. Preparers 5. Rate-regulated Activities
- Each of these groups meets between two and six times per annum. They are not decision-making bodies but they do report into and provide advice directly to the Board.
- Two Working Groups, chaired by the UKEB Secretariat, have been set up as follows: 1. Financial Instruments 2. Sustainability These groups meet between two and six times per annum and provide advice to the UKEB Secretariat.
- There is proactive engagement with stakeholders across various mediums to ensure that their views are heard and the potential impact of IASB proposals is understood.
- Public consultation comment letters received from stakeholders are made available on the UKEB website unless the stakeholder requests otherwise.
- The Handbook (see s2.2 below) sets out the required approach to stakeholder engagement, including public consultations, at the technical project level.
4. Regulatory Strategy and Budget
- There is a clearly defined and robust process for ensuring that UKEB's Regulatory Strategy and Budget are: 1. designed to support achievement of its statutory functions; and 2. subject to timely scrutiny and approval, both internally by the Board and by DBT and the FRC Accounting Officer. The Regulatory Strategy and Budget for 2023/24 were both approved during this reporting period, working closely with DBT and the FRC. They were also subject to public consultation. The Regulatory Strategy and Feedback Statement were approved by the Board in a public meeting and are published on the UKEB website.
- Managing Public Money principles were applied rigorously throughout the reporting period. Both the Board and the FRC Accounting Officer regularly reviewed the 2022/23 financial position and general budget management.
5. Risk Management
UKEB has a clearly defined and embedded risk management framework, including a detailed risk register, that is subject to Board monitoring and review. It ensures that UKEB has a clear understanding of its risk environment and a focused approach to the managing, monitoring and recording of its key risks.
2.2 Due Process Framework
A robust due process framework is central to the development of high-quality financial reporting and delivery of accountability and transparency to stakeholders. The core elements of UKEB's due process framework are set out in the Handbook which, having been in development since UKEB was established in 2021, was finalised for publication in December 2022. Development of the Handbook involved a significant amount of stakeholder engagement and consultation to ensure that stakeholder views were fully considered by the Board throughout the project.
Whilst the Handbook was in development, the Board was guided by UKEB's core values and guiding principles and its duties and responsibilities as set out in the MoU and ToR. Given the nature of an organisation in set-up phase, the Board was, from the outset, holding detailed discussions on its approach to due process in relation to live projects that had to be progressed to align with IASB timelines whilst, in parallel, discussing the drafting of individual sections of the Handbook. This parallel approach to project management and due process development, albeit done by necessity, allowed UKEB to gain valuable insights by testing the practical application of its due process approach proposals in real time. It enabled UKEB to develop a robust due process framework as detailed in the Handbook.
The evolution of the UKEB's approach to due process has been evident in the Board's approach to live projects. Development of the Due Process Compliance Statement, for example, was first discussed by the Board in October 2021 and has been applied to projects completed since then i.e. in advance of the Handbook being finalised.
Appendix A sets out the projects that UKEB has undertaken during the reporting period and the core due process steps taken. Further detail of UKEB's projects is also published on the UKEB website to ensure transparency and strengthen stakeholder engagement.
2.3 Terms of Reference
Terms Updates
Two changes to the UKEB ToR were approved during the reporting period, as follows:
1. Annual Reporting Process (Effective date: 23 September 2022)
Section 10.3 was updated to make clear that (a) the UKEB's annual report to the Secretary of State, on the exercise of its Functions, will be laid in Parliament and * (b) the UKEB's annual report to the FRC, regarding its governance and due process, will be made publicly available.
2. Due Process Handbook Review Process (Effective date: 17 November 2022)
Section 10.1(b) was amended and 10.1(c) added to clarify that the Handbook will be reviewed at least once every five years under the direction of the Board. Subsequent revisions do not require Secretary of State approval.
Website Publication Delays
The UKEB TOR (s8.3) states that the agenda and agenda papers for each public meeting will usually be made available on the UKEB website no later than 5 working days before the meeting.
UKEB website technical issues during the reporting period resulted in delays to the website publication of Board papers for the 9 May 2022 and 23 March 2023 Board meetings beyond their required publication deadline, as set out in the ToR. In those instances, whilst the technical issue was resolved, UKEB's contingency plan, of sharing a link to a temporary webpage, was invoked.
3. Board Effectiveness
3.1 Board Composition & Appointments
The UKEB Board, as set out below, is comprised of the Chair and twelve members. Collectively they bring together a range of relevant backgrounds and expertise.
| Name | Role | Category | Term End Date |
|---|---|---|---|
| Pauline Wallace | Executive Chair | September 2025 | |
| Amir Amel-Zadeh | Non-Executive Member | Academic | March 2024 |
| Michael Wells | Non-Executive Member | Academic | March 2024 |
| Giles Mullins | Non-Executive Member | Accounting Firm | March 2024 |
| Sandra Thompson | Non-Executive Member | Accounting Firm | March 2024 |
| Robin Cohen | Non-Executive Member | Economist | September 2025 |
| Paul Lee | Non-Executive Member | Investor | March 2024 |
| Liz Murrall | Non-Executive Member | Investor | March 2024 |
| Edward Knapp | Non-Executive Member | Investor | September 2025 |
| Kathryn Cearns | Non-Executive Member | Other | March 2024 |
| Katherine Coates | Non-Executive Member | Other | March 2024 |
| Mike Ashley | Non-Executive Member | Preparer of Accounts | March 2024 |
| Phil Aspin | Non-Executive Member | Preparer of Accounts | March 2024 |
The interim Chair, appointed by the Secretary of State in September 2020 to lead the set-up of UKEB and appointment of the inaugural Board, was announced as UKEB's first permanent Chair in September 2022. The appointment followed a fair and open process, led by BEIS, and is for a three-year term.
Two additional Board members, Robin Cohen (Economist) and Edward Knapp (Investor), were appointed in September 2022, for a three-year term, to further strengthen the Board's knowledge and expertise in economics and investment matters. They were appointed by the Chair, with the approval of the Secretary of State, following a fair and open process. The interview panel was comprised of the Chair, a BEIS representative, an FRC Board member and an independent panel member.
3.2 Annual Board Effectiveness Review
UKEB's first Annual Board Effectiveness Review, led by the Chair, was completed in 2022 and a summary report published on the UKEB website. The positive findings of the review were encouraging, particularly for a new Board leading a new organisation. The key takeaway for the Board, however, was a clear message that there was still work to be done to ensure that it continues to build upon the solid foundations laid in its inaugural year.
The 2023 Annual Board Effectiveness Review is already in progress with a preliminary completion date of July 2023.
3.3 Board Succession Planning
Ten of the Board's twelve members commenced their 3-year term at the same time in March 2021 i.e. when UKEB was established. Succession planning activities are already in progress to ensure continued stability in UKEB's ongoing operations up to and beyond March 2024.
Appendix A Due Process Documents Published
Set out below is a summary of the UKEB projects undertaken during the reporting period and the core due process steps taken.
| Type of Project | Project Initiation Plan | Final Comment Letter | Final Comment Letter Date | Feedback Statement | DPCS |
|---|---|---|---|---|---|
| Influencing Projects | |||||
| International Sustainability Standards Board: IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information and IFRS S2 Climate Related Disclosures | Exposure Draft | √ | 27/07/22 | √ | |
| International Tax Reform – Pillar Two Model Rules (Proposed Amendments to IAS 12) | Exposure Draft | √ | √ | 09/03/23 | √ |
| Non-Current Liabilities with Covenants (Proposed Amendments to IAS 1) | Exposure Draft | √ | √ | 21/03/22 | √ |
| Supplier Finance Arrangements (Proposed Amendments to IAS 7 and IFRS 7) | Exposure Draft | √ | √ | 28/03/22 | √ |
| Research Projects | |||||
| Subsequent Accounting for Goodwill | Research | √ | N/a | N/a | |
| • Phase 1 desk-based research | √2 | 17/12/212 | |||
| • Phase 2 field-testing | √3 | 26/09/223 | |||
| Intangibles Research Project (Phase 1): Major Output 1 - Qualitative Research Report: UK Stakeholder Views on Accounting for Intangibles | Research | √ | √3 | 22/03/233 | N/a |
| Endorsement and Adoption Projects | |||||
| Narrow Scope Amendments (Effective date: 1 January 2022) | |||||
| Amendment to IFRS 1 First-time Adoption of International Financial Reporting Standards – Subsidiary as a First-time Adopter (Annual Improvements to IFRS 2018–2020) | √ | √ | √ | √ | |
| Amendment to IFRS 9 Financial Instruments – Fees in the '10 per cent' Test for Derecognition of Financial Liabilities (Annual Improvements to IFRS 2018–2020) | √ | √ | √ | √ | √ |
| Amendment to IAS 41 Agriculture – Taxation in Fair Value Measurements (Annual Improvements to IFRS 2018–2020) | √ | √ | √ | √ | √ |
| Onerous Contracts – Cost of Fulfilling a Contract (Amendments to IAS 37) | √ | √ | √ | √ | √ |
| Property, Plant and Equipment: Proceeds before Intended Use (Amendments to IAS 16) | √ | √ | √ | √ | √ |
| Reference to the Conceptual Framework (Amendments to IFRS 3) | √ | √ | √ | √ | √ |
| Narrow Scope Amendments (Effective date: 1 January 2023) | |||||
| Disclosure of Accounting Policies (Amendments to IAS 1 Presentation of Financial Statements and to IFRS Practice Statement 2 Making Materiality Judgements) | √ | √ | √ | √ | √ |
| Definition of Accounting Estimates (Amendments to IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors) | √ | √ | √ | √ | √ |
| Deferred Tax related to Assets and Liabilities arising from a Single Transaction (Amendments to IAS 12 Income Taxes) | √ | √ | √ | √ | √ |
| IFRS 17 Insurance Contracts (Effective date: 1 January 2023) | |||||
| IFRS 17 Insurance Contracts | √4 | √ | √ | √ | √ |
| Narrow Scope Amendments (Effective date: on or after 1 January 2024, with early application permitted) | |||||
| Amendments to IFRS 16 Lease Liability in a Sale and Leaseback | √ | √ | _55 | _55 | _55 |
| Narrow Scope Amendments (Effective date: 1 January 2024) | |||||
| IAS 1 Narrow-scope Amendments 2020 and 2022: | √ | √ | _66 | _66 | _66 |
| (1) 2020 Amendment to IAS 1 Classification of Liabilities as Current or Non-current (2020) | |||||
| (2) 2022 Amendments to IAS 1 Non-current Liabilities with Covenants |
Footnotes
-
Following the changes announced on 7 February 2023, oversight of UKEB's discharge of its statutory functions has moved from BEIS to the Department for Business and Trade. ↩
-
Letter submitted to IASB rather than a Final Comment Letter. ↩↩
-
Final Report published, rather than a Final Comment Letter. ↩↩↩↩
-
The process to endorse and adopt IFRS 17 commenced before the UKEB was established. The previous governance process approved an equivalent of a Project Initiation Plan. ↩
-
The DECA was published on 5 January 2023 with a 90-day consultation period closing on 5 April 2023, outside the reporting period. ↩↩↩
-
The DECA was published on 9 March 2023 with a 90-day consultation period closing on 8 June 2023, outside the reporting period. ↩↩↩