Due Process Handbook
UK Endorsement Board December 2022
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2022 All Rights Reserved
- I. Introduction
- 2. Statutory functions of the UKEB
- 3. Terms of Reference and Guiding Principles
- 4. Governance activities
- Quorum of attendance
- Voting process for endorsement decisions
- Voting process for approving or reviewing the UKEB's Due Process Handbook
- Voting process for other decisions
- Transparency of meetings and stakeholder observers
- Appendix D: Illustrative diagram to determine whether to undertake a post-implementation review (PIR)
- Draft Endorsement Criteria Assessment (DECA)
- DECA with a shorter consultation period
- Project closure
- Adoption package
- Final Endorsement Criteria Assessment (ECA) (mandatory)
- Feedback statement (mandatory)
- Due process compliance statement (mandatory)
- Adoption statement (mandatory)
- Voting on the adoption of a new or amended international accounting standard (mandatory)
- Decision-making
- Publication of the results of the vote
- 7. Thought leadership and research programme
- Objectives of thought leadership
- Leading the UK debate
- Participating proactively in the development of global standards
- Representing UK views in international fora with the aim of influencing debate
- Engaging with other UK bodies and bodies in other jurisdictions
- Research programme
- Main outputs
- Milestones
- Common milestones for all research documents
- Project initiation plan (mandatory)
- Desk-based research
- Outreach activities
- Approval and publication (mandatory)
- Additional milestones for a research document that includes an invitation to comment
- 8. Post-implementation reviews
- 8. Post-implementation reviews
- Introduction
- Process for a Standard adopted under Regulation 6
- Meaning of 'significant change in accounting practice'
- Process for undertaking a post-implementation review for a Standard adopted under Regulation 6
- Influencing an IASB post-implementation review
- Process for carrying out a UKEB Post-implementation review
- Phase one of a UKEB post-implementation review
- Phase two of a UKEB post-implementation review
- Project closure for a UKEB post-implementation review
- 9. Advisory groups
- Appendix A: Description of common milestones
- Appendix B: Relationship between Statutory Instruments (SI) and other governance documents for the UK Endorsement Board
- Appendix C: Terms of Reference outline for advisory groups
- Appendix D: Illustrative diagram to determine whether to undertake a post-implementation review (PIR)
I. Introduction
Purpose
1.1The purpose of the Due Process Handbook (Handbook) is to set out the due process that the UK Endorsement Board (UKEB) follows in carrying out its statutory functions, which consist of:
- influencing the development of international accounting standards 1 and the other activities of the International Accounting Standards Board (IASB) and the IFRS Interpretations Committee 2; and
- endorsing and adopting new international accounting standards, amendments to international accounting standards or IFRIC Interpretations ('a new or amended standard') for use in the UK.
1.2This Handbook describes additional due process steps that the UKEB follows for:
- carrying out its thought leadership activities and developing its own research programme;
- performing its own post-implementation reviews;
- setting up and operating advisory groups; and
- ensuring it complies with the required due process steps in this Handbook.
1.3The Secretary of State for the Department of Business, Energy and Industrial Strategy (BEIS) (Secretary of State) delegated the functions relating to influencing, endorsing and adopting international accounting standards for application in the UK to the UKEB in May 2021 3. The Secretary of State maintains a regular review of the performance of the UKEB in exercising those functions. The UK Financial Reporting Council (FRC) oversees the effective governance of the UKEB and its adherence to the due process set out in this Handbook. It also provides operational support. The FRC does not have the power to direct the UKEB in
1.4relation to the determination of its programme of work or the outcome of its technical decision-making 4.
This Handbook forms one of the key documents of the UKEB. A diagram of the relationship between these documents can be found in Appendix B.
2. Statutory functions of the UKEB
2.1The statutory functions exercisable by the Secretary of State that were delegated to the UKEB are set out in the Statutory Instrument 2019 No. 685 (SI 2019/685) 5. The main statutory functions are reproduced below:
Regulation 5
Responsibility for adoption of international accounting standards
The Secretary of State is responsible for—
- the adoption of international accounting standards for use within the United Kingdom, with a view to harmonising the financial information presented by the companies required by section 403(1) of the Companies Act 2006 to prepare their accounts in accordance with UK-adopted international accounting standards, in order to ensure—
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom; and
- participating in and contributing to the development of a single set of international accounting standards.
Regulation 6
Power of the Secretary of State to adopt international accounting standards
- The Secretary of State may adopt international accounting standards for use within the United Kingdom, in accordance with regulations 7 and 8.
- In exceptional circumstances, the Secretary of State may exercise the power to adopt international accounting standards in accordance with paragraph (3) or (4).
- Where the effect of regulation 7 is that an international accounting standard taken as a whole cannot be adopted, the Secretary of State may adopt an international accounting standard in part only, provided that—
- those parts of the standard which are not adopted are—
- severable from the standard so that the rest of the standard is operational;
- severed only to the extent necessary to enable adoption of the rest of the standard for use within the United Kingdom; and
- adoption of that part of the standard would be in compliance with regulation 7.
- those parts of the standard which are not adopted are—
- Where there is an option available as part of the standard, the Secretary of State may—
- make provision in the standard to extend the scope of undertakings eligible to use that option; and
- make such extension of scope subject to an undertaking meeting criteria specified by the Secretary of State.
Regulation 7
Basis for adoption of international accounting standards
- The Secretary of State may only adopt an international accounting standard under regulation 6 if the Secretary of State is of the view that, in relation to the form of the standard the Secretary of State intends to adopt—
- the standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
- the standard is not contrary to either of the following principles—
- In deciding whether the use of a standard is likely to be conducive to the long term public good in the United Kingdom, the Secretary of State must have regard, in particular, to the following matters—
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard; and
- whether the use of the standard is likely to have an adverse effect on the economy of the United Kingdom, including on economic growth.
- The Secretary of State may, by regulations made by statutory instrument, amend paragraph (2).
- Regulations made under paragraph (3) are subject to annulment in pursuance of a resolution of either House of Parliament.
Regulation 8: Adoption of standards: consultation
Before adopting an international accounting standard under regulation 6, the Secretary of State must consult such persons as the Secretary of State considers to be representative of those with an interest in the quality and availability of accounts, including users and preparers of accounts.
Regulation 11: Periodic review by Secretary of State of impact of adopted standard
- The Secretary of State must publish a statement setting out the Secretary of State's policy on what amounts to a significant change in accounting practice, and must keep this policy statement under review.
- Paragraphs (3) and (4) apply in relation to the adoption of any standard by the Secretary of State under regulation 6 which the Secretary of State considers likely to lead to a significant change in accounting practice.
- The Secretary of State must—
- carry out a review of the impact of the adoption of the standard; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used).
- The Secretary of State may carry out subsequent reviews from time to time, and in the event of doing so the Secretary of State must publish a report setting out the conclusions of any review conducted.
Regulation 17: Reporting by the body
- The body must, at least once in each calendar year for which the delegation regulations are in force, make a report to the Secretary of State on—
- the discharge of the functions transferred to it, and
- such other matters as the Secretary of State may by regulations require.
- Delegation regulations may modify paragraph (1) as it has effect in relation to the calendar year in which the regulations come into force or are revoked
- The Secretary of State must lay before Parliament copies of each report received under this paragraph.
3. Terms of Reference and Guiding Principles
Terms of Reference
3.1The Terms of Reference 6 (ToR) further elaborate on the UKEB's role and responsibilities as they relate to the statutory functions. The UKEB's key responsibilities include:
- Considering and deciding whether to endorse and adopt 7 new or amended international accounting standards for application in the UK 8. This includes a formal endorsement criteria assessment as set out in SI 2019/685.
- Influencing the development of IFRS. The UKEB will follow, contribute to and monitor debates on the IASB's and IFRS Interpretations Committee's projects; consult with UK stakeholders to obtain their views; highlight any concerns to the IASB at different stages of their projects, including the development of the IASB's agenda; and respond to the IASB's draft proposals and consultations (including a request for information on an IASB post-implementation review) 9.
- Ensuring that there is an open and transparent due process including a public consultation process with UK stakeholders on items such as draft comment letters to the IASB or draft endorsement criteria assessments.
- Reporting to the FRC Board in relation to the UKEB's effective operation, governance and adherence to the Handbook.
- Reporting to the Secretary of State in relation to the performance of the UKEB's statutory functions.
- Each year, prepare a regulatory strategy which must be submitted to the Secretary of State for approval.
- Reviewing, at least once every five years, the UKEB's Handbook to ensure that it meets the guiding principles set out in paragraph 3.3 of this Handbook, making recommendations for its revision following such consultation as is deemed appropriate by the UKEB.
3.2The ToR are set by the Secretary of State and adopted by the UKEB.
Guiding Principles
3.3Paragraphs 4.1-4.5 in Section 4 of the ToR require the UKEB to act at all times in accordance with the following guiding principles:
- Accountability—includes consulting with UK stakeholders that are affected by financial reporting, undertaking activities and due process procedures in a timely manner and providing a rationale for the decisions it makes. The UKEB is accountable to:
- its stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators);
- its oversight body (the FRC) in relation to its effective operation, governance and adherence to the Handbook; and
- the Secretary of State in relation to the performance of its statutory functions.
- Independence—to ensure that it acts in the UK's long term public good and that it is independent from other organisations or stakeholder groups, including the FRC and BEIS, in respect of the performance of its statutory functions, including its technical decision making.
- Transparency—to determine its technical decisions after having assessed the relevant evidence received and having followed its Handbook. To undertake its activities in a transparent manner so that stakeholders are aware of current projects and understand how decisions have been made (e.g. by making formal comment letters submitted to the UKEB publicly available 10 on a timely basis).
- Thought leadership—to:
- lead and represent the UK on international accounting standards and reporting;
- represent UK views in international fora with the aim of influencing debate;
- engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice; and
- pro-actively participate in the development of new global accounting standards, for example by undertaking research.
3.4These guiding principles are embedded into the processes described in this Handbook.
Milestones and proportionality of due process activities
3.5This Handbook specifies mandatory milestones as well as other milestones (not labelled as 'mandatory') that will guide the UKEB in performing its required due process steps on individual projects. These milestones build on the UKEB's statutory functions (as described in Section 2), its Terms of Reference and its Guiding Principles (as described above in this section) and its Governance activities (as described in Section 4).
3.6Milestones labelled as 'mandatory' should always be undertaken and reflected in the project initiation plan (PIP) for each specific project (unless as explained in paragraph 3.9 below). Milestones not labelled as 'mandatory' may also be considered, as appropriate, and if undertaken will also be reflected in the PIP.
3.7The activities undertaken to achieve the milestones for each project should be proportionate to the significance, urgency, complexity (i.e. nature or scope), size, expected timeline and expected interest or controversy attached to the project.
3.8Examples of the application of a proportionate approach include:
- It is expected that for major amendments, e.g. complex amendments or new standards, the activities undertaken would be far more extensive than for 'minor' projects (e.g. amendments that meet the IASB's criteria for annual improvements or for narrow-scope amendments 11);
- The consultation for a tentative agenda decision issued by the IFRS Interpretations Committee 12 requiring an urgent response may be undertaken only with a selected group or small number of stakeholders.
3.9The UKEB may decide not to undertake a 'mandatory' milestone for a particular project (refer to paragraph 3.6 above). The UKEB should discuss the reasons for this decision at a public Board meeting. The PIP of the applicable project should clearly outline these reasons.
Reviewing due process activities
3.10The UKEB may decide to undertake a review of a project after its completion so that any "lessons learnt" can be incorporated into the process for future projects.
4. Governance activities
Quorum of attendance
4.1Paragraph 5.1 of the UKEB's ToR sets out the quorum for UKEB (Board) meetings. This requires that a minimum of sixty percent of the appointed Board members (Members) (including the UKEB Chair as an appointed Member) attend a meeting of the Board. This paragraph is reproduced below:
> 5.1The quorum for UK Endorsement Board meetings will be sixty percent of the appointed Members.
Voting process for endorsement decisions
4.2Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements in paragraphs 5.2–5.5 of the UKEB's ToR. These paragraphs are reproduced below:
> 5.2Decisions to adopt a standard or amendment to a standard or an IFRS Interpretations Committee interpretation must be made by at least two-thirds of the Members, including the Chair. In exceptional circumstances, if the Chair is not available Members may elect another Member to act as an alternate Chair. > > 5.3Following the conclusion of a final written vote, in relation to the decision in paragraph 5.2, the Chair shall make public the outcome of that vote within 3 working days. Publication of the results of the vote on a standard or part standard will, where the result is to adopt a standard in whole or in part, constitute the adoption of that standard by the UK Endorsement Board, on a date specified by the UK Endorsement Board. > > 5.4Where the vote to adopt a standard or amendment or interpretation does not reach the required majority, the Chair may, after consultation with external parties including BEIS, choose to ask the UK Endorsement Board to return to the vote. This may include asking the UK Endorsement Board to vote on part of the standard, amendment or interpretation if it appears that this will have the required support. A subsequent decision to adopt the part standard or part amendment to a standard or part interpretation must be made by at least two-thirds of the Members. > > 5.5Where a vote by the UK Endorsement Board to adopt a standard, amendment, or interpretation, in whole or in part, has failed to reach the required majority and, in the opinion of the Chair, there is no prospect of such majority being reached, the UK Endorsement Board Chair must provide a written explanation of circumstances to the Secretary of State within 10 working days of the failure to adopt. The Secretary of State may require further evidence. The Chair must inform Members of any recommendations by the Secretary of State.
4.3A decision to adopt a new or amended standard must be made at a public Board meeting and is tentative only. This decision must be formalised by circulation outside the meeting by a formal written vote in favour by two-thirds of Members. Paragraphs 6.42–6.48 of the Handbook provide more details on the process followed by the Board in deciding whether to endorse a new or amended standard.
Voting process for approving or reviewing the UKEB's Due Process Handbook
4.4The approval and any future revisions to the Handbook require discussion and approval at a public Board meeting. The revisions to the Handbook will take place under normal circumstances every five years (ToR paragraph 10.2(c)).
4.5The Board's approval of the Handbook and of any revision to it requires the support of a simple majority of the Members present at the meeting. Following this approval, it will be published on the UKEB website.
Voting process for other decisions
4.6Other decisions at public meetings do not require a formal written vote by the Board. They require the support of a simple majority of the Members present at the meeting, with approval given in a public meeting.
Transparency of meetings and stakeholder observers
4.7The UKEB's ToR set out the operating procedures that the UKEB applies in carrying out its responsibilities. Those procedures include the frequency and form of Board meetings (in Section 6 of the ToR), as well as rules for observers attending these meetings (in Section 7 of the ToR).
4.8The Board may hold meetings in person, by webcast, or by telephone or other similar means. In deciding the format of meeting, the UKEB Chair should take into consideration public access and attendance (ToR paragraph 6.2).
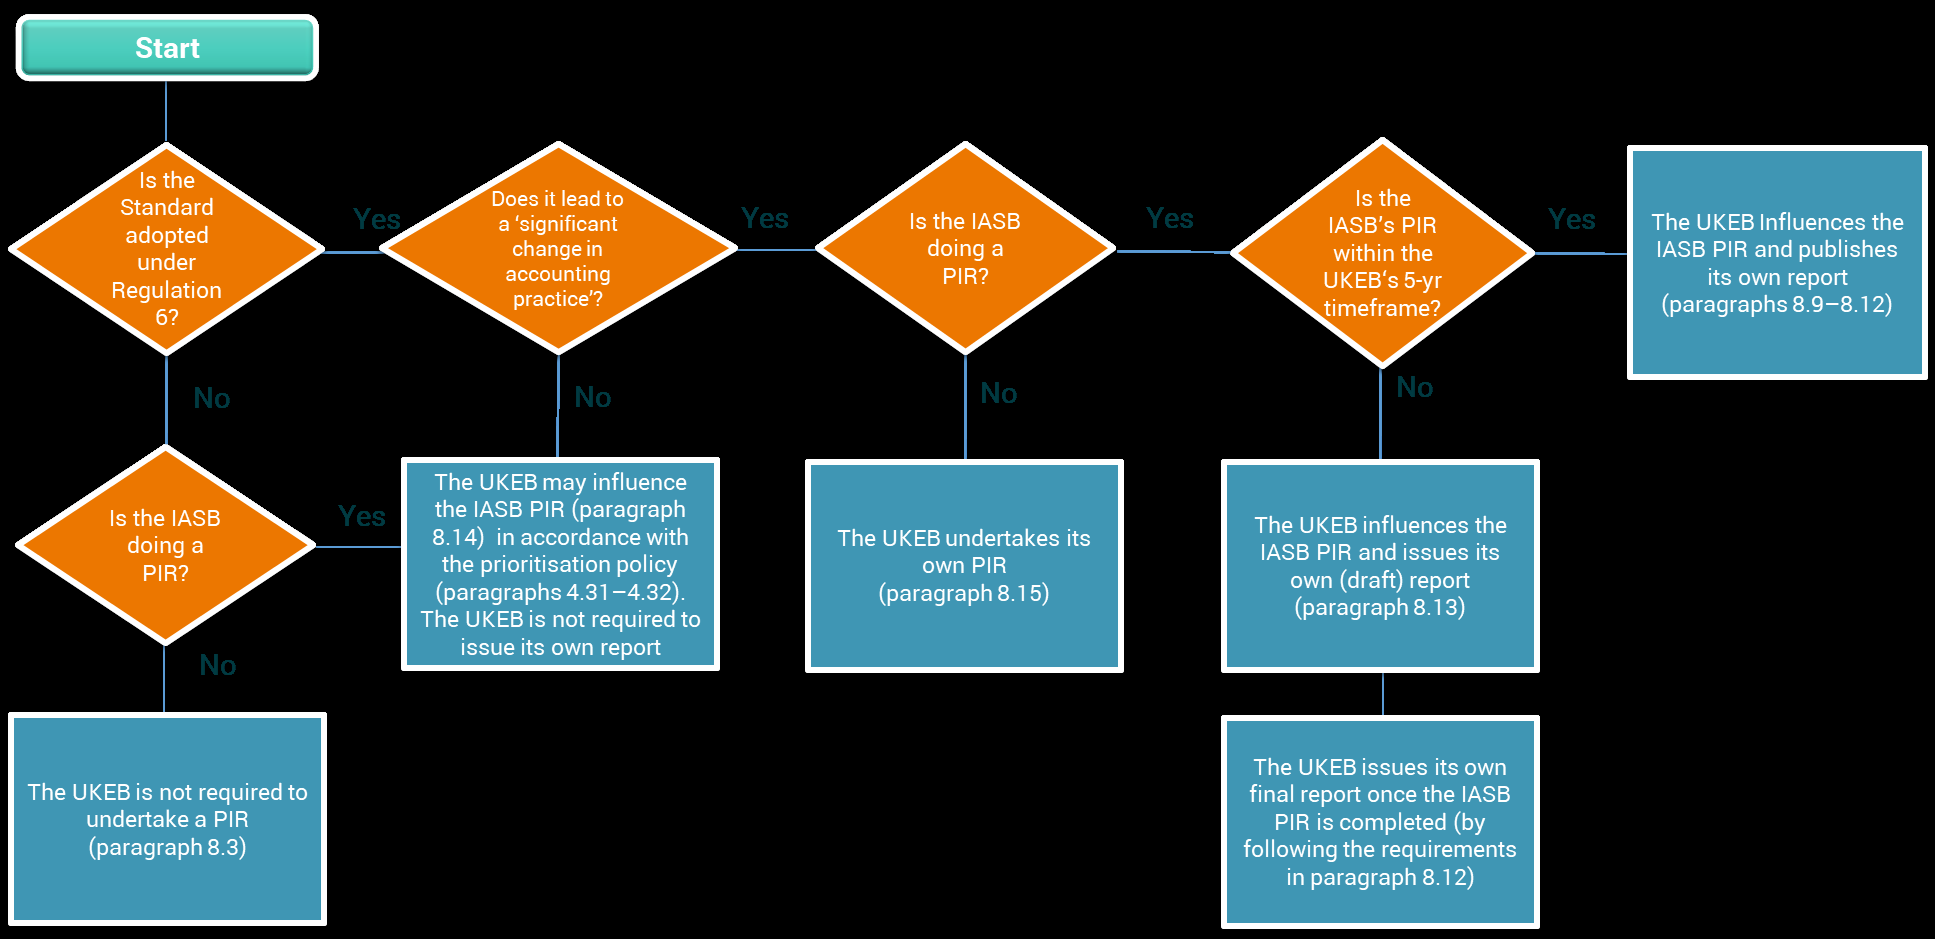
Appendix D: Illustrative diagram to determine whether to undertake a post-implementation review (PIR)
<a class="section__global-number" href="#paragraph-5-5-1" id="paragraph-5-5-1">5.5</a>Where a vote by the UK Endorsement Board to adopt a standard, amendment, or interpretation, in whole or in part, has failed to reach the required majority and, in the opinion of the Chair, there is no prospect of such majority being reached, the UK Endorsement Board Chair must provide a written explanation of circumstances to the Secretary of State within 10 working days of the failure to adopt. The Secretary of State may require further evidence. The Chair must inform Members of any recommendations by the Secretary of State.

<a class="section__global-number" href="#paragraph-4-3-1" id="paragraph-4-3-1">4.3</a> A decision to adopt a new or amended standard must be made at a public Board meeting and is tentative only. This decision must be formalised by circulation outside the meeting by a formal written vote in favour by two-thirds of Members. Paragraphs 6.42–6.48 of the Handbook provide more details on the process followed by the Board in deciding whether to endorse a new or amended standard.

### Voting process for approving or reviewing the UKEB's Due Process Handbook

<a class="section__global-number" href="#paragraph-4-4-1" id="paragraph-4-4-1">4.4</a> The approval and any future revisions to the Handbook require discussion and approval at a public Board meeting. The revisions to the Handbook will take place under normal circumstances every five years (ToR paragraph 10.2(c)).

<a class="section__global-number" href="#paragraph-4-5-1" id="paragraph-4-5-1">4.5</a> The Board's approval of the Handbook and of any revision to it requires the support of a simple majority of the Members present at the meeting. Following this approval, it will be published on the UKEB website.

### Voting process for other decisions

<a class="section__global-number" href="#paragraph-4-6-1" id="paragraph-4-6-1">4.6</a> Other decisions at public meetings do not require a formal written vote by the Board. They require the support of a simple majority of the Members present at the meeting, with approval given in a public meeting.

### Transparency of meetings and stakeholder observers

<a class="section__global-number" href="#paragraph-4-7-1" id="paragraph-4-7-1">4.7</a> The UKEB's ToR set out the operating procedures that the UKEB applies in carrying out its responsibilities. Those procedures include the frequency and form of Board meetings (in Section 6 of the ToR), as well as rules for observers attending these meetings (in Section 7 of the ToR).

<a class="section__global-number" href="#paragraph-4-8-1" id="paragraph-4-8-1">4.8</a> The Board may hold meetings in person, by webcast, or by telephone or other similar means. In deciding the format of meeting, the UKEB Chair should take into consideration public access and attendance (ToR paragraph 6.2).

<a class="section__global-number" href="#paragraph-4-9" id="paragraph-4-9">4.9</a> Regular meetings of the Board are planned as far in advance as is practicable to help the UKEB Secretariat ('Secretariat'), Members, official observers (with speaking rights) of the Board and stakeholders prepare for those meetings. The meetings schedule for the calendar year is published on the UKEB website (ToR paragraph 8.2).

<a class="section__global-number" href="#paragraph-4-10" id="paragraph-4-10">4.10</a> Meetings are held in public and open to attendance by members of the public (as non-speaking observers). However, the Board may hold certain discussions in private or in the presence of invited observers with speaking rights only. For instance:

<ol markdown="1" type="a">
<li markdown="1">meetings held to discuss administrative issues (ToR paragraph 5.6); or</li>
<li markdown="1">education sessions held before public Board meetings, for example, to enable Members to improve their understanding of new or complex proposals or standards.</li>
</ol>
<a class="section__global-number" href="#paragraph-4-11" id="paragraph-4-11">4.11</a> Only Members and observers with speaking rights[^13] (ToR paragraph 3.4(e)) have the right to speak at Board meetings. Other individuals may be invited by the UKEB Chair to speak at all or part of any meeting, as and when appropriate (ToR, paragraph 7.2).

<a class="section__global-number" href="#paragraph-4-12" id="paragraph-4-12">4.12</a> Only public meetings are recorded and, whenever practicable, webcast live. Recordings of public meetings are made available on the UKEB website.

### Minutes of Board meetings

#### Minutes of public Board meetings

<a class="section__global-number" href="#paragraph-4-13" id="paragraph-4-13">4.13</a> Minutes of UKEB public meetings summarise the Board discussion and decisions reached.

<a class="section__global-number" href="#paragraph-4-14" id="paragraph-4-14">4.14</a> Section 9 of the UKEB's ToR sets out the requirement to minute UKEB public meetings and any decisions made by the Board to ensure stakeholders are informed about the UKEB's activities, including tentative decisions made by Members to adopt a new or amended standard before those decisions are formalised by a written vote (ToR paragraph 5.3). In line with these requirements:

<ol markdown="1" type="a">
<li markdown="1">The Secretary to the Board (i.e. the Operations Director, or their nominee) minutes the meetings and decisions of the UKEB, including recording the names of those present and in attendance (ToR paragraph 9.2). The Secretariat is responsible for ensuring that the minutes reflect the Board's decisions at each meeting.</li>
</ol>
<a class="section__global-number" href="#paragraph-4-15" id="paragraph-4-15">4.15</a> The minutes for public meetings serve to inform interested parties about the progress made on technical projects in a timely manner.

#### Minutes of private Board meetings

<a class="section__global-number" href="#paragraph-4-16" id="paragraph-4-16">4.16</a> The minutes for each UKEB private meeting are circulated to Members for approval at the next private meeting. Once approved extracts of the minutes are published and made available on the UKEB website.

### UKEB Secretariat papers

<a class="section__global-number" href="#paragraph-4-17" id="paragraph-4-17">4.17</a> Section 8 of the UKEB's ToR sets out requirements for the notice of meetings and Secretariat papers for public meetings.

<a class="section__global-number" href="#paragraph-4-18" id="paragraph-4-18">4.18</a> The Secretariat is responsible for developing papers with recommendations and supporting analysis of technical issues for consideration by the members of the Board.

<a class="section__global-number" href="#paragraph-4-19" id="paragraph-4-19">4.19</a> The objective of the Secretariat papers is to provide enough information for members of the Board to make informed decisions on technical matters. In developing these papers, the Secretariat is expected to conduct research, stakeholder outreach and to seek advice from members of the Board. However, recommendations ultimately reflect the Secretariat's views, after consideration of the information obtained.

<a class="section__global-number" href="#paragraph-4-20" id="paragraph-4-20">4.20</a> The Board agenda and Secretariat papers for each public meeting are usually made available on the UKEB website no later than five working days[^14] before they are scheduled for discussion at a Board meeting (ToR, paragraph 8.3). This is to allow Members enough time to consider and assess the Secretariat's recommendations. It is the responsibility of the UKEB members to assess whether they have sufficient information and time to be able to make decisions based on the Secretariat's recommendations. Secretariat papers may have to be distributed closer to the meeting date, in exceptional circumstances only, and with the prior approval of the UKEB Chair, for example if an urgent issue has arisen.

<a class="section__global-number" href="#paragraph-4-21" id="paragraph-4-21">4.21</a> Also, only in exceptional circumstances, and taking into consideration the Guiding Principles, the UKEB Chair may, at their absolute discretion, decide that all or part of certain Secretariat papers used for discussion by the Board at public meetings should not be made publicly available (ToR, paragraph 8.4). This may be, for example, if releasing that information could breach UK law, commercial confidentiality or prejudice the conduct of public affairs. However, such circumstances are expected to be rare.

<a class="section__global-number" href="#paragraph-4-22" id="paragraph-4-22">4.22</a> Secretariat papers used for discussion by the Board at private Board meetings are not made publicly available.

<a class="section__global-number" href="#paragraph-4-23" id="paragraph-4-23">4.23</a> The Secretariat may supplement papers orally at a Board meeting, for example, to provide an update on recent events.

### Keeping stakeholders informed

<a class="section__global-number" href="#paragraph-4-24" id="paragraph-4-24">4.24</a> As a part of the guiding principle of transparency (ToR paragraph 4.4), the UKEB is committed to keeping its stakeholders and the general public informed about its activities. The principal means of communication between the UKEB and its stakeholders is through public meetings, and the posting of relevant information and documents on the UKEB website.

<a class="section__global-number" href="#paragraph-4-25" id="paragraph-4-25">4.25</a> In particular, the UKEB publishes on its website:

<ol markdown="1" type="a">
<li markdown="1">Its work plan, meeting schedules and agenda.</li>
<li markdown="1">Its progress on individual projects or the Board's deliberations and compliance with due process by posting:
<ol markdown="1" type="i">
<li markdown="1">public Secretariat papers to be discussed at public Board meetings;</li>
<li markdown="1">minutes of public Board meetings summarising the Board discussion and decisions reached after approval by the Board (ToR, paragraph 9.2);</li>
<li markdown="1">links to the recordings of public Board meetings; and</li>
<li markdown="1">the draft/final comment letters submitted to the IASB, draft/final Endorsement Criteria Assessments and project closure documents such as feedback statements, due process compliance statements or adoption statements.</li>
</ol>
</li>
<li markdown="1">Media and information releases relating to its activities.</li>
<li markdown="1">IASB or IFRS Interpretations Committee consultation documents open for comment that are part of the projects included in the UKEB's work plan, by providing links to these documents on the IASB's website.</li>
<li markdown="1">Any comment letters submitted to the UKEB, whether in response to consultation documents or unsolicited, unless the respondent has requested confidentiality.</li>
</ol>
<ol markdown="1" type="f">
<li markdown="1">Access to educational materials or webinars.</li>
</ol>
<a class="section__global-number" href="#paragraph-4-26" id="paragraph-4-26">4.26</a> All public materials, including those related to the UKEB due process, are freely available on the website.

### Complaints process

<a class="section__global-number" href="#paragraph-4-27" id="paragraph-4-27">4.27</a> The UKEB's complaints policy is accessible on its website[^15]. The UKEB reviews complaints on its standard of service, the behaviour of its personnel and on any action or lack of action by personnel affecting an individual or group when exercising or failing to exercise the UKEB's functions.

### UKEB's work plan

<a class="section__global-number" href="#paragraph-4-28" id="paragraph-4-28">4.28</a> The UKEB's work plan consists of a set of technical projects that the UKEB manages.

<a class="section__global-number" href="#paragraph-4-29" id="paragraph-4-29">4.29</a> As a starting point and absent evidence to the contrary, the UKEB assumes that where a technical issue is significant enough to be added to the IASB's work plan, similar issues exist in the UK and therefore merit addition to the UKEB's technical work plan. The Board, in consultation with the Technical Director, prioritises individual projects and resource allocation based on the factors mentioned in paragraphs 4.31–4.32 of this Handbook.

<a class="section__global-number" href="#paragraph-4-30" id="paragraph-4-30">4.30</a> The UKEB's work plan includes the projects mentioned below. This list does not attach any priority.

<ol markdown="1" type="a">
<li markdown="1">Research projects derived from the UKEB's thought leadership and research programme[^16].</li>
<li markdown="1">Influencing projects[^17] that include technical issues identified by the IASB and by the IFRS Interpretations Committee that give rise to:
<ol markdown="1" type="i">
<li markdown="1">proposals for minor or narrow-scope amendments to international accounting standards that meet the IASB's criteria for annual improvements or for narrow-scope amendments[^18];</li>
<li markdown="1">proposals for new standards or major amendments to existing standards;</li>
</ol>
</li>
</ol>
<ol markdown="1" type="i">
<li markdown="1">research proposals;</li>
<li markdown="1">requests for information (for example on the IASB's post-implementation reviews or on consultations on the IASB's work plan);</li>
<li markdown="1">draft IFRIC Interpretations; and</li>
<li markdown="1">IFRIC tentative agenda decisions on which the Board has decided to respond to the IFRS Interpretations Committee[^19].</li>
</ol>
<ol markdown="1" type="c">
<li markdown="1">The UKEB's own post-implementation review projects[^20].</li>
<li markdown="1">Endorsement projects[^21], which include the endorsement and adoption of new or amended standards.</li>
<li markdown="1">International Sustainability Standards Board (ISSB) projects that have an overlap with IASB projects[^22].</li>
</ol>

### Prioritising technical projects in the UKEB's work plan

<a class="section__global-number" href="#paragraph-4-31" id="paragraph-4-31">4.31</a> In prioritising and allocating resources to individual projects, the level of activities should be proportionate to the issue being addressed. To help assess the issue, the Board considers various factors, including:

<ol markdown="1" type="a">
<li markdown="1">the importance of the issue to UK stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies, regulators and others interested in financial reporting);</li>
<li markdown="1">the effect an issue has or is expected to have on the UK economy or UK entities using UK-adopted international accounting standards, including both the number of entities affected and the size of the effect;</li>
<li markdown="1">interactions with other current or proposed projects on the work plan;</li>
<li markdown="1">the urgency of the issue;</li>
<li markdown="1">consideration of the timeline reflecting an intention to complete endorsement considerations in advance of the effective date of the IASB's new or amended standard; and</li>
</ol>
<ol markdown="1" type="f">
<li markdown="1">the availability of staff resources.</li>
</ol>
<a class="section__global-number" href="#paragraph-4-32" id="paragraph-4-32">4.32</a> The assessment is not limited to using the IASB's assessment of the potential impact of a project as the UKEB's remit is different. The IASB considers the potential impact on many jurisdictions whereas the UKEB assesses the potential impact from a UK perspective. This may mean that in the UK the UKEB allocates a different significance to a project compared with the IASB. For example, when UK entities do not frequently undertake the types of transactions addressed in an IASB project, the project would be allocated a lower significance and a reduced number of outreach activities would be planned.

### Updating the UKEB's work plan

<a class="section__global-number" href="#paragraph-4-33" id="paragraph-4-33">4.33</a> The UKEB's work plan is updated regularly to add or remove projects from the work plan and to reflect estimated project timelines on the basis of recent Board decisions. It is presented for approval at the Board private meetings and once approved, is uploaded onto the UKEB website.

### Consulting on the UKEB's work plan

<a class="section__global-number" href="#paragraph-4-34" id="paragraph-4-34">4.34</a> The UKEB consults on its work plan every year as part of its consultation on its regulatory strategy as required by paragraph 3.2(j) of the ToR[^23].

## 5. Influencing process {: #section-5-influencing-process }

### Overview of the UKEB's influencing process

<a class="section__global-number" href="#paragraph-5-1-1" id="paragraph-5-1-1">5.1</a> The UKEB shares a common objective with other national standard setters: that of influencing the development and maintenance of high-quality, understandable, enforceable and globally accepted international accounting standards after consulting[^24] with the public and gathering stakeholder feedback on documents for comment. The means of achieving this objective is set out in this section.

<a class="section__global-number" href="#paragraph-5-2-1" id="paragraph-5-2-1">5.2</a> The UKEB's influencing activities include the proactive monitoring by the Secretariat of a range of projects being undertaken by the IASB and IFRS Interpretations Committee. As part of UKEB public meetings, the Secretariat provides the Board with a general update on the progress and decisions being made by the IASB on active projects, on the matters discussed at IFRS Interpretations Committee meetings, and on the matters discussed by the ISSB. The Board discussions may result in the identification of specific concerns or areas of focus for future work by the UKEB[^25] and, where appropriate, the UKEB may consider communicating this feedback to the IASB, to the IFRS Interpretations Committee[^26] or to the ISSB.

### Milestones

<a class="section__global-number" href="#paragraph-5-3-1" id="paragraph-5-3-1">5.3</a> The milestones for influencing projects (except for tentative agenda decisions[^27]) are shown below. In undertaking activities to achieve those milestones, the UKEB takes a proportionate approach (refer to paragraphs 3.5–3.9 of this Handbook).

<ol markdown="1" type="a">
<li markdown="1">Project initiation plan (mandatory).</li>
<li markdown="1">Desk-based research.</li>
<li markdown="1">Outreach activities (mandatory).</li>
<li markdown="1">Draft comment letter (generally mandatory unless impracticable).</li>
<li markdown="1">Final comment letter (mandatory).</li>
</ol>
<ol markdown="1" type="f">
<li markdown="1">Project closure, including:
<ol markdown="1" type="i">
<li markdown="1">A feedback statement (mandatory); and</li>
<li markdown="1">A due process compliance statement (mandatory).</li>
</ol>
</li>
</ol>

### Project initiation plan (mandatory)

<a class="section__global-number" href="#paragraph-5-4-1" id="paragraph-5-4-1">5.4</a> A project initiation plan (PIP) is prepared for approval by the Board at a public meeting at the commencement of an influencing project.

<a class="section__global-number" href="#paragraph-5-5-a" id="paragraph-5-5-2">5.5</a> The objective of the PIP for an influencing project is to assess the potential impact and scale of the proposals being addressed by the project and, consequently, the level of analysis and outreach that should be undertaken in line with a proportionate approach (refer to paragraphs 3.5–3.9 of the Handbook).

<a class="section__global-number" href="#paragraph-5-6" id="paragraph-5-6">5.6</a> For a description of the purpose and content of the PIP refer to paragraphs A1–A2 in Appendix A of this Handbook.

<a class="section__global-number" href="#paragraph-5-7" id="paragraph-5-7">5.7</a> If changes arise subsequent to commencement of a project and these changes represent a major change to the nature or scope of a project, the PIP is updated to address those changes. The revised PIP is tabled for noting at a public meeting, giving Members the opportunity to discuss it if necessary.

<a class="section__global-number" href="#paragraph-5-8" id="paragraph-5-8">5.8</a> The project plan included in the PIP as approved by the Board forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraphs A12–A14 in Appendix A of this Handbook for the description of a 'due process compliance statement').

### Desk-based research

<a class="section__global-number" href="#paragraph-5-9" id="paragraph-5-9">5.9</a> Desk-based research may be undertaken to assist with the assessment of the appropriate extent of analysis and outreach and to gather evidence on the issue under consideration. For a description of this type of research refer to paragraph A3 in Appendix A of this Handbook.

### Outreach activities (mandatory)

<a class="section__global-number" href="#paragraph-5-10" id="paragraph-5-10">5.10</a> In line with its guiding principle of accountability (ToR paragraph 4.2(d)), the UKEB gathers input, views, opinions or other feedback from UK stakeholders on specific projects to influence the development of a proposal for a new or amended standard and to build robust and evidence-based recommendations to the IASB.

<a class="section__global-number" href="#paragraph-5-11" id="paragraph-5-11">5.11</a> The UKEB always undertakes some outreach activity to gather feedback on influencing projects. The amount and type of outreach to be undertaken, together with the rationale, is highlighted in the PIP.

<a class="section__global-number" href="#paragraph-5-12" id="paragraph-5-12">5.12</a> For a description of the potential outreach activities that could be undertaken refer to paragraphs A4–A8 in Appendix A of this Handbook.

### Draft comment letter (generally mandatory)

<a class="section__global-number" href="#paragraph-5-13" id="paragraph-5-13">5.13</a> A draft comment letter is issued in all circumstances unless impracticable (see paragraph 5.17).

<a class="section__global-number" href="#paragraph-5-14" id="paragraph-5-14">5.14</a> A draft comment letter explains the UKEB's preliminary response to an IASB or an IFRS Interpretations Committee consultation document. It is made available for public consultation on the UKEB website once approved by the Board. This letter is normally preceded or accompanied by an Invitation to Comment that sets out the matters on which feedback is sought.

<a class="section__global-number" href="#paragraph-5-15" id="paragraph-5-15">5.15</a> The consultation period for a draft comment letter is not less than 30 days unless this period is shortened (refer to paragraph 5.16).

### Draft comment letter with a shorter consultation period

<a class="section__global-number" href="#paragraph-5-16" id="paragraph-5-16">5.16</a> The UKEB may decide to issue a draft comment letter with a reduced comment period of less than 30 days when there is limited time to consult (i.e. due to the urgency of an issue or to the existence of reduced comment periods set by the IASB[^28]). The rationale for a shorter consultation period is given in the PIP (refer to paragraph A2(e) in Appendix A of this Handbook).

<a class="section__global-number" href="#paragraph-5-17" id="paragraph-5-17">5.17</a> If issuing a draft comment letter even with a reduced comment period is not practicable (e.g. because the deadline to respond to the IASB makes it impracticable to receive and analyse responses), the UKEB still carries out outreach activities to obtain input from UK stakeholders[^29].

### Final comment letter (mandatory)

<a class="section__global-number" href="#paragraph-5-18" id="paragraph-5-18">5.18</a> The UKEB considers the stakeholder feedback received on the draft comment letter or from other outreach undertaken and uses this input to issue a final version of the comment letter to the IASB. The Board approves the final comment letter at a public meeting. The final comment letter is submitted to the IASB and posted on the UKEB website. The comment letters submitted to the UKEB (where the respondent has not requested confidentiality) will be published on the UKEB website when received.

### Project closure

#### Feedback statement (mandatory)

<a class="section__global-number" href="#paragraph-5-19" id="paragraph-5-19">5.19</a> Consultation feedback received on the draft comment letter (and any other input and feedback derived from other outreach activities after publication of the draft comment letter) is recorded, assessed, the evidence evaluated, and reported in a feedback statement. Where the UKEB does not publish a draft comment letter, the Secretariat provides a summary of the feedback received from the outreach undertaken in a feedback statement.

<a class="section__global-number" href="#paragraph-5-20" id="paragraph-5-20">5.20</a> For a description of the purpose and content of a feedback statement refer to paragraphs A9–A11 in Appendix A of this Handbook.

<a class="section__global-number" href="#paragraph-5-21" id="paragraph-5-21">5.21</a> The Board discusses and provides comments on a draft feedback statement and approves the final feedback statement for publication.

<a class="section__global-number" href="#paragraph-5-22" id="paragraph-5-22">5.22</a> A feedback statement is published on the UKEB website, usually at the same time as the final comment letter is submitted to the IASB.

#### Due process compliance statement (mandatory)

<a class="section__global-number" href="#paragraph-5-23" id="paragraph-5-23">5.23</a> The Secretariat summarises the due process activities undertaken in a closing control report called 'due process compliance statement'. For a description of the purpose and content of this statement refer to paragraphs A12–A14 in Appendix A of this Handbook.

<a class="section__global-number" href="#paragraph-5-24" id="paragraph-5-24">5.24</a> The (draft) due process compliance statement is initially presented to the Board along with the final comment letter and feedback statement for approval.

<a class="section__global-number" href="#paragraph-5-25" id="paragraph-5-25">5.25</a> The Board discusses, provides comments and approves a (draft) due process compliance statement at a public Board meeting. A final version of this compliance statement reflecting completion of the final stages of the project is brought to the Board for noting at a subsequent meeting.

<a class="section__global-number" href="#paragraph-5-26" id="paragraph-5-26">5.26</a> Once the final version of the due process compliance statement has been noted by the Board it is published on the UKEB website.

### Influencing tentative agenda decisions

<a class="section__global-number" href="#paragraph-5-27" id="paragraph-5-27">5.27</a> The IFRS Interpretations Committee publishes tentative agenda decisions to explain why a standard-setting project should not be added to the IASB's work plan to address a question submitted. The comment period for a tentative agenda decision is normally 60 days[^30].

<a class="section__global-number" href="#paragraph-5-28" id="paragraph-5-28">5.28</a> When the Board reviews the Secretariat's update on the IFRS Interpretations Committee's activities as part of its monitoring activities (refer to paragraph 5.2) the Board decides whether to respond to a tentative agenda decision.

<a class="section__global-number" href="#paragraph-5-29" id="paragraph-5-29">5.29</a> The UKEB expects to respond to a limited number of tentative agenda decisions published by the IFRS Interpretations Committee. Some factors to consider when deciding whether to respond may be:

<ol markdown="1" type="a">
<li markdown="1">The degree of impact of the IFRS Interpretations Committee tentative agenda decision on UK companies (for example, in cases when the tentative agenda decision is expected to affect a significant number of UK companies);</li>
<li markdown="1">Disagreement with the analysis performed by the IFRS Interpretations Committee; or</li>
<li markdown="1">Usefulness of the explanations and clarifications included in the tentative agenda decision.</li>
</ol>
<a class="section__global-number" href="#paragraph-5-30" id="paragraph-5-30">5.30</a> The Board might also choose to respond to a tentative agenda decision even if it agrees with the analysis performed by the IFRS Interpretations Committee, to provide public support for the tentative agenda decision. For example, this may apply in cases where others have expressed disagreement with the analysis in the tentative agenda decision.

<a class="section__global-number" href="#paragraph-5-31" id="paragraph-5-31">5.31</a> If an issue discussed by the IFRS Interpretations Committee arises outside the usual Board meeting cycle, the UKEB Chair can approve initiation of work on the tentative agenda decision.

### Project milestones for tentative agenda decisions

<a class="section__global-number" href="#paragraph-5-32" id="paragraph-5-32">5.32</a> Given that the consultation period for a tentative agenda decision is usually 60 days, which is much shorter than for other IASB due process documents, the UKEB is not able to follow all the milestones in paragraph 5.3. However, some outreach activities are undertaken, e.g. consultation with a representative group of stakeholders and/or with members of the UKEB's standing and/or ad-hoc advisory groups.

<a class="section__global-number" href="#paragraph-5-33" id="paragraph-5-33">5.33</a> After considering comments from UK stakeholders on tentative agenda decisions, the UKEB may decide to recommend that the IFRS Interpretations Committee:

<ol markdown="1" type="a">
<li markdown="1">finalises a tentative agenda decision[^31];</li>
</ol>
<ol markdown="1" type="b">
<li markdown="1">revises (or abandons) a tentative agenda decision; or</li>
<li markdown="1">refers the matter to the IASB to consider adding a standard-setting project to the IASB's work plan.</li>
</ol>

## 6. Endorsement process {: #section-6-endorsement-process }

### UK statutory requirements for endorsement and adoption

<a class="section__global-number" href="#paragraph-6-1" id="paragraph-6-1">6.1</a> New or amended standards issued by the IASB are not part of UK-adopted international accounting standards until the UKEB has endorsed and adopted those standards[^32].

<a class="section__global-number" href="#paragraph-6-2" id="paragraph-6-2">6.2</a> The primary objective of endorsing and adopting international accounting standards for use in the UK as set out in SI 2019/685[^33] is to harmonise the financial information presented by relevant companies.

<a class="section__global-number" href="#paragraph-6-3" id="paragraph-6-3">6.3</a> This is to ensure:

<ol markdown="1" type="a">
<li markdown="1">a high degree of transparency and international comparability of financial statements; and</li>
<li markdown="1">the efficient allocation of capital, including the smooth functioning of capital markets in the United Kingdom.</li>
</ol>
<a class="section__global-number" href="#paragraph-6-4" id="paragraph-6-4">6.4</a> The regulatory power embodied in the UKEB's endorsement and adoption function lends weight and authority to the UKEB's influencing activity.

<a class="section__global-number" href="#paragraph-6-5" id="paragraph-6-5">6.5</a> The UKEB adopts international accounting standards for use within the UK, in accordance with Regulations 6–9 in SI 2019/685 (these Regulations are described below).

<a class="section__global-number" href="#paragraph-6-6" id="paragraph-6-6">6.6</a> Regulation 6. Permits the adoption of a standard in part only and/or to extend an option available as part of a standard. The Regulation states that this may occur 'in exceptional circumstances'. Regulation 6(3)(b) indicates that the amended standard (i.e. the part-adopted standard) would need to meet the endorsement criteria set out in Regulation 7.

<a class="section__global-number" href="#paragraph-6-7" id="paragraph-6-7">6.7</a> Regulation 7. Requires that an international accounting standard only be adopted if:

<blockquote markdown="1">'(a) the standard is not contrary to either of the following principles—
<ol markdown="1" type="i">
<li markdown="1">an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;</li>
<li markdown="1">consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;</li>
</ol>
(b) the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
(c) the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.'</blockquote>
<a class="section__global-number" href="#paragraph-6-8" id="paragraph-6-8">6.8</a> Regulation 8. Contains a requirement to consult those with an interest in the quality and availability of accounts, including users and preparers, before adopting a standard.

<a class="section__global-number" href="#paragraph-6-9" id="paragraph-6-9">6.9</a> Regulation 9. Sets out the requirement to publish a final decision on adopting a new or amended international accounting standard.

### Overview of UKEB endorsement and adoption process

<a class="section__global-number" href="#paragraph-6-10" id="paragraph-6-10">6.10</a> The UKEB applies its own process before it decides whether to endorse and adopt a new or amended international accounting standard. This process is to ensure the Board fulfils its statutory responsibility relating to endorsement and adoption of international accounting standards (described in paragraphs 6.1–6.9). This process takes place after a new or amended standard has been issued by the IASB and before the standard is effective. This process is described below.

### Milestones

<a class="section__global-number" href="#paragraph-6-11" id="paragraph-6-11">6.11</a> The milestones for endorsement and adoption projects are listed below. In undertaking activities to achieve these milestones, the UKEB takes a proportionate approach (refer to paragraphs 3.5–3.9 of this Handbook):

<ol markdown="1" type="a">
<li markdown="1">Project initiation plan (mandatory).</li>
<li markdown="1">Desk-based research.</li>
<li markdown="1">Outreach activities (mandatory).</li>
<li markdown="1">Draft Endorsement Criteria Assessment (DECA) (mandatory).</li>
</ol>
<ol markdown="1" type="e">
<li markdown="1">Project closure, including vote on adoption as well as the following documents:
<ol markdown="1" type="i">
<li markdown="1">Final Endorsement Criteria Assessment (ECA) (mandatory).</li>
<li markdown="1">Feedback statement (mandatory).</li>
<li markdown="1">Due process compliance statement (mandatory).</li>
<li markdown="1">Adoption statement (mandatory).</li>
</ol>
</li>
<li markdown="1">Publication of the documents set out in (e) (mandatory).</li>
</ol>

### Project initiation plan (mandatory)

<a class="section__global-number" href="#paragraph-6-12" id="paragraph-6-12">6.12</a> A project initiation plan (PIP) is prepared for approval by the Board at a public meeting at the commencement of an endorsement project.

<a class="section__global-number" href="#paragraph-6-13" id="paragraph-6-13">6.13</a> The objective of the PIP for an endorsement project is to assess the potential impact and scale of the new or amended standard and, consequently, the level of analysis and outreach that should be undertaken in line with a proportionate approach (refer to paragraphs 3.5–3.9 of the Handbook).

<a class="section__global-number" href="#paragraph-6-14" id="paragraph-6-14">6.14</a> For a description of the purpose and content of the PIP refer to paragraphs A1–A2 in Appendix A of this Handbook.

<a class="section__global-number" href="#paragraph-6-15" id="paragraph-6-15">6.15</a> If changes arise subsequent to commencement of a project and these changes represent a major change to the nature or scope of a project, the PIP is updated to address those changes. The revised PIP is tabled for noting at a public meeting, giving Members the opportunity to discuss it if necessary.

<a class="section__global-number" href="#paragraph-6-16" id="paragraph-6-16">6.16</a> The project plan included in the PIP as approved by the Board forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraphs A12–A14 in Appendix A of this Handbook for the description of a 'due process compliance statement').

### Desk-based research

<a class="section__global-number" href="#paragraph-6-17" id="paragraph-6-17">6.17</a> Desk-based research may be undertaken to assist with the assessment of the appropriate extent of analysis and outreach and to gather evidence on the issue under consideration. For a description of this type of research refer to paragraph A3 in Appendix A of this Handbook.

### Outreach activities (mandatory)

<a class="section__global-number" href="#paragraph-6-18" id="paragraph-6-18">6.18</a> In line with its guiding principle of accountability (ToR paragraph 4.2(d)), the UKEB gathers input, views, opinions or other feedback from UK stakeholders to determine whether a specific ‘endorsement project' meets the UK's statutory requirements for endorsement and adoption (refer to paragraph 6.7 of this Handbook for a description of these requirements).
6.19 The UKEB always undertakes some outreach activity to gather feedback on the DECA. The amount and type of outreach to be undertaken, together with the rationale, is highlighted in the PIP. The responses received during the influencing phase may also be relevant in deciding the level of outreach for endorsement projects.
6.20 For a description of the potential outreach activities that could be undertaken refer to paragraphs A4–A8 in Appendix A of this Handbook.
6.21 As a minimum, Regulation 8 of SI 2019/685 requires the UKEB to consult with a representative range of stakeholders before adopting an international accounting standard. Publication of the DECA on the UKEB website and notifying UK stakeholders is expected to be sufficient in the following situations:
- When amendments to international accounting standards are minor and meet the criteria for annual improvements or for narrow-scope amendments.
- When there is limited time to consult e.g. for an urgent narrow-scope amendment issued by the IASB where it shortens the period between publication date and effective date of the amendment13 and the amendment is urgently required to be adopted by entities.
6.22 For more complex projects that include major amendments, the UKEB conducts, using the principle of proportionality, activities appropriate to the nature and/or size of the amendment or standard to be endorsed and adopted. This is, for example, when:
- an amendment or standard changes an area of accounting that affects most UK entities applying UK-adopted international accounting standards; or
- an amendment or standard changes an area of accounting that affects a small number of UK entities applying UK-adopted international accounting standards but it is a major change.
Draft Endorsement Criteria Assessment (DECA)
6.23 A Draft Endorsement Criteria Assessment (DECA) is a mandatory milestone before endorsing and adopting a new or amended international accounting standard and constitutes a formal assessment of whether the new or amended standard meets the endorsement criteria. These criteria are set out in paragraph 6.7 of this Handbook.
Content
6.24 In general, a DECA considers and addresses the following:
- Introduction: legislative framework and approach to the assessment:
- purpose of the DECA;
- summary and explanation of legislative background to endorsement criteria; and
- description of endorsement criteria (including text of criteria from SI 2019/685) and what is meant by each criterion.
- Rationale for the new or amended international accounting standard, i.e. summary background, context and objectives and main accounting requirements.
- Whether or not the standard is not contrary to the principle that an entity’s accounts or consolidated accounts must give a true and fair view (SI 2019/685 Regulation 7(1)(a))14.
- Whether or not use of the new or amended standard is likely to be conducive to the long term public good in the UK (SI 2019/685 Regulation 7(1)(b)), including:
- whether the use of the standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the standard15;
- whether the use of the standard is likely to have an adverse effect on the economy of the UK, including on economic growth.
- Whether or not the standard meets the criteria of relevance, reliability, comparability and understandability required of the financial information needed for making economic decisions and assessing the stewardship of management (SI 2019/685 Regulation 7(1)(c)).
- Whether or not the new or amended standard is likely to lead to a significant change in accounting practice (refer to paragraph 8.6 of this Handbook) and therefore, whether it meets the criteria for a post-implementation review. If it does, the DECA/ECA should additionally indicate the proposed timing of that review (refer to paragraph 8.7 of this Handbook) and follow the requirements in Section 8 ‘Post-implementation reviews’ of this Handbook.
6.25 In relation to the assessment of whether a new or amended standard is likely to be conducive to the long-term public good in the UK, the UKEB undertakes economic analysis work in a proportionate way to the nature and scope of the project.
6.26 Where one or more Members are considering not supporting the endorsement and adoption of a new or amended standard, the relevant matter(s) and concern(s) of the Member(s) should be reflected in the DECA, so that it is included in the public consultation (refer to paragraph 6.45 of this Handbook).
6.27 A DECA is approved by the Board at a public meeting and made available for public consultation on the UKEB website.
6.28 The consultation period for a DECA is not less than 90 days unless this period is shortened (refer to paragraph 6.29 below).
DECA with a shorter consultation period
6.29 The UKEB may decide to issue a DECA with a consultation period of less than 90 days but not less than 14 days when there is limited time to consult (e.g. for an urgent narrow-scope amendment issued by the IASB where the period between publication date and effective date is short and the amendment is urgently required to be adopted by entities). The rationale for a shorter consultation period is given in the PIP (refer to paragraph A2(e) in Appendix A of this Handbook).
Project closure
6.30 The project closure process for endorsement projects comprises the following steps:
- preparation of an 'adoption package' by the Secretariat (mandatory); and
- voting on the adoption of a new or amended standard (mandatory).
Adoption package
6.31 The following paragraphs set out a description of the content of the individual documents included in the 'adoption package' which are:
- a final Endorsement Criteria Assessment (ECA);
- a feedback statement;
- a due process compliance statement;
- an adoption statement; and
- the text of UK-adopted international accounting standard that is the subject of the endorsement decision.
Final Endorsement Criteria Assessment (ECA) (mandatory)
6.32 The UKEB considers the stakeholder feedback received on the DECA and uses this input to issue a final version of the Endorsement Criteria Assessment (final ECA).
Feedback statement (mandatory)
6.33 Consultation feedback received on the DECA (and any other input and feedback derived from other outreach activities after publication of the DECA) is recorded, assessed, the evidence evaluated, and reported in a feedback statement.
6.34 For a description of the purpose and content of a feedback statement refer to paragraphs A9–A11 in Appendix A of this Handbook.
6.35 The Board discusses and provides comments on a draft feedback statement and approves the final feedback statement for publication.
6.36 A feedback statement is published on the UKEB website, usually at the same time as the final ECA is published.
Due process compliance statement (mandatory)
6.37 The Secretariat summarises the due process activities undertaken in a closing control report called 'due process compliance statement'. For a description of the purpose and content of this Statement refer to paragraphs A12–A14 in Appendix A of this Handbook.
6.38 The Board discusses, provides comments and approves a (draft) due process compliance statement at a public Board meeting. A final version of this compliance statement reflecting completion of the final steps is brought to the Board for noting at a subsequent meeting.
6.39 Once the final version of the due process compliance statement has been noted by the Board it is published on the UKEB website.
Adoption statement (mandatory)
6.40 The adoption statement includes:
- a statement that the new or amended standard has been:
- adopted for use within the UK, in compliance with the requirements in Regulations 7 and 8 of SI 2019/685 and the reasons for this decision; or
- partially adopted in accordance with paragraph (3) of Regulation 6 of SI 2019/685 and the reasons for this decision;
- when applicable, reasons for extending the scope of undertakings eligible to use an option in the standard in accordance with paragraph (4) of Regulation 6, setting out the full details;
- a description of the financial years in respect of which that standard must be used;
- the wording of the adopted standard (in a separate document); and
- a list of the Members that approved the adoption of the new or amended standard by written vote in accordance with paragraph 6.42(b) (see below).
6.41 On an annual basis, the UKEB updates the new or amended international accounting standards that have been adopted during the year into a consolidated text of UK-adopted international accounting standards16.
Voting on the adoption of a new or amended international accounting standard (mandatory)
6.42 Decisions on the endorsement and adoption of a standard or amendment are made at public Board meetings and follow the requirements in paragraphs 5.1–5.5 of the ToR17 and are summarised below:
- Quorum attendance—A minimum of sixty percent of the appointed members18 are required to attend a meeting of the Board (ToR, paragraph 5.1).
- Decision-making—The final approval for a standard to be formally adopted for use in the UK is brought to a public meeting where the Board provides a tentative vote that is subsequently formalised by a written vote. An affirmative written vote of at least two-thirds of all of the appointed Members (ToR, paragraph 5.2), is required for the decision to be passed. Each member of the Board has one vote. Where the vote to adopt a new or amended standard, in whole or in part, does not reach the required majority, the UKEB shall follow the requirements in paragraphs 5.4–5.5 of the ToR.
- Publication of the results of the vote—Within 3 working days (ToR paragraph 5.3) of completion of the written vote.
Decision-making
6.43 The Board, at a public meeting, holds a tentative vote on the decision to adopt a new or amended standard based on the discussion of the 'adoption package' (see paragraph 6.31 of this Handbook).
6.44 The Board’s tentative vote must be formalised by circulation outside the meeting by a formal written vote (in paper or electronic form). This vote constitutes proper evidence of the decisions of members of the Board.
6.45 Where a Member does not support the endorsement and adoption of a new or amended standard, that view is reflected in the DECA (refer to paragraph 6.26 of this Handbook), in the Board discussions and consequently in the Members’ vote when adopting that new or amended standard.
Publication of the results of the vote
6.46 The UKEB publishes on the UKEB website the outcome of the formal written vote19 within 3 working days of completion of the written vote.
6.47 If the vote is affirmative, the closing date of the formal written vote is the date of the formal adoption of a new or amended standard.
6.48 The adoption statement and the text of the UK-adopted international accounting standard (that is the subject of the endorsement decision) are published on the UKEB website.
7. Thought leadership and research programme
Objectives of thought leadership
7.1 In applying the principle of thought leadership, paragraph 4.5 of the UKEB’s ToR states that the UKEB will:
- Lead the UK debate on international accounting standards and reporting.
- Represent UK views in international fora with the aim of influencing debate.
- Engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
- Pro-actively participate in the development of new global accounting standards for example by undertaking research.
Leading the UK debate
7.2 The UKEB leads the UK debate on international accounting standards and reporting by:
- Actively engaging and collaborating with UK stakeholders on areas that concern UK stakeholders during the process of developing its own views, with the aim of building robust and evidence-based recommendations. The UKEB achieves this by:
- identifying key stakeholder groups, preparing outreach plans, and taking suitable approaches to each stakeholder group;
- giving UK stakeholders a platform to provide specialist input on areas of concern through roundtables, forums, workshops, panel discussions or education sessions organised by the UKEB or through the UKEB’s advisory groups;
- soliciting UK stakeholders’ comments on public consultation documents and/or UKEB draft comment letters;
- arranging, where appropriate, for IASB Board members and/or for IASB staff to participate in UKEB outreach events to enable first-hand understanding of any concerns or views expressed by UK stakeholders; and
- acting as a conduit for UK feedback on IASB consultations.
- Developing and presenting the UKEB’s own thought leadership material to promote UK views and lead the accounting debate at relevant international fora.
Participating proactively in the development of global standards
7.3 The UKEB proactively participates in the development of new global accounting standards by:
- engaging with UK stakeholders and collecting evidence on relevant technical issues and communicating such evidence to the IASB and to other national standard-setters or regional organisations;
- developing potential ways to improve or remedy deficiencies in international accounting standards; and
- working proactively with others to stimulate debate on financial reporting matters on the IASB agenda at an early stage in the standard-setting process.
Representing UK views in international fora with the aim of influencing debate
7.4 The UKEB directly influences the IASB Board and maintains a global presence on the international financial reporting stage by:
- Identifying and promoting the appointment of UK representatives to the IASB’s consultative groups, subject to available UKEB resources. For example, this will include recommending UK representatives for appointment to the IASB’s Accounting Standards Advisory Forum (ASAF) to ensure that UK input on major technical issues related to the IASB’s standard-setting activities is considered in this forum.
- Maintaining effective relationships, communication and presence with the IASB and other national standard-setters or regional organisations, subject to available UKEB resources. For example, by:
- participating in the World Standard-setters conference organised by the IASB to share international accounting standards implementation and application experiences with other standard-setters around the world;
- participating in other international accounting forums organised by other parties independently (e.g. International Forum of Accounting Standard-Setters (IFASS)); or
- regularly attending (in person or remotely) key meetings and conferences of international financial reporting bodies to ensure adequate analysis and input, including expressing UK views.
- Communicating outcomes from international engagements to UK stakeholders, to assist in identifying concerns with international proposals.
- Issuing articles, podcasts or videos, to stimulate debate on a particular matter or technical issue.
- Obtaining input from, and engaging with, stakeholders to inform our views.
Engaging with other UK bodies and bodies in other jurisdictions
7.5 Regular contact between the UKEB and the FRC as well as with other national standard-setters or regional organisations in other jurisdictions is expected to increase the understanding, awareness and support for UK views, thereby allowing the UKEB to lead on the accounting debate.
7.6 The UKEB and other national standard-setters or regional organisations can interact in a range of ways including developing joint thought leadership and research documents, regular and ad-hoc emails, conferences and roundtables, blogs, articles, regional forums or telephone exchanges.
Research programme
Objective
7.7 Research is generally directed to identify specific issues associated with projects that are on the UKEB’s work plan. As such, research may be expected to have a problem-solving orientation20 by collecting evidence on the nature and extent of the perceived shortcomings of, and assessing potential ways to improve or to remedy a deficiency in, international accounting standards.
7.8 This type of research helps the UKEB:
- identify a new research project that could potentially be included in the UKEB’s work plan;
- assist the IASB in the identification of a new technical issue (for example, in response to the IASB’s five-yearly agenda consultation request) and in the analysis of potential solutions; or
- provide effective technical input into IASB proposals forming part of IASB’s current agenda.
7.9 Where resources are available, other more explorative research may also be performed by the UKEB to include the consideration of broader financial reporting matters, such as how financial reporting is evolving, and to encourage international debate on financial reporting matters. This type of research may be formally added to the UKEB’s technical agenda.
7.10 Research may be undertaken by the UKEB on its own or collectively with others (i.e. national standard-setters or regional organisations, regulators, academics and other interested parties).In all cases the independence of the UKEB will be maintained.
Main outputs
7.11 A research project may give rise to a single output or multiple outputs. The common categories of research outputs derived from the UKEB’s research programme are explained below:
- Discussion papers, as documents that include an overview of specified technical issues, including possible approaches to addressing these issues.
- Requests for information or feedback on a matter related to technical projects or broader consultations. For example, seeking comments on the UKEB’s technical work plan, post-implementation reviews, or help in assessing the practical implications of a potential financial reporting requirement.
- Research papers, to contribute to wider discussions on cross-cutting issues in financial reporting.
- Bulletins, to promote and stimulate debate within the UK on specific accounting matters.
- Research studies, as documents that summarise the input received from quantitative or qualitative studies or surveys on particular topics.
7.12 A research document that includes the Board’s preliminary views would normally be accompanied by an invitation to comment on those preliminary views. By contrast, a research document of a fact-finding nature which summarises pre-existing research, outreach or stakeholder feedback on a particular accounting topic, would not normally include views and/or an invitation to comment.
7.13 For all research documents the Board will determine on an individual basis whether a research document will include:
- the Board’s preliminary views; and/or
- an invitation to comment.
Milestones
7.14 The milestones are:
Common milestones for all research documents
- Identification of issues for research (mandatory);
- Project initiation plan (mandatory);
- Desk-based research;
- Outreach activities;
- Approval and publication (mandatory)
Additional milestones for a research document that includes an invitation to comment
- Draft research document and an invitation to comment (mandatory);
- Final research document (mandatory);
- Project closure includes:
- Feedback statement (mandatory);
- Due process compliance statement (mandatory); and
- Approval and publication of a final research document (mandatory).
Common milestones for all research documents
Identification of issues for research (mandatory)
7.15 The Secretariat may identify or may receive research proposals for inclusion in the UKEB work plan. Any suitable proposals that the UKEB Chair has agreed should go forward are discussed at a public Board meeting and, if supported, a project initiation plan is approved by the Board. Proposals may arise from the Secretariat’s own research, from a Member, from consulting with the UKEB’s advisory groups, from comments and information gained from public hearings, fieldwork (refer to paragraphs A7–A8 of this Handbook) from stakeholder comment letters or from a request from the IASB or from another standard-setter.
Project initiation plan (mandatory)
7.16 A project initiation plan (PIP) is prepared for approval by the Board at a public meeting at the commencement of a research project.
7.17 The objective of the PIP for a research project is to assess the potential impact and scale of the research project and, consequently, the level of analysis and outreach that should be undertaken in line with a proportionate approach (refer to paragraphs 3.5–3.9 of the Handbook).
7.18 For a description of the purpose and content of a PIP refer to paragraphs A1–A2 in Appendix A of this Handbook.
7.19 If changes arise subsequent to commencement of a project and these changes represent a major change to the nature or scope of a project, the PIP will be updated to address those changes. The revised PIP is tabled for noting at a public meeting, giving Members the opportunity to discuss it if necessary.
7.20 The project plan included in the PIP as approved by the Board forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraphs A12–A14 in Appendix A of this Handbook for the description of a ‘due process compliance statement’).
7.21 If the research is carried out collectively with other parties (i.e. national standard-setters or regional organisations, regulators, academics or others) then agreement on the following will be achieved before commencement of work:
- the responsibilities and expectations of each party involved, including expectations about use of the project output;
- whether the project will present only an analysis of the facts or whether it will contain views or recommendations; and
- the expected output (i.e. research paper, discussion paper or request for information), copyright and publication rights over the output.
Desk-based research
7.22 Desk-based research may be undertaken to assist with the assessment of the appropriate extent of analysis and outreach and to gather evidence on the issue under consideration. For a description of this type of research refer to paragraph A3 in Appendix A of this Handbook.
Outreach activities
7.23 In line with its guiding principle of accountability (ToR paragraph 4.2(d)), the UKEB may gather input, views, opinions or other feedback from UK stakeholders on specific research projects or technical matters to contribute to the development of its thought leadership and research programme. If outreach activities are undertaken, they are described in the PIP.
7.24 For a description of the potential outreach activities that could be undertaken refer to paragraphs A4–A8 in Appendix A of this Handbook.
Approval and publication (mandatory)
7.25 The Board approves all research documents at a public meeting. This approval does not require a formal written vote by the Board. It requires the support of a simple majority of the Members present at the meeting, with approval given in a public meeting. Following the approval of a research document, it will be published on the UKEB website.
Additional milestones for a research document that includes an invitation to comment
Draft research document and an invitation to comment (mandatory)
7.26 A draft research document may be issued on a particular topic that explains the Board’s preliminary views and that asks for stakeholder feedback on these views. It is made available for public consultation on the UKEB website once approved by the Board (by following the requirements in paragraph 7.25 of this Handbook). This research document is normally preceded or accompanied by an invitation to comment that sets out the matters on which feedback is sought.
7.27 The consultation period for a research document that includes an invitation to comment is 90 days.
7.28 Where the research document is on a topic that is urgent the Board may set a shorter consultation period. The rationale for a shorter consultation period is given in the PIP (refer to paragraph A2(e) in Appendix A of this Handbook).
Final research document (mandatory)
7.29 Where the Board has published a draft research document for comment, the UKEB will consider the stakeholder feedback received on the draft research document and use this input to issue a final research document. The Secretariat will bring a final revised version of the research document for Board approval at a public meeting (refer to paragraph 7.34 of this Handbook).
Project closure
Feedback statement (mandatory)
7.30 Consultation feedback received on a research document (and any other input and feedback derived from other outreach activities after publication of the research document) is recorded, assessed, the evidence evaluated, and reported in a feedback statement.
7.31 For a description of the purpose and content of a feedback statement refer to paragraphs A9–A11 in Appendix A of this Handbook.
7.32 The Board discusses and provides comments on a draft feedback statement and approves the final feedback statement for publication.
7.33 A feedback statement is published on the UKEB website, usually at the same time as the final research document is approved by the Board.
Approval and publication of a final research document (mandatory)
7.34 The Board approves a final research document at a public meeting by following the requirements in paragraph 7.25 of this Handbook prior to publication on the UKEB website.
Due process compliance statement (mandatory)
7.35 The Secretariat summarises the due process activities undertaken in a closing control report called 'due process compliance statement'. For a description of the purpose and content of this statement refer to paragraphs A12–A14 in Appendix A of this Handbook.
7.36 The (draft) due process compliance statement is initially presented to the Board along with the final research document and feedback statement for approval.
7.37 The Board discusses, provides comments and approves a (draft) due process compliance statement at a public Board meeting. A final version of this compliance statement reflecting completion of the final stages of the project is brought to the Board for noting at a subsequent meeting.
7.38 Once the final version of the due process compliance statement has been noted by the Board it is published on the UKEB website.
8. Post-implementation reviews
Introduction
8.1 The objective of a post-implementation review is to review the impact of the adoption of an international accounting standard21.
8.2 For a standard adopted under Regulation 622 (i.e. adopted by the UKEB for use within the UK) that is likely to lead to a 'significant change in accounting practice' (see paragraph 8.6 of this Handbook), the UKEB is required to follow the requirements in paragraph 3 of Regulation 11 in SI 2019/685. The process will vary depending on whether or not the IASB undertakes a post-implementation review of the standard and whether the IASB completes this review within the timeframe stipulated by paragraph 3 in Regulation 11 (i.e. no later than 5 years after the date on which the standard takes effect). This process is further explained in paragraphs 8.5–8.43.
8.3 For a standard adopted under Regulation 423 (i.e. adopted by the European Union before the end of the Transition Period i.e. 31 December 2020), the requirements in Regulation 11 in SI 2019/685 for post-implementation reviews do not apply and consequently, the UKEB is not required to undertake such a review. However, the UKEB may decide to influence any post-implementation review that the IASB undertakes.
8.4 Although not required, the UKEB may also decide to initiate subsequent reviews from time to time of a standard adopted under Regulation 6, in accordance with paragraph 4 of Regulation 1124. This may be, for example, in a situation where there are significant unexpected changes to financial reporting or unexpected costs or challenges arising from the application of a particular standard which create the need to undertake a review of that Standard. In this case, the UKEB should follow the 'Process for carrying out a UKEB Post-implementation review' in paragraphs 8.16–8.43 of this Handbook.
8. Post-implementation reviews
Introduction
8.1The objective of a post-implementation review is to review the impact of the adoption of an international accounting standard21.
8.2For a standard adopted under Regulation 622 (i.e. adopted by the UKEB for use within the UK) that is likely to lead to a 'significant change in accounting practice' (see paragraph 8.6 of this Handbook), the UKEB is required to follow the requirements in paragraph 3 of Regulation 11 in SI 2019/685. The process will vary depending on whether or not the IASB undertakes a post-implementation review of the standard and whether the IASB completes this review within the timeframe stipulated by paragraph 3 in Regulation 11 (i.e. no later than 5 years after the date on which the standard takes effect). This process is further explained in paragraphs 8.5–8.43.
8.3For a standard adopted under Regulation 423 (i.e. adopted by the European Union before the end of the Transition Period i.e. 31 December 2020), the requirements in Regulation 11 in SI 2019/685 for post-implementation reviews do not apply and consequently, the UKEB is not required to undertake such a review. However, the UKEB may decide to influence any post-implementation review that the IASB undertakes.
8.4Although not required, the UKEB may also decide to initiate subsequent reviews from time to time of a standard adopted under Regulation 6, in accordance with paragraph 4 of Regulation 1124. This may be, for example, in a situation where there are significant unexpected changes to financial reporting or unexpected costs or challenges arising from the application of a particular standard which create the need to undertake a review of that Standard. In this case, the UKEB should follow the 'Process for carrying out a UKEB Post-implementation review' in paragraphs 8.16–8.43 of this Handbook.
Process for a Standard adopted under Regulation 6
Introduction
8.5A standard adopted under Regulation 6 that is likely to lead to a 'significant change in practice' (see paragraph 8.6 below), is subject to the requirements in paragraph 3 of Regulation 11 which requires the UKEB to:
- 'carry out a review of the impact of the adoption of the standard [i.e. where the standard is likely to lead to a 'significant change in accounting practice']; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)'.
Meaning of 'significant change in accounting practice'
8.6Whether or not a standard adopted under Regulation 6 is likely to lead to a 'significant change in accounting practice' will usually depend on the number of entities affected and the impact on those entities and may require judgement. It usually occurs when a new standard is issued by the IASB25.
8.7The UKEB is required to explain in the DECA/ECA whether or not the new or amended standard is likely to lead to a significant change in accounting practice and if it does, the DECA/ECA should explain the proposed timing of that review (refer to paragraph 6.24(f) of this Handbook). The project initiation plan (PIP) that is specific to the post-implementation review project should include this explanation. The PIP is subject to Board approval at a public meeting26.
Process for undertaking a post-implementation review for a Standard adopted under Regulation 6
8.8The obligations in paragraph 8.2 of this Handbook can be substantially fulfilled by influencing and responding to an IASB post-implementation review in accordance with the process described in paragraphs 8.9–8.12. Paragraphs 8.13–8.15 describe the process that should be followed if:
- the IASB does not finalise its post-implementation review in time for the UKEB to comply with its post-implementation review obligations within the timeframe stipulated by Regulation 11.
- the IASB undertakes a post-implementation review of a standard that is not likely to lead to a 'significant change in accounting practice'.
- the IASB does not undertake a post-implementation review of a standard that is likely to lead to a 'significant change in accounting practice'.
Influencing an IASB post-implementation review
8.9The IASB conducts post-implementation reviews to assess the effect of a new or amended standard27. This review normally begins after the new requirements have been applied internationally for two years28. The IASB commences its post-implementation review with a request for information which sets out the initial identification and assessment of the matters to be examined.
8.10The UKEB promotes awareness on its website of an IASB post-implementation review.
8.11The influencing process set out in Section 5 of this Handbook applies to the UKEB response to a request for information on an IASB post-implementation review. This process includes the preparation of a project initiation plan, desk-based research, carrying out outreach activities (including consultation with UK stakeholders and UKEB advisory groups), preparing draft and final comment letters and preparing project closure documents such as a feedback statement and a due process compliance statement.
8.12In addition to the process described above and once the IASB has completed its post-implementation review, the UKEB explains in a separate report29 how the UKEB feedback has been addressed by the IASB as well as any additional UK-specific impacts of adoption of that standard by the UKEB. This report will include:
- an overview of the IASB post-implementation review and of the UKEB's influencing process and its timeline;
- background information to the international accounting standard under review;
- a summary of the evidence gathered and findings;
- the UKEB's conclusions from the review; and
- recommendations or steps it plans to take, if any, as a result of the review.
8.13If the IASB has commenced but not finalised its post-implementation review in time for the UKEB to comply with its post-implementation review obligations, (i.e. within the timeframe stipulated by paragraph 3 in Regulation 11, that is, no later than 5 years after the date on which the standard takes effect), the UKEB must at least within that timeframe issue a (draft) report describing the impact of the adoption of the standard and its preliminary conclusions on the review30. Once the IASB has completed its post-implementation review, the UKEB will issue a separate (final) report in accordance with paragraph 8.12 of this Handbook.
8.14If the IASB undertakes a post-implementation review of a standard that is not likely to lead to a 'significant change in accounting practice', the UKEB is not required to carry out its own post-implementation review in accordance with Regulation 11. The UKEB may decide to influence the IASB post-implementation review (in accordance with the prioritisation policy in paragraphs 4.31–4.32 of this Handbook) and if it decides to do so, it will follow the process in paragraphs 8.9–8.11 of this Handbook.
8.15If the IASB does not undertake a post-implementation review of a standard that is likely to lead to a 'significant change in accounting practice', the UKEB is required by paragraph 3 of Regulation 11 to undertake its own post-implementation review. This review should be completed no later than 5 years after the date on which the international accounting standard takes effect, in accordance with paragraph (3)(b) of Regulation 11. The process for undertaking a UKEB post-implementation review is described below in paragraphs 8.16–8.43 of this Handbook.
Process for carrying out a UKEB Post-implementation review
8.16Each post-implementation review that the UKEB carries out has two phases as described below.
Phase one of a UKEB post-implementation review
8.17In the first phase of a post-implementation review, the UKEB sets out the scope of such a review. It does so on the basis of targeted consultation31 with stakeholders that represent different stakeholder communities (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators), to gather their input, views, opinions or feedback on technical matters. These initial consultations help the UKEB establish the questions to ask in the public request for information.
8.18The milestones for the first phase are:
- Project initiation plan (PIP) (mandatory);
- Desk-based research;
- Initial consultation (mandatory); and
- Publication of a request for information (mandatory).
Project initiation plan (mandatory)
8.19A project initiation plan (PIP) is prepared for approval by the Board at a public meeting at the commencement of a post-implementation review project. The PIP should include steps for phase one (the milestones are described in paragraph 8.18 above) and phase two of the project (see paragraphs 8.34–8.43).
8.20The objective of the PIP for a post-implementation review project is to consider the reasons provided in the DECA/ECA for undertaking the post-implementation review, setting out the work to be undertaken to test the implementation of the standard and the scope for such a review.
8.21For a description of the purpose of the PIP refer to paragraphs A1–A2 in Appendix A of this Handbook.
8.22If changes arise subsequent to commencement of a project and these changes represent a major change to the nature or scope of a project, the PIP will be updated to address those changes. The revised PIP is tabled for noting at a public meeting, giving Members the opportunity to discuss it if necessary.
8.23The project plan included in the PIP as approved by the Board forms the basis for compliance with the due process steps set out in this Handbook (refer to paragraphs A12–A14 in Appendix A of this Handbook for the description of a 'due process compliance statement').
Desk-based research
8.24Desk-based research may be undertaken to assist with the assessment of the appropriate extent of analysis and outreach and to gather evidence on the need for a post-implementation review. This may include review of:
- the IASB's and the UKEB's previous work on the issue to identify the issues that were important or contentious during the development of the standard, which should be identifiable from the basis for conclusions, project summary, feedback statement or effects analysis of the relevant standard;
- any relevant research, including that performed by the Secretariat and academics; and
- any issues brought to the UKEB's attention prior to the commencement of the post-implementation review.
8.25Some additional activities that could be undertaken are described in paragraph A3 in Appendix A of this Handbook.
Initial consultation (mandatory)
8.26The Board and its Secretariat consults with stakeholders to help identify areas where unexpected costs or implementation problems were encountered.
8.27This initial review draws on the broad network of UKEB-related bodies and interested parties, such as the UKEB's advisory groups, and other outside groups of, for example, preparers, auditors or users. The purpose of these consultations is to inform the UKEB so that it can establish an appropriate scope for the review. The extent of consultation needed for this phase will depend on the international accounting standard being reviewed and pre-existing information about the implementation of that standard.
8.28Where the initial review indicates that there is no need for a post-implementation review, the review moves directly to the final report stage in phase two of the UKEB post-implementation review (see paragraphs 8.39–8.43 of this Handbook).
Publication of a request for information (mandatory32)
8.29When the UKEB is satisfied that it has sufficient information to establish the scope of the review it issues a request for information on the post-implementation review of the international accounting standard.
8.30A request for information sets out the matters for which the UKEB is seeking feedback together with a rationale for the information being sought and any initial assessment by the UKEB of the impact of the international accounting standard. It also describes the reasons for undertaking such review (in line with Regulation 11).
8.31Publication of a request for information does not require a formal written vote by the Board. It requires the support of a simple majority of the Members present at the meeting, with approval given in a public meeting.
8.32The consultation period for a request for information is 90 days.
8.33Where the request for information is on a topic that is urgent the Board may set a shorter consultation period. The rationale for a shorter consultation period is given in the PIP (refer to paragraph A2(e) in Appendix A of this Handbook).
Phase two of a UKEB post-implementation review
8.34In the second phase the UKEB collects and reviews information, sourced via the request for information issued during the first phase and other outreach, to help it assess the impact of the international accounting standard being reviewed. During this evidence-gathering phase of the post-implementation review the UKEB also conducts outreach activities to engage with different stakeholders.
8.35If necessary, the PIP will be updated as set out in paragraph 8.22 of this Handbook.
8.36The milestones for the second phase are:
- Outreach activities (mandatory).
- Project closure: issue of a final report (mandatory) and a due process compliance statement (mandatory).
Outreach activities (mandatory)
8.37The amount of outreach to be undertaken, together with the rationale, is highlighted in the PIP.
8.38For a description of the potential outreach activities that could be undertaken refer to paragraphs A4–A8 in Appendix A of this Handbook.
Project closure for a UKEB post-implementation review
Final report (mandatory)
8.39Feedback received from the UKEB request for information (and any other input and feedback derived from other outreach activities after publication of the request for information) is recorded, assessed, the evidence evaluated, and then incorporated into the analysis and discussion of the technical issues in a report that the Board discusses and approves at a public meeting prior to publication on the UKEB website. This report ensures that the UKEB fulfils its obligations in paragraph 3 of Regulation 11(a)–(b) of reviewing the impact of the adoption of the standard and of setting out the conclusions of that review.
8.40The content of this report includes:
- an overview of the UKEB post-implementation review process and its timeline;
- background information to the international accounting standard under review;
- a summary of the evidence gathered and findings;
- a summary of the outreach activities and sources of stakeholder comments (after publication of the request for information); and
- the UKEB's conclusions from the review.
Due process compliance statement (mandatory)
8.41For a UKEB post-implementation review, the Secretariat summarises the due process activities undertaken in a closing control report called 'due process compliance statement'. For a description of the purpose and content of this statement refer to paragraphs A12–A14 in Appendix A of this Handbook.
8.42The Board discusses, provides comments and approves a (draft) due process compliance statement at a public Board meeting. A final version of this compliance statement reflecting completion of the final stages of the project is brought to the Board for noting at a subsequent meeting.
8.43Once the final version of the due process compliance statement has been noted by the Board it is published on the UKEB website.
9. Advisory groups
Introduction
9.1The UKEB undertakes targeted consultation by appointing its own standing and ad-hoc advisory groups, with the purpose of gathering technical advice and other input on its projects or other technical matters (e.g. UK-specific implementation issues).
9.2Members of advisory groups comprise experts who:
- provide advice and recommendations on specific agenda projects for example by sharing:
- knowledge and understanding of financial reporting issues and/or concerns raised by UK stakeholders; and
- up-to-date insight into developments and market sentiment on financial reporting matters, helping develop a timely understanding of any concern areas;
- deliver best practice, practical experience and expertise as well as potential solutions that can improve the quality of information; and
- help amplify the UKEB's views across the UK reporting community and drive the debate of contemporary issues.
Composition of advisory groups
Types of advisory groups
9.4Advisory groups are not decision-making bodies, but advisory in nature and can be standing or ad-hoc. Their characteristics are described in the table below:
| Type | Standing | Ad-hoc |
|---|---|---|
| Duration | Advisory group with an indefinite life. Intended to be long-lived. | Intended to be short-lived for a pre-defined time or set duration and is project-based. |
| Description | Provides regular and focused input on a wide range of strategic and technical issues. | Provides focused input on specific technical issues. |
| May support the implementation and/or transition to a new international accounting standard33 | ||
| Members– stakeholder type | Usually includes stakeholders from a particular industry, sector or stakeholder type (e.g. preparers, auditors users, academics or professional accounting organisations). | Usually includes a 'mix' of senior professionals from different stakeholder groups but with a specialist knowledge of the specific issue or technical area relevant to the group. |
| It can also include a 'mix' of stakeholders with shared interests34. | It can also include a narrower (even single) stakeholder group when appropriate to a particular project (e.g. users or academics only for a particular project, e.g. a research project). | |
| Benefits | Benefits are the same for both standing and ad-hoc advisory groups. | |
| Enables the Board to access regular and timely advice on areas of specialist knowledge and receive a 'real-world' view of the impact of proposals, generally on major projects. |
9.5From time to time, the Secretariat may need specialised technical input into project work. In such cases, the Board may approve the creation of a working group which reports to the Secretariat. The Secretariat will provide updates to the Board on the input received from the working group.
Types of participants
9.6Participants in a UKEB advisory group (standing or ad-hoc) may originate from the following stakeholder groups:
- Users – those with practical experience in analysing and using financial information as users of accounts. Users include 'buy-side' fund managers, institutional investors and retail investors as well as participants from 'sell-side' investment banks and ratings agencies.
- Preparers – those with considerable practical experience of financial reporting and knowledge and understanding of the financial reporting issues faced by IFRS reporters. Preparers have backgrounds in large or small, listed or unlisted UK-based companies applying international accounting standards.
- Academics – researchers with expertise and experience in the use of accounting by individuals, organisations and government. This group could include researchers with interests in accounting policy, governance and environmental issues, quantitative analysis, wider corporate reporting and economics.
- Accounting firms – those with a close interest in the use and implementation of international accounting standards. Accounting firms have insights to share on the use of international accounting standards by a range of different sectors and on any concerns arising from that use. They include large and medium-sized professional services firms in the UK.
- Accounting bodies – those with a close interest in the use and implementation of international accounting standards and able to provide insights on current and emerging issues.
- Regulators – those that regulate or supervise a particular industry or business activity. Regulators have insights to share on the use of international accounting standards by different sectors and on any concerns arising from that use.
Operating procedures
Approval for the creation of an advisory group
9.7The establishment of an advisory group is approved at a Board meeting by a majority of Members present at that meeting.
Terms of reference
9.8Each advisory group has its own Terms of Reference, setting out:
- the advisory group's purpose and responsibilities;
- membership rules;
- meetings and administrative arrangements; and
- date of approval of the Terms of Reference and process for making changes.
9.9An outline of the content of the Terms of Reference applicable to each advisory group (standing or ad-hoc) is included in Appendix C of this Handbook.
Recruitment
9.10Consistent with the UKEB's guiding principles of accountability and transparency, all recruitment for advisory groups should be via a public advertisement, inviting applications. Appointments should be based on interviews with Members and members of the Secretariat. The Board retains the option to make the occasional direct appointment; however, this would need to be in exceptional circumstances, for example when there are few experts in a particular area or no other expert is forthcoming.
Appointments and membership
9.11In selecting members, the UKEB Chair seeks to ensure that the membership in the advisory groups is diverse in terms of skills, experience, background, race and other characteristics, and achieves a gender balance.
9.12Members of advisory groups are appointed in their personal capacity. Alternates are not permitted.
9.13Membership of an advisory group (including the chair of this group) is approved by a majority of Members present at a meeting. Once approved, the members of an advisory group are listed on the UKEB website.
9.14Depending on the advisory group's nature and purpose, the UKEB Chair may appoint a chair for the advisory group (chair) who may be an advisory group member, a Member or a Secretariat member.
9.15Members of advisory groups are appointed for an initial term of up to three years renewable for a second term of up to three additional years, or for the length of the project (for ad-hoc groups). The length of term may be shortened or lengthened if circumstances warrant. There will be staggered rotation of members to ensure continuity on the advisory group. Changes to appointments arising from such reviews are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB website.
Meetings
9.16Administrative support to the advisory group is provided by the Secretariat as necessary, including organising meetings and updating members about the project's progress.
9.17Technical papers for meetings of advisory groups will generally be prepared by the Secretariat or members of the advisory group, as appropriate. These papers are confidential unless all members of the group agree to share them more widely (e.g. present them at a public Board session).
9.18Members are welcome to attend any meetings of an advisory group.
9.19Meetings of advisory groups are closed and held in private. The chair will provide updates from their advisory groups to the Board at a public meeting.
9.20Meetings of advisory groups may be held in the presence of invited observers with speaking rights only if the chair deems it beneficial to the work of the group.
9.21Members of advisory groups will be expected to:
- review all relevant material before the meeting;
- provide specialist knowledge and technical advice in line with the purpose and responsibilities of the group's Terms of Reference;
- make evidence-based and objective contributions, to the extent possible;
- aim for consensus-building wherever possible and, to that end, should be prepared to be challenged on their views and open to consideration of other members' perspectives;
- remain respectful and professional in all interactions with other members of the group and with the Secretariat; and
- attend all meetings.
Frequency for ad hoc advisory groups
9.22Once work on a project commences, the Board and/or the Secretariat may consult advisory groups when it is beneficial to the project to do so.
Effectiveness review
9.23The Board will evaluate the purpose and effectiveness of each advisory group every three years (or more frequently, if circumstances warrant), to assess each group as to whether:
- It is continuing to serve the function for which it was established. The Board revises the Terms of Reference applicable to each advisory group as necessary.
- The composition continues to be appropriate. This will include appointments and re-appointments of members. Any changes to membership are approved by the Board at a private meeting. The membership of the advisory group is then updated on the UKEB website.
Appendix A: Description of common milestones
The following milestones are common across projects. Each section in the Handbook indicates whether any of these milestones are mandatory or not.
Project initiation plan
A1A project initiation plan (PIP) is a process control document that is issued at the commencement of a technical project for approval by the Board.
A2The PIP outlines the approach to the project, including:
- An overview of the project including a description of the project objective and proposed timeline. In addition:
- for an endorsement project, the proposed timeline reflects the intention to complete the UKEB's endorsement considerations in advance of the effective date of the particular project; and
- for a post-implementation review project, the PIP provides an overview of the post-implementation review and the reasons for undertaking this review, including how the UKEB has reached the conclusion that a standard subject to such review constitutes a 'significant change in accounting practice' (if applicable).
- A description of milestones including appropriate stakeholder engagement that will be undertaken to achieve those milestones.
- Available and required resources for the project (including whether those resources are already allowed for in the annual plan or budget).
- Expected output. For example, for:
- an influencing project, a draft/final comment letter to the IASB;
- an endorsement project, a draft/final Endorsement Criteria Assessment;
- a research project, any of the outputs mentioned in paragraph 7.11 of the Handbook and whether the output(s) are expected to include views and/or an invitation to comment;
- a post-implementation review project, a draft/final comment letter to the IASB (when influencing IASB's post-implementation reviews) or a request for information (for a UKEB's post-implementation review).
- If applicable, the rationale and/or factors considered to justify departing from the required consultation period for a specific project (as specified in this Handbook).
- Consideration of the need to receive input from one or more advisory groups.
Desk-based research
A3Desk-based research usually includes a review of the UKEB's and/or of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports by other national standard-setters, regional organisations (e.g. EFRAG) or by other stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators). Additionally, the UKEB could liaise with national standard-setters or with regional organisations who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Outreach activities
A4The outreach activities that the UKEB undertakes may include some or all of the following:
- convening and obtaining input from standing advisory groups and/or ad-hoc advisory groups35;
- meetings and/or interviews with stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators);
- undertaking fieldwork (refer to paragraphs A7–A8);
- email communications with subscribers to the UKEB website accompanied by an associated news alert;
- a request for feedback on the project's webpage;
- obtaining input from UKEB working groups;
- to the IASB (when influencing IASB's post-implementation reviews) or a request for information (for a UKEB's post-implementation review).
- If applicable, the rationale and/or factors considered to justify departing from the required consultation period for a specific project (as specified in this Handbook).
Consideration of the need to receive input from one or more advisory groups.
Desk-based research
A3Desk-based research usually includes a review of the UKEB's and/or of the IASB's previous work on this issue. It may also include, for example, a review of literature, academic papers, financial statements or of past papers or reports by other national standard-setters, regional organisations (e.g. EFRAG) or by other stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators). Additionally, the UKEB could liaise with national standard-setters or with regional organisations who have carried out influencing activities or are in the process of performing such activities on the same (or related) project.
Outreach activities
A4The outreach activities that the UKEB undertakes may include some or all of the following:
- convening and obtaining input from standing advisory groups and/or ad-hoc advisory groups35;
- meetings and/or interviews with stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators);
- undertaking fieldwork (refer to paragraphs A7–A8);
- email communications with subscribers to the UKEB website accompanied by an associated news alert;
- a request for feedback on the project's webpage;
- obtaining input from UKEB working groups;
- the commissioning of external economic studies (i.e. data gathering and analysis conducted by external consultants to assess aspects of the economic impact of a standard on the UK); and
- arranging informal meetings with IASB members and/or staff and/or with other national standard-setters or regional organisations and their participation in UK outreach events.
A5Liaison with the IASB when undertaking outreach on an IASB due process document, e.g. an exposure draft, may enhance the efficiency and effectiveness of the UKEB's work. Examples of benefits could include:
- enhanced credibility and attraction of outreach events if conducted jointly with the IASB; and
- greater insight into technical issues.
A6The UKEB will maintain full transparency about its interaction with stakeholders including the IASB. Steps will include:
- maintaining a public register of meetings of Members and senior members of the Secretariat and stakeholders; and
- being transparent about the sources of information used in UKEB material.
Fieldwork
A7Examples of fieldwork may include some or all of the following:
- Surveys—organised to gather data or other information on a specific subject;
- Field tests—include testing the application of technical proposals as if they were already in effect, to assess the understandability of the requirements and/or the resulting implementation issues. Field tests can be based on, for example:
- the completion of case studies;
- asking participants to assess how a technical proposal would apply to actual transactions;
- asking users how they process information; or
- assessing how accounting systems may be affected.
- Workshops or interviews—bring interested parties together and allow for in-depth analysis, for example to assess how technical proposals might be interpreted or applied or to ensure the correct understanding of the results of a survey or field test.
- Public events—meetings with a larger number of interested stakeholders and organisations to listen to, and exchange views on, specific topics. These could take the form of roundtables, discussion forums, webinars and webcasts. These public events provide stakeholders with the opportunity to better understand and present their views on developing proposals.
A8Fieldwork can focus on one or more specific groups of stakeholders (e.g. users, preparers, academics, accounting firms, accounting bodies and regulators).
Feedback statement
A9The purpose of a feedback statement is to inform stakeholders how the UKEB has responded to, or has addressed, the main comments or views received from stakeholders who participated in outreach events or submitted comment letters on a specific project.
A10A feedback statement demonstrates the UKEB's adherence to its overarching guiding principles as follows:
- Accountability to stakeholders who submitted comment letters and/or participated in outreach, to the FRC as oversight body and to others: showing that the UKEB is taking account of stakeholders' views and fulfilling its due process obligations.
- Transparency about how the main comments or views have been addressed.
- Independence in that the UKEB acts in the UK's long term public good and is independent in its assessment of comments or views received from stakeholders and in determining any adoption decision or the content of its final comment letter to the IASB.
A11Although the objective of all feedback statements is the same, the form and content will be proportionate to the objective of the underlying document, e.g. discussion papers have different objectives from exposure drafts. In general, a feedback statement includes the following content:
- An objective.
- Summary background. For example, a brief description of the:
- IASB's proposal(s) (for an influencing project);
- the new or amended standard (for an endorsement project); or
- the research document that invited comments (for a research project).
- An explanation of the main feedback received through comment letters or outreach activities on:
- the draft comment letter (for an influencing project);
- the DECA (for an endorsement project); or
- the research document that invited comments (for a research project).
- A description of the UKEB's response (i.e. how comments or views received from stakeholders have been addressed) in:
- the final comment letter (for an influencing project);
- the final ECA (for an endorsement project); or
- the final research report (if applicable).
- A summary of the outreach activities and sources of stakeholder comments, e.g. from individual stakeholder meetings, formal responses to draft comment letters or to a DECA, or from other outreach events.
Due process compliance statement
A12A due process compliance statement is a closing report that summarises the due process activities undertaken compared against due process requirements. It also retrospectively validates how the processes and activities undertaken complied (or not) with the PIP.
A13The due process compliance statement fulfils the following objectives:
- It provides a record of the activities undertaken by the Secretariat to comply with the UKEB's due process.
- It provides a basis for holding the Secretariat accountable to the Board for the due process procedures that it follows in practice.
- It informs the Board and stakeholders about the work undertaken. If discrepancies are identified in respect of the milestones and activities that were described in the PIP, the due process compliance statement provides an explanation as to why, and how those milestones and/or activities still meet due process compliance requirements.
Content
A14The due process compliance statement includes the following sections:
- Project details:
- If influencing an IASB due process document: title, date of publication and comment letter deadline.
- If a UKEB thought leadership or research project: project title, date of publication, comment letter deadline (if applicable).
- If endorsing an IASB standard or amendment: title, date of publication and the IASB's effective date.
- A description of due process steps undertaken covering the following areas:
- Project preparation (i.e. the PIP and/or a revised version of the PIP and desk-based research).
- Communications (e.g. public meetings, documents posted on the UKEB website).
- Outreach activities (e.g. advisory groups, fieldwork undertaken).
- Preparation of documents for public comment (e.g. draft comment letter for influencing activities).
- Project finalisation and project closure (e.g. final comment letter, feedback statement for influencing activities).
- Metrics or evidence to demonstrate that the process was undertaken as agreed in the PIP and/or in the revised version of the PIP (if applicable) (e.g. number of meetings held).
- An explanation of why the Secretariat decided not to undertake a due process step for a given project, if relevant (i.e. why an outreach activity specified in the PIP was not undertaken).
- A conclusion as to whether, in the Secretariat's opinion, applicable due process steps have been complied with.
Appendix B: Relationship between Statutory Instruments (SI) and other governance documents for the UK Endorsement Board
Appendix C: Terms of Reference outline for advisory groups
Terms of Reference
Name, purpose and responsibilities
C1Name of advisory group, purpose and responsibilities to the Board and/or to the Secretariat.
C2Guiding principles and compliance with legislative framework.
Membership
C3Appointments and membership. Description of how members are selected and duration of membership.
C4Size: minimum and maximum number of members.
C5What the Board and/or the Secretariat expect from the members of the advisory group and consequences of failing to meet the expectations set out in the terms of reference (for example dismissal after non-attendance at a certain number of meetings, etc).
Meetings and administrative arrangements
Process for holding meetings
C6Indication that meetings of advisory groups:
- are closed and held in private;
- may be held in the presence of invited observers with speaking rights only if the chair deems it beneficial to the work of the group.
C7Requirements for attendance and an indication that alternates are not permitted.
C8Location, duration (i.e. number of hours) and frequency (i.e. number of meetings per month and/or per year).
C9Indication of who will act as the chair of the advisory group.
Notice of meetings and agendas
C10State obligation for the Secretariat to:
- make available meeting agendas and papers only for the members of the advisory groups before the meeting; and
- provide summary minutes of meetings and to publish them on the website.
Remuneration for members
C11Indication that members will not be remunerated and that they will be entitled to claim expenses in line with the FRC's policy.
Approval of Terms of Reference and changes
C12Date of approval of the Terms of Reference and process for making changes to the terms.
Appendix D: Illustrative diagram to determine whether to undertake a post-implementation review (PIR)
Contact Us UK Endorsement Board 1 Victoria Street
| London | SW1H 0ET | United Kingdom www.endorsement-board.uk
Footnotes
-
This term has the meaning given in SI 2019/685 by referring to Article 2 of Regulation (EC) No 1606/2002 of the European Parliament and of the Council of 19 July 2002 on the application of international accounting standards: '...'international accounting standards' shall mean International Accounting Standards (IAS), International Financial Reporting Standards (IFRS) and related Interpretations (SIC-IFRIC interpretations), subsequent amendments to those standards and related interpretations, future standards and related interpretations issued or adopted by the International Accounting Standards Board (IASB)'. ↩
-
Paragraph 1.3 of the IASB and IFRS Interpretations Committee Due Process Handbook states that the IFRS Interpretations Committee "assists the [IASB] Board in improving financial reporting through timely assessment, discussion and resolution of financial reporting issues identified to it within the IFRS framework". ↩
-
The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 609 (SI 2021/609). https://www.legislation.gov.uk/uksi/2021/609/made/data.pdf ↩
-
The respective responsibilities of the UKEB, the FRC and the Secretary of State are set out in this Memorandum of Understanding. ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685). https://www.legislation.gov.uk/uksi/2019/685/made ↩
-
The UKEB Terms of Reference can be found here. ↩
-
While the relevant legislation uses only the term 'adoption' and does not refer to 'endorsement', for the purposes of this Handbook the term 'endorsement' is generally used when referring to the assessment of new (or amended) standards against the statutory adoption criteria, reflecting general usage. This is not intended to imply the existence of two distinct statutory functions or processes. ↩
-
The process for endorsing new or amended standards is described in Section 6. ↩
-
The process for influencing international accounting standards is described in Section 5. The process for influencing IASB post-implementation reviews is described in Section 8. ↩
-
Where the respondent has not requested confidentiality. ↩
-
'Annual improvements' are amendments that meet the criteria in paragraphs 6.10–6.14 in the IASB and IFRS Interpretations Committee Due Process Handbook and are sufficiently minor or narrow in scope to be bundled together in a single Exposure Draft document (even though amendments are unrelated). 'Narrow-scope amendments' do not meet the criteria for annual improvements but meet the criteria in paragraph 5.16 in that same Handbook and are considered 'narrow' in scope. ↩
-
The Board considers the tentative agenda decisions (issued by the IFRS Interpretations Committee) to which it will respond and incorporates them into the work plan. The Board expects to respond to a limited number of tentative agenda decisions in line with paragraph 5.29 of this Handbook. ↩
-
For example, the IASB published the amendment Covid-19-Related Rent Concessions beyond 30 June 2021 (Amendment to IFRS 16) on 31 March 2021. It was effective for annual reporting periods beginning on or after 1 April 2021. Earlier application was permitted, including in financial statements not authorised for issue (or signed) at 31 March 2021. ↩
-
Refer to paragraph 6.7 of this Handbook. ↩
-
This analysis includes consideration of the costs that would be incurred if the standard were not adopted and any disadvantages of non-adoption. ↩
-
This is consistent with Regulation 9(3) of SI 2019/685. ↩
-
Refer to paragraphs 4.1–4.2 of this Handbook. ↩
-
The term 'Members' includes the UKEB Chair as an appointed Member. ↩
-
If the formal written vote is not to adopt, then only the outcome of the vote will be published. ↩
-
This is not intended to lead to the UKEB issuing technical advice and/or interpretations of the standards. ↩
-
Refer to Appendix D 'Illustrative diagram to determine whether to undertake a post-implementation review'. ↩↩
-
For example, IFRS 15 Revenue from Contracts with Customers or IFRS 16 Leases. ↩↩
-
This paragraph states that "The Secretary of State may carry out subsequent reviews from time to time, and in the event of doing so the Secretary of State must publish a report setting out the conclusions of any review conducted". ↩↩
-
During the endorsement process, the UKEB should indicate in the DECA its preliminary view regarding whether the new or amended standard meets the criteria for a post-implementation review and, if so, the likely timing of that review in line with the requirements in this section. Refer to paragraph 6.24(f) of this Handbook. ↩
-
Refer to paragraphs 8.19–8.23 in this Handbook. ↩
-
In the IASB and IFRS Interpretations Committee Due Process Handbook, paragraph 6.48 states that the IASB "is required to conduct a post-implementation review of each new IFRS Standard or major amendment". Paragraph 6.51 states that an IASB PIR is "an opportunity to assess the effect of the new requirements on investors, preparers and auditors following the issuance and application of a Standard". ↩
-
Refer to paragraphs 6.48–6.59 in the IASB and IFRS Interpretations Committee Due Process Handbook. ↩
-
This report ensures that the UKEB fulfils its obligations in Regulation 11(3)(a)–(b) of reviewing the impact of the adoption of the Standard and of setting out the conclusions of that review. ↩
-
This in line with the approach taken by the Better Regulation Framework guidance in the UK. ↩
-
For example, by consulting the broad network of UKEB-related bodies and interested parties, such as the UKEB's advisory groups (see Section 9 of the Handbook). ↩
-
Unless paragraph 8.28 applies. ↩
-
This may be the case for an advisory group providing expert perspectives (for example, on how rate-regulatory schemes operate) or providing input on the implementation of new requirements in an international accounting standard. ↩
-
For example, accounting bodies and auditors have both a close interest in the use and implementation of international accounting standards and both have insights to share on the use of standards and on any concerns arising from that use. ↩