UKEB 2024/2025 Regulatory Strategy
The UKEB does not accept any liability to any party for any loss, damage or costs however arising, whether directly or indirectly, whether in contract, tort or otherwise from action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2024 All Rights Reserved
1. Introduction
The financial year 2023/24 has been another busy one for the UKEB. With the finalisation of our Due Process Handbook at the end of the previous year, the Board was able to focus on its core statutory responsibilities of influencing the development of IFRS and adopting new standards and amendments. In particular, we enhanced our research capabilities, allowing us to influence international accounting at an earlier stage.
Highlights of the UKEB's achievements in this past year include the following:
- Adoption of four narrow scope amendments to IFRS, including urgent changes to IAS 12, to reflect the International Tax Reform Pillar Two Model Rules, and to IAS 7 and IFRS 7 to introduce disclosures for Supplier Finance Arrangements.
- The publication of three final comment letters and the issue of two draft comment letters for consultation, in response to IASB exposure drafts.
- The publication of two comment letters to the IASB in response to Post Implementation Reviews of IFRS 9 Impairment and IFRS 15 Revenue from Contracts with Customers.
- Monitoring the IASB's redeliberations of live standard setting projects and influencing their debate, through discussion at UKEB Board meetings, active participation in discussions at the IASB's Accounting Standards Advisory Forum (ASAF) and presentations at other international standard setter events.
- Continuing our research into intangibles.
The Memorandum of Understanding between the UKEB, the Secretary of State and the FRC requires us to consider any additional areas of work when requested to do so by the Secretary of State. Following on from a request in 2022/23 to provide views to the ISSB on its sustainability standards from our perspective as the body responsible for endorsing and adopting international accounting standards in the UK, we continued our work reviewing the interaction between the two sets of standards. In particular, we carried out the following additional work during the year:
- The publication of two research reports on the connectivity between accounting and sustainability disclosures in corporate reports.
- The publication of a comment letter to the ISSB in response to its agenda consultation.
The Board has been supported significantly in its work this year by the discussions of the four standing advisory groups (Accounting Firms and Institutes, Preparers, Investors, and Academics) and of the Financial Instruments Working Group, all of which were established in 2022/23. In addition, an ad-hoc advisory group was established on Rate-regulated Activities and we have also appointed a Sustainability Working Group to advise the Secretariat on connectivity issues. The insights provided by all of these groups have been critical in ensuring that the Board is properly informed of the views of key UK stakeholder groups, and I am very grateful to the members of these groups for the enthusiasm with which they have engaged in this important process.
2023/24 has been another very successful year for the UKEB, and one in which we have established our presence as an influencer on the international stage. I am very grateful to the Board for the energy and expertise they have all brought to our debates. I would also like to thank our hard-working Secretariat who have shown tremendous dedication and have provided us with excellent support and advice.
As the expected workplan set out in this Regulatory Strategy shows, 2024/25 is likely to be another very busy year and we will need to give careful consideration to the prioritisation of our resources. We are looking forward to a stimulating and challenging year.
Pauline Wallace Chair
2. Our Purpose
The UKEB was established with a specific mission and vision, to be achieved via a core set of values as outlined below.
2.1 Mission
To serve the UK public good by leading the development and synthesis of UK views on financial reporting and representing them in the international arena, ensuring that the UK's voice is influential in the development of high-quality international accounting standards that are suitable for adoption in the UK.
2.2 Vision
To maintain the high quality of UK financial reporting that underpins confidence in the UK's capital markets and reinforces its reputation for transparency.
2.3 Values
The UKEB operates in the public interest, following the seven principles of public life and our four guiding principles.
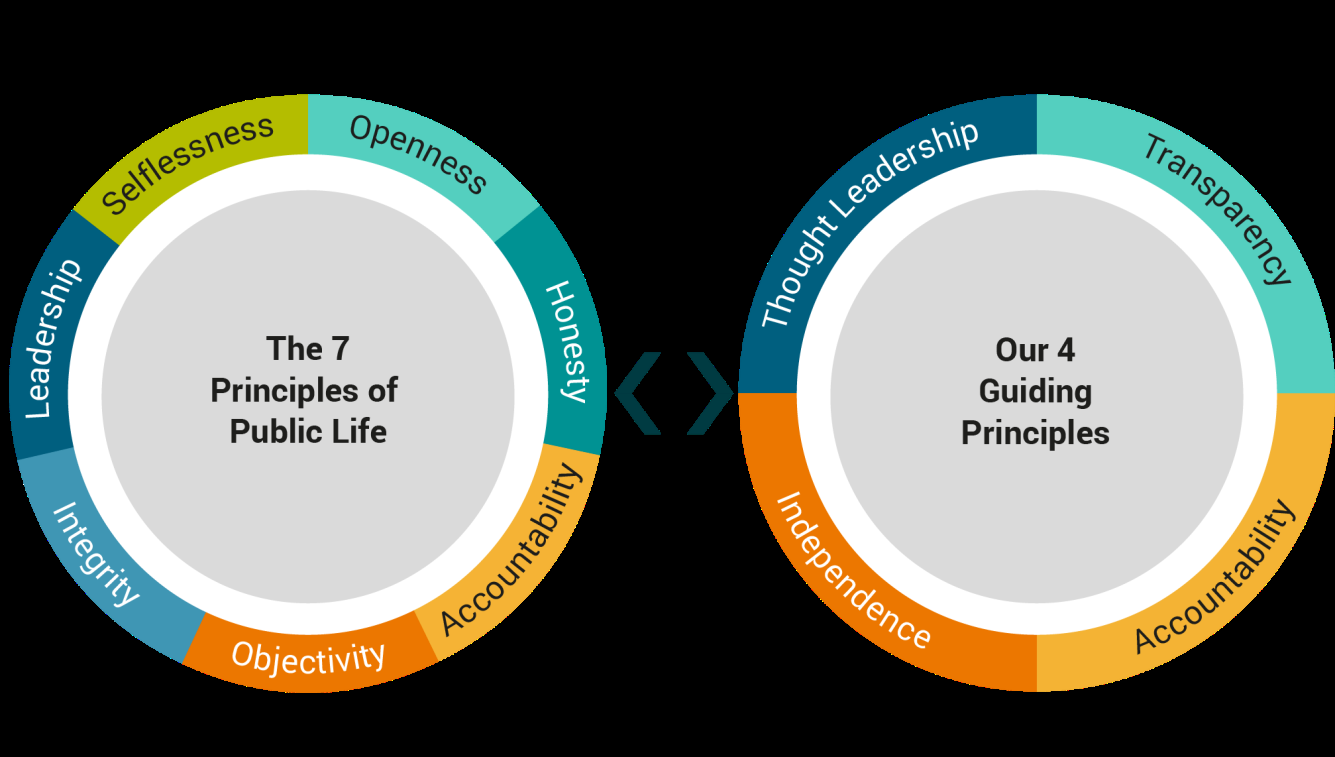
3. Strategic Objectives
The UKEB's strategic objectives are derived from its statutory functions, as delegated to it by the Secretary of State for the Department for Business, Energy and Industrial Strategy (BEIS) in May 20211.
3.1 Statutory functions
The statutory functions of the UKEB are to:
- participate in, and contribute to, the development of a single set of international financial reporting standards; and
- adopt international accounting standards when they meet the criteria in Statutory Instrument 2019/685 ‘The International Accounting Standard and European Public Limited-Liability Company (Amendments etc.) (EU Exit) Regulations 2019’.
The objectives for adoption of IFRS for use in the UK are to ensure:
- a high degree of transparency and international comparability of financial statements; and
- the efficient allocation of capital, including the smooth functioning of capital markets in the UK.
3.2 Strategic objectives 2024/25
Achievement of its strategic objectives will enable the UKEB to deliver against its statutory functions, in accordance with its stated mission, vision and values. The UKEB's three-year strategy for the period 2022-25 was published in March 2022 following consultation. In this third year, the UKEB's strategic objectives remain unchanged. The Board intends to continue to build on the work of the previous two years to achieve its three-year strategy.
In line with the UKEB's statutory responsibility to support the development of high-quality international accounting standards and decide upon their adoption for use in the UK, the Secretary of State for the Department of Business and Trade (DBT) has requested that, in addition to its statutory responsibilities, the UKEB will take a broader role in considering the interplay between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards. This would require the UKEB to undertake the following additional tasks:
- Considering the implications of the development of IFRS Sustainability Disclosure Standards for IFRS Accounting Standards;
- Assessing the consistency of content in IFRS Accounting Standards and IFRS Sustainability Disclosure Standards, with a goal that requirements are complementary and not contradictory; and
- Influencing the IASB and ISSB on these matters.
This additional work would involve the appointment of a UKEB Board member to the UK Government's new UK Sustainability Disclosure Technical Advisory Committee (TAC), led by DBT, and UKEB Secretariat representation on the Policy Implementation Committee (PIC).
Consideration of the impact of IFRS Sustainability Disclosure Standards on IFRS Accounting Standards and the UKEB's role on the TAC fits within the UKEB's statutory function to influence the work of the IASB and these responsibilities have therefore been included in the strategy and Work Plan set out in this document. To the extent, however, that the DBT request extends beyond the UKEB's statutory functions, this would require additional funding which is currently unavailable. Consequently, the proposed strategy does not include any such non-statutory work.
The objectives for 2024/25 are outlined below.
3.2.1 Influencing and thought leadership
The UKEB will take a principles-based, proactive and pragmatic approach to influencing the IASB and other global players, to help ensure the development of high-quality international accounting standards that promote transparency and comparability of financial information, and the smooth functioning of capital markets. In particular, it will:
- Aim to influence the IASB early on in its standards development cycle, providing evidence-based recommendations and thought leadership on emerging issues from a UK perspective.
- Conduct stakeholder engagement with key stakeholder groups on a flexible and proportionate basis, aimed at ensuring the quality and persuasiveness of information shared.
- Raise the UKEB's domestic and international profile by:
- working with our advisory groups and working groups to ensure regular and timely interaction with, and input from, UK stakeholders;
- further developing our relationship with the IASB including through active participation in the IASB's Accounting Standards Advisory Forum;
- participating in other international financial reporting groups and collaborating with those who share our goal of high-quality financial reporting; and
- Showcase UK thought leadership and research, and increase its influence with the IASB and other National Standard Setters, by:
- using relevant research as a key component of the UKEB's evidence-based and persuasive influencing and thought leadership activities, identifying the key issues to be addressed during the development of a standard;
- developing an active research programme aimed at addressing new and emerging issues in international accounting, with a particular focus on topics included in, or likely to be included in, the IASB's long-term agenda; and
- amplifying the research outcomes by highlighting the findings to the IASB and other international partners.
3.2.2 Adoption of accounting standards for use in the UK
The UKEB will aim to assess all new and amended international accounting standards for adoption in the UK on a timely basis. In particular, it will:
- assess new standards and amendments against the statutory adoption criteria;
- conduct proportionate stakeholder engagement to ensure that the practical implications of implementation of those standards and amendments for UK companies, their investors and other stakeholders have been appropriately established and assessed;
- liaise with IASB board members and staff to ensure a full understanding of the technical issues and bases for conclusions; and
- seek to identify all material issues relevant to the assessment of the impact of the standard on the UK long-term public good have been identified and assessed, including through the monitoring of other National Standard Setters' endorsement work.
3.2.3 Operations framework
Maintaining a robust operations framework is key to ensuring the requisite level of support to facilitate achievement of the influencing and adoption objectives detailed in sections 3.2.1 and 3.2.2 above. The core objectives are to:
- provide the UKEB with the support it requires to fulfil its statutory functions, aligned with the culture and values of the organisation;
- collaborate effectively with the FRC in its role as the UKEB's outsourced services provider;
- continue to embed the UKEB's enhanced stakeholder engagement capability, including an effective communications strategy and plan, and enhanced digital output; and
- maintain tight budgetary control, aligned to the principles of Managing Public Money.
4. Measuring Success
The UKEB will monitor progress in implementing its strategic objectives in a variety of ways.
Influencing the development of international accounting standards cannot readily be measured via key performance indicators and will instead be assessed through our:
- Regular monitoring of the UKEB's impact on IASB projects;
- Contributions at international standard setting forums including at the IASB's Accounting Standards Advisory Forum; and
- Interaction with other national and regional standard setters, bilaterally, as well as via contributions at meetings such as the International Forum of Accounting Standard Setters.
Other objectives will be monitored via key performance indicators in the following core areas:
- Compliance with the governance framework, based upon requirements set out in the Memorandum of Understanding, Terms of Reference and Service Level Agreement;
- Compliance with the Due Process Handbook in delivering to the technical workplan;
- Effective management of internal resource and outsourced services;
- Actual costs in line with agreed budget/forecast and adherence to Managing Public Money principles.
The Board will also ensure that its risk landscape is understood and managed appropriately. This will involve identifying, mitigating and monitoring key risks that would otherwise impede the UKEB's ability to achieve its strategic objectives and, therefore, to effectively perform its statutory functions.
Additional indicators of the Board's overall effectiveness in meeting its statutory objectives are incorporated in the following annual reports:
- Annual Board Effectiveness Review.
- A report to the Secretary of State setting out how the Board has discharged its delegated functions.
- A report to the FRC setting out how the Board has fulfilled its governance and due process responsibilities.
5. UKEB Work Plan
As the UKEB's statutory functions relate to influencing the IASB, during the development of new and amended international accounting standards, and the subsequent UKEB adoption decisions for those standards, the Work Plan is necessarily focused on the projects on the IASB's current and future agenda, and those issued standards and amendments requiring a UKEB adoption decision regarding their use in the UK.
Since May 2021, when the UKEB was delegated its statutory functions, the number of IASB projects and the resulting UKEB workload has increased significantly. The table below outlines the key projects completed by the UKEB during each of the financial years 2022/23 and 2023/24 and those on the Work Plan for the coming year. The table below shows the increase in confirmed IASB projects. The UKEB has to undertake work on these projects in line with its statutory functions. However, some of these projects have been deferred due to lack of resources and funding (see detail in the Work Plan). The UKEB will only undertake work on those deferred projects if resource and funding become available. Other ancillary UKEB activities including stakeholder engagement are not included in this table.
| UKEB Expected Workload 2024/25 Significant | Moderate | Limited | Total | UKEB Expected Workload 2023/24 Significant | Moderate | Limited | Total | UKEB Actual Workload 2022/23 Significant | Moderate | Limited | Total |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Adoption Projects | |||||||||||
| 1 | 2 | 1 | 1 | 2 | 2 | 1 | 0 | 9 | |||
| Influencing Projects | |||||||||||
| 1 | 7 | 5 | 1 | 3 | 0 | 1 | 0 | 0 | |||
| Connectivity Projects and Papers | |||||||||||
| 0 | 1 | 0 | 3 | 5 | 0 | 1 | 1 | 0 | |||
| Research Papers | |||||||||||
| 1 | 1 | 0 | 1 | 2 | 0 | 1 | 1 | 0 | |||
| Total-Active | 3 | 11 | 6 | 20 | 6 | 12 | 2 | 20 | 4 | 2 | 9 |
| Deferred Projects | |||||||||||
| 1 | 2 | 4 | 7 | - | - | - | - | - | - | - | - |
| Total for the year | 4 | 13 | 10 | 27 | 6 | 12 | 2 | 20 | 4 | 2 | 9 |
Looking ahead to 2024/25
This year the UKEB's workplan includes adoption and influencing projects driven by the IASB's current workplan, connectivity work to the extent that ISSB standards affect the development of IFRS Accounting Standards, and the UKEB's pro-active research work. Our work programme must remain aligned with that of the IASB.
Several of the IASB projects listed in the 2023/24 workplan did not commence during the year as expected. Consequently, these projects have been included in the 2024/25 workplan. Where the IASB has deferred projects to later periods this has been reflected in the UKEB's expected timeline for undertaking those projects. As mentioned above, due to resource constraints the UKEB does not intend to take forward certain projects on the IASB's current workplan during this financial year. However, if resources become available, the Board may consider adding some of these projects to its agenda at a later date.
Endorsement and adoption projects
To enable UK companies to prepare for use of a new standard by the effective date, the endorsement and adoption process must commence in good time. This is particularly crucial for companies that have dual-listed status (in the US, for example) where the listing authorities require foreign registrants to use full IFRS as issued by the IASB. The UK legislative framework prescribes the process for the adoption of new standards. It is multi-faceted, requiring consideration from accounting technical, economic and legal perspectives. In addition, it stipulates consultation with stakeholders. As a result, the adoption process is labour-intensive, requiring a long lead time to prepare for the formal adoption decision. Adequate time must be permitted to enable full consideration of all relevant UK-specific technical, economic and legal implications, project-specific stakeholder outreach and input, as well as regular engagement at Board level.
Influencing projects
The UKEB's planned influencing activities for 2024/25 will continue to be flexible to address any changes to the IASB's workplan, whilst remaining responsive to Board agenda time and staff resource constraints. The proposed UKEB Work Plan for 2024/25, as set out below, includes projects currently on the IASB Work Plan and the key new projects expected to be added over the coming months.
UKEB research
The workplan includes some activities relating to research. These are necessary to fulfil the UKEB's thought leadership guiding principle and relate to priority areas of future development of international accounting standards such as those relating to intangible assets and reporting climate-related matters in financial statements. In addition, some capacity to support the IASB in ad hoc, country-specific research is also necessary as it is key to effective, early influencing of projects and building our working relationships.
UKEB stakeholder engagement
The workplan also allocates time to formal stakeholder engagement through the Board's advisory and working groups, and attendance at other meetings, for example the UKEB's representation at the IASB's Accounting Standards Advisory Forum (ASAF), where it is one of twelve members.
UKEB Expected Workplan 2024/25
| UKEB Expected Workplan 2024/25 | Expected Workload | Expected Timing of UKEB Work2 |
|---|---|---|
| Adoption Projects3 | ||
| 1 Primary Financial Statements (waiting for IASB to issue the standard April 2024) | Significant | 2024-25 |
| 2 Disclosure Initiative – Subsidiaries without Public Accountability: Disclosures (waiting for IASB to issue the standard April 2024) | Moderate | 2024-25 |
| 3 Amendments to the Classification and Measurement of Financial Instruments (waiting for IASB to publish Amendment Q2 2024) | Moderate | 2024 |
| Influencing Projects Converting to Adoption Projects | ||
| 4 Rate-regulated Activities (waiting for IASB to publish a new standard 2025) | Significant | 2024-25 |
| 5 IFRS Annual Improvements Volume 11 | Limited Scope | 2024-25 |
| 6 Financial Instruments with Characteristics of Equity | Moderate | 2024-25 |
| UKEB Expected Workplan 2024/25 | Expected Workload | Expected Timing of UKEB Work2 |
|---|---|---|
| Influencing Projects | ||
| IASB standard-setting4: | ||
| 7 Dynamic Risk Management (ED expected H1 2025) | Moderate | 2025 |
| 8 Business Combinations—Disclosures, Goodwill and Impairment (ED expected March 2024) | Moderate | 2024 |
| 9 Equity Method (ED expected H2 2024) | Limited Scope | 2024-25 |
| IASB post-implementation reviews | ||
| 10 PIR IFRS 9 Hedge Accounting | Limited Scope | 2024-25 |
| 11 PIR IFRS 16 Leases | Moderate | 2024-25 |
| IASB maintenance projects | ||
| 12 Power Purchase Agreements (ED expected April 2024) | Limited Scope | 2024-25 |
| 13 Updating the Subsidiaries without Public Accountability: Disclosures Standard (ED expected Q2 2024) | Limited scope | 2024-25 |
| 14 Provisions—Targeted Improvements (ED expected H2 2024) | Moderate | 2024-25 |
| 15 Interpretations Committee projects | Limited Scope | Ongoing |
| UKEB Expected Workplan 2024/25 | Expected Workload | Expected Timing of UKEB Work2 |
|---|---|---|
| Connectivity (IASB) – Influencing Projects | ||
| 16 Connectivity – Climate-related and Other Uncertainties in the Financial Statements | Moderate | 2024-25 |
| UKEB Research Projects | ||
| 17 Intangibles research | Significant | 2024 |
| 18 Additional research (topics TBC) | Moderate | 2024-25 |
| Other Corporate Reporting | ||
| 19 IFRS Foundation Due Process Handbook | Moderate | 2024-25 |
| 20 Monitoring changes to UK corporate reporting framework | Moderate | Ongoing |
| UKEB Ongoing Projects | ||
| 21 Parliamentary and due process reporting on technical activities | Limited Scope | Ongoing |
| 22 Governance of iXBRL - UK-SEF/IFRS Taxonomy | Limited Scope | Ongoing |
| UKEB Stakeholder Engagement | ||
| 23 Membership of, and/or attendance at: | Moderate | Ongoing |
| * Accounting Standards Advisory Forum (ASAF) | ||
| * International Forum of Accounting Standard-Setters (IFASS) | ||
| * World Standard-Setters (WSS) | ||
| 24 UKEB Standing advisory groups: | Moderate | Ongoing |
| * Accounting Firms & Institutes Advisory Group (AFIAG) | ||
| * Preparer Advisory Group (PAG) | ||
| * Investor Advisory Group (IAG) | ||
| * Academics Advisory Group (AAG) | ||
| 25 UKEB ad-hoc advisory group: | Moderate | Ongoing |
| * Rate-regulated Activities Technical Advisory Group (RRA TAG) | ||
| 26 UKEB working groups | Moderate | Ongoing |
| * Financial Instruments Working Group (FIWG) | ||
| * Sustainability Working Group (SWG) |
Deferred Projects
The following table sets out certain projects that are on the IASB and ISSB's workplan (or are expected to be added to their workplans) but, due to lack of resource and/or funding, the UKEB does not intend to take forward during this financial year. However, if resources and/or funding become available, the Board may consider adding some of these projects to its agenda at a later date.
| Projects to be deferred | ||
|---|---|---|
| UKEB Expected Workplan 2024/25 | Expected Workload | Expected Timing of UKEB Work |
| 1 IFRS 17 Insurance Contracts (monitoring) | Limited scope | 2024-25 |
| IASB pipeline projects: Will be considered when added to the IASB agenda and addressed subject to resource availability | ||
| 2 Intangible Assets | Moderate | |
| 3 IFRS 9—Amortised Cost Measurement | Moderate | 2024-25 |
| 4 Statement of Cash Flows and Related Matters | Significant | |
| 5 Sale and Leaseback of an Asset in a Single-Asset Entity (IFRS 10 and IFRS 16) | Limited scope | |
| 6 International Tax Reform—Pillar Two Model Rules (IAS 12) | Limited scope | |
| 7 Use of a Hyperinflationary Presentation Currency by a Non-hyperinflationary Entity (IAS 21) | Limited scope | |
| Connectivity (IASB) – Influencing Projects5 Will be considered when added to the IASB and ISSB agenda and will only be addressed subject to resource availability | ||
| 7 Connectivity - Intangible Assets | ||
| 8 Connectivity - Pollutant Pricing Mechanisms |
| Projects to be deferred | ||
|---|---|---|
| UKEB Expected Workplan 2024/25 | Expected Workload | Expected Timing of UKEB Work |
| 9 Connectivity – Integration in Reporting and Management Commentary | 2024-25 | |
| 10 Connectivity – ISSB Conceptual Framework | Ongoing | |
| 11 Connectivity - New projects (Awaiting ISSB Agenda finalisation) | Ongoing |
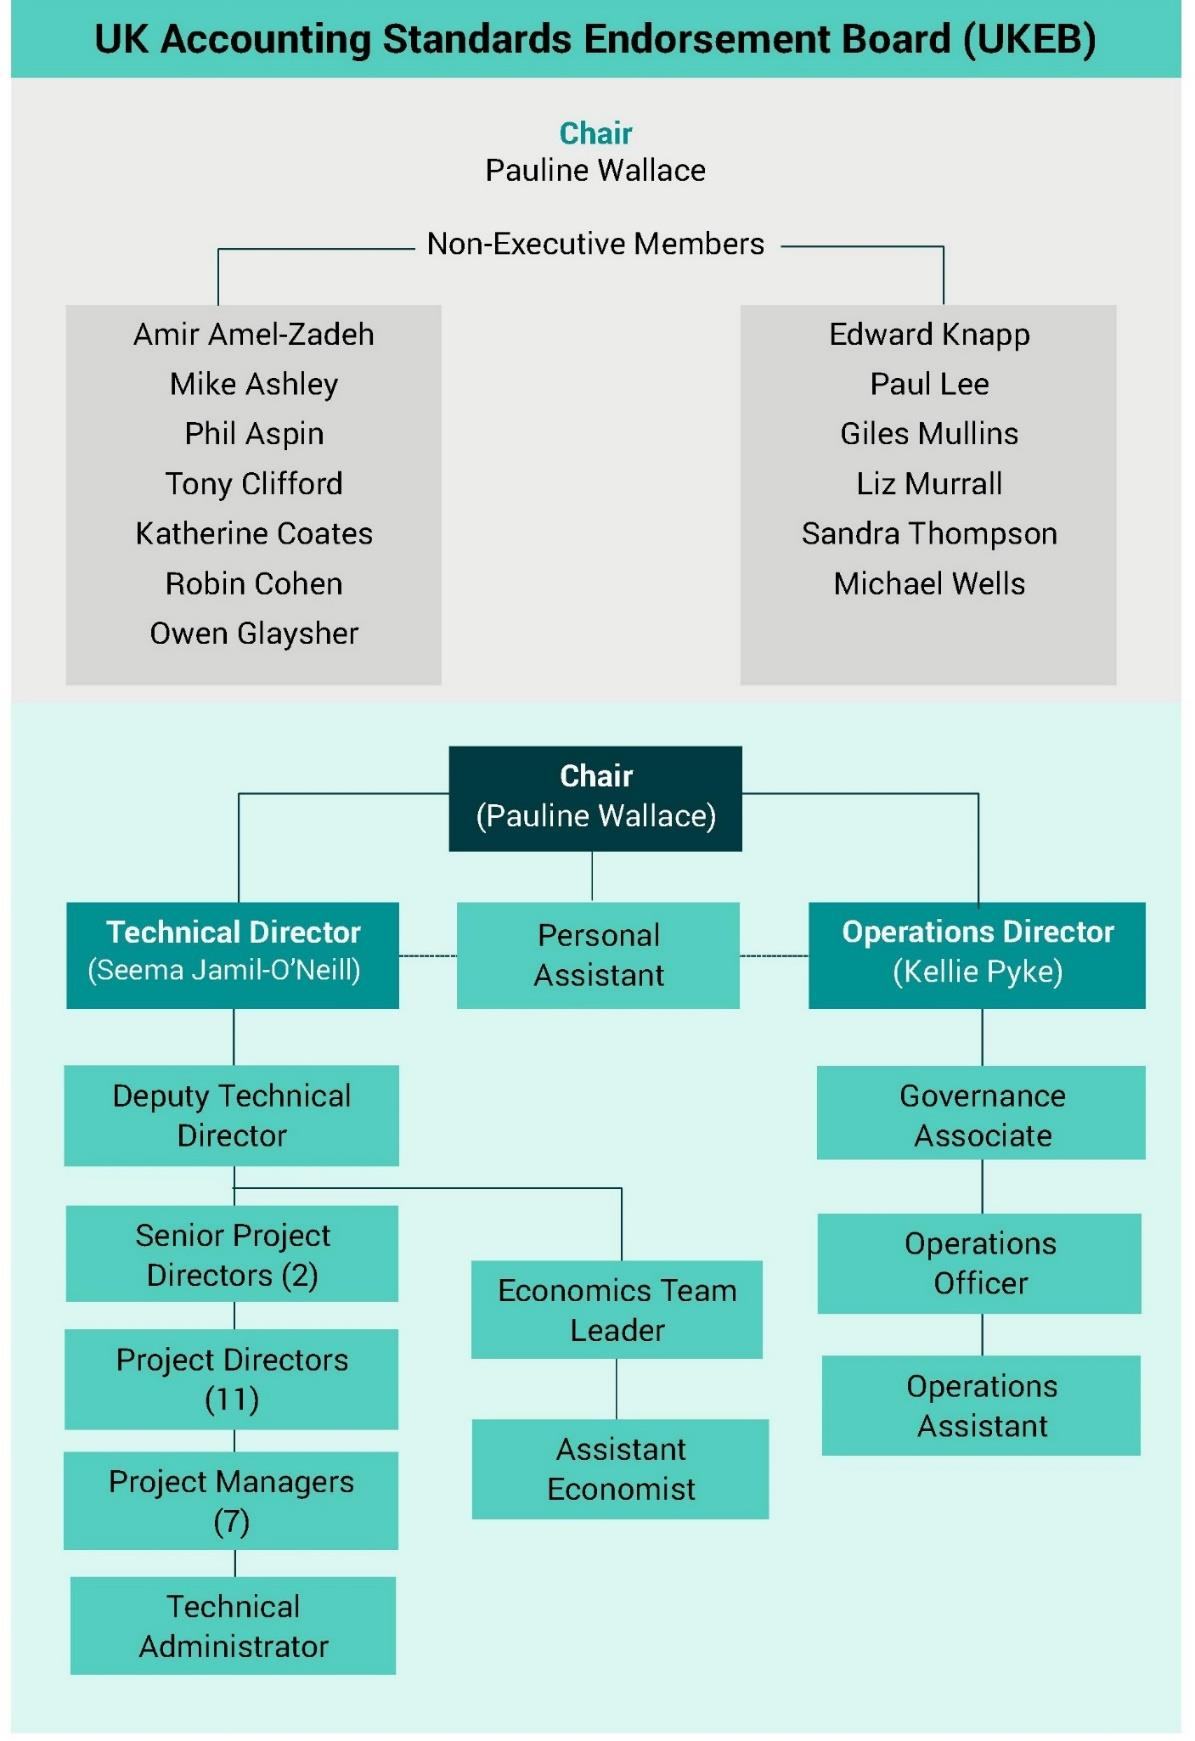
Appendix A: Organogram 2024/25
Contact Us UK Endorsement Board 10 South Colonnade | London | E14 4PU | United Kingdom www.endorsement-board.uk
Footnotes
-
Following the changes announced on 7 February 2023, oversight of the UKEB's discharge of its statutory functions moved from BEIS to the Department for Business and Trade. ↩
-
The Lack of Exchangeability endorsement and adoption project has not been included here as it is expected to be completed by 1 April 2024. ↩
-
The IASB's project on the Second Comprehensive Review of the IFRS for SMEs Accounting Standard is not included in this list as it is outside UKEB's remit. ↩
-
The ISSB is currently reviewing feedback from its Agenda Consultation. The ISSB projects referred here are an estimation of what may be included once the ISSB has finalised its Agenda. Similarly, the IASB projects are awaiting decision about inclusion to the active IASB workplan. These projects are included here for noting only. Decision on their inclusion to the UKEB's workplan will be made once the IASB and ISSB have decided on the project direction. ↩