6 Exposure Draft Proposed Targeted Amendments to the IFRS Foundation Constitution
22 October 2026
Agenda Paper 6
OFFICIAL - PUBLIC
Executive Summary
| Project Stage | ||||
|---|---|---|---|---|
| IFRS Foundation | Research / Pipeline | Exposure Draft | Redeliberation | Final Constitution Published |
| UKEB | Research / Influencing | Influencing | Monitoring | - |
Project Type
Influencing
Project Scope
Limited
Purpose of the Paper
The purpose of this paper is to obtain the Board’s: - Approval to issue a Final Comment Letter (FCL) (Appendix A) in response to the IFRS Foundation Trustee’s Exposure Draft (ED): Proposed Targeted Amendments to IFRS Foundation Constitution; - Approval to publish the Feedback Statement (Appendix B); and - Feedback on the [Draft] Due Process Compliance Statement (DPCS) (Appendix C).
Summary of the Issue
The IFRS Foundation Trustees have proposed targeted amendments to the IFRS Foundation Constitution, in the ED published on 18 August 2026. The consultation closes on 16 November 2026.
At its September 2026 meeting, the Board agreed to publish a Draft Comment Letter (DCL) for a 21-day consultation period. The shortened consultation period was agreed to allow the FCL to be brought to this meeting and for it to be submitted within the Foundation’s comment period.
Background
In 2024, the IFRS Foundation undertook a strategic and comprehensive review of its operations. As a result, the IFRS Foundation Trustees decided to streamline aspects of the Foundation’s operations and governance.
In 2025, the Trustees announced the decision to gradually reduce the size of its two standard-setting boards, the IASB and the ISSB, from 14 to 10 members.
Exposure Draft
On 18 August 2026, the Trustees of the IFRS Foundation published the ED Proposed Targeted Amendments to IFRS Foundation Constitution. The proposed amendments to the Constitution operationalise the reduction in the size of the Boards.
Other proposed amendments address matters relating to the operations of the smaller boards, such as the members’ geographical representation, voting arrangements, and other governance provisions.
UKEB Consultation on the DCL
The UKEB’s DCL was published on 22 September 2026 for a 21-day consultation, closing on 13 September 2026. Two written responses were received.
The DCL was discussed at the September 2026 meeting of the Financial Instruments Advisory Group (FIAG) and the October meeting of the Preparer Advisory Group (PAG). Members of both groups were supportive of the content of the letter.
We have also engaged with other organisations and regulators in the UK Corporate Reporting framework, and national standard setters and regulatory bodies in other jurisdictions.
Final Comment Letter
The FCL is included at Appendix A. It responds to the questions asked in the Consultation and recommends that the Trustees:
- Retain the IASB’s 14 members, with 12 members permitted, as a minimum size, to accommodate member turnover, when necessary.
- Preserve the strong geographical representation requirements linked to the jurisdictions and capital markets that adopt IFRS Accounting Standards;
- Enhance transparency regarding how future Board sizes and breadth of Board skills and experience will be determined and maintained;
- Actively manage the process for reducing the size of the boards to ensure the breadth of understanding and experience is maintained;
- Retain a super-majority style voting threshold for publication of Exposure Drafts and Standards;
- Retain stronger constitutional safeguards rather than transferring significant unconstrained discretion to the Trustees; and
- Clarify governance, accountability and reporting arrangements involving Trustees, Board members, Board Chairs and the Managing Executive Director to ensure their respective responsibilities are clearly defined.
Key changes from DCL
The FCL includes changes, from the draft published on 22 September 2026, to address points raised during the outreach period, and to ensure a better flow to the content of the letter. Additional sections have been highlighted for your information.
The revised letter places more focus on how the proposals could weaken the IASB’s legitimacy, representativeness and accountability, while offering a clearer and more focused set of recommendations for the Trustees.
In particular, the FCL key recommendations now specify that:
- the IASB should continue to consist of 14 members; the minimum of 12 members should relate to instances where the Board is managing member turnover; and
- the Trustees should actively manage the process for reducing the size of the boards to ensure the breadth of understanding and experience is maintained.
Decisions for the Board
1. Subject to addressing any comments raised at the meeting, does the Board approve:
- the FCL (Appendix A) for submission to the IFRS Foundation Trustees, and publication on the UKEB website?
- the Feedback Statement (Appendix B) for publication on the UKEB website?
2. Does the Board have any comments on the draft DPCS for the project (Appendix C)?
Recommendation
The Secretariat recommends that, subject to any amendments agreed at this meeting, the Board approves:
- the FCL for submission to the IFRS Foundation Trustees; and
- the FCL and Feedback Statement for publication.
Appendices
- Appendix A [Draft] Final Comment Letter.
- Appendix B Feedback Statement
- Appendix C [Draft] Due Process Compliance Statement
Appendix A: [Draft] Final Comment Letter
22 October 2026
Agenda Paper 6: Appendix A
OFFICIAL - PUBLIC
DRAFT FOR DISCUSSION
Mr Erkii Liikanen,
Chair, IFRS Foundation Trustees
IFRS Foundation
Colombus Building
7 Westferry Circus
Canary Wharf
LONDON
E14 4HD
[XX Month YYYY]
Dear Mr Liikanen
Exposure Draft: Proposed Targeted Amendments to IFRS Foundation Constitution
1. We welcome the opportunity to comment on the IFRS Foundation Trustees’ Exposure Draft: Proposed Targeted Amendments to the IFRS Foundation Constitution (the Constitution), published in August 2026.
2. It is vital for the Foundation to maintain its status as an independent, not-for-profit organisation operating in the public interest. The Foundation’s work is invaluable: it fosters trust, growth and long-term financial stability in global markets and the economy, as a whole.
3. The UK – including more recently the UK Endorsement Board – has always been a friend and strong supporter of the IASB and the wider IFRS Foundation. We continue to strongly support the IFRS Foundation's mission of developing high-quality global standards that promote transparency, accountability and comparability in international capital markets. Companies applying IFRS Accounting Standards produce information that leads to better investment decisions by investors and creditors, helping them to lower their cost of capital.
4. Given the UK Endorsement Board’s role, our comments focus on the proposed changes to the IASB, and on the role of the Trustees in relation to the IASB.
5. The Foundation’s current transformation programme provides a unique opportunity to reassess the governance structures and frameworks, that ensure its status as an independent, not-for-profit organisation, acting in the public interest, is maintained. However, we consider that the Trustees should be mindful not to risk the broad coalition of support upon which global standards depend.
6. Any framework of good governance requires the clear allocation of responsibilities, and of lines of oversight and accountability for the delivery of those responsibilities. Therefore, we strongly recommend the Foundation gives careful consideration to making further amendments to the Constitution, not only in relation to the composition of the two standard-setting boards but also in relation to the Trustees, their powers and oversight responsibilities.
7. Some areas where we believe the proposals need enhancing, in order to deliver these ambitions, are identified below.
Trustees
8. The proposals grant the Trustees substantial increased discretion, including:
- determining the number of board members, with regard to the respective board’s priorities and workload;
- permitting members to serve on a part-time basis; and
- the scope to allow the IASB to operate below the proposed minimum of 8 members;
9. However, no insight into how that discretion will be exercised has been provided, nor have any constraints or guardrails on the exercise of that discretion been set out.
10. Further, the suggestions that:
- the Trustees may substitute for board members in international outreach is unwelcome. It risks blurring the lines between governance and standard-setting and has the potential to reduce the Trustees’ ability to provide independent oversight of the two boards’ due process. In addition, it overlooks the need for transparency of decision-making on standards, a role that can only be delivered by the individual boards; and,
- jurisdictional participation in the boards can be considered across the two boards fails to recognise the vast difference in the nature of the standards being developed and published by the two boards, their global reach, and mandatory adoption status.
11. We would also encourage the Trustees to consider whether maintaining the current number of Trustees, is appropriate. Retaining 22 Trustees, while shrinking the size of both boards, risks giving the impression that the focus of the IFRS Foundation is more on governance than on its core standard-setting role.
IASB
12. We share the Trustees’ aim that the changes should not weaken the excellence of the IASB’s technical decision-making. The breadth of perspectives that board members bring to their technical debates, and their outreach to diverse stakeholders must be maintained. This is essential to the continued legitimacy of IASB and ISSB standards, and for maintaining global public and market confidence in them.
Size
13. We are unpersuaded that the size of the IASB should be reduced at all. While we appreciate that the amendments to the Constitution are proposed to apply to both boards, to create symmetry of their structure and governance, we believe there is clear public interest rationale for the IASB to be the larger, senior board. The existing size and structure of the IASB should be retained, to appropriately reflect the extent of international adoption of IFRS Accounting Standards, their required use by companies worldwide, and their importance to the global capital markets. We do not oppose introducing the proposed changes for the ISSB.
14. In the event of the IASB being reduced, we do not believe that it can remain effective with fewer than 12 members. Any further reduction below 12 risks placing undue burdens on fewer members, potentially impacting the quality and timeliness of decision-making. Fewer members in each geographical area also risks insufficient capacity to conduct stakeholder engagement.
Geographical representation and international support
15. The proposed reduction in geographical associations risks severing links of understanding and communication that are helpful in maintaining broad-based support for the IASB. The suggestion that this geographical connection can instead be maintained through input from consultative and advisory bodies or the technical staff is mistaken as the breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves. The proposed model considers geographical balance, but is likely to reduce practical representation from jurisdictions that account for significant elements of IFRS adoption and capital market activity.
16. A governance structure that weakens the voice of those jurisdictions and capital markets risks weakening their long-term support for international accounting standards.
17. We urge the IFRS Foundation to retain consistent and appropriate jurisdictional representation and recommend that the members from individual global regions are tasked to work together to seek and represent the views of stakeholders in that region, rather than only focusing on their specific jurisdiction.
Diversity of skills and backgrounds
18. The proposed reduction in board size also raises broader concerns, widely recognised in the governance literature, of reduced breadth of challenge and perspectives, more informal decision-making outside the boardroom, and other risks often summed up as “group think”. It would put at risk the broad diversity of views, skills and backgrounds around the board table (as admirably set out in the helpfully unchanged paragraph 26 of the Constitution and associated Annex) that are a necessary part of the legitimacy and quality of the IASB’s work.
Voting majorities
19. Similarly, super majority voting is another key aspect of maintaining the legitimacy of the board’s decision to issue an IFRS Accounting Standard that has global acceptance and support. A reduction in board numbers together with the changes proposed to the voting arrangements, have the potential to further dilute the necessary support. In particular, the Constitution should specify that the board should aim for consensus. If the members from a specific global area or representing a particular stakeholder group dissent to the publication of an Exposure Draft or Standard, further work should be carried out to develop an acceptable draft.
Key recommendations
20. In summary, we strongly recommend that the Trustees:
- Retain the IASB’s 14 members, with 12 members permitted, as a minimum size, to accommodate member turnover, when necessary.
- Preserve the strong geographical representation requirements linked to the jurisdictions and capital markets that adopt IFRS Accounting Standards.
- Enhance transparency regarding how future board sizes and breadth of board skills and experience will be determined and maintained.
- Actively manage the process for reducing the size of the boards to ensure the breadth of understanding and experience is maintained.
- Retain a super-majority style voting threshold for publication of Exposure Drafts and Standards.
- Retain stronger constitutional safeguards rather than transferring significant unconstrained discretion to the Trustees.
- Clarify governance, accountability and reporting arrangements involving Trustees, board members, board Chairs and the Managing Executive Director to ensure their respective responsibilities are clearly defined.
21. In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts. However, this letter, primarily, represents the Board’s view.
22. Our detailed views and rationale for our recommendations, in response to the questions raised in the Exposure Draft, are set out in Appendix A.
23. If you have any questions about this response, please do not hesitate to contact the project team at [email protected].
Yours sincerely
Paul Lee
Chair, UK Endorsement Board
About the UKEB: The UK Endorsement Board is responsible for the endorsement and adoption of IFRS Accounting Standards for use in the UK and is, therefore, the UK’s National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK’s engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
About IFRS in the UK: There are currently approximately 1,300 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.1 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.2
About this letter: This letter is intended to contribute to the Foundation’s due process.
Appendix A: Exposure Draft Proposed Targeted Amendments to the IFRS Foundation Constitution
Question 1—Board size and geographical allocation
Do you agree with how the Trustees propose to amend the Constitution to implement their decision to reduce the size of the boards by:
- specifying a range for board membership; and
- amending the geographical allocation of members to maintain appropriate international diversity and balance?
If not, why not, and what would you propose instead and why?
Reduction in Board size
A1. We do not support any reduction in the size of the IASB. However, we accept that a minimum of 12 members should be permitted, as a minimum size, as an exception, to accommodate for periods of member turnover, as necessary.
A2. The IASB performs a unique role in developing standards used in over 140 jurisdictions and across the world’s major capital markets. We are not persuaded that a board with any fewer members than 12 members can maintain the same breadth of expertise, experience, stakeholder engagement and jurisdictional understanding that has historically underpinned confidence in IFRS Accounting Standards.
Concentration of decision-making
A3. A smaller board inevitably concentrates decision-making authority in fewer individuals. A reduction in members will reduce the industry spread of expertise and the diversity of perspectives brought to technical deliberations, limiting breadth and independence of challenge in debate and so risking ‘group think’.
A4. The Trustees note (ED, pp 4 and 7) that the technical capacity of the board is supported by Foundation staff and consultative bodies. While these structures are important, they are not substitutes for the board members. Decisions at the board table are made by board members, not advisory groups or staff. The breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves.
Timeliness of standard-setting
A5. We also note the potential impact of a smaller board on the timeliness of standard-setting. Many IASB projects already span several years from initiation to completion, reflecting the complexity of the underlying issues, the implications for resulting financial information provided to global capital markets, and the importance of robust due process. Reducing the number of board members means responsibility for technical analysis and stakeholder engagement is focused on fewer individuals.
A6. This could constrain the board’s capacity to progress multiple projects simultaneously and may lead to longer project timelines, particularly where projects require significant outreach across jurisdictions and stakeholder groups. In our view, any governance changes should be assessed not only in terms of cost, but also in terms of their potential effect on the IASB's ability to deliver high-quality standards and amendments on a timely basis.
Variable Board size
A7. We note that the proposals suggest using a variable board size as a mechanism to respond to changes in workload (ED p 6 and para 25). We do not consider that board size can be adjusted quickly enough to respond to short- or medium-term changes in workload. This approach underestimates the time required to recruit individuals with the necessary technical expertise and international standing, completing the appointment process, and allowing new board members time to develop a detailed understanding of ongoing projects. In our view, this approach is unlikely to offer real practical benefit. Instead, it may create uncertainty regarding the future capacity of the board.
A8. We are particularly concerned that the ED provides very limited transparency regarding how the Trustees would determine the appropriate size of each board over time. References to “priorities and workload” are insufficiently specific.
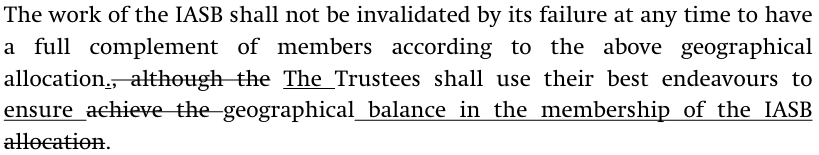
A9. We also note that the final sentence of paragraph 25 (“The work of the IASB shall not be invalidated by its failure at any time to have a full complement of members.”) proposes leaving open-ended discretion in the hands of the Trustees for the IASB to operate when it has fewer than 8 members. We believe there should be clarity over the intended timeframe within which any such – presumably temporary – reduction should be rectified. It would not be appropriate for the Trustees’ discretion to be open-ended.
Achieving a smooth transition
A10. We are also concerned that reducing the size of the board could create practical challenges in maintaining board resilience. In a small board, the departure of a single member may have a disproportionate effect on the board’s overall composition, particularly where that member contributes a specific geographical, professional, technical or stakeholder perspective. As members reach the end of their terms, the Trustees may face significant constraints in achieving an appropriate balance of experience and representation while also preserving continuity in the board's work.
A11. These challenges may be further compounded by the timing of appointments and reappointments. To maintain an appropriate balance of skills and perspectives, it may become necessary to adjust the timing of appointments or departures in ways that would not arise with a larger board. This could introduce unnecessary complexity into succession planning, discourage good candidates from applying, and may, at times, result in decisions being driven by the need to preserve board composition rather than by the natural completion of members' terms. We therefore encourage the Trustees to carefully consider the implications that a smaller board may have for maintaining both continuity and balance over the longer term.
A12. We also note that the Trustees’ current intention is to see a reduction of the IASB size through natural attrition, as existing members reach the end of their terms. We believe that the process needs to be more actively managed than this in order to ensure that the breadth of understanding and experience around the board table (as set out in paragraph 26 of the Constitution and associated Annex) is maintained throughout.
Recommendation
A13. We recommend that:
- the Constitution specify 14 members as the normal size of the IASB;
- any reduction below 14 members should be exceptional e.g. to allow for member turnover, and to an absolute minimum of 12 members, with a public timeline provided for the return to the normal level;
- any future decisions on board size should be demonstrably linked to workload and agenda consultation outcomes; and
- changes to the operation and governance are carefully handled in order to maintain board resilience.
A14. Stakeholders would also benefit from greater clarity regarding how often board size will be reassessed, the criteria applied and the evidence that would support reductions.
Position of the Trustees
A15. The proposals grant the Trustees substantial increased discretion, including:
- determining the number of board members, with regard to the respective board’s priorities and workload (paragraphs 25 and 44);
- permitting members to serve on a part-time basis (paragraphs 25A and 44A); and
- the scope to allow the IASB to operate below the proposed minimum of 8 members (paragraphs 25 and 44);
A16. However, no insight has been provided into how that discretion will be exercised, nor have any constraints or guardrails on the exercise of that discretion been set out.
A17. The proposals risk creating a perception of an imbalance between governance and technical standard-setting.
A18. The suggestion that the Trustees may substitute for IASB members in international outreach (that Trustees “provide strong links with particular jurisdictions”) is unwelcome: it risks blurring the lines between governance and standard-setting, potentially reducing the Trustees’ ability to provide independent oversight, and misses the need for transparency of decision-making on standards, a role that can only be delivered by the IASB itself. Any such blurring of the lines puts at risk the Trustees’ role in delivering due process oversight of the IASB. The success and legitimacy of the IFRS Foundation have been built on the IASB’s independence, technical expertise and international participation. These factors should not be diluted, and real care must be taken to ensure that no impression is given, whether through Constitutional language or by actions, that this might be happening.
A19. We would also encourage the Trustees to consider whether maintaining the current number of Trustees is appropriate. Retaining 22 Trustees, while shrinking the size of both boards, risks giving the impression that the focus of the IFRS Foundation is more on governance than on its core standard-setting role.
A20. Any changes must reflect the IFRS Foundation’s mission of working in the public interest to develop high-quality global standards that promote transparency, accountability and comparability in international capital markets. Stakeholder confidence that technical standard-setting remains at the heart of the IFRS Foundation's activities must be preserved.
A21. We suggest the following text changes to paragraph 25 of the Constitution:
- Revert to 14 members or change to “between 12 and 14 members” (and revert to current geographical spread in para 27);
- Delete proposed new text “with the Trustees determining the number of members having regard to the board’s priorities and workload”.
- Insert proposed deleted text “although the Trustees shall use their best endeavours to achieve a full complement” to the end of the paragraph.
Geographical allocation and jurisdictional legitimacy
A22. We would urge a reconsideration of the proposed reduction in geographical allocation from four members each from Asia-Oceania, Europe and the Americas to only two members each.
Geographical allocation
A23. The IASB is not simply a technical board. It is a global standard-setting body whose legitimacy depends on maintaining confidence amongst jurisdictions that adopt and implement IFRS Accounting Standards.
A24. Although board members act in the public interest, rather than as jurisdictional representatives, geographical allocation remains an important constitutional safeguard. It helps to ensure that the board’s decision-making is informed by practical experience from the jurisdictions and capital markets that use IFRS Accounting Standards. It also ensures informed stakeholder engagement in those jurisdictions at the board level.
A25. IFRS Accounting Standards derive their legitimacy from widespread adoption across global capital markets. It is essential that the board retains sufficient representation from those jurisdictions where the standards have the greatest economic significance and practical impact.
A26. In our view, geographical allocation should not be viewed solely through the lens of regional diversity. It should also reflect:
- the jurisdictions that have made the greatest commitment to IFRS Accounting Standards through adoption, implementation and ongoing participation in the standard-setting process; and
- the globally systemic capital markets that use IFRS Accounting Standards to enable significant flows of capital around the world.
A27. A governance structure that weakens the voice of those jurisdictions and capital markets risks weakening their long-term support for international standards.
A28. The proposed reduction from four members to two members from Europe, Asia-Oceania and the Americas appears inconsistent with the economic reality of global IFRS adoption. The majority of listed companies applying IFRS Accounting Standards, the largest pools of capital operating under those standards, and a substantial proportion of the IFRS Foundation’s funding, are concentrated within those regions. We, therefore, question whether a board structure that allocates only two members to each of those regions provides sufficient capacity to reflect the breadth and complexity of the issues arising across those markets.
A29. We consider that participation from Africa and other emerging economies remains relevant as consideration and inclusion of their perspectives ensure the status of IFRS as globally applicable standards is retained. However, this objective should not be achieved by significantly reducing representation from the largest IFRS capital markets.
A30. We urge the IFRS Foundation to retain consistent and appropriate jurisdictional representation and recommend that the members from individual global regions are tasked to work together to seek and represent the views of stakeholders in that region, rather than only focusing on their specific jurisdiction.
Jurisdictional participation across two boards
A31. The suggestion in the Invitation to Comment on the proposed amendments (page 7) that jurisdictional participation can be considered across the IASB and ISSB, collectively, is surprising. This assertion has not been explained, and we do not believe this is a credible basis on which to assess representation.
A32. The two boards have fundamentally different mandates and address different issues, requiring different expertise, perspectives and stakeholder engagement activities. Representation on one board does not provide meaningful participation in the technical decisions of the other. This is particularly important given the breadth and significance of the IASB's remit and the widespread use of IFRS Accounting Standards worldwide.
A33. In our view, jurisdictional participation needs to be considered separately for each board, with the composition of the IASB reflecting the jurisdictions and capital markets that rely on IFRS Accounting Standards, rather than being assessed across the Foundation’s governance structure as a whole.
Input from consultative and advisory groups
A34. We do not agree with the suggestion that jurisdictional participation can be adequately replaced through consultative bodies, advisory groups or other forums.
- Firstly, those bodies do not possess the decision-making authority of the IASB.
- Secondly, recent changes to some consultative mechanisms have reduced the weighting historically afforded to larger capital markets.
- Thirdly, the views expressed by advisory bodies, which (with the exception of ASAF) often include individuals providing views on an individual basis, cannot substitute for participation in board deliberations and voting.
A35. Consequently, we are not persuaded by the suggestion in the ED that reduced jurisdictional participation on the IASB can be compensated for through ASAF and other consultative bodies. The breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves.
Increased use of at-large appointments
A36. We support the Trustees’ proposal to formalise the recent practice of designating the Chair as one of the ‘at-large’ members. We agree that appointing the Chair from the ‘at-large’ group will ensure they are not seen as favouring the particular geographical region they otherwise might be drawn from.
A37. However, we are not convinced that the proposal to increase the overall number of at-large appointments will achieve the flexibility envisaged by the Trustees.
A38. The Constitution currently establishes a clear link between board composition and geographical participation. The proposed amendments weaken that link and replace it with significantly greater discretion, with no clarity over how that discretion might be exercised and any guardrails that might be in place.
A39. Although the ED states that overall geographical balance will be maintained, “geographical balance” is inherently less precise than the current geographical allocation requirements.
A40. The proposed framework might permit scenarios in which a disproportionate number of members came from a limited number of jurisdictions or regions while still being regarded as broadly balanced.
A41. We believe the Constitution should continue to prioritise geographical allocation rather than significantly expanding the number of at-large appointments.
A42. Our proposed alternative would be:
- three members from Asia-Oceania;
- three members from Europe;
- three members from the Americas;
- one member from Africa; and
- two to four at-large members (including the Chair),
resulting in a minimum of a 12-member board, with stronger geographical representation.
A43. The current, proposed number of IASB members in the ED and UKEB’s recommended numbers are set out below (paragraph 27 of the proposed Constitution):
Current and proposed number of IASB members
| Region | Current IASB | ED proposed IASB | UKEB recommends |
|---|---|---|---|
| Asia–Oceania | 4 | 2 | 3 |
| Europe | 4 | 2 | 3 |
| Americas | 4 | 2 | 3 |
| Africa | 1 | 1 | 1 |
| Any area (‘at-large members’) | 1 | 1–5 remaining | 4 |
| Total | 14 | 8–12 | 14 |
Significant capital market representation
A44. The UK, one of the largest and most internationally significant capital markets3 applying IFRS Accounting Standards, has always been supportive of the IFRS Foundation and the IASB.
A45. The Constitution should ensure that any future geographical model properly reflects the importance of major IFRS jurisdictions and capital markets, such as the UK, being appropriately reflected in the geographical representation of the IASB.
Question 2—Attributes of Board members
Do you agree with the Trustees’ decision to propose no changes in the Constitution:
- to the main provisions relating to part-time board membership; and
- to the main qualifications for membership of the boards?
If not, why not, and what would you propose instead and why?
Part-time IASB members
A46. We do not support retaining the existing provision allowing up to three part-time IASB members without further safeguards.
A47. A board of 8–12 members, with up to three part-time members, could have a significant proportion of its membership unable to devote full attention to technical and stakeholder responsibilities.
A48. The Trustees state that the reduction in board size can be accommodated through changes in how the boards undertake their work. We are concerned that, in practice, stakeholder engagement may be the activity most likely to be reduced.
A49. The development of high-quality standards requires both technical analysis and extensive stakeholder engagement. It should not be assumed that the latter can be scaled back without consequences.
A50. Part-time board members should be a rare exception. The limit on part-time members must be proportionate to the size of the board. At the lower level proposed in this ED, the limit should be one part-time member.
Qualifications for membership of Boards
A51. We agree that the existing qualification criteria remain appropriate. However, we think this should also include working knowledge of how standards fit into the corporate reporting framework within geographical areas and capital markets.
A52. We do not share the Trustees’ confidence that a smaller board can consistently maintain the same breadth of views, skills, professional backgrounds and perspectives that have historically contributed to the quality and credibility of IFRS Accounting Standards.
A53. In practice, reducing the size of the IASB inevitably increases the risk that important stakeholder groups, professional backgrounds or forms of expertise are not represented at the board table at particular points in time. While board members are expected to consider a wide range of views, direct participation from individuals with different professional experiences remains an important component of robust technical debate.
A54. Smaller boards are also at a greater risk of “group think” due to the limited range of perspectives expressed and potential lack of challenge.
A55. Recent board composition illustrates this concern; for example, the IASB currently lacks academic representation. Academic members have historically made valuable contributions by bringing independent research perspectives, conceptual rigour and long-term thinking to board deliberations. Academic presence has often strengthened the quality of technical analysis and challenge. A smaller board increases the likelihood that important perspectives of this nature are lost altogether rather than simply becoming less prominent.
A56. More generally, with any less than 12 members, it becomes increasingly difficult to achieve an appropriate balance across multiple dimensions simultaneously, including geographical diversity, investor and preparer perspectives, regulatory experience, auditing expertise, standard-setting experience and academic insight. The proposed reduction in board size creates a greater risk that individual vacancies or appointment decisions could materially affect the overall balance of the board in a way that would be less significant on a larger board.
Question 3—Voting arrangements
Do you agree with how the Trustees propose to update the voting requirements in the Constitution to facilitate effective decision-making for the smaller boards? If not, why not, and what would you propose instead and why?
Voting arrangements
A57. We do not support the proposed voting requirements, particularly as it would be operationalised with a smaller board. The publication of IFRS Accounting Standards should continue to require a stronger level of consensus than a simple majority plus one additional vote. We consider that to maintain global support, the aim should be to achieve as close to unanimity as possible.
A58. A significant minority of dissenting votes against an exposure draft (ED) or final Standard does not demonstrate the broad support necessary for a global standard. In particular, the Constitution should specify that if the members from a specific global area or representing a particular stakeholder group dissent to the publication of an ED or Standard, further work should be carried out to develop an acceptable draft.
A59. The existing voting arrangements have played an important role in demonstrating that issued Standards command broad support amongst board members, following extensive due process and stakeholder consultation. International adoption is facilitated when jurisdictions can see that a Standard has obtained substantial support from the board.
A60. For example, the proposed arrangements would permit publication of a Standard by six votes on an 8-member board. In our view, standards carrying global authority should not be capable of approval by, effectively, a narrow majority of a significantly reduced board.
Internal inconsistency and lack of clarity
A61. We also note several drafting issues requiring clarification:
- the relationship between the proposed “simple majority plus one” voting model and the Chair’s casting vote is unclear;
- the reference to decisions requiring a “simple majority” appears inconsistent with the voting requirements for Standards and Exposure Drafts;
- differing references to members “in office”, rather than “appointed members” and members “present at a meeting” require further explanation; and
- the Constitution should clarify the quorum applicable when approving Standards and Exposure Drafts.
Question 4—Other targeted amendments
Do you agree with the other proposed targeted amendments to the Constitution?
Section 25A
A62. We are concerned that the proposed wording no longer includes the requirement that the Trustees “use their best endeavours to achieve a full complement of members”.
A63. That requirement should be retained. Removing it weakens accountability and may reduce the urgency attached to filling board vacancies.
Board member terms
A64. The proposed amendments provide greater flexibility over appointment lengths and renewals.
A65. Whilst flexibility may be helpful, additional transparency is required regarding the factors to be considered when extending or not extending a member’s term.
A66. Greater clarity would strengthen confidence in the appointment process and the independence of board members.
Managing Executive Director
A67. We support efforts to clarify governance structures but believe further clarification is needed regarding reporting lines and responsibilities.
A68. In particular, it should be clear:
- whether staff report operationally to the Managing Executive Director or to the IASB and ISSB Chairs;
- how independence of the technical staff’s advice to the two boards and their subsequent decision making will be protected; and
- whether board members are accountable to the board Chairs, the Trustees or both.
Trustees and accountability
A69. We are concerned that some of the proposals may open the Trustees to unnecessary conflicts in their roles and responsibilities, or at least the appearance of such conflicts (see comments in paragraphs A16-A21 above).
A70. The proposals result in a significant transfer of discretion from the Constitution to the Trustees. The Constitution has historically provided important safeguards because changes to it require formal public consultation.
A71. The proposed amendments would significantly increase the discretion of the Trustees in relation to future decisions regarding board size and composition. However, we note that there is no clear indication of why the Trustees need these additional powers, nor of the constraints within which this new discretion will be exercised. In addition, some explanation is required of what key performance indicators will be used to measure success and how will the Memorandum of Understanding between the Trustees and the Monitoring Board will be amended to enable this review by the Monitoring Board.
A72. We appreciate that considering changes to governance and to the remit of the Trustees’ will be challenging. We therefore urge the Trustees to start this process by clearly explaining:
- what the problems are with the current structure that necessitate delegation of these additional powers to them, and how they intend to use them;
- to whom the Trustees are ultimately accountable;
- how their performance is evaluated; and
- what measures are used to assess whether they are successfully discharging their responsibilities.
Appendix B: Feedback Statement
DRAFT FOR DISCUSSION
Final Comment Letter (FCL)
22 October 2026
- Executive Summary
- Appendix A: [Draft] Final Comment Letter
- Appendix A: Exposure Draft Proposed Targeted Amendments to the IFRS Foundation Constitution
- Appendix B: Feedback Statement
- Appendix C: [Draft] Due Process Compliance Statement
- Milestone: Project Initiation Plan (PIP) (mandatory) [Due Process Handbook (Handbook) 6.12–6.16, A1–A2]
- Education Session/s (optional) [Handbook 4.10]
- Milestone: Desk-based Research (optional) [Handbook 5.9 and A3]
- Milestone: Outreach Activities [Handbook 5.10–5.12 and A4–A8]
- Milestone: Draft Comment Letter (DCL) published for comment (Mandatory unless impracticable) [Handbook 5.13–5.17 and A4(d)]
- Milestone: Final Comment Letter (FCL) [Handbook 5.18 and A4(d)]
- Milestone: Feedback Statement [Handbook 5.19–5.22 and A9–A11]
- Milestone: Due Process Compliance Statement (DPCS) [Handbook 5.23–5.26 and A12–A14]
- Communications (mandatory) [Handbook 4.20–4.25]
- Conclusion
Purpose and Disclaimer
This Feedback Statement presents the views of UK stakeholders received during the UKEB’s public consultation on the draft comment letter (DCL) relating to the IFRS Foundation Trustees’ Exposure Draft (ED) Proposed Targeted Amendments to the IFRS Foundation Constitution and, where relevant, explains how the UKEB addressed those views in its Final Comment Letter (FCL).
The UK Endorsement Board (UKEB) is the UK National Standard Setter for IFRS, responsible for the endorsement and adoption of international accounting standards, for use in the UK. The UKEB also leads the UK’s engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The comment letter, to which this feedback statement relates, forms part of those influencing activities and is intended to contribute to the IFRS Foundation’s due process.
The views expressed in this Feedback Statement are those of the UK Endorsement Board at the point of publication. Any sentiment or opinion expressed within this Feedback Statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Description of the Amendments
The Trustees of the IFRS Foundation published the ED Proposed Targeted Amendments to the IFRS Foundation Constitution.
Measures to streamline the Foundation’s operations and governance, following a 2024 review of its operations, included reducing the number of IASB and ISSB members.
The proposed amendments aim to operationalise the reduction in size of both standard-setting boards and provide a suitable governance framework for the smaller boards.
The ED proposes: - Specifying each board should normally comprise between eight and 12 members; - Reducing the number of members to be drawn from each global region and formalising the appointment of the Chair from the ‘at large’ category; and, - Requiring a simple majority plus one vote to approve the publication of Exposure Drafts and Standards.
Outreach approach
- The UKEB’s outreach activities took place between September and October 2026 and were conducted to assist the UKEB in developing its Comment Letter.
- The outreach approach was underpinned by the UKEB’s guiding principles of thought leadership, transparency, independence and accountability.
- Outreach activities included discussions with:
- The UKEB’s Financial Instruments Advisory Group (FIAG) and Preparer Advisory Group (PAG).
- UK and international bodies, including Government and regulators.
- Other National Standard-setters.
- Public consultation on the UKEB’s Draft Comment letter (DCL) was conducted for 21 days, from 22 September 2026 to 13 October 2026.
- The UKEB promoted awareness of the DCL, and encouraged stakeholders to respond, through the UKEB website, and a UKEB subscriber News Alert.
- All comments and views received were considered in reaching the UKEB final views on the proposals.
UKEB and stakeholder views
- The UKEB’s Draft Comment letter (DCL) recommended that the Trustees:
- Retain a larger IASB, with 12 as the normal minimum size.
- Preserve the stronger geographical representation requirements linked to the jurisdictions and capital markets that adopt IFRS Accounting Standards;
- Retain a super-majority style voting threshold for publication of Exposure Drafts and Standards;
- Enhance transparency regarding how future Board sizes and breadth of Board skills and experience will be determined and maintained;
- Retain stronger constitutional safeguards rather than transferring significant unconstrained discretion to the Trustees; and
- Clarify governance, accountability and reporting arrangements involving Trustees, Board members, Board Chairs and the Managing Executive Director to ensure their respective responsibilities are clearly defined.
- In addition to the feedback from the advisory groups, bodies and organisations set out above, the consultation also received two written responses. Overall, there was support for the UKEB’s DCL. The responses highlighted:
- The IASB's legitimacy, technical expertise, stakeholder representation or geographical balance should not be weakened by the proposed amendments.
- Greater transparency is required regarding Board composition and appointments.
In addition, one of the written responses raised broader corporate reporting and governance issues. However, they are outside the scope of the IFRS Foundation's consultation.
- Members of the UKEB’s Advisory Groups strongly recommended:
- The IASB retain a large, geographically representative board, to ensure the continued legitimacy of IFRS as global standards.
- The IASB continue to demonstrate the necessary breadth of skills and experience required of a global standard-setting board.
- In the absence of consensus, a super-majority style threshold be required for publishing Exposure Drafts and Standards.
- The Final Comment Letter (FCL) issued by the UKEB is mainly consistent with the views expressed in the DCL. However, the FCL addresses stakeholder feedback by emphasising that the:
- IASB should continue to consist of 14 members; the minimum of 12 members should relate to instances where the Board is managing member turnover.
- Trustees should aim to ensure that the proposed changes do not undermine representation, legitimacy and stakeholder confidence in the standard-setting process.
Contact Us
UK Endorsement Board
1 Harbour Exchange | London | E14 9GE
www.endorsement-board.uk
Appendix C: [Draft] Due Process Compliance Statement
22 October 2026
Agenda Paper 6: Appendix C
OFFICIAL - PUBLIC
DRAFT FOR DISCUSSION
The IFRS Foundation Trustees published Exposure Draft Proposed Targeted Amendments to the IFRS Constitution4 on 18 August 2026. The comment period ends on 16 November 2026.
Milestone: Project Initiation Plan (PIP) (mandatory) [Due Process Handbook (Handbook) 6.12–6.16, A1–A2]
| Milestone Requirement | Status |
|---|---|
| PIP completed (including objective, timeline, milestones, outreach plan, resources, output and explanations for any change in consultation period or whether an advisory group is necessary) and approved at public meeting | Complete: The PIP was approved at the 17 September 2026 Board meeting. |
| Assessment of whether PIP required updating | Complete: The PIP was published on the UKEB webpage on 22 September 2026. |
Education Session/s (optional) [Handbook 4.10]
| Milestone Requirement | Status |
|---|---|
| Board provided with Education session/s | Complete: N/A |
Milestone: Desk-based Research (optional) [Handbook 5.9 and A3]
| Milestone Requirement | Status |
|---|---|
| Review of relevant documentation | Complete: the Secretariat has reviewed: • IFRS Foundation documents (including the Constitution, Annual Reports and related documents, and feedback to previous consultations on the Constitution). • The Corporate Governance Code. • Relevant capital markets data. |
Milestone: Outreach Activities [Handbook 5.10–5.12 and A4–A8]
| Milestone Requirement | Status |
|---|---|
| Evidence of consultation | Complete: Due to the short timeline for the UKEB project, consultation activities were focused on consultation with the UKEB’s advisory groups, other organisations and regulators in the UK Corporate Reporting framework, and national standard setters and regulatory bodies in other jurisdictions. The UKEB received two formal comment letters. |
Milestone: Draft Comment Letter (DCL) published for comment (Mandatory unless impracticable) [Handbook 5.13–5.17 and A4(d)]
| Milestone Requirement | Status |
|---|---|
| The UKEB sets comment period for responses to Draft Comment Letter and published on website for public consultation | Complete: The DCL was published for consultation for 21 days on 22 September 2026 (comment period deadline: 13 October 2026). |
| Review and approval at a UKEB public meeting | Complete: The DCL was reviewed and approved, subject to further revisions, at the Board meeting on 17 September 2026. |
Milestone: Final Comment Letter (FCL) [Handbook 5.18 and A4(d)]
| Milestone Requirement | Status |
|---|---|
| Public responses to DCL assessed and published on website | Complete: The UKEB received two formal comment letters which were published on the UKEB website. All responses were assessed, reflected as appropriate in the FCL and summarised in the Feedback Statement. Verbal responses, provided at the advisory group meetings were assessed and reflected, as appropriate, in the FCL and summarised in the Feedback Statement. |
| FCL approved by the UKEB in public meeting | [Complete: The FCL was approved by the Board at its 22 October 2026 public meeting, subject to suggested amendments.] |
| FCL submitted to the IFRS Foundation Trustees and posted on UKEB website | [Complete: The FCL was submitted to the IFRS Foundation Trustees and posted on the UKEB website on [DD MM 2026]] |
Milestone: Feedback Statement [Handbook 5.19–5.22 and A9–A11]
| Milestone Requirement | Status |
|---|---|
| Feedback Statement approved for publication by the UKEB in a public meeting | Complete: A draft of the Feedback Statement [insert hyperlink] was presented to the Board for approval to the Board at its 22 October 2026 public meeting. [The Board approved the draft Feedback Statement, subject to editorial changes.] |
| Feedback Statement published on the UKEB website | [Complete: The final Feedback Statement was published on the UKEB website on {DD MM 2026].] |
Milestone: Due Process Compliance Statement (DPCS) [Handbook 5.23–5.26 and A12–A14]
| Milestone Requirement | Status |
|---|---|
| DPCS approved by the UKEB in public meeting | Complete: A draft DPCS was presented for approval to the Board at its 22 October 2026 public meeting. [A final DPCS was presented, for noting, at the Board’s 26 November 2026 meeting.] |
| DPCS published on the UKEB website | [Complete: The final DPCS was published on the UKEB website after the 26 November 2026 Board meeting.] |
Communications (mandatory) [Handbook 4.20–4.25]
| Milestone Requirement | Status |
|---|---|
| Board meeting papers posted and publicly available usually no later than 5 working days before a Board meeting | Complete: The UKEB’s meeting papers were published on the UKEB website 5 working days before the public meetings. Meeting minutes and recordings were made publicly available via the UKEB website. |
| Project webpage contains a project description with up-to-date project information | Complete: The project webpage has been updated regularly on a timely basis. |
| Subscriber alerts | Complete: Subscribers were alerted via email 5 working days before each Board meeting, with links to the agenda, papers and the option to dial in to observe the discussion. |
| News Alerts | Complete: A News Alert was published on [DD MM 2026] alerting stakeholders to the FCL and the Feedback Statement. |
Conclusion
This project complies with the applicable due process steps, as set out in the December 2022 Handbook.
Footnotes
-
UKEB calculation based on London Stock Exchange Group (LSEG) and Eikon data, November 2025. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩
-
The UK is home to one of the world's largest capital markets. For example, companies listed on the London Stock Exchange had a combined market capitalisation exceeding £3.2 trillion in 2025, making London one of the most significant financial centres globally and one of the largest markets reporting under IFRS Accounting Standards. All UK entities with securities listed on a UK regulated market must prepare their consolidated financial statements using UK-adopted IFRS Accounting Standards. London's market serves both domestic and international issuers and investors, meaning that IFRS Accounting Standards play a critical role in the efficient functioning of global capital markets operating through the UK. ↩
-
Exposure Draft: Proposed Targeted Amendments to the IFRS Foundation Constitution ↩