8 Exposure Draft Proposed Targeted Amendments to IFRS Foundation Constitution
17 September 2026 Agenda Paper 8 OFFICIAL - PUBLIC
Executive Summary
| Board | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review | Additional Stage |
|---|---|---|---|---|---|---|---|---|
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review | |
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing | UKEB Post Implementation Review |
Project Type: Influencing
Project Scope: Limited
Purpose of the Paper
The purpose of this paper is to:
- Provide the Board with a proposed Project Initiation Plan (PIP) for the project to influence the IFRS Foundation Trustee’s Exposure Draft (ED): Proposed Targeted Amendments to IFRS Foundation Constitution.
- Obtain Board feedback on the PIP and proposed draft comment letter.
- Request the Board’s approval to publish the PIP on the UKEB website and the draft comment letter for consultation with stakeholders.
Summary of the Issue
The IFRS Foundation Trustees have proposed targeted amendments to the IFRS Foundation Constitution, in the ED published on 16 August 2026. The consultation on the proposals closes on 16 November 2026.
The IFRS Foundation Trustees announced the reduction in the size of its two standard-setting boards, the IASB and the ISSB, from 14 to 10 members. The Trustees propose amending the Constitution in order to operationalise this reduction. Other proposed amendments address matters relating to the operations of the smaller boards, such as the members’ geographical representation, voting arrangements, and other governance provisions.
Project Initiation Plan
The PIP is included at Appendix A. It recommends a ‘Limited scope’ project plan.
Due to the timing of the publication of the ED, the UKEB September 2026 meeting is the first opportunity for the Board to consider a PIP for the project and review a draft comment letter. As the UKEB’s November meeting is scheduled for 26 November 2026, after the Trustees’ consultation period ends, the Board will review the Final Comment Letter at its meeting in October 2026.
To facilitate this timeline, a 21-day consultation period is proposed.
Draft Comment Letter
The Draft Comment letter is included at Appendix B. It responds to the questions asked in the Consultation and recommends that the Trustees:
- Retain a larger IASB, with 12 members as the normal minimum size.
- Preserve the stronger geographical representation requirements linked to the jurisdictions and capital markets that adopt IFRS Accounting Standards;
- Retain a super-majority style voting threshold for publication of Exposure Drafts and Standards;
- Enhance transparency regarding how future Board sizes and breadth of Board skills and experience will be determined and maintained;
- Retain stronger constitutional safeguards rather than transferring significant unconstrained discretion to the Trustees; and
- Clarify governance, accountability and reporting arrangements involving Trustees, Board members, Board Chairs and the Managing Executive Director.
Invitation to Comment
An Invitation to Comment is included at Appendix C. It reiterates our position in response to the ED’s proposals and asks stakeholders whether they agree with our position, and provide rationale for their view.
Decisions for the Board
Subject to addressing any comments raised at the meeting, does the Board approve:
- the Project Initiation Plan; and
- the Draft Comment Letter and ITC to be published for a 21-day consultation?
Recommendation
We recommend the Board approves the PIP and Draft Comment Letter, subject to the comments raised by the Board being addressed.
Appendices
- Appendix A [Draft] Project Initiation Plan: Proposed Targeted Amendments to IFRS Foundation Constitution.
- Appendix B Proposed Draft Comment Letter
- Appendix C Invitation to Comment
Appendix A: Project Initiation Plan
Purpose
A1 This paper sets out the plan to influence the IFRS Foundation Trustees’ Exposure Draft (ED) Proposed Targeted Amendments to the IFRS Foundation Constitution. The ED was published on 18 August 2026 with a consultation period ending on 16 November 2026.
A2 The ED aims to operationalise the Trustees’ 2025 decision to reduce the size of the International Accounting Standards Board (IASB) and the International Sustainability Standards Board (ISSB), from 14 to 10 members each.
Background
A3 In 2024, the IFRS Foundation carried out a review of its operations, which informed a transformation programme, to streamline aspects of the Foundation’s operations and governance structure. The programme aims to ensure the IFRS Foundation’s continued service as the global corporate reporting standard-setter.
A4 Streamlining measures include reducing the size of both standard-setting boards and the IFRS Foundation Constitution is being amended to operationalise the change. The Trustees’ proposed amendments intend to provide a suitable governance framework for the smaller boards to ensure they continue to function effectively.
Summary of Proposed Changes
A5 The proposed amendments align requirements relating to the two boards with the proposed reduction in board members. The matters addressed are set out below.
Board size
A6 Currently, the IASB and the ISSB shall normally comprise 14 members each. The Trustees propose amending the Constitution to reduce this number so to specify that each Board should normally comprise between eight and 12 members. The Trustees will take account of the respective boards’ workload and priorities in determining the number of members appointed to it.
A7 The proposals anticipate that from 2028, each board will be expected to comprise of 10 members. The upper limit of 12 members is to provide flexibility if, for example, there are a large number of part-time members.
Geographical representation
A8 Board members are appointed as individuals and not to represent their respective jurisdiction. Nonetheless, the board is appointed to represent the geographical diversity of the standards’ application.
A9 Therefore, the number of members to be drawn from each area of the globe has been reduced, in line with the reduction in the size of the boards. The Trustees state that the proposals “maintain the principle of broad international balance, ensuring that the boards continue to reflect the global nature of the Foundation’s work and supporting confidence that the boards remain geographically diverse and credible global standard setters”.
A10 The Trustees also propose formalising the recent practice of appointing the Chair from the ‘at-large’ category, so that it is not restricted to any specific region.
Voting arrangements
A11 The Trustees propose to align the voting provisions with the reduced size of the boards:
- Decisions relating to the publication of Exposure Drafts and Standards will change from super-majority voting to requiring a simple majority plus one vote, with a minimum of five affirmative votes.
- All other decisions will require a simple majority, with a minimum of four affirmative votes.
Project Plan
A12 A proportionate approach has been applied in accordance with paragraphs 3.7 and 5.3 of the UKEB’s Due Process Handbook. The Secretariat recommends the ‘Limited scope’ project plan shown below. The factors considered in arriving at this project plan are described in paragraphs A13–A21. A timeline for the key project milestones is presented in paragraph A25.
| Key Activities | Due Process Handbook Reference | Status |
|---|---|---|
| Creation of a Project Initiation Plan (this document) | 5.4 - 5.8 | Mandatory |
| Desk-based research to support the proportionality assessment including: a) Review of previous Constitution amendments and consultation responses |
5.9 | Optional |
| Publication of a Draft Comment Letter for public consultation a) The DCL will be published on the UKEB website. b) Announcement of the publication of the DCL and ITC will be made via the UKEB News Alert publication, and LinkedIn posts. c) The DCL and ITC will be issued for comment for 21 days. |
5.13 - 5.17 | Generally mandatory |
| Stakeholder outreach pre-DCL publication The timeline for this project has not accommodated formal pre-DCL stakeholder outreach. |
5.10 - 5.12 | Mandatory |
| Stakeholder outreach post-DCL publication a) Stakeholder outreach will be via written responses to the DCL consultation–responses will be published on the UKEB website. b) In addition, the DCL consultation will be highlighted as an item for noting at meetings of the UKEB Advisory Groups scheduled during the consultation period.1 |
5.10 - 5.12 | Mandatory |
| Final Comment Letter A final comment letter will be created for Board approval, submission to the IFRS Foundation Trustees, and publication on the UKEB website. |
5.18 | Mandatory |
| Project Closure A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
5.19 - 5.26 | Mandatory |
Proportionality Assessment
Significance and Size
A13 The UKEB is responding to this consultation because the governance of the IFRS Foundation and the operation of its two boards directly impacts the development of IFRS standards.
A14 Changes to the Constitution may impact how the UKEB is able to engage with the IFRS Foundation and the members of its boards, particularly the IASB, in carrying out its statutory functions and adhering to its own due process requirements.
Complexity
A15 The proposals are intended to operationalise the Trustees’ decision to reduce the size of the two standard-setting boards. As such, we do not believe that the proposals are highly technical or complex. However, some complexity arises from understanding the governance implications of the changes being proposed.
Expected Timeline / Urgency
A16 The IFRS Foundation Trustees published the Exposure Draft of Proposed Targeted Amendments to the IFRS Foundation Constitution on 18 August 2026 for a 90-day consultation period. The consultation ends on 16 November 2026.
A17 Due to the timing of the UKEB Board meetings, the September 2026 meeting is the first opportunity for the Board to review a draft comment letter. As the UKEB’s November meeting is scheduled for 26 November 2026, after the Trustees’ consultation period ends, the Board will review the Final Comment Letter at its meeting in October 2026.
A18 To facilitate this timeline, a 21-day consultation period is proposed.
Expected Interest / Sensitivity
A19 Given the impact of the work of the IFRS Foundation on the transparency in the UK capital market, we expect other UK bodies within the company reporting framework to respond to the consultation.
Feedback on the Proposals from Desk-based Research
A20 We reviewed the IFRS Foundation Constitution, Annual Reports and related documents, feedback to previous consultations, the Corporate Governance Code, and reviewed relevant capital markets data.
Connectivity
A21 As the Constitution applies to the operation of the IFRS Foundation and both its standard-setting boards, the UKEB has an interest in the proposed changes to the ISSB, as well as the IASB.
Recommended UKEB Project Scope
A22 Based on the proportionality assessment above we recommend a ‘Limited’ project scope, and the approach described in this document reflects this.
Resources Allocated
A23 To undertake the activities described in this project plan, a Project Director – Governance Lead has been assigned for the brief period of the project, with some assistance from other senior resource with knowledge and understanding of the workings of the two boards. The required resources are allowed for in the 2025/26 UKEB plan and budget.
Setting up an Ad-hoc Advisory Body
A24 The UKEB will not require a separate ad-hoc advisory body for this project. Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
Project Timeline
A25 The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time.
| Date | Milestone |
|---|---|
| 17 September 2026 | Project Initiation Plan for Board approval Draft Comment Letter for Board approval |
| 21 September – 12 October 2026* | Estimated DCL consultation period |
| 22 October 2026 | Board review of Final Comment Letter, Feedback Statement, draft Due Process Compliance Statement |
| 13 November 2026 | Final Comment Letter submitted to IASB (deadline 16 November 2026) |
| 26 November 2026 | Due Process Compliance Statement for noting |
* To be confirmed
Appendix B: Proposed Draft Comment Letter
Mr Erkii Liikanen,
Chair, IFRS Foundation Trustees
IFRS Foundation
Colombus Building
7 Westferry Circus
Canary Wharf
LONDON
E14 4HD
[XX Month YYYY]
DRAFT FOR DISCUSSION
Dear Mr Liikanen,
Exposure Draft: Proposed Targeted Amendments to IFRS Foundation Constitution
1 We welcome the opportunity to comment on the IFRS Foundation Trustees’ Exposure Draft: Proposed Targeted Amendments to the IFRS Foundation Constitution (the Constitution), published in August 2026.
2 The UK – including more recently the UK Endorsement Board – has always been a friend and strong supporter of the IASB and the wider IFRS Foundation. We continue to be strongly supportive of the IFRS Foundation's mission of developing high-quality global standards that promote transparency, accountability and comparability in international capital markets. Companies applying the standards produce information that leads to better investment decisions, lowering the cost of capital, and we support the Foundation’s work in the public interest to foster trust, growth and long-term financial stability in global markets and the economy as a whole. All comments that we make in this response should be understood in the context of that broad support.
3 Using the current financial challenges as a moment to reassess governance structures and frameworks for the Foundation – while maintaining its vital status as an independent, not-for-profit organisation – makes sense. We believe that this reassessment should directly include issues in relation to the Trustees as well as the two standard-setting Boards – particularly as we note that the draft already in effect makes changes with regard to the powers of the Trustees. Any framework of good governance requires the clear allocation of responsibilities, and of lines of oversight and accountability for the delivery of those responsibilities.
4 Given the UK Endorsement Board’s role, we focus our comments on the proposed changes to the IASB, and on the role of the Trustees in relation to the IASB.
Trustees
5 We share the Trustees’ aim that the changes should not weaken the excellence of the IASB’s technical decision-making, the breadth of perspectives that Board members bring to their technical debates, and the outreach that they maintain to diverse stakeholders. We agree that this is essential for maintaining global public and market confidence in the standards produced by the two boards and for maintaining their continued global legitimacy. We identify some areas where we believe the proposals need enhancing in order to deliver these ambitions.
6 Proposals grant the Trustees substantial increased discretion – including over the size of each Board from time to time, any failure to maintain intended geographic diversity, and over the scope for the IASB to operate below the stated minimum of 8 members – without providing any insight into how that discretion will be exercised, and any constraints and guardrails on the exercise of that discretion.
7 Further, the suggestion that the Trustees may substitute for IASB members in international outreach is unwelcome: it risks blurring the lines between governance and standard-setting, potentially reducing the Trustees’ ability to provide independent oversight, and misses the need for transparency of decision-making on standards, a role that can only be delivered by the IASB. We would also encourage the Trustees to consider whether maintaining the current number of Trustees while shrinking the size of both Boards risks giving the impression that the focus of the IFRS Foundation is more on governance than on its core standard-setting role.
IASB
8 We are unpersuaded that the IASB should be reduced below 12 members. Any reduction beyond this risks placing undue burdens on fewer members, potentially impacting the quality and timeliness of decision-making, and capacity for stakeholder engagement. It also would put at risk the broad diversity of skills and backgrounds around the Board table (as admirably set out in the helpfully unchanged paragraph 26 of the Constitution and associated Annex) that is a necessary part of the legitimacy and quality of the IASB’s work.
9 Further, the associated reduction in geographical associations risks severing links of understanding and communication that are helpful in maintaining broad-based support for the IASB. The suggestion that this geographical connection can instead be maintained through input from consultative and advisory bodies or the technical staff is mistaken as the breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves. The proposed model considers geographical balance, but is likely to reduce practical representation from jurisdictions that account for significant elements of IFRS adoption, capital market activity and funding. We do not think the Trustees should risk the broad coalition of support upon which global standards depend.
Key recommendations
10 We strongly recommend that the Trustees:
- Retain a larger IASB, with 12 members as the normal minimum size.
- Preserve the stronger geographical representation requirements linked to the jurisdictions and capital markets that adopt IFRS Accounting Standards;
- Retain a super-majority style voting threshold for publication of Exposure Drafts and Standards;
- Enhance transparency regarding how future Board sizes and breadth of Board skills and experience will be determined and maintained;
- Retain stronger constitutional safeguards rather than transferring significant unconstrained discretion to the Trustees; and
- Clarify governance, accountability and reporting arrangements involving Trustees, Board members, Board Chairs and the Managing Executive Director.
11 In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts. However, this letter, primarily, represents the Board’s view.
12 Our detailed views and rationale for our recommendations, in response to the questions raised in the Exposure Draft (ED), are set out in Appendix A.
13 If you have any questions about this response, please do not hesitate to contact the project team at [email protected].
Yours sincerely,
Paul Lee
Chair, UK Endorsement Board
About the UKEB: The UK Endorsement Board is responsible for the endorsement and adoption of IFRS Accounting Standards for use in the UK and is, therefore, the UK’s National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK’s engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
About IFRS in the UK: There are currently approximately 1,300 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.2 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.3
About this letter: This letter is intended to contribute to the Foundation’s due process.
Appendix B - Appendix A: Detailed Response to Exposure Draft Questions
Question 1—Board size and geographical allocation
Do you agree with how the Trustees propose to amend the Constitution to implement their decision to reduce the size of the boards by:
(a) specifying a range for board membership; and
(b) amending the geographical allocation of members to maintain appropriate international diversity and balance?If not, why not, and what would you propose instead and why?
A1 The current and proposed number of IASB members is set out below (paragraph 27 of the proposed Constitution):
| Region | Current IASB | Proposed IASB |
|---|---|---|
| Asia–Oceania | 4 | 2 |
| Europe | 4 | 2 |
| Americas | 4 | 2 |
| Africa | 1 | 1 |
| Any area (‘at-large members’) | 1 | 1–5 remaining members |
| Total | 14 | 8–12 |
Reduction in Board size
A2 We understand the Trustees’ decision to reduce the minimum size of the IASB to 12 members. However, we do not support any further reduction to the minimum size of the IASB.
A3 The IASB performs a unique role in developing standards used in over 140 jurisdictions and across the world’s major capital markets. We are not persuaded that a Board with any fewer members than 12 can maintain the same breadth of expertise, experience, stakeholder engagement and jurisdictional understanding that has historically underpinned confidence in IFRS Accounting Standards.
Concentration of decision-making
A4 A smaller Board inevitably concentrates decision-making authority in fewer individuals. A reduction in members will reduce the industry spread of expertise and the diversity of perspectives brought to technical deliberations.
A5 The Trustees note (ED, pp 4 and 7) that the technical capacity of the Board is supported by Foundation staff and consultative bodies. While these structures are important, they are not substitutes for the Board members. Decisions at the Board table are made by Board members, not advisory groups or staff. The breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves.
Timeliness of standard-setting
A6 We also note the potential impact of a smaller Board on the timeliness of standard-setting. Many IASB projects already span several years from initiation to completion, reflecting the complexity of the underlying issues, the implications for resulting financial information provided to global capital markets, and the importance of robust due process. Reducing the number of Board members means responsibility for technical analysis and stakeholder engagement is focused on fewer individuals.
A7 This could constrain the Board’s capacity to progress multiple projects simultaneously and may lead to longer project timelines, particularly where projects require significant outreach across jurisdictions and stakeholder groups. In our view, any governance changes should be assessed not only in terms of cost, but also in terms of their potential effect on the IASB's ability to deliver high-quality standards and amendments on a timely basis.
Variable Board size
A8 We note that the proposals suggest using a variable Board size as a mechanism to respond to changes in workload (ED p 6 and para 25). We do not consider that Board size can be adjusted quickly enough to respond to short- or medium-term changes in workload. This approach underestimates the time required to recruit individuals with the necessary technical expertise and international standing, completing the appointment process, and allowing new Board members time to develop a detailed understanding of ongoing projects. In our view, this approach is unlikely to offer real practical benefit. Instead, it may create uncertainty regarding the future capacity of the Board.
A9 We are particularly concerned that the ED provides very limited transparency regarding how the Trustees would determine the appropriate size of each Board over time. References to “priorities and workload” are insufficiently specific.
A10 We also note that the newly proposed final sentence of paragraph 25 (“The work of the IASB shall not be invalidated by its failure at any time to have a full complement of members.”) proposes leaving open-ended discretion in the hands of the Trustees for the IASB to operate when it has fewer than 8 members. We believe there should be clarity over the intended timeframe within which any such – presumably temporary – reduction should be rectified. It would not be appropriate for the Trustees’ discretion to be open-ended.
Achieving a smooth transition
A11 We are also concerned that reducing the size of the board could create practical challenges in maintaining board resilience. In a small board, the departure of a single member may have a disproportionate effect on the board’s overall composition, particularly where that member contributes a specific geographical, professional, technical or stakeholder perspective. As members reach the end of their terms, the Trustees may face significant constraints in achieving an appropriate balance of experience and representation while also preserving continuity in the Board's work.
A12 These challenges may be further compounded by the timing of appointments and reappointments. To maintain an appropriate balance of skills and perspectives, it may become necessary to adjust the timing of appointments or departures in ways that would not arise with a larger board. This could introduce unnecessary complexity into succession planning, discourage good candidates from applying, and may, at times, result in decisions being driven by the need to preserve board composition rather than by the natural completion of members' terms. We therefore encourage the Trustees to carefully consider the implications that a smaller Board may have for maintaining both continuity and balance over the longer term.
A13 We also note that the Trustees’ current intention is to see a reduction of the IASB size through natural attrition, as existing members reach the end of their terms. We believe that the process needs to be more actively managed than this in order to ensure that the breadth of understanding and experience around the Board table (as set out in paragraph 26 of the Constitution and associated Annex) is maintained throughout.
Recommendation
A14 We recommend that:
- the Constitution specify 12 members as the normal minimum size of the IASB;
- any reduction below 12 members should be exceptional, with a public timeline provided for the return to the normal level; and
- future decisions on Board size should be demonstrably linked to workload and agenda consultation outcomes.
A15 Stakeholders would also benefit from greater clarity regarding how often Board size will be reassessed, the criteria applied and the evidence that would support reductions.
Position of the Trustees
A16 The proposals risk creating a perception of an imbalance between governance and technical standard-setting. We would encourage the Trustees to consider whether maintaining the current number of Trustees while shrinking the size of both Boards risks giving the impression that the focus of the IFRS Foundation is more on governance than on its core standard-setting role.
A17 The suggestion that the Trustees may substitute for IASB members in international outreach (that Trustees “provide strong links with particular jurisdictions”) is unwelcome: it risks blurring the lines between governance and standard-setting, potentially reducing the Trustees’ ability to provide independent oversight, and misses the need for transparency of decision-making on standards, a role that can only be delivered by the IASB itself. Any such blurring of the lines puts at risk the Trustees’ role in delivering due process oversight of the IASB. The success and legitimacy of the IFRS Foundation have been built on the IASB’s independence, technical expertise and international participation. These factors should not be diluted, and real care must be taken to ensure that no impression is given, whether through Constitutional language or by actions, that this might be happening.
A18 Any changes must reflect the IFRS Foundation’s mission of developing high-quality global standards that promote transparency, accountability and comparability in international capital markets. Stakeholder confidence that technical standard-setting remains at the heart of the IFRS Foundation's activities must be preserved.
Geographical allocation and jurisdictional legitimacy
A19 We would urge a reconsideration of the proposed reduction in geographical allocation from four members each from Asia-Oceania, Europe and the Americas to only two members each.
Geographical allocation
A20 The IASB is not simply a technical board. It is a global standard-setting body whose legitimacy depends on maintaining confidence amongst jurisdictions that adopt and implement IFRS Accounting Standards.
A21 Although Board members act in the public interest, rather than as jurisdictional representatives, geographical allocation remains an important constitutional safeguard. It helps to ensure that the Board’s decision-making is informed by practical experience from the jurisdictions and capital markets that use IFRS Accounting Standards. It also ensures informed stakeholder engagement in those jurisdictions at the Board level.
A22 IFRS Accounting Standards derive their legitimacy from widespread adoption across global capital markets. It is essential that the Board retains sufficient representation from those jurisdictions where the standards have the greatest economic significance and practical impact.
A23 In our view, geographical allocation should not be viewed solely through the lens of regional diversity. It should also reflect:
- the jurisdictions that have made the greatest commitment to IFRS Accounting Standards through adoption, implementation, funding and ongoing participation in the standard-setting process; and
- the globally systemic capital markets that use IFRS Accounting Standards to enable significant flows of capital around the world.
A24 A governance structure that weakens the voice of those jurisdictions and capital markets risks weakening their long-term support for international standards.
A25 The proposed reduction from four members to two members from Europe, Asia-Oceania and the Americas appears inconsistent with the economic reality of global IFRS adoption. The majority of listed companies applying IFRS Accounting Standards, the largest pools of capital operating under those standards, and a substantial proportion of the IFRS Foundation’s funding, are concentrated within those regions. We, therefore, question whether a Board structure that allocates only two members to each of those regions provides sufficient capacity to reflect the breadth and complexity of the issues arising across those markets.4
A26 We consider that participation from Africa and other emerging economies remains relevant as consideration and inclusion of their perspectives ensure the status of IFRS as globally applicable standards is retained. However, this objective should not be achieved by significantly reducing representation from the largest IFRS capital markets.
A27 We urge the IFRS Foundation to retain consistent and appropriate jurisdictional representation.
Jurisdictional participation across two boards
A28 The suggestion in the Invitation to Comment on the proposed amendments (page 7) that jurisdictional participation can be considered across the IASB and ISSB, collectively, is surprising. This assertion has not been explained, and we do not believe this is a credible basis on which to assess representation.
A29 The two Boards have fundamentally different mandates and address different issues, requiring different expertise, perspectives and stakeholder engagement activities. Representation on one Board does not provide meaningful participation in the technical decisions of the other. This is particularly important given the breadth and significance of the IASB's remit and the widespread use of IFRS Accounting Standards worldwide.
A30 In our view, jurisdictional participation needs to be considered separately for each Board, with the composition of the IASB reflecting the jurisdictions and capital markets that rely on IFRS Accounting Standards, rather than being assessed across the Foundation’s governance structure as a whole.
Input from consultative and advisory groups
A31 We do not agree with the suggestion that jurisdictional participation can be adequately replaced through consultative bodies, advisory groups or other forums.
- Firstly, those bodies do not possess the decision-making authority of the IASB.
- Secondly, recent changes to some consultative mechanisms have reduced the weighting historically afforded to larger capital markets.
- Thirdly, the views expressed by advisory bodies, which (with the exception of ASAF) often include individuals providing views on an individual basis, cannot substitute for participation in Board deliberations and voting.
A32 Consequently, we are not persuaded by the suggestion in the ED that reduced jurisdictional participation on the IASB can be compensated for through ASAF and other consultative bodies. The breadth of inputs to decision-making cannot substitute for the breadth of understanding of the decision-makers themselves.
Increased use of at-large appointments
A33 We support the Trustees’ proposal to formalise the recent practice of designating the Chair as one of the ‘at-large’ members. We agree that appointing the Chair from the ‘at-large’ group will ensure they maintain their independence and are not seen as favouring a particular jurisdiction or geographical region.
A34 However, we are not convinced that the proposal to increase the overall number of at-large appointments will achieve the flexibility envisaged by the Trustees.
A35 The Constitution currently establishes a clear link between Board composition and geographical participation. The proposed amendments weaken that link and replace it with significantly greater discretion, with no clarity over how that discretion might be exercised and any guardrails that might be in place.
A36 Although the ED states that overall geographical balance will be maintained, “geographical balance” is inherently less precise than the current geographical allocation requirements.
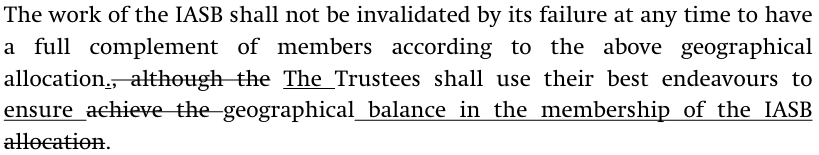
"The work of the IASB shall not be invalidated by its failure at any time to have a full complement of members according to the above geographical allocation., although the The Trustees shall use their best endeavours to ensure achieve the geographical balance balance in the membership of the IASB allocation."
A37 The proposed framework might permit scenarios in which a disproportionate number of members came from a limited number of jurisdictions or regions while still being regarded as broadly balanced.
A38 We believe the Constitution should continue to prioritise geographical allocation rather than significantly expanding the number of at-large appointments.
A39 One possible alternative would be:
- three members from Asia-Oceania;
- three members from Europe;
- three members from the Americas;
- one member from Africa; and
- two to four at-large members (including the Chair),
resulting in a minimum of a 12-member Board, with stronger geographical representation.
Significant capital market representation
A40 The UK, one of the largest and most internationally significant capital markets applying IFRS Accounting Standards, has always been supportive of the IFRS Foundation and the IASB.
A41 The Constitution should ensure that any future geographical model properly reflects the importance of major IFRS jurisdictions and capital markets, such as the UK, being appropriately reflected in the geographical representation of the IASB.
Question 2—Attributes of Board members
Do you agree with the Trustees’ decision to propose no changes in the Constitution:
(a) to the main provisions relating to part-time board membership; and
(b) to the main qualifications for membership of the boards?If not, why not, and what would you propose instead and why?
Part-time IASB members
A42 We do not support retaining the existing provision allowing up to three part-time IASB members without further safeguards.
A43 A Board of 8–12 members, with up to three part-time members, could have a significant proportion of its membership unable to devote full attention to technical and stakeholder responsibilities.
A44 The Trustees state that the reduction in Board size can be accommodated through changes in how the Boards undertake their work. We are concerned that, in practice, stakeholder engagement may be the activity most likely to be reduced.
A45 The development of high-quality standards requires both technical analysis and extensive stakeholder engagement. It should not be assumed that the latter can be scaled back without consequences.
A46 Part-time Board members should be a rare exception. The limit on part-time members must be proportionate to the size of the Board. At the lower level proposed in this ED, the limit should be one part-time member.
Qualifications for membership of Boards
A47 We agree that the existing qualification criteria remain appropriate. However, we do not share the Trustees’ confidence that a smaller Board can consistently maintain the same breadth of skills, professional backgrounds and perspectives that have historically contributed to the quality and credibility of IFRS Accounting Standards.
A48 In practice, reducing the size of the IASB inevitably increases the risk that important stakeholder groups, professional backgrounds or forms of expertise are not represented at the Board table at particular points in time. While Board members are expected to consider a wide range of views, direct participation from individuals with different professional experiences remains an important component of robust technical debate.
A49 Recent Board composition illustrates this concern; for example, the IASB currently lacks academic representation. Academic members have historically made valuable contributions by bringing independent research perspectives, conceptual rigour and long-term thinking to Board deliberations.
A50 Academic presence has often strengthened the quality of technical analysis and challenge. A smaller Board increases the likelihood that important perspectives of this nature are lost altogether rather than simply becoming less prominent.
A51 More generally, with any less than 12 members, it becomes increasingly difficult to achieve an appropriate balance across multiple dimensions simultaneously, including geographical diversity, investor and preparer perspectives, regulatory experience, auditing expertise, standard-setting experience and academic insight. The proposed reduction in Board size creates a greater risk that individual vacancies or appointment decisions could materially affect the overall balance of the Board in a way that would be less significant on a larger Board.
Question 3—Voting arrangements
Do you agree with how the Trustees propose to update the voting requirements in the Constitution to facilitate effective decision-making for the smaller boards? If not, why not, and what would you propose instead and why?
A52 We do not support the proposed voting requirements, particularly as it would be operationalised with a smaller Board. The publication of IFRS Accounting Standards should continue to require a stronger level of consensus than a simple majority plus one additional vote.
A53 The existing voting arrangements have played an important role in demonstrating that issued Standards command broad support amongst Board members, following extensive due process and stakeholder consultation. International adoption is facilitated when jurisdictions can see that a Standard has obtained substantial support from the Board.
A54 For example, the proposed arrangements would permit publication of a Standard by six votes on an 8-member Board (see Table below for details). In our view, standards carrying global authority should not be capable of approval by, effectively, a narrow majority of a significantly reduced Board.
Proposed voting requirements
| Number of members | Successful vote | Blocking minority |
|---|---|---|
| 8 | 6 (75%) | 3 |
| 9 | 6 (66.7%) | 4 |
| 10 | 7 (70%) | 4 |
| 11 | 7 (63.6%) | 5 |
| 12 | 8 (66.7%) | 5 |
Internal inconsistency and lack of clarity
A55 We also note several drafting issues requiring clarification:
- the relationship between the proposed “simple majority plus one” voting model and the Chair’s casting vote is unclear;
- the reference to decisions requiring a “simple majority” appears inconsistent with the voting requirements for Standards and Exposure Drafts;
- differing references to members “in office”, rather than “appointed members” and members “present at a meeting” require further explanation; and
- the Constitution should clarify the quorum applicable when approving Standards and Exposure Drafts.
Question 4—Other targeted amendments
Do you agree with the other proposed targeted amendments to the Constitution?
Section 25A
A56 We are concerned that the proposed wording no longer includes the requirement that the Trustees “use their best endeavours to achieve a full complement of members”.
A57 That requirement should be retained. Removing it weakens accountability and may reduce the urgency attached to filling Board vacancies.
Board member terms
A58 The proposed amendments provide greater flexibility over appointment lengths and renewals.
A59 Whilst flexibility may be helpful, additional transparency is required regarding the factors to be considered when extending or not extending a member’s term.
A60 Greater clarity would strengthen confidence in the appointment process and the independence of Board members.
Managing Executive Director
A61 We support efforts to clarify governance structures but believe further clarification is needed regarding reporting lines and responsibilities.
A62 In particular, it should be clear:
- whether staff report operationally to the Managing Executive Director or to the IASB and ISSB Chairs;
- how independence of the technical staff’s advice to the two Board and their subsequent decision making will be protected; and
- whether Board members are accountable to the Board Chairs, the Trustees or both.
Trustees and accountability
A63 We are concerned that some of the proposals may open the Trustees to unnecessary conflicts of interests (see comments in paragraphs A16-A18 above).
A64 The proposals result in a significant transfer of discretion from the Constitution to the Trustees. The Constitution has historically provided important safeguards because changes to it require formal public consultation.
A65 The proposed amendments would significantly increase the discretion of the Trustees in relation to future decisions regarding Board size and composition. However, we note that there is no clear indication of why the Trustees need these additional powers, nor of the constraints within which this new discretion will be exercised. In addition, some explanation is required of what key performance indicators will be used to measure success and how the Memorandum of Understanding between the Trustees and the Monitoring Board will be amended to enable this review by the Monitoring Board.
A66 We appreciate that considering changes to governance and to the remit of the Trustees will be challenging. We therefore urge the Trustees to start this process by clearly explaining:
- what the problems are with the current structure that necessitate delegation of these additional powers to them, and how they intend to use them;
- to whom the Trustees are ultimately accountable;
- how their performance is evaluated; and
- what measures are used to assess whether they are successfully discharging their responsibilities.
Conclusion
A67 We support the Trustees’ objective of ensuring the long-term sustainability of the IFRS Foundation. However, we believe the proposed amendments relating to the IASB risk weakening the governance arrangements that have underpinned the success and acceptance of IFRS Accounting Standards.
A68 The combined effect of reducing Board size, weakening geographical allocation requirements, increasing the number of at-large appointments and lowering the effective consensus required for publication of Standards could risk undermining stakeholder confidence in the legitimacy of IFRS Accounting Standards and, over time, weaken support for their global adoption and use.
A69 We urge the Trustees to enhance these proposals and to retain a governance framework that continues to command confidence amongst the jurisdictions, capital markets and stakeholders that rely upon IFRS Accounting Standards.
Appendix C: Invitation to Comment
Call for comments on the: Exposure Draft Proposed Targeted Amendments to IFRS Foundation Constitution
Deadline for completion of this Invitation to Comment:
Close of business, XX October 2026Please submit to:
[email protected]
Introduction
The objective of this Invitation to Comment is to obtain input from stakeholders on the UKEB’s Draft Comment Letter on the Exposure Draft (ED) Proposed Targeted Amendments to IFRS Foundation Constitution. The ED was published by the IFRS Foundation Trustees on 18 August 2026. The Trustees’ comment period ends on 16 November 2026.
UK endorsement and adoption process
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and is, therefore, the UK’s National Standard Setter for IFRS. The UKEB also leads the UK’s engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations.
Who should respond to this Invitation to Comment?
Stakeholders with an interest in the quality of accounts prepared in accordance with IFRS Accounting Standards.
How to respond to this Invitation to Comment
Please download this document, answer any questions on which you would like to provide views, and return it with the ‘Your Details’ form to [email protected] by close of business on XX October 2026.
Brief responses to individual questions are welcome, as well as comprehensive responses to all questions.
Privacy and other policies
The data collected, through submitting this document, will be stored and processed by the UKEB. By submitting this document, you consent to the UKEB processing your data for the purposes of influencing the development of and adopting IFRS for use in the UK. For further information, please see our Privacy Statements and Notices and other Policies (e.g. Consultation Responses Policy and Data Protection Policy).5
The UKEB’s policy is to publish on its website all responses to formal consultations issued by the UKEB unless the respondent explicitly requests otherwise. A standard confidentiality statement in an e-mail message will not be regarded as a request for non-disclosure. If you do not wish your signature to be published, please provide the UKEB with an unsigned version of your submission. The UKEB prefers to publish responses that do not include a personal signature. Other than the name of the organisation/individual responding, information contained in the “Your Details” document will not be published. The UKEB does not edit personal information (such as telephone numbers, postal or e-mail addresses) from any other response document submitted; therefore, only information that you wish to be published should be submitted in such responses.
Your details
- Name: ____________________________
- Email address: ____________________________
- Are you responding:
- On behalf of an organisation [ ]
- As an individual [ ]
- If responding on behalf of an organisation, Name of organisation: ____________________________
- Please select what best describes the organisation:
- An organisation applying IFRS Accounting Standards [ ]
- A user of company accounts prepared under IFRS [ ]
- An accounting firm / auditor [ ]
- A regulator [ ]
- Other [ ]
- If your response was ‘Other’, please describe: ____________________________
- Is your organisation a listed entity?
- UK listed [ ]
- UK AIM listed [ ]
- Other listed [ ]
- Unlisted [ ]
- Would you be happy for UKEB to contact you if needed to discuss your responses?
- Yes [ ]
- No [ ]
Questions
Board size and geographical allocation of board members
-
The UKEB DCL proposes that the Trustees retain a normal minimum size of 12 IASB members. It does not support the proposal to introduce a range for board membership of between 8 and 12 members. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 1.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
The UKEB’s DCL does not support the ED proposal to amend the geographical allocation of members. The UKEB DCL proposes that the Trustees preserve stronger geographical representation requirements linked to jurisdictions and capital markets that adopt IFRS Accounting Standards. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 2.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
The UKEB DCL does not support the proposed substantial increase in the number of at-large appointments. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 3.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
Do you have any other comments on the UKEB’s DCL in relation, or the ED proposals, in relation to board size and geographical allocation of members?
Click or tap here to enter text.
Attributes of Board members
-
The UKEB DCL raises certain concerns with the ED proposals relating to the attributes of Board members in paragraphs A42 - A51 of the Appendix to the DCL. These include the proposed number of part-time members and the ability for a smaller board to maintain an appropriate balance of skills, professional backgrounds and perspectives. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 5.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
Do you have any other comments on the ED proposals in relation to attributes of Board members?
Click or tap here to enter text.
Voting arrangements
-
The UKEB DCL proposes that the Trustees should retain a super majority style voting threshold for publication of Exposure Drafts and Standards. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 7.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
Do you have any other comments on the ED proposals in relation to voting arrangements?
Click or tap here to enter text.
Other targeted amendments
-
The UKEB DCL recommends the IFRS Trustees enhance transparency regarding how future Board sizes will be determined, retain stronger constitutional safeguards rather than transferring significant discretion to the Trustees, and clarify governance, accountability and reporting arrangements. Do you agree with the position in the DCL? If not, please give the rationale for your answer to question 9.
- Yes [ ] No [ ]
Click or tap here to enter text.
-
Do you have any other comments on the ED proposals for other targeted amendments?
Click or tap here to enter text.
Other comments
-
Do you have any other comments on the UKEB’s Draft Comment Letter?
Click or tap here to enter text.
Response generation
-
Did you/your organisation use a large language model (e.g. ChatGPT, Microsoft Copilot) to create any part of your/its response (response to this Invitation to Comment or a comment letter you are submitting as part of your response)?
- Yes [ ] No [ ]
If you answered yes to Question 12, please specify which model and what prompt(s) you used for the large language model.
Click or tap here to enter text.
Thank you for completing this Invitation to Comment
Please submit this document by close of business on XX October 2026 to:
[email protected]
Footnotes
Footnotes
-
The UKEB Advisory Groups scheduled during the period between the September 2026 and October 2026 Board meetings are the Financial Instruments Advisory Group (FIAG) and the Preparer Advisory Group (PAG). ↩
-
UKEB calculation based on London Stock Exchange Group (LSEG) and Eikon data, November 2025. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩
-
The UK is home to one of the world's largest capital markets. For example, companies listed on the London Stock Exchange had a combined market capitalisation exceeding £3.2 trillion in 2025, making London one of the most significant financial centres globally and one of the largest markets reporting under IFRS Accounting Standards. All UK entities with securities listed on a UK regulated market must prepare their consolidated financial statements using UK-adopted IFRS Accounting Standards. London's market serves both domestic and international issuers and investors, meaning that IFRS Accounting Standards play a critical role in the efficient functioning of global capital markets operating through the UK. ↩
-
These policies can be accessed from the footer in the UKEB website: https://www.endorsement-board.uk ↩