5 Intangible Assets
16 July 2026 Agenda Paper 5
Executive Summary
Project Stage
| Stage | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing / UKEB Post Implementation Review |
Project Type: Research Project
Project Scope: Significant
Purpose of the paper
This paper:
- summarises the key additional findings arising from the May and June 2026 workshops and highlights areas where stakeholder views have evolved or been further refined since the May 2026 Board paper;
- updates and further develops the cross-cutting themes and overarching questions arising from the case studies in light of the additional outreach findings; and
- sets out a draft of the Intangibles Research Report (see Appendix A). The report presents the cross-cutting themes and overarching questions arising from the four case studies. Appendix B contains a detailed summary of stakeholder feedback for each case study.
Summary of the outreach findings
The UKEB's Intangible Assets Research Project combines *top-down
- and bottom-up research approaches, as set out in the Project Initiation Plan approved in October 2025, to address longstanding challenges in accounting for intangible items. This paper forms part of the project's bottom-up research programme and builds on the preliminary findings presented to the Board in May 2026.
The additional outreach broadly reinforced the themes identified in the May 2026 paper. Rather than introducing fundamentally new issues, participants provided further evidence and examples that strengthened and refined the preliminary observations, while also helping to further develop the overarching questions arising from the outreach.
The draft Intangibles Research Report at Appendix A presents the cross-cutting themes and overarching questions arising from the four case studies. Appendix B contains a detailed summary of stakeholder feedback for each case study.
Together, the cross-cutting themes and overarching questions highlight recurring challenges relating the definition of an asset, the role of the business model, control, unit of account, recognition and value creation, uncertainty, expensing versus the recognition of future economic benefits, measurement, recognition versus disclosure, and comparability between acquired and internally generated resources. These themes arose consistently across the case studies, despite the different fact patterns considered.
Decisions for the Board
- Do Board Members have comments on the cross-cutting themes and overarching questions presented in paragraphs A28–A69 of Appendix A of this paper?
- Do Board members agree with the Secretariat’s view that Appendix B should not be published as part of the Intangibles Research Report?
- Subject to any comments at this meeting, does the Board support publication of the final research report?
Recommendation
N/A
Appendices
Appendix A: Intangibles Research Report (Case Study findings)
Appendix B: Detailed summary of stakeholder feedback
Objective
1 Since September 2025, the Secretariat has conducted a series of workshops to explore stakeholder views on four case studies developed as part of the UKEB's Intangibles Research Project:
- Training costs.
- Research and development costs (R&D).
- Carbon credits.
- Data‑focused case study.
2 Following the Board’s May 2026 discussion1, the Secretariat conducted four additional workshops in late May and early June 2026 involving 51 participants from a broad mix of stakeholders, including preparers, users, accounting firms, professional accountancy bodies and academia. IASB staff observed these discussions.
3 The workshops were designed to test the preliminary findings presented to the Board in May 2026, exploring topics raised in more detail, and identify any additional considerations relevant to the accounting for intangible resources.
4 The additional outreach largely reinforced the preliminary findings while providing greater depth and nuance in several areas. Across all four case studies, stakeholders raised questions about asset identification, value creation, control, the role of the business model, unit of account, uncertainty and measurement, as well as the appropriate balance between recognition and disclosure and the comparability of outcomes for acquired and internally generated resources.
5 The workshops were exploratory and were not intended to identify the "right" accounting outcome for the fact patterns presented. Instead, discussions focused on the underlying economics of the arrangements and their implications for recognition, measurement and disclosure.
Additional workshops
6 The additional workshops provided further evidence supporting the themes identified in the earlier outreach. Rather than introducing fundamentally new issues, participants elaborated on existing themes and helped clarify the areas that continue to present challenges in practice.
7 Three broad messages emerged from the additional discussions:
- participants increasingly focused on identifying the relevant asset before considering recognition and measurement questions;
- recurring challenges were identified in applying existing recognition and measurement requirements to resources whose value is created collectively, develops over time and remains subject to uncertainty. Participants also increasingly questioned whether value creation can always be attributed to a single asset, project or contract. Across several case studies, value was described as arising from combinations of resources, capabilities, knowledge and activities, raising questions about asset identification, unit of account and the application of existing recognition and measurement requirements; and
- while participants generally supported enhanced disclosures, discussions frequently returned to underlying recognition and measurement questions, suggesting that disclosure was often viewed as a complement to, rather than a complete substitute for, recognition and measurement.
| Case study | Key additional findings from the May/June 2026 workshops |
|---|---|
| Training costs | - Greater emphasis emerged on the distinction between contract-specific training linked to an enforceable contract and general workforce training. Some participants view the specific training as necessary to generate the related contract revenue and general training as a “licence to operate”. - Additional discussion focused on: whether a workforce can be controlled collectively; whether IFRS 15 Revenue from Contracts with Customers fulfilment cost accounting reflects a genuine asset or a cost deferral mechanism; and whether the relevant unit of account should be a contract or, in some circumstances, a portfolio of similar contracts. |
| Research and development | - Participants increasingly highlighted that value may arise from knowledge and learning generated across an R&D programme, including from projects that do not ultimately succeed. - Additional discussion focused on: whether future economic benefits may become sufficiently evident before regulatory approval; whether capitalisation could improve governance and accountability; and the tension between portfolio-level economics and project-level accounting. |
| Carbon credits | - Greater emphasis was placed on the role of policy, market demand and the ability to monetise credits in assessing future economic benefits. - Additional discussion focused on the treatment of Pending Issuance Units (PIUs)2, and concerns about delayed revenue recognition. Some participants suggest that the lengthy gap between upfront investment, receipt of cash and recognition of revenue may affect the attractiveness of carbon-credit projects. Participants also highlighted measurement issues relating to cost recoverability, market liquidity and pricing differences between credit types. |
| Data | - Participants devoted significant attention to identifying the relevant asset, including whether value resides in the data itself, processed outputs, transformation capabilities or a combination of these elements. - Additional discussion focused on: assessing control where data is shared or accessed through contractual arrangements; determining the appropriate unit of account; and understanding why internally generated data-related resources face greater recognition and measurement hurdles than comparable assets recognised in business combinations. |
Cross-cutting themes and overarching questions arising from the feedback
8 The Board previously considered preliminary versions of the cross-cutting themes and overarching questions at its May 2026 meeting. The additional outreach broadly reinforced the themes identified in the May 2026 paper. Rather than introducing fundamentally new issues, participants provided further evidence and examples that strengthened and refined the preliminary observations. The feedback also helped further develop the overarching questions arising from the outreach.
9 In the Intangibles Research Report included in Appendix A to this paper, the cross-cutting themes and overarching questions are presented as separate sections. This distinguishes the recurring themes identified across the case studies from the broader questions arising from those themes.
10 The Intangibles Research Report in Appendix A to this paper includes:
- The discussion of the cross-cutting themes arising from the outreach in paragraphs A28–A66; and
- The overarching questions arising from the feedback in paragraphs A67–A69.
11 The detailed findings for each case study are set out in Appendix B. These findings bring together feedback from all outreach activities undertaken as part of the project, including the additional workshops held in May and June 2026. The Secretariat does not propose including these findings as part of the published report. However, the findings are expected to be useful in the next phase of the project, where we plan to assess broader financial reporting issues relating to intangible resources and how they interact with existing accounting requirements.
12 Both Appendices have been updated to reflect the additional feedback received through the May and June 2026 workshops. To assist Board members in identifying changes since the Board's previous discussion, new content and significant revisions have been shaded in grey in the Intangibles Research Report. This formatting has been included solely for the Board's convenience and will not be retained in the final published version of the report.
Question for the Board
- Do Board Members have comments on the cross-cutting themes and overarching questions presented in paragraphs A28–A69 of Appendix A of this paper?
- Do Board members agree with the Secretariat’s view that Appendix B should not be published as part of the Intangibles Research Report?
- Subject to any comments at this meeting, does the Board support publication of the final research report?
Next steps
13 The case study phase represents the principal bottom-up component of the UKEB's Intangibles Research Project and is now substantially complete. The Intangibles Research Report, will be used to inform future engagement with the IASB and the next phase of the research.
14 Subject to Board feedback, the Secretariat proposes to publish Appendix A as a final research report on the case study programme and stakeholder outreach.
15 The next phase of work will focus on the top-down component of the UKEB's Intangibles Research Project. Using the evidence gathered through the case studies and stakeholder outreach, along with desk-based research, the Secretariat will consider the broader financial reporting issues relating to intangible resources. It will also assess how the findings interact with existing accounting requirements, the IASB’s Conceptual Framework and other standard-setting developments.
16 The Secretariat plans to bring a Project Initiation Plan to a future Board meeting, setting out the proposed scope, objectives and approach for the top-down phase of the project. The Secretariat will also consider how the themes and questions identified through the outreach point to broader principles that could help inform future discussions on the recognition, measurement and disclosure of intangible items for this phase of the project.
Project timeline
17 The high-level project timeline is shown below.
| Date | Milestones |
|---|---|
| October 2025 | Project Initiation Plan for Board approval |
| Q4 2025 | Develop and refine case studies |
| Q1–Q2 2026 | Stakeholder engagement and case study testing |
| May 2026 | Preliminary stakeholder feedback from case studies |
| July 2026 | Research report and final stakeholder feedback presented to the Board (this meeting) |
Appendix A: Intangibles Research Report (Case Study findings)
Board notes: (not for inclusion in the final report):
This Appendix contains the proposed Intangibles Research Report.
The Board has not previously considered the Intangibles Research Report in its current form. However, the Board considered preliminary versions of the cross-cutting themes and the overarching questions included as part of this report at its May 2026 meeting.
To assist Board members in identifying revisions arising from the additional workshops conducted in May and June 2026, as well as other substantive additions and refinements made since the Board's previous discussion, new content and significant revisions have been shaded in grey throughout these sections. This formatting has been included solely for the Board's convenience and will not be retained in the final published version of the report.
Executive summary
A1 This report presents the findings from the UKEB's case study-based research programme on intangible items. Through four case studies covering training costs, research and development (R&D), carbon credits and data, the project explored stakeholder views on the economics of intangible items and the related accounting challenges.
A2 Although the case studies addressed different types of intangible items, participants frequently returned to similar issues when discussing the underlying economics and the resulting accounting outcomes.
A3 Across all four case studies, stakeholders raised questions about asset identification, value creation, control, the role of the business model, unit of account, uncertainty and measurement, as well as the appropriate balance between recognition and disclosure and the comparability of outcomes for acquired and internally generated resources.
A4 Taken together, the feedback highlighted a recurring tension between the economics of investments in intangible items and how those investments are reflected in financial statements. Across the case studies, participants described activities that often require significant upfront investment, generate benefits over time and involve varying degrees of uncertainty.
A5 Participants also highlighted difficulties applying existing accounting requirements where value develops over time, is created through combinations of resources, capabilities and activities, or remains uncertain. Many discussions emphasised the importance of understanding an entity's business model and how it generates future economic benefits before assessing accounting outcomes.
A6 While there was strong support for enhanced disclosures, participants frequently questioned whether disclosures alone can address concerns about recognition, measurement and comparability, particularly where economically significant resources remain unrecognised or where similar resources receive different accounting outcomes depending on whether they are acquired or developed internally.
A7 These observations gave rise to broader questions about whether existing accounting requirements appropriately reflect the economics of intangible resources. Stakeholders questioned how accounting should identify and reflect assets whose value develops over time, is generated through combinations of resources and activities, or remains subject to uncertainty.
A8 The fact that similar questions arose across all four case studies suggests that they are not limited to particular transactions or fact patterns. Rather, they point to broader financial reporting challenges associated with intangible resources and modern sources of value creation.
A9 The insights from this report will be used to inform the next phase of the UKEB's Intangibles Research Project. This will consider the broader financial reporting implications of these findings and their interaction with existing accounting requirements, the IASB's Conceptual Framework and other standard-setting developments.
Introduction
Background and objective
A10 The UKEB's Intangibles Research Project builds on the UKEB's previous work on intangibles, which focused on the qualitative assessment and quantitative analysis of intangible reporting in the UK. The project also complements the IASB's work by seeking to understand what information about recognised and unrecognised intangible assets, including expenditure associated with them, users would find useful, while also considering preparers' views on that information.
A11 As set out in the Project Initiation Plan (PIP)3 for the Intangibles Research project, approved by the Board in October 2025, the project adopts both a top-down4 and a bottom-up approach to research. The insights gathered through this work are intended to help influence and test future IASB proposals on accounting for intangibles, including proposals relating to recognition, measurement and disclosure, and to identify broader principles that may be relevant to the accounting for intangible items.
A12 The bottom-up approach uses case studies to explore stakeholder views on the economics of intangible items and related accounting issues. This approach helps ensure the project is based on practical evidence from a range of informed stakeholders by using case studies to explore their perspectives on the economics of intangible items and related accounting issues.
A13 This report presents the findings from the project's bottom-up research programme. It begins by providing an overview of the development of the case studies, the outreach activities undertaken and the purpose of the stakeholder workshops. It then discusses the cross-cutting themes and overarching questions that emerged from the feedback across the four case studies before presenting a consolidated summary of the stakeholder feedback by case study.
A14 Together, these themes and findings provide insights into the accounting challenges identified by stakeholders.
Development of the case studies
A15 The case studies were developed to facilitate discussion with stakeholders on accounting issues associated with different types of intangible items.
A16 The topics for the case studies were identified through the UKEB's earlier intangibles research, discussions with stakeholders and consideration of relevant IFRS Interpretations Committee discussions.
A17 Following their identification, the Secretariat developed three case studies during late 2025 in consultation with members of the UKEB's advisory groups5 and informed by feedback received from the Board at its June 2025 meeting6. These case studies were approved by the Board in January 20267. At the same meeting, the Board supported the Secretariat's proposal to develop an additional data‑focused case study. The resulting four case studies formed the basis for the outreach discussed in this report.
A18 The four case studies were designed to highlight different economic characteristics and accounting challenges associated with intangible items and to stimulate discussion on questions relating to underlying economics, recognition, measurement and disclosure. The case studies focused on:
- Training costs – exploring accounting issues arising from training expenditure incurred to fulfil a customer contract.
- Research and development (R&D) costs – exploring the accounting for significant development expenditure incurred in the creation of a pharmaceutical product.
- Carbon credits – exploring accounting issues arising across the carbon‑credit value chain, including generation, trading, investment and use.
- Data – exploring the accounting implications of expenditure incurred to build and maintain a data resource that is central to an entity's business model.
A19 Further details of the case studies are provided in Appendix A8.
Outreach activities
A20 Between September 2025 and June 2026, the Secretariat conducted a series of workshops to explore stakeholder views on the four case studies. Participants included preparers and users of financial statements, accounting firms, professional accountancy bodies and academics.
A21 Initial outreach was conducted through workshops with a range of stakeholders, including the UKEB Academic Advisory Group (AAG), the UKEB Preparer Advisory Group (PAG), the UKEB Investor Advisory Group (IAG), the Corporate Reporting Users Forum (CRUF), CFA UK and the UK branch of the Chartered Accountants Australia and New Zealand (CAANZ). These workshops involved almost 100 participants.
A22 Four additional workshops (one for each case study) took place in late May and early June 2026, involving a further 51 participants. IASB staff observed some of these discussions.
Purpose of the workshops
A23 The workshops were exploratory and were not intended to identify the "right" accounting outcome for the fact patterns presented. Instead, discussions focused on the underlying economics of the arrangements and their implications for recognition, measurement and disclosure.
A24 The additional workshops helped test and further develop the preliminary findings presented to the Board in May 2026, explore topics raised during the earlier outreach in greater detail, and identify any additional considerations relevant to the accounting for intangible items.
A25 The Secretariat analysed the feedback identifying common themes, areas of divergence and recurring issues within and across the case studies. Given the qualitative nature of the outreach, and because not all case studies were discussed at every workshop, the analysis does not seek to quantify stakeholder views or assess the prevalence of particular opinions. Rather, it provides a summary of the views expressed and the key observations arising from the discussions.
Structure of the report
A26 The report is structured in two parts:
- First, it discusses the cross-cutting themes and overarching questions that emerged across the four case studies.
- Second, it presents a consolidated summary of the stakeholder feedback by case study.
A27 The cross-cutting themes identified from the outreach highlight several recurring questions that arose across the four case studies. The following section discusses these themes and questions before presenting the detailed feedback by case study.
Cross-cutting themes and overarching questions arising from the feedback
A28 Although the case studies addressed different types of intangible items, participants frequently returned to similar issues when discussing the underlying economics and the resulting accounting outcomes.
A29 Taken together, the feedback highlights a recurring tension between the economic substance of investments in intangible items and their treatment under existing accounting requirements. Across training costs, R&D, carbon credits and data, participants described activities that often require significant upfront investment, are expected to generate future economic benefits over time and involve varying degrees of uncertainty.
A30 The analysis below first considers the cross-cutting themes that emerged across the case studies and then discusses the broader questions arising from those themes.
Cross-cutting themes
A31 Across all four case studies, participants repeatedly returned to a common set of issues. The consistency with which these themes arose across the discussions suggests that they are not unique to any particular fact pattern but may reflect broader challenges associated with accounting for intangible items and modern sources of value creation.
Definition of an asset
A32 Across the case studies, stakeholders frequently debated the nature of the underlying asset trying to prise apart the set of rights or potential future benefits that may give rise to that asset. In the training case study, discussions focused on whether value resides in the workforce, the contract fulfilment capability or the related contract benefits. In the data case study, participants questioned whether value resides in raw data, processed outputs, transformation capabilities or combinations of these elements. Similar questions arose in the R&D and carbon‑credit case studies.
A33 Several participants observed that these discussions point to a more fundamental question concerning the identification of the relevant asset. In this context, some participants referred to the IASB’s 2018 Conceptual Framework's definition of an asset and noted that its focus on a present economic resource with the potential to produce economic benefits may support a broader consideration of what constitutes an asset, even where the timing or outcome of those benefits remains uncertain. As one participant observed, debates about recognition and measurement should not detract from the more fundamental question of “whether an asset even exists in the first place”.
A34 These observations suggest that many recognition and measurement challenges originate from more fundamental questions about the definition of the underlying asset.
Role of the business model
A35 Across several case studies, participants emphasised the importance of understanding how an entity generates value and future economic benefits before assessing recognition and measurement outcomes. The feedback indicated strong support for an approach that reflects how intangible resources are used within an entity's business model. Participants frequently observed that understanding whether a resource is held for use in operations, sale, trading or longer-term value appreciation is fundamental to understanding its economic role and, potentially, its accounting treatment.
A36 This theme was particularly evident in the carbon-credit case study, where discussions frequently focused on how different participants in the market—including project developers, brokers, investors and end users—derive value from credits. Participants often reached different views on recognition and measurement depending on how the credits were used within the business model. Similar comments arose in the data case study, where participants emphasised that evaluating whether an asset exists requires an understanding of how data contributes to an entity's products, services and revenue generation.
A37 Similar comments arose in the R&D case study, where some participants suggested that recognition depends not only on development progress but also on how an entity expects to generate value from the underlying resource. As one participant observed: “First, we’ve got to have a business model… and then maybe I can say that it may be worth something.” As one other participant explained: “It depends on your intention. Are you developing it to sell to somebody, or are you taking it to market yourself?”.
A38 These observations suggest that questions relating to asset identification, recognition and measurement cannot always be considered in isolation from the business model through which future economic benefits are generated. More broadly, the feedback suggests that stakeholders often viewed the business model as a key factor in understanding the economics of intangible resources and assessing how accounting outcomes should reflect those economics.
Control
A39 Questions of control arose consistently across the case studies. Participants debated whether a workforce can be controlled collectively, whether traditional notions of control remain appropriate for data that can be used simultaneously by multiple parties and whether contractual, licensing or regulatory rights may provide sufficient control even where legal ownership is absent.
A40 In discussing control, one participant challenged the focus on individual employees, observing that “You don't control individuals, but you control your workforce”. Similar questions arose in the data case study, where one participant questioned whether control is lost simply because others can also use the resource, asking: “Does it actually matter if someone else is using it?… As long as there is an agreement.”
A41 These discussions suggest that stakeholder views on recognition frequently depended on how control is interpreted, particularly where value arises from resources that are shared, contractually accessed or embodied in people rather than legally owned assets.
Unit of account
A42 Questions regarding the appropriate unit of account also arose across the case studies. Participants observed that conclusions regarding recognition, measurement and impairment often depended on how the relevant asset was defined and whether it should be assessed at the level of an individual item, contract, project, capability or broader portfolio of activities.
A43 In the training case study, many participants favoured a contract-level assessment because this reflected how contract performance is managed and analysed in practice. In the R&D case study, several participants supported a portfolio perspective, noting that knowledge, capabilities and scientific discoveries are often shared across projects and that investors frequently assess the prospects of an overall development pipeline rather than individual projects.
A44 Similar questions arose in the data case study, where participants debated whether value resides in the raw data, the output produced from the data, the transformation process or a combination of these elements. These discussions suggest that identifying the appropriate unit of account remains a significant challenge where value is generated through combinations of resources, capabilities and activities.
Recognition and value creation
A45 Across the outreach, participants highlighted difficulties in applying existing recognition requirements where value develops over time, depends on uncertain outcomes or is generated collectively across multiple activities. Several
Control
A39 Questions of control arose consistently across the case studies. Participants debated whether a workforce can be controlled collectively, whether traditional notions of control remain appropriate for data that can be used simultaneously by multiple parties and whether contractual, licensing or regulatory rights may provide sufficient control even where legal ownership is absent.
A40 In discussing control, one participant challenged the focus on individual employees, observing that "You don't control individuals, but you control your workforce". Similar questions arose in the data case study, where one participant questioned whether control is lost simply because others can also use the resource, asking: "Does it actually matter if someone else is using it?… As long as there is an agreement."
A41 These discussions suggest that stakeholder views on recognition frequently depended on how control is interpreted, particularly where value arises from resources that are shared, contractually accessed or embodied in people rather than legally owned assets.
Unit of account
A42 Questions regarding the appropriate unit of account also arose across the case studies. Participants observed that conclusions regarding recognition, measurement and impairment often depended on how the relevant asset was defined and whether it should be assessed at the level of an individual item, contract, project, capability or broader portfolio of activities.
A43 In the training case study, many participants favoured a contract-level assessment because this reflected how contract performance is managed and analysed in practice. In the R&D case study, several participants supported a portfolio perspective, noting that knowledge, capabilities and scientific discoveries are often shared across projects and that investors frequently assess the prospects of an overall development pipeline rather than individual projects.
A44 Similar questions arose in the data case study, where participants debated whether value resides in the raw data, the output produced from the data, the transformation process or a combination of these elements. These discussions suggest that identifying the appropriate unit of account remains a significant challenge where value is generated through combinations of resources, capabilities and activities.
Recognition and value creation
A45 Across the outreach, participants highlighted difficulties in applying existing recognition requirements where value develops over time, depends on uncertain outcomes or is generated collectively across multiple activities. Several discussions challenged the assumption that value can always be attributed to a single identifiable asset or project.
A46 Participants noted that unsuccessful R&D projects may still generate knowledge and learning that contribute to future innovations and successful projects. Discussions on training and data similarly highlighted the difficulty of identifying the relevant asset where value arises from broader capabilities, knowledge, systems and contractual relationships. As one participant observed in the context of training costs, the entity had "turned that cash into employees now who have know-how, who are going to generate money on that revenue contract".
A47 These observations suggest that questions regarding recognition often extend beyond whether expenditure has been incurred to whether value has been created, how that value is generated and whether it can be linked to an identifiable asset. Participants frequently questioned whether existing recognition requirements appropriately capture investments that generate future economic benefits through broader capabilities, knowledge or portfolios of activities.
Expensing versus recognition of future benefits
A48 Across several case studies, participants debated whether expenditure on intangible items should be recognised as an asset or expensed immediately. Discussions often focused on situations in which significant upfront expenditure was incurred to generate future economic benefits, but uncertainty remained regarding the timing, amount or likelihood of those benefits.
A49 Participants expressed differing views on how accounting should reflect such expenditure. Some supported immediate expensing because of uncertainty and concerns regarding control, measurement and recoverability. Others argued that immediate expensing may not always reflect the economics of investments that are expected to generate benefits over multiple periods. As one participant observed: "When you expense it, it’s gone. It’s a sunk cost. No one sees it again. No one questions it again…".
A50 These participants noted that capitalisation may improve visibility of cumulative investment, accountability for management decisions and understanding future profitability.
Measurement
A51 Measurement was another recurring theme across the outreach. Participants highlighted practical difficulties in allocating costs where resources support multiple activities, products or projects and raised questions about whether cost-based measures fully capture the economics of investments in intangible resources.
A52 Similar challenges were identified across training, R&D, carbon credits and data, particularly where value develops over time, supports multiple outputs or arises from combinations of resources and capabilities. As one participant noted in the R&D case study, "Cost is the only factual answer you can get to… but it’s also inherently wrong in the sense that that’s not the value of the asset."
A53 Participants also raised questions about practicality of alternative approaches. As one participant asked: "Who’s going to do the valuation? What are the assumptions? Who is going to audit it?".
Uncertainty
A54 A recurring theme across the outreach was the role of uncertainty in recognition and measurement decisions. Participants acknowledged that many intangible resources are expected to generate future economic benefits but differed on how uncertainty should influence accounting outcomes. Across the case studies, questions arose regarding uncertainty relating to employee retention, regulatory approval, market demand, future revenues, useful lives and recoverability.
A55 While some participants viewed uncertainty as a reason not to recognise an asset until outcomes become more certain, others questioned whether uncertainty should instead be reflected through measurement, impairment and disclosure. One participant summarised this tension by asking: "Should you not recognise it because it’s uncertain or recognise it and discount it by half in the measurement?".
A56 These discussions suggest that stakeholder concerns often relate not only to whether future economic benefits exist, but also how uncertainty surrounding those benefits should be reflected in financial reporting.
A57 Some participants also questioned whether enhanced disclosures alone can fully address these comparability concerns where economically similar intangible resources are recognised when acquired but remain unrecognised when developed internally.
Recognition versus disclosure
A58 Participants consistently supported enhanced disclosures regardless of whether recognition requirements change, including information about contract assumptions, R&D pipelines and milestones, carbon-credit project development and risks, and the role of data in business models and revenue generation.
A59 Several participants suggested that users need information to understand the underlying economics regardless of the accounting outcome. As one participant observed in the R&D case study: "Whether you capitalise it or whether you expense it, the conversations are pretty similar".
A60 However, discussions repeatedly returned to underlying questions of asset identification, recognition, measurement and comparability. Across several case studies, participants questioned whether enhanced disclosures alone can fully address concerns where economically significant resources remain unrecognised or where comparable resources receive different accounting outcomes depending on whether they are acquired or developed internally. As one participant observed: "There's no rigour behind the disclosure. There's rigour behind the recognition".
A61 This suggests that while enhanced disclosures may improve transparency, they have significant costs attached and still may not fully address stakeholder concerns that the underlying accounting outcomes do not reflect the economics of significant intangible resources.
Comparability between acquired and internally generated resources
A62 Participants also highlighted concerns regarding comparability. Several discussions focused on differences between the accounting treatment of internally generated and acquired intangible resources. Participants noted that resources such as trained workforces, data, knowledge and capabilities may be recognised when acquired in a business combination but face significantly greater recognition and measurement hurdles when developed internally.
A63 Similar concerns arose across the training, R&D and data case studies, where participants questioned whether comparable economic resources receive different accounting outcomes depending on how they are obtained. Several participants questioned whether the different accounting outcomes for acquired and internally generated intangible resources reflect underlying economic differences or simply differences in how those resources are obtained.
Overall observation
A64 Taken together, the feedback received throughout the project highlights recurring challenges relating the definition of an asset, the role of the business model, control, unit of account, recognition and value creation, uncertainty, expensing versus the recognition of future economic benefits, measurement, recognition versus disclosure, and comparability between acquired and internally generated resources. These themes arose consistently across the case studies, despite the different fact patterns considered.
A65 The consistency of these issues across all four case studies indicates that they are broader financial reporting challenges associated with intangible resources and modern sources of value creation, rather than issues specific to any individual fact pattern.
A66 The consolidated feedback also suggests that stakeholder concerns are not limited to disclosure gaps but extend to the recognition, measurement and comparability of economically significant intangible resources.
Overarching questions
A67 The cross-cutting themes identified from the feedback give rise to a number of broader questions that extend beyond the specific facts of the individual case studies. Across the outreach, stakeholders expressed a range of views on particular accounting outcomes but repeatedly returned to common questions about how existing accounting requirements reflect the economics of investments in intangible items.
A68 These questions do not seek to identify the "right" accounting outcome for any particular item. Rather, they reflect recurring challenges identified from the feedback received throughout the project.
A69 The overarching questions identified from the feedback received throughout the project are set out below.
| Theme | Overarching question(s) | Illustrative examples (from the case studies) | |
|---|---|---|---|
| 1 | Definition of an asset | What is the relevant asset being accounted for, and how should the asset be identified where value arises from combinations of resources, capabilities, contractual arrangements or future economic potential? | Debate arose as to whether value resides in the workforce, the contract fulfilment capability or the related contract benefits in the training case study. In the data case study, questions arose as to whether value resides in raw data, processed outputs, transformation capabilities or combinations of these elements. Similar questions arose in the R&D and carbon-credit case studies. |
| 2 | Role of the business model | How should the entity’s business model, specifically how it intends to generate value from an activity (for example through use, sale, or intermediation) inform the identification, recognition, measurement and presentation of intangible assets? | Accounting for expenditure should reflect the business model, therefore the same item may require different recognition and measurement approaches. For example: • For R&D: The output could be intended for sale or internal commercialisation. • For carbon credits: accounting outcomes are driven by how entities use and derive value from carbon credits, with differences across project developers, traders, investors and end users. • For data: Asset recognition should start with understanding the business model, that is, how the entity uses data and how that use generates future economic benefit. |
| 3 | Control | How should control be assessed for intangible assets where the entity’s ability to direct the use of, and obtain economic benefits from, a right does not depend on legal ownership, but arises from contractual, or regulatory arrangements? | Trained workforces, though not owned and subject to turnover, are contractually deployed to fulfil obligations; data accessed under shared or non-owned arrangements but controlled by the entity through contractual or licensing rights; carbon credits whose existence and transferability depend on certification and regulatory regimes. |
| 4 | Unit of account | At what level should investments be assessed to reflect how economics are managed and analysed in practice? | Contract-level assessment preferred for training costs; portfolio-level assessment for R&D pipelines; systems; unit of account may be unclear for data activities where value arises from combining data, systems and models; raw data may be considered a separate unit of account when it can be sold independently. Questions arose as to whether value should be assessed at the level of an asset, project, capability or broader portfolio of activities. |
| 5 | Recognition and value creation | How should accounting reflect situations in which value is created collectively across activities, capabilities, knowledge and relationships, rather than through a single identifiable asset or project? | R&D projects may generate valuable knowledge even when unsuccessful. Training creates workforce capabilities, while data creates value through combinations of data, systems and processes. These examples raise questions about whether existing recognition requirements capture how value is created and generates future economic benefits in practice. |
| 6 | Expensing versus recognition of future benefits | How should accounting reflect expenditure that is expected to generate future economic benefits but where uncertainty remains regarding the timing, amount or likelihood of those benefits? | Difficulty separating asset-creating data systems from ongoing data refresh costs; applying judgement in determining when R&D transitions from research to development; and identifying directly attributable training costs versus general staff expenditure. |
| 7 | Measurement | Is cost-based measurement sufficient where it may not represent the economic value or risk profile of an intangible investment? | R&D and data whose value may differ significantly from cost and where cost may be difficult to attribute due to integrated activities (e.g. cloud storage and staff time); carbon credits which may be measured differently depending on whether they are held for use, trading or investment. Challenges were also identified in allocating costs where resources support multiple activities, products or projects. |
| 8 | Uncertainty | How should uncertainty affect the recognition, measurement and disclosure of intangible resources that are expected to generate future economic benefits? How should accounting determine when an internally generated intangible asset exists where value is built through significant upfront investment, develops over time, may be generated collectively across activities and remains uncertain in timing or amount? |
R&D value emerging prior to regulatory approval; training costs incurred upfront to enable later contract profitability; carbon-credit projects and data capabilities involving long development phases before benefits are realised. Questions also arose regarding uncertainty relating to employee retention, regulatory approval, market demand, future revenues, useful lives and recoverability. Different views were expressed as to whether uncertainty should prevent recognition or instead be reflected through measurement, impairment or disclosure. |
| 9 | Recognition versus disclosure | What is the appropriate balance between recognition on the balance sheet and enhanced disclosure in explaining the economics of intangibles? | Strong demand for disclosure on assumptions and judgements (e.g. capitalisation, useful life, impairment) relating to R&D pipelines, training and data as well as information on carbon-credit development. There were also concerns that disclosure alone may not enable users to track value effectively or understand how assets are used over time. Questions were raised as to whether enhanced disclosures alone can address comparability concerns where acquired intangibles are recognised but economically similar internally generated intangibles are not. |
| 10 | Comparability between acquired and internally generated resources | Do current requirements produce comparable outcomes for economically similar resources depending on whether they are acquired or developed internally? | Trained workforces, data resources, knowledge and capabilities may be recognised when acquired in a business combination but face significantly greater recognition hurdles when developed internally. |
Next steps
A70 The case study phase represents the principal bottom-up component of the UKEB's Intangibles Research Project and is now substantially complete. The detailed findings set out in Appendix B to this report, together with the cross-cutting themes and overarching questions identified in this report, will be used to inform the next phase of the research.
A71 The next phase of the project will focus on the top-down component of the UKEB's Intangibles Research Project. Using the evidence gathered through the case studies and stakeholder outreach, the UKEB will consider the broader financial reporting issues relating to intangible resources and how the findings interact with existing accounting requirements, the IASB's Conceptual Framework and other standard-setting developments.
A72 The UKEB will consider whether the themes and questions identified through the outreach point to broader principles that could help inform future discussions on the recognition, measurement and disclosure of intangible items.
Appendix B: Detailed summary of stakeholder feedback
Board notes: (not for inclusion in the final report):
This Appendix contains a detailed summary of stakeholder feedback for each case study.
To assist Board members in identifying revisions arising from the additional workshops conducted in May and June 2026, as well as other substantive additions and refinements made since the Board's previous discussion, new content and significant revisions have been shaded in grey throughout these sections. This formatting has been included solely for the Board's convenience.
Introduction
B1 This section contains a detailed summary of stakeholder feedback gathered throughout the project. The summaries below draw together views expressed across workshops and other outreach activities conducted between September 2025 and June 2026 and are organised by case study, rather than reflecting any single workshop or stakeholder group.
Case Study 1: Training costs
Case study high-level description
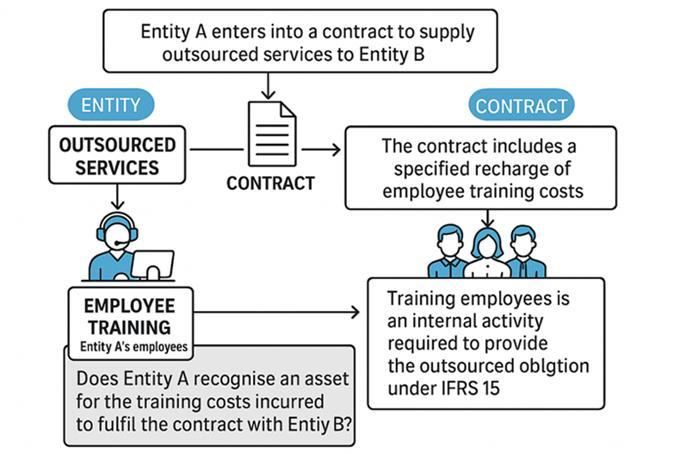
B2 This case study examines training costs incurred by an entity to fulfil an outsourced service contract within the scope of IFRS 15 Revenue from Contracts with Customers. The training is required for the entity to deliver the contracted services but does not constitute a separate performance obligation. The contract allows recovery of certain training costs, while other training costs are not recoverable. The case study explores whether such costs could give rise to an asset and how recognition, measurement, and disclosure should reflect the underlying economics.
Summary of stakeholder feedback
Underlying economics
B3 Preparers and users broadly agreed that the training costs in the case study are contract-specific mobilisation or set-up costs incurred to enable delivery of an outsourced service contract, and recoverable through future contract revenues, rather than general operating training expenditure. Users characterised training as a contract-enabling investment, without which the entity could not earn the related revenue, and observed that the three-year reimbursement period reflects the expected economic pattern of benefit.
B4 Auditors further emphasised the distinction between contract-specific training linked to an enforceable revenue contract and general workforce training. Some auditors described the training as a contract-specific set-up cost and noted that, unlike general training undertaken in the hope of generating future business, these costs were incurred specifically to deliver the contract and earn the related revenue.
B5 Users further noted that this pattern is consistent with the way service contracts are commonly structured and performed, with early phases typically loss-making and later phases highly profitable, reflecting that training and other mobilisation costs are incurred upfront to support delivery and revenues in later periods. As one user observed: "Initial phases [are] loss making and then later phases very highly profitable… that’s just a misallocation of costs".
B6 Academic participants similarly emphasised the basic cash-flow economics of the arrangement, noting that the entity incurs cash outflows for employee costs and training upfront to generate cash inflows from contract revenue over time. They viewed this timing pattern as central to understanding the economics of the transaction.
B7 Some preparers and auditors described the training as something like a "licence to operate", observing that the revenue could not be generated without the contract-specific training. Auditors also noted that management would typically include such costs when pricing the contract and assessing contract profitability. As one auditor explained: "These costs were incurred in order to generate this revenue."
Recognition
B8 Both preparers and users recognised a tension between the economic substance of the training costs and the requirement in IAS 38 to expense all training costs. However, notwithstanding these observations, participants did not reach a common view on capitalisation. Views diverged primarily on whether the entity controls the trained workforce, with concerns about employee attrition reinforcing those differences.
Arguments in favour of capitalisation
B9 Users did not object to the observation that, absent the requirements in IAS 38, the training costs in the case study could potentially meet the criteria for recognition as an asset under IFRS 159.
B10 Several users, particularly those with an investor background, emphasised that economic viability of a contract is more relevant than the resulting accounting outcome. They argued that recognising training costs entirely at contract inception does not reflect their role in enabling future contract revenues and hinders analysis of contract profitability over time, resulting in a lack of cost–revenue matching.
B11 Users also observed that expensing some mobilisation costs upfront while allocating others over a contract term obscures underlying performance. They noted that this makes it difficult to distinguish margins generated by the ongoing business from those reflecting upfront investment in a new contract.10
B12 Academic participants noted that IAS 38 leads to a conservative accounting outcome by requiring all training costs to be expensed, regardless of the underlying economics. They argued that the entity derives economic value from a workforce trained to serve a specific customer and that such value would be reflected in a transaction price if the customer were to acquire the service provider, due to reduced future recruitment and training costs.
B13 Both academics and users highlighted perceived inconsistencies between acquisition accounting and the treatment of internally generated intangibles. They noted that intangible resources such as a trained workforce or accumulated know-how would be recognised if acquired in a business combination, but not when developed internally. Academics also questioned why employee-related costs may be capitalised when incurred as development costs but must be expensed when incurred to train a workforce to deliver a specific service contract.
B14 Some auditors argued that, even independently of IFRS 15 Revenue from Contracts with Customers, a case could be made that the training creates a resource because the workforce becomes more valuable after the training than before. One participant observed that the entity had "turned that cash into employees who have know-how, who are going to generate money on that revenue contract".
B15 Those participants also challenged the view that employee attrition necessarily precludes control, arguing that entities control and direct the activities of a workforce, even if they do not control individual employees. One auditor commented: "You don't control individuals, but you control your workforce."
Unit of account
B16 Where participants considered capitalisation of training costs to be possible in principle, participants discussed the appropriate unit of account for any recognised asset. Two views emerged:
- View A – Separable asset: Training costs recognised as a standalone asset.
- View B – Contract-level asset: Training costs treated as part of a broader contract-level fulfilment or set-up asset, analysed alongside contract revenues and margins.
B17 Users expressed concern that treating training as a standalone asset (View A) would require significant judgement, given that the knowledge created through training resides in employees who may leave the entity. As one participant observed: "When you train an individual… that knowledge is with that individual. If you can’t stop that person from walking out the door, I find it hard to see how you would capitalise that".
B18 The contract-level view (View B) was strongly favoured by users, who explained that analysing training costs together with the related contract better reflects how performance is assessed in practice. From an investor perspective, participants emphasised the importance of understanding results at a contract level, noting that they want to "see what’s associated with contracts" and that it is difficult under current accounting to distinguish "what margins are in core business and what is growth in contracts."
B19 Auditors also generally favoured a contract-level unit of account, viewing the fact pattern as highly contract specific. One auditor stated: "I would see it as by contract in my view." Some participants acknowledged, however, that a portfolio approach could potentially be relevant where similar training activities support a homogeneous portfolio of service contracts.
B20 One auditor suggested that the analysis may be influenced by the form in which the results of the training are retained. Where contract-specific knowledge is embedded in manuals, systems or other organisational resources, rather than residing solely with employees, the case for viewing the resource as controlled by the entity may be stronger.
Arguments against capitalisation
B21 Opposition to capitalisation was grounded primarily in concerns about control. Participants emphasised that the knowledge created through training resides in employees, rather than in resources controlled by the entity. As a result, they questioned whether the entity has the ability to direct the use of, and obtain benefits from, the trained capability independently of the employees themselves. More broadly, participants also expressed concern about the implications of capitalising costs associated with "people" or normal operating activities. As one participant explained:
the asset is kind of the knowledge in those people and a company doesn’t control those people… "they might resign tomorrow."
B22 Attrition and short notice periods were cited as reinforcing these control concerns. Participants noted that trained employees may leave the entity before the expected benefits of training are realised, resulting in the loss of the knowledge created through training. This uncertainty about how long trained employees remain with the entity was seen as undermining the existence and recoverability of any recognised asset, making it difficult to support recognition of an asset expected to generate benefits over multiple periods when those benefits depend on factors outside the entity’s control.
B23 A participant also questioned whether IFRS 15 contract fulfilment cost guidance necessarily implies the existence of an asset. In this participant’s view the resulting accounting may instead be viewed as a cost deferral mechanism and argued that the resource created "cannot be transferred independently of the contract" and is extinguished when the contract ends.
B24 The same participant also questioned whether highly contract-specific training necessarily creates a longer-term advantage or enduring resource for the service provider, distinguishing between training that is specific to a particular customer contract and broader know-how that can be redeployed across multiple contracts.
Measurement (including impairment and amortisation)
B25 Users showed a clear preference for cost-based measurement, ("just tell me how much you spent"). Some participants were uneasy about using fair-value-type or cash-flow-based approaches because they rely on assumptions and introduce significant uncertainty. As one participant remarked:
You might have information about how profitable you expect this contract to be. That doesn’t mean it’s going to come true.
B26 Auditors also strongly supported cost-based measurement and continued to reject fair value approaches. Their reason was that the entity has "transferred one economic resource into another" and therefore cost should remain the relevant measurement basis.
B27 A small number of participants acknowledged that, in limited circumstances, a measurement approach that considers expected future benefits might better reflect the economics, particularly where training:
- creates capabilities that can be reused (and can support future contracts not just the initial one),
- may result in intellectual property (IP) or systems that retain value even if the original contract ends.
Attrition and impairment
B28 Where recognition was assumed in principle, participants discussed attrition primarily as a measurement issue rather than a recognition issue. They noted that employee turnover affects the period over which training benefits are realised and therefore informs assumptions about expected benefits, useful life, and impairment. Several participants emphasised that higher-than-expected attrition increases the risk that anticipated returns will not be achieved, with one noting that "attrition is the key thing."
B29 Participants explained that changes in attrition expectations would be reflected through impairment, making the effects of revised assumptions visible over time. As one participant observed, "if turnover is bigger than you think… you have an impairment test hanging over it." However, concerns were also raised about the operational burden of impairment testing and the sensitivity of the judgements required.
B30 Some auditors noted that attrition would not necessarily result in impairment where the remaining trained workforce is still sufficient to deliver the contract and recover the associated costs. They argued that impairment should be assessed at the level of the relevant unit of account rather than by reference to individual employees.
Amortisation and useful life
B31 There was no consensus on the appropriate amortisation period, with views divided between amortisation over the full contract term or over the three-year reimbursement period. Participants noted that determining a useful life would require judgement and should consider contract duration, workforce retention assumptions, and termination risk.
B32 Support was expressed for amortisation over the period in which economic benefits from the contract are generated, rather than over the reimbursement period alone. Auditors noted that reimbursement provisions may merely reflect timing of cash flows and may not correspond to the pattern in which the underlying economic benefits are consumed. As one participant explained, the economic benefits arise from the value generated by the contract.
Disclosure
B33 Users consistently called for enhanced disclosures even if recognition requirements do not change. They emphasised the need for information that enables an understanding of contract economics and risk–reward profiles, including contract scope, duration and specificity; whether arrangements are one-off or repeatable; the scale and nature of training and other mobilisation costs; reimbursement mechanisms; and key assumptions such as attrition. As one participant observed: "…the more information we can get about the terms of the contracts and the assumptions, the better."
B34 Academic participants additionally suggested disclosures about contractual duration, renewal and renegotiation terms, and the extent to which earnings depend on specific contractual relationships, as these factors may help users assess the sustainability of future earnings and the extent to which contract returns are protected.
B35 Auditors also suggested disclosure of amortisation approaches and assumptions, particularly where contracts are evergreen or have no fixed contractual term.
B36 Preparers, however, raised concerns about the practicality of providing such disclosures across large portfolios of service contracts, noting the volume and complexity of information that could be required. As one participant observed: "Sounds like a whole load of information you’re going to have to give across your whole portfolio of revenue contracts."
Case Study 2: Research and Development
Case study high-level description
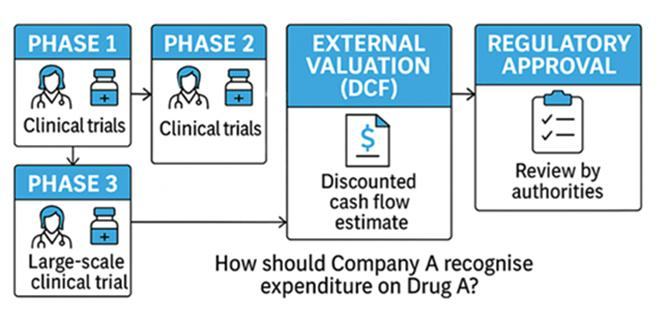
B37 This case study considers a large pharmaceutical company with a broad R&D pipeline that is incurring significant development expenditure on a drug that has progressed to Phase III clinical trials. Although the drug remains subject to regulatory approval, the company has sufficient resources to complete development and has obtained an external discounted cash flow valuation indicating expected future economic benefits. Participants were invited to consider whether and when this expenditure gives rise to a recognisable internally generated intangible asset, and how existing requirements address issues of recognition, measurement and disclosure in circumstances where economic potential is evident but outcomes remain uncertain.
Summary of stakeholder feedback
Underlying economics
B38 Participants described R&D as large upfront expenditure incurred with the expectation, but not assurance, of future economic benefits, particularly in sectors such as pharmaceuticals, technology and aerospace. For example, one participant characterised them as “an example of upfront costs, which are all expensed in the expectation of future potential revenues, uncertainty surrounding and subject to, regulatory approval”.
B39 One participant described early-stage research in practical terms as “money out the door” and expenditure that “drops on the floor,” reflecting the lack of clearly identifiable outputs at that stage. This participant characterised early research as having “infinite possibility,” while also observing that, at this point, “none of this money will ever come back”.
B40 However, several participants cautioned that describing early research in this way should not be taken to mean that it lacks an economic basis. They stressed that, even at early stages, spending decisions are grounded in judgement and expertise rather than chance. As one preparer observed:
“It is not a company that's just, ‘give me $100, I will throw it up in the air and see where it lands’… They must presumably have some rationale behind this.”
B41 Preparers and auditors stressed that R&D expenditure should not be viewed as random spending. They described investment decisions as being informed by scientific research, technical expertise and expectations of future economic benefits. One auditor characterised such spending as a calculated investment decision rather than a random activity.
B42 Preparers and auditors also emphasised that pharmaceutical R&D is often managed on a portfolio basis. They noted that companies may pursue a large number of projects with the expectation that only a small proportion will ultimately succeed, but that successful projects are expected to generate sufficient returns to justify the broader investment programme. One preparer described this as “a big bet at the beginning”, where “some of [the projects] are going to fall away, some of which is going to land”.
B43 Academics and preparers highlighted the interconnected nature of research activities. They noted that unsuccessful or abandoned projects may still generate valuable scientific knowledge that supports other projects in the pipeline or contributes to future products. As a result, participants questioned whether economic value can always be attributed to a single project because failed research may contribute to the eventual success of other products.
B44 One academic observed that the economics of an individual drug cannot be viewed entirely in isolation because individual projects often benefit from broader organisational resources, accumulated expertise and knowledge generated across the wider R&D programme.
Recognition
Research versus development
B45 Participants questioned whether there is a clear point at which research becomes development, noting that R&D involves progressive stages where “there is a point when something becomes something,” but where identifying that point is “very judgemental” rather than clearly defined.
B46 Preparers and auditors reiterated that distinguishing between research and development can be particularly challenging where knowledge generated from one project contributes to several others. They noted that unsuccessful projects frequently provide information that informs the development of later-stage products, further blurring the distinction between research and development activities.
B47 Preparers from technology-based industries similarly observed that innovation processes often involve overlapping stages of experimentation and development, making the distinction between research and development highly judgemental in practice.
Expensing versus capitalisation
B48 Participants broadly agreed that R&D expenditure represents economically rational investment. However, the significant uncertainty inherent in R&D, particularly in early stages, made it difficult to reach consensus on whether, and when, such expenditure should meet the criteria for asset recognition.
B49 Participants did not converge on a clear preference between expensing and capitalising R&D expenditure. They noted that both approaches are applied in practice within existing accounting requirements, with outcomes often reflecting the exercise of judgement. Participants cited diversity in practice, ranging from expensing all R&D costs to capitalising development expenditure only after, or shortly before, regulatory approval. For example:
- One user gave examples of a company that expenses all R&D costs, companies that capitalise development expenditure only after regulatory approval, and others that begin capitalising once a product is submitted for regulatory approval.
- One preparer explained that R&D expenditure was largely expensed in a listed environment but capitalised following a move to private-equity ownership, despite no change in the underlying projects or accounting requirements. As the participant noted, “with the same R&D projects and the same essential fact patterns, I effectively went from a position of not capitalising anything to pretty much anything to capitalise… and the standard allowed me to do that.” This was also cited as raising comparability concerns.
B50 Several preparers continued to support expensing development expenditure until regulatory approval is obtained. They argued that earlier recognition could create significant volatility through subsequent impairments and preferred the certainty of recognising expenditure as incurred.
B51 From a lender’s point of view, participants said that credit decisions are mainly based on cash flow, as this shows whether a business can afford to repay its debts. However, some noted that showing R&D spending on the balance sheet could still be helpful for comparisons and encourage better financial discipline, with lenders making their own adjustments to the figures where needed.
B52 Some users argued that expensing R&D reduces accountability, because once costs are recognised in profit or loss, they are no longer revisited or challenged. They contrasted this with capitalisation followed by impairment, which would require ongoing assessment and explanation of outcomes. As one participant put it:
“When you expense it, it’s gone. It’s a sunk cost. No one sees it again. No one questions it again… But if you had to capitalise it, and then you had to explain why you're writing off, there would be a record of that, and then the company would have to explain to the market”.
B53 Some preparers and auditors suggested that capitalisation could improve governance and accountability because recognised balances would require ongoing reassessment and explanation over time. They noted that capitalisation provides a clearer record of cumulative investment and subsequent outcomes than immediate expensing.
Internally generated versus acquired R&D
B54 One user noted that similar R&D can appear very different on the balance sheet depending on whether it is bought or developed internally, which may make some companies’ balance sheets appear understated.
B55 Preparers and auditors similarly noted that an externally acquired project at the same stage of development as an internally generated project would generally be recognised as an intangible asset despite being subject to many of the same uncertainties. Several participants viewed this as an inconsistency because the underlying economics may be very similar.
B56 One preparer highlighted that a project acquired midway through development would typically continue to be recognised as an intangible asset, whereas a comparable internally generated project could remain unrecognised despite being at the same stage of development.
Recognition thresholds and timing
B57 Across discussions with preparers, users, and academics, the focus was on when R&D should be recognised on the balance sheet, particularly whether recognition should happen while outcomes are still uncertain.
B58 Many preparers said that recognition is generally accepted only once regulatory approval is obtained, especially in pharmaceuticals. They explained that recognising costs earlier could lead to later write-downs and create volatility in reported results.
B59 While many preparers and auditors viewed regulatory approval as an important recognition threshold because approval remains outside management's control, some participants questioned whether recognition should depend solely on receiving formal regulatory approval.
B60 Some preparers observed that a number of the factors commonly associated with asset recognition, including management commitment, technical capability and expectations of future economic benefits, may already be present before regulatory approval is formally obtained.
B61 One academic noted that the 2018 Conceptual Framework refers to a present economic resource with the “potential” to produce economic benefits and suggested that this may support stronger consideration of recognition before regulatory approval than under earlier conceptual frameworks.
B62 Users described the issue as a choice between two approaches:
- not recognising an asset because uncertainty is too high; or
- recognising the asset but reflecting uncertainty by adjusting its value.
B63 One participant summed this up as:
“Should you not recognise it because it’s uncertain or recognise it and discount it by half in the measurement?”.
B64 Some preparers and auditors argued that capitalisation could improve governance and accountability by creating a requirement to monitor, reassess and explain recognised balances over time. They suggested that recognising and subsequently impairing unsuccessful projects may provide a clearer record of management's investment decisions than immediate expensing.
B65 One auditor noted that capitalisation can also provide a record of cumulative investment in a project and improve visibility over the total resources committed to its development.
Asset existence and the business model
B66 Participants emphasised that recognition depends less on development progress and more on the business model (i.e. if the asset will generate value, for example through sale or commercial use). As two participants explained:
“It depends on your intention. Are you developing it to sell to somebody, or are you taking it to market yourself?”
“That’s the definition of an asset. If you can make money out of it. If somebody will pay me something for it.”
Measurement
Cost vs fair value
B67 Participants highlighted a tension between measuring R&D at cost and at fair value. Cost was seen as objective and cautious, but a poor reflection of what an R&D asset is really worth. As one participant said:
“Cost is the only factual answer you can get to… but it’s also inherently wrong in the sense that that’s not the value of the asset.”
B68 Preparers, auditors and academics generally expressed limited support for fair value measurement of pharmaceutical R&D assets. They highlighted the absence of observable market prices and questioned whether reliable fair value estimates could be produced for highly uncertain development projects.
B69 One standard setter expressed concerns about valuation-based approaches, noting that they involved significant uncertainty and reliance on assumptions.
B70 Several auditors and preparers argued that historical cost provides a more objective and auditable measure and allows companies to track the cumulative cost of developing a product over time.
B71 Users said the key issue is understanding potential future value and the likelihood of success, even if it is unclear whether this uncertainty should be reflected directly in accounting numbers.
B72 Users noted that investors usually assess R&D-intensive businesses by estimating future value across a portfolio of projects and weighting outcomes by their probability of success. One participant observed that this assumes future value before outcomes are certain, which differs from the more cautious practice of expensing R&D.
B73 One participant cautioned against using DCF-based fair value models on the balance sheet, noting that these can be highly sensitive to assumptions and may end up reflecting expected market values rather than a reliable measure of a specific asset.3
Unit of account
B74 Users stressed that R&D is best assessed at a portfolio level, as uncertainty and outcomes look very different across multiple projects than when considered one by one. They noted that this better reflects how investors view R&D-intensive businesses. In this context, users suggested that external valuations and a company’s track record could help support measurement where outcomes are uncertain, although views differed on how convincing this would be in practice. Participants also observed that investors are generally more comfortable with uncertainty than auditors.
B75 Academics, auditors and some preparers also supported a portfolio perspective, noting that knowledge, capabilities and scientific discoveries are often shared across projects. They also observed that investors frequently assess the overall prospects of a company's development pipeline rather than focusing exclusively on individual projects.
B76 However, preparers and auditors also identified practical challenges with a portfolio approach. They questioned how portfolio boundaries would be defined, how costs would be allocated as projects evolve, and how projects that generate new research opportunities would be incorporated into a portfolio.
B77 Some auditors cautioned that a portfolio approach could result in large aggregated balances that become difficult to attribute to individual projects and could raise challenges similar to those associated with goodwill impairment testing.
Disclosure
Lack of disaggregation
B78 Disclosure was the area of strongest agreement across preparers, users, and academics. Participants agreed that a single total R&D expense figure is of limited usefulness. They noted that R&D is often “hidden or merged with other expenses,” and that current disclosures do not meet user needs. Users supported this view by referring to survey evidence showing that most respondents want more information about intangibles.
What users want to know
B79 Users want context and evidence of progress, not just headline numbers. Users want information on how projects move through development stages, past success rates, how concentrated R&D spending is, and management’s view of the likelihood of success. A company’s track record was seen as especially important in assessing credibility and future prospects. As one user said:
“I would look at your previous success rate... How realistic is this company about the product it’s bringing through that process?..”
B80 Preparers, auditors and academics suggested that users would benefit from additional information about the composition and progress of a company's development pipeline. They referred to information such as the number of projects at different development stages, movement between stages, historical success rates, key milestones, development progress and management's assessment of future prospects.
B81 Some preparers suggested that aggregated disclosures by therapeutic area, research category or business segment could provide useful information about investment priorities while reducing commercial sensitivity concerns.
B82 Participants also noted that simple metrics, such as returns on R&D, and information on how spending is concentrated across projects can help investors assess effectiveness and challenge management’s assumptions. As one participant explained:
“If there’s a spend of 160 on one project and 40 across a lot of small projects, that would encourage you as an investor to focus on the big project and test management on their future assumptions”.
Disclosure versus recognition
B83 Many participants, particularly users and academics, said that disclosure matters more than whether R&D costs are capitalised or expensed. They noted that investors look for similar information under both approaches and focus on understanding the scale, nature, and progress of R&D activity regardless of the accounting treatment. As one participant commented:
“Whether you capitalise it or whether you expense it, the conversations are pretty similar.”
B84 Preparers, auditors and standard setters also expressed support for enhanced disclosures. Several participants argued that improved disclosures could address many of the information gaps arising from immediate expensing, particularly where disclosures explain project progress, development stages, governance processes and management's assessment of future prospects.
B85 One standard setter suggested that enhanced disclosures could provide useful information about advanced-stage projects without creating concerns about balance sheet manipulation that may arise from earlier recognition.
B86 However, one academic cautioned that disclosure should complement rather than replace recognition, arguing that “disclosure in general cannot substitute for recognition”.
Commercial sensitivity
B87 Participants also recognised the tension between useful disclosure and commercial sensitivity, noting that companies are reluctant to reveal their “secret sauce,” especially where value depends on a small number of projects.
B88 Some participants argued that consistent disclosure is still possible if requirements are clearly defined and applied uniformly. As one participant stressed, disclosure frameworks should be “not open to interpretation” to avoid minimal compliance and ensure disclosures are genuinely comparable across companies.
B89 Preparers were particularly concerned that highly detailed disclosures could reveal commercially sensitive information, investment priorities or development strategies to competitors.
B90 Nevertheless, auditors, academics and preparers generally agreed that useful disclosures can be provided without revealing proprietary information. Examples suggested included reporting the number of projects at different development stages, broad categories of research activity, progress against milestones and pipeline summaries without identifying specific products or technologies.
Case Study 3: Carbon credits
Case study high-level description
B91 The case study considers an environmental project developer that acquires degraded forest and peatland for restoration, with the aim of removing CO₂ from the atmosphere over time. The project is validated and verified annually under the UK Woodland Carbon Code, enabling the developer to issue carbon credits on the UK Land Carbon Registry as sequestration occurs. These credits may be sold or assigned to other market participants, including intermediaries and end users. Participants were asked to explore the accounting implications of these activities from four perspectives:
- the project developer;
- an environmental-credit broker or trader;
- an investor holding credits for appreciation; and
- an end user purchasing credits to offset emissions.
Business model
B92 The feedback suggests that accounting outcomes were largely driven by how entities use and derive value from carbon credits, with differences across project developers, traders, investors and end users indicating an implicit business-model perspective in participants’ views, particularly in relation to recognition and measurement.
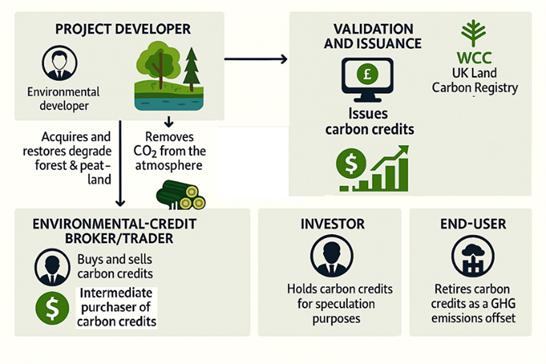
Summary of stakeholder feedback
The project developer (generator of carbon credits)
Underlying economics
B93 Participants viewed the project developer as running a long-term, capital-intensive project. The forest, peatland, or engineered asset was seen as the main productive asset, with carbon credits generated later through verification and certification. As one participant put it, “The trees are like a machine… you’re investing in a big machine that’s going to create something that you can sell.”
B94 Participants agreed that at the outset the developer owns land, but no carbon credits yet exist because “nothing is being generated, nothing has been certified.” They highlighted several risks, including certification risk, physical risks such as fire or destruction, and regulatory and market price volatility.
B95 A preparer highlighted the importance of the broader policy and regulatory environment in which carbon-credit projects operate and noted that carbon-credit values may be affected by policy support and market demand. The preparer cautioned that entities should consider the possibility that market support for carbon credits could decline, observing that developers could be “wiped out of the market quickly” if demand for credits were to disappear.
B96 Some users added that returns may not come only from carbon credits, noting that timber income and increases in land value could also contribute to overall returns.
B97 One auditor also emphasised that, particularly in voluntary carbon markets, value depends heavily on the existence of willing buyers and market demand and noted that “the value of those credits is dependent on what the market is prepared to pay for them”. Another participant observed that without sufficient demand there may be little value beyond “a piece of paper that says I did something good as a corporate citizen”.
B98 An auditor further highlighted the distinction between mandatory and voluntary schemes, noting that voluntary schemes can be more difficult to analyse because there is often no underlying legal obligation driving demand.
Recognition
B99 Participants discussed which costs should be recognised and how they could be recovered. Views generally supported recognising:
- Costs linked to a single long-term asset, such as land or restoration assets (for example, restored peatland), which still have value even if carbon credits are never sold; and
- Costs that arise only from taking part in carbon-credit schemes, which can be recovered only through selling carbon credits, not through the land or restoration asset itself.4
B100 There was significant debate about whether a project developer should recognise a separate carbon-credit asset once credits are certified, distinct from the land or capitalised project costs.
- Some participants supported recognition, arguing that a carbon credit only exists once it is certified and registered and becomes a separate, tradable unit.
- Others disagreed, arguing that only the underlying land should be recognised, with carbon credits reflected only as revenue when sold: “The underlying asset is recognised as PPE and carbon credits as revenue”.
B101 Participants also discussed when capitalisation should begin during the project lifecycle. Some preparers supported capitalising land acquisition and restoration costs from the outset, on the basis that these activities create long-term capacity to generate value, even though carbon credit sales occur later.
B102 Some users, however, said that capitalisation depends on the project reaching sufficient maturity, certification, and market credibility, and that early-stage activities may be too uncertain to recognise as assets.
B103 Several participants described current practice among project developers as recognising land and forestry assets as fixed assets while accumulating carbon-credit-related costs as inventory. In this view, carbon credits are produced for sale and therefore resemble inventory generated from a long-term productive asset. As one auditor explained, “For the project developer, it's something that they produce for sale”, while another stated, “For me, it is inventory from the developer's perspective.”
B104 Participants also highlighted significant cost-allocation challenges for developers, given the long development cycle and substantial upfront investment required. One auditor asked: “How do you allocate the high CapEx, the depreciation, which costs go into the credits?”
B105 Several participants identified revenue recognition as a significant practical challenge. Participants noted that project developers may receive cash from selling Pending Issuance Units (PIUs)5 well before verified credits are issued but are generally unable to recognise revenue until final credits are verified and transferred. One auditor observed that “They can't start recognising revenue until the actual carbon credit is verified and sold.” One participant stated that if entities could “recognise revenue sooner when they receive these preliminary units … that will encourage the big investors to actually put the money into this project”.
B106 Some participants suggested that the inability to recognise revenue earlier may discourage investment in carbon-credit projects. One auditor commented that “The investors do not want to invest at the moment because they can't derive the profits sooner”, while another stated that “It's very much balance sheet accounting at the start and then the revenues very late stages, which is the biggest problem.”
B107 Some participants suggested that accounting requirements could be developed to permit earlier recognition of revenue from preliminary units. One participant referred to the possibility of developing “specific rules for this type of activity”, similar to approaches used in other sectors.
B108 An academic participant questioned whether preliminary issuance units meet the criteria for asset recognition given the uncertainties involved and suggested that disclosure rather than recognition may be more appropriate in some circumstances.
Measurement
B109 Participants generally preferred using cost to measure project developers’ activities, especially where these create land-based assets, such as land, forests, or restored peatland, or involve scheme-specific costs that can only be recovered by selling carbon credits. Fair-value approaches were mostly rejected in these cases, due to concerns about whether they would be appropriate or reliable.6
B110 Where carbon credits are certified and registered, discussions did not show clear support for either a cost-based or fair-value approach.
B111 Auditors highlighted recoverability and net realisable value as important considerations for project developers. Participants noted that developers may incur costs over many years before credits are generated and sold, making the assessment of recoverability particularly important.
B112 An auditor noted that market liquidity is critical when considering value and recoverability, stating that “Whether or not there is an active or liquid market ... is probably the most critical thing.”
B113 Participants also observed that pricing may vary significantly according to the quality and characteristics of credits. One participant noted that prices can differ significantly between credits depending on quality and associated nature or community outcomes. The participant observed that some credits were being sold for “£25 £27 ... a tonne”…”while others were being sold for upwards of £100 a tonne”.
Disclosure
B114 Users stressed that disclosure is critical given the large upfront costs and the long delay before carbon credit revenues begin. Investors want clear explanations of project progress, including how and when a project moves from development to generating revenue. As one user said: “If I was an investor, I’d want that annual report that says how much you’ve actually done at that stage.”
B115 At the same time, participants warned that disclosure alone is not a substitute for recognising assets, noting that narrative information without recognition can lack consistency and discipline (“There's no rigour behind the disclosure. There's rigour behind the recognition”). Participants also cautioned that disclosure should not become overly detailed or reveal commercially sensitive information.
B116 Preparers emphasised the importance of providing broader contextual information, including market behaviour, the distinction between mandatory and voluntary schemes and future prospects. One preparer stated that “It's not going to be a case where the numbers speak for themselves.”
B117 Several participants suggested that disclosures should explain the transition from development activities to revenue generation, including key milestones and revenue timelines. Some participants also suggested explaining the relationship between preliminary unit sales and later credit verification.
B118 Auditors highlighted the importance of disclosures relating to cost-capitalisation methodologies, recoverability of costs and risks arising from long project lead times. One auditor referred specifically to “risks relating to recovery of costs as a result of long lead time and cost capitalisation methodology.”
B119 Participants also identified physical and delivery risks as important disclosure matters, including risks associated with fire, delivery risk and disputes that could affect project value.
B120 A preparer stressed the importance of narrative reporting, commenting that “The narrative is more informative, more interesting and more relied on than the specifics of the numbers” and that disclosures should be understandable to “an ordinary person, not a sophisticated industry person.”
Environmental-credit broker / trader
Underlying economics
B121 Brokers were seen as operating only once carbon credits are certified and registered. Their role is to trade and intermediate between buyers and sellers, not to develop projects.
Recognition
B122 There was broad agreement that brokers recognise carbon credits when they acquire certified units.
Measurement
B123 Participants were generally more open to fair-value measurement for brokers where credits are held for trading. As one participant explained (“So, you either hold them at cost if you intend to use them in your business, or you hold them at fair value if you trade them”).
B124 Auditors further highlighted the importance of market liquidity and active markets when considering value and measurement. One auditor described “the ability to monetize and whether or not there is an active or liquid market” as “a very critical point”.
B125 Some compared carbon credits to shares but cautioned that the comparison is limited, noting that carbon markets are “not quite like shares on the FTSE” and are typically smaller, less liquid and more volatile.7
Disclosure
B126 Participants did not raise specific disclosure issues for brokers.
Investor holding environmental credits for capital appreciation
Underlying economics
B127 Investors were described as holding carbon credits to benefit from price increases rather than for use. Control and marketability were seen as key, with returns highly sensitive to credit quality and regulatory change, including the risk that “a politician comes in and abolishes the whole regime.”
B128 Participants reinforced the importance of market liquidity and the ability to monetise credits. Participants suggested that future economic benefits depend not only on legal ownership but also on the existence of sufficient market demand. One participant remarked that “the value of those credits is dependent on what the market is prepared to pay for them”.
Recognition
B129 Participants generally agreed that certified and registered carbon credits held for capital appreciation meet the definition of an asset, as they are controlled by the investor, transferable, and expected to generate future economic benefits through resale.
B130 Some participants suggested that assessments of future economic benefits may depend on whether credits can realistically be monetised. One participant described “the ability to monetise and whether or not there is an active or liquid market” as a “very critical point.”
Measurement
B131 Participants said measurement should reflect why the credits are held.
- Fair value was seen as more relevant where credits are held for trading or speculation in an active market;
- Cost was viewed as more appropriate where credits are held for longer-term or strategic purposes.
B125 Some compared carbon credits to shares but cautioned that the comparison is limited, noting that carbon markets are “not quite like shares on the FTSE” and are typically smaller, less liquid and more volatile7.
Disclosure
B126 Participants did not raise specific disclosure issues for brokers.
Investor holding environmental credits for capital appreciation
Underlying economics
B127 Investors were described as holding carbon credits to benefit from price increases rather than for use. Control and marketability were seen as key, with returns highly sensitive to credit quality and regulatory change, including the risk that “a politician comes in and abolishes the whole regime.”
B128 Participants reinforced the importance of market liquidity and the ability to monetise credits. Participants suggested that future economic benefits depend not only on legal ownership but also on the existence of sufficient market demand. One participant remarked that “the value of those credits is dependent on what the market is prepared to pay for them”.
Recognition
B129 Participants generally agreed that certified and registered carbon credits held for capital appreciation meet the definition of an asset, as they are controlled by the investor, transferable, and expected to generate future economic benefits through resale.
B130 Some participants suggested that assessments of future economic benefits may depend on whether credits can realistically be monetised. One participant described “the ability to monetise and whether or not there is an active or liquid market” as a “very critical point.”
Measurement
B131 Participants said measurement should reflect why the credits are held.
- Fair value was seen as more relevant where credits are held for trading or speculation in an active market;
- Cost was viewed as more appropriate where credits are held for longer-term or strategic purposes.
B132 Participants also noted that fair-value measurement depends on market maturity and liquidity. While fair value was seen as appropriate where credits can be easily sold, they cautioned that carbon-credit markets are often immature and volatile, making them unlike deep public markets. In these cases, fair value could add volatility and complexity without clearly improving decision-making.
B133 Participants observed that significant price differentials may exist between different categories of credits depending on perceived quality and associated environmental or social benefits. As one auditor noted, “there's a lot of price differential as well between different sort of quality of carbon credits”.
B134 Participants added that measurement may need to change if the purpose for holding credits changes, for example if credits initially held for strategic use are later traded or sold.
Disclosure
B135 Users stressed the need for clear explanations of price volatility, uncertainty, and management judgement.
End user (purchaser to offset emissions)
Underlying economics
B136 There was strong agreement that end users are consumers, not investors. From this perspective, carbon credits have a limited economic life tied to emissions, as they are bought to offset emissions and retired once used: “They are purely going to use them, retire them”.
B137 Participants debated whether the economics of voluntary carbon-credit purchases differ from expenditures undertaken for broader social or charitable purposes. One auditor suggested that where there is no obligation to offset emissions and no active market through which credits can be sold, purchases may be similar in nature to voluntary charitable activity and stated, “It almost makes me think it would be no different from if a for profit company decided to start doing charitable work.”
B138 Other participants disagreed with a pure charity analogy and argued that voluntary purchases may form part of broader transition strategies and responses to stakeholder expectations. One preparer argued that carbon-credit purchases differ from charitable donations because they are “preparing for a new economy” and form part of a broader economic transition.
Recognition
B139 Participants noted that a carbon credit is recognised while it is held and available for use by the end user. Derecognition occurs when the credit is used and retired in the registry, after which it can no longer be transferred or reused.8 As one participant said: “They are purely going to use them, retire them, they will not exist once they've used them as an offset”.
B140 Participants debated whether carbon credits held in voluntary markets necessarily give rise to future economic benefits where no active market exists. One auditor argued that where there is no mechanism to monetise credits and no obligation to satisfy, demonstrating future economic benefits may be more difficult.
B141 Other participants noted that many entities purchase credits in advance of future retirement and may obtain economic benefits from doing so. One auditor noted that some entities purchase credits early “on the expectation that carbon price is going to go up” and therefore viewed such credits as assets until retirement.
B142 Several participants characterised credits held for future offsetting purposes as intangible assets, particularly where the credits are held for multiple periods before retirement. One participant stated that this “very clearly leads you down the route of holding it as an intangible on the balance sheet until such time as you retire it”.
B143 Users cautioned that requiring companies to expense the full cost of credits immediately when purchased to meet emissions commitments could discourage their use, even where credits support real emissions reductions9.
Measurement
B144 Participants strongly preferred cost-based measurement for end users, with the cost recognised when the credits are used to offset emissions and are retired.
B145 Preparers, auditors and an academic participant reinforced support for cost-based measurement and expressed reservations about fair-value approaches. One preparer explained that “I don't see how it could be helpful to users to have very fluctuating values on something which is extremely judgemental as a fair valuation.”
B146 An academic participant supported “a conservative cost based approach” and suggested maintaining “a very close watch on impairment indicators” where credits are held for extended periods.
Disclosure
B147 Participants agreed that, for end users, the impact of buying, using, and retiring carbon credits should be clear from the financial statements, rather than relying only on sustainability reporting.
B148 An academic participant suggested that disclosures could distinguish between credits held for future use and credits already retired and could include an “estimated retirement schedule”.
B149 Participants also suggested linking disclosures on carbon-credit holdings to broader emissions-reduction and transition strategies. One participant specifically recommended providing a “link to an emission strategy” so that users can understand how acquired credits are expected to be deployed over time.
B150 Some participants suggested that understanding the reasons for purchasing carbon credits may help users interpret the transactions, particularly where purchases are linked to public commitments, stakeholder expectations or broader transition plans.
Case Study 4: Data
Case study high-level description
B151 The case study explored the accounting issues that arise when an entity incurs significant expenditure to build and use a large internal dataset that is central to its business model but not legally owned. It invited consideration of whether such expenditure gives rise to a recognisable intangible asset, and if so, how recognition, measurement and disclosure should reflect the underlying economics, including shared data arrangements, continuous data enhancement, and uncertainty over future benefits.
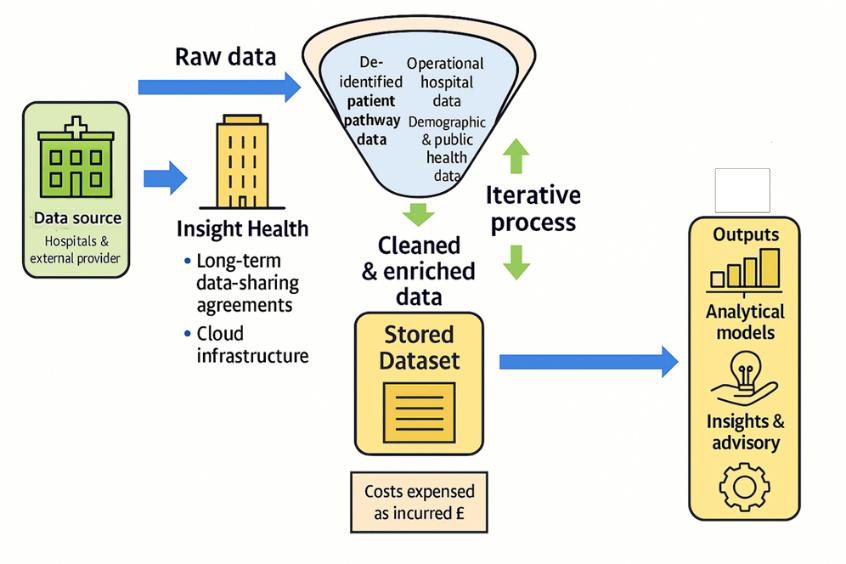
Summary of stakeholder feedback
Underlying economics
B152 Participants agreed that the economics of data depend on the entity’s business model and how data-related activities generate future benefits.
B153 A participant observed that in determining the business model, it will be important to assess whether the entity is operating as a principle or agent in the transaction as this has a direct impact on the business model.
B154 Participants observed that the fact pattern prohibits the resale of raw data. As a result, participants focused on how the entity in the case study adds value to the raw data, through the systems, models and intellectual property developed through processing and analysis10.
B155 Preparers emphasised that the data and related modelling capabilities are central to the entity’s business model and revenue generation. Several preparers noted that the entity could not provide its products or services without the data and related processing activities. One preparer stated: “their whole business model centres around the content, the data that they're providing. And without that, they wouldn't exist as a business.” Preparers also noted that users would want to understand “the core essence of how you make money”.
B156 Preparers noted that value may arise from a combination of data, AI capabilities and the work performed on the data, rather than from the underlying data alone. One preparer described this as “the value is the combined data plus the capability”. Another participant referred to “the data and the turning of that into decision useful information”.
B157 Accountancy body representatives focused on the economic substance of the arrangement and questioned whether the entity acts as a principal or an agent when licensing or reselling data obtained from third parties. They observed that this assessment could significantly affect the analysis of the business model and the source of value creation.
B158 Accountancy body representatives also distinguished between data products that can be sold repeatedly to multiple customers and one-off outputs prepared for a specific customer. They observed that different conclusions may arise depending on whether the output can be sold repeatedly or whether it is produced in response to a specific customer request. In the latter case, one participant asked: “Do you have an asset there or is it just a service that's being provided?”.
Recognition
Business model and future benefits
B159 Recognition was seen as possible in principle, but highly dependent on control, use within the business model, and a clear link to future economic benefits.
B160 Participants stressed that asset recognition should start with understanding the business model, that is, how the entity uses data and how that use generates future economic benefit. One participant noted:
“First, we’ve got to have a business model… and then maybe I can say that it may be worth something.”
B161 A key concern was the difficulty of applying IAS 38’s restrictive criteria to data-related activities. However, some participants warned that lowering recognition thresholds could increase the risk of over-capitalisation and later impairment.
B162 Participants did note that internally generated data-related items face higher recognition hurdles than acquired intangibles, due to judgement and uncertainty in demonstrating future benefits. As one participant said: “you’ve still got to be able to prove that it’s going to actually make you some money.” 11
B163 Preparers were generally more willing to acknowledge that future economic benefits may exist where data-driven outputs generate revenue or are fundamental to the entity’s products and services. Several preparers pointed to the fact that the entity generates revenue from its products and services and that the business would not exist without the data and related processing activities.
B164 Accountancy body representatives were more cautious. While they agreed that the activities create value, they questioned whether that value necessarily gives rise to an asset. As one participant stated: “I can certainly see value but whether that value translates to an asset is a separate question.”
B165 Some preparers compared the activities to a production process in which raw data is transformed into something new and useful. One preparer from the pharmaceutical industry explained that value may arise from creating a “new utility” from the underlying data.
B166 Preparers also discussed whether multiple assets may exist in the case study. Some participants suggested there could be separate assets associated with the raw data, the finished output created from the data and the process or capability used to transform the data. However, no consensus was reached.
Control
B167 Control was the most debated issue, particularly in relation to data accessed under shared or non-owned arrangements but controlled by the entity through contractual or licensing rights. Some participants questioned whether control exists when others can also use the data (“They share the data. They don’t control it. And everyone else can use it as well.”).
B168 Others referred to the Conceptual Framework, suggesting that exclusive control may not be required if contracts give the entity the ability to direct the use of data and obtain economic benefits. “Does it actually matter if someone else is using it?… As long as there is an agreement.”
B169 The discussion indicated that the existence of control depends on the specific terms of the contractual arrangement, including the extent of the entity’s right to direct use and obtain economic benefits.
B170 Preparers expressed mixed views regarding control. Some took a restrictive view and noted that they would be reluctant to recognise an asset unless the entity was clearly in control of it and could continue to use it over time. One preparer commented that “you would be very slow to put something on your balance sheet, unless you know you're in total control of it”.
B171 Other preparers argued that ownership is not necessarily the determining factor. These participants suggested that contractual rights, including licensing arrangements and rights of use, may provide sufficient control where the entity can use the data within its products or services and generate economic benefits from it.
B172 Several preparers questioned whether traditional notions of control developed for physical assets are appropriate for data. They noted that datasets can be used simultaneously by multiple parties and suggested that control may be better assessed by reference to rights of use rather than exclusive possession. One participant described data as “more of a shared resource”.
B173 One auditor suggested that where the underlying data cannot be sold in its existing state, the relevant asset may be something other than the data itself, such as the outputs or insights created from using that data. Some auditors suggested that where the underlying data cannot be sold or controlled independently, the asset may instead be the enhanced output derived from that data.
B174 Accountancy body representatives drew parallels with inputs such as wind or seawater, noting that businesses may rely heavily on these resources but do not necessarily control them as assets. These participants questioned whether acquiring rights to use data is sufficient to establish control of an asset.
Unit of account
B175 Participants observed that value in the case study arises from the combination of raw data with the systems, models and processes used to transform that data into useful outputs (effectively forming a “secret sauce”).12 However, no clear conclusion was reached on whether this creates challenges in identifying the appropriate unit of account, given that the resulting value may not be attributable to a single identifiable asset but instead emerges from a set of interdependent elements.
B176 At the same time, there were no objections to the view that raw data may, in some cases, exist as a standalone item, particularly where it can be sold independently without further value-adding activities.
B177 Preparers expressed different views on what the asset actually is. Some used a manufacturing analogy and viewed raw data as an input that is transformed into a higher-value output. Under this view, separate assets could potentially exist for the raw data, the finished product created from that data and the process used to create the output.
B178 Other preparers questioned whether the data itself is the asset and suggested that the focus should instead be on the unique process, capability or “utility” created by the entity.
B179 Auditors were generally more cautious about identifying multiple assets and questioned whether the different elements could be meaningfully separated and measured. Some suggested that one asset may simply be consumed or utilised in creating another asset.
B180 Accountancy body representatives noted that different conclusions may arise depending on whether the output can be sold repeatedly to multiple customers or is produced for a specific customer request.
Measurement
Cost vs Fair value
B181 The cost model was widely viewed as the most practical and cautious approach, with little support for fair value.
B182 Participants raised concerns about fair value, including reliance on assumptions, cash-flow forecasts, valuation complexity, and auditability. As one participant put it: “Who’s going to do the valuation? What are the assumptions? Who is going to audit it?”
B183 Participants noted significant judgement in identifying costs that relate directly to an asset. Staff costs were seen as capitalisable only where time can be clearly linked to specific projects. Cloud, server, and storage costs were viewed as particularly difficult to allocate, as they support many activities.
B184 One participant suggested a revenue-based approach, starting with first-year revenues from a proprietary model and building value over time. However, they acknowledged this would involve significant judgement and assumptions.
B185 Preparers highlighted significant practical challenges in measuring data-related assets beyond any initial acquisition or licensing costs. Particular concerns related to allocating costs associated with data cleansing, enhancement, AI tools, systems and ongoing maintenance activities. Several participants noted that measurement would be difficult for both preparers and auditors.
B186 Participants also raised concerns about cost allocation, particularly where data contributes both to outputs sold externally and to internally generated insights or capabilities.
B187 Some preparers questioned why similar intangible assets can often be recognised and measured in a business combination while internally generated assets face significantly greater recognition and measurement challenges.
Useful life and amortisation
B188 Useful life and amortisation were seen as particularly challenging due to the evolving and iterative nature of data. Participants highlighted the uncertainty around the useful life of data and whether regular updates represent maintenance or new assets.
B189 There were concerns that capitalisation of updates could cause asset values to grow over time, unless older data is written off or clearly distinguished from new assets.
B190 Preparers reiterated that the continual updating and refinement of datasets makes it difficult to identify a clear point of completion. Participants questioned whether ongoing changes represent maintenance of an existing asset or the creation of new assets.
Impairment
B191 Participants noted that capitalising data may introduce volatility in profit or loss. There were concerns that the carrying amount of data-related assets could build up over time and, if later assessed to be overstated, be reduced significantly in a single period through impairment, resulting in large, sudden write-downs (“cliff edge” impairments). This effect could be more pronounced during periods of weaker performance, creating a “double hit” in profit or loss.
B192 Participants also noted that audit scrutiny may act as a constraint on capitalisation. Participants noted that “auditors tend to be balance sheet focused” and may be sceptical of capitalised amounts where there is a risk of subsequent impairment.
B193 Participants observed that changes in underlying assets, including data, may lead to obsolescence and trigger impairment when those assets no longer contribute to future economic benefits13.
Disclosure
B194 There was strong support for enhanced disclosure due to the high level of judgement involved in recognising and measuring data-related assets. As one participant noted: “You’d need to be consistent and explain what you have done and the reason behind it. Your assumptions would be important so your analysts can make sense of it.”
B195 Participants highlighted the following disclosures as most useful:
- Key assumptions used to determine useful lives;
- Accounting policy choices and reasons for them;
- Descriptions of recognised data-related asset classes, including aggregation;
- Discount rates used and related sensitivities.
B196 Participants generally did not support disclosure of costs that were not capitalised, noting limited usefulness where no asset is recognised. Instead, disclosures should focus on recognised assets and the key judgements made.
B197 Participants also stressed that disclosures should not compromise commercial sensitivity.
B198 Preparers strongly supported enhanced narrative disclosures explaining how the business acquires, processes and uses data to generate revenue and create value. Several participants considered this information important regardless of whether related expenditure is recognised as an asset or expensed. One preparer stated: “I would want to understand… what you're actually doing, how you're taking that data, what you're doing to it.”
B199 Some preparers suggested that recognising an asset could help users better understand the business model by providing a closer link between revenues and the costs incurred to generate those revenues. Others considered enhanced disclosures to be more important than recognition because of the difficulties associated with measurement.
B200 Preparers generally did not consider these disclosures to be more commercially sensitive than disclosures already required for other intangible assets. Several participants noted that entities can explain their business model, key assumptions and value creation processes without disclosing proprietary methods or their “special sauce”. One participant observed that “nobody goes into so much detail that they're giving their state secrets away.”
Footnotes
-
See Agenda Papers 6 and 6A Preliminary stakeholder feedback on the case studies. ↩
-
Pending Issuance Units (PIUs) are units issued under the UK Woodland Carbon Code that represent expected future carbon sequestration before verified carbon credits are formally issued. ↩
-
From a Secretariat perspective, these concerns may reflect the fact that DCF-based measures require extensive forward-looking assumptions and are highly sensitive to changes in inputs. ↩↩
-
The Secretariat interprets that these “carbon-scheme specific costs” do not enhance the land or forest itself and are incurred only because the developer wants to issue and sell carbon credits; they are recoverable only through the successful issuance and sale of carbon credits. Examples include certification, validation and verification fees, registry-related costs, and other carbon-scheme-specific monitoring or consultancy expenditures. These costs would be capitalised as a separate cost pool if recovered through the future sale of carbon credits. ↩↩
-
Pending Issuance Units (PIUs) are units issued under the UK Woodland Carbon Code that represent expected future carbon sequestration before verified carbon credits are formally issued. ↩↩
-
The Secretariat interprets this as reflecting concerns that fair-value measurement would require incorporating long-dated and uncertain assumptions about future carbon-credit certification and pricing. ↩↩
-
In the Secretariat’s view these characteristics were seen as introducing greater uncertainty and limiting the reliability of fair-value measurement in practice. ↩↩↩
-
Participants described carbon credits held by end users as being used and then retired, rather than expiring over time. The Secretariat understands this to mean that recognition and derecognition are linked to use and retirement, rather than to the passage of time or amortisation over a defined period. ↩↩
-
For example, a company might purchase carbon credits for £10 million to support a long-term emissions-reduction strategy. If the full amount is recognised as an immediate expense in profit or loss in the year of purchase, this may make reported performance appear worse in that period, even though the environmental benefits are realised over a longer time horizon. Participants noted that this accounting outcome could influence management decisions about whether and when to purchase credits. ↩↩
-
The Secretariat notes, however, that in other circumstances raw data itself may be sold or otherwise generate economic benefits. ↩↩
-
The Secretariat interprets these comments as reflecting the additional judgement required where recognition is assessed in the absence of a purchase transaction, compared with externally acquired items where a transaction price may provide initial evidence. ↩
-
The Secretariat plans to explore this point at future workshops. ↩
-
As noted, these challenges are not unique to data and can also arise for other assets, for example inventories or other assets that may become obsolete over time. This highlighted the importance of getting a better understanding at future workshops of the factors that lead to impairment, including patterns of use, technological change and evidence of ongoing economic benefit. ↩