5 Statement of Cash Flows and Related Matters Research Paper
25 June 2026 Agenda Paper 5
Executive Summary
| Project Stage | |||||||
|---|---|---|---|---|---|---|---|
| IASB | Research / Workplan | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
| Project Scope | Moderate |
|---|---|
Purpose of the paper
In November 2024, the Board discussed the Project Initiation Plan for this UKEB research project and suggested that, if time and resources allow, the UKEB would consider undertaking research on the statement of cash flows for financial institutions, targeted towards banks and insurers.
The IASB plans to start its work on financial institutions in H2 2026.
A draft research paper was presented to the Board in May 2026, being the sixth in a series of research papers on the Statement of Cash Flows and Related Matters. An updated draft is presented in Appendix A.
The UKEB will present its research findings to the IASB’s Accounting Standards Advisory Forum (ASAF) in July 2026. At that meeting, the IASB will also seek feedback from ASAF members to inform its own research on the statement of cash flows for financial institutions (see Appendix B).
Summary of the Issue
Stakeholders support substantive reform to the statement of cash flow to improve reporting for banks and insurers, rather than incremental updates that are perceived as adding little value.
There is strong support for simplifying the statement of cash flows, given its limited relevance and high cost, while retaining some useful insights through a streamlined version supported by targeted disclosures. Any changes should be carefully scoped to avoid duplication, extra burden, or unintended consequences.
A key priority for preparers is fixing the definition of cash and cash equivalents, so that it better reflects how financial institutions manage liquidity. Preparers also request clearer guidance on classification.
Decisions for the Board
- The Board is asked for general comments and observations on the updated paper of UKEB research findings on the statement of cash flows for banks and insurers (Appendix A).
- The Board is asked whether the sixth UKEB research paper on this matter should be published on the UKEB website, subject to any changes discussed at this meeting.
Other questions for the Board
In preparation for the ASAF meeting in July 2026 (see Appendix B):
- Do Board Members agree that the key messages to be provided to ASAF in relation to requirements for financial institutions should be supportive of the IASB’s general approach, subject to the need for the UKEB to consult stakeholders on any detailed proposals?
- Do Board Members agree with the key message to be provided to ASAF regarding the IASB potential approach for exemption, presentation requirements and disclosure requirements?
- Do Board Members agree that the best approach to scoping the requirements should be based on regulatory requirements, such as the Basel framework?
- Do Board Members have any advice on industry groups or other stakeholders the IASB should speak to as they carry out outreach on this topic during Q3 of 2026?
Appendices
- Appendix A: UKEB research paper 6 – Statement of Cash Flows and Related Matters: Further research – Banks and Insurers
- Appendix B: IASB project – Statement of Cash Flows for Financial Institutions
Background: Statement of Cash Flows and Related Matters
The IASB added a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation (published March 2021).
In the Feedback Statement to the Request for Information (published July 2022) most respondents recommended the addition of a project on cash flows to the IASB’s workplan, rating it as high priority.
The IASB staff have performed initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB’s decision on the scope of the project and will also address possible ways of improving the perceived deficiencies.
The IASB discussed the initial research outcomes in March 2025, and in May 2025 discussed the topics to include in the project plan and a draft timeline for work on the project. The IASB plans to publish an Exposure Draft in 2027.
A UKEB research project on the Statement of Cash Flows and Related Matters supports meeting the UKEB’s responsibilities regarding thought leadership in accordance with the UKEB Terms of Reference. It will also help the Board to deliver the UKEB’s 2026-27 Regulatory Strategy, to influence the IASB early in its development cycle, by providing timely and effective input 1. To date the UKEB has published five research reports on various aspects of the cash flow project.
The UKEB research has focused on gathering primary evidence on the improvements UK investors and creditors suggest for the statement of cash flows, and UK preparer views on those possible improvements. This has provided a foundation for the UKEB to propose potential solutions for the problems already identified by the IASB, as well as any other issues identified through UKEB outreach.
Appendix A: Statement of Cash Flows and Related Matters: Further research – Financial Institutions
June 2026 Second DRAFT FOR DISCUSSION
- Executive Summary
- Decisions for the Board
- Background: Statement of Cash Flows and Related Matters
- Appendix A: Statement of Cash Flows and Related Matters: Further research – Financial Institutions
- Executive Summary
- Introduction
- Background
- Usefulness of the Statement of Cash Flows of Banks and Insurance companies
- Stakeholder Recommendations
- Scoping
- Concluding observations
- Annex 1: UK Regulatory regime
- Annex 2: Simplified Cash Flow Statement example
- Appendix B: IASB project – Statement of Cash Flows and Related Matters
- Executive Summary
- Purpose
- Background
- July 2026 ASAF meeting
- Group A: Applicability of tentative decisions to financial institutions
- Group B: Further analysis needed to explore possible adaptation for financial institutions
- UKEB Key Messages
- Response to ASAF questions
- Exemptions, presentation and disclosure requirements
- Exemptions
- Presentation requirements
- Supplementary disclosure requirements
- UKEB Key Messages
- Response to ASAF questions
- Next steps
Executive Summary
1 In January 2026, the UKEB commenced research to understand how banks and insurance companies could provide better information to users of their financial statements.
2 The research suggests that there is no single solution, but rather a set of complementary improvements that could enhance the usefulness of cash flow-related information. These include simplifying the presentation of the statement of cash flows, increasing disaggregation in the notes, and, most importantly, improving the linkage between IFRS financial statements and regulatory capital, liquidity and solvency information.
User priorities
3 This research paper highlights the distinction between the business models, and cash generation, of banks and insurance companies (life and general insurance companies), and the extent to which the users of their financial statements are looking for different information in the financial statements.
4 Banks and insurance companies are operated in a heavily regulated environment. As a result, their investors’ common information needs include:
- reconciliations that ‘bridge the gap’ between the IFRS financial statements and key regulatory metrics that constrain the operation of the business, such as capital and liquidity adequacy (for banks) and capital and solvency requirements (for insurance companies); and
- information about the limitations on dividends linked to surplus capital or shareholder funds.
5 Different types of users of bank and insurance companies’ financial statements use their statement of cash flows for different purposes. As a result, there is a diversity in views amongst those users about usefulness of the statement of cash flows for such entities.
6 Therefore, giving banks and insurance companies an option to provide a simplified statement of cash flows, could still meet users’ needs, whilst potentially reducing the cost for preparers. This option could be contingent on those regulated entities providing regulatory returns (on capital and liquidity or solvency) to the relevant regulator in its jurisdiction, and reconciliations to key constraining regulatory metrics being included in the financial statements.
7 Whilst regulatory regimes are not global, with some like the Basel framework more widely adopted, stakeholders considered that entities being regulated in this way was an appropriate way to scope any requirements for banks and insurance companies.
Preparer concerns
8 Preparers acknowledge that the statement of cash flows for banks and insurance companies is of limited use to users and support the provision of supplementary disclosures that ‘bridge the gap’ between regulatory metrics and the IFRS financial statements.
9 However, they raised concerns that any new requirements should avoid duplicating regulatory information, adding to the reporting burden, requiring disclosure of sensitive information and unintended consequences (such as bringing additional regulatory information within audit scope).
10 In addition, preparers raised concerns with the current requirements in IAS 7 Statement of Cash Flows for:
- Cash and cash equivalents – the request was to more closely align with how banks and insurance companies manage liquidity in practice (this is similar to the concerns raised by preparers in non-financial institutions). Preparers are also seeking more guidance on whether, and when, specific items such as central bank deposits can be included in cash equivalents.
- Classification of cash flows – whilst IFRS 18 introduces guidance on main business activities in relation to the income statement, preparers are calling for more guidance in relation to classification in the statement of cash flows.
Key Recommendations
11 The key recommendation from stakeholders were:
- A Simplified Statement of Cash Flows
- Limited supplementary disclosures, mainly reconciliations, that ‘bridge the gap’ between key regulatory metrics (liquidity and solvency, and capital) and IFRS financial statements, and information about constraints on capital distribution (i.e. dividend payout capacity)
- A choice of options to improve the definition of ‘cash and cash equivalents’:
- Remove bright line (‘three month’ guidance);
- Require an accounting policy disclosure; and
- Disclosure note providing maturity analysis for cash and cash equivalent components.
Next steps
13 The IASB is expected to publish an Exposure Draft of proposed changes to IAS 7, and potential changes to other IFRS Accounting Standards, in 2027.
14 The views expressed in this paper are those conveyed by UK stakeholders during the outreach carried out by the UKEB. They do not represent UKEB member views and will not necessarily affect the conclusions in any endorsement and adoption assessment by the UKEB on new, or amended, IFRS Accounting Standards.
Introduction
Purpose and objective of research paper
15 Building on earlier work in its Statement of Cash Flows and Related Matters project, the UKEB has undertaken further research on the usefulness of the statement of cash flows for certain financial institutions to help identify reporting that could better meet investor needs.
16 In May 2025, the IASB tentatively decided to explore how its project might address financial institutions, focusing on:
- improvements to the statement of cash flows generally before deciding how any changes might apply to the requirements for financial institutions;
- exemptions for financial institutions from some or all of the requirements for presenting a statement of cash flows; and
- any presentation or supplementary disclosure requirements specific to financial institutions that might enhance the usefulness of information about cash flows for such entities.
17 The IASB decided the research should focus on whether to retain, eliminate, or simplify, the cash flows statement for financial institutions.
Research process and methodology
18 In November 2024, the UKEB agreed to explore improvements specific to financial institutions, particularly insurance companies and banks, where value is driven more by capital generation than cash generation.
19 This paper incorporates findings from outreach conducted in early 2026 with members of the UKEB Advisory and Working Groups [2]. Interviews were also undertaken with preparers from banks and insurance companies. Discussions focused on:
- the usefulness of cash flow statements for banks and insurance companies and reasons for limited relevance for users; and
- potential approaches the IASB could consider to improve the usefulness of information provided to users.
20 These findings were triangulated with other research, which comprised:
- Financial statement analysis: reviewing annual reports of UK banks and insurance companies to identify useful voluntary disclosures, such as reconciliations of regulatory capital and liquidity and solvency metrics to IFRS figures.
- Review of other disclosures: examining cash flow and liquidity-related information presented outside the financial statements, including regulatory reporting that is publicly available.
Background
Diversity of financial institutions
21 Financial institutions encompass a wide range of business models, including banks (retail/commercial), central banks, insurance and reinsurance companies [3], investment banks, asset managers, mortgage companies, and other entities. However, cash flow statements, required for all entities, are considered to provide information of only limited usefulness for some financial institutions, particularly banks and insurance companies.
22 Both banks and insurance companies are subject to substantial regulatory capital and liquidity or solvency requirements (see Annex 1 for details of the UK regulatory regime). However, the underlying drivers of capital and liquidity and solvency management for banks and insurance companies differ. Therefore, the information needs of investors to assess the effect of regulatory capital and liquidity or solvency requirements may also differ depending on whether they are banks or insurance companies [4].
Banks
23 For banks [5], the statement of cash flows often provides limited information. Core activities such as lending and deposit-taking do not consistently result in movements in cash and cash equivalents. For example,
- loan issuance or repayment only affect cash when the customer transfers funds between banks.
- interest income and expense frequently do not result in immediate cash movements, as they are often settled through internal account balances rather than external cash transfers.
24 Banks are also subject to regulatory requirements in relation to capital adequacy to fulfil any claims against their assets.
Insurance companies
25 Insurance companies typically receive premiums from policyholders upfront (premiums float), then invest (typically in high-quality liquid fixed income investments, like government and corporate bonds. These investments provide stable and predictable returns to ensure that funds are available when claims need to be paid) to generate investment income to sustain their operations and grow their businesses.
26 However, there are significant differences between life insurance and non-life (general) insurance cash flows due to the duration, predictability, and investment characteristics of liabilities.
27 Cash flow statements for general insurance companies focus on short-term underwriting and claims, while life insurance cash flows are shaped by long-term policy obligations and investment strategies. This means that their cash flow statements are structurally and functionally different despite following the same IAS 7 framework.
28 For non-life general insurance companies, the claim ratios (claims to premiums) are important. Life insurance companies provide coverage related to a person's mortality and can include savings and protection plans. Financial analysis often focuses on the long-term investment income generated from premium investments, as these policies tend to have longer durations.
29 Such companies must also comply with regulatory requirements to maintain adequate equity reserves so they are financially able to fulfil claims i.e. they must be solvent.
Existing requirements under IAS 7 Statement of Cash Flows
30 IAS 7 does not differentiate between financial and non-financial entities. It requires all entities to present a statement of cash flows on the basis that users need information on how cash is generated and used, regardless of business model. Accordingly, no exemption from preparing a statement of cash flows is available for financial institutions.
31 The findings included in the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives [6], support the feedback also received by the IASB on the limited usefulness of the statement of cash flows for banks and insurance companies:
- Most users and preparers believe that the statement of cash flows for banks and insurance companies provides limited incremental value –
- banks and insurance companies typically managing portfolios of liquid assets beyond what is included within ‘cash and cash equivalents’.
- the statement of cash flows only represents a subset of such portfolios and therefore does not align with how the overall business is managed.
- Preparers also expressed that it was rare to receive questions from users on cash flows.
- When explicitly asked about the usefulness of the risk management disclosures required by IFRS 7 Financial Instruments: Disclosures, there were mixed views on the extent to which the required disclosures were useful.
- Preparers and users place greater focus and reliance on information provided using non-GAAP measures and within regulatory reporting. Information contained within regulatory reporting was noted to be more standardised and disclosures around liquidity and capital management were noted to be more extensive, resulting in enhanced comparability and relevance.
Usefulness of the Statement of Cash Flows of Banks and Insurance companies
Investors and other users’ views
32 Investors find the statement of cash flows is useful for banks and insurance companies as a bridge between the statement of financial performance and statement of financial position. It provides a sense check of liquidity, and explains differences between accounting and cash movements.
33 They also noted that certain items, where available in the statement of cash flows, are useful for all entities, including for banks and insurance companies, such as dividends paid, capital issuance/repayment, share option exercises, interest paid/received, debt movements, and business acquisitions and disposals.
34 However, investors generally observed that, over and above those aspects, the statement of cash flows has limited usefulness, noting the following key challenges:
- the statement of cash flows does not reflect how financial institutions manage cash or liquidity risk in practice;
- ‘operating’ and ‘financing’ activities are indistinguishable because financial institutions’ operating assets are financial assets (potentially breaking the usual operating–investing–financing model of IAS 7);
- the statement of cash flows does not differentiate between cash belonging to shareholders and customer/policyholder cash; and
- investors focus more on regulatory capital generation and constraints, not gross cash movements.
Usefulness of other disclosures
35 Users of financial statements for banks and insurance companies place greater reliance on regulatory capital and liquidity (banks) and solvency (insurance companies) disclosures due to the likely constraint placed on dividend payouts.
36 While IFRS standards (outside IAS 7) include some liquidity-related disclosures and are considered useful, there is a notable gap in clearly linking financial statements with regulatory information. This leads users in the UK to rely on publicly available regulatory data to attempt to create their own reconciliations.
37 IFRS 7 Financial Instruments: Disclosures provides requirements for preparing information on liquidity, which might be considered sufficient for some users:
- Paragraph B11E of IFRS 7 requires disclosure of maturity analysis of financial assets held for managing liquidity risk.
- IFRS 7 (paragraph 39, 42E(e) and B11B), and IAS 1 Presentation of Financial Statements (paragraph 65) (replaced by IFRS 18 Presentation and Disclosure in Financial Statements effective 1 January 2027) also require information about the maturity analysis of financial liabilities.
- Information on liquidity gap disclosures showing whether there is an excess of assets or liabilities in specific time buckets might also be useful.
- Regarding information on encumbered assets, disclosures on financial assets pledged as collateral, as required by paragraph 14–15 of IFRS 7.
38 For insurance companies, in addition to the information required in IFRS 7, IFRS 17 Insurance Contracts includes the following disclosure requirements:
- Paragraph 132(b) of IFRS 17 requires maturity analyses of insurance and reinsurance contracts.
- Paragraph 126 of IFRS 17 requires an entity to “disclose information about the effect of the regulatory frameworks in which it operates; for example, minimum capital requirements or required interest-rate guarantees”. This should lead to insurance companies disclosing any constraints such as dividend payout capacity, but to ensure comparability, it may be necessary for this disclosure requirement to be more prescriptive.
39 In addition, paragraphs 134–136 of IAS 1 [7] require an entity to “disclose information that enables users of its financial statements to evaluate the entity’s objectives, policies and processes for managing capital”. Some entities go beyond those capital disclosures, providing disclosures involving forward-looking information, such as dividend payout capacity (although insurance companies are expected to disclose this information under IFRS 17 requirements, as noted above).
40 Potentially, most information for capital flows could be derived from the statement of changes in equity and other disclosures.
41 Similarly, information about the collection and uses of cash resources could be derived from the statement of financial position and related breakdowns of the line items in the notes (where disaggregation is sufficient), which serve the purposes of showing the sources of funding and their uses. Some companies in the UK voluntarily provide such disclosures.
42 Users identified the most valuable information as the disclosures that link regulatory capital and liquidity information to the financial statements. Opportunities to link existing IFRS requirements, including those listed above, should be considered before requiring new liquidity information for banks and insurance companies.
Preparer and accounting firm views
43 There was broad agreement amongst preparers and accounting firm representatives that the statement of cash flows has limited usefulness for banks and insurance companies.
44 One accounting firm representative observed that liquidity (banks) and solvency (insurance companies) is primarily managed through regulatory frameworks, stress testing and ratios, rather than IAS 7 cash flow metrics. They concurred with investors that IAS 7 classifications (operating, investing and financing, and the definition of cash equivalents) do not align well with financial institution business models, where liquidity instruments exist along a spectrum, making the concept of “cash equivalents” somewhat artificial and leading to inconsistent practices.
45 Preparers, particularly banks, described the statement as backward-looking, produced for compliance purposes and not used internally for decision-making or liquidity management. They emphasised that banking is inherently liquidity-driven, with constant balance sheet movement. More relevant and decision-useful information is already provided through regulatory disclosures in the UK. These disclosures include liquidity coverage ratios and other risk metrics.
46 Importantly, the ‘financing’ section is seen as valuable for understanding capital and funding actions, such as dividends, buybacks, and issuance or redemption of debt. While this information could theoretically be disclosed in notes, doing so may reduce prominence and comparability across banks.
47 Preparers’ primary concerns related to improving the definition of cash and cash equivalents and improving the consistent classification of cash flows.
Definition of cash and cash equivalents
48 UKEB stakeholder outreach with accounting firm representatives and preparers identified significant concerns with the IAS 7 definition of ‘cash and cash equivalents’, particularly for banks. Some preparers described the definition as counterintuitive and misaligned with banking practice, creating unnecessary complexity.
49 A key issue is IAS 7’s reliance on ‘original maturity’ (the date of acquisition of an investment) rather than ‘remaining maturity’ (how long before the investment matures after the reporting date). This results in economically identical High-Quality Liquid Assets being classified differently based solely on when they were acquired, despite having the same near-term liquidity profile. This approach conflicts with regulatory liquidity management, which focuses on ‘remaining maturity’, and often forces banks to maintain parallel data sets, increasing operational burden without clear benefit. IAS 7 is also believed to drive management behaviour i.e. investing in shorter term investments as the reporting period end approaches, if management’s driver is to appear to hold more cash and cash equivalents.
50 Similarly, mandatory central bank deposits—while economically equivalent to cash—are often restricted and therefore fall outside IAS 7 definitions, leading to imperfect workarounds by preparers, such as creating ‘restricted cash’ classifications. Clearer guidance on central bank deposits (and other restricted items) may be needed in IAS 7 to ensure that the requirements are more consistently applied.
51 These definitional issues were described by one stakeholder as a major “policy bugbear,” with many stakeholders calling for solutions to these issues to be prioritised by the IASB. More broadly, stakeholders emphasised that banks operate across a continuum of liquidity instruments—from overnight to longer-dated maturities—making the binary concept of ‘cash equivalents’ inherently artificial.
52 Some users suggested improvements, such as tightening and standardising the reconciliation of ‘cash and cash equivalents’, noting that the measure currently lacks consistency and may include items such as required central bank deposits, collateral, restricted balances and short-dated instruments.
Consistent classification of cash flows
53 An accounting firm representative noted that for financial institutions, traditional cash flow categories do not align well with business models. Activities typically classified as ‘investing’ or ‘financing’ are often core, revenue-generating operations.
54 For example, raising funds through deposits, equity or debt issuance may be economically similar, but differences in loan maturities can significantly affect cash flow patterns between otherwise comparable banks. This makes classification outcomes inconsistent and reduces comparability.
55 A preparer from an insurance company raised similar concerns, noting that premiums received and subsequently invested to meet regulatory capital requirements are often classified as ‘investing’ rather than ‘operating’, despite being central to their business model. Stakeholders suggested redefining these categories for financial institutions, including a revised concept of ‘financing’ linked more directly to capital.
56 In the absence of clear guidance, diversity in practice persists. Although IFRS 18 introduces similar classification labels for the income statement, stakeholders do not expect the guidance in IFRS 18 to resolve these issues, as the underlying mismatch with business activities of financial institutions remains.
Stakeholder Recommendations
Simplified Statement of Cash Flows
57 One way to solve the classification challenges that banks and insurance companies face might be to permit banks and insurance companies to provide a simplified statement of cash flows, without classification labels, but with sufficient disaggregated information (consistent with the disaggregation principles introduced in IFRS 18 [8]). Annex 2 includes a sample of a simplified cash flow statement produced by an insurance company.
58 Users and accounting firms interviewed were supportive, as long as relevant disaggregated information is provided in the notes to the accounts. This might provide a proportionate approach given the perceived limited usefulness to users of the statement of cash flow of financial institutions.
59 However, one insurance preparer interviewed, was concerned that while removing the ‘operating’, ‘investing’, and ‘financing’ categories from the cash flow statement might reduce preparation effort, it could damage comparability. They considered comparability critical, especially among UK insurance companies, and more valuable than cost savings for preparers.
60 It is worth noting that the IASB has tentatively decided to introduce new requirements, to address stakeholder feedback on the need for more information for non-cash transactions and other non-cash items. These may require all entities (financial and non-financial) to provide:
- a ‘working capital’ movement note, showing components of operating assets and liabilities, and reconcile the movements shown in the statement of financial position to the movement shown in the cash flow statement.
- a mandatory reconciliation of changes in financing activities, as currently suggested in IAS 7.44D, to satisfy the requirement in IAS 7.44A.
61 Should these requirements be introduced by the IASB then single line entries on the face of the statement of cash flows would suffice for ‘changes in working capital’ and ‘net cash flows from financing activities’. Each single line could be cross-referenced and reconciled to a detailed note in the financial statements. This would further simplify the statement of cash flows produced by all entities.
Enhanced disaggregation
62 Simplified cash flow statements, if permitted, would need to be supplemented by appropriate disaggregated information in the notes.
63 Investors strongly supported enhanced presentation and disaggregation of cash flow information. They view this as the most practical solution while also being the least burdensome to preparers and capable of improving comparability without fully rewriting IAS 7.
64 Investors suggested that targeted disaggregation by meaningful drivers is desirable. This would be consistent with the principles in IFRS 18, as this would reflect diversified business models, and provide clearer presentation, which could be provided in the notes rather than on the face of the statement of cash flows.
65 The IASB would need to consider whether existing requirements are sufficient to ensure that users are still able to access cash flow information related to certain items that stakeholders have highlighted need to be transparent. These include dividend payments, capital issued and repaid, share options exercised, business acquisitions and disposals, interest payments and receipts, and changes in debt.
Limited supplementary disclosures
66 Internationally, banks, insurance companies, and some other financial institutions operate in a highly regulated environment and are bound by a regime of capital and risk management, to ensure their financial stability and resilience. Banks are further bound by leverage and liquidity requirements, and insurance companies by solvency requirements. This includes provision of extensive reporting to regulators, some of which may be publicly available. See Annex 1 for details of the UK regulatory regime.
67 As noted above, users of financial statements for banks and insurance companies, place greater reliance upon the regulatory disclosures rather than on the statement of cash flows, as part of their decision-making processes. Due to the notable gap in clearly linking financial statements with regulatory information, users rely on publicly available regulatory data to attempt to create their own reconciliations to the IFRS statements.
Reconciling to Regulatory Capital, Liquidity and Solvency information
Banks – Regulatory liquidity and capital disclosures
68 Pillar III of the Basel framework requires a comprehensive set of disclosures for banks to be publicly available [9]. Therefore, extensive disclosures are already provided by UK banks in publicly available regulatory information, investor packs, in the front half of the annual report, or voluntarily in financial statements. These disclosures include Liquidity Cover Ratio, Net Stable Funding Ratio and High-Quality Liquid Assets by UK banks.
69 Practical examples of disclosures provided by UK insurance companies that could inform standard setting including disclosures of:
- Capital and earnings reconciling between IFRS and Solvency UK (Solvency II (SII)) requirements.
- Publicly available audited solvency reports (Solvency and Financial Condition Report - SFCR [10]), showing the Solvency UK and IFRS metrics for excess of assets over liabilities and supporting tables showing the reconciliation and an explanation of the different methodologies adopted.
70 Preparers acknowledged that supplementary disclosures that ‘bridge the gap’ and reconcile regulatory capital reporting to the financial statements might provide users with better information. For example, if an entity provides capital and liquidity reporting to an external regulator, providing a reconciliation of that key performance indicators (Alternative Performance Measures) to an IFRS measure would be helpful, and would mean a simplified statement of cash flows could be sufficient.
71 Many preparer and accounting firm representatives suggested that investors and analysts tend to focus more on:
- Capital adequacy and risk-weighted assets (RWAs) [11].
- Forward looking liquidity metrics, such as Liquidity Cover Ratio and Net Stable Funding Ratio.
72 Investors suggested enhanced disclosures and better linkage of cash flow movements to regulatory capital requirements would significantly improve usefulness. Several investors emphasised that users currently manually derive connections from multiple notes. They felt that this approach would be the most useful to investors, the least burdensome to preparers, and capable of improving comparability without fully rewriting IAS 7.
73 A credit manager at a UK bank noted that bank liquidity is assessed largely through the liquidity and funding stack, not through ‘cash from operating activities’. They went on to note that since this cash flow-related information is decision-useful for investors and users of accounts, the IASB should require its inclusion. They noted that users lean on the size and quality of the liquidity buffer, i.e. High-Quality Liquid Assets [12], and how it maps to the Liquidity Cover Ratio eligible assets, and the degree of funding stability, through the Net Stable Funding Ratio [13].
74 One accounting firm representative suggested that liquidity and expected cash flow disclosures are more relevant for banks and insurance companies than an IAS 7-style statement of cash flows:
- IFRS 7 liquidity tables currently show contractual maturities, which often paint an unrealistic picture – “all banks appear insolvent” if deposits are shown as on‑demand.
- Expected maturity profiles or disclosures aligned with regulatory liquidity metrics (e.g. Liquidity Cover Ratio-related insights) may be more meaningful.
- Some UK‑specific disclosures, e.g. disclosures of expected credit loss (DECL) [14], provide helpful visibility into gross loan movements (net new money, portfolio changes), but these are not mandatory globally. The stakeholder noted this asymmetry could justify improved international disclosure requirements.
Insurance companies: Regulatory solvency and capital disclosures
75 One preparer (insurance) interviewed stated that anchoring cash flow reporting for insurance companies around capital would result in a stronger alignment between IAS 7 and capital disclosures currently in IAS 1 [15].
76 The preparer also advocates improving IAS 7, with more detailed guidance tailored to financial institutions, including a requirement to distinguish between cash attributable to shareholders and amounts belonging to policyholders.
77 The preparer suggested that bringing similar information into IFRS financial statements would not materially increase audit burden and could improve overall financial reporting quality. They considered that providing an explicit link between cash flows and capital and other regulatory constraints would make information in the financial statements more decision-useful than relying on external disclosures.
78 Users suggested that it may not be necessary to require IFRS Accounting Standards to replicate regulatory templates, but IFRS Standards could close the gap with:
- a limited, auditable bridge, that requires financial institutions to provides a clear reconciliation from ‘cash and cash equivalents’ to liquidity resources and constraints; and
- a short commentary explaining the main drivers when the liquidity buffer moves materially.
Benefits and challenges of providing supplementary disclosures
79 The main benefit of requiring certain financial institutions to provide additional limited disclosure of key metrics, defined by regulators, against which those financial institutions monitor the success of their businesses, is to bridge the gap between those key metrics and IFRS defined measures. This would help users understand how they are reconciled, thus improving transparency of information. Users will benefit from not having to attempt their own reconciliation between the regulatory metrics and the audited financial statements.
80 The challenge will be assessing which specific metrics provide the most useful information for users on a global basis, and how financial institutions might present required reconciliations without unnecessarily duplicating information required to be disclosed outside the financial statements.
Scoping
81 One of the most significant issues for any proposals would be the practical challenges in clearly defining the entities that should qualify for exemption, particularly for diversified groups (conglomerates) that include both financial and non-financial activities [16].
82 It was suggested that the IASB could refer to Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4) [17], where the concept of activities predominantly connected with insurance was introduced. Alternatively, scoping could be based on whether other regulatory reporting was required for an entity.
UKEB Outreach
83 Investors acknowledged that while an exemption from, or adjustments to, the requirement to prepare a statement of cash flows for financial institutions may be conceptually attractive, it would be difficult to implement in practice.
84 Investors and accounting firm representatives readily acknowledge the challenge of defining the scope, particularly for conglomerates that combine financial and non‑financial activities (e.g. manufacturing groups with financing arms). Some stakeholders suggested limiting any exemption to entities whose primary business is clearly banking and recognised as such by markets or regulators, thereby excluding mixed business models.
85 Others pointed to IAS 30 Disclosures in the Financial Statements of Banks and Similar Financial Institutions [18] as a potential starting point, which defined banks based on core activities (deposit-taking and lending). However, this approach may still be difficult to apply consistently across jurisdictions. Also, the nature of banking has changed since IAS 30 was developed, with the rise of ‘fin tech’ firms and challenger banks.
86 Definitional challenges are compounded by the global diversity of regulatory frameworks. Financial institutions are typically defined through legal and regulatory constructs that vary by jurisdiction, making it difficult to translate these into a consistent IFRS-based scope.
87 Despite these challenges, some stakeholders believe a feasible path exists. They noted that precedents for scoping already exist in IFRS, such as IFRS 7’s reference to Value-at-Risk, demonstrating that IFRS can incorporate externally developed methodologies. Similarly, past IASB work defining insurance companies based on liability ratios suggests that quantitative thresholds could be used for scoping [19]. Definitions from sustainability standards (e.g. IFRS S2 Climate-related Disclosures) or regulatory frameworks (e.g. Basel III/Pillar III) could also provide a basis for scoping.
88 However, they stressed that any exemption should not introduce new burdens, commercially sensitive disclosures, or additional reporting complexity. Therefore, any alternative disclosures would need to rely on information already prepared and clearly add value for users.
89 Participants also emphasised that the IASB could not rely solely on jurisdiction‑specific regulatory definitions and would instead need a globally consistent, principle-based approach, potentially anchored to widely adopted frameworks like Basel III.
90 Ultimately, stakeholders noted that any reform would need to carefully assess whether the benefits of change outweigh the costs and consider more flexible, principle-based solutions, such as explicitly applying materiality to the presentation of the statement of cash flows.
Concluding observations
91 The research confirms a broad and consistent view across investors, preparers and accounting firms that the statement of cash flows, as currently required by IAS 7, provides only limited incremental insight for banks and insurance companies.
92 While certain elements, particularly those relating to financing and capital movements, remain useful, the overall structure and definitions within IAS 7 do not align well with financial institution business models or with how liquidity and capital are managed in practice. As a result, users rely more heavily on regulatory and alternative disclosures, which are better aligned to decision-making needs but are not clearly linked to IFRS financial statements.
93 The findings suggest that there is no single solution, but rather a set of complementary improvements that could enhance the usefulness of cash flow‑related information. These include
- simplifying the presentation of the statement of cash flows;
- increasing disaggregation in the notes;
- improving the linkage between IFRS financial statements and regulatory capital, liquidity and solvency information; and
- targeted supplementary disclosures, particularly reconciliations bridging IFRS measures to regulatory metrics.
This approach appears to offer a proportionate means of addressing user needs without duplicating existing reporting or imposing unnecessary burden on preparers.
94 However, defining the scope of financial institutions eligible for any modification or exemption remains a significant practical challenge, particularly given the diversity of business models and regulatory regimes globally. A principles-based approach, building on existing IFRS requirements and leveraging established regulatory frameworks, may offer the most pragmatic path forward while ensuring that any changes deliver clear benefits to users relative to their cost and complexity.
Annex 1: UK Regulatory regime
95 In the UK, day-to-day regulation and supervision of the UK financial services industry (including banks and insurance companies) is divided between the Prudential Regulation Authority (PRA), a division of the Bank of England (BoE), and the Financial Conduct Authority (FCA) [20]. In addition, the European Central Banks's policies hold relevance for banks operating internationally or within the EU. These policies influence banking regulations, impacting how banks function and comply with global standards.
96 For multi-national groups, operations, including overseas branches, subsidiaries and associates, can be subject to many rules and regulations applicable to the conduct of banking and other financial services business in each of the jurisdictions in which a group operates.
97 The table below shows some of the regulatory requirements for banks and insurance companies in the UK:
| Company | Banks | Insurance – general (non-life) | Insurance – life |
|---|---|---|---|
| Regulator | Bank of England’s Prudential Regulation Authority (PRA) | Bank of England’s Prudential Regulation Authority (PRA) | Bank of England’s Prudential Regulation Authority (PRA) |
| Regime | ✓ Basel Committee for Banking Supervision (BCBS) | ✓ Solvency UK (Solvency II directive under Basel) | ✓ Solvency UK (Solvency II directive under Basel) |
| Liquidity requirements | ✓ Liquidity Cover Ratio (LCR) ✓ Unencumbered High-quality Liquid Assets (HQLA) ✓ Net stable funding ratio (NSFR) |
||
| Pillar 1 – Quantitative financial and solvency information – capital management | ✓ Minimum Capital Requirement (MCR) ✓ Minimum requirements for own funds and eligible liabilities (MREL) ✓ Risk Weighted assets (RWA) ✓ Tier 1 Capital = Common Equity Tier 1 (CET1) and Additional Tier 1 (AT1) instruments ✓ Tier 1 Capital Leverage Ratio = Tier 1 Capital ÷ Total Consolidated Assets × 100 ✓ Debt to equity ratio, Debt to assets ratio, Debt to capital ratio ✓ Supplementary Leverage Ratio (SLR) - minimum level of Tier 1 capital against total exposures i.e. on-balance-sheet assets (loans, securities) and off-balance-sheet items (derivatives, guarantees) |
✓ Minimum Capital Requirement (MCR) 25% – 45% of SCR ✓ Solvency Capital Requirement (SCR) ✓ UK Solvency II Own Funds |
✓ Minimum Capital Requirement (MCR) 25% – 45% of SCR ✓ Solvency Capital Requirement (SCR) ✓ UK Solvency II Own Funds |
| Pillar II - Governance and Risk Management | ✓ Banks disclose Pillar 2 requirements and leverage ratio Pillar 2 requirements on an annual basis, and the ECB publishes the consolidated Pillar 2 requirements of all the banks it supervises, subject to permission by the bank. | ✓ Own Risk and Solvency Assessment (ORSA) ✓ Analysis of Change (AOC) in SCR over time |
✓ Own Risk and Solvency Assessment (ORSA) ✓ Analysis of Change (AOC) in SCR over time |
| Pillar III – Supervisory Reporting and Disclosure | ✓ Pillar III published disclosures - unaudited | ✓ Annual Solvency and Financial Condition Report (SFCR) - audited [21] | ✓ Annual Solvency and Financial Condition Report (SFCR) - audited [21] |
Banks – Regulatory liquidity and capital disclosures
98 Banks are required to comply with capital, leverage and liquidity requirements and provide regular regulatory returns to the PRA [22], including Liquidity Cover Ratio, High-Quality Liquid Assets, Net Stable Funding Ratio and encumbered assets.
99 The Liquidity Cover Ratio requirement takes into account the relative stability of different sources of funding and potential incremental funding requirements in a stress situation [23]. The Liquidity Cover Ratio is designed to promote short-term resilience of a bank's liquidity risk profile by holding sufficient High-Quality Liquid Assets to survive an acute stress scenario lasting for 30 days. The Net Stable Funding Ratio has been developed to promote a sustainable and stable structure of assets and liabilities.
Insurance companies – Regulatory liquidity and capital disclosures
100 Insurance company regulatory reporting requirements are governed by the Solvency UK reporting part of the PRA Rulebook [24], which includes a requirement for regulated firms to produce an annual Solvency and Financial Condition Report (SFCR) and provide regular information on the Solvency Capital Requirement, Solvency UK liquidity reporting and UK Solvency II Own Funds. These are also referred to as Pillar III or Pillar 3 disclosures.
101 The Solvency Capital Requirement [25] is mandated by the Solvency II Directive issued by the European Union (EU) in 2009 [26] and is a critical financial mandate for insurance and reinsurance companies in the EU, ensuring they maintain sufficient capital to cover all quantifiable risks, like underwriting and operational risks. Solvency II or Solvency UK requires a Solvency Capital Requirement annual recalculation for accurate risk management. If authorities find the requirement doesn't reflect the risk of a specific insurance type, they can raise the capital requirement. A Solvency Capital Requirement ensures these companies can meet their financial obligations to policyholders with a 99.5% probability over a 12-month period, meaning financial ruin is less than once in 200 cases. The formula uses a modular approach, assessing and then combining exposure to each risk category.
102 In addition to the Solvency Capital Requirement, a Minimum Capital Requirement must also be calculated. The Minimum Capital Requirement is a safety threshold below which national regulators would intervene, if breached. The Minimum Capital Requirement aims for an 85% probability of adequacy over a year. Understanding the Solvency Capital Requirement alongside the Minimum Capital Requirement helps firms avoid potential regulatory interventions and stabilize their operations in a competitive market.
103 The equivalent of equity in a Solvency UK balance sheet is the Solvency II Own Funds figure. Insurance companies tend to hold more own funds than the Solvency Capital Requirement. Insurance companies usually set a metric, the Solvency Ratio, being Total Own Funds divided by the Solvency Capital Requirement, e.g. say 140%–180% of the Solvency Capital Requirement, so that they hold a significant buffer for having the capacity to support the payout of dividends, the reinvestment of cash into its own activities, to support organic growth of the business and inorganic growth (acquisitions).
Annex 2: Simplified Cash Flow Statement example
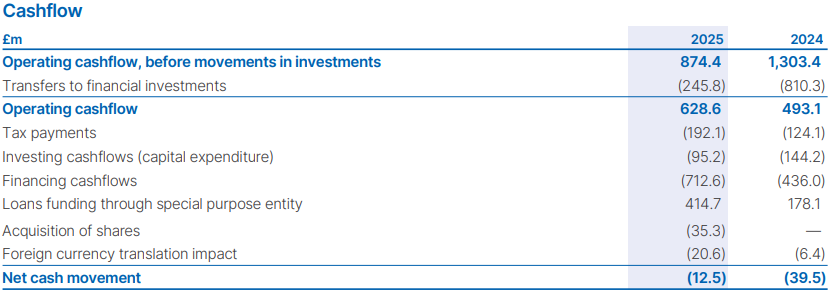
Admiral Group plc Annual Report and Accounts 2025 Group capital structure and financial position included in the Strategic Report (pages 52–53). By comparison, the full IAS 7 Statement of Cash Flows reported in the financial statements can be found on page 209 of the Admiral Group plc Annual Report and Accounts 2025.
Contact Us UK Endorsement Board 13th Floor | 1 Harbour Exchange | Harbour Exchange Square | London | E14 9GE www.endorsement-board.uk
Appendix B: IASB project – Statement of Cash Flows and Related Matters
Executive Summary
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing UKEB Post Implementation Review |
IASB Next Milestone: Exposure Draft (2027)
Purpose
B1 The purpose of this paper is to ask for Board Members’ views on the key messages the UKEB plans to convey at the July 2026 Accounting Standards Advisory Forum (ASAF) meeting. At the meeting, the IASB technical staff will provide ASAF members with an overview of the IASB’s initial research and activities to date relating to the statement of cash flows for financial institutions and will seek ASAF members’ views on its approach for financial institutions, including:
- Whether the expected benefits of the tentative improvements to cash flow information generally, apply to financial institutions.
- Possible exemptions for financial institutions, from some or all of the requirements from presenting a statement of cash flows.
- Possible presentation or supplementary disclosure requirements specific for financial institutions that might enhance the usefulness of information about cash flows for such entities.
B2 The IASB technical staff will also seek ASAF members’ advice on any industry groups or other stakeholders to engage with during outreach on this topic.
B3 Input received at the ASAF meeting will be used by the IASB staff to help plan future work for financial institutions and develop ideas for discussion with the IASB members at a future meeting.
Background
B4 At its May 2025 meeting, the IASB decided (among other decisions) to consider any additional changes to cash flow statement requirements for financial institutions only after concluding discussions on the above topics.
B5 The project was moved to the IASB’s standard setting work plan in January 2026.
B6 The tentative decisions made by the IASB to date on this project can be found in Appendix A of Staff Agenda Paper 20 for the May 2026 IASB meeting [27].
July 2026 ASAF meeting
Statement of Cash Flows for Financial Institutions
Improvements being explored for entities that are not financial institutions
B7 The areas of improvement being explored for entities that are not financial institutions are set out in paragraph B4 above. More detail and the IASB’s tentative decisions to date can be found in Appendix of Staff paper 4 for the ASAF July 2026 meeting [28]. For each areas of improvement, the IASB staff have undertaken initial analysis of:
- the applicability of the IASB’s tentative decisions for financial institutions (that is, would the possible change affect the financial statements prepared by a financial institution); and
- the likely costs and benefits of any changes for financial institutions.
B8 The IASB has not held any detailed discussions on the topic of the statement of cash flows for financial institutions [29], consequently the UKEB Secretariat have not been able to seek feedback from UKEB Advisory Groups prior to bringing this topic to the Board.
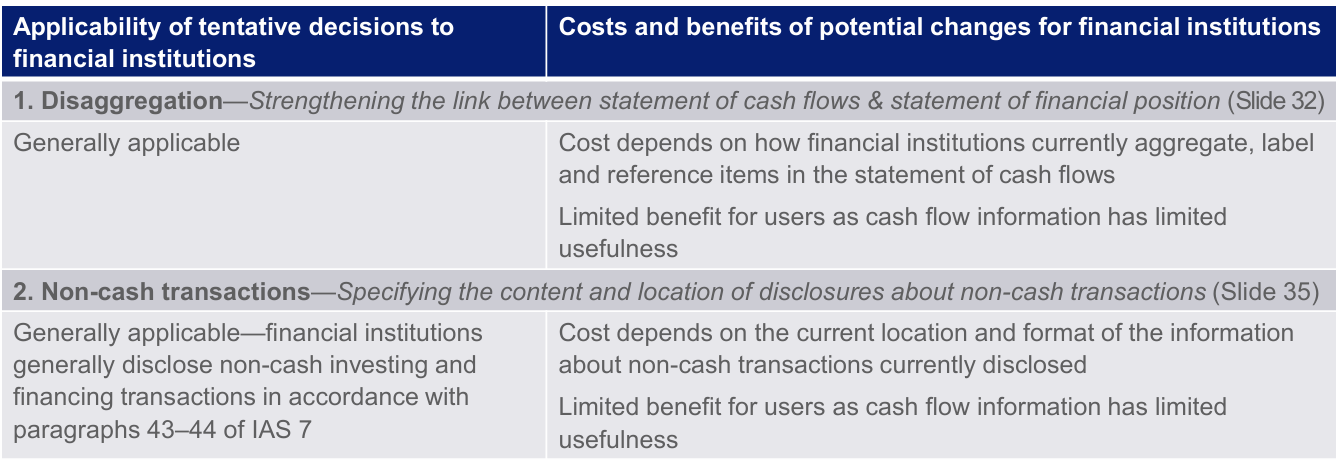
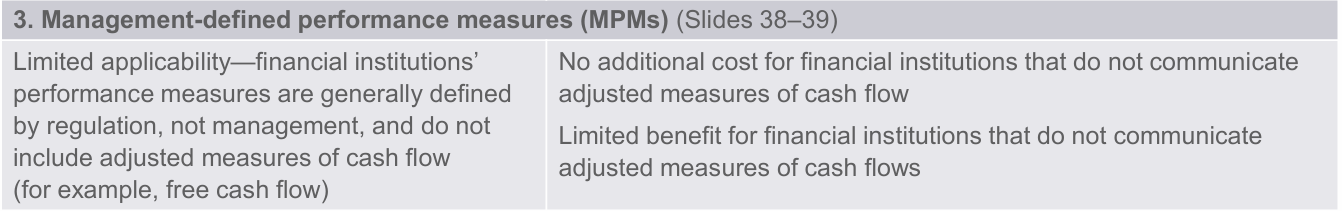
B9 Based on the IASB staff’s initial analysis, the areas of improvements have been split into two groups that reflect how they might be considered in the future:
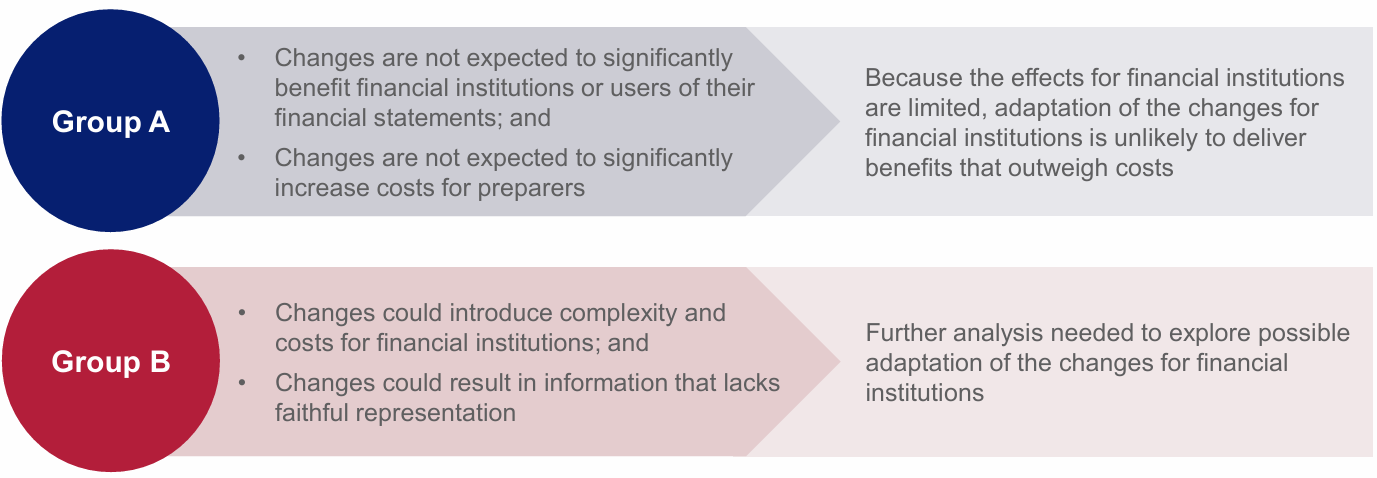
Group A: Applicability of tentative decisions to financial institutions
Disaggregation and Non-cash transactions
Management-defined performance measures (MPMs)
Classification requirements and definition of cash equivalents
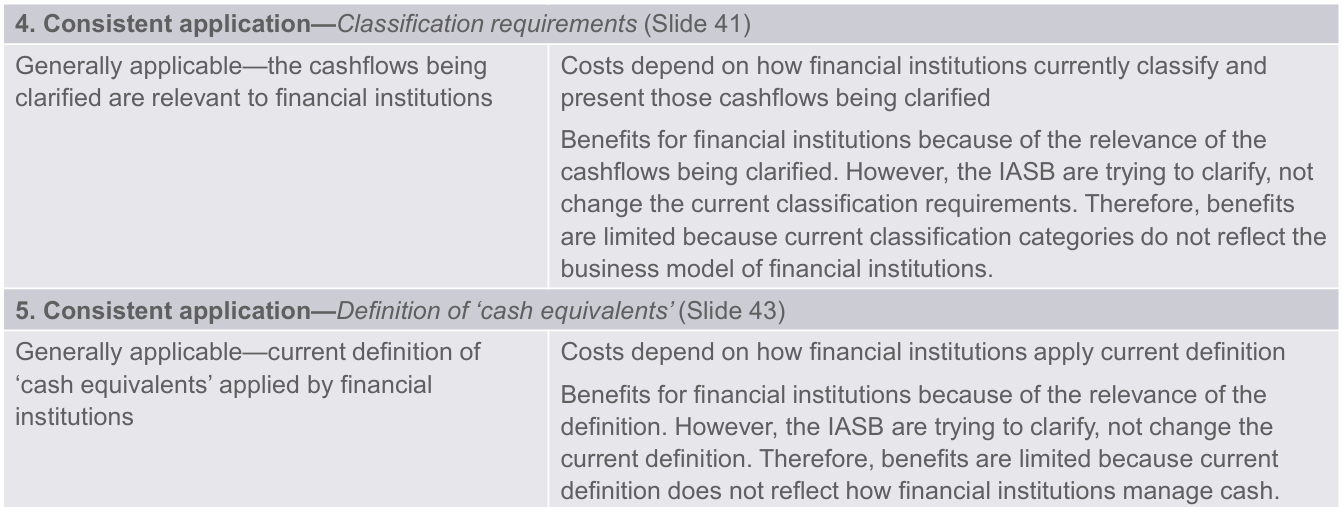
Group B: Further analysis needed to explore possible adaptation for financial institutions
Disclosing changes in liabilities from financing activities
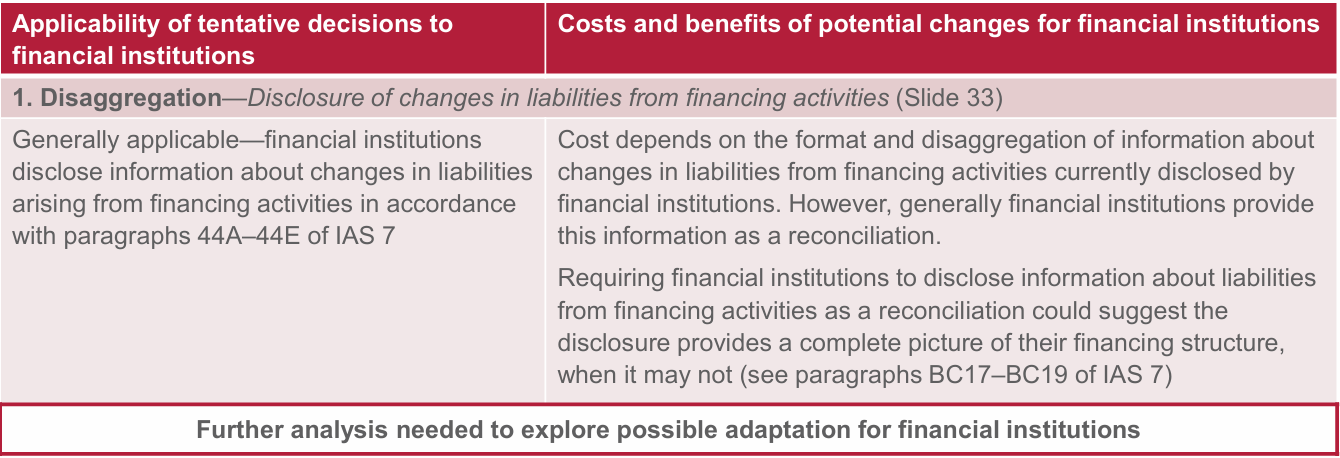
Disclosing non-cash changes in working capital assets and liabilities
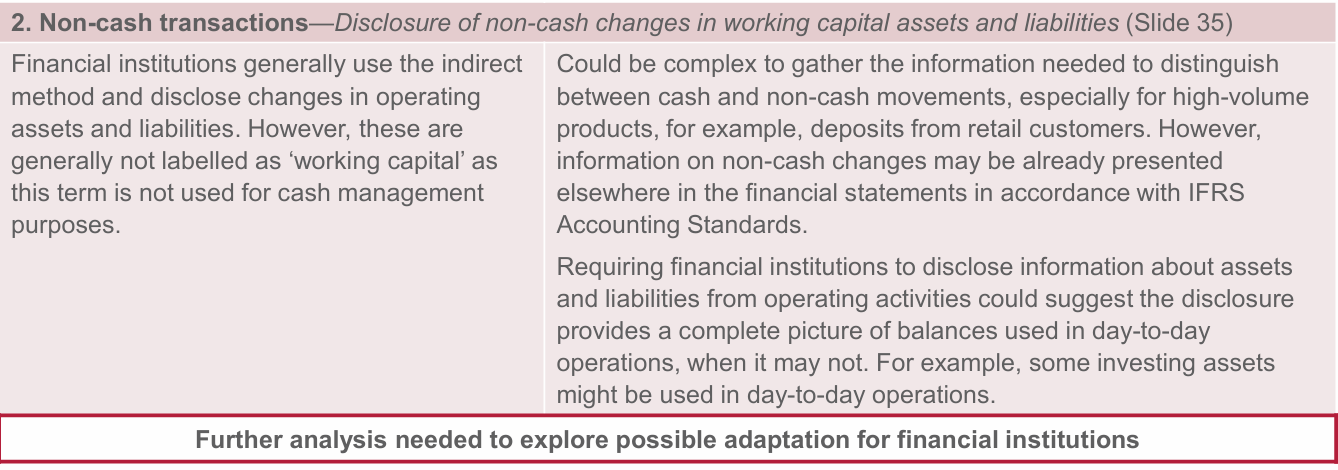
B10 ASAF members will be asked the following questions:
- “Do you agree with the staff's initial analysis of the applicability of the improvements for financial institutions and how they might be considered in the future?
- Do you have any suggestions of possible adaptations for financial institutions relating to:
- the disclosure of changes in liabilities from financing activities; and
- the disclosure of non-cash changes in working capital assets and liabilities?”
UKEB Key Messages
B11 Disaggregation: UKEB research suggested that disaggregation of information for users of financial statements for financial institutions is important, despite the limited usefulness of the statement of cash flows. As identified in the UKEB’s sixth research paper, should the IASB provide an exemption from preparing a full statement of cash flows, requirements should ensure that users receive transparent information that is useful to them, including dividends paid, capital issuance/repayment, share option exercises, interest paid/received, debt movements, and business acquisitions and disposals.
B12 MPMs: Whilst banks’ and insurers’ performance measures are generally defined by regulation, not management, there are varying degrees of reference to these regulatory metrics in the Alternative Performance Measures note in the financial statements. Similar requirements for MPMs in IFRS 18 could be extended to certain regulatory metrics so that there is a link between the financial statements and the regulatory metrics that users say are more useful than the statement of cash flows.
B13 Changes in financing liabilities and working capital movements: Mandating a reconciliation in the notes to the financial statements, would assist in simplifying the statement of cash flows, which providing useful information.
Response to ASAF questions
B14 The UKEB supports the IASB’s efforts to improve the usefulness of information provided to users whilst not significantly increasing the cost for preparers.
B15 We have not had the opportunity to test the IASB’s approach with stakeholders, but we support the direction of travel.
Question for the Board
- Do Board Members agree that the key messages to be provided to ASAF in relation to requirements for financial institutions should be supportive of the IASB’s general approach, subject to the need for the UKEB to consult stakeholders on any detailed proposals?
Exemptions, presentation and disclosure requirements
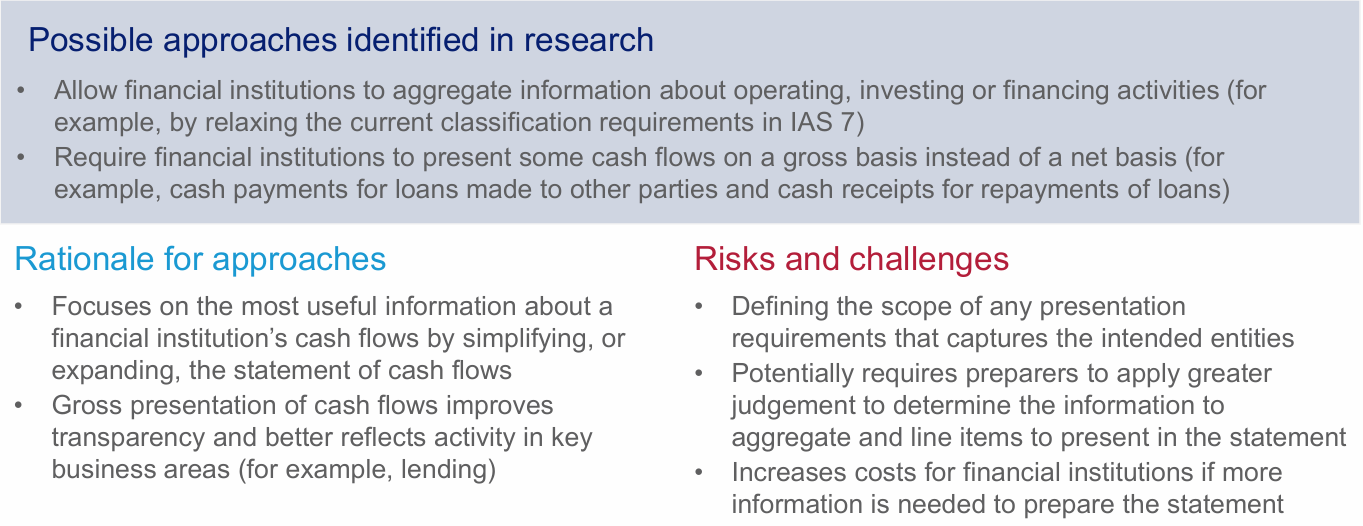
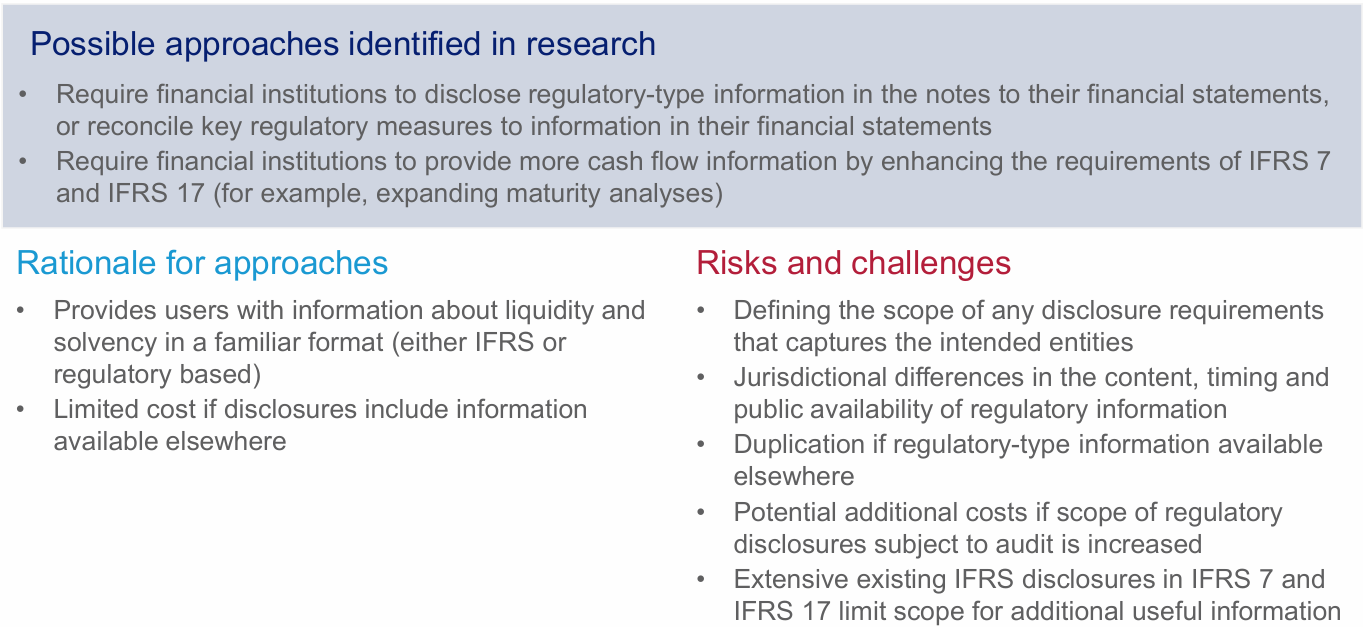
B16 IASB staff have identified possible exemptions, presentation and disclosure requirements for financial institutions, and explored the rationale for the different approaches based on research to date; and identified the key risks and challenges that would have to be considered.
B17 The IASB staff have identified possible approaches for scoping exemptions and requirements:
- Activity based – for example, specified main business activities used in IFRS 18 Presentation and Disclosure in Financial Statements for specific classification requirements.
- Threshold-based – for example, significance of liabilities from insurance contracts used in IFRS 4 Insurance Contracts for the scope of an exemption from applying IFRS 9 Financial Instruments (IFRS 17 superseded IFRS 4).
- Other – for example, a combination of activity, objective and relevant legislation used for the scope of IAS 30 Disclosures in the Financial Statements of Banks and Similar Financial Institutions (IFRS 7 superseded IAS 30).
Exemptions
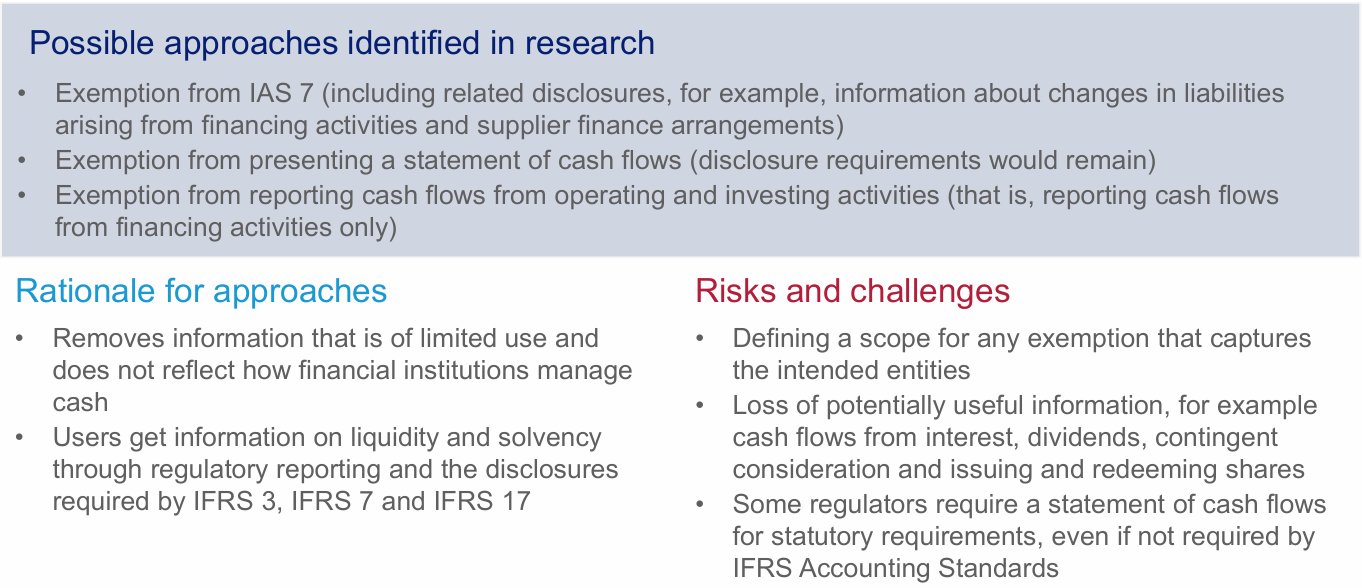
Presentation requirements
Supplementary disclosure requirements
B18 ASAF members will be asked the following questions:
- To help the IASB consider next steps, which of the approaches would be most beneficial or challenging in your jurisdiction?
- For each approach, do you have:
- Any suggestions about how to address or reduce the identified risks and challenges?
- Any suggestions or concerns about scoping an exemption or requirement (for example, regulation or legislation specific to your jurisdiction)?
UKEB Key Messages
B19 Exemption:
- UKEB research a simplified statement of cash flows being presented, given that some users find the statement of cash flows useful for financial institutions. However, items to be included in that simplified statement requires further field-testing.
- Therefore, we do not support an exemption from the requirements in IAS 7.44A to provide changes in financing liabilities, as it is understood from our research that users find this information useful.
B20 Presentation requirements. UKEB research supports:
- The possible approaches to allow financial institutions to aggregate information about operating, investing or financing activities (for example, by relaxing the current classification requirements in IAS 7), given that consistent application of classification was an issue identified as a preparer priority.
- Requiring financial institutions to present some cash flows on a gross basis instead of a net basis (for example, cash payments for loans made to other parties and cash receipts for repayments of loans), as users told us this information would be useful.
B21 Supplementary disclosure requirements. UKEB research supports:
- The IASB’s potential approach to require financial institutions to disclose regulatory-type information in the notes to their financial statements, and reconcile key regulatory measures to information in their financial statements.
- Requiring financial institutions to provide enhanced disclosures for example, expanding maturity analyses, including requiring a maturity analysis of cash and cash equivalents.
B22 Scoping: Whilst the IASB refers to the potential use of IFRS precedents for scoping, the UKEB’s sixth research paper, based on UKEB stakeholder feedback, shows stronger support for scoping based on regulatory requirements.
Response to ASAF questions
B23 The UKEB welcomes the IASB’s approach to seeking to provide solutions in relation to providing an exemption from a full statement of cash flows. However, given that the statement of cash flows does have some usefulness, a simplified statement is preferred to a full exemption.
B24 The UKEB is supportive of scoping different requirements for financial institutions and believes this would best be approached by referring to regulatory requirements. We acknowledge that there may not be a global baseline, however some regimes are more prevalent, such as the Basel framework and could form the basis for an international requirement.
Questions for the Board
- Do Board Members agree with the key message to be provided to ASAF regarding the IASB potential approach for exemption, presentation requirements and disclosure requirements?
- Do Board Members agree that the best approach to scoping the requirements should be based on regulatory requirements, such as the Basel framework?
Next steps
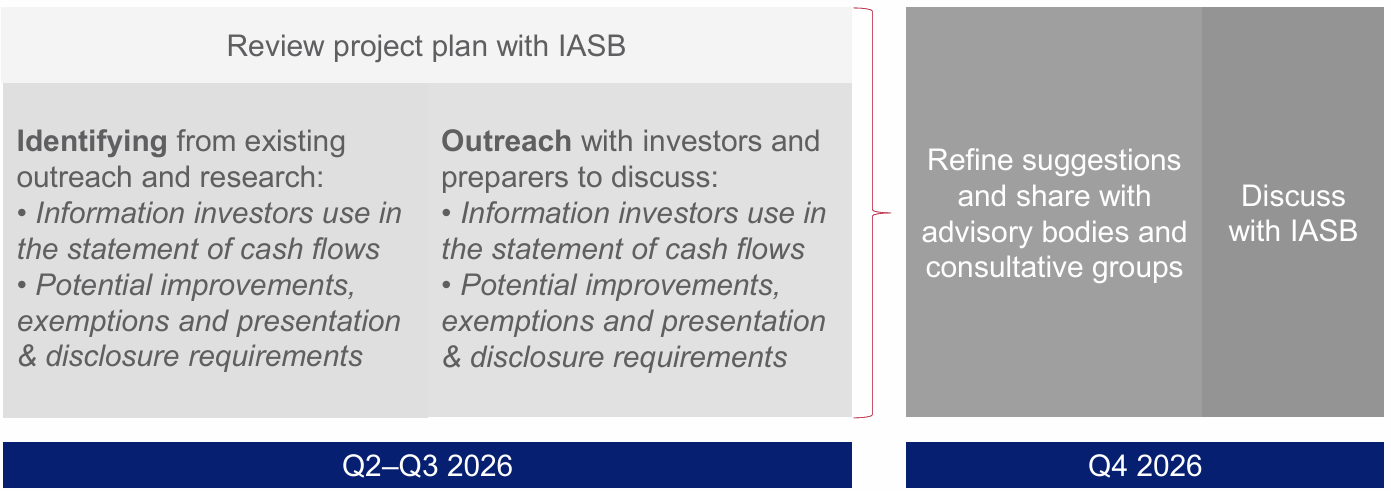
B25 The IASB’s plan for the remainder of 2025/2026 is:
B26 ASAF members will be asked the following question:
- Do you have any advice on industry groups or other stakeholders we should speak to as we carry out outreach on this topic during Q3 of 2026?
Question for the Board
- Do Board Members have any advice on industry groups or other stakeholders the IASB should speak to as they carry out outreach on this topic during Q3 of 2026?
Footnotes
-
See paragraph 9 of the UKEB 2026/27 Regulatory Strategy, year 2 of the UKEB 2025/28 three-year Regulatory Strategy. ↩
-
The meeting summary for the UKEB Investor Advisory Group meeting on 2 February 2026 can be found on the UKEB website here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/investor-advisory-group/. The meeting summary for the UKEB Accounting Firms and Institutes Advisory Group meeting on 10 March 2026 can be found here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/accounting-firms-and-institutes-advisory-group/. Details of the UKEB Financial Instruments Working Group can be found on the UKEB website here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/financial-instruments-working-group/. ↩
-
Reinsurers are insurers for insurance companies, enabling insurance companies to reduce their exposure to significant claims, by paying insurance premiums to reinsurers for the transfer of insurance liabilities. Reinsurers reinvest the insurance premiums they receive. By offsetting the risk of loss in insurance liabilities, insurance companies do not need to keep as much capital on hand to cover potential losses. Thus, they can invest the capital elsewhere to increase their revenues. ↩
-
Paragraphs 87 of the Staff Agenda Paper 20A for the IASB March 2025 meeting. ↩
-
For three examples of statements of cash flows disclosed by banks, see Lloyds Banking Group plc Annual Report and Accounts 2025, Consolidated Cash Flows Statement (page 217) and related note 40 (pages 295-296), Barclays PLC Annual Report 2025, Consolidated Cash Flows Statement (page 401) and HSBC Holdings plc Annual Report and Accounts 2025, Consolidated Cash Flows Statement (page 82). ↩
-
See paragraphs C170–C178 of the UKEB third research paper Statement of Cash Flows: UK User and Preparer Perspectives. ↩
-
IAS 1 is replaced by IFRS 18 effective 1 January 2027. These specific paragraphs are replaced by paragraphs 126–129 of IFRS 18 which require an entity to “disclose in the notes information that enables users of financial statements to evaluate the entity’s objectives, policies and processes for managing capital” (emphasis added). ↩
-
See Section 2.4 Grouping of Information of Effects Analysis–IFRS 18 Presentation and Disclosure in Financial Statements published by the IFRS Foundation in April 2024. ↩
-
See example: HSBC Pillar 3 disclosures at 31 December 2025. ↩
-
The Solvency and Financial Condition Report (‘SFCR’) is a regulatory report required by the Reporting and Group parts of the Prudential Regulation Authority (‘PRA’) Rulebook. This report, including the accompanying Quantitative Reporting Templates (‘QRTs’), sets out aspects of a Group’s business and performance, system of governance, risk profile, valuation methods used for solvency purposes and capital management. ↩
-
Risk-weighted assets (RWAs) are used to link the minimum amount of capital that banks must hold, with the risk profile of the bank’s lending activities (and other assets). ↩
-
The liquidity cover ratio (LCR) determines if a bank holds sufficient High Quality Liquid Assets to survive a short-term liquidity stress for a period of 30 days. Banks are required to maintain LCR at a minimum of 100%. ↩
-
Net stable funding ratio (NSFR) determines if a bank holds sufficient long-term stable funding to cover the duration of their long-term assets. Banks are required to maintain minimum NSFR of 100% on standalone as well as consolidated level at all times, as assessed based on regulatory guidelines (Annex III of the Bank of England’s Prudential Regulation Authority covers instructions for reporting on stable funding). ↩
-
The Taskforce on Disclosures about Expected Credit Losses (DECL), sponsored by the Financial Conduct Authority (FCA), the Financial Reporting Council (FRC) and the Prudential Regulation Authority (PRA), published guidance on a complete set of high quality IFRS 9 Expected Credit Loss accounting (ECL) disclosures. Its third report comprises a comparison of preparers’ and users’ assessments of adoption of Taskforce recommendations and good practice disclosure examples – see https://www.frc.org.uk/news-and-events/news/2022/09/taskforce-on-disclosures-about-expected-credit-losses-decl-updated-guidance/. The guidance is aimed primarily at the biggest UK-headquartered banks and building societies but is also likely to be relevant to a much wider group of preparers. ↩
-
IAS 1 Presentation of Financial Statements (paragraphs 134–136). ↩
-
These issues are explored in more detail in Accounting Miscellany blog: Cash flow statements for banks, insurance companies and investment funds (published 16 May 2025). ↩
-
The IASB issued “Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4)” on 12 September 2016. The amendments address concerns arising from implementing the financial instruments Standard, IFRS 9, before implementing IFRS 17 Insurance Contracts; the amendments also supplemented existing options in IFRS 4 to address those concerns. IFRS 9 Financial Instruments was issued on 24 July 2014 and became effective on 1 January 2018. IFRS 17 was issued on 18 May 2017 and became effective on 1 January 2023. ↩
-
IAS 30 Disclosures in the Financial Statements of Banks and Similar Financial Institutions was effective 1 January 1991 and superseded by IFRS 7 Financial Instruments: Disclosures, effective 1 Jan 2007. ↩
-
See slides 6–7 of September 2016 IFRS Project Summary and Feedback Statement Applying IFRS 9 Financial Instruments with IFRS 4 Insurance Contracts (Amendments to IFRS 4). A company’s activities are predominantly connected with insurance, if, and only if: (a) the amount of its insurance liabilities is significant compared with its total amount of liabilities; and (b) the percentage of its liabilities connected with insurance relative to its total amount of liabilities is: (i) greater than 90 per cent; or (ii) less than or equal to 90 per cent but greater than 80 per cent, and the company does not engage in a significant activity unconnected with insurance. Liabilities connected with insurance include investment contracts measured at FVPL, and liabilities that arise because the insurer issues, or fulfils obligations arising from, these contracts (such as deferred tax liabilities arising on its insurance contracts). ↩
-
Both the PRA and the FCA apply standards that generally either anticipate or go beyond requirements established by global or European Union (EU) standards, whether in relation to capital, leverage and liquidity, resolvability and resolution or matters of conduct. The UK is in the process of reviewing, repealing and, where relevant, replacing the EU legislation that was on shored into UK law following the UK’s departure from the EU (known as “assimilated law”). The Financial Services and Markets Act 2023 (FSMA 2023) established a framework for the revocation of assimilated law relating to financial services. However, the Government is not expected to revoke assimilated law relating to financial services unless the FCA and/or PRA have drafted and consulted on rules in the relevant areas, where it is appropriate that the provisions are replaced. There is a significant volume of assimilated law for the UK Government to repeal and replace, so this process remains ongoing and the regulatory landscape continues to develop. There is potential for an increase in regulatory implementation costs to adapt systems and controls, as a result of these developments, although areas of divergence from assimilated law have been limited to date. [see pages 342–346 of the Barclays PLC Annual Report 2025]. ↩
-
An independent external audit of the SFCR is required, gathering sufficient appropriate evidence to provide an overall reasonable assurance opinion that the public disclosure in scope complies in all material respects with PRA rules and Solvency II Regulations. ↩↩
-
See https://www.bankofengland.co.uk/prudential-regulation/regulatory-reporting/regulatory-reporting-banking-sector/banks-building-societies-and-investment-firms ↩
-
Market stress events such as the March 2020 ‘dash for cash’ at the onset of the Covid-19 pandemic, and the September 2022 liability-driven investment (LDI) crisis. ↩
-
See https://www.bankofengland.co.uk/prudential-regulation/regulatory-reporting/regulatory-reporting-insurance-sector ↩
-
See https://www.investopedia.com/terms/s/solvency-capital-requirement.asp. The EU Solvency II directive designates three pillars or tiers for capital requirements. Pillar I covers the quantitative requirements; that is, the amount of capital an insurer should hold. Pillar II establishes requirements for the governance, effective supervision, and risk management of insurance companies. Pillar III details disclosure and transparency requirements. Solvency Capital Requirements (SCR) are critical to maintaining the financial stability of insurance and reinsurance companies within the EU. As a result, insurance companies are required to manage and disclose risks accurately, fostering reliability and trust in the sector. ↩
-
In the UK, the EU Solvency II regime was adapted by the PRA’s 2024 reforms and the phased implementation of ‘Solvency UK’ was completed on 31 December 2024, following the UK’s departure from the EU. Solvency UK is referenced except when referring to financial metrics, when Solvency II is referred to in line with the current PRA guidance and consistent with the prudential regime in the PRA policy manual. Solvency UK was designed to make the UK insurance market more competitive, dynamic, and capable of supporting domestic investment, while still ensuring financial stability and policyholder security under the PRA objectives. See https://www.pwc.co.uk/financial-services/assets/pdf/pra-finalises-new-solvency-uk-framework.pdf ↩
-
See Appendix A of the IASB Staff Agenda Paper 20 for the May 2026 meeting. ↩
-
UKEB Board members have received updates on the tentative decisions to date in the following meetings. See UKEB project webpage for links to papers: https://www.endorsement-board.uk/projects/statement-of-cash-flows-and-related-matters/ ↩
-
The IASB held meetings with its Financial Instruments Consultative Group in May 2026 and a joint FASB–IASB education meeting in June 2026. A summary of the meetings can be found on slide 9 of Staff paper 4 of the July 2026 ASAF meeting. ↩