Updated Project Initiation Plan - Risk Mitigation Accounting Proposed amendments to IFRS 9 and IFRS 7
Purpose
A1. This paper sets out the plan to influence the development of the proposed amendments to IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures included in the International Accounting Standards Board’s (IASB) Exposure Draft (ED) Risk Mitigation Accounting (Proposed amendments to IFRS 9 and IFRS 7). The ED was published on 3 December 2025 with the consultation period originally ending on 31 July 2026 and subsequently extended1 to 30 November 2026.
Background
A2. The implementation of IFRS 9 Financial Instruments aimed to introduce improved hedge accounting requirements. However, this did not provide a solution for complex risk management situations where risks are managed dynamically. In such cases entities were permitted to continue applying IAS 39 Financial Instruments: Recognition and Measurement2. The IASB has noted that entities continue to find it challenging to account for their dynamic risk management activities in this manner, as the requirements are not designed for such situations, and the constraints make it difficult for entities to faithfully represent the economic effect of such risk management activities3.
A3. The ED scope is limited to interest rate repricing risk4, in instances where entities meet the criteria to demonstrate that this risk is being managed dynamically. The ED aims to provide a more faithful representation of the entity’s economic position for such risk management activities.
A4. Consistent with the existing hedge accounting requirements of IFRS 9, the proposed requirements are voluntary. The IASB proposes to withdraw IAS 39 when the proposed amendments are available for use.
Summary of Proposed Changes
A5. A summary of the proposed changes can be found in the IASB’s snapshot document.
Project Plan
Proportionality Assessment
Significance and Size
Entities Affected by the Proposals
A6. The proposals affect entities that manage their interest rate repricing risk dynamically on a net portfolio basis. The scope of the proposals includes all entities that manage risk in this way, and that meet the qualifying criteria. Given the nature of interest rate repricing risk, we expect this will primarily affect the banking sector. However, some insurance entities, non-bank financial services firms and corporates with sophisticated treasury practices may also be within scope of the proposals.
Sector size
A7. In 2022, the UK financial system’s assets totalled approximately £27 trillion, of which £14 trillion was held by banks (excluding the Bank of England) and £2 trillion was held by insurance companies. As context, in the same year, the UK’s gross domestic product was approximately £2.5 trillion5.
A8. The UK is home to three global systemically important banks6, and a further four domestic systemically important banks7. Additionally, the hedging of interest rate repricing risk is widely used across the UK banking sector.
A9. 16% of the FTSE 100 market cap is represented by the banking sector8.
A10. We therefore conclude that this sector is significant to the UK economy.
Complexity
A11. Hedging strategies can be complex, and the associated accounting requirements reflect this. Further, the proposed requirements are not just restricted to the finance function; they will also require significant input from the risk management and treasury functions.
A12. The UKEB understands that dynamic risk management strategies vary between entities, reflecting the nature of their portfolios and internal procedures. Accordingly, the proposals may affect different entities in different ways. The UKEB therefore expects this project to have a high degree of complexity.
Expected Timeline / Urgency
A13. The ED was published on 3 December 2025 with the consultation period originally ending 31 July 2026 and subsequently extended9 to 30 November 2026.
A14. The IASB has also published a request for fieldwork with deadlines for preliminary and final field test results by 31 July 2026 and 30 November 2026, respectively. The field test results are expected to provide important insight into the proposals, as the requirements are complex and affect activities across organisations, including finance, risk management and treasury functions.
Expected Interest / Sensitivity
A15. The UKEB does not expect wide general interest given the requirements are primarily expected to have a material effect on the financial services sector.
A16. However, there may be significant interest from stakeholders of affected entities. In addition, the primary focus of this ED, the banking industry, is a regulated industry in the UK and therefore the project is likely to be of interest to the relevant UK regulators.
Feedback on the Proposals from Initial Outreach
A17. Feedback from initial outreach with stakeholders suggests that there are mixed views on a number of conceptual and practical aspects of the proposed amendments. Given the complexity of this project, it is too early to conclude on the effectiveness of the proposals at this stage.
A18. Stakeholders have also noted the importance of effective hedge accounting requirements as this ensures:
- the financial statements closely represent the underlying economic position of the entity;
- volatility is appropriately reflected in the financial statements; and
- stable and predictable capital levels reflecting the underlying economic position can be demonstrated when interest rates move, supporting market confidence and ongoing lending to the UK market.
Connectivity
A19. The UKEB has not been made aware of any significant connectivity implications for this project.
Recommended UKEB Project Scope
A20. Based on the proportionality assessment above, the UKEB regards this as a ‘Significant’ project, and the scope and approach described in this document reflects this.
A21. In addition, the UKEB also decided on the following additional course of action:
- Continuing to engage with relevant UK stakeholders to obtain any subsequent feedback on the outcome of their completed field tests.
- The Board to consider a summary of any additional feedback gathered in early 2027.
- The Board may, at that time, consider whether to take further steps in light of any new information that may have been received. Such actions may, for example, include a further letter to the IASB incorporating the feedback received from the field tests.
Project - Key Activities
| Key Activities | Due Process Handbook |
|---|---|
| Board Education Sessions | 4.10b Optional |
| Creation of a Project Initiation Plan (this document) | 5.4-5.8 Mandatory |
Desk-based research to support the proportionality assessment including:
|
5.9 Optional |
Publication of a Draft Comment Letter for public consultation
|
5.13-5.17 Generally mandatory |
Stakeholder outreach
|
5.10-5.12 Mandatory |
| Final Comment Letter A final comment letter will be created for Board approval, submission to the IASB, and publication on the UKEB website. |
5.18 Mandatory |
| Project Closure A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
5.19-5.26 Mandatory |
Resources Allocated
A22. To undertake the activities described in this project plan, within the specified timelines, a project team consisting of 2 Project Directors (1.2 in total), with oversight from a Senior Project Director, should be sufficient. The required resources are allowed for in the UKEB Regulatory Strategy.
A23. In addition, the project team will consider whether input from the economics team will be needed. Factors considered in assigning this resource may include the need to ascertain the prevalence of transactions, whether the proposed accounting appropriately reflects the underlying economics of transactions for UK stakeholders and consideration of related economic effects.
Setting up an Ad-hoc Advisory Body
A24. Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
A25. As appropriate, these advisory and working groups may be supplemented by inviting colleagues from their broader businesses to facilitate roundtables benefiting from wider perspectives.
Project Timeline
A26. The proposed high-level timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses. The UKEB’s timeline for this project needs to balance:
- publishing the Draft Comment Letter (DCL) early to raise awareness about the project and encourage engagement with stakeholders; and
- allowing more time for the UKEB and stakeholders to identify matters which could be included in the DCL.
A27. The UKEB expects to:
- have a preliminary discussion on the proposed amendments in February 2026;
- consider a proposed DCL in March 2026;
- depending on the outcome of the discussion at its March meeting, publish the DCL following the March or April 2026 Board meetings;
- submit a final comment letter by the IASB deadline; and
- consider whether to take further steps in light of any new information that may have been received subsequent to the submission of the final comment letter to the IASB (see paragraph A21 above).
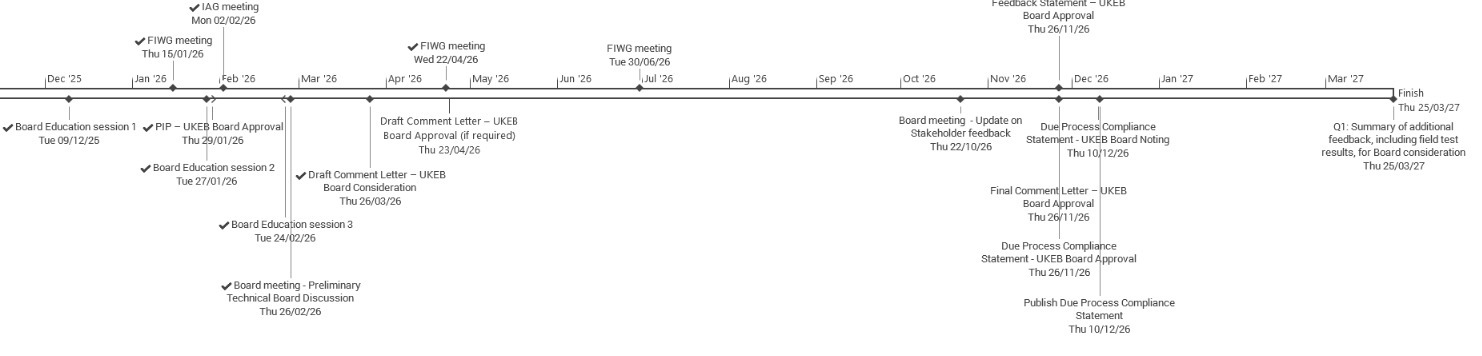
| Date / Period | Activity / Milestone |
|---|---|
| 9 December 2025 | Board Education Session 1: Introduction to banks and risk management |
| January 2026 |
|
| February 2026 |
|
| 26 March 2026 | Draft Comment Letter for Board consideration* |
| 23 April 2026 | Draft Comment Letter for Board approval* |
| April – 21 October 2026 | Estimated DCL consultation period (approx. 175 days) |
| 22 October 2026 | Technical Paper: Update on stakeholder feedback (incl. verbal update on Comment Letters received) |
| 26 November 2026 | Board review of Final Comment Letter, Feedback Statement, draft Due Process Compliance Statement |
| November 2026 | Final Comment Letter submitted to IASB (deadline 30 November 2026) |
| 10 December 2026 | Due Process Compliance Statement for noting. |
| Q1 2027 | Summary of additional feedback if any, including field test results, for Board consideration |
Project Timeline Diagram
A28. The diagram below is a graphical view of the key milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
Footnotes
-
On 19 May 2026, the IASB decided to extend the comment period on its Exposure Draft from 31 July 2026 to 30 November 2026. The extension aligns the IASB’s deadline for comment letters with the deadline for the submission of final fieldwork results. ↩
-
See paragraphs 6.1.3 and 7.2.21 of IFRS 9. ↩
-
This is noted by the IASB in paragraph IN7 of the ED. ↩
-
As noted in paragraph IN1 of the ED, “[f]or purposes of risk mitigation accounting, repricing risk is a type of interest rate risk that arises from differences in the timing and amount of financial instruments that reprice to benchmark interest rates”. ↩
-
See section 1.2 of the Commons Library’s publication in November 2024 Financial Services in the UK. ↩
-
See the 2025 List of Global Systematically Important Banks identified by the Financial Stability Board in consultation with the Basel Committee on Banking Supervision and national authorities. ↩
-
See the List of other systematically important institutions for 2024 identified by the Prudential Regulation Authority. The four additional domestic systematically important banks are Lloyds Banking Group Plc, Nationwide Building Society, NatWest Group Plc and Santander UK Group Holdings Plc. ↩
-
This is calculated from Reuters data as of 30 December 2025 based on entities reporting under IFRS Accounting Standards. ↩
-
On 19 May 2026, the IASB decided to extend the comment period on its Exposure Draft from 31 July 2026 to 30 November 2026. The extension aligns the IASB’s deadline for comment letters with the deadline for the submission of final fieldwork results. ↩
-
This included a presentation on this project from the IASB staff. See the November 2023 FIWG meeting summary for more details. ↩
-
This included presentations on this project from the IASB staff and from UK banking and insurance industry perspectives. See the November 2024 FIWG meeting summary for more details. ↩