ECA - IFRS 19 Subsidiaries without Public Accountability Disclosures
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
©2026 All Rights Reserved
- 1. Executive Summary
- 2. Introduction
- 3. Main requirements in IFRS 19 and accounting impact
- Potential accounting impact of IFRS 19 in the UK
- UK accounting frameworks
- Expected use of reduced disclosure standards in the UK
- Table 3: A comparison of scope of IFRS 19 versus FRS 101
- Assessment of the specific key aspects of reductions in disclosure requirements in IFRS 19 against the technical accounting criteria
- Transition requirements—first-time adoption and comparative information
- Business combinations
- Financial instruments
- Interests in other entities
- Statement of cash flows (presentation requirements)
- Basis of preparation
- Income taxes
- Related party transactions
- Impairment of assets
- Assessment against the endorsement criteria
- Impairment of assets
- Assessment against the endorsement criteria
- Overall conclusion on whether IFRS 19 meets the technical accounting criteria
- 5. UK long term public good assessment
- 6 True and fair view assessment
- 7 Is IFRS 19 likely to lead to a significant change in accounting practice?
- Introduction
- UK statutory requirements
- Due Process Handbook requirements
- What constitutes a significant change in accounting practice?
- Approach to the assessment
- The number of entities that will be affected by IFRS 19
- Potential impact on entities applying the requirements in IFRS 19
- Overall conclusion
- Appendix A: Glossary
- Appendix B: UK statutory requirements for adoption and the approach to the endorsement criteria assessment
- Introduction
- UK statutory requirements
- Approach to the endorsement criteria
- Technical accounting criteria: Relevance, Reliability, Understandability and Comparability
- Whether IFRS 19 is likely to be conducive to the long term public good in the UK
- True and fair view assessment
- Does IFRS 19 lead to a significant change in accounting practice?
- Appendix C: Overarching differences between IFRS 19 and FRS 101
- Appendix D: Evidence about the costs and benefits of IFRS 19
- Contact Us
1. Executive Summary
Background
1.1IFRS 19 Subsidiaries without Public Accountability: Disclosures was issued by the International Accounting Standards Board (IASB) in May 2024. This Endorsement Criteria Assessment (ECA) presents the UKEB's assessment of whether the Standard, as subsequently amended, meets the UK's statutory requirements for adoption of IFRS.
1.2This assessment addresses the endorsement criteria set out in Regulation 7 of Statutory Instrument (SI) 2019/685 (the Regulations). These endorsement criteria are described in more detail in Appendix B. Section 4, 5 and 6 discuss whether these criteria are met.
1.3The ECA also addresses, in Section 7 whether IFRS 19 is likely to lead to a significant change in accounting practice, as set out in Regulation 11 of Sl 2019/685.
1.4The UKEB conducted targeted outreach activities to collect evidence to assess whether IFRS 19 meets the technical and the long term public good assessment criteria for endorsement.
IFRS 19 Subsidiaries without Public Accountability: Disclosures
1.5A summary of the requirements of IFRS 19 is presented in Section 3 of this ECA. IFRS 19 is a reduced disclosure IFRS Accounting Standard. It has an effective date of 1 January 2027, with earlier application permitted.
Technical accounting criteria
1.6The assessment of IFRS 19 against the technical accounting criteria in Section 4 of this ECA considers the Standard, together with all the amendments, to date. Given that IFRS 19 is a voluntary, disclosure-only standard and taking a proportionate approach, only key aspects of reductions in disclosures were analysed against the technical accounting criteria (an 'exceptions-based approach').
1.7In conducting this overall assessment against the technical accounting criteria, the UKEB is required to adopt an absolute, rather than a relative, approach.
1.8Overall, the UKEB concluded that IFRS 19 meets the technical accounting criteria.
UK long term public good
1.9The UKEB's analysis of whether IFRS 19 is likely to be conducive to the long term public good in the UK is presented in Section 5 of this ECA.
1.10The assessment concludes that IFRS 19 will lead to improvements in the quality of financial reporting in the UK. In particular, it will enable groups using IFRS with eligible subsidiaries to apply consistent accounting policies when preparing financial statements throughout the group.
1.11The cost benefit analysis (CBA) takes a qualitative approach as there will be substantial variation in the nature and extent of the costs and benefits of IFRS 19 for entities, depending on their specific circumstances. However, as IFRS 19 is a voluntary standard, preparers will only apply it if they assess that benefits will outweigh implementation costs.
1.12Engagement with users suggested that the reduced disclosures are tailored towards their needs and carry a limited risk that they will lose decision-useful information.
1.13IFRS 19 is not expected to lead to wider economic effects that are detrimental to the UK economy, including on economic growth. An analysis of a non-adoption counterfactual illustrates that not adopting IFRS 19 for use in the UK would have a potentially detrimental effect on the UK economy.
1.14Overall, the UKEB concluded that the use of IFRS 19 is likely to be conducive to the long term public good in the UK.
True and fair view principle
1.15Section 6 of the ECA addresses whether IFRS 19 is not contrary to the true and fair view principle for both individual and consolidated accounts set out in Regulation 7(1)(a) of SI 2019/685 (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts, as a whole.
1.16The assessment has not identified any IFRS 19 requirement that would prevent individual or consolidated accounts prepared using IFRS 19 from giving a true and fair view of the entity's assets, liabilities, financial position and profit or loss. Consequently, the UKEB concluded that IFRS 19 is not contrary to the true and fair view principle set out in Regulation 7(1)(a) of SI 2019/685.
Is IFRS 19 likely to lead to a significant change in accounting practice?
1.17In Section 7 of the ECA, the UKEB considers that IFRS 19 will not significantly change the way eligible subsidiaries communicate information in the primary financial statements and the notes. The Standard does not change the recognition, measurement and presentation requirements in IFRS Accounting Standards and offers limited reductions in disclosures.
1.18As a result, it concludes that IFRS 19 is not likely to lead to a significant change in accounting practice and does not meet the criteria for a post-implementation review (PIR) under Regulation 11 in SI 2019/685.
Legal Context
1.19IFRS 19 is a reduced disclosure Standard, which is only available to eligible subsidiaries preparing their accounts under IFRS Accounting Standards. The IASB sets out the scope of the Standard1, by reference to its definition of "public accountability”2.
1.20The UK Government sets the scope of reporting requirements for UK-registered entities under the Companies Act 2006 (the Act). Part 16 of the Act defines "public interest entity"3 and “public interest company”4 in relation to Audit requirements. The definitions are not relevant in the context of reporting under UK-adopted international accounting standards.
1.21The Board considered whether the difference, between the definition in the Standard and the definitions in the Act, was of relevance or concern. The Board's view is that a company, which is either required or permitted to apply UK-adopted international accounting standards, would be permitted to apply IFRS 19, if it falls within the scope set out in the Standard. Therefore, this issue is not deemed relevant to the UKEB's endorsement assessment of IFRS 19. The Companies Act public interest considerations would also continue to apply, as relevant.
2. Introduction
Purpose
2.1The UK Endorsement Board (UKEB) is the UK National Standard Setter for IFRS5, responsible for the endorsement and adoption of international accounting standards, for use in the UK.
2.2The purpose of this Endorsement Criteria Assessment (ECA) is to determine whether IFRS 19 Subsidiaries without Public Accountability: Disclosures (the Standard) issued by the International Accounting Standards Board (IASB) in May 2024 and as amended subsequently6, meets the UK's statutory requirements for adoption as set out in Regulation 7 of Statutory Instrument 2019/6857 (SI 2019/685).
2.3The Standard has an effective date of 1 January 2027 with earlier application permitted. If an entity applies IFRS 19 for an earlier period, it shall disclose that fact in the notes.
2.4The UKEB influenced the development of IFRS 19. This included submitting Final Comment Letters on:
- a)23 February 20228, in response to the IASB's Exposure Draft ED/2021/7 Subsidiaries without Public Accountability: Disclosures9 (ED); and
- b)28 November 202410, in response to the IASB's Exposure Draft ED/2024/5 Amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures (the 'catch-up' ED)11.
Background to the Standard
2.5Section 3 of this ECA provides a brief description of the main requirements in the Standard, and a high-level analysis of the potential accounting impact in the UK.
Scope of the adoption assessment
2.6IFRS 19 is a voluntary international reduced disclosure standard for the preparation of eligible subsidiaries' financial statements, as part of IFRS Accounting Standards.
2.7For the purposes of this adoption assessment, any reference to IFRS 19 or the Standard means the Standard as issued in May 2024, including the consequential amendments and the Amendments, i.e. the amended Standard. The following are relevant:
- a)The IASB issued consequential amendments to IFRS 19 when issuing the following amendments to IFRS Accounting Standards:
- Amendments to IFRS 9 and IFRS 7–Amendments to the Classification and Measurement of Financial Instruments, issued in May 2024; and
- Amendments to IFRS 9 and IFRS 7–Contracts Referencing Nature-dependent Electricity, issued in December 2024.
- b)In addition, in August 2025, the IASB issued Amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures (the 'Amendments') which included limited reductions to disclosure requirements for new or amended IFRS Accounting Standards issued between 28 February 2021 and May 2024.
- c)IFRS 19 contains reduced disclosure requirements for IFRS 14 Regulatory Deferral Accounts. IFRS 14 is not adopted in the UK. Therefore, the reduced disclosure requirements set out under the subheading 'IFRS 14 Regulatory Deferral Accounts' in the Standard have not been included in the scope of this adoption assessment.
2.8UK-adopted international accounting standards comprise only the mandatory sections of standards.12 The Bases for Conclusions, Implementation Guidance, and Illustrative Examples of the IFRS Accounting Standards are not adopted by the UKEB and amendments to these non-mandatory sections are not considered in this ECA. 13
Structure of the assessment
2.9The UKEB's analysis is presented in the following sections:
- a)Appendix B describes UK statutory requirements for the adoption of new or amended international accounting standards and the approach to the endorsement criteria assessment.
- b)Section 3 outlines:
- the main requirements in the Standard;
- entities in scope of the Standard;
- users of subsidiaries' financial statements and their information needs; and
- the potential accounting impact of IFRS 19 in the UK.
- c)Sections 2-4 discuss whether IFRS 19 meets the requirements for adoption described in Appendix B. More specifically:
- Section 4: addresses whether IFRS 19 meets the technical accounting criteria and explains the approach to the assessment of these criteria.
- Section 5: analyses whether IFRS 19 is likely to be conducive to the long term public good in the UK.
- Section 6: considers whether IFRS 19 is not contrary to the true and fair view principle for individual and consolidated accounts.
- d)Section 7 considers whether IFRS 19 is likely to lead to a significant change in accounting practice.
Adoption decision
2.10Sections 4, 5 and 6 set out how IFRS 19 meets the requirements for adoption described in Appendix B of this document.
2.11On the basis of these assessments, the UKEB concludes that IFRS 19 meets the statutory endorsement criteria. Therefore, the UKEB is of the view that it will adopt IFRS 19 for use in the UK.
3. Main requirements in IFRS 19 and accounting impact
3.1This section outlines:
- a)the main requirements in the Standard;
- b)entities in scope of the Standard;
- c)users of subsidiaries' financial statements and their information needs; and
- d)the potential accounting impact of IFRS 19 in the UK.
Main requirements in IFRS 19
Overview of the Standard
3.2IFRS 19 is a reduced disclosure IFRS Accounting Standard. It was developed as part of the IASB's Disclosure Initiative – a set of projects aimed at improving the effectiveness of financial statement disclosures. The IASB developed IFRS 19 in response to demand from stakeholders, particularly preparers, who requested that eligible subsidiaries should be permitted to apply the recognition, measurement and presentation requirements of IFRS Accounting Standards but with reduced disclosure requirements.
3.3IFRS 19 aims to simplify the preparation of financial statements for eligible subsidiaries by reducing the required disclosures in their financial statements, compared with disclosure requirements in full IFRS Accounting Standards.
3.4The objective of IFRS 19 as stated in paragraph 1 of the Standard is as follows:
"IFRS 19 Subsidiaries without Public Accountability: Disclosures specifies the disclosure requirements an entity is permitted to apply instead of the disclosure requirements in other IFRS Accounting Standards.”
3.5IFRS 19 does not change the recognition, measurement or presentation requirements in other IFRS Accounting Standards. These must still be followed by entities applying IFRS 19.
3.6To illustrate the approach IFRS 19 takes, in reporting items of inventory, an eligible subsidiary applies:
- e)the recognition, measurement and presentation requirements in IAS 2 Inventories; and
- f)the disclosure requirements in IFRS 19, under the subheading 'IAS 2 Inventories'.
3.7Paragraph 6 of IFRS 19 requires entities to provide additional disclosures if they consider that users would not be able to understand a subsidiary's financial position, financial performance and cash flows from the disclosures provided under IFRS 19.
Statement of compliance
3.8IFRS 19 is part of IFRS Accounting Standards. An eligible subsidiary which applies IFRS 19 asserts its compliance with IFRS Accounting Standards and states that it has applied IFRS 19.
Comparative information
3.9IFRS 19 allows eligible subsidiaries that elect to apply the Standard in one reporting period to later revoke that prior election. Furthermore, an entity is not prohibited from electing to apply IFRS 19 again, after a previous revocation of an election to apply the Standard.
3.10Table 1 below summarises the requirements in IFRS 19 for comparative information.
Table 1: IFRS 19 requirements on comparative information
| Comparative information requirements |
|---|
| IFRS 19 applied to current period, full IFRS applied to previous period |
| Comparative information (that is, information for the preceding period) is required for all amounts reported in the current period's financial statements i.e. fewer disclosures in the current period under IFRS 19, unless IFRS 19 or another IFRS Accounting Standard permits or requires otherwise. |
| Full IFRS applied to current period, IFRS 19 was applied to previous period |
| Comparative information is required, in respect of the preceding period, for all amounts reported in the current period's financial statements i.e. more disclosures in the current period under full IFRS Accounting Standards, unless another IFRS Accounting Standard permits or requires otherwise. |
Entities in scope of the Standard
Entities eligible to apply the Standard
3.11IFRS 19 is a voluntary Standard. Paragraph 7 of IFRS 19 sets out the eligibility criteria that an entity is required to satisfy to apply the Standard:
"An entity may elect to apply this Standard in its consolidated, separate or individual financial statements if, and only if, at the end of the reporting period:
- it is a subsidiary;
- it does not have public accountability [....]; and
- it has an ultimate or intermediate parent that produces consolidated financial statements available for public use that comply with IFRS Accounting Standards.”
3.12Paragraph 11 of IFRS 19 defines public accountability14:
"An entity has public accountability if:
- its debt or equity instruments are traded in a public market or it is in the process of issuing such instruments for trading in a public market (a domestic or foreign stock exchange or an over-the-counter market, including local and regional markets); or
- it holds assets in a fiduciary capacity for a broad group of outsiders as one of its primary businesses (for example, banks, credit unions, insurance companies, securities brokers/dealers, mutual funds and investment banks often meet this second criterion)."
Eligible UK entities in scope of the Standard
3.13In the UK, IFRS 19 could be adopted by:
- a)UK-registered subsidiaries of UK group companies; and
- b)UK-registered subsidiaries of group companies with overseas parents.
3.14In addition, UK group companies with overseas subsidiaries may also choose to apply IFRS 19 when preparing accounts for their overseas subsidiaries, to the extent that the standard is available for use in the relevant jurisdictions.
3.15Current estimates put the potential number of subsidiaries owned by entities listed on the London Stock Exchange (LSE), as of January 2025, eligible to apply IFRS 19, using the scope and definitions of the Standard15 at approximately 78,000. It includes approximately 21,000 subsidiaries domiciled in the UK and 57,000 subsidiaries domiciled abroad16 17.
3.16UK law permits unlisted UK-registered companies the option to use UK-adopted international accounting standards, and approximately 14,000 such companies take up this option18. It is acknowledged that subsidiaries of unlisted groups (which do not have public accountability) are in the scope of IFRS 19 and may elect to apply the Standard if they satisfy the eligibility criteria in IFRS 1919. However, due to lack of data availability, it was not possible to estimate the number of eligible subsidiaries owned by private or foreign-domiciled groups.
Users of subsidiaries' financial statements and their information needs
3.17Financial statements of subsidiaries without public accountability typically have few users and do not tend to attract a lot of investor interest. Typically, the main users are internal, such as parent entities. The few external users are primarily providers of credit such as bank lending departments. Other external users may include non-controlling shareholders and suppliers 20.
3.18Typically, internal users of subsidiaries' financial statements can request additional information directly from management. Therefore, they are unlikely to rely solely on publicly available financial statements to satisfy their information needs. Whilst some external users, e.g. bank lending departments can also request additional information, it is not available to the other external users such as non-controlling shareholders.
3.19Table 2 below summarises non-controlling interests (NCI) data obtained from the 2023 consolidated financial statements of UK listed entities:
Table 2: Prevalence of non-controlling interests (NCI) in UK listed entities21
| Dimension | Observation |
|---|---|
| Total book value of NCI | £40bn Approx |
| Proportion of aggregate net assets represented by NCI | 2.5% Approx |
| Proportion of UK listed entities reporting NCI in equity | 26% Approx |
Source: UKEB calculations based on Reuters-Eikon data. Figures are consolidated and do not comprise intercompany transactions, meaning that the sum of NCI for individual subsidiaries is likely to be higher.
3.20In addition, the proportion of FTSE 100 listed entities reporting NCI was much higher than that for FTSE 250 listed entities, indicating that NCI are concentrated among larger companies by market capitalisation. More specifically, fewer than 10 entities account for approximately 80% of the total book value of NCI reported by all listed entities. NCI are most commonly reported by entities in the energy and basic materials industry sectors.22
3.21Outreach with preparers suggests that the main external user group of their subsidiaries' financial statements is providers of credit such as bank lending departments. These lenders are particularly interested in the subsidiaries' financial statements when external borrowings are not supported by parent or intra-group guarantees.
3.22Providers of credit to eligible subsidiaries are likely to be focused on information about the liquidity and solvency of the eligible subsidiary, consistent with the principles for reducing disclosures in IFRS 19.23 Outreach with bank lending departments confirmed that these principles provide them with useful information that meets their needs in analysing financial statements of subsidiaries without public accountability. Specifically, lenders indicated that information about the cash flows of a subsidiary is useful in assessing repayment capacity i.e. liquidity
Footnotes
3.19 Table 2 below summarises non-controlling interests (NCI) data obtained from the 2023 consolidated financial statements of UK listed entities:
| Dimension | Observation |
|---|---|
| Total book value of NCI | £40bn Approx |
| Proportion of aggregate net assets represented by NCI | 2.5% Approx |
| Proportion of UK listed entities reporting NCI in equity | 26% Approx |
Source: UKEB calculations based on Reuters-Eikon data. Figures are consolidated and do not comprise intercompany transactions, meaning that the sum of NCI for individual subsidiaries is likely to be higher.
3.20 In addition, the proportion of FTSE 100 listed entities reporting NCI was much higher than that for FTSE 250 listed entities, indicating that NCI are concentrated among larger companies by market capitalisation. More specifically, fewer than 10 entities account for approximately 80% of the total book value of NCI reported by all listed entities. NCI are most commonly reported by entities in the energy and basic materials industry sectors.22
3.21 Outreach with preparers suggests that the main external user group of their subsidiaries' financial statements is providers of credit such as bank lending departments. These lenders are particularly interested in the subsidiaries' financial statements when external borrowings are not supported by parent or intra-group guarantees.
3.22 Providers of credit to eligible subsidiaries are likely to be focused on information about the liquidity and solvency of the eligible subsidiary, consistent with the principles for reducing disclosures in IFRS 19.23 Outreach with bank lending departments confirmed that these principles provide them with useful information that meets their needs in analysing financial statements of subsidiaries without public accountability. Specifically, lenders indicated that information about the cash flows of a subsidiary is useful in assessing repayment capacity i.e. liquidity and solvency.[^24] Lenders may also be interested in information about assets which could be pledged as security for amounts borrowed by the eligible subsidiary.
Potential accounting impact of IFRS 19 in the UK
3.23 The objective of IFRS 19 is to simplify the preparation of eligible subsidiaries' financial statements whilst maintaining the usefulness of the financial statements to their users.
3.24 Currently, subsidiaries of groups preparing consolidated financial statements using full IFRS Accounting Standards either use local Generally Accepted Accounting Principles (GAAP) or full IFRS Accounting Standards to prepare their individual financial statements.
- If local GAAP is used, subsidiaries must prepare financial information on a full IFRS basis for group reporting, as well as preparing financial information on a local GAAP basis for their statutory financial statements. This dual reporting means that, usually, reconciliations between local GAAP and full IFRS Accounting Standards information are needed. If such entities can apply IFRS 19 instead, the recognition, measurement and presentation of items would be aligned with full IFRS Accounting Standards, eliminating the need for such dual reporting and reconciliations.
- If full IFRS Accounting Standards are currently used, eligible subsidiaries will continue to have recognition, measurement and presentation of items aligned with group reporting, but will benefit from the reduced disclosure requirements by applying IFRS 19.
UK accounting frameworks
3.25 Section 395 of the Companies Act 2006 (the Act) defines the accounting frameworks to be used by an individual UK company when preparing its financial statements. It specifies the use of one of the following two accounting frameworks for the preparation of accounts:[^25]
- UK-adopted International Accounting Standards (IAS individual accounts); or
- the framework set out in the Act (Companies Act individual accounts).
3.26 UK-registered companies (except for charities) may choose to use either of these two frameworks when preparing their individual accounts.
3.27 IFRS 19 endorsed for use in the UK is part of UK-adopted international accounting standards. Accordingly, eligible subsidiaries electing to use IFRS 19 will be preparing IAS accounts.
3.28 The figure below provides a visual representation of the implications of IFRS 19 for UK accounting frameworks.
Figure 1: Implications of IFRS 19 for UK accounting frameworks
UK Accounting Frameworks after adoption of IFRS 19
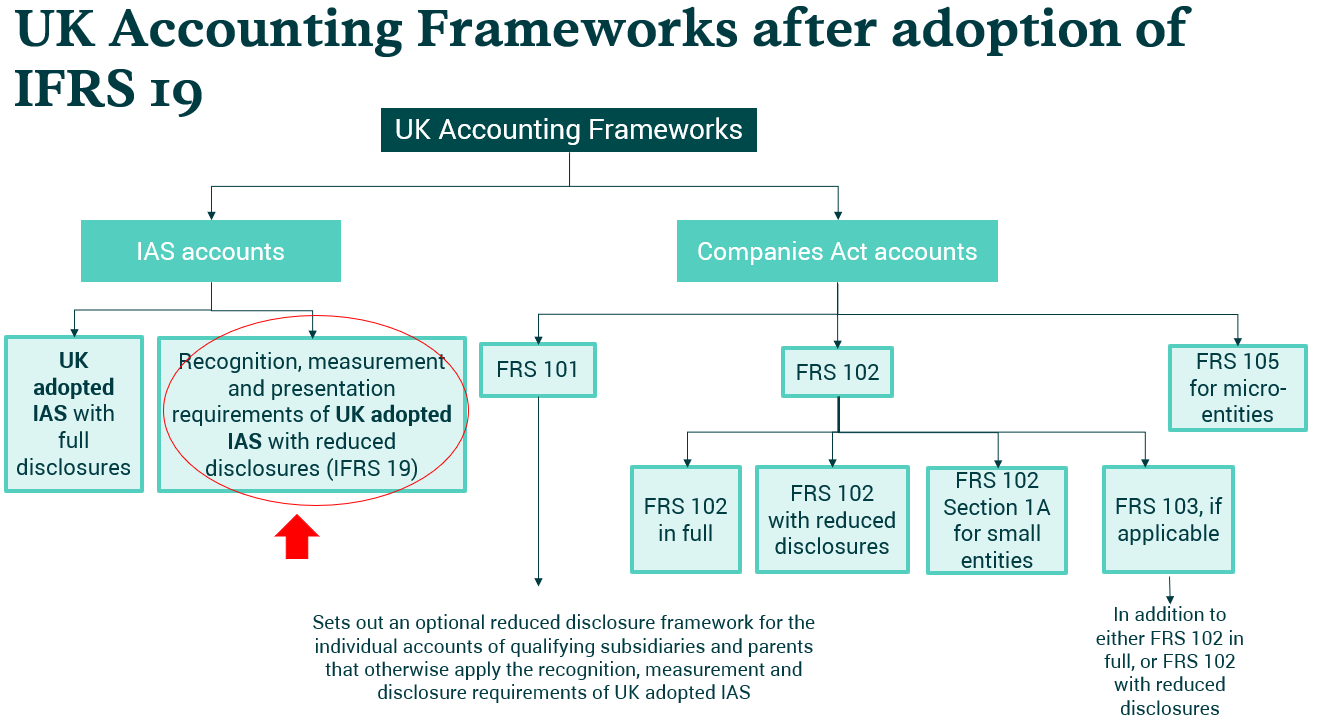
3.29 The different financial reporting standards and options under UK GAAP result in various options for the preparation of Companies Act accounts.
3.30 If Companies Act accounts are prepared, subsidiaries of UK listed groups may apply:
- Financial Reporting Standard 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland (FRS 102);[^26] or
- if they are qualifying entities,[^27] they may elect to apply Financial Reporting Standard 101 Reduced Disclosure Framework (FRS 101).
3.31 An entity that applies FRS 102 is required to apply FRS 103 Insurance Contracts to:
- insurance contracts (including reinsurance contracts) that it issues and reinsurance contracts that it holds; and
- financial instruments (other than insurance contracts) that it issues with a discretionary participation feature.
FRS 103 has been included in the figure for completeness.
3.32 FRS 105 The Financial Reporting Standard applicable to the Micro-Entities Regime has been included here for completeness but would not be available for use by subsidiaries within a group containing a traded entity or if the subsidiary is consolidated into group accounts.
3.33 IFRS 19 does not introduce a new accounting framework, as it is part of the current IAS accounts framework.
3.34 Feedback from UKEB outreach with users, in particular bank lending departments, indicated that the introduction of IFRS 19 will not introduce significant additional complexity to the UK Accounting Framework. These users regularly deal with multiple existing accounting standards and raised no concerns about the introduction of IFRS 19 as an option for preparing subsidiary financial statements.
Expected use of reduced disclosure standards in the UK
3.35 FRS 101, the reduced disclosure Standard under the Companies Act accounts framework, is conceptually similar to IFRS 19. It permits eligible entities to apply recognition, measurement and presentation requirements in UK-adopted international accounting standards, with some amendments in place for compliance with the Act.
3.36 The scope and disclosure requirements of FRS 101 and IFRS 19 differ in some respects. Table 3 below compares the scope of the two reduced disclosure standards. Regarding the disclosure requirements, broadly fewer disclosures are required under FRS 101 than under IFRS 19.
Table 3: A comparison of scope of IFRS 19 versus FRS 101
| | IFRS 19 | FRS 101 | |:-------------------------------------------|:--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | Scope | May be applied by subsidiaries that do not have public accountability. ---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- ------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------ -------------------| | Definition | An eligible subsidiary should have an ultimate or intermediate parent that produces consolidated financial statements available for public use that comply with IFRS Accounting Standards. An entity has public accountability and therefore is not eligible to apply IFRS 19 if:
- its debt or equity instruments are traded in a public market; or
- it holds assets entrusted to it by its customers (i.e. in a fiduciary capacity) e.g. banks, credit unions, insurance companies, securities brokers/dealers, mutual funds and investment banks.
----------------------------------------------------------
| Available to individual financial statements of subsidiaries | Available for public use that comply with IFRS Accounting Standards. ---------------------------------------------------- | Available to individual financial statements of ultimate parent companies |
| IFRS Accounting Standard (subheading in IFRS 19) | Identification criteria | Identified as key aspect? | Subheading in this section under which assessed |
|---|---|---|---|
| IAS 12 Income Taxes | Potentially significant impact on the usefulness of financial statements for users of eligible subsidiaries' financial statements | ✓ | Income taxes |
| IAS 16 Property, Plant and Equipment | No significant reduction in disclosures | ||
| IAS 19 Employee Benefits | |||
| IAS 20 Accounting for Government Grants and Disclosure of Government Assistance | No reduction in disclosures | ||
| IAS 21 The Effects of Changes in Foreign Exchange Rates | No significant reduction in disclosures | ||
| IAS 23 Borrowing Costs | No reduction in disclosures | ||
| IAS 24 Related Party Disclosures | Potentially significant impact on the usefulness of financial statements for users of eligible subsidiaries' financial statements and the requirements interact with the UK Companies Act requirements | ✓ | Related party transactions |
| IAS 27 Separate Financial Statements | No significant reduction in disclosures | ||
| IAS 29 Financial Reporting in Hyperinflationary Economies | Unlikely to have a significant impact on the usefulness of eligible subsidiaries' financial statements and no reduction in disclosures |
| IFRS Accounting Standard (subheading in IFRS 19) | Identification criteria | Identified as key aspect? | Subheading in this section under which assessed |
|---|---|---|---|
| IAS 32 Financial Instruments: Presentation | No significant reduction in disclosures | ||
| IAS 34 Interim Financial Reporting | Unlikely to have a significant impact on the usefulness of eligible subsidiaries' financial statements | ||
| IAS 36 Impairment of Assets | Potentially significant impact on the usefulness of financial statements for users of eligible subsidiaries' financial statements | ✓ | Impairment |
| IAS 37 Provisions, Contingent Liabilities and Contingent Assets | No significant reduction in disclosures | ||
| IAS 38 Intangible Assets | |||
| IAS 40 Investment Property | |||
| IAS 41 Agriculture | Whilst there is a significant reduction in disclosures, it is unlikely to have a significant impact on the usefulness of eligible subsidiaries' financial statements |
Notes:
-
IAS 1—an entity electing to apply IFRS 19 for a reporting period earlier than the reporting period in which it first applies IFRS 18 is required to apply the IAS 1 disclosures set out in Appendix B of IFRS 19. IFRS 18 was adopted for use in the UK in December 2025 and it will be effective for annual reporting periods beginning on or after 1 January 2027 i.e. the same effective date as for IFRS 19.
-
IFRS Accounting Standards which do not contain any disclosure requirements have been excluded from this table. These are: IFRS 9 Financial Instruments, IFRS 10 Consolidated Financial Statements, IFRS 11 Joint Arrangements, IAS 28 Investments in Associates and Joint Ventures and IAS 39 Financial Instruments: Recognition and Measurement.
-
IAS 26 Accounting and Reporting by Retirement Benefit Plans is only applicable to entities with public accountability, so has been excluded from this table for that reason. IFRS 19 excludes the disclosures set out in IAS 26.
-
If an eligible subsidiary applies IFRS 19 and applies IFRS 8 Operating Segments, IFRS 17 Insurance Contracts or IAS 33 Earnings per Share, it is required to provide all the disclosure requirements in those Standards (i.e. there are no disclosure reductions for eligible subsidiaries applying IFRS 19 and any of these three Standards).
Assessment of the specific key aspects of reductions in disclosure requirements in IFRS 19 against the technical accounting criteria
4.11 This section includes an overall assessment of the specific key aspects of reductions in disclosures of IFRS 19 against the technical accounting criteria. For a description of the main requirements in IFRS 19, refer to Section 3 of this ECA.
4.12 Input for this assessment was obtained from:
- engagement with UKEB Advisory Groups;
- interviews with preparers (considering applying IFRS 19);
- interviews with users (principally bank lending departments using subsidiaries' financial statements); and
- desktop analysis including a review of the disclosure requirements in IFRS 19, the basis for these requirements and its effects analysis.
4.13 Overall, the UKEB received positive feedback from outreach with UK stakeholders, who did not highlight any significant issues of concern. For example, users of financial statements, particularly bank lending departments using subsidiary financial statements, did not raise any significant issues. These users said that the disclosure requirements in IFRS 19 lead to financial information that is understandable, relevant, reliable and comparable for their decision-making.
4.14 Our overall conclusion on whether IFRS 19 meets the technical accounting criteria is set out at the end of this Section.
Transition requirements—first-time adoption and comparative information
IFRS 19 and Companies Act 2006 requirements
4.15 An entity is required to apply IFRS 1 when it prepares its first IFRS financial statements. IFRS 19 requires reduced IFRS 1 disclosures when an eligible subsidiary prepares its first IFRS financial statements.
4.16 Under the UK accounting framework, eligible subsidiaries electing to use IFRS 19 would be preparing IAS accounts. The Companies Act 2006 (the Act) permits a company to revert to UK GAAP (Companies Act accounts) from UK-adopted IAS (IAS accounts) if it has not reverted to UK GAAP in the previous five years, other than for a "relevant change of circumstance" e.g. a company ceasing to be a subsidiary undertaking within a group that applies UK GAAP 24.
4.17 When an eligible subsidiary elects to apply IFRS 19 in the current period, but the Standard was not applied in the immediately preceding period, IFRS 19 requires comparative information to be provided for all amounts reported in the current period's financial statements. This includes comparative information for narrative and descriptive information if it is necessary for an understanding of the current period's financial statements 25.
Assessment against the endorsement criteria
4.18 These requirements on comparative information in IFRS 19 will provide useful and relevant information to users of subsidiaries' financial statements and a clear understanding of how its performance in the current period compared to the preceding period. This should enable users to compare the performance of an eligible subsidiary between reporting periods.
4.19 In addition, if an eligible subsidiary's election to apply IFRS 19 means that it is switching from a local GAAP to IFRS for the first time, the disclosure requirements in the Standard 26 are a streamlined version of those in IFRS 1.
4.20 IFRS 19 requires the key disclosures in IFRS 1. In particular, the Standard requires:
- An explanation of transition to IFRS Accounting Standards from previous GAAP i.e. how the transition affected the reported financial position, financial performance and cash flows.
- Reconciliations of equity and total comprehensive income from previous GAAP to amounts under IFRS.
4.21 These requirements will enable a user to understand the transitional effect of switching from a local GAAP to IFRS. This will result in the provision of relevant information on initial application and comparable information over time for users.
4.22 When an eligible subsidiary elects to apply IFRS 19 in one reporting period, the election is subsequently reversible 27. This could lead to a risk that an eligible subsidiary revokes an election to apply IFRS 19 (IAS accounts) and switches to UK GAAP (Companies Act accounts) because of differences in recognition and measurement requirements, potentially impacting relevance, reliability, understandability and comparability.
4.23 However, requirements in the Act, relating to switching from IAS accounts (UK-adopted IAS) to Companies Act accounts (UK GAAP) 28, would apply. As a result, the circumstances in which an eligible subsidiary can switch from IFRS 19 (IAS accounts) to Companies Act accounts (UK GAAP) will be limited. The requirements in the Act relating to reverting to UK GAAP, once IFRS 19 has been applied, ensure the understandability and comparability of the financial statements of eligible subsidiaries for users.
Business combinations
IFRS 19 requirements
4.24 IFRS 19 includes reduced disclosures for IFRS 3 29 but retains the key disclosure requirements that apply to all business combinations within the scope of IFRS 3. These include:
- The name and a description of the acquiree.
- The acquisition date.
- Percentage of voting equity interests acquired.
- A qualitative description of the factors that make up the goodwill recognised.
- The acquisition-date fair value of the total consideration transferred and description of the components of that consideration.
- The details of contingent consideration arrangements and indemnification assets e.g. amount recognised as of the acquisition date.
- The amount of any gain recognised in a bargain purchase.
- The amount of non-controlling interest in the acquiree, recognised at the acquisition date for each business combination in which the acquirer holds less than 100 per cent of the equity interests.
Assessment against the endorsement criteria
4.25 As noted above, IFRS 19 requires key disclosures in respect of business combinations. Where an eligible subsidiary undertakes a transaction that meets the definition of a business combination in IFRS 3 30, particularly where such a transaction is significant, eligible subsidiaries will be required to provide the key information. Users of their financial statements will obtain relevant and understandable information which will enable them to evaluate the nature and financial effect of the business combination.
4.26 In addition, users will obtain reliable information because these business combinations will be accounted for in accordance with the requirements of IFRS 3. The disclosures will also provide useful information to users for inter-period comparability.
4.27 Therefore, in aggregate, the accounting treatment together with the disclosures, supports the relevance, reliability, comparability and understandability for business combinations entered into by eligible subsidiaries.
Financial instruments
IFRS 19 requirements
4.28 IFRS 19 includes reduced disclosures for IFRS 7 31. The application of the principles 32 the IASB used to determine the reduced disclosure requirements in IFRS 19, resulted in relatively few reductions to the required disclosures of IFRS 7. IFRS 7 disclosures that are not required by IFRS 19 include:
- Certain information when an entity has designated a financial asset (or group of financial assets) at fair value through profit or loss that would otherwise be measured at fair value through other comprehensive income or amortised cost e.g. maximum exposure to credit risk, the amount of change in the fair value of the financial asset (or group of financial assets) that is attributable to changes in the credit risk.
- For a financial liability designated as at fair value through profit or loss: any transfers of the cumulative gain or loss within equity during the period including the reason for such transfers; if a liability is derecognised during the period, the amount (if any) presented in other comprehensive income that was realised at derecognition.
- The detailed disclosures for investments in equity instruments designated at fair value through other comprehensive income e.g. the reasons for using this presentation alternative, the fair value of each such investment at the end of the reporting period, the reasons for disposing of the investments (if derecognised).
- The detailed disclosures for offsetting financial assets and financial liabilities e.g. gross amounts of those recognised financial assets and recognised financial liabilities, description of the rights of set-off associated with the entity's recognised financial assets and recognised financial liabilities subject to enforceable master netting arrangements and similar agreements.
- The detailed disclosures when an entity holds collateral (of financial or non-financial assets) and is permitted to sell or repledge the collateral in the absence of default by the owner of the collateral e.g. the fair value of the collateral held; the fair value of any such collateral sold or repledged.
- An analysis of the gain or loss recognised in the statement of comprehensive income arising from the derecognition of financial assets measured at amortised cost, showing separately gains and losses arising from derecognition of those financial assets.
- The detailed disclosures for hedge accounting e.g. in relation to the risk management strategy and in situations in which an entity frequently resets (i.e. discontinues and restarts) hedging relationships.
- The detailed disclosures for transfers of financial assets e.g. in relation to transferred financial assets that are not derecognised in their entirety.
4.29 IFRS 19 includes the following disclosure requirements that are in IFRS 7, which are only applicable to eligible subsidiaries that provide financing to customers as a main business activity, as described in IFRS 18 33:
- Credit risk management practices and how they relate to the recognition and measurement of expected credit losses (paragraph 69 of IFRS 19).
- Explanation of how significant changes in the gross carrying amount of financial instruments during the period contributed to changes in the loss allowance (paragraph 70 of IFRS 19).
- Credit risk exposure: gross carrying amount of financial assets and the exposure to credit risk on loan commitments and financial guarantee contracts (paragraph 71 of IFRS 19).
4.30 Financial instruments of an eligible subsidiary are accounted for under IFRS 9 and IAS 32, if they are within the scope of these standards.
Assessment against the endorsement criteria
4.31 IFRS 19 does not change the overall types of disclosures for eligible subsidiaries. Instead, the reduced disclosures will provide a proportionate framework to address the types of transactions and risks for the entities in scope and disclose the information that will be directly relevant and useful for their users. Consequently, the requirements promote a faithful representation of an eligible subsidiary's financial position and performance, ensuring the reliability and relevance of the financial information.
4.32 IFRS 19, while still requiring certain information to be disclosed, eliminates the detailed disclosures for each topic of IFRS 7 disclosures. This is because they are not expected to be required by the users of eligible subsidiaries' financial statements in their decision-making. For example:
- Users will still be able to understand the effect of investments in equity instruments, designated as measured at fair value through other comprehensive income at initial recognition, on the solvency and liquidity of the subsidiary without the extent of detail specified by the IFRS 7 disclosures.
- The reduced disclosures will still provide users of accounts with relevant and understandable information about financial instruments in an eligible subsidiary's financial statements. For example, for a transaction where an entity has transferred financial assets in such a way that part, or all, of the transferred financial assets do not qualify for derecognition, IFRS 19 requires disclosure of: the nature of the transferred assets; the nature of the risks and rewards of ownership to which the entity is exposed; and when the entity continues to recognise all of the transferred assets, the carrying amounts of the transferred assets and the associated liabilities.
4.33 Consistent with the principles the IASB used to assess the needs of users of financial statements, liquidity is one of the pieces of information likely to be a focus of users of eligible subsidiaries' financial statements. IFRS 19 requires liquidity risk disclosures. 34 Therefore, these provide relevant and understandable information.
4.34 The reduced disclosure requirements relating to credit risk will provide users with these disclosures on credit risk only when eligible subsidiaries provide financing to customers as a main business activity e.g. a subsidiary that is a non-bank lender. This will provide relevant and understandable information to users. Other disclosures on credit risk will be provided by all eligible subsidiaries where relevant (see paragraphs 65-67 of IFRS 19). Therefore, the restriction does not impact the relevance and understandability of financial statements for users for those subsidiaries that do not provide financing to customers.
4.35 The overall reduced disclosure requirements for IFRS 7, in IFRS 19, are expected to provide relevant, reliable, comparable and understandable information to users of eligible subsidiaries' financial statements to evaluate:
- the significance of financial instruments for the eligible subsidiary's financial position and performance; and
- the nature and extent of risks arising from financial instruments to which the eligible subsidiary is exposed during the period and at the end of the reporting period, and how the eligible subsidiary manages those risks.
Interests in other entities
IFRS 19 and Companies Act 2006 requirements
4.36 The Companies Act 2006 (the Act) provides intermediate parent companies with certain exemptions from preparing group accounts. For example, a company is exempt from the requirement to prepare group accounts if it is a subsidiary undertaking wholly owned by a UK-registered immediate parent undertaking 35. An equivalent exemption is available for subsidiaries of a parent undertaking registered outside the UK. 36
4.37 In order to apply these exemptions, an eligible intermediate parent must comply with conditions relating to disclosure, audit and filing of the accounts 37.
4.38 Where an intermediate parent does not satisfy the conditions set out in the Act, it will be required to prepare group accounts. However, those entities will have the ability to elect to apply IFRS 19 in their consolidated financial statements, which will mean that they will produce a full set of consolidated IFRS financial statements, but with disclosures reduced in accordance with the Standard.
4.39 The IFRS 12 disclosures in IFRS 19 will be of particular relevance in such circumstances 38. The objective of the disclosure requirements of IFRS 12 is to require an entity to disclose information that enables users of its financial statements to evaluate 39:
- the nature of, and risks associated with, its interests in other entities; and
- the effects of those interests on its financial position, financial performance and cash flows.
4.40 IFRS 19 reduces the disclosure requirements for IFRS 12 by more than half 40. However, key information regarding interests in other entities is still required by IFRS 19. In particular, a company applying IFRS 19 is required to provide key information regarding its interests in subsidiaries (i.e. as an intermediate parent), joint ventures, associates and unconsolidated structured entities. This includes where an eligible subsidiary, which is itself a parent, determines that it is an investment entity.
4.41 For example, IFRS 19 requires an eligible subsidiary to disclose the following information for interests in subsidiaries 41:
- The date of the end of the reporting period of the financial statements of the subsidiary, if that date is different from the date used in the preparation of the consolidated financial statements.
- Significant restrictions (for example, statutory, contractual and regulatory restrictions) on its ability to access or use the assets and settle the liabilities of the group.
- Terms of any contractual arrangements that could require the parent or its subsidiaries to provide financial support to a consolidated structured entity.
- If financial or other support has been provided to a consolidated structured entity (without having a contractual obligation to do so)—the type and amount of support provided and the reasons for providing the support.
- Current intentions to provide financial or other support to a consolidated structured entity.
- Any gain or loss, where there is loss of control of a subsidiary, including the portion of that gain or loss attributable to measuring any investment retained in the former subsidiary at its fair value at the date when control is lost; and the line item(s) in profit or loss in which the gain or loss is recognised (if not presented separately).
Assessment against the endorsement criteria
4.42 Information about an intermediate parent's interests and involvement in other entities and the composition of that sub-group is likely to be of interest to users of their accounts, as it would provide them with information about the risks arising for that intermediate group, as a whole. For example, information about the subsidiaries' financial position and performance, the relevant cash flows, and other risks arising from material transactions, may be useful to users of those accounts.
4.43 IFRS 19 reduces the IFRS 12 disclosures significantly. However, the reduced disclosure requirements continue to provide information that would allow the users to ascertain the intermediate parent's obligations, commitments and cash flows in relation to its subsidiaries, thereby providing relevant information.
4.44 Therefore, the disclosures, where these are applicable, are likely to provide relevant, useful and understandable information to users.
Statement of cash flows (presentation requirements)
IFRS 19 requirements
4.45 IFRS 19 requires an eligible subsidiary to use the same recognition, measurement and presentation requirements in IFRS Accounting Standards but allows it to provide reduced disclosures.
4.46 Under IFRS Accounting Standards a complete set of financial statements comprises 42:
- a statement (or statements) of financial performance for the reporting period;
- a statement of financial position as at the end of the reporting period;
- a statement of changes in equity for the reporting period;
- a statement of cash flows for the reporting period;
- notes for the reporting period;
- comparative information in respect of the preceding period; and
- a statement of financial position as at the beginning of the preceding period, if required.
4.47 Therefore, a set of financial statements prepared under IFRS 19 will include the same primary statements as under full IFRS Accounting Standards. In particular, eligible subsidiaries will be required to prepare a statement of cash flows.
Assessment against the endorsement criteria
4.48 A statement of cash flows tracks the inflow and outflow of cash, providing insights into a company's financial health and helps users to assess its liquidity and solvency. Evidence indicates that for users and lenders cash flow information is value-relevant and is useful for predicting future cash flows from operating activities 43.
4.49 A full set of financial statements, including the statement of cash flows will result in relevant and comparable information to users of eligible subsidiaries' financial statements, enabling them to make informed decisions. The evidence obtained by the UKEB, from interviews with bank lending departments, suggests that a subsidiary's cash flow information is useful for the assessment of its repayment capacity.
Basis of preparation
IFRS 19 requirements
4.50 IFRS 19 includes all the disclosure requirements in IAS 8 44, except those in paragraph 6B of IAS 8, which requires an explicit and unreserved statement of compliance to be made in the notes, if an entity is claiming its financial statements comply with IFRS Accounting Standards. This paragraph is modified in IFRS 19 to require an eligible subsidiary to state it has applied the Standard in addition to the disclosure requirement in paragraph 6B of IAS 8.
Assessment against the endorsement criteria
4.51 IAS 8 includes some key disclosures to enable users to understand important aspects of the financial statements, in particular the requirement to disclose:
- Information as part of fair presentation and compliance with IFRS Accounting Standards i.e. when an entity departs from a requirement of an IFRS, it is required to disclose e.g.:
- That management has concluded that the financial statements present fairly the entity's financial position, financial performance and cash flows, for each period presented.
- The financial effect of the departure on each item in the financial statements that would have been reported in complying with the requirement.
- Information in relation to going concern e.g. when management is aware, in making its assessment, of material uncertainties related to events or conditions that may cast significant doubt upon the entity's ability to continue as a going concern, the entity shall disclose those uncertainties.
- Judgements that management has made in the process of applying the entity's accounting policies and that have the most significant effect on the amounts recognised in the financial statements.
- Assumptions that management has made about the future, and other major sources of estimation uncertainty at the end of the reporting period, that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities within the next financial year. In respect of those assets and liabilities, the notes shall include details of their nature; and their carrying amount as at the end of the reporting period.
4.52 Given that IFRS 19 requires all the disclosures in IAS 8, the disclosure requirements in the Standard will provide users with relevant and reliable information that will help them understand the basis of preparation of eligible subsidiaries' financial statements. This should enable users to compare the financial statements over time.
Income taxes
IFRS 19 requirements
4.53 The disclosure requirements in IAS 12 are designed to provide information to users relating to income taxes.
4.54 IFRS 19 requires most of the disclosure requirements in IAS 12 45. A key disclosure in IAS 12 is the requirement to disclose a tax reconciliation i.e. a breakdown of components of tax expense (income) e.g.:
- Current tax expense (income).
- Any adjustments recognised in the period for current tax of prior periods.
- The amount of deferred tax expense (income) relating to the origination and reversal of temporary differences.
- Deferred tax expense arising from the write-down, or reversal of a previous write-down, of a deferred tax asset.
Assessment against the endorsement criteria
4.55 The requirement in IFRS 19 to disclose a tax reconciliation will ensure that users obtain relevant and understandable information relating to income taxes.
Related party transactions
IFRS 19 and Companies Act requirements
4.56 IAS 24 includes disclosure requirements in relation to related party transactions. The disclosures highlight the possibility that an entity's financial position and profit or loss may have been affected by the existence of related parties, and by transactions and outstanding balances, including commitments, with such parties 46.
4.57 IFRS 19 includes all the disclosure requirements in IAS 24 47, except for the requirement in paragraph 14 of IAS 24:
"To enable users of financial statements to form a view about the effects of related party relationships on an entity, it is appropriate to disclose the related party relationship when control exists, irrespective of whether there have been transactions between the related parties."
4.58 Further, all UK-registered entities (whichever accounting framework they report under) are required to provide certain information, specifically related to related undertakings, in the notes to their accounts under The Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410) 48. Therefore, in any event, a UK-registered subsidiary electing to apply IFRS 19 will be required to provide this information in addition to the disclosure requirements set out in the Standard relating to related party transactions.
Assessment against the endorsement criteria
4.59 IFRS 19 includes relatively few reductions to the disclosures in IAS 24. Therefore, the related party transactions disclosures required by IFRS 19 will ensure users are provided with relevant and reliable information and the understandability and comparability of eligible subsidiaries' financial statements will not be impacted. The additional disclosures required by Schedule 4 of the Regulations will also provide users with useful and relevant information about related undertakings.
4.60 The related party transaction disclosures required by IFRS 19, together with those required by company law, should help users adjust their analysis, where necessary, if an eligible subsidiary's financial position and profit or loss have been affected by the existence of related parties, or by transactions and outstanding balances, including commitments, with such parties.
Impairment of assets
IFRS 19 requirements
4.61 IFRS 19 requires most of the key disclosures in IAS 36 49. The disclosures of IAS 36 not included in IFRS 19 are unlikely to be relevant to users of eligible subsidiaries' financial statements. For example, IAS 36 requires an entity that
- banks and other lending institutions;
- entities that provide financing to customers to enable those customers to buy the entity's products; and
- lessors that provide financing to customers in finance leases.
- a maturity analysis for non-derivative financial liabilities (including issued financial guarantee contracts) that shows the remaining contractual maturities.
- a maturity analysis for derivative financial liabilities. The maturity analysis shall include the remaining contractual maturities for those derivative financial liabilities for which contractual maturities are essential for an understanding of the timing of the cash flows (see paragraph B11B).
- a description of how it manages the liquidity risk inherent in (a) and (b).
4.57IFRS 19 includes all the disclosure requirements in IAS 2447, except for the requirement in paragraph 14 of IAS 24:
"To enable users of financial statements to form a view about the effects of related party relationships on an entity, it is appropriate to disclose the related party relationship when control exists, irrespective of whether there have been transactions between the related parties."
4.58Further, all UK-registered entities (whichever accounting framework they report under) are required to provide certain information, specifically related to related undertakings, in the notes to their accounts under The Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 (SI 2008/410)48. Therefore, in any event, a UK-registered subsidiary electing to apply IFRS 19 will be required to provide this information in addition to the disclosure requirements set out in the Standard relating to related party transactions.
Assessment against the endorsement criteria
4.59IFRS 19 includes relatively few reductions to the disclosures in IAS 24. Therefore, the related party transactions disclosures required by IFRS 19 will ensure users are provided with relevant and reliable information and the understandability and comparability of eligible subsidiaries' financial statements will not be impacted. The additional disclosures required by Schedule 4 of the Regulations will also provide users with useful and relevant information about related undertakings.
4.60The related party transaction disclosures required by IFRS 19, together with those required by company law, should help users adjust their analysis, where necessary, if an eligible subsidiary's financial position and profit or loss have been affected by the existence of related parties, or by transactions and outstanding balances, including commitments, with such parties.
Impairment of assets
IFRS 19 requirements
4.61IFRS 19 requires most of the key disclosures in IAS 3649. The disclosures of IAS 36 not included in IFRS 19 are unlikely to be relevant to users of eligible subsidiaries' financial statements. For example, IAS 36 requires an entity that reports segment information in accordance with IFRS 8 to disclose the following for each reportable segment:
- the amount of impairment losses recognised in profit or loss and in other comprehensive income during the period; and
- the amount of reversals of impairment losses recognised in profit or loss and in other comprehensive income during the period.
4.62This disclosure is not required by IFRS 19. Because of the scope of IFRS 8, a subsidiary permitted to apply IFRS 19 is not required to apply IFRS 8. Further, an eligible subsidiary is unlikely to choose to apply IFRS 8. Therefore, this disclosure is not relevant to eligible subsidiaries.
Assessment against the endorsement criteria
4.63Estimates and judgements used in the measurement of recoverable amounts of cash generating units, containing goodwill or intangible assets with indefinite useful lives, are important information for users of accounts.
4.64IAS 36 includes the requirement to disclose estimates used to measure recoverable amounts of cash generating units containing goodwill or intangible assets with indefinite useful lives.
4.65In particular, if the unit's (group of units') recoverable amount is based on value in use, IAS 36 requires certain disclosures to enable users to understand the judgements and assumptions made by management. For example, IAS 36 requires disclosure of 50:
- each key assumption on which management has based its cash flow projections for the period covered by the most recent budgets/forecasts. Key assumptions are those to which the unit's (group of units') recoverable amount is most sensitive;
- the growth rate used to extrapolate cash flow projections beyond the period covered by the most recent budgets/forecasts, and the justification for using any growth rate that exceeds the long term average growth rate for the products, industries, or country or countries in which the entity operates, or for the market to which the unit (group of units) is dedicated; and
- the discount rate(s) applied to the cash flow projections.
4.66Similarly, if the unit's (group of units') recoverable amount is based on fair value less costs of disposal, IAS 36 requires certain disclosures51, e.g.:
- the valuation technique(s) used to measure fair value less costs of disposal; and,
- if fair value less costs of disposal is not measured using a quoted price for an identical unit (group of units)—each key assumption on which management has based its determination of fair value less costs of disposal, the level of the fair value hierarchy within which the fair value measurement is categorised in its entirety (without giving regard to the observability of 'costs of disposal').
4.67IFRS 19 maintains these disclosure requirements of IAS 36 in relation to value in use52 and fair value less costs of disposal53. This will ensure that users obtain relevant, reliable and understandable information relating to estimates and judgements used to measure recoverable amounts of cash generating units containing goodwill or intangible assets with indefinite useful lives.
Overall conclusion on whether IFRS 19 meets the technical accounting criteria
4.68In drawing our conclusion as to whether IFRS 19 meets the technical accounting criteria, we have considered the reduced disclosure requirements in IFRS 19 for key aspects.
4.69The UKEB conclusion is that IFRS 19 disclosure requirements will result in relevant, reliable, understandable and comparable information for users of eligible subsidiaries' financial statements 54.
4.70Entities applying IFRS 19 are required to consider whether to provide additional disclosures when compliance with the specific requirements in the Standard is insufficient 55 to achieve the objectives of understandability, relevance, reliability and comparability. We have taken account of such disclosure requirements in our assessment. In coming to our conclusion, we have also taken into account that financial statements prepared in accordance with IFRS 19 have a different group of users from entities that have public accountability.
4.71Overall, therefore, the UKEB concludes that IFRS 19 meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
5. UK long term public good assessment
5.1This section analyses whether IFRS 19 is likely to be conducive to the long term public good in the UK. The assessment is based on the following:
- an analysis of whether the use of IFRS 19 is likely to improve the quality of financial reporting; and
- an economic impact assessment.
5.2Each of the sections above contributes to the Board's overall assessment of whether IFRS 19 is conducive to the long term public good in the UK.
5.3Appendix D contains information that supplements the analysis in this section.
Is use of IFRS 19 likely to improve the quality of financial reporting?
Approach for this assessment
5.4Regulation 7(2)(a) of SI 2019/685 requires the UK long term public good assessment to consider whether the use of the IFRS 19 is likely to improve the quality of financial reporting. In conducting this assessment, the UKEB adopts a relative approach.
5.5This assessment also considers whether IFRS 19 is likely to meet the IASB's stated objective for the Standard, of simplifying the preparation of subsidiaries' financial statements whilst maintaining their usefulness for users.
Improvements introduced by IFRS 19 for eligible subsidiaries
5.6The IASB developed IFRS 19 in response to demand from stakeholders, particularly from preparers of financial statements. They requested that, given the main users of subsidiaries' financial statements (e.g. parent entities, bank lending departments, rating agencies) tend to be in a position to ask for additional information, if necessary, such preparers should be permitted to apply IFRS Accounting Standards with reduced disclosure requirements.
5.7The main areas where IFRS 19 is likely to improve or maintain the quality of financial reporting for subsidiaries in the UK are:
- IFRS 19 will enable groups using IFRS with eligible subsidiaries to apply consistent accounting policies when preparing financial statements throughout the group. This will simplify group reporting and potentially improve the quality of the subsidiary's financial statements. Subsidiaries applying local GAAP that elect to transition to IFRS 19 will align their accounting policies with the parent preparing IFRS consolidated financial statements. This will also improve intra-group comparability, from the perspective of parent entities, in particular, as well as any other users interested in group and subsidiaries' financial statements.
- The requirement in IFRS 19 for an eligible subsidiary to use the same recognition, measurement and presentation requirements in IFRS Accounting Standards will provide users with financial statement information that is as reliable as that presented in full IFRS.
- Feedback from UKEB outreach with lenders indicated that the reduced disclosures in IFRS 19 will provide sufficient information to assess subsidiaries' financial statements for lending decisions, thereby providing information that is as relevant and understandable as that presented in full IFRS.
- IFRS 19 aims to remove disclosures that go beyond the needs of relevant users. This will reduce some complexity and improve users' understanding of the financial performance, position and cash flows of eligible subsidiaries. This benefit would apply, in particular, to those subsidiaries applying full IFRS Accounting Standards which elect to transition to IFRS 19.
- Finally, it should be noted that IFRS 19 maintains the requirements in full IFRS Accounting Standards in relation to primary financial statements including the requirement to prepare a statement of cash flows, which would help users understand the liquidity of the subsidiary. As a result, IFRS 19 is expected to provide these users of subsidiaries' financial statements with decision-useful information to analyse financial statements more efficiently.
Summary of whether IFRS 19 is likely to improve the quality of financial reporting
5.8Stakeholders, in particular preparers, consulted during the UKEB's outreach, suggested that the use of IFRS 19 will:
- allow groups to simplify the preparation of subsidiaries' financial statements by using IFRS Accounting Standards both for group reporting purposes and for their own financial statements, but with reduced disclosures for the latter. This will eliminate the need for these subsidiaries to maintain additional accounting records from those maintained for group reporting under IFRS; and
- maintain or improve the usefulness of the financial statements for the users of these subsidiaries' financial statements.
5.9Therefore, the UKEB concludes that IFRS 19 is likely to improve the quality of financial reporting for subsidiaries in the UK.
Economic impact assessment
5.10The economic impact assessment considers the following:
- Government guidance on costs and benefits analysis.
- An analysis of the costs and benefits likely to result from the use of IFRS 19.
- Whether the use of IFRS 19 is likely to have an adverse effect on the economy of the UK, including on economic growth (wider economic effects).
- The consequences of not adopting IFRS 19 (counterfactual analysis).
Government guidance
5.11The UK government's Better Regulation Framework (BRF) provides a set of guidelines for UK government departments and public bodies on how to conduct economic impact assessments56.
5.12The UKEB is not currently required to apply the BRF. However, the UKEB considered and agreed that it should broadly follow the BRF guidance.
5.13Accordingly, the cost benefit analysis (CBA) of IFRS 19 was developed broadly considering the BRF57. The UKEB followed the principle of proportionality of assessment. This means "ensuring the appropriate level of resources is invested in gathering and analysing evidence on the impacts of a policy". Consistently, the UKEB conducted relatively limited stakeholder engagement to gather evidence for the long term public good assessment for IFRS 19, given that it is a voluntary standard and the expected appetite for use of the Standard among UK-registered subsidiaries (see paragraph 5.43 b) i)).
Analysis of costs and benefits from the use of IFRS 19
Objective
5.14The assessment of the long term public good requires an analysis of costs and benefits associated with the use of IFRS 19.
5.15The cost benefit analysis (CBA) considers the impact of IFRS 19 in terms of the direct58 costs and benefits (including cost savings) anticipated for preparers, users and other stakeholders (e.g. auditors, regulators). Indirect effects59 are considered in the wider economic effects section.
5.16The analysis focuses on the incremental costs and benefits of IFRS 19 (i.e. costs and benefits incurred as a direct result of meeting the disclosure requirements of the Standard).
5.17This CBA takes a qualitative approach. This is due to the following:
- Identifying subsidiaries that will elect to apply IFRS 19 is not feasible due to the voluntary nature of the Standard (see paragraph 5.34).
- At the time of writing, feedback from some preparers indicated that stakeholders had, generally, not commenced detailed assessments of the costs and benefits of IFRS 19. Therefore, the availability of quantitative evidence is limited.
Consequently, the UKEB considered that the quantification of the expected monetary costs and benefits was not feasible.
5.18As the assessment of costs and benefits is qualitative, this ECA does not analyse in detail how (and where) subsidiary-level costs/benefits accrue or are allocated to group-level ones.
5.19Given that IFRS 19 is voluntary, preparers are expected to assess whether the anticipated benefits of applying the Standard outweigh implementation costs, prior to deciding whether to apply it. The costs and benefits discussed in paragraphs 5.22-5.55 therefore illustrate the potential transition impacts IFRS 19 may have on eligible subsidiaries that elect to apply it and the subsequent implications for users of their financial statements.
5.20The qualitative evidence on implementation costs describes the expected monetary costs of applying IFRS 19 (e.g. changes to accounting systems) as well as the relevant opportunity costs (e.g. staff reallocation from other activities to IFRS 19 implementation).
Collection of evidence
5.21This analysis draws upon evidence obtained from:
- desk-based research; 60
- engagement with UKEB Advisory Groups;
- interviews with preparers; and
- interviews with bank lending departments using subsidiaries' financial statements. 61
Users
Benefits for users
5.22As noted in Section 3 para 3.18, subsidiaries without public accountability generally have few users of their financial statements that are external to the group. The main external users of these financial statements are credit providers (e.g. bank lending departments) and non-controlling interests62.
5.23During outreach, users were asked to provide information about the anticipated benefits of IFRS 19, and whether the reduced disclosure requirements would reduce the usefulness of subsidiaries' financial statements.
5.24Users expressed overall support for the use of IFRS 19, as it would remove disclosures that are not usually directly relevant for their analysis. This would ensure subsidiaries' financial statements provide disclosures targeted to their needs.
5.25As previously noted (see Section 3 para 3.19), unlike users that hold, trade or analyse the performance of securities traded on public markets, most users of subsidiaries' financial statements, in particular lenders, can typically request additional information from management.
5.26Based on desk-based research and outreach with users, the UKEB has identified the following main benefits of IFRS 19 for users:
- The financial statements of subsidiaries would eliminate those disclosures in full IFRS Accounting Standards that go beyond the needs of users of the financial statements of eligible subsidiaries. As a result, the IFRS 19 disclosures would provide these users with decision-useful information to analyse financial statements more efficiently.
- For those subsidiaries switching from local GAAP, users would obtain more internationally comparable information as recognition, measurement and presentation requirements would be aligned with IFRS Accounting Standards. This was highlighted as an advantage by some users.
- The IFRS 19 requirement to prepare a statement of cash flows was confirmed by users as being useful when assessing debt repayment capacity.
5.27Members of the UKEB Investor Advisory Group (IAG), which include both equity and debt capital providers, expressed support for IFRS 19. They considered that the use of a consistent accounting framework within groups and across jurisdictions could make their analyses easier and help them compare companies. IAG members expressed a preference for the consistency of a single international framework for financial reporting, over the diversity that arises from the use of multiple local GAAP frameworks.
5.28Stakeholder feedback suggested that non-controlling interests (NCI) may be a user of subsidiaries' financial statements that are potentially affected by IFRS 19. However, engagement with stakeholders also suggested that NCI are unlikely to be negatively affected by the reduced disclosures in IFRS 19.
5.29Appendix D reports additional evidence obtained through stakeholder engagement with lenders.
Costs for users
5.30Users are not expected to incur significant costs from the use of IFRS 19. As noted, lenders and other users of subsidiaries' accounts:
- analyse subsidiaries' accounts relatively infrequently; and
- can request additional information directly from management, which mitigates the risk that disclosures provided under IFRS 19 might fail to meet their needs.
5.31Therefore, the main costs users may incur are minor familiarisation costs with the reduced disclosure requirements in IFRS 19.
5.32Users are not expected to incur any ongoing costs or cost reductions.
Preparers
5.33As noted in Section 3, IFRS 19 will impact eligible subsidiaries and the groups that control those subsidiaries.
5.34IFRS 19 is a voluntary Standard that will only be applied if the benefits from its use exceed the costs. Therefore, the considerations below apply to eligible subsidiaries that decide to apply IFRS 1963.
5.35Stakeholder engagement suggested that, in most cases, the decision to apply IFRS 19 is made at the group level. However, at times this decision is made by the individual subsidiary, depending on the extent to which decision-making about financial reporting is decentralised at the group level.
5.36Therefore, this assessment distinguishes between costs and benefits accruing to subsidiaries and those affecting the group, as a whole. Specifically, this analysis considers:
- UK-registered subsidiaries of UK group companies;
- overseas subsidiaries of UK group companies, to the extent that any costs/cost savings would be consolidated into group-level results; and
- UK-registered subsidiaries of group companies with overseas parents.
Overall impact of IFRS 19
5.37The costs and benefits of applying IFRS 19 are expected to vary depending on the factors listed in Table 6 below, as corroborated using feedback from preparer outreach.
| Table 6: Determinants of the costs and benefits of applying IFRS 19 |
|---|
| The accounting framework applied before transitioning to IFRS 19 |
| Size and complexity of the subsidiary's operations |
| The number of subsidiaries in the group |
| Geographical spread of subsidiaries in the group |
| Existing financial reporting processes in the group |
| The number of jurisdictions adopting IFRS 19 |
| The extent to which group-level reporting is centralised (e.g. shared service centres) |
| Applicable law and regulation, including tax regulation |
5.38Given the number and complexity of the factors described above, in the absence of a quantitative assessment of monetary costs, it is difficult to generalise how IFRS 19 will produce costs and benefits for preparers. This is likely to vary on a group-by-group basis.
5.39The UKEB has prepared three case studies to illustrate how IFRS 19 will affect groups with different characteristics. The case studies outline the direct effects of applying IFRS 19 on groups/subsidiaries of different sizes and with different levels of centralisation. The main finding from the case studies is that the extent to which cost savings are reaped at a group, or at a subsidiary level, will depend on those determinants.
5.40Large groups with shared service centres (SSC) would reap group-level synergies and experience efficiency gains. On the other hand, smaller groups/groups characterised by less centralisation would see costs savings being reaped regionally, or even at individual entity levels. These case studies are presented in Appendix D.
5.41While it is not possible to generalise the potential impacts, the UKEB considered that:
- The accounting framework that the subsidiaries apply before transitioning to IFRS 19 is one of the most important determinants of the cost and benefit assessment for both groups and individual subsidiaries.
- For groups, the degree of centralisation of financial reporting processes is also important.
Therefore, the remainder of this section mainly discusses how these two determinants affect overall cost and benefit considerations.
Benefits for preparers
5.42During outreach, preparers were asked to provide information about cost savings and other benefits they expect from the application of IFRS 19.
# Subsidiary-level analysis
5.43The benefits will vary depending on the accounting framework that an eligible subsidiary applied before transitioning to IFRS 19.64 In particular:
- For subsidiaries that apply IFRS Accounting Standards, the less burdensome disclosure requirements in IFRS 19, compared with full IFRS Accounting Standards, are expected to reduce the ongoing time, cost and effort involved in preparing financial statements. Cost savings will vary depending on the extent of the disclosure reporting before transitioning to IFRS 19 and the complexity of the transactions.
- For subsidiaries that apply UK GAAP, the expected benefits will depend on whether they applied FRS 101 or FRS 10265:
- For subsidiaries that apply FRS 101 there is no perceived incentive to elect to apply IFRS 19, as indicated by preparers. This is because FRS 101 provides greater cost relief in terms of preparing their financial statements disclosures than they would obtain from using IFRS 1966. Preparers noted that, unlike IFRS 19, FRS 101 provides an exemption from presenting a statement of cash flows, which was reported to be burdensome to prepare.
- For subsidiaries that apply FRS 102, electing to transition to IFRS 19 would entail higher implementation costs, although they may be able to reap group-level benefits from aligned accounting policies with IFRS Accounting Standards (see Section 3 paragraph 3.25).
- For overseas subsidiaries of UK groups67 that decide to transition to IFRS 19 from the relevant local GAAP, the benefits in terms of cost savings will vary depending on the extent of the differences between the local GAAP and IFRS Accounting Standards. These entities may also benefit from removing the need to maintain dual accounting records for their own financial statements and for group reporting purposes. Obviously, adoption of IFRS 19 would depend on the application of the Standard in the respective jurisdictions.
# Group-level analysis
5.44IFRS 19 can be particularly beneficial to groups that have a broad international presence. The application of the Standard among subsidiaries located in different jurisdictions would help align accounting policies within the group. Preparers confirmed this, noting that IFRS 19 uses the same recognition, presentation and measurement requirements as full IFRS Accounting Standards used in the consolidated accounts. IFRS 19 would remove the need to maintain multiple accounting records and eliminate the associated costs. Preparers also reported that they expect the consolidation process to be streamlined and subject to a lower risk of errors due to alignment across the group. The need for reconciliation would also be eliminated.
5.45In particular, groups with SSC preparing multiple subsidiaries' accounts expect efficiency gains because the use of IFRS 19 will reduce the number of local GAAPs being used. IFRS 19 is expected to reduce the costs of preparing eligible subsidiaries' accounts in SSC, reduce the reliance on local GAAP expertise and expedite the audit process. Stakeholder outreach with preparers suggested that groups that use the SSC model, will derive significant benefits from IFRS 19 because of the scale at which the Standard could be applied to generate process efficiencies in financial reporting.
5.46Finally, stakeholders noted that for groups to realise significant benefits, from the alignment of reporting requirements offered by IFRS 19, they will need to have a critical mass of eligible subsidiaries using the Standard. This will depend on the global adoption of IFRS 19, as well as local law in the jurisdictions where their subsidiaries operate68.
Costs for preparers
5.47During outreach, preparers were asked to provide information about the costs they expect to incur, as a result of applying IFRS 19, both at a subsidiary and at a group level.
# Subsidiary-level analysis
5.48Similarly to the benefits, costs incurred by a given subsidiary will depend mainly on the accounting framework it applied prior to transition to IFRS 19.
5.49For subsidiaries that apply IFRS Accounting Standards69:
- One-off costs are expected to be minimal. These are attributable to minor familiarisation costs and some adjustments to their accounting systems and processes. Adjustments may be necessary to filter out the reduced disclosures for the financial statements of subsidiaries that elect to apply IFRS 19.
- Ongoing costs are not expected to be significant. The main ongoing costs these entities would incur relate to updating their knowledge, templates and systems, as future amendments are made to IFRS 19.
5.50For subsidiaries that apply local GAAP70:
- One-off costs may be relatively high. These entities would incur familiarisation, accounting system changes and data processing costs since the local GAAP they previously applied may be significant differences in recognition, measurement and presentation requirements compared to IFRS Accounting Standards. These entities could also incur costs related to staff training, recruiting or reallocating staff with IFRS expertise. Preparers also reported that audit costs may increase at the subsidiary level as auditing IFRS accounts is typically costlier than auditing local GAAP financial statements, since IFRS financial statements may contain more information than the local GAAP financial statements. In general, the magnitude of these costs would depend on how closely aligned the local GAAP is with IFRS and the complexity of the subsidiaries' transactions.
- Ongoing costs may potentially be significant. These entities may experience increased costs to prepare, and have audited, financial statements on an ongoing basis. For instance, preparers reported that the IFRS 19 requirement to prepare a cash flow statement and the associated disclosures would have a significant ongoing cost impact on entities that currently use UK GAAP.
# Group-level analysis
5.51Groups are expected to incur minor, mainly one-off costs upon transitioning to IFRS 19. These are mainly attributable to familiarisation and changes to accounting systems (for example, to remove reduced disclosures from the system and processes). On an ongoing basis, groups will incur costs to remain up to date with the reporting requirements of IFRS 19.
5.52Feedback from preparers suggested that:
- Groups will conduct an internal cost-benefit assessment before transitioning to IFRS 19, which, in itself, will lead to some one-off costs.
- Given that it is a voluntary Standard, there is no mandatory effective date for the application of IFRS 19. Therefore, some groups may set a phased approach for their eligible subsidiaries to transition to IFRS 19. This means that a small number of eligible subsidiaries would transition to the Standard before its application is widened to other eligible subsidiaries in later reporting periods. This would spread the transition costs over several periods and, potentially, reduce them, in comparison to a one-off transition of more eligible subsidiaries at once, by using the early implementation experience to provide efficiencies and education on the effects.
- For groups that will elect to apply IFRS 19, preparers expect a decreased reliance on local GAAP expertise. However, this cost saving would be counterbalanced by higher reliance on IFRS expertise which might incur additional costs.
# Audit costs
5.53Audit costs are discussed as part of preparers' implementation costs, as auditors would pass on some, or all, of the extra audit costs to their clients via increased audit fees.
5.54At a subsidiary level, incremental audit costs will depend on the accounting framework applied by a given subsidiary before applying IFRS 19:
- For subsidiaries that apply IFRS Accounting Standards, audit costs may decrease. This is because application of IFRS 19 would result in a reduced volume of information in the notes subject to audit compared with a set of financial statements prepared under full IFRS Accounting Standards. Two large preparers indicated that they expect only a small decrease in audit costs, given the limited reductions in disclosures.
- For subsidiaries that apply local GAAP, audit costs may increase. This is because the auditors may conduct additional work and charge a higher fee to audit IFRS 19 financial statements, compared with local GAAP.
However, these considerations will depend on the degree of alignment in recognition, presentation, measurement and disclosure between IFRS and local GAAP, as well as the size and complexity of the underlying transactions.
5.55At a group-level, preparers indicated that, for groups with subsidiaries in many jurisdictions, the transition to IFRS 19 may be associated with lower audit costs for the group accounts. This is due to a reduction in the number of reconciliation items between the subsidiary local GAAP accounting records and the group reporting records prepared under IFRS.
Costs and benefits to regulators
5.56IFRS 19 is not expected to create significant incremental costs or benefits for regulators. Some of the potential costs may include familiarisation costs and staff training.
5.57There is a limited risk that the information disclosed under IFRS 19 might be insufficient to meet the needs of specific regulators. However, as regulators can typically request additional information from management, beyond that included in financial statements, the reduced disclosure requirements are unlikely to pose a significant risk in this regard71.
Summary of costs and benefits analysis
5.58Users: The financial statements of subsidiaries without public accountability are generally only of interest to a limited number of users external to the group. Feedback received suggested that external users analyse subsidiaries' financial statements infrequently. Therefore, the impact of the reduced disclosures will only materialise under the limited circumstances in which these users analyse subsidiaries' financial statements. Users are expected to benefit from financial statements that contain disclosures which are more tailored to their needs and easier to analyse. User feedback suggested the risk that the reduced disclosures would remove information that is important for their decision-making was very limited. Users are expected to incur negligible one-off costs due to the implementation of IFRS 19.
5.59Preparers[^93]: Given that IFRS 19 is a voluntary Standard, eligible subsidiaries will only apply it if the anticipated benefits outweigh the costs.
- In the majority of cases, the assessment of whether benefits exceed the costs is likely to be carried out at a group level. Groups are expected to reap benefits associated with applying consistent financial reporting requirements, making group-level reporting more efficient and less prone to error. Large groups with a multinational presence are expected to benefit the most from IFRS 19. At a group level, costs are mainly expected to be one-off and related to familiarisation and changes to their reporting systems.
- Subsidiary-level costs and benefits will largely depend on the accounting framework in use before transition. Subsidiaries that apply IFRS Accounting Standards are expected to incur very minor one-off implementation costs which are likely to be outweighed by ongoing cost savings gained in the long term. Subsidiaries that apply local GAAPs will likely incur more substantial transition costs, though the extent of these costs will depend on alignment between local GAAP and IFRS Accounting Standards.
- In general, the ongoing costs of IFRS 19 are expected to be much lower than the one-off transition costs.
- Importantly, the nature and extent of the costs and benefits of IFRS 19 will vary based on each entity's unique circumstances.
- Some entities (either groups or subsidiaries) may incur familiarisation costs when considering adopting IFRS 19 but ultimately determining that the costs do not outweigh the benefits.
5.60Regulators are not expected to be adversely affected by the reduced disclosure requirements of IFRS 19.
Analysis of wider economic effects
Approach used for this assessment
5.61The assessment of the long term public good involves a consideration of whether the use of IFRS 19 is likely to have an adverse effect on the economy of the UK, including on economic growth. These are referred to as “wider economic effects".
5.62With reference to research published by the UKEB[^94], IFRS Accounting Standards are generally associated with the following wider economic effects:
- Transmission mechanisms: how the new requirements affect the way information is communicated to internal and external stakeholders. These include effects on management's stewardship, consistent with previous work[^95].
- First-order indirect effects: capital market effects triggered by the enhanced interaction between users and capital markets.
- Second-order indirect effects (real effects): microeconomic effects that go beyond capital markets (e.g. product & pricing decisions or effects on tax obligations and dividend distribution).
- Third-order indirect effects: micro and macroeconomic effects that go beyond microeconomic agents involved in the accounting systems (e.g. externalities, network effects and macroeconomic effects).
Transmission mechanisms
Preparers
5.63The UKEB considered the potential impact of IFRS 19 on the following transmission mechanisms:
- Management's stewardship. IFRS 19 is not expected to have a significant impact on the presentation of management's use of economic resources, transparency over management's performance, or management's discretion in presenting the entity's financial performance. This is on the basis that IFRS 19 does not alter recognition and measurement requirements. IFRS 19 also requires subsidiaries to provide additional information to their users, when necessary[^96]. This mitigates the risk that information presented in the financial statements will be insufficient to assess subsidiaries' management's stewardship.
- How information circulates within the organisation. The effect of IFRS 19 on the transmission of information within a group is likely to vary based on the existing set-up of reporting systems within the group:
- For groups comprised of subsidiaries that exclusively use IFRS Accounting Standards, the reduced disclosure requirements are unlikely to have a significant impact.
- For groups comprised of subsidiaries that use various local GAAPs, IFRS 19 could improve the transmission of information within the organisation. If IFRS 19 was applied by all the subsidiaries within these groups, finance teams may benefit from more comparable information as there would be a more widespread use of IFRS among subsidiaries. This may enhance management's decision-making and improve corporate governance.
- Streamlining of internal systems and processes. IFRS 19 may enhance reporting systems and processes by allowing preparers to simplify their accounting templates and allowing them to remove the applicable disclosures from their systems. These changes will expedite the overall financial reporting process. Additionally, IFRS 19 may eliminate the need to maintain accounting records prepared using different accounting frameworks.
First-order indirect effects (capital market effects)
5.64To the extent that lending to subsidiaries is not centralised, subsidiaries that transition from local GAAP to IFRS Accounting Standards, to apply IFRS 19, may experience modest improvements in access to finance, due to the widespread adoption of IFRS recognition, measurement and presentation principles throughout the group. Feedback from users suggests that the application of IFRS 19 would not affect an entity's ability to raise funds.
Second-order indirect effects
5.65Since the economic impact of IFRS 19 will be relatively small, second-order indirect effects are generally not expected.
5.66Some effects on competition may be expected. Stakeholder feedback suggested that IFRS 19 could make corporate acquisitions marginally more attractive as target entities that apply IFRS Accounting Standards may be eligible to apply the reduced disclosure requirements.
Third-order effects
Macroeconomic effects, including economic growth
5.67IFRS 19 is aligned with the UK Government's position of reducing companies' regulatory burden to promote economic growth[^97]. IFRS 19 is expected to lower compliance costs for businesses, which may have a positive long-term impact on innovation and productivity, thereby supporting economic growth and competitiveness within the UK.
5.68No significant macroeconomic effects are anticipated as a direct result of IFRS 19 requirements[^98]. However, to the extent that preparers experience a change in the cost of capital or access to finance, IFRS 19 could produce higher order impacts on investment and consumption in the UK economy.
Summary of the analysis of wider economic effects
5.69Overall, IFRS 19 is not expected to lead to wider economic effects that are detrimental to the UK economy, including on economic growth.
Consideration of the consequences of not adopting IFRS 19 (counterfactual analysis)
5.70This section considers the consequences of not adopting IFRS 19 for use in the UK (the 'non-adoption scenario'). The analysis assumes that IFRS 19 is widely adopted in other jurisdictions.
5.71In a non-adoption scenario, UK-registered subsidiaries are not likely to be adversely affected in the short to medium-term. This is because UK GAAP already has a widely used reduced disclosure framework, FRS 101[^99]. As noted, stakeholders' feedback suggested that appetite for adoption of IFRS 19 among UK-registered subsidiaries is limited.
5.72However, if the Standard is not adopted in the UK, UK subsidiaries would not have the option to apply IFRS 19. This may have negative consequences as:
- UK subsidiaries of overseas groups would not be able to transition to IFRS 19, reducing the overall group-level benefits of applying IFRS 19[^100].
- Application of IFRS 19 may facilitate direct access to finance by subsidiaries by enhancing international comparability.
5.73In addition, and as noted by stakeholders, IFRS 19 is likely to deliver greater benefits, the higher the number of jurisdictions that adopting the Standard. As a consequence, individual jurisdictions have an interest in adopting the Standard to guarantee widespread use of IFRS 19 for groups that have subsidiaries with a broad international presence. In a non-adoption scenario, UK groups with overseas subsidiaries are unlikely to be adversely affected if there is widespread adoption of IFRS 19 in other jurisdictions, as the overseas subsidiaries of UK groups would be able to apply IFRS 19.
5.74These considerations suggest that, while not adopting IFRS 19 for use in the UK is unlikely to have a strong negative impact on UK entities in the short-term, the UK has an interest in applying the Standard to facilitate its widespread adoption, upon which long-term economic benefits for preparers rely. In a non-adoption scenario, UK subsidiaries would not have the option of applying IFRS 19, which would reduce the group-level benefits for overseas group and potentially affect access to finance for UK-registered entities.
Overall assessment
5.75Overall, based on an holistic assessment of the evidence reported in this section, the UKEB considered that the use of IFRS 19 is likely to be conducive to the long term public good in the UK
6 True and fair view assessment
Introduction
6.1This section considers whether IFRS 19 is not contrary to the true and fair view principle for individual and consolidated accounts.
Legislative basis and our approach to the assessment
6.2The UKEB is required to consider whether an international accounting standard being assessed for use in the UK meets certain legislative criteria set out in Regulation 7 (1) of SI 2019/685. The first criterion set out in that regulation requires that an international accounting standard can be adopted only if:
"[....] the standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]"
6.3In this section of the ECA we consider whether IFRS 19 meets this endorsement criterion. For the sake of brevity, we refer to our assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair view principle'. However, these abbreviated expressions do not imply that our assessment has considered anything other than the full terms of the endorsement criterion set out above.
6.4The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair view principle. In other words, it is an ex-ante assessment. We have therefore considered whether IFRS 19 contains any requirement that would prevent accounts prepared using the standard from giving a true and fair view.
6.5Our approach is to determine whether IFRS 19 is not contrary to the true and fair view principle in respect of any of the items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. In carrying out our assessment of the impact of IFRS 19, we have also considered the disclosures required by the Standard and its interaction with other UK-adopted international accounting standards.
6.6For the purposes of our assessment, we consider the requirement in paragraph 6A IAS 8 Basis of Preparation of Financial Statements to 'present fairly the financial position, financial performance and cash flows of an entity'[^101] to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
6.7Our assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
Interaction with other UK-adopted international accounting standards
6.8We have considered whether the application of IFRS 19 would necessarily create distortions in its interaction with other UK-adopted international accounting standards.
6.9IFRS 19 is a reduced disclosure standard and does not change the recognition, measurement and presentation of the items in the financial statements for those eligible subsidiaries applying full IFRS Accounting Standards that elect to transition to the Standard. Therefore, it is unlikely that IFRS 19 will have a negative impact on other UK-adopted international accounting standards.
6.10In addition, feedback from stakeholders, and our own assessment in Section 4, has not indicated that any distortions arising from the interaction of IFRS 19 with other UK-adopted international accounting standards are a major concern for UK stakeholders.
Reduced disclosures
6.11Disclosures play a role in ensuring that financial statements are relevant and contribute to a faithful representation of an entity's assets, liabilities, equity, income and expenses.
6.12IFRS 19 eliminates disclosures required in full IFRS Accounting Standards that have been assessed to be of less relevance to users of eligible subsidiaries' financial statements.
6.13However, paragraph 6 of the Standard does require eligible subsidiaries to consider whether additional disclosures are needed to meet users' information needs and to provide these disclosures when necessary. This requirement will contribute to maintaining the usefulness of the financial statements for users.
6.14In addition, feedback from stakeholders, and our own assessment in Section 4, indicates that the disclosures under IFRS 19 are likely to be sufficient to provide a complete and reliable depiction of an eligible subsidiary's assets, liabilities, financial position and profit or loss, and that the reduction in disclosures is not a major concern for UK stakeholders.
6.15Consultation feedback on the ECA indicated that stakeholders generally agreed with the UKEB's tentative conclusion that IFRS 19 was not contrary to the true and fair view principle.
6.16Section 4 of this ECA concludes that IFRS 19 as a whole meets the technical accounting criteria. The technical accounting criteria refer to reliability which includes the notion of faithful representation of the economic substance of transactions and events (see Appendix B of the ECA). The technical accounting criteria assessment therefore further underpins the overall true and fair view assessment.
6.17Our assessment has not indicated that the reduced disclosures of IFRS 19 would prevent individual accounts prepared using the Standard from giving a true and fair view of the entity's assets, liabilities, financial position and profit or loss. We are satisfied, therefore, that the circumstances in which the application of IFRS 19 would result in accounts which did not give a true and fair view would be extremely rare.
6.18SI 2019/685 requires an assessment of whether IFRS 19 is not contrary to the true and fair view principle for both individual and consolidated accounts. We have not identified any reason why the IFRS 19 true and fair view assessment should conclude differently for consolidated accounts[^102].
Overall conclusion
6.19Overall, therefore, we conclude that IFRS 19 is not contrary to the true and fair view principle set out in Regulation 7 (1) (a) of SI 2019/685.
7 Is IFRS 19 likely to lead to a significant change in accounting practice?
Introduction
7.1This section considers whether IFRS 19 is likely to lead to a significant change in accounting practice for the purposes of the statutory requirements set out below.
UK statutory requirements
7.2Paragraphs 1-4 of Regulation 11 of SI 2019/685 require a review of the impact of the adoption of an international accounting standard[^103] when this standard is likely to lead to a significant change in accounting practice. These paragraphs are reproduced below (emphasis added):
"(1) The Secretary of State must publish a statement setting out the Secretary of State's policy on what amounts to a significant change in accounting practice, and must keep this policy statement under review. (2) Paragraphs (3) and (4) apply in relation to the adoption of any standard by the Secretary of State under regulation 6 which the Secretary of State considers likely to lead to a significant change in accounting practice. (3) The Secretary of State must—
- carry out a review of the impact of the adoption of the standard; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used).
(4) The Secretary of State may carry out subsequent reviews from time to time, and in the event of doing so the Secretary of State must publish a report setting out the conclusions of any review conducted.”
Due Process Handbook requirements
What constitutes a significant change in accounting practice?
7.3Paragraph 1 of Regulation 11 of SI 2019/685 does not define the term 'significant change in accounting practice'. However, it does require the UKEB to publish a statement setting out its policy on what amounts to a significant change in accounting practice. This can be found in paragraph 8.6 of the UKEB Due Process Handbook:
Whether or not a standard adopted under Regulation 6 is likely to lead to a 'significant change in accounting practice' will usually depend on the number of entities affected and the impact on those entities and may require judgement. It usually occurs when a new standard is issued by the IASB.
Approach to the assessment
7.4In this section we consider whether IFRS 19 is likely to lead to a 'significant change in accounting practice'.
7.5The UKEB has considered for this assessment:
- the number of entities that will be affected by IFRS 19; and
- the potential impact on entities applying the requirements in IFRS 19.
The number of entities that will be affected by IFRS 19
7.6IFRS 19 is a voluntary standard that is restricted to subsidiaries that do not have public accountability and, as discussed in Section 3, is expected to be applicable to:
- UK subsidiaries of UK group companies; and
- UK subsidiaries of group companies with overseas parents.
7.7In addition, UK group companies with overseas subsidiaries may also choose to apply IFRS 19 when preparing accounts for their overseas subsidiaries, to the extent that the standard is available for use in the relevant jurisdictions.
7.8Feedback from outreach with preparers has indicated that UK groups with only UK-registered subsidiaries are likely to continue to use FRS 101.
7.9Given the nature of the Standard, and feedback on its attractiveness, the UKEB does not expect a significant uptake in the UK.
Potential impact on entities applying the requirements in IFRS 19
7.10IFRS 19 is a disclosure-only standard and is not expected to bring a significant change in accounting practice as:
- It does not introduce new disclosure requirements. The disclosure requirements in IFRS 19 are a subset of existing disclosure requirements in other IFRS Accounting Standards.
- It offers relatively few reductions to the required disclosures in full IFRS Accounting Standards.
- It does not include requirements on how entities recognise, measure and present items in the financial statements. This means that those eligible subsidiaries applying full IFRS Accounting Standards, before transitioning to IFRS 19, will continue applying the same recognition, measurement and presentation requirements in preparing financial statements. This means that applying IFRS 19 will impact the disclosures rather than other aspects of how items are accounted for in subsidiary financial statements.
Overall conclusion
7.11Having considered the above, the UKEB does not consider that IFRS 19 will bring a significant change in the way eligible subsidiaries prepare the primary financial statements and communicate information in the notes. As a result, it concludes that IFRS 19 is not likely to lead to a significant change in accounting practice and does not meet the criteria requiring a mandatory post-implementation review (PIR) under Regulation 11 in SI 2019/685.
Appendix A: Glossary
| Term | Description |
|---|---|
| The Amended Standard or the Standard | IFRS 19, the Amendments and further consequential amendments published by the IASB in 2024 |
| The Amendments | Amendments to IFRS 19 issued in August 2025 |
| BRF | Better Regulation Framework |
| CBA | Cost benefit analysis |
| [Draft] ECA | Draft Endorsement Criteria Assessment |
| ECA | Endorsement Criteria Assessment |
| ED | Exposure Draft |
| EFRAG | European Financial Reporting Advisory Group |
| Eligible subsidiary | An eligible subsidiary is one that is eligible to apply IFRS 19 |
| EU | European Union |
| FCL | Final Comment Letter |
| FRC | Financial Reporting Council |
| FRS | UK Financial Reporting Standard |
| FRS 101 | Reduced Disclosure Framework (a UK GAAP standard) |
| FRS 102 | The Financial Reporting Standard applicable in the UK and Republic of Ireland (a UK GAAP standard) |
| FRS 103 | Insurance Contracts (a UK GAAP standard) |
| FRS 105 | The Financial Reporting Standard applicable to the Micro-entities Regime (a UK GAAP standard) |
| GAAP | Generally Accepted Accounting Principles |
| IAG | UKEB Investor Advisory Group |
| IASB | International Accounting Standards Board |
| IFRS | International Financial Reporting Standard(s) |
| LSE | London Stock Exchange |
| NCI | Non-controlling interest; a minority shareholder |
| Notes | Disclosure notes to the financial statements |
| PIE | Public interest entity |
| PIR | Post-implementation review (of an accounting standard) |
| SMEs | Small and Medium-sized Entities |
| SSC | Shared service centre (used by some groups to centralise subsidiaries' financial reporting) |
| SI 2008/410 | UK Statutory Instrument 2008/410: The Large and Medium-sized Companies and Groups (Accounts and Reports) Regulations 2008 |
| UKEB | UK Endorsement Board |
Appendix B: UK statutory requirements for adoption and the approach to the endorsement criteria assessment
Introduction
B1.This appendix sets out the UK statutory requirements for the adoption of new or amended international accounting standards, and the endorsement criteria assessment approach.
UK statutory requirements
B2.Paragraph 1 of Regulation 7 of SI 2019/685[^104] requires that an international accounting standard only be adopted if:
- the standard[^105] is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
Approach to the endorsement criteria
B3.This ECA assesses the criteria above, in the following order:
- Whether the Standard meets the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c)). We refer to these criteria collectively as the 'technical accounting criteria' (refer to Section 4).
- Whether use of the Standard is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)). Regulation 7(2) of SI 2019/685 includes specific areas to consider for this assessment (refer to Section 5). They are:
- whether the Standard is likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the Standard; and
- whether the Standard is likely to have an adverse effect on the economy of the UK, including on economic growth.
- Whether the Standard is not contrary to the principle that an entity's accounts must give a true and fair view (Regulation 7(1)(a)) (refer to Section 6).
Technical accounting criteria: Relevance, Reliability, Understandability and Comparability 72
B4 A description of the technical accounting criteria73 is provided below:
| Criterion | Description |
|---|---|
| Relevance | Information is relevant if it is capable of making a difference in the decision-making of users or in their assessment of the stewardship of management. The information may aid predictions of the future, confirm or change evaluations of the past, or both. |
| Reliability | Financial information is reliable if, within the bounds of materiality, it: a) can be depended on by users to represent faithfully what it either purports to represent or could reasonably be expected to represent; b) is complete; and c) is free from material error and bias. |
| Understandability | Financial information should be readily understandable by users with a reasonable knowledge of business and economic activities and accounting, and a willingness to study the information with reasonable diligence. |
| Comparability | Information is comparable if it enables users to identify and understand similarities in, and differences among, items. Information about an entity should be comparable with similar information about other entities and with similar information about the same entity for another period. |
B5 In conducting the overall assessment against the technical accounting criteria, the UKEB adopts an absolute, rather than a relative, approach. This is an absolute assessment against the criteria (does IFRS 19 provide information that is understandable, relevant, reliable and comparable?) rather than a relative one (does IFRS 19 provide information that is more or less understandable, relevant, reliable and comparable than current, or any other, accounting standard(s) i.e. UK Generally Accepted Accounting Principles (UK GAAP) or full IFRS Accounting Standards?).
B6 As explained in Section 4, given the nature of IFRS 19 i.e. a voluntary, disclosure-only standard applicable only by eligible subsidiaries of group entities, the UKEB has conducted a high-level analysis against the technical accounting criteria by considering 'key aspects' of reduction in disclosures (an 'exceptions-based approach'). The objective is to explain that financial statements prepared under IFRS 19 have the potential to 'enhance' or 'maintain' one or more of the qualitative characteristics.
B7 A separate comparative consideration of whether IFRS 19 is likely to enhance or maintain the quality of financial reporting is included within the UK long term public good assessment in Section 5.
Whether IFRS 19 is likely to be conducive to the long term public good in the UK 74
B8 Regulation 7(2) of SI 2019/685 sets out certain matters that are required to be considered in the assessment of whether a standard is likely to be conducive to the long term public good in the UK. These are:
B9 When assessing whether the use of IFRS 19 is likely to improve or maintain the quality of financial reporting, the UKEB performs a relative assessment of whether the information required by IFRS 19 is likely more or less understandable, relevant, reliable and comparable than that specified by UK GAAP or full IFRS Accounting Standards respectively.
B10 When assessing the costs and benefits that are likely to result from the use of IFRS 19 the UKEB considers both the initial costs/benefits associated with the implementation of IFRS 19, as well as the expected ongoing costs and benefits over future years. This allows an assessment of the economic effects over the longer-term, consistent with the assessment of the long term public good in the UK.
B11 When assessing whether the use of a new accounting standard is likely to have an adverse effect on the economy of the United Kingdom, including on economic growth, the UKEB assesses the potential impact of the standard beyond direct costs and benefits, including capital market effects (e.g. cost of capital), microeconomic factors such as products, pricing and competition, and the national economy.
True and fair view assessment75
The first adoption criterion, set out in Regulation 7(1) of SI 2019/685, states that an international accounting standard can only be adopted if:
B12 For the sake of brevity, UKEB refers to the assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair principle'. However, these abbreviated expressions do not imply that the assessment has considered anything other than the full terms of the endorsement criterion set out above.
B13 The duty of the UKEB under Regulation 7(1)(a) is to determine generically, whether that standard is 'not contrary' to the true and fair principle. In other words, it is an ex-ante assessment. The UKEB has therefore considered whether the IFRS 19 contain any requirements that would prevent accounts prepared using the IFRS 19 from giving a true and fair view.
B14 The approach is to determine whether IFRS 19 is not contrary to the true and fair principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of IFRS 19 taken as a whole, including its interaction with other UK-adopted international accounting standards.
B15 For the purposes of the assessment, the UKEB considers the requirement in paragraph 6A IAS 8 Basis of Preparation of Financial Statements to 'present fairly the financial position, financial performance and cash flows of an entity'76 to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
B16 This assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
Does IFRS 19 lead to a significant change in accounting practice?
B17 A standard adopted by the UKEB, under Regulation 6 of SI 2019/685, that it considers is likely to lead to a 'significant change in accounting practice', is subject to the requirements in paragraph 3 of Regulation 11 of SI 2019/685. This requires the UKEB to:
"[...] c) carry out a review of the impact of the adoption of the standard; and d) publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)".
B18 Section 7 discusses whether IFRS 19 leads to a significant change in accounting practice.
Appendix C: Overarching differences between IFRS 19 and FRS 101
C1 The table below highlights the overarching differences between the two standards:
| Topic | IFRS 19 | FRS 101 |
|---|---|---|
| Accounting framework | Financial statements prepared by an eligible subsidiary in accordance with IFRS 19 are IAS accounts. | Financial statements prepared by a qualifying entity in accordance with FRS 101 are Companies Act individual accounts. |
| Scope | IFRS 19 is restricted to subsidiaries that do not have public accountability. | FRS 101 is not restricted to entities that do not have public accountability. FRS 101 may be applied to the individual financial statements of a qualifying entity77. |
| IFRS 19 can also be used in consolidated financial statements prepared by an intermediate parent, because it would also be a subsidiary. | FRS 101 is only available for use in individual financial statements. | |
| IFRS 19 can only be applied by eligible subsidiaries i.e. it is not available to ultimate parents. | FRS 101 is available for use in the individual financial statements of ultimate parent companies, as well as subsidiaries. | |
| Eligibility criteria | IFRS 19 requires that the consolidated accounts in which the entity is included are prepared in accordance with IFRS Accounting Standards and are available for public use. | FRS 101 does not require the group accounts into which the entity has been consolidated to be prepared under IFRS only that they are intended to give a true and fair view. It can therefore be adopted by entities which are consolidated into financial statements prepared under certain frameworks other than IFRS, such as US GAAP. |
| Approach | IFRS 19 adopted a 'bottom-up approach' setting out reduced disclosure requirements that are required. | FRS 101 adopted a 'top-down approach' by providing exemptions from specific disclosure requirements of adopted IFRS. |
| Principles for reducing disclosures | Disclosure requirements in IFRS Accounting Standards satisfying the following principles78 are required by IFRS 19: | The following principles79 for determining the disclosure requirements in adopted IFRS which should be required for qualifying entities are applied: |
| - Liquidity and solvency: an entity's ability to generate cash flows and continue as a going concern. | - Relevance: Does the disclosure requirement provide information that is capable of making a difference to the decisions made by the users of the financial statements of a qualifying entity? | |
| - Short-term cash flows, obligations, commitments and contingencies: an entity's ability to meet its obligations. | - Cost constraint on useful financial reporting: Does the disclosure requirement impose costs on the preparers of the financial statements of a qualifying entity that are not justified by the benefits to the users of those financial statements? | |
| - Measurement uncertainty: significant judgements and estimates used by management. | - Avoid gold plating: Does the disclosure requirement override an existing exemption provided by company law? | |
| - Disaggregation of amounts: separation of amounts presented in the financial statements. | ||
| Preparation of statement of cash flows | Requires the presentation of a statement of cash flows. | No requirement to produce a statement of cash flows. |
| Disclosure objectives | IFRS 19 excludes all disclosure objectives because including such objectives in IFRS 19 might result in the perception that entities are required to provide the same disclosures they would otherwise have provided had they not applied IFRS 19. | No automatic exemption from disclosure objectives although FRS 101 does provide some exemptions from the disclosure objectives of IFRS–in particular those in IFRS 7 Financial Instruments: Disclosures and IFRS 13 Fair Value Measurement, as long as equivalent disclosures are present in the consolidated financial statements in which the entity is included. FRS 101 also removes part of the disclosure objectives of IFRS 15 Revenue from Contracts with Customers and IFRS 16 Leases, but unconditionally. |
| Exemptions if equivalent disclosures made in group accounts | No 'equivalent disclosures' condition for exemption from disclosure requirements mainly because the financial statements of subsidiaries should be 'stand-alone' i.e. they must provide users with all the information they need without those users having to consult the parent's consolidated financial statements. | Certain disclosure exemptions are available in some areas, subject to the condition that equivalent disclosures are included in the consolidated financial statements of the group in which the entity is consolidated, for example, in relation to share-based payments (IFRS 2), acquisitions (IFRS 3), impairment (IAS 36), certain disclosures in respect of International Tax Reform – Pillar Two Model Rules (IAS 12). |
| Disclosure of exemptions taken | Not applicable. | A qualifying entity taking advantage of FRS 101 must include in the notes to its financial statements a brief narrative summary of the disclosure exemptions taken. |
| Compliance statement | An eligible subsidiary applying IFRS 19 asserts compliance with IFRS Accounting Standards, including the Standard. | A qualifying entity taking advantage of FRS 101 should include a statement stating: "These financial statements were prepared in accordance with Financial Reporting Standard 101 Reduced Disclosure Framework." |
Appendix D: Evidence about the costs and benefits of IFRS 19
D1 This Appendix reports detailed evidence that underpins the costs and benefits analysis conducted as part of the long term public good assessment in Section 5.
Evidence from qualitative interviews with lenders
D2 The following paragraphs summarise views that emerged from engagement with lenders, which underpins the analysis reported in the main body of the Endorsement Criteria Assessment.
D3 Lenders support IFRS 19. Feedback suggested that IFRS 19 would be beneficial to large financial institutions with multinational clients as it would reduce the number of local GAAPs that they potentially have to deal with when conducting their analyses. Additionally, one lender mentioned that by making the consolidation process simpler, IFRS 19 could potentially allow preparers to publish financial statements earlier, therefore benefitting lenders and other users.
D4 Lenders agree that applying the principles the IASB used to reduce disclosures would not remove decision-useful information. This is on the basis that the principles preserve information about a subsidiary's ability to generate cash and settle its obligations80. These considerations are important to lenders as their main concern is entities' ability to service their debt as well as assessing the likelihood of default.
D5 Lenders generally focus on subsidiaries' headline financial metrics. Examples include cash flow, profit, EBITDA and other large and material items (e.g. significant off-balance sheet pension liabilities). The reduced disclosures are therefore not expected to adversely affect lenders but allow them to navigate subsidiaries' accounts more efficiently.
D6 Lenders analyse subsidiaries' accounts relatively infrequently. This is because in most circumstances entities either borrow at a group level or provide intra-group guarantees. Lenders mainly analyse subsidiaries' accounts to investigate specific issues (e.g. a significant change in the subsidiary's performance or a covenant breach) or when intra-group guarantees are not provided (e.g. to subsidiaries in given jurisdictions or industries).
D7 Lenders rely on the cash flow statements for their decisions. Lenders indicated that the requirement to prepare a statement of cash flows under IFRS 19 is welcome, as the cash flows statement provides them with decision-useful information.
The potential impact of IFRS 19 on preparers: case studies
D8 The UKEB has prepared three case studies to illustrate how IFRS 19 will affect groups with different characteristics.
D9 Table D1 mainly aims to provide information that would help the Board decide on adoption. However, it may also help preparers weigh expected costs and benefits when deciding whether to apply IFRS 19.
D10 The case studies are based on interviews conducted with preparers of financial statements.
D11 In the three case studies, individual subsidiaries apply either local GAAP (including FRS 101 for UK subsidiaries) or IFRS Accounting Standards.
Table D1: Case studies – Impact of IFRS 19
| Small-sized de-centralised group | Medium-sized group with some centralisation | Large, complex, highly centralised group | |
|---|---|---|---|
| Structure of the group | 100 subsidiaries in 20 jurisdictions. | <200 subsidiaries in 40 jurisdictions, most of which are in one region. | >800 subsidiaries in over 100 jurisdictions. |
| Reporting systems and processes within the group | Local statutory accounts are prepared by financial reporting teams within each subsidiary using local GAAP or IFRS (depending on applicable local law). Local accounts are then reconciled with IFRS for the purpose of group reporting. | Regional shared service centres (SSC) are responsible for subsidiaries' statutory reporting within their region. SSC are relatively decentralised from the ultimate parent company. Subsidiaries prepare their financial information in accordance with IFRS for group reporting. Local statutory accounts are prepared using local GAAP, as required by local and regional law. | Global finance teams in a small number of SSC prepare multiple sets of subsidiary financial statements, following directions from the finance team at group-level. Subsidiary statutory reporting is highly controlled by the group. Subsidiaries prepare their financial information in accordance with IFRS for group reporting. Local statutory accounts are prepared using local GAAP or IFRS, depending on applicable local law. |
| Cost and benefit implications | Subsidiary-level Benefits: Under IFRS 19, subsidiaries would no longer need dual accounting records for local statutory and group reporting. Costs: Because accounts preparation is relatively de-centralised, implementation costs of IFRS 19 will mainly be incurred at the subsidiary level. |
Subsidiary-level Benefits: Subsidiaries will no longer need dual accounting records for local statutory and group reporting, if they are permitted to use IFRS 19 for their statutory accounts. Costs: Little to no costs to be incurred at the subsidiary level. |
Subsidiary-level Benefits: Under IFRS 19, subsidiaries would no longer need dual accounting records for local statutory and group reporting. Costs: Little to no costs to be incurred at the subsidiary level. |
| Group-level Benefits: IFRS 19 could allow the group to align the reporting frameworks used by all subsidiaries. Costs: Little to no costs to be incurred at a group level. |
Group-level Benefits: IFRS 19 could align the reporting frameworks used by subsidiaries within the group. This could result in simplifications to processes at SSC. Costs: The costs of IFRS 19 will primarily be incurred by the regional SSC. They may include familiarisation costs, training and recruiting staff with IFRS expertise. |
Group-level Benefits: IFRS 19 will allow the group to align reporting frameworks used by many or all subsidiaries, reduce the reliance on local GAAP expertise and remove the need for dual reporting. The group will potentially be able to standardise the preparation of financial statements under IFRS 19 for subsidiaries in multiple jurisdictions. Costs: The costs of implementing IFRS 19 will primarily be incurred at the group level. |
D12 To summarise, the extent to which the costs and benefits of IFRS 19 materialise at a group or individual subsidiary level, would depend on how centralised the preparation of consolidated financial statements is.
- Decentralised groups are characterised by subsidiaries that prepare their own financial statements and that submit consolidation packages to the parent company. These groups do not have centralised financial reporting processes. In such groups, the cost of implementing IFRS 19 will primarily be incurred at the level of the individual subsidiary. The benefits of IFRS 19 will mainly materialise at the level of the individual subsidiary, in the form of reporting simplifications. Some benefits would be also observed at the group level, through the alignment of accounting requirements.
- In highly centralised groups, SSC prepare the subsidiaries' financial statements. In these groups, the costs and benefits of IFRS 19 will mainly materialise at the group level.
Third-party work on the economic assessment of IFRS 19
D13 Desk-based research forms part of the evidence that the UKEB used for the ECA. This section summarises the work carried out by other organisations on the costs and benefits of applying IFRS 19 (the Standard). The results of third-party research are broadly in line with those reported by the UKEB in this ECA.
IASB Effects Analysis
D14 Upon publishing IFRS 19, the IASB published an Effects Analysis to accompany the Standard 81. The Effects Analysis outlines the costs and benefits that the IASB expects the Standard to generate at an international level.
D15 The IASB gathered evidence through formal consultation, direct outreach with stakeholders, fieldwork and input received from advisory bodies.
D16 The IASB's evaluation of effects was mainly qualitative. The rationale given was that quantifying costs, and particularly benefits, is subjective and difficult.
D17 The main results of the analysis are outlined in paragraphs D18-D22 below.
Determinants of effects
D18 The costs and benefits (collectively ‘effects') of the Standard will vary depending on factors such as:
- the accounting standards applied by eligible subsidiaries prior to transition;
- the reporting systems and processes within the group;
- the number of subsidiaries within the group that choose to apply IFRS 19;
- the size and complexity of the subsidiaries' operations; and
- local law and regulation.
D19 In addition, the IASB notes that the magnitude of both costs and benefits will depend on the number of subsidiaries that apply the Standard globally.
Costs
D20 Preparers: Subsidiaries are anticipated to incur some one-off implementation costs, although these costs are not expected to be significant. They are mainly attributable to changes to systems and processes and familiarisation with the requirements of the Standard. In addition, implementation costs may arise for the group as a whole, depending on the set-up of the reporting systems and processes within the group. The IASB anticipates that, in most cases, the implementation costs of the Standard will be outweighed by the ongoing cost savings in subsequent periods. Furthermore, the IASB notes that an entity may choose not to apply IFRS 19 if it concludes that the implementation costs outweigh the benefits, since the Standard will be applied on voluntary basis.
Benefits
D21 Preparers: Eligible subsidiaries are anticipated to benefit from reporting simplifications, which reduce the time, cost and effort involved in preparing the accounts. The Standard also allows companies to benefit from aligning accounting policies within the group, thus removing the need for dual accounting records and eliminating the associated costs. Cost reductions may also include potential reductions to subsidiary audit costs if application of IFRS 19 results in a reduced volume of information subject to audit (which will depend on the accounting standards applied by eligible subsidiaries prior to transition).
D22 Users: The IASB developed the reduced disclosure requirements of IFRS 19 using a set of principles that were tested with users of accounts via a survey and interviews82 and are set out in Section 4 and Section 5. The majority of survey respondents were lenders. Most respondents (lenders and others) agreed with the principles developed by the IASB. The development of the Standard using these principles should enable subsidiaries without public accountability to provide proportionate information that meets the needs of users of their accounts. As a result, users of accounts may benefit from simplified accounts that are still relevant for their decision-making.
European Financial Reporting Advisory Group (EFRAG) Draft Endorsement Advice on IFRS 19
D23 In May 2025, EFRAG published its Draft Endorsement Advice on IFRS 19 for public consultation 83. The assessment summarises EFRAG's technical and economic analysis of IFRS 19. In its Draft Endorsement Advice, EFRAG confirmed that IFRS 19 satisfies the criteria for endorsement in the EU and is, therefore, tentatively recommended for endorsement 84.
D24 In September 2025, EFRAG submitted its final endorsement advice to the European Commission (the Commission)85, which recommended the endorsement of IFRS 19. At the time of writing, the Commission is expected to make an endorsement decision within the next few months.
D25 For its assessment, EFRAG gathered evidence through desk-based research, direct outreach with stakeholders and related research. EFRAG also considered the feedback received from their technical expert groups and working groups. The Commission asked EFRAG to conduct a more in-depth cost-benefit analysis on the Standard through preparer and user surveys, outreach meetings and a public education session 86.
D26 This outreach identified that the relevant users of eligible subsidiaries' accounts are typically lenders. However, EFRAG also notes that the user group for these accounts is likely to be 'very limited' because shareholders have access to information they need from other sources, and third-party finance is often guaranteed by the parent. EFRAG notes that some providers of finance, analysts and investors may use eligible subsidiaries' accounts.
D27 EFRAG notes that quantification of costs and benefits appeared difficult for most respondents, so its analysis its qualitative in nature and based on stakeholder feedback. EFRAG notes that costs and benefits will differ between entities, and between jurisdictions within the European Union.
D28 The findings of EFRAG's Endorsement Advice are, overall, consistent with the findings of the UKEB.
- charities;
- entities that are both required to apply Schedule 3 to the Regulations and have contracts that are within the scope of IFRS 17 Insurance Contracts, and
- entities that are not companies but are both required to apply requirements similar to those in Schedule 3 to the Regulations and have contracts that are within the scope of IFRS 17.
D27EFRAG notes that quantification of costs and benefits appeared difficult for most respondents, so its analysis its qualitative in nature and based on stakeholder feedback. EFRAG notes that costs and benefits will differ between entities, and between jurisdictions within the European Union.
D28The findings of EFRAG's Endorsement Advice are, overall, consistent with the findings of the UKEB.
Contact Us
UK Endorsement Board 1 Harbour Exchange
| London | E14 9GE www.endorsement-board.uk
Footnotes
-
IFRS 19, para 7 ↩
-
IFRS 19, paras 11-12 ↩
-
Companies Act 2006, s 494A ↩
-
Companies Act 2006, s 519A ↩
-
International Financial Reporting Standards (IFRS), as issued by the International Accounting Standards Board (IASB). ↩
-
IFRS 19 was issued in May 2024 and amended in May 2024, December 2024 and August 2025. ↩
-
Link to SI 2019/685 ↩
-
Link to Final Comment Letter on the ED to develop IFRS 19. ↩
-
IASB ED/2021/7 Exposure Draft: Subsidiaries without Public Accountability: Disclosures. ↩
-
Link to Final Comment Letter on the catch-up ED. ↩
-
IASB ED/2024/5 Exposure Draft: Amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures. In July 2024, the IASB published the 'catch-up' ED which covered disclosure requirements issued between 28 February 2021 and 1 May 2024 that were included in IFRS 19 without disclosure reductions when IFRS 19 was issued in May 2024. ↩
-
The term 'standard' is used to refer to amendments to international accounting standards, in line with the definition of 'international accounting standards' in SI 2019/685, which includes 'subsequent amendments to international accounting standards'. ↩
-
The introduction to the IASB's yearly bound volumes differentiates between mandatory and non-mandatory sections of the standards. Mandatory pronouncements relate to IFRS Standards, IAS Standards, Interpretations and Mandatory Application Guidance. These are UK-adopted international accounting standards. Non-mandatory guidance includes Bases for Conclusions, Dissenting Opinions, Implementation Guidance and Illustrative Examples, together with the IFRS Practice Statements. These are not adopted by the UKEB as they are not international accounting standards, as defined in SI 2019/685. ↩
-
In May 2025, the IASB published Educational Module 1 IFRS for SMEs Accounting Standard (Third Edition) Small and Medium Sized Entities, which provides further guidance on assessing whether an entity has public accountability. ↩
-
This calculation is based on data obtained from Reuters. Subsidiaries that are likely to have public accountability have been excluded from the analysis. These include Banks, Brokerage Services, Collective Investment Fund Operators, Credit Unions, Hedge Funds, Insurers, Investment Managers and Microfinanciers. ↩
-
These figures were calculated by collating a comprehensive list of subsidiaries from the group structure of each listed entity. ↩
-
Due to the classification methodology within the Reuters database, these figures refer to entities that are classified as subsidiaries based on a quantitative measure of ownership (i.e. ownership of 50% +1 of voting stock) as opposed to the qualitative measure of control defined in IFRS 10 Consolidated Financial Statements. ↩
-
UKEB estimate based on FAME (company information in the UK and Ireland produced by the Bureau Van Dijk, a Moody's analytics company), Company Watch financial analytics and other proprietary data. ↩
-
The IFRS 19 eligibility criteria include that the entity does not have public accountability and has a parent (ultimate or intermediate) that produces consolidated financial statements available for public use that comply with IFRS Accounting Standards. ↩
-
Preparer outreach indicated that suppliers of trading subsidiaries may use their financial statements, but that preparers may provide additional information to suppliers if they request it. ↩
-
Excluding banks, insurance companies, funds and trusts. ↩
-
An analysis of NCI disclosures among the 10 largest entities by book value of NCI suggests that a significant proportion of subsidiaries with NCI are likely to have public accountability, for example because they have securities listed on public capital markets. This suggests that, while NCI among UK-listed entities amounts to approx. £40 billion, the economic relevance of NCI among entities potentially in scope of IFRS 19 is expected to be lower. ↩↩
-
Paragraph BC 33 in the Basis for Conclusions of IFRS 19 states that 'In assessing the needs of users of financial statements of eligible subsidiaries, the principles focused on the information needs of these users i.e. information about short-term cash flows, liquidity, measurement uncertainties, disaggregation of amounts in the financial statements and accounting policy choices.' ↩↩
-
Companies Act 2006, ss 395 and 403 ↩
-
IFRS 19, para 14 ↩
-
IFRS 19, paras 21–30 ↩
-
IFRS 19, para 13 ↩
-
A company may switch from UK GAAP to UK-adopted IAS at any time i.e. there are no restrictions, in the Companies Act 2006. However, there are some conditions to satisfy in the Companies Act for a company to switch from UK-adopted IAS to UK GAAP. ↩
-
The disclosure requirements for business combinations are set out in paragraphs 35-37 of IFRS 19 under the sub-heading 'IFRS 3 Business Combinations'. ↩
-
IFRS 3 Appendix A Defined terms defines a business combination as 'a transaction or other event in which an acquirer obtains control of one or more businesses. Transactions sometimes referred to as 'true mergers' or 'mergers of equals' are also business combinations as that term is used in this IFRS.' ↩
-
The disclosure requirements are set out in paragraphs 42-73 of IFRS 19 under the sub-heading 'IFRS 7 Financial Instruments: Disclosures'. They were subsequently amended by the catch-up Amendments and consequential amendments to IFRS 19. ↩
-
Paragraph BC 33 in the Basis for Conclusions of IFRS 19 states that 'In assessing the needs of users of financial statements of eligible subsidiaries, the principles focused on the information needs of these users i.e. information about short-term cash flows, liquidity, measurement uncertainties, disaggregation of amounts in the financial statements and accounting policy choices.' ↩
-
Paragraph B32 of IFRS 18 lists the following as examples of entities that might provide financing to customers as a main business activity: ↩
-
Paragraph 72 of IFRS 19 requires an entity to disclose: ↩
-
Companies Act 2006, s 400 ↩
-
Companies Act 2006, s 401 ↩
-
Companies Act 2006, ss 400 and 401 ↩
-
The disclosure requirements for interests in other entities are set out in paragraphs 74-94 of IFRS 19 under the sub-heading 'IFRS 12 Disclosure of Interests in Other Entities'. ↩
-
IFRS 12, para 1 ↩
-
IASB Effects Analysis (2024) reported a 68% reduction in disclosure requirements for IFRS 12 (page 19). The percentage reduction was calculated by comparing the number of disclosures under the subheading 'IFRS 12' in IFRS 19 and in the full IFRS Accounting Standard. ↩
-
IFRS 19, paras 76–81 ↩
-
IFRS 18, para 10 ↩
-
UKEB Research Paper: Statement of Cash Flows: Background and Key Issues, December 2024 (paragraphs A25-A28). ↩
-
The disclosure requirements for basis of preparation are set out in paragraphs 173 – 187 of IFRS 19 under the sub-heading 'IAS 8 Basis of Preparation of Financial Statements'. ↩
-
The disclosure requirements for income taxes are set out in paragraphs 192-199 of IFRS 19, under the sub-heading 'IAS 12 Income Taxes'. They were subsequently amended by the catch-up Amendments to IFRS 19. ↩
-
IAS 24, para 1 ↩
-
The disclosure requirements for related party transactions are set out in paragraphs 226-237 of IFRS 19 under the sub-heading 'IAS 24 Related Party Disclosures'. ↩↩
-
Schedule 4 Information on related undertakings required whether preparing Companies Act or IAS Accounts. ↩↩
-
The disclosure requirements for impairment of assets are set out in paragraphs 250-256 of IFRS 19 under the sub-heading 'IAS 36 Impairment of Assets'. ↩↩
-
IAS 36, para 134(d) ↩
-
IAS 36, para 134(e) ↩
-
IFRS 19, para 245(d) ↩
-
IFRS 19, para 254(e) ↩
-
Excluding the disclosure requirements relating to IFRS 14 Regulatory Deferral Accounts, as IFRS 14 has not been adopted for use in the UK. ↩
-
IFRS 19, para 6 ↩
-
The BRF applies to "regulatory provisions", defined in paragraph 2.3 of the BRF. Paragraph 2.4 of the BRF clarifies that provisions in scope are made by ministers. ↩
-
The BRF is grounded in the principles of the Green Book, which applies to public entities more broadly (e.g. regulators, arm's length bodies). The Green Book was also consulted to ensure consistency. ↩
-
Direct costs and benefits refer to those are generally immediate and unavoidable (Regulatory Policy Committee: Guidance on direct versus indirect effects). ↩
-
Subsequent effects that occur as a result of the direct impacts, including changes in firm behaviour, are considered indirect effects (Regulatory Policy Committee: Guidance on direct versus indirect effects). ↩
-
Primarily economic assessments conducted by other standard-setters, including the IASB's effects analysis for IFRS 19 and the introduction of FRS 101 in the UK. (See Appendix D) ↩
-
A total of 8 interviews were conducted, including 5 with preparers and 3 with users of financial statements. 10 written responses were received. The UKEB considered that these interviews provided a sufficient evidence base as recurring themes began to emerge from subsequent interviewees. ↩
-
Other users may include regulators and tax authorities. Stakeholder feedback suggested that landlords, customers and suppliers may also use a subsidiary's financial statements, depending on the subsidiary's business model. More specialised users were also noted, including financial modelling professionals and trade credit insurers. ↩
-
Detailed evidence on costs and benefits for entities that decide to apply IFRS 19 is provided to draw conclusions on the potential wider economic effects associated with IFRS 19 and to allow the Board to take an evidence-based decision on the adoption of the Standard, in compliance with SI 2019/685 and in line with the UKEB guiding principles. ↩
-
See Section 3, paras 3.45-3.46 and Table 4 for an explanation of the potential accounting impact of transitioning to IFRS 19. ↩
-
FRS 101 can only be used for individual financial statements, meaning sub-groups within a wider group cannot use FRS 101 for their consolidated financial statements. ↩
-
During outreach with stakeholders, the UKEB collected qualitative evidence on UK preparers' appetite for using IFRS 19. At the time of writing, stakeholder feedback suggested that the appetite for using IFRS 19 among UK subsidiaries was relatively limited. None of the preparers the UKEB engaged with reported that they were planning to use IFRS 19 for their UK-based subsidiaries. ↩
-
Although these entities are not based in the UK, preparer feedback indicated that the cumulative benefit of IFRS 19 would accrue at a group level and would be proportional to the number of overseas subsidiaries that apply the Standard. It is acknowledged that benefits to the local economies may be considered in the costs and benefits assessments of other national standard-setters. ↩
-
In some jurisdictions, unlisted entities are required to prepare their financial statements in accordance with local GAAP e.g. for tax purposes. ↩
-
The considerations in this paragraph would largely apply to subsidiaries that apply FRS 101 as the standard is substantially aligned with IFRS Accounting Standards. However, these subsidiaries would experience high ongoing costs due to the need to produce a cash flow statement. ↩
-
For UK entities, the considerations in this paragraph would largely apply to subsidiaries that apply FRS 102. ↩
-
The following considerations further mitigate this risk. Firstly, subsidiaries in the scope of IFRS 19 do not have public accountability. As these entities do not manage assets in fiduciary capacity, in most cases these subsidiaries are unlikely to pose threats to financial stability. Secondly, these entities do not have publicly traded equity or debt. This minimises the risk that regulatory oversight may be insufficient to protect security holders. Thirdly, it is unlikely that the reduced disclosures would prevent them from being compliant with their regulatory reporting requirements, as emerged from outreach with a preparer in a regulated industry. ↩↩
-
Refer to Section 4 Technical accounting criteria assessment. ↩
-
These descriptions are based on the qualitative characteristics of financial statements in the Framework for the Preparation and Presentation of Financial Statements adopted by the IASB in April 2001. These qualitative characteristics became part of the criteria for endorsement and adoption of IFRS in the EU's IAS Regulation (1606/2002), and, subsequently, in SI 2019/685. ↩
-
The requirement in paragraph 6A of IAS 8 was moved from paragraph 15 of IAS 1 Presentation of Financial Statements unchanged following the issuance of IFRS 18 Presentation and Disclosure in Financial Statements. The title of IAS 8 was changed from Accounting Policies, Changes in Accounting Estimates and Errors to Basis of Preparation of Financial Statements. This change is effective on 1 January 2027. ↩
-
For the purposes of FRS 101, qualifying entity is defined as a member of a group where the parent of that group prepares publicly available consolidated financial statements which are intended to give a true and fair view (of the assets, liabilities, financial position and profit or loss) and that member is included in the consolidation. Thee following are not qualifying entities: ↩
-
IFRS 19 Basis for Conclusions, para BC3 ↩
-
FRS 101 Basis for Conclusions, para 7 ↩
-
Lenders also expressed support for the other principles that were used. They include preserving information about measurement uncertainties, accounting policy choices and the disaggregation of amounts presented in the primary financial statements. ↩
-
IASB Effects Analysis – IFRS 19 Subsidiaries without Public Accountability: Disclosures. ↩
-
The IASB reports interviewing 13 users from 7 jurisdictions, and receiving 54 survey responses, of which 14 were from users. ↩
-
EFRAG's Draft Letter to the European Commission Regarding Endorsement of IFRS 19 Subsidiaries without Public Accountability: Disclosures ↩
-
To assess the long term public good, EFRAG analyses: (a) whether the Standard improves financial reporting, (b) the costs and benefits associated with the Standard, and (c) whether the Standard might have an adverse effect on the European economy, including financial stability and economic growth. ↩
-
Link to the EFRAG Final Endorsement Advice ↩
-
IFRS 19 Subsidiaries without Public Accountability: Disclosures, Summary of the EFRAG's Survey and Outreach Results, Paper 09-02, EFRAG FR TEG meeting, April 2025. This paper states that 10 responses to the survey were received, 9 from preparers and 1 from a user. ↩