Feeback Statement - 2026-2027 Regulatory Strategy
February 2026
Foreword
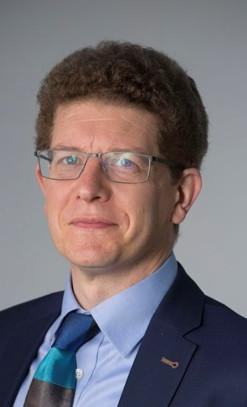
The UK Endorsement Board is pleased to present our response to the thoughtful and welcome comments received from stakeholders on Year 2 of our draft Regulatory Strategy 2025/28, covering the 2026/27 period.
On behalf of the Board, I thank all respondents for their considered feedback.
We expect the next year to be another busy period. The UKEB will continue to focus on the UK long term public good, balancing the needs of investors and businesses, and supporting effective and efficient capital allocation and growth in the economy, through comparable and proportionate reporting standards.
Paul Lee UKEB Chair
Our purpose
The UK Endorsement Board (UKEB) is the UK's National Standard Setter for IFRS, responsible for the endorsement and adoption of IFRS for use in the UK. We also lead the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
Statutory functions:
- participate in, and contribute to, the development of a single set of international financial reporting standards; and
- adopt international accounting standards when they meet the criteria in Statutory Instrument 2019/685 'The International Accounting Standard and European Public Limited-Liability Company (Amendments etc.) (EU Exit) Regulations 2019'.
Other functions:
- consider the connectivity between UK-adopted international accounting standards and IFRS Sustainability Disclosure Standards or UK Sustainability Reporting Standards.
Icon of a target.
Objectives and background
This feedback statement summarises the comments received from respondents during the UKEB's public consultation on the draft 2026/27 Regulatory Strategy and explains the UKEB's position in response to those comments.
The draft 2026/27 Regulatory Strategy was published for consultation on 15 December 2025 and was open for comment for eight weeks, closing on 6 February 2026. During the consultation period, the UKEB promoted awareness of the draft Strategy and Invitation to Comment through various channels including the UKEB website, subscriber news alerts and LinkedIn posts.
The Board received five comment letters, from the following respondents:
- PwC (Auditors and Accounting Firms);
- Mr E Beale (Member of the Public);
- ICAEW (Professional Accountancy Bodies);
- ICAS (Professional Accountancy Bodies); and
- SME Alliance Limited (Membership organisation).
The comment letters were published on the UKEB website, and all feedback was considered when finalising the Strategy.
Summary - Strategy
Respondents supported the UKEB's proposed 2026/27 Regulatory Strategy, both in terms of the overarching strategic objectives and the workplan.
The UKEB's collaborative and open approach was commended, and respondents appreciated the considerable effort it makes to engage with stakeholders.
Stakeholders commented that the UKEB successfully balances its statutory responsibilities of influencing the development of IFRS, and providing thought leadership, and assessing IFRS for endorsement and adoption for use in the UK, contributing to the UK's long term public good.
The UKEB will continue to assess its project prioritisation, its stakeholder engagement activities, and its approach to monitoring and measuring the Board's effectiveness in meeting its statutory objectives. The Board will be seeking to make improvements where possible.
Specific areas of feedback, and the UKEB's responses, are set out on the following pages.
Strategy: Feedback and UKEB response
| Stakeholder feedback | UKEB response |
|---|---|
| 1 Respondents noted the considerable efforts made by the UKEB, throughout 2025, to engage with stakeholders and support the proposal to host a one-day conference which will allow the UKEB to engage with a broader range of stakeholders. | Since the UKEB was established five years ago, it has become a globally respected national standard-setter. The conference will provide the UKEB with an opportunity to showcase its research work and to engage with stakeholders in person. |
| 2 A stakeholder queried why the IASB's Agenda Consultation project, which is a key opportunity for the UKEB to influence the IASB's work, is not a 'significant' project on the workplan. They also queried why the endorsement of IFRS 19 Subsidiaries without Public Accountability: Disclosures is not a 'limited' scope project as it is expected to be completed in early 2026/27. | In the UKEB Work Plan, the designation as 'moderate' relates to the expected workload for the Board and Secretariat during the financial year 2026/27, not the significance or importance of the project. The Agenda Consultation is expected to be a 'moderate' project as it will not require in depth technical analysis. The Board set the endorsement of IFRS 19 Subsidiaries without Public Accountability: Disclosures as a 'moderate' project. This tagging is applicable until the project closes. It does not change as the project spans financial years. However, the reallocation of resources is taken into account in the UKEB's forward planning. |
| 3 A respondent asked how the UKEB plans to consider the interplay between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards and whether any capacity is available for this work. | The UKEB considers whether there are any connectivity issues between IFRS Accounting Standards and IFRS Sustainability Disclosure Standards, as part of each project initiation plan. This is kept under review and any issues identified are considered by the Board. |
| 4 A respondent noted the draft 2026/27 Strategy does not include any detail on how the UKEB might assess its impact. Acknowledging that it is likely to be challenging for certain aspects of its work, the UKEB was asked to indicate how it might assess its impact given the prominence of this topic in the UKEB's 2025/28 Regulatory Strategy. | The UKEB monitors a range of factors when considering its impact. This includes the Board's active monitoring of the IASB's projects at each Board meeting (papers labelled 'IASB Update'), which gives the opportunity to understand the impact of its work on the decisions made at the international level. In addition, invitations to present UKEB work and research at international standard setting fora such as the IASB's Accounting Standards Advisory Forum (ASAF) and the International Forum of Accounting Standard Setters (IFASS) are clear indicators of the significant impact made by the Board. |
Summary - Research
Respondents commended the UKEB on its research work to date on accounting for intangibles and agreed that this remains a topic in which there is considerable stakeholder interest.
Stakeholders expressed their support for the UKEB to consider conducting further research in relation to the following topics, which will be considered by the Board at a future meeting:
- Cryptoassets, extending to other digital assets, such as stablecoins, tokens, and other digital currencies, as well as a broader consideration of intangible assets arising from blockchain;
- Customer-related intangibles recognised in a business combination;
- Carbon and other environmental credits;
- The impact of Artificial Intelligence;
- Levies and non-reciprocal transactions; and
- Acquisition accounting in the insurance sector.
Specific areas of feedback, and the UKEB's responses, are set out on the following page.
Research: Feedback and UKEB response
| Stakeholder feedback | UKEB response |
|---|---|
| 1 Respondents commended the UKEB for its research work to date on accounting for intangible assets and encouraged the UKEB to plan its work in parallel to the IASB's work. However, while they suggested UKEB could continue to build on its 2025/26 case-study based research, clarity on which case studies the UKEB plans to examine was requested. | The UKEB has developed its case studies to complement the work of the IASB. They were presented to the Board at its public meeting in January 2026. |
| 2 Stakeholders made helpful suggestions for other projects that could be added to the UKEB's workplan. Most of these align with existing projects on the agenda or in the pipeline. They also requested that the UKEB workplan include resource allocation for potential research projects as this would provide a more holistic picture of the influencing work of the UKEB. | The UKEB will consider adding a research project pipeline page to its website to allow stakeholders to engage early on potential projects. |
Disclaimer
This feedback statement has been produced to set out the UKEB response to stakeholder comments received on the draft 2026/27 Regulatory Strategy. It should not be relied upon for any other purpose.
The views expressed in this feedback statement are those of the UKEB at the point of publication.
Any sentiment or opinion expressed within this Feedback Statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board 1 Harbour Exchange | London | E14 9GE www.endorsement-board.uk