Project Initiation Plan - Translation to a Hyperinflationary Presentation Currency (IAS 21)
Purpose
1This paper sets out the plan to assess whether to adopt for use in the UK1 the narrow-scope amendments Translation to a Hyperinflationary Presentation Currency (Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates) (the Amendments)2 issued by the International Accounting Standards Board (IASB) in November 2025. The Amendments specify translation requirements for an entity whose presentation currency is that of a hyperinflationary economy, and either its own functional currency or that of its foreign operation is that of a non-hyperinflationary economy.
2The Amendments have an effective date of 1 January 2027, with earlier application permitted. The UKEB's statutory functions mean that it must consider the Amendments against the statutory adoption criteria3 before their formal adoption for use in the UK. The Board's aim would be to ensure the adoption decision is completed in good time to permit UK entities to use the Amendments on the IASB effective date of 1 January 2027.
3The UKEB did not influence the development of the Amendments due to lack of any direct impact for UK companies. This approach was agreed in its Regulatory Strategy 2024/254. The Amendments were developed under the IASB's exposure draft (ED) Translation to a Hyperinflationary Presentation Currency.
Background
4The IFRS Interpretations Committee (IFRIC) received a submission5 about the application of IAS 21 and IAS 29 Financial Reporting in Hyperinflationary Economies on the consolidation of a subsidiary whose functional currency is the currency of a non-hyperinflationary economy (non-hyperinflationary currency) by a parent whose functional currency is the currency of a hyperinflationary economy (hyperinflationary currency).
5Diversity in practice was observed because IAS 21 and IAS 29 do not specify whether the parent is required to restate the current year and comparative amounts presented for its subsidiary with a non-hyperinflationary functional currency.
6To address this matter the IASB issued an ED in July 2024 to propose narrow-scope amendments to IAS 21. The amendments were intended to address diversity in practice and improve the usefulness of the information provided in the financial statements. The amendments specify the translation requirements for an entity whose presentation currency is that of a hyperinflationary economy, and either its own functional currency or that of its foreign operation is that of a non-hyperinflationary economy.
7A summary of the main changes from existing IAS 21 requirements to the Amendments is included in Table 1 of this paper.
Description of the Amendments
Table 1: Overview of the Amendments
| Issued for public comment | Translation to a Hyperinflationary Presentation Currency—issued for public comment in July 2024 (comment period ended on 22 November 2024)6. |
| Title and issue date of final amendments | Translation to a Hyperinflationary Presentation Currency (Amendments to IAS 21) issued on 13 November 20257. |
| Origin | See Background on pages 4 and 5 of the ED for further detail. |
| What has changed? |
|
Project Plan
8The following factors have been considered when developing the project plan.
Proportionality Assessment
The Amendments have been subject to Public Consultation
9The Amendments were issued by the IASB for public comment as an Exposure Draft in July 2024. The IASB received 32 comment letters.
10Generally, feedback to the IASB supported the proposals, however, a concern was raised on the re-translation of comparative information for the results and financial position of foreign operations with a non-hyperinflationary functional currency. The IASB addressed this issue by introducing an exception in the final amendments.
11In August 2025 the IASB staff circulated a draft of the final amendments8 to International Forum of Accounting Standard Setters members. The UKEB Secretariat had the opportunity to submit fatal flaw comments directly to the IASB staff. No fatal flaw comments were identified from this review.
12The final amendments were published by the IASB in November 2025 and are consistent with those in the ED, except for the introduction of an exception on the re-translation of comparative information for the results and financial position of foreign operations with a non-hyperinflationary functional currency.
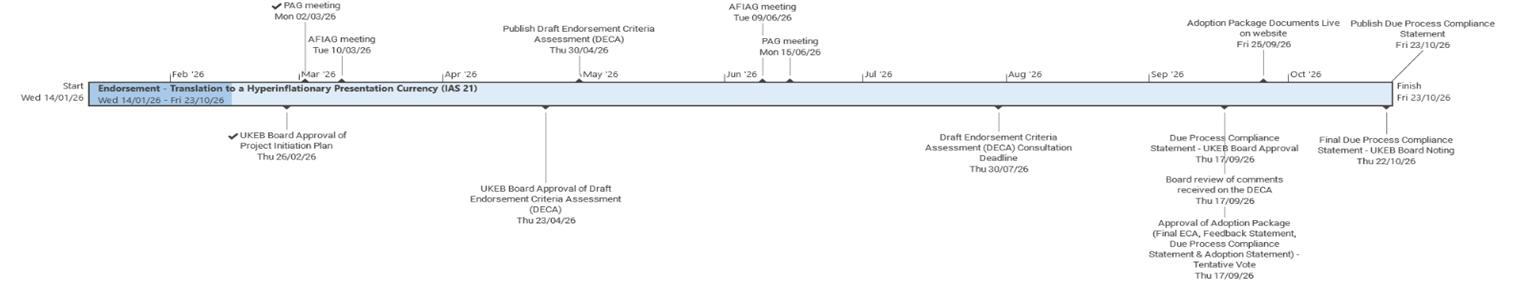
Significance and Size
IASB Project Scope
13The IASB classifies the project as a narrow-scope standard setting project. The application of the Amendments will be limited to entities whose presentation currency is that of a hyperinflationary economy, and either its own functional currency or that of its foreign operation is that of a non-hyperinflationary economy.
Entities Affected by the Proposals
14The proposals affect entities whose presentation currency is that of a hyperinflationary economy, and either its own functional currency or that of its foreign operation is that of a non-hyperinflationary economy.
15Given the Amendments are narrow scope in nature and merely affect entities whose presentation currency is that of a hyperinflationary economy, no significant change in practice or material effect on entities' financial statements is expected in the UK.
16The Economics team has performed research in February 2026 to understand the prevalence of entities potentially affected by the Amendments in the UK9. Based on the research conducted, the Amendments are only expected to potentially affect fewer than five entities.10
Complexity
17The Amendments mainly provide additional guidance and specify requirements for entities whose presentation currency is a hyperinflationary currency. The Amendments are mostly consistent with the requirements in IAS 21 and IAS 29 and are not expected to introduce any new principles or change existing principles in IFRS Accounting Standards.
Expected Timeline / Urgency
18There is no indication of any need for urgent resolution or an accelerated timeline in the UK.
Expected Interest / Sensitivity
19There is no indication of wider UK concerns in relation to this project.
Recommended UKEB Project Scope
20Based on the proportionality assessment above, the UKEB regards this as a 'limited' project scope.
Resources Allocated
21To undertake the activities described in this project plan, a project team has been assigned consisting of a Project Manager with oversight from a Project Director. The required resources are allowed for in the 2025/26 UKEB plan and budget. In addition, the economics team will proportionately contribute to the development of the contents of the economic impact assessment.
Setting up an Ad-hoc Advisory Body
22Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
Project Timeline
23The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
24The proposed timeline indicates the UKEB's consideration of the adoption package at its September 2026 meeting.
Table 2: Project activities and timeline
| Due Process Handbook | Date | Milestones/activities |
|---|---|---|
| 4.10b Optional | 26 February 2026 | Board Education Session |
| 6.12–6.16 Mandatory | 26 February 2026 | Project Initiation Plan for Board approval |
| 6.17 Optional | H1 2026 | Desk-based research including:
|
| 6.23–6.28 Mandatory | 23 April 2026 | Draft Endorsement Criteria Assessment (DECA) for Board approval |
| 6.18–6.22 Mandatory | H1 2026 | Outreach activities including:
|
| 6.23–6.28 and 6.32 Mandatory | 17 September 2026 | Board review comments received on the DECA |
| 6.30–6.48 Mandatory | 17 September 2026 | Consideration of the Adoption Package Board members provide a tentative vote |
| 6.42–6.48 Mandatory | Late September 2026 | Voting form is sent to Board members |
| 6.46–6.48 Mandatory | Late September/early October 2026 | Publication of voting outcome and Adoption Package on the UKEB website |
| 6.38–6.39 Mandatory | 22 October 2026 | Due Process Compliance Statement for noting |
| 1 January 2027 | Effective date of the Amendments (earlier application permitted by the IASB, subject to the UKEB adoption for use in the UK) |
Estimated DECA consultation period (not less than 90 days): 30 April–29 July 202611
Project Initiation Plan: Translation to a Hyperinflationary Presentation Currency (Amendments to IAS 21)-Project Timeline
25The diagram below is a graphical view of the mandatory milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
Footnotes
-
The UK's statutory requirements for adoption of international accounting standards are set out in The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 no. 685 (the Regulations, or SI 2019/685) ↩
-
Translation to a Hyperinflationary Presentation Currency (Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates) a copy of the text of the Amendments will be made available to Board Members ↩
-
The statutory adoption criteria are in Regulation 7 of SI 2019/685 ↩
-
See page 18 of the UKEB's Regulatory Strategy 2024/25 ↩
-
IFRIC June 2022 meeting-Consolidation of a Non-hyperinflationary Subsidiary by a Hyperinflationary Parent (IAS 21 and IAS 29) ↩
-
Link to the IASB's ED ↩
-
Link to the Amendments ↩
-
The IASB shares this draft for editorial review in line with the requirements in paragraph 3.32 of the IFRS Foundation Due Process Handbook. ↩
-
The economics team has performed research based on the data from Financial Conduct Authority's (FCA) National Storage Mechanism. ↩
-
Approximately 1400 entities with equity listed on UK regulated markets (London Stock Exchange and Aquis Exchange) mandatorily prepare their financial statements in accordance with IFRS. (source: LSEG Workspace). ↩
-
To be confirmed ↩