5 Amendments to the Fair Value Option (IAS 28)
29 January 2026 Agenda Paper 5
Executive Summary
Project Stage
| IASB | Research / Pipeline | Discussion Paper | Redeliberation | Exposure Draft | Redeliberation | Final Standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Type
Influencing and Endorsement
Project Scope
Limited
Purpose of the Paper
The purpose of this paper is to:
- Provide the Board with a proposed combined Project Initiation Plan (PIP) for the influencing and endorsement phases of the project relating to the IASB's project on Amendments to the Fair Value Option (IAS 28), for which an Exposure Draft ('ED') is expected in February 2026.
- Obtain Board feedback and approval of the PIP and recommended timelines.
Summary of the Issue
The IASB is developing proposals to clarify the scope of investments in an associate or joint venture that can be measured using the fair value option. Some stakeholders have raised concerns with the IASB about diversity in practice in the interpretation of the scope of paragraphs 18-19 of IAS 28 Investments in Associates and Joint Ventures. This may cause a presentational issue for some preparers applying IFRS 18 Presentation and Disclosure in Financial Statements for the first time.
24 January 2026 Agenda Paper 5
The IASB has identified this as an urgent issue as IFRS 18 is required to be applied from 1 January 2027. To address the urgency of this project and the fact that the UKEB's influencing work is expected to be very closely followed by the need to assess the Amendments for UK adoption, the draft PIP proposes to cover both the influencing and endorsement work to help make the process efficient. The workplan is based on the UKEB completing its influencing work in April 2026 and its endorsement work in November 2026.
Influencing
The IASB is not expected to publish the ED until after the PIP is approved. If the ED is published ahead of the February 2026 meeting, it is likely that it will not arrive in time for the Board paper deadline for that meeting. Therefore, if necessary, the DCL will be provided as a late paper for the February 2026 UKEB meeting.
If the ED is not issued in advance of the February 2026 UKEB meeting, the DCL and FCL can be considered at the March and April 2026 UKEB meetings respectively. This will still be in time to meet the expected 60-day deadline for responding to the IASB.
Given the timing of the UKEB meetings and the fact that the IASB intends to require a shortened 60 day comment period from the date of publication, the Board will need to consider either:
- a shortened comment period for its own DCL, or
- a delay in submitting its own FCL to the IASB by a few working days.
Endorsement
Given the urgency attached to the project, and assuming the IASB publishes the Amendments by the end of June 2026, the project plan proposes an endorsement decision in either:
- early November 2026, or
- early December 2026.
Either timeline should provide certainty to stakeholders prior to the mandatory application date of IFRS 18 of 1 January 2027.
Options for public consultation period of DCL and DECA
There are two options for the Board to consider for the public consultation period for each of the Draft Comment Letter (DCL) and Draft Endorsement Criteria Assessment (DECA). The influencing options are set out in paragraphs A19 and A20, and the endorsement and adoption options in paragraphs A21-A23. Text relating to the two options is included in square brackets throughout the draft PIP to give visibility to the Board on the proposed text for inclusion. The published PIP will only include the options approved by the Board at this meeting.
24 January 2026 Agenda Paper 5
Decisions for the Board
- Does the Board agree that a shortened, 14-day, comment period for the DCL is appropriate?
- Does the Board agree that a shortened, 80-day, comment period for the DECA is appropriate?
- Subject to the options approved at the meeting being reflected in the PIP, does the Board approve the PIP for publication?
Recommendation
We recommend that:
- the Board approves the proposed shortened 14-day DCL consultation period to meet the anticipated IASB comment period deadline;
- the Board approves the shortened 80-day DECA consultation period, to consider an adoption package at the October UKEB meeting with a formal endorsement vote in early November 2026; and
- the Board approves the PIP.
Appendices
Appendix A [Draft] Project Initiation Plan: Amendments to the Fair Value Option (IAS 28).
29 January 2026 Agenda Paper 5: Appendix A
Appendix A: Project Initiation Plan Exposure Draft Amendments to the Fair Value Option (IAS 28)
Purpose
A1This paper sets out the plan for the influencing and endorsement phases of the project related to the urgent IASB project Amendments to the Fair Value Option (Proposed amendments to IAS 28) (the Amendments). The Exposure Draft (ED) is expected to be published in February 2026 with a 60 day consultation period (shortened from the usual 120 days).
A2The project aims to address an issue that has been identified by entities preparing to apply IFRS 18 Presentation and Disclosure in Financial Statements for the first time. IFRS 18 is effective from periods beginning on or after 1 January 2027, hence the need for an urgent project. The amendments would need to be published in 2026 and effective on or before the effective date of IFRS 18.
A3Given the urgency of the Amendments and the IASB's accelerated timetable, this PIP addresses both the influencing and the endorsement and adoption stages of the project.
Background
A4IAS 28 Investments in Associates and Joint Ventures (IAS 28) requires investments in associates and joint ventures to be accounted for using the equity method, unless a different method is permitted by the standard.
A5Paragraph 18 of IAS 28 states the circumstances when the fair value option may be applied:
'When an investment in an associate or a joint venture is held by, or is held indirectly through, an entity that is a venture capital organisation, or a mutual fund, unit trust and similar entities including investment-linked insurance funds, the entity may elect to measure that investment at fair value through profit or loss in accordance with IFRS 9....
A6Paragraph 55 of IFRS 18 requires income from all investments accounted for using the equity method to be classified in the investing category in the statement of profit or loss. Income from investments in associates and joint ventures that
29 January 2026 Agenda Paper 5: Appendix A
are not accounted for using the equity method is required to be classified in the operating category.
A7The IASB has received feedback that there is diversity of practice in the interpretation of the scope of the fair value option in IAS 28. While this might not have had a material financial reporting impact previously, it is expected that the classification split required between operating and investing in the statement of profit or loss could have a material financial reporting impact under IFRS 18.
Summary of Proposed Changes
A8A brief summary of the expected proposed amendments is shown in the table below1.
Amendments to the Fair Value Option (IAS 28)
| Aspect | Details |
|---|---|
| Issued for public comment | The Exposure Draft is expected to be issued for public comment in February 2026, with a 60-day comment period. |
| Origin | See Background paragraphs A4–A7 above. |
29 January 2026 Agenda Paper 5: Appendix A
| Topic | Details |
|---|---|
| What is expected to change? | Paragraphs 18 and 19 of IAS 28 permit the use of the fair value option for certain investments in associates or joint ventures. The anticipated changes relate to clarifying the meaning of 'similar entities' in paragraphs 18 and 19 of IAS 28. The ED is expected to propose:
|
| Timeline | The ED comment period is expected to close in April 2026. Final amendments are expected to be issued by the IASB in June 2026. |
Project Plan
Proportionality Assessment
Significance and Size
A9The Amendments are expected to be narrow in scope, as they aim to clarify the accounting treatment of the fair value option. This clarification is understood to be consistent with existing practice in the UK and expected to be primarily of relevance to insurance entities.
Complexity
A10The Amendments are expected to be limited to the minor changes set out above. Therefore, the Amendments are not expected to introduce any new principles or change existing principles in the IFRS Accounting Standards.
29 January 2026 Agenda Paper 5: Appendix A
Expected Timeline / Urgency
A11These amendments are needed urgently. They are aimed at addressing existing diversity of practice internationally in interpretation of paragraph 18 of IAS 28, ahead of first time adoption of IFRS 18.
Expected Interest / Sensitivity
A12Four IASB members indicated their intention to dissent from the proposals expected to be included in the ED. They generally supported widening the scope to permit a broader fair value option for interests in associates and joint ventures. During the IASB discussions there was acknowledgement that a wider change would require a longer consultation. However, this would be difficult to achieve within the required timeframes.
Feedback on the Proposals from Desk-based Research / Initial Outreach
A13There is no indication of wider UK concerns in relation to this project. Initial limited outreach indicates that application of these paragraphs of IAS 28 has not historically been an area of significant judgement in the UK.
Connectivity
A14No connectivity implications have been identified.
Recommended UKEB Project Scope
A15Based on the proportionality assessment above we recommend a ‘Limited' project scope. The approach described in this document reflects this scope.
Project: Key Activities
| Activity | Due Process Handbook |
|---|---|
| Creation of a Project Initiation Plan (this document) | 5.4–5.8 Mandatory |
Desk-based research to support the proportionality assessment including:
|
5.9 Optional |
| Publication of a Draft Comment Letter (DCL) for public consultation | 5.13–5.17 |
29 January 2026 Agenda Paper 5: Appendix A
| Activity | Due Process Handbook |
|---|---|
| Key Activities: Influencing The DCL will be published on the UKEB website. Announcement of the publication of the DCL and Invitation to Comment (ITC) will be made via the UKEB News Alert publication, and LinkedIn posts. The DCL and ITC will be issued for comment for a shortened period of 14 days due to the urgency of the project. |
Generally mandatory |
| Stakeholder outreach We have conducted limited outreach, including with accounting firm representatives and an insurer. We intend to conduct further limited outreach, including with advisory and working group members. ----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- |
5.10–5.12 Mandatory |
| Final Comment Letter A final comment letter (FCL) will be created for Board approval, submission to the IASB, and publication on the UKEB website. |
5.18 Mandatory |
| Project Closure A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
5.19–5.26 Mandatory |
Endorsement and adoption (after IASB redeliberates and publishes final Amendments)
| Item | Reference |
|---|---|
Desk-based research to support the proportionality assessment including: The Secretariat will review:
|
6.17 Optional |
29 January 2026 Agenda Paper 5: Appendix A
| Item | Reference |
|---|---|
| Publication of a Draft Endorsement Criteria Assessment (DECA) for public consultation The DECA will be published on the UKEB website. Announcement of the publication of the DECA for consultation will be made via the UKEB News Alert publication for subscribers, and LinkedIn posts. The DECA and ITC will be issued for comment for a shortened period of 80 days, due to the urgency of the project. |
6.23–6.28 Mandatory |
| Stakeholder outreach Publish DECA for stakeholder comment on the UKEB website. Notify UKEB Advisory groups of the DECA publication, as appropriate (ongoing during the DECA comment period). |
6.18–6.22 Mandatory |
| Creation of an adoption package Creation of an adoption package including the Final Endorsement Criteria Assessment (ECA), Adoption Statement, Feedback Statement and Due Process Compliance Statement. Publication of required documents on the UKEB website. |
6.30–6.48 Mandatory |
Resources Allocated
A16To undertake the activities described in this project plan, a project team has been assigned consisting of a Project Director, with oversight of a senior project director. Input will be obtained from the economics team for the long term public good assessment.
29 January 2026 Agenda Paper 5: Appendix A
Setting up an Ad-hoc Advisory Body
A17Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
Project Timeline
A18The proposed high-level project timeline is shown below for both the influencing and endorsement and adoption phases of the project. This provides a best estimate based on information known at this time. [NB: We have set out below two options for the timeline for the influencing phase, and two options for the timeline for the endorsement and adoption phase. The final PIP will only include the options approved at the Board meeting.]
Influencing stage
A19[For the comment period for the DCL we have the following options:]
- [Influencing option one: The comment period for the DCL will be 14-days. This is shorter than the standard 30-day comment period to allow the Board to consider stakeholder feedback and respond to the IASB in time for its comment letter deadline. A shortened comment period is permitted by the Due Process Handbook in circumstances, such as these, where the IASB has shortened the comment period for the ED to expedite the final publication of the amendment. This allows submission of the FCL before the end of the IASB comment period.]
- [Influencing option two: The comment period for the DCL will be the standard 30-day comment period. This would require consideration of the FCL at the April 2026 UKEB meeting and would result in anticipated submission of the FCL between 6-10 days after the IASB deadline.]
A20[We recommend that the Board approves the proposed shortened 14-day DCL consultation period to meet the anticipated IASB comment period deadline.]
Endorsement and adoption stage
A21Given the urgency attached to the project, the plan proposes an endorsement decision in early [November/December] 2026, assuming the IASB publishes the Amendments by the end of June 2026. This timeline should provide certainty to stakeholders prior to the mandatory application date of IFRS 18 of 1 January 2027.
29 January 2026 Agenda Paper 5: Appendix A
A22[For the comment period for the DECA we have the following options:]
- [Endorsement option one: The comment period for the DECA will be a shortened 80-day consultation period which is shorter than the standard 90-day period. A shortened comment period is permitted by the Due Process Handbook where there is limited time to consult for urgent narrow scope amendments where the period between publication date and effective date is short, and the amendment may be required urgently. This timetable would allow the adoption package and a tentative vote at the October 2025 UKEB meeting, and a formal vote in early November 2025.]
- [Endorsement option two: The comment period for the DECA will be the standard 90-day consultation period. Following this timetable, the adoption package and tentative vote would be considered at the November 2025 UKEB meeting, followed by a formal vote in early December 2025.]
A23[We recommend that the Board approves the shortened 80-day DECA consultation period, to consider an adoption package at the October UKEB meeting with a formal endorsement vote in early November 2026.]
A24If the IASB does not issue the Amendments by the end of June, the project plan would be reassessed and new proposals brought back to the Board.
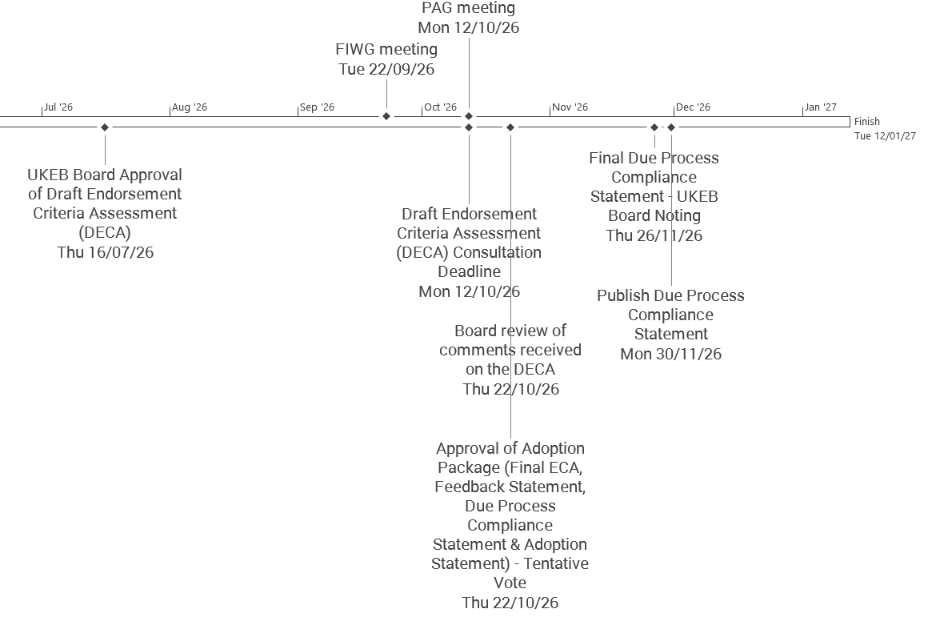
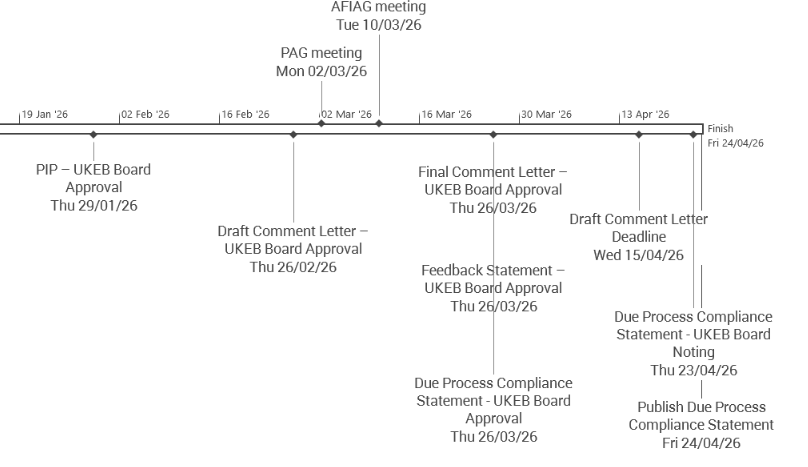
Influencing phase [(showing option one)]:
| Date | Activity |
|---|---|
| 29 January 2026 | Project Initiation Plan for Board approval |
| February 2026 | ED expected to be published with 60-day comment period* |
| 26 February 2026 | Draft Comment Letter for Board approval |
| Estimated DCL consultation period (14 days): 3 March 2026 – 17 March 2026* | |
| 26 March 2026 | Board review of Final Comment Letter, Feedback Statement, draft Due Process Compliance Statement |
| Week commencing 30 March 2026 | Final Comment Letter submitted to IASB (deadline expected to be mid April 2026) |
| 23 April 2026 | Due Process Compliance Statement for noting |
* To be confirmed
29 January 2026 Agenda Paper 5: Appendix A
Endorsement phase [(showing option one)]:
| Date | Activity |
|---|---|
| 16 July 2026 | Draft Endorsement Criteria Assessment for Board approval |
| Estimated DECA consultation period (80 days): 24 July 2026–12 October 2026* | |
| 22 October 2026 | Board review comments received on the DECA Consideration of the Adoption Package Board members provide a tentative vote |
| Early-November 2026 | Voting form is sent to Board members |
| Mid-November 2026 | Publication of voting outcome and Adoption Package on the UKEB website |
| 26 November 2026 | Due Process Compliance Statement for noting |
| 1 January 2027 | Effective date of the Amendments (earlier application permitted by the IASB, subject to the UKEB adoption for use in the UK)* |
* To be confirmed
29 January 2026 Agenda Paper 5: Appendix A
Project Initiation Plan: Amendments to the Fair Value Option (IAS 28) Project Timeline
A25The diagrams below show graphical views of the mandatory milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
Influencing
29 January 2026 Agenda Paper 5: Appendix A
Endorsement