6 Statement of Cash Flows and Related Matters
Executive Summary
Project Stage
| IASB | Research / Workplan | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Influencing | Monitoring | Endorsement | Influencing |
Project Scope
Moderate
Purpose of the paper
Having completed four UKEB research papers on the Statement of Cash Flows and Related Matters, it is clear UK users believe the IASB should undertake targeted improvements to the statement of cash flows to address their priority concerns.
Following the presentation of the fourth UKEB research paper Statement of Cash Flows: UK Users' views on potential ways forward at the July 2025 UKEB meeting, the Board agreed that further UKEB research be undertaken in relation to supplementary net debt disclosure. This is one of the highest priorities for users consulted during the UKEB initial research.
This further research undertaken includes:
- Financial statement analysis of 40 non-UK annual reports to assess the prevalence of net debt disclosures, including as a key financial performance indicator. Examples of non-UK net disclosures are provided in Annex 2.
- Review of other National Standard Setters (NSS) published material on net debt.
- Review of other material on net debt, including that published by regulators.
This paper also summarises the previous UKEB research on net debt (in Appendix A: Annex 1).
Summary of the Issue
The paper concludes that:
- Extending current requirements to include a net debt reconciliation could be an 'easy win' and significantly improve the usefulness of the financial statements for users, with potentially limited incremental cost for preparers, given the prevalence of disclosure of a net debt metric in annual reports of both UK and non-UK jurisdictions.
- There would be added benefit to users should the IASB define the minimum components they expect to see included in a net debt disclosure. Whilst companies could disclose entity-specific net debt, the anticipated MPM requirements for cash flow measures, would require a company to reconcile its 'adjusted net debt' to that 'IFRS-defined net debt', and give users a common baseline to compare net debt across companies.
- Requiring the supplementary net debt disclosure to provide disaggregated information, and those disaggregated components to be cross-referenced and reconciled to the statement of cash flows, the statement of financial position and other supplementary notes to the accounts, would improve the cohesiveness and the usefulness to users of the financial statements.
Decisions for the Board
1The Board is asked for general comments and observations on the UKEB research findings on net debt disclosures (Appendix A).
2Do Board members agree, subject to comments received in this meeting, that a final version of the research findings should be published on the UKEB website?
Recommendation
The Secretariat recommends that a final version of the research findings should be published on the UKEB website.
Appendices
Appendix A UKEB research paper 5 – Statement of Cash Flows and Related Matters: Further research – Net debt
Background: Statement of Cash Flows and Related Matters
The IASB added a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation (published March 2021).
In the Feedback Statement to the Request for Information (published July 2022) most respondents recommended the addition of a project on cash flows to the IASB's workplan, rating it as high priority.
The IASB staff have performed initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB's decision on the scope of the project and will also address possible ways of improving the perceived deficiencies.
The IASB discussed the initial research outcomes in March 2025, and in May 2025 discussed the topics to include in the project plan and a draft timeline for work on the project. The IASB will decide on the project direction in January 2026.
A UKEB project on the statement of cash flows and related matters supports meeting the UKEB's responsibilities regarding thought leadership in accordance with the UKEB Terms of Reference. It will also help the Board to deliver the UKEB's 2024-25 Regulatory Strategy (page 8) aim, to influence the IASB early in its development cycle, by providing timely and effective input.
The UKEB research has focused on gathering primary evidence on the improvements UK investors and creditors suggest for the statement of cash flows, and UK preparer views on those possible improvements. This has provided a foundation for the UKEB to propose potential solutions for the problems already identified by the IASB, as well as any other issues identified through UKEB outreach.
Appendix A: Further research – Net debt
Introduction
A1.At its July UKEB meeting¹ the Board agreed to undertake further research Statement of Cash Flows and Related Matters Project. It agreed to investigate:
a) the prevalence of reporting net debt outside of the UK, either as a key performance indicator in annual reports, or reported on in the IFRS financial statements; and b) why net debt disclosures are important to users.
A2.To gather evidence, the UKEB research included:
a) Financial statement analysis a review of annual reports of companies reporting under IFRS Accounting Standards outside of the UK, to evaluate the prevalence of net debt in published company information, such as a key performance indicator, and the prevalence of voluntary disclosure of net debt in the financial statements. b) A review of other National Standard Setters and Regulators published material on net debt.
A3.This paper also summarises the previous UKEB research referencing calls for a net debt reconciliation (see Annex 1), including:
a) the benefits of the net debt disclosure for users; b) whether the IASB should define the term 'net debt'; and c) best practice and illustrative example of what a net debt requirement may include, the level of disaggregation, and how it should be reconciled to other parts of the financial statements.
A4.In May 2025, the IASB tentatively decided the topics it plans to explore in its project on the Statement of Cash Flows and Related Matters². As part of the IASB's work on improving the transparency of information about common cash flow measures, it plans to assess potential ways to improve other specific information with management definitions/approach, including disaggregation of net debt³, given this was a priority for most investors.
A5.Previous UKEB research undertaken between October 2024 to July 2025 (see Annex 1) highlighted supplementary disclosures that users believe would enhance the usefulness of the statement of cash flows specifically, and the financial statements more generally.
A6.That work identified the highest priority supplementary disclosure for most UK users is a net debt reconciliation. The UKEB thinks that this could be mandated as an extension of the existing requirements in IAS 7.44A-44E. This would require companies to provide disclosures that enable users of financial statements to evaluate changes in liabilities arising from financing activities, including both changes arising from cash flows and non-cash changes⁴; this should be clearly linked to the information reported in the statement of cash flows.
A7.The UKEB's fourth research paper Statement of Cash Flows: UK Users' views on potential ways forward, explored alternative formats for the statement of cash flows, including elevating the net debt to the face of the statement of cash flows. Whilst this approach received some support overall, users suggested that a supplementary net debt reconciliation in the notes to the financial statements would be sufficient.
A8.The UKEB undertook research into disclosures currently presented by a sample of UK listed entities reporting under IFRS Accounting Standards, and presented its findings in the UKEB's second research paper: Statement of Cash Flows: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed Companies⁵. The paper concluded that most UK listed companies provide voluntary disclosures of net debt and suggested that if this information is useful to users, then mandating a requirement for all companies to disclose a net debt reconciliation would be an ‘easy win' to improve cash flow and other information provided to users, in the scope of the IASB's project on the Statement of Cash Flows and Related Matters.
A9.As noted in that paper, net debt is a financial liquidity metric that is used to determine how well a company can pay all its debts if they come due immediately, and whether the company is able to take on more debt. It measures a company's current interest-bearing debt on its statement of financial position compared to its liquid assets i.e. cash and cash equivalents. It shows how much cash would remain if all debts were paid off, and if a company has sufficient liquidity to meet its debt obligations. Net debt is commonly used in valuation and is an important metric for analysts.
A10.Since voluntary disclosure of net debt is already prevalent in the UK, the UKEB thinks that introducing a supplementary disclosure requirement would:
a) Incur limited incremental cost to preparers. b) Improve the usefulness of the financial statements, by providing more complete and transparent information to users for all companies, enabling them to complete their own analysis of a company's liquidity and capital management, and its ability to generate sufficient future cash flows to service its debt and grow its operations. c) Enhance the cohesiveness of financial statements, by requiring it to be reconciled to: i. the statement of cash flows; ii. the components of net debt disclosed in other notes to the financial statements; iii. the existing requirements to disclose changes in liabilities arising from financing activities (IAS 7.44A-44E); and iv. other notes to the accounts, such as leases and business combinations (agreeing to net debt acquired on acquisitions).
A11.The UKEB undertook a user poll in March 2025 and published its findings as part of the summary of the first three UKEB research papers in July 2025⁶. Consistent with the feedback from previous interviews with UK stakeholders, the poll provided strong evidence for the need to enhance the statement of cash flows and the notes to the financial statements, by requiring companies to provide a net debt reconciliation, and the need for more granular and transparent disclosures, to improve the cohesiveness of the primary financial statements.
Existing disclosure requirements in IAS 7
A12.The IASB's Third Agenda Consultation Request for Information⁷, notes that many stakeholders recommended that companies should be required to present a statement of changes in net debt.
A13.Prior to the Third Agenda Consultation, the IASB had carried out a significant amount of work on net debt in 2013⁸ and 2014⁹, which led to the 2016 Disclosure Initiative amendments to IAS 7. These amendments introduced the requirement for companies to disclose changes in liabilities arising from financing activities (IAS 7.44A–44E). However, the IASB stopped short of requiring a full net debt reconciliation.
A14.As mentioned in the UKEB first research paper Statement of Cash Flows: Background and Key Issues¹⁰, the IASB recognised that the 2016 Disclosure Initiative was not consistently implemented and in February 2019 published brief: Changes in financing liabilities—what does good disclosure look like? This paper emphasised that one way to fulfil the requirement in IAS 7.44A–44E¹¹, is to provide a reconciliation between the opening and closing balances of financing liabilities (also known as an “IAS 7 reconciliation").
A15.In contrast, a net debt reconciliation reconciles movements in a net balance comprising all debt less cash and cash equivalents. Some companies, including many in the UK, choose to provide a net debt reconciliation¹² instead of an IAS 7 reconciliation.
A16.However, as noted by the IFRS Interpretations Committee at its meeting in June 2019¹³, the Committee was “informed by users of financial statements.....that disclosure relating to changes in liabilities arising from financing activities applying IAS 7 Statement of Cash Flows does not always meet their information needs. In particular, investors raised concerns about observable trends in the quality and consistency of disclosure applying paragraphs 44A–44E of IAS 7”.
A17.Therefore, despite the 2016 initiative, users are still not getting the information they need in relation to net debt for all companies. The changes in liabilities arising from financing activities is only part of the information they need. Users want to be able to see net debt, reconciled to both the change in financing liabilities and the statement of cash flows, without having to search the financial statements for all the information.
A18.Concerns with the disclosure was raised in the FRC 2020 thematic report on cash flow and liquidity disclosures (page 10), and the investors focus on net debt was reinforced in the FRC's July 2017 Feedback Statement on its Discussion Paper Improving the Statement of Cash Flows (page 5) and the FRC Lab project report: Net Debt Reconciliations published in 2012.
A19.One of the concerns highlighted by users is that the change in liabilities arising from financing activities is not reconciled to the cash flows relating to financing activities shown on the face of the statement of cash flows. So, there is an opportunity for the IASB to improve the requirements. A full net debt reconciliation, with a breakdown between cash and non-cash items, should lead to improved information for users.
A20.The UKEB suggests that the IASB not only mandate an IAS 7 reconciliation for changes in liabilities arising from changes in financing activities, but also extend the requirement, to require a net debt reconciliation, which would link the information more transparently to the statement of cash flows and the other primary financial statements.
Financial report analysis
Research process and methodology
A21.The UKEB identified four large jurisdictions using IFRS Accounting Standards outside of the UK to investigate the international prevalence of net debt disclosure:
a) Australia; b) Europe; c) Canada; and d) Japan.
A22.For each of the four jurisdictions, the UKEB identified the top ten most indebted listed companies¹⁴. The 2024 annual reports of the 40 sampled companies were reviewed to evaluate:
a) The prevalence of net debt as a key financial indicator, disclosed in the annual report. b) The prevalence of net debt reported in the financial statements.
Findings
A23.The table below sets out the results of the financial statement analysis for the 40 companies sampled:
| Jurisdiction | Australia | Europe | Canada | Japan | TOTAL |
|---|---|---|---|---|---|
| No. of annual reports | 10 | 10 | 10 | 10 | 40 |
| No. of companies with net debt as a key performance indicator | 9 | 7 | 6 | 3 | 25 |
| No. of companies with net debt disclosed in financial statements | 8 | 6 | 6 | 4 | 24 |
| Average number of references to net debt | 22 | 24 | 22 | 3 | 71 |
A24.Australia had the most disclosures of net debt, with nine of the 10 companies sampled disclosing net debt, both as a key performance indicator in the front half of their annual reports, as well a financial metric in the financial statements themselves. Three of those companies sampled presented a net debt note.
A25.Europe and Canada both had net debt disclosures that were relatively prevalent, with over half the sample in each jurisdiction reporting net debt as both a key performance indicator and a financial metric. Companies in Europe presented detailed disclosures on net debt, including changes in net debt and a net debt chart (Annex 2 provides a sample of disclosures reported by some of those sampled companies).
A26.Japan was a jurisdiction where net debt was not as prevalent. Four companies in the sample mentioned net debt in their financial statements, generally in notes on liquidity and capital resources / capital management, and usually in the form of a net debt/equity ratio.
A27.Overall, a high number of companies in the sample did refer to net debt as a key performance indicator, either as part of a financial ratio, or in relation to liquidity and capital resources.
A28.Given that a significant number of companies disclose net debt as a key performance indicator, the findings:
a) reinforce the importance of this net debt information for users, in line with UKEB earlier research findings; and b) suggest that for large jurisdictions that use IFRS Accounting Standards the incremental cost of preparing a net debt disclosure should be low, given that many companies would appear to already be calculating and presenting this information.
Other National Standard Setters and Regulators
A29.The findings are consistent with recent financial statement analysis carried out by the IASB, where “in the non-financial institutions analysed, 19 out of 25 entities provided the amount of 'net debt' or equivalents (such as 'net financial debt' and 'net cash'). Some entities provide more than one net debt measure”¹⁵.
A30.The Canadian Accounting Standard Setter (AcSB) recommended in a presentation to ASAF in September 2024¹⁶ that the IASB explore replacing the statement of cash flows with another statement using a measure different from cash and cash equivalent, to reflect an entity's available liquid assets or funding sources to meet its liquidity needs.
A31.This AcSB presentation also referred to Improving the Statement of Cash Flows, a Discussion Paper, prepared in October 22016, by staff of the UK Financial Reporting Council, which suggested that the statement of cash flows should be required to report inflows and outflows of cash, rather than cash and cash equivalents. The UK FRC staff paper also suggested that the statement of cash flows should contain a separate section that reports cash flows relating to the management of liquid resources (see page 10 of that report).
A32.The European Financial Reporting Advisory Group (EFRAG) noted in its discussion paper: The Statement of Cash Flows – Objectives, Usages and Issues (November 2024), that the IASB consider whether the statement of cash flows could be replaced by another statement to achieve more alignment with commonly used cash flow measures, as well as to solve some other matters such as those related to non-cash transactions. The possible alternative statements presented included a statement of changes in net debt (see page 79 and 88–92 of that report).
A33.The EFRAG discussion paper also noted that some consider net debt to be a key performance metric that is completely ‘ignored', even with the IAS 7 Disclosure Initiative aimed at enhancing information related to changes in debt. The 2016 amendments to IAS 7 (adding paragraphs 44A–44E) require disclosure of information to help users evaluate changes in liabilities arising from financing activities; however, the information provided is still insufficient. The lack of a definition of 'net debt' results in non-comparability. However, it noted that defining net debt can be challenging.
A34.As noted in paragraph A114 of the UKEB first research paper: Statement of Cash Flows: Background and Key Issues, best practices for presenting a net debt reconciliation were considered in the FRC's Financial Reporting Lab project report on Net Debt Reconciliations (September 2012). In the FRC's report (see page 4), it was considered that best practice highlights key movements and shows cash and non-cash drivers of changes to net debt.
Concluding observations
A35.UKEB evidence suggests that there are opportunities for the IASB to improve the usefulness of reporting by requiring companies to disclose a net debt reconciliation of the movement in net debt, reconciled to the statement of cash flows and to the components of net debt in the balance sheet notes, such as the business combinations note in relation to acquired net debt.
A36.The reconciliation could be based on the existing requirements in IFRS. The UKEB suggests that a net debt disclosure would simply be an extension of the existing requirements in IAS 7.44A–44 E, for changes in liabilities arising from financing activities, showing both cash and non-cash changes. This would also assist with providing users with some of the non-cash information they need.
A37.Based on UK stakeholder feedback, the UKEB has suggested certain disaggregated components should be included in the net debt disclosure, such as the impact of factoring and reverse factoring (supply chain finance) arrangements. The operational effectiveness would need to be field-tested.
A38.The UKEB suggests that a baseline net debt IFRS definition would be useful, so that entities can disclose a reconciliation of their entity-specific adjusted net debt to that IFRS-defined measure, to make it easier for users to compare entity-specific net debts i.e. the adjusting items are transparent.
A39.Should the IASB introduce cash flow MPMs, leveraging the IASB's work done in developing IFRS 18 i.e. introducing IASB defined sub-totals, cash flow related MPMs should be reconciled to the appropriate IASB defined sub-total.
A40.Whilst the UKEB observed that entities in some jurisdictions provide voluntary supplementary net debt reconciliations, including in the front half of the annual report, mandating a net debt reconciliation in the financial statements would provide greater consistency and audit assurance to users across all companies.
A41.The UKEB's observations suggest that if companies were required to provide a net debt reconciliation it would give rise to limited incremental cost to preparers. However, further research and field-testing is needed to ensure that any improvements to disclosure requirements suggested in this research paper balance the costs of providing the additional information and the related benefits.
Annex 1: Previous UKEB research referencing calls for a net debt reconciliation
A42.The UKEB has previously published research which concluded that users would benefit from mandatory disclosure of net debt¹⁷.
A43.UKEB Research Paper 1. Statement of Cash Flows: Background and Key Issues (December 2024) – based on desk-based research, exploring perceived issues with the statement of cash flows. (See paragraphs A104–A116 of that paper for information on net debt).
A44.UKEB Research Paper 2. Statement of Cash Flows: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed Companies (February 2025) – based on a review of current reporting practices among UK listed companies. This research highlighted an opportunity to leverage the existing UK practice for supplementary disclosures that could enhance statutory reporting of cash flows and related matters. Examples of such voluntary cash flow disclosures were discussed during some of the later interviews conducted with users and preparers (between December 2024 and March 2025 to inform the third UKEB research paper) to determine what voluntary disclosures are most useful, and to understand how the information is used. (See paragraphs B89–B96 of that paper for information on net debt).
A45.UKEB Research Paper 3. Statement of Cash Flows: UK User and Preparer Perspectives (March 2025) – based on interviews with investors and preparers to better understand their perspectives on the current and potential future reporting requirements. (See paragraphs C117–C126 of that paper for information on net debt).
Excerpt from paragraph C21 of the UKEB third research report:
“Improvements should focus on integration, better classification, and reconciliation to net debt".
Analyst
Excerpt from paragraph C123 of the UKEB third research report:
“If I could make one change it would be to turn the statement of cash flows into a net debt statement".
Preparer
A46.A user survey¹⁸ conducted by the UKEB in March 2025 to gather wider UK user views, which also provided feedback on UK listed company voluntary disclosures observed by the UKEB in its second research paper, and other disclosures suggested by UK stakeholders during the outreach meetings to inform its third research paper.
A47.UKEB Research Paper 4. Statement of Cash Flows: UK Users' views on potential ways forward (July 2025) – based on further stakeholder interviews, covering two areas of cash flow reporting: a) Alternative formats for the statement of cash flows and b) Potential supplementary disclosures to improve cash flow-related requirements, mapping the links between the statement of cash flows and requirements in other IFRS Accounting Standards, to: (i) enhance the interconnectivity of existing cash flow-related reporting requirements contained in IFRS Accounting Standards; and (ii) introduce overarching principles aimed at enhancing cohesiveness in financial statement information, by requiring links between amounts in the statement of cash flows to other primary statements. (See paragraphs 36 – 45 of that paper for more information on net debt).
A48.As noted in the UKEB fourth research paper, a supplementary net debt reconciliation emerged as the clear priority for both users and preparers. It is regarded as providing relevant information without disrupting the current IAS 7 format. Users value the way it makes apparent various cash and non-cash movements in net debt.
a) The interviews supported previous research that found such disclosures are important to investors both for equity valuation purposes and to investigate perceived problems with a company's debt or liquidity. b) Net debt disclosures give investors the confidence that they have understood issues related to the development of financial obligations that must be met, and issues relating to the capital structure and the enterprise value attributable to net debt versus shares¹⁹.
Defining net debt
A49.IFRS Accounting Standards make no reference to the term 'net debt' and have no requirement to provide a net debt reconciliation. However, a UKEB review of a sample of 30 UK listed annual reports to develop the UKEB second research paper, found that most companies disclosed a net debt reconciliation²⁰
A50.Following discussions at its May 2025 meeting, the IASB indicated that the definition of net debt is a topic it does not plan to explore further. However, UK stakeholder feedback noted above, and the prevalence of the measure in UK reporting, provides evidence for the IASB to consider introducing a mandatory requirement for companies to include a net debt reconciliation in their financial statements, building on the existing disclosure requirements in IAS 7 paragraphs 44A to 44E²¹.
A51.When companies do not provide a net debt reconciliation, analysts generally attempt to create their own. Thus, introducing a requirement for companies to provide a net debt reconciliation would assist investors in understanding management's view of net debt and provide transparent information that reconciles to other areas of the financial statements.
Best practice and Illustrative example of net debt
A52.During interviews UK users commented that any suggested net debt disclosure should:
a) Clearly show the components that companies include in their entity-specific definition of net debt, which might include other liquid investments that do not meet the definition of cash and cash equivalents – components would need to be shown in the reconciliation with sufficient disaggregation to enable users to link the movement to the corresponding balance sheet line item. b) Require the effects of business combinations (mergers and acquisitions) on the components of net debt be clearly reconcilable to the business combinations note. c) Show fair value changes and the retranslation of foreign currency denominated amounts. d) Show separately cash movements and non-cash items, and how they relate to other aspects of the financial statements, such as the income statement and statement of financial position. e) Make clear the nature of any derivatives included in net debt and whether the net debt includes accrued interest. f) Clearly explain any fair value hedge adjustments to reported net debt, or debt-related derivatives not included in the company's definition of net debt. g) Separately list movements that are different in nature, such as significant foreign currency movements and fair value changes. Whilst it is considered reasonable for companies to show a category of "other" movements, there should be a requirement for companies to provide confirmation that there are no material offsetting amounts included in that category, and to describe the nature of items included.
A53.An illustrative example of the possible net debt reconciliation was included in our fourth research paper and replicated below.
Notes:
1.Cross-references to relevant sections of the financial statements would ensure cohesiveness. For example, the cash flow column would be expected to cross-refer to the statement of cash flows; the opening and closing balances would be expected to cross-refer to the statement of financial position; and the M&A movements would be expected to cross-refer to the acquisitions and disposals disclosures presented in accordance with IFRS 3.B64(i) and IAS 40(d).
2.Separate inclusion of movements relating to factoring and supply chain financing would meet user demands for greater transparency around such arrangements. This would build on the disclosure objectives in IFRS 7 and the disclosure requirements in IAS 7.44A to 44E and IAS 7.44F to 44H.
A54.As suggested within the example, a reconciliation would be enhanced by cross-referencing amounts to relevant disclosures in other sections of the financial statements. This would address stakeholder expectations, identified during this research and earlier phases of the project.
Factoring receivables and payables
A55.Users interviewed had concerns about the transparency of disclosures on factoring and reverse factoring arrangements, and so a separate column for any liabilities arising from factoring and reverse factoring arrangements is included in the illustrative example above.
A56.Factoring can help a company maintain an optimal level of working capital by converting invoices into cash, ensuring it has enough funds to cover expenses, pay suppliers, and invest in growth. By understanding how a company uses factoring, investors can gauge its ability to manage its short-term financial needs.
A57.Investors analyse the creditworthiness of a company's customers and the terms of its factoring agreement to assess the potential risks involved.
A58.IFRS 7 Financial Instruments: Disclosures requires entities to disclose the nature and extent of risks arising from financial instruments. This includes qualitative and quantitative information about credit risk, liquidity risk, and market risk, with a focus on how the entity manages these risks.
A59.There is no specific requirement to disclose cash flow information in relation to factoring arrangements, in either IFRS 7 or IAS 7.
A60.Users interviewed suggested that in order to provide transparency about factoring and reverse factoring arrangements, the net debt disclosure could be further enhanced by requiring disaggregated components of balances subject to these arrangements that have not met IFRS 9 Financial Instruments derecognition requirements.
IFRS defined sub-totals and management performance measures (MPMs)
A61.It is understood that the IASB has tentatively decided to extend the requirements in IFRS 18 requiring disclosure of MPMs for income and expenses²², to cash flow measures.
A62.Whilst the UKEB understands that the IASB is currently consulting on potential rewording to extend the MPM requirements to cash flows measures, an MPM as currently defined in IFRS 18, is a subtotal of income and expenses that:
a) is used in public communications outside financial statements²³; b) is used to communicate to investors, management's view of an aspect of the financial performance of the company as a whole; and c) is not listed in IFRS 18 or specifically required by IFRS Accounting Standards.
A63.IFRS 18 introduced sub-totals that companies are required to disclose on the face of the income statement²⁴. A company will disclose information about its MPMs in a single note to the financial statements. The note will include a statement that the MPMs provide management's view of an aspect of the financial performance of the company as a whole and are not necessarily comparable with measures sharing similar labels or descriptions provided by other companies.
A64.Similar to income and expense MPMs, the IASB could require the disclosure of, and reconciliation of, such cash flow MPMs to IFRS defined sub-totals in a single note in the financial statements.
A65.Users interviewed said that to improve transparency and assist them in comparing cash flow measures not defined in IFRS reported by different companies, it would be useful if the IASB introduced new IFRS defined sub-totals in the statement of cash flows. This would facilitate the reporting of cash flow related MPMs and reconciliation back to IFRS define sub-totals.
Net debt as an IFRS-defined measure
A66.Some stakeholders said it would be useful if the IASB defined net debt. There are mixed views however, as some users said that entity-specific net debt measures, give an insight into what the company considers are its components of net debt, and indicate how a company is managing its liquidity and capital management.
A67.As net debt is currently not defined in IFRS, the IASB could introduce a baseline definition for net debt. This would mean that preparers who disclose an entity-specific definition of net debt (adjusted net debt), would need to reconcile it to the closest IFRS-defined measure; it would be helpful to users if that IFRS-defined measure was a net debt measure, so users could transparently and more easily compare one company's entity-specific adjusted net debt with another company's net debt measure.
Annex 2: Examples of net debt disclosure outside the UK
Example 1: Australia – Rio Tinto Annual Report 2024
19 Net debt
Analysis of changes in net debt
The table below summarises, by currency, our net debt, after taking into account relevant cross-currency interest rate swaps and foreign exchange contracts:
| Net debt by currency | Borrowings excluding overdrafts US$m | Lease liabilities US$m | Derivatives related to net debt US$m | Cash and cash equivalents US$m | Other investments US$m | Net debt US$m (2024) | Net debt US$m (2023) |
|---|---|---|---|---|---|---|---|
| US dollar | (12,181) | (539) | (343) | 7,108 | 212 | (5,743) | (4,033) |
| Australian dollar | (92) | (501) | 721 | 128 | (186) | (247) | |
| Canadian dollar | (158) | (158) | 81 | (235) | (247) | ||
| South African rand | (2) | 167 | 165 | 130 | |||
| Other | (213) | 407 | 194 | 105 | |||
| Total | (12,431) | (1,413) | (343) | 8,484 | 212 | (5,491) | (4,231) |
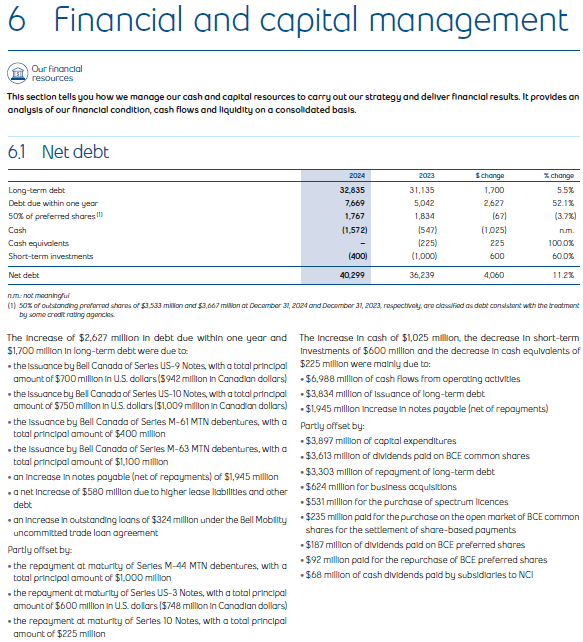
Example 2: Canada – BCE Inc. Annual Report 2024
6 Financial and capital management
Our financial resources This section tells you how we manage our cash and capital resources to carry out our strategy and deliver financial results. It provides an analysis of our financial condition, cash flows and liquidity on a consolidated basis.
6.1 Net debt
| 2024 | 2023 | $ change | % change | |
|---|---|---|---|---|
| Long-term debt | 32,835 | 31,135 | 1,700 | 5.5% |
| Debt due within one year | 7,669 | 5,042 | 2,627 | 52.1% |
| 50% of preferred shares¹ | 1,767 | 1,834 | (67) | (3.7%) |
| Cash | (1,572) | (547) | (1,025) | n.m. |
| Cash equivalents | (225) | 225 | 100.0% | |
| Short-term investments | (400) | (1,000) | 600 | 60.0% |
| Net debt | 40,299 | 36,239 | 4,060 | 11.2% |
¹50% of outstanding preferred shares of $3,533 million and $3,667 million at December 31, 2024 and December 31, 2023, respectively, are classified as debt consistent with the treatment by some credit rating agencies.
The Increase of $2,627 million in debt due within one year and $1,700 million in long-term debt were due to: * the issuance by Bell Canada of Series US-9 Notes, with a total principal amount of $700 million in U.S. dollars ($942 million in Canadian dollars) * the issuance by Bell Canada of Series US-10 Notes, with a total principal amount of $750 million in U.S. dollars ($1,009 million in Canadian dollars) * the issuance by Bell Canada of Series M-61 MTN debentures, with a total principal amount of $400 million * the issuance by Bell Canada of Series M-63 MTN debentures, with a total principal amount of $1,100 million * an increase in notes payable (net of repayments) of $1,945 million * a net increase of $580 million due to higher lease liabilities and other debt * an increase in outstanding loans of $324 million under the Bell Mobility uncommitted trade loan agreement
Partly offset by: * the repayment at maturity of Series M-44 MTN debentures, with a total principal amount of $1,000 million * the repayment at maturity of Series US-3 Notes, with a total principal amount of $600 million in U.S. dollars ($748 million in Canadian dollars) * the repayment at maturity of Series 10 Notes, with a total principal amount of $225 million
The Increase in cash of $1,025 million, the decrease in short-term Investments of $600 million and the decrease in cash equivalents of $225 million were mainly due to: * $6,988 million of cash flows from operating activities * $3,834 million of issuance of long-term debt * $1,945 million increase in notes payable (net of repayments)
Partly offset by: * $3,897 million of capital expenditures * $3,613 million of dividends paid on BCE common shares * $3,303 million of repayment of long-term debt * $624 million for business acquisitions * $531 million for the purchase of spectrum licences * $235 million paid for the purchase on the open market of BCE common shares for the settlement of share-based payments * $187 million of dividends paid on BCE preferred shares * $92 million paid for the repurchase of BCE preferred shares * $68 million of cash dividends paid by subsidiaries to NCI
Example 3: Europe – Deutsche Telekom AG Annual Report 2024
Calculation of net debt
millions of €
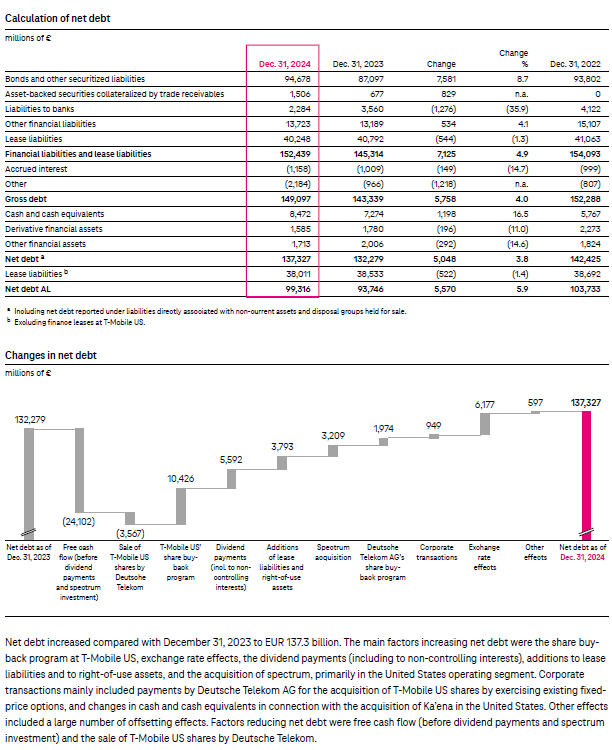
*Including net debt reported under liabilities directly associated with non-current assets and disposal groups held for sale. bExcluding finance leases at T-Mobile US.
Changes in net debt
millions of €
Net debt increased compared with December 31, 2023 to EUR 137.3 billion. The main factors increasing net debt were the share buy-back program at T-Mobile US, exchange rate effects, the dividend payments (including to non-controlling interests), additions to lease liabilities and to right-of-use assets, and the acquisition of spectrum, primarily in the United States operating segment. Corporate transactions mainly included payments by Deutsche Telekom AG for the acquisition of T-Mobile US shares by exercising existing fixed-price options, and changes in cash and cash equivalents in connection with the acquisition of Ka'ena in the United States. Other effects included a large number of offsetting effects. Factors reducing net debt were free cash flow (before dividend payments and spectrum investment) and the sale of T-Mobile US shares by Deutsche Telekom.
Example 4: Japan – KDDI Corp Annual Report 2024
31. Cash flow
An analysis of net debt and the movements in net debt for the periods presented are as follows:
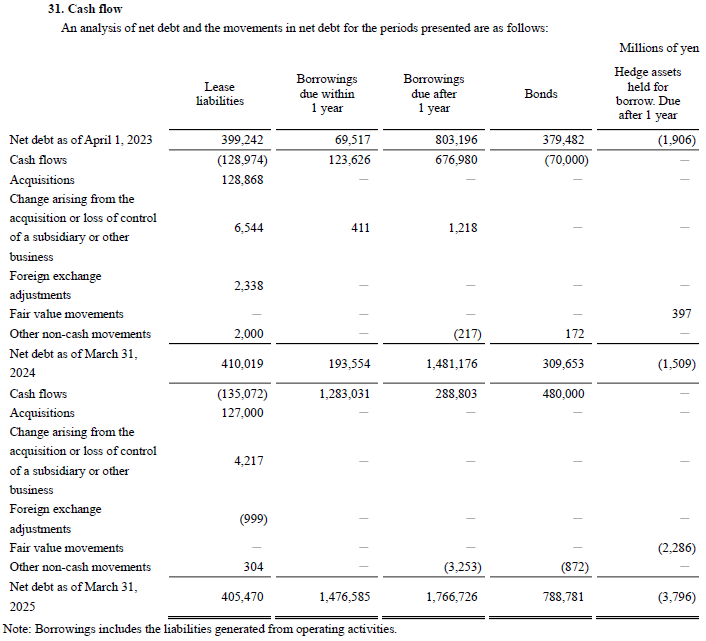
Note: Borrowings includes the liabilities generated from operating activities.
Footnotes
¹At the July 2025 UKEB meeting, the UKEB Secretariat presented the [draft] fourth UKEB research paper Statement of Cash Flows: UK Users' views on potential ways forward. ²See page 6 of Staff agenda paper 20A of the IASB meeting on 20 May 2025. ³See page 10 of Staff agenda paper 20A of the IASB meeting on 20 May 2025. ⁴See paragraph 4 and pages 13-15 of the UKEB fourth research paper Statement of Cash Flows: UK Users' views on potential ways forward, published in July 2025. ⁵See paragraphs B89-B95 of the UKEB second research paper: Statement of Cash Flows: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed Companies. ⁶See pages 9-12 of the summary of the first three UKEB research papers. ⁷See paragraph B76(b) of the Request for Information Third Agenda Consultation (March 2021) and paragraphs 12, 38(c) and 50 of the Staff Agenda Paper 20C for the IASB March 2025 meeting. ⁸See Staff Paper 6 Net Debt for the October 2013 Capital Markets Advisory Committee meeting and Staff Paper 8A Amendments t IAS 1: Net Debt for the October 2013 IASB meeting. ⁹See Staff Paper 11C Changes in Debt for the March 2014 IASB meeting. ¹⁰See paragraph A105 of the UKEB first research paper Statement of Cash Flows: Background and Key Issues. ¹¹The IAS 7 Disclosure Initiative in 2016 introduced amendments to IAS 7 (adding paragraphs 44A–44E) aimed at enhancing information related to changes in debt. It requires disclosure of information to help users evaluate changes in liabilities arising from financing activities. ¹²See paragraphs B90 and B96 of the UKEB second research paper Statement of Cash Flows: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed Companies. ¹³See Staff Paper 5 for the June 2019 meeting of the IFRS Interpretations Committee (IFRIC) and the IFRIC update June 2019. ¹⁴The top ten most indebted listed companies in each jurisdiction were identified using Reuters. Although Reuters has a 'Net Debt' parameter, the figure used is not taken directly from the financial statements; Reuters constructs a 'Net Debt' figure using its own formula. The UKEB restricted the search to entities which use IFRS, and has excluded Banks, Insurers, Funds & Trusts. ¹⁵See paragraphs 50-52 of the Staff Agenda Paper 20C for the IASB March 2025 meeting. ¹⁶See page 14 of the AcSB presentation to ASAF on Statement of Cash Flows Research Findings (September 2024). ¹⁷See UKEB Presentation to the International Forum of Accounting Standard Setters (IFASS) in March 2025 in its initial research findings (see page 13-14). ¹⁸Appendix E of 22 May 2025 Agenda paper 5 provides a summary of the responses to 15 questions in the User poll on the Statement of Cash Flows and Related Matters carried out between 25 March and 22 April 2025. ¹⁹FRC Lab's 2012 report on net debt reconciliations (NDR). ²⁰See paragraph 95 of the second research paper Statement of Cash Flows and Related Matters: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed companies, presented to the Board in February 2025. This paper was based on a review of a sample of annual reports for 30 UK Listed companies and highlighted cash flow related disclosures that those companies include in their financial statements beyond the requirements of IAS 7 and other IFRS Accounting Standards. ²¹IAS 7 paragraph 44A requires companies to disclose information about changes in financing liabilities. The subsequent paragraphs explain, amongst other matters, that this information may be presented in the form of a reconciliation of the opening and closing balances of liabilities arising from financing activities (IAS 7 paragraph 44D). IAS 7 paragraph 44E explains that the information may be combined with disclosures of changes in other assets and liabilities. Most UK companies adopt this method by presenting a net debt reconciliation. ²²See page 20 of IFRS 18 Effects Analysis published April 2024. Other performance measures outside the scope of IFRS 18 include: Free cash flow, Net debt, Return on equity, Number of customers, Customer satisfaction. ²³IFRS 18 presumes that a subtotal of income and expenses used in public communications outside financial statements represents management's view of financial performance. A company is permitted to rebut this presumption if it has reasonable and supportable information demonstrating that such a subtotal does not communicate management's view. This rebuttable presumption is discussed in Section 4.2 (page 52) of IFRS 18 Effects Analysis published April 2024 ²⁴Sub-totals introduced by IFRS 18 on the face of the income statement are (a). Operating profit and (b). Operating profit before depreciation, amortisation and impairments within the scope of IAS 36 Impairment of Assets.