4 Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 9 and IFRS 7)
Executive Summary
Project Stage
| IASB | Research / Pipeline | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Scope
Moderate
Purpose of the paper
This paper requests the Board's approval of the individual documents included in the 'adoption package' for the project to assess Amendments to *IFRS 9 and IFRS 7– Contracts Referencing Nature-dependent Electricity
- (the Amendments) for adoption.
The documents included in the adoption package are:
- the [draft] Endorsement Criteria Assessment (ECA);
- the [draft] Feedback Statement;
- the [draft] Due Process Compliance Statement;
- the [draft] Adoption Statements for the Amendments; and
- the [draft] text of the UK-adopted international accounting standards (Amendments to IFRS 9 and IFRS 7– Contracts Referencing Nature-dependent Electricity).
This paper also asks Board members to provide a tentative vote on the adoption of the Amendments.
Summary of the Issue
In March 2025, the UKEB published a Draft Endorsement Criteria Assessment (DECA) that tentatively concluded that the Amendments meet the adoption criteria set out in legislation. Five formal responses to the DECA consultation were received. A summary of the feedback received, along with recommended changes to the ECA wording, was discussed by the Board in June
- The [draft] ECA presented in this pack reflects the actions agreed at the June meeting. The amendments to *IFRS 19 Subsidiaries without Public Accountability: Disclosures
- included in the Amendments, will be considered for adoption at a future date as part of the UKEB's assessment work for the adoption of IFRS 19 as a whole. Accordingly, the amendments to IFRS 19 have not been considered as part of this adoption assessment. A tentative vote on the adoption of the Amendments will be held at this meeting. Voting forms for the formal written vote will be sent to Board members in July
- The result of that formal vote, when completed, will be updated on the UKEB website, in line with the Board's Terms of Reference.
Decisions for the Board
- Subject to any changes identified at this meeting, does the Board approve the documents in the adoption package?
- Does the Board tentatively approve the adoption of the Amendments to IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures for use in the UK?
Recommendation
The Secretariat recommends the Board:
- approves the relevant documents in the adoption package; and
- tentatively approves the adoption of the Amendments to IFRS 9 and IFRS 7 for use in the UK.
Appendices
- Appendix A [Draft] ECA
- Appendix B [Draft] Feedback Statement
- Appendix C [Draft] Due Process Compliance Statement
- Appendix D [Draft] Adoption Statements for the Amendments to IFRS 9 and IFRS 7
- Appendix E Annex to the Adoption Statement: Text of the UK-adopted international accounting standard Amendments to IFRS 9 and IFRS 7– Contracts Referencing Nature-dependent Electricity
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
The key changes and requirements introduced by the Amendments1 are summarised below.
- The Amendments apply only to contracts which reference nature-dependent electricity. Such contracts expose an entity to variability in the volume of electricity generated from natural sources which cannot be controlled.
- The Amendments clarify the requirements of the 'own-use' exception included in paragraph 2.4 of IFRS 9 Financial Instruments for contracts to purchase nature-dependent electricity.
- The Amendments permit the application of cash flow hedge accounting to hedging relationships in which the hedged item is a variable amount of forecast electricity transactions, and the hedging instrument is a contract referencing nature-dependent electricity.
- The Amendments require entities to disclose information about their contracts referencing nature-dependent electricity.
Endorsement of the Amendments
UKEB endorsement project
1At its February 2025 meeting, the UKEB approved a Project Initiation Plan for the endorsement project on Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments).
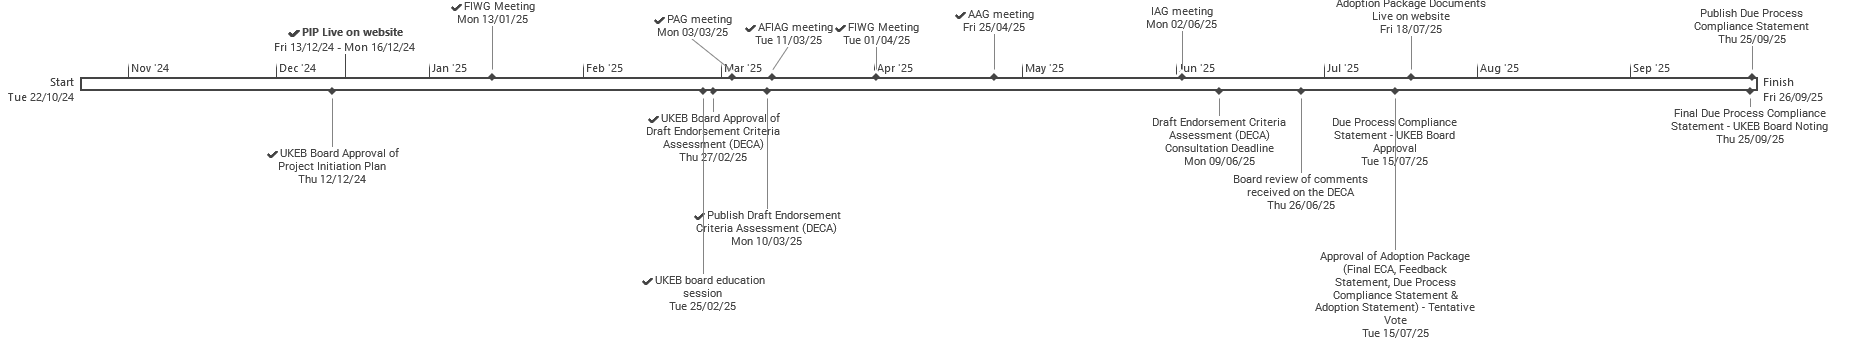
2At its March 2025 meeting, the UKEB approved the Draft Endorsement Criteria Assessment (DECA) of the Amendments for stakeholder consultation. The DECA sets out the UKEB's provisional assessment of whether the Amendments meet the UK's statutory requirements for adoption. The DECA was published on 10 March 2025 and was open for comment until 9 June 2025.
3At its June 2025 meeting the UKEB discussed the feedback received during the DECA consultation. Changes to the text in the Endorsement Criteria Assessment (ECA) arising from that feedback are marked up in Appendix A.
Scope of the adoption assessment
4The Amendments make related amendments to the mandatory2 parts of IFRS 7 Financial Instruments: Disclosures and IFRS 9 Financial Instruments and to Application Guidance that is an integral part of IFRS 9. These changes to the mandatory parts of the Standards form part of the UKEB's adoption assessment.
5Although not referenced in the title, the Amendments also include consequential amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures. The consequential amendments to IFRS 19 contained within the Amendments will not be considered for adoption as part of the endorsement assessment of these Amendments. Instead, they will be considered for adoption as part of the IFRS 19 endorsement assessment. If IFRS 19 is endorsed for use in the UK, the effective date will be set out in the relevant adoption statement.
6The Amendments also include additions to the Illustrative Examples which accompany IFRS 9 and the Basis for Conclusions of IFRS 9 and IFRS 7. These have not been included as part of the UKEB's assessment as UK-adopted international accounting standards comprise only the mandatory sections of standards.
Project closure
7In accordance with the UKEB's Due Process Handbook paragraph 6.30, the project closure process for endorsement projects comprises the following steps:
- preparation of an 'adoption package' for the Amendments; and
- voting on the adoption of the amended standard.
Adoption package
8The Secretariat has completed the work on the assessment of the Amendments. The Board is therefore asked whether it has any comments on the documents which, in accordance with paragraph 6.31 of the Due Process Handbook, form the adoption package for the Amendments:
- the ECA (Appendix A);
- the Feedback Statement (Appendix B);
- the draft Due Process Compliance Statement (Appendix C);
- the Adoption Statements for the Amendments (Appendix D); and
- the Annex to the Adoption Statement: the text of the UK-adopted international accounting standards (Appendix E).
Decision for the Board
- Subject to any changes identified at this meeting, does the Board approve the documents in the adoption package?
Voting on the adoption of the Amendments
9Decisions on the adoption of a standard or amendments are made at public Board meetings and follow the requirements of paragraphs 5.2-5.5 of the UKEB's Terms of Reference (ToR).
10In line with the ToR and paragraphs 6.42-6.44 of the Due Process Handbook, at this meeting Board members are asked to provide a tentative vote on the adoption of the Amendments based on the information included in the adoption package.
Decision for the Board
- Does the Board tentatively approve the adoption of the Amendments to IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures for use in the UK?
Next steps
11The written forms for the formal vote will be sent to Board members in July 2025. The result of that formal vote, when completed, will be updated on the UKEB website in line with the Board's ToR.
12A final version of the Due Process Compliance Statement will be presented to the Board for noting in September 2025. Once this has been noted by the Board it will be published on the UKEB website.
Endorsement and adoption timeline
Endorsement Criteria Assessment
Amendments to IFRS 9 and IFRS 7 - Contracts Referencing Nature-dependent Electricity
July 2025
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2025 All Rights Reserved
- Executive Summary
- Appendices
- Endorsement of the Amendments
- Endorsement and adoption timeline
- Endorsement Criteria Assessment
- Introduction
- I. UK statutory requirements for adoption
- 2. Description and assessment of the Amendments
- Purpose of this Feedback Statement
- Description of the Amendments
- UKEB consultation on the DECA
- UKEB public consultation on the DECA
- Overall Assessment
- Detailed assessment—Comments from respondents
- Disclaimer
- Contact Us
- Appendix C: DRAFT Due Process Compliance Statement: Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
- Adoption Statement
- Approval by the UK Endorsement Board
- Adoption Statement
- Approval by the UK Endorsement Board
- Terms of Use for Users
- Amendments to IFRS 9 Financial Instruments
- Appendix B
- Amendments to IFRS 7 Financial Instruments: Disclosures
Introduction
Purpose
1The purpose of this Draft Endorsement Criteria Assessment (DECA) is to determine whether the Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments) issued by the International Accounting Standards Board (IASB) in December 2024 meet the UK's statutory requirements for adoption as set out in Regulation 7 of Statutory Instrument 2019/685 3 (SI 2019/685).
2The Amendments have an effective date of 1 January 2026 with earlier application permitted.
3The UKEB actively influenced the development of the Amendments. This included submitting a Final Comment Letter on 6 August 2024 in response to the IASB's Exposure Draft Contracts for Renewable Electricity.
Background to the Amendments
4Section 2 in this DECA provides a brief description of the Amendments.
Scope of the adoption assessment
5The Amendments make changes to the mandatory parts of IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures. These changes to the mandatory parts of the standard form part of the UKEB's adoption assessment.
6As UK-adopted international accounting standards comprise only the mandatory2 sections of standards4, the Amendments to the Illustrative Examples and Basis for Conclusions of IFRS 9 and IFRS 7 are not adopted by the Board and are not considered in this DECA.
7IFRS 19 Subsidiaries without Public Accountability: Disclosures (IFRS 19) will be considered for adoption at a future date. The consequential Amendments to IFRS 19 included in the Amendments will be considered as part of the UKEB's assessment work for the adoption of IFRS 19. Accordingly, the Amendments to IFRS 19, included as a separate element in the Amendments, have not been considered for adoption by the UKEB in this DECA.
8If IFRS 19 (including the Amendments to IFRS 19 within the Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity) is endorsed for use in the UK, the effective date for those disclosures will be set out in the relevant adoption statement.
Structure of the assessment
9The UKEB's analysis is presented in the following sections:
- Section 1: describes UK statutory requirements for adoption of new or amended international accounting standards and states the UKEB's adoption decision; and
- Section 2: discusses how the Amendments meet the criteria in Section 1.
Do the Amendments lead to a significant change in accounting practice?
10A standard adopted by the UKEB under Regulation 6 of SI 2019/685 that it considers is likely to lead to a 'significant change in accounting practice', is subject to the requirements in paragraph 3 of Regulation 11 of SI 2019/685 that the UKEB:
- carry out a review of the impact of the adoption of the standard; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)".
11Section 2 of the DECA discusses whether the Amendments lead to a significant change in accounting practice.
I. UK statutory requirements for adoption
UK statutory requirements
1.1Paragraph 1 of Regulation 7 of SI 2019/685 requires that an international accounting standard only be adopted if:
"(a) the standard5 is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
(b) the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and (c) the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.”
1.2This DECA assesses the criteria above in the following order:
- Whether the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c)).
- Whether the Amendments are not contrary to the principle that an entity's accounts must give a true and fair view (Regulation 7(1)(a)).
- Whether use of the Amendments is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)). Regulation 7(2) of SI 2019/685 includes specific areas to consider for this assessment. They are:
- whether the Amendments are likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the Amendments; and
- whether the Amendments are likely to have an adverse effect on the economy of the UK, including on economic growth.
Relevance, Reliability, Understandability and Comparability
1.3Information is relevant if it is capable of making a difference in the decision-making of users7 or in their assessment of the stewardship of management. The information may aid predictions of the future, confirm or change evaluations of the past, or both.
1.4Financial information is reliable if, within the bounds of materiality, it:
- can be depended on by users to represent faithfully what it either purports to represent or could reasonably be expected to represent;
- is complete; and
- is free from material error and bias.
1.5Financial information should be readily understandable by users with a reasonable knowledge of business, economic activities and accounting, and a willingness to study the information with reasonable diligence.
1.6Information is comparable if it enables users to identify and understand similarities in, and differences among, items. Information about an entity should be comparable with similar information about other entities and with similar information about the same entity for another period.
1.7In conducting the overall assessment against the technical accounting criteria, the UKEB is required to adopt an absolute, rather than a relative, approach. This means that this assessment is an absolute one against the criteria (do the Amendments provide information that is understandable, relevant, reliable and comparable?) rather than a relative one (do the Amendments provide information that is more understandable, relevant, reliable and comparable than current, or any other, accounting?). When an assessment of any individual aspect or requirement of the Amendments uses comparative language (e.g. 'enhances comparability'), the objective is to explain that any individual aspect or requirement of the Amendments has the potential to “enhance” one or more of the qualitative characteristics. Consideration of whether the Amendments are likely to improve the quality of financial reporting is separate from this assessment and is included within the UK long term public good assessment in Section 2.
True and fair view assessment
1.8As noted above, the first adoption criterion set out in Regulation 7(1) of SI 2019/685 requires that an international accounting standard can be adopted only if:
"[....] the standard is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]”
1.9For the sake of brevity, the UKEB refers to the assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair principle'. However, these abbreviated expressions do not imply that the assessment has considered anything other than the full terms of the endorsement criterion set out above.
1.10The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair principle. In other words, it is an ex-ante assessment. The UKEB has therefore considered whether the Amendments contain any requirement that would prevent accounts prepared using the Amendments from giving a true and fair view.
1.11The approach is to determine whether the Amendments are not contrary to the true and fair principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of the Amendments taken as a whole, including their interaction with other UK-adopted international accounting standards.
1.12For the purposes of the assessment, the UKEB considers the requirement in IAS 1 Presentation of Financial Statements for financial statements to 'present fairly the financial position, financial performance and cash flows of an entity'8 to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
"[....] the standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]"
1.9For the sake of brevity, the UKEB refers to the assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair principle'. However, these abbreviated expressions do not imply that the assessment has considered anything other than the full terms of the endorsement criterion set out above.
1.10The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair principle. In other words, it is an ex-ante assessment. The UKEB has therefore considered whether the Amendments contain any requirement that would prevent accounts prepared using the Amendments from giving a true and fair view.
1.11The approach is to determine whether the Amendments are not contrary to the true and fair principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of the Amendments taken as a whole, including their interaction with other UK-adopted international accounting standards.
1.12For the purposes of the assessment, the UKEB considers the requirement in IAS 1 Presentation of Financial Statements for financial statements to 'present fairly the financial position, financial performance and cash flows of an entity'[^9] to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
1.13This assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
Adoption decision
1.14Section 2 of this DECA discusses how the Amendments meet the statutory endorsement criteria set out in this Section 1.
1.15On the basis of these assessments, and subject to any stakeholder feedback, the UKEB concludes that the Amendments meet the statutory endorsement criteria. The UKEB is therefore of the view that it will adopt the Amendments for use in the UK.
2. Description and assessment of the Amendments
Description
| Amendments to IFRS 9 and IFRS 7 | |
|---|---|
| True and fair view assessment | |
|---|---|
Purpose of this Feedback Statement
This Feedback Statement presents the views of UK stakeholders received during the UKEB's public consultation on the Draft Endorsement Criteria Assessment (DECA) of Amendments to *IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
- and where relevant explains how the UKEB has addressed those views in the final ECA.
Description of the Amendments
Amendments to IFRS and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments) were issued by the IASB in December 2024. A summary of the Amendments is presented below.
| The Amendments | Key changes |
|---|---|
| IFRS 9 Financial Instruments – Scope | The Amendments apply only to contracts which reference nature-dependent electricity. Such contracts expose an entity to variability in the volume of electricity generated from natural sources which cannot be controlled. |
| IFRS 9 - Own-use | The Amendments clarify the requirements of the ‘own-use’ exception included in paragraph 2.4 of IFRS 9 for contracts to purchase nature-dependent electricity. |
| IFRS 9 - Hedge accounting | The Amendments permit the application of cash flow hedge accounting to hedging relationships in which the hedged item is a variable amount of forecast electricity transactions, and the hedging instrument is a contract referencing nature-dependent electricity. |
| IFRS 7 Financial Instruments: Disclosures | The Amendments require entities to disclose information about their contracts referencing nature-dependent electricity. |
The Amendments have been issued by the IASB to enable entities to more faithfully represent contracts referencing nature-dependent electricity in their financial statements. The Amendments are effective for annual reporting periods beginning on or after 1 January
- Earlier application is permitted. The date of initial application shall be the beginning of a reporting period, which could be a period other than an annual period.
The own-use Amendments to IFRS 9 must be applied retrospectively based on the facts and circumstances in existence at the date of initial application. Comparative information is not required and may only be presented where possible without the use of hindsight.
The hedge accounting Amendments to IFRS 9 must be applied prospectively.
An entity applies the Amendments to IFRS 7 at the same time as it applies the Amendments to IFRS 9.
UKEB consultation on the DECA
Prior to publishing the DECA, we gathered stakeholder feedback through discussions with subject matter experts and certain UKEB advisory and working groups. Their feedback was incorporated in the DECA.
Outreach activities following publication of the DECA included: * discussions with UKEB Advisory and Working Groups including the Preparer Advisory Group, the Accounting Firms and Institutes Advisory Group, the Investor Advisory Group, the Academic Advisory Group and the Financial Instruments Working Group*; * a round table attended by three members of the Rate-regulated Activities Technical Advisory Group and one subject matter expert from an accounting firm; and * public consultation on the DECA.
*The current number of members of each of these groups is as follows: the Accounting Firms and Institutes Advisory Group has eleven members, the Investor Advisory Group has eleven members, the Academic Advisory Group has nine members, and the Financial Instruments Working Group has ten members. Further information about Advisory and Working Groups can be accessed here.
UKEB public consultation on the DECA
The DECA was published for consultation for 91 days, between 10 March 2025 and 9 June
- During the consultation period, the UKEB promoted awareness of the DECA and encouraged stakeholders to respond through News Alerts, LinkedIn posts, and the UKEB website. * Five formal written responses from stakeholders were received. * These responses were published on the UKEB website. * All stakeholder comments and views were considered in reaching the UKEB's final assessment of the Amendments.
| Stakeholder type | Number of formal responses |
|---|---|
| Accounting firms | 4 |
| Professional body | 1 |
| Total | 5 |
Overall Assessment
Respondents to the DECA generally concurred with the UKEB's assessment based on the adoption criteria in paragraph 1 of Regulation 7 SI 2019/685 and are supportive of the adoption of the Amendments.
Detailed assessment—Comments from respondents
| UKEB Tentative Assessment | Stakeholder Views* | UKEB Final Assessment |
|---|---|---|
| Technical Accounting Criteria Assessment | ||
| The DECA tentatively concluded that the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management, as required by Regulation 7(1) of SI 2019/685. | Five formal responses supported the endorsement of the Amendments. Of these, three addressed the technical accounting criteria and all three agreed with the UKEB's tentative conclusion in the DECA. Respondents who provided formal or informal feedback on whether the Amendments were capable of being applied in practice, agreed that they were. One Advisory Group member highlighted the importance of paragraph 2.3B of the Amendments which states that an entity shall not apply the Amendments to IFRS 9 "by analogy to other contracts, items or transactions." | Amended the ECA to refer to paragraph 2.3B of the Amendments to support the technical criteria assessment. |
| Technical Accounting Criteria Assessment (continued) | ||
| The DECA tentatively concluded that the Amendments met the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management, as required by Regulation 7(1) of SI 2019/685. | One member of the Preparer Advisory Group was of the view that the disclosures required for contracts meeting the 'own-use' exception would be onerous and costly to provide. However, one member of the Investor Advisory Group was of the view that additional disclosures required under the own-use Amendments might provide more useful information than a fair valuation at a single point in time. | The DECA acknowledged at page 27 that stakeholder feedback on the cost of disclosures has been mixed but that, overall, the cost of disclosures is not expected to be significant or higher than the cost of obtaining a fair valuation for the relevant contracts. No changes proposed in the final ECA. |
| True and fair view assessment | ||
| The DECA tentatively concluded that the Amendments are not contrary to the true and fair view principle set out in Regulation 7(1) of SI 2019/685. | Five formal responses supported the endorsement of the Amendments. Of these, three addressed the true and fair view assessment and agreed with the UKEB's tentative conclusion in the DECA. | No changes. |
| UK long term public good | ||
| The DECA tentatively concluded that the use of the Amendments was likely to be conducive to the long term public good in the UK as required by Regulation 7(1) of SI 2019/685. | Five formal responses supported the endorsement of the Amendments. Of these, three responses addressed the UK long term public good assessment. All three agreed with the UKEB's tentative conclusion in the DECA. | Consistent with the tentative assessment in the DECA. |
| Significant change in accounting practice | ||
| The DECA concluded that the Amendments are not likely to lead to a significant change in accounting practice and do not meet the criteria for a post-implementation review under Regulation 11 in SI 2019/685. | Five formal responses supported the endorsement of the Amendments. Of these, three responses addressed this matter and agreed with the UKEB's tentative conclusion in the DECA. One Advisory Group member fed back that the hedge accounting Amendments might constitute a change in accounting practice, as hedge accounting would potentially be available for certain contracts where this had not previously been the case. However, most respondents who provided formal or informal feedback on this point agreed that the Amendments were unlikely to lead to a significant change in accounting practice, referring to the narrow scope of the Amendments and the limited number of entities who had entered into contracts referencing nature-dependent electricity to date. | No changes. |
*Formal feedback refers to written feedback which was provided in response to the DECA and published on the UKEB website. Unless explicitly stated in the table, feedback was provided informally.
Disclaimer
This Feedback Statement has been produced in order to set out the UKEB's response to stakeholder comments received on the UKEB's DECA on the IASB's *Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
- and should not be relied upon for any other purpose.
The views expressed in this Feedback Statement are those of the UK Endorsement Board at the point of publication.
Any sentiment or opinion expressed within this Feedback Statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board 13th Floor
| 1 Harbour Exchange | Harbour Exchange Square | London | E14 9GE www.endorsement-board.uk
Appendix C: DRAFT Due Process Compliance Statement: Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
15 July 2025 Agenda Paper 4: Appendix C
| Title of the Amendments | Issue dates |
|---|---|
| Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments). | Exposure Draft Contracts for Renewable Electricity issued 8 May 2024 (the ED). Final Amendments issued 18 December 2024. Effective for annual reporting periods beginning on or after 1 January 2026. Earlier application permitted. |
Project preparation
| Step | Mandatory / optional¹ | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Added to the UKEB technical work plan [Due Process Handbook (Handbook) 4.30] | Mandatory | Project is included in the UKEB published technical work plan | Complete: the Amendments were included in the UKEB published technical work plan dated 12 December 2024. |
| Project Initiation Plan (PIP) [Handbook 6.12 to 6.16, A1 to A2 and A12 to A14] | Mandatory | PIP, including an outreach plan for stakeholders, resource allocation and an assessment of whether to set up an ad hoc advisory group, approved at a UKEB Board public meeting. | Complete: The PIP included the purpose, background, proposed outreach activities, milestones and timelines for the project. The resource allocated was 0.8 of a Project Director, along with appropriate support from a Project Manager and from the UKEB Economics team and oversight of one Senior Project Director. Taking a proportionate approach, an ad hoc advisory group was considered unnecessary. The PIP was approved at the 12 December 2024 Board meeting and published on the UKEB webpage. |
| Assessment of whether PIP required updating. | Mandatory | Assessment of whether PIP required updating. | Complete: The Secretariat monitored this throughout the project, the nature and scope of which remained as proposed in the original PIP. |
| Education sessions [Handbook 4.10] | Optional | Board provided with Education sessions | Complete: The Board was provided with an education session on 25 February 2025 (private session). |
Desk-based research
| Step | Mandatory / optional² | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Desk-based research [Handbook 6.17 and A3] | Optional | Review of relevant documentation | Complete: the Secretariat has reviewed relevant documentation, including: • The IASB’s work on the Amendments (including staff papers, the ED, the Amendments); • the Dissenting Opinion on the Amendments; • The Bases for Conclusions for the Amendments; • Previous work done by the UKEB while influencing the IASB’s project on Power Purchase Agreements, including minutes of meetings with UK stakeholders and subject matter experts and information from the financial statements of UK listed IFRS reporters; Energy sector reports³; and • The European Financial Reporting Advisory Group (EFRAG) endorsement advice to the European Commission. |
Outreach
| Step | Mandatory / optional¹ | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Consult with a representative range of stakeholders prior to adoption [Handbook 6.18 to 6.22 and A4 to A8] | Mandatory | Evidence of consultation | As described in the PIP, consultation activities were focused on consultation with UKEB advisory groups and public consultation on the DECA (see table at paragraph A11 of the PIP). The Secretariat also convened a roundtable with UK stakeholders and subject matter experts. |
| DECA [Handbook 6.23 to 6.29 and A4(d)] | Mandatory | DECA reviewed and approved at a UKEB public meeting and published on the UKEB website for public consultation for a period of | Complete: The DECA was reviewed and approved for publication (subject to minor changes) at the February 2025 Board meeting. The DECA was published on the UKEB project page for consultation on 10 March 2025, for a 91-day consultation period, ending 9 June 2025. |
In accordance with the Due Process Handbook. For example, Aurora Energy Research (2022) and UK Energy Trends, July to September 2024. In accordance with the Due Process Handbook.
| Step | Mandatory / optional4 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| more than 90 days. | A News Alert (published on 10 March 2025) and a LinkedIn post (published on 10 March 2025) were issued to publicise the DECA and solicit stakeholder feedback. | ||
| Mandatory | Public responses to DECA assessed and published on website | Complete: The UKEB received five formal written responses to the DECA consultation, which were published on the UKEB project webpage. A summary of the feedback received was presented at the June 2025 UKEB meeting. Minor changes, agreed with the Board, were made to the draft ECA. Feedback received was summarised in the Feedback Statement. |
Project finalisation and project closure
| Step | Mandatory / optional5 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Final Endorsement Criteria Assessment (ECA) [Handbook 6.32 and 6.40 to 6.48 and A4d] | Mandatory | Final ECA approved by the UKEB in a public meeting and published on the website | [Complete: The Board approved the ECA at its 15 July 2025 public meeting. The final ECA was published on the UKEB website. A News Alert on [date] and a LinkedIn post on [date] were published to alert stakeholders to the endorsement and adoption of the Amendments]. |
| Feedback Statement [Handbook 6.33 to 6.36 and A9 to A11] | Mandatory | Feedback Statement approved by the UKEB in a public meeting and published on the UKEB website | [Complete: The Board approved the feedback statement at its 15 July 2025 public meeting. The final Feedback Statement was published on the UKEB website on [date].] |
| Adoption Statement [Handbook 6.40 to 6.48] | Mandatory | Adoption Statement approved by the UKEB in public meeting and published on the UKEB website | [Complete: The Adoption Statements for the Amendments were approved by the Board at its 15 July 2025 public meeting. The final Adoption Statements for the Amendments was published on [date].] |
| Voting on adoption of the Amendments [Handbook 6.42 to 6.48] | Mandatory | Tentative vote | [Complete: A tentative vote took place at the 15 July 2025 Board meeting, based on the discussion of the adoption package, which included the final draft ECA, draft Feedback Statement, draft Due Process Compliance Statement, draft Adoption Statements for the Amendments and the text of the UK-adopted international accounting standard Amendments to IFRS 9 and IFRS 7-Contracts Referencing Nature-dependent Electricity. The vote was indicative only.] |
| Mandatory | Evidence of written vote (in paper or electronic form) | [Complete: The Adoption Statement and voting forms were sent to the Board for voting (accompanied by the text of the Amendments to be adopted) on XX July 2025 (written forms due by XX July 2025). The vote was formalised when the final written voting forms were received.] | |
| Due Process Compliance Statement (DPCS) [Handbook 6.37 to 6.39 and A12 to A14] | Mandatory | Outcome of the vote within 3 working days of the formal vote published on website | [Complete: The announcement of the adoption of the Amendments was published on the UKEB website on XX July 2025.] |
| Mandatory | DPCS approved by the UKEB in public meeting and published on the UKEB website | [Complete: A draft DPCS was presented for approval to the Board at its 15 July 2025 public meeting. [A final DPCS was tabled for noting at the Board's 25 September 2025 meeting. The final DPCS was published on the UKEB website after the 25 September 2025 Board meeting.] |
Ongoing communications
| Step | Mandatory / optional6 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Public Board meetings [Handbook 4.10] | Mandatory | UKEB public meetings held to discuss technical project | Complete: The Board approved:A paper summarising feedback received during the DECA consultation period was discussed by the Board at its meeting on 26 June 2025. |
| Secretariat papers [Handbook 4.20] | Mandatory | Board meeting papers posted and publicly available usually no later than five working days before a Board meeting | Complete: The UKEB's meeting papers were published on the UKEB website five working days before the public meetings. Meeting minutes and recordings were made publicly available via the UKEB website. |
| Project webpage [Handbook 4.25(b)] | Mandatory | Project webpage contains a project description with up-to-date information on the project. | Complete: The project webpage has been updated regularly on a timely basis. Optional News Alerts and LinkedIn posts were issued throughout the project, as appropriate, for the publication of the DECA, [the Final ECA and Feedback Statement] as detailed in the relevant sections above. |
Conclusion
This project complies with the applicable due process steps, as set out in the Handbook (published December 2022).
Adoption Statement
Amendments to IFRS 9 and IFRS 7—Contracts Referencing Nature-dependent Electricity
(Amendments to IFRS 9 Financial Instruments)
1The UK Endorsement Board is designated under regulation 2(1) of The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 6091 (“the Delegating Regulations”) for the purpose of enabling it to exercise functions of the Secretary of State under Chapter 3 of Part 2 of The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 6852 (“the Regulations").
2Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (“the Amendments”) contain related amendments to IFRS 9 and IFRS 7 Financial Instruments: Disclosures. These related amendments have been assessed by the UK Endorsement Board within a single overarching Endorsement Criteria Assessment. The Amendments also include an amendment to IFRS 19 Subsidiaries without Public Accountability: Disclosures, which will be considered for adoption at a future date as part of the UKEB's assessment work for the adoption of IFRS 19, as a whole. Accordingly, the amendments to IFRS 19 have not been considered as part of this adoption. If IFRS 19 is endorsed for use in the UK, the effective date will be set out in the relevant adoption statement.
3The UK Endorsement Board, in exercise of the powers conferred by regulation 6(1) of the Regulations, adopts the following amendments to international accounting standards published by the International Accounting Standards Board (IASB), for use within the United Kingdom:
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 9 Financial Instruments) (“the Standard”)3.
4In accordance with regulation 7(1) of the Regulations, the UK Endorsement Board is of the view that:
- the Standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the Standard is likely to be conducive to the long term public good in the United Kingdom; and
- the Standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
5In accordance with regulation 8 of the Regulations, the UK Endorsement Board is of the view that adequate consultation with persons representative of those with an interest in the quality and availability of accounts, including users and preparers of accounts, has been undertaken before the adoption decision.
6The adopted Standard referred to in paragraph 3:
- must be used for financial years beginning on or after 1 January 2026;
- may be used for financial years beginning before 1 January 2026. An entity must disclose if it applies these amendments for an earlier period. The initial application date shall be the beginning of a reporting period.
7The text of the Standard is set out in the annex to this statement.
Approval by the UK Endorsement Board
Adoption of Amendments to IFRS 9 and IFRS 7—Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 9 Financial Instruments)
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity published by the IASB in December 2024 was approved for adoption by XX members of the UK Endorsement Board.
| Pauline Wallace, Chair | |
|---|---|
| Amir Amel-Zadeh | |
| Michael Ashley | |
| Philip Aspin | |
| Anthony Clifford | |
| Katherine Coates | |
| Robin Cohen | |
| Owen Glaysher | |
| Edward Knapp | |
| Paul Lee | |
| Michael Metcalf | |
| Peter Reilly | |
| Michael Wells |
XX XX 2025
Adoption Statement
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
(Amendments to IFRS 7 Financial Instruments: Disclosures)
1The UK Endorsement Board is designated under regulation 2(1) of The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 6091 (“the Delegating Regulations”) for the purpose of enabling it to exercise functions of the Secretary of State under Chapter 3 of Part 2 of The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 6852 (“the Regulations").
2Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (“the Amendments”) contain related amendments to IFRS 9 Financial Instruments and IFRS 7. These related amendments have been assessed by the UK Endorsement Board within a single overarching Endorsement Criteria Assessment. The Amendments also include an amendment to IFRS 19 Subsidiaries without Public Accountability: Disclosures, which will be considered for adoption at a future date as part of the UKEB's assessment work for the adoption of IFRS 19, as a whole. Accordingly, the amendments to IFRS 19 have not been considered as part of this adoption. If IFRS 19 is endorsed for use in the UK, the effective date will be set out in the relevant adoption statement.
3The UK Endorsement Board, in exercise of the powers conferred by regulation 6(1) of the Regulations, adopts the following amendments to international accounting standards published by the International Accounting Standards Board (IASB), for use within the United Kingdom:
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 7 Financial Instruments: Disclosures) (“the Standard”)3.
4In accordance with regulation 7(1) of the Regulations, the UK Endorsement Board is of the view that:
- the Standard is not contrary to either of the following principles—
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the Standard is likely to be conducive to the long term public good in the United Kingdom; and
- the Standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.
5In accordance with regulation 8 of the Regulations, the UK Endorsement Board is of the view that adequate consultation with persons representative of those with an interest in the quality and availability of accounts, including users and preparers of accounts, has been undertaken before the adoption decision.
6The adopted Standard referred to in paragraph 3 shall be applied at the same time as an entity applies the related amendments to IFRS 9 for contracts referencing nature-dependent electricity.
7The text of the Standard is set out in the annex to this statement.
Approval by the UK Endorsement Board
Adoption of Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 7 Financial Instruments: Disclosures)
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity published by the IASB in December 2024 was approved for adoption by XX members of the UK Endorsement Board.
| Pauline Wallace, Chair | |
|---|---|
| Amir Amel-Zadeh | |
| Michael Ashley | |
| Philip Aspin | |
| Anthony Clifford | |
| Katherine Coates | |
| Robin Cohen | |
| Owen Glaysher | |
| Edward Knapp | |
| Paul Lee | |
| Michael Metcalf | |
| Peter Reilly | |
| Michael Wells |
XX XX 2025
UK-adopted international accounting standards contain copyright material of the IFRS® Foundation (Foundation) in respect of which all rights are reserved.
Reproduced and distributed by the UK Endorsement Board (“UKEB”), pursuant to the delegation by the Secretary of State in the International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 609, with the permission of the Foundation within the United Kingdom only. No rights granted to third parties other than as permitted by the Terms of Use (see below) without the prior written permission of the UKEB, and the Foundation.
'UK-adopted international accounting standards' are issued by the UKEB in respect of their application in the United Kingdom and have not been prepared or endorsed by the International Accounting Standards Board.
Terms of Use for Users
1The IFRS Foundation and the UK Endorsement Board (“UKEB") (pursuant to the delegation by the Secretary of State in the International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 No. 609), grant users of the UK-adopted international accounting standards' (Users) the permission to reproduce the 'UK-adopted international accounting standards' for
- the User's Professional Use, or
- private study and education
Professional Use: means use of ‘UK-adopted international accounting standards' in the User's professional capacity in connection with the business of providing accounting services for the purpose of application of IFRS as adopted by the UK for preparation of financial statements and/or financial statement analysis to the User's clients or to the business in which the User is engaged as an accountant.
For the avoidance of doubt, the abovementioned usage does not include any kind of activities that make (commercial) use of the ‘UK-adopted international accounting standards' other than direct or indirect application of the 'UK-adopted international accounting standards' such as but not limited to commercial seminars, conferences, commercial training or similar events.
2For any application that falls outside Professional Use, Users shall be obliged to contact the UKEB and the IFRS Foundation for a separate individual licence under terms and conditions to be mutually agreed.
3Except as otherwise expressly permitted in this notice, Users shall not, without prior written permission of the UKEB and the Foundation, have the right to license, sublicense, transmit, transfer, sell, rent, or otherwise distribute any portion of the 'UK-adopted international accounting standards' to third parties in any form or by any means, whether electronic, mechanical or otherwise either currently known or yet to be invented.
4Users are not permitted to modify or make alterations, additions or amendments to or create any derivative works from the 'UK-adopted international accounting standards' save as otherwise expressly permitted in this notice.
For further details about licensing the IFRS Foundation's intellectual property please contact [email protected].
Amendments to IFRS 9 Financial Instruments
Paragraphs 2.3A−2.3B, 2.8, 6.10.1–6.10.2, 7.1.15, 7.2.51–7.2.53, B2.7–B2.8 and their subheadings are added. A subheading is also added before paragraph 2.4. Paragraph 2.6 is amended. New text is underlined. Paragraphs 2.4 and 2.5 are not amended but are included for ease of reference.
Chapter 2 Scope
2.3A Paragraphs 6.10.1–6.10.2 and B2.7–B2.8 apply only to contracts referencing nature-dependent electricity. Contracts referencing nature-dependent electricity are contracts that expose an entity to variability in the underlying amount of electricity because the source of electricity generation depends on uncontrollable natural conditions (for example, the weather). Contracts referencing nature-dependent electricity include both contracts to buy or sell nature-dependent electricity and financial instruments that reference such electricity. 2.3B An entity shall not apply paragraphs 6.10.1–6.10.2 and B2.7–B2.8 by analogy to other contracts, items or transactions.
Contracts to buy or sell non-financial items
2.4 This Standard shall be applied to those contracts to buy or sell a non-financial item that can be settled net in cash or another financial instrument, or by exchanging financial instruments, as if the contracts were financial instruments, with the exception of contracts that were entered into and continue to be held for the purpose of the receipt or delivery of a non-financial item in accordance with the entity's expected purchase, sale or usage requirements. However, this Standard shall be applied to those contracts that an entity designates as measured at fair value through profit or loss in accordance with paragraph 2.5.
2.5 A contract to buy or sell a non-financial item that can be settled net in cash or another financial instrument, or by exchanging financial instruments, as if the contract was a financial instrument, may be irrevocably designated as measured at fair value through profit or loss even if it was entered into for the purpose of the receipt or delivery of the non-financial item in accordance with the entity's expected purchase, sale or usage requirements. This designation is available only at inception of the contract and only if it eliminates or significantly reduces a recognition inconsistency (sometimes referred to as an 'accounting mismatch') that would otherwise arise from not recognising that contract because it is excluded from the scope of this Standard (see paragraph 2.4).
2.6 There are various ways in which a contract to buy or sell a non-financial item can be settled net in cash or another financial instrument or by exchanging financial instruments. These include:
A contract to which (b) or (c) applies is not entered into for the purpose of the receipt or delivery of the non-financial item in accordance with the entity's expected purchase, sale or usage requirements and, accordingly, is within the scope of this Standard. Other contracts (which include contracts as described in paragraph 2.3A) to which paragraph 2.4 applies are evaluated to determine whether they were entered into and continue to be held for the purpose of the receipt or delivery of the non-financial item in accordance with the entity's expected purchase, sale or usage requirements and, accordingly, whether they are within the scope of this Standard.
2.8 An entity shall also apply paragraphs B2.7–B2.8 to assess whether contracts referencing nature-dependent electricity (as described in paragraph 2.3A) are entered into and continue to be held for the purpose of the receipt of electricity in accordance with the entity's expected usage requirements.
Chapter 6 Hedge accounting
6.10 Contracts referencing nature-dependent electricity
6.10.1 Some contracts referencing nature-dependent electricity are designated as hedging instruments in hedges of forecast electricity transactions. In addition to the requirements in paragraph 6.3.7, for such a hedging relationship an entity is permitted to designate as the hedged item a variable nominal amount of forecast electricity transactions that is aligned with the variable amount of nature-dependent electricity expected to be delivered by the generation facility as referenced in the hedging instrument. The other hedge accounting requirements of this chapter continue to apply to such a hedging relationship. 6.10.2 If the cash flows of the contract referencing nature-dependent electricity designated as the hedging instrument are conditional on the occurrence of a forecast transaction that is designated as the hedged item in accordance with paragraph 6.10.1, this forecast transaction is presumed to be highly probable as required by paragraph 6.3.3.
2.6There are various ways in which a contract to buy or sell a non-financial item can be settled net in cash or another financial instrument or by exchanging financial instruments. These include:
A contract to which (b) or (c) applies is not entered into for the purpose of the receipt or delivery of the non-financial item in accordance with the entity's expected purchase, sale or usage requirements and, accordingly, is within the scope of this Standard. Other contracts (which include contracts as described in paragraph 2.3A) to which paragraph 2.4 applies are evaluated to determine whether they were entered into and continue to be held for the purpose of the receipt or delivery of the non-financial item in accordance with the entity's expected purchase, sale or usage requirements and, accordingly, whether they are within the scope of this Standard.
2.8An entity shall also apply paragraphs B2.7-B2.8 to assess whether contracts referencing nature-dependent electricity (as described in paragraph 2.3A) are entered into and continue to be held for the purpose of the receipt of electricity in accordance with the entity's expected usage requirements.
Chapter 6 Hedge accounting
6.10 Contracts referencing nature-dependent electricity
6.10.1Some contracts referencing nature-dependent electricity are designated as hedging instruments in hedges of forecast electricity transactions. In addition to the requirements in paragraph 6.3.7, for such a hedging relationship an entity is permitted to designate as the hedged item a variable nominal amount of forecast electricity transactions that is aligned with the variable amount of nature-dependent electricity expected to be delivered by the generation facility as referenced in the hedging instrument. The other hedge accounting requirements of this chapter continue to apply to such a hedging relationship. 6.10.2If the cash flows of the contract referencing nature-dependent electricity designated as the hedging instrument are conditional on the occurrence of a forecast transaction that is designated as the hedged item in accordance with paragraph 6.10.1, this forecast transaction is presumed to be highly probable as required by paragraph 6.3.3.
Chapter 7 Effective date and transition
7.1 Effective date
7.1.15Contracts Referencing Nature-dependent Electricity, issued in December 2024, added paragraphs 2.3A-2.3B, 2.8, 6.10.1–6.10.2, 7.2.51-7.2.53, and B2.7-B2.8 and amended paragraph 2.6. An entity shall apply these amendments for annual reporting periods beginning on or after 1 January 2026. Early application is permitted. If an entity applies the amendments for an earlier period, it shall disclose that fact.
7.2 Transition
Transition for Contracts Referencing Nature-dependent Electricity
7.2.51An entity shall apply paragraphs 2.3A-2.3B, 2.8 and B2.7-B2.8 retrospectively in accordance with IAS 8 using the facts and circumstances at the date of initial application (the date when an entity first applies the amendments). The date of initial application shall be the beginning of a reporting period, which might be a reporting period other than an annual reporting period. An entity need not restate prior periods to reflect the application of these amendments. The entity is permitted to restate prior periods only if it is possible to do so without the use of hindsight. If the entity does not restate prior periods, it shall recognise any difference between the previous carrying amount and the carrying amount at the date of initial application of these amendments in the opening retained earnings (or other component of equity, as appropriate) at the beginning of that reporting period. 7.2.52If a contract referencing nature-dependent electricity (as described in paragraph 2.3A) would be outside the scope of IFRS 9 as a result of applying the requirements in paragraphs B2.7-B2.8, an entity is permitted, at the date of initial application, to irrevocably designate this contract as measured at fair value through profit or loss in accordance with paragraph 2.5. 7.2.53An entity shall apply paragraphs 6.10.1–6.10.2 prospectively to new hedging relationships designated on or after the date of initial application. An entity is permitted, at the date of initial application, to discontinue a hedging relationship in which a contract referencing nature-dependent electricity (as described in paragraph 2.3A) has been designated as the hedging instrument, if the same hedging instrument is designated in a new hedging relationship in accordance with paragraphs 6.10.1-6.10.2.
Appendix B
Application guidance
This appendix is an integral part of the Standard.
Scope (Chapter 2)
Contracts to buy nature-dependent electricity
B2.7Some contracts referencing nature-dependent electricity (as described in paragraph 2.3A) require an entity to buy and take delivery of the electricity when it is generated. These contractual features expose the entity to the risk that it would be required to buy electricity during a delivery interval in which the entity cannot use the electricity. The entity might also have no practical ability to avoid making sales of unused electricity because the design and operation of the electricity market in which the electricity is transacted under the contract require any amounts of unused electricity to be sold within a specified time. When an entity applies the requirements in paragraph 2.4, such sales are not necessarily inconsistent with the contract being held in accordance with the entity’s expected usage requirements. An entity entered into and continues to hold such a contract in accordance with its expected electricity usage requirements if the entity has been, and expects to be, a net purchaser of electricity for the contract period. An entity is a net purchaser of electricity if it buys sufficient electricity to offset the sales of any unused electricity in the same market in which it sold the electricity. B2.8In determining whether an entity is a net purchaser of electricity, the entity shall consider reasonable and supportable information (that is available without undue cost or effort) about its past, current and expected future electricity transactions over a reasonable amount of time. The entity identifies ‘a reasonable amount of time’ by considering the variability in the amount of electricity expected to be generated due to the seasonal cycle of the natural conditions and the variability in the entity’s demand for electricity due to its operating cycle. In determining whether the entity has been a net purchaser, ‘a reasonable amount of time’ shall not exceed 12 months.
Amendments to IFRS 7 Financial Instruments: Disclosures
Paragraphs 5B–5D, 30A–30C, 44OO–44PP and the subheading before paragraph 30A are added. Paragraph 5 is included for ease of reference. New text is underlined.
Scope
5This IFRS applies to contracts to buy or sell a non-financial item that are within the scope of IFRS 9.
5BParagraph 30A applies only to contracts to buy nature-dependent electricity that satisfy the requirements in paragraph 2.3A of IFRS 9 and are outside the scope of that Standard in accordance with paragraphs B2.7–B2.8 of IFRS 9. 5CParagraph 30B applies only to contracts that satisfy the requirements in paragraph 2.3A of IFRS 9 and have been designated in a cash flow hedging relationship in accordance with paragraph 6.10.1 of IFRS 9. 5DParagraph 30C applies only to contracts that satisfy the requirements in paragraph 2.3A of IFRS 9 and have been entered into with regards to an entity’s electricity purchases. These contracts comprise those:
- within the scope of IFRS 9; and
- outside the scope of IFRS 9 in accordance with paragraph 2.4 of that Standard, including those excluded in accordance with paragraphs B2.7–B2.8 of that Standard.
Significance of financial instruments for financial position and performance
Other disclosures
Contracts referencing nature-dependent electricity
30AAn entity shall disclose in a single note in its financial statements information about contracts that meet the criteria set out in paragraph 5B. In particular, the entity shall disclose information that enables users of its financial statements to understand the effects these contracts have on the amount, timing and uncertainty of its future cashflows and on its financial performance. To meet these objectives, an entity shall disclose:
- information about contractual features that expose the entity to:
- variability in the underlying amount of electricity (see paragraph 2.3A of IFRS 9); and
- the risk that the entity would be required to buy electricity during a delivery interval in which the entity cannot use the electricity (see paragraph B2.7 of IFRS 9).
- information about unrecognised commitments arising from such contracts as at the reporting date, including:
- the estimated future cash flows from buying electricity under these contracts. The entity shall apply its judgement when identifying the appropriate time bands within which to disclose the estimated future cash flows.
- qualitative information about how the entity assesses whether a contract might become onerous (see IAS 37 Provisions, Contingent Liabilities and Contingent Assets), including the assumptions the entity uses in making this assessment.
- qualitative and quantitative information about effects on the entity’s financial performance for the reporting period. The disclosure is based on the information that is applicable to the reporting period that the entity used to assess whether it has been a net purchaser of electricity (see paragraph B2.8 of IFRS 9). An entity shall disclose information for the reporting period about:
- the costs arising from purchases of electricity made under the contracts, disclosing separately how much of the purchased electricity was unused at the time of delivery;
- the proceeds arising from sales of unused electricity; and
- the costs arising from purchases of electricity made to offset sales of unused electricity.
30BAn entity shall disaggregate, for its contracts that meet the criteria set out in paragraph 5C, the information the entity discloses, by risk category, about the terms and conditions of hedging instruments in accordance with paragraph 23A. 30CIf an entity discloses information about other contracts referencing nature-dependent electricity as described in paragraph 5D (including those contracts described in paragraph 30B) in other notes in its financial statements, the entity shall include cross-references to those notes in the single note required by paragraph 30A.
Effective date and transition
44OOContracts Referencing Nature-dependent Electricity, issued in December 2024, which also amended IFRS 9, added paragraphs 5B–5D, 30A–30C and 44PP. An entity shall apply these paragraphs when it applies the amendments to IFRS 9. If an entity does not restate comparative information when it first applies the amendments to IFRS 9 in accordance with paragraph 7.2.51 of that Standard, the entity shall not provide comparative information for the disclosures required by paragraphs 30A–30C. Similarly, an entity that applies IFRS 19 Subsidiaries without Public Accountability: Disclosures shall not provide comparative information for the disclosures required by paragraphs 64A–64C. 44PPIn the reporting period in which an entity first applies Contracts Referencing Nature-dependent Electricity, the entity need not disclose the quantitative information that would otherwise be required by paragraph 28(f) of IAS 8. Similarly, an entity that applies IFRS 19 need not disclose the quantitative information that would otherwise be required by paragraph 178(f) of IFRS 19.
Footnotes
-
Accessible here: The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021 ↩↩↩
-
Accessible here: The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 ↩↩↩↩
-
In this Adoption Statement the term "Standard" is used to refer to amendments to international accounting standards, in line with the definition of 'international accounting standards' used in the Regulations, which includes 'subsequent amendments to international accounting standards'. ↩↩↩
-
In accordance with the Due Process Handbook. ↩↩
-
In accordance with the Due Process Handbook. ↩↩
-
In accordance with the Due Process Handbook. ↩
-
In the Framework for the Preparation and Presentation of Financial Statements adopted by the IASB, the users of financial reports include present and potential investors, employees, lenders, suppliers and other trade creditors, customers, governments and their agencies and the public. While the UK has not adopted this Framework, in this document 'users' is taken to have a similar meaning. ↩
-
Paragraph 15 of IAS 1 Presentation of Financial Statements. ↩