8 Statement of Cash Flows and Related Matters
OFFICIAL - PUBLIC 15 July 2025 Agenda Paper 8
Executive Summary
Project Stage
| IASB | Research / Pipeline | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Scope
Moderate
Purpose of the paper
At the 28 March 2025 UKEB meeting, the Board agreed that further UKEB research be undertaken and presented to the Board in July
- The Project Initiation Plan (PIP), approved at the November 2024 Board meeting, was updated to reflect the additional research, and the updated PIP was approved at the 22 May 2025 UKEB meeting. The research included:
- Alternative presentation formats and disclosures for the statement of cash flows – based on previous research conducted, incorporating the key suggestions made by users and preparers. Mocked-up presentation formats, and examples of voluntary disclosures provided by some UK listed companies, tested with primary users and preparers. Potential disclosures (on the face of the statement of cash flows or in the notes to the financial statements) that might be more useful would then be used to encourage further discussion about the ways forward for this project and provide evidence to the IASB.
- Interconnectivity of IFRS Standards / Cohesiveness of Financial Statements i. mapping the links between the statement of cash flows and requirements in other IFRS Standards to highlight the existing connections, (or refine the requirements to strengthen the connections). This could allow the IASB to make minor changes that bring significant incremental value to users. ii. Connectivity between the statement of cash flows and other general purposes financial reports would be investigated, subject to resource availability.
Summary of the Issue
The research paper concludes that UK users interviewed consider that the IASB should undertake targeted improvements to the statement of cash flows to address their priority concerns. Specific opportunities identified by stakeholders to enhance the statement of cash flows that the IASB might consider when progressing with the project include requiring companies to provide:
a) A net debt reconciliation. b) More complete and transparent information on key areas, to allow users to undertake their own analysis of a company’s working capital management and ability to generate future cash flows. Specifically: i. movements in working capital, including factoring. ii. exceptional and adjusting items (including both the amounts reported in the income statement and the statement of cash flows). iii. cash flow-related management defined performance measures (MPMs), such as free cash flow, supported by IFRS-defined sub-totals in the statement of cash flows. iv. non-cash information, including both non-cash transactions (such as share-based payments) and non-cash items (such as foreign exchange and fair value movements).
One possible way to strengthen both the connection between IFRS Accounting Standards and enhance the cohesiveness between the financial statements is for the IASB to consider introducing an “information principle”. This would require companies to disclose information that would enable the user to link information disclosed in each of the primary financial statements.
Decisions for the Board
1The Board is asked for general comments and observations on the UKEB research findings (Appendix A).
2Do Board members agree, subject to comments received in this meeting, that a final version of the research findings should be published on the UKEB website?
3The Board is asked for general comments on the IASB update (Appendix B).
Recommendation
The Secretariat recommends that a final version of the research findings should be published on the UKEB website.
Appendices
Appendix A UKEB research paper 4 – Statement of Cash Flows and Related Matters: UK users' views on ways forward Appendix B IASB update
Background: Statement of Cash Flows and Related Matters
The IASB added a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation (published March 2021).
In the Feedback Statement to the Request for Information (published July 2022) most respondents recommended the addition of a project on cash flows to the IASB’s workplan, rating it as high priority.
The IASB staff have performed initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB’s decision on the scope of the project and will also address possible ways of improving the perceived deficiencies. The IASB discussed the initial research outcomes in March 2025, and in May 2025 discussed the topics to include in the project plan and a draft timeline for work on the project (see Appendix B). The IASB will decide on the project direction in Q4 2025.
A UKEB project on the statement of cash flows and related matters supports meeting the UKEB’s responsibilities regarding thought leadership in accordance with the UKEB Terms of Reference. It will also help the Board to deliver the UKEB’s 2024-25 Regulatory Strategy (page 8) aim, to influence the IASB early in its development cycle, by providing timely and effective input.
The UKEB research has focused on gathering primary evidence on the improvements UK investors and creditors suggest for the statement of cash flows, and UK preparer views on those possible improvements. This has provided a foundation for the UKEB to propose potential solutions for the problems already identified by the IASB as well as any other issues identified through UKEB outreach.
- Executive Summary
- Background: Statement of Cash Flows and Related Matters
- Appendix A: Statement of Cash Flows and Related Matters: UK users' views on ways forward
- 15 July 2025 Agenda paper 8: Appendix A
- Movements in working capital
- Factoring receivables and payables
- Exceptional and adjusting items
- Other cash flow measures – sub-totals and management performance measures (MPMs)
- Cash flows from discontinuing operating activities
- Non-cash information
- Information principle
- Cross-referencing
- Other areas of cash flow reporting
- Disclosures encouraged by IAS 7
- Concluding observations
- Annex B.01: Four alternative formats explored in the research
- Annex B.02: Alternative format 1: Net Debt Basis
- Annex B.03: Alternative format 2: Realigned Operating Activities
- Annex B.04: Alternative format 3: Hybrid P&L and Cash Flow Statement
- Annex B.05: Alternative format 4: Receipts and uses of cash
- Annex B.05: Alternative format 4: Receipts and uses of cash
- Annex B.06: Supplementary disclosure examples
- Appendix B: Statement of Cash Flows and Related Matters: IASB update
Appendix A: Statement of Cash Flows and Related Matters: UK users' views on ways forward
Executive Summary
A1.In March 2025 the UKEB decided to undertake research to understand how cash flow information could be improved by considering:
- alternative formats for the Statement of Cash Flows; and
- potential supplementary disclosures.
A2.This research has highlighted supplementary disclosures that users believe, if mandated by the IASB, would provide relevant information that could enhance the usefulness of the statement of cash flows and the financial statements more generally.
A3.Research into potential alternative formats for the statement of cash flows, including outreach with UK stakeholders showed that reformatting of the statement of cash flows would not achieve the intended outcome of the project to provide users with more useful information.
A4.By contrast, the highest priority for most UK users is a mandatory requirement to provide a net debt reconciliation, incorporating information about changes in liabilities from financing activities (currently required in IAS 7). Users also highlighted the need for information in such a reconciliation to clearly link to the information reported in the statement of cash flows.
A5.Another priority for UK users interviewed is to have access to supplementary disclosures to provide more complete and transparent information on key areas, to complete their own analysis of a company’s working capital management and ability to generate future cash flows. Users are less concerned with classification of cash flows or what constitute cash and cash equivalents.
A6.Testing with primary users and preparers, examples of voluntary disclosures provided by some UK listed companies, and models of further enhanced disclosures, that the IASB could consider mandating, include:
- movements in working capital, including factoring.
- exceptional and adjusting items (including both the amounts reported in the income statement and the statement of cash flows).
- cash flow-related management defined performance measures (MPMs), such as free cash flow, supported by IFRS-defined sub-totals in the statement of cash flows.
- non-cash information, including both non-cash transactions (such as share-based payments) and non-cash items (such as foreign exchange and fair value movements).
A7.With regard to improving the information disclosed in the notes to the financial statements, mapping the links between the requirements in IAS 7 Statement of Cash Flows and the requirements in other IFRS Standards has highlighted some existing connections, but also opportunities to refine the requirements to strengthen the connections.
A8.One possible way to strengthen both the connection between IFRS Accounting Standards and enhance the cohesiveness between the financial statements is for the IASB to consider introducing an "information principle". This would require companies to disclose information that would enable the user to link information disclosed in each of the primary financial statements. An information principle would potentially lead to better disclosures and improve transparency on how the information disclosed in each note relates to the other notes (for example, share-based payments, derivatives, leases, capital expenditure and the impact of mergers and acquisitions (M&A)).
A9.This research paper also highlights areas where users suggested that disclosure could be improved, such as requiring a company to disclose restricted cash, when providing a breakdown of the components of cash and cash equivalents.
A10.The net debt reconciliation and other potential supplementary disclosures that might be more useful to users, highlighted in this paper, will be used to encourage further discussion about the ways forward for this project and provide relevant evidence to the IASB.
A11.Further research and field-testing are required to ensure that any improvements to disclosure requirements suggested in this research paper balance the costs of providing the additional information and the related benefits.
Introduction
Purpose and objective of research paper
A12.At its March 2025 meeting, the Board agreed to undertake further research1 covering two areas of cash flow reporting:
- Alternative formats for the statement of cash flows that the IASB could explore2, taking into account known limitations of the current format and suggestions received from UK users and preparers during earlier phases of the UKEB research.
- Potential supplementary disclosures to improve cash flow-related requirements, mapping the links between the statement of cash flows and requirements in other IFRS Accounting Standards, to: i. enhance the interconnectivity of existing cash flow-related reporting requirements contained in IFRS Accounting Standards; and ii. introduce overarching principles aimed at enhancing cohesiveness in financial statement information and to enhancing by requiring links between amounts in the statement of cash flows to other primary statements.
A13.This paper also explores:
- Other areas of cash flow reporting that UK preparer stakeholders considered a priority (such as cash and cash equivalents); and
- Disclosures encouraged by IAS 7 and whether the IASB should either remove the requirements, make the disclosures mandatory, or find a compromise.
Research process and methodology
A14.To support later interviews with users of financial statements, preliminary proposals were developed after reviewing:
- Publicly available academic literature.
- UKEB Research Paper 1. Statement of Cash Flows: Background and Key Issues (December 2024) – based on desk-based research, exploring perceived issues with the statement of cash flows.
- UKEB Research Paper 2. Statement of Cash Flows: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed Companies (February 2025) – based on a review of current reporting practices among UK listed companies. This research highlighted an opportunity to leverage the existing UK practice for supplementary disclosures that could enhance statutory reporting of cash flows and related matters. Examples of such voluntary cash flow disclosures were discussed during some of the later interviews conducted with users and preparers (between December 2024 and March 2025 to infirm the third UKEB research paper) to determine what voluntary disclosures are most useful, and to understand how the information is used.
- UKEB Research Paper 3. Statement of Cash Flows: UK User and Preparer Perspectives (March 2025) – based on interviews with investors and preparers to better understand their perspectives on the current and potential future reporting requirements.
- A user survey3 conducted by the UKEB in March 2025 to gather wider UK user views, which also provided feedback on UK listed company voluntary disclosures observed by the UKEB in its second research paper, and other disclosures suggested by UK stakeholders during the outreach meetings to inform its third research paper.
Alternative formats explored in the research
A15.Four alternative formats for presenting the statement of cash flows were developed for consultation. These formats range from minor modifications to more fundamental redesigns of the existing IAS 7 format:
- Alternative 1: Net Debt Basis
- Alternative 2: Realigned Operating Activities
- Alternative 3: Hybrid P&L and Cash Flow Statement
- Alternative 4: Receipts and Uses of Cash
A16.Each of the alternatives aimed to address the priorities, issues and concerns identified during earlier research. Annex B.01 provides an overview of each alternative, highlighting their main advantages and limitations. Annex B.02 to B.05 provide a visual illustration of the four formats.
A17.To evaluate and refine each of the alternatives, feedback was initially sought from the UKEB Investor Advisory Group (IAG)4.
A18.Alternative 1: Net Debt Basis received the most positive feedback. IAG members suggested that investors place substantial value on disclosures around companies’ net debt. It aligns with how most treasury functions manage liquidity and is seen as a meaningful indicator of financial position. However, some IAG members preferred this disclosure to be introduced as a note to the financial statements rather than a primary statement. Utilising a note would preserve cohesiveness while avoid disrupting the existing structure for the statement of cash flows.
A19.Alternative 2: Realigned Operating Activities received limited support from IAG members. Although conceptually logical (because it classifies asset-related cash flows in operating activities rather than in investing activities) users and preparers felt it primarily reorganises information that is already clearly identifiable on the face of the statement of cash flows currently prescribed by IAS 7.
A20.Alternative 3: Hybrid P&L and Cash Flow Statement received some support from IAG members, due to its potential to promote cohesiveness by linking a company’s profit to cash on a line-by-line basis. However, it was viewed as overly detailed and potentially difficult to follow. Concerns were also raised about the practical burden of preparing this statement.
A21.Alternative 4: Receipts and Uses of Cash was not supported by IAG members, because it largely rearranges existing IAS 7 information, delivering limited incremental value. IAG members felt that the IASB’s efforts should focus on supporting users’ needs by ensuring that relevant information is transparently available within financial statements and is appropriately disaggregated and cohesively presented.
A22.Overall, feedback received from the IAG members indicated that, while elements of the four alternatives may be useful, targeted enhancements of cash flow disclosures, rather than a structural overhaul of the IAS 7 format, would be the most appropriate approach to the IASB’s project.
A23.Feedback from the IAG was used to refine the proposals presented to the UKEB Preparer Advisory Group (PAG)5, which consisted of the two alternative presentations formats preferred by the IAG members (Alternative 1 Net Debt basis and Alternative 3 Hybrid P&L and cash Flows Statement), and other possible supplementary disclosures.
A24.PAG members were asked whether these disclosures could be reasonably provided, and what, if any, challenges preparers might face in providing them.
A25.Most PAG members supported requiring a company to provide a net debt reconciliation that reconciles to the statement of cash flows, given that most UK preparers present a net debt reconciliation as an extension to the current disclosure requirement for the change in financing liabilities.
A26.Most PAG members were not supportive of requiring a company to provide a reconciliation between the income statement on a line-by-line basis to the statement of cash flows.
A27.Regarding potential supplementary disclosures, on the whole PAG members were supportive of:
- Movements in working capital.
- Sub-totals – requiring companies to reconcile cash flow related management performance measures (MPMs) to IASB defined subtotals on the statement of cash flows.
- Single note disclosure for exceptional items.
A28.There were mixed views around a single note disclosure for non-cash transactions with concerns that that it would lead to duplication of information which would further lengthen the annual report.
A29.Incorporating the feedback from IAG and PAG two alternative presentations along with a range of additional disclosures were then selected to field-test with 10 users, through semi-structured interviews in late June 2025. The table below summarises the profile of the users that participated in the interviews.
| 10 Users interviewed by category | ||
|---|---|---|
| Institutional Investors | 3 | 30% |
| Professional Body/Representative group members | 3 | 30% |
| Analysts / Researchers (Equity, Fixed Income) | 2 | 20% |
| Credit Rating Agencies | 1 | 10% |
| Creditors/ Lenders | 1 | 10% |
| TOTAL | 10 | 100% |
Findings
A30.The interviews identified the following disclosures as a priority for users:
- Net debt reconciliation.
- Movements in working capital (operating receivables and payables), reconciled to the statement of cash flows.
- Exceptional and adjusting items – cash flow impact and income statement impact.
- Other cash flow measures – sub-totals and management performance measures – more transparent disclosure leveraging the IASB’s work done in developing IFRS 18 Presentation and Disclosure in Financial Statements, by: i. introducing IASB defined sub-totals on the statement of cash flows, and requiring cash flow related MPMs to be reconciled to the appropriate IASB defined sub-total; and ii. applying the disaggregation principles set out in IFRS 18 that apply to all primary financial statements, including the statement of cash flows.
- Non-cash information covering both non-cash movements (e.g. foreign exchange and fair value adjustments) and non-cash transactions with a similar economic impact (e.g. stock options paid to employees).
- Information principle to assist cohesiveness between primary financial statements.
A31.Utilising voluntary disclosures provided by UK listed companies, and feedback from interviews with UK stakeholders, the following sections illustrate disclosures that the IASB could consider requiring companies to provide.
Net debt reconciliation
A32.A supplementary net debt reconciliation emerged as the clear priority for both users and preparers. It is regarded as providing relevant information without disrupting the current IAS 7 format. Users valued the way it makes apparent various cash and non-cash movements in net debt.
A33.The interviews supported previous research that found such disclosures are important to investors both for equity valuation purposes and to investigate perceived problems with a company’s debt or liquidity. Net debt disclosures give investors the confidence that they have understood issues related to the development of financial obligations that must be met, and issues relating to the capital structure and the enterprise value attributable to net debt versus shares6.
A34.IFRS Accounting Standards make no reference to the term ‘net debt’ and have no requirement to provide a net debt reconciliation. However, a UKEB review of a sample of 30 UK listed annual reports found that most companies disclosed a net debt reconciliation7.
A35.Following discussions at its May 2025 meeting, the IASB indicated that the definition of net debt is a topic it does not plan to explore further. However, UK stakeholder feedback noted above, and the prevalence of the measure in UK reporting, provides evidence for the IASB to consider introducing a mandatory requirement for companies to include a net debt reconciliation in their financial statements, building on the existing disclosure requirements in IAS 7 paragraphs 44A to 44E8.
A36.When companies do not provide a net debt reconciliation analysts generally attempt to create their own. Introducing a requirement for companies to provide a net debt reconciliation would assist investors in understanding management’s view of net debt and provide transparent information that reconciles to other areas of the financial statements.
A37.During interviews UK users commented that any suggested net debt disclosure should:
- Clearly show the components that companies include in their definition of net debt, which might include other liquid investments that do not meet the definition of cash and cash equivalents. Components would need to be shown in the reconciliation with sufficient disaggregation to enable users to link the movement to the corresponding balance sheet line item.
- Require the effects of M&A activity on the components of net debt be clearly reconcilable to the business combinations note.
- Show fair value changes and the retranslation of foreign currency denominated amounts.
- Show separately cash movements and non-cash items, and how they relate to other aspects of the financial statements, such as the income statement and statement of financial position.
- Make clear the nature of any derivatives included in net debt and whether the net debt includes accrued interest.
- Clearly explain any fair value hedge adjustments to reported net debt, or debt-related derivatives not included in the company’s definition of net debt.
- Separately list movements that are different in nature, such as significant currency movements and fair value changes. Whilst it is considered reasonable for companies to show a category of “other” movements, there should be a requirement for companies to provide confirmation that there are no material offsetting amounts included in that category, and to describe the nature of items included.
A38.An illustrative example of the possible net debt reconciliation is shown on the next page. Users interviewed had concerns about the transparency of disclosures on factoring and reverse factoring arrangements, and so a separate column for any liabilities arising from factoring and reverse factoring arrangements is included. As suggested within the example, a reconciliation would be enhanced by cross-referencing amounts to relevant disclosures in other sections of the financial statements. This would address stakeholder expectations, identified during this research and earlier phases of the project (see later section on cross-referencing).
| Gross debt | |||
|---|---|---|---|
| Cash and cash equivalents | Other liquid investments | Bonds | |
| 2024 | 2024 | 2024 | |
| £m | £m | £m | |
| Balance at start of year | 0.0 | 0.0 | 0.0 |
| Cash flows from operating activities | 0.0 | 0.0 | 0.0 |
| Cash flows from investing activities [including cash impact of M&A] (Note 1) | 0.0 | 0.0 | 0.0 |
| Cash flows from financing activities: | |||
| Cash receipts – borrowings and derivatives | 0.0 | 0.0 | 0.0 |
| Cash payments – borrowings and derivatives | 0.0 | 0.0 | 0.0 |
| Interest paid | 0.0 | 0.0 | 0.0 |
| Dividends paid | 0.0 | 0.0 | 0.0 |
| ESOPs – purchase of shares | 0.0 | 0.0 | 0.0 |
| Total cash flows from financing activities | 0.0 | 0.0 | 0.0 |
| Cash movements | 0.0 | 0.0 | 0.0 |
| Uplift on index-linked debt | 0.0 | 0.0 | 0.0 |
| Non-cash impact of M&A (Note 1) | 0.0 | 0.0 | 0.0 |
| Changes in fair value | 0.0 | 0.0 | 0.0 |
| Foreign exchange | 0.0 | 0.0 | 0.0 |
| Other adjustments (details will be required) | 0.0 | 0.0 | 0.0 |
| Reclassifications (details will be required) | 0.0 | 0.0 | 0.0 |
| Non-cash movements | 0.0 | 0.0 | 0.0 |
| Balance at end of year | 0.0 | 0.0 | 0.0 |
| Note 1 | Note 1 | Note 1 | |
Notes:
- Cross-references to relevant sections of the financial statements would ensure cohesiveness. For example, the cash flow column would be expected to cross-refer to the statement of cash flows; the opening and closing balances would be expected to cross-refer to the statement of financial position; and the M&A movements would be expected to cross-refer to the acquisitions and disposals disclosures presented in accordance with IFRS 3.B64(i) and IAS 40(d).
- Separate inclusion of movements relating to factoring and supply chain financing would meet user demands for greater transparency around such arrangements. This would build on the disclosure objectives in IFRS 7 and the disclosure requirements in IAS 7.44A to 44E and IAS 7.44F to 44H.
15 July 2025 Agenda paper 8: Appendix A
| Cash and liquid cash equivalents | Other liquid investments | Gross debt | Total liabilities from financing activities | Net debt | |||||
|---|---|---|---|---|---|---|---|---|---|
| 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | |
| Balance at start of year | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Cash flows from operating activities | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Cash flows from investing activities [including cash impact of M&A] (Note 1) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Cash flows from financing activities: | |||||||||
| - Cash receipts – borrowings and derivatives | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| - Cash payments – borrowings and derivatives | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| - Interest paid | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| - Dividends paid | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| - ESOPs – purchase of shares | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Total cash flows from financing activities | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Cash movements | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Uplift on index-linked debt | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Non-cash impact of M&A (Note 1) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Changes in fair value | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Foreign exchange | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Other adjustments (details will be required) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Reclassifications (details will be required) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Non-cash movements | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Balance at end of year | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Note 1 | Note 1 | Note 1 | Note 1 | Note 1 | Note 1 | Note 2 |
Notes:
1Cross-references to relevant sections of the financial statements would ensure cohesiveness. For example, the cash flow column would be expected to cross-refer to the statement of cash flows; the opening and closing balances would be expected to cross-refer to the statement of financial position; and the M&A movements would be expected to cross-refer to the acquisitions and disposals disclosures presented in accordance with IFRS 3.B64(i) and IAS 40(d).
2Separate inclusion of movements relating to factoring and supply chain financing would meet user demands for greater transparency around such arrangements. This would build on the disclosure objectives in IFRS 7 and the disclosure requirements in IAS 7.44A to 44E and IAS 7.44F to 44H.
Movements in working capital
A39Change in working capital is a cash flow item that reflects the actual cash used to operate the business. It will help determine where a company is in its working capital cycle and can help explain how a company uses its assets to generate growth, which can allow investors to predict changes in company value[^9].
A40IAS 7 does not specifically mention the term 'working capital', although paragraph 20 of IAS 7 states that under the indirect method net cash flow from operating activities is adjusted for changes in inventories, receivables, and payables. The Standard does not include additional presentation or disclosure requirements related to these movements, i.e. the level of disaggregation required on the face of the statement of cash flows is not prescribed.
A41The UKEB analysis of annual reports for 30 UK listed companies observed that those companies often present these items in the 'operating cash flows' section of the statements of cash flows as single line 'changes in working capital'. It was also observed that some companies include changes in other current assets and current liabilities within 'changes in working capital', leading to differing components and levels of disaggregation in the statement of cash flows.
A42As noted in the first research paper, the FRC's 2020 thematic report on cash flow and liquidity disclosures raised concerns about inconsistencies between working capital movements and statement of financial position movements[^10]. This finding was consistent with feedback from users during the interviews. Those users highlighted the importance of reconciling working capital movements presented in the statement of cash flows to changes in the balance sheet, especially when there are significant unexplained differences or there is insufficient disaggregation to link the disclosures.
A43According to that FRC 2020 thematic, examples of better disclosures include:
- a reconciliation to explain the cash flow impact of working capital movements, where changes in cash flows from working capital are inconsistent with movements in the statement of financial position;
- a logical ordering of items presented, for example, grouping similar items together; and
- cross-references to relevant notes.
A44As noted in the UKEB third research paper[^11], a few users said they need appropriate disclosure and disaggregation of what comprises a company's working capital and its movements. Such information may be transparent when the movement in working capital is disaggregated on the face of the statement of cash flows (or in a related ‘operating cash flows' analysis note) and cross-referenced to the related notes showing movements in the respective assets and liabilities.
A45The current diversity in reporting practice and inability of users to reconcile the movement shown on the face of the statement of cash flows with the movement in the respective asset and liabilities, reinforces that the cohesiveness between the statement of cash flows and the statement of financial position is important and could be improved.
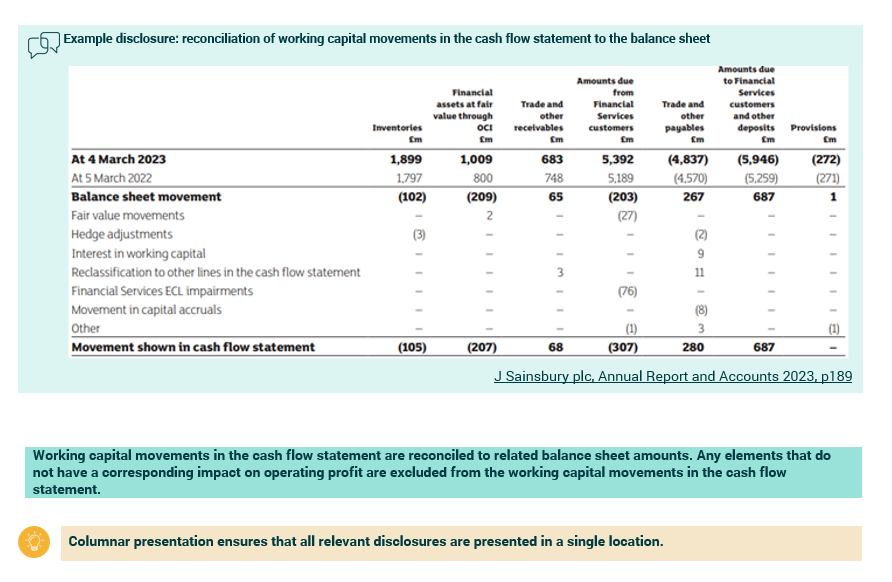
A46As noted in paragraph 47 of the second research paper, some UK listed companies voluntarily provide reconciliations to clarify how working capital movements in the statement of cash flows relate to amounts in the statement of financial position (see two examples below)[^12]. These examples were discussed during UKEB interviews with users.
J Sainsbury plc, Annual Report and Accounts 2023, p189
Working capital movements in the cash flow statement are reconciled to related balance sheet amounts. Any elements that do not have a corresponding impact on operating profit are excluded from the working capital movements in the cash flow statement.
Columnar presentation ensures that all relevant disclosures are presented in a single location.
A47The second example below (Vertu Motors plc, Annual Report 2024, page 139) shows the impact of business combinations in the year on the movement of working capital shown in the consolidated statement of cash flows:
Vertu Motors plc, Annual Report 2024, page 139
34. Cash flow from movement in working capital
The following table reconciles the movement in balance sheet headings to the movement in working capital as presented in the consolidated cash flow statement.
| 2024 | Current trade and other receivables (Note 23) £'000 | Trade and other payables £'000 | Total working capital movement £'000 | |
|---|---|---|---|---|
| Inventories (Note 21) £'000 | ||||
| Trade and other payables (Note 25) | (869,931) | |||
| Contract liabilities (Note 29) | (23,475) | |||
| At 29 February 2024 | 761,996 | 93,702 | (893,406) | |
| At 28 February 2023 | 674,380 | 85,827 | (784,175) | |
| Balance sheet movement | (87,616) | (7,875) | 109,231 | 15,187 |
| Acquisitions (Note 17) | 4,199 | 281 | (2,661) | 129 |
| Deferred consideration (Note 17) | (250) | 1,049 | ||
| Disposals | (104) | (27) | 9 | 61 |
| Movement excluding business combinations | (83,521) | (7,621) | 106,329 | 282 |
| Pension related balances | 16,708 | |||
| Increase in capital creditor | ||||
| Increase in interest accrual | ||||
| Derivative financial instruments (Note 27) | ||||
| Movement as shown in Consolidated Cash Flow Statement |
A48Users suggested entity-specific disclosure is preferable to the IASB defining working capital. This approach provides a management perspective on what assets and liabilities a company considers to be the components of its working capital and how such working capital is managed. Most users also suggested that separate disclosure of factoring payables and receivables would be useful.
A49Most users suggested that it would be useful for the IASB to require specific line items such as such as trade and other payables, trade and other receivables and inventories (if relevant). However, a company should also be allowed to include other entity specific items. When a company has not included those minimum expected items, the reasons should be explained.
A50Most users suggested that they need to be able to understand which components, shown on the statement of financial position, the company is managing as part of its working capital management. Therefore, the disaggregation shown in the working capital movement disclosure should be sufficient to enable users to link that information to the statement of financial position and related notes.
A51Most users suggested they need to be able to assess the impact of specific types of changes on each category of working capital, where material, such as:
- M&A activity
- disposals
- non-cash transactions; and
- non-cash items, such as foreign exchange and fair value movements.
This level of disaggregation is similar to the level of disaggregation suggested in IAS 7 for the disclosure of changes in liabilities arising from financing activities[^13].
A52Some users suggested that segmental information should be required to be disclosed where management monitor the working capital of different business segments separately, and where there are different business models in those segments that can lead to significantly different absorption of working capital.
A53It should be noted that PAG members expressed some concerns regarding providing a working capital movement note, specifically:
- providing support for reconciling items due to unavailability of information in accounting systems;
- commercial sensitivity associated with disclosing some movements;
- challenges by auditors where companies provide commentary on immaterial reconciling items grouped as "other"; and
- increase in audit costs.
A54In mitigation, users interviewed acknowledged that only material information should be disclosed. They also agreed it would be sufficient for companies to use a category for “other” items, as long as companies confirm there are no material offsetting amounts included in the amount and describe the nature of items included.
A55The IASB could prescribe the minimum categories expected in the working capital movement note. A mandatory single line for working capital movements on the face of the statement of cash flows, cross-referenced to a mandatory working capital movements note, would suffice (also see later section on IFRS defined sub-totals).
Factoring receivables and payables
A56As noted above, better disclose of the impact of factoring receivables and payables is important to users.
A57Factoring can help a company maintain an optimal level of working capital by converting invoices into cash, ensuring it has enough funds to cover expenses, pay suppliers, and invest in growth. By understanding how a company uses factoring, investors can gauge its ability to manage its short-term financial needs.
A58Investors analyse the creditworthiness of a company's customers and the terms of its factoring agreement to assess the potential risks involved.
A59IFRS 7 Financial Instruments: Disclosures requires entities to disclose the nature and extent of risks arising from financial instruments. This includes qualitative and quantitative information about credit risk, liquidity risk, and market risk, with a focus on how the entity manages these risks.
A60There is no specific requirement to disclose cash flow information in relation to factoring arrangements, in either IFRS 7 or IAS 7.
A61Users interviewed suggested that to provide transparency about factoring and reverse factoring arrangements, working capital disclosures could be further disaggregated to separately identify components of balances subject to these arrangements that have not met IFRS 9 Financial Instruments derecognition requirements. Please also refer to the net debt reconciliation section above for proposals to improve transparency of liabilities arising from factoring and reverse factoring arrangements.
Exceptional and adjusting items
A62IFRS Accounting Standards, including IAS 7, do not explicitly refer to exceptional or other adjusting items. However, they are frequently included in the statement of profit or loss to communicate information intended to help users better understand the financial statements.
A63Users interviewed observed that understanding the cash impact of non-recurring items is important to them to assess a company's financial health and in making more informed investment decisions. Understanding the nature of a non-recurring item and its cash flow impact was also seen as important for financial valuation.
A64Those users confirmed that, generally, analysts adjust for non-recurring items, as these one-time events can significantly impact a company's reported performance. If not adequately disclosed, this can lead to difficulty in accurately assessing a company's underlying operating performance and future potential.
A65Most UK listed companies use the indirect method for disclosing operating cash flows. If the starting point includes exceptional items, the cash impact of those exceptional items is not transparent, unless the full profit or loss impact is added back and then the cash impact separately disclosed, or otherwise explicitly disclosed in supporting commentary[^14].
A66Per paragraph 36 of the second research paper, the Basis for Conclusions to IFRS 18 Presentation and Disclosure in Financial Statements paragraph BC93 notes that "an entity might disclose information about an aspect of its operating performance by presenting a management-defined performance measure of operating profit excluding expenses it regards as non-recurring or unusual". No such requirement is set out in IFRS 18 in relation to 'cash flows from operating activities'.
A67As noted in paragraph 63 of the second research paper, despite a UK Regulator (the FRC) specifically identifying information on the cash impact of exceptional or other adjusting items as an area in which they would like to see better disclosure, such information is not widely provided by companies.
A68Disclosing the cash impact of exceptional items ensures consistency between cash flow disclosures and the statement of profit or loss disclosure requirements.
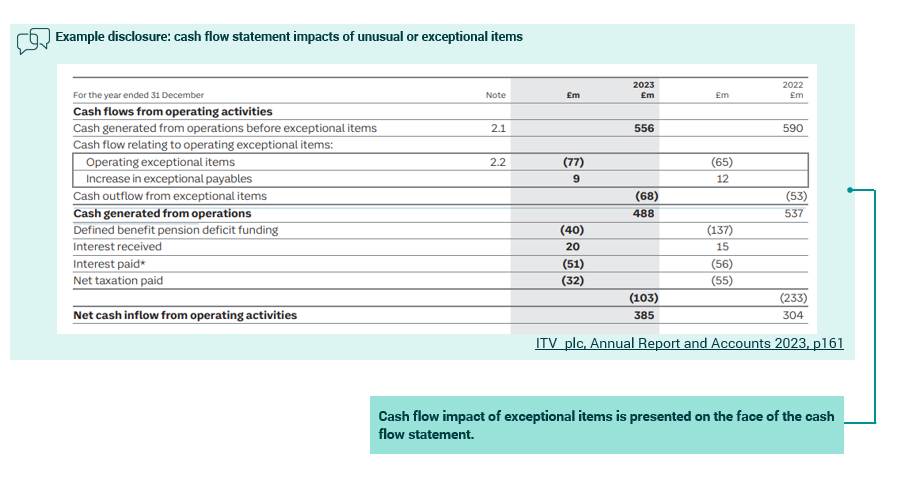
A69Paragraphs 38–40 of the second UKEB research paper, set out two examples of voluntary disclosures of exceptional items, one on the face of the statement of cash flows, as follows:
ITV plc, Annual Report and Accounts 2023, p161
Cash flow impact of exceptional items is presented on the face of the cash flow statement.
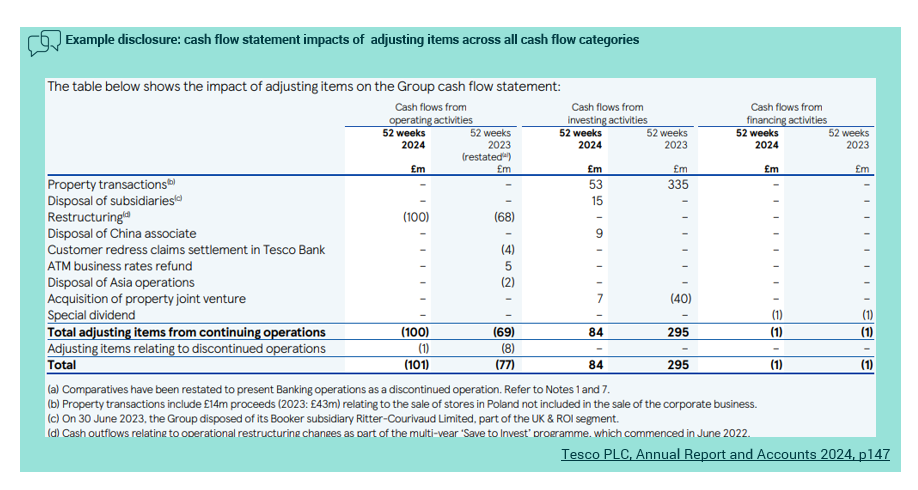
A70The second example demonstrates how the cash impact of exceptional and other adjusting items is shown in a note and disaggregated by nature and by cash flow classification, clearly showing exceptional cash flows relating to operating, investing and financing activities:
Tesco PLC, Annual Report and Accounts 2024, p147
A71Whilst some exceptional items will impact both primary statements in the same year, this is not always the case due to timing, and some exceptional items may impact multiple years. Since users adjust for exceptional items in identifying sustainable future cash flows, it would be helpful if disclosures explained such timing differences.
A72Below is an example of how a disclosure might be provided for exceptional items. Disaggregation principles introduced by IFRS 18 should apply. The example separately discloses exceptional items related to continuing operations from discontinued operations and shows which category (operating, investing, financing) that the items ae included in the income statement and the statement of cash flows:
CASH FLOW IMPACT OF EXCEPTIONAL AND ADJUSTING ITEMS (Prior year comparatives would be expected)
| INCOME STATEMENT | STATEMENT OF CASH FLOWS | |||||
|---|---|---|---|---|---|---|
| Operating activities | Investing activities | Financing activities | Operating activities | Investing activities | Financing activities | |
| 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | |
| Operating activities include the impact of the following exceptional items*: | ||||||
| Restructuring and integration programmes | ||||||
| Disposal of PP&E and intangibles | ||||||
| Disposal of subsidiaries and associates | ||||||
| Acquisition-related expenses | ||||||
| Other (with details)** | ||||||
| Total operating profit/cash flow impact of exceptional and adjusting items from continuing operations | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Restructuring and integration programmes | ||||||
| Disposal of PP&E and intangibles | ||||||
| Disposal of subsidiaries and associates | ||||||
| Acquisition-related expenses | ||||||
| Other (with details)** | ||||||
| Total operating profit/cash flow impact of exceptional and adjusting items from discontinuing operations | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Total operating profit/cash flow impact of exceptional and adjusting items | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
* Should be consistent with IFRS 18 disaggregation principles ** "Other" items should not include material offsetting amounts. A footnote explaining the nature of the items included in "other" would be useful to users.
Other cash flow measures – sub-totals and management performance measures (MPMs)
A73IFRS 18 introduces MPMs for income and expenses[^15]. An MPM is a subtotal of income and expenses that:
- is used in public communications outside financial statements[^16];
- is used to communicate to investors, management's view of an aspect of the financial performance of the company as a whole; and
- is not listed in IFRS 18 or specifically required by IFRS Accounting Standards.
A74IFRS 18 introduced sub-totals required to be disclosed on the face of the income statement[^17]. A company will disclose information about its MPMs in a single note to the financial statements. The note will include a statement that the MPMs provide management's view of an aspect of the financial performance of the company as a whole and are not necessarily comparable with measures sharing similar labels or descriptions provided by other companies.
IFRS defined sub-totals for cash flow measures and MPMS
A75Users interviewed said that to improve transparency and assist them in comparing cash flow measures not defined in IFRS reported by different companies, it would be useful if the IASB introduced new IFRS defined sub-totals in the statement of cash flows. This would facilitate the reporting of cash flow related MPMs and reconciliation back to IFRS define sub-totals.
A76A universal example discussed was free cash flow. Users interviewed said that they do not require the IASB to define free cash flow as they use their own measures. These measures vary depending upon the company, the sector, size or a number of other factors. However, when free cash flow measures are provided by companies, they do give users an insight to management's view of performance and liquidity.
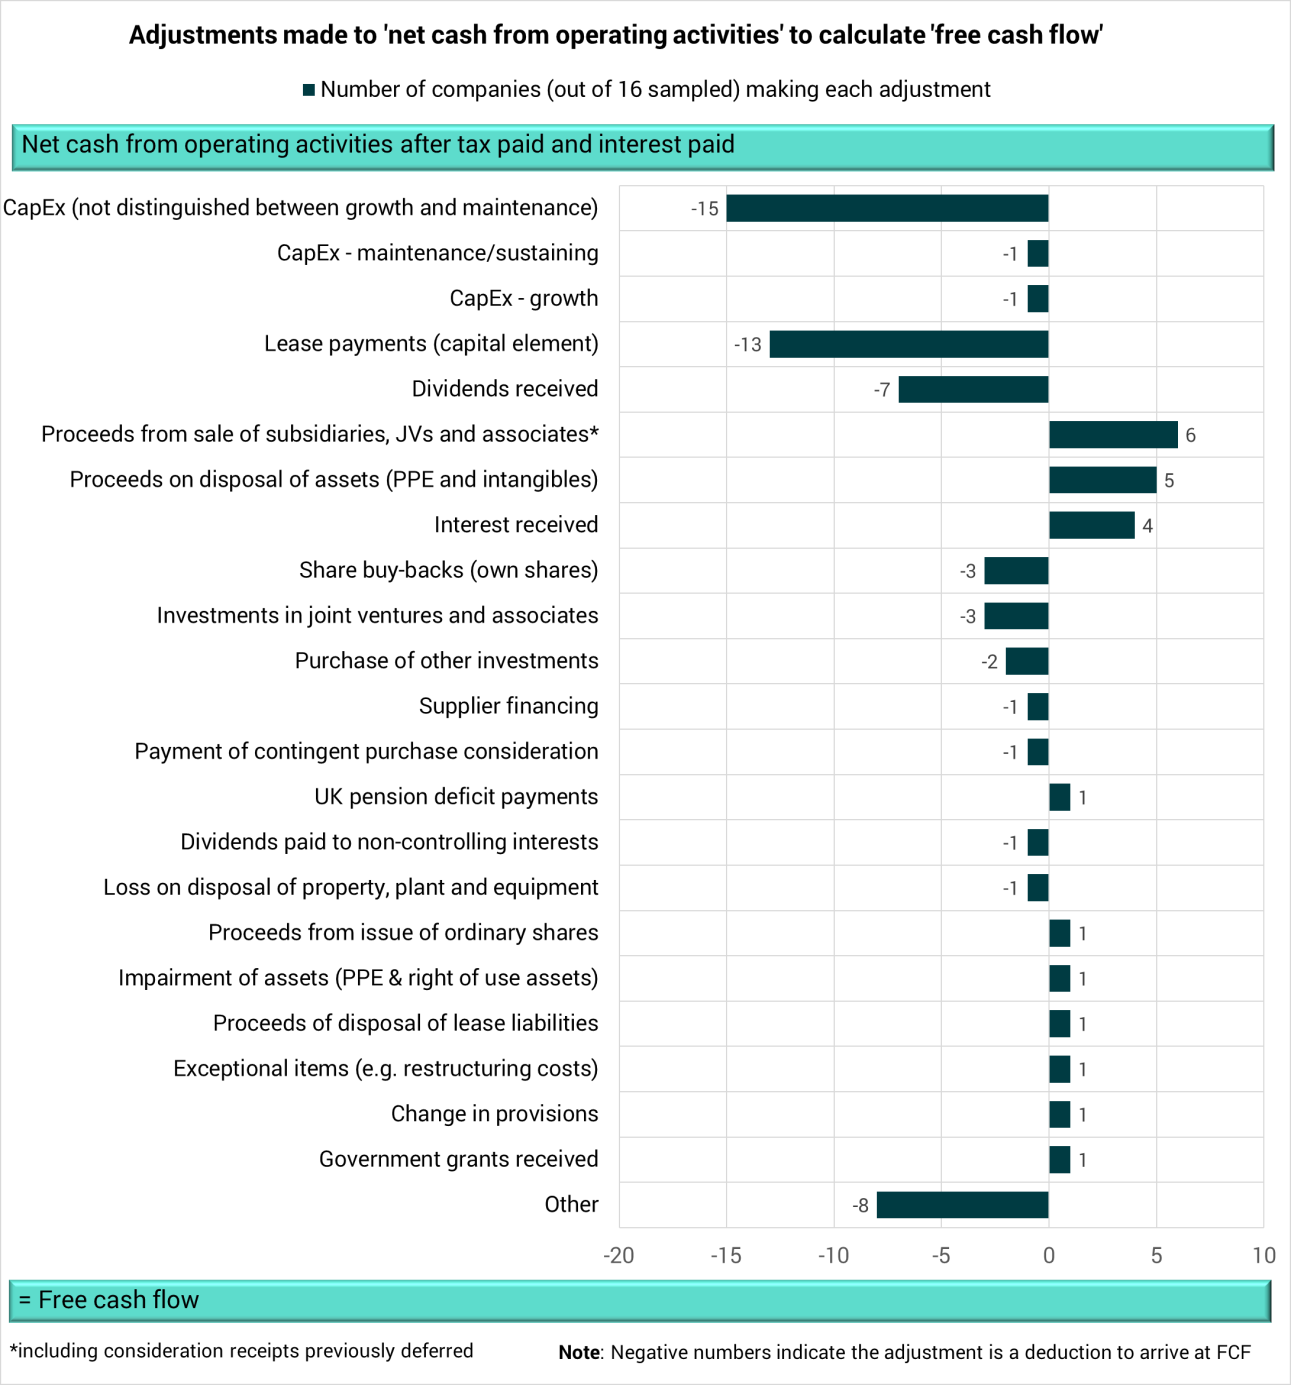
A77In the UKEB's review of a sample annual reports of 30 UK listed companies, to inform the second UKEB research paper, 16 of those companies disclosed a free
*including consideration receipts previously deferred Note: Negative numbers indicate the adjustment is a deduction to arrive at FCF
A78Some IAG members also shared their approach to calculating free cash flow, as shown in the chart below:
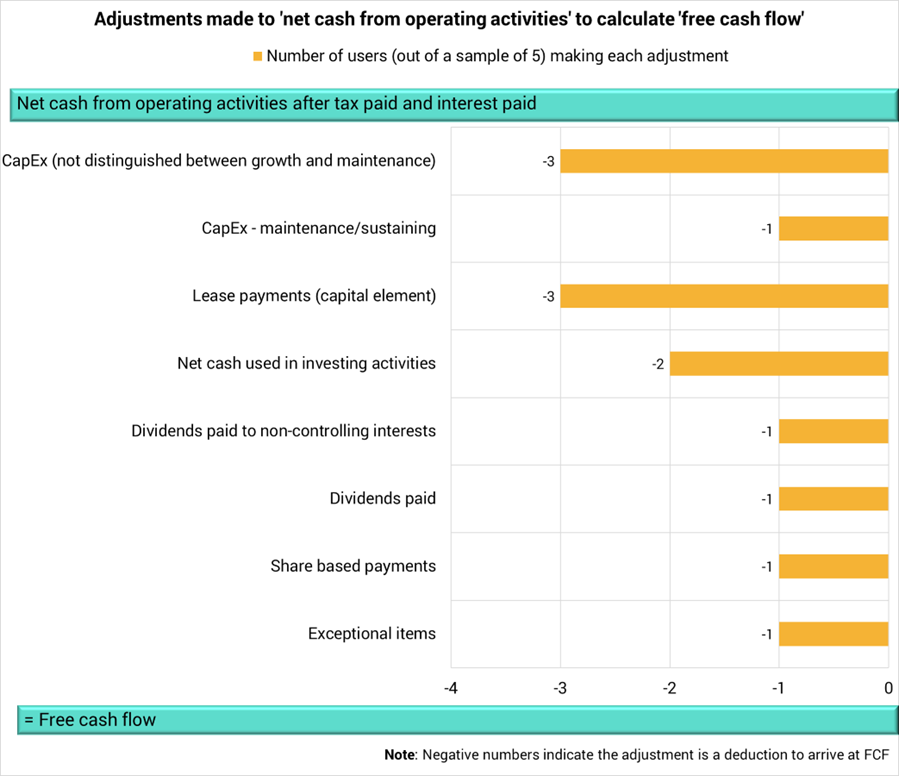
Note: Negative numbers indicate the adjustment is a deduction to arrive at FCF
A79Through our consultation with both preparers and users, the sub-total that should be the starting point for free cash flow is "cash flows from operating activities from continuing operations”, as observed in the example below:
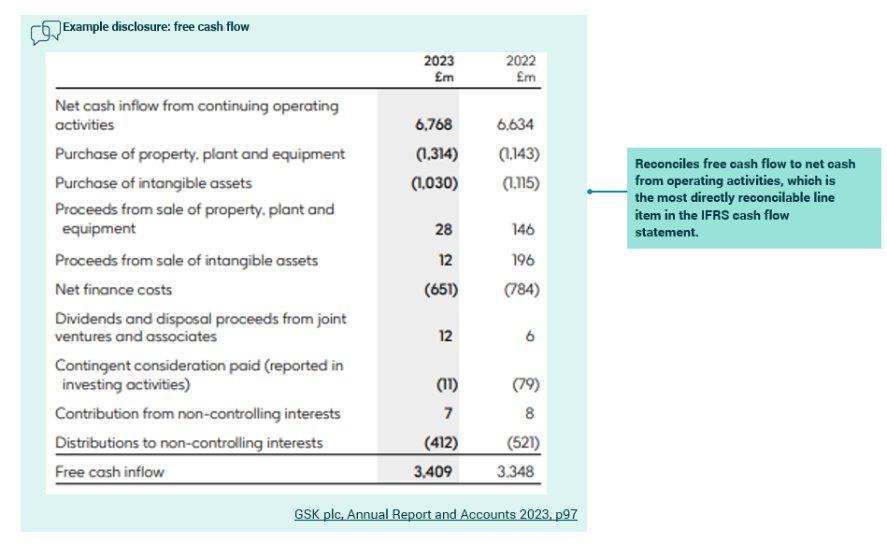
Reconciles free cash flow to net cash from operating activities, which is the most directly reconcilable line item in the IFRS cash flow statement.
GSK plc, Annual Report and Accounts 2023, p97
A80Similar to income and expense MPMs, the IASB could require the disclosure of, and reconciliation of, such cash flow MPMs to IFRS defined sub-totals in a single note in the financial statements. As noted above, the IASB might also consider including a sub-total for movements in working capital.
Cash flows from discontinuing operating activities
A81No mention of discontinued operations is made in IAS 7. However, paragraph 33 (c) of IFRS 5 Non-current Assets Held for Sale and Discontinued Operations requires[^18] "net cash flows attributable to the operating, investing and financing activities of discontinued operations to be presented separately in the statement of cash flows or the notes".
A82If the IASB introduces separate sub-totals for continuing and discontinuing operations it would need to remove the option described above per paragraph 33c of IFRS 5.
A83During the user interviews, stakeholders asked for better disclosure of cash flows from discontinuing operations. Some suggested that this would be best presented in a note in segmental format (see later section on segmental cash flows) for each line of the statement of cash flows.
A84Given the choice already provided to companies, it might be consistent for the IASB to only introduce a sub-total for 'cash flows from operating activities' and retain the note disclosure for further analysis by continuing and discontinuing activities. The advantage of this approach would be to keep the face of the statement of cash flows simplified, and mandating a supplementary note for disaggregation, if a company has discontinued operations. The level of granularity in the note would be left to the company to decide, whilst considering the disaggregation principles introduced in IFRS 18.
A85Whilst this approach may lead to diversity in the level of disaggregation in the note disclosure, there is already a minimum disclosure requirement in IFRS 5 for a company to provide a total for continuing and discontinuing cash flows for each category of cash flow (operating, investing, financing).
A86One example of a UK listed entity already providing detailed segmental cash flow information in a note showing continuing and discontinuing operations is Tesco PLC Annual Report and Financial Statements 2024 (page 143).
Non-cash information
A87As noted in the UKEB first research paper[^19], there is an argument that excluding all non-cash transactions from the statement of cash flows does not result in comparable information for similar transactions with the same economic effect.
A88For example, the purchase of an asset (or a business) in exchange for an entity's own shares is similar to first selling its own shares and then purchasing an asset with the cash received. Users might expect that the two transactions should be presented similarly in the statement of cash flows. The same could apply to other non-cash transactions, including, for example, sales in exchange for cryptocurrencies or obtaining a beneficial interest as consideration for transferring financial assets (excluding cash).
A89The increasing prevalence of non-cash changes in debt that are regarded as being economically equivalent to cash flows, is an increasing challenge for investors. Because such changes in debt do not involve cash flows, they are not reflected in the statement of cash flows.
A90Some users interviewed said it is difficult to reconcile the statement of financial position to the statement of cash flows, and there is a need for more information on non-cash effects of some transactions.
A91The UKEB initial outreach carried out in December 2024 to March 2025, and the User poll conducted in March–April 2025, suggested that information about non-cash transactions was one of the highest priorities for users.
A92Over the course of the research and outreach, a number of areas have been highlighted, as listed below, for which users said they needed more information. Disclosure requirements for such items are included in other IFRS Accounting Standards, although there are few requirements in those standards for the disclosure of cash flow information, or a requirement to disaggregate cash and non-cash information:
- Leases - IFRS 16 Leases;
- Capital Expenditure – IAS 16 Property, Plant & Equipment and IAS 38 Intangible Assets;
- Mergers and Acquisitions (M&A) and divestitures – IFRS 12 Disclosure of Interests in Other Entities and IFRS 3 Business Combinations;
- Derivatives - IFRS 9 Financial Instruments;
A93During the interviews, users acknowledged that some companies provide the information needed, but it is often voluntary and scattered throughout the financial statements.
A94Initially, the UKEB determined that such information needs might be met if companies were required to disclose non-cash information in a single note in the financial statements, to bridge the information gap for users.
A95Single-note disclosure of non-cash transactions that show effective offsetting flows (e.g. property, plant, and equipment (PPE) acquired by means of a lease, pension service costs, factoring of trade receivables, share-based payments, debt to equity conversions and certain M&A where consideration is non-cash), might assist analysts not to double count – non-cash transactions can have later real cash flows. For example, it would be important for analysts not to include in free cash flow measures, both the effective capital expenditure (capex) and the lease rental payments in respect of capitalised leases.
A96An example of how non-cash transactions might be disclosed is set out below. As well as the effective cash flows, this example includes the impact on the cash flow statement of any related cash flows included in the cash flows statement in the year that the non-cash transaction occurred (as shown for the acquisition of PP&E by means of a lease in the example):
NON-CASH TRANSACTIONS WITH SIMILAR ECONOMIC IMPACT AS CASH FLOWS ****
| Description of transaction: | Note ref | RELATED AMOUNTS INCLUDED IN STATEMENT OF CASH FLOWS | EFFECTIVE CASH FLOWS | ||||
|---|---|---|---|---|---|---|---|
| Operating activities | Investing activities | Financing activities | Operating activities | Investing activities | Financing activities | ||
| 2024 | 2024 | 2024 | 2024 | 2024 | 2024 | ||
| Non-cash consideration received from (paid to) customers | Working capital note | (2.0) | 2.0 | ||||
| Asset contributions from customers | Capex note | ||||||
| Equity-settled share-based payment charges | Share-based payments note | ||||||
| Withholding taxes and fees deducted at source | |||||||
| Government grants | (100.0) | 100.0 | |||||
| Acquisition of property, plant and equipment by means of leases | Leases note | (1.0) | 0.0 | (10.0) | 10.0 | ||
| Acquisition of subsidiary by issue of ordinary shares | |||||||
| Capitalisation of costs (e.g. borrowing costs and staff costs) | Capex note | ||||||
| Debt-to-equity conversions | |||||||
| Other (with details) | |||||||
| Total non-cash transactions with similar economic impact as cash flows | (1.0) | 0.0 | 0.0 | (100.0) | (12.0) | 112.0 | |
| Note: Sum of all totals offsets to zero |
**** The impact on the cash flows in the current year needs to be transparent to ensure no double-counting e.g. lease payments made in the reporting year that a new lease is entered into
- Share-based payments – IFRS 2 Share-based payments;
- Provisions - IAS 37 Provisions, Contingent Liabilities and Contingent Assets;
- Factoring receivables – IFRS 7 Financial Instruments: Disclosures; and
- Discontinued operations – IFRS 5 Non-current Assets Held for Sale and Discontinued Operations.
A93During the interviews, users acknowledged that some companies provide the information needed, but it is often voluntary and scattered throughout the financial statements.
A94Initially, the UKEB determined that such information needs might be met if companies were required to disclose non-cash information in a single note in the financial statements, to bridge the information gap for users.
A95Single-note disclosure of non-cash transactions that show effective offsetting flows (e.g. property, plant, and equipment (PPE) acquired by means of a lease, pension service costs, factoring of trade receivables, share-based payments, debt to equity conversions and certain M&A where consideration is non-cash), might assist analysts not to double count – non-cash transactions can have later real cash flows. For example, it would be important for analysts not to include in free cash flow measures, both the effective capital expenditure (capex) and the lease rental payments in respect of capitalised leases.
A96An example of how non-cash transactions might be disclosed is set out below. As well as the effective cash flows, this example includes the impact on the cash flow statement of any related cash flows included in the cash flows statement in the year that the non-cash transaction occurred (as shown for the acquisition of PP&E by means of a lease in the example):
A97The interviews identified that the key information that users are missing is information that would allow users to link the information disclosed in the primary financial statements and in the related notes.
A98Users were challenged to find relevant information due to:
- lack of cross-referencing between primary financial statements and related notes; and
- incomplete information disclosed.
A99Examples provided of such challenges include:
- Working capital – reconciling the movement in working capital disclosed on the face of the statement of cash flows (where presented using the indirect method) to the movement in working capital in the statement of financial position and related notes. If a reconciliation between the statement of cash flows and the statement of financial position was mandatory, including separate disclosure of factoring payables and receivables, then users' information needs should be met (see previous section on movements in working capital).
- M&A activity - reconciling the cash and non-cash impact of M&A activity on working capital, leases, capital expenditure, etc. Users' information needs should be met if:
- a working capital movement note was mandatory and required disclosure of the impact of M&A activity that could be linked to the business combinations note; and
- in the leases note ad capital expenditure note, the M&A impact was disclosed separately, and could be tied back to the business combinations note.
A100A possible approach the IASB could use is to include an "information principle" in IAS 7. This principle is covered in the next section.
Information principle
A101Users interviewed emphasised that they assess company performance holistically by considering the statement of cash flows alongside other primary financial statements, therefore cohesiveness between the primary financial statements is important.
A102Being able to reconcile between the primary financial statements ensures that the information presented is accurate, reliable and provides transparency for users. This would be expected to enhance decision-making by users. For example, by comparing the cash generated from operations to operating profit, users can assess the quality of earnings and understand how well the company is managing its working capital.
A103Thematic review reports published by the FRC note that reconciliations between the statement of cash flows and other primary financial statements are useful for understanding relationships between the different statements9. These reconciliations are especially helpful for understanding the impact of non-cash movements, such as foreign exchange differences, fair value movements and acquisitions or disposals, on changes in working capital.
A104There is no principle outlined in IAS 7 suggesting that amounts shown in the statement of cash flows should be capable of being reconciled by the user to the other primary financial statements. IAS 7 paragraph 45 does require a company to present a reconciliation of the cash and cash equivalent amounts in its statement of cash flows with equivalent items reported in the statement of financial position this requirement is discussed later in this paper.
A105The only other relevant paragraph is IAS 7 paragraph 44D. Paragraphs 44A–44E of IAS 7 (added to IAS 7 following the 2016 Disclosure Initiative) set out the disclosure requirements for changes in liabilities arising from financing activities. It states that if a company chooses to use a reconciliation of opening and closing balances in the statement of financial position for liabilities arising from financing activities (including both changes arising from cash flows and non-cash changes), the company shall "provide sufficient information to enable users of the financial statements to link items included in the reconciliation to the statement of financial position and the statement of cash flows". This “information principle” appears to be limited to the specific requirement for the change in financing liabilities and requires only a two-way reconciliation between two of the primary financial statements.
A106With regard to reconciling the statement of cash flows to the statement of profit or loss, there are no specific requirements. However, where a company uses the indirect method for disclosing cash flows from operating activities, a reconciliation to the statement of profit or loss is implicit, but the level of information provided depends on the disaggregation provided.
A107Where the indirect method is used, adjustments to the starting profit figure, made by adding back non-cash items, provides an opportunity to reconcile items to the statement of financial position, where the notes have enough granularity to show increases and decreases in the balances that are the result of non-cash transactions.
A108The IASB could consider adding an overriding “information principle” to IAS 7 for example for companies: "to ensure that the financial statements provide sufficient information to enable users to link items included in the statement of cash flows to the other primary financial statements".
A109An "information principle” would improve the requirements in IAS 7, similar to the requirements for disclosing the changes in financing liabilities, leading to the disclosure of both changes arising from cash flows and non-cash changes (such as changes arising from obtaining or losing control of subsidiaries or other businesses, the effect of changes in foreign exchange rates, and changes in fair values).
A110Almost all users interviewed are supportive of such an "information principle". Some users interviewed were concerned that an “information principle” may not lead to consistent and comparable information. However, the role of auditors and regulators to ensure that companies comply with such a principle, was acknowledged.
A111Annex B.06 maps the links to other IFRS Accounting Standards and includes examples of voluntary disclosures observed in UK listed companies, linking information between the primary financial statements and related notes, that more companies might provide should an information principle be introduced.
A112The advantage of a principle is that no specific disclosure requirements should need to be added to other Accounting Standards to ensure that sufficient information is provided for users to map the links between primary financial statements and between notes.
Cross-referencing
A113More generally, UKEB research has highlighted that very few companies provide cross references from their statement of cash flows to relevant notes in their financial statements. This makes it challenging to clearly understand the relationship between the statement of cash flows and other sections of the financial statements.
A114The absence of cross referencing in the statement of cash flows to notes in the financial statements is surprising. There is often relevant information in various notes distributed across the financial statements (for example in the leases note, the reconciliation of financing liabilities and the provisions note). However few companies provide references to these notes for relevant cash flows.
A115There would appear to be an opportunity to enhance the cohesiveness of the financial statements and enhance user understanding, if amounts on the face of the statement of cash flows were referenced to notes which agree to the amounts presented in the statement of cash flows, and the reason for any difference explained.
Other areas of cash flow reporting
A116In areas where companies may need to exercise judgement when determining or disclosing cash flow amounts and related balances, there is a high potential for diverse approaches being adopted by companies.
Cash and cash equivalents
A117Users interviewed understand cash and cash equivalents to be readily available funds for a company's day-to-day operations and therefore provide an indication of its ability to pay short-term debts. In this context, it is important that amounts that companies include in cash equivalents reflect their cash management strategy.
A118IAS 7 paragraph 46 requires companies to disclose their accounting policy for determining the composition of cash and cash equivalents. The FRC's thematic review on cash flow and liquidity disclosures, emphasised the importance of:
- Providing sufficiently detailed accounting policies that clearly define the items included in cash and cash equivalents.
- Providing an analysis of the components of cash and cash equivalents e.g. cash at bank, short term deposits, money market funds.
- A description of the terms of deposits (i.e. maturity, break clauses and interest rates.
- Explaining the rationale for including overdrafts within cash and cash equivalents, if applicable including the term of the arrangements).
- Providing information about restricted cash balances and the nature of the restrictions, and amount.
Restricted balances
A119IAS 7 paragraph 48 sets a high-level disclosure requirement for restricted cash balances, requiring companies to disclose significant restricted balances and provide commentary. As a result, companies have to exercise judgement in determining the level of detail to include in their disclosures.
A120The extract below provides an example of a company which:
- described the nature of the restricted balances and the associated restrictions; and
- explained the accounting implications – in this case, that the restrictions meant that the balances should not be included in cash and cash equivalents (companies generally do not explain their conclusion that the restrictions are not severe enough to impact their inclusion in cash and cash equivalents).
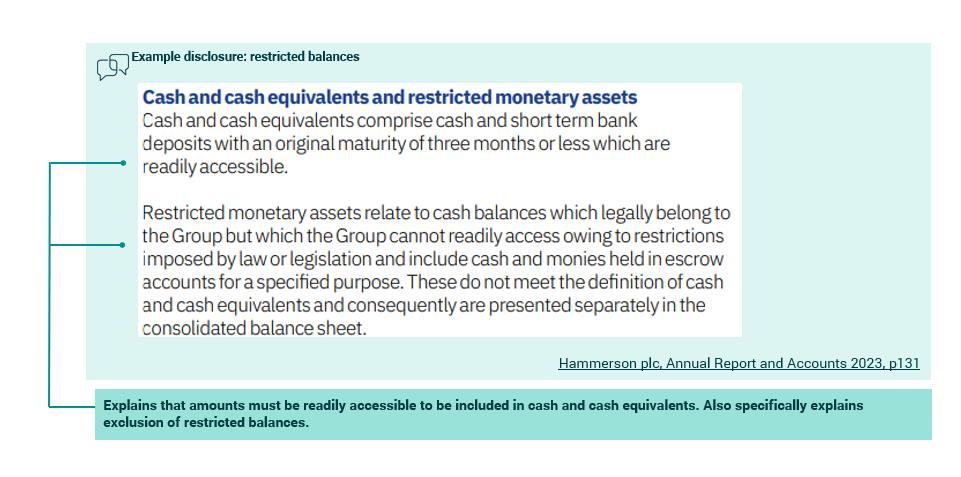
A121Users however suggested that restricted cash balances would be more transparently disclosed if the restricted amount was set out in tabular format when a company discloses the components of cash and cash equivalents.
Disclosures encouraged by IAS 7
Growth and maintenance expenditure
A122IAS 7 paragraphs 50–51, state that it may be helpful for companies to disclose aggregate cash flows that represent increases in operating capacity separately from those cash flows that are required to maintain operating capacity.
A123While such information may be useful in enabling the user to determine whether the entity is investing adequately in the maintenance of its operating capacity, there was not a high demand for such information during the UKEB outreach.
A124In the IASB's May 2025 meeting, members discussed the topics they are planning on looking into in the project. The IASB are not currently looking to define growth and maintenance expenditure.
A125Users acknowledged that it makes sense for the IASB not to define growth and maintenance expenditure, as it is very judgmental and would not necessarily increase comparability amongst companies.
A126However, it was suggested that better information might be available to users if the IASB required companies to disclose disaggregation of growth and maintenance expenditure using their own determination/judgement, where a company provides information on growth or maintenance expenditure:
- in publicly available information; or
- internally for management monitoring purposes.
Segmental cash flows
A127IAS 7 paragraph 50–51 encourage companies to disclose the amount of cash flows arising from the operating, investing and financing activities of each reportable segment.
A128The disclosure of segmental cash flows enables users to obtain a better understanding of the relationship between the cash flows of the business as a whole and those of its component parts and the availability and variability of segmental cash flows. For example, different business segments may have differing cash generation and usage profiles or differing working capital absorption.
A129The illustrative example in IAS 7 (Illustrative Example10 D) which presents only aggregate operating, investing, and financing cash flows for each operating segment.
A130During the interviews, many users said segmental cash flow information would be useful.
A131However, during the May 2025 IASB meeting, the IASB noted that they are not planning to develop new segmental reporting requirements for cash flows at this time. The IASB suggested that it might look at the requirements for segmental information at a later stage, or as a separate project on segments.
A132During the interviews, different users had different priorities in relation to segmental information on cash flows. Some users were not concerned with receiving segmental information of cash flows and relied upon disclosures provided by other segmental reporting requirements under IFRS 8 Operating Segments.
A133Some users said that segmental reporting was particularly useful for working capital movements reported under the indirect method on the statement of cash flows, where companies had significantly different business segments that absorbed different amounts of working capital (see earlier section on movements in working capital).
A134If companies have significantly different business segments that lead to different cash flows, it is likely that they are monitoring these cash flows separately in the business.
A135Therefore, rather than retain the 'encouraged' disclosure, it was suggested that the IASB could consider what specific requirements would assist users and introduce mandatory requirements to provide such segmental cash flows in certain circumstances i.e. where companies already have access to this information.
Concluding observations
A136Users indicate that there are opportunities for the IASB to improve reporting by requiring companies to disclose:
- Net debt reconciliation, including a reconciliation to the statement of cash flows.
- Movements in working capital (operating receivables and payables), reconciled to the statement of cash flows.
- Exceptional and adjusting items showing cash flow impact and income statement impact.
- Cash flow related MPMs leveraging the IASB's work done in developing IFRS 18 by introducing IASB defined sub-totals and requiring cash flow related MPMs to be reconciled to the appropriate IASB defined sub-total.
- Non-cash transactions with a similar economic impact (e.g. stock options paid to employees) in a single note to the accounts.
A137However, other non-cash information might be better disclosed by introducing an information principle. This principle would assist in enhancing the cohesiveness between primary financial statements, by requiring companies to provide more complete disclosures in, and improved cross-referencing between, certain notes to the accounts.
A138In particular, the key areas that users need information on, such as capital expenditure, leases, business combinations and derivatives, that would enable users to link the information provided about these items in each of the primary financial statements; this would include the impact on cash flows, and not just the impact on the financial performance (income statement) and the financial position (balance sheet) of the company.
A139There are also opportunities for the IASB to improve other areas of cash flow reporting, such as the information on cash and cash equivalents, by requiring additional disclosures on how much of the cash and cash equivalents reported on the statement of cash flows by component is restricted.
Annex B.01: Four alternative formats explored in the research
A140The table below shows provides a high-level description of the four alternative formats for the statement of cashflows explored in the research and outlines their key advantages and limitations.
| Alternative 1: Net Debt Basis | Alternative 2: Realigned Operating Activities | Alternative 3: Hybrid P&L and Cash Flow Statement | Alternative 4: Receipts and Uses of Cash | |
|---|---|---|---|---|
| Overview of each alternative | Reconciles opening and closing net debt rather than cash. | Classifies PP&E and intangible cash flows as operating. | Maps each income statement line to corresponding cash flows. | Categorises cash flows as sources (core, non-core, and financing) and uses (mandatory and discretionary), rather than operating investing and financing. |
| Key Advantages | Aligns with treasury practices (which manage cash, borrowings, and related derivatives). | Cohesiveness presentation of income statement and cash flow statement. | Clarifies profit-to-cash conversion. | Highlights internally generated cash surplus or shortfall (transparency around sustainability business's internal cash generation). |
| Elevates the importance of net debt as a key metric. | Aligning operating cash flows with operating profit enhances conceptual cohesiveness. | Transparency about earnings quality. | Visibility of discretionary and non-discretionary payments. | |
| Promotes standardisation of net debt disclosures. | Disaggregation enhances forecasting. | Highlights any reliance on external funding (rather than internal cash generation) to support liquidity. | ||
| Improves cohesiveness by reducing mismatches with the reconciliation of financing liabilities. |
| Key Limitations | ||||
|---|---|---|---|---|
| Separating debt and equity flows may impair cohesiveness. | Primarily reorganises existing information. | Volume of information may reduce understandability. | Primarily reorganises existing information. | |
| Less relevant in low-leverage or asset-light companies. | Does disaggregate growth and maintenance expenditure. | Complexity and potentially burdensome to preparers. | Simplistic view of 'growth vs maintenance' question. | |
| Ignores assets acquired through M&A. | Risk of inconsistent application. |
Annex B.02: Alternative format 1: Net Debt Basis
| 2024 | 2023 | ||
|---|---|---|---|
| Cash flows from operating activities | 870.0 | 889.9 | In this cash flow reporting concept, the IAS 7 cash flows from operating activities section remains unchanged. Supplementary disclosures are separately suggested to provide users with additional helpful information (e.g. the cash impact of exceptional and other adjusting items, reconciliations of working capital movements to the balance sheet and economically equivalent non-cash transactions). |
| Cash generated from operations | 865.4 | 883.1 | |
| Operating profit | 480.2 | 440.8 | |
| Adjustments for: | |||
| Depreciation of property, plant and equipment | 406.1 | 385.5 | |
| Amortisation of intangible assets | 32.7 | 38.1 | |
| Loss on disposal of property, plant and equipment | 6.7 | 4.2 | |
| Amortisation of deferred grants and contributions | (17.4) | (16.2) | |
| Equity-settled share-based payments charge | 2.1 | 5.1 | |
| Pension contributions paid less pension expense charged to operating profit | (7.1) | 0.4 | |
| Changes in working capital: | |||
| (Increase)/Decrease in inventories | (7.2) | 3.9 | |
| (Increase)/Decrease in trade and other receivables | (26.9) | 27.2 | |
| (Decrease)/Increase in trade and other payables | (4.2) | (5.5) | |
| Increase/(Decrease) in provisions | 0.4 | (0.4) | |
| Tax received/(paid) | 4.6 | 6.8 | |
| Cash flows from investing activities | (680.7) | (577.6) | The IAS 7 cash flows from investing activities section remains unchanged. Supplementary disclosures are separately suggested to provide users with additional helpful information (e.g. the cash impact of exceptional and other adjusting items and economically equivalent non-cash transactions). |
| Proceeds on the disposal of property, plant and equipment | 4.8 | 0.0 | |
| Purchase of property, plant and equipment | (749.5) | (675.9) | |
| Purchase of intangibles | (14.6) | (18.1) | |
| Acquisition of subsidiaries and businesses, net of cash acquired | 0.0 | 0.0 | |
| Disposal of subsidiaries, net of cash disposed | 0.0 | 90.5 | |
| Loans (to)/from JVs and associates | 0.0 | 5.0 | |
| Interest received | 50.7 | 15.8 | |
| Dividends received | 0.0 | 0.0 | |
| Grants and contributions received | 27.9 | 5.1 | |
| Cash flows from financing activities, excluding repayment of (proceeds from) financing liabilities | (499.4) | (426.2) | As the primary statement reconciles opening and closing net debt, the debt-related cash flows in IAS 7 cash flows from financing activities no longer appear on the face of the primary statement. These can be seen in the net debt reconciliation (supplementary disclosures) which the IASB might also consider elevating to a primary statement as suggested by some stakeholders. |
| Proceeds from the issue of share capital | 0.0 | 0.0 | |
| Share buyback | 0.0 | 0.0 | |
| Repurchase of shares to satisfy exercise of share options | (3.8) | (6.8) | |
| Dividends paid | (320.0) | (301.2) | |
| Interest paid | (175.6) | (118.2) | |
| Other | 0.0 | 0.0 | Supplementary disclosures are also separately suggested to provide users with additional helpful |
| Net increase in net debt | (310.1) | (113.9) | |
| Net forex and non-cash adjustments to net debt | (251.8) | (516.6) | |
| Net debt at the beginning of the year | (8,200.8) | (7,570.0) | |
| Net debt at the end of the year | (8,762.7) | (8,200.5) | |
| Net debt comprises: | |||
| Change in Net debt resulting from Cash flows - Cash and cash equivalents | 1,379.3 | 327.9 | |
| Cash at bank and in hand | 3.7 | 2.6 | |
| Short-term bank deposits | 1,375.6 | 325.3 | |
| Liabilities from financing activities | (10,142.0) | (8,528.4) | |
| Net Debt at the end of the year | (8,762.7) | (8,200.5) |
Annex B.03: Alternative format 2: Realigned Operating Activities
| 2024 | 2023 | ||
|---|---|---|---|
| Cash flows from operating activities | 138.6 | 291.5 | An alternative title for this section might be 'cash flows from main/ core business activities'. |
| Cash generated from (used in) trading and supporting operations | 865.4 | 883.1 | |
| Operating profit | 480.2 | 440.8 | |
| Adjustments for: | |||
| Depreciation of property, plant and equipment | 406.1 | 385.5 | |
| Amortisation of intangible assets | 32.7 | 38.1 | |
| Loss on disposal of property, plant and equipment | 6.7 | 4.2 | |
| Amortisation of deferred grants and contributions | (17.4) | (16.2) | |
| Equity-settled share-based payments charge | 2.1 | 5.1 | |
| Pension contributions paid less pension expense charged to operating profit | (7.1) | 0.4 | |
| Changes in working capital: | |||
| (Increase)/Decrease in inventories | (7.2) | 3.9 | |
| (Increase) Decrease in trade and other receivables | (26.9) | 27.2 | |
| (Decrease)/Increase in trade and other payables | (4.2) | (5.5) | |
| Increase/(Decrease) in provisions | 0.4 | (0.4) | |
| Cash generated from (used in) purchase or sale of operating assets | (731.4) | (598.4) | This concept proposes that the cash impact of trading and supporting activities, purchases of PP&E, and purchases of intangible assets should be included in a single section of the cash flow statement - because the profits generated by these assets, along with their depreciation and amortization, are included in operating profit. Similarly, acquisition-related cash flows should be included in operating activities, as the resulting changes in the nature and scale of the main business directly impact operating profit and cash flows. |
| Proceeds on the disposal of property, plant and equipment | 4.8 | 0.0 | |
| Purchase of property, plant and equipment | (749.5) | (675.9) | |
| Purchase of intangibles | (14.6) | (18.1) | |
| Grants and contributions received | 27.9 | 5.1 | |
| Acquisition of subsidiaries and businesses, net of cash acquired | 0.0 | 0.0 | |
| Disposal of subsidiaries, net of cash disposed | 0.0 | 90.5 | |
| Tax received (paid) | 4.6 | 6.8 | |
| Cash flows from other/ non-core business activities | 50.7 | 20.8 | Purchases and sales of other assets (not used in the main business activities) remain in the IAS 7 investment activities section. Returns from these assets are also included here. |
| Loans (to) from JVs and associates | 0.0 | 5.0 | |
| Interest received | 50.7 | 15.8 | |
| Dividends received | 0.0 | 0.0 | |
| Cash flows from financing activities | 862.1 | (203.2) | |
| Proceeds from borrowings net of issuance costs | 1,610.0 | 501.1 | |
| Repayments of borrowings | (248.5) | (278.1) | |
| Proceeds from/ (repayments of) short-term loans | 0.0 | 0.0 | |
| Interest paid | (175.6) | (118.2) | |
| Proceeds from the issue of share capital | 0.0 | 0.0 | |
| Share buyback | 0.0 | 0.0 | |
| Repurchase of shares to satisfy exercise of share options | (3.8) | (6.8) | |
| Dividends paid | (320.0) | (301.2) | |
| Other | 0.0 | 0.0 | |
| Net increase in cash and cash equivalents | 1,051.4 | 109.1 | |
| Net forex adjustment to cash balances | 0.0 | (1.3) | |
| Cash and cash equivalents at the beginning of the year | 327.9 | 220.1 | |
| Cash and cash equivalents at the end of the year | 1,379.3 | 327.9 |
Annex B.04: Alternative format 3: Hybrid P&L and Cash Flow Statement
| Reported profit or loss | Timing differences - changes in working capital | Timing differences - other than WC | FX gains or losses | FV gains or losses | Other Non-cash adjustments | Other reclassification items | Cash flow before reclassification of interest to investing and financing activities | Reclassification of interest to investing and financing activities | Reported operating cash flows | |
|---|---|---|---|---|---|---|---|---|---|---|
| 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | 2024 £m | |
| INCOME STATEMENT TO OPERATING CASH FLOW RECONCILIATION | ||||||||||
| Revenue | 1,949.5 | (26.9) | 0.0 | 0.0 | 0.0 | (17.4) | (22.0) | 1,883.2 | 0.0 | 1,883.2 |
| Other income | 18.8 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 18.8 | 0.0 | 18.8 |
| Staff costs | (205.1) | 0.0 | (7.1) | 0.0 | 0.0 | 2.1 | 0.0 | (210.1) | 0.0 | (210.1) |
| Other operating costs | (602.4) | (11.0) | 0.0 | 0.0 | 0.0 | 6.7 | 0.0 | (606.7) | 0.0 | (606.7) |
| Allowance for expected credit losses - trade and other receivables | (22.0) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 22.0 | 0.0 | 0.0 | 0.0 |
| Depreciation of property, plant and equipment | (406.1) | 0.0 | 0.0 | 0.0 | 0.0 | 406.1 | 0.0 | 0.0 | 0.0 | 0.0 |
| Amortisation of intangible assets | (32.7) | 0.0 | 0.0 | 0.0 | 0.0 | 32.7 | 0.0 | 0.0 | 0.0 | 0.0 |
| Infrastructure renewals expenditure | (219.8) | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | (219.8) | 0.0 | (219.8) |
| Total operating expenses | (1,469.3) | (11.0) | (7.1) | 0.0 | 0.0 | 447.6 | 22.0 | (1,017.8) | 0.0 | (1,017.8) |
| Operating profit | 480.2 | (37.9) | (7.1) | 0.0 | 0.0 | 430.2 | 0.0 | 865.4 | 0.0 | 865.4 |
| Investment income | 85.6 | 0.0 | (6.3) | 0.0 | 0.0 | (28.6) | 0.0 | 50.7 | (50.7) | 0.0 |
| Finance expense | (389.3) | 0.0 | 204.2 | 0.0 | 0.0 | 9.5 | 0.0 | (175.6) | 175.6 | 0.0 |
| Allowance for expected credit losses - loans to joint ventures | (2.4) | 0.0 | 0.0 | 0.0 | 0.0 | 2.4 | 0.0 | 0.0 | 0.0 | 0.0 |
| Net finance expense | (306.1) | 0.0 | 197.9 | 0.0 | 0.0 | (16.7) | 0.0 | (124.9) | 124.9 | 0.0 |
| Disposal of subsidiary | 0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Share of losses of JVs and associates | (4.1) | 0.0 | 0.0 | 0.0 | 0.0 | 4.1 | 0.0 | 0.0 | 0.0 | 0.0 |
| Profit before tax | 170.0 | (37.9) | 190.8 | 0.0 | 0.0 | 417.6 | 0.0 | 740.5 | 124.9 | 865.4 |
| Current tax | 5.8 | 0.0 | (1.2) | 0.0 | 0.0 | 0.0 | 0.0 | 4.6 | 0.0 | 4.6 |
| Deferred tax | (48.9) | 0.0 | 0.0 | 0.0 | 0.0 | 48.9 | 0.0 | 0.0 | 0.0 | 0.0 |
| Total tax | (43.1) | 0.0 | (1.2) | 0.0 | 0.0 | 48.9 | 0.0 | 4.6 | 0.0 | 4.6 |
| Profit for the year | 126.9 | (37.9) | 189.6 | 0.0 | 0.0 | 466.5 | 0.0 | 745.1 | 124.9 | 870.0 |
Annex B.05: Alternative format 4: Receipts and uses of cash
| 2024 | 2023 | ||
|---|---|---|---|
| Cash generated internally [from main/ core business activities and other business activities] | 916.1 | 898.9 | Separating cash flows from 'main business' and 'other business activities' highlights how much the main business is supported by non-core activities. |
| Cash from main/ core business activities [including trading activities and supporting operations] | 865.4 | 883.1 | |
| Operating profit | 480.2 | 440.8 | |
| Adjustments for: | |||
| Depreciation of property, plant and equipment | 406.1 | 385.5 | |
| Amortisation of intangible assets | 32.7 | 38.1 | |
| Loss on disposal of property, plant and equipment | 6.7 | 4.2 | |
| Amortisation of deferred grants and contributions | (17.4) | (16.2) | |
| Equity settled share based payments charge | 2.1 | 5.1 | |
| Pension contributions paid less pension expense charged to operating profit | (7.1) | 0.4 | |
| Changes in working capital: | 0.0 | 0.0 | |
| (Increase)/Decrease in inventories | (7.2) | 3.9 | |
| (Increase)/Decrease in trade and other receivables | (26.9) | 27.2 | |
| (Decrease)/Increase in trade and other payables | (4.2) | (5.5) | |
| Increase/(Decrease) in provisions | 0.4 | (0.4) | |
| Cash from other/non-core business activities [from other return-generating assets] | 50.7 | 15.8 | |
| Interest received | 50.7 | 15.8 | |
| Dividends received | 0.0 | 0.0 | |
| Other | 0.0 | 0.0 | |
| Mandatory cash flows and ongoing asset purchases and disposals | (1,150.9) | (1,078.4) | |
| Mandatory cash flows | (419.5) | (389.5) | |
| Interest paid | (175.6) | (118.2) | |
| Tax received/(paid) | 4.6 | 6.8 | |
| Repayments of borrowings (mandatory) | (248.5) | (278.1) | |
| Ongoing asset purchases and disposals | (731.4) | (688.9) | Separately distinguishes organic asset growth (through ongoing asset purchases and disposals within the business) and inorganic asset growth (through business combinations). This should be broadly aligned with expenditure to maintain the existing business and expenditure to expand the business. |
| Proceeds on the disposal of property, plant and equipment (not acquisition-related) | 4.8 | 0.0 | |
| Purchase of property, plant and equipment (not acquisition-related) | (749.5) | (675.9) | |
| Purchase of intangibles (not acquisition-related) | (14.6) | (18.1) | |
| Other (with details) | 27.9 | 5.1 | |
| Internally generated cash surplus (shortfall) before discretionary cash flows | (234.8) | (179.5) | |
| Discretionary and acquisition-related cash flows | (323.8) | (212.5) | |
| Discretionary distributions to shareholders and other non-mandatory payments to providers of finance | (323.8) | (308.0) | |
| Dividends paid | (320.0) | (301.2) | |
| Repayments of borrowings (discretionary) | 0.0 | 0.0 | |
| Share buyback (discretionary) | 0.0 | 0.0 | |
| Repurchase of shares to satisfy exercise of share options (discretionary) | (3.8) | (6.8) | |
| Other (with details) | 0.0 | 0.0 | |
| Other discretionary and acquisition-related cash flows | 0.0 | 95.5 | |
| Acquisition of subsidiaries and businesses, net of cash acquired | 0.0 | 0.0 | |
| Disposal of subsidiaries, net of cash disposed | 0.0 | 90.5 | |
| Loans (to) from JVs and associates | 0.0 | 5.0 | |
| Other (with details) | 0.0 | 0.0 | |
| Net internally generated cash surplus (shortfall) | (558.6) | (392.0) | Separate disclosure of the net internally generated cash surplus (or shortfall) highlights the extent to which the business is self-sustaining from a cash perspective |
| Cash generated externally | 1,610.0 | 501.1 | |
| Proceeds from borrowings net of issuance costs | 1,610.0 | 501.1 | |
| Proceeds from/ (repayments of) short-term loans | 0.0 | 0.0 | |
| Proceeds from the issue of share capital | 0.0 | 0.0 | |
| Other | 0.0 | 0.0 | |
| Net increase in cash and cash equivalents | 1,051.4 | 109.1 | |
| Net forex adjustment to cash balances | 0.0 | (1.3) | |
| Cash and cash equivalents at the beginning of the year | 327.9 | 220.1 | |
| Cash and cash equivalents at the end of the year | 1,379.3 | 327.9 |
Annex B.05: Alternative format 4: Receipts and uses of cash
Separating cash flows from 'main business' and 'other business activities' highlights how much the main business is supported by non-core activities.
Separately distinguishes organic asset growth (through ongoing asset purchases and disposals within the business) and inorganic asset growth (through business combinations). This should be broadly aligned with expenditure to maintain the existing business and expenditure to expand the business.
Separate disclosure of the net internally generated cash surplus (or shortfall) highlights the extent to which the business is self-sustaining from a cash perspective.
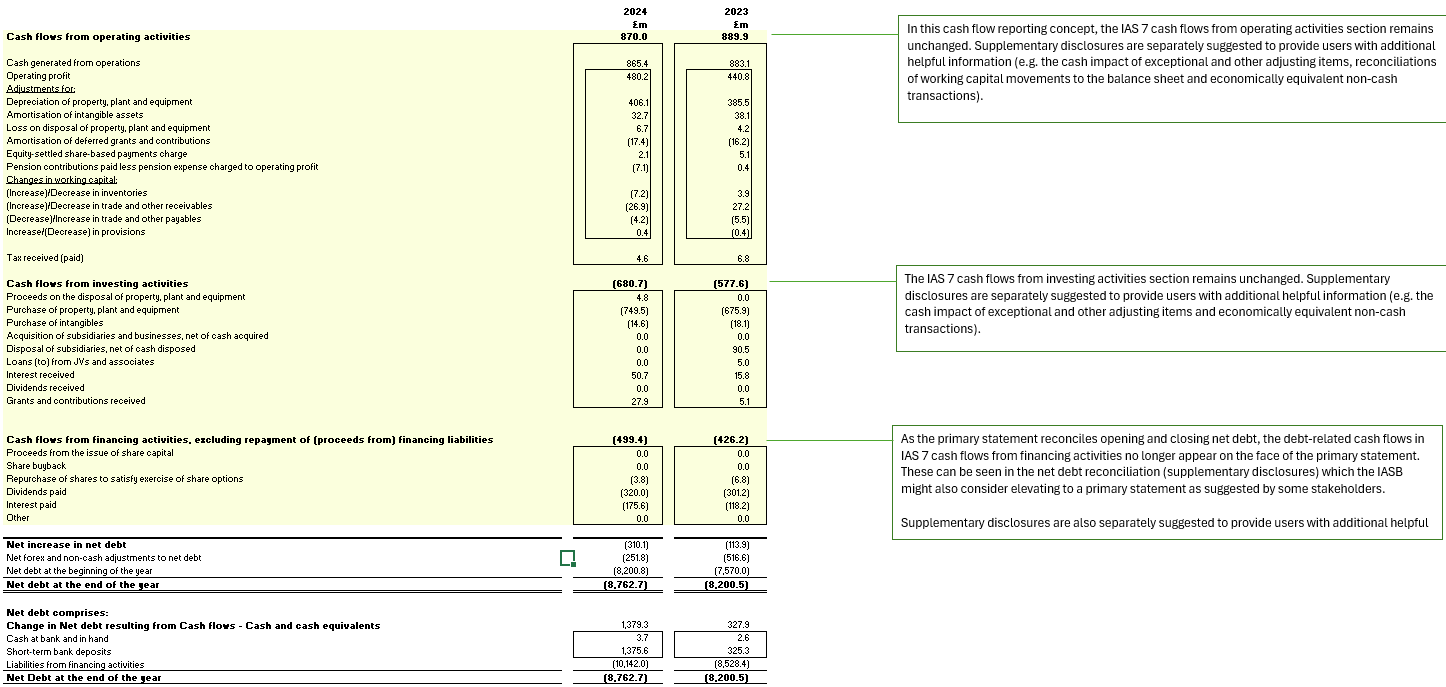
Annex B.06: Supplementary disclosure examples
A141. In this research paper, it was suggested that the IASB might consider introducing an information principle that might lead to enhanced disclosures in certain notes to the financial statements, improving the cohesiveness between the primary financial statements.
A142. Information of existing requirements and example disclosures are provided below for:
- Leases
- Share-based payments
- Tax payments
- Capital expenditure
- Derivatives
- Business combinations (M&A transactions)
- Provisions
Leases
A143. Although companies do not report the 'effective' investing and financing flows arising from finance leases in the actual statement of cash flows, IAS 7 does require that significant non-cash financing and investing transactions are disclosed elsewhere in the financial statements11. Ideally, analysts would like to see these on the same page as the statement of cash flows, or at least the location of this information clearly cross-referenced in that statement12.
A144. Paragraph 50 of IFRS 16 Leases sets out the presentation requirements (categories) in the statement of cash flows for a lessee13, and paragraphs 51–59 of IFRS 16 set out the disclosure requirements, including amounts for the reporting period (paragraph 53), which includes total cash outflow for leases.
A145. Paragraph 52 of IFRS 16 requires a lessee to "disclose information about its leases for which it is a lessee, in a single note or separate section in its financial statements. However, a lessee need not duplicate information that is already presented elsewhere in the financial statements, provided that the information is incorporated by cross-reference in the single note or separate section about leases". It is interesting that IFRS 16 sets out specific requirements for cross-referencing.
A146. Paragraph B52 of IFRS 18 says that "additional information relating to sale and leaseback transactions that, depending on the circumstances, may be needed to satisfy the disclosure objective in paragraph 51 (of IFRS 18) and could include information that helps users of financial statements to assess (d) the cash flow effect of sale and leaseback transactions in the reporting period".
A147. During the earlier UKEB outreach and user interviews, users noted that they needed more information on leases.
A148. As part of its post-implementation review of IFRS 16 Leases14, the IASB is also gathering information in whether improvements to the disclosure requirements for leases (including cash flows disclosures) are needed.
Share-based payments
A149. Whilst paragraphs 44–52 of IFRS 2 Share-based payments, sets out the disclosure requirements for such transactions, the Standard makes no reference to the statement of cash flows.
A150. Below is an example of one UK listed company’s disclosure (Tesco plc Annual report 2024 p189) for share-based payments, cross-referencing to the income statement, the statement of cash flows, and the statement of changes in equity:
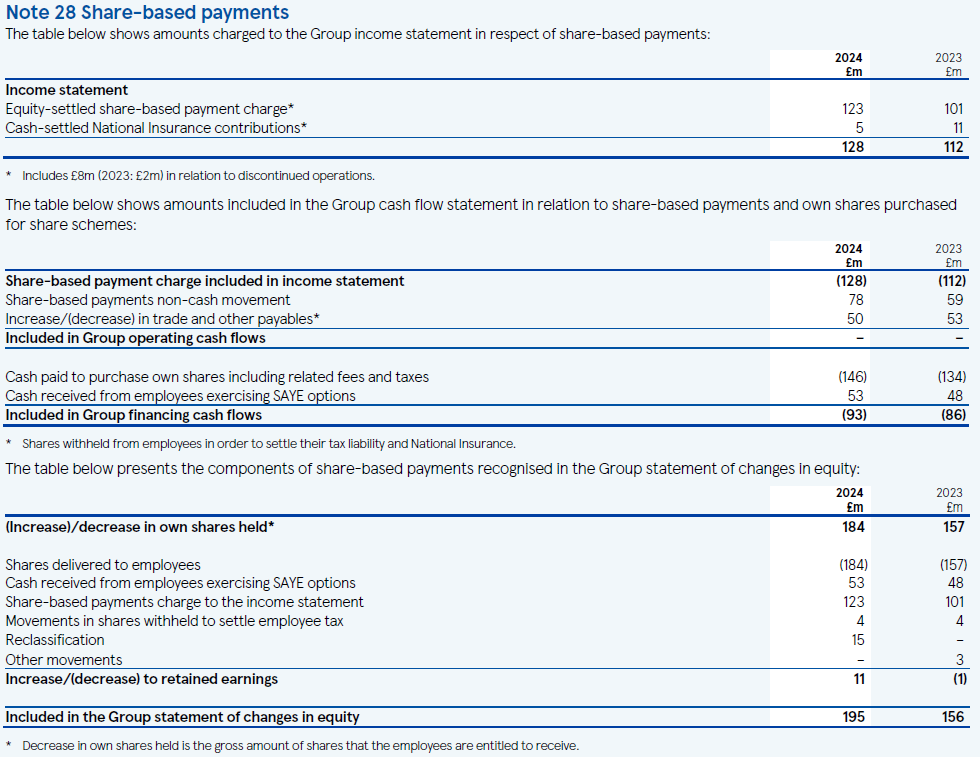
A151. Some companies provide more detail in the front half (Strategic report) of their annual report.
Tax payments
A152. Paragraph 35 of IAS 7 requires that "cash flows arising from taxes on income shall be separately disclosed and shall be classified as cash flows from operating activities unless they can be specifically identified with financing and investing activities".
A153. During outreach most users told us that they would prefer tax cash flows to be disclosed separately and not included in operating, investing or financing activities, even where they can be specifically identified.
A154. Voluntary disclosures relating to tax cash flows include a reconciliation between tax payments in the statement of cash flows and tax charges recognised in the statement of profit or loss and statement of financial position:
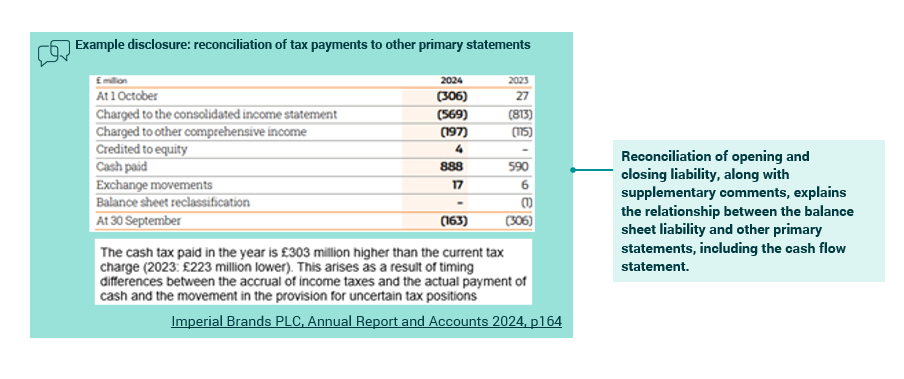
Reconciliation of opening and closing liability, along with supplementary comments, explains the relationship between the balance sheet liability and other primary statements, including the cash flow statement.
Capital expenditure
A155. During UKEB outreach, stakeholders suggested that a breakdown of fixed asset additions to separately disclose cash transactions, cash-timing differences (e.g. accrued capex) and non-cash transactions (e.g. leased assets, transfer of assets, etc), would be useful.
A156. UKEB review of a sample of annual reports of UK listed companies noted voluntary disclosures relating to capital expenditure that some companies provide, include a reconciliation, explaining the differences between capital expenditure payments and additions to property, plant, and equipment:
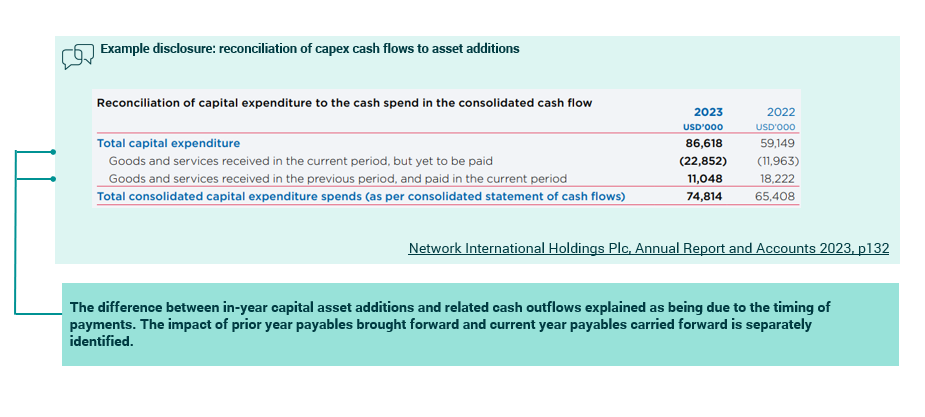
The difference between in-year capital asset additions and related cash outflows explained as being due to the timing of payments. The impact of prior year payables brought forward and current year payables carried forward is separately identified.
A157. Another example (see United Utilities plc 2024 Annual report p204) is such a reconciliation is below:
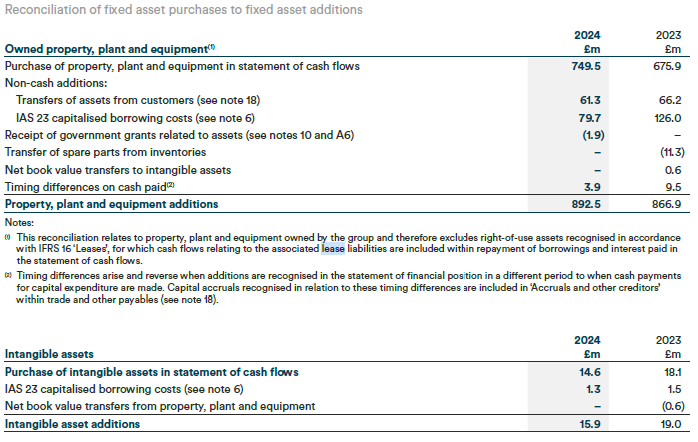
Derivatives cash flows
A158. IAS 7 paragraph 16 states that where a contract is accounted for as a hedge, its cash flows should be classified in the same manner as the hedged item. It does not, however, specify whether such cash flows should be separately identifiable. In addition, the Standard does not provide guidance on economic hedges or derivatives where hedge accounting is not applied.
A159. Understanding the cash flows from derivatives help users evaluate the potential financial impact of a derivative strategy, considering factors like the timing and amount of future payments, which is crucial for deciding whether to enter into a derivative position. The cash flows may also help users to assess whether there is sufficient liquidity to meet future obligations arising from derivative contracts.
A160. Our research highlighted that UK listed companies typically provide limited information on the cash effects of derivatives in the statement of cash flows.
- Some UK listed companies provide transparency by describing their accounting policies for classification of derivative cash flows – see example below. We believe it would be useful for companies to explain in an accounting policy note, the classification of derivative cash flows in circumstances where hedge accounting is applied, and those circumstance where hedge accounting is not applied.
- Where companies enter into hedges relating to operating activities, we believe it would be useful for companies to disclose the impact of those derivatives in the operating activities section of the statement of cash flows.
- Some companies in our sample disclosed derivative cash flows relating to investing and financing activities on the face of the statement of cash flows, as illustrated in the example below.
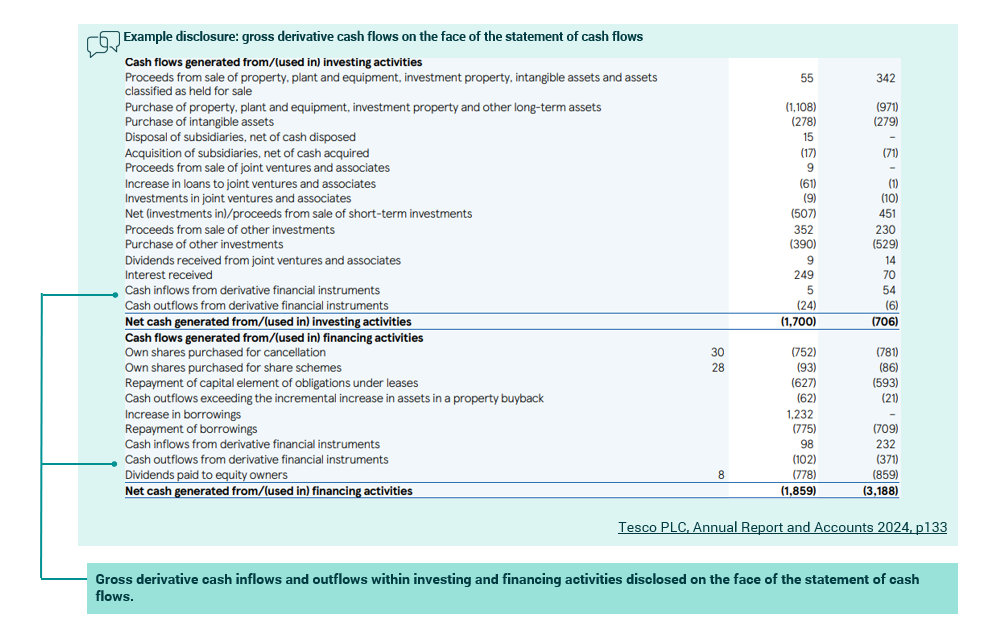
Cash impact of M&A transactions
A161. Paragraph 39 of IAS 7 states that "the aggregate cash flows arising from obtaining or losing control of subsidiaries or other business should be presented separately and classified as investing activities".
A162. Reporting the aggregate cash and non-cash impact of merger and acquisition (M&A) activities in a single note in the financial statements is useful as such transactions may be reported in different sections of the statement of cash flows. For example, the cash balance of a new subsidiary is reported as a cash inflow when first consolidated, the acquisition may be paid for in cash or by the issue of equity and there may be a deferred or contingent consideration element. Such cash flows should be disclosed within investing activities (as required by IAS 7 paragraph 39). There may also be cash flows for related acquisition costs which should be disclosed within cash flows from operating activities (as required by IAS 7 paragraph 14).
A163. Some transactions that result in a zero cash flow in fact comprise two offsetting 'effective' flows which, had they been transacted separately, would each have appeared in the statement of cash flows. Whether the purchase is a single transaction, or a separate equity issue followed by a cash purchase, does not affect the underlying economics, but does produce very different disclosures in the statement of cash flows. This applies to several situations in addition to business combinations, including leasing and supplier finance arrangements. Considering just cash flows reported in the statement of cash flows can lead to analyst metrics, such as free cash flow, which are incomplete and unsuitable for use in equity valuation.
A164. Issues may arise due to inherent tensions between the IFRS Accounting Standard requirements and companies' desire to present the aggregate cash impact of M&A transactions.
A165. As noted in our third research paper, a few users noted that non-cash information for M&A activity may be disclosed not only in separate notes to the financial statements, but also in different places in the statement of cash flows, or indeed there may be non-cash elements in the transaction (as noted in the second research paper15).
A166. One credit rating agency noted that effects of M&A activity or disposals also make it hard for analysts to extract working capital movements from the statement of financial position, when there are insufficient disclosures about such transactions.
A167. Users also need cash flow information about an acquired entity to accurately assess its ability to generate cash for future operations, and to evaluate the impact of an acquisition on the acquiring company's liquidity.
A168. Paragraph 1 of IFRS 12 notes that the objective of the standard is "to require an entity to disclose information that enables users of its financial statements to evaluate: ....(b) the effects of those interests on its financial position, financial performance and cash flows", and paragraph 10 of IFRS 12 requires information to be disclosed "that enables users of its consolidated financial statements (a) to understand: ....(ii) the interest that non-controlling interests have in the group's activities and cash flows (paragraph 12)".
A169. There are also a range of transactions where no specific guidance exists, leading to diversity in practice, including payment of variable consideration in a business combination.
Provisions
A170. During interviews, users noted that they need more information on provisions. Whilst companies are required to provide details of movements during the year, companies do not generally provide a breakdown of cash flows as part of the utilised amount.
A171. There are no disclosure requirements in IAS 37 Provisions, Contingent Liabilities and Contingent Assets related to cash flows. The only reference made to provisions in IAS 7 is in paragraph 20, where the standard states that one alternative, under the indirect method, of determining net cash flow from operating activities, is by adjusting profit or loss for the effects of:
- changes during the period in inventories and operating receivables and payables;
- non-cash items such as depreciation, provisions, deferred taxes, unrealised foreign currency gains and losses, and undistributed profits of associates; and
- all other items for which the cash effects are investing or financing cash flows.
A172. Paragraph 84 of IAS 37, whilst requiring information necessary for a roll forward for each class of provision, does not require disclosure of cash and non-cash changes.
A173. The UKEB did not find any examples of provision disclosures in the sample annual reports reviewed in their research, where cash flows relating to provision movements was disclosed.
Appendix B: Statement of Cash Flows and Related Matters: IASB update
Background
IASB research project
B1. The IASB added a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation (published March 2021).
B2. In the Feedback Statement to the Request for Information (published July 2022) most respondents recommended the addition of a potential project on cash flows to the IASB's workplan, rating it as high priority.
B3. The IASB staff have performed initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7. This evidence supports the IASB's decision on the scope of the project and provides possible ways of improving the perceived deficiencies.
B4. The IASB discussed the initial research outcomes at its March 2025 meeting.
Purpose of this paper
B5. This paper provides the Board with an update on the IASB's research project on the Statement of Cash Flows and Related Matters.
B6. The IASB met on 20 May 2025 to discuss1:
- the topics to include in the project plan;
- the topics to exclude from the project plan;
- the project approach for topics related to financial institutions; and
- a draft timeline for work on the project.
B7. The IASB decided that it will assess potential ways to improve:
- the disaggregation of cash flow information in the financial statements;
- the reporting of information about non-cash transactions in the financial statements;
- the transparency of information communicated about cash flow measures not specified in IFRS Accounting Standards;
- the consistent application of requirements to classify cash flows as operating, investing or financing; and
- the consistent application of the definition of 'cash equivalents'.
B8. The IASB decided it will not:
- aim to redefine the operating, investing and financing categories;
- aim to align the classification of cash flows in the statement of cash flows with the classification of related income and expenses in the statement of profit or loss, which is set out in IFRS 18 Presentation and Disclosure in Financial Statements;
- define 'growth and maintenance capital expenditures';
- define the measures ‘free cash flows' or 'net debt';
- expand the definition of 'cash and cash equivalents';
- develop new requirements for cash flow information by segment;
- develop specific requirements for offsetting cash flows;
- develop alternatives to a statement of cash flows; or
- amend the requirement in IAS 7 Statement of Cash Flows for an entity to present operating activities using the direct or the indirect method.
B9. The IASB decided it will approach the statement of cash flows for financial institutions by considering:
- improvements to the statement of cash flows generally before deciding how any changes might apply to the requirements for financial institutions;
- exemptions for financial institutions from some or all of the requirements for presenting a statement of cash flows; and
- any presentation or supplementary disclosure requirements specific to financial institutions that might enhance the usefulness of information about cash flows for such entities.
B10. The IASB plans to discuss potential ways to improve financial reporting for the selected topics at future meetings.
Footnotes
-
May 2025 IASB Staff paper Agenda 20A Agenda Paper 20A sets out (i) the recommended topics to explore and (ii) the project plan. ↩↩
-
The IASB decided (see Page 6 of Staff agenda paper 20A of the IASB meeting on 20 May 2025 ) that topics it plans to explore will not necessarily include alternatives to a statement of cash flows. However, the IASB will likely consider making changes to the face of the statement of cash flows, such as reordering, or adding sub-totals to assist with requiring cash flow related management performance measures. The alternative presentations considered by the UKEB were for discussion purposes – the information could equally be required on the face of the statement of cash flows or in the notes to the financial statements. ↩
-
Appendix E of 22 May 2025 Agenda paper 5 provides a summary of the responses to 15 questions in the User poll on the Statement of Cash Flows and Related Matters carried out between 25 March and 22 April 2025. ↩
-
The meeting summary of the UKEB IAG meeting held on 2 June 2025 can be found here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/investor-advisory-group/ ↩
-
The meeting summary of the UKEB PAG meeting held on 16 June 2025 can be found here: https://www.endorsement-board.uk/about-us/structure/advisory-groups/preparer-advisory-group/ ↩
-
See paragraph 95 of the second research paper Statement of Cash Flows and Related Matters: Non-mandatory and Voluntary Cash Flow Disclosures Provided by UK Listed companies, presented to the Board in February 2025. This paper was based on a review of a sample of annual reports for 30 UK Listed companies and highlighted cash flow related disclosures that those companies include in their financial statements beyond the requirements of IAS 7 and other IFRS Accounting Standards. ↩
-
IAS 7 paragraph 44A requires companies to disclose information about changes in financing liabilities. The subsequent paragraphs explain, amongst other matters, that this information may be presented in the form of a reconciliation of the opening and closing balances of liabilities arising from financing activities (IAS 7 paragraph 44D). IAS 7 paragraph 44E explains that the information may be combined with disclosures of changes in other assets and liabilities. Most UK companies adopt this method by presenting a net debt reconciliation. ↩
-
See section 6 Cash Flow Statements (pages 37–40) of the November 2018 FRC Thematic Review: Reporting by Smaller Listed and AIM Quoted Companies and FRC Thematic Review: Cash flow statements and liquidity (IAS 7, IFRS 7) (page 8). ↩
-
Illustrative Examples (IEs) are part of the Accompanying Guidance to IFRS Accounting Standards. However, the IEs do not form a mandatory part of the Standards. ↩
-
IAS 7 paragraph 43. ↩
-
https://www.footnotesanalyst.com/some-cash-flow-measures-should-include-non-cash-flows/ ↩
-
Paragraph 50 of IFRS 16 Leases states that "In the statement of cash flows, a lessee shall classify: (a) cash payments for the principal portion of the lease liability within financing activities; (b) cash payments for the interest portion of the lease liability applying the requirements in IAS 7 Statement of Cash Flows for interest paid; and (c) short-term lease payments, payments for leases of low-value assets and variable lease payments not included in the measurement of the lease liability within operating activities". ↩
-
Information on the IASB Post-implementation review of IFRS 16 Leases can be found on the IASB website: https://www.ifrs.org/projects/work-plan/post-implementation-review-of-ifrs-16-leases/ ↩
-
See paragraphs C55–C60 of the UKEB second research paper Statement of Cash Flows and Related Matters: Non-mandatory and Voluntary Cash Flow Disclosures provided by UK Companies. ↩