5 Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-Dependent Electricity
For a document on web accessibility, aiming for a "clean, semantic markdown optimized for web accessibility" is good. However, there are a few points where the request provides ambiguous advice, or even anti-patterns, when considered within the larger context of web content management and general accessibility principles. Let's break down the implications of the advice given, especially with the examples:
Ambiguous / Potentially Problematic Advice in the Request:
-
Omitting the Document's Own Title:
- Request: "Omit ONLY the exact heading/text that duplicates this title." and "Begin your output with the first genuine content... never with a heading that just restates the document's own title."
- Implication: This is a common requirement in CMS systems where the document title is added automatically at a higher level (e.g., as the
<h1>of the webpage). In this specific context, it's a practical instruction for content integration. - Potential Problem from a Pure Accessibility Standpoint: If the markdown were to be consumed as a standalone document (e.g., downloaded as a
.mdfile, or rendered without a CMS), it would lack its primary<h1>heading. A document should have an<h1>that describes its main topic. The request, however, explicitly forbids<h1>altogether and mandates omitting the title. - Conclusion: For this specific request, follow the instruction. It implies a specific web environment.
-
Custom IDs for Numbered Sections Only (
{: #id }):- Request: "Use
{: #id }syntax for numbered sections only. Regular headings like 'Governance' get auto-generated IDs." - Implication: This is a stylistic choice related to how the target website generates IDs.
- Potential Problem: This implies that all headings (numbered or not) would ideally have stable, predictable IDs for linking. Relying on "auto-generated IDs" can be less robust if the generation logic changes or if specific external links are needed that target unnumbered headings.
- Conclusion: Follow the instruction for this request. It's a specific formatting rule for the desired output.
- Request: "Use
-
HTML Ordered Lists with
type="a|A"andmarkdown="1":- Request:
<ol markdown="1" type="a">and<ol markdown="1" type="A"> - Implication: This is for styling lists that use alphabetical numbering (a, b, c or A, B, C) in the PDF. The
markdown="1"is crucial for parsing markdown inside HTML blocks, which is excellent. - Potential Problem from a Pure Accessibility/Semantic Standpoint: While
typeattribute for<ol markdown="1">is technically valid in HTML5, the modern, semantically preferred way to achieve alphabetical numbering is purely through CSS. HTML should describe structure, not presentation. Screen readers might announce "list item A" or "list item 1" depending on implementation, buttype="a"doesn't inherently convey a semantic difference from a numerical list, only a presentational one. For accessibility, the order is paramount, and numericaltype="1"is the default and clearest. If the alphabetization implies a categorization rather than an order, then an unordered list (<ul markdown="1">) with custom text could be more semantic. However, given the examples, it's clearly for presentation of ordered lists. - Conclusion: Follow the instruction. It's a specific requirement for styling.
- Request:
-
Wrapping All Tables in
<div class="table-container" markdown="1">:- Request:
<div class="table-container" markdown="1">...</div> - Implication: This is for styling, specifically to enable horizontal scrolling for wide tables on small screens, which is a common and good practice for web responsiveness.
- Potential Problem: None from an accessibility perspective, as long as the table itself remains semantically correct (
<table>,<thead>,<tbody>,<th>,<td>). - Conclusion: This is good practice for responsive tables. Follow it.
- Request:
-
Numbered Paragraphs with
<a class="section__global-number" href="#paragraph-N" id="paragraph-N">N</a>Content...:- Request: "Create self-linking anchor tags:
<a class="section__global-number" href="#paragraph-N" id="paragraph-N">N</a>Content goes here..." - Implication: This is an attempt to make specific paragraphs individually addressable via URLs (deep linking), which is a fantastic accessibility and usability feature.
- Potential Problem: While well-intentioned, inserting
<a>tags around the number but within the paragraph flow (<p><a...>N</a...></p></a>Content) can sometimes cause issues with screen readers perceiving the paragraph content as split or interrupting the natural flow if the link is only around the number. A more robust semantic approach might involve using an actual heading for each numbered item if it's a significant conceptual chunk (even if visually rendered like a paragraph), or if deep linking to paragraphs is critical, ensuring the<a>tag wraps the entire paragraph content or is a<span>witharia-labelledbyor similar for the number, making it clear it's part of the same paragraph. - However: The request's example explicitly shows the
<a>wrapping only the numberN. This means theNitself becomes a clickable link to that specific paragraph's anchor. This pattern is often used in legal/standard documents. It's acceptable, but should be done carefully. - Conclusion: Follow the instruction for this specific pattern. It's a very specific implementation detail for numbered paragraphs in this context.
- Request: "Create self-linking anchor tags:
-
Blockquote Formatting (
<blockquote markdown="1">):- Request: "Do NOT wrap the entire blockquote content in
**bold**-- only use bold for specific emphasized words/phrases that are bold in the original PDF." - Implication: Good advice.
<blockquote markdown="1">is for semantic quotation, not for making text bold. Excessive bolding within a blockquote hinders readability and screen reader experience, as it implies all content is equally important, negating the purpose of selective emphasis. - Conclusion: This is unequivocally good accessibility practice.
- Request: "Do NOT wrap the entire blockquote content in
Overall Assessment:
The instructions are very detailed and provide a specific conversion framework for a particular CMS or web platform. While some points might raise semantic eyebrows from a pure HTML/accessibility purist perspective (e.g., <h1> omission, type attribute on ol), they are clearly requirements for this task, suggesting a pre-defined rendering environment. The critical instructions regarding hyperlinks, tables, markdown="1", and heading hierarchy are all aimed at creating a robust, accessible, and semantically consistent output within the given constraints.
The anti-pattern examples are particularly helpful in clarifying what not to do, reinforcing the importance of semantic hierarchy and not inventing data.
My task is to follow these instructions precisely. I will focus on:
* Accurate heading levels and their specified ID syntax.
* Correct table and list rendering, including the HTML wrappers.
* Precise hyperlink conversion (only explicit links).
* Correct image replacement.
* Footnote handling.
* Strict adherence to the title omission rule.
* No <h1> and no skipped heading levels.
* Preserving all substantive content.
This is a well-defined and comprehensive set of instructions.26 June 2025 Agenda Paper 5 OFFICIAL - PUBLIC
Executive Summary
Project Stage
| IASB | Research / Pipeline | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Type
Endorsement and adoption
Project Scope
Moderate
Purpose of the paper
In December 2024, the International Accounting Standards Board (IASB) published Amendments to IFRS 9 and IFRS 7 - Contracts Referencing Nature-dependent Electricity (the Amendments). This paper summarises the feedback received from stakeholders during the recent Draft Endorsement Criteria Assessment (DECA) consultation in respect of the endorsement of the Amendments for use in the UK.
The Board is asked to consider whether the feedback received should lead to any change to the draft endorsement assessment before finalisation of the Endorsement Criteria Assessment (ECA).
Summary of the Issue
The DECA was published by the UKEB on 10 March 2025, following approval at the February 2025 Board meeting. The public consultation was open for comment until 9 June 2025. Five written responses were received to the consultation and were uploaded on the UKEB website. All support the endorsement of the Amendments.
In addition, the UKEB also consulted with UK stakeholders and subject matter experts on the DECA, including the Financial Instruments Working Group, the Accounting Firms & Institutes Advisory Group, the Investor Advisory Group and the Preparer Advisory Group. The Secretariat also convened a round table discussion which was attended by several members of the Rate-regulated Activities Technical Advisory Group. We provided the Academic Advisory Group with a brief update on the project and the DECA. Overall, feedback from consultation was supportive of the UKEB's draft assessment of the Amendments against the endorsement criteria. However, some suggested improvements to the analysis in the DECA. Where relevant, some changes are proposed for inclusion in the in the final ECA for the Board to consider (see Appendix A).
Decisions for the Board
Does the Board agree with the Secretariat's proposed response (see Appendix A to this paper) to the stakeholder feedback received on the DECA?
Recommendation
We recommend the Board makes certain, limited changes to the text of the ECA as specified in Appendix A.
Appendices
Appendix A Summary of feedback received on the DECA
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
The key changes and requirements which have been introduced by the Amendments and assessed in the DECA are summarised below.
- The Amendments apply only to contracts which reference nature-dependent electricity. Such contracts expose an entity to variability in the contracted volume of electricity which is generated from natural sources which cannot be controlled.
- The Amendments clarify the requirements of the 'own-use' exception included in paragraph 2.4 of IFRS 9 Financial Instruments for contracts to purchase nature-dependent electricity.
- The Amendments permit the application of cash flow hedge accounting to hedging relationships in which the hedged item is a variable amount of forecast electricity transactions, and the hedging instrument is a contract referencing nature-dependent electricity.
- The Amendments require entities to disclose information about their contracts referencing nature-dependent electricity.
Appendix A: Summary of feedback received on the DECA for Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
| Respondent1 | Feedback summary |
|--------------------------------------|------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| Preparer Advisory Group
3 March 2024 | - Members were asked for their views on the unapproved version of the DECA which was very similar to the final approved version which was published for comment on 10 March.
- The majority of PAG members did not have contracts in scope of the Amendments. However, one member was of the view that the disclosures required for contracts meeting the 'own-use' exception would be onerous and costly to provide. | The DECA acknowledges that stakeholder feedback on the cost of disclosures has been mixed, but that in most cases, the cost of disclosures is not expected to be significant or higher than the cost of obtaining a fair valuation for the relevant contracts.
No changes proposed in the final ECA. |
| Accounting Firms & Institutes Working Group
11 March 2024 | - Overall, members were supportive of the Amendments and were of the view they were capable of being applied in practice. | Although members were of the view that the hedge accounting Amendments might constitute a change in accounting practice, the general feedback from the DECA consultation has been that due to its optional nature this change is unlikely to be significant.
The Secretariat recommends the technical criteria assessment of the scope of the Amendments in the ECA be modified to refer to paragraph 2.3B of the Amendments. |
| | - Members agreed with the assessment in the DECA that the own-use Amendments were unlikely to lead to a significant change in accounting practice.
- However, members noted that the hedge accounting Amendments might constitute a change in accounting practice, as hedge accounting would potentially be available for certain contracts where it had not previously been the case.
- Members agreed that the Amendments removed a barrier to the use of contracts referencing nature-dependent electricity, as set out in the long term public good assessment in the DECA.
- Members did not have significant concerns about entities failing the net purchaser assessment due to one-off reductions in demand and having to fair value contracts for their remaining lives. One AFIAG member noted that the twelve-month cap on the backward-looking net-purchaser assessment was sufficiently broad to take account of fluctuations in electricity demand. | |
| Investor Advisory Group
2 June 2024 | - One member highlighted the importance of paragraph 2.3B of the Amendments which states that an entity shall not apply the Amendments to IFRS 9 "by analogy to other contracts, items or transactions."
- Members were of the view that the own-use and hedge accounting amendments would provide useful information. One member observed that the additional disclosures required under the own-use amendments might provide more useful information than a fair valuation at a single point in time.
- When asked, no members expressed disagreement with the tentative conclusions in the DECA that the Amendments are unlikely to have an adverse effect on the UK economy and may remove a barrier to the use of contracts referencing nature-dependent electricity. | No changes proposed in the final ECA. |
| Financial Instruments Working Group
1 April 2025 | - Overall, members were supportive of the Amendments and were of the view they were capable of being applied in practice. | No changes proposed in the final ECA. |
| Roundtable with subject matter experts
27 March 2025 | - Members agreed with the assessment in the DECA that the Amendments were unlikely to lead to a significant change in accounting practice.
- Overall, stakeholders were supportive of the Amendments and were of the view they were capable of being applied in practice.
- Twelve months was considered to be a sensible window for making the backward-looking net-purchaser assessment.
- Members agreed with the assessment in the DECA that the Amendments were unlikely to lead to a significant change in accounting practice. | No changes proposed in the final ECA. |
| Response 1
Deloitte LLP | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 2
ICAEW | Agrees with the assessment in the DECA and supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 3
Grant Thornton UK LLP | Agrees with the assessment in the DECA and supports endorsement of the Amendments.
The response agrees with the assessment in the DECA that the application of the own-use requirements in the Amendments will be subject to ongoing judgements, for example, in relation to evolving technology. The response notes that the Amendments in “IFRS 9 B2.7 allow for this ongoing assessment as technology evolves”.
The response acknowledges the inevitable complexity associated with applying the hedge accounting Amendments but states that “in our view, this complexity does not prevent the amendments from being capable of being applied in practice".
The response also states that as the Amendments "are narrow in scope, and in our experience, only a limited number of entities have entered into these contracts to date, we agree that the amendments are not likely to lead to a significant change in practice." | No changes proposed in the final ECA. |
| Response 4
PwC | Agrees with the assessment in the DECA and supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 5
KPMG | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Accounting firm verbal feedback | Page 30 of the DECA states that feedback from stakeholders suggests that “the Amendments may effectively remove a barrier for entities wishing to enter into a contract referencing nature-dependent electricity".
The ability to apply hedge accounting may in turn allow entities to enter such contracts and reduce entities' exposure to electricity price volatility. | The Secretariat recommends the relevant paragraph in the ECA be modified to address this point. |
| Accounting firm verbal feedback | Page 17 of the DECA states "The Amendments require disclosure of qualitative information about how an entity “assesses whether a contract might become onerous...including the assumptions the entity uses in making this assessment.” At present, entities only provide information about commitments which have already become onerous, so this disclosure is expected to provide useful information about the potential for relevant contracts to become onerous and the long-term exposures of such contracts."
However, this may not be the case for those contracts which are currently accounted for at fair value but are expected to meet the own-use exception as a result of the Amendments. For these contracts, entities will already be providing some disclosures about Level 3 inputs as required by IFRS 13 Fair Value Measurement. | The Secretariat recommends the relevant paragraph in the ECA be modified to address this point. |
Question for the Board
Does the Board agree with the Secretariat's proposed response to the stakeholder feedback received on the DECA?
Next steps
- The adoption package for the Amendments will be presented to the Board at its July 2025 public meeting and a tentative indicative vote on whether to adopt the Amendments for use in the UK will be taken at that meeting.
- Subject to feedback received from the Board on this paper, the ECA will reflect the drafting recommendations in the table above.
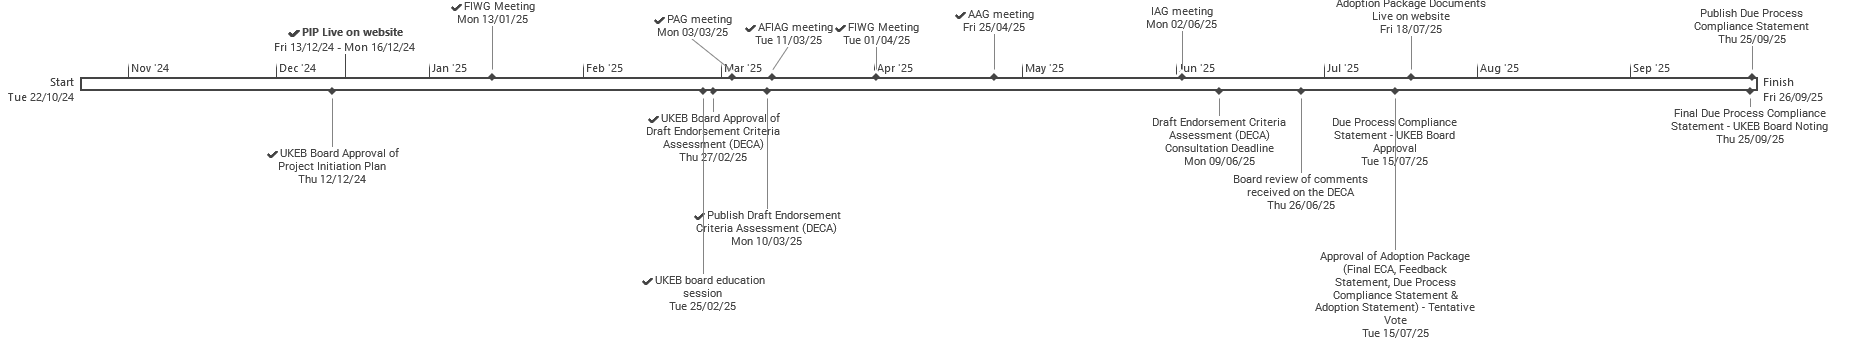
The high-level project timeline is shown below.
| Date | Milestones |
|---|---|
| 12 December 2024 | Draft Project Initiation Plan for Board approval. |
| 30 January 2025 | Technical papers for discussion at Board meeting. |
| 27 February 2025 | DECA for Board approval. |
| DECA consultation period: 10 March – 9 June 2025 | |
| 26 June 2025 | Board review of feedback received on the DECA. |
| 15 July 2025 | Consideration of Adoption Package. Board members provide a tentative vote. |
| Second half of July | Voting form sent to Board members. Publication of voting outcome and Adoption Package on the UKEB website. |
| 25 September 2025 | Due Process Compliance Statement for noting. |
Endorsement and adoption timeline
Footnotes
-
Although the Academic Advisory Group received an update on the project and the DECA on 25 April 2025, the members did not provide any feedback.