UKEB ISSB ED Webinar Slides
UKEB 30 June 2022
The views expressed in this presentation are those of the presenters and not necessarily those of any organisation, nor are they necessarily reflective of any official government policy or position.
1. Welcome
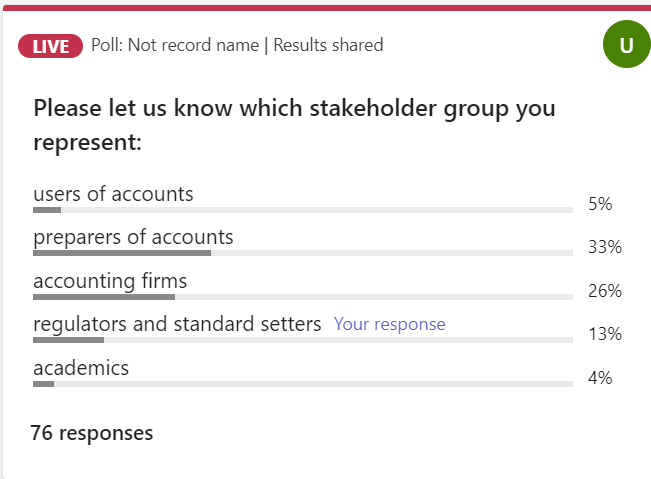
First Audience Poll
Please let us know which stakeholder group you represent:
- users of accounts
- preparers of accounts
- accounting firms
- regulators and standard setters
- academics
- none of the above
2. Regulatory Overview
UK Endorsement Board: Influencing functions
IFRS Accounting Standards
A diagram illustrating the flow: UK stakeholders → UKEB → IASB, representing the endorsement and adoption process.
IFRS Sustainability Disclosure Standards
A diagram illustrating the flow: UK stakeholders → UKEB → IASB and ISSB, representing the endorsement and adoption process.
The UKEB is responsible for endorsement and adoption of IFRS accounting standards for use in the UK
BEIS has requested that the UKEB consider the overlap of the proposed ISSB sustainability disclosure standards with those issued by the IASB.
Cross government views
 BEIS
Debbie Crawshawe
Accounting Expert
 FCA
Mark Manning
ESG and Policy Lead
 UKEB
Seema Jamil-O'Neill
Technical Director
 FRC
Sarah-Jayne Dominic
Policy, Programmes & Strategy
BEIS: SDR Regime
- SDR will create a flow of sustainability-related information from corporates through the financial system, enabling more efficient capital allocation and reducing greenwashing.
Greening Finance: A Roadmap to Sustainable Investing
Publication cover with the title, date (October 2021), and "HM Government" logo, representing a roadmap to sustainable investing.
- For corporates, SDR consists of two main elements
- Green Taxonomy
- International Sustainability Standards
- BEIS will be consulting later this year
FCA: Transparency along the value chain...
TCFD Financial Disclosures and FCA Document:
A document cover for "Proposals to enhance climate-related disclosures by listed issuers and clarification of existing disclosure obligations" (Policy Statement PS20/17, December 2020), featuring the TCFD and FCA logos.
"Better corporate disclosures will help inform market pricing and support business, risk and capital allocation decisions..."
IFRS Sustainability Exposure Draft:
A document cover for "Exposure Draft IFRS® Sustainability Disclosure Standard" ([Draft] IFRS S2 Climate-related Disclosures, March 2022), with comments due by 29 July 2022.
"...once the ISSB's future standards are endorsed for use in the UK, we expect, subject to consultation, that both the Companies Act and Listing Rules will reference the endorsed international standards directly”
"... the appropriate time to consult on introducing mandatory climate-related disclosure requirements will be alongside proposals to adapt our rules to reference a UK-endorsed ISSB standard in our framework instead of the TCFD's recommendations"
"The proposals... build upon the recommendations of the Task Force on Climate-Related Financial Disclosures (TCFD)..."
"IOSCO sees urgent need for global consistent, comparable and reliable sustainability disclosure standards”
IOSCO welcomes the publication of the ISSB's two proposed IFRS Sustainability Disclosure Standards. We will review the proposals, with the objective to endorse them for use by our member jurisdictions.
"Independent assurance is a cornerstone to building trust in the information that underpins capital markets"
Endorsement by IOSCO can pave the way for adoption of the Standards around the world, delivering much-needed consistency and comparability in sustainability-related information to the capital markets
Ashley Alder, Chair of the IOSCO Board, March 2022
Report on Sustainability-related Issuer Disclosures
A document cover for the "Report on Sustainability-related Issuer Disclosures, Final Report" by OICU-IOSCO.
UKEB - Draft Comment Letter: areas for consideration
| Topics | Areas for further consideration? |
|---|---|
| Definition / boundaries | Should the term 'sustainability' be defined? Are the boundaries clear enough? |
| Global baseline | Must be ambitious but also must be achievable for all. |
| Business model | Is this prominent enough for users? |
| Materiality v Significant | Is two better than one? |
| Connectivity | Recognition, measurement and timeframes differ from accounting |
| Pace of change | Legislative pace, phasing and proportional considerations |
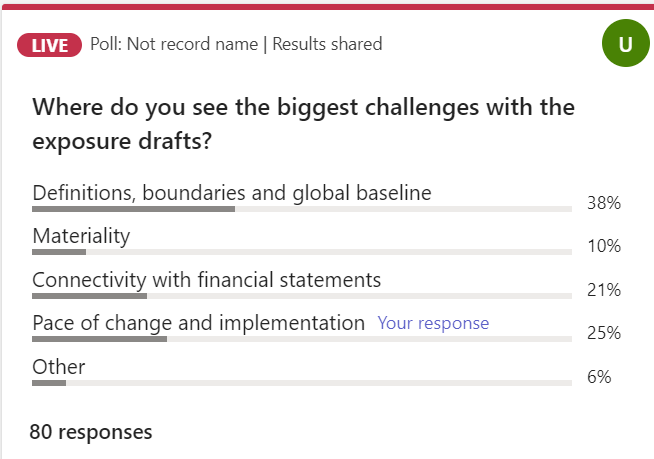
Second Audience Poll
Where do you see the biggest challenges with the exposure drafts?
- Definitions, boundaries and global baseline
- Materiality
- Connectivity with financial statements
- Pace of change and implementation
- Other
FRC: Sustainability reporting ecosystem
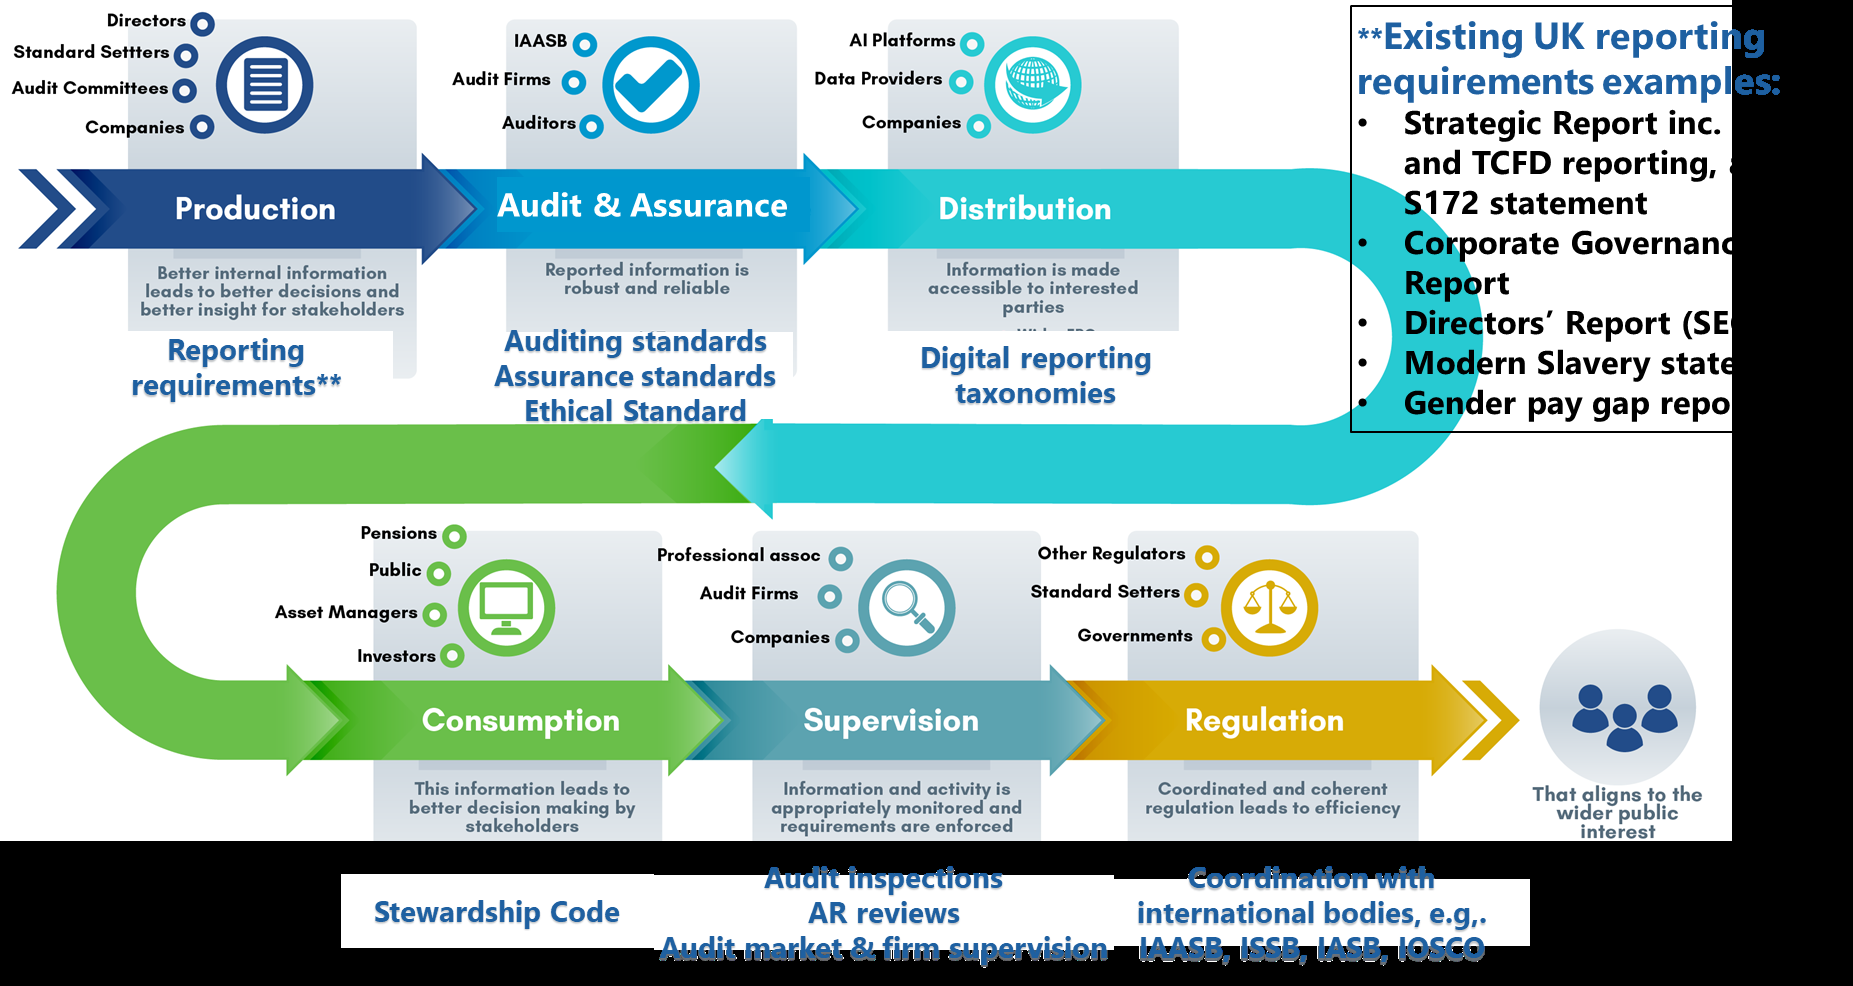
Existing UK reporting requirements examples:
- Strategic Report inc. NFSIS and TCFD reporting, and S172 statement
- Corporate Governance Report
- Directors' Report (SECR)
- Modern Slavery statement
- Gender pay gap reporting
3. Panel Discussion
Panel Moderator
 Jane Fuller
Visiting Professor at City,
University of London,
Fellow CFA UK
 FCA
Mark Manning
ESG and Policy Lead
 UKEB
Seema Jamil-O'Neill
Technical Director, Chair
 ISSB
Lois Guthrie
Senior Technical Advisor
 ICGN
Christine Chow
Board member
 Federated Hermes
Louise Dudley
Portfolio Manager
 Barclays Bank
Gerbrand Muller
Head of Finance for Sustainability and ESG
 United Utilities
Sabrina Curry
Investor Relations
4. Q&A from the audience
Questions submitted at event registration
We received 30 'burning questions' from attendees upon registering for the event.
A diagram illustrating "Questions submitted at event registration" grouped around three core areas:
Implementation: * Due process v speed of delivery * Timeline * Companies in scope * Transition relief * UK endorsement process (4)
Global baseline
Scope: * Achieving jurisdictional alignment (4) * UK subsidiaries of foreign entities * Are SASB standards mandatory or guidance? * Disclosure of all significant sustainability risks and opportunities?
5. Wrap Up
Wrap Up and Next steps
An icon depicting a conference table with chairs, representing a meeting.
Presentation of final comment letter to the 18 July public UKEB Board meeting for review and approval
An icon depicting a laptop with a globe on the screen, representing online submission or publication.
Submission of the final letter to the ISSB by 29 July and publication on UKEB website
UK Endorsement Board: how to get involved
An icon of a megaphone, representing alerts or announcements.
Sign up for subscriber alerts at [email protected]
An icon of an envelope, representing email communication.
Email to express your interest in outreach on a particular project at [email protected]
An icon of a laptop with a globe on the screen, representing a website.
Follow projects and developments on the UKEB website www.endorsement-board.uk
An icon of linked circles, representing a social media network.
Follow us on LinkedIn
Thank You
UK Endorsement Board 1 Victoria Street | London | SW1H 0ET https://www.endorsement-board.uk/ [email protected]