7 IFRS Foundation Due Process Handbook
27 February 2025 Agenda Paper 7 UKEB UK Endorsement Board
Executive Summary
Project Stage
| IFRS Foundation | Research | Exposure Draft | Redeliberation | Final DPH Published |
|---|---|---|---|---|
| UKEB | Monitoring | Influencing | Monitoring | - |
Project Type
| Project Type | Influencing - Strategic |
|---|---|
Project Scope
| Project Scope | Limited |
|---|---|
Purpose of the paper
The purpose of this paper is for the Board to:
- Comment on and approve the proposed Project Initiation Plan (PIP) for the project to influence the IFRS Foundation's Exposure Draft (ED): Proposed Amendments to the IFRS Foundation Due Process Handbook.
- Comment on the points being considered for inclusion in the UKEB's Comment Letter to the IFRS Foundation, as set out in Appendix B.
- Approve the publication of the PIP on the UKEB website and the circulation of the appendix to the members of the UKEB advisory and working groups for comment.
Summary of the Issue
The IFRS Foundation's Exposure Draft Proposed Amendments to the IFRS Foundation Due Process Handbook (the Handbook) aims to:
- reflect the establishment of the International Sustainability Standards Board (ISSB) and formally set out its due process.
- make other enhancements and clarifications to the existing requirements in the Handbook.
Project Initiation Plan and issues proposed for inclusion in the Comment Letter
The PIP proposes a proportionate approach to developing the UKEB's response to the Exposure Draft. The IFRS Foundation's due process has a direct impact on how the UKEB carries out its own statutory functions, including compliance with its own due process requirements. This means that, unlike other IFRS Foundation due process documents, the UKEB, as the National Standard Setter, – rather than preparers, investors, auditors, etc – can be considered the primary stakeholder to respond to the proposed changes in this ED. Therefore, the PIP proposes a limited scope project that does not include formal outreach with stakeholders, beyond consultation with the UKEB Advisory and Working Groups.
Given the limited scope of this ED's proposals, a high-level list of issues proposed for inclusion in the UKEB's Comment Letter is included at Appendix B for the Board's consideration. Any other significant issues, identified by the Board during the meeting, will be incorporated into this list and the UKEB's (final) comment letter before finalisation.
Subject to Board approval at this meeting, the PIP will be published on the UKEB website. An updated version of Appendix B, incorporating any comments at this meeting, will be sent to the UKEB advisory and working group members, via email, for their comments and views.
Decisions for the Board
Subject to addressing any comments raised at the meeting does the Board approve:
- the PIP for publication on the UKEB website?
- Appendix B for circulation to the members of the UKEB's advisory and working groups for comment?
Recommendation
The Secretariat recommends that the Board approves:
- the PIP for publication on the UKEB website; and
- Appendix B for circulation to the members of the UKEB's advisory and working groups for comment.
Appendix
Appendix A Project Initiation Plan Appendix B Points proposed for inclusion in the UKEB (Final) Comment Letter
Proposed Amendments to the IFRS Foundation Due Process Handbook
On 19 December 2024, the Trustees of the IFRS Foundation published the ED Proposed Amendments to the IFRS Foundation Due Process Handbook proposing amendments to the IFRS Foundation Due Process Handbook.
Primarily, the amendments reflect the creation of the ISSB and formally applies the IFRS Foundation's due process to its operations. However, the amendments also include enhancements and clarifications to the Handbook, based on the Foundation's recent experiences.
The main proposed changes to the Handbook are set out below:
Reflecting the ISSB in the Handbook:
The ED inserts references to the ISSB to formally confirm that the Handbook now applies to the IASB, the ISSB and the IASB's Interpretations Committee. Additional amendments aim to build connectivity between the two boards into the due process requirements in order to create a cohesive framework and to ensure consistency and clarity for stakeholders.
The specific due process for the SASB standards and taxonomy is inserted at Annex B.
Enhancements and clarifications
Further enhancements and clarifications are proposed throughout the Handbook, including, inter alia:
- amendments to the objective and timing of PIRs;
- amendments to the requirements for annual improvements, to specify that they may include minor or narrow-scope amendments that update a requirement or material accompanying an IFRS Standard;
- changes to some of the titles used (e.g. 'annual improvements' and 'educational material'); and
- changes to the text to clarify existing processes.
Other targeted amendments
There are twelve other areas where small enhancements and clarifications are made, including, inter alia:
- requiring the DPOC to review the due process a board followed before a major new IFSR Standard or Amendment is issued;
- allowing surveys to be used to collect responses to formal consultations; and,
- explaining how boards may build on the work of other standard-setters;
The consultation closes on 28 March 2025.
Appendix A: Project Initiation Plan: Proposed Amendments to the IFRS Foundation Due Process Handbook (Exposure Draft)
Purpose
A1This paper sets out the plan to influence the proposed amendments to the IFRS Foundation Due Process Handbook (the Handbook) included in the IFRS Foundation's Exposure Draft (ED) Proposed Amendments to the IFRS Foundation Due Process Handbook. The ED was published on 19 December 2024 with a consultation period ending on 28 March 2025.
A2The UKEB is responding to this ED as the content of the Handbook impacts how the UKEB engages with and influences the IFRS Foundation, its boards and committees, in carrying out its own statutory duties.
A3The IFRS Foundation last updated the Handbook in August 2020. The ISSB started operating in 2022, after the current Handbook was issued. It does not, therefore, reference the ISSB's work directly.
A4For over two years, the ISSB has been applying the due process set by the IFRS Foundation, in the current Handbook, for the International Accounting Standards Board (IASB) to follow. However, the Due Process Oversight Committee (DPOC) of the Trustees of the IFRS Foundation has now decided to formally specify that the IASB and ISSB are applying the same due process, as set out in the Handbook.
A5The DPOC is also using this opportunity to propose targeted enhancements and clarifications to the Handbook, based on the Foundation's recent experiences.
Summary of proposed changes
A6The DPOC is of the view that the current due process is robust and thorough, and that the 2020 amendments are working well. Accordingly, the ED's proposed amendments are enhancements and clarifications, rather than fundamental changes to the Foundation's due process. The most extensive changes are set out in the sections below.
Reflecting the ISSB in the Handbook
A7The proposed amendments update the Handbook to include references to the ISSB. However, the DPOC intends to continue to monitor the need for changes or additions to the due process as it notes the ISSB is still at an early stage in its operations and, both boards are at an early stage in their connectivity work.
SASB Standards
A8The ED also proposes adding a new Annex B1, setting out the due process for the SASB Standards and the SASB Standards Taxonomy. While they are not IFRS Standards, IFRS S1 requires that entities applying that standard must consider SASB Standards for sustainability-related risks and disclosures.
A9The due process set out in the new annex was approved by the DPOC and published on the Foundation's website in 2022. The due process allows the SASB Standards Board Adviser Group to develop amendments to the SASB standards, for ratification by the ISSB.
A10The ED does not propose any changes to formally incorporate the SASB Standards as ISSB industry-based standards, which have been through full due process.
Reflecting Connectivity
A11A new IFRS Foundation objective is proposed, which is that the IASB and ISSB develop complementary sets of Standards.
A12Several proposed amendments to the Handbook focus on enhancing the integration between the IASB and ISSB; and strengthening the connections between the boards and their respective standards. Together, the amendments aim to provide a cohesive framework for the development and implementation of the two boards' standards, ensuring consistency and clarity for stakeholders.
Post-implementation Reviews
A13The requirements for a Post-implementation Review (PIR) were not substantively amended in the 2020 update. At that time, the IASB had only conducted 3 PIRs. Subsequently, the Foundation has gained more experience from PIRs on major IFRS Accounting Standards. The DPOC monitored these developments, through its oversight of the IASB's PIRs, and proposes reflecting them in the Handbook. The amended requirements will also apply to the ISSB when it undertakes PIRs on its standards.
A14The proposed amendments include setting an objective for PIRs: “to assess whether the effects of applying the new Standard / major amendments are as intended when developed".
A15The ED also proposes starting a PIR “after the requirements have been applied for some time to ensure information is available to assess the requirements' effects in their entirety.. (while balancing the need to conduct a review within a reasonable period of time to ensure the relevant board is aware of matters that require attention)". This will replace the current requirement of commencing work two years after international application (around 30-36 months after the effective date).
Invitation to Comment
A16The Invitation to Comment (ITC) asks two questions:
- Do you agree with how the DPOC proposes to reflect the creation of, and the due process for, the ISSB in the Handbook?
- Do you agree with the proposed enhancements and clarifications to the Handbook?
Project Plan
A17As this project does not respond to a paper issued by either the IASB, ISSB or IFRIC, it is not specifically covered by the UKEB's Due Process Handbook. However, the proposed approach aligns with the due process requirements for technical influencing projects, made proportionate to the non-technical nature by including two slight variations:
- The UKEB will not publish a Draft Comment Letter (DCL). Instead, the Board will agree a list of the main points to be included in the Comment Letter.
- There will be no formal stakeholder outreach via the publication of a DCL. Instead, the list of issues to be referenced in the (Final) Comment Letter will be sent, via email, to the members of the UKEB's Advisory and Working Groups for comments and views, in time for preparation of the UKEB's (F)CL.
A18A proportionate approach has been applied in accordance with paragraphs 3.7 and 5.3 of the UKEB's Due Process Handbook. The Secretariat recommends the 'Limited scope' project plan shown below. The factors considered, in arriving at this project plan, are described in paragraphs A19-A25. A timeline for the key project milestones is presented in paragraph A30.
Project - key activities
| Key activities | Due Process Handbook |
|---|---|
| Board Education Session (complete) | 4.10b |
| Optional | |
| Creation of a Project Initiation Plan (this document) | 5.4-5.8 |
| Mandatory | |
| Desk-based research to support the proportionality assessment including: | |
| a) Review of UKEB Due Process Handbook and other organisations due process requirements. | 5.9 |
| b) Review of DPOC papers, presentations and meetings. | Optional |
| Stakeholder outreach pre-PIP | |
| a) The list of issues to be considered for inclusion in the UKEB's Comment Letter were discussed with UK and international bodies with an interest in this project, including Government and regulators. | |
| b) In addition, the project was highlighted as an item for noting at the meeting of the UKEB Investor Advisory Group, which was scheduled during the period between the Board Education Session and the February 2025 Board meeting. | 5.10-5.12 |
| Mandatory | |
| Stakeholder outreach post PIP | |
| a) The list of issues to be included in the UKEB's Comment Letter will be circulated, via email, to all the members of the UKEB Advisory and Working Groups, for comment. | |
| b) In addition, the project will be highlighted as an item for noting at the forthcoming meetings of the UKEB Advisory Groups2 that are scheduled for the period between the February 2025 and March 2025 Board meetings. | |
| (Final) Comment Letter | |
| A (final) comment letter will be created for Board approval, submission to the IASB, and publication on the UKEB website. | 5.18 |
| Mandatory | |
| Project Closure | |
| A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. | 5.19-5.26 |
| Mandatory |
Proportionality assessment
Significance and size
A19The UKEB is the primary stakeholder for this project, as the IFRS Foundation's due process directly impacts how the UKEB carries out its statutory functions and adheres to its own due process requirements.
Complexity
A20The proposals are intended to formally apply the same due process requirements to the ISSB, as the IASB, and to provide both boards (and the IASB's Interpretations Committee) with an enhanced and clarified due process. As such, we do not believe that the proposals are highly technical or complex.
Expected timeline / urgency
A21There is no indication of any need for urgent resolution or accelerated timeline in the UK.
Expected interest / sensitivity
A22There is no indication of wider UK stakeholder concerns in relation to this project.
Feedback on the proposals from desk-based research / initial outreach
A23Engagement with other UK bodies with responsibility for areas of UK company reporting confirmed that the content of our respective letters is not expected to be contradictory.
A24Review of the UKEB's Due Process Handbook3 (DPH) highlighted the following differences from the proposals in the ED:
- PIRs – the proposed objective of the PIR is “to assess whether the effects of applying the new Standard / major amendments are as intended when developed". This differs from the UKEB's DPH, which states that the objective of our PIRs is to “assess the impact of adoption".
- PIRs – the ED proposes removing the requirement for PIRs to commence after the new requirements have been applied internationally for 2 years. In the UK, legislation4 sets out the requirement that PIRs must be carried out for any Standard considered likely to lead to a significant change in accounting practice. A report of the review's conclusions must be published no later than 5 years after the date on which the standard takes effect.
Connectivity
A25The ED proposes amendments to the Handbook to improve connectivity between the boards and their respective sets of Standards.
Recommended UKEB project scope
A26Based on the proportionality assessment above we recommend a 'Limited' project scope, and the approach described in this document reflects this.
Resources allocated
A27To undertake the activities described in this project plan, a Project Director – Governance Lead has been assigned for the brief period of the project. The required resources are allowed for in the 2025/26 UKEB plan and budget.
A28In addition, some input from the economics team has been allocated, to develop the UKEB's recommendations regarding the IFRS Foundation's approach to undertaking impact assessments.
Setting up an ad-hoc advisory body
A29The UKEB will not require a separate ad-hoc advisory body for this project. Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted, as outlined in the project plan.
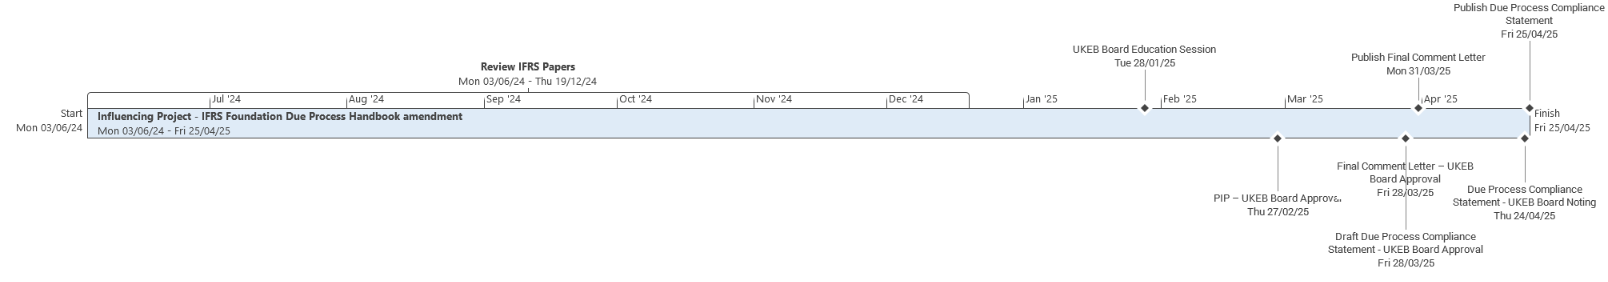
Project Initiation Plan: Proposed amendments to the IFRS Foundation Due Process Handbook (Exposure Draft) - Project timeline.
A30The diagram below is a graphical view of the mandatory milestone activities described above.
Appendix B: Points proposed for inclusion in the UKEB (Final) Comment Letter
Reflecting the ISSB in the Handbook [ED page 5]
Annex B – SASB Standards
B1To be considered internationally applicable and adoptable, the SASB Standards should be subject to the usual due process steps applied to all IFRS Standards.
B2This would align with the proposed new requirement, at paragraph 6.6 of the amended Handbook, which specifies that materials from other standard-setting bodies which “might have been subject to consultative procedures during their development” still require “the board to apply the Foundation's due process to any proposed requirements incorporating such material”.
B3It is important that a transparent process is followed for appointing members to committees or groups involved in the development of SASB Standards. In addition, for the development and ratification of the SASB Standards to meet the criteria of public accountability, the process for technical decisions should be transparent. This includes the Standards being discussed at public meetings and the papers for those meetings being published
Connectivity [ED page 6]
B4We are broadly supportive of the proposals to formalise connectivity between the boards and their respective sets of standards.
B5In practice, sustainability disclosures are now being prepared by finance departments, leveraging their experience with control environments, external reporting and engagement with auditors. To avoid consultation fatigue, or disjointed approaches from the two boards, connectivity and co-ordination between the boards is critical.
B6Paragraph 6.25 proposes that the steps taken to develop Standards compatible with the other board's Standards, are summarised by the technical staff at the end of a standard-setting project. While this is a helpful addition, we suggest that the relevant board should also be required to consider and discuss potential connectivity matters at the start of the standard setting process and to monitor these periodically during its deliberations.
Post-implementation Reviews (PIRs) [ED page 7]
B7The current Handbook states that a PIR "is an opportunity to assess the effect of the new requirements". The ED sets an explicit objective for PIRs: "to assess whether the effects of applying the new Standard / major amendments are as intended when developed' [emphasis added]. The basis on which the "intention" can be determined is not clear, given standards have an objective.
B8Currently, PIRs are carried out 2 years after international application (around 30-36 months after the effective date). Paragraph 6.55 of the proposed amended Handbook sets out that a PIR will begin “after the new requirements have been applied for some time to ensure information is available to assess the requirements' effects in their entirety." This could lead to PIRs being delayed or postponed. Boards should consider whether sufficient information is available after two years. If not, the PIR should not be delayed beyond a further 3 years (5 years from the effective date).
B9Another way to address this may be that, for Standards or amendments which lead to a significant change in accounting practice the relevant board should set up a Transitional Implementation Group. The group could monitor international implementation issues and provide a more agile process for addressing them before excessive implementation costs have been absorbed by preparers.
B10[There is currently no provision for the boards to consider the body of their respective standards and carry out PIRs on older standards which may no longer meet stakeholder needs.]
B11If the SASB Standards are to be internationalised and become full IFRS Standards, they should also be within scope of the PIR process.
Interpretations Committee [ED page 8]
B12IFRIC is required, at paragraph 5.17, to consider four criteria when assessing the need for a standard-setting project. Criterion a) specifies "the matter has widespread effect" The ED proposes the following clarification: “that is, the circumstance or transaction is prevalent and there is diversity in the application of IFRS Accounting Standards". It would be helpful if "prevalence" was defined (e.g. by reference to the number and size of entities, relevant sizes of jurisdictional capital markets, etc).
B13IFRIC should have the ability to recommend a standard setting project where, after implementation, the accounting required by a new or amended Standard is leading to unintended or poor accounting outcomes (albeit the standard is clear).
B14The ED confirms that the Interpretations Committee only relates to the IASB and IFRS Accounting Standards. However, it would be helpful if the Handbook set out how connectivity issues will be considered by IFRIC and the TIG. A single, joint Interpretations Committee could be considered as a potential future option.
Surveys [ED page 11]
B15Paragraph 3.68 of the proposed amended Handbook adds provision for the boards to offer stakeholders the opportunity to respond to formal consultations by completing a survey.
B16The use of surveys may negatively impact the assessment of proposals and how stakeholder views are conveyed e.g. artificially narrowed range of responses, ineffective interpretation of results, and inaccurate analysis of the type of respondent and the weighting that should be attributed to them (i.e. the difference between individual respondents and large organisations or standard setters).
B17The survey format is also problematic for standard setters as the questions are only visible as a respondent proceeds through the survey. This makes it difficult for standard setters to consult with the full range of their own stakeholders (investors, preparers, accounting firms, auditors etc) on the content of the consultation, in formulating their own views in the response.
Re-exposure Criteria [ED page 11]
B18Paragraph 6.28 of the proposed amended Handbook should require the boards to consider stakeholder feedback, specifically from ASAF/SSAF, which provide views at the jurisdictional level, and relevant consultative groups, which may provide personal views, before making a final decision on re-exposure.
B19Paragraph 6.30 sets out that “the board weighs the cost of delaying improvements to financial reporting against the relative urgency to introduce changes". The approach of weighing cost against urgency may lead to inappropriate prioritisation decisions.
Workplan Consultation [ED page 11]
B20Workplan consultations should also reflect the boards formal and public assessment of the connectivity of the projects, proposed to be included on the agenda.
Additional points proposed for inclusion
Comment Periods
B21The boards' consultations need to be issued for a sufficient period of time to enable stakeholders to provide considered responses.
B22National standard-setters (NSS) are required to follow their own due process and often hold their meetings at the end of the calendar month. Setting consultation deadlines for the 1st of the month following the actual 90/120 day deadline would normally allow NSS to get FCLs approved at their own board meetings.
Impact assessments
B23The boards should also consider the timing of their consultations. For example, December is a popular year-end for listed companies (around 50% of UK listed entities have a December year-end5), and a holiday period for jurisdictions in both hemispheres. While the boards should be able to issue consultations at the end of the year, consideration should be given whether the length of the consultation makes accommodations for this, and the outreach engaged in during this period.
B24Further consideration may need to be given to how the two boards analyse the likely costs and benefits ("effects") of new requirements on affected parties as well as associated wider economic effects.
B25In describing how the IASB fulfils its Public Accountability duty, the proposed amended Handbook caters for an assessment of costs and benefits associated with new IFRS standards or amendments (paragraphs 3.77-3.82 - Effects Analysis). Economic effects are considered at all stages of the standard-setting process.
B26The Handbook includes considerations on the assessment of costs and benefits at the early stages of a project, but these are generic in nature. This results in analysis that is very qualitative in nature and can be based on tentative decisions, with no clarity on the actual requirements in the final standard, which can mean the actual impact of applying the standard is very different to that considered during its development.
B27In addition, paragraphs on the Effects Analysis (3.77-3.82) could be rearranged, be based on objective measures and grounded in economics to ensure that a sound evidence-based assessment is delivered.
Footnotes
-
Annex A - The IFRS Taxonomies due process; Annex B - The SASB Standards and the SASB Standards Taxonomy due process ↩
-
The UKEB Advisory Groups scheduled during the period between the February 2025 and March 2025 Board meetings are the Preparer Advisory Group (PAG) and the Accounting Firms and Institutes Advisory Group (AFIAG). ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (SI 2019/685 - Regulation 11) ↩
-
December is also the most common year-end in Canada (54%) and the EU (De, Esp, Ita, Fra) (88.9%) ↩