5 Contracts Referencing Nature-dependent Electricity (Amendments to IFRS 9 and IFRS 7)
27 February 2025 Agenda Paper 5
Executive Summary
Project Stage
| IASB | Research / Pipeline | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| UKEB | Research / Influencing | Research / Influencing | Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Scope
Moderate
Purpose of the paper
The purpose of this paper is to:
- Obtain Board feedback on the Draft Endorsement Criteria Assessment (DECA), and related Invitation to Comment (ITC) for the Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments).
- Request the Board's approval to publish the DECA and ITC on the UKEB website for stakeholder consultation for a 90 day comment period.
Summary of the Issue
The purpose of the DECA is to assess whether the Amendments meet the statutory criteria for adoption set out in SI 2019/685[^1] and to discharge the UKEB's statutory duty to consult those with an interest in the quality and availability of accounts, including users and preparers. The DECA includes:
- a description of the UK statutory requirements for adoption of new and amended international accounting standards.
- a description of the Amendments; and
- an assessment of whether the Amendments meet the statutory criteria for adoption.
An entity shall apply the Amendments for annual reporting periods beginning on or after 1 January 2026. Earlier application is permitted.
Questions and decision for the Board
- Does the Board have any comments on the tentative conclusion in paragraph 2.5 of the DECA that the Amendments are not likely to lead to a significant change in accounting practice?
- Does the Board have any comments on the DECA (Appendix A) or the Invitation to Comment (ITC) (Appendix B)?
- Does the Board agree that, subject to any amendments or additions required by the Board, the DECA and ITC can be published for public consultation?
Recommendation
Subject to any amendments or additions required by the Board, the Secretariat recommends that the Board approves the DECA and ITC for public consultation.
Appendices
Appendix A [Draft] Endorsement Criteria Assessment of Amendments to IFRS 9 and IFRS 7 - Contracts Referencing Nature-dependent Electricity. Appendix B DECA – Invitation to comment.
Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity
The key changes and requirements introduced by the Amendments[^2] are summarised below.
- The Amendments apply only to contracts which reference nature-dependent electricity. Such contracts expose an entity to variability in the contracted volume of electricity which is generated from natural sources which cannot be controlled.
- The Amendments extend the ‘own-use' exception included in paragraph 2.4 of IFRS 9 to contracts to purchase nature-dependent electricity which meet certain conditions.
- The Amendments permit the application of cash flow hedge accounting to hedging relationships in which the hedged item is a variable amount of forecast electricity transactions and the hedging instrument is a contract referencing nature-dependent electricity.
- The Amendments require entities to disclose information about their contracts referencing nature-dependent electricity.
Background
1In December 2024 the IASB published final Amendments to IFRS 9 and IFRS 7, introducing new requirements and guidance for contracts referencing nature-dependent electricity.
2The publication of these Amendments concluded the IASB's narrow-scope standard setting project on Power Purchase Agreements (PPAs). The purpose of the IASB project was to develop a timely solution for application challenges reported by entities in accounting for contracts referencing nature-dependent electricity, while minimising the risk of unintended consequences for the application of IFRS 9's requirements to other contracts, transactions and items.
3The Amendments have been developed by the IASB to enable a more faithful representation of contracts referencing nature-dependent electricity in the accounts and to require entities to provide complementary disclosures to help users understand, for example, the potential effect of such contracts on future cashflows.
DECA
4The DECA setting out the proposed draft assessment of the Amendments against the statutory criteria is set out at Appendix A to this paper.
5An Invitation to Comment (ITC) is included at Appendix B. The objective of this Invitation to Comment is to obtain input from stakeholders on the endorsement and adoption of the Amendments.
Do the amendments lead to a significant change in accounting practice
6The DECA tentatively concludes in paragraphs 2.3 to 2.5 that the Amendments are not likely to lead to a significant change in accounting practice.
7This tentative conclusion is informed in part by the relatively small number of listed entities currently disclosing information about PPAs in their financial statements (our research indicated that while more than 60 listed entities referred to PPAs in the front half of their annual reports, only a minority of these provided disclosures about PPAs they hold in the notes to their financial statements).
8The Amendments are narrow in scope but could have an impact on the accounting for contracts referencing nature-dependent electricity across a wide variety of businesses as the economy-wide use of renewable electricity increases.
9The renewable energy sector is also evolving and there are expected to be significant developments in the near to medium future as economies aim to decarbonise. The way in which electricity markets operate and related contracts are structured is likely to change. Although it is difficult to anticipate what those developments will be with any certainty, advancements in battery storage for example could significantly alter the contract terms.
10It is possible that technological change may reduce the need for these Amendments over time. For example, there may no longer be any need for hedge accounting Amendments that address the needs of entities holding virtual PPAs. There may therefore be merit in reviewing the ongoing need for the Amendments at a future point.
Question for the Board
- Does the Board have any comments on the tentative conclusion in paragraph 2.5 of the DECA that the Amendments are not likely to lead to a significant change in accounting practice?
Stakeholder outreach
11Feedback from stakeholder outreach to December 2024 was summarised in the Project Initiation Plan[^3].
12Subsequently, the Amendments have been discussed at the Financial Instruments Working Group in January 2025 and with various other subject matter experts. Stakeholders did not express any significant concerns and generally felt that the Amendments would improve the financial reporting of contracts in scope.
Consequential amendments to IFRS 19
13Although not referenced in the title, the Amendments also include consequential amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures (IFRS 19). The effective date for IFRS 19 is annual periods commencing on or after 1 January 2027.
14The UKEB has not yet formally commenced endorsement work on IFRS 19. The endorsement of these Amendments in their entirety, including the consequential amendments to IFRS 19, would mean endorsing an amendment to a standard which is not yet a UK-adopted international accounting standard.
15Therefore, the consequential amendments to IFRS 19 contained within the Amendments will not be considered for adoption as part of the endorsement assessment of these Amendments. Instead, they will be considered for adoption as part of the IFRS 19 endorsement assessment.
16This approach is set out in paragraphs 7 - 8 of the DECA.
Questions for the Board
- Does the Board have any comments on the DECA (Appendix A) or the Invitation to Comment (ITC) (Appendix B)?
- Does the Board agree that, subject to any amendments or additions required by the Board, the DECA and ITC can be published for public consultation?
Next steps and timeline
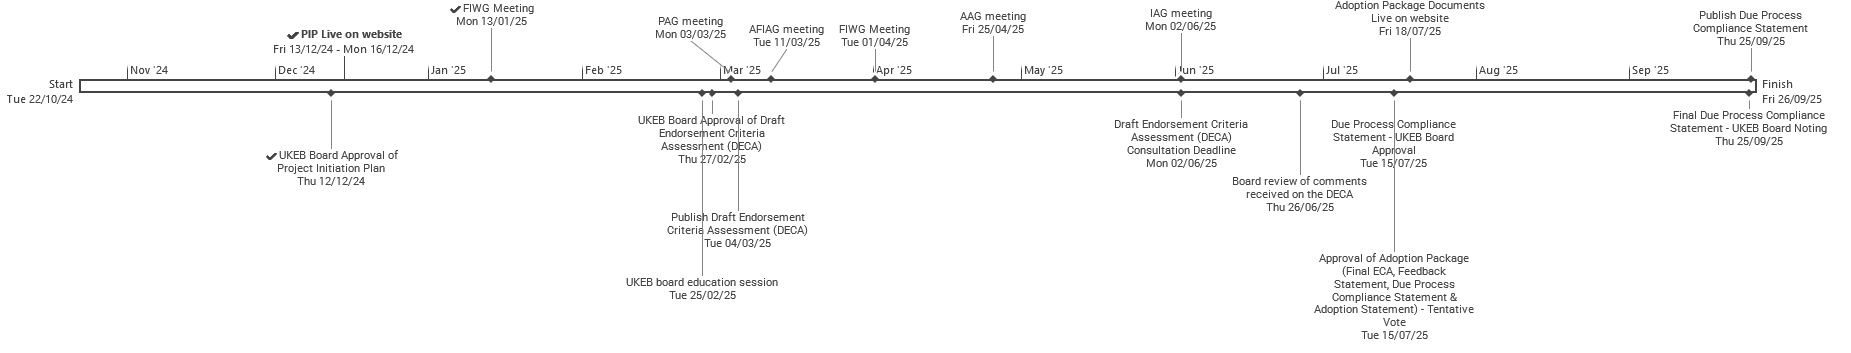
17Subject to amendments or additions to the DECA required by the Board, the proposed timeline is set out below. The Board will be alerted if there are any significant changes.
18In accordance with the Project Initiation Plan (PIP), the proposed timeline aims for the Board to consider whether to adopt the Amendments in July 2025.
| Date | Milestones |
|---|---|
| 12 December 2024 | Draft Project Initiation Plan for Board approval. |
| 30 January 2025 | Technical papers for discussion at Board meeting. |
| 27 February 2025 | DECA for Board approval. |
| Estimated DECA consultation period (90 days): 4 March – 2 June 2025 | |
| 26 June 2025 | Board review of feedback received on the DECA. |
| 15 July 2025 | Consideration of Adoption Package. Board members provide a tentative vote. |
| Second half of July | Voting form sent to Board members. Publication of voting outcome and Adoption Package on the UKEB website. |
| 25 September 2025 | Due Process Compliance Statement for noting. |
Endorsement and adoption timeline
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2025 All Rights Reserved
Introduction
Purpose
1The purpose of this Draft Endorsement Criteria Assessment (DECA) is to determine whether the Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity (the Amendments) issued by the International Accounting Standards Board (IASB) in December 2024 meet the UK's statutory requirements for adoption as set out in Regulation 7 of Statutory Instrument 2019/685[^4] (SI 2019/685).
2The Amendments have an effective date of 1 January 2026 with earlier application permitted.
3The UKEB actively influenced the development of the Amendments. This included submitting a Final Comment Letter on 6 August 2024 in response to the IASB's Exposure Draft Contracts for Renewable Electricity.
Background to the Amendments
4Section 2 in this DECA provides a brief description of the Amendments.
Scope of the adoption assessment
5The Amendments make changes to the mandatory parts of IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures. These changes to the mandatory parts of the standard form part of the UKEB's adoption assessment.
6As UK-adopted international accounting standards comprise only the mandatory[^5] sections of standards, the Amendments to the Illustrative Examples and Basis for Conclusions of IFRS 9 and IFRS 7 are not adopted by the Board and are not considered in this DECA.
7IFRS 19 Subsidiaries without Public Accountability: Disclosures (IFRS 19) will be considered for adoption at a future date. The consequential Amendments to IFRS 19 included in the Amendments will be considered as part of the UKEB's assessment work for the adoption of IFRS 19. Accordingly, the Amendments to IFRS 19, included as a separate element in the Amendments, have not been considered for adoption by the UKEB in this DECA.
8If IFRS 19 (including the Amendments to IFRS 19 within the Amendments to IFRS 9 and IFRS 7 – Contracts Referencing Nature-dependent Electricity) is endorsed for use in the UK, the effective date for those disclosures will be set out in the relevant adoption statement.
Structure of the assessment
9The UKEB's analysis is presented in the following sections:
- Section 1: describes UK statutory requirements for adoption of new or amended international accounting standards and states the UKEB's adoption decision; and
- Section 2: discusses how the Amendments meet the criteria in Section 1.
Do the Amendments lead to a significant change in accounting practice?
10A standard adopted by the UKEB under Regulation 6 of SI 2019/685 that it considers is likely to lead to a 'significant change in accounting practice', is subject to the requirements in paragraph 3 of Regulation 11 of SI 2019/685 that the UKEB:
- carry out a review of the impact of the adoption of the standard; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)”.
11Section 2 of the DECA discusses whether the Amendments lead to a significant change in accounting practice.
1. UK statutory requirements for adoption
UK statutory requirements
1.1Paragraph 1 of Regulation 7 of SI 2019/685 requires that an international accounting standard only be adopted if:
"(a) the standard[^6] is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
(b) the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and (c) the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management.”
1.2This DECA assesses the criteria above in the following order:
- Whether the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c)).
- Whether the Amendments are not contrary to the principle that an entity's accounts must give a true and fair view (Regulation 7(1)(a)).
- Whether use of the Amendments is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)). Regulation 7(2) of SI 2019/685 includes specific areas to consider for this assessment. They are:
- whether the Amendments are likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the Amendments; and
- whether the Amendments are likely to have an adverse effect on the economy of the UK, including on economic growth.
Relevance, Reliability, Understandability and Comparability[^7]
1.3Information is relevant if it is capable of making a difference in the decision-making of users[^8] or in their assessment of the stewardship of management. The information may aid predictions of the future, confirm or change evaluations of the past, or both.
1.4Financial information is reliable if, within the bounds of materiality, it:
- can be depended on by users to represent faithfully what it either purports to represent or could reasonably be expected to represent;
- is complete; and
- is free from material error and bias.
1.5Financial information should be readily understandable by users with a reasonable knowledge of business, economic activities and accounting, and a willingness to study the information with reasonable diligence.
1.6Information is comparable if it enables users to identify and understand similarities in, and differences among, items. Information about an entity should be comparable with similar information about other entities and with similar information about the same entity for another period.
1.7In conducting the overall assessment against the technical accounting criteria, the UKEB is required to adopt an absolute, rather than a relative, approach. This means that this assessment is an absolute one against the criteria (do the Amendments provide information that is understandable, relevant, reliable and comparable?) rather than a relative one (do the Amendments provide information that is more understandable, relevant, reliable and comparable than current, or any other, accounting?). When an assessment of any individual aspect or requirement of the Amendments uses comparative language (e.g. ‘enhances comparability'), the objective is to explain that any individual aspect or requirement of the Amendments has the potential to “enhance” one or more of the qualitative characteristics. Consideration of whether the Amendments are likely to improve the quality of financial reporting is separate from this assessment and is included within the UK long term public good assessment in Section 2.
True and fair view assessment
1.8As noted above, the first adoption criterion set out in Regulation 7(1) of SI 2019/685 requires that an international accounting standard can be adopted only if:
"[....] the standard is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]”
1.9For the sake of brevity, the UKEB refers to the assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair principle'. However, these abbreviated expressions do not imply that the assessment has considered anything other than the full terms of the endorsement criterion set out above.
1.10The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair principle. In other words, it is an ex-ante assessment. The UKEB has therefore considered whether the Amendments contain any requirement that would prevent accounts prepared using the Amendments from giving a true and fair view.
1.11The approach is to determine whether the Amendments are not contrary to the true and fair principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of the Amendments taken as a whole, including their interaction with other UK-adopted international accounting standards.
1.12For the purposes of the assessment, the UKEB considers the requirement in IAS 1 Presentation of Financial Statements for financial statements to 'present fairly the financial position, financial performance and cash flows of an entity' to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
[Draft] Adoption decision
1.13This assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
1.14Section 2 of this DECA discusses how the Amendments meet the statutory endorsement criteria set out in this Section 1.
1.15On the basis of these assessments, and subject to any stakeholder feedback, the UKEB [tentatively] concludes that the Amendments meet the statutory endorsement criteria. The UKEB is therefore of the view that it will adopt the Amendments for use in the UK.
2. Description and assessment of the Amendments
Description
| | Amendments to IFRS 9 and IFRS 7 ```