4 Amendments to the Classification and Measurement of Financial Instruments
Executive Summary
| Entity | Research / Pipeline | Discussion paper | Redeliberation (1) | Exposure Draft | Redeliberation (2) | Final standard | Post Implementation Review |
|---|---|---|---|---|---|---|---|
| IASB | Research / Pipeline | Discussion paper | Redeliberation | Exposure Draft | Redeliberation | Final standard | Post Implementation Review |
| UKEB | Research / Influencing | Research / Monitoring | Influencing | Monitoring | Endorsement | Influencing |
Project Type: Endorsement and adoption Project Scope: Moderate
Purpose of the paper
This paper summarises the feedback received from stakeholders during the recent DECA1 consultation on the endorsement of Amendments to IFRS 9 and IFRS 7 for use in the UK. The Board is asked to consider whether the feedback received should lead to any changes to the endorsement assessments before finalization of the Endorsement Criteria Assessment (ECA).
Summary of the Issue
The DECA was published by the UKEB on 26 September 2024, following approval at the September 2024 Board meeting. The public consultation was open for comments until 10 January 2025.
Seven written responses were received to the consultation. All responses were uploaded on the UKEB website. Six of the seven written responses support the assessment in the DECA and support the endorsement of the Amendments. One respondent did not answer the Invitation to Comment questions but instead provided wider comment on the interaction with current business/economic events. In addition, the Investor Advisory Group provided feedback on the DECA. The IAG was supportive of the UKEB's assessment of the Amendments against the endorsement criteria included in the DECA.
Decisions for the Board
Does the Board agree with the Secretariat's proposed response (see Appendix A to this paper) to the stakeholder feedback received on the DECA?
Recommendation
We recommend the Board makes certain, limited, changes to the text of the ECA.
Appendices
Appendix A: Summary of feedback received on the Draft Endorsement Criteria Assessment (DECA) – Amendments to the Classification and Measurement of Financial Instruments – Amendments to IFRS 9 and IFRS 7.
Amendments to IFRS 9 and IFRS 7 - Amendments to the Classification and Measurement of Financial Instruments (Amendments).
The Amendments are a response to feedback received by the IASB in relation to:
- The potential effect on financial liabilities of a Tentative Agenda Decision made by the IFRS Interpretations Committee regarding the treatment of cash received by electronic transfer as settlement for a financial asset.
- Certain matters arising from the Post implementation Review of IFRS 9 - Classification and Measurement (the PIR).
Proposed amendments to address the feedback were provided in the Exposure Draft Amendments to the Classification and Measurement of Financial Instruments - Proposed amendments to IFRS 9 and IFRS 7 (the ED). Prior to issuing the final Amendments in May 2024, the IASB made changes to certain proposals in response to feedback received during the ED consultation.
The UKEB actively influenced the development of the Amendments by responding to the PIR in January 2022, and responding to the consultation on the ED in July 2023.
A summary of key Amendments is presented below.
IFRS 9 Recognition and derecognition
- Clarifies the requirements for the recognition and derecognition of financial assets and liabilities. In particular, notes that financial liabilities are derecognised on the settlement date, which is the date on which the liability is extinguished.
- Provides a new alternative to the use of settlement date if certain criteria are satisfied.
IFRS 9 Classification of financial assets
- Adds further guidance to clarify how financial instruments with contingent features (such as ESG-linked features) should be assessed when considering the "basic lending” and “solely payments of principal and interest” requirements of IFRS 9.
- Provides improved guidance for the classification of assets with non-recourse features and contractually linked instruments
IFRS 7 Disclosure
- Requires additional disclosure of gains or losses in the fair value of investments in equity instruments that have been designated at fair value through other comprehensive income.
- Requires qualitative and quantitative disclosures for financial assets and liabilities with contingent features.
Appendix A: Summary of feedback received on the Draft Endorsement Criteria Assessment (DECA) – Amendments to the Classification and Measurement of Financial Instruments – Amendments to IFRS 9 and IFRS 7.
| Respondent | Feedback summary | Secretariat recommendation for Final ECA |
|---|---|---|
| Investor Advisory Group, 4 November 2024 | Noted the costs and benefits contained in the DECA appeared substantially correct. Believed the benefits of the Amendments would outweigh any costs to users of financial statements. |
No changes proposed in the final ECA. |
| Response 1 Deloitte LLP | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 2 Grant Thornton UK LLP | Agrees with the assessment in the DECA. | No changes proposed in the final ECA. |
| Response 3 ICAEW | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 4 PWC | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 5 KPMG | Supports endorsement of the Amendments. | No changes proposed in the final ECA. |
| Response 6 Forvis Mazars | Agrees with the assessment in the DECA. Makes a number of observations on the project, including that it is too early to conclude with certainty on whether system changes will be required for implementation, and that the Amendments will not be available for early adoption in the UK for years ending 31 December 2024. |
No changes proposed in the final ECA. a. To permit a timely decision on the Amendments the DECA analysis is based on the best available information at the time of writing. b. Following IASB's publication of the final text of the Amendments, stakeholders told us that there was little appetite for early adoption, and existing practices could likely be used for a further year2. |
| Response 7 SME Alliance Ltd | The Invitation to Comment questions were not answered, nor does the letter state whether the respondent supports endorsement of the Amendments. In summary the response: a. Recommends review of the Amendments, and the underlying IFRS 9 standard, in the context of current events, including the Government announcement on the role of regulators with respect to economic growth3. b. Recommends the impact of the FCA's proposed Public Offers and Admissions to Trading Regulations regime (POATR) should also be considered. |
No changes proposed in the final ECA. a. Whilst the UKEB is not a regulator, the statutory adoption criteria require it to formally consider the impact of adopting a standard or amendment and that it does not have an adverse effect on the UK economy. As such, wider considerations, including the effect on long-term public good and the UK economy, have been assessed on pages 20-26 of the DECA. b. The proposed changes to the prospectus rules do not appear relevant to the endorsement criteria for international accounting standards specified in SI 2019/365. The changes4 focus on the size of issuance at which a prospectus is required for the further issuance of securities already admitted to trading, sustainability disclosures, and protected forward looking statements. |
| Accounting firm - verbal feedback | The accounting firm observed the paragraphs in the technical accounting criteria assessment describing the changes to financial assets5, and the recognition of financial liabilities6, did not reference the improved clarity provided by the Amendments. They advised inclusion of this point in this ECA. | The wording amending the Application Guidance in this area (new paragraph B3.1.2A) is consistent with concepts and language used in existing text in the main body of the Standard (paragraph 3.1.1). The Secretariat recommends the relevant paragraph in the ECA be modified to address this point. This will be marked up in the ECA due to be presented to the Board in March 2025. |
Question for the Board
1Does the Board agree with the Secretariat's proposed response (See Appendix A to this paper) to the stakeholder feedback received on the DECA?
Next steps
1The adoption package for the Amendments will be presented to the Board at its March 2025 public meeting and a tentative indicative vote on whether to adopt the amendments for use in the UK will be taken at that meeting.
2Subject to feedback received from the Board on this paper, the adoption package will reflect the next steps recommended by the Secretariat in the table above.
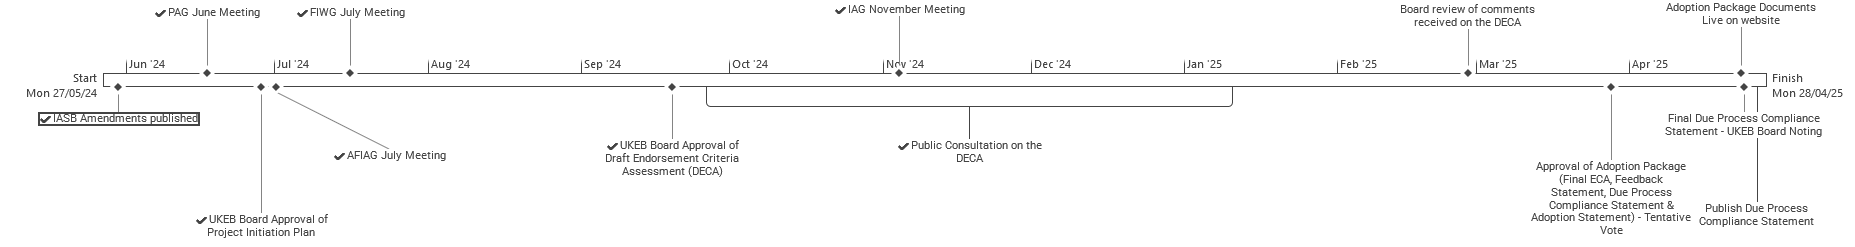
The high level project timeline is shown below.
| Date | Milestones |
|---|---|
| 28 June 2024 | Draft Project Initiation Plan for Board approval. |
| 19 September 2024 | DECA for Board approval. |
| DECA consultation period: 26 September 2024 – 10 January 2025 | |
| 27 February 2025 | Board review of feedback received on the DECA. |
| 28 March 2025 | Consideration of the Adoption Package. Board members provide a tentative vote. |
| April 2025 | Voting form sent to Board members. Publication of voting outcome and Adoption Package on the UKEB website. |
| 24 April 2025 | Due Process Compliance Statement for noting. |
Amendments to IFRS 9 Classification and Measurement of Financial Instruments (effective date 1 January 2026*) – Endorsement and adoption timeline
- Early adoption is permitted. In addition, an entity may elect to early adopt only the amendments to the requirements for the classification of financial assets (Section 4.1 of the standard), and associated disclosures, without applying the other amendments to the standard.
Footnotes
-
Draft Endorsement Criteria Assessment (DECA) in respect of the narrow-scope amendments Amendments to the Classification and Measurement of Financial Instruments - Amendments to IFRS 9 and IFRS 7 (the Amendments), issued by the International Accounting Standards Board (IASB) in May 2024. ↩
-
Financial Instruments Working Group, 16 July 2024, refer Minutes paragraph 6 ↩
-
Chancellor calls on watchdog bosses to tear down regulatory barriers that hold back growth - GOV.UK ↩
-
The FCA consultation on the POATR proposals closed in October 2024, and final text proposals are not yet available. The consultation document states the substantive changes proposed affect the threshold at which a prospectus is required for the further issuance of securities already admitted to trading on a regulated market, sustainability related disclosures, and protected forward looking statements. These topics do not appear to affect IFRS accounting. ↩
-
Financial Assets, DECA paragraph 2.8 page 11, "The recognition and derecognition criteria for financial assets in paragraph B3.1.2A are consistent with the existing requirements of IFRS 9 paragraphs 3.1.1 and 3.2.3. The new paragraph therefore introduces no change for financial assets, so this aspect of the Amendments is not considered further in the following analysis". ↩
-
Financial Liabilities - Recognition DECA paragraph 2.8 page 12. "Paragraph B3.1.2A states that the entity shall recognise a financial liability on the date on which the entity becomes party to the contractual provisions of the instrument. This is consistent with the existing requirement at IFRS 9 paragraph 3.1.1. The new paragraph therefore introduces no change in respect of the recognition of financial liabilities, so this aspect of the Amendments is not considered further in the following analysis." ↩