8 Statement of Cashflows and Related Matters
12 December 2024 Agenda Paper 8
Project Type: Research Project Project Scope: Moderate
Purpose of the paper
The purpose of this paper is to obtain the Board's feedback on the background research paper, and determine if and how it should be published by the UKEB.
The revised Project Initiation Plan (PIP) is also presented for noting.
Summary of the Issue
In September 2024, the International Accounting Standards Board (IASB) moved its project on the Statement of Cash Flows and Related Matters from the research pipeline to the research work plan and announced its intention to start a research project1 to review and improve the requirements for the statement of cash flows and related matters in IFRS Accounting Standards.
The IASB project comes in response to feedback received during the IASB's Third Agenda Consultation when investors, companies, and others, identified this project as a high priority. Stakeholders—particularly investors—have suggested that the current requirements in IAS 7 could be enhanced to provide more useful information to users of financial statements.
The IASB will now conduct initial research, including meetings with stakeholders and review of existing studies, to gather evidence on the nature and extent of perceived deficiencies in current reporting and the likely benefits of developing new financial reporting requirements.
The IASB plans to discuss the initial research outcomes and determine the next steps for this project in the first quarter of 2025.
The research paper (Appendix A) provides a comprehensive basis for developing later research and engaging with the IASB and other National Standard Setters on the IASB project Statement of Cashflows and Related Matters. It is based on desk-based research and explores:
1the background of the Standard IAS 7 Statement of Cash Flows and its relationship with the conceptual framework; 2the importance of the statement of cash flows to investors and other users; and 3the key perceived issues with the statement of cash flows that have been identified by the IASB.
It is intended to inform the Board's future work on this topic, including the interview questions that will be used to develop the second research paper exploring UK user and preparer views.
The revised Project Initiation Plan (PIP) (Appendix B) is for noting. It reflects the feedback received from the Board at the November 2024 meeting. The main change is that the proposed discussion paper for May 2025 has been replaced by a new milestone for the UKEB to consider whether additional research is appropriate and feasible given the IASB's project plan and UKEB priorities at that time. It also incorporates some minor changes for grammar/clarity/consistency.
The evidence gathered in this and other UKEB papers will be used to stimulate debate, engage with the IASB and other national standard-setters or regional organisations, with the aim of ultimately supporting the development of high-quality international accounting standards for use in the UK and internationally.
Decisions for the Board
1Does the Board have any comments on the draft research paper “Statement of Cash Flows and Related Matters: Background and key issues" (Appendix A)? 2Subject to addressing any comments at this meeting, does the Board prefer that the paper is published:
- on the UKEB website as a standalone document as soon as possible; or
- at a later date as part of a possible consolidated report incorporating any future work?
The revised PIP (Appendix B) is included for noting and will be published on the UKEB website after this meeting.
Recommendation
The Secretariat can see benefits in both approaches. However, a single report combining all relevant research is likely to be most impactful.
Appendices
| Appendix A | [Draft] Research Paper - Statement of Cash Flows and Related Matters: Background and key issues |
| Appendix B | Revised PIP (for noting) |
Appendix A: Statement of Cash Flows and Related Matters: Background and key issues
[UK stakeholders] attach considerable importance to the statement of cash flows and believe that a number of improvements to the requirements of IAS 7 should be considered. (FRC Letter to IASB, 2017)
UKEB research into the Statement of Cash Flows and Related Matters
1The UKEB proactively participates in the development of new global accounting standards by:
- engaging with UK stakeholders and collecting evidence on relevant technical issues and communicating such evidence to the International Accounting Standards Board (IASB1) and to all national standard-setters or regional organisations;
- developing potential ways to improve or remedy deficiencies in international accounting standards; and
- working proactively with others to stimulate debate on financial reporting matters on the IASB agenda at an early stage in the standard-setting process.
2The UKEB has embarked on a proactive research project on the Statement of Cash Flows and Related Matters to enable it to gather an evidence base that can contribute to the future work of the IASB on this topic and to ensure that any future standard reflects the views of UK stakeholders.
3The IASB decided to add a project on the Statement of Cash Flows and Related Matters to the research pipeline, following feedback on its Request for Information: Third Agenda Consultation.
4Most respondents to the Request for Information recommended the addition of a potential project on this topic to the IASB's workplan. It is notable that most users of financial statements2 who recommended addition of this topic rated it as high priority.
5The IASB plans to perform initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB's decision on the scope of the project. The initial research will also address possible ways of improving the perceived deficiencies.
6The UKEB is contributing to this research by building on the work already done in the UK by the FRC (and others). While there has been research into the perceived problems with the Statement of Cash Flows, and possible solutions to these problems, to date direct evidence from preparers and users has been limited.
7This research paper explores:
- the background of IAS 7 and relationship with the conceptual framework;
- the importance of the statement of cash flows to investors and other users; and
- the key issues with the statement of cash flows and whether standard setting could address some of those perceived issues, helping preparers better understand the requirements in IAS 7 and providing users with more useful information.
8The paper also covers recent changes to IAS 7 including IFRS 18 Presentation and Disclosure in Financial Statements.
9This paper was developed by undertaking a desk-top review of:
- IASB staff papers on the Statement of Cashflows and Related Matters research project. This included an academic literature review in September 2024, a joint meeting held between the IASB and the US Financial Accounting Standards Board (FASB) in October 2024, a joint Capital Markets Advisory Committee and Global Preparer Forum meeting in June 2024, and their respective separate meetings in November 20243;
- Thematic reviews, and annual reviews of corporate reporting, published by the UK regulator, the Financial Reporting Council (FRC); and
- Accounting firm manuals and other accounting firm publications.
10This paper is intended to assist the Board in its work and provide a thorough introduction to the topic for interested stakeholders. It will also inform interviews with UK Stakeholders, specifically users and preparers, to seek their perspectives on how the statement of cash flows could be improved.
11These interviews will be summarised in a UK Investor and Preparer Perspectives paper, which to support UKEB discussions and future decision-making, and inform engagement with the IASB and other National Standard Setters (NSS) on this project.
Background
IAS 7 Statement of Cash flows
12IAS 7 is a relatively short standard (consisting of only 63 paragraphs). This paper does not provide a detailed review of the standard, however, where relevant the main requirements are set out later in this paper.
13The opening paragraph of IAS 7 sets out the purpose of the standard:
'Information about the cash flows of an entity is useful in providing users of financial statements with a basis to assess the ability of the entity to generate cash and cash equivalents and the needs of the entity to utilise those cash flows. The economic decisions that are taken by users require an evaluation of the ability of an entity to generate cash and cash equivalents and the timing and certainty of their generation.
The objective of the Standard is to require the provision of information about the historical changes in cash and cash equivalents of an entity by means of a statement of cash flows which classifies cash flows during the period from operating, investing and financing activities in a manner which is most appropriate to its business'. (Emphasis added)
14IAS 7 goes on to provide a range of reasons the statement of cash flows can be useful (IAS 7:4-5), stating that it enables users to:
- Evaluate:
- changes in net assets of an entity;
- an entity's financial structure (including its liquidity and solvency); and,
- an entity's ability to affect the amounts and timing of cash flows in order to adapt to changing circumstances and opportunities.
- Assess an entity's ability to generate cash and cash equivalents.
- Develop models to assess and compare the present value of the future cash flows of different entities.
- Compare the operating performance of different entities, because it eliminates the effects of using different accounting treatments for the same transactions and events.
- Assess the amount, timing and certainty of future cash flows.
- Check the accuracy of past assessments of future cash flows.
- Examine the relationship between profitability and net cash flow and the impact of changing prices.
Conceptual Framework for Financial Reporting
15The Conceptual Framework for Financial Reporting (conceptual framework) describes the objective of, and the concepts for, general purpose financial reporting.
16Paragraph 3.3 of the conceptual framework outlines that the financial statements consist of:
- The statement of financial position
- The statement of financial performance
- Other statements and notes presenting information about (among other things) cash flows.
While the conceptual framework mentions the Statement of Financial Position 28 times and the Statement(s) of Financial Performance 23 times no direct mention is made of the statement of cash flows.
17The “assessment of the amount, timing and uncertainty of (the prospects for) future net cash inflows” (paragraph 1.3) is identified as key to the decisions that users need to make based on general purpose financial accounting. The conceptual framework asserts that this is best achieved with the use of accrual accounting:
"Accrual accounting [which] depicts the effects of transactions and other events and circumstances on a reporting entity's economic resources and claims in the periods in which those effects occur, even if the resulting cash receipts and payments occur in a different period. This is important because information about a reporting entity's economic resources and claims and changes in its economic resources and claims during a period provides a better basis for assessing the entity's past and future performance than information solely about cash receipts and payments during that period.” (Conceptual Framework, paragraph 1.17, emphasis added)
18That being said, paragraph 1.20 of the conceptual framework (for easier reading the paragraph is reformatted) states that:
"Financial performance reflected by past cash flows
Information about a reporting entity's cash flows during a period .... helps users:
- to assess the entity's ability to generate future net cash inflows; and
- to assess management's stewardship of the entity's economic resources.
That information indicates how the reporting entity obtains and spends cash, including information about its borrowing and repayment of debt, cash dividends or other cash distributions to investors, and other factors that may affect the entity's liquidity or solvency. Information about cash flows helps users:
- understand a reporting entity's operations;
- valuate its financing and investing activities;
- assess its liquidity or solvency; and
- interpret other information about financial performance”.
19The remainder of the conceptual framework is primarily relevant to the other financial statements.
Concerns with IAS 7
20IAS 7 was first issued in 1992, with only limited modifications made since that time. There have been increasing calls for the IASB to undertake a comprehensive review of the Standard. Factors driving these concerns include:
- The business environment has evolved substantially in this time. There is a risk that the statement of cash flows in its current form, has failed to keep pace with changes in financial reporting practices, evolving business environments and non-traditional transactions.
- The statement of cash flows has regularly featured in questions asked to the IFRS Interpretations Committee (Interpretations Committee), with several directly relevant Agenda Decisions currently listed on the IASB's website (see Appendix B).
- Regulators often cite the statement of cash flows as an area of concern. The UK's FRC annual report reviews consistently rank it amongst the top ten issues that lead to restatements.
21Recent changes to other IFRS Accounting Standards have impacted the requirements in IAS 7, such as:
- Amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures (Supplier finance arrangements) effective 1 January 2024; and
- the new Standard IFRS 18 Presentation and Disclosure in Financial Statements effective 1 January 2027:
- the amendments will require all companies to use the 'operating profit' subtotal as defined in IFRS 18 as the starting point for the indirect method of reporting;
- the presentation alternatives for cash flows related to interest and dividends paid and received will be removed.
The importance of cash flow reporting for users of financial statements
23Any targeted improvements to the statement of cash flows, or proposed changes made following a comprehensive review, need to consider how the statement of cash flows is used by the primary users.
24The extent to which the statement of cash flows is used varies significantly from one user to another making it difficult to satisfy all users with one statement. Any changes to IAS 7 will need to assess the priorities of users and how they use it to assist their decision-making.
Why is cash flow important?
25A statement of cash flows tracks the inflow and outflow of cash, providing insights into a company's financial health and operational efficiency. It measures how well a company manages its cash position, meaning how well the company generates cash to pay its debt obligations and fund its operating expenses.
26As one of the primary financial statements, the statement of cash flows complements and bridges the gap between the statement of financial position and the statement of financial performance, by showing how much cash is generated by, and spent on, operating, investing, and financing activities for a specific period.
27Academic evidence4 on the usefulness of the statement of cash flows for non-financial entities asserts that for users and lenders cash flow information is value relevant and is useful for predicting future cash flows from operating activities. Also, evidence on whether cash flows or earnings are better in predicting future cash flows from operating activities is mixed, but disaggregating earnings into cash and non-cash components improves forecasts of future cash flows from operating activities;
28Cash flow information is often used as a proxy to understand earnings quality and therefore the statement of cash flows is a critical component of high-quality financial reporting for investors6.
UK perspective
29The Feedback Statement to the FRC's 2016 Discussion paper Improving the Statement of Cash Flows, concurred that information contained within the statement of cash flows is integral for assessing the liquidity, working capital management, and quality of earnings reported by companies.
30As suggested in a recent Footnote Analyst article7, cash flow metrics are important when assessing liquidity, as the foundation of discounted cash flow (DCF) valuation and sometimes even in uncovering profit manipulation. Following the cash flows in both purchase and revenue transactions help in understanding the dynamics of a business and in forecasting future working capital changes and operating cash flows. The article states that investors are keen to understand cash conversion and the cash conversion cycle.
31Given the potential for earnings management, e.g. bringing forward revenue recognition or by deferring expenses, investors are interested in historical single-period cash flow metrics. Cash flows are seen as incredibly difficult to manipulate.8 A divergence between the trend in profitability versus cash generation may be an indicator of profit management.
Alternatives to the statement of cash flows
32Whilst some users base their assessment of the ability of an entity to generate cash and cash equivalents on the statement of cash flows, others calculate cash flows using their own models. Analysts may also use information from the statement of cash flows, such as capital expenditure (CapEx) when calculating free cash flows.
33Some of those analyst models could be explored as potential alternatives, or additions, to the statement of cash flows, including:
- Net debt reconciliation / Statement of changes in net debt (see paragraphs 107–109)
- Free Cash Flow (see paragraphs 119–123)
- Statement of changes in working capital (see paragraphs 124–126)
Key issues identified
34The following section draws from the feedback on the IASB's Third Agenda Consultation, subsequent work undertaken by the IASB project team and the FRC's work to identify and examine seven key areas of concern regarding the statement of cash flows:
- Classification of cash flows
- Disaggregation of cash flow information
- Definition of cash and cash equivalents
- Reporting cash flows from ‘operating' activities — direct vs. indirect method
- Effects of non-cash transactions
- Cash flow measures and other disclosures
- Statement of Cash Flows for financial institutions
Classification of cash flows
IAS 7 requirements
35The statement of cash flows is divided into three primary sections, based around specific activities.
36Operating activities are the principal revenue-producing activities of the entity and other activities that are not investing or financing activities (IAS 7.6).
37IAS 7.13 states that the amount of cash flows arising from operating activities:
is a key indicator of the extent to which the operations of the entity have generated sufficient cash flows to repay loans, maintain the operating capability of the entity, pay dividends and make new investments without recourse to external sources of financing.
38Investing activities are the acquisition and disposal of long-term assets and other investments not included in cash equivalents.
39IAS 7.16 states that the separate disclosure of cash flows arising from investing activities (emphasis added):
is important because the cash flows represent the extent to which expenditures have been made for resources intended to generate future income and cash flows. Only expenditures that result in a recognised asset in the statement of financial position are eligible for classification as investing activities.
40Financing activities are activities that result in changes in the size and composition of the contributed equity and borrowings of the entity.
41IAS 7.17 states that separate disclosure of cash flows arising from financing activities:
is important because it is useful in predicting claims on future cash flows by providers of capital to the entity.
What's the issue?
42Accurately classifying historic cash flows as ‘operating', ‘investing', or 'financing' activities is central to users' understanding of the nature of an entity's activities that have generated and used cash during the reporting period.
43If entities are inconsistent in their classification of cash flows, this results in the statement of cash flows not being comparable between entities and relevant information not being transparent.
44Research reviewed by the IASB found that entities with market-related incentives to inflate cash flows from operating activities were likely to opportunistically classify cash flow line items from one category to another9.
45It is often assumed that the ‘'operating' category includes only those cash flows that arise from an entity's principal revenue producing activities. However, cash flows arising from 'operating' activities represent a residual category, which includes any cash flows that do not qualify to be recorded within either 'investing' or 'financing' activities. As a result, operating activities can include cash flows that may initially not appear to be ‘operating' in nature (e.g. cash inflows from other revenue sources that are not from the sale of goods or rendering of services, such as proceeds from an insurance claim)10.
46Another concern around classification was considered by the Interpretations Committee meeting in July 2012, relating to IAS 7.16 (updated in 2009). The Interpretations Committee decided that only expenditures that result in a recognised asset in the statement of financial position are eligible for classification as investing activities11.
47Other challenges identified include multiple-component transactions (see paragraph 99); factoring receivables; related inflows and outflows classified differently; and tax payments which are classified as cash flows from operating activities 'by default' and not presented separately, like in IFRS 18.
48There are also a range of transactions where no specific guidance exists, leading to diversity in practice, including (but not limited to):
- cash received from factoring12 of trade receivables;
- cash payments related to the purchase of an asset on deferred payment terms from the supplier;
- payment of variable consideration in a business combination;
- cash flows related to obtaining a contract, that are capitalised in accordance with IFRS 15 Revenue from Contracts with Customers,
- payments at the inception of a lease (if not all the amounts under a lease contract are due at inception of the lease).
Recent changes to IAS 7 on issuing IFRS 18
49The current classification in the statement of cash flows is not aligned with the classification in the statement of profit or loss that was proposed in the Primary Financial Statements Project (this classification is included in IFRS 18 Presentation and Disclosure in Financial Statements effective from 1 January 202713).
50While IFRS 18 does not itself deal with the format of the statement of cash flows, the IASB has made some limited amendments to IAS 7 as part of that project. Accounting policy choices for the presentation of cash flows related to interest and dividends paid and received have been removed. The new requirement is that these items must be reported outside of the operating activity section of the statement of cash flows in either investing or financing, as appropriate14. However, for entities that invest in assets or provide financing to customers as a main business activity, there is still some flexibility in relation to the categorisation of interest and dividend received and interest paid.
51The other main change resulting from IFRS 18 is that the reporting of cash flows for operating activities (when presented using the indirect method) must start with the newly defined 'operating profit'. At present companies start the calculation with a variety of profit measures, including operating profit, pre-tax profit and net income. Having a common starting point, plus the greater comparability achieved by removing presentation options, means that cash flow data will become more relevant and understandable, particularly the cash flows from operating activities metric15.
52Unfortunately, while IFRS 18 uses the same categories as the statement of cash flows (operating, financing, and investing) the application of these labels in the statement of financial performance is not identical. The key difference is the treatment of CapEx – in the statement of cash flows this is part of investing cash flow but the equivalent (accruals accounting) statement of financial performance impact, in the form of depreciation and amortisation, is included in operating profit16.
53Furthermore, the cash flows from operating activities requirement is post-tax, but the starting point of the indirect method ‘operating profit' is pre-tax.
Stakeholder views
54Feedback received by the IASB from the Third Agenda Consultation, and from its independent user and preparer advisory bodies, namely the Capital Markets Advisory Committee (CMAC) and Global Preparers Forum (GPF):
Some stakeholders:
- requested the IASB revisit the classification of cash flows into operating, investing and financing categories specified in IAS 7, in the light of differences in the classification requirements of IFRS 18 Presentation and Disclosure in Financial Statements, which is effective form 1 January 2027.
- suggested classification requirements be revised to provide more detail on CapEx, in particular separating capital maintenance from capital growth expenditure (This topic is discussed later in this paper in the section on disaggregation of cash flow information).
UK perspective
55The FRC's October 2016 Discussion paper ‘Improving the Statement of Cash Flows’ is useful in the context of the IASB's current research project on the Statement of Cash Flows and Related Matters, since the paper stimulated debate on opportunities to make the statement of cash flows more useful. In the Feedback Statement in July 2017, the FRC noted:
- Most respondents believe that ‘operating activities' should be positively defined or described, and many request consistency between the statement of cash flows and the statement of profit or loss, as they believe it allows genuine disparities between cash and profit performance to be identified and explained.
- There were split views as to whether or not CapEx should be reported within operating activities rather than as an investing activity, with some suggesting a change in classification will not result in more relevant and reliable information.
- The majority of respondents consider that all cash flows relating to financing liabilities should be reported in the financing category of the statement of cash flows.
- A majority of respondents thought that tax should be in a separate section of the statement of cash flows.
56The FRC's Corporate Reporting Review team has published a number of other reports identifying concerns with the reporting of cash flows in the financial statements, including:
- FRC 2020 thematic report on cash flow and liquidity disclosures;
- FRC 2022 thematic report on business combinations; and
- multiple annual corporate reporting reviews.
57The FRC consistently notes that many of the concerns they identify could have been avoided if the company had a robust pre-issuance review built into its financial statement close process.
58Finally, as a result of the UKEB's own outreach, one respondent to the recent UKEB preparer survey on IFRS 18 questioned why 'operating' should be a default category in the statement of cash flows.
Disaggregation of cash flow information
IAS 7 requirements
59As set out in IAS 7.50, additional information may be relevant to users in understanding the financial position and liquidity of an entity. Disclosure of this information, together with a commentary by management, is encouraged and may include:
- the amount of undrawn borrowing facilities that may be available for future operating activities and to settle capital commitments, indicating any restrictions on the use of these facilities;
- the aggregate amount of cash flows that represent increases in operating capacity separately from those cash flows that are required to maintain operating capacity; and
- the amount of the cash flows arising from the operating, investing and financing activities of each reportable segments.
60The separate disclosure of cash flows that represent increases in operating capacity and cash flows that are required to maintain operating capacity is useful in enabling the user to determine whether the entity is investing adequately in the maintenance of its operating capacity. An entity that does not invest adequately in the maintenance of its operating capacity may be prejudicing future profitability for the sake of current liquidity and distributions to owners (IAS 7.51).
61The disclosure of segmental cash flows enables users to obtain a better understanding of the relationship between the cash flows of the business as a whole and those of its component parts and the availability and variability of segmental cash flows (IAS 7.52).
What's the issue?
62Due to the flexibility in IAS 7 on how to aggregate information, some users find the detail in the statement of cash flows insufficient to understand the sources and uses of cash. Given that the disclosures in IAS 7.50 are only encouraged and are not mandatory requirements, there is diversity in practice in how comprehensive information provided by companies is.
63Limited academic evidence17 reviewed by the IASB on disaggregation of cash flow information, indicates that more disaggregated information is better for users.
Stakeholder views
64Feedback received by the IASB from the Third Agenda Consultation and from its independent user and preparer advisory bodies (CMAC and GPF):
Several stakeholders said some information presented in the statement of cash flows should be required to be disaggregated in order to improve transparency, for example:
- Discontinued operations—net cash flows attributable to the operating, investing and financing activities;
- CapEx, specifically disaggregating growth and maintenance expenditure – although some GPF members said such distinction of cash flows would be difficult;
- changes in working capital; and
- cash flow by business segments—cash flows can be very different for different segments of a business.
65Additionally, IAS 7 does not distinguish between dividends to non-controlling interests and to common shareholders. Disaggregation on the face of the statement of cash flows would be useful to users, for example, when considering dividend payments to estimate the value of the parent entity's equity.
Related changes to IAS 7 on issuing IFRS 18
66IFRS 18 provides enhanced guidance on aggregation and disaggregation including:
- roles of primary financial statements and the notes, which help determine the line items presented in the primary financial statements and the information disclosed in the notes; and
- principles which focus on grouping items based on their shared characteristics.
67These principles are applied throughout the financial statements, including the statement of cash flows.
UK perspective
68In the Feedback Statement to the FRC's October 2016 Discussion paper ‘Improving the Statement of Cash Flows’ the majority of respondents do not consider that disclosure should be required of the extent to which CapEx represents 'replacement' or 'expansion', although some respondents consider that disclosure of this could be encouraged (note however the issues already identified when disclosures are only encouraged). The most frequent reason given to the FRC for not disaggregating was that the division of such cash flows would necessitate too many arbitrary judgements to be useful.
69The ACCA18, has also observed that 'companies have far too much latitude to aggregate very different categories and can avoid disclosing really important stuff. The article noted, among other things, that CapEx is frequently lumped with 'investments', and that there is often a large (unexplained) number called 'movement in other liabilities'.
Definition of cash and cash equivalents
IAS 7 requirements
70Central to the statement of cash flows is the ability of the entity to generate cash and cash equivalents. Cash equivalents are “short-term, highly liquid investments (such as short-term debt securities) that are readily convertible to known amounts of cash and that are subject to an insignificant risk of changes in value”.
71Per IAS 7.7 (for easier reading the paragraph is presented here in three parts):
- "Cash equivalents are held for the purpose of meeting short-term cash commitments rather than for investment or other purposes”.
- "For an investment to qualify as a cash equivalent it must be readily convertible to a known amount of cash and be subject to an insignificant risk of changes in value. Therefore, an investment normally qualifies as a cash equivalent only when it has a short maturity of, say, three months or less from the date of acquisition".
- “Equity investments are excluded from cash equivalents unless they are, in substance, cash equivalents, for example in the case of preferred shares acquired within a short period of their maturity and with a specified redemption date”.
What's the issue?
72The definitions of ‘cash' and 'cash equivalents' are important for the statement of cash flows, particularly to ensure companies provide relevant and comparable information. There can be different interpretations on the definitions of cash and cash equivalents in applying the standard, which may cause diversity in practice which could affect comparability of the statement of cash flows between entities.
73Specific concerns with the definitions of ‘cash' and 'cash equivalents' include:
- the meaning of 'short-term maturity19';
- how much emphasis should be placed on the reference to ‘three months';
- whether central bank digital currencies would be cash and cash equivalents; and
- how to assess whether there is an insignificant risk of changes in value of an investment, that is otherwise readily convertible into cash.
74Concerns have also been raised that the requirements in IAS 7 for which items can be considered cash equivalents are:
- too restrictive – exclusion of certain items with a slightly longer maturity than three months may not align with the entity's liquidity management approach, and the assessment of solvency by credit agencies, who may have a broader focus and look at investments that could be converted into cash within a six-months period; or
- not sufficiently restrictive – for the liquidity analysis, it is not useful to have items that cannot immediately be converted into cash i.e. they may take three months to be converted.
75Over recent years, the Interpretations Committee have received a number of questions on applying IAS 7 and in particular questions on cash and cash equivalents (see Appendix B).
Stakeholder views
76Feedback received by the IASB from the Third Agenda Consultation and from its independent user and preparer advisory bodies (CMAC and GPF):
Some stakeholders suggested the IASB consider whether the statement of cash flows should report separately flows of cash, from those of cash equivalents.
Stakeholders further questioned:
- whether cryptocurrencies could be considered as cash20; and
- whether there is a better basis other than the maturity period of an investment to determine whether the investment is a cash equivalent.
Some GPF members noted that cash and cash equivalents:
- are internally defined differently than they are defined in IAS 7, resulting in different starting and ending points, and different classifications, in the statement of cash flows;
- different companies classify the same financial instruments differently, which might hinder comparability among companies.
UK perspective
77In the FRC's letter to the Chair of the IASB, following its 2016 Discussion paper ‘Improving the Statement of Cash Flows’, the FRC noted, in relation to cash and cash-equivalents that there were split views as to whether or not the statement of cash flows should report flows of cash, or of cash and cash equivalents.
78The FRC's 2020 thematic report on cash flow and liquidity disclosures observed inappropriate judgements or lack of disclosure on components of cash and cash equivalents.
79In relation to the FRC's annual corporate reporting reviews, issues with how cash and cash equivalents had been defined by preparers, or issues with lack of explanations, were highlighted in seven of the past 14 annual reviews. The most common issue was that the basis for inclusion or exclusion of amounts from cash and cash equivalents (e.g. overdrafts, investments) were unclear or inconsistent (e.g. between the parent's and the consolidated statement of cash flows).
Reporting cash flows from ‘operating' activities – direct vs. indirect method
IAS 7 requirements
80An entity can report cash flows from operating activities in one of two different ways (IAS 7.18–20):
- the direct method, whereby major classes of gross cash receipts and gross cash payments are disclosed – these may be obtained either:
- from the accounting records of the entity; or
- by adjusting sales, cost of sales (interest and similar income and interest expense and similar charges for a financial institution) and other items in the statement of comprehensive income for:
- changes during the period in inventories and operating receivables and payables;
- other non-cash items; and
- other items for which the cash effects are investing or financing cash flows.
- the indirect method, whereby the net cash flow from operating activities is determined by adjusting profit or loss21 for the effects of:
- transactions of a non-cash nature, such as depreciation, provisions, deferred taxes, unrealised foreign currency gains and losses, and undistributed profits of associates;
- changes during the period in inventories and operating receivables and payables; and
- all other items of income or expense associated with investing or financing cash flows.
What's the issue?
82Providing an option for how entities present cash flows from operating activities creates diversity. This is especially challenging when different methods are used within the same group, which can potentially lead to inconsistencies in reporting.
83The indirect method is criticised for not showing actual cash flows, rather turning the statement of cash flows into a reconciliation of other statements. This means that the information needed to calculate cash flows from operating activities using the indirect method is already available in the other financial statements, without providing any new information22.
84There is also significant variability in how companies and industries present cash flows using the indirect method, which makes comparability and analysis more difficult for users.
85The primary argument favouring the direct method is that it provides information on the specific sources of operating cash receipts and payments. This information can be useful:
- In understanding a company's historical performance and capacity to repay existing obligations.
- In the prediction of the future financing needs of a company23.
86The main arguments in support of the indirect method are:
- It provides a link between, and allows users to reconcile, the statement of cash flows and the statement of financial position, which can be used alongside users' analyses24.
- It shows the reasons for differences between net income and cash flows from operating activities.
- It is useful for forecasting growth and understanding how much cash flow is being absorbed by working capital – the method mirrors a forecasting approach.
- Adjusting net income to cash flows from operating activities is easier and less costly than reporting gross operating cash receipts and payments.
87Academic evidence reviewed by the IASB25, showed that the direct method provides users with more useful information than the indirect method for forecasting entities' future cash flows and earnings. Direct method information is also more strongly associated with share prices than indirect method information.
88Some evidence suggests that indirect method information (such as reconciliation between cash flows from operating activities and net income) remains useful in the presence of direct method information. Some academics argued that using both the direct and indirect methods in combination would improve comparability across entities.
89Under US GAAP, companies must present a reconciliation between net income and cash flow when they use the direct method. This reconciliation is equivalent to the indirect method.
Stakeholder views
90Feedback received by the IASB from the Third Agenda Consultation and from its independent user and preparer advisory bodies (CMAC and GPF):
Some stakeholders requested the IASB consider the feasibility of requiring the direct method because, in their view, the indirect method fails to provide users with some decision-useful information.
Stakeholders said:
- the direct method would reduce the difficulty of reconciling the statement of cash flows to the other primary financial statements;
- the direct method could provide more information about cash flows from operating activities, such as cash flows arising from supplier finance arrangements and cash collected from customers26; and
- the direct and indirect methods, used in combination, might help to eliminate basic cash flow errors.
Some stakeholders and CMAC members noted that the indirect method does provide some useful information. Some stakeholders and GPF members noted the potential complexity and associated costs to preparers in implementing the direct method.
UK perspective
91While preferences vary across jurisdictions and organisations, most entities in the UK present cash flows from operating activities using the indirect method27.
92In the FRC's letter to the Chair of the IASB, based on the Feedback Statement to its 2016 Discussion paper ‘Improving the Statement of Cash Flows’, the FRC noted that, in relation to the direct and indirect method, a majority of respondents agreed that:
- the direct method statement of cash flows should continue to be permitted; and
- a reconciliation of operating activities should be presented in all cases.
93The FRC's 2020 thematic report on cash flow and liquidity disclosures raised the following concerns where the indirect method had been used:
- working capital changes were inconsistent with statement of financial position movements;
- material unexplained variances existed in impairment and depreciation charges in reconciliation and other notes to the accounts.
Effects of non-cash transactions
IAS 7 requirements
94'Investing' and 'financing' transactions that do not require the use of cash or cash equivalents are excluded from the statement of cash flows. However, IAS 7.43 requires that these transactions are “disclosed elsewhere in the financial statements in a way that provides all the relevant information about these investing and financing activities".
What's the issue?
95Many investing and financing activities do not have a direct impact on current cash flows although they do affect the capital and asset structure of an entity. The exclusion of non-cash transactions from the statement of cash flows is consistent with the objective of a statement of cash flows as these items do not involve cash flows in the current period. Examples of non-cash transactions provided in IAS 7.44 include:
- the acquisition of assets either by assuming directly related liabilities or by means of a lease;
- the acquisition of an entity by means of an equity issue; and
- the conversion of debt to equity.
96However, there is an argument that excluding all non-cash transactions from the statement of cash flows does not result in comparable information for similar transactions with the same economic effect. For example, the purchase of an asset (or a business) in exchange for an entity's own shares is similar to first selling its own shares and then purchasing an asset with the cash received. One might expect that the two transactions should be presented similarly in the statement of cash flows. The same could apply to other non-cash transactions, including, for example, sales in exchange for cryptocurrencies or obtaining a beneficial interest as consideration for transferring financial assets (excluding cash).
97The increasing prevalence of non-cash changes in debt that are regarded as being economically equivalent to cash flows, is an increasing challenge for investors. Because such changes in debt do not involve cash flows, they are not reflected in the statement of cash flows. One commonly cited example was supplier financing. However, recent changes to disclosure requirements for Supplier Finance Arrangements (May 2023) may go some way to resolving the lack of non-cash disclosures for such arrangements (see paragraph 101).
98Including non-cash transactions in the statement of cash flows could be argued to not be a faithful representation and could be confusing to users and it should be considered that there are already other requirements to disclose information about non-cash transactions, including information about non-cash changes in debt, for example disclosing changes in liabilities arising from financing activities which can often be found in the debt reconciliation that most companies provide28 (see paragraphs 102–103).
99Non-cash flow transactions could also include multiple component transactions that involve cash or cash equivalents, but which result in cash flows to and from an entity being reduced compared to a situation where the various components had not been bundled. Multiple component transactions may not only affect the cash flows of a transaction but could also affect the classification of the cash flows.
100Other examples of non-cash transactions are:
- when a company takes on acquired debt as part of an acquisition;
- foreign exchange changes; or
- changes in fair values.
Recent changes to IAS 7
Supplier Finance Arrangements
101In May 2023, the IASB introduced disclosure requirements29 for supplier finance arrangements to enable users to assess the effects of those arrangements on the entity's liabilities and cash flows and on the entity's exposure to liquidity risk. Companies are required to provide the new disclosures for the first time for annual reporting periods beginning on or after 1 January 2024.
Changes in liabilities arising from financing activities
102In 2016 the IASB's IAS 7 Disclosure Initiative added paragraphs 44A-E to IAS 7, which require companies to provide information in the notes to the accounts that enables investors to evaluate changes in debt, including those arising from both cash and non-cash movements. One way that companies fulfil this requirement is by disclosing a debt reconciliation from the opening to the closing statement of financial position.
103Although a reconciliation is not mandatory, the IASB have suggested it is an effective way for companies to meet this requirement and most companies disclose a reconciliation in applying the amendment. This disclosure is generally titled 'debt reconciliation', 'net debt reconciliation', or a 'reconciliation of liabilities from financing activities'30(see paragraphs 107–109).
Stakeholder views
104Feedback received by the IASB from the Third Agenda Consultation and from its independent user and preparer advisory bodies (CMAC and GPF):
Some stakeholders (including some users and some CMAC members) said it is difficult to reconcile the statement of financial position to the statement of cash flows, and there is a need for more information on non-cash effects of some transactions such as leases and the factoring of trade receivables.
Some stakeholders suggested:
- either requiring non-cash movements be presented in the statement of cash flows or requiring further disclosures of non-cash movements in an accompanying note to the statement of cash flows;
- companies be required to present a statement of changes in net debt because there is a poor level of compliance with the requirements in IAS 7.44A–44E to disclose changes in liabilities arising from financing activities, including both changes arising from cash flows and non-cash changes.
105In its Investor perspective: Providing insights into cash flow economics published in October 2023, the IASB acknowledged that information about non-cash changes in debt is important for investment analysis. As investors seek insights into a company's ability to service its debt and to invest for the future and pay dividends, transparency around non-cash changes in debt is essential for an appreciation of the underlying cash flow dynamics of a business.
106Investors often rebuild the statement of cash flows to include both reported cash flows and changes in debt regarded as economically equivalent to cash flows. Information from the statement of cash flows—together with information about movements in debt—can be used to:
- reconcile changes in net debt (from the opening to closing statement of financial position) to ensure that cash flows and changes in debt regarded as economically equivalent to cash flows have been identified;
- analyse a company's underlying cash flows from operating activities and free cash flow generation;
- understand the sources of a company's finance and how those sources have been used over time;
- improve confidence in forecasting a company's future cash flows;
- better assess a company's ability to service and repay its debts.
Net Debt Reconciliation / Statement of changes in Net Debt
107The amount of cash held by an entity can be affected just before the end of the reporting period by borrowing money, whereas the net debt will not be affected by such actions. Some users therefore consider a statement of changes in net debt, or net debt reconciliation more useful, for example, when estimating the value of an entity, such as enterprise value.
108The usefulness of a net debt reconciliation was confirmed by some respondents to the IASB Third Agenda consultation, who suggested the IASB require entities to present one. In addition to equity valuation, a net debt reconciliation can be used for investigating potential issues with debt or liquidity.
109Some of the perceived issues with the statement of cash flows, could be resolved by requiring a net debt reconciliation, despite there currently being no definition of 'net debt' in IFRS Accounting Standards. In addition to depicting cash movements and non-cash movements, a net debt reconciliation can be particularly helpful in understanding complex debt structures.
UK perspective
110Disclosure of non-cash transactions which comprise offsetting ‘effective flows' was also noted in a recent Footnote analyst article31, as one area for the IASB to consider. Those investors that understand the issue, can make adjustments based on existing disclosures, but it would help all investors if the presentation of these items is improved.
111In the FRC's letter to the Chair of the IASB, following it 2016 Discussion paper ‘Improving the Statement of Cash Flows’, the FRC noted in its overarching message that a majority of respondents agree that notional cash flows should not be reported in the statement of cash flows although there should be disclosure of non-cash transactions.
112Issues with non-cash transactions being incorrectly shown as cash flows were highlighted in eight of the past 14 FRC annual corporate reporting reviews. The most common error was the acquisition of assets under finance leases/right of use assets reported as a cash flow. IAS 7.44a specifically includes leased assets as a non-cash transaction, which should be excluded from a statement of cash flows but disclosed elsewhere in the financial statements (IAS 7.43).
113In addition, in seven of the last 14 annual reviews, the FRC noted omissions or inadequate disclosures, the most common of which was the omission or incompleteness of disclosures on changes in liabilities arising from financing32.
114The FRC Lab project report: Net Debt Reconciliations published in 2012, explored existing voluntary practices to identify those that investors found useful. The report sets out best practices that include highlighting key movements and showing cash-drivers and non-cash drivers of changes:
- Cash drivers: investors are able to reconcile items in the financial statements with the relating changes in net debt. Information on cash movements can be used to understand how an entity's net debt movements reconcile to management's expectation of cash flows, so users can assess the effectiveness of management's financial policy and identify any potential variance. The net debt reconciliation also captures working capital absorption, debt-servicing dynamics and foreign exchange movements.
- Non-cash drivers: investors highlight the usefulness of separately presenting the reconciling items that are non-cash movements in net debt, such as finance lease additions, foreign exchange and fair value movements, acquired debt and disposals.
115A net debt reconciliation could present a reconciliation of each component of net debt from one date to another (for an example see page 189 of National Grid plc Annual Report and Accounts 2023-24–Note 29 Net Debt).
116The ACCA33, has suggested a logical place to finish a cashflow statement is with the movement in net debt, given net debt is a key performance metric. They noted that compliance with the IAS 7 Disclosure Initiative 'is patchy' and the information is often buried in the notes.
Cash flow measures and other disclosures
Stakeholder views
117Feedback received by the IASB from the Third Agenda Consultation and from its independent user and preparer advisory bodies (CMAC and GPF):
Stakeholders:
- Suggested standardised definitions of some cash flow measures, for example, free cash flow would be useful – most GPF and CMAC members agreed.
- Noted there is a lack of information in the statement of cash flows that is needed to calculate cash flows measures, such as free cash flow.
- Said it might not be necessary for the IASB to define free cash flow if it required entities to provide additional disclosures that provide transparent information calculating specific measures and understanding how companies manage cash inflows and outflows to meet payment obligations, plan for future payments etc.34
- Said it would be useful to have a reconciliation between cash flows from operating activities and the company's definition of free cash flow, which would eliminate the need to standardise the definition of free cash flow, since defining free cash flow could be challenging.
Measures and disclosures
118In addition to free cash flow, research has suggested that other measures, are also useful to investors, including changes in working capital. We explore both below.
Free Cash Flow
119Investors want to know how companies manage cash inflows and outflows to meet payment obligations and determine what cash is available to maintain the sustainability of the business, to invest in the future growth of the business, and to pay dividends. Investors use information in the statement of cash flows and other primary financial statements and accompanying notes to calculate other metrics, such as 'free cash flow'.
120Free cash flow is a non-GAAP performance measure. It is generally defined as the amount by which a company's cash flows from operating activities exceeds its working capital needs and expenditures on fixed assets (that is, CapEx). However, investors often have their own definitions of such cash flow measures, with some analysts having multiple definitions which they apply depending upon, for example, the company, the industry sector or jurisdiction.
121Free cash flow is considered an indicator of a company's financial flexibility and is of interest to holders of the company's equity, debt, preferred stock and convertible securities, as well as potential lenders and investors.
122Some investors prefer using free cash flow instead of net income to measure a company's financial performance and calculate the intrinsic value of the company, because they consider that free cash flow is more difficult to manipulate35 than net income.
123Academic evidence reviewed by the IASB36, showed that an increasing number of entities disclose free cash flow and that:
- Free cash flow definitions varied among entities.
- Some entities disclose free cash flow to:
- present a more favourable financial position; or
- provide better information to users.
- There is a growing usefulness of free cash flow to users, particularly for entities with high levels of asymmetric information, younger entities, and entities in high technology industries.
Statement of changes in working capital
124Whilst working capital is the difference between a company's current assets (such as cash, accounts receivable and inventories of raw materials and finished goods) and its current liabilities (such as accounts payable), due to limitations37 in the working capital metric, a statement of changes in working capital (net change in a company's operating assets and operating liabilities across a specified period38) can be more useful.
125Change in working capital is a cash flow item that reflects the actual cash used to operate the business and will help determine where a company is in its working capital cycle.
126Changes in working capital can help explain how a company uses its assets to generate growth. Understanding how a company uses its assets and liabilities, can allow investors to predict changes in company value39.
UK perspective
127In the FRC's October 2016 Discussion paper ‘Improving the Statement of Cash Flows’, the regulator asked stakeholders which components of cash flows from operating activities should an accounting standard identify as particularly significant, and why, as well as how standard setters should decide whether to require disclosure of the amount of such components, or of changes in related working capital items.
128A variety of views were expressed in response to this question, which included the following.
- Existing requirements are sufficient. Each entity should determine which components are material, significant or relevant in their own circumstances.
- Further outreach is required to determine which components users would like to see disclosed and to judge the appropriate balance between costs and benefits.
129Only a few respondents identified specific items that they consider should be required. One standard-setter expressed the view that:
- movements in trade debtors, trade creditors, inventories, depreciation, amortisation and impairments plus other movements in working capital should be presented; and
- disclosure of payments from customers and payments to suppliers should not be required.
130Finally, one respondent to the recent UKEB preparer survey on IFRS 18 commented that one of the biggest challenges is that IFRS has no definition of free cash flow, which is an often used management and investor metric. Guidance would be useful, given that the analyst community generally reconcile from an alternative performance measure (APM). If defined, free cash flow would be captured as a management performance measure (MPM) and therefore a more useful reconciliation included in the notes to the financial statements.
Statement of Cash Flows for financial institutions
IAS 7 requirements
131IAS 7.3 states that the statement of cash flows should be relevant to all entities, even financial institutions:
Users of an entity's financial statements are interested in how the entity generates and uses cash and cash equivalents. This is the case regardless of the nature of the entity's activities and irrespective of whether cash can be viewed as the product of the entity, as may be the case with a financial institution. Entities need cash for essentially the same reasons however different their principal revenue-producing activities might be. They need cash to conduct their operations, to pay their obligations, and to provide returns to their investors. Accordingly, this Standard requires all entities to present a statement of cash flows.
What's the issue?
132It has been suggested that the statement of cash flows for financial institutions (in particular banks and insurance companies) is not seen to provide useful information to users of the financial statements.
Stakeholder views
133As part of the Third Agenda Consultation and reiterated at the June 2024 joint CMAC/GPF meeting:
Some stakeholders suggested that the statement of cash flows prepared in accordance with IAS 7 has limited usefulness for financial institutions:
- the statement of cash flows does not reflect how financial institutions manage cash and assess liquidity risk exposure in practice;
- enhanced disclosures on liquidity are already provided via the requirements set out in IFRS 7 Financial Instruments: Disclosures and sometimes even outside IFRS, such as liquidity ratios prescribed by the Basel Committee; and
- the requirements in IAS 7 are not specific to the banking industry, and it is difficult to calculate some items.
Some stakeholders suggested either:
- removing the requirement to present a statement of cash flows for financial institutions; or
- developing a statement of cash flows specifically for financial institutions.
However, some stakeholders also expressed that it is important for a financial institution to present a statement of cash flows because it provides essential information, such as cash flows relating to dividend payments, capital issued and repaid, and acquisitions and disposals.
UK perspective
134There has been limited literature in the UK on the statement of cash flows for financial institutions. For example, issues that arise in the context of financial institutions were not discussed in the feedback statement on the FRC's October 2016 Discussion paper ‘Improving the Statement of Cash Flows’40. Similarly, financial services companies such as banks and insurers, which are subject to regulatory capital, liquidity and solvency regimes, were excluded from the FRC's 2020 Thematic review: Cash Flow and Liquidity Disclosures.
135Early engagement by the Secretariat with certain UK stakeholders has indicated a view that any project considering financial institutions would need to account for very different business models within the different categories of financial institutions. Financial institutions include retail and commercial banks, credit unions, savings and loan associations, investment banks and companies, brokerage firms, insurance companies, mortgage companies, asset managers and multi-industry conglomerates.
Next Steps
136Early discussions with UK stakeholders indicate little appetite for focusing on the statement of cash flows for financial institutions at this stage of the project. Rather, the IASB could consider a fundamental review of the requirements for financial institutions in the longer term.
137This research paper sets out results of desk-based research undertaken to understand the key issues with the statement of cash flows and whether standard setting could address some of those perceived issues, helping preparers better understand the requirements in IAS 7 and providing users with more useful information. The UKEB has not yet concluded on what recommendations it has, if any, for amending the statement of cash flows. Any future recommendations will be developed based on a range of evidence, research and outreach.
138The UKEB Secretariat will now engage with UK stakeholders to hear their views.
139Outreach will include seeking suggestions for targeted improvements to IAS 7, an understanding of the information investors request or receive outside of the financial statements and whether such information should be included in the primary financial statements.
140Further research is needed to fully understand the changes required to the statement of cash flows before any path forward is considered. The UKEB will continue to undertake proactive research on the Statement of Cash Flows and Related Matters.
141There also remain opportunities for further research on the Statement of Cash Flows and Related Matters in the UK. The UKEB would encourage stakeholders to also consider undertaking relevant academic and professional research. There are many potential areas that would be of interest, from the perspectives of both preparers and users of financial statements in the UK.
142We are aware that several national standard-setters41 have ongoing, or recently completed, standard setting or research projects on the topic. We are reviewing the outputs of these projects for evidence on the nature and extent of the perceived key issues identified by the IASB in other jurisdictions, the likely benefits of developing new requirements, and to identify whether other issues have been raised. A summary will be considered by the Board at a future date.
143This paper, and others, will be used to assist the Board in its future work, including to stimulate debate, engage with the IASB and other national standard-setters or regional organisations, with the aim of ultimately supporting the development of high-quality international accounting standards for use in the UK and internationally.
Appendix A: Glossary
| Term | Description |
|---|---|
| ACCA | The Association of Chartered Certified Accountants |
| AASB | The Australian Accounting Standards Board |
| AcSB | The Canadian Accounting Standards Board |
| CapEx | Capital expenditure |
| CMAC | The IFRS Foundation Capital Markets Advisory Committee |
| Conceptual Framework | IFRS Foundation Conceptual Framework for Financial Reporting (revised March 2018) |
| EFRAG | The European Financial Reporting Advisory Group |
| FRC | The Financial Reporting Council – UK regulator |
| GPF | The IFRS Foundation Global Preparers Forum |
| IAS 7 | International Accounting Standard (IAS) 7 Statement of Cash Flows |
| IASB | The International Accounting Standards Board |
| IFRS 7 | International Financial Reporting Standard (IFRS) 7 Financial Instruments: Disclosures |
| IFRS 9 | International Financial Reporting Standard (IFRS) 9 Financial Instruments |
| IFRS 15 | International Financial Reporting Standard (IFRS) 15 Revenue from Contracts with Customers |
| IFRS 18 | International Financial Reporting Standard (IFRS) 18 Presentation and Disclosure in Financial Statements |
| Interpretations Committee | The IFRS Interpretations Committee |
| Net Debt Reconciliation | Also known as Statement of changes in net debt |
| NSS | National Standard Setters |
| NWC | Net working capital |
| Users | Primary users of financial statements per the Conceptual Framework paragraph 1.5 |
Appendix B: The Interpretations Committee Agenda decisions
Definition of cash and cash equivalents
B1The Interpretations Committee has considered a number of issues42 related to whether an asset is cash or cash equivalent, including:
- April 2022 Demand Deposits with Restrictions on Use arising from a Contract with a Third Party.
- June 2019 Holdings of cryptocurrencies.
- June 2018 Classification of short-term loans and credit facilities.
- May 2013 Identification of cash equivalents - whether investments can be classified as cash equivalents based on the remaining period to maturity.
- July 2009 Determination of cash equivalents - whether shares or units of money market funds that are redeemable at any time can be classified as cash equivalents.
- March 2008 Classification of expenditures – recommended that IAS 7 should be amended to make explicit that ‘only an expenditure that results in a recognised asset can be classified as a cash flow from investing activity' (IAS 7.16 in April 2009).
- August 2005 Value added Tax - whether cash flows should be presented inclusive or exclusive of value added tax (VAT). The Interpretations Committee recommended that entities should disclose whether the gross cash flows are inclusive or exclusive of VAT.
B2In addition to the Interpretations Committee agenda decisions, whether 'cash in transit' is cash was reflected in Amendments to the Classification and Measurement of Financial Instruments (Amendments to IFRS 9 and IFRS 7), issued by the IASB in May 2024.
Effects of non-cash transactions
B3The Interpretations Committee has considered issues related to the effect of non-cash transactions:
- December 2020 Supply Chain Financing Arrangements—Reverse Factoring an Disclosure of changes in liabilities arising from financing activities.
- September 2019 Disclosure of Changes in Liabilities Arising from Financing Activities.
Appendix C: Bibliography
- ACCA Why cashflow statements are useless. Accounting and Business Magazine. Published November 2020 (accaglobal.com)
- Analyst Prep article Direct and Indirect Methods – Cash from Operating Activities published 5 March 2020
- https://www.askmoney.com/investing/cash-inflow-outflow.
- Basel Committee on Banking Supervision (2008). Principles for Sound Liquidity Risk Management and Supervision, Bank for International Settlements, ISBN 92-9197-767-5 (online). The Statement of Cash Flows–Objectives, usages, and issues 90
- Basel Committee on Banking Supervision (2013). Basel III: The Liquidity Coverage Ratio and liquidity risk monitoring tools, Bank for International Settlements, ISBN 92-9197-912-0 (online).
- BDO IFRS in Practice – IAS 7 Statement of Cash Flows 2022/23, BDO IFRS Advisory Limited.
- Beatty, R., Riffe, S. and Welch, I. 1997. How Firms Make Capital Expenditure Decisions: Financial Signals, Internal Cash Flows, Income Taxes and the Tax Reform Act of 1986. Review of Quantitative Finance and Accounting, 9, 227–250.
- Dechow P, University of California, Berkeley, Ge W, University of Washington, Schrand C, University of Pennsylvania Understanding Earnings Quality: A Review of the Proxies, their Determinants, and their Consequences, 50 J. Acct.& Econ. 344 (August 2010).
- Deloitte. IFRS 18 IASB publishes new standard on presentation and disclosure in financial statements published May 2024
- Deloitte IGAAP 2024 (subscription required)
- Deloitte IASB issues amendments to IAS 7 Statement of Cash Flows requiring disclosure of changes in liabilities arising from financing activities published February 2016
- EFRAG Feedback statement The Statement of Cash Flows: Issues for Financial Institutions published May 2016.
- EFRAG Short Discussion Series THE STATEMENT OF CASH FLOWS ISSUES FOR FINANCIAL INSTITUTIONS published July 2015
- EY IFRS 18 changes financial performance reporting published 14 May 2024
- Financial Accounting Standards Board (FASB) Feedback Summary on the 2021 Invitation to Comment: Agenda Consultation
- FASB Statement of Cash Flows. Presentation for FASB/IASB Education meeting, September 2023
- Financial Reporting Council (FRC) Annual Reviews of Corporate Reporting
- https://www.frc.org.uk/library/supervision/corporate-reporting-review/crr-annual-activity-reports/
- FRC Thematic review: Offsetting in the Financial Statements (2024) https://media.frc.org.uk/documents/Thematic_Review_on_Offsetting_in_the_financial_statements_W8voeL6.pdf
- FRC Thematic review: The audit of cash flow statements (2021) https://media.frc.org.uk/documents/Audit_of_Cashflow_Statements.pdf
- FRC Thematic review: Cash Flow and Liquidity Disclosures (2020) https://media.frc.org.uk/documents/Cash_flow_statements_and_liquidity_IAS_7_IFRS_7.pdf
- FRC Thematic review: Review of financial reporting effects of Covid-19 (2020) https://media.frc.org.uk/documents/Review_of_financial_reporting_effects_of_Covid-19.pdf
- FRC Thematic review: Small Listed and AIM Quoted Companies (2018) https://media.frc.org.uk/documents/Small_Listed_and_AIM_Quoted_Companies.pdf
- FRC Lab project: Disclosures on the sources and uses of cash (2019) https://media.frc.org.uk/documents/Disclosures_on_sources_uses_of_cash_-_FRC_Financial_Reporting_Lab_Report.pdf
- FRC Lab report: Net Debt Reconciliations (2012) https://media.frc.org.uk/documents/FRC_Lab_project_report_Net_Debt_Reconciliations.pdf
- Greuning, H.V., Scott, D. and Terblanche, S. (2013). International Financial Reporting Standards: A Practical Guide – sixth edition (covers all IASB standards through September 2010)
- Hales, J. and Orpurt, S. F. (2013), 'A Review of Academic Research on the Reporting of Cash Flows from Operations', Accounting Horizons, 27 (3), 539–578.
- Investopedia / Hayes, A. Understanding Liquidity and How to Measure It. Investopedia updated 18 May 2024
- Investopedia Cash Flow Statements: Reviewing Cash Flow From Operations updated 30 April 2024
- Investopedia Different Types of Financial Institutions updated 19 September 2023
- Institute of Chartered Accountants in England and Wales (ICAEW) Tips and common pitfalls in preparing and auditing cashflow statements published 10 September 2024.
- International Accounting Standards Board (IASB) IASB/FASB Staff Agenda Paper 7A (70A) October 2009 IASB/FASB meeting
- IASB Staff Agenda Paper 5 June 2009 IASB meeting Changes in liabilities arising from financing activities (IAS 7) – Initial consideration
- IASB Staff Agenda Paper 11B December 2014 IASB meeting
- IASB Staff Paper Agenda 20A Academic Literature Review for the 16 September 2024 IASB meeting.
- IASB Third Agenda Consultation Feedback Statement (July 2022) – see proposed short-listed projects
- IASB Supplier Finance Arrangements amendments to IAS 7 Statement of Cash Flows published May 2023
- IFRS Foundation Amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures.
- IFRS Foundation Conceptual Framework for Financial Reporting (revised March 2018)
- IFRS Foundation IAS 7 Statement of Cash Flows (version prior to 2024 updates re IFRS 18)
- IFRS Foundation Disclosure Initiative (Amendments to IAS 7) January 2016
- IFRS Foundation In Brief: Changes in financing liabilities—what does good disclosure look like?
- Patel A B, OBE Everything You Need To Know About The Importance of Cash Flow In Stock Picking published 7 February 2022.
- PwC IFRS 18 is here: redefining financial performance reporting published 9 April 2024
- PwC FRC areas of focus: IAS 7 & cash flow classification published 23 November 2022
- PwC Viewpoint (subscription required) https://viewpoint.pwc.com/dt/gx/en/iasb/standards/standards__1_INT/standards__1_INT/ias_7_statement_of_c__9_INT/basis_for_conclusion__45_INT.html#pwc-topic.dita_1851090907133734
- The Footnotes Analyst Cooper, S. and Jullens, D. Cash is king – except when analysing performance published 20 May 2024
- The Footnotes Analyst Cooper, S. and Jullens, D. Why IFRS 18 is good news for investors published 20 March 2024
- U.S. Securities and Exchange Commission / Munter, P. The Statement of Cash Flows: Improving the Quality of Cash Flow Information Provided to Investors published 4 December 2023.
Appendix B: Project Initiation Plan
| Exposure Draft Statement of Cash Flows and Related Matters | |
|---|---|
Purpose
B1The UKEB delegated functions include responsibility for "participating in and contributing to the development of a single set of international accounting standards.” Undertaking pro-active thought leadership activities is key to the UKEB's ability to effectively deliver this statutory function.
B2The UKEB's Terms of Reference (ToR) further explain that with regard to thought leadership, the UKEB shall:
- Lead the UK debate on international accounting standards and reporting.
- Represent UK views in international fora with the aim of influencing debate.
- Engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
- Proactively participate in the development of new global accounting standards, for example by undertaking research.
B3A project on the statement of cash flows and related matters, as described below, supports the UKEB meeting these responsibilities. It is also consistent with the 2024–25 Regulatory Strategy as it supports the UKEB's “aim to influence the IASB early on in its standards development cycle, providing evidence-based recommendations and thought leadership on emerging issues from a UK perspective” (page 8).
Background
B4The IASB decided to add a project on the Statement of Cash Flows and Related Matters to its research pipeline following feedback on its Request for Information: Third Agenda Consultation.
B5Most respondents to the Request for Information recommended the addition of a potential project on cash flows to the IASB's workplan and many of them rated it as high priority. It is notable that most users of financial statements who recommended addition of this topic rated it as high priority.
B6The Board received an update on this project, including an overview of the IASB's research plan in an IASB General Update paper in October 2024.
B7The IASB staff have identified the following topics to explore in this project:
- changing the requirements for classifying cash flows into operating, investing and financing categories;
- specific disaggregation requirements for information about cash flows (for example, separating capital expenditures into maintenance and growth);
- changing the definition of cash and cash equivalents;
- requiring the use of the direct method;
- presentation or disclosure requirements for additional information about the non-cash effects of some transactions;
- presentation or disclosure requirements for information about commonly used cash flow measures (for example, free cash flow); and
- specific requirements for the statement of cash flows for financial institutions.
IASB plan for research to support a decision on project scope
B8The IASB staff plan to perform initial research to gather evidence of the nature and extent of the perceived deficiencies and the likely benefits of developing new financial reporting requirements for IAS 7 Statement of Cash Flows. This research is intended to provide evidence to support the IASB's decision on the scope of the project. The initial research will also address possible ways of improving the perceived deficiencies.
B9The IASB is considering a number of approaches it could take to the project. These include:
- A comprehensive review of IAS 7, which could lead to a new IFRS Accounting Standard.
- A phased project that could make targeted improvements to address some of the issues identified in the short-term, while undertaking a longer-term project to perform a comprehensive review of IAS 7.
- A limited project which would identify and address a few specific areas of concern.
B10Initial research findings are expected to be reported to the IASB in Q1 2025, when the IASB will be asked whether it has enough evidence to decide on the project scope at a subsequent meeting.
Opportunity for the UKEB
B11There is an opportunity for the UKEB to build on the work already done in the UK by the FRC (and others). While there has been research into the problems with the statement of cash flows and possible solutions to these problems, to date direct evidence from preparers and users has been limited. The UKEB can utilise its previous stakeholder engagement experience to seek more comprehensive feedback from preparers and investors.
B12Subject to approval of this Project Initiation Plan, this project would aim to gather primary evidence on key stakeholder views, specifically, the improvements investors and creditors want made to the statement of cash flows, and preparer views on these possible improvements. This would provide a foundation for the UKEB to engage with the IASB for this project.
B13Research would be grounded in previous work undertaken by the IASB, FRC and UKEB. It will focus primarily on exploring opportunities already identified for improvements to the statement of cash flows and related disclosures, using targeted stakeholder interviews, supported by UKEB Advisory Group discussions.
B14IFRS 18 Presentation and Disclosure in Financial Statements Primary Financial Statements made limited amendments to IAS 7. The UKEB's IFRS 18 surveys sought views on these changes, and these findings, along with additional research will form part of this research.
B15The IASB's current timetable for completion of the research phase of their project means that the work would be more constrained than previous UKEB pro-active research projects. We would also stage the research so that the Board has opportunity to engage with the research more regularly, with a view to incorporating hose views into the final published report.
Project Plan
Proportionality assessment
Significance and size
IASB Project scope
B16The IASB is currently in the research phase of the project, and no decision has yet been made on the IASB's project scope.
Entities affected by the proposals
B17The statement of cash flows is a primary financial statement that all entities are required to prepare. Any changes have the potential to affect all entities that prepare financial statements using IFRS Accounting Standards.
Complexity
B18The requirements of IAS 7 are quite limited. Generally, the statement of cash flows is not considered a complex area of accounting.
B19However, over the past 14 years, the Statement of cash Flows has been consistently among the top 10 issues identified by the FRC's Corporate Reporting Review (CRR) team as part of the annual review of financial statements. In the last four years it has been one of the top three issues every year, resulting in 46 restatements in company accounts.
Expected timeline / urgency
B20The IASB is expected to start making decisions about the scope of the project in 2025. To effectively participate in this discussion, publishing a research report during H1 2025 would be ideally timed to contribute to the IASB process. The September 2025 Accounting Standards Advisory Forum (ASAF) meeting will provide an opportunity to present a summary of the UKEB's research and views on the direction of the project.
Expected interest / sensitivity
B21As noted above, there was a significant response to IASB's Request for Information: Third Agenda Consultation, calling for a project addressing the statement of cash flows. Given the pervasive nature of the statement there will be significant interest in the project.
B22Early discussions with UK stakeholders have indicated significant interest in the project. There are also strong views on what should be prioritised and the extent to which change is feasible.
Feedback on the proposals from desk-based research / initial outreach
B23There has been significant interest in the UK in the statement of cash flows. As part of this proposed project the Secretariat plan to provide the Board with a comprehensive review of the relevant literature. One key element to that literature is work already done by the FRC.
FRC's Improving the Statement of Cash Flows Report - 2016
B24In 2016, the FRC published a discussion paper “Improving the Statement of Cash Flows” for public comment, which focused on the existing IAS 7 Statement of Cash Flows and was timed to feed into the IASB's Primary Financial Statements project, from which IFRS 18 Presentation and Disclosure in Financial Statements resulted. This was followed in 2017 by a feedback statement of comments received from stakeholders.
B25The discussion paper made a number of recommendations, including:
- Notional cash flows should not be reported in any section of the statement of cash flows. However, transparent disclosure of non-cash transactions should be required.
- Operating activities should be positively defined or described (perhaps as including transactions with customers, employees and suppliers) rather than being a residual or default classification.
- Entities should be encouraged to disclose the extent to which expenditure on property, plant and equipment represents 'maintenance' or 'growth'.
- The statement of cash flows should report inflows and outflows of cash, rather than cash and cash equivalents.
- A reconciliation of profit and cash flow should be presented in all cases (including where a direct method statement of cash flows is presented). The reconciliation should be required to reconcile a sub-total in the statement of profit or loss that represents operating income (rather than, for example, net profit or loss) and reconcile that to cash flow from operating activities.
B26That discussion paper received 22 comment letters, 12 from the UK. Three letters were from preparers and four were from user groups. Some of the highlights from the feedback:
- A large majority of respondents agree that notional cash flows should not be reported in the statement of cash flows although there should be disclosure of non-cash transactions.
- A majority of respondents agree that operating activities be positively defined or described.
- There are split views as to whether the statement of cash flows should report flows of cash or of cash and cash equivalents.
Initial Engagement with UKEB Advisory Groups
B27Early discussions with UKEB Advisory Groups (PAG, IAG, and AFIAG1) have drawn a mixed response. While all AGs seem content that the key issues have been identified by the IASB, there is no clear consensus yet on how those issues could be best tackled. Focusing on the links between the statement of cash flows and the other primary financial statements, however, was a key theme.
B28There was clear support for the UKEB undertaking further research, in particular for exploring possible approaches to enhance the statement of cash flows. A number of members also expressed an interest in participating in that research.
Connectivity
B29A stakeholder who participated in the Investor Advisory Group indicated a growing interest in specifically identifying "green spending" as part of the Statement of cash Flows. With increasing focus on disclosure of entities' climate-related risks it is not unreasonable to expect a greater focus on “green cashflows”.
B30This is also consistent with expectations of the Bank of England and the Basel committee's Principles for the effective management and supervision of climate-related financial risks. Both of which call for greater measurement, disclosure and monitoring of climate risks, and the important role that accounting plays in this process.
B31The implications for connectivity will be assessed as part of the outreach on the project.
Recommended UKEB project scope
B32Based on the proportionality assessment above we recommend a “moderate scope" project and the approach described in this document reflects this.
B33The UKEB would undertake the following set of activities primary outputs of the project currently expected are:
- December 2024: Background paper -- This research paper will set the stage, examining the background of the project, relevant research and including an examination of previous CRR findings. The paper would include discussion of the relevant recent changes made by IFRS 18. It would also analyse the last 10 years of concerns raised by CRR about cash flows as a specific example of some of the issues encountered by preparers.
- March 2025: UK Investor and Preparer Perspectives paper – This research paper will summarise user and preparer perspectives on how the Statement of cash Flows could be improved including consideration of financial institutions. The intention is to conduct around 10 - 12 interviews with a diverse range of users and the same number of preparers of financial statements along with discussion with the IAG (early February) and PAG (early March).
- April 2025: UKEB discussion on its views on scope and approach for the IASB's cash flows project based on research undertaken.
B34In meetings subsequent to the March Board meeting, the UKEB will consider whether:
- the UKEB papers, developed to that, point, should be consolidated into a single comprehensive report for publication; and
- whether additional research is appropriate and feasible given the IASB’s project plan and UKEB priorities at that time.
- May 2025: UKEB Perspectives Discussion Paper (Draft) - This paper will outline the UKEB's recommendations for the scope and approach to the cash flow project. It will be accompanied by an invitation to comment and a 90-day comment period (June – August).
- September 2025: UKEB Perspectives Discussion Paper (Final) - UKEB final discussion paper.
B35There is no intention to undertake research collectively with other parties as part of this project.
Project - key activities
| Key activities | Due Process Handbook |
|---|---|
| Identification of issues for research (this document) | 7.15 |
| Mandatory | |
| Creation of a Project Initiation Plan (this document) | 7.16–7.21 |
| Mandatory | |
| Desk-based research to support the proportionality assessment including: | 7.22 |
|
Optional |
| Outreach activities: | 7.23–7.24 |
| As described above the UKEB will gather views and opinions from UK stakeholders, particularly users and investors, to contribute to the development of this research. This will include one-to-one interviews with preparers and users, and discussions with UKEB Advisory Groups. | Optional |
| Publication of a Background paper2: | 7.25 |
|
Mandatory |
| Publication of an UK Investor and Preparer Perspectives paper2: | 7.25 |
|
Mandatory |
Resources allocated
B36To undertake the activities described in this project plan a project team has been assigned consisting of two Project Directors working with the Project Director – Research Lead. The required resources are allowed for in the 2024/25 UKEB plan and budget.
Project timeline
B37The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses.
| Date | Milestones |
|---|---|
| November 2024 | Project Initiation Plan for Board approval |
| December 2024 | Background paper |
| March 2025 | UK Investor and Preparer Perspectives paper |
| May 2025 | Draft UKEB Perspectives Discussion Paper for Board approval |
| 2025* | Estimated draft paper consultation period (not less than 90 days): June–August |
| September 2025 | Board review of Final UKEB Perspectives Discussion Paper, Feedback Statement, draft Due Process Compliance Statement |
| September 2025 | Final Comment Letter submitted to IASB (deadline xx month 202x) |
| October 2025 | Due Process Compliance Statement for noting. |
To be confirmed
Project Initiation Plan: Statement of Cash Flows and Related Matters - Project timeline.
B38The diagram below is a graphical view of the mandatory milestone activities described above. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any major changes, as the project progresses
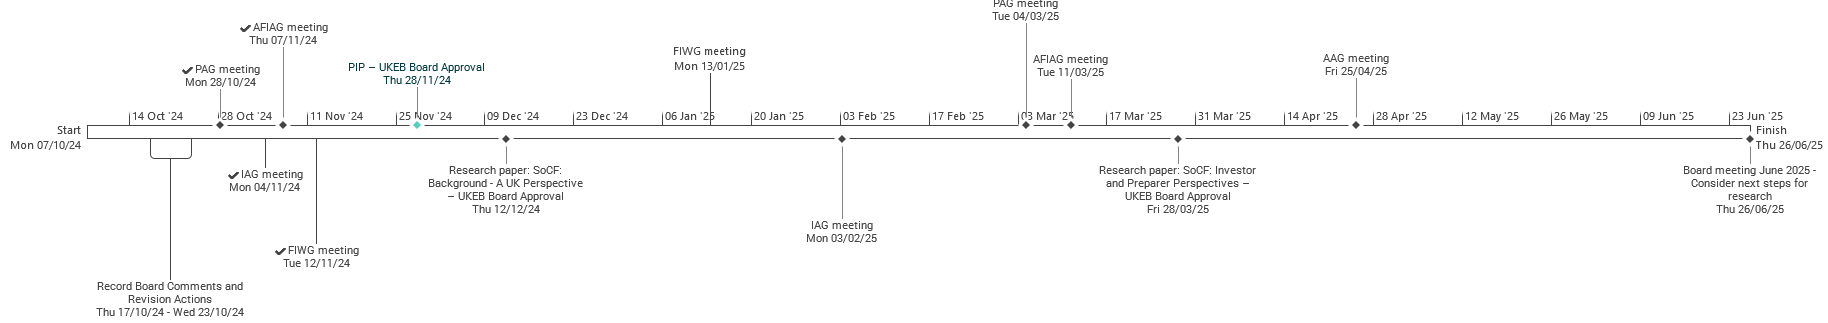
Footnotes
-
Preparers Advisory Group; Investors Advisory Group; Accounting Firms and Institutes Advisory Group ↩↩↩
-
These could be published individually or as part of a consolidated report. ↩↩↩
-
Papers and meeting summaries for the various IASB meetings and their advisory groups can be found on the IASB project webpage here. ↩
-
Academic evidence reviewed by the IASB and presented in Staff Paper Agenda 20A Academic Literature Review for the 16 September 2024 IASB meeting. ↩
-
See Patricia Dechow, University of California, Berkeley, Weili Ge, University of Washington, Catherine Schrand, University of Pennsylvania Understanding Earnings Quality: A Review of the Proxies, their Determinants, and their Consequences, 50 J. Acct. & Econ. 344 (August 2010). ↩
-
The Statement of Cash Flows: Improving the Quality of Cash Flow Information Provided to Investors published by the U.S. Securities and Exchange Commission on 4 December 2023. ↩
-
see Footnote analyst – Cash is king – except when analysing performance published 20 May 2024. ↩
-
Alpesh B Patel OBE: Everything You Need To Know About The Importance of Cash Flow In Stock Picking published 7 February 2022. ↩
-
Paragraph 8 of Staff Paper Agenda 20A Academic Literature Review for the 16 September 2024 IASB meeting. ↩
-
BDO IFRS in Practice – IAS 7 Statement of Cash Flows. ↩
-
In March 2008, The Interpretations Committee issued Classification of expenditures, recommending to the IASB that IAS 7 should be amended to make explicit that 'only an expenditure that results in a recognised asset can be classified as a cash flow from investing activity'. Consequently, in Improvements to IFRSs issued in April 2009, the Board removed the potential misinterpretation by amending paragraph 16 of IAS 7 to state explicitly that only an expenditure that results in a recognised asset can be classified as a cash flow from investing activities, since misinterpretation of the reference in paragraph 11 of IAS 7, for an entity to assess classification by activity that is most appropriate to its business, might have implied that the assessment is an accounting policy choice. ↩
-
In December 2020, The Interpretations Committee published an agenda decision Supply Chain Financing Arrangements–Reverse Factoring considering the impact of a reverse factoring arrangement on presentation in the balance sheet, the derecognition of a financial liability, presentation in the SCF and in the notes to the financial statements. The committee mainly noted: a) the cash flows in a reverse factoring arrangement will typically be classified as either cash flows from operating activities or cash flows from financing activities; and b) the classification of the liability in the statement of financial position may help in determining whether the associated cash flows are from operating or financing activities. ↩
-
Early adoption of IFRS 18 is permitted. ↩
-
The introduction of IFRS 18 will result in a change in practice for some entities now that IAS 7 no longer permits entities to show dividends paid as operating activities. PwC guidance has been that dividends paid could be considered as operating activities because this allows users to determine the entity's ability to pay dividends out of cash flows from operating activities. ↩
-
see Footnote analyst - Why is IFRS 18 good news for investors published 20 March 2024. ↩
-
See page 17 of the IFRS Accounting Effects Analysis IFRS 18 Presentation and Disclosure in Financial Statements published April 2024 ↩
-
Paragraphs 9–11 of Staff Paper Agenda 20A Academic Literature Review for the 16 September 2024 IASB meeting. ↩
-
ACCA AB Magazine article: Why cashflow statements are useless, published in 2020. ↩
-
In June 2018, the Interpretations Committee issued Classification of short-term loans and credit facilities after receiving a request asking about short-term loans and credit facilities that have a short contractual notice period, and the balance does not often fluctuate from being negative to positive to include in its SCF as a component of cash and cash equivalents. The Committee concluded that the entity does not include the short-term arrangements as components of cash and cash equivalents. This is because these short-term arrangements are not repayable on demand. ↩
-
In June 2019, the Interpretations Committee published a decision on Holdings of Cryptocurrencies concluding that IAS 2 Inventories applies to cryptocurrencies when they are held for sale in the ordinary course of business. If IAS 2 is not applicable, an entity applies IAS 38 Intangible Assets to holdings of cryptocurrencies. ↩
-
Amendments to IAS 7 as a result of the Primary Financial Statements project will require the starting point for the indirect method to be 'operating profit' as defined in IFRS 18 Presentation and Disclosure in Financial Statements. ↩
-
See page 37–47 of Greuning, H.V., Scott, D. and Terblanche, S. (2013). International Financial Reporting Standards: A Practical Guide – sixth edition (Chinese, English). Washington, D.C., World Bank Group. ↩
-
Analyst Prep article Direct and Indirect Methods – Cash from Operating Activities published 5 March 2020. ↩
-
Observations conveyed by some Board members at the IASB September 2024 meeting. ↩
-
Paragraphs 13–19 of Staff Paper Agenda 20A Academic Literature Review for 16 September 2024 IASB meeting. ↩
-
In May 2023, the IASB issued Supplier Finance Arrangements, which amended IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures. The Amendments complement the existing disclosure requirements in IFRS Accounting Standards and are aimed at providing users of financial statements with information to assess the effect of supplier finance arrangements on an entity's liabilities, cash flows and exposure to liquidity risk. ↩
-
One article suggests that 90% of companies use the indirect method https://www.askmoney.com/investing/cash-inflow-outflow). See also Hales, J. and Orpurt, S. F. (2013), 'A Review of Academic Research on the Reporting of Cash Flows from Operations', Accounting Horizons, 27 (3), 539–578. ↩
-
The main exception is companies in financial sectors such as banking and insurance. ↩
-
Amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures. ↩
-
In September 2019, the Interpretations Committee concluded in its agenda decision Disclosure of Changes in Liabilities Arising from Financing Activities that the principles and requirements in IFRS Standards provide an adequate basis for an entity to disclose information about changes in liabilities arising from financing activities that enables investors to evaluate those changes. Accordingly, the Committee concluded that the disclosure requirements in IAS 7.44B–44E, together with requirements in IAS 1, are adequate to require an entity to provide disclosures that meet the objective in IAS 7.44A. ↩
-
see Footnote analyst-Why is IFRS 18 good news for investors published 20 March 2024. ↩
-
See IAS 7.44A–44E. ↩
-
ACCA AB Magazine article: Why cashflow statements are useless, published in 2020. ↩
-
A point raised by one Board member at the IASB September 2024 meeting was that Management Performance Measures (MPMs) would be welcomed by users. ↩
-
See section 4.6.7 (page 37–47) of Greuning, H.V., Scott, D. and Terblanche, S. (2013). International Financial Reporting Standards: A Practical Guide – sixth edition (Chinese, English). Washington, D.C., World Bank Group. ↩
-
Paragraphs 20–24 of Staff Paper Agenda 20A Academic Literature Review for 16 September 2024 IASB meeting. ↩
-
Whilst working capital can be very insightful in determining a company's short-term health, some downsides to the calculation can make the metric difficult to interpret: a) Complexity: Working capital impacted by movements in all current asset and current liability accounts. Key information can be hidden by aggregation. b) Nature of assets: Working capital fails to consider the specific types of underlying accounts. c) Causes: The causes of changes may not be clear. ↩
-
Wall Street Prep: Change in Net Working Capital (NWC) Step-by-Step Guide to Understanding Change in Net Working Capital (NWC) updated 30 July 2024, which includes examples of calculating changes in net working capital. ↩
-
E-Investing for beginners: Changes in Working Capital: An Easy Walk Through by Dave Ahern updated 3 June 2024, which includes examples of calculating changes in working capital. ↩
-
The Discussion Paper, responses, Feedback Statement and letter to the IASB can be found on the FRC website. ↩
-
Other national standard setters include the Australian Accounting Standard Board (AASB), the Canadian Accounting Standards Board (AcSB), and the European Financial Reporting Accounting Group (EFRAG). ↩
-
BDO Global - Statement of Cash Flows ↩