4 Results of the surveys on IFRS 18 Presentation and Disclosure in Financial Statements and identification of significant issues
12 December 2024 Agenda Paper 4
UKEB UK Endorsement Board
Executive Summary
| Project Type | Endorsement and adoption project |
|---|---|
| Project Scope | Significant |
Purpose of the paper
This paper provides:
1The criteria used by the Secretariat to identify and assess 'significant' issues for inclusion in the UKEB's draft endorsement criteria assessment (DECA). 2A preliminary summary and analysis of the feedback obtained on the preparer and user surveys on IFRS 18 Presentation and Disclosure in Financial Statements. 3An update on the timeline of the planned activities for the IFRS 18 endorsement work during 2025.
Summary of the Issue
In line with the Project Initiation Plan (PIP) on IFRS 18, the preparer and user surveys were undertaken during Q3 and Q4 2024 to gather evidence on key aspects of IFRS 18. The Board agreed to include an explicit project milestone to review the survey results. The aim of the review is to determine whether survey evidence was sufficient for the Board to form the basis for its preliminary decision in the DECA, or further outreach or research was needed.
Significant issues for inclusion in DECA
When considering the feedback received from stakeholders, the Secretariat developed criteria to identify and assess issues to be included for detailed consideration the DECA on an exceptions-based approach, consistent with previous significant adoption projects. The details of an initial assessment of issues against those criteria is included in Appendix A.
Feedback from Surveys
The survey results indicated that the requirements in IFRS 18 have been generally well-received by both preparers (see Appendix B) and users (see Appendix C). Respondents showed support for specific aspects of IFRS 18 but highlighted a few potential areas of concern or difficulty.
From a long-term public good perspective, respondents indicated that the costs associated with the implementation of IFRS 18 are expected to be low as a share of operating costs and users will expect to reap several benefits from the adoption of IFRS 18. In addition, some ad hoc outreach with auditors via a questionnaire provided input on the relevant impact on audit processes and increase in costs for their work (see Appendix D). No wider economic impact was identified.
Consideration of further outreach
The Secretariat's preliminary analysis of the feedback received indicates that the areas of concern or difficulty raised by respondents (mostly technical accounting issues) can be considered 'significant'. None appear so critical in nature that further evidence would be needed before the commencing the drafting of the DECA. Therefore, this paper does not recommend additional outreach or research activities, including commissioning an external economic report.
Decisions for the Board
Overall: Paper 4
1Does the Board agree with the criteria used in the identification of ‘significant' issues for detailed consideration in the DECA?
Appendix A
2Does the Board agree with the Secretariat's preliminary assessment against the criteria for identification of the 'significant' issues?
Appendix B
3Does the Board have any questions or comments on the preliminary [draft] report results from preparers' survey?
Appendix C
4Does the Board have any questions or comments on the preliminary [draft] report results from users' survey?
Overall: Paper 4
5Does the Board agree that there is no need to conduct significant additional outreach or research activities (including commissioning an external economic study on the possible impact of the use of IFRS 18 in the UK)?
Recommendation
The UKEB Secretariat recommends that the Board:
- Considers and approves the criteria used in the identification of 'significant' issues.
- Considers and approves that the Secretariat does not need to conduct additional significant outreach or research activities (including commissioning an external economic study on the possible impact of the use of IFRS 18 in the UK).
- Considers and approves the Secretariat's preliminary assessment of the issues identified as 'significant'.
- Provides comments on the preliminary [drafts] report results from preparers' and users' surveys.
Appendices
Appendix A: Preliminary assessment of 'significant' issues Appendix B: Preliminary [draft] report of results from preparers' survey Appendix C: Preliminary [draft] report of results from users' survey Appendix D: Preliminary [draft] report of views from auditors' questionnaire Appendix E: Design of the surveys
Background
1The UKEB endorsement work on IFRS 18 Presentation and Disclosure in Financial Statements formally commenced earlier this year (February 2024) when the Board approved the Project Initiation Plan (PIP) for the project to assess whether the requirements of IFRS 18 meet the UK's statutory requirements for adoption of IFRS as set out in Statutory Instrument 2019/685 (the Regulations). The PIP was subsequently presented for noting in March 2024 (with a few amendments agreed by the Board at the March 2024 Board meeting).
2As agreed in the PIP (see paragraphs 14-15) the Secretariat:
- Organised educational activities (a webcast in May 20241 and a webinar in July 20242) with the participation of the IASB to educate UK stakeholders on the main requirements of IFRS 18.
- Carried out preparer and user surveys in Q3 2024 which focused on gathering evidence on whether IFRS 18:
- meets the technical accounting criteria3; and
- is likely to be conducive to the long-term public good in the UK4 (i.e. assessment of costs and benefits and wider economic impact).
The surveys also helped the Secretariat gain more information on the issues previously identified by UK stakeholders5 and on their level of significance (more detail below and in Appendix A).
4In late October 2024 and early November 2024, the Secretariat discussed some of the preliminary feedback received from preparers, users and auditors with members of the UKEB's advisory groups (PAG, AFIAG and IAG7) to cross-validate the survey results with the relevant stakeholder groups and identify any other areas of concern.
5The PIP also included an explicit milestone in Q4 2024 to review a preliminary summary and analysis of the feedback obtained on the preparer and user surveys on IFRS 18. This was aimed at assessing whether further research e.g., commissioning an external economic study, was necessary to provide the Board with information to be used as the basis of its preliminary decisions in the DECA.
6The appendices to this paper provide the Board with a:
- Preliminary assessment of the level of significance of the main issues identified from the feedback obtained on the preparer and user surveys on IFRS 18. This summary has also been supplemented with views from UKEB's advisory groups (refer to Appendix A).
- Preliminary (draft) reports of survey results from preparers (Appendix B) and of survey results from users (Appendix C). These Appendices include:
- an overview of respondents;
- a summary of their views on the main technical requirements of IFRS 18; and
- a summary of their views on the expected costs and benefits and the wider economic impact of this standard.
A brief summary of the key messages received from the survey results from preparers and users is included at the end of this paper.
- The results from the short questionnaire that was distributed by the UKEB to members of the UKEB AFIAG (Appendix D).
- The methodology used to conduct the surveys (Appendix E).8
Criteria for identifying 'significant' issues
7The Secretariat developed certain criteria to aid in the identification and assessment of 'significant' issues for inclusion in the DECA. These criteria are largely consistent with those used in previous adoption work.
8A 'significant' issue means an aspect of IFRS 18 that is likely to have one or more of the following features:
- It has generated significant UK public interest and/or controversy.
- It has been subject to substantial debate with stakeholders raising practical challenges.
- There is a question over whether IFRS 18's requirements meet a particular aspect of the technical accounting criteria (i.e. understandability, relevance, reliability or comparability).
- A particular issue is expected to have a significant direct economic effect on UK entities using UK-adopted international accounting standards due to, for example, the size of the effect, the nature or scope of the issue or the number of entities affected.
- It has a potentially material, indirect economic impact in the UK (e.g. to the long term public good and/or to the efficient and effective functioning of UK capital markets).
9A preliminary assessment of issues, identified during outreach, against these criteria is included at Appendix A.
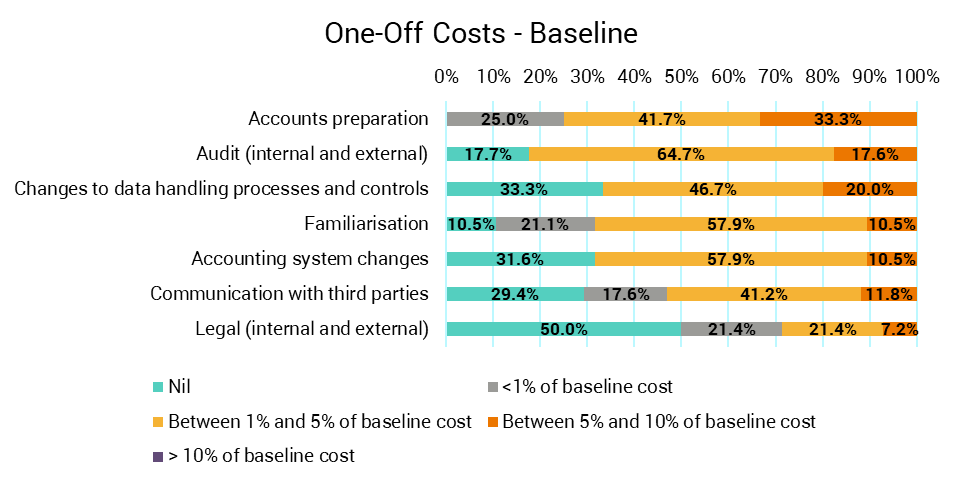
Question for the Board
1Does the Board agree with the criteria used in the identification of 'significant' issues for detailed consideration in the DECA?
Key messages from the preparer and user surveys
10A high-level summary of the results from both surveys is included below. Detailed summaries are included in Appendices B and C of this paper. Information about survey design and the survey questions is in Appendix E of this paper.
Feedback on technical accounting requirements in IFRS 18
11IFRS 18 has been generally well-received by preparers and users. They highlighted support for specific aspects of IFRS 18 but also went on to identify a few potential areas of concern or difficulty.
Categories and subtotals
12There was general agreement that the requirements for categories and subtotals in the income statement would enhance comparability and consistency, in particular by users of financial statements who found the new structure a useful starting point for their analysis.
13A few preparers found some of the specific classification requirements in IFRS 18 challenging. Preparers were concerned that allowing an accounting policy choice9 in IFRS 18 for entities that provide financing to customers as a main business activity would impair comparability across entities applying that choice.
14Both preparers and users expressed mixed views on the requirements to classify income and expenses from investments in associates and joint ventures accounted for using the equity method in the investing category. Some of these respondents think that entities should have flexibility to classify these income and expense in the operating category when these investments are integral to the entity's main business operations. Users did not express strong views in this respect.
Management-defined performance measures
15Preparers agreed in principle with the requirements on management-defined performance measures but found the disclosure of the effects for tax and NCI leading to extra costs. Users welcomed the discipline and transparency that these requirements would bring. Some preparers observed that the co-existence of both MPMs and alternative performance measures (APMs) would lead to users' confusion. By contrast, a number of users reported that they understand the nature of MPMs and APMs.
Aggregation and disaggregation
16Although preparers generally expressed agreement for the improved requirements on aggregation and disaggregation, a few raised concerns about introducing principles-based guidance that could potentially involve significant judgment and lead to inconsistent application and lack of comparability. Preparers in general did not find the disclosure of specified operating expenses by nature10 challenging. Users in general welcomed this disclosure.
Limited changes to the statement of cash flows
17Respondents (preparers and users) agreed in principle with the limited changes to the statement of cash flows. However, there was some disappointment that IFRS 18 had not sought full alignment between the categories in the income statement and the activities in the statement of cash flows.
Feedback on costs and benefits and wider economic impact
18The implementation costs associated with IFRS 18 (comprised of incremental one-off and ongoing costs) are expected to be low, both in terms of operating costs and baseline costs (i.e., the cost to prepare their most recent set of annual financial statements). Audit costs are expected to see the highest percentage increase out of all cost categories, followed by accounts preparation, accounting system changes/maintenance and familiarisation.
19Most users expect the standard will lead to more efficient use of time spent analysing financial statements, and an increase in the quality of analysis/reports.
20Preparers were of the view that the standard would have a positive effect on (i) comparability of the entity's reporting of financial performance; and (ii) transparency of the entity's reporting of financial performance.
21Users were of the view that the standard would improve the ability to compare entities' performance (i) over multiple periods, (ii) with other entities; and to assess an individual entity's performance.
22Overall, both preparers and users believe the standard will have either mildly positive or no effect on the wider economy.
Secretariat's preliminary assessment
23The Secretariat's preliminary analysis in Appendix A against the criteria noted in paragraph 8 above, indicates that the areas of concern or difficulty raised by respondents (mostly technical accounting issues) can be considered 'significant'. However, none are so critical in nature that they would delay commencement of the drafting of the DECA.
24Therefore, the Secretariat does not consider that additional outreach or research activities11, including commissioning an external economic study, need to be performed. The Secretariat expects to carry out a few 1-2-1 interviews to gather some additional information on implementation costs (in line with paragraph 23 of the PIP12). These are in train.
Project timetable and next steps
25A high-level project timeline is presented, subject to Board agreement that no critical evidence has emerged from the feedback received and that commissioning an external economic study is not necessary. It suggests that no changes are necessary to the original PIP plan. This means that the Secretariat plans to commence work on drafting the Draft Endorsement Criteria Assessment (DECA) on IFRS 18 and bring it for Board approval in the coming months.
Question for the Board
5Does the Board agree that there is no need to conduct additional outreach or research activities (including commissioning an external economic study on the possible impact of the use of IFRS 18 in the UK)?
26In line with the activities carried out in the past for major projects (i.e. IFRS 17) the Secretariat plans to issue separate reports of the results from the preparers' survey (included in Appendix B) and of the results from the users' survey (included in Appendix C) and use them as supporting materials for the DECA.
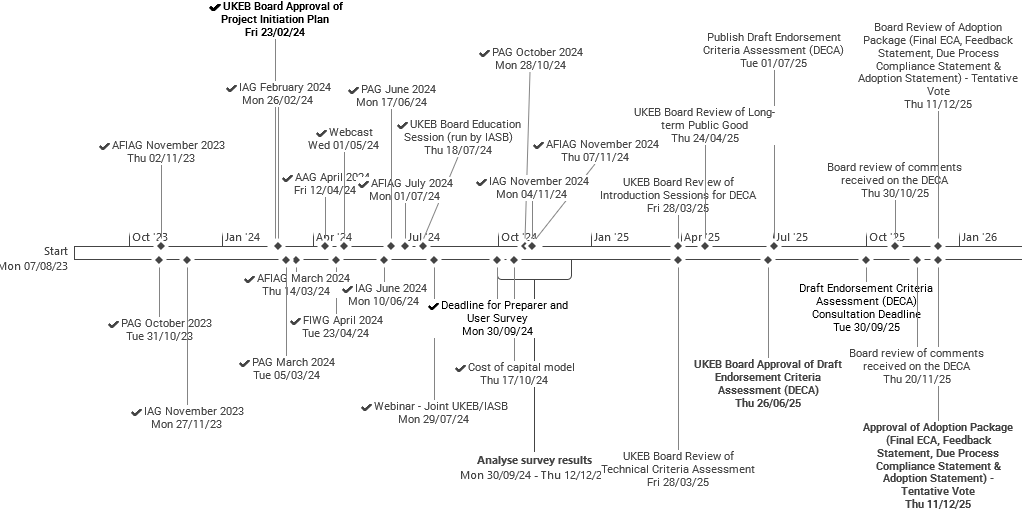
Annex 1: Timeline for IFRS 18 endorsement
27The timeline below for the endorsement of IFRS 18 assumes (a) no critical evidence has emerged from the feedback received and (b) the Board makes an adoption decision by the end of Q4 2025.
This diagram presents a detailed project timeline for IFRS 18 endorsement, structured by activity type (Education activities, Outreach, Economics, DECA and ECA) and across time from Feb-Mar 2024 to Q4 2025. It highlights key milestones such as PIP approval and noting, educational webcasts and webinars, preparer and user surveys (Q3-Q4 2024), engagement with advisory groups, cost of capital model development, DECA drafting, and Board review and approval processes. A significant "Review milestone" is marked in Dec 2024, leading into drafting and consultation periods for the DECA in 2025.
Annex 2: Financial Statements MSP Plan - Upcoming Tasks report
Appendix A: Preliminary assessment of significant issues
Background
A1As explained in paragraph 45(a) of the Project Initiation Plan, the assessment of whether IFRS 18 meets the technical accounting criteria of understandability, relevance, reliability and comparability is made for IFRS 18 as a whole.
A2The assessment necessarily involves considering specific individual aspects of the requirements. In reporting this assessment in the Draft Endorsement Criteria Assessment (DECA), the Secretariat will focus its analysis only on significant issues raised by UK stakeholders (an 'exceptions-based' approach). This means assessing all UK-specific concerns arising from the requirements in the standard against the technical accounting criteria but reporting in the DECA the detailed analysis only in relation to “significant” issues.
A3This paper provides a preliminary assessment of issues identified against certain criteria developed to aid the identification and assessment of 'significant' issues for inclusion in the DECA.
A4The process adopted to identify the 'significant' issues in this paper involved:
- Desktop analysis of the requirements in IFRS 18 and the basis for these requirements.
- Review of the UKEB Secretariat response to the IASB's Exposure Draft ED/2019/7 General Presentation and Disclosures (ED).
- Identification of preliminary issues (that were reported as part of the PIP).13
- Review of survey results from preparers and from users.
- Input from the UKEB's advisory groups.
- Other sources, such as the EFRAG's Draft Endorsement Advice on IFRS 18.
A5As a reminder, the criteria used to identify a 'significant' issue are listed below (and are largely consistent with those used in previous adoption work). To qualify, an issue is likely to have one or more of the following features:
- It has generated significant UK public interest14 and/or controversy.
- It has been subject to substantial debate with stakeholders raising some practical challenges.
- There is a question over whether IFRS 18's requirements meet a particular aspect of the technical accounting criteria (i.e., understandability, relevance, reliability or comparability).
- A particular issue is expected to have a significant direct economic effect on UK entities using UK-adopted international accounting standards due to, for example, the size of the effect, the nature or scope of the issue or the number of entities affected.
- It has a potentially material, indirect economic impact in the UK (e.g. to the long term public good and/or to the efficient and effective functioning of UK capital markets).
What did the analysis reveal?
A6The application of the criteria noted above led to the following 'significant' issues being identified:
- Classification of income and expenses from associates and joint ventures accounted for using the equity method in the investing category.
- Accounting policy choice for the classification of income and expenses for entities that provide financing to customers.
- Having two sets of performance measures (MPMs and Alternative Performance Measures (APMs)) in the annual report.
- Disclosure of the income tax effect and the effect on non-controlling interests (NCI) in the MPM reconciliation.
A7A description of the issue together with the Secretariat's initial analysis of the level of significance are listed in Table A1 below.
A8In the Secretariat's view none of the issues identified are critical in nature so that they would delay commencement of the drafting of the DECA because:
- They would not present significant or material challenges as to whether, overall, they meet the technical accounting criteria, the long-term public good criteria or the true and fair view.
- For each of the issues identified there are mitigating factors that could potentially reduce the level of significance or effect of the issue identified.
A9The Secretariat considers that there is sufficient evidence already gathered to draft a preliminary assessment for the Board to consider on these issues. Therefore, no additional outreach activities to assess these issues in more depth are proposed15.
Question for the Board
2Does the Board agree with the Secretariat's preliminary assessment against the criteria for identification of the 'significant' issues?
Table A1: List of preliminary main "significant" issues identified
Issues relating to categories and subtotals
Classification of income and expenses from associates and joint ventures accounted for using the equity method in the investing category
| Summary of IFRS 18 requirements | IFRS 18 requires entities to classify in the investing category all income and expenses from investments in associates and joint ventures accounted for using the equity method. This includes (a) the entity's share of profit or loss from associates, joint ventures and unconsolidated subsidiaries; and (b) other income and expenses from those investments (e.g. impairment losses). In addition, the transitional provisions in paragraph C7 of IFRS 18 allow an eligible entity to change its election for measuring an investment in an associate or joint venture from the equity method to fair value through profit or loss (applying paragraph 18 of IAS 28 Investments in Associates and Joint Ventures). |
|---|---|
| Concerns raised | Stakeholders have asked for flexibility in the classification of income and expenses from equity-accounted investments in associates and joint ventures as part of the 'operating' category when these investments are considered 'integral' to the entity's main business activities. In their view this would allow users to understand the true nature and strategic value of these investments within the entity's main business operations. Insurers are particularly concerned that not classifying those income and expenses in ‘operating' would create a presentation mismatch as the operating category would only include expenses related to insurance contract liabilities and no associated investment results from the assets (that are used to back insurance contracts). Users did not express strong concerns in respect of the required classification in investing. Some stakeholders did not support the election offered on transition to IFRS 18 because:
|
Footnotes
Table A1: List of preliminary main “significant” issues identified
Issues relating to categories and subtotals
Classification of income and expenses from associates and joint ventures accounted for using the equity method in the investing category
Summary of IFRS 18 requirements
IFRS 18 requires entities to classify in the investing category all income and expenses from investments in associates and joint ventures accounted for using the equity method. This includes (a) the entity's share of profit or loss from associates, joint ventures and unconsolidated subsidiaries; and (b) other income and expenses from those investments (e.g. impairment losses).
In addition, the transitional provisions in paragraph C7 of IFRS 18 allow an eligible entity to change its election for measuring an investment in an associate or joint venture from the equity method to fair value through profit or loss (applying paragraph 18 of IAS 28 Investments in Associates and Joint Ventures).
Concerns raised
Stakeholders have asked for flexibility in the classification of income and expenses from equity-accounted investments in associates and joint ventures as part of the 'operating' category when these investments are considered 'integral' to the entity's main business activities. In their view this would allow users to understand the true nature and strategic value of these investments within the entity's main business operations.
Insurers are particularly concerned that not classifying those income and expenses in ‘operating' would create a presentation mismatch as the operating category would only include expenses related to insurance contract liabilities and no associated investment results from the assets (that are used to back insurance contracts).
Users did not express strong concerns in respect of the required classification in investing.
Some stakeholders did not support the election offered on transition to IFRS 18 because:
- Introducing an election would only impair comparability across entities in the same sector/industry;
- The election is limited to eligible entities;
- Using fair value to measure an investment in an associate or joint venture may add a layer of complexity and subjectivity for the measurement of some of these investments.
Preliminary analysis of the level of “significance” of the issue
The following points are relevant in this analysis:
UK preparer respondents to the survey and members of UKEB's advisory groups (Preparer Advisory Group (PAG) and Accounting Firms & Institutes Advisory Group (AFIAG)19) questioned whether the classification of income and expenses from associates and joint ventures accounted for using the equity method in the investing category would lead to relevant information for users.
In addition, in the UK there is currently diversity of practice in classification of results of associates and joint ventures, as some entities include these results in operating profit and others present them elsewhere within the income statement20.
Mitigating factors
Entities will be able to indicate that their equity-accounted investments are 'integral' by including an additional subtotal (i.e. operating profit and income and expenses from associates and joint ventures accounted for using the equity method)
Entities could also add MPMs to adjust for the effect of the income and expenses derived from equity-accounted investments (e.g. adjusted operating profit).
Eligible entities could elect to measure an investment in an associate or joint venture from the equity method to fair value through profit or loss on transition to IFRS 18.
Issues relating to categories and subtotals
Accounting policy choice for the classification of income and expenses for entities that provide financing to customers
Summary of IFRS 18 requirements
IFRS 18 includes requirements for entities that provide financing to customers as a main business activity. The entities are required to make an accounting policy choice to classify, in the operating category or in the financing category, income and expenses from liabilities that arise from transactions that involve only the raising of finance (and that are not related to the provision of financing to customers).
Concerns raised
Concerns have been raised on the potential loss of comparability resulting from the application of the accounting policy choice that is permitted for entities that provide financing to customers as a main business activity. For example, a bank or a manufacturing entity that provides financing to customers could exercise this choice in different ways.
Stakeholders also think that it will be challenging for entities to communicate their accounting policy choice to investors to explain why certain income and expenses are classified in different categories of the income statement.
Preliminary analysis of the level of “significance” of the issue
The following points are relevant in this analysis:
UK preparer respondents to the survey and members of the UKEB's Financial Instruments Working Group (FIWG)[^18] questioned whether providing an accounting policy choice would lead to comparable information across entities in the same sector.
In addition, in the UK there is currently diversity of practice in the presentation of income and expenses where entities provide finance to customers as a main business activity.[^19]
Mitigating factor: Consistent practices may develop within individual sectors once IFRS 18 is implemented.
Issues relating to management-defined performance measures (MPMs)
Having two sets of performance measures (MPMs and Alternative Performance Measures (APMs)) in the annual report
Summary of IFRS 18 requirements
Entities are required to disclose information about MPMs in a single note to the financial statements as to why and how the measure(s) communicate(s) management's view of an aspect of the entity's financial performance. Alternative performance measures outside of the scope of MPMs will be presented outside the financial statements.
Concerns raised
Concerns have been raised on the co-existence of two sets of performance measures (i.e. MPMs and APMs) because it could lead to user confusion in respect of:
- The type of measures that would be included within the scope of MPMs (e.g. adjusted operating profit is an MPM but adjusted revenue is not an MPM).
- Including MPMs and APMs in different locations of the annual report (i.e. MPMs are required to be included as part of the financial statements; whereas APMs are generally included in the annual report, i.e. outside the financial statements).
Feedback also suggested that potentially more internal controls may be needed on the investor relations material, because the MPMs will be required to be signed off by the auditors unlike the APMs.
Stakeholders also envisaged challenges communicating MPMs internally and externally, particularly regarding the scope of MPMs.
Some stakeholders also indicated that they may incur additional costs by subjecting MPMs to audit (as APMs are not required to be audited).
Preliminary analysis of the level of “significance” of the issue
The following points are relevant in this analysis:
The co-existence of different performance measures (APMs and MPMs) in the annual report has generated significant UK public interest. UK preparer respondents to the survey and members of PAG[^20] have questioned whether having these two sets of performance measures in the annual report provides relevant and understandable information.[^21]
Preparer respondents to the survey have also noted that subjecting MPMs to auditing could present challenges for both preparers (i.e. could increase audit fees) and auditors (i.e. could add complexity to the audit process[^22]).
Mitigating factor
Users are sophisticated enough to understand the difference between APMs and MPMs.
Users have also reported that auditing MPMs will enhance user's confidence and credibility in these measures.
Issues relating to management-defined performance measures (MPMs)
Disclosure of the income tax effect and the effect on non-controlling interests (NCI) in the MPM reconciliation
Summary of IFRS 18 requirements
Entities are required to disclose the income tax effect and the effect on non-controlling interests for each reconciling item disclosed in the MPM reconciliation.
Concerns raised
Concerns have been raised on the disclosure requirements of the effects of income tax and NCI in the MPM reconciliations because it would lead to additional work and the allocation of these effects would not necessarily lead to useful information for users.
Respondents also reported that their current practices are not consistent with the requirement in IFRS 18 to:
- Include the tax effect for each reconciling item and a description of how this tax effect is determined. This is because:
- Their reconciliation is to operating profit so adding the tax effects is viewed as unnecessary;
- The tax effects would be immaterial;
- The tax effects would be of little value, as users in other jurisdictions do not normally request this information; and
- The tax effects are normally provided aggregated for the combined reconciling items and not for each individual reconciling item.
- Include the effect on non-controlling interests (NCIs) for each reconciling item. This is because these effects are considered immaterial or the entity does not have a NCI include the tax or NCI effects for each reconciling item.
Preliminary analysis of the level of “significance” of the issue
The following points are relevant in this analysis:
UK preparer respondents to the survey and members of AFIAG[^23] questioned (a) the need for this disclosure the disclosure of the income tax effect and the effect on NCI in the MPM reconciliation and (b)
whether it would lead to relevant and more understandable information for users.
Preparers have also raised practical challenges in implementing the requirement to disclose the tax effect for each reconciling item and some think this may be complex and costly[^24].
Mitigating factors
Users have reported that information on NCI and tax effects is useful for their analysis.
IFRS 18 allows three options for calculating the tax effect for each reconciling item within the MPM reconciliation. Amongst these options, IFRS 18 allows a “simplified approach”[^25], which could potentially alleviate the costs of preparing disclosures about the tax effects for preparers.
Appendix B: Preliminary [draft] report results from preparers' survey
Background
B1This Appendix summarises the preliminary results of the preparers' survey on IFRS 18 Presentation and Disclosure in Financial Statements and provides:
- An overview of respondents followed by a summary of their views.
- A detailed summary of the feedback received on the main technical requirements of IFRS 18. More specifically on:
- categories and subtotals;
- management-defined performance measures (MPMs);
- aggregation and disaggregation; and
- limited changes to the statement of cash flows.
- A detailed summary of the feedback received on the perceived costs and benefits of IFRS 18 and the wider economic impact, comprised of assessments of:
- implementation costs;
- direct benefits; and
- wider economic effects.
Overview of survey responses
Demographics
B3The survey gathered a total of 46 responses from preparers using UK-adopted International Accounting Standards in their financial statements that are either listed or incorporated in the UK. Nearly all responses (96%) were submitted on behalf of a group. The remaining responses (4%) came from individual entities.
B4Of the responding entities:
- 41% are listed on the FTSE 100;
- 22% are listed on the FTSE 250;
- 11% are listed on the Alternative Investment Market (AIM); and
- 26% are either UK private companies or UK subsidiaries of companies listed abroad.
B5The responses came from a broad representation of eleven key UK sectors ranging from the financial services sector, through to real estate and basic materials (see Chart 1 below).
Chart 1: Industry distribution of the respondents in preparers' survey

B6Around 19 respondents (41%) have at least one of the two 'specified main business activities' as defined in IFRS 18 (i.e. either they invest in assets or provide financing to customers or carry out both activities). Among these respondents:
- 11 entities invest in assets as a main business activity;
- 4 entities provide financing to customers as a main business activity; and
- 4 entities have both specified main business activities.
Familiarity with the requirements in IFRS 18
B7Almost all respondents[^26] reported being familiar with the requirements in IFRS 18. However, amongst those respondents just over a quarter reported having done an in-depth assessment of the Standard. These results are shown below.
Chart 2: Level of familiarity with the requirements in IFRS 18

Overall views
Overall rating
B8Respondents were generally supportive of specific aspects of the requirements of IFRS 18. When asked about the overall support of the requirements in IFRS 18 (using a scale of 1 (no knowledge) to 10 (extensive knowledge)), the average rating for all respondents was 6[^27]. This was due to potential areas of concern or difficulty that are described in this report.
Expected changes
B9Four respondents (9%) observed that the application of IFRS 18 is not expected to bring significant changes to the data they currently collect. These respondents also considered that IFRS 18 is not expected to bring significant changes to the way they are presenting or disclosing information.
B10One respondent did not consider that there was a need for a new standard on presentation and disclosure. Another respondent did not foresee many benefits on the application of IFRS 18 for their particular industry.
Whether there is enough time to implement IFRS 18
B11One respondent noted that the effective date of IFRS 18 of 1 January 2027, is reasonable and allows sufficient time to implement the Standard. On the contrary, another respondent suggested that the timeline of adoption may be challenging. It was also noted that for entities that have dual listings and are required to provide more than one comparative period it may take them longer to implement IFRS 18.
Section 1: Feedback on technical requirements
Categories and subtotals
B12The survey obtained respondents' views on:
- The overall requirements on defined categories and subtotals.
- The requirements for entities with specified main business activities (that either they invest in assets or provide financing to customers or carry out both activities).
- The classification of income and expenses from investments in associates and joint ventures accounted for using the equity method in the investing category (i.e. equity-accounted investments).
- The transitional provisions in paragraph C7 of IFRS 18 that allow an eligible entity to change its election for measuring an investment in an associate or joint venture from the equity method to fair value through profit or loss (applying paragraph 18 of IAS 28 Investments in Associates and Joint Ventures).
Overall requirements on defined categories and subtotals
B13The survey included a question about the overall requirements for defined categories and subtotals. This question was answered by respondents that have (and that do not have) specified main business activities. As shown in Chart 3 below:
- 78% of the respondents who do not have a specified main business activity strongly agree or agree with these requirements, 15% were neutral, 4% disagree with these requirements and 3% strongly disagree; and .
- 63% of the respondents that have a specified main business activities strongly agree or agree with these requirements; 21% were neutral, 11% disagree with these requirements and 5% strongly disagree.
Chart 3: Feedback on the overall requirements for categories and subtotals

Why did respondents agree with the requirements on defined categories and subtotals?
B14Respondents who agreed with the requirements on defined categories and subtotals (this includes those respondents who reported having and not having specified main business activities) observed a number of benefits derived from these requirements. They think that these requirements will:
- help achieve more consistency in the presentation of information in the income statement across entities and potentially reduce diversity in practice;
- help provide more comparable information (e.g. a more comparable operating profit line) that would help users with their analysis;
- provide entities with flexibility to tailor their financial information to ‘tell their story'. For example, entities may be able to add extra subtotals or to include MPMs that would help a user understand an entity's performance;
- enhance the understandability of an entity's business activities;
- potentially remove the need to include some adjusted performance measures; and
- increase the relevance of financial performance information for users.
Why did respondents disagree with the requirements on defined categories and subtotals?
B15A few of the respondents who were neutral or who agree or strongly disagree with the requirements on defined categories and subtotals (this includes those respondents who reported having and not having specified main business activities) observed a a few challenges derived from these requirements. A summary of these challenges is presented below:
- One respondent indicated that these requirements leave some room for interpretation which could in turn lead to a loss of comparability.
- Respondents reported that some requirements may add unnecessary complexity for preparers and/or would appear confusing to users. For example:
- One respondent commented that the classification of foreign currency exchange differences in different categories of the income statement would add complexity as it would require entities to trace the nature of the transactions giving raise to differences which would involve changes in accounting systems[^28].
- One respondent commented that classifying interest income on cash equivalents (in investing) and interest expense on borrowings (in financing) would be confusing to users.
- One respondent commented that applying the requirements for the classification of fair value gains and losses from derivatives would be complex (as fact patterns may vary) and would involve systems changes.
- One respondent was of the view that EBITDA should have been a required subtotal in IFRS 18 as it is a widely used subtotal. (although one respondent acknowledged that this subtotal could potentially be derived from the current structure).
- One respondent observed that the classification of single transactions in different categories may lead to confusion. For
Requirements for entities with specified main business activities
Overview of responses
B16The survey included a question about the requirements for entities with specified main business activities. This question was answered by respondents that reported having (and not having) specified main business activities. As shown in Chart 4 below:
- 59% of the respondents who do not have a specified main business activity strongly agree or agree with these requirements, 37% were neutral and 4% disagree with these requirements; and .
- 42% of the respondents who have a specified main business activity strongly agree or agree with these requirements; 37% were neutral, 11% disagree with these requirements and 10% strongly disagree.
Chart 4: Feedback on the requirements applicable to entities with a specified main business activity

Why did respondents agree with the requirements for entities with specified main business activities?
B17Respondents who agreed with the requirements for entities with specified main business activities (this includes those respondents who reported having and not having specified main business activities) observed the following benefits derived from these requirements. They will:
- bring more comparability and consistency for investor's analysis;
- provide a more faithful representation of the nature of an entity's main business activities (for example, by excluding from operating profit income and expenses not directly related to an entity's main business activities); and
- allow these entities to portray their operations in a better way by giving them a choice in the presentation of certain income and expenses.
B18One respondent from the insurance sector agreed that the requirements on categories and subtotals will be an improvement but noted that IFRS 17 Insurance Contracts has already helped enhance comparability (for entities within the scope of this Standard).
Why did respondents disagree with the requirements for entities with specified main business activities?
B19Respondents who reported not having main specified business activities did not report concerns on the specific requirements applicable to entities with specified main business activities apart from one respondent who commented that the required separation of financing and investing results would require costly system changes (e.g. for a subsidiary that will need to split intercompany results across the different categories by its nature).
B20Respondents who reported having main specified business activities (these include those that were neutral or that they disagree or strongly disagree with the requirements for specified main business activities) expressed the following concerns:
- Two respondents observed that allowing an accounting policy choice[^29] for entities that provide financing to customers as a main business activity would lead to a loss of comparability.
- One respondent from the real estate sector observed that IFRS 18 will change the classification of some income and expenses that they normally exclude from 'operating' (for example ‘revaluation gains and losses') and therefore they may have to rely on MPMs to continue excluding these items from their operations.
- Two respondents from the insurance sector were not convinced that the required categorisation in IFRS 18 will result in better comparability across the insurance sector.
- One respondent commented that more guidance is needed to understand the link between the requirements in IFRS 17 and the presentation and disclosure requirements in IFRS 18 to make sure that they are consistent.
- One respondent observed that it is too early to determine the impact of the requirements for banks.
Classification of income and expenses from equity-accounted investments
Overview of responses
B21The survey included a question about the requirements for classifying income and expenses from investments in associates and joint ventures accounted for using the equity method. This question was answered by respondents who reported having (or not having) investments in associates and joint ventures that are considered 'integral' to their main operations. As shown in Chart 5 below:
- 48% of the respondents who reported not having 'integral' investments in associates and joint ventures strongly agree or agree with the classification requirements for income and expenses derived from equity-acounted investments in 'investing'; 45% were neutral and 7% disagree with these requirements.
- 42% of the respondents who reported having 'integral' investments in associates and joint ventures agree with the classification requirements for income and expenses derived from equity-acounted investments in 'investing'; 16% were neutral; 26% disagree with these requirements and 16% strongly disagree.
Chart 5: Feedback on the classification of equity-accounted investments

Why did respondents agree with the requirement to classify income and expenses derived from equity-accounted investments in 'investing'?
B22Respondents consider that the requirement to classify income and expenses derived from equity-acounted investments in ‘investing' will bring more comparability and consistency in the presentation of these income and expenses.
B23Respondents that were ‘neutral' to this requirement observed that they:
- do not have investments in associates and joint ventures accounted for using the equity method; or,
- do not consider their investments in associates and joint ventures to be either material and/or integral to their main business operations.
Why did respondents disagree with the requirement to classify income and expenses derived from equity-accounted investments in 'investing'?
B24Some of the respondents who disagreed with the requirement to classify income and expenses derived from equity-accounted investments in 'investing' (around 26% from a variety of sectors) think that entities should have flexibility to classify equity-accounted investments in the operating category when these investments are:
- considered as part of the entity's main business operations; or
- considered strategic partnerships. For example, joint ventures are commonly used in large-scale infrastructure projects that require substantial capital to develop and structure large-scale infrastructure projects.
B25In the view of some of these same respondents, not having flexibility to classify these investments in the operating category may:
- limit the understanding of the true nature and strategic value of those investments and of an entity's main business operations;
- signal that management is making poor investment decisions in the case of investments in associates and joint ventures that are making losses;
- create a presentation mismatch for insurance companies as the operating category would only include expenses related to insurance contract liabilities and no associated investment results from the assets (that are used to back insurance contracts). In their view this would not provide useful information for users.
B26One respondent observed that adding a subtotal of operating profit and income and expenses from associates and joint ventures accounted for using the equity method would not help users understand that these investments are part of an entity's main business activities.
B27One respondent noted that it will continue using alternative performance measures to indicate that its equity-accounted investments are part of their main business operations.
Transitional provisions to permit an eligible entity to change the measurement basis of an investment in an associate or joint venture
B28Paragraph C7 of the Transitional Provisions in IFRS 18 permit an eligible entity to change its election for measuring an investment in an associate or joint venture from the equity method to fair value through profit or loss. The survey asked for comments on this relief.
Why did respondents agree with the election offered on transition?
B29Many respondents (54%) were neutral on the election offered on transition to IFRS 18. Some respondents commented that this is because they do not have investments in associates and joint ventures accounted for using the equity method. 5
B30Some respondents (24%) agreed with the election offered on transition to IFRS 18, because it provides respondents with a one-time opportunity:
- to classify the income and expenses from investments in associates and joint ventures in the operating category if these investments are made in the course of an entity's main business activities; and
- to better reflect the value of their investments in associates and joint ventures.
Why did respondents disagree with the election offered on transition?
B31Some respondents (21%) did not support the election offered on transition to IFRS 18 because:
- introducing an election would impair comparability across entities in the same sector/industry;
- the election offered on transition is limited to eligible entities; 6
- using fair value to measure an investment in an associate or joint venture would:
- increase earnings volatility in profit and loss, which may lead to the presentation of additional performance measures;
- add a layer of complexity and subjectivity in the measurement of these investments, for example, in determining the fair value of unlisted investees; and
- be onerous as entities will be required to prepare disclosures under other IFRS Accounting Standards.
Feedback on management-defined performance measures
B32The survey obtained respondents' views on the requirements in IFRS 18, particularly on:
- The overall MPM requirements.
- The level of consistency of current practices with the requirements for calculating and disclosing MPMs.
Overall MPM requirements
Why did respondents agree with the MPM requirements?
B33Nearly half of respondents (56%) considered that the requirements on MPMs will represent an improvement over current practices for communicating financial performance. Some of the reasons provided were that:
- including these measures in a single location in a note to the financial statements will bring discipline, transparency and confidence on those measures as they will be subject to external audit; and
- the MPM requirements will improve understandability and comparability of these measures for users.
Chart 6: Feedback on overall MPM requirements

Why did respondents were neutral or disagree with the MPM requirements?
B34From the respondents who were neutral (24%) or who disagree (18%) with the MPM requirements the following concerns were identified:
- Around 15% of respondents observed that having two sets of performance measures (Alternative Performance Measures or ‘APMs' and MPMs), located in different sections of the annual report would be confusing for users. In addition, it would be unclear if any specific performance measure is more relevant than the other.
- Around 11% of respondents observed that entities with dual listings in other jurisdictions may be subject to different rules when disclosing its non-GAAP performance measures, creating inconsistencies and confusion to users. For example, the requirement to disclose MPMs in the financial statements may be inconsistent with the requirements set out by the US securities regulator to disclose alternative performance measures outside the financial statements.
- A few respondents (4%) disagreed with MPMs being only subtotals of income and expenses and observed that other measures, including for example, net debt or adjusted cash flow metrics are important in some industries for evaluating the performance of an entity. One of those respondents also expressed confusion about which measures would be within the scope of the MPM requirements and was of the view that IFRS 18 does not gives enough guidance in this respect.
- One respondent noted that as the definition of the operating category does not permit insurers to exclude certain items (e.g. fair value investment variances or economic assumption changes) they will rely on MPMs to make adjustments to operating profit.
- A few respondents were of the view that subjecting MPMs to auditing could present challenges for both preparers (i.e. could increase audit fees) and auditors (i.e.could add complexity to the audit process).
- One respondent did not see the benefit of transferring their APMs to the financial statements and viewed this as an onerous task.
Other views
B35A few respondents questioned the need to have a new set of requirements given that many entities already follow ESMA's Guidelines on Alternative Performance Measures (APMs) 7 which are considered fit for purpose.
B36A couple of respondents 8 explicitly mentioned an increase of their adjusted performance measures following their implementation of IFRS 17 (one noted that this was due to IFRS 17 not reflecting interest rate risk in line with management).
B37One respondent expressed support for the overall objective of the MPM disclosure requirements but questioned whether their own performance measures (which explain differences between their statutory results and the regulatory allowed revenues) would in fact meet the definition of MPMs.
Level of consistency of current practices with the requirements for calculating and disclosing MPMs
B38The survey asked respondents if their current practices for communicating performance measures were aligned (or not) with the requirements for MPMs in IFRS 18.
B39The following practices were reported to be aligned with the following MPM requirements:
- Disclosure of how MPMs are calculated. Around 96% of respondents noted that their current practice is consistent with this requirement. In addition, 89% agree that they include an explanation of why, in management's view, their alternative performance measures provide useful information about the entity's financial performance.
- Reconciliation between their MPMs and the most directly comparable subtotal listed in IFRS 18 or total/subtotal specifically required by other IFRS Accounting Standards. Around 91% of respondents noted that they add this reconciliation.
- Explanation of why, in management's view, the MPM provides useful information about the entity's financial performance. Around 89% of respondents noted that their current practice is consistent with this requirement.
- Clear explanations of any changes on their MPMs (including changing their calculation, introducing or removing performance measures): Around 78% agree that they provide these explanations. A few of these respondents also noted that they have not made changes to their performance measures recently.
B40The following practices were reported not be aligned with the following MPM requirements:
- Inclusion of the tax effect for each reconciling item and a description of how this tax effect is determined. Around 57% of respondents identified that their current practices are not consistent with the requirements in IFRS 18 to include the tax effect for each reconciling item and a description of how this tax effects is determined. This is because:
- their reconciliation is to operating profit so adding the tax effects is viewed as unnecessary;
- the tax effects would be immaterial;
- the tax effects would be of little value, as users in other jurisdictions do not normally request this information; and
- the tax effects are normally provided aggregated for the combined reconciling items and not for each individual reconciling item.
- Inclusion of the effect on non-controlling interests for each reconciling item. Around 59% of respondents identified that their current practices are not consistent with the requirements in IFRS 18 to include the effect on non-controlling interests for each reconciling item. This is because these effects are considered immaterial or the entity does not have NCIs.
Aggregation and disaggregation
B41The survey obtained respondents' views on the requirements in IFRS 18, particularly on:
- the principles of aggregation and disaggregation; and
- the disclosure of specified operating expenses by nature (depreciation, amortisation, employee benefits, inventory write-downs (including reversals) and impairment losses (including reversals) when an entity presents line items classified by function.
General views on the requirements for aggregation and disaggregation
Why did respondents agree with the requirements on aggregation and disaggregation?
B42A narrow majority of respondents (61%) supported the requirements on aggregation and disaggregation because they:
- Improve the comparability and consistency of the information presented and/or disclosed across different entities and industries (i.e. by introducing principles-based guidance on how to group and separate items based on their shared/dissimilar characteristics).
- Enhance the understandability, relevance and reliability of the primary financial statements as they require entities to:
- provide useful structured summaries that would avoid excessive detail or clutter in the primary financial statements; and
- disaggregate large "other" balances.
- Help users of financial statements identify and understand the main sources of income and expenses, and how they relate to the entity's main business activities.
- Supplement the existing materiality principles and guidance.
- Make preparers reconsider how they aggregate and disaggregate information which could result in better information for users.
Chart 7: General views on the principles of aggregation and disaggregation

Why did respondents were neutral or disagree with the requirements on aggregation and disaggregation?
B43A majority of the respondents who were neutral to the requirements on aggregation and disaggregation (around 20% of total respondents) thought that the requirements on aggregation and disaggregation will have a small effect on the information they currently include in their financial statements as they think that some of these principles are implicit in other requirements or guidance in IFRS Accounting Standards. For example, they observe that:
- IAS 1 Presentation of Financial Statements, requires entities to add lines, headings or subtotals in the financial statements to help users understand an entity's financial performance.
- The Conceptual Framework for Financial Reporting, requires entities to group items in the financial statements on the basis of shared characteristics.
- IFRS 17 includes requirements to disaggregate specific items in the income statement and in the statement of financial position.
B44Other few respondents (around 6%) were of the view that introducing principle-based guidance on aggregation was concerning because it would require:
- significant judgement in determining an appropriate aggregation or disaggregation basis, for example, on the application of materiality judgements or on the disaggregation of large ‘other' balances;
- long narrative disclosures to explain how information was aggregated or disaggregated; or
- different interpretations and/or different approaches leading to inconsistent application and a lack of comparability (which to one of the respondents appears to be in opposition with the objectives of IFRS 18).
B45On respondent noted that it was too early to determine the impact of the requirements on aggregation and disaggregation on its financial information.
B46Two respondents observed that the illustrative examples in IFRS 18 would not be useful for particular sectors or industries. These respondents think that more industry-specific examples should be developed. For instance, it was observed that the illustrative examples in IFRS 18:
- show items that would be immaterial for some sectors (e.g. for the gas, water and multiutilities sector); or
- do not show items that are commonly presented in some industries (e.g. credit impairment losses are normally material for banks).
B47One respondent observed that it is unclear how the guidance on aggregation and disaggregation in IFRS 18 interacts with the proposed illustrative example 8 ('Disclosure of disaggregated information') in IASB's Exposure Draft ‘Climate-related and Other Uncertainties in the Financial Statements' (issued in July 2024) 9.
B48One respondent found the interaction of the guidance on aggregation and disaggregation with the requirements of XBRL unclear.
Disclosure of specified operating expenses by nature
B49The survey asked respondents to rate the level of difficulty in gathering information on specified operating expenses by nature. For approximately a third of respondents this question was not applicable. The following summarises their responses for the disclosure of:
- Depreciation: Approximately half of the respondents (52%) found disclosing this information ‘easy' or 'very easy'. A small proportion of respondents were neutral (4%) or found disclosing this information rather complex (13%). 31% indicated that this was not applicable.
- Amortisation: Approximately half of the respondents (52%) found disclosing this information ‘easy' or 'very easy'. A small proportion of respondents were neutral (7%) or found disclosing this information rather complex (9%). 32% indicated that this was not applicable.
- Impairment losses (including reversals of impairment losses): Approximately half of the respondents (52%) found disclosing this information 'easy' or 'very easy'. A small proportion of respondents were neutral (9%) or found disclosing this information rather complex (7%). 32% indicated that this was not applicable.
- Inventory write downs (including reversals of write-downs of inventories). Approximately a third of respondents (33%) found disclosing this information 'easy' or 'very easy'. A small proportion of respondents were neutral (4%) or found disclosing this information rather complex (9%). 54% indicated that this was not applicable.
- Employee benefits: Around 37% of respondents found disclosing this information 'easy' or 'very easy'. A small proportion of respondents were neutral (4%). A third of respondents (30%) found this disclosure 'somewhat complex' or 'very complex’. No further reasons were provided in this respect. 29% indicated that this was not applicable.
Challenges identified
B50For a few respondents it is unclear if the required specified information by nature will be useful for users.
Limited changes on the statement of cash flows
B51The survey included a question about the extent to which respondents thought that the limited amendments to IAS 7 would improve the usefulness of the statement of cash flows. As shown in Chart 8 below:
- 48% of the respondents were neutral about these limited changes;
- 37% of respondents agreed or strongly agreed with these changes;
- 11% of respondents disagree or strongly disagreed with these requirements; and
- 4% of respondents did not respond to this question.
Chart 8: Feedback on the limited changes on the statement of cash flows

Why were respondents neutral to these changes?
B52Respondents who were neutral to the limited changes to the statement of cash flows observed that:
- Their current practices for reporting cash flows will not be significantly affected by the limited changes made to the statement of cash flows. Some of the individual reasons provided are that:
- The respondent reports cash flows from operating activities using the direct method.
- The respondents already report cash flows in line with the limited changes made to the statement of cash flows.
- These changes are considered 'minor' or not significant. For example, they observe that:
- Cash flows from interest/dividends are already required in IAS 7 and are only being reclassified into other categories of the statement of cash flows.
- Having 'operating profit' as a starting point only reduces the number of items that should be reconciled as part of the indirect reconciliation of cash flows.
Why did respondents agree to the limited changes to the statement of cash flows?
B53Respondents who agreed with the limited changes to the statement of cash flows think that:
- Having a consistent starting point (i.e. 'operating profit') for reporting cash flows from operating activities is helpful.
- Reducing options will enhance comparability and reduce diversity in practice.
Why did respondents disagree to the limited changes to the statement of cash flows?
B54Respondents who disagree with the limited changes to the statement of cash flows observe the following:
- Three respondents think that there should be full alignment between the categories in the income statement and the activities in the statement of cash flows because otherwise they think that users will be confused. For example, derived from the requirements in IFRS 18, depreciation of property, plant and equipment will be classified in the operating category in the income statement, whereas the related capital expenditures would be classified as part of the investing category in the statement of cash flows.
- Referring to the requirements in IAS 7 (that are not part of the limited changes to the statement of cash flows), one respondent questioned why 'operating' should be a default category in the statement of cash flows.
- Two respondents from the insurance sector, one respondent from the aerospace and defense sector noted that the statement of cash flows is not useful/has limited usefulness for their industries.
- One respondent noted that the classification of dividends from associates and joint ventures is ambiguous and may lead to diversity in practice.
Other views
B55One respondent noted that including a definition of 'free cash flow' (which the respondent observes is often used) and guidance on how to reconcile this alternative performance measure would have been a more useful change.
Section 2: Feedback on perceived costs and benefits and the wider economic impact
B56The survey collected information as input to the long-term public good (LTPG) assessment. This is an economic assessment that the UKEB performed relating to costs and benefits incurred by stakeholders and wider economic effects on the UK economy.
B57In the part on LTPG assessment, the survey obtained data on:
- incremental one-off costs;
- as a percentage of baseline costs; and
- as a percentage of operating costs;
- incremental ongoing costs:
- as a percentage of baselines costs; and
- as a percentage of operating costs.
- the wider economic impact of IFRS 18.
- at group level (consolidated), if possible;
- comprised of: ongoing accounting system maintenance, staff costs; audit and legal costs;
- inclusive of any costs incurred to prepare interim reporting;
- exclusive of, to the extent possible, costs of producing non-financial statements information, such as the first half of the annual report or investors' presentations.
Direct implementation costs
Survey questions
B59Direct implementation costs for preparers were estimated by asking preparers' finance departments to forecast the extra costs that they expected to incur as a result of implementing IFRS 18.
B60In line with the Better Regulation Framework (2023) and the principles of the Green Book (2022), the estimates focused on incremental costs (i.e. costs expected to be incurred as a direct result of meeting the requirements of the standard that preparers would not incur otherwise). Costs were also split into one-off implementation and ongoing costs.
B61Based on the literature on the topic and industry practice, direct implementation costs are found to be comprised of the following cost categories:
- familiarisation;
- accounting system changes; 10
- changes to data handling processes and controls; 11
- accounts preparation; 12
- communication with third parties;
- audit costs; 16 and
- legal costs. 17
B62Consistently with the Better Regulation Framework, direct implementation costs were expressed in relation to a counterfactual. A counterfactual is the costs that preparers would have incurred in absence of the standard.
B63The UKEB considered that the counterfactual should be, when available, the cost respondents incurred to prepare the most recent set of financial statements, referred to as 'baseline cost' in the remainder of this appendix. When unavailable 18, operating cost as per previous year-end were used as a counterfactual.
B64The analysis of the responses differs depending on the counterfactual used. Although overall the results are comparable as preparers were asked to report about the same categories of incremental ongoing and one-off costs regardless of the counterfactual used (i.e. baseline vs operating costs).
B65Of all respondents, 24 provided information on incremental one-off costs as a share of baseline costs and 17 respondents chose to report incremental costs as a share of operating costs. The remaining respondents did not provide any granular incremental cost information.
Incremental costs as a share of baseline costs
Incremental one-off costs
B66On average, respondents anticipated incremental one-off costs to be relatively contained, with the majority of respondents indicating that they expected them to be lower than 5% of baseline costs for all cost categories. 19
B67Concerning individual 20 incremental one-off costs categories:
- Accounts preparation was the cost category likely to increase the most. This is likely due to the nature of IFRS 18, as the standard mostly affects presentation in the financial statements. While no respondents stated that the change in accounts preparation costs as a result of IFRS 18 would be nil, two-thirds of respondents stated that the incremental one-off costs in this cost category as a result of IFRS 18 would be less than 5% of baseline costs. A third of respondents expected a change between 5% and 10% of baseline costs.
- Audit costs was the cost category preparers suggested would experience the second-largest change. The increase was assessed to be relatively contained, with 17% of the respondents expecting zero cost changes, 65% of respondents expecting cost changes of between 1% and 5% of baseline cost, and 18% of the respondents expecting a change between 5% and 10% of baseline costs.
- In the case of changes to data handling processes and controls, the majority of respondents, 80% of them, expected extra one-off costs to be between nil to less than 5% of baseline costs. A relatively small percentage
Incremental costs as a share of baseline costs
Incremental one-off costs
B66On average, respondents anticipated incremental one-off costs to be relatively contained, with the majority of respondents indicating that they expected them to be lower than 5% of baseline costs for all cost categories. 19
B67Concerning individual20 incremental one-off costs categories:
- Accounts preparation was the cost category likely to increase the most. This is likely due to the nature of IFRS 18, as the standard mostly affects presentation in the financial statements. While no respondents stated that the change in accounts preparation costs as a result of IFRS 18 would be nil, two-thirds of respondents stated that the incremental one-off costs in this cost category as a result of IFRS 18 would be less than 5% of baseline costs. A third of respondents expected a change between 5% and 10% of baseline costs.
- Audit costs was the cost category preparers suggested would experience the second-largest change. The increase was assessed to be relatively contained, with 17% of the respondents expecting zero cost changes, 65% of respondents expecting cost changes of between 1% and 5% of baseline cost, and 18% of the respondents expecting a change between 5% and 10% of baseline costs.
- In the case of changes to data handling processes and controls, the majority of respondents, 80% of them, expected extra one-off costs to be between nil to less than 5% of baseline costs. A relatively small percentage
- of respondents, 20%, believed these costs will be between 5% and 10% of baseline costs.
- For the other categories of costs (familiarisation, accounting system changes, communication with third parties, and legal costs), roughly 90% of respondents indicated that these costs will be between nil and 5% of baseline costs, respectively. The rest of respondents said that these costs will be between 5% and 10% of baseline costs.
Chart 9: Incremental one-off costs as a share of baseline costs
Incremental ongoing costs
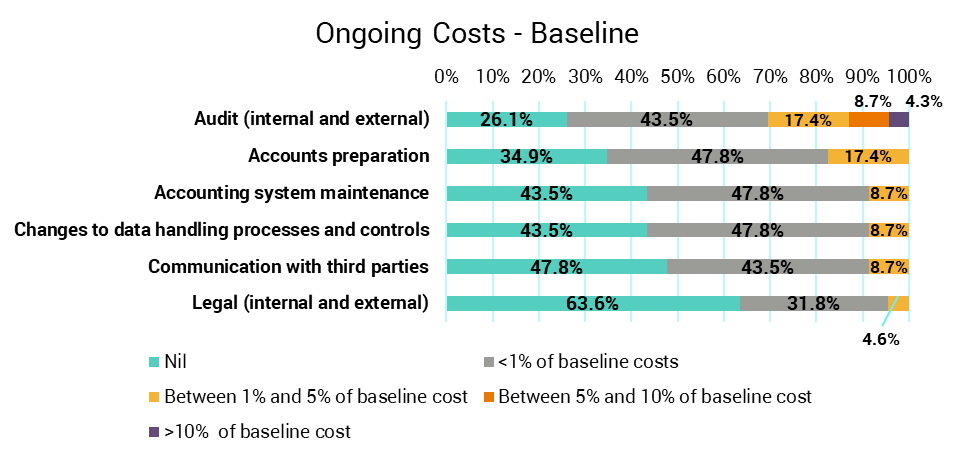
B68A total of 23 respondents provided information on incremental one-off costs as a share of baseline costs. Over 69% of respondents in all cost categories expected incremental ongoing costs to be nil or less than 1% of baseline costs, suggesting that incremental ongoing costs are expected to be lower than one-off costs, and in general contained. Further detail:
- Audit costs represented the cost category with the highest expected extra cost as a share of baseline costs. Still, 69.6% of respondents believed the incremental ongoing audit costs as a result of the standard will be less than 1% of baseline costs or nil. 17.4% of respondents said that it will be between 1% and 5% of baseline costs, and 8.7% of respondents said that these costs will be between 5% and 10% of baseline costs. 4.3% of respondents anticipating that these costs will be more than 10% of baseline costs.
- Accounts preparation was the cost category with the second largest expected change. Over 80% of respondents said the extra ongoing costs will be less than 1% of baseline costs or nil. The percentage of respondents saying that these costs will be between 1% and 5% of baseline costs was identical to that of audit costs (17%). No respondents believed these costs would account for more than 5% of baseline costs
- Accounting system maintenance represents the cost categories with the joint fourth-highest expected incremental ongoing costs. Over 43% of respondents said these costs would be zero. 48% of respondents said these costs will be less than 1% of baseline costs. 9% of respondents said these costs will be between 1% and 5% of baseline costs. No respondents said these costs will exceed 5% of baseline costs.
- Changes to data handling processes and controls showed the same data/results as accounting system maintenance with similar results for communication with third parties. For these costs, over 90% of respondents said these costs will be less than 1% of baseline costs, with nearly 50% of respondents saying these costs will be zero.
- For legal costs, over 95% of respondents said they will be less than 1% of baseline costs with 64% of all respondents saying they will be zero.
Chart 10: Ongoing costs reported as a percentage of baseline costs
Incremental costs as a share of operating costs
B69Respondents were asked to provide information about the same incremental one-off and ongoing costs categories as respondents who expressed incremental costs as a share of baseline costs. Looking at incremental one-off and ongoing costs as a share of operating costs allows one to express incremental cost relative to the size of the respondent's operating activities.
Incremental one-off costs
B70Audit costs were the cost category anticipated to be mostly affected, as nearly 18% of the respondents indicated that they expect an increase between one and five percent of operating costs. However, for all cost categories, including audit costs, over 80%, of the respondents estimated that incremental one-off costs would be nil or less than one percent of operating cost. In the case of legal (internal and external) costs, the majority of respondents, over 53%, stated that these will be nil.
Chart 11: One-off costs reported as a percentage of operating costs
One-Off Costs - Operating This stacked horizontal bar chart illustrates the percentage distribution of one-off costs relative to operating costs across various categories.
- Audit (internal and external): 5.9% Nil, 76.5% <1% operating cost, 17.6% Between 1% and 5% operating cost.
- Accounting system changes: 11.8% <1% operating cost, 88.2% Nil.
- Accounts preparation: 11.8% <1% operating cost, 88.2% Nil.
- Familiarisation: 17.6% <1% operating cost, 82.4% Nil.
- Changes to data handling processes and controls: 18.7% <1% operating cost, 81.3% Nil.
- Communication with third parties: 29.4% <1% operating cost, 70.6% Nil.
- Legal (internal and external): 52.9% Nil, 47.1% <1% operating cost.
The chart uses a legend: * Nil (dark blue) * <1% of operating cost (light blue) * Between 1% and 5% of operating cost (orange) * > 5% of operating cost (grey)
Incremental ongoing costs
B71Only 15 out of 17 respondents completed questions concerning ongoing costs as a percentage of operating costs. For all cost categories at least 86% of respondents estimated incremental ongoing costs to be either nil or less than 1% of operating costs.
B72Audit costs were the cost category anticipated to be mostly affected, with 13% of the respondents indicating that they expect an increase between one and five percent of operating costs.
B73In the case of accounting system maintenance, changes to data handling processes and controls, legal (internal and external), and communication with third parties, the majority of respondents, at least 60% of them, estimated the costs would be nil.
B74A seemingly significant percentage of respondents, over 46%, estimated that accounts preparation costs will be nil.
Chart 12: Ongoing costs reported as a percentage of operating costs
Ongoing Costs - Operating This stacked horizontal bar chart illustrates the percentage distribution of ongoing costs relative to operating costs across various categories.
- Audit (internal and external): 26.7% Nil, 60.0% <1% operating cost, 13.3% Between 1% and 5% operating cost.
- Accounts preparation: 46.7% Nil, 53.3% <1% operating cost.
- Accounting system maintenance: 60.0% Nil, 40.0% <1% operating cost.
- Changes to data handling processes and controls: 60.0% Nil, 40.0% <1% operating cost.
- Legal (internal and external): 66.7% Nil, 33.3% <1% operating cost.
- Communication with third parties: 80.0% Nil, 20.0% <1% operating cost.
The chart uses a legend: * Nil (dark blue) * <1% of operating cost (light blue) * Between 1% and 5% of operating cost (orange) * > 5% of operating cost (grey)
B75To gather extra information about the impact of implementation costs on day-to-day operations, follow-up emails were sent to preparers who expressed their implementation costs as a share of baseline costs, asking them to also express them as a share of operating costs. Preparers confirmed that, when expressed as a share of operating costs, incremental adoption costs would be between close to nil and no more than 1% of operating costs.
B76Consistently, one responded noted: ‘Incremental ongoing costs after implementation should be relatively low, as should implementation costs when compared with other standards.'
B77One comment suggested that the impact on business will largely depend on how aligned their presentation is with the future requirements: ‘Given that our current methodology appears very similar to what IFRS 18 is proposing and the changes are fairly transparent I would not consider that this would result in significant cost increments.'
B78A respondent raised concern that the standard does not address the needs of specific industries/entities, considering the difficulty of catering for specific industry needs when issuing an accounting standard. They said ‘[I] [a]gree with the overall aim of the standard but the finer points will lead to additional costs for some entities...[there] [h]as to be consideration of the industry effect which is difficult to standardise amongst all financial statements.'
Implementation costs: absolute estimates
B79Respondents were asked to provide a baseline cost estimate in £ million, if available. Only three entities gave an estimate, ranging from £0.5 million to £1.6 million.
B80In a follow-up discussion on the topic, a preparer clarified how baseline costs were calculated. They noted that, given the requirements in IFRS 18, baseline costs were comprised of finance department costs related to the preparation of the accounts at year-end. In other words, they would not be comprised of day-to-day operating costs of the finance department, as the standard does not affect recognition and measurement. Consistently, this preparer estimated incremental ongoing costs associated with the adoption of IFRS 18 to be contained.
B81Respondents were also asked to provide estimates in £ million for incremental one-off and ongoing costs associated with implementation of IFRS 18. A total of 10 respondents provided this information (including the ones who provided information on baseline costs):
- Incremental one-off costs estimates ranged from a minimum of £50,000 to a maximum of £500,000.
- Incremental ongoing costs estimates ranged from a minimum of £0 to a maximum of £100,000.
B82The UKEB is currently recruiting additional survey respondents and conducting 1-2-1 interviews to obtain more cost data to extrapolate a market-wide estimate.
Wider economic effects
B83Preparers were asked about wider economic effects/impact of associated with IFRS 18.
B84Preparers were asked to indicate the extent to which they expected the implementation of IFRS 18 to affect a number of outcomes. A list of different outcomes were provided, focusing on three main topics: anticipated benefits for users, management and stewardship and other economic effects. 45 respondents provided an answer to this question.
Anticipated Benefits To Users
B85The first three outcomes related to anticipated benefits for users. Respondents were asked to indicate whether they expected IFRS 18 to affect:
- The reporting of entity's financial performance in line with underlying economics. This outcome split opinions, with 44% of respondents indicating that they anticipate no effect, a sizable share of respondents
- (31%) indicating that they anticipate a mild to strong positive effect, and nearly 16% of the respondents indicating that a mild to strong negative effect was anticipated. In the sample, 2% of respondents said this did not apply to their organisation, and 7% of respondents said they did not know or were unsure.
- The comparability of the entity's reporting of financial performance. A majority of respondents, 60%, indicated that they anticipate a mild to strong positive effect, 28% of respondents stated no effect was expected, and 12% of respondents stated they anticipated a mild to strong negative effect.
- The transparency of the entity's financial performance. A slight majority of respondents (51%) indicated that they anticipate a mild to strong positive effect, though it is worth noting that over 40% of respondents did not anticipate an effect, while 9% of respondents stated a mild to strong negative effect was expected.
Management and Stewardship
B86The second three outcomes related to preparers' views on management and stewardship. Respondents were asked to indicate whether they expected IFRS 18 to affect:
- Management's discretion in presenting the entity's financial performance. This outcome split opinions, with the largest share of respondents (49%) indicating that they anticipate a mild to strong positive effect, 42% of respondents indicating that they anticipate no effect, 5% of respondents indicating that they expect a mild to strong negative effect and 4% saying they do not know or are unsure.,
- Presentation of management's use of economic resources to users. A clear majority of respondents, 61%, indicated that they anticipate no effect, 16% said they expect a mild to strong positive effect, 14% said they expect a mild to strong negative effect, 2% said this did not apply to their organisation, 7% said they did not know or were unsure, and
- Transparency over management's performance in financial reporting. A narrow majority of respondents (53%) indicated that they expected no effects, with the remaining responses leaning slightly towards a positive effect (24%). There was some indication that negative effects may be expected (16%), 2% of respondents said this question did not apply to their organisation, and 5% of respondents said they did not know or were unsure.
Other Transmission Mechanisms
B87This list of outcomes related to preparers' views on mechanisms that may impact the underlying economics of the business. [^18] These were:
- Information transmission within the organisation.
- Streamlining of internal systems and processes.
- Disclosure of proprietary information, where more disclosures were interpreted to be a negative effect.
- Competitors' assessment of the entity performance, a better assessment was interpreted to be a negative effect.
- Internal assessment of competitors' financial performance, where a better assessment was interpreted to be a positive effect.
- Risk of litigation, where lower risk was interpreted to be a positive effect.
B88For most of the outcomes listed, large majorities of respondents indicated that no effect was expected.
B89The only exception was the internal assessment of competitors' financial performance, for which a mild positive effect was expected by 44% of respondents, contrasting with 40% who believed that no effect was expected (the remaining 16% either expected a negative effect or did not have an opinion).
B90The survey allowed respondents to indicate if there were other effects not listed. Most respondents indicated that no other effects were expected.
Chart 13: Wider economic impacts of IFRS 18 as assessed by preparers of primary financial statements

B91Comments from preparers include:
- “In our view, the additional costs especially for the audit of financial statements are outweighed by the benefits”.
- “The standard will make companies' financial performance easier to compare and will provide more information for investors' analysis. At the same time the standard will require additional implementation and external audit costs."
B92Some comments suggested further investigation:
- A preparer suggested that “regulators and other bodies who require financial information to be presented in a particular way, and who rely on IFRS as a starting point, may also end up incurring costs".
- A preparer noted that “Certain changes in presentation may move the revenue [thresholds] that categorised the entity from small to medium size entity, potentially resulting in incremental disclosures burden."
B93The UKEB Secretariat will undertake further proportionate investigation to consider these comments.
Further economic impacts
B94Preparers were also asked for their opinion on the effects of IFRS 18 on the following items:
- Management compensation schemes.
- Covenants.
- Dividend payments.
- Tax liabilities.
B95Preparers expected no effect on any of these items (between 74% to 86% indicated that no effect was expected). Preparers noted that:
- "the new standard won't have impact on measurement. Presentational differences from a statutory perspective will not impact any of the above measures"; and
- "given that the changes are presentational, and do not affect the recognition or measurement of assets, liabilities, income or expense, we do not expect that there would be any substantive effect based on a change in which financial performance information is structured and summarised."
Robustness Checks
B96Robustness checks for the IFRS 18 preparers survey have been conducted. The purposes of these robustness checks is to see if there is any bias in the results based on known characteristics of respondents that might encourage bias.
B97To perform the robustness checks the analysis was conducted on restricted samples to check whether the exclusion of certain types of respondents alters the results. The robustness checks were based on:
- Familiarity with the standard (in-depth assessment, high-level assessment, overall familiarity, or none). During the analysis of the data, it was considered whether respondents who were not familiar with the standard could bias the results. Therefore, analyses were restricted to a group of respondents respectively comprised of those whose familiarity with IFRS 18 came from an in-depth assessment of the standard, and those whose familiarity with IFRS 18 came from an in-depth or a high-level assessment of the standard.
- Market segment (FTSE 100; FTSE 250; AIM; or Private/Parent Company listed Abroad). It was considered that the experience of large firms concerning IFRS 18 may be different from the experience of small firms. The possibility of respondents from large firms biasing the results was considered. Therefore, analyses was conducted grouping respondents by their market segment. The results from the survey were grouped by market segment to see if there were differences for any group compared to the overall results.
B98Results from these robustness checks do not contradict the results from the main study.
Question for the Board
- Does the Board have any questions or comments on the preliminary [draft] report results from preparers' survey?
Appendix C: Preliminary [draft] report results from users’ survey
Background
C1This Appendix summarises the preliminary results of the UKEB's users' survey on IFRS 18 Presentation and Disclosure in Financial Statements and provides:
- An overview of respondents followed by a summary of their views.
- A detailed summary of the feedback received on the main technical requirements of IFRS 18. More specifically on:
- categories and subtotals;
- management-defined performance measures (MPMs);
- aggregation and disaggregation; and
- limited changes to the statement of cash flows.
- A detailed summary of the feedback received on the perceived costs and benefits of IFRS 18 and the wider economic impact, comprised of assessments of:
- implementation costs;
- direct benefits; and
- wider economic effects.
C2Information about survey design and the survey questions is in Appendix E of this paper.
Overview of survey responses
Demographics
C3The survey gathered a total of 22 responses. A total of 77% of respondents were located within the UK (some of which also trade in the UK) and 23% were located outside the UK and trade in the UK. A total 41% of respondents invest in/lend to/trade in/analyse/rate UK companies.
Chart 1: Demographics of the respondents in the users' survey
Demographics of the respondents in the users' survey This horizontal bar chart displays the geographic and investment-related demographics of the survey respondents. * "The respondent invests in/lends to/trades in/analyses/rates UK companies" shows 41%. * "The respondent is based in the UK" shows 77%. The x-axis ranges from 0% to 100%.
C4The occupation of the respondents is shown in Chart 2 below:
Chart 2: Occupation of the respondents in the users' survey
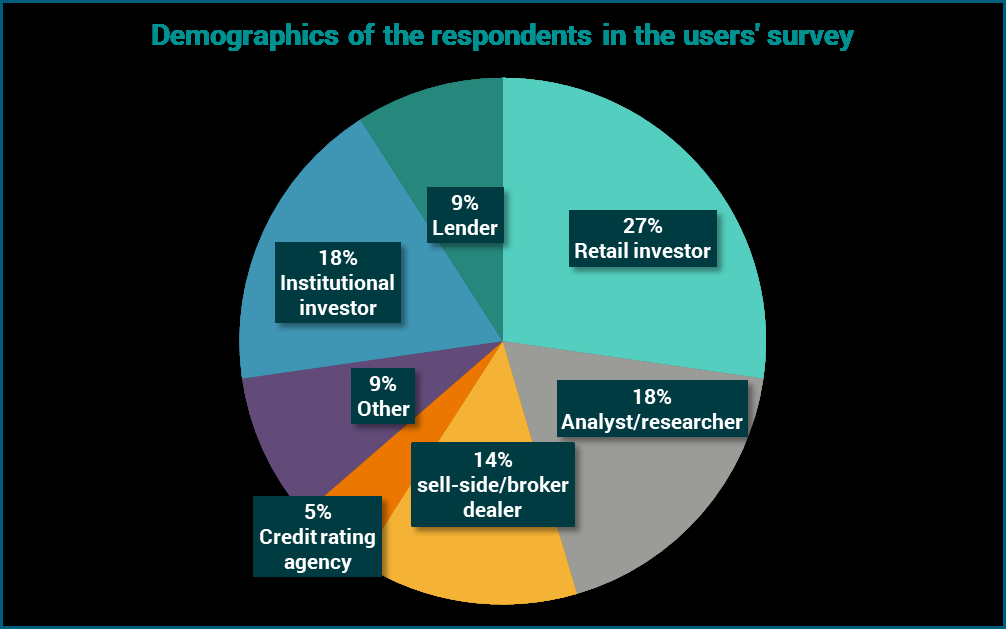
Familiarity with the requirements in IFRS 18
C5Almost 80% of respondents reported being familiar with the requirements in IFRS 18. However, amongst those respondents only a third reported having done an in-depth assessment of the Standard. These results are shown in Chart 3 below.
Chart 3: Level of familiarity
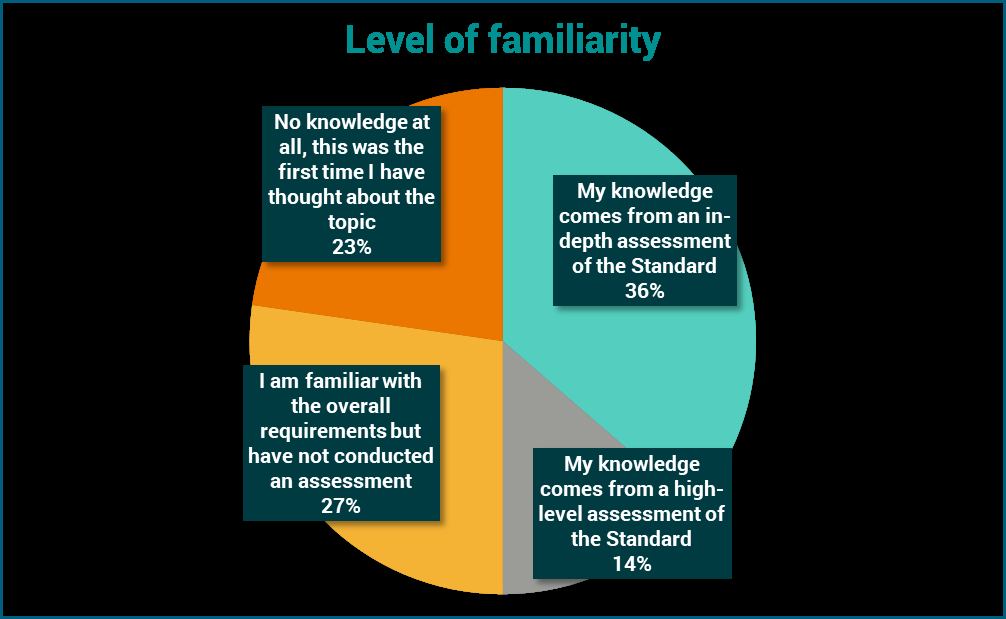
Overall views on IFRS 18
C6Respondents showed support of specific aspects of the requirements of IFRS 18. When asked about the overall support of the requirements in IFRS 18 (using a scale of 1 (no knowledge) to 10 (extensive knowledge)), respondents allocated an average rating of 7.0.
C7Respondents highlighted only a few areas of concern or difficulty that are described in this report.
Section 1: Feedback on technical requirements
C8The survey obtained users' views received on the main technical requirements of IFRS 18.
Categories and subtotals
Benefits of new structure and defined subtotals in the income statement
C9A great majority of respondents agree that the new structure and defined subtotals in the income statement will be useful as this will:
- enhance the overall decision-usefulness of IFRS financial statements (86%). In this respect two respondents mentioned that:
- the new structure appears clearer and more logical; and
- standardised subtotals would facilitate benchmarking and sector comparisons; and
- the structure is aligned with how most respondents view the financial statements.
- improve users' ability to compare performance:
- between entities (91%); and
- between reporting periods for the same entity (86%).
- provide decision-useful information about financial performance (86%);
- improve the understanding of the drivers of financial performance (77%); and
- reduce diversity in:
- the presentation of subtotals amongst entities (86%). Some respondents indicated that they welcomed the presentation of an 'operating profit' subtotal;
- the identification of operating activities amongst entities (77%). One respondent observed that including additional subtotals would help respondents 'tell their own story'.
Chart 4: Overall feedback on the requirements of categories and subtotals

C10One respondent (a lender) observed that the new prescribed structure is not significantly different from the structure currently used by some entities.
C11Two respondents observed that the new structure will be useful as a starting point for users' analysis.
Classification requirements for associates and joint ventures accounted for using the equity method
Benefits observed
C12A majority of respondents (64%) agreed with the requirement to classify income and expenses from investments in associates and joint ventures accounted for using the equity method in the investing category. Of the remaining respondents, 23% neither agreed not disagreed, and only the remaining 13% showed disagreement.
C13Respondents mentioned that this classification is useful because:
- the equity method combines income and expenses that users of financial statements would usually analyse separately;
- the entity is not able to exercise control over the associate and joint ventures; and
- users normally consider the results from equity method investments separately to avoid distorting user's analysis of operating margins.
C14One respondent (a retail investor) noted that while “ultimately this is the only way to ensure consistency”, it would be helpful to require a company to explain which of their investments in associates and joint ventures are integral or closer to the entity's core operations. Along similar lines, another respondent noted that they agreed with this presentation “as long as it's made clear where it's presented and on what basis".
C15One respondent suggested that “The removal of equity accounted entities from the operating line is a huge win for users of financial statements”.
Challenges identified
C16A few respondents (13%) disagreed with the classification of income and expenses derived from investments in associates and joint ventures in the investing category. Some respondents indicated in the comment box that when those investments are integral or close to the entity's core operations the classification in the operating category would be more appropriate.
Management-defined performance measures
Benefits observed
C17A great majority of respondents (95%) agree that the requirements on MPMs will be useful because these requirements will add discipline and transparency to the disclosure of MPMs. Many users (86%) observed that auditing MPMs will enhance users' confidence in and credibility of these measures.
C18Many respondents (77%) were of the view that the requirements on MPMs will help users understand how entities view their performance and 86% of them agree that the requirements on MPMs will make it easier for users to track an entity's performance over time. Additionally, many respondents (68%) also think that the MPM requirements will help users compare performance between entities in the same period.
C19A great majority of respondents (95%) agree that the requirements on MPMs will make it easier for users to find those measures in the financial statements (as they will be disclosed in a single note).
C20Many respondents (86%) found it useful to require a reconciliation of MPMs to the most comparable subtotal.
C21Many respondents (82%) found it useful to require information about the tax effect and the effect of non-controlling interests (NCI) for each reconciling item1.
Chart 5: Overall feedback on the MPM requirements
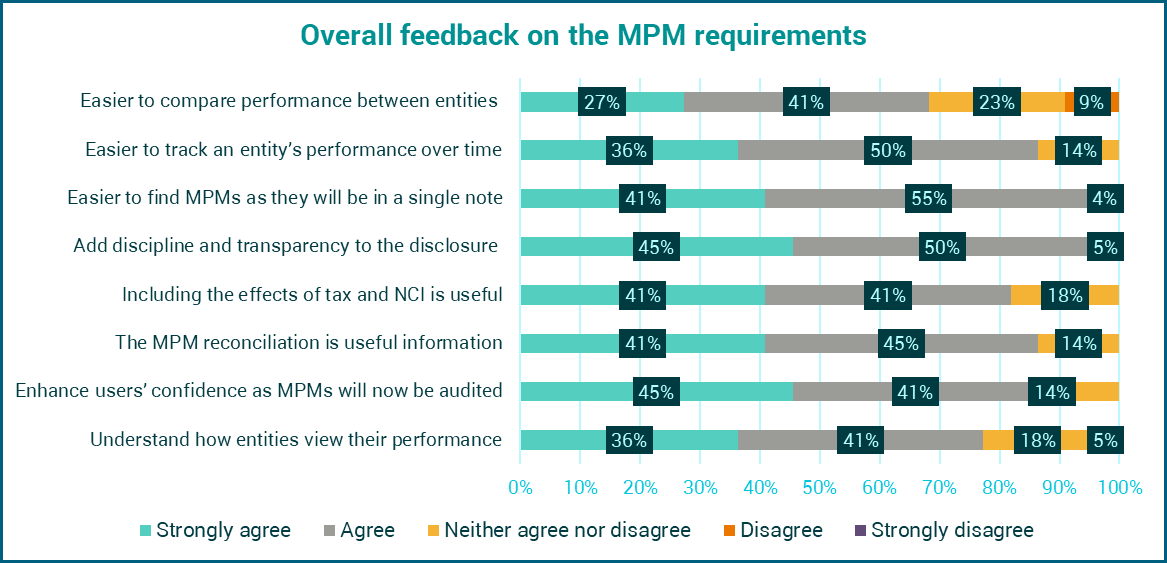
C22One respondent (a retail investor) suggested that an explicit requirement to disclose comparative information from previous years2 as well as requiring the presentation of actual versus target performance measures would also be helpful.
Other views
C23Respondents' views were split, with no clear majorities emerging, on the following issues:
- Whether users will get confused with the disclosure of MPMs and APMs in different sections of the annual report (40% of respondents agreed; 20% neither agreed or disagreed; 40% disagreed).
- Whether the reporting by entities of different MPMs may confuse users (41% of respondents agreed; 18% neither agreed or disagreed; 41% disagreed).
Chart 6: Feedback on the MPM requirements
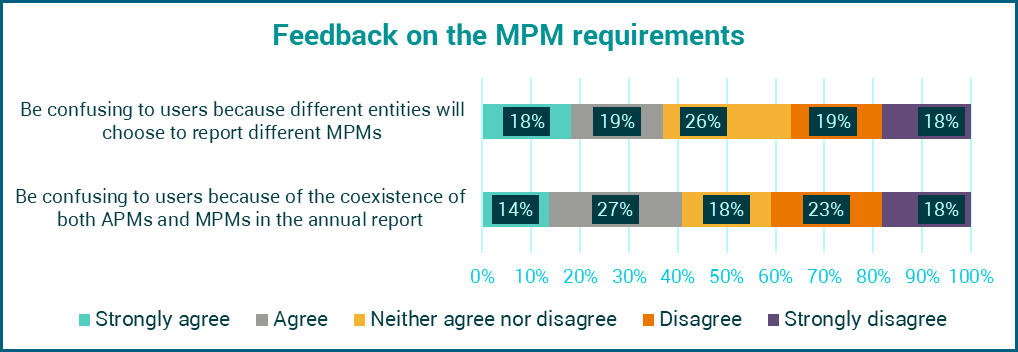
C24In this respect:
- Two respondents (an institutional investor, lender) agree that confusion and lack of comparability is inevitable because management will choose to provide different performance measures in different sections of the annual report.
- A few other respondents (institutional investors, analysts and researchers) consider that no confusion should arise as users are sophisticated enough to understand the nature of MPMs and APMs.
C25A respondent (credit rating agency) observed that management will continue using both APMs and MPMs to steer the narrative around business performance.
Aggregation and disaggregation
Benefits observed
C26Most respondents (77%) agreed that the requirements on aggregation and disaggregation will enhance the decision usefulness of:
- the information on the face of the financial statements; and
- the notes to the financial statements.
C27Respondents also indicated that the requirements will bring increased clarity and transparency of the information presented/disclosed.
C28Most respondents (77%) agreed that the guidance on the use of the label ‘other’ and requiring the disaggregation of large ‘other’ items will enhance comparability.
C29Most respondents (82%) agreed that the guidance on the use of the label ‘other’ will also enhance ‘understandability’ and would potentially prevent companies from "masking” performance drivers.
C30Additionally, most respondents (77%) also agreed that information on specified operating expenses by nature in the notes (if an entity presents operating expenses by function on the face of the income statement) will be useful.
Chart 7: Overall feedback on the requirements of aggregation and disaggregation
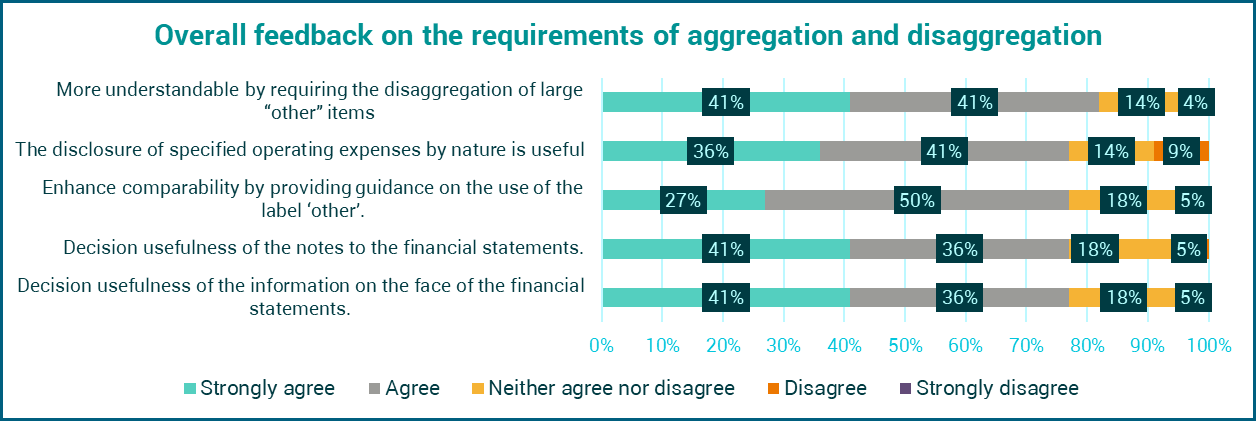
Challenges identified
C31Around 13% of respondents showed some concern that the aggregation and disaggregation principles may be interpreted in different ways leading to a loss of comparability.
Limited changes on the statement of cash flows
Benefits observed
C32Many respondents (68%) agreed that the limited amendments to IAS 7 Statement of Cash Flows will improve the usefulness of the statements of cash flows. Some of these respondents commented that this is because:
- having a consistent starting point (i.e. 'operating profit') for reporting cash flows from operating activities is helpful because this will enhance the comparability of the statement of cash flows and will be easier to interpret by users; and
- standardising the classification of interest and dividend cash flows in the statement of cash flows will lead to consistency and better comparability of this information across entities.3
Chart 8: Feedback on the limited changes on the statement of cash flows
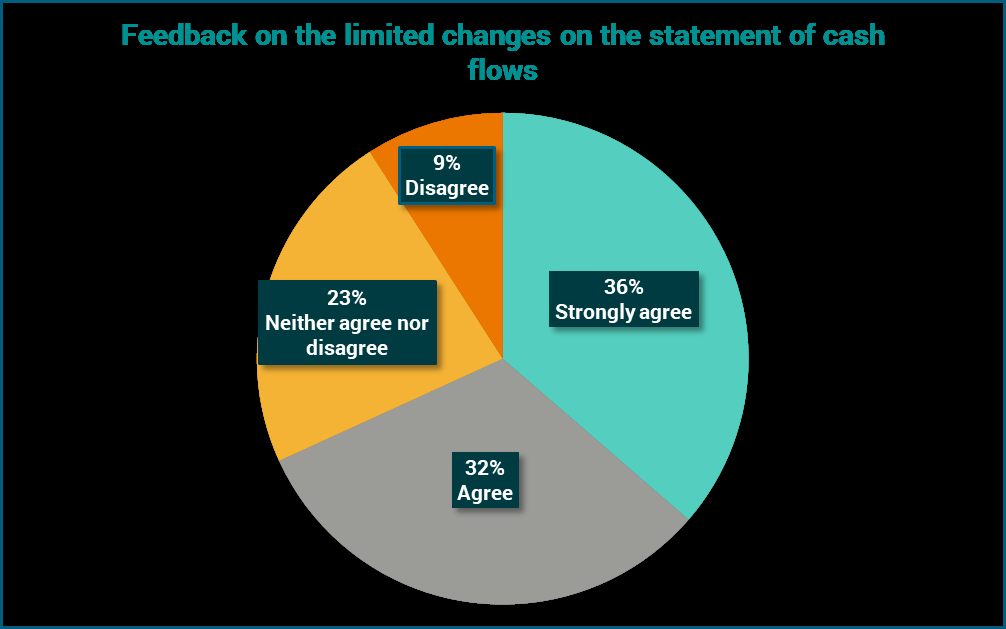
Challenges identified
C33Two respondents (an institutional investor, a retail investor) noted their disappointment that IFRS 18 had not sought full alignment between the categories in the income statement and the activities in the statement of cash flows. One respondent (sell-side broker dealer) noted that banks do not find the statement of cash flows useful.
Section 2: Feedback on costs and benefits and the wider economic impact
C34The survey investigated users' views and collected information as input to the long-term public good (LTPG) assessment on IFRS 18.
C35In its LTPG assessment, the survey obtained data on:
- direct costs to users:
- incremental one-off costs;
- incremental ongoing costs;
- direct benefits for users; and
- the wider economic impact of IFRS 18.
Direct costs to users
C36Respondents were asked about incremental one-off and ongoing costs, as well as about incremental cost reductions associated with the adoption of IFRS 18.
One-off costs
C37Respondents were asked to provide an estimate of the extra one-off costs related to the analysis of the first set of financial statements after the implementation of IFRS 18. Costs were expressed as a share of their operating costs, when applicable. The cost categories identified were:
- familiarisation;
- analysis of revised data from financial systems; and
- changes in internal processes or systems for analysing financial statements.
C38A total of 18 users responded to this question as follows:
- A majority of users, ranging between 55% and 61% depending on the cost category considered, indicated that one-off costs were expected to be nil; and
- The remaining portion of the responses indicated one-off costs were expected to be lower than 1% of operating costs (only one respondent suggested that familiarisation costs may be between 1% and 5% of operating costs).
C39One analyst noted that “The main cost will be a one-time change to our models that is far outweighed by the benefits”. One retail investor noted that: “The cost, if any, will be time, not monetary, but worthwhile for users/investors.”
Ongoing costs
C40Users were asked to provide an estimate of any annual extra costs that they anticipated their organisation would incur on the analysis of revised data from IFRS 18 financial statements on an ongoing basis. Costs had to be indicated as a share of their operating costs. Comments suggested that users do not expect any significant ongoing costs.4
Ongoing cost reductions
C41Users were asked to provide an estimate of any annual cost reductions that they anticipate their organisation will incur on the analysis of revised data from IFRS 18 financial statements on an ongoing basis.
C42Comments suggested that most users do not expect significant ongoing cost reductions.
C43However, two users mentioned cost savings.
- An institutional investor noted: “Overall this will reduce modelling costs on an ongoing basis as the presentation of the numbers is more closely aligned with how our standard model is constructed.”
- An analyst noted: “Savings will be ongoing (but will taper off as the saving are internalised into our new modelling).”
C44Another user commented on how the standard may lead to a more efficient allocation of resources: “There will be no cost cuts as the resources will be spent on doing more strategic analysis on the value chains of the businesses and the competitive dynamics for the industries.”
Direct benefits for users
C45Academic literature suggests that enhanced financial reporting can lead to a number of direct benefits for users, such as more efficient use of time spent analysing financial statements or improved decision-making/capital allocation. Accordingly, the implementation of IFRS 18 may be expected to provide users with similar benefits.
C46The users' survey draws from the academic literature to investigate direct benefits for users. In particular, the survey asked users to indicate whether they expected IFRS 18 to lead to any of the following benefits:
- more efficient use of time spent analysing financial statements;
- an increase in the quality of analysis/reports;
- enhanced company valuations/assessments;
- more precise forecasts/predictions; and
- enhanced lending/investment decisions.
Users were asked to select all the options that applied.
C47The results suggest that most respondents believe that the standard will be associated with more efficient use of time spent analysing financial statements (86%), and an increase in the quality of analysis/reports (76%). A significant percentage of users believe the standard will lead to enhanced company assessments (48%).5 The chart below provides a graphical representation.
Chart 9: Direct benefits of IFRS 18 to users of primary financial statements
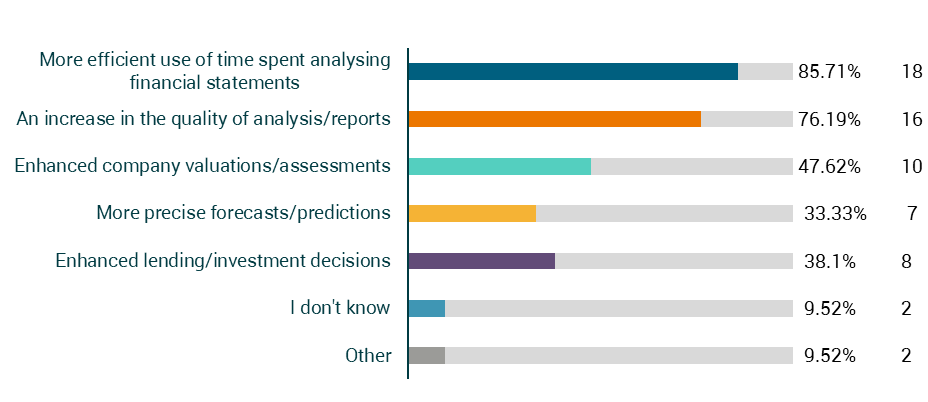
Wider economic impact
C48A total of 19 users provided their views on the wider economic impact of IFRS 18. On the items listed below, users indicated that IFRS 18 will either slightly improve or greatly improve their ability to analyse financial statements:
- compare entities' performance over multiple periods;
- assess an individual entity's performance;
- compare entities' performance with other entities;
- understand how entities measure their own performance;
- conduct research;
- allocate time spent analysing financial statements efficiently; and
- allocate capital efficiently between entities.
C49On some responses were more split. These were:
- evaluate management's use of economic resources (47% [improve], 32% [neither improve nor worsen], 0% [worsen], 0% [does not apply to my organisation], 21% [don't know/unsure]),
- allocate capital at an appropriate rate of return (42% [improve], 26% [neither improve nor worsen], 0% [worsen], 16% [does not apply to my organisation], 16% [don't know/unsure]),
- conduct accurate credit ratings (37% [improve], 31% [neither improve nor worsen], 0% [worsen], 16% [does not apply to my organisation], 16% [don't know/unsure), and
- utilise high quality third-party research (32% [improve], 47% [neither improve nor worsen], 0% [worsen], 5% [does not apply to my organisation], 16% [don't know/unsure).
C50For the assessment of a company's solvency, a narrow majority of respondents indicated that no effect was anticipated. This result is expected considering that IFRS 18 mainly deals with the presentation of financial performance (and therefore would not alter balance sheet line items or ratios).
C51It is worth noting that almost no respondents indicated that the standard will negatively impact any of the activities mentioned. Chart 10 provides a graphical representation of these results.
Chart 10: Wider economic impacts of IFRS 18 (users)
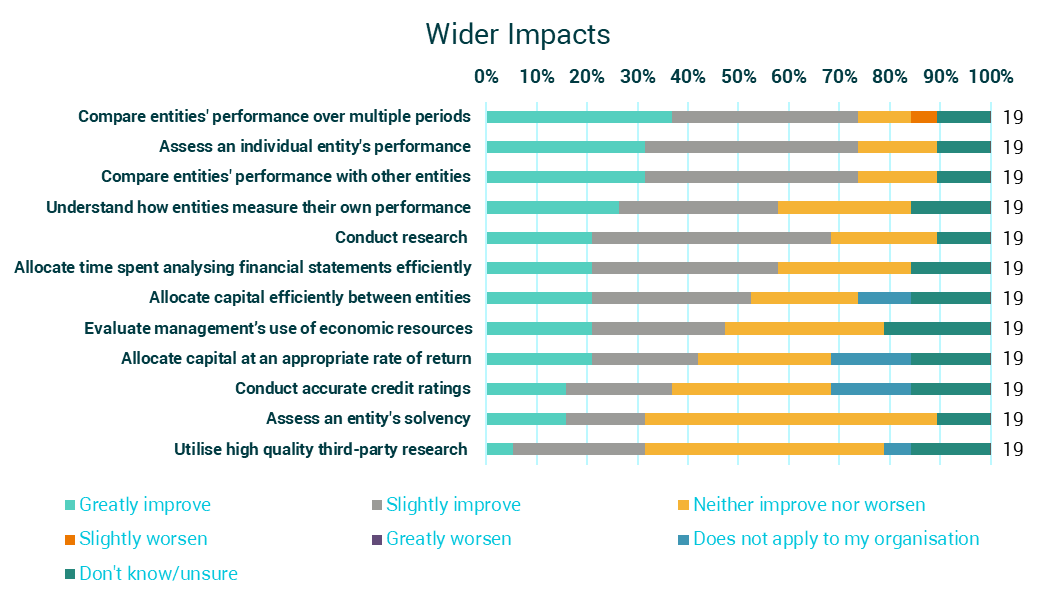
C52In summary, in terms of the direct benefits to users (consisting mostly of retail investors, institutional investors, and analysts/researchers), the preliminary view is that they agree that IFRS 18 will lead to more efficient use of time spent analysing financial statements, and an increase in the quality of analysis/reports. There is also agreement that the standard will enhance company valuations/assessments and will also allocate capital efficiently between entities.
C53Users believe that the implementation of IFRS 18 will neither improve nor worsen the ability of their organisation to utilise high quality third-party research.
Questions for the Board
4.Does the Board have any questions or comments on the preliminary [draft] report results from users' survey?
Appendix D: Preliminary [draft] report of views from auditors' questionnaire
Background
D1This appendix presents the results from the questionnaire distributed to members of the UKEB AFIAG on IFRS 18 Presentation and Disclosure in Financial Statements.
D2The aims of this exercise were:
- to obtain auditors' insight on the requirements of IFRS 18 and on the impact of this Standard in their audit processes; and
- to explore whether the views from auditors were aligned with the views from preparers.
D3Given that distribution was limited to UKEB AFIAG members the questionnaire does not formally qualify as a survey.
Overview of questionnaire responses
Technical accounting
D4Auditors broadly supported the requirements in IFRS 18.
Incremental one-off audit costs
D5On incremental one-off costs respondents indicated that:
- Some minor to significant extra one-off costs will be incurred as a result of IFRS 18. These will be largely attributable to:
- training;
- changes to templates;
- changes to reporting guidance; and
- changes in extraction of underlying data.
- Costs will depend on the nature and complexity of the business rather than its size. Considering IFRS 18 requirements, audit costs will be higher depending on:
- the assessment of the presence of specified main business activities;
- the number and nature of MPMs;
- the prevalence of foreign exchange transactions; and
- the change in the level of judgement about disaggregation based on the new requirements.
Incremental ongoing audit costs
D6Auditors indicated that incremental ongoing costs will depend on the conclusions of the initial assessment, but are expected to be more contained than the expected increase in one-off audit costs.
Impact of audit and advisory fees on audited entities
D7There were a number of comments from AFIAG members relating to the potential impact of the implementation of IFRS 18 on audit and advisory fees:
- There was some indication that extra fees may disproportionately affect smaller entities rather than larger entities.
- Extra costs for auditors will likely translate into higher fees. AFIAG members indicated that it was too early to provide reliable estimates of the absolute or relative increase in fees. Some respondents indicated that the increase in one-off fees may be sizable.
- Whether there is a permanent increase in fees will largely depend on the nature and complexity of the business, e.g. number of MPMs.
- AFIAG members indicated that there will likely be additional advisory fees for consulting services on the implementation of IFRS 18.
Appendix E: Design of the surveys
Aim of the surveys
E1This section describes the methodology utilised to collect data on the perspectives from preparers and users on:
- the main technical requirements of IFRS 18; and
- the perceived costs and benefits of IFRS 18 and the wider economic impact.
Survey design
Questionnaire design
E2The drafting of the questions, which started in April 2024, was informed by the following sources:
- desk-based research; and
- stakeholder engagement.
Desk-based research:
E3The drafting of the survey questions on the technical requirements was based on the review of the following materials:
- IASB materials such as: IFRS 18 Presentation and Disclosure in Financial Statements (including main guidance, application guidance, illustrative examples and basis for conclusions) and IASB staff papers;
- UKEB Board papers;
- Comment letters submitted by UK stakeholders to the IASB's exposure draft1;
- Comment letters submitted to the UKEB in the influencing phase of the project2;
- Relevant materials produced by other parties including accounting firms, regulators and other national standard setters; and
- Endorsement Criteria Assessment (ECA) for IFRS 17 Insurance Contracts3.
E4The drafting of the survey questions on the likely costs and benefits and wider economic impacts was based on the materials above, where relevant. In addition we reviewed:
- the IASB's IFRS 18 Effects Analysis (April 2024)4; and
- relevant academic and industry literature.
Stakeholder engagement
E5The drafting of survey questions takes into the consideration the feedback received from the Board, from the UKEB's advisory groups (Academic Advisory Group (AAG), Accounting Firms & Institutes Advisory Group (AFIAG), Investor Advisory Group (IAG), Preparer Advisory Group (PAG)) and from the UKEB’s Financial Instruments working group (FIWG).
E6The Secretariat had interactions with individual stakeholders; and with other standard-setters.
Testing and piloting
E7Early drafts of the questionnaire were tested internally (among UKEB technical staff) and with the AAG.
E8Near-complete drafts of the questionnaires were piloted with relevant advisory groups in June and July 2024. The responses received as part of the pilot were included in the pool of responses.
E9Responses from the piloting showed that no fatal flaws were present. The feedback was used to improve the survey design. Responses to the survey questions from the piloting were considered legitimate responses and included in the pool of responses for data analysis purposes.
Structure of the questionnaire
E10Both surveys were comprised of two parts:
- Section 1: Questions to obtain respondents' views on the presentation and disclosure requirements in IFRS 18, focusing on four areas:
- categories and subtotals;
- management-defined performance measures (MPMs);
- aggregation and disaggregation; and
- limited changes to the statement of cash flows.
- Section 2: Questions to obtain respondents' views on the likely costs and benefits associated with the new requirements as well as wider economic effects.
E11The following filtering criteria were applied:
- Preparers survey: The survey sought views from respondents who used UK-adopted International Accounting Standards in their financial statements.
- Users survey: The survey sought views from respondents who use or analyse or have used or analysed in the past IFRS financial statements to make investing and/or lending decisions or provide professional advice to others.
E12The surveys were comprised mostly of multiple choice questions and rating questions. In addition, most questions included a comment box to allow for the collection of qualitative information to supplement the closed-ended responses.
E13The questionnaire contains explanatory text and provides links to pre-recorded education materials. Respondents with prior knowledge of the standard could skip the educational materials, leading to a (tested) completion time of approximately 20 minutes. For respondents who needed to view the educational materials, testing suggested that the survey would have taken approximately 40 minutes to complete.
E14The education materials provided included:
- Links to educational videos5 and written summaries of IFRS 18 requirements on the four areas of changes. These were placed at the beginning of the respective sections.
- Descriptions of key terms, such as baseline costs or individual cost items (e.g. changes to accounting system; data handling; and accounts preparation), were placed at the beginning of Section 2.
Distribution
E15The surveys were programmed and administered using an online survey tool. A PDF version of the surveys was also distributed via email to allow potential respondents to view and circulate the survey questions internally to relevant people/teams before responding.
E16The surveys were launched on 15 July 2024 and remained open for over two months until 30 September 2024.
E17The surveys were advertised through a number of channels including:
- UKEB news alerts6 (on the website and to individual registered contacts of the UKEB);
- UKEB and individual LinkedIn posts;
- A UKEB educational webcast7 on IFRS 18; and
- A joint UKEB-IASB educational and outreach webinar8 on IFRS 18, during which the surveys were advertised using QR codes.
E18The following external organisations supported the distribution of the survey by sharing the survey links with their membership using distribution lists, newsletters and social media engagement:
- Users' groups: Chartered Financial Analyst UK (CFA UK); The Corporate Reporting User Forum (CRUF); The Investment Association (IA); The British Private Equity & Venture Capital Association (BVCA); The UK Shareholders' Association (UKSA).
- Preparers' groups: The 100 Group; The Quoted Companies Alliance (QCA); The Association of British insurers (ABI); UK Finance9;
- Accounting professional bodies: The Association of Chartered Certified Accountants (ACCA); The Institute of Chartered Accountants in England and Wales (ICAEW).
Agenda Paper 4: Appendix E
E15.The surveys were programmed and administered using an online survey tool. A PDF version of the surveys was also distributed via email to allow potential respondents to view and circulate the survey questions internally to relevant people/teams before responding.
Distribution
E16.The surveys were launched on 15 July 2024 and remained open for over two months until 30 September 2024.
E17.The surveys were advertised through a number of channels including:
- UKEB news alerts6 (on the website and to individual registered contacts of the UKEB);
- UKEB and individual LinkedIn posts;
- A UKEB educational webcast7 on IFRS 18; and
- A joint UKEB-IASB educational and outreach webinar8 on IFRS 18, during which the surveys were advertised using QR codes.
E18.The following external organisations supported the distribution of the survey by sharing the survey links with their membership using distribution lists, newsletters and social media engagement:
- Users' groups: Chartered Financial Analyst UK (CFA UK); The Corporate Reporting User Forum (CRUF); The Investment Association (IA); The British Private Equity & Venture Capital Association (BVCA); The UK Shareholders' Association (UKSA).
- Preparers' groups: The 100 Group; The Quoted Companies Alliance (QCA); The Association of British insurers (ABI); UK Finance9;
- Accounting professional bodies: The Association of Chartered Certified Accountants (ACCA); The Institute of Chartered Accountants in England and Wales (ICAEW).
- Investors' relations department of companies listed on the London Stock Exchange.
- Users' contacts from the Reuters/Eikon database.
E19.The Financial Reporting Council (FRC) also supported the distribution of the IFRS 18 surveys by sharing the UKEB news alerts with their subscribers. The FRC has around 10,000 individuals on its subscriber list. This included publishing the news alert on the FRC website.
E20.The UKEB is confident that the distribution covered the majority of relevant preparers and users of financial statements in the UK.
Survey questions
E21.Annex 1 in the next page provides a summary of the topics addressed by the questions included in the surveys for preparers and users.
Annex 1: Topics addressed by the questions included in the preparers' and users' surveys
| Preparers' survey | Users' survey |
|---|---|
| Cover Page | |
| Filtering questions to identify UK companies and IFRS reporters. | Filtering questions to identify users of financial statements (prepared by UK companies and IFRS reporters). |
| Demographics | |
| Section 1: Questions to collect information for the assessment of the technical accounting criteria | |
| Categories and subtotals | |
| - Overall requirements | - Overall requirements |
| - Specific classification requirements for entities with specified main business activities | - Specific classification requirements for income and expenses from equity-accounted investments in associates and joint ventures |
| - Specific classification requirements for income and expenses from equity-accounted investments in associates and joint ventures | |
| Management-defined performance measures (MPMs) | |
| - Overall requirements | - Overall requirements |
| - Current practice for communicating performance measures | |
| Aggregation and disaggregation | |
| - Overall requirements | - Overall requirements |
| - Disclosure of specified operating expenses by nature | |
| Limited amendments to the statement of cash flows | |
| - Overall requirements | - Overall requirements |
| Other views on technical requirements | |
| Section 2: Questions to collect information for the assessment of Long Term Public Good (LTPG) | |
| - Baseline costs for preparation of annual financial statements | - Not applicable |
| - Incremental one-off costs | - Incremental one-off costs |
| - Incremental ongoing costs | - Incremental ongoing costs |
| - Not applicable | - Direct benefits for users |
| - Wider economic impact | |
| Closing | |
| - Overall support | - Overall support |
| - Level of familiarity | - Level of familiarity |
| Consent for further discussion and contact details |
Footnotes
-
One respondent was against allowing choices in calculating the tax effect for reconciling items (i.e. where respondents provide a reasonable estimate of these tax effects). ↩↩↩
-
The Secretariat observes that paragraph 32 of IFRS 18 requires comparative information for information disclosed in the notes to the financial statements. ↩↩↩
-
One respondent showed concern that the approach for classifying interest and dividends cash flows is not aligned with US GAAP. ↩↩↩
-
Some comments are reported: "Nil", "Negligible", "Very marginal", "All costs will be one-time", "not applicable". ↩↩↩
-
The numbers for the previous percentages do not need to add up to 100% as respondents could select multiple items. ↩↩↩↩
-
News alerts were published on the UKEB website on 1 August 2024, 3 September 2024, 9 September 2024 and 25 September 2024. ↩↩↩
-
See the recording of the UKEB educational webcast on IFRS 18 here. ↩↩↩↩
-
See the recording of the joint UKEB-IASB educational and outreach webinar on IFRS 18 here. ↩↩↩↩
-
UK Finance and the ABI can be seen as a users' group too. The UKEB kindly asked the users' survey to be distributed to their members' relevant departments. ↩↩↩↩
-
Accounting system is understood as the system (increasingly software) designed to record the accounting transactions and events of a business and account for them in a way that complies with its policies and procedures. ↩↩
-
Data handling is understood as the flowing of transaction data through processes and controls and the recording of these data flows in accounting information systems/software as well as the conversion of year-end and consolidation journals/adjustments into that data flow, before financial statements and notes disclosures are prepared. ↩↩
-
Accounts preparation is understood as the final step of preparation of financial statements and disclosure notes, assuming the data needed has been recorded and appropriate adjustments made. ↩↩
-
In Q4 2023 the Secretariat identified the following issues: 1) Associates and joint ventures accounted for using the equity method presented in the investing category 2) Existence of MPMs and Alternative Performance Measures (APMs) and usefulness of the required disclosure of the tax and NCI effects and 3) Disclosure of specific expenses by nature. ↩
-
For example, it was raised as an issue in the Secretariat's response to the IASB's Exposure Draft ED/2019/7 General Presentation and Disclosures (ED). ↩
-
Refer to paragraph 39 of the PIP. These activities include roundtables, structured interviews or any additional long-term public good assessment activities such as commissioning an external economic study. ↩
-
Comprised of both external and internal audit costs (when the latter are present). The revision and piloting process suggested that the two could be lumped together without loss of generality. ↩
-
Comprised of both external and internal legal costs (when the latter are present). The revision and piloting process suggested that the two could be lumped together without loss of generality. ↩
-
In some circumstances baseline costs may be considered a commercially sensitive information. In some circumstances, preparers may not possess the information at all. This design allowed us to gather information about costs from most respondents. In addition, expressing incremental costs as a percentage encouraged respondents to provide the information. This survey design, agreed on after extensive revision, testing and piloting, allowed the UKEB to increase the number of responses it received. ↩
-
In the charts that follow, cost categories are ranked by size of expected change. ↩↩↩
-
Asking respondents to express incremental costs as a percentage of the baseline costs allowed us to extract information about the cost categories most likely to be affected because baseline costs are typically a small fraction of operating costs. Put more simply, an incremental cost that is less than 1% of operating costs may result to be between 1% and 5%, or even greater than 5%, when calculated a share of the baseline costs of preparing financial statements. ↩↩↩