5 Exposure Draft Equity Method of Accounting – IAS 28 Investments in Associates and Joint Ventures
17 October 2024 Agenda Paper 5
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Limited |
| Purpose of the paper |
The purpose of this paper is to:
- Obtain Board feedback on and approval for the Project Initiation Plan (PIP) for the Exposure Draft IASB ED/2024/7 Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x).
- Obtain Board feedback on the Draft Comment Letter (DCL) and Invitation to Comment (ITC) in relation to the Exposure Draft (ED).
- Request Board approval to publish the DCL and ITC on the UKEB website for stakeholder consultation.
Summary of the Issue
IAS 28 Investments in Associates and Joint Ventures and IFRS 11 Joint Arrangements require an entity to apply the equity method of accounting to investments in associates and joint ventures in its consolidated financial statements. IAS 27 Separate Financial Statements permits use of the equity method in an investor's separate financial statements for its investments in subsidiaries, associates and joint ventures.
IASB Exposure Draft
The IASB's project objectives are to improve the understandability of IAS 28, and to reduce diversity in practice by answering application questions about the equity method set out in that standard. To meet the project objectives, the IASB proposes to:
- Restructure and create additional requirements in IAS 28, including new illustrative examples.
- Add disclosure requirements to IFRS 12 Disclosure of Interests in Other Entities and IAS 27 Separate Financial Statements.
Project Initiation Plan and Draft Comment Letter
The PIP proposes a proportionate approach to developing the UKEB's response to the Exposure Draft. The UKEB does not adopt illustrative examples for use in the UK.
Given the limited scope of this ED's proposals and that UKEB Secretariat analysis suggests that material holdings in associates and joint ventures accounted for using the equity method are not widespread among UK listed companies applying IFRS, a high-level DCL containing draft feedback to the IASB is also included for Board comment. The ITC includes the 11 questions in the IASB's ED and asks stakeholders whether they agree with the proposals and to provide their rationale. If any significant issues are identified as part of the consultation, these can then be incorporated in the UKEB's comment letter before finalisation. The ITC includes one additional question asking stakeholders for comments on the costs and benefits of the ED's proposals.
Subject to Board approval at this meeting, the PIP and DCL will be published on the UKEB website. The DCL will remain open for stakeholder consultation for the requisite 30 days.
Other information
A link to the IASB Snapshot explaining the project is provided. The IASB has also published a series of webcasts explaining the proposals.
Should Board members like an education session, this can be arranged as an online session for interested Board members.
Decisions for the Board
Subject to addressing any comments raised during this meeting:
- does the Board approve the PIP?
- does the Board approve the DCL and ITC for publication for a 30-day comment period?
Recommendations
The Secretariat recommends that the Board:
- approves the PIP; and
- approves the DCL and accompanying ITC for a 30-day consultation.
Appendices
- Appendix A Project Initiation Plan (PIP)
- Appendix B Draft Comment Letter (DCL)
- Appendix C Invitation to Comment (ITC)
17 October 2024 Agenda Paper 5: Appendix A
Appendix A: Project Initiation Plan Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x)
Purpose
A1This paper sets out the plan to influence the proposed amendments to IAS 28 Investments in Associates and Joint Ventures included in the IASB Exposure Draft (ED) IASB ED/2024/7 Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x). The ED was published on 19 September 2024 with a consultation period ending on 20 January 2025.
A2The ED aims to improve the understandability of IAS 28, and to reduce diversity in practice by answering application questions1 about the equity method of accounting (equity method). The IASB's approach was to identify, explain and apply the principles that underlie IAS 28. As a result, the IASB proposes to restructure and create additional requirements in IAS 28 and proposes three new illustrative examples.
A3The IASB emphasises that no fundamental overhaul of the equity method has been undertaken as part of this project2.
A4To complement its proposed amendments to IAS 28, the ED also proposes amendments to the following IFRS Accounting Standards to improve disclosure requirements:
- IFRS 12 Disclosure of Interests in Other Entities; and
- IAS 27 Separate Financial Statements.
A5The ED also proposes related amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures3 to provide reduced disclosure requirements for eligible subsidiaries.
17 October 2024 Agenda Paper 5: Appendix A
Background
A6IFRS Accounting Standards require an investor or joint venturer to apply the equity method for investments in associates and joint ventures in its consolidated financial statements. An entity may apply the equity method in its separate financial statements for investments in subsidiaries, joint ventures and associates.
A7The IASB's 2015 Agenda Consultation noted that a number of queries on equity accounting, and its interaction with the accounting for other types of interests in other entities, had been raised with the Interpretations Committee. The IASB subsequently added a project on the equity method to its research pipeline to explore ways to address these questions and the resulting diversity in practice in accounting for investments in associates and joint ventures. In 2023 the project was promoted to standard setting, resulting in the publication of this ED.
A8The Board has received regular updates on this project in IASB General Update papers between June 2022 and July 20244. The IASB published a summary of tentative decisions in March 2024 and made further tentative decisions in June 2024.
Project plan
A9A proportionate approach has been applied in accordance with paragraphs 3.7 and 5.3 of the UKEB's Due Process Handbook. The Secretariat recommends the 'Limited scope' project plan shown below. The factors considered in arriving at this project plan are described in paragraphs A10–A22. A timeline for the key project milestones is presented in paragraph A26.
| Key activities | UKEB Due Process Handbook |
|---|---|
| Creation of a Project Initiation Plan (this document) | 5.4-5.8 Mandatory |
| Desk-based research to support the proportionality assessment including: | 5.9 Optional |
|
17 October 2024 Agenda Paper 5: Appendix A
| Key activities | UKEB Due Process Handbook |
|---|---|
| Publication of a Draft Comment Letter for public consultation | 5.13-5.17 Generally mandatory |
|
|
| Stakeholder outreach pre-DCL publication | |
|
|
| Stakeholder outreach post-DCL publication | 5.10-5.12 Mandatory |
|
|
| Final Comment Letter | 5.18 Mandatory |
| A final comment letter will be created for Board approval, submission to the IASB, and publication on the UKEB website. | |
| Project closure | 5.19-5.26 Mandatory |
| A Feedback Statement and Due Process Compliance Statement will be prepared. Once approved by the Board these documents will be published on the UKEB website. |
Proportionality assessment
Significance and size
IASB project scope
A10The IASB objective for this project is to provide clarification to application questions arising under IAS 28 and improve the understandability of the Standard. This approach should provide preparers with solutions to long-standing application difficulties, reduce diversity in practice and lead to more comparable and understandable information for users. Whilst this may result in some entities needing to change their accounting policies, the improved comparability for users is beneficial to the long-term public good.
17 October 2024 Agenda Paper 5: Appendix A
A11As noted at paragraph A3 above, the IASB has not conducted a fundamental review of the requirements of the equity method itself.
Entities affected by the proposals
A12The proposals affect entities that:
- are required by IAS 28 to use the equity method to account for investments in associates or joint ventures in consolidated financial statements or in individual financial statements6; and
- choose to use the equity method, as described in IAS 28, to account for investments in associates, joint ventures or subsidiaries in separate financial statements, as permitted by IAS 27.
A13Initial outreach to accounting firms indicated that the majority of UK companies do not have material equity accounted investments (or, if they had investments they would not be materially changed by the proposals). However, one firm noted that a minority of companies do have material equity accounted investments, some of which are economically significant entities. Feedback suggested that it is rare for UK entities to use the equity method in their separate financial statements.
A14The Secretariat conducted an analysis of Reuters-Eikon data to ascertain the prevalence of associates and joint ventures accounted for using the equity method among UK listed entities. The desktop research allowed the Secretariat to conclude that, among the approximately 1,400 listed entities which apply IFRS in the UK, as of the 2023 year-end:
- Only 22% (305 entities) have recognised holdings in associates and joint ventures using the equity method.
- The total value of these holdings was £123.6 billion, only 1.2% of total assets recognised on balance sheets.
- Only 5% of UK listed entities have investments in associates and joint ventures in excess of 5% of total assets.
17 October 2024 Agenda Paper 5: Appendix A
- For half of the entities that recognise associates and joint ventures using the equity method, their recognised holdings in associates and joint ventures are 1.1% or less of total assets.
- Holdings in associates and joint ventures are highly concentrated among a few large companies, with the five largest companies accounting for nearly 60% of total holdings, and the largest 20 companies accounting for 85% of total holdings.
A15This analysis suggests that, while not negligible, material holdings in associates and joint ventures accounted for using the equity method are not widespread among UK listed companies applying IFRS.
Complexity
A16The proposals are intended to provide preparers with clarifications related to the application of the equity method and to improve the understandability of the Standard. As such, we do not believe that the proposals are highly technical or complex.
Expected timeline / urgency
A17As noted in paragraph A7, this ED is the culmination of a long running IASB project. There is no indication of any need for urgent resolution or accelerated timeline in the UK.
Expected interest / sensitivity
A18There is no indication of wider UK concerns in relation to this project.
A19One IASB member indicated an intention to dissent from the proposals in the ED7.
Feedback on the proposals from desk-based research / initial outreach
A20Desk-top review by the Secretariat of accounting firm manuals suggests that IAS 28 is silent on the approach to certain aspects of accounting under the equity method. This is consistent with the IASB's findings that there is diversity in practice in application of the equity method. The proposals address some, but not all, such areas identified in the accounting manual review.
A21One accounting firm told us that, in their experience, the proposals are broadly aligned with current UK practice. Another accounting firm noted that some entities' investments would not be materially changed by the proposals, and initial analysis found some proposals helpful. However, they expressed concern as to the practicalities of certain proposals for entities with frequent changes in ownership interest, and for the proposed retrospective application of some requirements. It was also noted that retrospective application of the impairment requirements could, theoretically, give rise to counterintuitive results, such as uplifts in the carrying amount. Accounting firm work in analysing the proposals is ongoing.
17 October 2024 Agenda Paper 5: Appendix A
A22IASB analysis identified that the proposal that will likely affect most entities applying the equity method would be the recognition of gains and losses from transactions with (and between) equity accounted investments—an investor would recognise the full gain or loss resulting from all transactions with the associate8. The accounting firms we contacted are still considering the implications of this proposal.
UKEB project scope
A23Based on the proportionality assessment above we recommend a 'limited' project scope and the approach described in the project plan reflects this.
Resources allocated
A24To undertake the activities described in this project plan a project team has been assigned consisting of 0.75 of a Project Director. The required resources are allowed for in the 2024/25 UKEB plan and budget.
Setting up an ad-hoc advisory body
A25The UKEB will not require a separate ad-hoc advisory body for this project. Existing UKEB advisory and working groups have the necessary skills and expertise to support this project and will be consulted as outlined in the project plan.
Project timeline
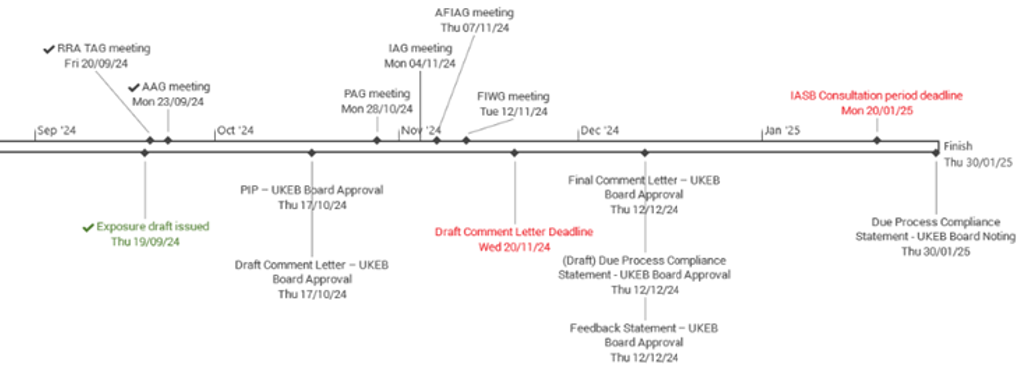
A26The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board, to reflect any material changes, as the project progresses.
17 October 2024 Agenda Paper 5: Appendix A
| Date | Milestones |
|---|---|
| 17 October 2024 | Project Initiation Plan for Board approval Draft Comment Letter for Board approval |
| Estimated DCL consultation period (30 days): 21 October – 20 November 2024 | |
| 12 December 2024 | Board review of Final Comment Letter, Feedback Statement, draft Due Process Compliance Statement |
| December 2024 | Final Comment Letter submitted to IASB (deadline 20 January 2025) |
| 30 January 2025 | Due Process Compliance Statement for noting. |
17 October 2024 Agenda Paper 5: Appendix A
Project Initiation Plan: Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x) - Proposed timeline
A27The diagram below is a graphical view of the key milestones and outreach activities described above.
17 October 2024 Agenda Paper 5: Appendix B
Dr Andreas Barckow Chair International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
[Date]
Dear Dr Barckow
Invitation to Comment: Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x)
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,400 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.9 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.10
3The UKEB welcomes the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x) (the ED). In developing this letter, we consulted with stakeholders in the UK. We are not aware of pervasive or material concerns in the UK arising from the ED proposals.
17 October 2024 Agenda Paper 5: Appendix B
4If you have any questions about this response, please contact the UKEB project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
17 October 2024 Agenda Paper 5: Appendix C
Appendix C: Invitation to Comment
Call for comments on the UKEB Draft Comment Letter on IASB Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x)
Deadline for completion of this Invitation to Comment:
Wednesday 20 November 2024
Please submit to: [email protected]
Introduction
The objective of this Invitation to Comment is to obtain input from stakeholders on the UKEB Draft Comment Letter (DCL) responding to the questions as set out in the Exposure Draft Equity Method of Accounting—IAS 28 Investments in Associates and Joint Ventures (revised 202x), published by the International Accounting Standards Board (IASB) on 19 September 42024. The IASB's consultation period ends on 20 January 2025. Responses to this Invitation to Comment are requested by 20 November 2024.
UK endorsement and adoption process
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. This DCL is intended to contribute to the IASB's due process. The views expressed by the UKEB in the DCL are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
Who should respond to this Invitation to Comment?
Stakeholders with an interest in the quality of accounts prepared in accordance with international accounting standards.
17 October 2024 Agenda Paper 5: Appendix C
How to respond to this Invitation to Comment
Please download this document, answer any questions on which you would like to provide views, and return it together with a completed ‘Your Details' form to [email protected] by close of business on Wednesday 20 November 2024.
Brief responses providing views on individual questions are welcome, as well as comprehensive responses to all questions.
Privacy and other policies
The data collected through responses to this document will be stored and processed by the UKEB. By submitting this document, you consent to the UKEB processing your data for the purposes of influencing the development of and adopting IFRS for use in the UK. For further information, please see our Privacy Statements and Notices and other Policies (e.g. Consultation Responses Policy and Data Protection Policy)11.
The UKEB's policy is to publish on its website all responses to formal consultations issued by the UKEB unless the respondent explicitly requests otherwise. A standard confidentiality statement in an e-mail message will not be regarded as a request for non-disclosure. If you do not wish your signature to be published, please provide the UKEB with an unsigned version of your submission. The UKEB prefers to publish responses that do not include a personal signature. Other than the name of the organisation/individual responding, information contained in the “Your Details” document will not be published. The UKEB does not edit personal information (such as telephone numbers, postal or e-mail addresses) from any other response document submitted; therefore, only information that you wish to be published should be submitted in such responses.
17 October 2024 Agenda Paper 5: Appendix C
Proposed amendments to IAS 28 Investments in Associates and Joint Ventures
Measurement of cost of an associate
Question 1—Measurement of cost of an associate (Appendix A and paragraphs 13, 22, 26 and 29 of [draft] IAS 28 (revised 202x))
Paragraph 32 of IAS 28 requires an investor that obtains significant influence to account for the difference between the cost of the investment and the investor's share of the net fair value of the associate's identifiable assets and liabilities either as goodwill (included in the carrying amount of the investment) or as a gain from a bargain purchase (recognised in profit or loss). However, IAS 28 does not include requirements for how an investor measures the cost of the investment on obtaining significant influence—for example:
- whether to measure any previously held ownership interest in the associate at fair value; or
- whether and if so how to recognise and measure contingent consideration.
The IASB is proposing an investor:
- measure the cost of an associate, on obtaining significant influence, at the fair value of the consideration transferred, including the fair value of any previously held interest in the associate.
- recognise contingent consideration as part of the consideration transferred and measure it at fair value. Thereafter:
- not remeasure contingent consideration classified as an equity instrument; and
- measure other contingent consideration at fair value at each reporting date and recognise changes in fair value in profit or loss.
Paragraphs BC17–BC18 and BC89–BC93 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
17 October 2024 Agenda Paper 5: Appendix C
Changes in an investor's ownership interest while retaining significant influence
Question 2—Changes in an investor's ownership interest while retaining significant influence (Paragraphs 30–34 of [draft] IAS 28 (revised 202x))
IAS 28 does not include requirements on how an investor accounts for changes in its ownership interest in an associate, while retaining significant influence, that arise from:
- the purchase of an additional ownership interest in the associate;
- the disposal of an ownership interest (partial disposal) in the associate; or
- other changes in the investor's ownership interest in the associate.
The IASB is proposing to require that an investor:
- at the date of purchasing an additional ownership interest in an associate:
- recognise that additional ownership interest and measure it at the fair value of the consideration transferred;
- include in the carrying amount the investor's additional share of the fair value of the associate's identifiable assets and liabilities; and
- account for any difference between (i) and (ii) either as goodwill included as part of the carrying amount of the investment or as a gain from a bargain purchase in profit or loss.
- at the date of disposing of an ownership interest:
- derecognise the disposed portion of its investment in the associate measured as a percentage of the carrying amount of the investment; and
- recognise any difference between the consideration received and the amount of the disposed portion as a gain or loss in profit or loss.
- for other changes in its ownership interest in an associate:
- recognise an increase in its ownership interest, as if purchasing an additional ownership interest. In (a)(i), ‘the fair value of the consideration transferred' shall be read as 'the investor's share of the change in its associate's net assets arising from the associate's redemption of equity instruments'.
- recognise a decrease in its ownership interest, as if disposing of an ownership interest. In (b)(ii) ‘the consideration received' shall be read as 'the investor's share of the change in its associate's net assets arising from the associate's issue of equity instruments'.
Paragraphs BC20–BC44 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
17 October 2024 Agenda Paper 5: Appendix C
Recognition of the investor's share of losses
Question 3—Recognition of the investor's share of losses (Paragraphs 49–52 of [draft] IAS 28 (revised 202x))
Paragraph 38 of IAS 28 requires that if an investor's share of losses equals or exceeds its interest in the associate, the investor discontinue recognising its share of further losses. However, IAS 28 does not include requirements on whether an investor that has reduced the carrying amount of its investment in an associate to nil:
- on purchasing an additional ownership interest, recognises any losses not recognised as a 'catch up' adjustment by deducting those losses from the cost of the additional ownership interest; or
- recognises separately its share of each component of the associate's comprehensive income.
The IASB is proposing an investor:
- on purchasing an additional ownership interest, not recognise its share of an associate's losses that it has not recognised by reducing the carrying amount of the additional ownership interest.
- recognise and present separately its share of the associate's profit or loss and its share of the associate's other comprehensive income.
Paragraphs BC47–BC62 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
17 October 2024 Agenda Paper 5: Appendix C
Transactions with associates
Question 4—Transactions with associates (Paragraph 53 of [draft] IAS 28 (revised 202x))
Paragraph 28 of IAS 28 requires an investor to recognise gains and losses resulting from transactions between itself and an associate only to the extent of unrelated investors' interests in the associate.12 This requirement applies to both 'downstream' transactions (such as a sale or contribution of assets from an investor to an associate) and 'upstream' transactions (such as a sale of assets from an associate to an investor).
If an investor loses control of a subsidiary in a transaction with an associate, the requirement in IAS 28 to recognise only a portion of the gains or losses is inconsistent with the requirement in IFRS 10 to recognise in full the gain or loss on losing control of a subsidiary.
The IASB is proposing to require that an investor recognise in full gains and losses resulting from all 'upstream' and 'downstream' transactions with its associates, including transactions involving the loss of control of a subsidiary.
Paragraphs BC63–BC84 of the Basis for Conclusions explain the IASB's rationale for this proposal.
Do you agree with this proposal?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
Impairment indicators (decline in fair value)
Question 5—Impairment indicators (decline in fair value) (Paragraph 57 of [draft] IAS 28 (revised 202x))
Paragraphs 41A–41C of IAS 28 describe various events that indicate the net investment in an associate could be impaired. Paragraph 41C of IAS 28 states that a significant or prolonged decline in the fair value of an investment in an equity instrument below its cost is objective evidence of impairment. One of the application questions asked whether an investor should assess a decline in the fair value of an investment by comparing that fair value to the carrying amount of the net investment in the associate at the reporting date or to the cost of the investment on initial recognition.
17 October 2024 Agenda Paper 5: Appendix C
The IASB is proposing:
- to replace 'decline...below cost' of an investment in paragraph 41C of IAS 28 with 'decline...to less than its carrying amount';
- to remove 'significant or prolonged' decline in fair value; and
- to add requirements to IAS 28 explaining that information about the fair value of the investment might be observed from the price paid to purchase an additional interest in the associate or received to sell part of the interest, or from a quoted market price for the investment.
The IASB is also proposing to reorganise the requirements in IAS 28 relating to impairment to make them easier to apply, and to align their wording with the requirements in IAS 36 Impairment of Assets.
Paragraphs BC94–BC106 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
Application of the proposed requirements to investments in subsidiaries to which the equity method is applied in separate financial statements
Question 6—Investments in subsidiaries to which the equity method is applied in separate financial statements
Paragraph 10 of IAS 27 permits a parent entity to use the equity method in IAS 28 to account for investments in subsidiaries, joint ventures and associates in separate financial statements.
The IASB is proposing to retain paragraph 10 of IAS 27 unchanged, meaning that the proposals in this Exposure Draft would apply to investments in subsidiaries to which the equity method is applied in the investor's separate financial statements.
Paragraphs BC112–BC127 of the Basis for Conclusions explain the IASB's rationale for this proposal.
17 October 2024 Agenda Paper 5: Appendix C
Do you agree with this proposal?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
Proposed amendments to IFRS 12 Disclosure of Interests in Other Entities and IAS 27 Separate Financial Statements—Disclosure requirements
Question 7—Disclosure requirements (Paragraphs 20(c), 21(d)–21(e) and 23A–23B of IFRS 12 and paragraph 17A of IAS 27)
The IASB is proposing amendments to IFRS 12 in this Exposure Draft. For investments accounted for using the equity method, the IASB is proposing to require an investor or a joint venturer to disclose:
- gains or losses from other changes in its ownership interest;
- gains or losses resulting from 'downstream' transactions with its associates or joint ventures;
- information about contingent consideration arrangements; and
- a reconciliation between the opening and closing carrying amount of its investments.
The IASB is also proposing an amendment to IAS 27 to require a parent—if it uses the equity method to account for its investments in subsidiaries in separate financial statements—to disclose the gains or losses resulting from its 'downstream' transactions with its subsidiaries.
Paragraphs BC137–BC171 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
17 October 2024 Agenda Paper 5: Appendix C
Proposed amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures
Question 8—Disclosure requirements for eligible subsidiaries (Paragraphs 88(c), 91A and 240A of IFRS 19)
IFRS 19 permits eligible subsidiaries to apply IFRS Accounting Standards with reduced disclosure requirements. It specifies the disclosure requirements an eligible subsidiary applies instead of the disclosure requirements in other IFRS Accounting Standards.
As part of developing proposed amendments to the disclosure requirements in other IFRS Accounting Standards, the IASB regularly considers which of those proposed amendments should be included in IFRS 19, based on the IASB's principles for reducing disclosure requirements for eligible subsidiaries.
The IASB is proposing amendments to IFRS 19 to require an eligible subsidiary:
- to disclose information about contingent consideration arrangements; and
- to disclose gains or losses resulting from ‘downstream' transactions with its associates or joint ventures.
The IASB is also proposing an amendment to IFRS 19 to require a subsidiary that chooses to apply the equity method to account for its investments in subsidiaries in separate financial statements to disclose gains or losses resulting from 'downstream' transactions with those subsidiaries.
Paragraphs BC172–BC177 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative, taking into consideration the principles for reducing disclosure requirements for eligible subsidiaries applying IFRS 19 (see paragraph BC175 of the Basis for Conclusions):
17 October 2024 Agenda Paper 5: Appendix C
Other matters
Transition
Question 9—Transition (Paragraphs C3–C10 of [draft] IAS 28 (revised 202x))
The IASB is proposing to require an entity:
- to apply retrospectively the requirement to recognise the full gain or loss on all transactions with associates or joint ventures;
- to apply the requirements on contingent consideration by recognising and measuring contingent consideration at fair value at the transition date—generally the beginning of the annual reporting period immediately preceding the date of initial application—and adjusting the carrying amount of its investments in associates or joint ventures accordingly; and
- to apply prospectively all the other requirements from the transition date.
The IASB is also proposing relief from restating any additional prior periods presented.
Paragraphs BC178–BC216 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals?
| Yes | No |
|---|---|
If you agree, please explain why you agree. If you disagree, please explain why you disagree and your suggested alternative:
Expected effects of the proposals
Question 10—Expected effects of the proposals
Paragraphs BC217–BC229 of the Basis for Conclusions explain the IASB's analysis of the expected effects of implementing its proposals.
Do you agree with this analysis?
| Yes | No |
|---|---|
If you disagree with the IASB analysis of the expected effects of the proposals, please explain which aspects of the analysis you disagree with and why:
17 October 2024 Agenda Paper 5: Appendix C
Other proposals
Question 11a—Appendices and Illustrative Examples
Do you have any comments on Appendix D to the Exposure Draft or the Illustrative Examples accompanying the Exposure Draft?
Question 11b—Understandability
Do you have any comments or suggestions on the way the IASB is proposing to re-order the requirements in IAS 28, as set out in the Exposure Draft?
Costs vs. benefits
Question 12a—Costs
What do you believe are the short-term and long-term cost implications of applying the proposals?
Question 12b—Benefits
What do you believe are benefits to users of financial statements of entities applying the proposals?
Would you like to provide any other comments on the ED? If so, please do so in the box below.
17 October 2024 Agenda Paper 5: Appendix C
Thank you for completing this Invitation to Comment
Please submit this document by close of business on Wednesday 20 November 2024 to: [email protected]
Footnotes
Footnotes
-
Application questions in the scope of the project are set out in the Basis for Conclusions (Table 1 paragraph BC13). Paragraph BC15 Table 2 provides a list of the 10 principles identified as underlying IAS 28. ↩
-
IFRS 19 permits subsidiaries that do not have public accountability and meet other specified criteria (eligible subsidiaries) to apply IFRS Accounting Standards with reduced disclosures requirements. It also specifies the disclosure requirements an eligible subsidiary is permitted to apply instead of the disclosure requirements in other IFRS Accounting Standards. ↩
-
Links to the IASB General update papers for this project can be found on the UKEB project webpage here. ↩
-
The UKEB Advisory Groups scheduled during the consultation period are the Accounting Firms & Institutes Advisory Group (AFIAG), the Investor Advisory Group (IAG), and the Preparer Advisory Group (PAG). The relevant UKEB working groups scheduled during the consultation period are the Financial Instruments Working Group (FIWG). ↩
-
The term 'individual financial statements' is sometimes used to describe the financial statements of an entity with no subsidiaries (per Basis for Conclusions BC219). ↩
-
See Alternative View AV1 on pages 62-64 of the Basis for Conclusions. Mr Cendon supports the proposals in the Exposure Draft amending the equity method requirements in IAS 28. However, in his opinion, IAS 27 should have been amended to include an option to apply the equity method of accounting differently when the parent has control of the investee (that is, when the investee is a subsidiary) and the entity elects to apply the equity method. ↩
-
Paragraph 28 of IAS 28 requires an investor to restrict the gain or loss recognised in a transaction with an associate to the extent of the unrelated investors' interests in the associate. That requirement applies to both downstream and upstream transactions. The portion of the gain or loss that is not recognised at the date of the transaction is recognised subsequently, when the transferred asset is sold to unrelated third parties or consumed over time. However, paragraphs 25 and B97–B99 of IFRS 10 require an investor to recognise in full the gains or losses on the loss of control of a subsidiary. The proposals aim to eliminate the inconsistency between the requirements in IAS 28 and IFRS 10 when an investor accounts for the sale or contribution of a subsidiary to an associate. ↩
-
UKEB calculation based on LSEG and Eikon data, May 2024. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩
-
These policies can be accessed from the footer in the UKEB website here. ↩
-
This Invitation to Comment describes the requirement in paragraph 28 of IAS 28 that is currently in effect. The IASB amended that requirement when it issued Sale or Contribution of Assets between an Investor and its Associate or Joint Venture (Amendments to IFRS 10 and IAS 28) in 2014, but the effective date of those amendments has been deferred indefinitely. ↩