6 Exposure Draft Climate-related and Other Uncertainties in the Financial Statements
19 September 2024 Agenda Paper 6
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
| Purpose of the paper |
The purpose of this paper is to obtain Board approval for publication of the Draft Comment Letter (DCL) and Invitation to Comment (ITC) for the IASB Exposure Draft Climate-related and Other Uncertainties in the Financial Statements – Proposed illustrative examples.
Executive Summary
Summary of the issue
The IASB Exposure Draft (ED) was issued on 31 July 2024 with a comment deadline of 28 November 2024.
The UKEB Board approved a Project Initiation Plan (PIP) for the ED at its July 2024 meeting, in anticipation of the ED publication.
As anticipated in the PIP the ED contains eight illustrative examples which broadly align with the IASB staff draft examples previously discussed at ASAF.
The illustrative examples are proposed to accompany individual IFRS Accounting Standards and will not form an integral part of those Standards. Consequently, the ED does not contain an effective date or any transition requirements.
The ED does not seek to: develop an Accounting Standard on climate-related risks; broaden the objective of financial statements; change the definitions of assets and liabilities; or develop accounting requirements for pollutant pricing mechanisms. Instead, it provides guidance on how the requirements in the Standards could be applied to provide investors with better information about climate-related risks and other uncertainties.
The UKEB does not adopt illustrative examples for use in the UK. However, as the examples will be relevant to a wide range of UK entities applying IFRS and given the UKEB's remit to consider the overlap between IASB and ISSB issued standards, the Board agreed to undertake an influencing project, mainly with the aim of raising awareness of the examples with UK stakeholders.
Decisions for the Board
DCL and Invitation to Comment
Does the Board support the inclusion of paragraph 8 on Longer term strategy in the DCL, and question 2 on this in the draft Invitation to Comment?
Subject to addressing any comments raised during the meeting, does the Board approve the DCL for publication and draft ITC, for stakeholder feedback?
Recommendation
The Secretariat recommends that the Board approves the DCL and accompanying draft ITC.
Appendices
- Appendix A Draft Comment Letter
- Appendix B Invitation to Comment
Background
1The IASB has proposed eight illustrative examples on how companies apply IFRS Accounting Standards when reporting the effects of climate-related and other uncertainties in their financial statements.
2The IASB developed these illustrative examples in response to strong demand from stakeholders, particularly from investors. They expressed concerns that information about climate-related uncertainties in financial statements was sometimes insufficient or appeared to be inconsistent with information provided outside the financial statements.
3The illustrative examples focus on areas such as materiality judgements, disclosures about assumptions and estimation uncertainties, and disaggregation of information. The principles and requirements illustrated are intended to apply equally to other types of uncertainties beyond climate-related uncertainties.
Draft Comment Letter
4The DCL is attached at Appendix A for consideration and approval, with the accompanying Invitation to Comment at Appendix B. Overall, the DCL supports the IASB's objectives but makes recommendations to enhance the ED's proposals.
5The DCL is supportive of the ED and makes several recommendations to enhance the approach and content of the illustrations. The main observations and recommendations are:
- The IASB may wish to consider other standard setting solutions as the examples may place too much reliance on paragraphs 31 and 125 of IAS 1 Presentation of Financial Statements.
- A request that the IASB elaborates on its longer-term strategy regarding connectivity and alignment with the ISSB's future standards as part of its upcoming Agenda Consultation.
- Illustrative examples accompanying the relevant accounting standards is the most efficient route to address users' immediate requirements. We have provided several comments that enhance relevance and support connectivity.
6As approved by the UKEB at the July 18 meeting the DCL will be issued for a 45-day comment period ending on 8 November 2024.
Research and outreach
7In March 2024, the Secretariat gathered the feedback on the IASB's draft illustrative examples from the UKEB Sustainability Working Group and other Advisory Groups which has been reflected in the letter1. In addition, the Secretariat conducted some further desk-based research, including reviewing the ED, IASB staff papers and meeting summaries and other relevant publications from accounting firms.
8Since the July 2024 UKEB meeting, further stakeholder outreach has been limited due to the summer holidays. However, some stakeholders have since reached out and are keen to engage during September and October 2024. We will engage as appropriate with those stakeholders during the consultation period of the DCL.
Questions for the Board
1. Does the Board support the inclusion of paragraph 8 on Longer term strategy in the DCL, and a question on this in the draft Invitation to Comment?
2. Subject to addressing any comments raised during the meeting, does the Board approve the DCL for publication and draft Invitation to Comment for stakeholder feedback?
Next steps
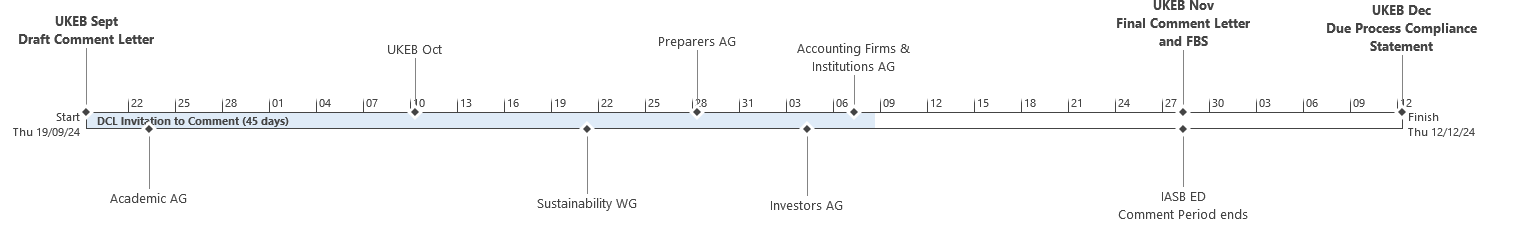
9If the UKEB approves the DCL, it will be issued for a 45 day public consultation. A Final (draft) comment letter will be presented at the 28 November UKEB meeting along with the accompanying Feedback Statement and draft Due Process Compliance Statement.
10As the IASB comment deadline is the same day as the UKEB's November 2024 meeting, the IASB has been advised that the UKEB letter may be delayed by a few days to address any Board comments, if necessary.
11Further information on the project timeline is presented in the table below.
| Expected Dates | Milestone | Status |
|---|---|---|
| 18 July 2024 | Board: Discusses and approves Project Initiation Plan (PIP). | Completed |
| IASB Exposure Draft consultation period (120 days): 31 July – 28 November 2024 | ||
| 31 July 2024 | IASB: Publishes ED with a 120-day comment period | Completed |
| 19 September 2024 | Board: Consideration and approval of Draft Comment Letter (DCL) | This meeting |
| 23 September 2024 (estimate) | Secretariat: Publishes DCL and Invitation to Comment on website and alerts key stakeholders (as soon as possible after 19 September Board meeting) | To be completed |
| UKEB DCL consultation period (45 days): 24 September – 8 November 2024 | ||
| 28 November 2024 | IASB: Exposure Draft consultation period ends | To be completed |
| 28 November 2024 | Board: Discusses and approves Final Comment Letter (FCL), Feedback Statement and draft Due Process Compliance Statement (DPCS) | To be completed |
| [29 November] 2024 | Secretariat: Submits FCL to IASB and publishes FCL on website (as soon as possible after 28 November Board meeting) | To be completed |
| 12 December 2024 | Board: Notes completed DPCS | To be completed |
| 13 December 2024 | Secretariat: Publishes DPCS on website | To be completed |
Timeline
Dr Andreas Barckow Chairman International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
28 November 2024
Dear Dr Barckow
Exposure Draft IASB/ED/2024/6 Climate-related and Other Uncertainties in the Financial Statements - Proposed illustrative examples
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments, and interpretations. In addition, the Department for Business and Trade has asked the UKEB to consider the overlap between IASB and ISSB issued standards.
2This letter is intended to contribute to the IFRS Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
3There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.2 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.3
4We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB) Exposure Draft Climate-related and Other Uncertainties in the Financial Statements - Proposed illustrative examples (the ED). We support the IASB's objective in developing the illustrative examples as well as the timely publication of the ED, and we are broadly supportive of the approach. Whilst not a mandatory part of accounting standards, the examples proposed in the ED should provide relevant guidance to many UK entities applying IFRS. UKEB research4 undertaken in 2023 has also shown that connectivity between sustainability disclosures and financial reporting is important to users of those reports.
5In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts.
6Our main observations and recommendations are set out in the paragraphs below. Responses to the detailed questions in the ED are included in Appendix A to this letter.
Overarching comments
7We have identified some instances in the ED where the IASB may wish to consider other standard setting solutions as the guidance provided may be going beyond existing interpretations of those requirements, for example in relation to paragraphs 31 and 125 of IAS 1 Presentation of Financial Statements. For further information please refer to paragraph A4 in Appendix A.
Longer-term strategy
8We would suggest that the IASB consider elaborating on its longer-term strategy regarding connectivity and alignment with the future ISSB's/other sustainability standards as part of its upcoming Agenda Consultation. For further information please refer to A23 – A24 in Appendix A.
Illustrative examples
9While we recognise the challenges of delivering guidance as sustainability reporting is expected to evolve in the near future, it is also clear that demand for clarity regarding connectivity is urgent and necessary in all jurisdictions that apply IASB's standards and are now committed to providing sustainability information to investors. As highlighted in the joint National Standard Setters letter to the International Sustainability Standards Board (ISSB) on its Agenda Consultation, we consider that maintaining close alignment and connectivity between financial and sustainability reporting is paramount to ensure that the information produced for investors is compatible and comparable.
10We agree that providing illustrative examples should improve the current level of reporting for the effects of climate-related and other uncertainties in the financial statements. However, we consider that these examples could be enhanced by including a scenario where there is an impact on the financial statements, and by incorporating explicit reference to IFRS Sustainability Disclosure Standards.
11Appendix A includes further detail of some overarching comments on certain unintended consequences, and areas where we consider that the examples could be improved. For further information please refer to paragraphs A1-A10 in Appendix A.
Approach to developing illustrative examples
11We are generally supportive of the IASB's approach to developing the examples and in particular that the examples should illustrate how an entity applies the requirements in IFRS Accounting Standards (BC14). We also agree with the approach of focusing the examples on the requirements that are among the most relevant for reporting the effects of climate related and other uncertainties in financial statements.
12We do however have some comments on the fact patterns and technical content of the examples. Our comments are aimed at helping enhance the relevance of the illustrations and to support connectivity. These are included in the paragraphs A11 to A22 in Appendix A.
13If you have any questions about this response, please contact the project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Exposure Draft Climate-related and Other Uncertainties in the Financial Statements – Proposed illustrative examples
Question 1 – Providing illustrative examples
The IASB is proposing to provide eight examples illustrating how an entity applies the requirements in IFRS Accounting Standards to report the effects of climate-related and other uncertainties in its financial statements. The IASB expects the examples will help to improve the reporting of these effects in the financial statements, including by helping to strengthen connections between an entity's general purpose financial reports.
Paragraphs BC1–BC9 of the Basis for Conclusions further explain the IASB's rationale for this proposal.
(a) Do you agree that providing examples would help improve the reporting of the effects of climate-related and other uncertainties in the financial statements? Why or why not? If you disagree, please explain what you would suggest instead and why.
The IASB is proposing to include the examples as illustrative examples accompanying IFRS Accounting Standards instead of publishing them as educational materials or including them in the Standards. Paragraphs BC43–BC45 of the Basis for Conclusions further explain the IASB's rationale for this proposal.
(b) Do you agree with including the examples as illustrative examples accompanying IFRS Accounting Standards? Why or why not? If you disagree, please explain what you would suggest instead and why.
(a) Improvements in reporting
A1While we recognise the challenges of delivering guidance as sustainability reporting is expected to evolve in the near future, it is also clear that demand for clarity regarding connectivity is urgent and necessary in all jurisdictions that apply IASB's standards and are now committed to providing sustainability information to investors. Jurisdictions representing over half the global economy by GDP have now taken steps towards aligning with or adopting ISSB standards5. In other jurisdictions, such as the EU where companies are expected to apply ESRS, recent activity indicates that there is expected to be a high degree of interoperability with ISSB standards.
A2As highlighted in the joint National Standard Setters letter6 to the International Sustainability Standards Board (ISSB) on its Agenda Consultation, we consider that maintaining close alignment and connectivity between financial and sustainability reporting is paramount to ensure that the information produced for investors is compatible and comparable. We are encouraged that one of the objectives set out in the ED (BC21) is to illustrate the provision of connected information in general purpose financial reports and to reinforce compatibility with IFRS Sustainability Disclosure Standards.
A3We agree that providing illustrative examples should improve the current level of reporting for the effects of climate-related and other uncertainties in the financial statements. We include below some comments on certain unintended consequences and areas where we consider that the examples could be further improved.
A4We have identified some instances within the ED where the IASB may wish to consider other standard setting solutions as the guidance provided may be going beyond existing interpretations of those requirements.
- We support the clarification provided in example four7 regarding IAS 1 paragraph 125 but are concerned that the illustration may now place too much reliance on this paragraph. If IASB research (BC36) has indicated that there is evidence that disclosure of uncertainties beyond the 1-year limit is not meeting user needs, then we suggest that the IASB consider if any amendments to the standard are required.
- Examples one8 and five9 appear to illustrate instances where materiality judgements based on IAS 1 paragraph 31 lead to additional disclosures. However, this may also place too much reliance on a requirement that was intended to apply when compliance with other IFRS may be insufficient to enable users to understand the impact of particular transactions, other events and conditions. We understand that in current practice this requirement is used in relatively rare situations.
- We also note that examples one and two10 suggests that the 'lack of effect' is also required for disclosure which appears to be inconsistent with the original intention of IAS 1 paragraph 31. It may be unclear to stakeholders the extent to which disclosing items which do not have a material effect on entity's financial statements provide useful information. The IASB may wish to consider whether using paragraph 112(c) of IAS 1 would be more appropriate as it relates to '...information that is not presented elsewhere in the financial statements but is relevant to an understanding of any of them.' Alternatively, the IASB may need to review this paragraph for a potential amendment if it is not achieving its intended purpose.
A5We are concerned about potential unintended consequences if the climate focused examples are used as analogies for all 'other' uncertainties. The IASB may wish to provide more context to help frame primary users' expectations that these examples relate to all sustainability-related risks. Alternatively, additional fact patterns or examples that cover a wider variety of uncertainties, such as risks arising from nature, human capital, or artificial intelligence, may provide the range of examples that could be analogised in future as other sustainability risks are identified.
A6We note that the examples do not illustrate circumstances when there is an impact on the financial statements. Users have advised us that this is a key area where they perceive a disconnect across general purpose financial reports. The IASB may wish to consider providing an example where a climate-related or other uncertainty did result in an impact on the financial statements.
A7The UKEB research into connectivity11 highlighted stakeholder feedback that they are seeking clarity on how the IFRS Foundation's two sets of standards are intended to work in practice. We consider that the IASB could deliver this by incorporating in some of the examples references to, or illustrative connections with, IFRS Sustainability Disclosure Standards. As examples one and two are specifically intended to reinforce compatibility with IFRS Sustainability Disclosure Standards, the IASB may wish to consider reflecting in the fact pattern where the entity has applied the requirements of IFRS S1 paragraph 3512. This approach may provide a more direct connection across the general-purpose financial reports and provide a clearer context for the relevant financial statement disclosures. The UKEB would be pleased to support a joint IASB and ISSB project team to develop connectivity illustrative examples through our advisory and sustainability working groups.
(b) Illustrative examples accompanying IFRS Accounting Standards
A8In general, we agree that the IASB's proposal to include the examples as accompanying illustrative material to the relevant accounting standards should provide stakeholders accessible and relevant guidance when using those standards. We note however, that there are some areas where other standard setting solutions may be required (see paragraph A4 above).
A9Whilst the examples are not mandatory, and so do not add or change any IFRS accounting requirements, we anticipate that they will be useful to stakeholders when they are considering accounting for relevant business transactions. We are aware that IASB guidance is often referred to by auditors when engaging with entities on their application of the standards.
A10We note in BC45 of the ED that, in addition to including the examples in the relevant accounting standards, the IASB may also group the examples and publish them as a single document. We consider that this would be useful as, without this, some stakeholders may struggle to understand the connections, for example to the context of materiality to the individual examples when included in different standards.
Question 2 – Approach to developing illustrative examples
Examples 1–8 in this Exposure Draft illustrate how an entity applies specific requirements in IFRS Accounting Standards. The IASB decided to focus the examples on requirements:
(a) that are among the most relevant for reporting the effects of climate-related and other uncertainties in the financial statements; and
(b) that are likely to address the concerns that information about the effects of climate-related risks in the financial statements is insufficient or appears to be inconsistent with information provided in general purpose financial reports outside the financial statements.
Paragraphs BC10–BC42 of the Basis for Conclusions further explain the IASB's overall considerations in developing the examples and the objective and rationale for each example.
Do you agree with the IASB's approach to developing the examples? In particular, do you agree with the selection of requirements and fact patterns illustrated in the examples and the technical content of the examples?
Please explain why or why not. If you disagree, please explain what you would suggest instead and why.
A11We are generally supportive of the IASB's approach to developing the examples and in particular that the examples should illustrate how an entity applies the requirements in IFRS Accounting Standards (BC14). We also agree with the approach of focusing the examples on the requirements that are among the most relevant for reporting the effects of climate related and other uncertainties in financial statements.
A12We do however have some comments on the fact patterns and technical content of the examples. Our comments are aimed at helping enhance the relevance of the illustrations and to support connectivity. These are included in the paragraphs that follow.
A13We support the use of standalone examples but also consider walk-through examples would be beneficial. We appreciate that walk-through examples are significantly more complex to develop and would take longer to build a consensus. The IASB may wish to consider developing more in-depth examples, as the next phase of work with the ISSB.
A14In relation to materiality judgements and the disclosure of additional information, we are concerned that examples one and two only reference the qualitative aspect of materiality. We suggest the IASB consider emphasising in each example that there is a single definition of materiality, and concluding on it requires consideration of both quantitative and qualitative aspects.
A15In relation to assumptions and other sources of estimation uncertainty, stakeholders have advised in relation to IAS 36 Impairment of Assets that there are current challenges in practice with connectivity between climate-related scenarios and impairment assumptions, the effects on expected cash flows (beyond a five-year period) and how those may affect asset terminal values. The IASB may wish to consider if some of these aspects could be reflected in example three13 or potentially included in a future joint illustrative example with the ISSB.
A16We suggest that example four could be improved by providing the rationale for the entity performing impairment testing at a CGU level. The IASB may wish to consider aligning the fact pattern more closely to the requirements of IAS 36 paragraph 67 (a) and (b). In addition, we recommend that any impact on the useful economic lives of the non-current assets should also be considered in the fact pattern.
A17We suggest that including direct references to IFRS 7 paragraph 33 (qualitative disclosures) and paragraph 34 (quantitative disclosures) and illustrating their application would help clarify the approach in example six14.
A18In relation to example seven15, stakeholders have advised us that the most relevant challenges in practice relate to cases when assets may need to be replaced or repurposed due to climate-related risks and the potential implications for impairment, reduction in useful economic life and consequential acceleration of depreciation and potential decommissioning provisions. The IASB may wish to consider if some of these aspects could be reflected in example seven or potentially included in a future joint illustrative example with the ISSB.
A19In relation to example eight16, we understand that in practice it is rare for an entity to determine their classes of PP&E based on the level of greenhouse gas emitted as carbon intensity is rarely binary. In addition, as entities tend to approach the transition to net zero by changing assets on a piecemeal basis the illustration may be difficult to apply in practice.
A20It appears that the illustration used in example eight may be directly relevant to certain entities, such as an energy generating entity which could potentially disaggregate assets into specific categories such as wind, nuclear, coal, etc. However, the illustration may not be practical for service industries and therefore the example may not be widely applicable. The IASB may need to consider if this will create an expectation gap between users and preparers.
A21As IFRS 18 is not yet effective there is the risk that the guidance in example eight may cause confusion regarding whether entities should develop practice based on the requirements of IFRS 18 or IAS 1. In addition, the IASB may wish to consider including an explanation for how the aggregation and disaggregation principles in IFRS 18 interact with the guidance in paragraph 37 of IAS 16 Property, Plant and Equipment (IAS 16). This would be helpful in terms of how the characteristics of 'nature' and 'use' connect with the disclosures required in paragraph 73 of IAS 16.
A22We also consider that it would be helpful to clarify in example eight how materiality was assessed and how the disaggregation resulted in material information. For example, if an entity with a diverse fixed asset base used an income statement-based materiality to disaggregate their assets with differing climate-related risk characteristics, this may result in very granular disclosures which may not produce useful information.
Question 3 – Other comments
Do you have any other comments on the Exposure Draft?
A23We consider that stakeholders will find it helpful if the IASB could communicate its longer-term strategy regarding connectivity and alignment with the ISSB's due process in relation to the areas outlined below.
- The evolving nature of sustainability reporting increases the risk that the illustrative examples may be quickly superseded by industry practice. It would be helpful to understand if the IASB will establish and communicate an overall strategy which could include the process by which these examples will be updated or further developed to ensure they remain relevant.
- The risk of duplicated reporting is identified (BC25) but assumed to be mitigated as IFRS Sustainability Disclosure Standards allow cross referencing to other reports published by the entity, for example, the entity's financial statements. However, as there is no equivalent requirement in accounting standards this is not a two-way connection. We suggest that as part of a wider connectivity strategy, IASB may wish to consider a potential requirement to link, where feasible and appropriate, to the relevant ISSB disclosures from the financial statements.
- Our research into connectivity indicates that stakeholders are seeking application guidance for when material sustainability disclosures may become material for financial statements disclosures. As IFRS Practice Statement 2 Making Materiality Judgements was created before the inception of the ISSB and development of sustainability standards, the IASB should consider reviewing whether more authoritative guidance or a different standard setting solution is now required.
A24In the UK, existing requirements under the Companies Act 2006 for sustainability reporting and from the Financial Conduct Authority (FCA) regarding TCFD disclosures significantly overlap with the requirements included in IFRSs S1 and S2. UK companies in scope of both the Companies Act and the FCA rules already produce sustainability and TCFD disclosures in their annual reports. As a result, UK-based investors and other stakeholders are keenly aware of the potential for lack of connectivity between financial and sustainability reporting and disclosure. We consider that existing UK practice may help the IASB understand the current and potential future sources of lack of connectivity arising from the ISSB's future development of other standards. We would be happy to assist the IASB in sourcing such future examples.
Appendix B: Invitation to Comment
Call for comments on the UKEB Draft Comment Letter on IASB's Exposure Draft Climate-related and Other Uncertainties in the Financial Statements - Proposed illustrative examples
Deadline for completion of this Invitation to Comment:
Midday on [8 November 2024]
Please submit to: [email protected]
Introduction
The objective of this Invitation to Comment is to obtain input from stakeholders on the UKEB Draft Comment Letter (DCL) on the Exposure Draft (ED) Climate-related and Other Uncertainties in the Financial Statements – Proposed illustrative examples, published by the International Accounting Standards Board (IASB) on 31 July 2024.
UK endorsement and adoption process
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments, and interpretations. This letter is intended to contribute to the IASB's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
Who should respond to this Invitation to Comment?
Stakeholders with an interest in the quality of accounts prepared in accordance with international accounting standards.
How to respond to this Invitation to Comment
Please download this document, answer any questions on which you would like to provide views, and return it together with the 'Your Details' form to [email protected] by midday on [8 November 2024].
Brief responses providing views on individual questions are welcome, as well as comprehensive responses.
Privacy and other policies
The data collected through responses to this document will be stored and processed by the UKEB. By submitting this document, you consent to the UKEB processing your data for the purposes of influencing the development of and adopting IFRS for use in the UK. For further information, please see our Privacy Statements and Notices and other Policies (e.g. Consultation Responses Policy and Data Protection Policy)17.
The UKEB's policy is to publish on its website all responses to formal consultations issued by the UKEB unless the respondent explicitly requests otherwise. A standard confidentiality statement in an e-mail message will not be regarded as a request for non-disclosure. If you do not wish your signature to be published, please provide the UKEB with an unsigned version of your submission. The UKEB prefers to publish responses that do not include a personal signature. Other than the name of the organisation/individual responding, information contained in the “Your Details” document will not be published. The UKEB does not edit personal information (such as telephone numbers, postal or e-mail addresses) from any other response document submitted; therefore, only information that you wish to be published should be submitted in such responses.
Questions
1. The UKEB's draft letter suggests that the IASB may wish to consider other standard setting solutions as the examples may be placing too much reliance on paragraphs 31 and 125 of IAS 1 Presentation of Financial Statements. Do you agree with this position? Please explain why or why not.
2. The UKEB suggests that the IASB elaborate on its longer-term strategy regarding connectivity and alignment with the ISSB's future standards as part of its upcoming Agenda Consultation. Do you agree with this position? Please explain why or why not.
3. The UKEB's draft comment letter (DCL) agrees that providing illustrative examples should help improve the reporting of the effects of climate-related and other uncertainties in the financial statements, and is generally supportive of the approach taken by the IASB to developing the examples. Do you agree with this position? Please explain why or why not.
4. Do you have any comment on potential costs and benefits in relation to the illustrative examples.
5. Do you have any other comments on the Exposure Draft or the DCL you would like to share?
Thank you for completing this Invitation to Comment
Please submit this document by Midday on [8 November 2024] to [email protected]
Footnotes
-
UKEB April 2024 Board meeting, IASB General Update - Appendix D: Climate-related matters ↩
-
UKEB calculation based on LSEG and Eikon data, May 2023. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩
-
UKEB estimate based on FAME (company information in the UK and Ireland produced by the Bureau Van Dijk, a Moody's analytics company), Company Watch financial analytics and other proprietary data. ↩
-
A Study in Connectivity: Analysis of 2022 UK Company Annual Reports (UKEB 2023) ↩
-
Jurisdictions representing over half the global economy by GDP take steps towards ISSB Standards (IFRS Foundation 2024) ↩
-
National Standard Setters Sustainability Forum Joint Letter paragraphs 4 – 9 (UKEB 2023). ↩
-
Disclosure of assumptions: general requirements (IAS 1/IAS 8) ↩
-
Materiality judgements leading to additional disclosures (IAS 1/IFRS 18) ↩
-
Disclosure of assumptions: additional disclosures (IAS 1/IFRS 18) ↩
-
Materiality judgements not leading to additional disclosures (IAS 1/IFRS 18) ↩
-
A Study in Connectivity: Analysis of 2022 UK Company Annual Reports (UKEB 2023) ↩
-
IFRS S1 paragraph 35 requires the disclosure of how sustainability-related risks and opportunities have affected an entity's financial position, financial performance, and cash flows. ↩
-
Disclosure of assumptions: specific requirements (IAS 36) ↩
-
Disclosure about credit risk (IFRS 7) ↩
-
Disclosure about decommissioning and restoration provisions (IAS 37) ↩
-
Disclosure of disaggregated information (IFRS 18) ↩
-
These policies can be accessed from the footer in the UKEB website here: https://www.endorsement-board.uk ↩