4 Amendments to the Classification and Measurement of Financial Instruments
19 September 2024 Agenda Paper 4 UKEB UK Endorsement Board
Executive Summary
| Project Type |
|---|
| Endorsement and adoption |
| Project Scope |
|---|
| Moderate |
Purpose of the paper
The purpose of this paper is to:
- Obtain Board feedback on the Draft Endorsement Criteria Assessment (DECA), and related Invitation to Comment (ITC) for the Amendments to IFRS 9 and IFRS 7—Amendments to the Classification and Measurement of Financial Instruments (Amendments).
- Request the Board’s approval to publish the DECA and ITC on the UKEB website for stakeholder consultation for a 90 day comment period.
Summary of the Issue
The Amendments contain further guidance for the IFRS 9 Financial Instruments requirements for recognition and derecognition, and for the classification and measurement of financial instruments. This includes classification guidance for instruments containing contingent features, such as ESG-linked1 instruments. The Amendments also contain targeted changes to disclosure requirements in IFRS 7 Financial Instruments: Disclosures and consequential amendments to IFRS 19 Subsidiaries without Public Accountability.
The purpose of the DECA is to assess whether the Amendments meet the statutory criteria for adoption set out in SI 2019/6852. The DECA includes:
- a description of the UK statutory requirements for adoption of new and amended international accounting standards.
- a description of the Amendments; and
- an assessment of whether the Amendments meet the statutory criteria for adoption.
The Amendments have an effective date of annual reporting periods commencing on or after 1 January 2026. Earlier application is permitted. Additionally, the Amendments permit early application of only the requirements for the classification of financial assets (and associated disclosures), without applying the other Amendments to the standard at the same time.
Decisions for the Board
- Does the Board have any comments on the DECA (Appendix A) or the Invitation to Comment (ITC) (Appendix B)?
- Does the Board agree that, subject to any amendments or additions required by the Board, the DECA and ITC can be published for public consultation?
Recommendation
Subject to any amendments or additions required by the Board, the Secretariat recommends that the Board approves the DECA and ITC for public consultation.
Appendices
Appendix A [Draft] Endorsement Criteria Assessment of Amendments to IFRS 9 and IFRS 7 - Amendments to the Classification and Measurement of Financial Instruments. Appendix B DECA – Invitation to comment.
Background
1In May 2024, the IASB published its final Amendments to IFRS 9 and IFRS 7—Amendments to the Classification and Measurement of Financial Instruments (Amendments).
2The Amendments contain further guidance for the IFRS 9 Financial Instruments requirements for recognition and derecognition, and for the classification and measurement of financial instruments. This includes classification guidance for instruments containing contingent features, such as ESG-linked instruments. The Amendments also contain targeted changes to disclosure requirements in IFRS 7 Financial Instruments: Disclosures.
3The Amendments aim to reduce diversity in practice, and provide users of financial statements with additional information, including new disclosures that will help them understand the potential effect on cashflows of financial instruments with contingent features.
4The Amendments are effective for annual periods commencing on or after 1 January 2026. Early application is permitted. Additionally, the Amendments permit early application of only the requirements for the classification of financial assets (and associated disclosures), without applying the other Amendments to the standard at the same time.
DECA
5The DECA, setting out the proposed draft assessment of the Amendments against the statutory criteria is set out at Appendix A to this paper. An Invitation to Comment (ITC) is included at Appendix B.
Stakeholder outreach
6Feedback from stakeholder outreach to June 2024 was summarised in the Project Initiation Plan3. Subsequent outreach noted the following:
- Outreach in July 2024 with the Financial Instruments Working Group (FIWG) discussed the potential costs and benefits of the Amendments. This information has been used to inform analysis in the DECA.
- Outreach in July 2024 with the Accounting Firms and Institutes Advisory Group (AFIAG) noted no significant concerns with the Amendments. Members of the AFIAG did not expect the Amendments to give rise to significant extra cost. No objections to the implementation date of January 2026 were noted – the fact there is no requirement to restate comparative information was considered helpful in this regard.
Consequential amendments to IFRS 19
7Although not referenced in the title, the Amendments also include consequential amendments to another recently issued IASB standard, IFRS 19 Subsidiaries without Public Accountability: Disclosures. The effective date for IFRS 19 is annual periods commencing on or after 1 January 2027.
8The UKEB has not yet commenced endorsement work on IFRS 19. An endorsement decision on that standard is not expected in time for the effective date of these Amendments. The Secretariat’s analysis of this issue is as follows:
- The consequential amendments to IFRS 19 are being separately consulted on as part of the current IASB ED: Amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures. There is still a possibility that there may be further changes subsequent to the consultation closing.
- The endorsement of these Amendments in their entirety, including the consequential amendments to IFRS 19, would mean endorsing an amendment to a standard which is not yet an UK-adopted international accounting standard.
9Therefore, the recommendation is that the consequential amendments to IFRS 19, contained within the Amendments, are not considered for adoption as part of the endorsement assessment of these Amendments. Instead, we recommend they be considered for adoption as part of the IFRS 19 endorsement assessment.
10This approach is set out in paragraphs 7-8 of the DECA.
Questions for the Board
- Does the Board have any comments on the DECA (Appendix A) or the Invitation to Comment (ITC) (Appendix B)?
- Does the Board agree that, subject to any amendments or additions required by the Board, the DECA and ITC can be published for public consultation?
Next Steps and timeline
11In accordance with the Project Initiation Plan (PIP), the Board’s aim would be to reach a decision as to whether or not to adopt the Amendments prior to June 2025 interim reporting commencing. If adopted, this timing would allow for early application of the Amendments by entities with December year ends.
12Subject to amendments or additions to the DECA required by the Board, the proposed timeline is set out below. The Board will be alerted if there are any significant changes.
| Date | Milestones |
|---|---|
| 19 September 2024 | DECA for Board approval. |
| Estimated DECA consultation period (90 days): late September 2024 – early January* 2025 | |
| 27 February 2025 | Board review of feedback received on the DECA. |
| 28 March 2025 | Consideration of the Adoption Package. |
| Board members provide a tentative vote. | |
| April 2025 | Voting form sent to Board members. |
| Publication of voting outcome and Adoption Package on the UKEB website. | |
| 22 May 2025 | Due Process Compliance Statement for noting. |
* A 90-day comment period would lead to a comment deadline in late December 2024, over the winter holiday period for most stakeholders. Therefore, to allow stakeholders maximum opportunity to respond to the DECA, the consultation will close on 6 January 2025.
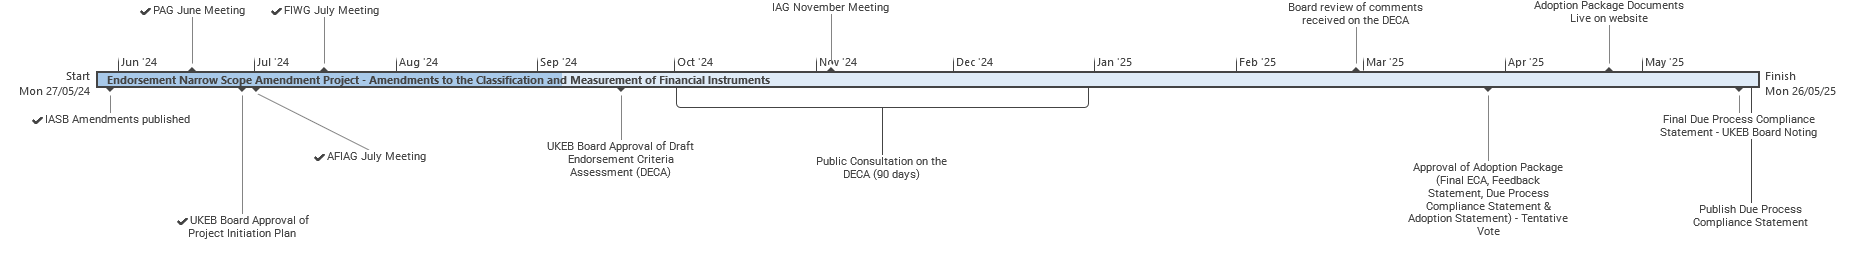
* Early application is permitted. It is also permitted to apply early only the Amendments to the requirements for the classification of financial assets (and associated disclosures) without applying the other Amendments to the standard.
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from any omission from it.
© 2024 All Rights Reserved
- Executive Summary
- Appendices
- Background
- DECA
- Stakeholder outreach
- Consequential amendments to IFRS 19
- Questions for the Board
- Next Steps and timeline
- Introduction
- Section 1: UK statutory requirements for adoption
- 2. Section 2: Description and assessment of the Amendments
- Title and issue date of final amendments
- Origin
- Effective date and transition
- Consequential amendments
- Assessment of the UK statutory requirements for adoption
- Technical accounting criteria assessment conclusion
- True and fair view assessment
- UK long term public good assessment
- Long term public good assessment conclusion
- Do the Amendments lead to a significant change in accounting practice?
- Appendix A: Glossary
- Appendix B: Invitation to Comment
- Questions
Introduction
Purpose
1The purpose of this Draft Endorsement Criteria Assessment (DECA) is to determine whether the Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments (the Amendments) issued by the International Accounting Standards Board (IASB) in May 2024 meet the UK's statutory requirements for adoption as set out in Regulation 7 of Statutory Instrument 2019/6854 (SI 2019/685).
2The Amendments have an effective date of 1 January 2026 with earlier application permitted.
3The UKEB actively influenced the development of the Amendments. This included submitting a Final Comment Letter on 19 July 20235 in response to the IASB's Exposure Draft Amendments to the Classification and Measurement of Financial Instruments – Proposed amendments to IFRS 9 and IFRS 76.
Background to the Amendments
4Section 2 in this DECA provides a brief description of the Amendments.
Scope of the adoption assessment
5The Amendments make changes to the mandatory parts of IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures. These changes to the mandatory parts of the standard form part of the UKEB's adoption assessment.
6As UK-adopted international accounting standards comprise only the mandatory7 sections of standards. The amendments to the Implementation Guidance of IFRS 7, the Dissenting Opinion to the IFRS 9 amendments, and the Basis for conclusions of IFRS 9 and IFRS 7 are not adopted by the Board and are not considered in this DECA.
7IFRS 19 Subsidiaries without Public Accountability: Disclosures will be considered for adoption at a future date. The amendments to IFRS 19, which are part of the Amendments, will be considered when the UKEB considers the adoption of IFRS 19. Accordingly, the amendments to IFRS 19, which are included in the Amendments, have not been considered for adoption by the UKEB as part of its considerations of the Amendments.
8If IFRS 19, as amended (including the amendments to IFRS 19 within the Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments), is endorsed for use in the UK the effective date for those disclosures will be set out in the relevant adoption statement.
Structure of the assessment
9The UKEB's analysis is presented in the following sections:
- Section 1: describes UK statutory requirements for adoption of new or amended international accounting standards; and
- Section 2: discusses how the Amendments meet the criteria in Section 1.
Do the Amendments lead to a significant change in accounting practice?
10A standard adopted by the UKEB under Regulation 6 of SI 2019/685 that it considers is likely to lead to a 'significant change in accounting practice', is subject to the requirements in paragraph 3 of Regulation 11 of SI 2019/685 that the UKEB:
- carry out a review of the impact of the adoption of the standard; and
- publish a report setting out the conclusions of the review no later than 5 years after the date on which the standard takes effect (being the first day of the first financial year in respect of which it must be used)".
11Section 2 of the DECA discusses whether the Amendments lead to a significant change in accounting practice.
Section 1: UK statutory requirements for adoption
UK statutory requirements
1.1Paragraph 1 of Regulation 7 of SI 2019/685 requires that an international accounting standard only be adopted if:
- the standard8 is not contrary to either of the following principles-
- an undertaking’s accounts must give a true and fair view of the undertaking’s assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking;
- the use of the standard is likely to be conducive to the long term public good in the United Kingdom; and
- the standard meets the criteria of understandability, relevance, reliability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management."
1.2This DECA assesses the criteria above in the following order:
- Whether the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management (Regulation 7(1)(c)).
- Whether the Amendments are not contrary to the principle that an entity's accounts must give a true and fair view (Regulation 7(1)(a)).
- Whether use of the Amendments is likely to be conducive to the long term public good in the UK (Regulation 7(1)(b)). Regulation 7(2) of SI 2019/685 includes specific areas to consider for this assessment. They are:
- whether the Amendments are likely to improve the quality of financial reporting;
- the costs and benefits that are likely to result from the use of the Amendments; and
- whether the Amendments are likely to have an adverse effect on the economy of the UK, including on economic growth.
Relevance, Reliability, Understandability and Comparability
1.3Information is relevant if it is capable of making a difference in the decision-making of users9 or in their assessment of the stewardship of management. The information may aid predictions of the future, confirm or change evaluations of the past, or both.
1.4Financial information is reliable if, within the bounds of materiality, it:
- can be depended on by users to represent faithfully what it either purports to represent or could reasonably be expected to represent;
- is complete; and
- is free from material error and bias.
1.5Financial information should be readily understandable by users with a reasonable knowledge of business and economic activities and accounting, and a willingness to study the information with reasonable diligence.
1.6Information is comparable if it enables users to identify and understand similarities in, and differences among, items. Information about an entity should be comparable with similar information about other entities and with similar information about the same entity for another period.
1.7In conducting the overall assessment against the technical accounting criteria, the UKEB is required to adopt an absolute, rather than a relative, approach. This means that this assessment is an absolute one against the criteria (do the Amendments provide information that is understandable, relevant, reliable and comparable?) rather than a relative one (do the Amendments provide information that is more understandable, relevant, reliable and comparable than current, or any other, accounting?). When an assessment of any individual aspect or requirement of the Amendments uses comparative language (e.g. 'enhances comparability'), this does not mean that the objective is to reflect a real comparison in relative terms. Instead, the objective is to explain that any individual aspect or requirement of the Amendments has the potential to “enhance” one or more of the qualitative characteristics. Consideration of whether the Amendments are likely to improve the quality of financial reporting is separate from this assessment and is included within the UK long term public good assessment in Section 2.
True and fair view assessment
1.8As noted above, the first adoption criterion set out in Regulation 7(1) of SI 2019/685 requires that an international accounting standard can be adopted only if:
"[....] the standard is not contrary to either of the following principles-
- an undertaking's accounts must give a true and fair view of the undertaking's assets, liabilities, financial position and profit or loss;
- consolidated accounts must give a true and fair view of the assets, liabilities, financial position and profit or loss of the undertakings included in the accounts taken as a whole, so far as concerns members of the undertaking; [....]”
1.9For the sake of brevity, the UKEB refers to the assessment against this endorsement criterion as 'the true and fair view assessment' and to the principles set out in Regulation 7(1)(a) as the ‘true and fair principle'. However, these abbreviated expressions do not imply that the assessment has considered anything other than the full terms of the endorsement criterion set out above.
1.10The duty of the UKEB under Regulation 7(1)(a) is to determine generically, before a standard is applied to a set of accounts, whether that standard is 'not contrary' to the true and fair principle. In other words, it is an ex-ante assessment. The UKEB has therefore considered whether the Amendments contain any requirement that would prevent accounts prepared using the Amendments from giving a true and fair view.
1.11The approach is to determine whether the Amendments are not contrary to the true and fair principle in respect of any of the specific items identified in Regulation 7(1)(a) (namely, the assets, liabilities, financial position and profit or loss) in the context of the preparation of the accounts as a whole. A holistic approach has been taken to this assessment, considering the impact of the Amendments taken as a whole, including their interaction with other UK-adopted international accounting standards.
1.12For the purposes of the assessment, the UKEB considers the requirement in IAS 1 Presentation of Financial Statements for financial statements to 'present fairly the financial position, financial performance and cash flows of an entity'11 to be equivalent to the Companies Act 2006 requirement for accounts to give a true and fair view.
1.13This assessment is separate from the duty of directors under section 393(1) of the Companies Act 2006, which requires directors to be satisfied that a specific set of accounts gives a true and fair view of an undertaking's or group's assets, liabilities, financial position and profit or loss.
[Draft] Adoption decision
1.14Section 2 of this DECA discusses how the Amendments meet the statutory endorsement criteria set out in this Section 1.
1.15On the basis of these assessments, and subject to any stakeholder feedback, the UKEB [tentatively] concludes that the Amendments meet the statutory endorsement criteria. The UKEB is therefore of the view that it will adopt the Amendments for use in the UK.
2. Section 2: Description and assessment of the Amendments
Title and issue date of final amendments
2.1Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments, issued on 30 May 2024.
Origin
2.2The Amendments are a response to feedback received by the IASB in relation to:
- The potential effect on financial liabilities of a Tentative Agenda Decision made by the IFRS Interpretations Committee regarding the treatment of cash received by electronic transfer as settlement for a financial asset.
- Certain matters arising from the Post implementation Review of IFRS 9 – Classification and Measurement (PIR) including:
- Application of the requirements for assessing contractual cash flow characteristics to financial assets with environmental, social and governance (ESG) linked features.
- Clarification of the application of the contractual cash flow assessment to contractually linked instruments.
- Disclosure of fair value changes for equity instruments presented at fair value in other comprehensive income.
2.3Proposed amendments to address these matters were provided in the Exposure Draft Amendments to the Classification and Measurement of Financial Instruments -Proposed amendments to IFRS 9 and IFRS 7 (the ED). The IASB made changes to the ED proposals in response to stakeholder feedback prior to issuing the final Amendments.
Effective date and transition
2.4The Amendments are effective for annual reporting periods commencing on or after 1 January 2026. Early application is permitted. It is also permitted to apply early only the Amendments to the requirements for the classification of financial assets (and associated disclosures) without applying the other Amendments to the standard.
2.5The Amendments to IFRS 9 are to be applied retrospectively. Entities are not required to restate prior periods to reflect the application of the Amendments.
Consequential amendments
2.6Other than the matters related to IFRS 19, that are discussed in paragraphs 7-8, the amendments to not give rise to consequential amendments to other standards.
Assessment of the UK statutory requirements for adoption
Technical accounting criteria assessment
2.7For clarity of analysis, the technical accounting criteria assessment of the Amendments will be considered in three sections as follows:
- IFRS 9 - Recognition and derecognition.
- IFRS 9 - Classification of financial assets.
- IFRS 7 - Disclosures.
2.8For the purposes of this analysis the terms relevance, reliability, understandability and comparability are as described in paragraphs 1.3 - 1.6 of this document.
A. Amendments to IFRS 9 – Recognition and derecognition
What has changed?
The new paragraph B3.1.2A provides clarification of the date of initial recognition or derecognition of financial assets and financial liabilities.
Financial assets
The recognition and derecognition criteria for financial assets in paragraph B3.1.2A are consistent with the existing requirements of IFRS 9 paragraphs 3.1.1and 3.2.3. The new paragraph therefore introduces no change for financial assets, so this aspect of the Amendments is not considered further in the following analysis.
Financial liabilities
Recognition
Paragraph B3.1.2A states that the entity shall recognise a financial liability on the date on which the entity becomes party to the contractual provisions of the instrument. This is consistent with the existing requirement at IFRS 9 paragraph 3.1.1. The new paragraph therefore introduces no change in respect of the recognition of financial liabilities, so this aspect of the Amendments is not considered further in the following analysis.
Derecognition
Paragraph B3.1.2A provides clarification that the point of derecognition for financial liabilities is the settlement date. It explains that the settlement date is the date on which the liability "is extinguished because the obligation specified in the contract is discharged or cancelled or expires", or in some other way qualifies for derecognition. This explanation is consistent with the existing requirement in IFRS 9 paragraphs 3.3.1 and 3.3.2, therefore the introduction of the term settlement date acts as a clarification of existing requirements, rather than creating new requirements.
The new paragraphs B3.3.8 – B3.3.10 describe a new alternative to the use of settlement date for the derecognition of financial liabilities settled in cash using an electronic payment system. In such cases the liability may be deemed to be discharged, and hence derecognised, if it meets certain criteria including:
- the entity issued a payment instruction which resulted in the entity having no practical ability to withdraw, stop or cancel the payment;
- there is no practical ability to access the cash to be used for payment; and
- the settlement risk of the payment system is insignificant.
If the alternative is used, it shall be applied to all payments made using that payment system.
Technical criteria assessment
Relevance and reliability
The clarification that settlement date should be used for the derecognition of financial liabilities is relevant to decisions made by users, as it provides information to allow users to understand the outstanding liabilities and the cash position of the entity.
Derecognising the liability only when it is extinguished creates reliable information as it provides a faithful representation of the underlying economics of the transaction.
The new alternative permits derecognition of liabilities at a different time to the settlement date, for payments made using an electronic payment system that meet certain criteria. However, in practical terms, this also provides a faithful representation of the underlying electronic transaction. This treatment acknowledges that electronic payments are typically quicker and have different characteristics than traditional pay payment methods. For example, when using a payment system with low settlement risk, once the payment instruction is sent and the funds can longer be accessed nor the payment cancelled, the liability can in effect be viewed as discharged. The qualifying criteria in paragraph 3.3.8 act to ensure that derecognition does not take place while the payment is still uncertain. Accordingly, the alternative to derecognition on the settlement date can also be considered to provide relevant information, in the case of qualifying electronic payments.
Understandability
Continuing to recognise a financial liability until such time as it is extinguished by being paid, cancelled or it expires aligns with when a user would expect a liability to be extinguished. Hence the clarification that this criterion be used for derecognition helps ensure the presentation of information that is understandable for users.
While the criteria for application of the alternative to settlement date for derecognition of liabilities may appear complex, the resulting information is simpler to understand. The criteria ensure that derecognition does not take place while the payment of the liability is still uncertain. Continuing to recognise the liability until the cash for the instructed payment can no longer be accessed, the payment cannot be cancelled, and the electronic system has low settlement risk aligns with a “common sense” approach of when users would expect a liability to be considered as extinguished. Hence, this is expected to facilitate information which is understandable to users.
Comparability
The clarification highlights that derecognition should take place at settlement date. This clarity will reduce diversity in practice, resulting in greater consistency in financial reporting, and improve its comparability.
However, the Amendments have also introduced an alternative method, with a different point of derecognition when using electronic cash payments which meet certain criteria. This means certain entities could derecognise the liability at different times, depending on whether or not the alternative method is used. Practices could also vary within entities, if some payment systems used qualify for the alternative method while others do not.
The introduction of the alternative might create a risk to consistency, and therefore comparability. However:
- The qualifying criteria to use the alternative create clear and consistent limitations as to the circumstances in which the alternative can be used. This means that if a payment system fails to meet the criteria for one entity, it should fail for all entities, mitigating risks of inconsistency.
- It is possible that standard practice will emerge where, for payment systems that meet the criteria, the alternative method is routinely used. Paragraph B3.3.10, which requires that if the alternative method is used it shall be applied to all payments made using that payment system, supports such behaviour. This could result in entities that use a particular payment system having a consistent approach to settlement date, mitigating risks to consistency and comparability.
- As these requirements affect the accounts only for transactions which take place a few days prior to reporting period end, any inconsistency arising from use of the alternative may, in many cases, be immaterial.
- The alternative applies to financial liabilities but not to financial assets. A liability settled via electronic payment may be derecognised prior to the cash being received and accounted for by the payee. Given the volume and variety of payments routinely made by entities, it is not possible for users of accounts to monitor a liability being derecognised by one entity and the cash being received by another. Hence, as financial accounts present aggregated information, the use of the alternative is not expected to have a practical impact on the comparability of financial information for users of accounts in this regard.
- This difference in timing between financial assets and financial liabilities may impact intra-group transactions. However, such groups typically have access to the necessary information on when the cash was both paid and received, to ensure the individual entity and group accounts accurately reflect the underlying transaction and that practical challenges on consolidation can be overcome.
Transition requirements
The restatement of comparative information is not required by the Amendments. This can potentially impair comparability in the transition year, as the historic transactions may be recorded on a different basis to the current year transactions, disrupting trend analysis on that entity. However, given the transactions potentially affected by the Amendments are those balances paid shortly before reporting period end and expected to settle within a few days of the initial application date, this is likely to have only a minor effect on the presentation of the statement of cash flows in the first reporting period following application of the amendments. Further, comparative information will be provided from the second year of implementation.
B. Amendments to IFRS 9 - Classification of financial assets.
What has changed?
In summary, the Amendments:
- Add paragraph B4.1.8A to clarify that the assessment of the elements of interest focuses on what an entity is being compensated for, rather than how much compensation it receives. However, it notes the amount of compensation may indicate the entity is being compensated for something other than a basic lending risk or cost, and provides examples of instruments inconsistent with basic lending.
- Amend paragraph B4.1.10 to specify that cash flows related to the contingent event must move in the same direction as the change in the basic lending risk or cost. When analysing contractual cash flows, all cash flows that could arise before or after the contingent event should be considered, irrespective of the probability of the change in contractual cash flows occurring.
- Add paragraph B4.1.10A to acknowledge that some contingent features give rise to cash flows that are consistent with basic lending arrangements both before and after the contingent event. However, if the contingent event itself does not relate directly to a change in basic lending risks or costs, then a further requirement must be met. In such cases, entities must determine if, in all contractually possible scenarios, the cash flows are not significantly different to the cash flows on an otherwise identical financial instrument without a contingent feature. This analysis may be qualitative or quantitative depending on the circumstances.
- Add paragraphs B4.1.16A and amend paragraphs B4.1.16 and B4.1.17 to more clearly define non-recourse features. This includes clarifying that the effect of other arrangements, such as subordinated debt or equity instruments issued by the debtor, should be considered in the assessment.
- Add paragraph B4.1.20A and amend paragraphs B4.1.20 and B4.1.21 to more clearly define contractually linked instruments. The Amendments also clarify that contractually linked transactions involving only a structured entity, its sponsoring entity and a creditor may not need to apply the contractually linked requirements subject to meeting certain criteria.
- Amend paragraph B4.1.23 to clarify that, for contractually linked instruments, instruments in the underlying pool can include financial instruments not within the scope of the classification requirements, if they have payments equivalent to solely payment of principal and interest (for example certain leases).
Technical criteria assessment
Relevance and reliability
The ability to appropriately classify instruments as measured at amortised cost or fair value is relevant as the resulting classification provides users with: information about the underlying nature of the transaction, the measurement approach used, and the specific disclosures most relevant to that type of instrument. In the case of the amortised cost classification this includes information on net interest income and expected credit losses, which are relevant to allowing users to assess the performance of the underlying asset portfolio.
The improved clarity provided by the Amendments is expected to reduce the risk of misclassification, resulting in more reliable information.
Understandability
As noted above, the ability to classify basic lending instruments as measured at amortised cost results in the disclosure of information that enables users to understand the performance of the instrument.
Further, the new disclosures created by the Amendments provide additional information about the nature of those instruments, which is expected to further improve understandability (this is discussed in Section C below).
Comparability
The clarification of the concepts of basic lending, solely payments of principal and interest, and other matters pertaining to classification provide a clearer path to assess whether financial instruments with contingent features should be classified as measured at amortised cost or at fair value. Where instruments have similar characteristics, this clarity facilitates consistency in classification, and therefore results in greater comparability.
Transition requirements
Retrospective application of the Amendments, as required by the transition requirements, generally enhances comparability as it enables users to compare entities' financial position across financial reporting periods and across reporting entities.
The restatement of comparative information is not required by the Amendments. This can potentially impair comparability in the transition year, as the historic data may be classified on a different basis to the current year data and disrupt trend analysis on that entity.
However, this is only relevant to the extent that classification under the existing requirements would be different to that achieved under the Amendments. We understand that the Amendments are not expected to lead to widespread reclassifications of existing instruments. Further, the Amendments require entities to disclose information about the measurement of the financial assets immediately before and after the Amendments are applied. Accordingly, we expect the transition requirements to have a largely neutral effect on comparability.
C. Amendments to IFRS 7: Disclosure.
What has changed?
Investments in equity instruments designated at fair value through other comprehensive income
The Amendments require additional disclosure of fair value information for equity investments designated at fair value through other comprehensive income (FVOCI). This includes showing separately the fair value gain or loss on instruments derecognised during the period, and those retained at period end. Transfers of cumulative gain or loss are also required to be disclosed for instruments derecognised during the reporting period.
Instruments with contingent features
The Amendments require additional disclosure to assist users understand the effect of contractual terms that could change the amount of contractual cashflows, based on the occurrence (or non-occurrence) of a contingent event which is not related to basic lending risks or costs.
The disclosures apply to financial assets and financial liabilities measured at amortised cost, and for financial assets meased at fair value through other comprehensive income.
The additional disclosures include information on the nature of the contingent event, the amount of financial assets or liabilities subject to contingent events, and quantitative information on possible changes to cash flows that could arise as a result of the contingent event.
Technical criteria assessment
Relevance and reliability
Investments in equity instruments designated at fair value through other comprehensive income
The additional disclosures for investments in equity instruments designated at FVOCI (the investments) required by the Amendments are relevant to users of accounts as the increased transparency will enhance their ability to understand the fair value of such investments, and in particular distinguish between the fair value gain or loss from investments disposed of during the period and those that are retained at the end of the reporting period. This information is relevant to users of accounts as it provides additional information to assist users consider entities' current and future investment performance.
Distinguishing between profits and losses from investments disposed of during the period versus investments retained provides a faithful representation of the underlying transaction as it distinguishes between profits or losses which have now crystalised, and profits or losses which may be subject to further change.
Instruments with contingent features
The increased transparency arising from the Amendments will enhance users' ability to assess the impact on the entity's cashflows should a contingent event occur. Further, the disclosure of information on the nature of such contingent features, and the quantum of such instruments held, may assist users of accounts in assessing whether such variability aligns to their investment (or other) objectives, and risk appetite.
Understandability
Investments in equity instruments designated at fair value through other comprehensive income
The additional disclosure required by the Amendments will permit users of accounts to distinguish between the gains and losses on the investments disposed of during the period (i.e. realised gains or losses) and unrealised gains or losses on investments retained by the entity at the end of the reporting period. This will assist them in understanding the certainty of those profits and losses, and in identifying those which may still be subject to further valuation change between the reporting date and when the investments are ultimately realised.
Instruments with contingent features
The Amendments will increase transparency and enable users of accounts to understand whether or not an entity has exposure to instruments with contingent features, and any potential resulting impact on contractual cashflows. This will increase user understanding of the types of instruments held by an entity and of the potential future impact on cashflows arising from such instruments.
As the Amendments allow entities to determine an appropriate level of aggregation, and to assess whether further information is necessary to allow users to evaluate the quantitative information presented, information can be presented in a way most helpful to provide users of accounts an understanding of that specific organisation. Discretion as to the level of aggregation can help entities avoid unnecessarily voluminous information that may obscure more useful information for users.
Comparability
Investments in equity instruments designated at fair value through other comprehensive income
The Amendments provide users of accounts with greater granularity of the profits or losses reported for the investments. This provides the opportunity for more detailed comparisons to be made between entities, or within an entity over time.
Instruments with contingent features
The Amendments enhance comparability by requiring entities with assets or liabilities with contingent features to provide information on the quantum of such instruments, and the potential financial impact from changes arising due to these contractual terms. This will allow users of accounts to compare the potential impact of such contractual terms across multiple entities, and from one reporting period to another. Without this new disclosure it is difficult for such comparisons to be made.
Transition requirements
Retrospective application of the Amendments' transition requirements is expected to aid consistency and comparability as the new disclosures apply to all relevant financial instruments held by the organisation, not just those acquired or originated subsequent to the implementation date of the Amendments.
The restatement of comparative information is not required by the Amendments. This can potentially impair comparability in the transition year, as the new disclosures will not be presented for historic information. However, this will not disrupt existing trend analysis as this is the first time the information has been published, and comparative information will be provided from the second year of implementation.
Technical accounting criteria assessment conclusion
2.9Overall, the UKEB concludes that the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management, as required by Regulation 7(1)(c) of SI 2019/685.
True and fair view assessment
2.10As discussed above, overall the Amendments meet the technical accounting criteria of relevance, reliability, understandability, and comparability of financial information. Reliability includes the notion of faithful representation of the economic substance of transactions and events. The technical accounting criteria assessment underpins the overall true and fair view assessment.
2.11The assessment has not identified any requirement of the Amendments, when considered in conjunction with international accounting standards adopted for use in the UK, that would prevent individual or group accounts prepared using the Amendments from giving a true and fair view of the undertaking's or group's assets, liabilities, financial position and profit or loss. The UKEB is satisfied, therefore, that the circumstances in which the application of the Amendments would result in accounts which did not give a true and fair view would be extremely rare.
2.12Overall, the UKEB concludes that the Amendments are not contrary to the true and fair view principle set out in Regulation 7(1)(a) of SI 2019/685.
UK long term public good assessment
UK long term public good
Description of entities that will be impacted
There are currently approximately 1,400 entities with equity listed on the London Stock Exchange (LSEG) that prepare their financial statements in accordance with UK-adopted international accounting standards. In addition, UK law allows unlisted companies the option to use UK-adopted international accounting standards and approximately 14,000 such companies currently take up this option.12
The different elements of the Amendments are each likely to affect different instruments and transactions, thus not impacting all companies in the same way.
Recognition and derecognition
The clarification in the new paragraph B3.1.2A of IFRS 9 and the provision of a new alternative to the use of settlement date for the derecognition of certain financial liabilities (new paragraphs B3.3.8-B3.3.10 in IFRS 9) will be relevant to all companies that apply UK-adopted International Accounting Standards.
Classification of financial instruments
The Amendments in paragraphs B4.1.8A, B4.1.10, B4.1.10A of IFRS 9 mainly affect companies that offer financial instruments with contingent features, such as sustainability-linked loans (SLLs). A SLL is a loan whereby an economic outcome is linked to the sustainability performance of the borrower. For example, if the borrower meets certain ESG targets tailored for that company, the interest payable on the loan will reduce.
There is evidence that, among loans with contingent features, SLLs in particular are increasingly prevalent globally.14 A review of the literature and stakeholder engagement revealed no estimates of the value of this market in the UK; however, the prevalence of SLLs seems to be growing, as noted in a letter published by the Financial Conduct Authority.15 Research on UK companies’ annual reports suggested that they are widely using SLLs. However, the disclosures often put together various types of ESG finance products (such as green lending – funding tied to specific projects – and ESG-linked bonds) making it often impossible to isolate the prevalence of SLLs.16 It was therefore not possible to estimate the exact prevalence or value of these specific contracts in the UK. However, UKEB research and stakeholder engagement suggest that the value of SLLs on UK banks’ balance sheet is in the range of tens of GBP billions.
The other amendments to IFRS 9 relating to classification of financial instruments mainly affect companies with financial instruments with non-recourse features or contractually linked instruments. In-house research and stakeholder engagement revealed that no known UK estimates of the number or value of such instruments exist, or the number of entities holding them. It was therefore not possible to estimate the exact prevalence or value of these contracts in the UK.17 However we note that the Amendments affect only the entities holding the assets, typically banks and other financial institutions.
Disclosure
The amendments to IFRS 7 will affect:
- Entities with equity instruments designated at fair value through other comprehensive income. Stakeholder engagement suggested that these are not common in the UK.
- Entities with financial assets and financial liabilities measured at amortised cost, or financial assets meased at fair value through other comprehensive income, that have contingent features, the prevalence of which is discussed above.
Do the amendments improve financial reporting?
As discussed above in the technical accounting criteria assessment, overall the Amendments are expected to enhance the relevance, reliability, comparability and understandability of financial information. Consequently, it is expected that the Amendments will improve financial reporting.
Costs for preparers and users
Given that the amendments are narrow in scope, the UKEB conducted a proportionate level of stakeholder engagement, primarily through its advisory and working groups, [and consultation on the draft assessment] to estimate the costs likely to be incurred by preparers and users of financial statements. The assessment is qualitative in nature.
Preparers’ costs
Recognition and derecognition
The costs associated with the clarification of the date of initial recognition or derecognition of financial instruments are likely to vary depending on an entity’s existing practices and how the clarification is implemented. Stakeholder feedback suggested that entities will need to undertake an exercise to assess existing practices against the clarification. This investigation would largely require the application of additional human resources to the task, so the estimated cost was considered relatively low. Depending on the findings of this review, changes to reporting may be required. This may include system changes such as how/when payment system information feeds to the ledger. Depending on the nature and extent of the findings it was considered that this may have a low to medium cost impact, but not constitute a material cost on its own.
Entities may also choose to apply the alternative in B3.3.8 if certain criteria are met. Entities wishing to use the new alternative to settlement date would be required to conduct an analysis of the contractual terms of various payment systems to determine if/at what point they meet the necessary criteria. This piece of analysis may lead to low to medium costs based on associated changes to accounting systems, though it was thought that implementation costs would not be material. Stakeholders suggested that this analysis may be undertaken centrally, for example by industry working groups, which would mitigate the cost to any individual entity and drive consistency of practice.
To the extent costs are incurred in relation to the Amendments, these are expected to be one off costs around the time of implementation, rather than ongoing costs.
Classification of financial instruments
The amendments are not expected to lead to material additional cost for preparers in relation to either instruments with contingent features or instruments with non-recourse features/contractually linked instruments.
Disclosure
- Investments in equity instruments designated at fair value through other comprehensive income – Such investments are not common in the UK. Accordingly, the additional disclosure requirements for such instruments are not expected to give rise to material change or costs in the UK.
- Financial instruments with contingent features - It is expected that entities already hold the necessary data to complete the disclosure but it may not currently reside within the finance function. This may necessitate an exercise to identify and source the data, involving human resources and potential system changes. This is expected to have low to medium cost implications, with costs scaling depending on the degree of IT systems work chosen. Costs would be primarily incurred at the time of implementation. Material ongoing costs would not be expected post-implementation.
Users’ costs
No costs were identified for users of financial statements other than minor familiarisation costs.
Benefits for preparers and users
Given that the amendments are narrow in scope, the UKEB conducted a proportionate level of stakeholder engagement, primarily through its advisory and working groups, [and consultation on the draft assessment], to estimate the benefits likely to be reaped by preparers and users of financial statements. The assessment is qualitative in nature.
Recognition and derecognition
The Amendments clarify the requirements for derecognition. It is expected that some entities already use the approach outlined, while others may need to make changes to align to the Amendments. The clarification is a benefit to users as it is likely to reduce diversity in practice. Additionally, the clarification is a benefit to preparers as:
- it reduces uncertainty, therefore helping reduce the risk of incorrect application of the requirements; and
- the new alternative may allow preparers to reduce their long term effort and cost (if the requirements for use of the alternative are met), while not damaging the interests of users.
The improved clarity is therefore expected to improve relevance, reliability and comparability, largely for the direct benefit of users of accounts.
Classification of financial instruments
The amendments provide clearer requirements and additional guidance. This reduces the risk of inappropriate classification for preparers, and reduces the risk of diversity in practice for the benefit of users.
The amendments may also remove a barrier to achieving amortised cost accounting for instruments with contingent features, in instances where amortised cost accounting would be the appropriate classification. This benefits users as they will then receive the decision-useful information relevant to basic lending, which would not be provided if the instruments were classified as measured at fair value. This may also benefit preparers, as, in the absence of a liquid reference market, it is often more complex and hence expensive to determine the fair value of an instrument.
Disclosure
By adding additional disclosures, the Amendments enhance the transparency and decision-usefulness of reporting for the direct benefits of users of accounts.
Whether the amendments are likely to have an adverse effect on UK economy
The Amendments primarily clarify existing accounting requirements and introduce targeted new disclosures. They are therefore not expected to have any significant wider economic effects beyond the direct impacts on users and preparers discussed above.
In terms of potential indirect wider economic benefits we note the Financial Conduct Authority (FCA) recently called for greater transparency on SLLs.18 The Amendments add disclosure requirements for instruments with contingent features, thus enhancing the transparency of financial statements. The additional disclosure is consistent with the FCA’s call for greater transparency and is anticipated to have a neutral to minor positive economic effect.
As a result, overall the UKEB considers that the Amendments are not likely to have an adverse effect on the UK economy, including on economic growth.
Long term public good assessment conclusion
2.13Having considered all relevant aspects, including the trade-off between the costs and benefits of implementing the Amendments, the UKEB concludes that the use of the Amendments is likely to be conducive to the long term public good in the UK as required by Regulation 7(1)(b) of SI 2019/685.
Do the Amendments lead to a significant change in accounting practice?
2.14The UKEB is required to assess whether or not the Amendments are likely to lead to a ‘significant change in accounting practice’ and therefore meet the criteria for a post-implementation review.
2.15The Amendments do not fundamentally change the requirements of IFRS 9 or IFRS 7 or introduce new principles. They primarily clarify existing accounting requirements. The Amendments also introduce additional disclosure requirements for certain types of financial instruments.
2.16As a result, and subject to any stakeholder feedback, the UKEB [tentatively] concludes that the Amendments are not likely to lead to a significant change in accounting practice and do not meet the criteria for a post-implementation review under Regulation 11 in SI 2019/685.
Appendix A: Glossary
| Term | Description |
|---|---|
| The Amendments | Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments |
| DECA | Draft Endorsement Criteria Assessment |
| ECA | Endorsement Criteria Assessment |
| ED | Exposure Draft |
| EU | European Union |
| FCL | Final Comment Letter |
| FVOCI | Fair Value through Other Comprehensive Income |
| IAS | International Accounting Standard |
| IASB | International Accounting Standards Board |
| IFRS | International Financial Reporting Standard(s) |
| SI | Statutory Instrument |
| UKEB | UK Endorsement Board |
Contact Us UK Endorsement Board 6th Floor | 10 South Colonnade | London | E14 4PU www.endorsement-board.uk
Appendix B: Invitation to Comment
September 19 2024 Agenda Paper 4: Appendix B UKEB UK Endorsement Board
Deadline for completion of this Invitation to Comment:
Close of business, [date]
Please submit to: [email protected]
Introduction
The objective of this Invitation to Comment is to obtain input from stakeholders on the endorsement and adoption of Amendments to IFRS 9 and IFRS 7 – Amendments to the Classification and Measurement of Financial Instruments (the Amendments), published by the International Accounting Standards Board (IASB) in May 2024. The Amendments aim to clarify the requirements for the derecognition of financial liabilities, and for assessing the classification of financial assets, particularly those with contingent features. In addition, the amendments introduce a limited number of additional disclosure requirements. The Amendments aim to address diversity in practice and improve the usefulness of the information provided to the investors. The Amendments will be effective for annual periods beginning on or after 1 January 2026. Earlier application is permitted. The information collected from this Invitation to Comment is intended to help with the endorsement assessment.
UK endorsement and adoption process
The requirements for UK adoption are set out in Statutory Instrument 2019/68519.
The powers to formally adopt international accounting standards for use in the UK were delegated to the UK Endorsement Board in May 202120.
Who should respond to this Invitation to Comment?
Stakeholders with an interest in the quality of accounts prepared in accordance with IFRS Accounting Standards.
How to respond to this Invitation to Comment
Please download this document, answer any questions on which you would like to provide views, and return it to [email protected] by close of business on [date].
Brief responses to individual questions are welcome, as well as comprehensive responses to all questions.
Privacy and other policies
The data collected through submitting this document will be stored and processed by the UKEB. By submitting this document, you consent to the UKEB processing your data for the purposes of influencing the development of and adopting IFRS for use in the UK. For further information, please see our Privacy Statements and Notices and other Policies (e.g. Consultation Responses Policy and Data Protection Policy)21.
The UKEB's policy is to publish on its website all responses to formal consultations issued by the UKEB unless the respondent explicitly requests otherwise. A standard confidentiality statement in an e-mail message will not be regarded as a request for non-disclosure. If you do not wish your signature to be published, please provide the UKEB with an unsigned version of your submission. The UKEB prefers to publish responses that do not include a personal signature. Other than the name of the organisation/individual responding, information contained in the “Your Details” document will not be published. The UKEB does not edit personal information (such as telephone numbers, postal or e-mail addresses) from any other response document submitted; therefore, only information that you wish to be published should be submitted in such responses.
Assessment against endorsement criteria
Our draft assessment [tentatively] concludes that:
- the Amendments meet the criteria of relevance, reliability, understandability and comparability required of the financial information needed for making economic decisions and assessing the stewardship of management, as required by SI 2019/685 (see Regulation 7(1)(c));
- application of the Amendments is not contrary to the principle that an entity's accounts must give a true and fair view as required by SI 2019/685 (see Regulation 7(1)(a)); and
- that the Amendments are likely to be conducive to the long term public good in the UK as required by SI 2019/685 (see Regulation 7(1)(b)), having considered:
- whether they will generally improve the quality of financial reporting;
- the costs and benefits that are likely to result from their use; and
- whether they are likely to have an adverse effect on the economy of the UK, including on economic growth.
Our assessment of the Amendments is set out in Section 2 of the DECA on the pages indicated below:
| Page | |
|---|---|
| Rationale for the Amendments | 10 |
| Technical accounting criteria assessment | 11-20 |
| True and fair view | 20-21 |
| UK long term public good (including costs and benefits for preparers and users) | 21-26 |
Questions
Technical accounting criteria assessment
- Do you agree with the draft assessment of the Amendments against the technical accounting criteria? (please select one option)
| Yes | No |
|---|---|
- Please include any comments you may have in response to question 1:
Click or tap here to enter text.
True and fair view
- Do you agree with the draft assessment that the Amendments are not contrary to the true and fair view requirement? (please select one option)
| Yes | No |
|---|---|
- Please include any comments you may have in response to question 3:
Click or tap here to enter text.
UK long term public good
- Do you agree with the initial overall assessment of costs and benefits likely to arise from the Amendments? (please select one option)
| Yes | No |
|---|---|
- Please include any comments you may have in response to question 5, including if any costs or benefits have been omitted:
Click or tap here to enter text.
- Do you agree with the draft assessment that the Amendments are likely to be conducive to the long term public good in the UK? (please select one option)
| Yes | No |
|---|---|
- Please include any comments you may have in response to question 7:
Click or tap here to enter text.
- Do you have any other comments you would like to add?
Click or tap here to enter text.
Thank you for completing this Invitation to Comment
Please submit this document by close of business on [date] to: [email protected]
Footnotes
-
These are instruments where the terms include sustainability-linked targets such as certain Environmental, Social or Governance practices of the entity. ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 685 (SI 2019/685) ↩
-
Project Initiation Plan, paragraphs A13-A17. ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 No. 685 (SI 2019/685). ↩
-
UKEB Final Comment Letter - Amendments to the Classification and Measurement of Financial Instruments. ↩
-
Exposure Draft: Amendments to the Classification and Measurement of Financial Instruments. ↩
-
Mandatory pronouncements are IFRS Standards, IAS Standards, Interpretations and mandatory application guidance. Non-mandatory guidance includes basis for conclusions, dissenting opinions, implementation guidance and illustrative examples, together with the IFRS practice statements. This categorisation is set out in the introduction to the IASB yearly bound volumes. ↩
-
The term "standard" includes standards (International Accounting Standards (IAS), International Financial Reporting Standards (IFRS)), amendments to those standards and related Interpretations (Standing Interpretations Committee / International Financial Reporting Interpretations Committee interpretations) issued or adopted by the IASB. This DECA relates to amendments to those standards. ↩
-
These descriptions are based on the qualitative characteristics of financial statements in the Framework for the Preparation and Presentation of Financial Statements adopted by the IASB in April 2001. These qualitative characteristics became part of the criteria for endorsement and adoption of IFRS in the EU's IAS Regulation (1606/2002), and, subsequently, in SI 2019/685. ↩
-
In the Framework for the Preparation and Presentation of Financial Statements adopted by the IASB, the users of financial reports include present and potential investors, employees, lenders, suppliers and other trade creditors, customers, governments and their agencies and the public. While the UK has not adopted this Framework, in this document 'users' is taken to have a similar meaning. ↩
-
Paragraph 15 of IAS 1 Presentation of Financial Statements. ↩
-
UKEB calculation based on LSEG and Eikon data, July 2024. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). Companies that function as investment vehicles (funds and trusts, REITS) are included in the count. ↩
-
UKEB estimate based on FAME, Companies Watch and other proprietary data. ↩
-
The Principles for Responsible Investment, a UN-backed network of investors, suggest that the market was worth USD 322 billion as of 2021, up from just USD 6 billion in 2016. See https://www.unpri.org/pri-blog/sustainability-linked-loans-a-strong-esg-commitment-or-a-vehicle-for-greenwashing/10243.article ↩
-
See https://www.fca.org.uk/publication/correspondence/sll-letter-june-2023.pdf ↩
-
For example, in their 2023 annual report, HSBC noted that "On-balance sheet sustainable lending transactions increased by 7% compared with 2022" (page 49, TCFD disclosures). However, they reported a figure that puts together sustainable lending and ESG-bonds underwriting, making it impossible to isolate the prevalence of SLLs. ↩
-
A keyword search on annual reports performed on the Sentieo platform returned scant and non-conclusive evidence on the prevalence of these instruments among UK entities. ↩
-
See https://www.fca.org.uk/news/news-stories/fca-outlines-concerns-about-sustainability-linked-loans-market ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019: https://www.legislation.gov.uk/uksi/2019/685/made ↩
-
The International Accounting Standards (Delegation of Functions) (EU Exit) Regulations 2021: https://www.legislation.gov.uk/uksi/2021/609/contents/made ↩
-
These policies can be accessed from the footer in the UKEB website here: https://www.endorsement-board.uk ↩