6 Climate-related and Other Uncertainties in the Financial Statements
18 July 2024 Agenda Paper 6
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
| Purpose of the paper | This paper provides the Board with a draft Project Initiation Plan (PIP) for the project to influence the IASB's forthcoming Exposure Draft (ED) resulting from its Climate-related and Other Uncertainties in the Financial Statements (CROUFS) project. |
Summary of the Issue
The IASB's project explores targeted actions to improve the reporting of climate-related and other uncertainties by illustrating how an entity can apply IFRS Accounting Standards to report their effects in the financial statements. It does not seek to: develop an Accounting Standard on climate-related risks; broaden the objective of financial statements; change the definitions of assets and liabilities; or develop accounting requirements for pollutant pricing mechanisms. The IASB expects to publish an ED containing eight illustrative examples that are intended to accompany IFRS Accounting Standards by 31 July 2024, for a 120-day comment period. The IASB may consider further standard-setting depending on feedback to the ED.
This PIP is based on the eight draft illustrative examples (the examples) discussed at the March 2024 IFRS Accounting Standards Advisory Forum (ASAF) and meetings. Summary of stakeholder comment on the examples was included at the UKEB's April 2024 meeting.
Decisions for the Board
Subject to any changes at this meeting, does the Board approve the PIP for the project?
Recommendation
We recommend the Board approves the PIP.
Appendices
Appendix A Draft Project Initiation Plan – Climate-related and Other Uncertainties in the Financial Statements.
Appendix A: Draft Project Initiation Plan – Climate-related and Other Uncertainties in the Financial Statements
Purpose
A1.The IASB has indicated its intention to publish an Exposure Draft (ED) on Climate-related and Other Uncertainties in the Financial Statements (CROUFS). The ED is expected to contain eight illustrative examples that are intended to accompany IFRS Accounting Standards and is anticipated to be published by 31 July 2024 for a 120-day comment period.
A2.This paper sets out a proposed approach and plan for an influencing project for the forthcoming CROUFS ED.
Background
A3.As the ED has yet to be published, this Project Initiation Plan (PIP) is based on the eight draft illustrative examples (the examples) discussed at the March 2024 IFRS Accounting Standards Advisory Forum (ASAF)1 and the March2 and April3 IASB meetings. The UKEB also noted a paper4 summarising stakeholder views at its April 2024 meeting.
A4.The IASB has provided the following overview of the eight examples:
- Example 1 illustrates the application of materiality to a scenario in which the fact pattern and circumstance appear to have no immediate effect on the financial statements.
- Example 2 illustrates a scenario in which no disclosure is required of climate transition risks. This is due to there being no effects on the entity beyond the entity's existing use of renewable energy and carbon offsets. It is assumed that users of financial statements would not reasonably expect there to be any material financial impacts in this industry.
- Example 3 is relevant to entities in industries with high greenhouse gas emissions and significant amounts of goodwill. The application section focuses on the measurement and disclosure requirements of IAS 36.
- Example 4 addresses a scenario when IAS 36 has no specific relevant disclosure requirement, but there is a significant risk of a material adjustment in less than 1 year and therefore disclosures under IAS 1.125 are applicable.
- Example 5 addresses a fact pattern in which the entity's key assumption is that a deferred tax asset (DTA) is likely to be fully utilised before new regulations come into force curtailing the entity's ability to operate and generate profits. The conclusion is that additional disclosure is required to understand fully the impact of future events, as required by IAS 1.31.
- Example 6 illustrates how climate-related risks, such as flooding risks, may manifest themselves in loan portfolios.
- Example 7 illustrates disclosures concerning the uncertainties involved in determining provisions under IAS 37. While the topic of the example is related to climate-related and sustainability matters, the principle is of general application.
- Example 8 illustrates how disaggregated information can be necessary to understand the different characteristics of items including their risks. The example illustrates an entity which has significant amounts of PPE with a range of different exposures to climate-related risks.
Initial stakeholder feedback
A5.In response to the IASB request in March 2024 to ASAF members for feedback on the examples the UKEB conducted outreach with Advisory and Working Groups. Twenty-three responses were received from a range of Board, Advisory and Working Group members.
Project approach
A6.A proportionate approach will be applied to the influencing project milestones in paragraph 5.3 of the UKEB's Due Process Handbook (Handbook), reflecting in particular the fact that significant initial stakeholder feedback has already been gathered.
A7.The table below provides a brief description of the proposed activities the Secretariat intends to deliver and their current status.
| Proposed activities | Handbook references | Status |
|---|---|---|
| Board Education session | 4.10(b) | In progress |
| Scheduled for July 2024 | Optional | |
| Project Initiation Plan (PIP) | 5.4-5.8 | In progress |
| Review and approval at the July 2024 UKEB meeting. | Mandatory | |
| Desk-based research | 5.9 | In progress |
| a) A review of UKEB research and staff papers regarding connectivity for climate-related matters | Optional | |
| b) Review of IASB papers, presentations, meetings, and education materials. | ||
| c) Review of any available comment letters on the ED from UK stakeholders | ||
| Outreach approach | 5.10-5.12 | In progress |
| As UKEB Advisory and Working Groups have already had opportunity to comment on the examples. If necessary, outreach prior to the issue of the Draft Comment Letter will focus on engagement with other stakeholders including external representative bodies. | Mandatory | |
| Draft Comment Letter (DCL) | Not started | |
| The DCL is proposed to be published for comment on the UKEB website. | 5.13-5.15 | UKEB approval for publication at the September 2024 meeting and publication following that meeting. |
| During the comment period stakeholders will be encouraged to comment via the usual UKEB public channels. The UKEB Advisory and Working Groups will also be re-engaged. | Mandatory | |
| Final Comment Letter (FCL) | 5.18 | Not started |
| The IASB comment period is expected to be 120-days and if issued on 31 July would close at the end on 28 November 2024 | Mandatory | UKEB to approve at the November 2024 meeting. |
| Feedback statement (FBS) and Due Process Compliance Statement (DPCS) | 5.19-5.26 | The FCL will be submitted to IASB and published on UKEB website with the FBS. |
| A draft DPCS will be reviewed at the November 2024 meeting and a final version noted at the December 2024 meeting. | Mandatory | Final DPCS to be published on UKEB website following noting at UKEB December 2024 meeting. |
A8.The following factors have been considered in developing a proportionate project plan.
Project scope
A9.The project scope is therefore relatively narrow. The IASB has decided that the project will explore targeted actions to improve the reporting of climate-related and other uncertainties and to illustrate how an entity can apply IFRS Accounting Standards to report their effects in the financial statements through a series of eight examples.
A10.The IASB have also decided that the project will not seek to:
- develop an Accounting Standard on climate-related risks;
- broaden the objective of financial statements;
- change the definitions of assets and liabilities; or
- develop accounting requirements for pollutant pricing mechanisms.
A11.In addition, the examples will not form part of the mandatory elements of IFRS Accounting Standards but will accompany those standards. Therefore, the examples will not be subject to consideration for adoption in the UK.
Significance and complexity
Relevance in the UK
A12.While the examples will not be adopted for use in the UK, they will accompany IFRS Accounting Standards and will potentially be relevant to a wide range of entities applying IFRS.
Complexity
A13.The examples are intended to reflect practical application situations and to provide illustrative clarity for stakeholders. As such, they are not anticipated to be highly technical or complex.
Expected timeline/urgency
A14.There appears to be a high level of interest from stakeholders and demand from users for greater clarity. We await confirmation from the IASB regarding their timeline.
A15.The UKEB November 2024 meeting, where the FCL will be considered for approval, may be on the same day as the submission deadline to the IASB. Possible need for an extension to the submission deadline will be kept under review.
Findings to date from desk-based research/ preliminary activities.
A16.Stakeholders have indicated that the examples would be helpful as an initial step to support the application of accounting standards to climate risks and other uncertainties and to improve connectivity for users of general-purpose financial statements. However, stakeholders made some initial suggestions as to how the examples could be enhanced. Themes from the stakeholder feedback are included in Annex A for information.
Expected interest / potential controversy
A17.There is wide interest in this project from a range of stakeholders. We have not been made aware of any critical concerns on the proposed ED to date.
A18.We understand that the ISSB intends to begin considering the concept of materiality as applicable to the Sustainability Disclosure standards it issues. As both the IASB and ISSB use the same definition and as stakeholders raised the application of materiality in their feedback to us, implications from that work and any tentative decisions by the ISSB will also be kept under review.
Resources allocated
A19.To undertake the activities described in this project plan a project team has been assigned consisting of 0.50 of a Project Director and limited Project Manager support, as required. The required resources are allowed for in the UKEB Regulatory Strategy.
Setting up an ad-hoc advisory
A20.The UKEB will not require a separate ad-hoc advisory body for this project as the UKEB Sustainability Working Group5 (SWG) is already in place. The members of the SWG have provided initial comments and will be consulted again, along with the other UKEB Advisory and Working Groups as the project progresses.
Project timeline
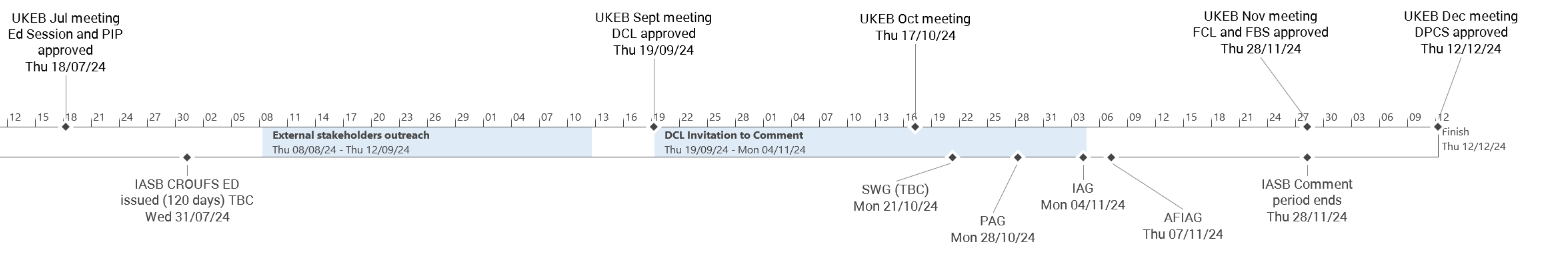
A21.The proposed high-level project timeline is shown below. This provides a best estimate based on information known at this time. If necessary, a revised PIP will be presented to the Board to reflect any material changes as the project progresses.
| 2024 | Milestones |
|---|---|
| 18 July | Education session and Draft Project Initiation Plan for UKEB approval. |
| 31 July (TBC) | IASB issue CROUFS Exposure Draft for 120 days |
| 19 September | Draft Comment Letter for UKEB review and approval |
| 19 September to 4 November | Draft Comment Letter consultation (45 days) |
| 28 November | IASB consultation period closes (TBC) |
| UKEB review of: | |
| 1. Final Comment Letter (FCL) | |
| 2. Feedback Statement (FBS) | |
| 3. Draft Due Process Compliance Statement (DPCS). | |
| Submission of FCL to IASB and publication of the FCL and FBS on the UKEB website. | |
| 12 December | Final DPCS presented to UKEB for noting. |
A22.The approach and therefore plan include the below key assumptions:
- the IASB issue the ED by the end of July 2024
- the ED is not significantly different in scope or number of examples to those previously circulated and discussed
- the DCL is published for comment for 45 days due to anticipated stakeholder interest and because the time between the September and October 2024 UKEB meetings is less than the mandatory 30 days required for an influencing project per the Handbook.
A23.Key risks to note:
- The UKEB November 2024 meeting to approve the FCL may fall on the same day as the submission deadline to the IASB. It may prove necessary to request a limited submission deadline extension from the IASB.
Climate-related and Other Uncertainties in the Financial Statements – Proposed timeline
A24.The diagram below is a graphical view of the content in the table above.
Annex A: Stakeholder feedback on CROUFS draft illustrative examples
A25.The main themes from the initial outreach with stakeholders are noted below for information.
Connectivity
A26.Several stakeholders considered that the examples did not adequately illustrate connectivity between the financial statements and the associated sustainability disclosures.
Materiality
A27.Users noted a common concern regarding a lack of disclosure regarding near to medium term climate-related risks on the grounds of low quantitative materiality. They encourage the IASB to add further examples to illustrate when a disclosure may be required regardless of quantum or term.
A28.Some stakeholders were concerned that the examples sought to artificially distinguished between quantitative and qualitative materiality. Their preference was for one definition to be used but for both aspects to be emphasised.
A29.Most stakeholders were concerned that Example 1 'Materiality judgements leading to additional disclosures' may over-extend the use of IAS 1 (IAS 1) Presentation of Financial Statements paragraph 31. They considered this was rarely used at present and generally only in unforeseen circumstances. They considered that this approach could result in unrealistic user disclosure expectations, not just on climate, but also for other macroeconomic issues.
A30.Some stakeholders were concerned that Example 5 'Disclosure of additional information' appeared to set a precedent for requiring disclosure of matters that might occur beyond the 12 month time horizon. They considered this would be a significant change from current practice if the IASB intended consistent application across all areas, that is in addition to climate.
Measurement considerations
A31.Users considered it would be helpful if the examples could illustrate the circumstances when a provision should be made for a material asset retirement obligation. Other stakeholders suggested it would be helpful to include scenarios where assets were replaced or repurposed, as they were both current issues in practice.
A32.Some stakeholders considered Example 7 ‘Disclosures about decommissioning and restoration provisions' to be overly simplistic. They commented that when measuring provisions under IAS 37 Provisions, Contingent Liabilities and Contingent Assets companies omitted these costs more because they were very difficult to estimate as opposed to on grounds of materiality.
A33.Stakeholders recommended that Example 3 'Value in use calculation and disclosures' should address how climate-related risks could impact expected cash flows and terminal values beyond a five-year period per IAS 36 Impairment of Assets as these were current issues in practice.
Disclosure of disaggregated information
A34.Stakeholders observed that Example 8 ‘Disclosure of disaggregated information' may not be helpful as the disaggregation of information was already required if the resulting information was material. It was suggested that the example could be enhanced by a discussion of the application of materiality judgements in disaggregating the information.
Nature of examples - standalone or walkthrough
A35.There were mixed views regarding whether standalone examples would be more effective than walkthrough or scenario-based examples.
Choice of standard setting ‘vehicle' - accompanying IFRS Accounting Standards
A36.A range of stakeholders and many Users emphasised the need for enforceability. They noted that while previous educational guidance and articles from the IASB had been helpful, they had not been wholly effective in changing behaviour as they could not be enforced.
A37.Many stakeholders emphasised the importance of exposing the examples to due process and consultation. Many also considered that illustrative examples that accompanied IFRS Accounting Standards would achieve an appropriate balance between authority and sufficient detail to support consistent application.