4 Rate-regulated Activities
Project Type: Influencing Project Scope: Significant
Executive Summary
Purpose of the paper
The purpose of this paper is to present to the Board for its consideration and approval the following:
- A draft letter to the IASB setting out the UKEB's concerns in relation to certain aspects of the forthcoming standard on regulated assets and regulated liabilities.
- A draft consolidated report setting out the UKEB Secretariat's work on the top-down approach to address accounting for rate-regulated entities with no direct relationship between their regulatory capital base (RCB) and property, plant and equipment (PPE).
Summary of the Issue The IASB published an Exposure Draft (ED) Regulated Assets and Regulated Liabilities in January
- The IASB is currently redeliberating the proposals. It is expected to publish a final standard in 2025.
The IASB tentatively decided to clarify that a rate-regulated entity is:
- Required to recognise the timing differences that are included in the regulatory capital base (RCB) only when its property, plant and equipment (PPE) and RCB have a direct relationship.
- Not permitted to recognise the timing differences that are included in the RCB when an entity's PPE and RCB do not have a direct relationship.
This IASB tentative decision will provide a comprehensive approach to the recognition of regulatory assets or liabilities in relation to timing differences for rate-regulated entities whose PPE and RCB have a direct relationship. By contrast, for entities with no direct relationship between PPE and RCB, the IASB's tentative decision will provide only a partial approach to the recognition of regulatory assets or liabilities in relation to timing differences included in the RCB.
An IASB survey in 2023 identified that approximately 50% of entities within the scope of the standard that responded to its survey appear to be in the no direct relationship category.
Almost all UK rate-regulated entities are in the no direct relationship category. As such, under the IASB's current proposals, UK rate-regulated entities will not be able to recognise regulatory assets or regulatory liabilities arising from enforceable rights and obligations relating to timing differences included in the RCB.
The UKEB Secretariat's initial work has identified that under the IASB's proposed approach only approximately 40% of the total timing differences would be recognised for UK water entities, approximately 50% for UK energy entities and a varying percentage for UK aviation entities.
The key questions that arise from the IASB's approach are as follows:
- Will partial recognition of timing differences for entities with a no direct relationship be understandable to users?
- Is partial recognition of timing differences by potentially around 50% of rate-regulated entities with no direct relationship appropriate?
- Does it lead to a lack of comparability between direct and no direct relationship entities?
- Is a lack of a level playing field between direct and no direct relationship entities appropriate?
- Will the benefits for preparers with a no direct relationship between PPE and RCB, of recognising only approximately 40% of the timing differences, outweigh the costs?
Consolidated report
The UKEB top-down approach considers how timing differences included in the RCB for no direct relationship entities could be recognised and whether they could be monitored and tracked.
It is intended to supplement the IASB's proposals in the ED and subsequent tentative decisions. It does not affect the other IASB proposals and tentative decisions, such as on measurement and presentation.
The draft consolidated report is based on the papers on the top-down approach that were previously discussed by:
- The RRA TAG in March 2024.
- The UKEB in March, April and May 2024. The approach was presented to IFASS in April 2024 and EFRAG RRAWG in May
- The UKEB Secretariat also consulted with other NSS and their feedback, to the extent received, has also been included in the draft report.
Letter to the IASB
A draft of a letter to the IASB, setting out the UKEB's concerns with the IASB's decisions in relation to recognition of regulatory assets and liabilities for entities with no direct relationship, the potential impact and the potential solution, is included at Appendix A.
The Board is asked to consider the letter for submitting to the IASB. The letter will be accompanied by a finalised version of the consolidated report.
Decisions for the Board
Subject to any comments at the meeting, do Board members approve the draft letter and draft consolidated report for publication on the UKEB website and sending to the IASB?
Recommendation
That Board members approve the draft letter and consolidated report for publication on the UEKB website and sending to the IASB.
Appendices
Appendix A Draft letter to the IASB Appendix B Consolidated report on the UKEB Secretariat's top-down approach
Appendix A: Draft letter to the IASB
Dr Andreas Barckow Chair International Accounting Standards Board 7 Westferry Circus Canary Wharf London E14 4HD
xx July 2024
Dear Andreas
IASB Project: Regulatory Assets and Regulatory Liabilities
1I am writing to you on behalf of the UK Endorsement Board in relation to the IASB's project on the development of a standard for entities subject to regulatory agreements that are capable of creating regulatory assets and regulatory liabilities.
2The UKEB would like to congratulate the IASB and its staff on their ongoing work on development of the standard. It is a much-needed standard on a topic where, as the IASB itself recognised, the existing accounting standards do not permit reporting the full effect of rate-regulated activities on current and future revenues, and associated assets and liabilities. As a result, there is significant diversity in accounting practice, both here in the UK and globally. In the UK this has led to a significant proliferation of alternative performance measures (APMs) by rate-regulated entities. Rate-regulated companies currently produce APMs to help better explain their results, which are not otherwise easily understandable to investors and other users of their accounts.
3We understand that the IASB set itself the objective while developing this standard of providing users with insights into how regulatory assets and regulatory liabilities will affect the amount, timing and uncertainty of the reporting entity's future cash flows. This required the development of a model that would reflect the total allowed compensation for goods and services supplied in a period as part of an entity's reported financial performance. Additionally, an entity would be required to recognise its regulatory assets and regulatory liabilities in its statement of financial position.
4The IASB's initial tentative decision in December 2022, made in response to stakeholder feedback on the Exposure Draft, was to identify separately entities with a direct and those with no direct relationship between their property, plant and equipment (PPE) and their regulatory capital base (RCB). We consider this a positive development as the different features of the regulatory regimes in individual jurisdictions mean that the IASB's objective, of recognising total allowed compensation and related regulatory assets and liabilities, may need to be achieved in different ways for the types of regulatory regimes in order for the standard to be operational in practice.
5However, the follow-on tentative decision – not to permit recognition of regulatory assets and liabilities for entities with no direct relationship between PPE and RCB – was made on the basis that a potential regulatory asset or liability met the recognition criteria but could not be tracked through a 'bottom-up' reconciliation between PPE and RCB. This appears to omit the possibility that the IASB's objectives could be met in different ways. Nor does it fully address stakeholder concerns in relation to reporting and has the potential to deliver only limited comparability and understandability for investors.
6The affected companies in the UK have also told us that applying the IASB's no direct relationship approach is unlikely to allow them to report fully their financial performance and financial position in an understandable way. Examples of potential regulatory assets/liabilities that would not be recognised on the statement of financial position for such entities include:
- The difference between accounting and regulatory capitalisation of expenditure, including the capitalisation of interest;
- The difference between accounting and regulatory depreciation;
- Inflation adjustments included in the RCB1; and
- Any other incentive mechanism adjustment to RCB.
As a result, the affected entities would need to continue to utilise APMs to facilitate investors' understanding of their financial information.
7As you are aware, we asked the UKEB Secretariat to explore potential alternatives to the IASB's tentative decisions regarding its no direct relationship approach. Our Secretariat has developed the top-down approach to an initial concept level. The top-down approach may enable entities with no direct relationship between RCB and PPE with recognition of regulatory assets and liabilities on the statement of financial position that fully reflects their total allowed compensation for the period.
8This has been developed as a supplement to the IASB's existing approach for recognition of regulatory assets for entities with a direct relationship between RCB and PPE. It aims to maintain consistency with the IASB's objectives for the new standard as well as concepts within the IFRS Foundation's Conceptual Framework for Financial Reporting.
9However, we recognise that further work is necessary to develop fully the top-down approach and field test it with UK entities and companies in other jurisdictions. We also understand that the IASB is under time pressure to complete the project due to a more urgent need for the standard elsewhere in the world. We would therefore encourage the IASB to develop this further for inclusion in the standard at a suitable future juncture.
Yours sincerely
Pauline Wallace
Consolidated report on the UKEB Secretariat's top-down approach July 2024
[IFRS Foundation Copyright and disclaimer wording to be inserted here – if needed]
The UKEB does not accept any liability to any party for any loss, damage or costs howsoever arising, whether directly or indirectly, whether in contract, tort or otherwise from any action or decision taken (or not taken) as a result of any person relying on or otherwise using this document or arising from an omission from it.
© 2024 All Rights Reserved
- Executive Summary
- Consolidated report
- Letter to the IASB
- Decisions for the Board
- Recommendation
- Appendices
- IASB Project: Regulatory Assets and Regulatory Liabilities
- Introduction
- Section 1: Current IASB proposals
- Section 2: Why is this an issue?
- Section 3: A potential solution – the top-down approach
- Section 4: The solution tested against standard-setting questions
- Questions to address
- Analysis of questions already addressed
- Question 1: What is the difference between the IASB's current proposals and the top-down approach?
- Question 2: What are the items that comprise the difference between RCB and PPE?
- Question 3: Do the assets and liabilities arising from the top-down approach meet the definitions of regulatory assets and/or regulatory liabilities in the IASB's proposals?
- Added to regulated rate to be charged to customers in future periods
- Operating expenses included in RCB
- Inflation adjustment included in RCB
- RRA TAG feedback
- Question 4: Does the top-down approach meet the unit of account requirements in the IASB's proposals?
- Question 5: Does the top-down approach meet the recognition criteria in the IASB's proposals?
- Question 6: Can the timing differences included in the RCB be tracked and monitored?
- Section 5: Other issues to be considered before finalisation
- Appendix A: Illustrating the top-down approach - recognition
- Appendix B: Analogies to other IFRS Standards
- Appendix B: Analogies to other IFRS Standards
- Appendix C: Information currently reported by UK rate-regulated entities using alternative performance measures
Introduction
Purpose
1The IASB published an Exposure Draft (ED) Regulatory Assets and Regulatory Liabilities in January 2021 and is continuing its redeliberations following feedback on the ED. It is expected that a standard will be published in 2025.
2Paragraph 1 of the ED sets out the IASB's objective for the [draft] Standard as:
"This [draft] Standard sets out the principles for the recognition, measurement, presentation and disclosure of regulatory assets, regulatory liabilities, regulatory income and regulatory expense. The objective of those principles is for an entity to provide relevant information that faithfully represents how regulatory income and regulatory expense affect the entity's financial performance, and how regulatory assets and regulatory liabilities affect its financial position." [emphasis added]
Paragraph 2 of the ED notes that:
"This information, together with information required by other IFRS Standards, enables users of financial statements to understand:
- the relationship between an entity's revenue and expenses as completely as would have been possible if the total allowed compensation for the goods or services supplied had been fully reflected in revenue in the period in which the entity supplied those goods or services. That understanding will provide insights into the entity's prospects for future cash flows.
- the entity's regulatory assets and regulatory liabilities. That understanding will provide insights into how regulatory assets and regulatory liabilities will affect the amount, timing and uncertainty of the entity's future cash flows."
3The IASB's subsequent tentative decision to prohibit entities with no direct relationship between property, plant and equipment (PPE) and their regulatory capital base (RCB) from recognising the timing differences arising between those two balances as regulatory assets or liabilities is termed as the direct (no direct) relationship concept. It leads to significant concerns about lack of completeness and therefore the understandability for users of the IFRS accounts of UK entities within the scope of this Standard. All UK entities within scope of this [draft] Standard have no direct relationship between their PPE and RCB.
4The UKEB Secretariat commenced work on development of a top-down approach ('the top-down approach') to address the concerns relating to the accounting outcomes arising from the IASB's tentative decisions on the direct (no direct) relationship concept. The top-down approach was developed to concept level with input from the UKEB Rate-Regulated Technical Advisory Group (RRA TAG) and other stakeholders. The approach addresses the recognition of rights and obligations arising from timing differences included in the regulatory capital base (RCB) of entities whose property, plant and equipment (PPE) and RCB have no direct relationship.
5This paper summarises the development work to-date and the further work required to fully develop it into a standard setting solution, providing information on the following aspects:
- Section 1: Current IASB proposals
- Section 2: Why is this an issue – UK perspective
- Section 3: A potential solution – the top-down approach
- Section 4: The solution tested against standard-setting questions
- Section 5: Other issues to be considered before finalisation
- Appendix A: Illustrating the top-down approach – recognition.
- Appendix B: [Analogies to other IFRS standards]
- Appendix C: Information currently reported by UK rate-regulated entities using alternative performance measures
Section 1: Current IASB proposals
The direct (no direct) relationship concept
IASB tentative decisions
6In December 20222 the IASB tentatively decided to base some of the accounting requirements on whether there is a direct or no direct relationship between an entity's property, plant and equipment (PPE) and regulatory capital base (RCB), 'the direct (no direct) relationship concept'.
7The direct (no direct) relationship concept was not included in the ED. This concept came about when feedback on the ED indicated that the ED "...assumed there is always a close relationship between the RCB and an entity's assets..."3 and that "...the 'allowed revenue' is closely linked to operating expenditure and depreciation included in the financial statements..."4. These are typical features of cost-based regulatory schemes5. The ED therefore addresses mainly cost-based regulatory schemes and not incentive-based6 regulatory schemes.
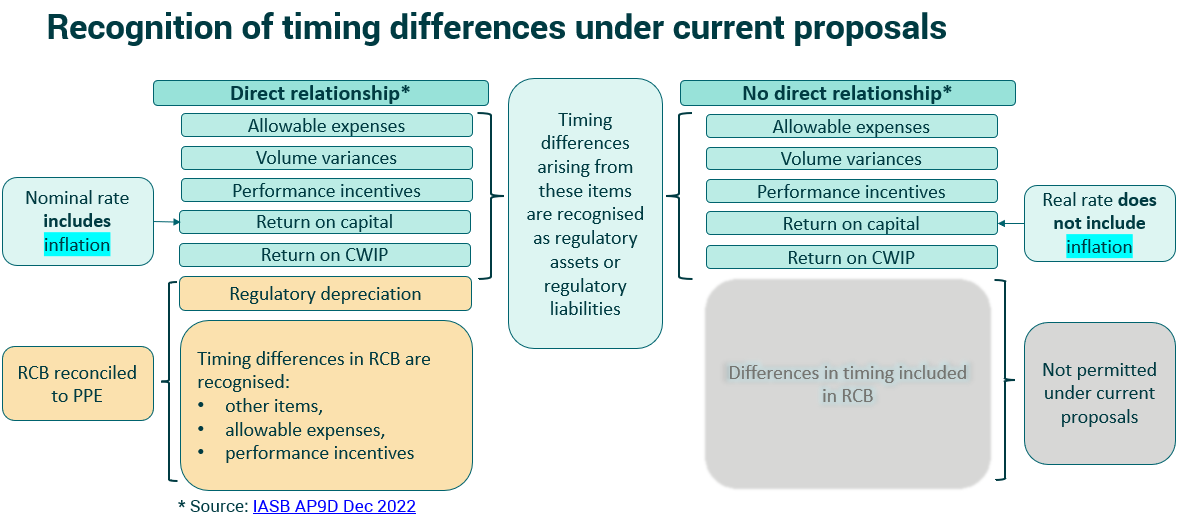
8The direct (no direct) relationship concept will have implications for the extent to which rate-regulated entities within the scope of the IASB's ED will be able to recognise regulatory assets or regulatory liabilities. The approach currently proposed by the IASB means that:
- All rate-regulated entities:
- Are required to recognise regulatory assets or regulatory liabilities for enforceable present rights and obligations arising from timing differences that are recovered (fulfilled) in the regulated rate in the current or following regulatory period, e.g. 5 years. These timing differences are also referred to as 'revenue adjustments'.7
- Are prohibited from recognising the inflation adjustment included in the RCB. However, as noted in paragraphs 17 to 22 below, this tentative decision mainly affects entities whose PPE and RCB have no direct relationship.
- Rate-regulated entities whose PPE and RCB have a direct relationship (direct relationship entities): are also required to recognise all enforceable present rights and obligations arising from timing differences that are included in the RCB and recovered (fulfilled) in the regulated rate through regulatory depreciation over several regulatory periods, e.g. 20 years.
- Rate-regulated entities whose PPE and RCB have no direct relationship (no direct relationship entities): are prohibited from recognising enforceable present rights and obligations arising from timing differences included in the RCB.
The rationale for the IASB's tentative decisions on the direct (no direct) relationship concept
9The rationale behind the IASB's tentative decisions on the direct (no direct) relationship concept is:
- The recognition of allowable expenses or performance incentives (penalties) that are timing differences and included in the RCB is prohibited due to it being "...difficult and costly for entities to track the movement of individual items of allowable expense or performance incentives included in the regulatory capital base."8
- The recognition of inflation adjustments that are timing differences and included in the RCB is prohibited because "... the costs arising from the recognition of that asset would outweigh the benefits of the information provided for users [...]."9. As noted in paragraphs 16 to 20 below, this tentative decision seems equitable for all entities, but has a more significant impact on the no direct relationship entities.
The timing differences recognised under the current proposals
10The diagram below sets out the timing differences that commonly occur under regulatory agreements.
The impact of the direct (no direct) relationship concept
Survey on the direct (no direct) relationship
11In 2023, the IASB undertook a survey on the direct (no direct) relationship. It found that the direct (no direct) relationship seems to be "... an appropriate approach for determining whether differences in timing arise from the regulatory compensation an entity receives on its regulatory capital base in a variety of regulatory schemes."10 It found that the PPE and RCB of approximately 50% of entities that responded to the survey, and were able to conclude on whether their PPE and RCB have a direct or no direct relationship, did not have a direct relationship11.
12The IASB's survey also found that direct relationship entities are generally subject to cost-based regulatory schemes, while no direct relationship entities are generally subject to incentive-based regulatory schemes. A detailed explanation of the features of these two types of schemes can be found in Agenda Paper 9A12 of the IASB's May 2022 meeting.
13The tentative decisions on the direct (no direct) relationship concept provides a more complete model for the recognition of timing differences for direct relationship entities than for no direct relationship entities. Applying the ED and IASB tentative decisions will therefore more closely reflect the underlying economics in the financial statements only for those entities with a direct relationship between PPE and RCB.
14For entities with no direct relationship between PPE and RCB, timing differences arising from items included in RCB, typically allowable expenses, performance incentives and inflation, will not be permitted for recognition.
Allowable expenses and performance incentives
15As stated above, under the current IASB proposals the no direct relationship entities will not be permitted to recognise those regulatory assets and regulatory liabilities arising from enforceable rights and obligations for timing differences related to allowable expenses and performance incentives included in the RCB. By contrast, entities with direct relationship will be required to recognise these regulatory assets and regulatory liabilities.
UK perspective
16All UK rate-regulated entities have no direct relationship between PPE and RCB. Under the current proposals, these entities would therefore only recognise timing differences that are revenue adjustments. The UKEB Secretariat's work so far has identified that only approximately 40% of the total timing differences for UK water entities and up to 50% for UK energy entities constitute such revenue adjustments and would be recognised. The proportion expected to be recognised by the entities in the UK aviation sector will vary depending on the point in time within the price control period.
Inflation
17In many regulatory schemes, one element of allowed revenue is a return on the RCB, typically calculated using a weighted average cost of capital or a regulatory interest rate stipulated in the regulatory agreement. Some regulatory agreements apply a nominal return to the regulatory capital base while other regulatory agreements adjust the regulatory capital base for inflation and apply to it a real rate of return which excludes inflation. A nominal rate of return is higher than a real rate of return as the nominal rate includes a component that constitutes compensation for inflation.
13 The tentative decisions on the direct (no direct) relationship concept provides a more complete model for the recognition of timing differences for direct relationship entities than for no direct relationship entities. Applying the ED and IASB tentative decisions will therefore more closely reflect the underlying economics in the financial statements only for those entities with a direct relationship between PPE and RCB.
14 For entities with no direct relationship between PPE and RCB, timing differences arising from items included in RCB, typically allowable expenses, performance incentives and inflation, will not be permitted for recognition.
Allowable expenses and performance incentives
15 As stated above, under the current IASB proposals the no direct relationship entities will not be permitted to recognise those regulatory assets and regulatory liabilities arising from enforceable rights and obligations for timing differences related to allowable expenses and performance incentives included in the RCB. By contrast, entities with direct relationship will be required to recognise these regulatory assets and regulatory liabilities.
UK perspective
16 All UK rate-regulated entities have no direct relationship between PPE and RCB. Under the current proposals, these entities would therefore only recognise timing differences that are revenue adjustments. The UKEB Secretariat's work so far has identified that only approximately 40% of the total timing differences for UK water entities and up to 50% for UK energy entities constitute such revenue adjustments and would be recognised. The proportion expected to be recognised by the entities in the UK aviation sector will vary depending on the point in time within the price control period.
Inflation
17 In many regulatory schemes, one element of allowed revenue is a return on the RCB, typically calculated using a weighted average cost of capital or a regulatory interest rate stipulated in the regulatory agreement. Some regulatory agreements apply a nominal return to the regulatory capital base while other regulatory agreements adjust the regulatory capital base for inflation and apply to it a real rate of return which excludes inflation. A nominal rate of return is higher than a real rate of return as the nominal rate includes a component that constitutes compensation for inflation.
18 In December 202213, the IASB discussed the inflation adjustment to the RCB and stated that "We have observed that the nominal approach is more commonly used by cost-based schemes and the real approach is more commonly used by incentive-based schemes..."14
19 Entities whose regulatory agreements apply a nominal interest model are therefore compensated for inflation through the higher (nominal) return on capital (the nominal rate) calculated on the RCB. The return on capital is included in the entities' allowed revenue, which in turn is a determinant of the regulated rate charged to customers. This means that the inflation element is recognised immediately in revenue as and when the regulated rates are charged to customers by entities subject to nominal rate (typically those with a direct relationship between PPE and RCB).
20 Entities whose regulatory agreements apply a real interest model typically get compensated for inflation through an inflation adjustment to the RCB. This compensation is recovered by the entities in the regulatory depreciation of the RCB. The regulatory depreciation is included in allowed revenue and therefore in the regulated rate over a long period, typically 25 years.
21 Therefore, the IASB's tentative decision to prohibit all entities from recognising the inflation adjustment to the RCB, will generally affect only entities that use the real interest model as they would be prohibited from recognising the inflation adjustment to the RCB even though it is recovered when charged to customers in the regulated rates. The compensation for inflation earned by direct relationship entities automatically flows through to revenue as part of the nominal rate of return that is used in calculating the return on capital included in allowed revenue.
UK perspective
22 Regulatory agreements in the UK are typically incentive-based and all UK rate-regulated entities operate under the real interest model. This means that these entities will be prohibited from recognising the compensation received for inflation as the timing difference relating to inflation is included in the RCB.
Unit of account
23 One of the IASB's key concerns is the ability of an entity to track individual timing differences and, as a result, the UKEB Secretariat's view is that it is important to consider the appropriate level of the unit of account when accounting for regulatory assets and regulatory liabilities. An analysis of the IASB's proposals and tentative decisions relating to the unit of account is set out in this section.
24 Unit of account was considered in the ED proposals and further refined by the IASB's subsequent tentative decisions.
ED proposals
25 The ED addresses the unit of account in paragraph 24:
"An entity shall account for the right or obligation arising from each individual difference in timing described in paragraph 12(a) as a separate unit of account. However, if rights, obligations, or rights and obligations arising from the same regulatory agreement have similar expiry patterns and are subject to similar risks, they may be treated as arising from the same individual difference in timing."
Paragraph 12(a) states:
"differences in timing arise because the regulatory agreement includes part of that total allowed compensation in determining the regulated rates for goods or services supplied in a different period (past or future)”
Subsequent IASB tentative decisions
26 At its December 202315 meeting, the IASB agreed to:
"clarify that the unit of account is the right or obligation arising from a difference in timing or from a group of differences in timing when the differences in timing included in that group are:
- created by the same regulatory agreement;
- have similar expiry patterns; and
- be subject to similar risks."
27 The description in paragraph 21 of Agenda Paper 9A of its December 2023 meeting notes that:
"When a regulatory agreement groups differences in timing and considers them to be a single adjustment to the future regulated rate [...], those differences in timing would have the same expiry pattern and be subject to the same risks. This would be an example of a right or obligation arising from a group of differences in timing. We think paragraph 24 of the Exposure Draft would capture this example, but that paragraph could be redrafted for greater clarity and the final Standard could include such an example."
28 Therefore, grouping of timing differences is permitted when they are considered by the regulator as a single adjustment to the future regulated rate. This is because the total adjustment would have the same expiry pattern and be subject to the same risks.
29 Paragraph 4.49 of the Conceptual Framework for Financial Reporting ('the Conceptual Framework') acknowledges that, in some circumstances, it may be appropriate to select one unit of account for recognition and a different unit of account for measurement. It gives an example where contracts may sometimes be recognised individually but measured as a portfolio of contracts.
30 As noted in Appendix B, there are a number of IFRS Standards that permit the application of the unit of account at a higher level.
31 We note that the original tentative decisions relating to timing differences arising from operating expenses, performance incentives (or penalties) and the inflation adjustment included in RCB were made in December 2022 before the tentative decisions relating to unit of account which were made in December 2023.
32 We believe the interaction between tentative decisions on the unit of account and those relating to the non-recognition of timing differences arising from operating expenses, performance incentives (or penalties) and the inflation adjustment included in RCB should be considered by the IASB. This could result in use of a higher unit of account so that the cost-benefit relationship changes to require recognition of these timing differences. However, this paper has only considered timing differences arising from operating expenses, performance incentives (or penalties) and the inflation adjustment to illustrate the key areas of interaction and concern.
Section 2: Why is this an issue?
Objective of the ED
33 The objective of the IASB's project is to make the financial statements of companies subject to rate regulation more useful and comparable for users of those accounts. The concerns with the IASB's proposed approach include:
- Will partial recognition of timing differences for no direct relationship entities result in financial information that is useful? Will it be relevant and understandable to users? How will users be able to compare performance between direct and no direct relationship entities? There is a risk that the objective to make the financial statements of rate-regulated entities more useful and more comparable will fail to be met for a large proportion of affected entities.
- Could partial recognition of timing differences for approximately 50% of rate-regulated entities have a negative impact on those entities' relative attractiveness to investors and competitiveness?
- For no direct relationship entities, will the benefits for preparers and users of recognising approximately 40% to 50% of the timing differences, and associated disclosures, outweigh the related costs?
34 Partial recognition of timing differences will lead to some regulatory assets and regulatory liabilities remaining off Balance Sheet.
Reflecting the underlying economics and comparability
35 The non-recognition of the timing differences we are considering in this report (i.e. operating expenses, performance incentives (or penalties) and the inflation adjustment) included in RCB means that the application of the IASB's current approach will lead to an incomplete representation of the relevant information related to the financial performance and position of these entities. Users of financial statements of entities with no direct relationship will continue to have incomplete information on the relationship between those entities' revenue and expenses, and so insufficient insight into the prospects for future cash flows. In addition, the financial statements of entities with a direct relationship between PPE and RCB and those with no direct relationship between PPE and RCB will not provide directly comparable information, undermining the information relevance of IFRS accounts.
36 UK rate-regulated entities currently make extensive use of alternative performance measures (APMs) and regulatory performance measures to report underlying performance. One entity's recent annual report noted that use is made of APMs to communicate a measure of historical or future financial performance, financial position, or cash flows that are not reported in the financial statements with the aim being to provide a better understanding of the entity's underlying performance. These APMs include information on the RCB, and timing differences included in the RCB to which the entity is entitled and is expecting to recover (fulfil) in future regulated rates.
37 Under the current IASB proposals, entities will need to continue reporting this information in this way to be able to reflect the impact of the features of the regulatory regimes under which they operate.
38 Further details of information UK rate-regulated entities currently report can be found in Appendix C.
Section 3: A potential solution – the top-down approach
The UKEB Secretariat's top-down approach
39 The UKEB Secretariat started developing an alternative top-down approach that could be used for rate-regulated entities with no direct relationship between PPE and RCB to recognise regulatory assets and regulatory liabilities on a comprehensive basis.
40 The top-down approach considers how enforceable rights and obligations arising from timing differences included in the RCB for no direct relationship entities could be recognised and whether they could be tracked and monitored. The top-down approach is aimed as supplementary to the IASB's current proposals rather than as a replacement.
41 The UKEB considered the Secretariat's work at its meetings in March, April and May 2024 and provided challenge and commentary on the development of the approach. This has enabled the Secretariat to take this work to concept level. Further work is required to ensure a fully developed standard setting proposal. In the remaining sections below, we set out the analysis of work performed by the Secretariat as well as an assessment of further work required.
Key components and mechanics
42 Given that rate-regulated entities with no direct relationship between PPE and RCB cannot directly reconcile the two asset bases, the top-down approach is proposed to work for each year, as follows:
- Identify the lowest level that the RCB is calculated, e.g. by line of business.
- Calculate the difference between the value of PPE and RCB at the end of the reporting period at the lowest level.
- Eliminate items that will never be included in RCB (permanent differences). These could include for example:
- Borrowing costs capitalised under IFRS Accounting Standards,
- Assets capitalised in PPE contributed by parties other than the entity,
- The identifiable assets acquired and liabilities assumed in a business combination that are recognised at their fair values in accordance with IFRS 3 Business Combinations, but where no equivalent adjustment is made in the RCB, including any goodwill that arises, and
- Assets are revalued with no equivalent adjustment made in the RCB.
- Recognise the resulting residual difference as:
- A regulatory asset. If RCB exceeds PPE, there is excess value in the RCB that is yet to be recovered from customers. If this is an enforceable right, in line with the regulatory agreement, the difference would result in an addition to future regulated rates charged to customers, if the difference recognised is an enforceable present right arising from the timing differences grouped together in RCB by the regulator and is more likely than not to exist.
- A regulatory liability. If PPE exceeds RCB, part of the RCB value for providing goods or services in future periods has already been charged to customers. If this is an enforceable obligation, in line with the regulatory agreement, the difference would result in a deduction from future regulated rates if the difference recognised is an enforceable present obligation arising from the timing differences grouped together in RCB by the regulator and is more likely than not to exist.
- Measure the residual difference applying the approach proposed in the ED.
- The residual difference would be amortised by applying the same depreciation rate as the rate applied to the overall RCB and continue to be inflated.16
Timing differences recognised under the top-down approach
43 The diagram below depicts the timing differences (included in RCB) that would be recognised under the top-down approach.
Impact of UKEB Secretariat's proposed top-down approach
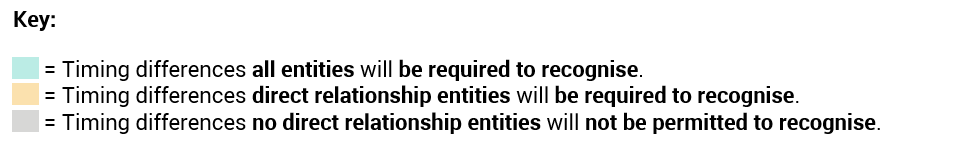
Key: - = Timing differences all entities will be required to recognise. - = Timing differences direct relationship entities will be required to recognise. - = Timing differences no direct relationship entities will be required to recognise.
Revenue adjustments
44 The top-down approach does not affect the IASB's current proposals relating to enforceable present rights and obligations arising from timing differences that are recovered (fulfilled) in the regulated rate in the current or following regulatory period. These adjustments are typically referred to as 'revenue adjustments'.
RCB adjustments
45 The top-down approach uses the difference between RCB and PPE to recognise regulatory assets and liabilities after removing permanent differences. This difference is treated as the timing difference for the purpose of recognition of regulatory assets and liabilities.
46 This approach assumes that the unit of account will be at a line of business level (by year) rather than the IASB's approach, which focuses on individual timing differences.
Section 4: The solution tested against standard-setting questions
Questions to address
47 The UKEB advised the Secretariat at the April 2024 meeting to consider the following questions when developing the top-down approach:
- What is the difference between the top-down approach and the IASB's proposals?
- What items comprise the difference between RCB and PPE?
- Do the assets and liabilities arising from the top-down approach meet the definitions of regulatory asset and/or regulatory liability as per IASB proposals?
- Does the top-down approach meet the unit of account requirements in the IASB's proposals?
- Does the top-down approach meet the recognition criteria in the IASB's proposals?
- Can the timing differences reflected in RCB be tracked and monitored?
- Does the top-down approach meet the measurement requirements in the IASB's proposals?
- Does the top-down approach meet the disclosure requirements in the IASB's proposals?
- Transition for the top-down approach.
Analysis of questions already addressed
48 This section sets out a brief analysis of the questions the UKEB Secretariat has already addressed in developing this approach to concept level. The analysis includes feedback received from the RRA TAG and other stakeholders.
49 A more detailed analysis of each of the questions below can be found in the UKEB's Agenda Paper 717 of its May 2024 meeting.
Question 1: What is the difference between the IASB's current proposals and the top-down approach?
50 As an overview, the main differences between the IASB's proposals and the top-down approach are:
- Under the IASB's current proposals, the no direct entities will be prohibited from recognising regulatory assets and regulatory liabilities arising from enforceable rights and obligations relating to timing differences included in the RCB. The top-down approach will enable the recognition of a regulatory asset or regulatory liability that encompasses these rights and obligations.
- Under the top-down approach, the unit of account for accounting for timing differences will be at a higher level than the level currently proposed by the IASB. As explained in Section 3, this will possibly also address the IASB's concerns relating to the cost of recognition.
51 The RRA TAG generally agreed with the analysis of the differences between the IASB's proposals and the top-down approach.
Question 2: What are the items that comprise the difference between RCB and PPE?
52 To determine the components of the difference between RCB and PPE for entities with no direct relationship the following list initially considers items that may be treated differently in the regulatory calculations than in the IFRS financial statements:
- Operating expenses including performance incentives (or penalties).
- Inflation adjustment.
- Difference between the regulatory depreciation and the accounting depreciation where the recovery period for an asset is different from the useful economic life.
- The split of any over- or under-spend of total regulatory allowed revenue between regulatory allowed revenue and RCB. The split is determined in the regulatory agreement, but that split may not reflect the nature of the actual expenses.
- Borrowing costs and/or asset retirement costs where they are capitalised in the IFRS financial statements but not included in RCB.
- Current assets.
Operating expenses
53 Operating expenses lead to one of the differences between RCB and PPE. This is because of the differences that may exist between the capitalisation of costs under IFRS accounting and the regulatory accounting. Under IFRS there is a split of total expenditure between operating and capital expenditure, whilst under regulatory accounting there is a split of total expenditure (‘Totex') between amounts recognised in revenue (ʻpay-as-you-go') and amounts recognised in the RCB ('non-pay-as-you-go').
54 If expenditure is recognised in the IFRS financial statements in one period the regulatory agreement may require that it is charged in a future period (in the regulated rate), creating a timing difference.
55 Performance incentives (or penalties) for the current period are included in (or deducted from) the future regulated rate charged to customers. Because the performance incentive (or penalty) relates to performance in the current period but is charged (deducted) in a future period (in the regulated rate) it is also a timing difference.
56 The items typically included in the RCB of the entities in the three UK rate-regulated sectors are included below.
Inflation
57 The inflation adjustment included in RCB is one of the differences between RCB and PPE. This is because the inflation adjustment is dealt with as a separate item in the regulatory agreement. This is a permitted adjustment by regulatory agreements within the UK as it is a part of the compensation for the return on capital.
58 In IFRS financial statements income and expense amounts may be affected by inflation but it is not a separately recognised item. For example, inflation is not permitted to be recognised in PPE. Under IAS 16 Property, Plant and Equipment, PPE is initially recognised at cost. PPE is subsequently recognised under the cost model or the revaluation model. Measurement under the revaluation model as set out in paragraph 31 of IAS 16:
"After recognition as an asset, an item of property, plant and equipment whose fair value can be measured reliably shall be carried at a revalued amount, being its fair value at the date of the revaluation less any subsequent accumulated depreciation and subsequent accumulated impairment losses.[...]"
And paragraph 6 of IAS 16 states that fair value is: "The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.”
59 Most entities do not use the revaluation model. Where an entity does use a revaluation model the amount is a fair value less accumulated depreciation and impairment losses.
60 Because the inflation adjustment relates to goods or services provided in the current period but is charged in a future period (in the regulated rate) it is a timing difference.
UK rate-regulated sectors
61 The UK rate-regulated sectors that are thought to be in the scope of the ED are:
- The UK water sector, regulated by the Water Services Regulation Authority (Ofwat).
- The UK energy sector (specifically transmission and distribution), regulated by the Office of Gas and Electricity Markets (Ofgem).
- The UK aviation sector (specifically one airport as well as the air traffic control service), regulated by the Civil Aviation Authority (CAA).
62 The work performed and stakeholder feedback received by the UKEB Secretariat revealed that there are some items that would typically be the main timing differences included in the RCB. These items are set out below.
Typical timing differences in the UK Water and Energy sectors
63 Ofwat and Ofgem typically include the following timing differences in the RCB:
- Differences in capitalisation of assets between PPE and RCB. Ofwat and Ofgem both operate the Totex adjustment mechanism. Under this mechanism the regulator would determine a ratio split (specific to each regulated entity) of the entity's over or underspend on total expenditure between expenditure adjusted through revenue (the industry term is 'fast money') and expenditure included in the RCB (the industry term is 'slow money'). This over or underspend forms part of the total allowed compensation (TAC) in the period the entity provided the goods or services.
- The inflation uplift of the RCB. Entities are compensated for inflation through an adjustment to the RCB.
- Differences between depreciation of assets in PPE and RCB. Both the items in a) and b) are recovered through the depreciation of the RCB. The depreciation of the RCB is included in allowed revenue in the future and therefore in future regulated rates.
Typical timing differences in the UK Aviation sector
64 The CAA typically includes the following timing difference in the RCB:
-
Airport
- Inflation indexation of the RCB. This is similar to the adjustment set out above for the water and energy sectors.
- The Traffic Risk Sharing mechanism. The revenue requirement the regulator determines for the airport is based on the number of passengers estimated to travel through the airport over every year of the price control period. The regulated rate is then calculated as a yield per passenger the airport charges the airline on which those passengers travel. If actual passenger numbers are above or below a certain level of the estimated passenger numbers, the airport over- or under-recovers on the yield per passenger and the regulator adjusts the yield per passenger for one or more future periods. This adjustment is done through revenue and through the RCB, with the split determined by the point in time in the current price control period.
- Capital expenditure incentives. Further work is required to establish the exact way in which this mechanism works.
- Cost of new debt mechanism. Further work is required to establish the exact way in which this mechanism works.
- A Reopener mechanism where the regulator may reopen historical items and include them in the RCB. Further work is required to establish the exact way in which this mechanism works.
All the above timing differences included in the RCB affect the calculation of the regulatory depreciation that is included in the revenue requirement and therefore the regulated rate in one or more future periods.
- Air traffic control service
- Inflation indexation of the RCB. This is similar to the adjustment set out above for the water and energy sectors.
- Pension costs. Further work is required to establish the exact way in which this mechanism works.
- Capital investments. Further work is required to establish the exact way in which this mechanism works.
66 The list of items was compiled using the input of the RRA TAG.
Question 3: Do the assets and liabilities arising from the top-down approach meet the definitions of regulatory assets and/or regulatory liabilities in the IASB's proposals?
IASB definitions for regulatory asset and regulatory liability
67 The IASB has defined a regulatory asset and regulatory liability in the ED as follows:
"Regulatory asset: An enforceable present right, created by a regulatory agreement, to add an amount in determining a regulated rate to be charged to customers in future periods because part of the total allowed compensation for goods or services already supplied will be included in revenue in the future.”
"Regulatory liability: An enforceable present obligation, created by a regulatory agreement, to deduct an amount in determining a regulated rate to be charged to customers in future periods because the revenue already recognised includes an amount that will provide part of the total allowed compensation for goods or services to be supplied in the future."
68 Below we consider whether the regulatory assets and regulatory liabilities arising from the top-down approach meet the key components of these definitions, namely:
- Enforceability; and
- Addition/deduction of an amount in determining the regulated rate charged to customers.
Enforceability
69 The regulatory asset definition requires “an enforceable present right, created by a regulatory agreement...”. The IASB proposals include guidance on enforceability. This includes an assessment as follows18:
- Whether there is an ability of the parties to a regulatory agreement to enforce the rights and obligations arising from the regulatory agreement.
- It depends on the legal and regulatory frameworks within the jurisdiction which an entity operates.
- The assessment is made at a point in time.
- Consideration of all reasonable and supportable evidence and the weight of that evidence.
- Consideration of the list of indicators in paragraph 27 of the ED aimed at enabling an entity to make an assessment of whether a regulatory asset or regulatory liability exists.
70 Paragraph 27 of the ED says:
"An entity determines whether a regulatory asset or regulatory liability exists using judgement considering all relevant facts and circumstances, including any:
- confirmation from the regulator of amounts to be added or deducted in determining future regulated rates;
- explicit requirements or guidelines in the regulatory agreement;
- regulatory decisions or court rulings interpreting the regulatory agreement;
- evidence that allowable expenses have been incurred;
- evidence that performance criteria leading to a performance incentive bonus or penalty have been met or have not been met;
- direct precedents—the entity's experience with the regulator's interpretation of the regulatory agreement in similar circumstances;
- indirect precedents—such as the experience of other entities regulated by the same regulator, the decisions of other regulators or court rulings in similar circumstances;
- preliminary views expressed by the regulator; or
- advice from qualified and experienced legal or other advisors.”
71 Our initial consideration is that all the above factors are present for UK rate-regulated entities. In particular, UK regulators typically express their preliminary views publicly. If so, this would mean that the regulatory agreements and the legal environment under which UK rate-regulated entities operate are enforceable.
Added to regulated rate to be charged to customers in future periods
72 The definition of a regulatory asset continues with "... to add an amount in determining a regulated rate to be charged to customers in future periods because part of the total allowed compensation for goods or services already supplied will be included in revenue in the future".
Operating expenses included in RCB
73 The proportion of total expenditure included in RCB relate to allowable expenses or performance incentives (or penalties) that are required by the regulatory agreement to be included in RCB. They relate to the goods or services supplied in the current period. The amounts are recovered (deducted) in future regulated rates through regulatory depreciation and return on capital.
70Paragraph 27 of the ED says:
"An entity determines whether a regulatory asset or regulatory liability exists using judgement considering all relevant facts and circumstances, including any:
- confirmation from the regulator of amounts to be added or deducted in determining future regulated rates;
- explicit requirements or guidelines in the regulatory agreement;
- regulatory decisions or court rulings interpreting the regulatory agreement;
- evidence that allowable expenses have been incurred;
- evidence that performance criteria leading to a performance incentive bonus or penalty have been met or have not been met;
- direct precedents—the entity's experience with the regulator's interpretation of the regulatory agreement in similar circumstances;
- indirect precedents—such as the experience of other entities regulated by the same regulator, the decisions of other regulators or court rulings in similar circumstances;
- preliminary views expressed by the regulator; or
- advice from qualified and experienced legal or other advisors.”
71Our initial consideration is that all the above factors are present for UK rate-regulated entities. In particular, UK regulators typically express their preliminary views publicly. If so, this would mean that the regulatory agreements and the legal environment under which UK rate-regulated entities operate are enforceable.
Added to regulated rate to be charged to customers in future periods
72The definition of a regulatory asset continues with "... to add an amount in determining a regulated rate to be charged to customers in future periods because part of the total allowed compensation for goods or services already supplied will be included in revenue in the future".
Operating expenses included in RCB
73The proportion of total expenditure included in RCB relate to allowable expenses or performance incentives (or penalties) that are required by the regulatory agreement to be included in RCB. They relate to the goods or services supplied in the current period. The amounts are recovered (deducted) in future regulated rates through regulatory depreciation and return on capital.
74Consequently, expenditure or performance incentives (or penalties) included in RCB meet the definition of a regulatory asset (regulatory liability).
Inflation adjustment included in RCB
75The regulatory agreement specifies that the RCB will include an inflation adjustment to the future regulated rate for the goods and services supplied in the current period. It is calculated on both the opening balance of RCB and the additions for the current year. This is how the regulatory agreement compensates the entity for the inflationary element when a real rate of return is applied to the RCB. As such, that inflation adjustment is part of total allowed compensation for goods or services supplied in that period. The amount is included in the RCB and, in agreement with the regulator, is recovered in future regulated rates charged to customers, through regulatory depreciation and return on capital.
76Consequently, the inflation adjustment included in RCB meets the IASB's definition of a regulatory asset.
RRA TAG feedback
77The RRA TAG members from the water and energy sectors stated that:
- Enforceability in the UK rate-regulated sectors is more relevant with respect to the measurement of the amounts relating the rights and obligations arising from timing differences included in the RCB. It is usually a given that the entities do have an enforceable right or obligation, but it is typically the amounts that need to be agreed with the regulators.
- Enforceability in the water sector may be more subjective as the regulator only formally agrees amounts every five years. However, entities submit annual regulatory performance reports for review to the regulator.
- Enforceability in the energy sector will be less subjective as the regulator agrees the amounts of the timing differences annually.
Question 4: Does the top-down approach meet the unit of account requirements in the IASB's proposals?
78The lowest level at which timing differences are being monitored and approved by regulators are the line of business level or total RCB level, depending on the sector. The entities submit regulatory returns to their regulators on an annual basis.
79For UK regulatory agreements, the application of paragraph 21 of Agenda Paper 9A of its December 2023 meeting seems to imply that timing differences can be grouped if it is the level at which the regulators assess the timing differences.
80The timing differences included in the RCB represent the difference in revenue that conceptually should be able to be generated by an entity's PPE and the revenue that can be generated from its RCB.
81In the UK, the way regulators for each sector track and monitor the timing differences included in the RCB is set out in the sections below.
UK water sector
82Ofwat views the RCB19 as a homogenous regulatory concept and represents one regulatory asset (the present value of future revenue) and as such is not separable or divisible. For the large water and sewage entities, Ofwat monitors and approves four business lines, each with its own RCB, within the regulatory agreement, as follows:
- water;
- wastewater;
- bioresources; and
- water resources.
83Ofwat does not have a lower level of monitoring and approval. Each of these lines of business will generally have similar expiry patterns and similar risks.
UK energy sector
84Ofgem views the RCB as "[...] a regulatory construct that reflects a company's historical investment, adjusted for inflation (currently RPI). [...] The revenues that companies are allowed to earn under their price controls include allowances for the regulatory depreciation and also for the return investors are expected to require for providing the capital."20
85For the energy entities, Ofgem monitors and approves the following business lines (in some entities these are split by geographical region), each of which having its own RCB:
- Electricity transmission.
- Electricity distribution.
- Gas transmission.
- Gas distribution.
- Offshore electricity transmission.
86Ofgem does not have a lower level of monitoring and approval. Each of these lines of business will generally have similar expiry patterns and similar risks.
UK aviation sector
87The CAA defines the RAB21 as:
"[...] regulated value of the regulated company. It is updated by investment and depreciation. The fair return to the airport operator is based on a return on the RAB."
88For the UK airport regulated by the CAA, the regulator monitors and approves the RCB as a whole and, where necessary, tracks separately certain timing differences such as the traffic risk sharing mechanism as the proportion included in the RCB depends on the timing within the price control period. Under the IASB's current proposals, the entity will be prohibited from recognising a regulatory asset or regulatory liability relating to the proportion of the timing difference included in the RCB.
89For the air traffic control services, the CAA monitors and approves the following lines of business, each of which has its own RCB:
- Flights over the UK.
- Flights for the North Atlantic service.
90Another example of allowable expenses that give rise to timing differences that are included in the RCB but tracked and monitored individually are pension costs. Under the IASB's current proposals, the entity will be prohibited from recognising a regulatory asset or regulatory liability relating to this timing difference.
Unit of account considerations under the top-down approach
91Considering the way in which UK regulators monitor and approve the timing differences included in the RCB, the top-down approach seems to meet the unit of account requirements under the IASB's proposals, more specifically in relation to the tentative decisions made in December 2023 on the grouping of timing differences. The unit of account will be at a higher level than that set out in the ED.
92This higher level for the unit of account may also have implications for the operational cost of tracking and monitoring, which could reduce if tracking is permitted for regulatory assets and regulatory liabilities at the level of line of business or total RCB level, by year.
RRA TAG feedback
93The RRA TAG generally agreed with the analysis, and the information relating to the levels at which regulators track and monitor timing differences was compiled using input from the RRA TAG.
94RRA TAG members generally also agreed that, once a regulator includes timing differences in the RCB, these items become subject to the same risks and are subject to the same expiry patterns. This is the case for all items except items tracked and monitored individually by the regulator e.g. the traffic risk sharing mechanism and the pensions costs.
Considering the appropriate unit of account for direct relationship entities
95A related issue to consider is whether, for direct relationship entities, the timing differences, although they can be tracked and monitored at asset level, are enforceable at individual timing difference level or at RCB level. Permitting a unit of account at a higher level could also reduce costs of applying the proposed ED for those entities.
Question 5: Does the top-down approach meet the recognition criteria in the IASB's proposals?
Recognition criteria in ED
96The IASB's proposals require an entity to recognise:
- "all regulatory assets and all regulatory liabilities existing at the end of the reporting period; and
- all regulatory income and all regulatory expense arising during the reporting period.”22
97Paragraph 28 of the ED proposes that if it is uncertain whether a regulatory asset or regulatory liability exists, it should be recognised if it is more likely than not that it exists. Per the IASB's proposals, this guidance is required to work in conjunction with the requirements in relation to meeting the regulatory asset and regulatory liability definition, which includes enforceability as a criterion.
Conceptual Framework
98Paragraph 5.6 of the Conceptual Framework sets out the recognition criteria that requires that an item:
- meet the definition of an asset/liability;
- provides users of accounts with relevant information that can be faithfully represented; and
- that the cost of recognition does not outweigh the benefits.
99The discussion on whether the timing differences we are considering in this paper (i.e. operating expenses, performance incentives (or penalties) and the inflation adjustment) included in RCB meet the definition of a regulatory asset or regulatory liability is addressed in Question 2 above.
100The current IASB proposals exclude the recognition of timing differences for entities with a no direct relationship because the costs of tracking individual timing differences outweigh the benefits of recognising them. The top-down approach proposes that the tracking of timing differences is undertaken at a higher unit of account – by line of business, by year – that is derived by comparing the balance of RCB and PPE. This should reduce the operational cost of tracking and monitoring of these timing differences.
Expenditure included in RCB
101For timing differences arising from expenditure allocated to the RCB and performance incentives (or penalties) included in the RCB, the definition of a regulatory asset (regulatory liability) is met (see Question 2 above).
102The assessment of whether the timing difference arising from expenditure allocated to the RCB and performance incentives (or penalties) included in the RCB, is more likely than not to exist, will in most instances be undertaken and confirmed at the same time as the assessment of whether a regulatory asset or regulatory liability exists.
103The IASB's tentative decisions have indicated that allowable expense or performance incentives included in the regulatory capital base would need to be tracked individually over time. In other words, separately from other amounts that are included in RCB. And as tracking at this individual timing difference level was deemed too costly, the IASB prohibited recognition.
Inflation adjustment included in RCB
104Because the inflation adjustment relates to goods or services provided in the current period but is charged in a future period (in the regulated rate) it is a timing difference. For the inflation adjustment, the definition of a regulatory asset is met (see Question 2 above).
105In most instances, the assessment of whether the timing difference arising from the inflation adjustment is more likely than not to exist will become apparent when assessing whether a regulatory asset or regulatory liability exists.
106The IASB's tentative decisions in December 202223 have indicated that the inflation adjustment to the RCB would need to be identified and tracked individually over time and that the entity would also need to be able to estimate the amount and timing of future cash flows arising from that regulatory asset. And as tracking at this individual timing difference level was deemed too costly, the IASB prohibited recognition.
Question 6: Can the timing differences included in the RCB be tracked and monitored?
107For this question, the UKEB Secretariat worked on establishing, for each sector, the following aspects relating to the timing differences included in the RBC:
- The nature of the differences typically included in the RCB and the lowest level at which the timing differences are tracked and monitored.
- The proportion of timing differences typically included in the RCB.
- The availability of information relating to these timing differences, i.e. whether it is publicly available.
The nature of the differences typically included in the RCB
108The analysis of the nature of the timing differences and the lowest level of tracking and monitoring is explained in Section 1.
The proportion of timing differences typically included in the RCB
109The work performed and stakeholder feedback received by the UKEB Secretariat revealed that the following approximate proportions of total timing differences are included in the RCB of the respective entities:
- UK Water sector: 60%
- UK Energy sector: 50%.
- UK Aviation sector: the proportion will vary depending on the timing within the price control period.
The availability of information relating to these timing differences
110The work performed and stakeholder feedback received by the UKEB Secretariat revealed that much of the information required for applying the top-down approach is publicly available in the UK. This section sets out an overview of the current reporting by entities. Further information can be found in Appendix C.
UK Water sector
111Entities publish a regulatory Annual Performance Report every year that contains various tables required by the regulator. This includes the variances between actual and forecast expenditure, movements in the RCB balance(s), performance against regulatory incentive mechanisms, etc.
112The entities make extensive use of alternative performance measures (APMs) and investor presentations to provide a better understanding of its underlying performance. The water regulator generally requires that the APMs are reconciled to the most directly comparable IFRS financial measures where practicable. This information is published on the entities' websites. More information on APMs entities typically publish can be found in Appendix B.
113The water regulator publishes updated RCB balances for each entity annually at the end of March. The Final Determinations24 and financial models of all entities are also available on the regulator's website.
UK Energy sector
114Entities publish a Regulatory Performance Report every year that contains various tables required by the regulator. This includes the variances between actual and forecast expenditure, movements in the RCB balance(s), performance against regulatory incentive mechanisms, etc.
115The entities make extensive use of alternative performance measures (APMs) and investor presentations to provide a better understanding of its underlying performance. The regulator generally requires that the APMs are reconciled to the most directly comparable IFRS financial measures where practicable. This information is published on the entities' websites. More information on APMs entities typically publish can be found in Appendix B.
116The Final Determinations (FD)25 and financial models of all entities are also available on the energy regulator's website.
UK Aviation sector
Airport
117The airport entity publishes Regulatory Accounts annually detailing actual against forecast performance for revenues, costs, volumes, etc. It also contains information on the RCB and reconciliations of regulatory revenue and operating costs to the underlying accounts and a reconciliation of the RCB to the 'net fixed assets' per the IFRS accounts. More information on APMs entities typically publish can be found in Appendix B.
118The aviation regulator publishes the Draft and Final Decisions26 on its website.
Air traffic control service
119The air traffic control service entity publishes Regulatory Accounts annually detailing actual against forecast performance for revenues, costs, volumes, etc. It also contains information on the RCB (e.g. movements, adjustments and potential clawbacks). More information on APMs entities typically publish can be found in Appendix B.
120The aviation regulator publishes the Draft and Final Decisions27 on its website.
Section 5: Other issues to be considered before finalisation
Remaining questions to address
121The following questions have not yet been addressed during the UKEB Secretariat's work, and would require addressing to develop the approach to a full standard setting solution:
- Does the top-down approach meet the measurement requirements in the IASB's proposals?
- Does the top-down approach meet the disclosure requirements in the IASB's proposals?
- Transition for the top-down approach28.
Appendix A: Illustrating the top-down approach - recognition
Introduction
A1A case study is provided to illustrate the top-down approach.
Case study
Background
A2The example is based on one line of business (electricity transmission) of a hypothetical entity operating in the UK energy sector.
A3Note that the top-down approach addresses only adjustments included in the RCB. Under the IASB's current proposals, all entities will be required to recognise revenue adjustments.
A4There is no direct relationship between the entity's PPE and RCB.
A5Items that constitute ‘permanent differences' are specifically excluded. For example, the following are excluded:
- Borrowing costs capitalised under IAS 23 Borrowing Costs – regulators typically do not allow for borrowing costs to be included in the RCB, which means that this cost will not be recovered from customers.
- Asset pre-funded by customers – the cost of this asset has already been included in the regulated rates charged to customers to pre-fund the construction of the asset. It will therefore not be included in the RCB as it has already been recovered from customers.
A6The impact of inflation is shown separately as the RCB is adjusted for inflation as part of the compensation earned during the period.
Fact pattern
A7All amounts are in £m.
A8Amounts per IFRS accounts at 31 March 2023:
- PPE = £15,970
- Capitalised borrowing costs of £180
- Additions to PPE = £1,260
- Assets pre-funded by customers = £100
- Depreciation = £800
- Closing PPE balance = £16,710
- Operating profit = £950
A9Amounts per regulatory performance report at 31 March 2023:
- Opening RCB balance = £15,970
- Additions to the RCB = £1,460
- Regulatory depreciation for the year = £1,220
- Inflation indexation of the RCB for the year = £1,370
- Closing RCB balance = £17,580
- Timing differences adjusted through revenue = £350 (to be added to future regulated rates)
Analysis applying the top-down approach
Timing differences adjusted through revenue
A10The top-down approach does not affect the IASB's proposals relating to timing differences adjusted through revenue. Therefore, the timing differences of £300m adjusted through revenue would be recognised as a regulatory asset and give rise to regulatory income.
Timing differences included in the RCB
| Description | PPE £m | RCB £m | Difference £m |
|---|---|---|---|
| Balance at 31 March 2023 | 16,710 | 17,580 | (870) |
| Less: Asset pre-funded by customers | (100) | N/A | (100) |
| Balance after stripping out 'permanent differences' | 16,610 | 17,580 | (970) |
| Journal entry (assuming a nil opening balance): | |||
| Dr Regulatory asset 970 | |||
| Cr Regulatory income 970 |
A11So, the net regulatory asset relating to the timing differences included in the RCB would consist of the following components:
| Item | Amount |
|---|---|
| Difference between capitalisation of additions | 200 |
| Difference between depreciation | (420) |
| Capitalised borrowing costs | (180) |
| Inflation | 1,370 |
| Total | 970 |
A12The comparison of PPE to RCB at the end of the accounting period would be analogous to an annual cohort of all timing differences included in the RCB. The regulator monitors the timing differences included in the RCB on an annual basis and considers the total RCB in determining the regulatory depreciation to be included in allowed revenue in future periods. The regulatory depreciation is therefore the way in which the timing differences included in the RCB form part of a single adjustment to the future regulated rate.
A13The entity populates the financial models required by the regulator on an annual basis and these models are reviewed by the regulator.
A14The regulatory asset would be measured in accordance with the proposals in the ED. The regulatory asset would be the amount calculated in the top-down approach, representing all timing differences included in the RCB that the entity is entitles to recover by adjusting future regulated rates, discounted to its present value using the regulatory interest rate.
A15The regulatory asset would be fulfilled and therefore unwind through the regulatory depreciation that would be included in the future regulated rates.
Alternative Performance Measures (APMs)
APMs in the absence of a standard
A16Currently, entities present a reconciliation of operating profit to regulatory financial performance by way of APMs in their annual reports and investor presentations. The entity in this example would therefore be reporting the following:
| Alternative Performance Measures: Year ended 31 March | 2023 |
|---|---|
| Operating profit | 950 |
| Timing differences adjusted through revenue | 350 |
| Difference between capitalisations of additions | 200 |
| Difference between accounting and regulatory depreciation | (420) |
| Capitalised borrowing costs | (180) |
| Inflation indexation of the RCB | 1,370 |
| Regulatory financial performance | 2,270 |
APMs under the IASB proposals
A17Under the current IASB proposals, the entity would still need to report the following information via the APMs:
| Alternative Performance Measures: Year ended 31 March | 2023 |
|---|---|
| Operating profit (£950m + £350m timing differences adjusted through revenue) | 1,300 |
| Difference between capitalisations of additions | 200 |
| Difference between accounting and regulatory depreciation | (420) |
| Capitalised borrowing costs | (180) |
| Inflation indexation of the RCB | 1,370 |
| Regulatory financial performance | 2,270 |
A18The entity would continue to use APMs to provide a reconciliation between operating profit and regulatory financial performance to show the impact of the timing differences included in the RCB that is not recognised under the IASB's current proposals.
A19If the entity cannot apply the top-down approach to recognise the enforceable rights and obligations arising from the timing differences included in the RCB, its IFRS accounts would not reflect the full total allowed compensation for the period the entity is entitled to. This means that the IFRS accounts would not reflect the underlying economics and the entity's financial performance and financial position for the period. Users of the IFRS accounts would also not be able to see the expectations of future cash flows from the regulatory asset(s) arising from the timing differences. Instead. the entity would need to continue making use of APMs to provide this very relevant information to the users.
APMs under the top-down approach
A20Under the top-down approach, the need for such APMs is expected to be removed.
A19If the entity cannot apply the top-down approach to recognise the enforceable rights and obligations arising from the timing differences included in the RCB, its IFRS accounts would not reflect the full total allowed compensation for the period the entity is entitled to. This means that the IFRS accounts would not reflect the underlying economics and the entity's financial performance and financial position for the period. Users of the IFRS accounts would also not be able to see the expectations of future cash flows from the regulatory asset(s) arising from the timing differences. Instead, the entity would need to continue making use of APMs to provide this very relevant information to the users.
APMs under the top-down approach
A20Under the top-down approach, the need for such APMs is expected to be removed.
Appendix B: Analogies to other IFRS Standards
Introduction
B1The IASB proposals require entities to track and monitor timing differences included in the RCB at asset level. The tentative decision to prohibit no direct relationship entities from recognising regulatory assets and regulatory liabilities arising from rights and obligations relating to timing differences included in the RCB is based on the IASB's concern about the tracking and monitoring of these timing differences through a ‘bottom-up' reconciliation of PPE and RCB.
B2There are a number of analogies from existing IFRS standards that could be used to address the IASB's concerns, especially on the unit of account and the IASB requirements relating to the level at which tracking and monitoring of timing differences takes place.
B3In the table below, the unit of account concept in other relevant IFRS standards is analysed and applied to Rate-regulated Activities (RRA).
| IFRS Standard APMS under the top-down approach
A19If the entity cannot apply the top-down approach to recognise the enforceable rights and obligations arising from the timing differences included in the RCB, its IFRS accounts would not reflect the full total allowed compensation for the period the entity is entitled to. This means that the IFRS accounts would not reflect the underlying economics and the entity's financial performance and financial position for the period. Users of the IFRS accounts would also not be able to see the expectations of future cash flows from the regulatory asset(s) arising from the timing differences. Instead, the entity would need to continue making use of APMs to provide this very relevant information to the users.
APMs under the top-down approach
A20Under the top-down approach, the need for such APMs is expected to be removed.
Appendix B: Analogies to other IFRS Standards
Introduction
B1The IASB proposals require entities to track and monitor timing differences included in the RCB at asset level. The tentative decision to prohibit no direct relationship entities from recognising regulatory assets and regulatory liabilities arising from rights and obligations relating to timing differences included in the RCB is based on the IASB's concern about the tracking and monitoring of these timing differences through a ‘bottom-up' reconciliation of PPE and RCB.
B2There are a number of analogies from existing IFRS standards that could be used to address the IASB's concerns, especially on the unit of account and the IASB requirements relating to the level at which tracking and monitoring of timing differences takes place.
B3In the table below, the unit of account concept in other relevant IFRS standards is analysed and applied to Rate-regulated Activities (RRA).
| IFRS Standard | Application to RRA |
|---|---|
| Conceptual Framework | |
1The Conceptual Framework (paragraph 4.51) states that a unit of account is selected to provide useful information to users of financial statements and that treating a group of rights and obligations as a single unit of account may provide more relevant information than treating each right and obligation as a separate unit of account if, for example, those rights and obligations:
|
2In UK regulatory agreement, regulators typically assess the timing differences that are included in the RCB collectively at line of business level or at total RCB level. The regulators then calculate a single adjustment to the future regulated rate in the form of the regulatory depreciation included in allowed revenue. The allowed revenue would be an indication of estimated future cash flows the entity would be entitled to. 3It is therefore clear that the characteristics set out in paragraph 4.51 seem to apply to the timing differences included in the RCB. |
| IAS 12 Income Taxes | |
| Recovery of temporary differences | 5When considering the approach of the regulators in calculating allowed revenue (and the regulated rate), rate-regulated entities recover in one regulated rate the individual timing differences included in the RCB at an aggregated level as regulatory agreements typically group timing differences and considers them to be a single adjustment to the future regulated rate. |
| 4In paragraph BC18 of the Basis for Conclusions of IAS 12 the IASB stated that the unit of account applied in determining the manner of recovery of temporary differences is the underlying asset as a whole, not the individual temporary differences. | |
| IAS 36 Impairment of Assets | |
| 6When assessing whether an asset is impaired, IAS 36 permits for the grouping of assets into cash-generating units in certain circumstances. 7Paragraph 66 of IAS 36 states: "If there is any indication that an asset may be impaired, recoverable amount shall be estimated for the individual asset. If it is not possible to estimate the recoverable amount of the individual asset, an entity shall determine the recoverable amount of the cash-generating unit to which the asset belongs (the asset's cash-generating unit)." 8A cash-generating unit is defined in paragraph 6 of IAS 36 as: "A cash-generating unit is the smallest identifiable group of assets that generates cash inflows that are largely independent of the cash inflows from other assets or groups of assets.” 9Paragraph BCZ114 of the Basis for Conclusions of IAS 36 states that, although identifying the lowest level of cash inflows for a group of assets would involve judgement, the IASC believed that the concept of cash-generating units is a matter of fact as assets work together to generate cash flows. | 10In many types of businesses, the assets on an entity would work together to generate cash flows. 11The assets of an entity providing utilities such as water or energy would collectively enable the entity to deliver the utility to customers. For example, the water reticulation system that connects reservoirs and purification plants to households would be a group of assets the entity would employ to deliver the water to customers. 12These entities typically assess the RCB at the total level or at business line level to consider whether there are any indicators that their PPE may be impaired. If the regulator decreases the value an entity's RCB, this means that the regulator expects a decrease in the value the entity will recover from customers in the future. The entities would consider this to be an indicator of impairment for the PPE of the entity. |
| IFRS 13 Fair Value Measurement | |
| 13IFRS 13 defines unit of account as: "The level at which an asset or a liability is aggregated or disaggregated in an IFRS for recognition purposes.” 14Paragraph 14 of IFRS 13 states that it depends on the unit of account whether an asset or liability is a stand-alone asset or liability or a group of assets and liabilities for recognition and disclosure purposes. It goes further to state that the unit of account for the asset or liability shall be determined in accordance with the IFRS that requires or permits the fair value measurement, except as provided in IFRS 13. 15In the Basis for Conclusions of IFRS 13, paragraph BC67 explains that some transactions relating to financial assets and financial liabilities held in a portfolio might involve grouping assets and liabilities in a way in which market participants would enter into a transaction, if the unit of account in other IFRSs does not prohibit the grouping. | 16Considering that regulatory agreements set out the terms for rate-regulated entities to provide goods or services to customers using a group of assets, namely the RCB, it is clear that the assets of a rate-regulated entity are grouped together for the purposes of the regulator making the economic decisions pertaining to the entity. This would involve the regulators agreeing the values of the RCB with the entity at line of business level or at total RCB level, depending on the sector. |
| IFRS 15 Revenue from Contracts with Customers | |
| Grouping contracts | |
| 17Paragraph 4 of IFRS 15 states: "This Standard specifies the accounting for an individual contract with a customer. However, as a practical expedient, an entity may apply this Standard to a portfolio of contracts (or performance obligations) with similar characteristics if the entity reasonably expects that the effects on the financial statements of applying this Standard to the portfolio would not differ materially from applying this Standard to the individual contracts (or performance obligations) within that portfolio. When accounting for a portfolio, an entity shall use estimates and assumptions that reflect the size and composition of the portfolio.” 18Paragraph BC69 of the Basis for Conclusions of states that the IASB "decided to include a practical expedient in paragraph 4 of IFRS 15 to acknowledge that a practical way to apply IFRS 15 to some contracts may be to use a 'portfolio approach'. The boards acknowledged that an entity would need to apply judgement in selecting the size and composition of the portfolio in such a way that the entity reasonably expects that application of the revenue recognition model to the portfolio would not differ materially from the application of the revenue recognition model to the individual contracts or performance obligations in that portfolio. In their discussions, the boards indicated that they did not intend for an entity to quantitatively evaluate each outcome and, instead, the entity should be able to take a reasonable approach to determine the portfolios that would be appropriate for its types of contracts.” | 19Rate-regulated entities, especially those providing utilities to customers, typically have large numbers of customers and apply the practical expedient in paragraph 4 of IFRS 15 and group together the contracts it has with these customers. 20Although the regulatory agreement of such an entity would contain many different regulatory adjustments that may result in timing differences, the regulatory agreements typically group timing differences and considers them to be a single adjustment to the future regulated rate. |
IASB article on IFRS 17 Insurance Contracts
Grouping contracts to reflect the economics
B4In an article29 published by the IASB ‘Investor Perspective: Insurance Contracts – Accounting to reflect economics', it is stated that “the unit of account is the cornerstone that ultimately will be responsible for many of the transparency improvements that will emerge under this new IFRS Standard".
B5The article also states that the requirements for determining the unit of account in IFRS 17 reflect the economic practice of the insurance industry as insurers account for the contracts with their customers on an aggregated basis rather than on a contract-by-contract basis.
B6Furthermore, the article explains the reason that the unit of account in IFRS 17 matters for determining the pattern of profitability with the aim to reflect trends in the profitability of a portfolio of contracts in the financial statements in a timely way while at the same time "the unit of account provides cost relief to insurers and a better reflection of the insurance economic practice, by allowing them to group insurance contracts for measurement purposes, based on the characteristics of the contracts and the insurers' approach to managing them.”
B7The article states that accounting for contracts on a group basis is a better reflection of the economics of the contracts and that "the requirements in IFRS 17 regarding the unit of account are designed to mitigate the loss of information caused by inappropriate offsetting so that financial statements faithfully represent the effect of managing insurance contracts on an aggregated level".
B8In explaining how insurance contracts will be aggregated under IFRS 17, the article states "when applying IFRS 17, an insurer will firstly identify its portfolios of insurance contracts. A portfolio of insurance contracts comprises contracts that are:
- Subject to similar risks, and
- Managed together”.
Application to RRA
B9When considering the approaches regulators in the UK take in managing the regulatory agreements, the allowed revenue (and therefore the regulated rate) an entity is entitled to will be determined at a level that aggregates certain differences in timing such as:
- regulatory depreciation on additions to the RCB that is calculated per business line, but then aggregated in one amount that goes into the allowed revenue calculation; and
- inflation indexation of the RCB that is calculated on the opening balance of the RCB per business line, but then aggregated in one amount that goes into the allowed revenue calculation.
B10The regulators in the UK does not assess the differences in timing on an individual asset level but rather considers the following:
- For the inflation indexation, the opening balance of the RCB at business line level or at total RCB level; and
- For the regulatory depreciation, the opening balance of the RCB and the additions to the RCB at business line level or at total RCB level.
Appendix C: Information currently reported by UK rate-regulated entities using alternative performance measures
Introduction
C1This appendix details the information regulated entities in the UK currently report by way of alternative performance measures (APMs), regulatory reporting, investor presentations and where this information can be found. The information is set out by sector.
UK rate-regulated sectors
UK water sector
Alternative Performance Measures and other reporting measures
C2UK water entities typically report the following information by way of APMs and/or investor presentations:
- Return on regulatory equity.
- RCB movements during the year and closing balance.
- RCB gearing.
- Underlying profit.
Location of information
C3The tables that can be found for each regulated entity which include information relating to RCB regulatory timing differences for an Ofwat-regulated entity are set out below:
| Item | Found here |
|---|---|
| Regulatory agreement. | Ofwat website - Final Determinations for PR19: https://www.ofwat.gov.uk/regulated-companies/price-review/2019-price-review/final-determinations/ |
Timing differences recognised in RCB:
|
Ofwat website – Price reviews for all price control periods: https://www.ofwat.gov.uk/regulated-companies/price-review/Ofwat website – Regulatory Capital Value Updates: https://www.ofwat.gov.uk/publications/regulatory-capital-value-updates/ |
| Depreciation of RCB is in RCB reconciliation (called run-off) and calculation of allowed revenue is set out in handbook. | Ofwat website - Financial model and rulebook for PR19: https://www.ofwat.gov.uk/regulated-companies/price-review/2019-price-review/data-tables-models/ - RCV run-off is on the 'RCV balance Summary' tab.Ofwat website – RCV adjustments feeder model for PR19: https://www.ofwat.gov.uk/publication/pr19-rcv-adjustments-feeder-model-published-june-2018/ – Indexation of the RCV is on the 'Calc' tab. |
| Allowed revenue includes the depreciation of RCB. | Ofwat website - Financial model and rulebook for PR19: https://www.ofwat.gov.uk/regulated-companies/price-review/2019-price-review/data-tables-models/Allowed revenue calculation:
|
UK energy sector
Alternative Performance Measures and other reporting measures
C4UK energy entities typically report the following information by way of APMs and regulatory performance measures (RPMs):
- Timing impacts of regulatory adjustments.
- Reconciliations of financial results to regulatory results, including:
- Adjusted operating profit to Regulated financial performance. The reconciling items include revenue adjustments, indexation of the RCB, regulatory vs IFRS depreciation difference, additions to the RCB, deferred tax adjustment.
- RCB balances for each regulated business.
- Regulatory financial position.
- Return on regulatory equity.
- RCB movements during the year and closing balance.
Location of information
C5The tables that can be found for each regulated entity which include information relating to RCB regulatory timing differences for an Ofgem-regulated entity are set out below:
| Item | Found here |
|---|---|
| Regulatory agreements. | Ofgem website: https://www.ofgem.gov.uk/industry-licensing/licences-and-licence-conditions |
Timing differences recognised in RCB:
|
Ofgem website – ED2 Price Control Financial Model: https://www.ofgem.gov.uk/publications/ed2-price-control-financial-model |
| Calculation of allowed revenue, including depreciation of the RCB set out in handbook. | Ofgem website – Financial model and rulebook for ED2: https://www.ofgem.gov.uk/sites/default/files/2023-02/ED2%20PCFH%20V1.pdf |
UK aviation sector
Alternative Performance Measures and other reporting measures
C6The UK airport entities typically report the following information by way of APMs:
- RCB balance.
- Regulatory gearing ratio.
C7The UK air traffic control services report certain information by way of APMS "[...] in order to provide better insight for managing our financial performance, we have adopted a number of non-IFRS measures: adjusted revenue and revenue allowances, adjusted profit before tax, debt-adjusted cash flows (DACF), net debt, the regulatory asset base (RAB), regulatory return (adjusted) and gearing. These alternative performance measures (APMs) are not defined by international financial reporting standards (IFRS) and should be considered in addition to, and are not intended to be a substitute for, IFRS and statutory measures. "31 A reconciliation of the APMs to IFRS measures is provided in the annual report.
Location of information
C8The tables that can be found for each regulated entity which include information relating to RCB regulatory timing differences for an Ofgem-regulated entity are set out below:
| Item | Found here |
|---|---|
| Regulatory agreement. | CAA website: Airport - https://www.caa.co.uk/commercial-industry/airports/economic-regulation/h7/consultations/final-and-initial-proposals-for-h7-price-control/ Air traffic control - https://www.caa.co.uk/commercial-industry/airspace/air-traffic-management-and-air-navigational-services/air-navigation-services/nats-en-route-plc-nerl-licence/ |
| Timing differences recognised in RCB: | Airport - https://www.heathrow.com/content/dam/heathrow/web/common/documents/company/investor/reports-and-presentations/annual-accounts/sp/2023_Heathrow_SP_Regulatory_Accounts.pdf Air traffic control - https://www.nats.aero/investors/annual-report-accounts/ |
Contact Us
UK Endorsement Board 6th Floor
| 10 South Colonnade | London | E14 4PU www.endorsement-board.uk
Footnotes
-
Excluding inflation for entities whose PPE and RCB have not direct relationship does not create parity between the two models. In the nominal rate model (cost-based regimes where entities' PPE and RCB would typically have a direct relationship) inflation is recovered in the period through revenue as the return on capital component in revenue is the nominal (real + inflation) return. In the real rate model (incentive-based regimes where entities' PPE and RCB would typically have no direct relationship) inflation is recovered through revenue in the future. The in-period return on capital component in revenue is only the real return. ↩
-
IASB Agenda Paper 9D - December 2022. ↩
-
Page 22 of IASB Agenda Paper 9A - May 2022. ↩
-
Other possible terms are 'revenue requirement' and 'authorised revenue' - IASB Agenda Paper 9A of May 2022. ↩
-
Cost-based schemes are defined in the IASB's Agenda Paper 9A (May 2022) as: "A form of regulation for setting an entity's prices (rates) in which there is a cause-and-effect relationship between the entity's specific costs and its revenues." ↩
-
The IASB's Agenda Paper 9A (May 2022) does not contain a definition, but states that, in theory the "Regulator sets ex ante a fixed rate for the service to be provided by the entity, who is then incentivised to optimise its processes since it will increase profits by reducing costs" and "...the components of allowed revenue may not always have a direct link with accounting expenses" ↩
-
The UKEB Secretariat's current understanding is that items affecting regulated rates only when the cash is paid or received will also be treated the same way for all entities. ↩
-
Paragraph 23, IASB paper 9C, December 2022: https://www.ifrs.org/content/dam/ifrs/meetings/2022/december/iasb/ap9c-other-items-included-in-the-regulatory-capital-base.pdf ↩
-
Paragraph 48, IASB paper 9A, December 2022: https://www.ifrs.org/content/dam/ifrs/meetings/2022/december/iasb/ap9a-inflation.pdf ↩
-
Page 19, IASB paper 9B, September 2023: https://www.ifrs.org/content/dam/ifrs/meetings/2023/september/iasb/ap9b-the-direct-no-direct-relationship-concept-report-on-findings-from-the-survey.pdf ↩
-
Paragraph 24, IASB paper 9B, September 2023 notes: "In 21 surveys, the respondents have concluded that their entities' regulatory capital base and property, plant and equipment had a direct relationship." And paragraph 36 of the same paper notes: "In 20 surveys, the respondents concluded that their regulatory capital base and their property, plant and equipment had no direct relationship." ↩
-
IASB Agenda Paper 9A - May 2022. ↩
-
IASB Agenda Paper 9A – December 2022. ↩
-
Paragraph 16, IASB Paper 9A, December 2022: https://www.ifrs.org/content/dam/ifrs/meetings/2022/december/iasb/ap9a-inflation.pdf ↩
-
IASB Agenda Paper 9A - December 2023. ↩
-
So, if the residual difference is set as RD, at the end of the first period and assuming the depreciation rate was 5% with a 2% inflation environment then at the end of the following year RD₁ = RD₀ x 0.95 x 1.02. This calculation takes into account the opening balance of the regulatory asset, deducts the depreciation for the first year and adds the inflation indexation the entity is entitled to for that year. At the end of the second period, one needs to work out the difference between the RCB and PPE and calculate the new balance as RD₂ = RCB - PPE - RD₁ and so forth. This calculation therefore takes the updated residual difference between RCB and PPE at the end of year 2 and deducts the residual difference at the end of year 1 in order to keep separate the proportion of the regulatory asset or regulatory liability relating to each period. This approach will enable the entity to evidence the full unwind of each annual adjustment. ↩
-
UKEB Agenda Paper 7 - May 2024. ↩
-
Summary of paragraph 34, IASB paper 9C, February 2023: https://www.ifrs.org/content/dam/ifrs/meetings/2023/february/iasb/ap9c-enforceability-and-recognition.pdf ↩
-
The term used in the UK water sector for RCB is regulatory capital value (RCV). ↩
-
Ofwat Glossary of Terms defines the term 'regulatory asset value (RAV) as this is the term the UK energy sector uses for the RCB. ↩
-
Regulatory asset base (RAB) is the term used for RCB in the UK aviation sector. It is defined in the CAA Glossary. ↩
-
Paragraph 25 of the ED. ↩
-
Paragraph 39 of IASB Agenda Paper 9A, December 2022. ↩
-
A Final Determination is agreed with the regulator for each five-year price control period. The documents relating to the Ofwat PR24 price review can be found here: https://www.ofwat.gov.uk/regulated-companies/price-review/2024-price-review/ ↩
-
A Final Determination is agreed with the regulator for each five-year price control period. The documents relating to the Ofgem ED2 Price Control Financial Model can be found here: https://www.ofgem.gov.uk/publications/ed2-price-control-financial-model ↩
-
The CAA's documents relating to the UK airport's H7 Final decision can be found here: https://www.caa.co.uk/commercial-industry/airports/economic-regulation/h7/consultations/final-and-initial-proposals-for-h7-price-control/ ↩
-
The CAA's documents relating to the UK air traffic control service (NR23 Price Control Final decision) can be found here: https://www.caa.co.uk/commercial-industry/airspace/air-traffic-management-and-air-navigational-services/air-navigation-services/nats-en-route-plc-nerl-licence/ ↩
-
Note: At the timing of writing, the IASB had not finalised its deliberations in relation to transition provisions for the requirements in the proposed Standard. ↩
-
IASB article – April 2018. ↩
-
In broad terms, additions are items constituting capital expenditure. ↩
-
Page 14: https://www.nats.aero/wp-content/uploads/2024/06/AR-24.pdf ↩