5 ED Business Combinations–Disclosures, Goodwill and Impairment (Proposed Amendments to IFRS 3 and IAS 36)
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
Purpose of the paper
The purpose of this paper is to obtain the Board's:
- approval to issue a Final Comment Letter (FCL) (Appendix A) in response to the IASB Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment Proposed amendments to IFRS 3 and IAS 36 (the ED);
- approval for the publication of the Feedback Statement (Appendix C); and
- feedback on the draft Due Process Compliance Statement (DPCS) (Appendix D).
Summary of the Issue
The IASB issued the ED on 14 March 2024 with a 120-day comment period ending 15 July
- The ED provides a package of proposed amendments to:
- the disclosure requirements in IFRS 3 Business Combinations, to improve the information that entities provide about business combinations and therefore increase the usefulness of the financial statements; and
- IAS 36 Impairment of Assets, to reduce the cost and complexity of the impairment test, and address concerns around impairment losses being recognised too late.
The UKEB's Draft Comment Letter (DCL) was published for stakeholder comment on 31 May
- This consultation closed on 1 July 2024.
Changes to the DCL resulting from feedback received are summarised in paragraph 10 of the paper.
Decisions for the Board
Subject to any amendments arising at this meeting, does the Board approve:
- The FCL (Appendix A) for issue to the IASB and publication on the UKEB website?
- The Feedback Statement (Appendix C) for publication on the UKEB website?
In addition, the Board is asked whether it has any comments on the draft DPCS for the project.
Recommendation
The Secretariat recommends that, subject to any amendments at this meeting, the Board approves the FCL and the Feedback Statement for issue and publication.
Appendices
| Appendix A | Final Comment Letter – clean copy |
| Appendix B | Final Comment Letter – marked up with changes from DCL |
| Appendix C | Feedback Statement |
| Appendix D | [Draft] Due Process Compliance Statement |
Background
1In this project, the IASB seeks to improve the information that entities provide to users of financial statements, at a reasonable cost, about the business combinations those entities make.
2The ED provides a package of proposed amendments to:
- the disclosure requirements in IFRS 3 Business Combinations, and
- IAS 36 Impairment of Assets, to reduce the cost and complexity of the impairment test, and address concerns around impairment losses being recognised too late.
3The IASB issued the ED on 14 March 2024 with a comment period ending 15 July 2024.
4The UKEB Draft Comment Letter (DCL) was published on the UKEB website on 31 May 2024, with a comment deadline of 1 July 2024.
5The DCL was broadly supportive of the package of proposed amendments, but provided observations and recommendations on a number of areas identified by our analysis or raised by UK stakeholders.
Outreach and feedback on the DCL
6Four written responses to the DCL were received, two from accounting firms, one from a preparer, and one from an industry body. The responses are available on the UKEB project webpage. As we held a number of meetings with stakeholders in developing the DCL, and the publication of the DCL was given little publicity due to the pre-election period, the small number of formal responses is not unexpected.
7Outreach to inform the comment letter included:
- discussions with the following UKEB Advisory Groups:
- Academic Advisory Group – 12 April 2024
- Accounting Firms and Institutes Advisory Group – 14 March 2024 and 1 July 2024;
- Investor Advisory Group – 26 February 2024;
- Preparer Advisory Group – 5 March 2024;
- Joint Investor Advisory Group & Preparer Advisory Group session – 10 June 2024;
- a virtual roundtable event with users of financial statements (which was extended to preparers, at the recommendation of the Board in April 2024), hosted jointly with the IASB; and
- one-to-one virtual interviews with preparers of financial statements, the majority of interviews being attended by the IASB.
8Although many stakeholders agreed with the UKEB draft position, there continue to be mixed views on the ED proposals and on some of the UKEB recommendations. However, there was no substantive new evidence, resulting in few changes to the DCL.
9To assist Board member review, changes to the DCL (excluding formatting and minor editorial changes) have been shown in a tracked changes version of the FCL (Appendix B).
10The table below presents a summary of the main points of feedback received during the consultation period for the UKEB's DCL and the changes proposed to the comment letter in the light of that feedback.
| Topic | Summary of stakeholder feedback / proposed change | Paragraph reference within FCL (DCL) |
|---|---|---|
| Disclosures: Strategic business combinations | Updated suggestion that the IASB consider other terms, as opposed to 'strategic', for the subset of the most important material business combinations, as some stakeholders did not agree with the term 'major' | 7, A7 |
| Disclosures: Strategic business combinations | Added a suggestion that the IASB consider how an entity disclose a series of 'strategic' acquisitions that takes place over different reporting periods. | New paragraph A14 |
| Disclosures: Strategic business combinations | Added academic research data that suggests 25% of UK acquisitions would be caught using the proposed thresholds | New paragraph A16 |
| Disclosures: Strategic business combinations | Clarified that the UKEB proposed threshold of market capitalisation is relative i.e. 10% | A17 (DCL A15) |
| Disclosures: Strategic business combinations | Deleted suggestion to the IASB to provide examples for applying materiality to qualitative thresholds, as considered unnecessary, given that materiality is an overriding concept when considering inclusion or exclusion of information in financial statements | A23c) (DCL A21c)) |
| Disclosures: Exemption from disclosing information | Clarified the UKEB suggestion that an entity should not be required to disclose the reason for applying the exemption, to include that an entity should still be required to disclose that it has applied the exemption, for example, for some key objectives and related targets, as users need that information | A5 |
| Disclosures: Other proposals in IFRS 3 | Added a suggestion that the IASB clarifies that the management approach applies to the quantitative information on expected synergies, such that disclosure should only be required where synergies drive the rationale for the acquisition, and that it is not expected that such information is prepared solely for the purpose of disclosing in the financial statements. | A40 (DCL A38) |
| Changes to the impairment test in IAS 36 | Deleted the UKEB suggestion to require disclosure of headroom where marginal, as most stakeholders thought existing requirements to disclose key assumptions and sensitivity analysis were adequate | 13, A58 (DCL A56) |
| Changes to the impairment test in IAS 36 | Added suggestion for entities to disclose changes in CGUs from the prior reporting period | A59 |
| Changes to the impairment test in IAS 36: Value in use calculation | Added a recommendation that the IASB provide guidance on what the resulting difference is between VIU and FVLCD following the proposed amendments to IAS 36 and why they should still be viewed differently | A65 |
| Changes to the impairment test in IAS 36: Value in use calculation | Enhanced the UKEB recommendation to disclose when uncommitted restructuring cashflows are included in recoverable amount (VIU), by suggesting the disclosure includes the fact, the nature, the amounts and expected timing of the restructuring | A63 (DCL A60) |
Final Comment Letter (FCL)
11The FCL is attached as Appendix A for consideration and, subject to any amendments, the Board is asked to approve for issue to the IASB and publication on the UKEB website.
Feedback Statement
12The Feedback Statement is attached for consideration, and, subject to any amendments at this meeting, the Board is asked to approve for publication on the UKEB website.
[Draft] Due Process Compliance Statement (DPCS)
13The [draft] DPCS is attached for consideration. A final version will be brought back to the 19 September 2024 meeting for noting, once the final project steps are complete.
Questions for the Board
- Subject to any amendments arising at this meeting, does the Board approve:
- The FCL (Appendix A) for issue to the IASB and publication on the UKEB website?
- The Feedback Statement (Appendix C) for publication on the UKEB website?
- Does the Board have any comments on the draft DPCS for the project?
Next steps
14The FCL will be submitted to the IASB as soon as possible after this Board meeting. The FCL together with the Feedback Statement will be published on the UKEB project webpage. The draft DPCS will be updated to reflect the final project steps and presented to the Board at the 19 September 2024 meeting for noting.
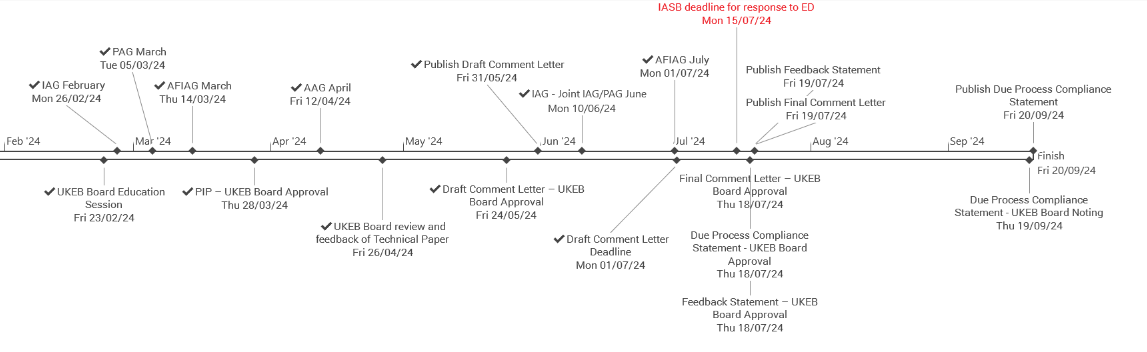
Timeline
Appendix A: UKEB response to detailed questions in IASB Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
Dr Andreas Barckow Chair International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
[Date]
Dear Dr Barckow
Invitation to Comment: Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.1 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.2
3The UKEB welcomes the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment. In developing this letter, we consulted with stakeholders in the UK, including preparers, accounting firms and institutes, academics, and users of financial statements.
4The UKEB is broadly supportive of the package of proposed amendments to the disclosure requirements in IFRS 3 Business Combinations and the impairment test in IAS 36 Impairment of Assets. The proposed amendments would provide investors with better information about the post-acquisition performance of acquired entities.
5Our main observations and recommendations, reflecting our UKEB outreach3 and desk-based research4, are set out in the paragraphs that follow.
Proposed amendments to IFRS 3 Business Combinations
Identifying the most important business combinations
6The UKEB broadly supports the IASB's proposals to require disclosure of information about the performance of business combinations, based on the acquirer's acquisition-date key metrics and related targets, for only a subset of the most important business combinations (the so-called 'strategic' business combinations) (see paragraphs A1–A6). We consider this strikes the right balance between the needs of users and the costs to preparers.
Terminology - strategic or major
7We consider that the use of the term 'strategic acquisitions' does not reflect the transactions for which users are keen to obtain additional disclosures. Preparers tell us that they only undertake acquisitions if they are strategic. We understand from users that they would prefer additional, meaningful disclosures for acquisitions that are substantive for the business, and which will allow them to hold management to account. As such, we consider that another term, such as 'major', 'substantial' or 'significant' may be more appropriate than 'strategic' to describe this subset of the most important business combinations (see paragraph A7)
Principles-based identification
8In addition, we consider that using only the proposed exhaustive list of quantitative and qualitative thresholds (the closed threshold approach), may not capture the most important acquisitions from a user's perspective. Instead, we recommend a principles-based approach to identifying the most important business combinations and set out a possible process to achieve this in Appendix B to this letter. Our recommendation is that a subset of acquisitions ('strategic' acquisitions) is identified by first applying both the quantitative and qualitative thresholds, as per the IASB's proposal. However, where an acquisition meets one or more of the qualitative or quantitative thresholds, an entity should be able to rebut the presumption that the acquisition is 'strategic' if it can demonstrate that the acquisition does not meet the overall description set out in paragraph BC54. The entity would be required to disclose the reason for the rebuttal and the acquisition would then not be subject to the additional disclosures for 'strategic' business combinations. This also demonstrates the importance of the description in paragraph BC54, which we recommend should be included in the standard itself.
9We consider that if the IASB proceeds with a principles-based approach, there would be less concern over the proposed thresholds (see paragraphs A15–A21 and A22–A23), due to the focus on the description in the Basis for Conclusions paragraph BC54.
Seriously Prejudicial Exemption
10The UKEB welcomes the proposal that an entity be exempt from disclosing some information if doing so can be expected to prejudice seriously the achievement of any of the entity's acquisition-date key objectives for the business combination (see paragraphs A24–A33). This should address some of the concerns from preparers about the cost and commercial sensitivity of disclosing information about material business combinations and 'strategic' business combinations.
11However, to ensure the appropriate application of the exemption, the UKEB recommends that the IASB clarifies that the exemption would only be used in 'extremely rare cases'. Other suggestions to assist in the application of the exemption are included under question 3 in appendix A.
Proposed amendments to IAS 36 Impairment of Assets
12We support the proposed amendments to IAS 36 that clarify the allocation of goodwill to cash-generating units (CGUs) (see paragraphs A54–A55) and require disclosure of the reportable segments that include a CGU or group of CGUs containing goodwill (see paragraphs A56–A59). However, we have some reservations about the extent to which these proposals will achieve the intended change.
13The UKEB broadly supports the IASB's efforts to reduce the cost and complexity of the impairment test and the proposed changes to the calculation of value in use (see paragraphs A60–A65), which applies to all assets tested for impairment in accordance with IAS 36. However, the UKEB recommends that the IASB introduce some disclosure requirements to address the risk that management use optimistic inputs when calculating value in use that could avoid or further delay the recognition of impairment losses, as discussed in more detail under question 7 in appendix A.
14Responses to the IASB's specific questions about the ED proposals are included in appendix A to this letter.
15If you have any questions about this response, please contact the UKEB project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: UKEB response to detailed questions in IASB Exposure Draft IASB/ED/2024/1 Business Combinations—Disclosures, Goodwill and Impairment Appendix B: Proposed Flowchart
- determination of 'strategic' business combinations
Proposed amendments to IFRS 3 Business Combinations
Disclosures: Performance of a business combination
Question 1—Disclosures: Performance of a business combination (proposed paragraphs B67A–B67G of IFRS 3)
In the PIR of IFRS 3 and in responses to the Discussion Paper the IASB heard that:
- users need better information about business combinations to help them assess whether the price an entity paid for a business combination is reasonable and how the business combination performed after acquisition. In particular, users said they need information to help them assess the performance of a business combination against the targets the entity set at the time the business combination occurred (see paragraphs BC18–BC21).
- preparers of financial statements are concerned about the cost of disclosing that information. In particular, preparers said the information would be so commercially sensitive that its disclosure in financial statements should not be required and disclosing this information could expose an entity to increased litigation risk (see paragraph BC22).
Having considered this feedback, the IASB is proposing changes to the disclosure requirements in IFRS 3 that, in its view, appropriately balance the benefits and costs of requiring an entity to disclose this information. It therefore expects that the proposed disclosure requirements would provide users with more useful information about the performance of a business combination at a reasonable cost.
In particular, the IASB is proposing to require an entity to disclose information about the entity's acquisition-date key objectives and related targets for a business combination and whether these key objectives and related targets are being met (information about the performance of a business combination). The IASB has responded to preparers' concerns about disclosing that information by proposing:
- to require this information for only a subset of an entity's business combinations—strategic business combinations (see question 2); and
- to exempt entities from disclosing some items of this information in specific circumstances (see question 3).
- Do you agree with the IASB's proposal to require an entity to disclose information about the performance of a strategic business combination, subject to an exemption? Why or why not? In responding, please consider whether the proposals appropriately balance the benefits of requiring an entity to disclose the information with the costs of doing so.
- If you disagree with the proposal, what specific changes would you suggest to provide users with more useful information about the performance of a business combination at a reasonable cost?
Disclosure objective
A1The UKEB agrees with the IASB's objective for the disclosure proposals – to provide users with information to help them assess the post-acquisition performance of a business combination at a reasonable cost. Users of accounts tell us that they would like entities to provide better information on business combinations, in particular to help them assess performance after acquisition, against acquisition-date key objectives and related targets.5
A2The UKEB supports the IASB's proposal to require an entity to disclose information about the performance of only 'strategic' business combinations (see Question 2 of this appendix) and support the proposal of an exemption (see Question 3 of this appendix). The IASB's proposal to limit the requirement for performance information to a subset of the most important business combinations may help achieve the balance between user's needs and preparers' concerns about the cost of providing the information.6
Commercially sensitive information
A3However, UK preparers still have some concerns about the risk of commercially sensitive information being disclosed, exposing them to increased litigation risk and potentially obscuring material information, all delivered at significant costs.
A4They note that the proposed requirement to disclose the key objectives and targets to which the exemption has been applied and the reason for applying the exemption to each item, in itself risks disclosure of potentially seriously prejudicial and commercially sensitive information.
A5We consider that one way to counteract this risk may be to remove the requirement for an entity to disclose the reason for invoking the exemption in a reporting period, where doing so is itself seriously prejudicial and commercially sensitive, whilst still disclosing that an exemption has been applied for some key objectives and/or related targets. The IASB could consider including additional requirements for the entity to disclose the reason for invoking the exemption at a future reporting date when the reason is no longer seriously prejudicial. This should ensure that users of accounts are provided with relevant information to assess management's stewardship and rationale at the earliest opportunity without exposing entities to litigation risk.
Integration of acquired business
A6If an entity plans to integrate the acquired business, those disclosures against acquisition-date key objectives will be based on a combined business, since information about the acquired business in isolation may not be available. Some preparers questioned the usefulness of combined information on subsequent performance. However, users welcomed the proposals, and noted that often acquired business are integrated within a relatively short period of time after acquisition and therefore expected that key objectives and related targets would be for a combined business.
Disclosures: Strategic business combinations
Question 2—Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
The IASB is proposing to require an entity to disclose information about the performance of a business combination (that is, information about the entity's acquisition-date key objectives and related targets for the business combination and whether these key objectives and related targets are being met) for only strategic business combinations—a subset of material business combinations. A strategic business combination would be one for which failure to meet any one of an entity's
Integration of acquired business
A6If an entity plans to integrate the acquired business, those disclosures against acquisition-date key objectives will be based on a combined business, since information about the acquired business in isolation may not be available. Some preparers questioned the usefulness of combined information on subsequent performance. However, users welcomed the proposals, and noted that often acquired business are integrated within a relatively short period of time after acquisition and therefore expected that key objectives and related targets would be for a combined business.
Disclosures: Strategic business combinations
Question 2—Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
The IASB is proposing to require an entity to disclose information about the performance of a business combination (that is, information about the entity's acquisition-date key objectives and related targets for the business combination and whether these key objectives and related targets are being met) for only strategic business combinations—a subset of material business combinations. A strategic business combination would be one for which failure to meet any one of an entity’s acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy.
The IASB is proposing that entities identify a strategic business combination using a set of thresholds in IFRS 3—a business combination that met any one of these thresholds would be considered a strategic business combination (threshold approach) (see paragraphs BC56–BC73).
The IASB based its proposed thresholds on other requirements in IFRS Accounting Standards and the thresholds regulators use to identify particularly important transactions for which an entity is required to take additional steps such as providing more information or holding a shareholder vote. The proposed thresholds are both quantitative (see paragraphs BC63–BC67) and qualitative (see paragraphs BC68–BC70).
- Do you agree with the proposal to use a threshold approach? Why or why not? If you disagree with the proposal, what approach would you suggest and why?
- If you agree with the proposal to use a threshold approach, do you agree with the proposed thresholds? Why or why not? If not, what thresholds would you suggest and why?
Terminology – strategic or major
A7We consider that the concept of ‘strategic' business combinations does not reflect the transactions for which users are keen to obtain additional disclosures. Preparers tell us that they undertake acquisitions only if they are strategic. We understand from users that they would prefer additional, meaningful disclosures for acquisitions that are substantive for the business, and which will allow them to hold management to account. As such, we consider that another term, such as ‘major’, ‘substantial’ or ‘significant’ may be more appropriate than ‘strategic’ to describe the subset of the most important business combinations.
Principles-based identification
A8The UKEB is concerned that using only the proposed exhaustive list of quantitative and qualitative thresholds (the closed threshold approach), may not capture the most important acquisitions from a user perspective. Instead, we would recommend a principles-based approach to identifying the most important business combinations and we set out a possible process to achieve this in appendix B to this letter. Our recommendation is that a subset of ‘strategic’ acquisitions is identified by first applying both the quantitative and qualitative thresholds, as per the IASB’s proposal. However, where an acquisition meets one or more of the qualitative or quantitative thresholds, an entity should be able to rebut the presumption that the acquisition is ‘strategic’ if it can demonstrate that the acquisition does not meet the overall description set out in paragraph BC54. The entity would be required to disclose the reason for the rebuttal and the acquisition would then not be subject to the additional disclosures for ‘strategic’ business combinations. This also demonstrates the importance of the description in paragraph BC54, which we recommend should be included in the standard itself.
A9We consider that if the IASB proceeds with a principles-based approach, there would be less concern over the proposed thresholds, (see paragraphs A15–A21 and A22–A23), due to the focus on the description in the Basis for Conclusions paragraph BC54.
Series of acquisitions
A10Users of financial statements also want information about a ‘series’ of business combinations that are collectively ‘strategic’7, as they have been acquired to achieve the same strategic objective, even if they do not meet the qualitative or quantitative thresholds individually.
A11Existing disclosure requirements for each material business combination in IFRS 3 relate to individually material or collectively material acquisitions8, therefore it would seem logical to extend this approach to ‘strategic’ business combinations that are collectively ‘strategic’.
A12The IASB acknowledged this when devising these proposals. In the Basis for Conclusions (paragraph BC73), the IASB noted that the qualitative thresholds might at least help an entity to identify the first in a series of business combinations entered into to achieve the same strategic objective. For example, the first in a series of business combinations could result in an entity entering into a new line of business or geographical area, enabling the acquisition of other businesses in the future.
A13The UKEB recommends that, since a company will be required to disclose the strategic rationale for each material business combination, the IASB could extend this requirement to disclose:
- those material acquisitions with the same strategic rationale; and
- whether or not an entity considers this series of acquisitions with the same strategic rationale to be ‘strategic’ (or ‘major’), and if so, disclose the key objectives for that series at the acquisition date of the first in the series.
This will ensure that:
- users receive a full picture of ‘strategic’ acquisitions undertaken by the entity; and
- the disclosures reflect how management will monitor the combined businesses with a similar objective e.g. increase in market share in a specific geographical area.
A14The IASB should give consideration as to how a company might disclose a series of ‘strategic’ acquisitions where they occur over different reporting periods.
Quantitative thresholds
A15Whilst the quantitative threshold of 10% may be seen as too low by some stakeholders, overall, the UKEB is supportive, as they appear reasonable when compared with thresholds used by regulators and auditors across different jurisdictions in identifying important business combinations.
A16Academic research9 suggests that approximately 25% of acquisitions in the UK would likely be classified as ‘strategic’ using only the proposed thresholds.
A17In response to stakeholder feedback, we recommend that the IASB add market capitalisation (where relevant) to the list of quantitative thresholds. Note that this suggested additional threshold has been included in Figure 1 in appendix B, which sets out our recommended principles-based approach described in paragraph A8 above. We suggest a threshold of 10% of market capitalisation.
A18Stakeholders highlighted concerns with the use of both ‘revenue’ and ‘operating profit’ (as defined by IFRS 18 Presentation and Disclosure in Financial Statements) to determine a ‘strategic’ business combination, due to the volatile nature of such metrics, and noted the following:
- if either the acquirer or acquiree had exceptional items in the year prior to the acquisition, the metrics at the end of the reporting period prior to the acquisition, used for the threshold assessment, could be distorted.
- the apparent inconsistency with the synergy categories proposed for quantitative information on expected synergies, when, for example, the strategic rationale for an acquisition might be the achievement of tax synergies.
A19Some stakeholders suggested using ‘operating profit before exceptional items’, as opposed to ‘operating profit’. However, the rebuttable presumption method, recommended in paragraph A8 above, should mitigate any such concerns with applying the quantitative thresholds.
Step acquisitions
A20During our outreach, some stakeholders were unclear on how the quantitative thresholds would apply to partial10 acquisitions and step11 acquisitions. The UKEB understands that the proposals will require the thresholds to be applied to the total holding. For example, in a partial acquisition, if an entity acquires 60% of the acquiree, IFRS 3 requires that 100% is consolidated (with a non-controlling interest of 40%), and the quantitative thresholds would be applied to the 100% of revenue, operating profit and assets (including goodwill), and not the 60%. Similarly in a step acquisition, where, for example, an acquirer has a 40% holding and increases its holding to 60%, the thresholds would apply to the 100% of the acquiree’s relative amounts (and not 60%, nor the 20% incremental holding).
A21We recommend that application guidance be added to the standard to clarify the treatment of such partial and step acquisitions, to ensure there is no diversity in practice.
Qualitative thresholds
A22The IASB’s proposed qualitative thresholds are aimed at capturing business combinations that would represent a strategic shift for an entity, but that would not be captured by the quantitative thresholds. Our outreach identified some concerns with applying the qualitative thresholds, as set out in paragraph A23 below. We consider that our recommendation of a principle-based approach set out in paragraph A8 above would alleviate some of the concerns and ensure that the qualitative thresholds capture the relevant business combinations.
A23However, should the IASB proceed with the proposed approach in the ED, it should be aware of the following concerns and related recommendations:
- a lack of clarity amongst stakeholders in relation to the qualitative thresholds, arising from the inconsistency between the ED (see application guidance paragraph B67C12) and the Basis for Conclusions (see paragraphs BC5513 and BC6814). The UKEB recommends the IASB clarify the thresholds by preceding both ‘line of business’ and ‘geographical area’ with the word ‘new’ or ‘new major’, depending upon intended requirements15. Whilst we understand that the proposed thresholds are based on IFRS 5 requirements, the UKEB suggests that the words ‘new major’ should relate to both line of business and geographical area, since a ‘new’ geographical area in itself may not be ‘strategic’ enough to warrant separate disclosure.
- uncertainty amongst stakeholders as to whether there would be a common understanding of the qualitative thresholds and therefore, they may be applied differently. For example, a new geographical area may be a region, a country or a continent. Similar concerns arise with determining new major lines of business. Applying materiality should help in this assessment.
Disclosures: Exemption from disclosing information
Question 3—Disclosures: Exemption from disclosing information (proposed paragraphs B67D–B67G of IFRS 3)
The IASB is proposing to exempt an entity from disclosing some of the information that would be required applying the proposals in this Exposure Draft in specific circumstances. The exemption is designed to respond to preparers’ concerns about commercial sensitivity and litigation risk but is also designed to be enforceable and auditable so that it is applied only in the appropriate circumstances (see paragraphs BC74–BC107).
The IASB proposes that, as a principle, an entity be exempt from disclosing some information if doing so can be expected to prejudice seriously the achievement of any of the entity’s acquisition-date key objectives for the business combination (see paragraphs BC79–BC89). The IASB has also proposed application guidance (see paragraphs BC90–BC107) to help entities, auditors and regulators identify the circumstances in which an entity can apply the exemption.
- Do you think the proposed exemption can be applied in the appropriate circumstances? If not, please explain why not and suggest how the IASB could amend the proposed principle or application guidance to better address these concerns.
- Do you think the proposed application guidance would help restrict the application of the exemption to only the appropriate circumstances? If not, please explain what application guidance you would suggest to achieve that aim.
Principle underpinning the proposed exemption
A24The UKEB welcomes the proposed addition of an exemption in the ED, and the principle underpinning the exemption – that an entity be exempted from disclosing specified information that it would be required to make if such a disclosure can be expected to seriously prejudice the achievement of any of the entity’s acquisition-date key objectives for the business combination (Basis of Conclusions paragraph BC79).
Exemption disclosure requirements
A25During our outreach, there was general support for the exemption, however both users and preparers raised concerns with its application. Preparers are concerned that the disclosure of the use of the exemption in itself may be commercially sensitive. Proposed paragraph B67D includes two factors that an entity should consider before using the exemption i.e. being able to describe a specific reason for not disclosing an item of information that identifies the seriously prejudicial effect the entity expects to result from disclosing the information, and whether the information is publicly available. For example, if an entity made an acquisition, as part of a planned ‘strategic’ series of acquisitions to enter a new geographical market, then disclosing the fact that one of its key objective and related target was to achieve x % market share in that geography may seriously prejudice the entity’s ability to carry out further acquisitions in that geographical area. See our UKEB recommendation in paragraph A5 above.
A26In its recent thematic reviews on reporting by the UK’s largest private companies16 and on IAS 37 Provisions, Contingent Liabilities and Contingent Assets17, the UK regulator, the Financial Reporting Council (the ‘FRC’) noted that the rationale for using an exemption is sometimes being taken without obvious justification18.
A27The UKEB recommends that the IASB provide illustrative examples of how such an exemption might be disclosed, for each item of information to which the exemption can be applied, as well as an example of how previously exempt information that is no longer prejudicial be disclosed. Such examples would also assist in clarifying when the exemption could be applied, in addition to the current non-exhaustive list of examples of when it cannot be applied.
Exemption application guidance
A28Some users are concerned about the proposed application guidance that accompanies the exemption (paragraphs B67D–B67G and Basis for Conclusions paragraphs BC90–BC107), which requires an entity to consider disclosing information at a sufficiently aggregated level, if doing so would resolve concerns of commercial sensitivity, before considering using the exemption. Users were concerned that if such aggregation was applied, in certain circumstances it may lead to loss of useful information that alone was not commercially sensitive. For example, where revenue synergies that were commercially sensitive are aggregated with cost synergies that were considered to be non-commercially sensitive.
A29Those users recommend that they would be content to receive information about the cost synergies (assuming they were not commercially sensitive), and the exemption be applied to the revenue synergies (if they were commercially sensitive). We support this suggestion, as this would lead to more useful information being disclosed than information on the aggregated amount for more than one category of synergy, as users tell us they use the information differently.
A30We understand that the proposed requirement is to permit aggregation in different ways, such as aggregation of total revenue synergy and total cost synergy for the same material acquisition, or aggregation of total revenue synergies, for example categories across material acquisitions with the same strategic rationale. However, the UKEB is not certain that it is clear how entities might aggregate certain items of information, and we recommend that the IASB clarify that aggregation would need to be made in a way that meets the overall objective of the disclosures.
A31The UKEB recommends that the IASB does not permit further aggregation of categories of synergy, i.e. not permit the combining of total cost synergies with total revenue synergies, or other categories of synergy for a material business combination; this will ensure that important non-commercially sensitive information is retained for users. (See Question 5 of this appendix for more information on the requirement to disclose quantitative information on expected synergies for each material business combinations).
Appropriate use of exemption
A32Users did not appear to be particularly concerned that the exemption would be used inappropriately and suggested that an entity would knowingly come under more scrutiny where it used an exemption, and therefore entities were likely to use the exemption in only limited circumstances.
A33As noted in the Basis for Conclusion (paragraph BC92), the IASB considered specifying how often it expects entities to apply the exemption—for example, whether it expects the application of the exemption to be extremely rare, similar to the requirement in paragraph 92 of IAS 3719, but decided against doing so. There is some diversity in the understanding of the application of the exemption and the UKEB recommends that the IASB clarify that it expects the exemption to only be used in ‘extremely rare cases’.
Disclosures: Identifying information to be disclosed
Question 4—Disclosures: Identifying information to be disclosed (proposed paragraphs B67A–B67B of IFRS 3)
The IASB is proposing to require an entity to disclose information about the performance of the entity’s strategic business combinations (that is, information about its acquisition-date key objectives and related targets for a strategic business combination and whether these key objectives and related targets are being met) that is reviewed by its key management personnel (see paragraphs BC110–BC114).
The IASB’s proposals would require an entity to disclose this information for as long as the entity’s key management personnel review the performance of the business combination (see paragraphs BC115–BC120).
The IASB is also proposing (see paragraphs BC121–BC130) that if an entity’s key management personnel:
- do not start reviewing, and do not plan to review, whether an acquisition-date key objective and the related targets for a business combination are met, the entity would be required to disclose that fact and the reasons for not doing so;
- stop reviewing whether an acquisition-date key objective and the related targets for a business combination are met before the end of the second annual reporting period after the year of acquisition, the entity would be required to disclose that fact and the reasons it stopped doing so; and
- have stopped reviewing whether an acquisition-date key objective and the related targets for a business combination are met but still receive information about the metric that was originally used to measure the achievement of that key objective and the related targets, the entity would be required to disclose information about the metric during the period up to the end of the second annual reporting period after the year of acquisition.
- Do you agree that the information an entity should be required to disclose should be the information reviewed by the entity’s key management personnel? Why or why not? If not, how do you suggest an entity be required to identify the information to be disclosed about the performance of a strategic business combination?
- Do you agree that:
- an entity should be required to disclose information about the performance of a business combination for as long as the entity’s key management personnel review that information? Why or why not?
- an entity should be required to disclose the information specified by the proposals when the entity’s key management personnel do not start or stop reviewing the achievement of a key objective and the related targets for a strategic business combination within a particular time period? Why or why not?
Management approach
A34The UKEB agrees with the proposals that information required to be disclosed for ‘strategic’ business combinations should be that reviewed and monitored by key management personnel (KMP)20. Whilst some stakeholders suggested that Chief Operating Decision Maker (CODM)21 may be a preferable level of management, we consider that the use of KMP aligns with the objective of providing the relevant performance information on the most important ‘strategic’ business combinations.
A35The UKEB also welcomes the proposed clarification to IAS 36 paragraph 83(b), that the level of management for the purpose of monitoring the subsequent performance of a ‘strategic’ business combination may not be the same as the level of management monitoring the business associated with goodwill for the purpose of impairment testing22.
How long information is required to be disclosed
A36The UKEB supports the proposed requirements to disclose if management either do not start, or stop, monitoring against acquisition-date key objectives and related targets as this will lead to decision useful information for users of accounts. We also agree that the core two full year periods after the year of acquisition is a reasonable timeframe during which an entity must disclose if management stops monitoring the performance of the acquisition against the acquisition-date key objectives and related targets, and to disclose the reason for stopping.
A37The UKEB supports the proposal that if the acquirer changes the metrics it uses to monitor the acquired business (whilst it would need to disclose that it had stopped monitoring against the acquisition-date key objectives), it would not need to disclose those new metrics or performance against those changed metrics, unless it refines (i.e. narrows the range of) the targets, as explained in the Basis for Conclusions (paragraph BC129). However, the UKEB recommends that this information is included in the application guidance, so that it is accessible and clarifies the requirements with regards to changed metrics.
Disclosures: Other proposals
Question 5—Disclosures: Other proposals
The IASB is proposing other amendments to the disclosure requirements in IFRS 3. These proposals relate to:
New disclosure objectives (proposed paragraph 62A of IFRS 3)
The IASB proposes to add new disclosure objectives in proposed paragraph 62A of IFRS 3 (see paragraphs BC23–BC28).
Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
The IASB proposes:
- to require an entity to describe expected synergies by category (for example, revenue synergies, cost synergies and each other type of synergy);
- to require an entity to disclose for each category of synergies:
- the estimated amounts or range of amounts of the expected synergies;
- the estimated costs or range of costs to achieve these synergies; and
- the time from which the benefits expected from the synergies are expected to start and how long they will last; and
- to exempt an entity from disclosing that information in specific circumstances.
See paragraphs BC148–BC163.
The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
The IASB proposes to replace the requirement in paragraph B64(d) of IFRS 3 to disclose the primary reasons for a business combination with a requirement to disclose the strategic rationale for the business combination (see paragraphs BC164–BC165).
Contribution of the acquired business (paragraph B64(q) of IFRS 3)
The IASB proposes to amend paragraph B64(q) of IFRS 3 to improve the information users receive about the contribution of the acquired business (see paragraphs BC166–BC177). In particular, the IASB proposes:
- to specify that the amount of profit or loss referred to in that paragraph is the amount of operating profit or loss (operating profit or loss will be defined as part of the IASB’s Primary Financial Statements project);
- to explain the purpose of the requirement but add no specific application guidance; and
- to specify that the basis for preparing this information is an accounting policy.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
The IASB proposes to improve the information entities disclose about the pension and financing liabilities assumed in a business combination by deleting the word ‘major’ from paragraph B64(i) of IFRS 3 and adding pension and financing liabilities to the illustrative example in paragraph IE72 of the Illustrative Examples accompanying IFRS 3 (see paragraphs BC178–BC181).
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
The IASB proposes to delete some disclosure requirements from IFRS 3 (see paragraphs BC182–BC183).
Do you agree with the proposals? Why or why not?
New disclosure objectives (proposed paragraph 62A of IFRS 3)
A38The UKEB supports the additional disclosure objectives in proposed paragraph 62A of IFRS 323, which provide the foundation for the proposed new disclosure requirements, to:
- respond to users’ need for better information about business combinations at the time of acquisition and on the subsequent performance of the most important acquisitions; and
- allow users to assess those business combinations more effectively.
A39These more specific disclosure objectives should enable preparers to understand better why users need a particular item of information and help entities disclose information that better meets the needs of users.
Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
A40The UKEB supports the new disclosure requirements in relation to the nature, timing and amount of expected synergies from a business combination, as it provides users with a better understanding of why an entity paid the price it did for the business combination. However, the UKEB suggests that the IASB clarifies that the management approach applies to this information, such that disclosure should only be required where synergies drive the rationale for the acquisition, and that the IASB does not expect that quantitative information on expected synergies is prepared solely for the purpose of disclosing in the financial statements.
A41During our outreach, almost all stakeholders supported the IASB’s decision not to define the word ‘synergies’, since the term appears to be widely understood24, and existing paragraph B64(e) of IFRS 3 requires an entity to disclose qualitative information about expected synergies. Feedback suggests that entities do not fail to identify expected synergies appropriately for the current requirements in IFRS 3.
A42The proposed requirement for quantitative information on expected synergies should enable companies to provide contextual and relevant information, rather than the often ‘boilerplate’ qualitative disclosures currently provided on expected synergies, as highlighted in the FRC’s thematic review of business combinations25. Assigning a value to expected synergies should help companies ensure that other separately identifiable intangibles are recognised by the acquirer, although the option to use a range as opposed to a point estimate may result in less useful information. The UKEB agrees with the proposal that such estimates may be disclosed as a range, since it is more likely that entities will estimate the expected synergies as a range.
A43The UKEB supports the proposal to provide quantitative information on expected synergies aggregated by category i.e. to disclose (as a point or as a range) revenue synergies, cost synergies, etc. Requiring more detailed cost synergies, such as employee-related cost synergies, might lead to disclosure of more sensitive information. Therefore, we think the proposal strikes the right balance between disclosure and maintaining confidentially of sensitive information and will address some preparer concerns raised during our outreach.
A44The UKEB also supports the requirement to disclose when the benefits expected from the synergies are expected to start and how long they are expected to last, noting that this disclosure would require the acquirer to specify whether the benefits from the synergies are expected to be finite or indefinite. Some stakeholders expressed views that information on expected synergies was forward-looking and should not be required to be disclosed in the financial statements and would be better suited to the management commentary. However, users were broadly supportive of including this information in the notes to the financial statements due to the audit assurance provided.
A45Some preparers did not concur with the IASB’s view that expected synergies are fixed at the time of acquisition (see Basis for Conclusion paragraph BC139), with some suggesting that this information may not be available at the time of acquisition (for example, in a hostile takeover close to the end of the reporting period), and where available, may be highly judgemental and be costly to provide evidence that the assumptions made in those estimates are reasonable and supportable and why the range of synergies are deemed achievable.
A46It was also noted that other information disclosed in the year of acquisition might be provisional and be adjusted in the ‘measurement period’26, but the same opportunity to adjust information about expected synergies is not proposed27. Therefore, information disclosed might be inconsistent if other provisional information is adjusted in the measurement period, and therefore of limited use to users.
A47The UKEB recommends that the ‘measurement period’ be applied to quantitative information on expected synergies, to provide an acquirer with the opportunity to update information on expected synergies where information comes to light in the ‘measurement period’ and other provisional figures have been adjusted, to ensure that information is consistent.
A48The UKEB welcomes an exemption (see paragraphs A24–A33), where disclosing an item of quantitative information on expected synergies can be expected to prejudice seriously the achievement of any one of the acquirer’s key objectives for the business combination. However, as noted in paragraph A25, some UK preparers’ still have concerns with the exemption requirements to disclose the item to which the exemption has been applied and the reason for applying the exemption to each item. We make a recommendation in paragraph A5 to counteract the risk of disclosing seriously prejudicial and commercially sensitive information.
A49As noted in paragraphs A28–A31, some users are also concerned about the proposed application guidance that accompanies the exemption, which requires entities to consider disclosing information at a sufficiently aggregated level to address concerns over disclosing commercially sensitive information, rather than use the exemption. However, due to the potential loss of useful information that could result, we make a recommendation to the IASB in paragraph A31 in order to provide users with the information they need.
The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
A50The UKEB supports the IASB proposal to replace the requirement in the application guidance paragraph B64(d) of IFRS 3 to disclose the ‘primary reasons’ for a business combination, with a requirement to disclose the ‘strategic rationale’28 for the business combination, acknowledging that, per the Basis for Conclusions (paragraph BC165), the proposed requirement is intended to provide a clearer link between the objectives for a business combination and an entity’s overall business strategy.
Contribution of the acquired business (paragraph B64(q) of IFRS 3)
A51The UKEB supports the IASB proposal in relation to contribution of the acquired business. These should be helpful for users of financial statements to forecast future performance of the combined entity.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
A52The UKEB supports the IASB proposal to improve the information entities disclose about the pension and financing liabilities assumed in a business combination. Users view such liabilities as part of the total capital employed in the business combination.
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
A53The UKEB supports the IASB proposal to delete certain paragraphs from IFRS 3 that are duplicated in other IFRS Accounting Standards or became redundant subsequent to amendments to IFRS 3 in 2008.
A50. The UKEB supports the IASB proposal to replace the requirement in the application guidance paragraph B64(d) of IFRS 3 to disclose the 'primary reasons' for a business combination, with a requirement to disclose the 'strategic rationale 28' for the business combination, acknowledging that, per the Basis for Conclusions (paragraph BC165), the proposed requirement is intended to provide a clearer link between the objectives for a business combination and an entity's overall business strategy.
Contribution of the acquired business (paragraph B64(q) of IFRS 3)
A51. The UKEB supports the IASB proposal in relation to contribution of the acquired business. These should be helpful for users of financial statements to forecast future performance of the combined entity.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
A52. The UKEB supports the IASB proposal to improve the information entities disclose about the pension and financing liabilities assumed in a business combination. Users view such liabilities as part of the total capital employed in the business combination.
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
A53. The UKEB supports the IASB proposal to delete certain paragraphs from IFRS 3 that are duplicated in other IFRS Accounting Standards or became redundant subsequent to amendments to IFRS 3 in 2008.
Proposed amendments to IAS 36 Impairment of Assets
Changes to the impairment test
Question 6—Changes to the impairment test (paragraphs 80–81, 83, 85 and 134(a) of IAS 36)
During the PIR of IFRS 3, the IASB heard concerns that the impairment test of cash-generating units containing goodwill results in impairment losses sometimes being recognised too late.
Two of the reasons the IASB identified (see paragraphs BC188–BC189) for these concerns were:
- shielding; and
- management over-optimism.
The IASB is proposing amendments to IAS 36 that could mitigate these reasons (see paragraphs BC192–BC193).
Proposals to reduce shielding
The IASB considered developing a different impairment test that would be significantly more effective at a reasonable cost but concluded that doing so would not be feasible (see paragraphs BC190–BC191). Instead, the IASB is proposing changes to the impairment test (see paragraphs 80–81, 83 and 85 of IAS 36) to reduce shielding by clarifying how to allocate goodwill to cash-generating units (see paragraphs BC194–BC201).
Proposal to reduce management over-optimism
The IASB's view is that management over-optimism is, in part, better dealt with by enforcers and auditors than by amending IAS 36. Nonetheless, the IASB is proposing to amend IAS 36 to require an entity to disclose in which reportable segment a cash-generating unit or group of cash-generating units containing goodwill is included (see paragraph 134(a) of IAS 36). The IASB expects this information to provide users with better information about the assumptions used in the impairment test and therefore allow users to better assess whether an entity's assumptions are over-optimistic (see paragraph BC202).
- Do you agree with the proposals to reduce shielding? Why or why not?
- Do you agree with the proposal to reduce management over-optimism? Why or why not?
Proposals to reduce shielding
How to allocate goodwill to cash-generating units (CGUs)
A54. The UKEB supports the addition of paragraphs 80A and 80B 29 to clarify that the CGU relevant for impairment testing is the lowest level at which management monitors the business associated with the goodwill, and that it should not be larger than an operating segment as defined by paragraph 5 of IFRS 8 before aggregation 30. The change in focus to the business associated with the goodwill, as opposed to the goodwill, is also welcome since it is the business associated with goodwill that will be monitored, not the goodwill.
A55. However, the IASB should be aware that this requirement may not achieve the intended reduction in shielding of goodwill, since goodwill is not allocated to the CGU or group of CGUs expected to benefit from the goodwill, if financial information is not regularly received by management at that lowest level of CGUs to monitor the business associated with goodwill. Therefore, goodwill could be more shielded than if the allocation of goodwill was based solely on the CGUs expected to benefit from the synergies.
Proposal to reduce management over-optimism
Disclose reportable segments which include a CGU or group of CGUs containing goodwill
A56. The UKEB supports the proposal requiring an entity to disclose the reportable segment in which a CGU or group of CGUs containing goodwill is included. This should not result in significant costs, since entities already have this information, and some entities already disclose this information voluntarily. Therefore, the benefits of increased transparency for users would outweigh any costs.
A57. The risk of management over-optimism is inherent in any impairment-only model. Requiring disclosure of the reportable segment in which a CGU containing goodwill is included would help users better assess and challenge the reasonableness of assumptions used in the impairment test. Users would be able to compare these assumptions with the information they receive about reportable segments and with their own assumptions about the future performance of those reportable segments. It aligns with the project objective of providing better information about business combinations.
A58. Whilst users are concerned that impairment losses are sometimes recognised too late and that there is no transparency on ‘close calls' for impairment losses that are not recognised, the UKEB notes that the existing disclosure requirements in IAS 36.134(f) should be sufficient, i.e. an entity is required to provide sensitivity analysis if a reasonably possible change in a key assumption used in impairment testing would cause the carrying amount to exceed its recoverable amount. This should help users identify if there are any 'close calls' with regards to impairment losses not being recognised.
A59. The UKEB recommends that the IASB require entities to disclose how CGUs have been identified to which goodwill is allocated, and to disclose any changes in CGUs and in the allocation of goodwill to those CGUs since the prior period. The IASB could also consider extending this requirement to show the related segments for the respective changes.
Changes to the impairment test: Value in use
Question 7—Changes to the impairment test: Value in use (paragraphs 33, 44–51, 55, 130(g), 134(d)(v) and A20 of IAS 36)
The IASB is proposing to amend how an entity calculates an asset's value in use. In particular, the IASB proposes:
- to remove a constraint on cash flows used to calculate value in use. An entity would no longer be prohibited from including cash flows arising from a future restructuring to which the entity is not yet committed or cash flows arising from improving or enhancing an asset's performance (see paragraphs BC204–BC214).
- to remove the requirement to use pre-tax cash flows and pre-tax discount rates in calculating value in use. Instead, an entity would be required to use internally consistent assumptions for cash flows and discount rates (see paragraphs BC215–BC222).
- Do you agree with the proposal to remove the constraint on including cash flows arising from a future restructuring to which the entity is not yet committed or from improving or enhancing an asset's performance? Why or why not?
- Do you agree with the proposal to remove the requirement to use pre-tax cash flows and pre-tax discount rates in calculating value in use? Why or why not?
A60. The proposed changes to the calculation of value in use applies to all assets tested for impairment in accordance with IAS 36, and not solely goodwill. The IASB should be aware that, since impairment losses on certain assets (excluding goodwill) are permitted to be reversed, the proposed changes could lead to reversal of impairment for some assets.
Removal of constraint to allowing cash flows from future uncommitted restructuring and from improving or enhancing an asset's performance
A61. During our outreach, stakeholders suggested that removal of the constraint could increase the risk that management use over-optimistic inputs in calculating value in use, so that the results are contrary to the IASB's aim – timely recognition of impairment losses. An increase in the measured value in use could therefore delay the recognition of impairment losses; if the measured value in use (VIU) increases and is higher than the fair value less costs of disposal, and if the VIU (recoverable amount) is higher than the carrying value, it could avoid or further delay the recognition of any impairment.
A62. Whilst the UKEB recognises some stakeholder concerns, the UKEB agrees with the proposal to remove the constraint to reduce the cost and complexity of the value in use calculation, by using internally consistent assumptions. However, we recommend to the IASB that the proposal is redrafted so that entities are required to include cash flows from uncommitted restructuring or asset improvements.
A63. The IASB proposal to remove the restriction on including cash flows arising from uncommitted restructuring or asset improvements could lead to inconsistent treatment and lack of comparability. The UKEB also recommends that the potential lack of consistency and comparability could be addressed by requiring entities to:
- disclose the fact that the recoverable amount of a CGU includes cash flows from uncommitted restructuring or asset improvements;
- disclose the nature and amounts of those uncommitted restructurings and when those are planned to occur; and
- disclose the risks associated with including such cash flows.
Permit the use of post-tax cash flows and post-tax discount rates
A64. The UKEB welcomes the proposal to permit the use of post-tax cash flows and post-tax discounts rates in calculating value in use and to disclose which rate has been used, since it is anticipated that this will align the standard with current practice.
A65. As a result of the proposed amendments to the IAS 36 VIU calculation, stakeholders have noted that there are fewer differences between the VIU and fair value less cost of disposal (FVLCD) method of calculating the recoverable amount for the purpose of the impairment test and we suggest that the IASB clarifies the remaining differences in the methods.
Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures
Question 8—Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures
The IASB proposes to amend the forthcoming IFRS X Subsidiaries without Public Accountability: Disclosures (Subsidiaries Standard) to require eligible subsidiaries applying the Subsidiaries Standard to disclose:
- information about the strategic rationale for a business combination (proposed paragraph 36(ca) of the Subsidiaries Standard);
- quantitative information about expected synergies, subject to an exemption in specific circumstances (proposed paragraphs 36(da) and 36A of the Subsidiaries Standard);
- information about the contribution of the acquired business (proposed paragraph 36(j) of the Subsidiaries Standard); and
- information about whether the discount rate used in calculating value in use is pre-tax or post-tax (paragraph 193 of the Subsidiaries Standard).
See paragraphs BC252–BC256.
Do you agree with the proposals? Why or why not?
A66. The UKEB welcomes the reduced disclosure requirements for eligible subsidiaries, which will reduce the cost for preparers by only requiring the disclosure of information considered useful to users of those financial statements.
Transition
Question 9—Transition (proposed paragraph 64R of IFRS 3, proposed paragraph 1400 of IAS 36 and proposed paragraph B2 of the Subsidiaries Standard)
The IASB is proposing to require an entity to apply the amendments to IFRS 3, IAS 36 and the Subsidiaries Standard prospectively from the effective date without restating comparative information. The IASB is proposing no specific relief for first-time adopters. See paragraphs BC257–BC263.
Do you agree with the proposals? Why or why not? If you disagree with the proposals, please explain what you would suggest instead and why.
A67. The UKEB is not aware of any significant concerns with the prospective transition requirements. The prospective requirements should provide enough time for internal controls and process to be updated. Not requiring restatement of comparative information will reduce any burden on preparers and remove any potential for use of hindsight in providing the information.
A68. The UKEB is not aware of any concerns with not providing relief for first-time adopters, given that they are expected to plan their transition to IFRS Accounting Standards with enough time.
Appendix B: Proposed Flowchart
Figure 1: UKEB recommendation - determination of 'strategic'* business combinations
Flowchart: Determination of 'strategic'* Business Combinations
- Start: Does the acquired business exceed any one of the quantitative thresholds or qualitative thresholds?
- Quantitative thresholds:
- Quantitative thresholds:
- the absolute amount of the acquiree's operating profit or loss is 10 per cent or more of the absolute amount of the acquirer's consolidated operating profit or loss; or
- the acquiree's revenue is 10 per cent or more of the acquirer's consolidated revenue;
* Qualitative thresholds: * the business combination resulted in the acquirer entering a new major line of business or geographical area of operations. (Paragraph B67C(c)) * Decision branches: * If Yes: Proceed to "Does the acquired business meet the description of a 'strategic' business combination?" * If No: Result is: The acquired business is not classified as a 'strategic' business combination, so no further disclosures are required (Paragraph B67A)
-
Decision Node: Does the acquired business meet the description of a 'strategic'* business combination?
- A 'strategic'* business combination would be "one for which failure to meet any one of an entity's acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy". (Paragraph BC54)
- Decision branches:
- If Yes: Proceed to "Disclose, in the year of acquisition: the acquisition-date key objectives and the related targets. (Paragraph B67A(a))"
- If No: Proceed to "Do you wish to rebut the presumption that the acquired business is 'strategic'*, because it does not meet the definition?"
-
Decision Node: Do you wish to rebut the presumption that the acquired business is 'strategic'*, because it does not meet the definition?
- Decision branches:
- If Yes: Action: Disclose the reason for using the rebuttal. Then, proceed to the final disclosure step.
- If No: Proceed to the final disclosure step.
- Decision branches:
-
Final Disclosure Step:
- Disclose, in the year of acquisition:
- the acquisition-date key objectives and the related targets. (Paragraph B67A(a))
- Disclose, in the year of acquisition, and in each subsequent reporting period for as long as key management personnel review actual performance (paragraph B67B), information as reviewed by key management personnel about:
- actual performance; and
- a statement of whether actual performance is meeting or has met an acquisition-date key objective and the related targets. (Paragraph B67A(b))
- Disclose, in the year of acquisition:
Note: The UKEB recommend that 'strategic' business combinations are termed 'major' business combinations.
Dear Dr Barckow
Invitation to Comment: Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
1. The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2. There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS. 31 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option. 32
3. The UKEB welcomes the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment. In developing this letter, we consulted with stakeholders in the UK, including preparers, accounting firms and institutes, academics, and users of financial statements.
4. The UKEB is broadly supportive of the package of proposed amendments to the disclosure requirements in IFRS 3 Business Combinations and the impairment test in IAS 36 Impairment of Assets. The proposed amendments would provide investors with better information about the post-acquisition performance of acquired entities.
5. Our main observations and recommendations, reflecting our UKEB outreach [to date] 33 and desk-based research 34, are set out in the paragraphs that follow.
Proposed amendments to IFRS 3 Business Combinations
Identifying the most important business combinations
6. The UKEB broadly supports the IASB's proposals to require disclosure of information about the performance of business combinations, based on the acquirer's acquisition-date key metrics and related targets, for only a subset of the most important business combinations (the so-called 'strategic' business combinations) (see paragraphs A1–A6). We consider this strikes the right balance between the needs of users and the costs to preparers.
Terminology - strategic or major
7. We consider that the use of the term 'strategic acquisitions' does not reflect the transactions for which users are keen to obtain additional disclosures. Preparers tell us that they only undertake acquisitions if they are strategic. We understand from users that they would prefer additional, meaningful disclosures for acquisitions that are substantive for the business, and which will allow them to hold management to account. As such, we consider that another term, such as 'major', 'substantial' or 'significant' may be more appropriate than 'strategic' to describe the subset of the most important business combinations (see paragraph A7)
Principles-based identification
8. In addition, we consider that using only the proposed exhaustive list of quantitative and qualitative thresholds (the closed threshold approach), may not capture the most important acquisitions from a user's perspective. Instead, we recommend a principles-based approach to identifying the most important business combinations and we set out a possible process to achieve this in Appendix B to this letter. Our recommendation is that a subset of 'strategic' acquisitions ('strategic' acquisitions) is identified by first applying both the quantitative and qualitative thresholds, as per the IASB's proposal. However, where an acquisition meets one or more of the qualitative or quantitative thresholds, an entity should be able to rebut the presumption that the acquisition is 'strategic' if it can demonstrate that the acquisition does not meet the overall description set out in paragraph BC54. The entity would be required to disclose the reason for the rebuttal and the acquisition would then not be subject to the additional disclosures for 'strategic' business combinations. This also demonstrates the importance of the description in paragraph BC54, which we recommend should be included in the standard itself.
9. We consider that if the IASB proceeds with a principles-based approach, there would be less concern over the proposed thresholds (see paragraphs A1516–A2117 and A2220–A2321), due to the focus on the description in the Basis for Conclusions paragraph BC54.
Seriously Prejudicial Exemption
10. The UKEB welcomes the proposal that an entity be exempt from disclosing some information if doing so can be expected to prejudice seriously the achievement of any of the entity's acquisition-date key objectives for the business combination (see paragraphs A2422–A3334). This should address some of the concerns from preparers about the cost and commercial sensitivity of disclosing information about material business combinations and ‘strategic' business combinations.
11. However, to ensure the appropriate application of the exemption, the UKEB recommends that the IASB clarifies that the exemption would only be used in 'extremely rare cases'. Other suggestions to assist in the application of the exemption are included under question 3 in appendix A.
Proposed amendments to IAS 36 Impairment of Assets
12. We support the proposed amendments to IAS 36 that clarify the allocation of goodwill to cash-generating units (CGUs) (see paragraphs A5452–A5553) and require disclosure of the reportable segments that include a CGU or group of CGUs containing goodwill (see paragraphs A5654–A5955). However, we have some reservations about the extent to which these proposals will achieve the intended change.
13. To address users' concerns that impairment losses are sometimes recognised too late and that there is no transparency on 'close calls' for impairment losses that are not recognised, the UKEB recommends that the IASB includes requirements to disclose the amount of headroom for each CGU containing goodwill, where that headroom is marginal (see paragraph A56).
14. The UKEB broadly supports the IASB's efforts to reduce the cost and complexity of the impairment test and the proposed changes to the calculation of value in use (see paragraphs A6057–A6561), which applies to all assets tested for impairment in accordance with IAS 36. However, the UKEB recommends that the IASB introduce some disclosure requirements to address the risk that management use optimistic inputs when calculating value in use that could avoid or further delay the recognition of impairment losses, as discussed in more detail under question 7 in appendix A.
15. Responses to the IASB's specific questions about the ED proposals are included in appendix A to this letter.
16. If you have any questions about this response, please contact the UKEB project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: UKEB response to detailed questions in IASB Exposure Draft IASB/ED/2024/1 Business Combinations—Disclosures, Goodwill and Impairment
Appendix B: Proposed Flowchart - determination of ‘strategic' business combinations
Appendix A: UKEB response to detailed questions in IASB Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
Proposed amendments to IFRS 3 Business Combinations
Disclosures: Performance of a business combination
Question 1—Disclosures: Performance of a business combination (proposed paragraphs B67A–B67G of IFRS 3)
In the PIR of IFRS 3 and in responses to the Discussion Paper the IASB heard that:
- users need better information about business combinations to help them assess whether the price an entity paid for a business combination is reasonable and how the business combination performed after acquisition. In particular, users said they need information to help them assess the performance of a business combination against the targets the entity set at the time the business combination occurred (see paragraphs BC18–BC21).
- preparers of financial statements are concerned about the cost of disclosing that information. In particular, preparers said the information would be so commercially sensitive that its disclosure in financial statements should not be required and disclosing this information could expose an entity to increased litigation risk (see paragraph BC22).
Having considered this feedback, the IASB is proposing changes to the disclosure requirements in IFRS 3 that, in its view, appropriately balance the benefits and costs of requiring an entity to disclose this information. It therefore expects that the proposed disclosure requirements would provide users with more useful information about the performance of a business combination at a reasonable cost.
In particular, the IASB is proposing to require an entity to disclose information about the entity's acquisition-date key objectives and related targets for a business combination and whether these key objectives and related targets are being met (information about the performance of a business combination). The IASB has responded to preparers' concerns about disclosing that information by proposing:
- to require this information for only a subset of an entity's business combinations—strategic business combinations (see question 2); and
- to exempt entities from disclosing some items of this information in specific circumstances (see question 3).
- Do you agree with the IASB's proposal to require an entity to disclose information about the performance of a strategic business combination, subject to an exemption? Why or why not? In responding, please consider whether the proposals appropriately balance the benefits of requiring an entity to disclose the information with the costs of doing so.
- If you disagree with the proposal, what specific changes would you suggest to provide users with more useful information about the performance of a business combination at a reasonable cost?
Disclosure objective
A1. The UKEB agrees with the IASB's objective for the disclosure proposals – to provide users with information to help them assess the post-acquisition performance of a business combination at a reasonable cost. Users of accounts tell us that they would like entities to provide better information on business combinations, in particular to help them assess performance after acquisition, against acquisition-date key objectives 35 and related targets 36.
A2. The UKEB supports the IASB's proposal to require an entity to disclose information about the performance of only ‘strategic' business combinations (see Question 2 of this appendix) and support the proposal of an exemption (see Question 3 of this appendix). The IASB's proposal to limit the requirement for performance information to a subset of the most important business combinations may help achieve the balance between user's needs and preparers' concerns about the cost of providing the information.
Commercially sensitive information
A3. However, UK preparers still have some concerns about the risk of commercially sensitive information being disclosed, exposing them to increased litigation risk and potentially obscuring material information, all delivered at significant costs.
A4. They note that the proposed requirement to disclose the key objectives and targets to which the exemption has been applied and the reason for applying the exemption to each item, in itself risks disclosure of potentially seriously prejudicial and commercially sensitive information.
A5. We consider that one way to counteract this risk may be to remove the requirement for an entity to disclose the reason for invoking the exemption in a reporting period, where doing so is itself seriously prejudicial and commercially sensitive, whilst still disclosing that an exemption has been applied for some key objectives and/or related targets. The IASB could consider including additional requirements for the entity to disclose the reason for invoking the exemption at a future reporting date when the reason is no longer seriously prejudicial. This should ensure that users of accounts are provided with relevant information to assess management's stewardship and rationale at the earliest opportunity without exposing entities to litigation risk.
Integration of acquired business
A6. If an entity plans to integrate the acquired business, those disclosures against acquisition-date key objectives will be based on a combined business, since information about the acquired business in isolation may not be available. Some preparers questioned the usefulness of combined information on subsequent performance. However, users welcomed the proposals, and noted that often acquired business are integrated within a relatively short period of time after acquisition and therefore expected that key objectives and related targets would be for a combined business.
Disclosures: Strategic business combinations
Question 2—Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
The IASB is proposing to require an entity to disclose information about the performance of a business combination (that is, information about the entity's acquisition-date key objectives and related targets for the business combination and whether these key objectives and related targets are being met) for only strategic business combinations—a subset of material business combinations. A strategic business combination would be one for which failure to meet any one of an entity's acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy.
The IASB is proposing that entities identify a strategic business combination using a set of thresholds in IFRS 3—a business combination that met any one of these thresholds would be considered a strategic business combination (threshold approach) (see paragraphs BC56–BC73).
The IASB based its proposed thresholds on other requirements in IFRS Accounting Standards and the thresholds regulators use to identify particularly important transactions for which an entity is required to take additional steps such as providing more information or holding a shareholder vote. The proposed thresholds are both quantitative (see paragraphs BC63–BC67) and qualitative (see paragraphs BC68–BC70).
- Do you agree with the proposal to use a threshold approach? Why or why not? If you disagree with the proposal, what approach would you suggest and why?
- If you agree with the proposal to use a threshold approach, do you agree with the proposed thresholds? Why or why not? If not, what thresholds would you suggest and why?
Terminology – strategic or major
A7. We consider that the concept of 'strategic' business combinations does not reflect the transactions for which users are keen to obtain additional disclosures. Preparers tell us that they only undertake acquisitions if they are strategic. We understand from users that they would prefer additional, meaningful disclosures for acquisitions that are substantive for the business, and which will allow them to hold management to account. As such, we consider that another term, such as 'major', 'substantial' or 'significant' may be more appropriate than 'strategic' to describe the subset of the most important business combinations.
Principles-based identification
A8. The UKEB is concerned that using only the proposed exhaustive list of quantitative and qualitative thresholds (the closed threshold approach), may not capture the most important acquisitions from a user perspective. Instead, we would recommend a principles-based approach to identifying the most important business combinations and we set out a possible process to achieve this in appendix B to this letter. Our recommendation is that a subset of 'strategic' acquisitions is identified by first applying both the quantitative and qualitative thresholds, as per the IASB's proposal. However, where an acquisition meets one or more of the qualitative or quantitative thresholds, an entity should be able to
acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy.
The IASB is proposing that entities identify a strategic business combination using a set of thresholds in IFRS 3—a business combination that met any one of these thresholds would be considered a strategic business combination (threshold approach) (see paragraphs BC56–BC73).
The IASB based its proposed thresholds on other requirements in IFRS Accounting Standards and the thresholds regulators use to identify particularly important transactions for which an entity is required to take additional steps such as providing more information or holding a shareholder vote. The proposed thresholds are both quantitative (see paragraphs BC63–BC67) and qualitative (see paragraphs BC68–BC70).
- Do you agree with the proposal to use a threshold approach? Why or why not? If you disagree with the proposal, what approach would you suggest and why?
- If you agree with the proposal to use a threshold approach, do you agree with the proposed thresholds? Why or why not? If not, what thresholds would you suggest and why?
Terminology – strategic or major
A7We consider that the concept of ‘strategic’ business combinations does not reflect the transactions for which users are keen to obtain additional disclosures. Preparers tell us that they undertake acquisitions only if they are strategic. We understand from users that they would prefer additional, meaningful disclosures for acquisitions that are substantive for the business, and which will allow them to hold management to account. As such, we consider that another term, such as ‘major’, ‘substantial’ or ‘significant’ may be more appropriate than ‘strategic’ to describe the subset of the most important business combinations.
Principles-based identification
A8The UKEB is concerned that using only the proposed exhaustive list of quantitative and qualitative thresholds (the closed threshold approach), may not capture the most important acquisitions from a user perspective. Instead, we would recommend a principles-based approach to identifying the most important business combinations and we set out a possible process to achieve this in appendix B to this letter. Our recommendation is that a subset of ‘strategic’ acquisitions is identified by first applying both the quantitative and qualitative thresholds, as per the IASB’s proposal. However, where an acquisition meets one or more of the qualitative or quantitative thresholds, an entity should be able to rebut the presumption that the acquisition is ‘strategic’ if it can demonstrate that the acquisition does not meet the overall description set out in paragraph BC54. The entity would be required to disclose the reason for the rebuttal and the acquisition would then not be subject to the additional disclosures for ‘strategic’ business combinations. This also demonstrates the importance of the description in paragraph BC54, which we recommend should be included in the standard itself.
A9We consider that if the IASB proceeds with a principles-based approach, there would be less concern over the proposed thresholds, (see paragraphs A15–A16, A21–A17 and A22–A23–A21), due to the focus on the description in the Basis for Conclusions paragraph BC54.
Series of acquisitions
A10Users of financial statements also want information about a ‘series’ of business combinations that are collectively ‘strategic’, as they have been acquired to achieve the same strategic objective, even if they do not meet the qualitative or quantitative thresholds individually.
A11Existing disclosure requirements for each material business combination in IFRS 3 relate to individually material or collectively material acquisitions37, therefore it would seem logical to extend this approach to ‘strategic’ business combinations that are collectively ‘strategic’.
A12The IASB acknowledged this when devising these proposals. In the Basis for Conclusions (paragraph BC73), the IASB noted that the qualitative thresholds might at least help an entity to identify the first in a series of business combinations entered into to achieve the same strategic objective. For example, the first in a series of business combinations could result in an entity entering into a new line of business or geographical area, enabling the acquisition of other businesses in the future.
A13The UKEB recommends that, since a company will be required to disclose the strategic rationale for each material business combination, the IASB could extend this requirement to disclose:
- those material acquisitions with the same strategic rationale; and
- whether or not an entity considers this series of acquisitions with the same strategic rationale to be ‘strategic’ (or ‘major’), and if so, disclose the key objectives for that series at the acquisition date of the first in the series.
This will ensure that:
- users receive a full picture of ‘strategic’ acquisitions undertaken by the entity; and
- the disclosures reflect how management will monitor the combined businesses with a similar objective e.g. increase in market share in a specific geographical area.
A14The IASB should give consideration as to how a company might disclose a series of ‘strategic’ acquisitions where they occur over different reporting periods.
Quantitative thresholds
A15Whilst the quantitative threshold of 10% may be seen as too low by some stakeholders, overall, the UKEB is supportive, as they appear reasonable when compared with thresholds used by regulators and auditors across different jurisdictions in identifying important business combinations.
A16Academic research39 suggests that approximately 25% of acquisitions in the UK would likely be classified as ‘strategic’ using only the proposed thresholds.
A17In response to stakeholder feedback, we recommend that the IASB add market capitalisation (where relevant) to the list of quantitative thresholds. Note that this suggested additional threshold has been included in Figure 1 in appendix B, which sets out our recommended principles-based approach described in paragraph A8 above). We suggest a threshold of 10% of market capitalisation.
A18Stakeholders highlighted concerns with the use of both ‘revenue’ and ‘operating profit’ (as defined by IFRS 18 Presentation and Disclosure in Financial Statements) to determine a ‘strategic’ business combination, due to the volatile nature of such metrics, and noted the following:
- if either the acquirer or acquiree had exceptional items in the year prior to the acquisition, the metrics at the end of the reporting period prior to the acquisition, used for the threshold assessment, could be distorted.
- the apparent inconsistency with the synergy categories proposed for quantitative information on expected synergies, when, for example, the strategic rationale for an acquisition might be the achievement of tax synergies.
A19Some stakeholders suggested using ‘operating profit before exceptional items’, as opposed to ‘operating profit’. However, the rebuttable presumption method, recommended in paragraph A8 above, should mitigate any such concerns with applying the quantitative thresholds.
Step acquisitions
A20During our outreach, some stakeholders were unclear on how the quantitative thresholds would apply to partial40 acquisitions and step41 acquisitions. The UKEB understands that the proposals will require the thresholds to be applied to the total holding. For example, in a partial acquisition, if an entity acquires 60% of the acquiree, IFRS 3 requires that 100% is consolidated (with a non-controlling interest of 40%), and the quantitative thresholds would be applied to the 100% of revenue, operating profit and assets (including goodwill), and not the 60%. Similarly in a step acquisition, where, for example, an acquirer has a 40% holding and increases its holding to 60%, the thresholds would apply to the 100% of the acquiree’s relative amounts (and not 60%, nor the 20% incremental holding).
A21We recommend that application guidance be added to the standard to clarify the treatment of such partial and step acquisitions, to ensure there is no diversity in practice.
Qualitative thresholds
A22The IASB’s proposed qualitative thresholds are aimed at capturing business combinations that would represent a strategic shift for an entity, but that would not be captured by the quantitative thresholds. Our outreach identified some concerns with applying the qualitative thresholds, as set out in paragraph A23 below. We consider that our recommendation of a principle-based approach set out in paragraph A8 above would alleviate some of the concerns and ensure that the qualitative thresholds capture the relevant business combinations.
A23However, should the IASB proceed with the proposed approach in the ED, it should be aware of the following concerns and related recommendations:
- a lack of clarity amongst stakeholders in relation to the qualitative thresholds, arising from the inconsistency between the ED (see application guidance paragraph B67C42) and the Basis for Conclusions (see paragraphs BC5543 and BC6844). The UKEB recommends the IASB clarify the thresholds by preceding both ‘line of business’ and ‘geographical area’ with the word ‘new’ or ‘new major’, depending upon intended requirements 45. Whilst we understand that the proposed thresholds are based on IFRS 5 requirements, the UKEB suggests that the words ‘new major’ should relate to both line of business and geographical area, since a ‘new’ geographical area in itself may not be ‘strategic’ enough to warrant separate disclosure.
- uncertainty amongst stakeholders as to whether there would be a common understanding of the qualitative thresholds and therefore, they may be applied differently. For example, a new geographical area may be a region, a country or a continent. Similar concerns arise with determining new major lines of business. Applying materiality should help in this assessment (see comment below).
- the potential for diversity in application of the qualitative thresholds, in particular from their interaction with the concept of materiality. The intention, set out in the Basis for Conclusions (paragraph BC53), is to identify a population of business combinations for which an entity would be required to disclose particular information. An entity would still assess materiality of the potential disclosures as usual. Should the IASB decide not to proceed with the UKEB recommendation in paragraph A8 above, the UKEB recommends the IASB provide illustrative examples, to help clarify how the concept of materiality would apply where the proposed qualitative thresholds may capture business combinations that the acquirer considers are immaterial.
Disclosures: Exemption from disclosing information
Question 3—Disclosures: Exemption from disclosing information (proposed paragraphs B67D–B67G of IFRS 3)
The IASB is proposing to exempt an entity from disclosing some of the information that would be required applying the proposals in this Exposure Draft in specific circumstances. The exemption is designed to respond to preparers’ concerns about commercial sensitivity and litigation risk but is also designed to be enforceable and auditable so that it is applied only in the appropriate circumstances (see paragraphs BC74–BC107).
The IASB proposes that, as a principle, an entity be exempt from disclosing some information if doing so can be expected to prejudice seriously the achievement of any of the entity’s acquisition-date key objectives for the business combination (see paragraphs BC79–BC89). The IASB has also proposed application guidance (see paragraphs BC90–BC107) to help entities, auditors and regulators identify the circumstances in which an entity can apply the exemption.
- Do you think the proposed exemption can be applied in the appropriate circumstances? If not, please explain why not and suggest how the IASB could amend the proposed principle or application guidance to better address these concerns.
- Do you think the proposed application guidance would help restrict the application of the exemption to only the appropriate circumstances? If not, please explain what application guidance you would suggest to achieve that aim.
Principle underpinning the proposed exemption
A24The UKEB welcomes the proposed addition of an exemption in the ED, and the principle underpinning the exemption – that an entity be exempted from disclosing specified information that it would be required to make if such a disclosure can be expected to seriously prejudice the achievement of any of the entity’s acquisition-date key objectives for the business combination (Basis for Conclusions paragraph BC79).
Exemption disclosure requirements
A25During our outreach, there was general support for the exemption, however both users and preparers raised concerns with its application. Preparers are concerned that the disclosure of the use of the exemption in itself may be commercially sensitive. Proposed paragraph B67D46 includes two factors that an entity should consider before using the exemption i.e. being able to describe a specific reason for not disclosing an item of information that identifies the seriously prejudicial effect the entity expects to result from disclosing the information, and whether the information is publicly available. For example, if an entity made an acquisition, as part of a planned ‘strategic’ series of acquisitions to enter a new geographical market, then disclosing the fact that one of its key objective and related target was to achieve x % market share in that geography may seriously prejudice the entity’s ability to carry out further acquisitions in that geographical area. See our UKEB recommendation in paragraph A5 above.
A26In its recent thematic reviews on reporting by the UK’s largest private companies47 and on IAS 37 Provisions, Contingent Liabilities and Contingent Assets48, the UK regulator, the Financial Reporting Council (the ‘FRC’) noted that the rationale for using an exemption is sometimes being taken without obvious justification49.
A27The UKEB recommends that the IASB provide illustrative examples of how such an exemption might be disclosed, for each item of information to which the exemption can be applied, as well as an example of how previously exempt information that is no longer prejudicial be disclosed. Such examples would also assist in clarifying when the exemption could be applied, in addition to the current non-exhaustive list of examples of when it cannot be applied.
Exemption application guidance
A28Some users are concerned about the proposed application guidance that accompanies the exemption (paragraphs B67D–B67G and Basis for Conclusions paragraphs BC90–BC107), which requires an entity to consider disclosing information at a sufficiently aggregated level, if doing so would resolve concerns of commercial sensitivity, before considering using the exemption. Users were concerned that if such aggregation was applied, in certain circumstances it may lead to loss of useful information that alone was not commercially sensitive. For example, where revenue synergies that were commercially sensitive are aggregated with cost synergies that were considered to be non-commercially sensitive.
A29Those users recommend that they would be content to receive information about the cost synergies (assuming they were not commercially sensitive), and the exemption be applied to the revenue synergies (if they were commercially sensitive). We support this suggestion, as this would lead to more useful information being disclosed than information on the aggregated amount for more than one category of synergy, as users tell us they use the information differently.
A30We understand that the proposed requirement is to permit aggregation in different ways, such as aggregation of total revenue synergy and total cost synergy for the same material acquisition, or aggregation of total revenue synergies, for example categories across material acquisitions with the same strategic rationale. However, the UKEB is not certain that it is clear how entities might aggregate certain items of information, and we recommend that the IASB clarify that aggregation would need to be made in a way that meets the overall objective of the disclosures.
A31The UKEB recommends that the IASB does not permit further aggregation of categories of synergy, i.e. not permit the combining of total cost synergies with total revenue synergies, or other categories of synergy for a material business combination; this will ensure that important non-commercially sensitive information is retained for users. (See Question 5 of this appendix for more information on the requirement to disclose quantitative information on expected synergies for each material business combinations).
Appropriate use of exemption
A32Users did not appear to be particularly concerned that the exemption would be used inappropriately and suggested that an entity would knowingly come under more scrutiny where it used an exemption, and therefore entities were likely to use the exemption in only limited circumstances.
A33As noted in the Basis for Conclusion (paragraph BC92), the IASB considered specifying how often it expects entities to apply the exemption—for example, whether it expects the application of the exemption to be extremely rare, similar to the requirement in paragraph 92 of IAS 3750, but decided against doing so. There is some diversity in the understanding of the application of the exemption and the UKEB recommends that the IASB clarify that it expects the exemption to only be used in ‘extremely rare cases’.
Disclosures: Identifying information to be disclosed
Question 4—Disclosures: Identifying information to be disclosed (proposed paragraphs B67A–B67B of IFRS 3)
The IASB is proposing to require an entity to disclose information about the performance of the entity’s strategic business combinations (that is, information about its acquisition-date key objectives and related targets for a strategic business combination and whether these key objectives and related targets are being met) that is reviewed by its key management personnel (see paragraphs BC110–BC114).
The IASB’s proposals would require an entity to disclose this information for as long as the entity’s key management personnel review the performance of the business combination (see paragraphs BC115–BC120).
The IASB is also proposing (see paragraphs BC121–BC130) that if an entity’s key management personnel:
- do not start reviewing, and do not plan to review, whether an acquisition-date key objective and the related targets for a business combination are met, the entity would be required to disclose that fact and the reasons for not doing so;
- stop reviewing whether an acquisition-date key objective and the related targets for a business combination are met before the end of the second annual reporting period after the year of acquisition, the entity would be required to disclose that fact and the reasons it stopped doing so; and
- have stopped reviewing whether an acquisition-date key objective and the related targets for a business combination are met but still receive information about the metric that was originally used to measure the achievement of that key objective and the related targets, the entity would be required to disclose information about the metric during the period up to the end of the second annual reporting period after the year of acquisition.
- Do you agree that the information an entity should be required to disclose should be the information reviewed by the entity’s key management personnel? Why or why not? If not, how do you suggest an entity be required to identify the information to be disclosed about the performance of a strategic business combination?
- Do you agree that:
- an entity should be required to disclose information about the performance of a business combination for as long as the entity’s key management personnel review that information? Why or why not?
- an entity should be required to disclose the information specified by the proposals when the entity’s key management personnel do not start or stop reviewing the achievement of a key objective and the related targets for a strategic business combination within a particular time period? Why or why not?
Management approach
A34The UKEB agrees with the proposals that information required to be disclosed for ‘strategic’ business combinations should be that reviewed and monitored by key management personnel (KMP)51. Whilst some stakeholders suggested that Chief Operating Decision Maker (CODM)52 may be a preferable level of management, we consider that the use of KMP aligns with the objective of providing the relevant performance information on the most important ‘strategic’ business combinations.
A35The UKEB also welcomes the proposed clarification to IAS 36 paragraph 83(b), that the level of management for the purpose of monitoring the subsequent performance of a ‘strategic’ business combination may not be the same as the level of management monitoring the business associated with goodwill for the purpose of impairment testing53.
How long information is required to be disclosed
A36The UKEB supports the proposed requirements to disclose if management either do not start, or stop, monitoring against acquisition-date key objectives and related targets as this will lead to decision useful information for users of accounts. We also agree that the core two full year periods after the year of acquisition is a reasonable timeframe during which an entity must disclose if management stops monitoring the performance of the acquisition against the acquisition-date key objectives and related targets, and to disclose the reason for stopping.
A37The UKEB supports the proposal that if the acquirer changes the metrics it uses to monitor the acquired business (whilst it would need to disclose that it had stopped monitoring against the acquisition-date key objectives), it would not need to disclose those new metrics or performance against those changed metrics, unless it refines (i.e. narrows the range of) the targets, as explained in the Basis for Conclusions (paragraph BC129). However, the UKEB recommends that this information is included in the application guidance, so that it is accessible and clarifies the requirements with regards to changed metrics.
Disclosures: Other proposals
Question 5—Disclosures: Other proposals
The IASB is proposing other amendments to the disclosure requirements in IFRS 3. These proposals relate to:
New disclosure objectives (proposed paragraph 62A of IFRS 3)
The IASB proposes to add new disclosure objectives in proposed paragraph 62A of IFRS 3 (see paragraphs BC23–BC28).
Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
The IASB proposes:
- to require an entity to describe expected synergies by category (for example, revenue synergies, cost synergies and each other type of synergy);
- to require an entity to disclose for each category of synergies:
- the estimated amounts or range of amounts of the expected synergies;
- the estimated costs or range of costs to achieve these synergies; and
- the time from which the benefits expected from the synergies are expected to start and how long they will last; and
- to exempt an entity from disclosing that information in specific circumstances.
See paragraphs BC148–BC163.
The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
The IASB proposes to replace the requirement in paragraph B64(d) of IFRS 3 to disclose the primary reasons for a business combination with a requirement to disclose the strategic rationale for the business combination (see paragraphs BC164–BC165).
Contribution of the acquired business (paragraph B64(q) of IFRS 3)
The IASB proposes to amend paragraph B64(q) of IFRS 3 to improve the information users receive about the contribution of the acquired business (see paragraphs BC166–BC177). In particular, the IASB proposes:
- to specify that the amount of profit or loss referred to in that paragraph is the amount of operating profit or loss (operating profit or loss will be defined as part of the IASB’s Primary Financial Statements project);
- to explain the purpose of the requirement but add no specific application guidance; and
- to specify that the basis for preparing this information is an accounting policy.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
The IASB proposes to improve the information entities disclose about the pension and financing liabilities assumed in a business combination by deleting the word ‘major’ from paragraph B64(i) of IFRS 3 and adding pension and financing liabilities to the illustrative example in paragraph IE72 of the Illustrative Examples accompanying IFRS 3 (see paragraphs BC178–BC181).
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
The IASB proposes to delete some disclosure requirements from IFRS 3 (see paragraphs BC182–BC183).
Do you agree with the proposals? Why or why not?
New disclosure objectives (proposed paragraph 62A of IFRS 3)
A38The UKEB supports the additional disclosure objectives in proposed paragraph 62A of IFRS 354, which provide the foundation for the proposed new disclosure requirements, to:
- respond to users’ need for better information about business combinations at the time of acquisition and on the subsequent performance of the most important acquisitions; and
- allow users to assess those business combinations more effectively.
A39These more specific disclosure objectives should enable preparers to understand better why users need a particular item of information and help entities disclose information that better meets the needs of users.
Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
A40The UKEB supports the new disclosure requirements in relation to the nature, timing and amount of expected synergies from a business combination, as it provides users with a better understanding of why an entity paid the price it did for the business combination. However, the UKEB suggests that the IASB clarifies that the management approach applies to this information, such that disclosure should only be required where synergies drive the rationale for the acquisition, and that the IASB does not expect that quantitative information on expected synergies is prepared solely for the purpose of disclosing in the financial statements.
A41During our outreach, almost all stakeholders supported the IASB’s decision not to define the word ‘synergies’, since the term appears to be widely understood55, and existing paragraph B64(e) of IFRS 3 requires an entity to disclose qualitative information about expected synergies. Feedback suggests that entities do not fail to identify expected synergies appropriately for the current requirements in IFRS 3.
A42The proposed requirement for quantitative information on expected synergies should enable companies to provide contextual and relevant information, rather than the often ‘boilerplate’ qualitative disclosures currently provided on expected synergies, as highlighted in the FRC’s thematic review of business combinations56. Assigning a value to expected synergies should help companies ensure that other separately identifiable intangibles are recognised by the acquirer, although the option to use a range as opposed to a point estimate may result in less useful information. The UKEB agrees with the proposal that such estimates may be disclosed as a range, since it is more likely that entities will estimate the expected synergies as a range.
A43The UKEB supports the proposal to provide quantitative information on expected synergies aggregated by category i.e. to disclose (as a point or as a range) revenue synergies, cost synergies, etc. Requiring more detailed cost synergies, such as employee-related cost synergies, might lead to disclosure of more sensitive information. Therefore, we think the proposal strikes the right balance between disclosure and maintaining confidentially of sensitive information and will address some preparer concerns raised during our outreach.
A44The UKEB also supports the requirement to disclose when the benefits expected from the synergies are expected to start and how long they are expected to last, noting that this disclosure would require the acquirer to specify whether the benefits from the synergies are expected to be finite or indefinite. Some stakeholders expressed views that information on expected synergies was forward-looking and should not be required to be disclosed in the financial statements and would be better suited to the management commentary. However, users were broadly supportive of including this information in the notes to the financial statements due to the audit assurance provided.
A45Some preparers did not concur with the IASB’s view that expected synergies are fixed at the time of acquisition (see Basis for Conclusion paragraph BC139), with some suggesting that this information may not be available at the time of acquisition (for example, in a hostile takeover close to the end of the reporting period), and where available, may be highly judgemental and be costly to provide evidence that the assumptions made in those estimates are reasonable and supportable and why the range of synergies are deemed achievable.
A46It was also noted that other information disclosed in the year of acquisition might be provisional and be adjusted in the ‘measurement period’57, but the same opportunity to adjust information about expected synergies is not proposed58. Therefore, information disclosed might be inconsistent if other provisional information is adjusted in the measurement period, and therefore of limited use to users.
A47The UKEB recommends that the ‘measurement period’ be applied to quantitative information on expected synergies, to provide an acquirer with the opportunity to update information on expected synergies where information comes to light in the ‘measurement period’ and other provisional figures have been adjusted, to ensure that information is consistent.
A48The UKEB welcomes an exemption (see paragraphs A24–A31), where disclosing an item of quantitative information on expected synergies can be expected to prejudice seriously the achievement of any one of the acquirer’s key objectives for the business combination. However, as noted in paragraph A25, some UK preparers’ still have concerns with the exemption requirements to disclose the item to which the exemption has been applied and the reason for applying the exemption to each item. We make a recommendation in paragraph A5 to counteract the risk of disclosing seriously prejudicial and commercially sensitive information.
A49As noted in paragraphs A28–A31, some users are also concerned about the proposed application guidance that accompanies the exemption, which requires entities to consider disclosing information at a sufficiently aggregated level to address concerns over disclosing commercially sensitive information, rather than use the exemption. However, due to the potential loss of useful information that could result, we make a recommendation to the IASB in paragraph A31 in order to provide users with the information they need.
The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
A50The UKEB supports the IASB proposal to replace the requirement in the application guidance paragraph B64(d) of IFRS 3 to disclose the ‘primary reasons’ for a business combination, with a requirement to disclose the ‘strategic rationale’59 for the business combination, acknowledging that, per the Basis for Conclusions (paragraph BC165), the proposed requirement is intended to provide a clearer link between the objectives for a business combination and an entity’s overall business strategy.
Contribution of the acquired business (paragraph B64(q) of IFRS 3)
A51The UKEB supports the IASB proposal in relation to contribution of the acquired business. These should be helpful for users of financial statements to forecast future performance of the combined entity.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
A52The UKEB supports the IASB proposal to improve the information entities disclose about the pension and financing liabilities assumed in a business combination. Users view such liabilities as part of the total capital employed in the business combination.
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
A53The UKEB supports the IASB proposal to delete certain paragraphs from IFRS 3 that are duplicated in other IFRS Accounting Standards or became redundant subsequent to amendments to IFRS 3 in 2008.
Proposed amendments to IAS 36 Impairment of Assets
Changes to the impairment test
Question 6—Changes to the impairment test (paragraphs 80–81, 83, 85 and 134(a) of IAS 36)
During the PIR of IFRS 3, the IASB heard concerns that the impairment test of cash-generating units containing goodwill results in impairment losses sometimes being recognised too late.
Two of the reasons the IASB identified (see paragraphs BC188–BC189) for these concerns were:
- shielding; and
- management over-optimism.
The IASB is proposing amendments to IAS 36 that could mitigate these reasons (see paragraphs BC192–BC193).
Proposals to reduce shielding
A50.A51. The UKEB supports the IASB proposal in relation to contribution of the acquired business. These should be helpful for users of financial statements to forecast future performance of the combined entity.
Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
A51.A52. The UKEB supports the IASB proposal to improve the information entities disclose about the pension and financing liabilities assumed in a business combination. Users view such liabilities as part of the total capital employed in the business combination.
Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
A52.A53. The UKEB supports the IASB proposal to delete certain paragraphs from IFRS 3 that are duplicated in other IFRS Accounting Standards or became redundant subsequent to amendments to IFRS 3 in 2008.
Proposed amendments to IAS 36 Impairment of Assets
Changes to the impairment test
| Question 6—Changes to the impairment test (paragraphs 80–81, 83, 85 and 134(a) of IAS 36) |
|---|
| During the PIR of IFRS 3, the IASB heard concerns that the impairment test of cash-generating units containing goodwill results in impairment losses sometimes being recognised too late. Two of the reasons the IASB identified (see paragraphs BC188–BC189) for these concerns were: - shielding; and - management over-optimism. The IASB is proposing amendments to IAS 36 that could mitigate these reasons (see paragraphs BC192–BC193). Proposals to reduce shielding |
The IASB considered developing a different impairment test that would be significantly more effective at a reasonable cost but concluded that doing so would not be feasible (see paragraphs BC190–BC191). Instead, the IASB is proposing changes to the impairment test (see paragraphs 80–81, 83 and 85 of IAS 36) to reduce shielding by clarifying how to allocate goodwill to cash-generating units (see paragraphs BC194–BC201).
Proposal to reduce management over-optimism
The IASB’s view is that management over-optimism is, in part, better dealt with by enforcers and auditors than by amending IAS 36. Nonetheless, the IASB is proposing to amend IAS 36 to require an entity to disclose in which reportable segment a cash-generating unit or group of cash-generating units containing goodwill is included (see paragraph 134(a) of IAS 36). The IASB expects this information to provide users with better information about the assumptions used in the impairment test and therefore allow users to better assess whether an entity’s assumptions are over-optimistic (see paragraph BC202).
- Do you agree with the proposals to reduce shielding? Why or why not?
- Do you agree with the proposal to reduce management over-optimism? Why or why not?
Proposals to reduce shielding
How to allocate goodwill to cash-generating units (CGUs)
A53.A54. The UKEB supports the addition of paragraphs 80A and 80B30 to clarify that the CGU relevant for impairment testing is the lowest level at which management monitors the business associated with the goodwill, and that it should not be larger than an operating segment as defined by paragraph 5 of IFRS 8 before aggregation31. The change in focus to the business associated with the goodwill, as opposed to the goodwill, is also welcome since it is the business associated with goodwill that will be monitored, not the goodwill.
A54.A55. However, the IASB should be aware that this requirement may not achieve the intended reduction in shielding of goodwill, since goodwill is not allocated to the CGU or group of CGUs expected to benefit from the goodwill, if financial information is not regularly received by management at that lowest level of CGUs to monitor the business associated with goodwill. Therefore, goodwill could be more shielded than if the allocation of goodwill was based solely on the CGUs expected to benefit from the synergies.
Proposal to reduce management over-optimism
Disclose reportable segments which include a CGU or group of CGUs containing goodwill
A55.A56. The UKEB supports the proposal requiring an entity to disclose the reportable segment in which a CGU or group of CGUs containing goodwill is included. This should not result in significant costs, since entities already have this information, and some entities already disclose this information voluntarily. Therefore, the benefits of increased transparency for users would outweigh any costs.
A56.A57. The risk of management over-optimism is inherent in any impairment-only model. Requiring disclosure of the reportable segment in which a CGU containing goodwill is included would help users better assess and challenge the reasonableness of assumptions used in the impairment test. Users would be able to compare these assumptions with the information they receive about reportable segments and with their own assumptions about the future performance of those reportable segments. It aligns with the project objective of providing better information about business combinations.
A58. Whilst To address user's are concerneds that impairment losses are sometimes recognised too late and that there is no transparency on ‘close calls' for impairment losses that are not recognised, the UKEB notes that the existing disclosure requirements in IAS 36.134(f) should be sufficient, i.e. an entity is required to provide sensitivity analysis if a reasonably possible change in a key assumption used in impairment testing would cause the carrying amount to exceed its recoverable amount recommends that the IASB includes requirements for an entity to disclose the amount of headroom for each CGU containing goodwill, where that headroom is marginal. This should will help users identify if there are any 'close calls' with regards to impairment losses not being recognised and may go some way to address the concern of users that impairment losses are sometimes recognised too late.
A57.A59. The UKEB recommends that the IASB require entities to disclose how CGUs have been identified to which goodwill is allocated, and to disclose any changes in CGUs and in the allocation of goodwill to those CGUs since the prior period. The IASB could also consider extending this requirement to show the related segments for the respective changes.
Changes to the impairment test: Value in use
| Question 7—Changes to the impairment test: Value in use (paragraphs 33, 44–51, 55, 130(g), 134(d)(v) and A20 of IAS 36) |
|---|
| The IASB is proposing to amend how an entity calculates an asset’s value in use. In particular, the IASB proposes: - to remove a constraint on cash flows used to calculate value in use. An entity would no longer be prohibited from including cash flows arising from a future restructuring to which the entity is not yet committed or cash flows arising from improving or enhancing an asset’s performance (see paragraphs BC204–BC214). - to remove the requirement to use pre-tax cash flows and pre-tax discount rates in calculating value in use. Instead, an entity would be required to use internally consistent assumptions for cash flows and discount rates (see paragraphs BC215–BC222). |
|
A58.A60. The proposed changes to the calculation of value in use applies to all assets tested for impairment in accordance with IAS 36, and not solely goodwill. The IASB should be aware that, since impairment losses on certain assets (excluding goodwill) are permitted to be reversed, the proposed changes could lead to reversal of impairment for some assets.
Removal of constraint to allowing cash flows from future uncommitted restructuring and from improving or enhancing an asset's performance
A59.A61. During our outreach, stakeholders suggested that removal of the constraint could increase the risk that management use over-optimistic inputs in calculating value in use, so that the results are contrary to the IASB’s aim – timely recognition of impairment losses. An increase in the measured value in use could therefore delay the recognition of impairment losses; if the measured value in use (VIU) increases and is higher than the fair value less costs of disposal, and if the VIU (recoverable amount) is higher than the carrying value, it could avoid or further delay the recognition of any impairment.
A60.A62. Whilst the UKEB recognises some stakeholder concerns, the UKEB agrees with the proposal to remove the constraint to reduce the cost and complexity of the value in use calculation, by using internally consistent assumptions. However, we recommend to the IASB that the proposal is redrafted so that entities are required to include cash flows from uncommitted restructuring or asset improvements.
A61.A63. The IASB proposal to remove the restriction on including cash flows arising from uncommitted restructuring or asset improvements could lead to inconsistent treatment and lack of comparability. The UKEB also recommends that the potential lack of consistency and comparability could be addressed by requiring entities to:
- a) disclose the fact that the where recoverable amount of a CGU includes cash flows from uncommitted restructuring or asset improvements;
- a)b) disclose the nature and amounts of those uncommitted restructurings and when those are planned to occur; and
- b)c) disclose the risks associated with including such cash flows.
Permit the use of post-tax cash flows and post-tax discount rates
A64. The UKEB welcomes the proposal to permit the use of post-tax cash flows and post-tax discounts rates in calculating value in use and to disclose which rate has been used, since it is anticipated that this will align the standard with current practice.
A62.A65. As a result of the proposed amendments to the IAS 36 VIU calculation, stakeholders have noted that there are fewer differences between the VIU and fair value less cost of disposal (FVLCD) method of calculating the recoverable amount for the purpose of the impairment test and we suggest that the IASB clarifies the remaining differences in the methods.
Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures
| Question 8—Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures |
|---|
| The IASB proposes to amend the forthcoming IFRS X Subsidiaries without Public Accountability: Disclosures (Subsidiaries Standard) to require eligible subsidiaries applying the Subsidiaries Standard to disclose: - information about the strategic rationale for a business combination (proposed paragraph 36(ca) of the Subsidiaries Standard); - quantitative information about expected synergies, subject to an exemption in specific circumstances (proposed paragraphs 36(da) and 36A of the Subsidiaries Standard); - information about the contribution of the acquired business (proposed paragraph 36(j) of the Subsidiaries Standard); and - information about whether the discount rate used in calculating value in use is pre-tax or post-tax (paragraph 193 of the Subsidiaries Standard). See paragraphs BC252–BC256. Do you agree with the proposals? Why or why not? |
A63.A66. The UKEB welcomes the reduced disclosure requirements for eligible subsidiaries, which will reduce the cost for preparers by only requiring the disclosure of information considered useful to users of those financial statements.
Transition
| Question 9—Transition (proposed paragraph 64R of IFRS 3, proposed paragraph 1400 of IAS 36 and proposed paragraph B2 of the Subsidiaries Standard) |
|---|
| The IASB is proposing to require an entity to apply the amendments to IFRS 3, IAS 36 and the Subsidiaries Standard prospectively from the effective date without restating comparative information. The IASB is proposing no specific relief for first-time adopters. See paragraphs BC257–BC263. Do you agree with the proposals? Why or why not? If you disagree with the proposals, please explain what you would suggest instead and why. |
A64.A67. The UKEB is not aware of any significant concerns with the prospective transition requirements. The prospective requirements should provide enough time for internal controls and process to be updated. Not requiring restatement of comparative information will reduce any burden on preparers and remove any potential for use of hindsight in providing the information.
A65.A68. The UKEB is not aware of any concerns with not providing relief for first-time adopters, given that they are expected to plan their transition to IFRS Accounting Standards with enough time.
Appendix B: Proposed Flowchart
Figure 1: UKEB recommendation
- determination of 'strategic'* business combinations
*The UKEB recommend that 'strategic' business combinations are termed 'major' business combinations
Exposure Draft Business Combinations – Disclosures, Goodwill and Impairment Proposed amendments to IFRS 3 and IAS 36 Final Comment Letter (FCL) July 2024
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The comment letter to which this feedback statement relates forms part of those influencing activities and is intended to contribute to the IFRS Foundation’s due process.
The views expressed by the UKEB in its comment letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
- Executive Summary
- Background
- Outreach and feedback on the DCL
- Final Comment Letter (FCL)
- Feedback Statement
- [Draft] Due Process Compliance Statement (DPCS)
- Next steps
- Timeline
- Appendix A: UKEB response to detailed questions in IASB Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
- Invitation to Comment: Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
- Proposed amendments to IFRS 3 Business Combinations
- Proposed amendments to IFRS 3 Business Combinations
- Integration of acquired business
- Disclosures: Strategic business combinations
- Terminology – strategic or major
- Principles-based identification
- Series of acquisitions
- Quantitative thresholds
- Step acquisitions
- Qualitative thresholds
- Disclosures: Exemption from disclosing information
- Principle underpinning the proposed exemption
- Exemption disclosure requirements
- Exemption application guidance
- Appropriate use of exemption
- Disclosures: Identifying information to be disclosed
- Management approach
- How long information is required to be disclosed
- Disclosures: Other proposals
- New disclosure objectives (proposed paragraph 62A of IFRS 3)
- Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
- The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
- Contribution of the acquired business (paragraph B64(q) of IFRS 3)
- Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
- Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
- Contribution of the acquired business (paragraph B64(q) of IFRS 3)
- Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
- Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
- Proposed amendments to IAS 36 Impairment of Assets
- Removal of constraint to allowing cash flows from future uncommitted restructuring and from improving or enhancing an asset's performance
- Permit the use of post-tax cash flows and post-tax discount rates
- Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures
- Transition
- Appendix B: Proposed Flowchart
- Appendix A: UKEB response to detailed questions in IASB Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment
- Disclosures: Exemption from disclosing information
- Disclosures: Identifying information to be disclosed
- Disclosures: Other proposals
- Question 5—Disclosures: Other proposals
- New disclosure objectives (proposed paragraph 62A of IFRS 3)
- Requirements to disclose quantitative information about expected synergies in the year of acquisition (proposed paragraph B64(ea) of IFRS 3)
- The strategic rationale for a business combination (paragraph B64(d) of IFRS 3)
- Contribution of the acquired business (paragraph B64(q) of IFRS 3)
- Classes of assets acquired and liabilities assumed (paragraph B64(i) of IFRS 3)
- Deleting disclosure requirements (paragraphs B64(h), B67(d)(iii) and B67(e) of IFRS 3)
- Proposed amendments to IAS 36 Impairment of Assets
- Proposed amendments to IAS 36 Impairment of Assets
- Changes to the impairment test
- Proposals to reduce shielding
- How to allocate goodwill to cash-generating units (CGUs)
- Proposal to reduce management over-optimism
- Disclose reportable segments which include a CGU or group of CGUs containing goodwill
- Changes to the impairment test: Value in use
- Removal of constraint to allowing cash flows from future uncommitted restructuring and from improving or enhancing an asset's performance
- Permit the use of post-tax cash flows and post-tax discount rates
- Proposed amendments to IFRS X Subsidiaries without Public Accountability: Disclosures
- Transition
- Appendix B: Proposed Flowchart
- Purpose of this Feedback Statement
- The IASB's Exposure Draft
- Outreach approach
- UKEB and stakeholder views
- Disclosures: Performance of a business combination (proposed paragraphs B67A–B67G of IFRS 3)
- Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
- Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
- Disclosures: Exemption from disclosing information (proposed paragraphs B67D–B67G of IFRS 3)
- Disclosures: Identifying information to be disclosed (proposed paragraphs B67A–B67B of IFRS 3)
- Disclosures: Other proposals in IFRS 3
- UKEB and stakeholder views
- UKEB and stakeholder views
- UKEB and stakeholder views
- Disclaimer
- Contact Us
- Appendix D: Due Process Compliance Statement: Exposure Draft Business Combinations – Disclosures, Goodwill and Impairment – Proposed amendments to IFRS 3 and IAS 36
- Draft Comment Letter (DCL)
- Project finalisation and project closure
- Ongoing communications
- Conclusion
Purpose of this Feedback Statement
This feedback statement presents the views of UK stakeholders received during the UKEB’s outreach activities on the IASB’s Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment issued on 14 March 2024, and explains how the UKEB’s Final Comment Letter addressed those views.
The IASB's Exposure Draft
The proposed amendments to IFRS 3 Business Combinations include:
- requirements to disclose information about the performance of a business combination against acquisition-date key objectives and related targets, for a subset of an entity’s material business combinations—termed ‘strategic’
- identifying ‘strategic’ acquisitions using a set of qualitative and quantitative thresholds (threshold approach)
- requirement to disclose quantitative information about expected synergies for each material acquisition
- an exemption, to address concerns around commercial sensitivity and litigation risk
- other targeted amendments to the disclosure requirements.
The proposed amendments to IAS 36 Impairment of Assets include:
- clarifying how an entity allocatees goodwill to cash-generating units (CGUs)
- requiring an entity to disclose in which reportable segment a CGU or group of CGUs containing goodwill is included
- changes to how an entity calculates an asset’s value in use (VIU). In particular, no longer prohibiting the inclusion of cash flows arising from a future restructuring to which the entity is not yet committed or from improving or enhancing an asset’s performance and removing the requirement to use pre-tax cash flows and pre-tax discount rates.
Finally, the ED also proposes:
- reduced disclosures to be included within IFRS 19 Subsidiaries without Public Accountability: Disclosures which would not require such entities to disclose the proposed information for ‘strategic’ business combinations
- prospective transition - an entity would apply the amendments to IFRS 3, IAS 36 and IFRS 19 prospectively from the effective date without restating comparative information, with no specific relief for first-time adopters.
Outreach approach
The UKEB’s outreach activities took place between February 2024 and July 2024 and were conducted to develop the UKEB Comment Letter on the ED.
All comments and views were considered in reaching the UKEB’s final assessment of the proposed amendments.
Outreach activities included:
- Discussions with the UKEB Advisory Groups:
- Academic Advisory Group
- Accounting Firms and Institutes Advisory Group
- Investor Advisory Group and
- Preparer Advisory Group
- A roundtable with users and preparers
- Meetings with preparers and a regulator
- Public consultation on the UKEB’s Draft Comment Letter (DCL).
The DCL was published for 30 days, between 31 May 2024 and 1 July 2024.
The UKEB promoted awareness of the DCL and encouraged stakeholders to respond through the UKEB website, UKEB subscriber News alerts and sharing the DCL with our outreach participants.
Four written responses to the DCL were received, two from accounting firms, one from a preparer, and one from an industry body.
Stakeholder feedback, together with UKEB Advisory Group feedback and informal feedback received during the comment period, is summarised on the following pages.
Although many stakeholders agreed with the UKEB draft position, there continued to be mixed views on the ED proposals and some of the UKEB recommendations. However, there was no substantive new evidence, resulting in few changes to the DCL.
| Stakeholder type | Organisations represented (excl. DCL responses) | Formal responses to DCL |
|---|---|---|
| Industry body* | - | 1 |
| Preparers | 6 | 1 |
| Users | 1 | - |
| Accounting firms and institutes | - | 2 |
| Investor body | 1 | - |
| Regulator | 1 | - |
| UKEB Advisory Groups | 4 | - |
| National Standard Setter | 1 | - |
| Total | 14 | 4 |
* one industry body representing 22 preparers
UKEB and stakeholder views
Disclosures: Performance of a business combination (proposed paragraphs B67A–B67G of IFRS 3)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Require an entity to disclose information about the performance of a business combination. In particular, to disclose: - information about the entity’s acquisition-date key objectives and related targets for a business combination; and - whether these key objectives and related targets are being met. | Agreed with the IASB’s objective for the disclosure and the proposed additional disclosures about the performance of business combinations Supported an exemption (see slide 9) but suggested improvements to ensure the exemption is only used in appropriate circumstances and to address: - preparer concerns around exemption disclosures - user concerns with obscuring important information. | Most stakeholders agreed with the UKEB’s draft position, supporting the objective for additional performance disclosures. However, there continued to be mixed views on the disclosure requirements and concerns continued to be raised about: - location of the information in the financial statements – as opposed to analyst packs or strategic report; - auditability of forward-looking information and objective and targets for non-IFRS measures; - relevance of acquisition-date key objectives and targets to users; - increase in audit costs and the cost of compliance of bringing non-IFRS measures, used internally to measure performance, into the scope of the financial statements. Similar views were expressed for both the requirements on performance information for ‘strategic’ acquisitions (slide 8) and on quantitative expected synergy information for all ‘material’ acquisitions (slide 11) | Consistent with draft position – not all entities provide additional voluntary information outside the financial statements and requiring information in the financial statements leads to greater accessibility and comparability across entities, industries and jurisdictions. Users welcomed the additional disclosures |
Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| - Performance against acquisition-date key objectives and related targets of the business combination is required for only a subset of material acquisitions – namely ‘strategic’. - A strategic business combination would be one for which failure to meet any one of an entity’s acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy (BC54). - ‘Strategic’ acquisitions are identified using a set of quantitative and qualitative thresholds (threshold approach) – an acquisition that meets any one of these thresholds would be considered ‘strategic’. | - Recommended replacing the term ‘strategic’ with the term ‘major’ – many consider all acquisitions to be strategic. - Expressed concern that using solely a ‘threshold approach’ may not capture just the most important acquisitions. - Suggested: ✓ a principles-based approach as opposed to closed threshold approach, allowing the presumption to be rebutted (after applying the thresholds) based on the definition of a ‘strategic’ acquisition (BC54) ✓ additional guidance on ‘operating profit’ ✓ an additional quantitative threshold – market capitalisation (for listed companies) ✓ more guidance on how to disclose a ‘series’ of important acquisitions ✓ examples to clarify application of materiality for qualitative thresholds. | - Most shared the UKEB’s concerns about the term ‘strategic’, but some recommended the terms ‘significant’, ‘reportable’, or ‘substantial’, rather than ‘major’. - Concerns continued to be raised that the proposed 10% quantitative threshold is too low, with some stakeholders suggesting that the ‘operating profit’ threshold be removed. - Stakeholders also suggested clarifications / amendments for: - how to disclose a ‘series’ which occurs over different reporting periods - whether the UKEB proposed market capitalisation threshold is absolute or relative – and that it could be volatile - examples to clarify application of materiality are unnecessary. - Some stakeholders questioned: - whether the rebuttable presumption would capture ‘strategic’ acquisitions not caught by the thresholds, and - the proposed definition of the rebuttable presumption. | Broadly consistent with the draft position – the proposed rebuttable presumption should address concerns that the 10% threshold is too low. Some amendments / clarifications made: - Included more terms other than ‘strategic’ for the IASB to consider - Added a suggestion that the IASB consider further how an entity might disclose a series of acquisitions that occurs over different reporting periods - Clarified that the suggested market capitalisation threshold is relative i.e. 10% - Deleted UKEB suggestion to provide examples for applying materiality to qualitative thresholds. |
Disclosures: Strategic business combinations (proposed paragraph B67C of IFRS 3)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Performance against acquisition-date key objectives and related targets of the business combination is required for only a subset of material acquisitions — namely 'strategic'. | • Recommended replacing the term 'strategic' with the term 'major' – many consider all acquisitions to be strategic. | • Most shared the UKEB's concerns about the term 'strategic', but some recommended the terms 'significant', 'reportable', or 'substantial', rather than 'major'. | Broadly consistent with the draft position – the proposed rebuttable presumption should address concerns that the 10% threshold is too low. |
| • A strategic business combination would be one for which failure to meet any one of an entity's acquisition-date key objectives would put the entity at serious risk of failing to achieve its overall business strategy (BC54). | • Expressed concern that using solely a 'threshold approach' may not capture just the most important acquisitions. | • Concerns continued to be raised that the proposed 10% quantitative threshold is too low, with some stakeholders suggesting that the 'operating profit' threshold be removed. | Some amendments / clarifications made: |
| • 'Strategic' acquisitions are identified using a set of quantitative and qualitative thresholds (threshold approach) – an acquisition that meets any one of these thresholds would be considered 'strategic'. | • Suggested: ✓ a principles-based approach as opposed to closed threshold approach, allowing the presumption to be rebutted (after applying the thresholds) based on the definition of a 'strategic' acquisition (BC54) ✓ additional guidance on 'operating profit' ✓ an additional quantitative threshold – market capitalisation (for listed companies) ✓ more guidance on how to disclose a 'series' of important acquisitions ✓ examples to clarify application of materiality for qualitative thresholds. |
• Stakeholders also suggested clarifications / amendments for: • how to disclose a 'series' which occurs over different reporting periods ○ whether the UKEB proposed market capitalisation threshold is absolute or relative – and that it could be volatile • examples to clarify application of materiality are unnecessary. |
• Included more terms other than 'strategic' for the IASB to consider • Added a suggestion that the IASB consider further how an entity might disclose a series of acquisitions that occurs over different reporting periods • Clarified that the suggested market capitalisation threshold is relative i.e. 10% • Deleted UKEB suggestion to provide examples for applying materiality to qualitative thresholds. |
| • Some stakeholders questioned: • whether the rebuttable presumption would capture 'strategic' acquisitions not caught by the thresholds, and ○ the proposed definition of the rebuttable presumption. |
Disclosures: Exemption from disclosing information (proposed paragraphs B67D–B67G of IFRS 3)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • An entity would be exempt from disclosing some of the information in specific circumstances to respond to preparers' concerns about commercial sensitivity and litigation risk. | • Generally supportive of exemption and underlying principle. | Stakeholders largely agreed with the UKEB's draft position, but there continued to be mixed views about whether the exemption is narrowly drafted (i.e. could not be used in all circumstances needed) or broad defined (its subjective nature will be difficult for auditors to challenge). | Broadly retained draft position, as the UKEB suggestion to limit the use of the exemption to “extremely rare cases", is consistent with IAS 37 Provisions, Contingent Assets and Contingent Liabilities and it is expected there would be a discussion between entities and auditors about appropriate use. |
| • As a principle, an entity is exempt from disclosing if doing so can be expected to prejudice seriously the achievement of any of the entity's acquisition-date key objectives for the business combination. | • Suggested the IASB: ✓ clarify the exemption only to be used 'in extremely rare cases' (similar to IAS 37) ✓ permit entities not to disclose the reason for invoking the exemption, if that disclosure could be seriously prejudicial ✓ provide illustrative examples for disclosures of exemptions ✓ clarify how an entity might 'sufficiently aggregate' information rather than using the exemption i.e. is this aggregation by acquisition or across acquisitions? |
Some stakeholders suggested the UKEB clarify its proposal to not disclose the reason for invoking the exemption i.e. disclosure of applying the exemption should still be required, as users need such information to assess or challenge management's intentions. | Clarified the UKEB suggestion that an entity should not be required to disclose the reason for applying the exemption, by adding that an entity should still disclose the fact that it has applied the exemption, for example, for some key objectives and related targets. |
| • Application guidance includes: • disclosing the reason for applying the exemption for each item of information • reassessing in future periods whether the exemptions should still be applied • considering if that information was already disclosed in other public available material ○ considering aggregating information at a sufficient level to resolve concerns, rather than applying the exemption. |
Disclosures: Identifying information to be disclosed (proposed paragraphs B67A–B67B of IFRS 3)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Requires an entity to disclose: • information* that is reviewed by its key management personnel (KMP) • for as long as the entity's KMP review the performance of the combination • the fact and the reason, if KMP either (a) do not start reviewing, or (b) stop reviewing before the end of the second annual reporting period after the year of acquisition • information about the metric that was originally used to measure the achievement of that key objective and related targets, even if an entity stops reviewing, but still receives that information, during the period up to the end of the second annual reporting period after the year of acquisition. |
• Supported the IASB proposal that the information required to be disclosed for 'strategic' business combinations should be that reviewed and monitored by KMP. | Most stakeholders agreed with the UKEB's draft position, but continued to raised concern that some information could be required to be disclosed indefinitely if management do not change metrics from those set at acquisition date. | Retained draft position – we believe that most entities would only track acquisition-date key objectives and related targets for a limited period, regardless of whether the acquired business is integrated or not. |
| • Agreed that the core two-year period is a reasonable timeframe. | Disclosure should not be onerous, as it is only required for information received and reviewed by management. | ||
| • Supported the proposal not to disclose changed metrics, unless it refines i.e. narrows the range of the targets, as explained in the Basis for Conclusions (BC129). However, suggested that the IASB includes the guidance on changed metrics in the body of the standard. |
*Information about the performance of the entity's strategic business combinations, being the acquisition-date key objectives and related targets for a strategic business combination and whether these key objectives and related targets are being met
Disclosures: Other proposals in IFRS 3
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Other amendments to the disclosure requirements in IFRS 3: • New disclosure objectives—proposed paragraph 62A • Requirements to disclose quantitative information about expected synergies in the year of acquisition for each 'material' acquisition—proposed paragraph B64(ea): ○ by category (for example, revenue synergies, cost synergies and each other type of synergy), • the estimated amounts or range of amounts of the expected synergies • the estimated costs or range of costs to achieve these synergies • the time from which the benefits expected from the synergies are expected to start and how long they will last, and ○ to exempt an entity from disclosing expected synergies in specific circumstances |
Supported the additional disclosure objectives in proposed paragraph 62A. | Some stakeholders agreed with the UKEB's draft position. | Broadly retained draft position, as similar feedback was considered for the draft. |
| With regards to the proposed disclosure of expected synergies in the year of acquisition for each 'material' business combination: • suggested a 'measurement period' similar to existing requirements in IFRS 3 where amounts accounted for on acquisition are provisional • suggested that the exemption guidance not permit aggregation of categories of synergies, due to the potential loss of important information for users. |
However, there continued to be mixed views on requiring entities to disclose quantitative information on expected synergies for 'material' acquisitions: • location – forward-looking is best located in management commentary • scope - the requirements are onerous and costly to prepare—some suggested the IASB only require for listed entities • auditability – assurance would pose a challenge • relevance – synergy disclosures should only be required where synergies drive the rationale for the acquisition and information should not be prepared solely for disclosure in financial statements. |
Updated to suggest that synergy information should only be required to be disclosed where such information was used by management in determining the price paid for the acquisition | |
| Other amendments to IFRS 3 disclosures: • Replacing the 'primary reasons' for a business combination in paragraph B64(d) with 'strategic rationale' |
Other comments were made regarding the IASB's decision not to reintroduce goodwill included. | ||
| • Contribution (revenue and profit or loss) of the acquired business (often referred to as pro forma information) ○ amending paragraph B64(q) to update 'profit or loss' to 'operating profit or loss' (as defined in IFRS 18) ○ explaining the purpose of the existing disclosure requirement • specifying that the basis for preparing this information is an accounting policy |
Supportive of the other proposed amendments. | Stakeholders generally agreed with the UKEB's draft position, although some suggested other useful disclosure they would like about acquired businesses. | As per draft position – operating profit as per IFRS 18 is defined so will lead to consistency of information and there is sufficient information on amortisation if users choose to remove for their analysis. |
| • Improving the information that entities disclose about the pension and financing liabilities assumed in a business combination by deleting the word 'major' from paragraph B64(i) and adding pension and financing liabilities to the Illustrative Examples (IE72) | Regarding the contribution of the acquiree to the combined business, some were concerned that operating profit was not an improved measure, as it includes amortisation which is often stripped out by investors to get a clearer picture of operating performance. Others thought that specifying the basis of preparation is an accounting policy was unnecessary and the basis could be sufficiently disclosed in the notes to the accounts. | An accounting policy is subject to greater discipline and leads to greater consistency of application for all acquisitions. | |
| • Deleting disclosure requirements in paragraphs B64(h), B67(d)(iii) and B67(e). |
UKEB and stakeholder views
Changes to the impairment test in IAS 36 (paragraphs 80–81, 83, 85 and 134(a) of IAS 36)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| To reduce shielding. • by clarifying how an entity allocates goodwill to cash-generating units (CGUs). |
• Supported the IASB's proposed additional paragraphs 80A and 80B to clarify that the CGU relevant for impairment testing is the lowest level at which management monitors the business associated with the goodwill, and that it should not be larger than an operating segment as defined by paragraph 5 of IFRS 8 before aggregation. | Most stakeholders agreed that the proposed clarifications may not have the intended consequences to change practice and therefore do not go far enough to reduce shielding of goodwill. However, we also heard that no further disclosures are required. | Broadly as per draft, but DCL amended to: • remove UKEB suggestion to require disclosure of headroom where marginal, as many stakeholders thought existing requirements* to disclose key assumptions and sensitivity analysis are adequate |
| To reduce management over-optimism. • by requiring an entity to disclose in which reportable segment a CGU or group of CGUs containing goodwill is included. |
• Cautioned the IASB that this clarification may not change practice and therefore may not achieve the intended reduction in shielding of goodwill. | Many stakeholders noted that the UKEB recommended headroom disclosure would not provide additional useful information to that already required in IAS 36*. It was also suggested the UKEB clarify how it defines 'marginal'. | • add suggestion that entities disclose how they determine the CGUs to which goodwill is allocated and any changes since prior period. |
| • Supported the disclosure of reportable segments in which CGUs containing goodwill are included. | Other suggestions included closing the loophole, whereby management can re-pool CGUs and move goodwill without disclosure. | ||
| • Suggested requiring the disclosure of the amount of headroom, where the amount of headroom is marginal. |
*IAS 36.134(f) requires an entity to provide sensitivity analysis if a reasonably possible change in a key assumption used in impairment testing would cause the carrying amount to exceed its recoverable amount, and therefore require impairment.
Changes to the impairment test in IAS 36: Value in use calculation (paragraphs 33, 44–51, 55, 130(g), 134(d)(v) and A20 of IAS 36)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Amend how an entity calculates an asset's value in use (VIU): • to remove a constraint on cash flows used to calculate value in use. An entity would no longer be prohibited from including cash flows arising from a future restructuring to which the entity is not yet committed, or cash flows arising from improving or enhancing an asset's performance; |
• Supported proposed changes to VIU in principle. | Whilst the majority of stakeholders agreed with the UKEB's draft position supporting the removal of the constraint on uncommitted restructuring cash flows, concern continued that it would result in delayed impairment. | Consistent with draft position but DCL amended to: • enhance the UKEB recommendation to disclose when uncommitted restructuring cashflows are included in recoverable amount (VIU), by suggesting the disclosure include the nature, the amounts and expected timing of the restructuring |
| • to remove the requirement to use pre-tax cash flows and pre-tax discount rates in calculating value in use. Instead, an entity would be required to use internally consistent assumptions for cash flows and discount rates. | • Suggested that entities be required to include such cash flows, rather than permitted, to ensure consistency of application. | Another concern raised by several stakeholders that the change to the VIU calculation brings it closer to the fair value less cost of disposal (FVLCD) calculation—the IASB should clarify the remaining differences. | • add recommendation that the IASB provide guidance on what the resulting difference is between VIU and FVLCD and why they should still be viewed differently. |
| • To mitigate risk of management over-optimistic, suggested adding a requirement to disclose: • when recoverable amount includes cash flows from uncommitted restructuring and asset enhancement, • the associated risks of including such cash flows. |
One stakeholder suggested that the UKEB could be more specific in our proposed disclosure when uncommitted cash flows are included in VIU, such as disclosing the fact, the nature, the amounts, expected timing, etc. | ||
| • Welcomed the proposal to permit the use of post-tax cash flows and post-tax discounts rates in calculating VIU to align with current practice. | Almost all stakeholders supported the use of post-tax cash flows and post-tax discount rates. |
UKEB and stakeholder views
Proposed amendments to IFRS 19 Subsidiaries without Public Accountability: Disclosures
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Amend IFRS 19 Subsidiaries without Public Accountability: Disclosures (Subsidiaries Standard) to require eligible subsidiaries applying the Subsidiaries Standard to disclose: • information about the strategic rationale for a business combination • quantitative information about expected synergies, subject to an exemption in specific circumstances • information about the contribution of the acquired business • information about whether the discount rate used in calculating value in use is pre-tax or post-tax. |
Welcomed the reduced disclosure requirements for eligible subsidiaries, which will reduce the cost for preparers by only requiring the disclosure of information considered useful to users of those financial statements. | Most stakeholders agreed with the UKEB's draft position. | Consistent with draft position – we consider that the reduced disclosure information is important for users of the financial statements and the proposed requirements are proportionate. |
| Some stakeholders suggested that: • quantitative information on expected synergies should not be required for eligible subsidiaries without public accountability, and required only for listed entities • if disclosures about acquisitions are provided in the group's consolidated financial statements, there should not be a requirement to disclose in the subsidiary's accounts, provided an appropriate cross-reference is included. |
UKEB and stakeholder views
Transition (proposed paragraph 64R of IFRS 3, proposed paragraph 140O of IAS 36 and proposed paragraph B2 of the Subsidiaries Standard IFRS 19)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Require an entity to apply the amendments to IFRS 3, IAS 36 and the Subsidiaries Standard prospectively from the effective date without restating comparative information. | • Not aware of any significant concerns with the prospective transition requirements. | Most stakeholders agreed with the UKEB's draft position. | Consistent with draft position. |
| • No specific relief for first-time adopters. | • Not aware of any concerns with not providing relief for first-time adopters. |
Disclaimer
This Feedback Statement has been produced in order to set out the UKEB's response to stakeholder comments received on the UKEB's Draft Comment Letter on the IASB's Exposure Draft Business Combinations – Disclosures, Goodwill and Impairment Proposed amendments to IFRS 3 and IAS 36 and should not be relied upon for any other purpose.
The views expressed in this Feedback Statement are those of the UK Endorsement Board at the point of publication.
Any sentiment or opinion expressed within this Feedback Statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board 6th Floor
| 10 South Colonnade | London | E14 4PU www.endorsement-board.uk
Appendix D: Due Process Compliance Statement: Exposure Draft Business Combinations – Disclosures, Goodwill and Impairment – Proposed amendments to IFRS 3 and IAS 36
The International Accounting Standards Board (IASB) published the Exposure Draft (ED) Business Combinations – Disclosures, Goodwill and Impairment Proposed amendments to IFRS 3 and IAS 36 on 14 March
- The IASB comment period ended on 15 July 2024.
Influencing process
Project preparation
| Step | Mandatory / optional? | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Added to UKEB technical work plan [Due Process Handbook (Handbook) 4.30] | Mandatory | Project included in the UKEB published technical work plan | Complete: the Exposure Draft (ED) was anticipated and included in the UKEB technical work plan published in January 2023. |
| Project Initiation Plan (PIP) [Handbook 5.4 to 5.8, A1 to A2 and A12 to A14] | Mandatory | PIP draft with project outline (background, scope, project objective) and approach for influencing (key milestones and timing) | Complete: The UKEB Secretariat included mandatory milestones for the project and considered, as appropriate, other milestones and activities. The PIP was approved at the 28 March 2024 Board meeting. |
| Mandatory | Outreach plan for stakeholders and communication approach outlined | Complete: The PIP included the outreach plan and approach. | |
| Mandatory | Resources allocated | Complete: One project director, with technical support and oversight from a senior project director, was allocated to the project. | |
| Mandatory | Assessment of whether to set up an ad-hoc advisory group | Complete: Taking a proportionate approach, an ad-hoc advisory group was not considered necessary due to specialist technical knowledge not deemed necessary for the project. | |
| Mandatory | Assessment of whether PIP required updating | Complete: No updates to the PIP were required. | |
| Project Initiation Plan (PIP) [Handbook 5.4 to 5.8, A1 to A2 and A12 to A14] (continued) | Mandatory | UKEB Board public meeting held to approve PIP | Complete: The PIP was approved at the 28 March 2024 Board meeting. |
| Education sessions [Handbook 4.10] | Optional | Board provided with education session | Complete: The Board was provided with an education session on the IASB's tentative decisions expected in the ED at the 23 February 2024 Board meeting – see Private meeting agenda. |
Desk-based research
| Step | Mandatory / optional? | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Desk-based research [Handbook 5.9 and A3] | Optional | Review of relevant documentation | Complete: the UKEB Secretariat has reviewed: • The IASB's work on the project, including the staff papers and the ED; • The Illustrative Examples accompanying IFRS 3 and IAS 36 included in the ED and the Basis for Conclusions to the ED; • Other educational material published by the IASB on their project webpage as well as the IASB webcast series on the proposals in the ED. • Other standard-setters' views. |
Outreach
| Step | Mandatory / optional? | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Outreach activities [Handbook 5.10 to 5.12 and A4 to A8] | Mandatory | Evidence of consultation | Complete: Outreach activities focused on consultation with 1. UKEB Advisory Groups; 2. one-to-one interviews with preparers, carried out jointly with the IASB; 3. a user/preparer roundtable event, hosted jointly with the IASB; and 4. obtaining responses to the Draft Comment Letter (DCL). The UKEB received four comment letters. The comment letters received were published on the UKEB project page. |
Draft Comment Letter (DCL)
| Step | Mandatory / optional2 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| DCL published for comment (mandatory unless impracticable) [Handbook paragraphs 5.13 to 5.17 and A4(d)] | Mandatory | Comment period set for responses to DCL | Complete: The DCL was published for consultation on 31 May 2024, with a minimum comment period of 30 days - comment deadline 1 July 2024. |
| Mandatory | Review and approval at a UKEB public meeting | Complete: The draft DCL was reviewed and approved, subject to suggested changes, at the 24 May 2024 Board meeting. | |
| Mandatory | DCL published on website for public consultation | Complete: The DCL was published for consultation on 31 May 2024, with a comment deadline of 1 July 2024. |
Project finalisation and project closure
| Step | Mandatory / optional2 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Final Comment Letter (FCL) [Handbook paragraph 5.18 and A4(d)] | Mandatory | Public responses to DCL considered and published on website | Complete: The UKEB received four comment letters which were published on the UKEB project webpage. All responses were assessed, reflected as appropriate in the FCL and summarised in the Feedback Statement. |
| Mandatory | FCL approved by the UKEB in public meeting | Complete: A FCL was presented for approval at the 18 July 2024 public Board meeting. [The Board approved the FCL subject to suggested amendments.] | |
| Mandatory | FCL submitted to the IASB and posted on UKEB website | Complete: [The FCL was submitted to the IASB and posted on the UKEB website on xx July 2024.] | |
| Feedback Statement [Handbook 5.19 to 5.22 and A9 to A11] | Mandatory | Feedback Statement approved for publication by the UKEB in a public meeting | Complete: A Feedback Statement was presented for approval at the 18 July 2024 public Board meeting. [The Board approved the Feedback Statement, subject to editorial changes.] |
| Mandatory | Feedback Statement published on the UKEB website | [Complete: The Feedback Statement was published on the UKEB project webpage on xx July 2024.] | |
| Due Process Compliance Statement (DPCS) [Handbook 5.23 to 5.26 and A12 to A14] | Mandatory | DPCS approved by the UKEB in public meeting | Complete: A draft DPCS was presented for approval at the 18 July 2024 Board meeting. [The final DPCS will be presented for noting at the 19 September 2024 Board meeting.] |
| Mandatory | DPCS published on the UKEB website | [The final DPCS will be published on the UKEB website after the 19 September 2024 Board meeting.] |
Ongoing communications
| Step | Mandatory / optional2 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Public Board meetings [Handbook 4.10] | Mandatory | UKEB public meetings held to discuss technical project | Complete: The board received various updates on the IASB redeliberation on the project:
The Board discussed an initial technical paper at the 26 April 2024 Board meeting. The Board approved the PIP at the 28 March 2024 Board meeting, the draft DCL, subject to suggested changes, at the 24 May 2024 Board meeting, [and the FCL and Feedback Statement at the 18 July 2024 Board meeting.] |
| Secretariat papers [Handbook 4.20] | Mandatory | Board meeting papers posted and publicly available usually no later than 5 working days before a Board meeting. | Complete: The UKEB's meeting papers were published on the UKEB website five working days before the public meetings. Meeting minutes and recordings were made publicly available via the UKEB website – Events webpage. |
| Project webpage [Handbook 4.25(b)] | Mandatory | Project webpage contains a project description with up-to-date information on the project. | Complete: The UKEB project webpage has been updated regularly on a timely basis. |
| Subscriber Alerts [Handbook 4.24] | Optional | Evidence that subscriber alerts have occurred | Complete: Subscribers were alerted via email five days before each Board meeting, with links to the agenda, papers and the option to dial in to observe the discussion. |
| News Alerts [Handbook 4.24] | Optional | News Alert to announce publication of key documents | Complete: A News Alert was published on 31 May 2024 calling for comments on the DCL. [A News Alert was published on xx July 2024 alerting stakeholders to the FCL. A link to the FCL was sent out to the UKEB advisory groups. A News Alert announcing publication of the Feedback Statement was published on xx July 2024.] |
Conclusion
This project complies with the applicable due process steps, as set out in the UKEB Due Process Handbook published December 2022.
Footnotes
-
The Exposure Draft Business Combinations—Disclosures, Goodwill and Impairment is available on project page of the IASB website. ↩
-
In accordance with the UKEB Due Process Handbook published December 2022. ↩↩↩↩
-
UKEB outreach to date is primarily our UKEB Advisory Group meetings with accounting firms and institutes, academics, preparers, investors and other users of financial statements. The UKEB also held a joint user/preparer roundtable on 7 May 2024 and several one-to-one interviews with preparers throughout May 2024. ↩
-
The Secretariat’s desk-based research included reviewing: the IASB’s work (staff papers, meeting summaries, etc) on the PIR of IFRS 3, the March 2020 Discussion Paper and the IASB’s tentative decisions prior to the publication of the Exposure Draft; accounting manuals; UK regulator thematic reviews, including FRC Thematic Review Business Combinations published in September 2022. ↩
-
The IASB proposes to add the following definition for key objective to IFRS 3: An objective (that is, a specific aim) for a business combination that is critical to the success of the business combination. A key objective is more specific than the strategic rationale for a business combination. Paragraph BC35 provides an example of an objective 'to increase sales of Entity A’s (the acquirer) own Product W in new Territory Y using the acquired sales channels of Entity B (the acquiree). ↩
-
The IASB proposes to add the following definition for target to IFRS 3: A target describes the level of performance that will demonstrate whether a key objective for a business combination has been met. A target shall be specific enough for it to be possible to verify whether the related key objective is being met. A target is measured using a metric that could be denominated in currency units or another unit of measurement. BC38 provides examples of a target, such as 'additional revenue of CU100 million of Product V in Territory W in 202X compared to 202Y or 'increasing the number of customers for Product Z by 5,000 by 202X compared to 202Y. ↩
-
A ‘series’ of acquisitions refers to acquisitions of different entities (as opposed to step acquisitions in the same entity). ↩
-
The existing application guidance paragraph B65 of IFRS 3 says" For individually immaterial business combinations occurring during the reporting period that are material collectively, the acquirer shall disclose in aggregate the information required by paragraph B64(e)–(q)”. ↩
-
Research data was provided by a member of the UKEB Investor Advisory Group, based on data from Ortiz, Peter, Urzúa, and Volpin (2023) and Cespa, Keswani and Urzua (2024). The data covers a sample of 28,742 UK deals where control is transferred during the period 1997-2021. There is financial data for acquirers and targets for approximately half of the deals. For these, around half would be classified as strategic using the proposed quantitative thresholds (targets' assets/sales larger than 10% of acquirers' assets/sales). When considering the qualitative thresholds, (target in a different industry/country), 42.3% (9.7%) of targets belong to a different industry (country). ↩
-
A ‘partial’ acquisition, is an initial acquisition of more than 50%, but less than 100% of the acquiree. ↩
-
‘Step’ acquisitions, are multiple acquisitions of the same entity, where a subsequent acquisition leads to the acquirer obtaining control e.g. the acquirer owns a 40% stake and acquires a further 20% stake, so it becomes an acquisition, as opposed to an investment. ↩
-
Application guidance paragraph B67C says "....c) the business combination resulted in the acquirer entering a new major line of business or geographical area of operations”. ↩
-
Basis for Conclusions paragraph BC55 says "....major new lines of business or geographies that are essential to the entity's overall business strategy....”. ↩
-
Basis for Conclusions Paragraph BC68 says "......entering a new major line of business or geographical area of operations”. ↩
-
As noted in the Basis for Conclusions (paragraph BC69), these thresholds are based on the thresholds in paragraph 32 of IFRS 5 Non-current Assets Held for Sale and Discontinued Operations used to identify discontinued operations. The thresholds have been adapted to reflect the purchase of a business instead of the discontinuance of an operation. Paragraph 32 of IFRS 5 says "A discontinued operation is a component of an entity that either has been disposed of, or is classified as held for sale, and (a) represents a separate major line of business or geographical area of operations, (b) is part of a single co-ordinated plan to dispose of a separate major line of business or geographical area of operations or (c) is a subsidiary acquired exclusively with a view to resale”. ↩
-
The FRC Thematic Review: Reporting by the UK’s largest private companies was published January 2024. ↩
-
The FRC Thematic Review: IAS 37 Provisions, Contingent Liabilities and Contingent Assets published in October 2021, selected main market companies for review. ↩
-
Neither IAS 37 Provisions, Contingent Liabilities and Contingent Assets, nor the UK Accounting Regulations (SI 2008/410) revenue disaggregation requirements, require a justification for the use of the exemption to be disclosed. When challenged to provide a rationale for the use of the exemption, some companies undertook to provide disclosures previously omitted under the exemption in coming years. ↩
-
Paragraph 92 of IAS 37 Provisions, Contingent Liabilities and Contingent Assets says that "in extremely rare cases, disclosure of some or all of the information required by paragraphs 84–89 can be expected to prejudice seriously the position of the entity in a dispute with other parties on the subject matter of the provision, contingent liability or contingent asset. In such cases, an entity need not disclose the information, but shall disclose the general nature of the dispute, together with the fact that, and reason why, the information has not been disclosed”. ↩
-
IAS 24 Related Party Disclosures defines key management personnel (KMP) as those persons having authority and responsibility for planning, directing, and controlling the activities of the entity, directly or indirectly, including any directors (whether executive or otherwise) of the entity [IAS24.9]. Other IFRS Accounting Standards use KMP to identify information to be disclosed by an entity–for example, paragraph 34(a) of IFRS 7 Financial Instruments: Disclosures. ↩
-
IFRS 8 Operating Segments does not provide an absolute definition of the term ‘Chief Operating Decision Maker’ (CODM) but explains it is intended to mean a function rather than a particular executive with a specific title. The function is that of allocating resources to operating segments and assessing their performance. ↩
-
The level of management for the purpose of monitoring the subsequent performance of a ‘strategic’ business combination is intended to identify the most important information for the most important acquisitions. The level of management monitoring the business associated with goodwill for the purpose of impairment testing is intended to allocate goodwill at the lowest level within an entity at which management is monitoring the business associated with goodwill for the purpose of the impairment test. ↩
-
Proposed paragraph 62A says "The acquirer shall disclose information that enables users of its financial statements to evaluate: (a) the benefits an entity expects from a business combination when agreeing on the price to acquire a business; and (b) for a strategic business combination (see paragraph B67C), the extent to which the benefits an entity expects from the business combination are being obtained”. ↩
-
As noted in the Basis for Conclusion paragraph BC160, most dictionaries define ‘synergies’ as arising from a combination of two or more items, and resulting in a combined performance or value greater than the sum of the items when considered separately. ↩
-
FRC Thematic Review Business Combinations published in September 2022. ↩
-
The measurement period is up to one year after the acquisition date, during which the acquirer may adjust the provisional amounts recognised for a business combination. ↩
-
The Basis for Conclusions paragraph BC139 suggests that assumptions reflected in the acquisition price and the assets and liabilities recognised as a result of the business combination, including expected synergies, are fixed at the date of acquisition. ↩
-
Per the Basis for Conclusions (paragraph BC 164), the description of the strategic rationale is likely to be broad, for example, 'to expand the entity's geographical presence in Region Z by acquiring Entity B, which trades in Region Z'. ↩↩
-
IAS 36 paragraph 80A: In applying paragraph 80, an entity first applies paragraph 80(a) to determine the lowest level at which the business associated with the goodwill is monitored for internal management purposes. Applying paragraph 80(a) requires an entity: (a) to identify the cash-generating units or groups of cash-generating units (see paragraph 81) expected to benefit from the synergies of the combination; and (b) to then determine the lowest level for which there is financial information about the cash-generating units identified in paragraph 80A(a) that management regularly uses to monitor the business associated with the goodwill. That financial information reflects how the benefits expected from the synergies of the combination are managed. Paragraph 80B: The requirement in paragraph 80(b) sets the highest level at which an entity is permitted to allocate goodwill for the purpose of applying paragraph 80(a) and is therefore applied only after paragraph 80(a) has been applied. ↩
-
IAS 36 paragraph 80A: In applying paragraph 80, an entity first applies paragraph 80(a) to determine the lowest level at which the business associated with the goodwill is monitored for internal management purposes. Applying paragraph 80(a) requires an entity: (a) to identify the cash-generating units or groups of cash-generating units (see paragraph 81) expected to benefit from the synergies of the combination; and (b) to then determine the lowest level for which there is financial information about the cash-generating units identified in paragraph 80A(a) that management regularly uses to monitor the business associated with the goodwill. That financial information reflects how the benefits expected from the synergies of the combination are managed. Paragraph 80B: The requirement in paragraph 80(b) sets the highest level at which an entity is permitted to allocate goodwill for the purpose of applying paragraph 80(a) and is therefore applied only after paragraph 80(a) has been applied. ↩↩
-
IFRS 8 Operating Segments permits (but does not require) operating segments to be aggregated for reporting purposes if, and only if, certain criteria are satisfied. Aggregation often improves the usefulness of the disclosures by avoiding excessive detail and focusing more readily on the overall trends and key information. ↩↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩
-
UKEB outreach to date is primarily our UKEB Advisory Group meetings with accounting firms and institutes, academics, preparers, investors and other users of financial statements. The UKEB also held a joint user/preparer roundtable on 7 May 2024_and several one-to-one interviews with preparers throughout May 2024. ↩
-
The Secretariat's desk-based research included reviewing: the IASB's work (staff papers, meeting summaries, etc) on the PIR of IFRS 3, the March 2020 Discussion Paper and the IASB's tentative decisions prior to the publication of the Exposure Draft; accounting manuals; UK regulator thematic reviews, including FRC Thematic Review Business Combinations published in September 2022. ↩
-
The IASB proposes to add the following definition for key objective to IFRS 3: An objective (that is, a specific aim) for a business combination that is critical to the success of the business combination. A key objective is more specific than the strategic rationale for a business combination. Paragraph BC35 provides an example of an objective 'to increase sales of Entity A's (the acquirer) own Product W in new Territory Y using the acquired sales channels of Entity B (the acquiree). ↩
-
The IASB proposes to add the following definition for target to IFRS 3: A target describes the level of performance that will demonstrate whether a key objective for a business combination has been met. A target shall be specific enough for it to be possible to verify whether the related key objective is being met. A target is measured using a metric that could be denominated in currency units or another unit of measurement. BC38 provides examples of a target, such as 'additional revenue of CU100 million of Product V in Territory W in 202X compared to 202Y or 'increasing the number of customers for Product Z by 5,000 by 202X compared to 202Y. ↩
-
A ‘series’ of acquisitions refers to acquisitions of different entities (as opposed to step acquisitions in the same entity). The existing application guidance paragraph B65 of IFRS 3 says" For individually immaterial business combinations occurring during the reporting period that are material collectively, the acquirer shall disclose in aggregate the information required by paragraph B64(e)–(q)”. The existing application guidance paragraph B67 of IFRS 3 says "the acquirer shall disclose the following information for each material business combination or in the aggregate for individually immaterial business combinations that are material collectively:........" ↩
-
The existing application guidance paragraph B65 of IFRS 3 says" For individually immaterial business combinations occurring during the reporting period that are material collectively, the acquirer shall disclose in aggregate the information required by paragraph B64(e)–(q)”. The existing application guidance paragraph B67 of IFRS 3 says "the acquirer shall disclose the following information for each material business combination or in the aggregate for individually immaterial business combinations that are material collectively:........" ↩
-
Research data was provided by a member of the UKEB Investor Advisory Group, based on data from Ortiz, Peter, Urzúa, and Volpin (2023) and Cespa, Keswani and Urzua (2024). The data covers a sample of 28,742 UK deals where control is transferred during the period 1997-2021. There is financial data for acquirers and targets for approximately half of the deals. For these, around half would be classified as strategic using the proposed quantitative thresholds (targets' assets/sales larger than 10% of acquirers' assets/sales). When considering the qualitative thresholds, (target in a different industry/country), 42.3% (9.7%) of targets belong to a different industry (country). ↩
-
A ‘partial’ acquisition, is an initial acquisition of more than 50%, but less than 100% of the acquiree. ↩
-
‘Step’ acquisitions, are multiple acquisitions of the same entity, where a subsequent acquisition leads to the acquirer obtaining control e.g. the acquirer owns a 40% stake and acquires a further 20% stake, so it becomes an acquisition, as opposed to an investment. ↩
-
Application guidance paragraph B67C says "....c) the business combination resulted in the acquirer entering a new major line of business or geographical area of operations". ↩
-
Basis for Conclusions paragraph BC55 says "....major new lines of business or geographies that are essential to the entity's overall business strategy....". ↩
-
Basis for Conclusions Paragraph BC68 says "......entering a new major line of business or geographical area of operations". ↩
-
As noted in the Basis for Conclusions (paragraph BC69), these thresholds are based on the thresholds in paragraph 32 of IFRS 5 Non-current Assets Held for Sale and Discontinued Operations used to identify discontinued operations. The thresholds have been adapted to reflect the purchase of a business instead of the discontinuance of an operation. Paragraph 32 of IFRS 5 says "A discontinued operation is a component of an entity that either has been disposed of, or is classified as held for sale, and (a) represents a separate major line of business or geographical area of operations, (b) is part of a single co-ordinated plan to dispose of a separate major line of business or geographical area of operations or (c) is a subsidiary acquired exclusively with a view to resale". ↩
-
Proposed paragraph B67D says "To determine whether an item of information is eligible for the exemption, an acquirer considers this non-exhaustive list of factors: (a) the effect of disclosing the item of information—an entity must be able to describe a specific reason for not disclosing an item of information that identifies the seriously prejudicial effect the entity expects to result from disclosing the information. A general risk of a potential weakening of competitiveness due to disclosing an item of information is not, on its own, sufficient reason to apply the exemption. An entity shall not use the exemption to avoid disclosing an item of information only because that item of information might be considered unfavourably by the capital market. (b) the public availability of information—for example, if an entity has made information publicly available, it would be inappropriate to apply the exemption to that information. Examples of publicly available documents include press releases, investor presentations and regulatory filings made by the entity that are available to the public". Basis for Conclusion paragraphs BC90 notes that the application guidance would require an entity: (a) to disclose, for each item of information to which an entity has applied the exemption, that it has applied the exemption and the reason for doing so. (b) to consider whether, instead of applying the exemption, it is possible to disclose information in a different way—for example, at a sufficiently aggregated level—without prejudicing seriously the entity's acquisition-date key objectives for a business combination. (c) to consider factors such as the effect of disclosing the information and the public availability of the information in determining whether the exemption is applicable. (d) to reassess in each reporting period whether the item of information still qualifies for the exemption. If it is no longer appropriate to apply the exemption, the entity would be required to disclose the item of information previously exempted. ↩
-
The FRC Thematic Review: Reporting by the UK’s largest private companies was published January 2024. ↩
-
The FRC Thematic Review: IAS 37 Provisions, Contingent Liabilities and Contingent Assets published in October 2021, selected main market companies for review. ↩
-
Neither IAS 37 Provisions, Contingent Liabilities and Contingent Assets, nor the UK Accounting Regulations (SI 2008/410) revenue disaggregation requirements, require a justification for the use of the exemption to be disclosed. When challenged to provide a rationale for the use of the exemption, some companies undertook to provide disclosures previously omitted under the exemption in coming years. ↩
-
Paragraph 92 of IAS 37 Provisions, Contingent Liabilities and Contingent Assets says that "in extremely rare cases, disclosure of some or all of the information required by paragraphs 84–89 can be expected to prejudice seriously the position of the entity in a dispute with other parties on the subject matter of the provision, contingent liability or contingent asset. In such cases, an entity need not disclose the information, but shall disclose the general nature of the dispute, together with the fact that, and reason why, the information has not been disclosed". ↩
-
IAS 24 Related Party Disclosures defines key management personnel (KMP) as those persons having authority and responsibility for planning, directing, and controlling the activities of the entity, directly or indirectly, including any directors (whether executive or otherwise) of the entity [IAS24.9]. Other IFRS Accounting Standards use KMP to identify information to be disclosed by an entity—for example, paragraph 34(a) of IFRS 7 Financial Instruments: Disclosures. ↩
-
IFRS 8 Operating Segments does not provide an absolute definition of the term ‘Chief Operating Decision Maker’ (CODM) but explains it is intended to mean a function rather than a particular executive with a specific title. The function is that of allocating resources to operating segments and assessing their performance. ↩
-
The level of management for the purpose of monitoring the subsequent performance of a ‘strategic’ business combination is intended to identify the most important information for the most important acquisitions. The level of management monitoring the business associated with goodwill for the purpose of impairment testing is intended to allocate goodwill at the lowest level within an entity at which management is monitoring the business associated with goodwill for the purpose of the impairment test. ↩
-
Proposed paragraph 62A says "The acquirer shall disclose information that enables users of its financial statements to evaluate: (a) the benefits an entity expects from a business combination when agreeing on the price to acquire a business; and (b) for a strategic business combination (see paragraph B67C), the extent to which the benefits an entity expects from the business combination are being obtained". ↩
-
As noted in the Basis for Conclusion paragraph BC160, most dictionaries define ‘synergies’ as arising from a combination of two or more items, and resulting in a combined performance or value greater than the sum of the items when considered separately. ↩
-
FRC Thematic Review Business Combinations published in September 2022. ↩
-
The measurement period is up to one year after the acquisition date, during which the acquirer may adjust the provisional amounts recognised for a business combination. ↩
-
The Basis for Conclusions paragraph BC139 suggests that assumptions reflected in the acquisition price and the assets and liabilities recognised as a result of the business combination, including expected synergies, are fixed at the date of acquisition. ↩
-
Per the Basis for Conclusions (paragraph BC 164), the description of the strategic rationale is likely to be broad, for example, ‘to expand the entity’s geographical presence in Region Z by acquiring Entity B, which trades in Region Z’. ↩