6 Power Purchase Agreements – Draft Comment Letter
Project Type: Influencing Project Scope: Limited
Executive Summary
The purpose of this paper is to obtain Board approval for publication of the Draft Comment Letter (DCL) (Appendix B) and the accompanying Invitation to Comment (Appendix C) on the IASB Exposure Draft Contracts for Renewable Electricity (the Amendments).
Summary of the Issue
Developments in reporting of greenhouse gas emissions (such as Streamlined Energy and Carbon Reporting regulations (“SECR”)) and in relation to reporting progress against targets to reduce greenhouse gas emissions (under Task Force on Climate-Related Financial Disclosures (“TCFD”) and in the future under IFRS S2 Climate-related Disclosures) have increased focus on Scope 2 emissions. Entities are increasingly entering into power purchase agreements (PPAs) to secure the supply of renewable electricity, validated by third-party renewable energy certificates (RECs), as well as for price security. These contracts include physical PPAs1 and virtual PPAs2.
Following stakeholder feedback, the IASB has issued an Exposure Draft with a 90-day comment period which proposes amendments to the 'own use' and hedge accounting requirements of IFRS 9 Financial Instruments for certain renewable electricity contracts, and additional disclosure requirements for those contracts.
Preliminary analysis of the proposals is set out in Appendix A.
The DCL highlights one significant concern about the scope of the ED, but otherwise supports the IASB's objectives while making recommendations to enhance the ED's proposals.
Decisions for the Board
- Subject to addressing any comments raised during the meeting, does the Board approve the DCL and Invitation to Comment for publication?
Recommendation
The Secretariat recommends that the Board approves the DCL and accompanying Invitation to Comment.
Appendices
- Appendix A Preliminary analysis
- Appendix B Draft Comment Letter
- Appendix C Invitation to Comment
Background
1Streamlined Energy Carbon Reporting requirements (SECR), Taskforce on Climate-Related Financial Disclosures (TCFD) and associated Companies Act 2006 requirements require UK entities to disclose their greenhouse gas emissions and progress towards net zero commitments. Entities are increasingly entering into PPAs to secure both price and a supply of renewable electricity, validated by third-party renewable energy certificates (RECs). However, there are accounting challenges as PPAs do not always currently meet the IFRS 9 'own use' requirements and may therefore have to be accounted for as derivatives. The remeasurement of derivatives to fair value can cause significant income statement volatility. In addition, where derivative accounting is required, it can be difficult to designate PPAs as a hedging instrument in a hedge accounting relationship.
2In respect of the own use requirements, accounting firm guidance3 indicates that PPAs are considered to be able to be settled net in cash because electricity can always be sold back to the grid, and they are thus readily convertible to cash. This brings them within the scope of IFRS 9 Financial Instruments. The guidance further indicates that PPAs generally meet the definition of a derivative, as their value varies in response to an underlying (the spot price of electricity).
3The entity must then consider whether it can apply the 'own use' requirements to its PPAs (IFRS 9 paragraphs 2.4 to 2.6). As part of this, it considers whether it has a past practice of settling similar contracts net in cash or selling shortly after delivery in order to generate a profit. If so, the contract will not qualify for 'own use'.4
4Stakeholders have reported that there is diversity in assessments of whether such PPAs meet the 'own use' requirements, but that they are often assessed as failing to meet the criteria.
5In addition, stakeholders have told the IASB that they are unable to apply hedge accounting to virtual or physical PPAs when accounted for as derivatives, as it is difficult to satisfy the criterion in IFRS 9 paragraph 6.3.3 that, in a cash flow hedge, if a hedged item is a forecast transaction, then it must be highly probable. The March 2019 IFRS Interpretations Committee Decision, which references IAS 39 IG F.3.10 and F.3.11, states that “Forecast energy sales cannot be specified solely as a percentage of sales during a period because that would lack the required specificity". The hedged item must be an identifiable amount. Stakeholders told the IASB that, by analogy with the March 2019 IFRS Interpretations Committee decision, they were unable to designate virtual PPAs6 as hedging instruments in a qualifying hedging relationship.
6In addition, ineffectiveness can arise due to differences in location, basis7 and timing. In some cases, sources of ineffectiveness might be sufficiently significant that the hedge will not qualify for designation or will have to be de-designated.8
7On 8 May 2024, the IASB published the ED Contracts for Renewable Electricity.9 In the ED, the IASB proposes amendments to the 'own use' and hedge accounting requirements of IFRS 9 Financial Instruments for certain renewable electricity contracts, and additional disclosure requirements for those contracts.
8Appendix A sets out our preliminary analysis of the main proposals.
Draft Comment Letter
9The DCL is attached for consideration and approval, with the accompanying Invitation to Comment. Overall, the DCL highlights one significant concern about the scope of the ED, but otherwise supports the IASB's objectives while making recommendations to enhance the ED's proposals.
10The Project Initiation Plan proposed a minimum 30 day comment period, with a longer comment period to be considered by the Board at this meeting if appropriate and practicable. A comment period ending on 4 July 2024 would allow a 35 day comment period, if the DCL is published on 30 May 2024. We recommend issuing the DCL with a comment period ending on 4 July 2024, subject to this allowing a minimum 30 day consultation period.
Research and outreach
11To inform the drafting of the DCL, the Secretariat has conducted desk-based research, including reviewing the ED and relevant publications from accounting firms.
12In addition, in January to April 2024, the Secretariat discussed the IASB's proposals with the Accounting Firms and Institutes and Investor Advisory Groups, the Financial Instruments Working Group and a variety of other relevant stakeholders. Their feedback was set out in the April 2024 IASB General Update.
13The secretariat has also held informal calls in May 2024 with stakeholders, including calls to discuss the contents of the ED.
Question for the Board
- Subject to addressing any comments raised during the meeting, does the Board approve the DCL and Invitation to Comment for publication?
Next steps
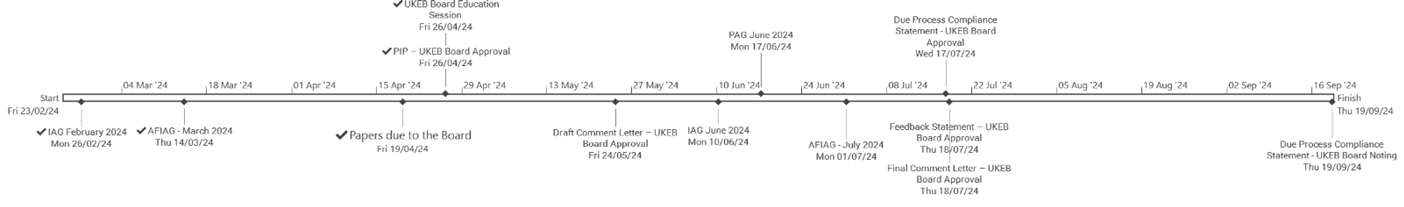
14In line with the PIP, outreach with stakeholders will continue between now and July 2024, including via publication of the DCL on the UKEB website and discussion with relevant advisory groups.
15The Secretariat plans to bring the Final Comment Letter, Feedback Statement and draft Due Process Compliance Statement to the July 2024 meeting for Board approval. Further information on the project timeline is presented below.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30(b)] | Added to UKEB technical work plan. | Completed. |
| Education session on IASB proposals on PPAs (optional) [Handbook 4.10] | An education session on the tentative proposals was provided to the Board before the April 2024 Board meeting. | Completed. |
| Desk-based research (optional) [Handbook 5.9] | The Secretariat has begun its programme of desk-based research, including review of IASB staff papers, publications from regulators, accounting firms and other relevant sources including accounting manuals as well as the ED. | In progress. |
| Outreach activities (mandatory) [Handbook 5.11] | We have already begun to engage with IAG, PAG, AFIAG and FIWG and will continue to engage with members at the June and July 2024 meetings. In addition, we plan to seek feedback from relevant specialists. | In progress. |
| Project Initiation Plan (PIP) (mandatory) [Handbook 5.4 to 5.8] | The Board approved the Project Initiation Plan at the April 2024 Board meeting. | Completed. |
| Draft comment letter (DCL) published for comment (generally mandatory) [Handbook paragraphs 5.13 to 5.17] | This paper | In progress |
| UKEB submits final comment letter (FCL) to the IASB (mandatory) [Handbook paragraph 5.18] | The IASB comment period closes on 7 August 2024. | As soon as possible after the July 2024 Board meeting. |
| Feedback statement and due process compliance statement for influencing stage of project | Secretariat publishes Feedback Statement and Due Process Compliance Statement on the UKEB website. | To be completed. |
Appendix A: Contracts for Renewable Electricity - Proposed amendments to IFRS 9 and IFRS 7 - Preliminary Analysis
Scope
IASB proposals
A1The IASB ED amendments1 are narrowly scoped. Paragraph 6.10.1 of the ED limits the scope of those proposals to contracts for renewable electricity, where the source of production is nature dependent, and where the contract exposes the purchaser to substantially all the volume risk. Paragraph 6.10.2 is clear that an entity shall not apply the amendments by analogy to other contracts.
Analysis
A2The IASB previously explored approaches to principles-based amendments to the standards to address this urgent issue. However, the approach followed in the ED of a narrowly scoped, rules-based exception to the requirements of IFRS 9 appears a pragmatic approach to address the issue, with reduced risk of unintended consequences.
A3The amendments do not apply to electricity contracts where the power is derived from non-renewable sources.
A4The ED contains alternative views from two IASB members. The reasons for their disagreement are, in summary:
- Fair value measurement is accepted as the most relevant information for contracts that can be net settled, unless the purpose of the contract is to purchase items for the entity's own use. This is the basis for the existing exception in IFRS 9.
- A further exception from IFRS 9 is warranted for situations where a purchaser intends to use all electricity produced, but nature causes an increase in production above expected levels, and the entity is forced to sell the excess.
- They disagree that the exception should be available to situations where the purchaser knows with reasonable certainty that it will not use, but sell, electricity delivered under the contract at certain points in a day or week.
- The proposals stray from the principal of neutrality, through favouring renewable electricity contracts over other contracts.
- Cash flow hedging should be assessed more generally as part of the post-implementation review of IFRS 9 hedge accounting (view expressed by one of the IASB members).
A5The proposals appear helpful in relation to 'pay-as-produced' contracts, and provide targeted relief in relation to ‘own use' and hedge accounting issues specific to those contracts. Pay-as-produced contracts, for example where a purchaser contracts to buy 40% of the output from a specified wind farm facility over a designated period, are understood to represent the majority of PPA contracts for renewable electricity in the UK.
A6However, the proposed wording of the amendments in 6.10.1 states: “An entity shall apply the requirements in paragraphs 6.10.3–6.10.6 to a contract for renewable electricity with both of the following characteristics: (a) the source of production of the renewable electricity is nature-dependent so that supply cannot be guaranteed at specified times or for specified volumes. Examples of such sources of production include wind, sun and water. (b) that contract exposes the purchaser to substantially all the volume risk under the contract through 'pay-as-produced' features. Volume risk is the risk that the volume of electricity produced does not align with the purchaser's demand for electricity at the time of production." This appears to mean that they would not apply to some other types of renewable electricity PPAs, for example contracts where the purchaser contracts to buy a fixed volume of power delivered in specified or equal instalments over the course of the contract. In discussion with us stakeholders have called these contracts ‘baseload' contracts, although we understand this term may not be consistently used and may not always accurately describe their nature.
A7We have heard feedback at AFIAG and FIWG that UK entities currently may struggle on occasions to apply the 'own use' requirements to some fixed volume ('baseload') contracts. This reflects the unique nature of the electricity market, where power is delivered in 30 minute units, and where the grid is required to be in balance for each of those periods, which typically requires participants to sell back into the grid contracted power which they do not use in that period.
A8Where such sales occur, we understand it is currently a matter of judgement whether such sales prevent the entity from meeting the 'own use' requirements within IFRS 9.2.42. We understand that factors such as the frequency and volume of such sales may influence that judgement. Typical problem areas can include where power demand is uneven over the course of a 24 hour period (e.g. a power intensive factory shuts at night), or where there are periods of significantly lower demand (e.g. if a factory closes for a holiday period or for a major refurbishment).
A9We understand that these contracts represent a growing share of UK corporate renewable electricity PPAs, and are often favoured by purchasers because they are a more effective method to manage risk exposures relating to power (e.g. price), as the amounts and timing of power delivered may more closely align with actual and forecast usage by the purchaser.
A10While the proposals are likely to be helpful to those entering into 'pay-as-produced' contracts, we are concerned that the apparent scope exclusion of other types of contracts may not be justified. While not all features of fixed volume (‘baseload') contracts raise the same accounting challenges as 'pay-as-produced' contracts, in particular in relation to cash flow hedge accounting3, we understand that 'own use' issues do arise in both types of contract. We also note that the rationale set out in BC18 of the ED in support of making amendments for 'pay-as-produced' contracts also appears to support including baseload contracts within the scope of the proposals. This point has been raised in the DCL.
A11In relation to the wording of paragraph 6.10.1 of the ED, the scope is defined by reference to "a contract for renewable electricity". This scope is clearly intended to apply to both physical PPAs and virtual PPAs. However, it is not clear that this definition would include virtual PPAs, as based on the plain meaning of the words it is not clear that a derivative over renewable electricity prices is a 'contract for electricity'. The DCL recommends that this is clarified.
A12The wording in paragraph 6.10.2 states that the amendments "provide exceptions to only the requirements in IFRS 9 specified in paragraphs 6.10.3-6.10.6”. These paragraphs include references to, among others, paragraphs 2.4 and section 6.3 of IFRS 9. While we assume the IASB did not intend to provide a blanket exception to those requirements of the standard, this appears to be the effect of this drafting. Further, the amendments do not actually provide an 'exception' from paragraph 2.4. A recommendation has been included in the DCL to clarify this point.
Own use proposals
IASB proposals
A13The proposals include clarifications of the requirements for those contracts within its scope in terms of the estimate that is required by the entity of expected purchase or usage requirements. It is clear that detailed long-term estimates are not required, although reasonable and supportable information at the reporting date in respect of at least the next 12 months is required to be considered.
A14The proposals also include guidance on the assessment of reasons for past and expected sales, to determine whether they are consistent with 'own use'. This includes clarified requirements in relation to future purchases of equivalent volumes of electricity, including an indication of what a reasonable timeframe would be.
Analysis
A15Paragraph 6.10.3(a) appears to helpfully address one of the aspects of concerns raised with the IASB about the challenges of accurately forecasting expected purchase or usage requirements on PPA contracts that are long-term (commonly 15-20 years). This is likely to be viewed favourably by those with contracts within scope of the proposals and make it easier to meet the 'own use' requirements.
A16However, in the absence of other detailed guidance on this point elsewhere, there appears a degree of risk that this may be interpreted as codifying the expectation for contracts not within the scope of these amendments. Paragraph 6.10.2 is clear that these requirements may not be applied by analogy to other contracts. However, users may read the requirements of 6.10.3(a) as setting an expectation that for other contracts an entity would be required to make a detailed estimate of purchases/usage running far into the future. While this may reflect existing practice, there is a possible unintended consequence that these provisions might make it harder for other renewable electricity contracts outside the scope of these provisions to meet the ‘own use' requirements. This point is raised in the DCL.
A17The requirements of paragraph 6.10.3(b) appear broadly consistent with the proposals brought to the March 2024 IASB meeting4. The text of the ED does however address some concerns raised at the April FIWG meeting, as 6.10.3(b)(iii) now refers to “expects to purchase at least an equivalent volume”, rather than referring to 'repurchasing'. Another point highlighted by FIWG members was the reference to a reasonable time, without indication of what that may be, and whether it would be better to define this, or leave it to judgement. The ED addresses this by referring to “(for example, one month)”. The BC also makes clear (ED BC 20(c)) that a reasonable time is typically a short time.
A18This clarification appears broadly sensible. It may not wholly satisfy entities that typically make assessments over a far longer period, for example to allow for mismatches in supply and demand due to seasonal volatility. This could also prove problematic for entities that may e.g. close a factory for a month in the summer or for maintenance. We note that the wording only refers to the one month period as an example, thus it does not rule out longer periods, and does appear to allow the use of judgement. Our preliminary view on this is that it appears to address some of the concerns raised based on the previous IASB agenda papers. We have noted this issue in our DCL as a pragmatic solution.
Hedge accounting proposals
IASB proposals
A19The proposals set out the conditions for designating a variable volume of forecast transactions as the hedged item in a cash flow hedge. The proposals also specify measurement requirements in relation to volume assumptions used for the hedging instrument and hedged item.
Analysis
A20Overall, the hedge accounting proposals appear to address the main concern that a variable nominal amount could not be designated as the hedged item, following the March 2019 Interpretations Committee Agenda decision5.
A21The drafting of these proposals is clearer than the outline set out in the IASB staff papers on hedge accounting6. The proposals also make clear that the proposal in 6.10.6 is a measurement requirement in measuring the hedge relationship, rather than a condition of entry into a hedging arrangement, as implied by paragraph 5(b) of the March IASB paper 3b. This addresses one of the main pieces of feedback highlighted in discussions at the April 2024 FIWG meeting on this topic.
A22However, the hedge accounting proposals at paragraphs 6.10.4 and 6.10.5 are difficult to follow and introduce new concepts, and it would be helpful to have illustrative examples of how these requirements would apply in practice. There are no illustrative examples accompanying the ED. This point has been made in the DCL.
A23Concerns were also raised by FIWG members in relation to the designated intervals over which the hedging arrangement would be assessed. The illustrative examples to paper 3b at the March 2024 IASB meeting indicated the use of intervals of one year. The April 2024 FIWG meeting noted that this was significantly longer than would be accepted currently for other hedging relationships, and was potentially problematic where a period of that length did not coincide with the entity's reporting period. In particular, problems were noted with how recycling of amounts from the cash flow hedge reserve would take place where a long period straddling the reporting date was used.
A24The ED does not refer to the period that must be used and the example in the staff papers is not repeated. As the ED is silent on this point, we have not included anything in our DCL. This will, however, be a point on which we will follow up during the consultation period.
Disclosure and other proposals
IASB Proposals
A25The IASB proposals make amendments to IFRS 7 to require certain disclosures in relation to contracts within the scope of the amendments. This information includes the duration of the contracts, the type of pricing, and either the fair value of the contracts or information about expected volumes and timings of transactions under the contracts (ED 42T).
A26For a purchaser of electricity, the proposals include disclosure requirements about the volumes of electricity purchased, average prices in those markets and, if the actual cost significantly differs from the average cost in the markets multiplied by the volume purchased, an explanation for significant variances.
A27In relation to the other aspects of the proposals:
- The IASB proposes that these disclosure requirements would effectively be replicated in IFRS 19 Subsidiaries without Public Accountability: Disclosures, with the exception of 42W (see paragraph A32 below).
- On transition, an entity is permitted to apply a modified retrospective approach to the restatement of comparatives in relation to own use. This approach would permit retrospective application, but recognising any adjustments to opening retained earnings in the period of initial application, rather than restating comparatives. The hedge accounting proposals are to be applied prospectively.
- The effective date is to be determined based on feedback, however early application will be permitted. This would mean the amendments would be available for early application as soon as issued, which is expected to be in Q4 2024 (see A36).
Analysis: Disclosures
A28The disclosure proposals are more narrowly scoped than had previously been indicated in the IASB staff papers. They were originally expected to apply to all contracts for renewable electricity but have now been limited to those contracts within the scope of the proposed amendments.
A29The proposals in the ED do not include some of the possible requirements discussed in staff papers, such as the actual pricing in the contracts, and other facets which had caused some concern regarding commercial sensitivity. They also do not include some other information which had been identified as potentially difficult to obtain, such as the counter-factual of what the power would have cost without the PPAs.
A30Overall, the disclosure proposals appear to strike the right balance. Feedback received by the IASB was that users wanted better information about the risks entities were exposed to from all significant long term contracts accounted for as executory contracts through the ‘own use' requirements. However, it is likely that this would have gone beyond the narrow scope of these amendments.
A31While the proposals appear to be less complex than previously indicated, we propose seeking feedback as to whether any aspects of the information required – such as the average prices of electricity, or volumes - will be challenging to compile and report.
IFRS 19
A32In relation to the proposals for IFRS 19, the disclosure requirements have in effect been transferred in full. The only paragraph that has not been included is 42W. This paragraph clarifies that an entity shall consider the amount of detail to include, the appropriate level of aggregation and disaggregation, and is not required to duplicate information already disclosed in accordance with other IFRS Accounting Standards. We understand this is because similar provisions are already included as general requirements within IFRS 197, although we have noted in the DCL that it may be helpful to explain the rationale for this in the BC.
Transition
A33The fact that an entity is not required to restate comparatives (and is only permitted to do so if it can be done without the benefit of hindsight) appears sensible, as does the requirement to apply the hedge accounting requirements prospectively.
A34However, 6.10.3 requires that the own use assessment is carried out “at inception of the contract and at each subsequent reporting date”. Our reading of the transition provisions is that, without specific instruction that on transition this assessment should be made at the date of initial application of the standard (and prospectively from that point), this would require an entity with a PPA entered into 6 years ago, for example, to reassess at inception and at each subsequent reporting date whether the contract would meet the criteria. This appears potentially onerous, and difficult to do without the use of hindsight. We note that the transition provisions of other standards – e.g. IFRS 16 C16 in relation to historic sale and leaseback transactions – include specific provisions that assessment of transactions prior to the date of initial application is not required. We have included a comment in the DCL proposing the IASB make this explicit in the transition provisions, as we do not think the intention is to require this assessment to be made at each previous reporting date.
Effective date
A35The IASB intends to issue the amendments before the end of 2024. The IASB is following a timetable which is significantly accelerated compared to its normal process. The ED asks whether an effective date of accounting periods beginning on or after 1 January 2025 would provide enough time for entities to prepare to apply the amendments. As these are new requirements, and in the light of the disclosure requirements associated with the amendments, the DCL recommends the IASB considers a later effective date, potentially 1 January 2026, but with the option to early adopt. We will seek feedback on this point in our outreach before finalising the comment letter.
A36While the IASB intends these amendments to be available for early application, for UK entities this will be subject to any UK endorsement of the amendments, which would be likely to require a minimum period of at least 6 months from issue.
Dr Andreas Barckow Chairman International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
[XX August 2024]
Dear Dr Barckow,
Exposure Draft IASB/ED/2024/3 Contracts for Renewable Electricity: Proposed Amendments to IFRS 9 and IFRS 7
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.10 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.11
3We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Exposure Draft (ED) Contracts for Renewable Electricity: Proposed Amendments to IFRS 9 and IFRS 7 (the Amendments). In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts.
4We support the IASB's objectives in developing the Amendments and we are broadly supportive of the proposals. We consider it important to provide clarity and minimise the risk of diversity in accounting practice in this increasingly important area. Our main observations and recommendations are set out in the paragraphs that follow. Responses to the IASB's specific questions about the ED are included in the Appendix to this letter.
Scope
5We support the pragmatic approach to address the issue through an exception based on specified characteristics. We agree that this approach should limit the risk of unintended consequences.
6We understand that the IASB's intention is to limit the scope of the amendments to contracts which, amongst other criteria, expose the purchaser to “substantially all the volume risk under the contract”. However, we are concerned that, as drafted, the scope limitation appears also to require the existence of 'pay-as-produced' features in the contract. This drafting appears to exclude other types of contract that may also transfer volume risk and otherwise meet the 'factors to consider' set out in paragraph 6.10.3.
7A growing part of the UK renewable electricity market comprises contracts which promise to deliver fixed volumes of renewable power over specified timeframes12. While these contracts do not experience the same extent of production volume variance observed in ʻpay-as-produced' contracts, they can also give rise to short-term supply-demand mismatches.
8These contracts can provide an effective solution for purchasers to protect themselves from risks associated with price volatility and security of supply of renewable electricity. However, we understand that short term supply-demand mismatches can lead to purchasers failing to meet the ‘own use' requirements, leading to derivative accounting for some of these contracts.
9We understand this may be the outcome even where the intention in entering into the contract is for the entity's expected purchase or usage requirements, and that when sales do arise the entity may expect to purchase additional amounts at other times over and above the contracted volumes. We understand that the question of whether such contracts meet the ‘own use' requirements is a matter of judgement depending upon the frequency and volume of sales.
10We cannot see that it will be helpful to users if two economically and commercially similar contracts for delivery of renewable electricity are treated differently. We are particularly concerned that there appears no clear conceptual reason why the contract in which the purchaser has less volume risk may be required to be treated as a derivative, whereas the contract in which the purchaser assumes more volume risk could be assessed as meeting the 'own use' requirements and accounted for as an executory contract.
11We believe these proposals could push purchasers to enter into higher risk contracts to achieve a more desirable accounting outcome.
12We recommend the IASB consider amending the wording of paragraph 6.10.1 to ensure that the scope of the amendments is driven solely by a contract's characteristics rather than by any particular description or labelling of its features. For example, 6.10.1 (b) could read: ‘that contract exposes the purchaser to substantially all the volume risk under the contract, for example through 'pay-as-produced' or similar features.' (additional wording to ED underlined).
13Our detailed comments on scope are in paragraphs A1 to A12 of the appendix.
'Own use' requirements
14We believe the proposals in relation to the ‘own use' requirements will be helpful to entities with instruments within the scope of the amendments. In spite of the clear statement that these requirements shall not be applied by analogy to other contracts, we believe there is a risk that this concession may be interpreted as setting expectations for the actions required by an entity assessing whether the 'own use' requirements are met for contracts that fall outside the scope of these amendments. For this reason we note the importance that these amendments are appropriately scoped.
15Our detailed comments on own use are in paragraphs A13 to A17 of the appendix.
Hedge accounting requirements
16We are broadly supportive of the proposed amendments to hedge accounting requirements for contracts within the scope of the amendments. However, this is a complex area, and we believe that it would be extremely helpful to develop illustrative examples to show users how the proposals are intended to apply in relation to variable volumes of sales and purchases of renewable electricity.
17Our detailed comments on hedge accounting are in paragraphs A18 to A20 of the appendix.
Transition
18While we welcome the modified retrospective approach proposed in the amendments for the application of the 'own use' requirements, we are concerned that the amendments may be read as requiring a reassessment of conditions at the inception of contracts within its scope and each subsequent reporting date.
19If the IASB intends that on transition the assessment referred to in 6.10.3 would take place only at the date of initial application of the amendments and then at subsequent reporting dates, we recommend this is made explicit.
20Our detailed comments on transition are in paragraphs A26 to A28 of the appendix.
Effective date
21We think it is likely that an application date of accounting periods beginning on or after 1 January 2025 may be difficult for some preparers, and recommend 2026, with the option of early adoption. However, we bring to your attention that any final amendments would not be available for application in the UK until they had been endorsed.
22Our detailed comments on the effective date are in paragraphs A29 to A31 of the appendix.
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Questions on ED Contracts for Renewable Electricity—Proposed amendments to IFRS 9 and IFRS 7
Question 1—Scope of the proposed amendments
Paragraphs 6.10.1–6.10.2 of the proposed amendments to IFRS 9 would limit the application of the proposed amendments to only contracts for renewable electricity with specified characteristics.
Do you agree that the proposed scope would appropriately address stakeholders' concerns (as described in paragraph BC2 of the Basis for Conclusions on this Exposure Draft) while limiting unintended consequences for the accounting for other contracts?
Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
Limitation of scope to 'pay-as-produced' contracts
A1We support the pragmatic approach to address the issue through an exception based on specified characteristics. We agree that this approach should limit the risk of unintended consequences.
A2We understand that the IASB's intention is to limit the scope of the amendments to contracts which, amongst other criteria, expose the purchaser to “substantially all the volume risk under the contract”. However, we are concerned that, as drafted, the scope limitation appears also to require the existence of 'pay-as-produced' features in the contract. This drafting appears to exclude other types of contract that may also transfer volume risk and otherwise meet the ‘factors to consider' set out in paragraph 6.10.3.
A3For example, stakeholders have expressed concerns that the amendments may exclude contracts that promise to deliver a fixed volume of power over a specified period.13 The risk that the renewable resource generating the power may produce more or less power than expected, through for example variations in levels of wind or sun, is retained by the seller rather than the purchaser. However, the purchaser in such contracts may still be exposed to short-term supply/demand mismatches, due to the risk that the power supplied under the contract does not match power consumption in designated 30 minute periods14 over the course of each 24 hours.
A4Where supply exceeds demand, the purchaser is generally required to sell such power back to the grid. Our understanding is that it is currently a matter of accounting judgement whether the frequency and volume of such sales are considered consistent with the 'own use' requirements. We understand that some such contracts that would be capable of being assessed as consistent with the factors set out in 6.10.3 of the ED may currently be assessed as not for 'own use' and require derivative accounting.
A5We understand that such fixed volume (or ‘baseload') contracts represent a significant, and growing, share of the UK renewable electricity market. We also understand that for many corporates purchasing under such contracts, management's intention when entering into these contracts is typically to receive electricity in accordance with expected purchase or usage requirements, and not to sell for the purposes of generating short term profits from price fluctuations. It is therefore not clear to us why the rationale set out in BC18 should not also apply to such contracts.
A6The alternative views accompanying the ED, and in particular AV8, highlight concerns about the neutrality of favouring contracts for renewable electricity over other contracts. We consider that as drafted the ED appears to favour one type of renewable electricity contract over another and are concerned that this could be seen as straying from the principle of neutrality. There may also be a risk of the amendments driving market or behavioural changes and lead to companies favouring 'pay-as-produced' contracts above other types of contract, to secure a particular accounting outcome.
A7We recommend the IASB consider amending the wording of paragraph 6.10.1 to ensure that the scope of the amendments is driven solely by a contract's characteristics rather than by any particular description or labelling of its features. For example, 6.10.1 (b) could read: ‘that contract exposes the purchaser to substantially all the volume risk under the contract, for example through 'pay-as-produced' or similar features' (additional wording to ED underlined).
Drafting points
A8Paragraph 6.10.1 limits the scope of these proposals to 'a contract for renewable electricity' with specified characteristics. The draft text distinguishes between 'normal purchase' contracts and contracts requiring net settlement of the difference between specified prices for the volume of electricity produced from a referenced production facility. While we do not believe there is significant scope for confusion here, it was not clear to us that the latter contracts would meet the requirement to be a contract for renewable electricity, as the contract does not involve any delivery of the underlying subject matter.
A9We understand the IASB intends these amendments to apply to virtual PPAs as well as physical PPAs. We recommend the IASB consider defining the term 'contract for renewable electricity' or otherwise making it beyond doubt that the scope includes virtual PPAs, for example by referring to "a contract relating to" or "a contract in respect of” renewable electricity.
A10We also observe that, in BC3 where the basis for including virtual PPAs within the proposals is discussed, a statement is made that “the objective of both physical PPAs and virtual PPAs is to ensure long-term access to renewable electricity...". As noted above, our understanding is that a virtual PPA does not involve the delivery of renewable electricity to the customer so may not in itself ensure access to electricity.
A11Paragraph 6.10.2 states that paragraphs 6.10.3-6.10.6 “provide exceptions to only the requirements in IFRS 9 specified in the paragraphs 6.10.3-6.10.6.” We are concerned that this reference to “exception”, might be understood to provide a total exception to the requirements of paragraphs 2.4 or Section 6.3 of IFRS 9. We recommend that consideration is given to this wording to make this clearer, for example through referring to “modify the requirements of IFRS 9 only as specified...".
A12As a further minor drafting point, we note the words in the final sentence of BC20(b) “contracts are timely reclassified as derivatives” would read better as “contracts are reclassified as derivatives on a timely basis...”.
Question 2—Proposed ‘own use’ requirements
Paragraph 6.10.3 of the proposed amendments to IFRS 9 includes the factors an entity would be required to consider when applying paragraph 2.4 of IFRS 9 to contracts to buy and take delivery of renewable electricity that have specified characteristics.
Do you agree with these proposals? Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
A13We are broadly supportive of the direction taken in the ED in relation to the 'own use' requirements. They appear to provide a pragmatic solution for those contracts within scope of the amendments.
A146.10.3(a) includes helpful guidance in relation to the assessment of expected purchase or usage requirements. In particular, the clarification that the entity is not required to make a detailed estimate for periods far in the future is expected to be welcomed by preparers.
A15In spite of the clear statement in paragraph 6.10.2 that these requirements shall not be applied by analogy to other contracts, we believe there is a risk that this concession may be interpreted as setting expectations for the actions required by an entity assessing whether the 'own use' requirements are met for contracts that fall outside the scope of these amendments – i.e. that detailed estimates would be required for periods far in the future. To the extent that this goes beyond existing guidance on the application of IFRS 9.2.4, this could lead to changes in practice, and cause entities to reach different conclusions on the required accounting for other contracts. While we believe the proposed solution is sensible for contracts within the scope of the amendments, we therefore caution that this solution is not free of risks of wider repercussions.
A16Paragraph 6.10.3(b)(i) includes the criteria that “the sale arises from the entity's exposure to the volume risk...”. It may be clearer to specify the volume risk that this refers to, for example “the volume risk arising under the contract”.
A17Paragraph 6.10.3(b)(iii) refers to purchase of electricity “within a reasonable time” and gives an example of one month. We note that some contracts where supply or demand is significantly affected by seasonal variations, e.g. for the generation of power from solar panels, or where demand drops significantly due to a factory closing for a month in the summer, may not meet the requirement within a month. However, on balance we feel this is a pragmatic solution, and support the inclusion of this indication of what is meant by 'reasonable' in this context.
Question 3—Proposed hedge accounting requirements
Paragraphs 6.10.4–6.10.6 of the proposed amendments to IFRS 9 would permit an entity to designate a variable nominal volume of forecast electricity transactions as the hedged item if specified criteria are met and permit the hedged item to be measured using the same volume assumptions as those used for measuring the hedging instrument.
Do you agree with these proposals? Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
A18In general, we welcome the proposed hedge accounting requirements. The designation of a variable volume of forecast electricity transactions as the hedged item should allow hedge accounting to more accurately reflect the economic substance of some arrangements involving these contracts. We are also broadly supportive of the approach taken to the other proposals, subject to the comments set out below.
A19We note that the hedge accounting proposals are relatively complex. We believe that users may find it difficult to understand how to apply these new concepts in practice, in particular the precise meaning of the drafting in paragraph 6.10.4(b). We strongly recommend the development of illustrative examples that show how the requirements of paragraphs 6.10.4 and 6.10.5 are intended to be applied in relation to purchases and sales of renewable electricity. As a more minor drafting point, we assume the text of 6.10.4 (b) should read “does not exceed”.
A20It was also unclear to us whether the text of 6.10.4(b) described a test only at the initial designation of the hedge, or whether there was some component of ongoing assessment of this measure.
Question 4—Proposed disclosure requirements
Paragraphs 42T–42W of the proposed amendments to IFRS 7 would require an entity to disclose information that would enable users of financial statements to understand the effects of contracts for renewable electricity that have specified characteristics on:
(a) the entity's financial performance; and
(b) the amount, timing and uncertainty of the entity's future cash flows.
Do you agree with these proposals? Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
A21We agree with these proposals. We consider they strike a reasonable balance between providing useful information about the effects and risks associated with these contracts, and concerns about commercial sensitivity.
A22We think that users may consider that disclosure of information of this nature would also be useful in relation to similar contractual exposures for contracts for renewable electricity that fall outside the scope of these requirements. However, we note that this may go beyond the scope of these amendments.
Question 5—Proposed disclosure requirements for subsidiaries without public accountability
Paragraphs 67A–67C of the proposed amendments to the forthcoming IFRS 19 Subsidiaries without Public Accountability: Disclosures would require an eligible subsidiary to disclose information about its contracts for renewable electricity with specified characteristics.
Do you agree with these proposals? Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
A23The application of IFRS 19 Subsidiaries without Public Accountability: Disclosures in the UK is conditional on the endorsement of the standard by the UKEB. The UKEB has not yet begun its endorsement assessment and the following comments should be viewed in that context.
A24We welcome the IASB's identification of consequential amendments to the standard in this ED. We think this is an efficient approach that will ensure disclosure requirements for eligible subsidiaries keep pace with the development of IFRS Accounting Standards for the parent entity's consolidated financial statements. We are broadly supportive of the proposed amendments.
A25We believe that it would be helpful if the Basis for Conclusions explained the rationale for the exclusion of IFRS 7 paragraph 42W from IFRS 19.
Question 6—Transition requirements
The IASB proposes to require an entity to apply:
(a) the amendments to the own-use requirements in IFRS 9 using a modified retrospective approach; and
(b) the amendments to the hedge accounting requirements prospectively.
Early application of the proposed amendments would be permitted from the date the amendments were issued.
Do you agree with these proposals? Why or why not?
If you disagree, please specify with which aspect of the proposals you disagree. What would you suggest instead and why?
A26We broadly support the IASB's proposals on transition. However, we are concerned that the requirements in 6.10.3 requiring an entity to assess a contract "at inception of the contract and at each subsequent reporting date”, coupled with retrospective application, may be unduly onerous and potentially difficult to apply without the benefit of hindsight.
A27If an entity had entered into contracts within the scope of the amendments several years previously, it may be difficult for them to reassess all the factors indicated in 6.10.3 at each historic reporting date. Because failure to meet the ‘own use' requirements is a once and for all assessment, this could make a difference to the outcome (i.e. the result of the assessment could be different depending on whether it was carried out at the inception of the contract a number of years ago at inception of the contract and at each subsequent reporting date, or only at the date of initial application of the amendments.)
A28If the IASB's intention is that on transition an entity should make the assessment of the factors in 6.10.3 only at the date of initial application of the amendments, or at the beginning of the reporting period if an entity applies these amendments in a reporting period during which the amendments are issued, we recommend this is made explicit in the transition provisions, for example as an optional transition exemption. We note that similar provisions have previously been included in transition provisions such as IFRS 16 paragraph C16, where no reassessment of historic sale and leasebacks was required by lessors.
Question 7—Effective date
Subject to feedback on the proposals in this Exposure Draft, the IASB aims to issue the amendments in the fourth quarter of 2024. The IASB has not proposed an effective date before obtaining input about the time necessary to apply the amendments.
In your view, would an effective date of annual reporting periods beginning on or after 1 January 2025 be appropriate and provide enough time to prepare to apply the proposed amendments? Why or why not?
If you disagree, what effective date would you suggest instead and why?
A29We note the urgency of the issue and support the IASB's efforts to finalise the amendments on a timely basis. We recognise the importance of these amendments being available for adoption as soon as possible and support the option to early adopt the amendments.
A30However, given the amendments are not expected to be finalised until the end of 2024, we consider that preparers may consider an effective date of 1 January 2025 to be challenging. Preparers may face challenges around the data required to assess the factors relating to the 'own use' requirements in 6.10.3, and in preparing the new disclosure requirements in 42V, which may require more lead time.
A31We recommend the IASB consider making these amendments effective for accounting periods beginning on or after 1 January 2026, with early adoption permitted.
Appendix C: Invitation to Comment
Call for comments on the Exposure Draft Contracts for Renewable Electricity: Proposed Amendments to IFRS 9 and IFRS 7
Deadline for completion of this Invitation to Comment:
Midday, [Thursday, 4 July 2024]
Please submit to:
Introduction
The objective of this Invitation to Comment is to obtain input from stakeholders on the Exposure Draft (ED) Contracts for Renewable Electricity: Proposed Amendments to IFRS 9 and IFRS 7, published by the International Accounting Standards Board (IASB) on 8 May 2024. The IASB's comment period ends on 7 August 2024.
UK endorsement and adoption process
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. This letter is intended to contribute to the IASB's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
Who should respond to this Invitation to Comment?
Stakeholders with an interest in the quality of accounts prepared in accordance with international accounting standards.
How to respond to this Invitation to Comment
Please download this document, answer any questions on which you would like to provide views, and return it together with the 'Your Details' form to [email protected] by midday on [Thursday, 4 July 2024].
Brief responses providing views on individual questions are welcome, as well as comprehensive responses to all questions.
Privacy and other policies
The data collected through responses to this document will be stored and processed by the UKEB. By submitting this document, you consent to the UKEB processing your data for the purposes of influencing the development of and adopting IFRS for use in the UK. For further information, please see our Privacy Statements and Notices and other Policies (e.g. Consultation Responses Policy and Data Protection Policy)17.
The UKEB's policy is to publish on its website all responses to formal consultations issued by the UKEB unless the respondent explicitly requests otherwise. A standard confidentiality statement in an e-mail message will not be regarded as a request for non-disclosure. If you do not wish your signature to be published, please provide the UKEB with an unsigned version of your submission. The UKEB prefers to publish responses that do not include a personal signature. Other than the name of the organisation/individual responding, information contained in the “Your Details” document will not be published. The UKEB does not edit personal information (such as telephone numbers, postal or e-mail addresses) from any other response document submitted; therefore, only information that you wish to be published should be submitted in such responses.
Questions
Scope
1The UKEB's draft comment letter (DCL) recommends the IASB consider amending the wording of the scope of the ED to ensure the scope of the amendments is driven solely by a contract's characteristics rather than by any particular description or labelling of its features. Do you agree with this recommendation? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
'Own-use' requirements
2The UKEB's DCL supports the proposals in relation to the ‘own use' requirements, subject to noting that the proposals may risk setting expectations for similar contracts outside the scope of these amendments. Do you agree with this comment? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
Hedge accounting requirements
3The UKEB's DCL supports the proposed amendments to the hedge accounting requirements for contracts within the scope of the amendments, but recommends the IASB develop illustrative examples to show users how the proposals are intended to apply. Do you agree with this recommendation? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
Other
4The UKEB's DCL supports the proposed amendments in relation to disclosures, and the proposed disclosure requirements for subsidiaries without public accountability. Do you agree with this position? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
5The UKEB's DCL notes that the transition requirements coupled with the own use requirements could be read as requiring preparers to assess contracts against the 'own use' requirements for a number of historic reporting periods. It recommends that the IASB makes it explicit that this assessment is required only at the date of initial application of the amendments. Do you agree with this recommendation? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
6The UKEB's DCL notes that an effective date of 1 January 2025 may present difficulties for some preparers and recommends that the IASB consider an effective date of 1 January 2026, with early adoption permitted. Do you agree with this recommendation? Please explain why or why not.
Yes [ ] No [ ]
Click or tap here to enter text.
7Do you have any comments on any other aspects of the proposals.
Yes [ ] No [ ]
Click or tap here to enter text.
8What benefits would these proposals provide you with?
Click or tap here to enter text.
9What costs would be associated with these proposals? Please share any qualitative or quantitative information on the cost of implementing the proposals you are aware of.
Click or tap here to enter text.
Thank you for completing this Invitation to Comment
Please submit this document by midday on [Thursday, 4 July 2024] to [email protected]
Footnotes
Footnotes
-
Physical power purchase agreements are those in which an energy generator physically delivers power to a user, often called an offtaker, for a price. Delivery can be via a grid. ↩↩
-
Virtual PPAs are typically structured as a 'contract for difference' between the fixed price (per MW of energy) determined in the virtual PPA and the spot price at which energy could be purchased from the grid (i.e. net settled swaps). No physical energy is exchanged. ↩↩
-
PwC EX40.79.3; EY IFRS accounting primer for renewable power purchase agreements 2.2.4 ↩↩
-
PwC EX40.79.3; EY IFRS accounting primer for renewable power purchase agreements 2.2.4; Deloitte DART D1 2.5.3-3. ↩↩
-
See the IFRIC March 2019 decision which responds to a question as to whether load-following swaps may be designated as hedging instruments, and accompanying staff paper. Also see EY Chapter 48 2.3 for commentary on the decision to this effect. ↩
-
Virtual PPAs are typically structured as a 'contract for difference' between the fixed price (per MW of energy) determined in the virtual PPA and the spot price at which energy could be purchased from the grid (i.e. net settled swaps). No physical energy is exchanged. ↩↩
-
The fair value of PPAs is often calculated on their P50 value (50% of the average volumes expected to be generated), whereas hedging is calculated on their P90 value (amount expected to be generated 90% of the time). This paragraph draws on PwC ViewPoint EX46.43.1. Deloitte 5.2.3 expresses similar caution. ↩↩
-
This paragraph draws on PwC ViewPoint EX46.43.1. Deloitte 5.2.3 expresses similar caution. ↩
-
UKEB calculation based on LSEG and Eikon data, May 2024. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩
-
Stakeholders have referred to these contracts as 'baseload' contracts, though we recognise this term may not be consistently used and may not always serve as an accurate description of their nature. ↩
-
Load following swaps Agenda paper: https://www.ifrs.org/content/dam/ifrs/meetings/2019/march/ifric/ap10-ifrs-9-load-following-swaps-incl-comment-letters.pdf and IFRIC update discussion: https://www.ifrs.org/news-and-events/updates/ifric/2019/ifric-update-march-2019/#5 ↩
-
IFRS 19 paragraphs 5-6 ↩
-
These policies can be accessed from the footer in the UKEB website here: https://www.endorsement-board.uk ↩