4 Power Purchase Agreements – Project Initiation Plan
Executive Summary
| Header | Value |
|---|---|
| Project Type | Influencing |
| Project Scope | Narrow-scope |
| Purpose of the paper | This paper provides the Board with a Project Initiation Plan (PIP) for the project relating to the IASB's proposed amendments to IFRS 9 Financial Instruments. |
Summary of the Issue
Developments in reporting of greenhouse gas emissions (such as Streamlined Energy and Carbon Reporting regulations (“SECR”)) and in relation to reporting progress against targets to reduce greenhouse gas emissions (under Task Force on Climate-Related Financial Disclosures (“TCFD”) and in the future under IFRS S2 Climate-related Disclosures) have increased focus on Scope 2 emissions. It appears that, increasingly, entities are entering into power purchase agreements (PPAs) for the supply of renewable electricity, validated by third-party renewable energy certificates (RECs), as well as for price security.
Following stakeholder feedback, the IASB added a project on whether IFRS 9 Financial Instruments could be amended to facilitate the application of the ‘own-use' exception to physical PPAs1 and whether virtual PPAs2 may be designated as hedging instruments in a qualifying hedging relationship.
The IASB expects to issue an Exposure Draft setting out its proposed amendments in May 2024 with a 90-day comment period. The Secretariat therefore asks the Board to consider two potential options for the timing of the publication of its DCL.
Option one: If the ED is published by 13 May 2024, publication of a UKEB DCL following the Board's May 2024 meeting for a 30-day comment period, with the FCL to be approved at the July 2024 Board meeting. However, if the ED is not published by 13 May 2024, publication of a UKEB DCL following the Board's June 2024 meeting for a 30-day comment period, with the FCL to be approved at an ad-hoc August 2024 meeting; or
Option two: Publication of a UKEB DCL in June 2024 for a 30-day comment period, with the FCL to be approved at an ad-hoc August 2024 Board meeting.
Decisions for the Board
- Does the Board agree with the Secretariat's recommendation that the project timeline should follow option one?
- Subject to that decision, does the Board approve the PIP?
Recommendation
The Secretariat recommends that the Board:
- approves option one;
- approves the PIP.
Purpose
1This paper provides the Board with a Project Initiation Plan (PIP) for the influencing phase of the project relating to the IASB's proposed amendments to IFRS 9 Financial Instruments.
Background
2Developments in reporting of greenhouse gas emissions (such as SECR) and in relation to reporting progress against targets to reduce greenhouse gas emissions (under TCFD and in the future under IFRS S2) have increased focus on Scope 2 emissions. It appears that, increasingly, entities are entering into PPAs for the supply of renewable electricity, validated by third-party RECs, as well as for price security.
3Following stakeholder feedback, the IASB added a project to its workplan on whether the 'own-use' exception could be applied to physical PPAs3 and whether virtual PPAs4 may be designated as virtual PPAs as hedging instruments in a qualifying hedging relationship.
4The UKEB has been actively monitoring the decisions taken by the IASB to inform the ED as part of its IASB General Update papers. The relevant UKEB papers are:
- April 2023 IASB General Update
- September 2023 IASB General Update
- December 2023 IASB General Update (under climate-related matters)
- January 2024 IASB General Update
- February 2024 IASB General Update (under climate-related matters)
- March 2024 IASB General Update
5The Preparer, Accounting Firms and Institutes and Investor Advisory Groups as well as the Financial Instruments Working Group discussed the topic at their meetings in January to March 2024.
Project Initiation Plan (PIP)
6The draft PIP is attached at Appendix A for the Board's consideration and approval.
7The IASB is currently expected to issue the ED in May 2024 with a short (90-day) comment period.
8If the DCL is reviewed at the 24 May 2024 Board, for which papers are required a week earlier, this leads to a very short window for producing the DCL. If the IASB publishes the ED before 13 May 2024 and the Board is content for the DCL to be prepared in a short time period, based primarily on engagement with advisory groups prior to the issuance of the ED, the Secretariat considers that this would be feasible. However, if the IASB publishes the ED after 13 May 2024, then the DCL would need to be reviewed at the June Board meeting and an ad-hoc meeting arranged early in August 2024 (option one).
9Alternatively, the Board may prefer to plan for a longer time to prepare the DCL and request an ad-hoc meeting in August to be arranged, regardless of the timing of the ED (option two).
10The Secretariat therefore asks the Board to consider two potential options for the timing of the publication of its DCL. These are:
- If the ED is published by 13 May 2024, to issue a DCL following the 24 May 2024 Board meeting for a public comment period of 30 days. The FCL would be submitted to the July Board meeting. If the ED is published after 13 May 2024, to issue a DCL following the 28 June 2024 Board meeting for a public comment period of 30 days, which would require an ad-hoc Board meeting in August 2024 in order to submit the comment letter on time (option one); or
- regardless of the date the ED is issued, to issue a DCL following the 28 June 2024 Board meeting for a public comment period of 30 days, which would require an ad-hoc meeting in August 2024 in order to submit the comment letter on time (option two).
Secretariat recommendation
11The Secretariat recommends option one, as this option may avoid the need for an ad-hoc meeting in August.
12The Secretariat does not recommend option two as, if the IASB publishes the ED in early May, then the project can be completed within the scheduled Board meetings.
Questions for the Board
- Does the Board agree with the Secretariat's recommendation that the project timeline should follow option one?
- Subject to that decision, does the Board approve the PIP?
Appendix A: Power Purchase Agreements – Project Initiation Plan
| Project Type | Project Scope |
|---|---|
| Influencing | Limited |
Purpose
A1This paper sets out the plan to influence the proposed Amendments Power Purchase Agreements (the Amendments), which are expected to be published by the IASB in May 2024. The tentative proposals are included in the IASB March 2024 Staff Paper agenda reference 3A and are summarised in the UKEB March IASB General Update.
Background
A2In June 2023, the IFRS Interpretations Committee referred a request to the IASB5 about whether IFRS 9 Financial Instruments paragraphs 2.4 to 2.6 (the 'own-use' exception) could be applied to physical power purchase agreements (PPAs).6 Following this referral, the IASB added a research project on this topic to its workplan.7
A3Stakeholders also told the IASB that, by analogy with a March 2019 Interpretations Committee decision8 on load-following swaps,9 they were unable to designate virtual PPAs10 as hedging instruments in a qualifying hedging relationship.
A4Developments in reporting of greenhouse gas emissions (such as Streamlined Energy and Carbon Reporting Regulations) and in relation to reporting progress against targets to reduce greenhouse gas emissions (under Task Force on Climate-related Financial Disclosures and in the future under IFRS S2 Climate-related Disclosures) have increased focus on Scope 2 emissions. It appears that, increasingly, entities are entering into PPAs for the supply of renewable electricity, validated by third-party renewable energy certificates (RECs), as well as for price security.
A5Consequently, in December 2023 the IASB decided to make narrow-scope amendments to IFRS 9 in order to permit PPAs to meet the 'own-use' and hedge accounting requirements, and to require entities to provide relevant disclosure.11 At the January 2024 ASAF meeting, preliminary feedback was provided on the IASB proposals. The IASB tentatively voted in favour of the staff proposals, set out below, at its March 2024 meeting.12
Tentative decisions
A6The IASB has tentatively decided to extend the ‘own use' requirement to those contracts for renewable electricity for which the source of production is nature-dependant, with the effect that the time or volume of supply cannot be guaranteed, and where the purchaser is exposed to substantially all of the volume risk under the contract through pay-as-produced features. Examples provided include wind, solar and hydroelectricity.
A7The IASB also has tentatively decided that the purchaser under the contract be required to consider the purpose, design and structure of the contract, and whether the volume expected to be delivered under the contract continues to be consistent with the entity's expected purchase or usage requirements.
A8In relation to the hedge accounting requirements, the IASB has tentatively decided that if certain criteria are met, entities would be permitted to designate a variable nominal volume or quantity of forecast sales or purchases of renewable electricity as the hedged item in a cash flow hedge. These criteria are as follows:
- The volume of the designated hedged item is specified as a proportion of the variable volume of the hedging instrument.
- The hedged item and hedging instrument are measured using the same volume assumptions, but other assumptions such as the pricing structure reflect the nature of the hedged item as renewable electricity.
A9The designated forecast sales or purchases of electricity are:
- For purchasers – highly probable if the entity has sufficient highly probable forecast purchases that exceed the estimated variable volume (or quantity) to be designated by the entity as the hedged item.
- For sellers – not required to be highly probable as the designated quantity of sales is certain to be hedged if it occurs.
A10The hedging proposals are expected to affect only IFRS 9 and will not change IAS 39 Financial Instruments: Recognition and Measurement.
A11The IASB tentatively decided to require disclosure of the following information for all contracts for renewable electricity:
- The terms and conditions of relevant contracts, including the contracts' duration, type of pricing, minimum or maximum quantities, cancellation clauses and whether they include renewable energy certificates.
- The net volume purchased or the total volume for which amounts were net-settled for the reporting period, and an explanation of any significant variances in the volume. Entities are also required to disclose the average market price per unit of electricity for the reporting period.
- Either the fair value of contracts accompanied by the information required by paragraph 93(g)-(h) of IFRS 13 Fair Value Measurement or the volume expected to be sold or purchased over the remainder of the contract, which could be provided as a range, and the assumptions supporting that analysis.
A12The IASB tentatively decided that entities will apply the amendments retrospectively. However, restatement of comparatives would not be required. The hedge accounting requirements should be applied prospectively. Where an entity can consider existing arrangements without hindsight, it may alter the designation of an existing hedged item and it may also hedge relationships from the time the criteria would have been met.
Project plan rationale
A13The following considerations have shaped the project plan.
The scope of the IASB project is to make limited-scope amendments to IFRS 9
A14Following stakeholder input and feedback, the IASB tentatively decided to scope the project as limited to contracts for renewable electricity with a nature-dependant source and in which the purchaser is exposed to substantially all the volume risk.13
A15The Amendments are therefore not expected to change the principles of IFRS 9. However, existing practice may change, if the Amendments specify requirements in areas in which entities previously considered they had a choice of accounting policy or indicate required accounting for contracts that are not specifically within scope. The project may also result in some additional presentation or disclosure requirements.
A16The Amendments may affect any entity that has entered into a PPA.
Renewable energy PPAs are increasing in prevalence in the UK
A17Research indicates that renewable energy PPAs have been around in the UK for some time, but have become more prominent in recent years.14 As at November 2023, the UK was regarded as the fourth most attractive global market for renewable energy PPAs.15
A1863 UK listed IFRS reporters in FY2022/2023, from across a range of sectors, referred to PPAs within their annual report. This indicates that they are relatively widely used.
A1912 entities referred to PPAs in their financial statements, of which eight were in the utilities and energy sectors.
Initial engagement with UK stakeholders suggests they welcome the project
A20At the February 2024 Investor Advisory Group (IAG) and Preparer Advisory Group (PAG), the March 2024 Accounting Firms and Institutes Advisory Group (AFIAG) and the January 2024 Financial Instruments Working Group (FIWG), stakeholders welcomed the project. However, their initial feedback, together with our desk-based research, based on early, high-level IASB staff proposals, has highlighted areas where the ED will require close review.
Setting up an ad-hoc advisory group is not necessary
A21The UKEB standing advisory groups are well placed to provide feedback on this limited scope project, so it is not considered necessary to set up a separate ad-hoc advisory group specific to this project.
[Project timelines]
A22[We have set out below two options for the timeline for the influencing phase. The Board is asked to decide its preferred timeline. Text pertaining to the two options is in square brackets throughout this document as we will publish the PIP with the approved option only.]
Project milestones
A23A proportionate approach is proposed, incorporating mandatory milestones listed in paragraph 5.3 of the UKEB's Due Process Handbook (Handbook). The table below provides a brief description of the work we have done and that we intend to do as part of this project.
A24Future dates are based on current expectations and are, therefore, subject to subsequent modification. The Board will be alerted to any significant changes.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30(b)] | Added to UKEB technical work plan. | Completed. |
| Education session on IASB proposals on PPAs (optional) [Handbook 4.10] | An education session on the tentative proposals will be provided to the Board before the public meeting, at which this document will be discussed, in April 2024. | Planned for the April 2024 Board meeting. |
| Desk-based research (optional) [Handbook 5.9] | The Secretariat has begun its programme of desk-based research, to include review of IASB staff papers, publications from regulators, accounting firms and other relevant sources including accounting manuals as well as the ED when published. | In progress. |
| Outreach activities (mandatory) [Handbook 5.11] | We have already begun to engage with IAG, PAG, AFIAG and FIWG and will continue to engage with members at the June and July 2024 meetings. In addition, we plan to seek feedback from relevant specialists. | In progress. |
| Project Initiation Plan (PIP) (mandatory) [Handbook 5.4 to 5.8] | This paper | To be brought to April 2024 Board meeting, ahead of the IASB's publication of the ED. |
| Draft comment letter (DCL) published for comment (generally mandatory) [Handbook paragraphs 5.13 to 5.17] | [Option One The Secretariat will publish the approved DCL for public comment for 30 days following the May 2024 Board meeting. If the ED is not published by 13 May 2024, the UKEB will publish the approved DCL for public comment for a minimum of 30 days following the June 2024 Board meeting.] [Option Two The Secretariat will publish the approved DCL for public comment for a minimum of 30 days following the June 2024 Board meeting.] |
[Option One As soon as possible after the May 2024 Board meeting, or if not possible, after the June 2024 Board meeting.] [Option Two As soon as possible after the June 2024 Board meeting.] |
| UKEB submits final comment letter (FCL) to the IASB (mandatory) [Handbook paragraph 5.18] | [Option One The IASB comment period is expected to close in mid-August 2024. The Secretariat will submit the FCL to the IASB as soon as possible following approval at the July 2024 UKEB meeting. If the ED is published after 13 May 2024, an ad-hoc meeting will be scheduled in August 2024 to permit the Board to review the FCL, permitting submission to the IASB before the 30-day comment period ends. A late paper may be required.] [Option Two An ad-hoc meeting will be scheduled in August 2024 to permit the Board to review the FCL, permitting submission to the IASB before the comment period ends. A late paper may be required.] |
[Option One As soon as possible after the July 2024 Board meeting, or if not possible due to the timing of the publication of the ED, as soon as possible after the August 2024 Board meeting.] [Option Two As soon as possible after the August 2024 Board meeting.] |
| Feedback statement and due process compliance statement for influencing stage of project | Secretariat publishes Feedback Statement and Due Process Compliance Statement on the UKEB website. | To be completed. |
Resources allocated
A25On the basis of this project plan, we consider that a project team consisting of one Project Director (0.8 FTE) and ad-hoc project manager support as available and technical support and oversight from a Senior Project Director should ensure the project timelines are achievable. Input from the economics team and communications support will be obtained as appropriate. Sufficient resources have been allocated in the Work Plan.
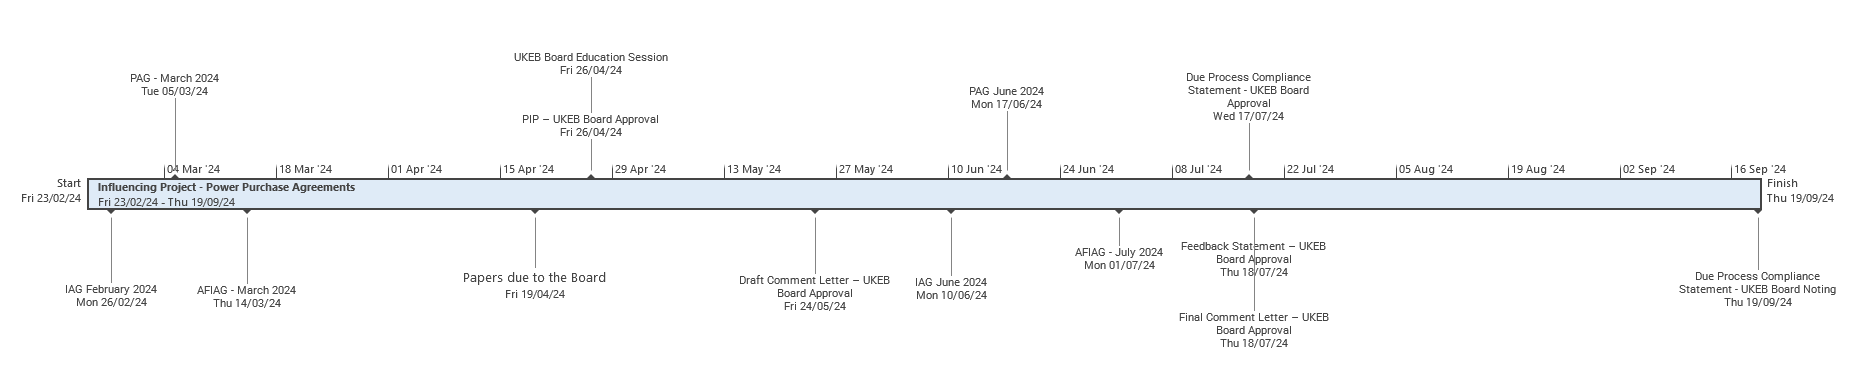
Detailed project timeline [Option One: If IASB publishes ED on or before 13 May 2024, FCL discussed at July Board meeting]
| Date | Milestone |
|---|---|
| October 2023 to April 2024 | Preliminary analysis and outreach before publication of Exposure Draft |
| 26 April 2024 | Board: Education session on proposed topics for Amendments. |
| 26 April 2024 | Board: Discusses and approves Project Initiation Plan (this document). |
| May 2024 | IASB publishes ED with 90-day comment period. |
| 17 May 2024 | Secretariat: Submits DCL to Board. |
| 24 May 2024 | Board: Discusses and approves DCL. |
| 29 May 2024 | Secretariat: Alerts key stakeholders to publication of DCL. |
| 29 May 2024 to 28 June 2024 | 30-day comment period. |
| 18 July 2024 | Board: Discusses and approves Final Comment Letter (FCL) and Feedback Statement, and reviews draft Due Process Compliance Statement. |
| As soon as possible after Board discussion | Secretariat: Submits FCL to IASB and publishes FCL on website. |
| 19 September 2024 | Board: Notes Due Process Compliance Statement. |
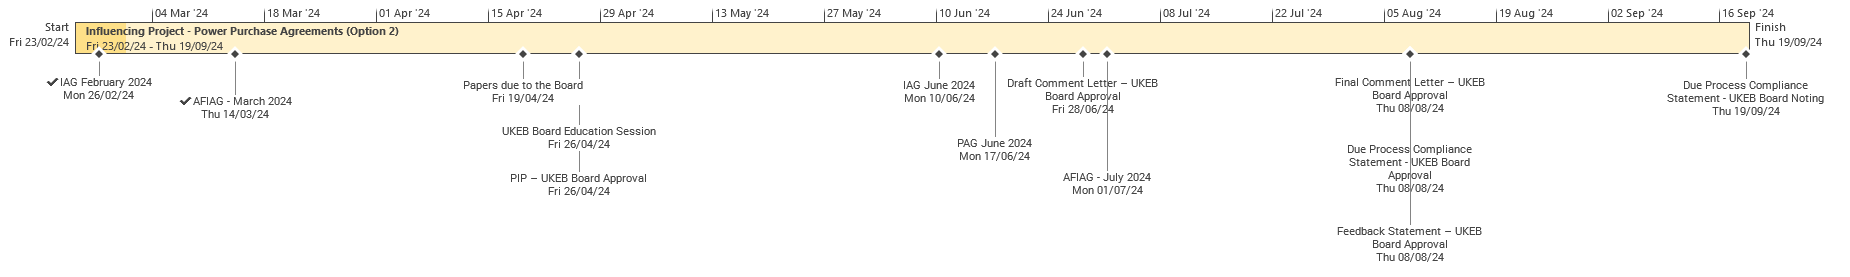
[Option One:] [if IASB publishes ED after 13 May 2024, FCL discussed at additional August Board meeting] [and] [Option Two]
| Date | Milestone |
|---|---|
| October 2023 to April 2024 | Preliminary outreach before publication of Exposure Draft |
| 26 April 2024 | Board: Education session on proposed topics for Amendments. |
| 26 April 2024 | Board: Discusses and approves Project Initiation Plan (this document). |
| May 2024 | IASB publishes ED with 90-day comment period. |
| May to July 2024 | Secretariat: Outreach with advisory groups, FIWG and relevant industry groups. |
| 21 June 2024 | Secretariat: Submits DCL to Board. |
| 28 June 2024 | Board: Discusses and approves DCL. |
| Shortly after 28 June 2024 | Secretariat: Alerts key stakeholders to publication of DCL. |
| 3 July to 2 August 2024 | 30-day comment period. |
| Early August 2024 | Board: Discusses and approves FCL, Feedback Statement and Due Process Compliance Statement at ad-hoc meeting. Late paper likely to be required. |
| As soon as possible after Board discussion | Secretariat: Submits FCL to IASB and publishes FCL on website. |
Footnotes
Footnotes
-
Physical power purchase agreements are those in which an energy generator physically delivers power to a user, often called an offtaker, for a price. Delivery can be via a grid. ↩
-
Virtual PPAs are typically structured as a 'contract for difference' between the fixed price (per MW of energy) determined in the virtual PPA and the spot price at which energy could be purchased from the grid (i.e. net settled swaps). No physical energy is exchanged. ↩
-
Physical power purchase agreements are those in which an energy generator physically delivers power to a user, often called an offtaker, for a price. ↩
-
Virtual PPAs are typically structured as a 'contract for difference' between the fixed price (per MW of energy) determined in the virtual PPA and the spot price at which energy could be purchased from the grid (i.e. net settled swaps). No physical energy is exchanged. ↩
-
The IFRIC Staff Paper Agenda Reference 2 summarises the IFRIC initial considerations and paragraph 85 includes the recommendation and rationale. The fact patterns submitted were summarised in the UKEB April 2023 IASB General Update Appendix 8H. ↩
-
Physical power purchase agreements are those in which an energy generator physically delivers power to a user, often called an offtaker, for a price. ↩
-
See the IASB 25 July 2023 PM meeting and the July 2023 Agenda Paper 12. See September 2023 IASB General Update Paper 5 Appendix B for a summary of the ASAF meeting at which national standard-setters were asked for their views on the prevalence of PPAs, their effects within financial statements and the scope of any potential solution. ↩
-
See the IFRIC March 2019 decision and accompanying staff paper. ↩
-
In that decision, the Interpretations Committee considered that the forecast energy sales lacked the required specificity to be designated as a hedged item and therefore did not qualify for hedge accounting. See IAS 39 Implementation Guidance F.3.10: "[...] a forecast transaction cannot be specified solely as a percentage of sales or purchases during a period." ↩
-
Virtual PPAs are typically structured as a 'contract for difference' between the fixed price (per MW of energy) determined in the virtual PPA and the spot price at which energy could be purchased from the grid (i.e. net settled swaps). No physical energy is exchanged. ↩
-
See December 2023 IASB Staff Paper agenda reference 3 and January 2024 IASB General Update Paper 5 Appendix A. ↩
-
See January 2024 ASAF meeting, the February 2024 IASB General Update, IASB March 2024 Staff Paper agenda reference 3A, March 2024 Staff Paper agenda reference 3B, March 2024 Staff Paper agenda reference 3C and the March 2024 IASB General Update. ↩
-
Bird and Bird Corporate PPAs: An International Perspective 2022 edition. ↩
-
EY Renewable Energy Country Attractiveness Index November 2023 edition. ↩