5 Financial Instruments with Characteristics of Equity
28 March 2024 Agenda Paper 5
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
Purpose of the paper
The purpose of this paper is to seek:
- Board approval for the issue of a Final Comment Letter (FCL) (Appendix B) on the Exposure Draft (ED) issued by the IASB on Financial Instruments with Characteristics of Equity (Amendments to IAS 32, IFRS 7 and IAS 1) (FICE);
- Board approval for the publication of the Feedback Statement (Appendix D); and
- Board feedback on the draft Due Process Compliance Statement (DPCS) (Appendix E).
Summary of the Issue
The IASB issued the FICE ED on 30 November 2023, with a comment period of 120 days. It proposes amendments on the following topics: effects of laws; obligations to redeem own equity; the fixed-for-fixed condition; contingent settlement provisions; shareholder discretion; presentation; disclosures; and transition. The UKEB's Draft Comment Letter (DCL) was published for stakeholder comment on 7 February
- This consultation closed on 8 March 2024.
Feedback received since the publication of the DCL has resulted in several proposed changes to the comment letter which are summarised at Appendix A.
A clean copy of the FCL is included as Appendix B; changes from the DCL are marked up at Appendix C.
Decisions for the Board
Subject to any amendments arising at this meeting, does the Board approve:
- The FCL (Appendix B) for issue to the IASB and publication on the UKEB website?
- The Feedback Statement (Appendix D) for publication on the UKEB website?
In addition, the Board is asked whether it has any comments on the draft DPCS (Appendix E) for the project.
Recommendation
The Secretariat recommends that, subject to any amendments agreed at this meeting, the Board approves the FCL and the Feedback Statement for issue and publication.
Appendices
Appendix A Feedback received since publication of DCL Appendix B Final Comment Letter – clean copy Appendix C Final Comment Letter – marked up with changes from DCL Appendix D Feedback Statement Appendix E (Draft) Due Process Compliance Statement
Background
1In this project, the IASB seeks to clarify the underlying classification principles within IAS 32 to assist in distinguishing financial liabilities from equity. The IASB also proposes disclosures to enhance understanding of instruments with both financial liability and equity characteristics and presentation requirements to show amounts attributable to ordinary shareholders separately from those attributable to other owners of an entity. The IASB issued the FICE ED on 29 November 2023, with the comment period closing on 29 March 2024.
2The UKEB DCL was informed by desk-based research and discussions with the following advisory groups:
- Financial Instruments Working Group - September 2023, November 2023 and January 2024 meetings;
- Accounting Firms and Institutes Working Group – November 2023; and
- Investor Advisory Group – November 2023.
3As described in the Project Initiation Plan (PIP), the Secretariat also conducted other outreach activities, including meeting with industry groups and regulators from sectors in which we understand relevant issues regularly arise, to inform the Draft Comment Letter (DCL).
4The DCL was approved at the January 2024 Board meeting and published on the UKEB website on 7 February 2024 with a comment deadline of 8 March 2024. The DCL was generally supportive of the IASB project but provided feedback and recommendations on a number of areas of concern. UKEB news alerts and LinkedIn posts were used to raise awareness of publication of the DCL.
Further outreach and feedback on the DCL
5Three written responses to the DCL were received and uploaded to the UKEB website. As we had held numerous meetings with stakeholders in developing the DCL, this number of formal responses was not unexpected. The Secretariat discussed the DCL with the Investor Advisory Group and the Preparer Advisory Group in February and March 2024, and held follow-up discussions with a number of stakeholders to explore points in further detail.
6A summary of the feedback received since the publication of the DCL and resulting changes to the comment letter are set out in Appendix A to this document. Final Comment Letter (FCL)
7A clean copy of the draft FCL is attached for consideration as Appendix B and, subject to amendments agreed by the Board, approval for issue to the IASB and publication on the UKEB website. To assist Board member review, significant changes (excluding formatting and minor editorial changes) are marked up at Appendix C.
Feedback Statement
8The draft Feedback Statement is attached for consideration as Appendix D, and, subject to amendments agreed by the Board, approval for publication on the UKEB website.
Due Process Compliance Statement (DPCS)
9The draft DPCS is attached for consideration as Appendix E. A final version will be brought back to the April 2024 meeting for noting once the final project steps are complete.
Questions for the Board
1Subject to any amendments agreed at this meeting, does the Board approve:
- The FCL (Appendix B) for issue to the IASB and publication on the UKEB website?
- The Feedback Statement (Appendix D) for publication on the UKEB website?
2Does the Board have any comments on the draft DPCS for the project?
Next steps
10The FCL will be submitted to the IASB as soon as possible. The FCL together with the Feedback Statement will be published on the UKEB website. The DPCS will be updated to reflect the final project steps and presented to the April 2024 meeting for noting.
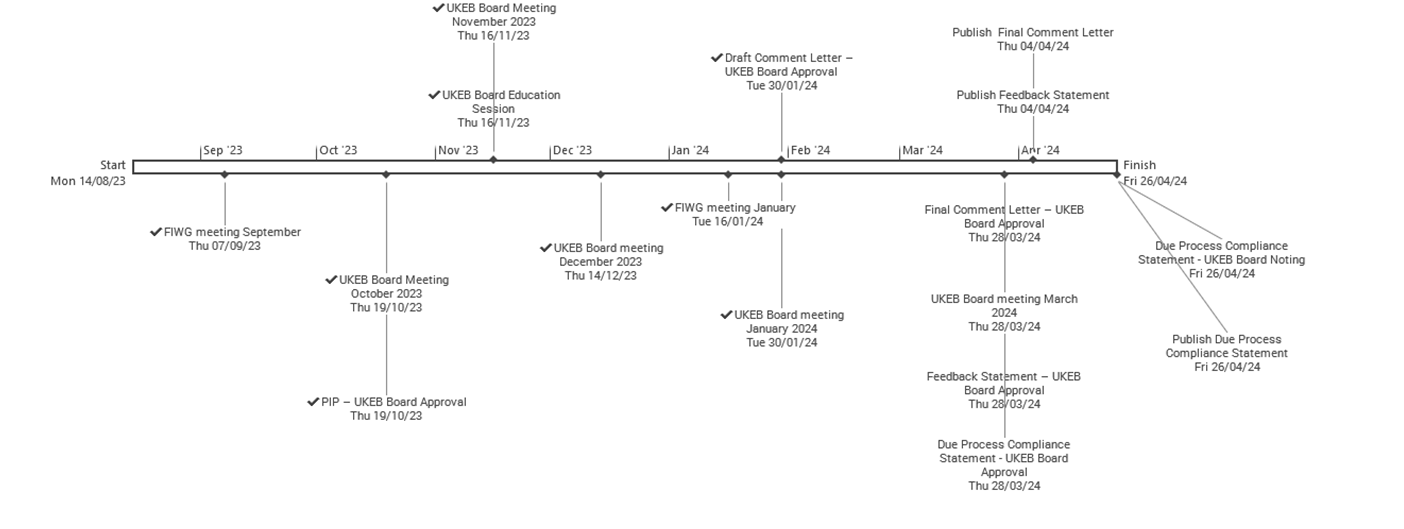
Timeline
Appendix A: Feedback received during the consultation period
Feedback reflected in the comment letter
The table below presents a summary of the main points of feedback received since the publication of the DCL and the changes proposed to the comment letter in the light of that feedback.
| Topic | Summary of stakeholder feedback/proposed change | Paragraph reference within letter |
|---|---|---|
| Significant amendments to comment letter | ||
| Reclassification | Additional discussion of equity derecognition and reclassification now included to highlight further difficulties with current proposals. | 8, A46 to A47 |
| Obligations to redeem own equity | Proposed recommendation to retain the existing reference to IFRS 9 within paragraph 23 and to remove the final two sentences of paragraph 23, as there are considerable challenges in introducing a new measurement basis. Supplementary alternative recommendation to discount liabilities from the expected settlement date. | 12 to 13, A16 to A22 |
| Contingent settlement provisions | Proposed recommendation to retain the existing reference to IFRS 9 within paragraph 23 and to remove paragraph 25A, as there are considerable challenges in introducing a new measurement basis. Supplementary alternative recommendation to discount liabilities from the expected settlement date. | 16, A31 (cross-referenced to A16 to A22) |
| Contingent settlement provisions | Recommended that IASB clarifies scope of paragraphs 25 and 25A as it appears unclear, and now may potentially create tension with IFRS 9 measurement requirements for some debt instruments with contingent settlement features. | 18, A32 to A33 |
| Fixed-for-fixed | Reordered paragraphs on passage of time adjustments to strengthen recommendation that financial instruments linked to determinable benchmark rates, such as interest or inflation, meet the fixed-for-fixed condition. | 20 to 22, A12 to A14 |
| Transition | Expressed concern that the new measurement basis for obligations to redeem own equity may result in changes to acquisition-date goodwill in past business combinations. Emphasised the importance of providing transition relief in this respect. | 28, A62, A68 |
| Transition | Explained that our recommendation that financial instruments that have been extinguished at the date of initial application should not be required to be restated. Clarified that our recommendation for the IASB to consider a transition relief to assess classification at the date of initial application, on the basis of the facts and circumstances at that date, including an assessment only of features that have not expired at that date, should be applied across the board. Referred to the transition arrangements proposed in the Classification and Measurement of Financial Instruments ED paragraph 7.2.48 as an appropriate comparison. | 30 and 31, A68 and A69 |
| Other amendments to comment letter | ||
| Contingent settlement provisions | Included a recommendation to remove the definition of liquidation. | A34 |
| Contingent settlement provisions | Observed that the measurement proposals may create inconsistencies within IAS 32 with paragraphs 31 and 32, which require fair value measurement of the whole instrument and of the liability component. | A30 |
| Fixed-for-fixed | Included a recommendation that the IASB confirms that rounding adjustments to prevent shares being issued in fractions do not breach the fixed-for-fixed condition. | A11 |
| Disclosures | Amended to suggest the IASB carries out field testing, as EFRAG is no longer carrying out field testing. | 24, A52 |
| Disclosures | Removed references to welcoming disclosure requirements overall, given absence of feedback to this effect. | 24, A51 |
| Disclosures | Clarified recommendation that both paragraphs 30A and 30B should be removed, by replacing cross-reference to the disclosure objective contained in ED paragraph 30A with reference to the overall disclosure objectives of IFRS 7 paragraph 1. | 25, A57 |
| Transition | Clarified why these amendments are especially relevant to private equity investors. | A64 |
Appendix B: Final Comment Letter – clean copy
Dr Andreas Barckow Chairman International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
XX March 2024
Dear Dr Barckow
Exposure Draft IASB/ED/2023/5 Financial Instruments with Characteristics of Equity: Proposed amendments to IAS 32, IFRS 7 and IAS 1
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.1 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.2
3We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB) Exposure Draft (ED) Financial Instruments with Characteristics of Equity: Proposed amendments to IAS 32, IFRS 7 and IAS 1 (the Amendments). In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts.
4We support the IASB's objectives in developing the Amendments, and we are broadly supportive of the proposals. We consider it important to provide clarity and minimise the risk of diversity in accounting practice in this complex area. Our main observations and recommendations are set out in the paragraphs that follow. Responses to the IASB's specific questions about the ED are included in the Appendix to this letter.
Reclassification
5We welcome the IASB's efforts to clarify this important area. However, we are concerned that the proposals in their current form could lead to: the classification of financial instruments diverging from their substance; inconsistencies between financial liabilities that result from obligations to redeem own equity and other financial liabilities; and an inappropriate change to established practice.
6The prohibition of reclassification in respect of contractual terms that become, or stop being, effective with the passage of time could result in misleading information. This is because the continuing recognition of a financial liability in such circumstances may no longer faithfully represent the substance of the financial instrument. Example circumstances include the expiry of a contingent settlement provision and a change in terms with the passage of time that results in the instrument meeting the criteria for equity classification.
7We recommend that the IASB consider requiring reclassification of instruments where contractual terms become, or stop being, effective with the passage of time. This would allow consistency with the current application of IAS 32 and avoid some of the potentially unintended outcomes highlighted by stakeholders. We do not consider that such a requirement would significantly increase costs or complexity for most preparers.
8However, if the IASB decides to proceed with the proposals in the ED, we recommend enhancing the Application Guidance on the distinction between reclassification and derecognition, for example in relation to the exercise of an issuer call option in an equity instrument. We believe that in some of the examples raised with us, and in the circumstances set out in paragraph BC143, derecognition of a liability component may be the appropriate outcome, thus resolving the problem.
9Our detailed comments on reclassification are in paragraphs A36 to A50 of the appendix.
Obligations to redeem an entity's own equity instruments
10We agree with the IASB that clarifications in this complex area should reduce diversity of practice.
11However, we are concerned that the proposal at ED question 3(c) in effect introduces a new measurement basis. We consider that the proposal could lead to a change in measurement for some instruments and may reduce the relevance of information provided to users. In particular, the addition in paragraph 23 of the ED “The redemption amount is discounted, assuming redemption will occur at the earliest possible redemption date specified in the contract” could lead to a change in measurement of some relatively common instruments in the UK, such as NCI put options with redemption amounts linked to EBITDA.
12We consider that there are significant challenges in introducing what is in effect a new measurement basis. We have particular concerns that introducing measurement provisions into a presentation standard goes beyond the objective of IAS 32, set out in paragraph 2 of the standard. This risks confusion for users in circumstances where this basis differs from the measurement requirements of IFRS 9 Financial Instruments.
13We recommend retaining the existing reference to IFRS 9 Financial Instruments within paragraph 23 and removing the final two sentences of ED paragraph 23. However, if the IASB proceeds with specifying a measurement basis, it would be preferable to discount liabilities from the expected settlement date, a practice used by some UK entities. This provides more relevant information and is more consistent with existing IFRS 9 measurement principles for instruments for which there is uncertainty about the timing or amount of cash flows.
14Our detailed comments on obligations to redeem own equity are in paragraphs A15 to A25 of the appendix.
Contingent settlement provisions
15The introduction of initial and subsequent measurement requirements within IAS 32 in this area similarly appears to go beyond the scope of this project and could lead to unintended consequences.
16We understand that, in the absence of guidance, preparers and auditors currently use their judgement to reach pragmatic answers. We note that the measurement requirements proposed in ED paragraphs 25A are the same as those in relation to the obligations to redeem own equity in ED paragraph 23 and therefore recommend removing paragraph 25A. We refer you to our concerns and recommendations set out at paragraphs 11 to 13 above.
17We understand the IASB considers paragraphs 25 and 25A to apply only in scenarios where the classification of an instrument is determined by a contingent settlement provision. However, we believe the scope is not clear, and that the new measurement guidance in paragraph 25A can be read as applying not only to features of a compound instrument, but to any contingent settlement feature in debt instruments. This additional application to common features within debt instruments such as tax or law change clauses or loan covenants appears to be an unintended consequence.
18Regardless of the introduction of measurement requirements, we recommend that the IASB clarify the application of this section by inserting the word 'only' before 'in the event of the occurrence or non-occurrence of uncertain future events' in paragraph 25.
19Our detailed comments on contingent settlement provisions are in paragraphs A26 to A34 of the appendix.
Fixed-for-fixed
20We broadly welcome the IASB's proposals in this area. However, the wording of ED paragraph 22C(b)(iii) has caused some confusion as to whether a passage-of-time adjustment could only be derived from a fixed rate, and whether there was any requirement for the rate to be reasonable.
21ED illustrative example 20 appears to rule out the use of a benchmark rate of interest from meeting the definition of a passage-of-time adjustment, which would depart from current UK practice. We recommend that the IASB include specific acknowledgement in the Standard that financial instruments that are linked to determinable benchmark rates meet the fixed-for-fixed condition, as not doing so appears overly restrictive.
22Further, we consider that providing additional explanation of the meaning of 'proportional', together with further examples of successful and unsuccessful passage-of-time adjustments, should help alleviate confusion.
23Our detailed comments on settlement in an entity's own equity instruments are in paragraphs A10 to A14 of the appendix.
Disclosures
24We welcome aspects of these proposals. However, we have concerns about the overall volume and cost of the additional disclosures. We recommend the IASB consider undertaking field testing before finalising the disclosures.
25Stakeholders have indicated that ED IFRS 7 paragraph 30B may be difficult to apply in groups, where establishing the priority of instruments on liquidation may not be possible when the instruments are held in different legal entities. Further, as claims within one legal entity are not subordinated to those in any other, a consolidated disclosure could be misleading. We recommend that the IASB remove paragraphs 30A and 30B, as the broad disclosure objectives set out in IFRS 7 paragraph 1 may be met more effectively by the requirement to disclose the terms and conditions of compound financial instruments in paragraph 17A, and the terms and conditions of financial instruments with financial liability and equity characteristics in paragraphs 30C to 30E.
26Our detailed comments on disclosures are in paragraphs A51 to A58 of the appendix.
Transition
27We are generally supportive of the principle of full retrospective adoption, as we recognise this leads to greater comparability across different reporting periods.
28However, stakeholders have raised concerns about the particular complexities of retrospective adoption of the amendments in the context of the proposals relating to obligations to redeem own equity associated with previous business combinations.
29Further concerns have been raised by representatives of small- and medium-sized accounting firms, and private equity investors. These stakeholders tell us that, for such entities, complex financial instruments are relatively commonplace, and that full retrospective restatement could lead to significant additional costs of transition with no clear benefit.
30We therefore recommend that consideration be given to providing transitional relief from full retrospective application where this would require undue cost or effort, as permitted under IFRS 9 in relation to impairment. We further recommend that if financial instruments have been extinguished at the date of initial application, they should not be required to be restated.
31We also recommend that the IASB consider an across-the-board transition relief from restating comparatives, which would permit entities to assess classification at the date of initial application, similar to the proposals in the Classification and Measurement of Financial Instruments ED paragraph 7.2.48. We suggest this is done on the basis of the facts and circumstances at that date, including an assessment only of features that have not expired at that date.
32Our detailed comments on transition are in paragraphs A60 to A69 of the appendix.
Laws and regulations
33As drafted, it is currently not clear how these provisions would apply to Additional Tier 1 and Restricted Tier 1 capital instruments issued in the UK by banks and insurers respectively. We recommend providing further clarity on how these provisions apply in scenarios where regulations require the inclusion of a loss absorption feature, but the issuer has some discretion over the form of that feature.
34Our detailed comments on laws and regulations are in paragraphs A1 to A9 of the appendix.
35If you have any questions about this response, please contact the project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Questions on ED Financial Instruments with Characteristics of Equity – Proposed amendments to IAS 32, IFRS 7 and IAS I
Question 1–The effects of relevant laws or regulations (paragraphs 15A and AG24A–AG24B of IAS 32)
The IASB proposes to clarify that:
- only contractual rights and obligations that are enforceable by laws or regulations and are in addition to those created by relevant laws or regulations are considered in classifying a financial instrument or its component parts (paragraph 15A); and
- a contractual right or obligation that is not solely created by laws or regulations, but is in addition to a right or obligation created by relevant laws or regulations shall be considered in its entirety in classifying the financial instrument or its component parts (paragraph AG24B).
Paragraphs BC12–BC30 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not?
If you disagree with any of the proposals, please explain what you suggest instead and why.
A1We welcome the proposals as a pragmatic solution to questions that arise around the extent to which a legal requirement is part of the contractual terms.
A2Paragraph 15A(b) appears to duplicate paragraph 15A(a) without enhancing the clarity of the requirement. In particular, paragraph 15A(b) raises questions about accounting for scenarios in which the law or regulation provides a choice or does not specify how its requirements should be met. We recommend that the IASB clarify how paragraph 15A(b) differs from 15A(a) or considers removing it.
A3The IASB has set out two examples of how these proposals may affect financial instruments: accounting for a financial instrument in a jurisdiction with a legal minimum dividend and accounting for a financial instrument with a bail-in feature.
A4As the UK does not have a legal minimum dividend, this amendment may affect foreign subsidiaries of UK groups but is not expected to affect UK practice.
Additional Tier 1 (AT1) and Restricted Tier 1 (RT1) Instruments
A5Paragraph BC13 contains guidance on accounting for AT1 instruments. We recommend it be moved to the IAS 32 Application Guidance.
A6Stakeholders have noted that, as drafted, it is not clear how these provisions would apply to AT1 and RT1 instruments issued in the UK by banks and insurers respectively. While it is not anticipated that the proposals would be likely to lead to any change in classification for UK-issued instruments, it is unclear how the proposals would apply in situations in which a legal or regulatory requirement could be satisfied in several ways. For example, in order to qualify as regulatory capital, an AT1 instrument must have a loss absorption feature. However, this could take the form of a conversion feature or a write down feature, neither of which are specified in law, but which would be specified in the contract. Is it the IASB's intention that this scenario is taken into account in classification?
A7We recommend that the IASB also include an illustrative example based on paragraph BC13 in order to clarify how laws and regulations might apply to AT1 and RT1 instruments, and which could usefully address the following fact pattern:
“Consider an AT1 instrument issued by an entity to meet regulatory requirements. It is a perpetual instrument with obligations that arise only on liquidation of the issuer.
The regulations require the instrument to have a loss absorption feature which operates either through conversion to common shares at a trigger point of at least a set percentage of the entity's Common Equity Tier 1 capital, or through a write-down mechanism which comes into force at a trigger point of at least a set percentage of the entity's Common Equity Tier 1 capital.
The regulations therefore require a loss absorption feature but provide choices for how the requirement might be satisfied.”
A8In addition, stakeholders have observed that the explanations in the Basis for Conclusions supporting the changes in relation to financial instruments with bail-in features could be enhanced, to avoid the risk of confusion. The IASB refers to 'bail-in' provisions in AT1 instruments in paragraph BC13. The description appears to conflate loss absorption features, which may be required by regulation for an instrument to qualify as regulatory capital, with bail-in, which is a resolution tool available to the regulator under legislation, as observed in paragraph BC21(a).
A9If paragraph BC13(a) is intended to apply to instruments such as AT1 instruments, we recommend that it refer to 'loss absorption provisions', rather than ‘bail-in provisions’. We also recommend the language be softened to reflect the relevant regulatory requirements. For example: "In order to qualify as Additional Tier 1 regulatory capital, such instruments may be required by regulation to include a loss absorption feature...”.
Question 2—Settlement in an entity's own equity instruments (paragraphs 16, 22, 22B–22D, AG27A and AG29B of IAS 32)
The IASB proposes to clarify when the fixed-for-fixed condition in paragraph 16(b)(ii) of IAS 32 is met by specifying that the amount of consideration to be exchanged for each of an entity's own equity instruments is required to be denominated in the entity's functional currency, and either:
- fixed (will not vary under any circumstances); or
- variable solely because of:
- preservation adjustments that require the entity to preserve the relative economic interests of future shareholders to an equal or lesser extent than those of current shareholders; and/or
- passage-of-time adjustments that are predetermined, vary with the passage of time only, and have the effect of fixing on initial recognition the present value of the amount of consideration exchanged for each of the entity's own equity instruments (paragraphs 22B–22C).
The IASB also proposes to clarify that if a derivative gives one party a choice of settlement between two or more classes of an entity's own equity instruments, the entity considers whether the fixed-for-fixed condition is met for each class of its own equity instruments that may be delivered on settlement. Such a derivative is an equity instrument only if all the settlement alternatives meet the fixed-for-fixed condition (paragraph AG27A(b)).
The IASB further proposes to clarify that a contract that will or may be settled by the exchange of a fixed number of one class of an entity's own non-derivative equity instruments for a fixed number of another class of its own non-derivative equity instruments is an equity instrument (paragraph 22D).
Paragraphs BC31–BC61 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A10We welcome the proposed clarifications and consider that they will reduce diversity in practice.
Preservation adjustments
A11We consider the wording of the requirement at 22C(a)(ii) could be enhanced to provide greater clarity. Future equity holders have no current interest in the entity's own equity instruments, so it is not clear how their interest can be 'preserved'. We consider that it would be helpful to include an illustrative example of a successful preservation adjustment. We also recommend that the IASB confirm that rounding adjustments to prevent shares being issued in fractions do not breach the fixed-for-fixed condition.
Passage-of-time adjustments
A12The wording of ED paragraph 22C(b)(iii) has caused some confusion among stakeholders. Some understood the term "a present value” to mean that only adjustments set at variable rates could meet the definition of a passage-of-time adjustment; others thought that both fixed and variable rates could do so.
A13ED illustrative example 20 appears to rule out the use of a benchmark rate of interest from meeting the definition of a passage-of-time adjustment. This would depart from current UK practice, in which financial instruments linked to benchmark rates of interest are generally considered to meet the fixed-for-fixed condition. We recommend that the IASB include specific acknowledgement in the Standard that financial instruments that are linked to determinable benchmark rates meet the fixed-for-fixed condition, as not doing so appears overly restrictive.
A14Further, some understood “any difference in the amounts of consideration to be exchanged on each possible settlement date represents compensation proportional to the passage of time” to imply that compensation should be reasonable; others thought it simply meant that the return would vary as time passes, irrespective of reasonableness. We consider that providing additional explanation of the meaning of 'proportional', together with further examples of successful and unsuccessful passage-of-time adjustments, should help alleviate that confusion. In particular, a number of stakeholders indicated they would welcome examples of features that applied over a period of time, not just at maturity, with clear guidance on whether they would qualify as passage-of-time adjustments. We would be happy to share our ideas for explanation and potential examples, should you wish to pursue this recommendation.
Question 3—Obligations to purchase an entity's own equity instruments (paragraphs 23 and AG27B–AG27D of IAS 32)
The IASB proposes to clarify that:
- the requirements in IAS 32 for contracts containing an obligation for an entity to purchase its own equity instruments also apply to contracts that will be settled by delivering a variable number of another class of the entity's own equity instruments (paragraph 23).
- on initial recognition of the obligation to redeem an entity's own equity instruments, if the entity does not yet have access to the rights and returns associated with ownership of the equity instruments to which the obligation relates, those equity instruments would continue to be recognised. The initial amount of the financial liability would, therefore, be removed from a component of equity other than non-controlling interests or issued share capital (paragraph AG27B).
- an entity is required to use the same approach for initial and subsequent measurement of the financial liability—measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right (paragraph 23).
- any gains or losses on remeasurement of the financial liability are recognised in profit or loss (paragraph 23).
- if a contract containing an obligation for an entity to purchase its own equity instruments expires without delivery:
- the carrying amount of the financial liability would be removed from financial liabilities and included in the same component of equity as that from which it was removed on initial recognition of the financial liability.
- any gains or losses previously recognised from remeasuring the financial liability would not be reversed in profit or loss. However, the entity may transfer the cumulative amount of those gains or losses from retained earnings to another component of equity (paragraph AG27C).
- written put options and forward purchase contracts on an entity's own equity instruments that are gross physically settled—consideration is exchanged for own equity instruments—are required to be presented on a gross basis (paragraph AG27D).
Paragraphs BC62–BC93 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A15We agree with the IASB that the clarifications listed above at questions 3(a), 3(b), 3(d), 3(e) and 3(f) in this complex area should reduce diversity of practice.
A16However, we are concerned that the proposal at 3(c) introduces a new measurement basis, which goes beyond the objective of IAS 32, set out in paragraph 2 of the standard, and risks confusion for users. The proposal also goes beyond the proposed clarification of classification outcomes (ED paragraphs IN4 to IN6), and may have unintended consequences.
A17We consider that the addition in paragraph 23 of the ED of “The redemption amount is discounted, assuming redemption will occur at the earliest possible redemption date specified in the contract” could lead to a change in measurement basis that may potentially limit the relevance of information provided to users. Our comments in paragraphs A18 to A22 below apply equally to the proposed new measurement basis for contingent settlement provisions referred to in question 4(b) below.
A18Measuring the financial liability at the earliest possible date of redemption may not provide useful information, for example, if that resulted in the liability being measured at an amount at which a holder was extremely unlikely to redeem and which was below the most likely redemption amount. In particular, disregarding expectations of timing could potentially produce misleading outcomes. Consider the following scenarios:
- Put options containing a stepped level of payments depending on the timing of exercise e.g. exercisable for £1 in first 12 months, £1m thereafter.
- Put options with variable payments, depending on time of exercise, e.g. redemption at a multiple of EBITDA at different points in time.
A19The current proposal could not reasonably accommodate the variability that is a common feature of obligations to redeem own equity. For example, if an instrument can be redeemed for a multiple of EBITDA at several points in time, measuring it at the earliest possible payment date could lead to it being measured at a lower amount than the most likely outcome.
A20As ED IFRS 7 paragraph 30F requires assessment of whether terms and conditions have become, or have stopped being effective with the passage of time, reassessing the timing and probability of redemption at each period end would result in useful information without adding significantly to the operational burden.
A21We consider that there are significant challenges in introducing a new measurement basis into IFRS, and especially into a presentation standard. The current proposals would require significant additional application guidance to be clear and effective. It would also be necessary to introduce scope exclusions from the measurement provisions of IFRS 9 to those financial instruments for which IAS 32 now provides measurement requirements to minimise the risk of conflict between the two standards. We therefore recommend retaining the existing reference to IFRS 9 within paragraph 23 and removing the final two sentences of ED paragraph 23.
A22However, if the IASB proceeds with specifying a measurement basis, we consider that more useful information would be provided by discounting liabilities from the expected settlement date, a practice used by some UK entities that permits entities to provide relevant information that is informed by experience of these bespoke contracts. This provides more relevant information than the proposed measurement basis as it is more consistent with existing IFRS 9 measurement principles for instruments for which there is uncertainty about the timing or amount of cash flows.
Net settlement at the election of the issuer
A23We support the requirement for gross presentation of contractual obligations to purchase own equity as set out in the first sentence of paragraph AG27D. However, our interpretation of the second sentence is that derivative accounting would be required where the holder, but not the issuer, can elect for net settlement of the contract. As net settlement is not within the control of the issuer, it is not clear why gross presentation should not also be required in this example.
A24We recommend that paragraph AG27D require gross presentation unless the issuer has the discretion to settle the instrument net, in which case derivative accounting would apply.
Scope
A25Stakeholders observed that the difficult questions on the interaction between the scope of the guidance on this area within IAS 32, IFRS 2 Share-based Payments and IFRS 3 Business Combinations remain unaddressed by this ED. We would welcome future efforts by the IASB to clarify these interactions.
Question 4—Contingent settlement provisions (paragraphs 11, 25, 25A, 31, 32A, AG28 and AG37 of IAS 32)
The IASB proposes to clarify that:
- some financial instruments with contingent settlement provisions are compound financial instruments with liability and equity components (paragraphs 25 and 32A);
- the initial and subsequent measurement of the financial liability (or liability component of a compound financial instrument) arising from a contingent settlement provision would not take into account the probability and estimated timing of occurrence or non-occurrence of the contingent event (paragraph 25A);
- payments at the issuer's discretion are recognised in equity even if the equity component of a compound financial instrument has an initial carrying amount of zero (paragraphs 32A and AG37);
- the term 'liquidation' refers to the process that begins after an entity has permanently ceased its operations (paragraph 11); and
- the assessment of whether a contractual term is 'not genuine' in accordance with paragraph 25(a) of IAS 32 requires judgement based on the specific facts and circumstances and is not based solely on the probability or likelihood of the contingent event occurring (paragraph AG28).
Paragraphs BC94–BC115 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A26We support the IASB proposals in relation to questions 4(a), (c) and (e).
A27However, the introduction of initial and subsequent measurement requirements within IAS 32 in this area similarly appears to go beyond the scope of this project and could lead to unintended consequences.
A28We understand that, in the absence of guidance, preparers and auditors currently use their judgement to reach pragmatic answers.
A29We note that the measurement requirements proposed in ED paragraphs 25A are the same as those in relation to the obligations to redeem own equity in ED paragraph 23. Stakeholders have further observed that as the current proposal is rule-based, it may give rise to a number of application questions. For example, entities may be required to recognise a loss on day 1. For example, if an instrument is issued at £1 which would be redeemed at £1.02 if a contingent settlement provision applied, it should be recognised at £1.02. It is not currently clear how to account for the instrument on day 2.
A30The proposal may also create inconsistencies within IAS 32. IAS 32 paragraph 31 requires that "[...] The sum of the carrying amounts assigned to the liability and equity components on initial recognition is always equal to the fair value that would be ascribed to the instrument as a whole.” IAS 32 paragraph 32 refers to determining the carrying amount of the liability component “by measuring the fair value of a similar liability (including any embedded non-equity derivative features) that does not have an associated equity component”. Applying the current proposals together with these requirements could lead to inconsistent outcomes. The interaction of ED paragraph 25A with paragraph 31 could require a debit entry in equity in some circumstances. If this outcome is intended, it would be helpful for this to be addressed in the Application Guidance to IAS 32.
A31We therefore refer you to our concerns and recommendations set out at paragraphs A16 to A22 above and recommend removing paragraph 25A.
Scope
A32We understand the IASB considers paragraphs 25 and 25A to apply only in scenarios where the classification of an instrument is determined by a contingent settlement provision. However, a number of stakeholders have observed that the current scope of paragraph 25 remains ambiguous and the new measurement guidance in paragraph 25A could be read as applying not only to features of a compound instrument but to any contingent settlement feature in debt instruments. This additional application to common features within debt instruments such as tax or law change clauses, or loan covenants, appears to be an unintended consequence.
A33IAS 32 paragraph 25 has previously been used to determine classification only. It has not previously determined a measurement basis. This proposal may therefore increase uncertainty about which measurement basis to apply to debt instruments with contingent settlement provisions. Regardless of the introduction of measurement requirements, therefore, we recommend that the IASB clarify the application of this section by inserting the word 'only' before 'in the event of the occurrence or non-occurrence of uncertain future events' in paragraph 25.
A34Domestic laws and regulations establish conditions for insolvency which vary by jurisdiction. While we have not tested the ED definition of liquidation against current UK domestic law, we are concerned that the introduction of a definition of this term in accounting standards could potentially lead to conflict between accounting standards and relevant domestic laws. We recommend removing this definition.
Question 5—Shareholder discretion (paragraphs AG28A–AG28C of IAS 32)
The IASB proposes:
- to clarify that whether an entity has an unconditional right to avoid delivering cash or another financial asset (or otherwise to settle a financial instrument in such a way that it would be a financial liability) depends on the facts and circumstances in which shareholder discretion arises. Judgement is required to assess whether shareholder decisions are treated as entity decisions (paragraph AG28A).
- to describe the factors an entity is required to consider in making that assessment, namely whether:
- a shareholder decision would be routine in nature—made in the ordinary course of the entity's business activities;
- a shareholder decision relates to an action that would be proposed or a transaction that would be initiated by the entity's management;
- different classes of shareholders would benefit differently from a shareholder decision; and
- the exercise of a shareholder decision-making right would enable a shareholder to require the entity to redeem (or pay a return on) its shares in cash or another financial asset (or otherwise to settle it in such a way that it would be a financial liability) (paragraph AG28A(a)–(d)).
- to provide guidance on applying those factors (paragraph AG28B).
Paragraphs BC116–BC125 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A35We welcome the IASB's guidance on this complex area. Stakeholders considered that analysis under the proposals would remain an area of judgement. The proposals provide useful additional guardrails to help determine classification.
Question 6—Reclassification of financial liabilities and equity instruments (paragraphs 32B–32D and AG35A of IAS 32)
The IASB proposes:
- to add a general requirement that prohibits the reclassification of a financial instrument after initial recognition, unless paragraph 16E of IAS 32 applies or the substance of the contractual arrangement changes because of a change in circumstances external to the contractual arrangement (paragraphs 32B–32C).
- to specify that if the substance of the contractual arrangement changes because of a change in circumstances external to the contractual arrangement, an entity would:
- reclassify the instrument prospectively from the date when that change in circumstances occurred.
- measure a financial liability reclassified from equity at the fair value of that financial liability at the date of reclassification. Any difference between the carrying amount of the equity instrument and the fair value of the financial liability at the date of reclassification would be recognised in equity.
- measure an equity instrument reclassified from a financial liability at the carrying amount of the financial liability at the date of reclassification. No gain or loss would be recognised on reclassification (paragraph 32D).
- provide examples of changes in circumstances external to the contractual arrangement requiring reclassification (paragraph AG35A).
Paragraphs BC126–BC164 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposal to reclassify the instrument prospectively from the date when a change in circumstances occurred give rise to any practical difficulties? If so, please describe those practical difficulties and the circumstances in which they would arise.
A36We welcome the IASB's efforts to clarify this important area. However, we are concerned that the proposals in the current form could lead to: the classification of financial instruments diverging from their substance; inconsistencies between financial liabilities that result from obligations to redeem own equity and other financial liabilities; and an inappropriate change to established practice.
A37The lack of guidance on reclassification might imply that IAS 32 prohibits it except where expressly stated, as suggested by ED paragraphs BC136 to BC137. However, the 1995 version of IAS 32 did include such a prohibition at paragraph 19, but this was removed in 2003. We consider it likely that the IASB no longer wished to prohibit this treatment. This is possibly because it was not consistent with IAS 32 paragraph 18, which states that “The substance of a financial instrument, rather than its legal form, governs its classification [...]” and with the Framework for the Preparation and Presentation of Financial Statements paragraph 51, which contains a similar requirement. Indeed, IAS 32 paragraph 23 refers to recognising a financial liability on reclassification from equity, in the context of the purchase of own shares.
A38Stakeholders' requests for clarification indicate that IAS 32 was not widely understood as prohibiting reclassification, and this has led to the development of diverse practices. Over the years, accounting firms have developed extensive guidance on reclassification to assist entities in providing up-to-date, relevant classification information to users.
A39The prohibition of reclassification in respect of contractual terms that become, or stop being, effective with the passage of time could result in the provision of misleading information. This is because continuing recognition of a financial liability in such circumstances may no longer faithfully represent the substance of the financial instrument. Example circumstances include the expiry of a contingent settlement provision and a change in terms that results in the instrument meeting the criteria for equity classification:
- An entity issues preference shares that are redeemable in cash should a contingent event, such as a change of control, occur within a 12-month period. However, if no such event occurs, subsequent dividends are discretionary and redemption is not required until liquidation. Under the ED proposals, reclassification would be prohibited as the expiry of the cash redemption obligation is anticipated within the contract. After the 12-month period the preference shares would be equity in substance but under the proposals they would remain classified as a financial liability.
- An entity issues a bond with a conversion feature that is variable in the first three years, but which subsequently becomes fixed. The same analysis would apply. After three years, the bond would meet the criteria for classification as equity, as it would meet the fixed-for-fixed condition, but under the proposals it would remain classified as a financial liability.
A40Contrary to the statement in paragraph BC132, an instrument meeting the criteria for equity classification may subsequently meet the definition of a financial liability. For example, an entity might issue a perpetual instrument with discretionary coupons and an issuer call option exercisable after, say, 5 years. The instrument meets the definition of an equity instrument at issue. However, if the entity exercises the call option, and this cannot be cancelled, the entity has a contractual obligation to repay the instrument in, say, 3 months.
A41The IASB has drawn an analogy with the IFRS 9 requirements for classification of financial assets. However, those classification requirements are for measurement purposes. Financial liabilities are a separate element of the financial statements from equity. The reclassification proposals therefore relate to a more fundamental distinction within the financial statements (Conceptual Framework paragraph 4.1 (a)).
A42We therefore consider that the IASB proposals represent a potential change in classification outcomes for some instruments, which stakeholders are concerned may reduce the usefulness of the financial statements. ED paragraph BC143 states that “Reclassification would be prohibited if the substance of the contractual arrangement changes because of a contractual term that becomes, or stops, being effective during the instrument's life, and therefore the instrument would continue to be classified as a financial liability.” A liability could therefore continue to be recognised that no longer meets the definition of a liability provided within the Conceptual Framework.
A43Given the above concerns, we recommend that the IASB consider requiring reclassification of instruments where contractual terms become, or stop being, effective with the passage of time. This treatment would be consistent with the proposal in ED paragraph 23 to require contracts to redeem own equity that expire to be removed from financial liabilities and included in equity.
A44ED paragraph BC145 states that the requirement to assess whether an instrument should be reclassified at each reporting date would “increase costs and complexity for preparers”. However, the disclosure requirement at ED IFRS 7.30F requires assessment of whether terms and conditions have become, or have stopped being, effective with the passage of time. Furthermore, stakeholder feedback indicates that many entities are already undertaking such assessments. We therefore do not consider that reassessing instruments for the passage of time at the reporting date would add significant cost or effort.
Interaction with derecognition criteria
A45It is possible that many of these concerns would be addressed by enhancing the requirements on the interaction between reclassification and derecognition, the IASB's proposed commentary on which is currently located in the Basis for Conclusions for the ED. We consider that guidance on this important area should form part of the IAS 32 Application Guidance.
A46The example at A40 has clear parallels with the existing example in AG25 of IAS 32. However, we observe that while AG25 identifies that an obligation arises on exercise of an option, it is silent on the required accounting. We understand the IASB considers that in such circumstances the equity instrument would be derecognised, and a financial liability recognised. However, in the absence of clear instruction within IAS 32, or indeed any authoritative guidance on derecognition of equity instruments, we believe that the required accounting is at best unclear in such circumstances. Stakeholders have told us that their understanding is that the ED proposals on reclassification would prohibit their current practice of recognising a financial liability on exercise of the issuer call option.
A47In all three examples, the dual possibilities of an event taking place (change of control, conversion while variable, or issuer call) or not taking place (no change of control, conversion while fixed, no call) are both present within the contractual terms from day 1. Further, in an example such as the AT1 instrument after exercise of the call option, it is not clear why derecognition is the appropriate outcome when the underlying instrument remains in existence until the redemption of the instrument takes place. Relying on disclosures of whether such events have taken place or not appears a poor substitute for being able to rely on the classification of the instrument providing relevant information.
A48ED paragraph BC143 also appears at odds with our understanding of current derecognition practices. It indicates that if a contractual clause “becomes, or stops being, effective” as a result of the passage of time, the instrument would continue to be recognised as a liability. A number of stakeholders told us that in this situation, they would expect derecognition.
A49We consider that the IASB should either adopt the term 'expiring', to be consistent with IFRS 9 paragraph 3.3.1, or explain the distinction between 'expiring' and 'ceases to be effective'. If the IASB decides to retain the proposal to prohibit reclassification for contractual terms that become, or stop being, effective with the passage of time, we recommend that application guidance be included to indicate the circumstances in which a derecognition assessment of a liability component of a financial instrument would be applied.
A50Furthermore, ED paragraphs BC128 and BC129 refer to derecognition of a financial instrument rather than the components described in the definition of a compound instrument (IAS 32 paragraph 28). However, IFRS 9 B3.3.1 refers to "a financial liability (or part of it)" in the context of liability derecognition. We recommend adopting that wording.
Question 7—Disclosure (paragraphs 1, 3, 12E, 17A, 20, 30A–30J and B5A–B5L of IFRS 7)
The IASB proposes:
- to expand the objective of IFRS 7 to enable users of financial statements to understand how an entity is financed and what its ownership structure is, including potential dilution to the ownership structure from financial instruments issued at the reporting date (paragraph 1).
- to delete the reference to derivatives that meet the definition of an equity instrument in IAS 32 from paragraph 3(a) of IFRS 7.
- to move paragraphs 80A and 136A from IAS 1 to IFRS 7. These paragraphs set out requirements for disclosures relating to financial instruments classified as equity in accordance with paragraphs 16A–16B and/or paragraphs 16C–16D of IAS 32 (paragraphs 12E and 30I). The IASB also proposes to expand paragraph 80A to cover reclassifications if there are changes in the substance of the contractual arrangement from a change in circumstances external to the contractual arrangement.
- to amend paragraph 20(a)(i) of IFRS 7 to require an entity to disclose gains or losses on financial liabilities containing contractual obligations to pay amounts based on the entity's performance or changes in its net assets, separately from gains or losses on other financial liabilities in each reporting period.
- to include disclosure requirements for compound financial instruments in IFRS 7 (paragraph 17A).
The IASB proposes to require an entity to disclose information about:
- the nature and priority of claims against the entity on liquidation arising from financial liabilities and equity instruments (paragraphs 30A–30B);
- the terms and conditions of financial instruments with both financial liability and equity characteristics (paragraphs 30C–30E and B5B–B5H);
- terms and conditions that become, or stop being, effective with the passage of time (paragraph 30F);
- the potential dilution of ordinary shares (paragraphs 30G–30H and B5I–B5L); and
- instruments that include obligations to purchase the entity's own equity instruments (paragraph 30J).
Paragraphs BC170–BC245 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with the proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A51We welcome aspects of these proposals. However, we have concerns about the overall volume and cost of the additional disclosures, in addition to the specific issues explained below.
A52Under the Basel Pillar 3 regulations, many banks and building societies are already making disclosures in many of these areas. It would be helpful to align similar requirements as far as possible in order to minimise confusion for users. We recommend that the IASB consider undertaking further field testing before finalising the disclosures.
Priority on liquidation
A53Stakeholders have indicated that it may be impracticable for groups to establish the priority of instruments on liquidation, as ED IFRS 7 paragraph 30B(a)(ii) requires, as claims are made against individual legal entities. In addition, as claims within one legal entity are not subordinated to those in any other, consolidating such claims could be misleading. For example, although a parent company can call in its debt from a subsidiary, under these proposals, intra-group debt would not be disclosed unless an entity made the disclosure on a disaggregated basis.
A54For groups including entities based in different countries with different legal frameworks governing liquidation, this may prove even more challenging. Stakeholders have told us that that this information is not currently routinely collected at a group level, and that there could be significant costs associated with collecting and auditing the information required for these disclosures.
A55Stakeholders have also told us that information on the priority of instruments on liquidation may be of limited relevance in regulated financial sectors, in which regulatory resolution may be a more likely outcome than liquidation. Entities in those sectors would have to highlight that liquidation is one possible outcome among several.
A56Overall, this feedback suggests that a consolidated disclosure requirement may not provide useful information.
A57We recommend that the IASB remove paragraphs 30A and 30B, as we believe the disclosure objectives set out in paragraph 1 of IFRS 7 will be more effectively met by the requirement to disclose the terms and conditions of compound financial instruments in paragraph 17A, and the terms and conditions of financial instruments with financial liability and equity characteristics in paragraphs 30C to 30E.
A58Stakeholders also questioned whether entities would be able to disclose how significant uncertainty about laws or regulations could affect priority on liquidation (ED paragraph 30E(c)) without disclosing sensitive legal advice. We recommend removing this paragraph.
Question 8—Presentation of amounts attributable to ordinary shareholders (paragraphs 54, 81B and 107–108 of IAS 1)
The IASB proposes to amend IAS 1 to require an entity to provide additional information about amounts attributable to ordinary shareholders. The proposed amendments are that:
- the statement of financial position shows issued share capital and reserves attributable to ordinary shareholders of the parent separately from issued share capital and reserves attributable to other owners of the parent (paragraph 54);
- the statement of comprehensive income shows an allocation of profit or loss and other comprehensive income attributable to owners of the parent between ordinary shareholders and other owners of the parent (paragraph 81B);
- the components of equity reconciled in the statement of changes in equity include each class of ordinary share capital and each class of other contributed equity (paragraph 108); and
- dividend amounts relating to ordinary shareholders are presented separately from amounts relating to other owners of the entity (paragraph 107).
Paragraphs BC246–BC256 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposed requirement to allocate issued share capital and reserves between ordinary shareholders and other owners of the parent give rise to any practical difficulties in determining the required amounts? If so, please describe the possible difficulties and specify areas in which further guidance would be helpful.
A59We welcome the proposals in this area, as they increase the visibility of complex capital structures for users.
Question 9—Transition (paragraphs 97U–97Z of IAS 32)
The IASB proposes to require an entity to apply the proposed amendments retrospectively with the restatement of comparative information (a fully retrospective approach). However, to minimise costs, the IASB proposes not to require the restatement of information for more than one comparative period, even if the entity chooses or is required to present more than one comparative period in its financial statements.
For an entity already applying IFRS Accounting Standards, the IASB proposes:
- to require the entity to treat the fair value at the transition date as the amortised cost of the financial liability at that date if it is impracticable (as defined in IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors) for the entity to apply the effective interest method in IFRS 9 Financial Instruments retrospectively (paragraph 97X);
- not to require the entity to separate the liability and equity components if the liability component of a compound financial instrument with a contingent settlement provision was no longer outstanding at the date of initial application (paragraph 97W);
- to require the entity to disclose, in the reporting period that includes the date of initial application of the amendments, the nature and amount of any changes in classification resulting from initial application of the amendments (paragraph 97Z);
- to provide transition relief from the quantitative disclosures in paragraph 28(f) of IAS 8 (paragraph 97Y); and
- no specific transition requirements in relation to IAS 34 Interim Financial Reporting for interim financial statements issued within the annual period in which the entity first applies the amendments.
For first-time adopters, the IASB proposes to provide no additional transition requirements.
Paragraphs BC262–BC270 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposal to apply the proposed amendments retrospectively give rise to any other cases in which hindsight would be necessary? If so, please describe those cases and the circumstances in which the need for hindsight would arise.
A60We are generally supportive of the principle of full retrospective adoption, as we recognise this leads to greater comparability across different reporting periods.
A61However, it is important that sufficient lead time is available to entities to prepare for transition, especially if the proposal for full retrospective application is retained. While classification outcomes may not ultimately change in many cases, this will not be clear until entities have been able to assess fully the final amendments. Understanding, preparing for, and communicating the outcome of transition may be challenging and expensive for some entities. Field testing of disclosure requirements, as recommended at A52, may also help inform the IASB's decision on an effective date.
A62Stakeholders have raised concerns about the particular complexities of retrospective adoption of the proposals relating to obligations to redeem own equity associated with previous business combinations. Full retrospective application could require both remeasurement of those obligations and consequential remeasurement of acquisition-date goodwill arising. In regulated sectors, this could adversely affect regulatory capital ratios.
A63Concerns have furthermore been raised by representatives of small- and medium-sized accounting firms, and private equity investors, that costs may exceed the benefits. These stakeholders tell us that, for such entities, complex financial instruments are relatively commonplace and that full retrospective restatement could lead to significant additional costs with no clear benefit. Many entities would have to engage professional advisers to assist with application of the new requirements.
A64Private equity investors, for example, would have to review a significant volume of bespoke structures, typically a number of years old, at significant expense, as they may hold interests in entities via financial instruments with characteristics of equity. They expect that such costs would be required to be passed on to investors in their funds. They generally did not consider that there would be any significant benefit to them as users of the financial statements in these cases, as, generally, classification outcomes were not expected to change.
A65Change in classification as a result of retrospective application of the requirements may present particular challenges in relation to hedge accounting. For entities which have previously applied hedge accounting in respect of a liability which is required to be restated as equity, which cannot be hedged, early termination of hedge accounting may result in additional cost and work. Equally, if entities reclassify an equity instrument as a financial liability, hedge accounting could have been applied in the past and now may need to be applied in the future.
A66If instruments were required to be retrospectively reclassified from equity to a financial liability, it would be necessary to measure their fair value at inception, which could also prove onerous and difficult to perform without hindsight.
A67Owing to the possibility that the cost of transition may outweigh the benefits of implementing these proposals for some companies, we recommend that consideration be given to providing transitional relief from full retrospective application where this would require undue cost or effort, as permitted under IFRS 9 paragraph 7.2.18 in relation to impairment.
A68We recommend that if financial instruments have been extinguished at the date of initial application, they should not be required to be restated. This is especially important for financial instruments including obligations to redeem own equity and contingent settlement provisions measured on the proposed new basis.
A69We also recommend that the IASB consider an across-the-board transition relief from restating comparatives, which would permit entities to assess classification at the date of initial application, similar to the proposals in the Classification and Measurement of Financial Instruments ED paragraph 7.2.48. We suggest this is done on the basis of the facts and circumstances at that date, including an assessment only of features that have not expired at that date. These adopt a proportionate approach that we consider would also be appropriate for these amendments.
Question 10—Disclosure requirements for eligible subsidiaries (paragraphs 54, 61A–61E and 124 of [IFRS XX])
The IASB proposes amendments to the draft Accounting Standard [IFRS XX Subsidiaries without Public Accountability: Disclosures], which will be issued before the proposals in the Exposure Draft are finalised.
[IFRS XX] will permit eligible subsidiaries to apply the recognition, measurement and presentation requirements in IFRS Accounting Standards with reduced disclosures.
The IASB's proposals select appropriate disclosure requirements from those proposed for IFRS 7, based on the IASB's agreed principles for reducing disclosures.
Paragraphs BC257–BC261 explain the IASB's rationale for the selected disclosures.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why, taking into consideration the reduced disclosure principles described in BC258.
A70The application of the IFRS Accounting Standard Subsidiaries without Public Accountability: Disclosures (forthcoming standard) in the UK is conditional on the endorsement of the standard by the UKEB. The UKEB has not yet begun its endorsement assessment and the following comments should be viewed in that context.
A71We welcome the IASB's identification of consequential amendments to the forthcoming standard in this ED. We think this is an efficient approach that should ensure disclosure requirements for eligible subsidiaries keep pace with the development of IFRS Accounting Standards for the parent entity's consolidated financial statements.
A72We support the application of the IASB's agreed principles for reducing disclosures for the forthcoming standard to the full set of disclosures proposed in this ED. Consequently, we broadly agree with the proposed reduced disclosures for eligible subsidiaries. However, the concerns raised above on the full set of proposed disclosures apply equally to eligible subsidiaries, where applicable.
A73We are, however, concerned that the cost-benefit considerations of the proposed reduced disclosures for eligible subsidiaries are not clearly laid out in this ED. We draw your attention to our recommendation in paragraph A52 that the IASB consider undertaking field testing before finalising the disclosures. We recommend that the IASB reconsider the cost-benefit considerations of the proposed reduced disclosures for eligible subsidiaries arising from this ED in the light of such field testing.
Exposure Draft IASB/ED/2023/5 Financial Instruments with Characteristics of Equity: Proposed amendments to IAS 32, IFRS 7 and IAS 1
Dr Andreas Barckow Chairman International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
XX March 2024
Dear Dr Barckow
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.1 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.2 3We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB) Exposure Draft (ED) Financial Instruments with Characteristics of Equity: Proposed amendments to IAS 32, IFRS 7 and IAS 1 (the Amendments). In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts.
4We support the IASB's objectives in developing the Amendments, and we are broadly supportive of the proposals. We consider it important to provide clarity and minimise the risk of diversity in accounting practice in this complex area. Our main observations and recommendations are set out in the paragraphs that follow. Responses to the IASB's specific questions about the ED are included in the Appendix to this letter.
Reclassification
5We welcome the IASB's efforts to clarify this important area. However, we are concerned that the proposals in their current form could lead to: the classification of financial instruments diverging from their substance; inconsistencies arising between financial liabilities that result from obligations to redeem own equity and other financial liabilities; and an inappropriate change to established practice.
6The prohibition of reclassification in respect of contractual terms that become, or stop being, effective with the passage of time could result in misleading information. This is because the continuing recognition of a financial liability in such circumstances may no longer faithfully represent the substance of the financial instrument. Example circumstances include the expiry of a contingent settlement provision and a change in terms with the passage of time that results in the instrument meeting the criteria for equity classification.
7We recommend that the IASB consider requiring reclassification of instruments where contractual terms become, or stop being, effective with the passage of time. This would allow consistency with the current application of IAS 32 and avoid some of the potentially unintended outcomes highlighted by stakeholders. We do not consider that such a requirement would significantly increase costs or complexity for most preparers.
8However, if the IASB decides to proceed with the proposals in the ED, we recommend additionalenhancing the Application Guidance on the distinction between reclassification and derecognition, for example in relation to the exercise of an issuer call option in an equity instrument. We believe that in some of the examples raised with us, and in the example-circumstances set out in paragraph BC143, derecognition of a liability component may be the appropriate outcome, thus resolving the problem.
9Our detailed comments on reclassification are in paragraphs A32A36 to A44A50 of the appendix.
Obligations to redeem an entity's own equity instruments
10We agree with the IASB that clarifications in this complex area should reduce diversity of practice in a number of ways.
11However, we are concerned that the proposal at ED question 3(c) in effect introduces a new measurement basis, which goes beyond the proposed clarification and classification outcomes and may lead to unintended consequences. We consider that the proposal could lead to a change in measurement for some instruments and may reduce the relevance of information provided to users. In particular, the addition in paragraph 23 of the ED “The redemption amount is discounted, assuming redemption will occur at the earliest possible redemption date specified in the contract” could lead to a change in measurement of some relatively common instruments in the UK, such as NCI put options with redemption amounts linked to EBITDA.
12We consider that there are significant challenges in introducing what is in effect a new measurement basis. We have particular concerns that introducing measurement provisions into a presentation standard goes beyond the objective of IAS 32, set out in paragraph 2 of the standard. This risks confusion for users in circumstances where this basis differs from the measurement requirements of IFRS 9 Financial Instruments.
12.13We consider thatrecommend retaining the existing reference to IFRS 9 Financial Instruments within paragraph 23 and removing the final two sentences of ED paragraph 23. However, if the IASB proceeds with specifying a measurement basis, it would be preferable to discount liabilities from the expected settlement date, a current UK practice used by some UK entities. This provides more relevant information and is more consistent with existing IFRS 9 measurement principles for instruments for which there is uncertainty about the timing or amount of cash flows.
13.14Our detailed comments on obligations to redeem own equity are in paragraphs A15 to A23A25 of the appendix.
Contingent settlement provisions
14.15The introduction of initial and subsequent measurement requirements within IAS 32 in this area similarly appears to go beyond the scope of this project and could lead to unintended consequences.
15.16We understand that, in the absence of guidance, preparers and auditors currently use their judgement to reach pragmatic answers. We note that the measurement requirements proposed in ED paragraphs 25A are the same as those in relation to the obligations to redeem own equity in ED paragraph 23 and therefore recommend removing paragraph 25A. We therefore recommend removing paragraph 25A. We therefore refer you to our concerns and recommendations set out at paragraphs 11 to 132 above.
16.17In addition,We understand the introduction ofIASB considers paragraphs 25 and 25A to apply only in scenarios where the classification of an instrument is determined by a contingent settlement provision. However, we believe the scope is not clear, and that the new measurement guidance in paragraph 25A appears to apply can be read as applying not only to features of a compound instrument, but also to any contingent settlement feature in debt instruments. This additional application to common features within debt instruments such as tax or law change clauses or loan covenants appears to be an unintended consequence.
17In addition to our recommendation set out at paragraph 12 above, we therefore recommend that the scope of the measurement proposals in paragraph 25A should be restricted to the financial liability components of compound financial instruments only.
18Regardless of the introduction of measurement requirements, we recommend that the IASB clarify the application of this section by inserting the word 'only before 'in the event of the occurrence or non-occurrence of uncertain future events' in paragraph 25.
18.19Our detailed comments on contingent settlement provisions are in paragraphs A24A26 to A30A34 of the appendix.
Fixed-for-fixed
19.20We broadly welcome the IASB's proposals in this area. However, the wording of ED paragraph 22C(b)(iii) has caused some confusion as to whether a passage-of-time adjustment could only be derived from a fixed rate, and whether there was any requirement for the rate to be reasonable.
20We consider that providing additional explanation of the meaning of 'proportional', together with further examples of successful and unsuccessful passage-of-time adjustments, should help alleviate that confusion.
21In addition, weED illustrative example 20 appears to rule out the use of a benchmark rate of interest from meeting the definition of a passage-of-time adjustment, which would depart from current UK practice. We recommend that the IASB include specific acknowledgement in the Standard that financial instruments that are linked to determinable benchmark rates, such as interest or inflation meet the fixed-for-fixed condition, as not doing so appears overly restrictive.
22Further, we consider that providing additional explanation of the meaning of 'proportional', together with further examples of successful and unsuccessful passage-of-time adjustments, should help alleviate confusion.
22.23Our detailed comments on settlement in an entity's own equity instruments are in paragraphs A10 to A14 of the appendix.
Disclosures
23Overall, weWe welcome the aspects of these proposals. We consider that they will enhance the quality of disclosure for financial instruments with characteristics of equity.
24We note that EFRAG is carrying out extensive field testing on the operabilityHowever, we have concerns about the overall volume and costs and benefits of these disclosure requirements. In the light of the results of the EFRAG field testing, of the additional disclosures. We recommend the IASB may wish to consider undertaking further field testing before finalising the disclosures.
25Stakeholders have indicated that ED IFRS 7 paragraphs 30A andparagraph 30B may be difficult to apply in groups, where establishing the priority of instruments on liquidation may not be possible when the instruments are held in different legal entities. Further, as claims within one legal entity are not subordinated to those in any other, a consolidated disclosure could be misleading. We recommend that the IASB remove this requirementparagraphs 30A and 30B, as the broad disclosure objectiveobjectives set out in IFRS 7 paragraph 30A1 may be met more effectively by the requirement to disclose the terms and conditions of compound financial instruments in paragraph 17A, and the terms and conditions of financial instruments with financial liability and equity characteristics in paragraphs 30C to 30E.
26Our detailed comments on disclosures are in paragraphs A45A51 to A53A58 of the appendix.
Transition
27We are broadly generally supportive of the proposals principle ofs for full retrospective adoption, as we recognise this should leads to greater comparability of issued instrumentsacross different reporting periods.
28However, stakeholders have raised concerns about the particular complexities of retrospective adoption of the amendments in the context of the proposals relating to obligations to redeem own equity associated with previous business combinations.
28.29Further concerns have been raised by representatives of small- and medium-sized accounting firms, and private equity investors. These stakeholders tell us that, for such entities, complex financial instruments are relatively commonplace, and that full retrospective restatement could lead to significant additional costs of transition with no clear benefit.
29.30We therefore recommend that consideration should be given to providing transitional relief from full retrospective application where this would require undue cost or effort, as proposed permitted under IFRS 9 in relation to impairment.
We further recommend that if financial instruments have been extinguished at the date of initial application, they should not be required to be restated.
31We also recommend that the IASB consider an across-the-board transition relief from restating comparatives, which would permit entities to assess classification at the date of initial application, similar to the proposals in the Classification and Measurement of Financial Instruments ED paragraph 7.2.48. We suggest this is done on the basis of the facts and circumstances at that date, including an assessment only of features that have not expired at that date.
30.32Our detailed comments on transition are in paragraphs A55A60 to A62A69 of the appendix.
Laws and regulations
31.33As drafted, it is currently not clear how these provisions would apply to Additional Tier 1 and Restricted Tier 1 capital instruments issued in the UK by banks and insurers respectively. We recommend providing further clarity on how these provisions apply in scenarios where regulations require the inclusion of a loss absorption feature, but the issuer has some discretion over the form of that feature.
32.34Our detailed comments on laws and regulations are in paragraphs A1 to A9 of the appendix.
33.35If you have any questions about this response, please contact the project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Questions on ED Financial Instruments with Characteristics of Equity — Proposed amendments to IAS 32, IFRS 7 and IAS 1
Question 1—The effects of relevant laws or regulations (paragraphs 15A and AG24A–AG24B of IAS 32)
The IASB proposes to clarify that:
- only contractual rights and obligations that are enforceable by laws or regulations and are in addition to those created by relevant laws or regulations are considered in classifying a financial instrument or its component parts (paragraph 15A); and
- a contractual right or obligation that is not solely created by laws or regulations, but is in addition to a right or obligation created by relevant laws or regulations shall be considered in its entirety in classifying the financial instrument or its component parts (paragraph AG24B).
Paragraphs BC12–BC30 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not?
If you disagree with any of the proposals, please explain what you suggest instead and why.
A1We welcome the proposals as a pragmatic solution to questions that arise around the extent to which a legal requirement is part of the contractual terms.
A2Paragraph 15A(b) appears to duplicate paragraph 15A(a) without enhancing the clarity of the requirement. In particular, paragraph 15A(b) raisedraises questions about accounting for scenarios in which the law or regulation provides a choice or does not specify how its requirements should be met. We recommend that the IASB clarifiesy how paragraph 15A(abb) differs from 15A(baa) or considers removing it.
A3The IASB has set out two examples of how these proposals may affect financial instruments: accounting for a financial instrument in a jurisdiction with a legal minimum dividend and accounting for a financial instrument with a bail-in feature.
A4As the UK does not have a legal minimum dividend, this amendment may affect foreign subsidiaries of UK groups but is not expected to affect UK practice.
Additional Tier 1 (AT1) and Restricted Tier 1 (RT1) Instruments
A5Paragraph BC13 contains guidance on accounting for AT1 instruments. We recommend it should be moved to the IAS 32 Application Guidance.
A6Stakeholders have noted that, as drafted, it is not clear how these provisions would apply to AT1 and RT1 instruments issued in the UK by banks and insurers respectively. In particularWhile it is not anticipated that the proposals would be likely to lead to any change in classification for UK-issued instruments, it is unclear how the proposals would apply in situations in which a legal or regulatory requirement could be satisfied in several ways. For example, in order to qualify as regulatory capital, an AT1 instrument must have a loss absorption feature. However, this could take the form of a conversion feature or a write down feature, neither of which are specified in law, but which would be specified in the contract. Is it the IASB's intention that this scenario is taken into account in classification?
A7We recommend that the IASB also include an illustrative example based on paragraph BC13 in order to clarify how laws and regulations might apply to AT1 and RT1 instruments, and which could usefully address the following fact pattern:
“Consider an AT1 instrument issued by an entity to meet regulatory requirements. It is a perpetual instrument with obligations that arise only on liquidation of the issuer.
The regulations require the instrument to have a loss absorption feature which operates either through conversion to common shares at a trigger point of at least a set percentage of the entity's Common Equity Tier 1 capital, or through a write-down mechanism which comes into force at a trigger point of at least a set percentage of the entity's Common Equity Tier 1 capital.
The regulations therefore require a loss absorption feature but provide choices for how the requirement might be satisfied.”
A8In addition, stakeholders have observed that the explanations in the Basis for Conclusions supporting the changes in relation to financial instruments with bail-in features could be enhanced, to avoid the risk of confusion. The IASB refers to 'bail-in' provisions in AT1 instruments in paragraph BC13. The description appears to conflate loss absorption features, which may be required by regulation for an instrument to qualify as regulatory capital, with bail-in, which is a resolution tool available to the regulator under legislation, as observed in paragraph BC21(a).
A9If paragraph BC13(a) is intended to apply to instruments such as AT1 instruments, we recommend that it should refer to 'loss absorption provisions', rather than ‘bail-in provisions’. We also recommend the language be softened to reflect the relevant regulatory requirements. For example: “In order to qualify as Additional Tier 1 regulatory capital, such instruments may be required by regulation to include a loss absorption feature...".
Question 2—Settlement in an entity's own equity instruments (paragraphs 16, 22, 22B–22D, AG27A and AG29B of IAS 32)
The IASB proposes to clarify that:
- fixed (will not vary under any circumstances); or
- variable solely because of:
- preservation adjustments that require the entity to preserve the relative economic interests of future shareholders to an equal or lesser extent than those of current shareholders; and/or
- passage-of-time adjustments that are predetermined, vary with the passage of time only, and have the effect of fixing on initial recognition the present value of the amount of consideration exchanged for each of the entity's own equity instruments (paragraphs 22B–22C).
The IASB also proposes to clarify that if a derivative gives one party a choice of settlement between two or more classes of an entity's own equity instruments, the entity considers whether the fixed-for-fixed condition is met for each class of its own equity instruments that may be delivered on settlement. Such a derivative is an equity instrument only if all the settlement alternatives meet the fixed-for-fixed condition (paragraph AG27A(b)).
The IASB further proposes to clarify that a contract that will or may be settled by the exchange of a fixed number of one class of an entity's own non-derivative equity instruments for a fixed number of another class of its own non-derivative equity instruments is an equity instrument (paragraph 22D).
Paragraphs BC31–BC61 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A10We welcome the proposed clarifications and consider that they will reduce diversity in practice.
Preservation adjustments
A11We consider the wording of the requirement at 22C(a)(ii) could be enhanced to provide greater clarity. Future equity holders have no current interest in the entity's own equity instruments, so it is not clear how their interest can be 'preserved'. We consider that it would be helpful to include an illustrative example of a successful preservation adjustment. We also recommend that the IASB confirm that rounding adjustments to prevent shares being issued in fractions do not breach the fixed-for-fixed condition.
Passage-of-time adjustments
A12The wording of ED paragraph 22C(b)(iii) has caused some confusion among stakeholders. Some understood the term “a present value" to mean that only adjustments set at variable rates could meet the definition of a passage-of-time adjustment; others thought that both fixed and variable rates could do so.
A13ED illustrative example 20 appears to rule out the use of a benchmark rate of interest from meeting the definition of a passage-of-time adjustment. This would depart from current UK practice, in which financial instruments linked to benchmark rates of interest are generally considered to meet the fixed-for-fixed condition. We recommend that the IASB includes specific acknowledgement in the Standard that financial instruments that are linked to determinable benchmark rates, such as interest or inflation, meet the fixed-for-fixed condition, as not doing so appears overly restrictive.
A14Further, some understood “any difference in the amounts of consideration to be exchanged on each possible settlement date represents compensation proportional to the passage of time” to imply that compensation should be reasonable; others thought it simply meant that the return would vary as time passes, irrespective of reasonableness.
A15We consider that providing additional explanation of the meaning of 'proportional', together with further examples of successful and unsuccessful passage-of-time adjustments, should help alleviate that confusion. In particular, a number of stakeholders indicated they would welcome examples of features that applied over a period of time, not just at maturity, with clear guidance on whether they would qualify as passage-of-time adjustments. One common instrument highlighted was variable rate convertible debt with accrued interest. We would be happy to share our ideas for explanation and potential examples, should you wish to pursue this recommendation.
Question 3—Obligations to purchase an entity's own equity instruments (paragraphs 23 and AG27B–AG27D of IAS 32)
The IASB proposes to clarify that:
- the requirements in IAS 32 for contracts containing an obligation for an entity to purchase its own equity instruments also apply to contracts that will be settled by delivering a variable number of another class of the entity's own equity instruments (paragraph 23).
- on initial recognition of the obligation to redeem an entity's own equity instruments, if the entity does not yet have access to the rights and returns associated with ownership of the equity instruments to which the obligation relates, those equity instruments would continue to be recognised. The initial amount of the financial liability would, therefore, be removed from a component of equity other than non-controlling interests or issued share capital (paragraph AG27B).
- an entity is required to use the same approach for initial and subsequent measurement of the financial liability—measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right (paragraph 23).
- any gains or losses on remeasurement of the financial liability are recognised in profit or loss (paragraph 23).
- if a contract containing an obligation for an entity to purchase its own equity instruments expires without delivery:
- the carrying amount of the financial liability would be removed from financial liabilities and included in the same component of equity as that from which it was removed on initial recognition of the financial liability.
- any gains or losses previously recognised from remeasuring the financial liability would not be reversed in profit or loss. However, the entity may transfer the cumulative amount of those gains or losses from retained earnings to another component of equity (paragraph AG27C).
- written put options and forward purchase contracts on an entity's own equity instruments that are gross physically settled—consideration is exchanged for own equity instruments—are required to be presented on a gross basis (paragraph AG27D).
Paragraphs BC62–BC93 of the Basis for Conclusions explain the IASB's rationale for these proposals. Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A15We agree with the IASB that the clarifications listed above at questions 3(a), 3(b), 3(d), 3(e) and 3(f) in this complex area should reduce diversity of practice in a number of ways.
A16However, we are concerned that the proposal at 3(c) introduces a new measurement basis, which goes beyond the objective of IAS 32, set out in paragraph 2 of the standard, and risks confusion for users risks confusion for users. The proposal also goes beyond the proposed clarification of classification outcomes (ED paragraphs IN4 to IN6), and may have unintended consequences.
A17We consider that the addition in paragraph 23 of the ED of “The redemption amount is discounted, assuming redemption will occur at the earliest possible redemption date specified in the contract” contract could lead to a change in measurement basis that may potentially limit the relevance of information provided to users. Our comments in paragraphs A18 to A22 below apply equally to the proposed new measurement basis for contingent settlement provisions referred to in question 4(b) below.
A18Measuring the financial liability at the earliest possible date of redemption may not provide useful information, for example, if that resulted in the liability being measured at an amount at which a holder was extremely unlikely to redeem and which was below the most likely redemption amount. In particular, disregarding expectations of timing could potentially produce misleading outcomes. Consider the following scenarios:
- Put options containing a stepped level of payments depending on the timing of exercise e.g. exercisable for £1 in first 12 months, £1m thereafter.
- Put options with variable payments, depending on time of exercise, e.g. redemption at a multiple of EBITDA at different points in time.
A19The current proposal could not reasonably accommodate the variability that is a common feature of obligations to redeem own equity. For example, if an instrument can be redeemed for a multiple of EBITDA at several points in time, measuring it at the earliest possible payment date could lead to it being measured at a lower amount than the most likely outcome.
A20As ED IFRS 7 paragraph 30F requires assessment of whether terms and conditions have become, or have stopped being effective with the passage of time, reassessing the timing and probability of redemption at each period end would result in useful information without adding significantly to the operational burden.
A21We consider it would be preferable to discount liabilities from the expected settlement date, a current UK practiceWe consider that there are significant challenges in introducing a new measurement basis into IFRS, and especially into a presentation standard. The current proposals would require significant additional application guidance to be clear and effective. It would also be necessary to introduce scope exclusions from the measurement provisions of IFRS 9 to those financial instruments for which IAS 32 now provides measurement requirements to minimise the risk of conflict between the two standards. We therefore recommend retaining the existing reference to IFRS 9 within paragraph 23 and removing the final two sentences of ED paragraph 23.
A22However, if the IASB proceeds with specifying a measurement basis, we consider that more useful information would be provided by discounting liabilities from the expected settlement date, a practice used by some UK entities that permits entities to provide relevant information that is informed by experience of these bespoke contracts. This provides more relevant information than the proposed measurement basis as it is more consistent with existing IFRS 9 measurement principles for instruments for which there is uncertainty about the timing or amount of cash flows.
Net settlement at the election of the issuer
A23We support the requirement for gross presentation of contractual obligations to purchase own equity as set out in the first sentence of paragraph AG27D. However, our interpretation of the second sentence is that derivative accounting would be permitted required where the holder, but not the issuer, has the ability to can elect for net settlement of the contract. As net settlement is not within the control of the issuer, it is not clear why gross presentation should not also be required in this example.
A24We recommend that paragraph AG27D should require gross presentation unless the issuer has the discretion to settle the instrument net, in which case derivative accounting would apply.
Scope
A25Stakeholders observed that the difficult questions on the interaction between the scope of the guidance on this area within IAS 32, IFRS 2 Share-based Payments and, to a lesser extent, IFRS 3 Business Combinations remain unaddressed by this ED. We would welcome future efforts by the IASB to clarify these interactions.
Question 4—Contingent settlement provisions (paragraphs 11, 25, 25A, 31, 32A, AG28 and AG37 of IAS 32)
The IASB proposes to clarify that:
- some financial instruments with contingent settlement provisions are compound financial instruments with liability and equity components (paragraphs 25 and 32A);
- the initial and subsequent measurement of the financial liability (or liability component of a compound financial instrument) arising from a contingent settlement provision would not take into account the probability and estimated timing of occurrence or non-occurrence of the contingent event (paragraph 25A);
- payments at the issuer's discretion are recognised in equity even if the equity component of a compound financial instrument has an initial carrying amount of zero (paragraphs 32A and AG37);
- the term ‘liquidation’ refers to the process that begins after an entity has permanently ceased its operations (paragraph 11); and
- the assessment of whether a contractual term is ‘not genuine’ in accordance with paragraph 25(a) of IAS 32 requires judgement based on the specific facts and circumstances and is not based solely on the probability or likelihood of the contingent event occurring (paragraph AG28).
Paragraphs BC94–BC115 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A26We support the IASB proposals in relation to questions 4(a), (c), (d) and (e).
A27However, the introduction of initial and subsequent measurement requirements within IAS 32 in this area similarly appears to go beyond the scope of this project and could lead to unintended consequences.
A28We understand that, in the absence of guidance, preparers and auditors currently use their judgement to reach pragmatic answers.
A29We note that the measurement requirements proposed in ED paragraphs 25A are the same as those in relation to the obligations to redeem own equity in ED paragraph 23. Stakeholders have further observed that as the current proposal is rule-based, it may give rise to a number of application questions. For example, entities may be required to recognise a loss on day 1. For example, if an instrument is issued at £1, which may would be redeemed at £1.02 if a contingent settlement provision applies applied, it should be recognised at £1.02. It is not currently clear how to account for the same instrument on day 2.
A30The proposal may also create inconsistencies within IAS 32. IAS 32 paragraph 31 requires that “/[...] The sum of the carrying amounts assigned to the liability and equity components on initial recognition is always equal to the fair value that would be ascribed to the instrument as a whole.” IAS 32 paragraph 32 refers to determining the carrying amount of the liability component “by measuring the fair value of a similar liability (including any embedded non-equity derivative features) that does not have an associated equity component”. Applying the current proposals together with these requirements could lead to inconsistent outcomes. The interaction of ED paragraph 25A with paragraph 31 could require a debit entry in equity in some circumstances. If this outcome is intended, it would be helpful for this to be addressed in the Application Guidance to IAS 32.
A31We therefore refer you to our concerns and recommendations set out at paragraphs A16 to A22 A20 above and recommend removing paragraph 25A.
In addition, Scope
A32We understand the introduction ofIASB considers paragraphs 25 and 25A to apply only in scenarios where the classification of an instrument is determined by a contingent settlement provision. However, a number of stakeholders have observed that the current scope of paragraph 25 remains ambiguous and the new measurement guidance in paragraph 25A appears to apply could be read as applying not only to features of a compound component instrument but to any contingent settlement feature in debt instruments. This additional application to common features within debt instruments such as tax or law change clauses, or loan covenants, appears to be an unintended consequence.
A30Further to our recommendation set out at A20, we therefore recommend restricting the scope of these requirements to the financial liability components of compound financial instruments only, for example through relocating paragraph 25A to paragraph 29A, within the part of the standard that deals with compound instruments.
A33IAS 32 paragraph 25 has previously been used to determine classification only. It has not previously determined a measurement basis. This proposal may therefore increase uncertainty about which measurement basis to apply to debt instruments with contingent settlement provisions. Regardless of the introduction of measurement requirements, therefore, we recommend that the IASB clarify the application of this section by inserting the word 'only' before 'in the event of the occurrence or non-occurrence of uncertain future events' in paragraph 25.
A34Domestic laws and regulations establish conditions for insolvency which vary by jurisdiction. While we have not tested the ED definition of liquidation against current UK domestic law, we are concerned that the introduction of a definition of this term in accounting standards could potentially lead to conflict between accounting standards and relevant domestic laws. We recommend removing this definition.
Question 5—Shareholder discretion (paragraphs AG28A–AG28C of IAS 32)
The IASB proposes:
- to clarify that whether an entity has an unconditional right to avoid delivering cash or another financial asset (or otherwise to settle a financial instrument in such a way that it would be a financial liability) depends on the facts and circumstances in which shareholder discretion arises. Judgement is required to assess whether shareholder decisions are treated as entity decisions (paragraph AG28A).
- to describe the factors an entity is required to consider in making that assessment, namely whether:
- a shareholder decision would be routine in nature—made in the ordinary course of the entity's business activities;
- a shareholder decision relates to an action that would be proposed or a transaction that would be initiated by the entity's management;
- different classes of shareholders would benefit differently from a shareholder decision; and
- the exercise of a shareholder decision-making right would enable a shareholder to require the entity to redeem (or pay a return on) its shares in cash or another financial asset (or otherwise to settle it in such a way that it would be a financial liability) (paragraph AG28A(a)–(d)).
- to provide guidance on applying those factors (paragraph AG28B).
Paragraphs BC116–BC125 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A35We welcome the IASB's guidance on this complex area. Stakeholders considered that analysis under the proposals would remain an area of judgement. The proposals provide useful additional guardrails to help determine classification.
Question 6—Reclassification of financial liabilities and equity instruments (paragraphs 32B–32D and AG35A of IAS 32)
The IASB proposes:
- to add a general requirement that prohibits the reclassification of a financial instrument after initial recognition, unless paragraph 16E of IAS 32 applies or the substance of the contractual arrangement changes because of a change in circumstances external to the contractual arrangement (paragraphs 32B–32C).
- to specify that if the substance of the contractual arrangement changes because of a change in circumstances external to the contractual arrangement, an entity would:
- reclassify the instrument prospectively from the date when that change in circumstances occurred.
- measure a financial liability reclassified from equity at the fair value of that financial liability at the date of reclassification. Any difference between the carrying amount of the equity instrument and the fair value of the financial liability at the date of reclassification would be recognised in equity.
- measure an equity instrument reclassified from a financial liability at the carrying amount of the financial liability at the date of reclassification. No gain or loss would be recognised on reclassification (paragraph 32D).
- provide examples of changes in circumstances external to the contractual arrangement requiring reclassification (paragraph AG35A).
Paragraphs BC126–BC164 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposal to reclassify the instrument prospectively from the date when a change in circumstances occurred give rise to any practical difficulties? If so, please describe those practical difficulties and the circumstances in which they would arise.
A36We welcome the IASB's efforts to clarify this important area. However, we are concerned that the proposals in the current form could lead to: the classification of financial instruments diverging from their substance; inconsistencies arising between financial liabilities that result from obligations to redeem own equity and other financial liabilities; and an inappropriate change to established practice.
A37The lack of guidance on reclassification might imply that IAS 32 prohibits it except where expressly stated, as suggested by ED paragraphs BC136 to BC137. However, the 1995 version of IAS 32 did include such a prohibition at paragraph 19, but this was removed in 2003. We consider it likely that the IASB no longer wished to prohibit this treatment. This is possibly because it was not consistent with IAS 32 paragraph 18, which states that “The substance of a financial instrument, rather than its legal form, governs its classification [...]” and with the Framework for the Preparation and Presentation of Financial Statements paragraph 51, which contains a similar requirement. Indeed, IAS 32 paragraph 23 refers to recognising a financial liability on reclassification from equity, in the context of the purchase of own shares.
A38Stakeholders' requests for clarification indicate that IAS 32 was not widely understood as prohibiting reclassification, and this has led to the development of diverse practices. Over the years, accounting firms have developed extensive guidance on reclassification to assist entities in providing up-to-date, relevant classification information to users.
A39The prohibition of reclassification in respect of contractual terms that become, or stop being, effective with the passage of time could result in the provision of misleading information. This is because continuing recognition of a financial liability in such circumstances may no longer faithfully represent the substance of the financial instrument. Example circumstances include the expiry of a contingent settlement provision and a change in terms that results in the instrument meeting the criteria for equity classification:
- An entity issues preference shares that are redeemable in cash, should a contingent event, such as a change of control, occur within a 12-month period. However, if no such event occurs, subsequent dividends are discretionary and redemption is not required until liquidation. Under the ED proposals, reclassification would be prohibited as the expiry of the cash redemption obligation is anticipated within the contract. After the 12-month period the preference shares would be equity in substance but under the proposals they would remain classified as a financial liability.
- An entity issues a bond with a conversion feature that is variable in the first three years, but which subsequently becomes fixed. The same analysis would apply. After three years, the bond would meet the criteria for classification as equity, as it would meet the fixed-for-fixed condition, but under the proposals it would remain classified as a financial liability.
A40Contrary to the statement in paragraph BC132, an instrument meeting the criteria for equity classification may subsequently meet the definition of a financial liability. For example, an entity might issue a perpetual instrument with discretionary coupons and an issuer call option exercisable after, say, 5 years. The instrument meets the definition of an equity instrument at issue. However, if the entity exercises the call option, and this cannot be cancelled, the entity has a contractual obligation to repay the instrument in, say, 3 months.
A41The IASB has drawn an analogy with the IFRS 9 requirements for classification of financial assets. However, those classification requirements are for measurement purposes. Financial liabilities are a separate element of the financial statements from equity. The reclassification proposals therefore relate to a more fundamental distinction within the financial statements (Conceptual Framework paragraph 4.1 (a)).
A42We therefore consider that the IASB proposals represent a potential change in classification outcomes for some instruments, which stakeholders are concerned may reduce the usefulness of the financial statements. ED paragraph BC143 states that “Reclassification would be prohibited if the substance of the contractual arrangement changes because of a contractual term that becomes, or stops, being effective during the instrument's life, and therefore the instrument would continue to be classified as a financial liability.” A liability could therefore continue to be recognised that no longer meets the definition of a liability provided within the Conceptual Framework.
A43Given the above concerns, we recommend that the IASB consider requiring reclassification of instruments where contractual terms become, or stop being, effective with the passage of time. This treatment would be consistent with the proposal in ED paragraph 23 to require contracts to redeem own equity that expire to be removed from financial liabilities and included in equity.
A44ED paragraph BC145 states that the requirement to assess whether an instrument should be reclassified at each reporting date would “increase costs and complexity for preparers”. However, the disclosure requirement at ED IFRS 7.30F requires assessment of whether terms and conditions have become, or have stopped being, effective with the passage of time. Furthermore, stakeholder feedback indicates that many entities are already undertaking such assessments. We therefore do not consider that reassessing instruments for the passage of time at the reporting date would add significant cost or effort.
Interaction with derecognition criteria
A45It is possible that many of these concerns would be addressed by enhancing the requirements on the interaction between reclassification and derecognition, the IASB's proposed commentary on which are is currently located in the Basis for Conclusions for the ED. We consider that guidance on this important area guidance should form part of the IAS 32 Application Guidance.
A46The example at A40 has clear parallels with the existing example in AG25 of IAS -32. However, we observe that while AG25 identifies that an obligation arises on exercise of an option, it is silent on the required accounting. We understand the IASB considers that in such circumstances the equity instrument would be derecognised, and a financial liability recognised. However, in the absence of clear instruction within IAS 32, or indeed any authoritative guidance on derecognition of equity instruments, we believe that the required accounting is at best unclear in such circumstances. Stakeholders have told us that their understanding is that the ED proposals on reclassification would prohibit their current practice of recognising a financial liability on exercise of the issuer call option.
A47In all three examples, the dual possibilities of an event taking place (change of control, conversion while variable, or issuer call) or not taking place (no change of control, conversion while fixed, no call) are both present within the contractual terms from day 1. Further, in an example such as the AT1 instrument after exercise of the call option, it is not clear why derecognition is the appropriate outcome when the underlying instrument remains in existence until the redemption of the instrument takes place. Relying on disclosures of whether such events have taken place or not appears a poor substitute for being able to rely on the classification of the instrument providing relevant information.
A48ED paragraph BC143 also appears at odds with our understanding of current derecognition practices, in that it. It indicates that if a contractual clause “becomes, or stops being, effective” as a result of the passage of time, the instrument would continue to be recognised as a liability. A number of stakeholders told us that in this situation, they would expect derecognition.
A49We consider that the IASB should either adopt the term 'expiring', to be consistent with IFRS 9 paragraph 3.3.1, or explain the distinction between 'expiring' and 'ceases to be effective'. If the IASB decides to retain the proposal to prohibit reclassification for contractual terms that become, or stop being, effective with the passage of time, we recommend that application guidance be included to indicate the circumstances in which a derecognition assessment of a liability component of a financial instrument would be applied.
A50In additionFurthermore, ED paragraphs BC128 and BC129 refer to derecognition of a financial instrument rather than the components described in the definition of a compound instrument (IAS 32 paragraph 28). However, IFRS 9 B3.3.1 refers to “a financial liability (or part of it)" in the context of liability derecognition. We recommend adopting that wording.
Question 7—Disclosure (paragraphs 1, 3, 12E, 17A, 20, 30A–30J and B5A–B5L of IFRS 7)
The IASB proposes:
- to expand the objective of IFRS 7 to enable users of financial statements to understand how an entity is financed and what its ownership structure is, including potential dilution to the ownership structure from financial instruments issued at the reporting date (paragraph 1).
- to delete the reference to derivatives that meet the definition of an equity instrument in IAS 32 from paragraph 3(a) of IFRS 7.
- to move paragraphs 80A and 136A from IAS 1 to IFRS 7. These paragraphs set out requirements for disclosures relating to financial instruments classified as equity in accordance with paragraphs 16A–16B and/or paragraphs 16C–16D of IAS 32 (paragraphs 12E and 30I). The IASB also proposes to expand paragraph 80A to cover reclassifications if there are changes in the substance of the contractual arrangement from a change in circumstances external to the contractual arrangement.
- to amend paragraph 20(a)(i) of IFRS 7 to require an entity to disclose gains or losses on financial liabilities containing contractual obligations to pay amounts based on the entity's performance or changes in its net assets, separately from gains or losses on other financial liabilities in each reporting period.
- to include disclosure requirements for compound financial instruments in IFRS 7 (paragraph 17A).
The IASB proposes to require an entity to disclose information about:
- the nature and priority of claims against the entity on liquidation arising from financial liabilities and equity instruments (paragraphs 30A–30B);
- the terms and conditions of financial instruments with both financial liability and equity characteristics (paragraphs 30C–30E and B5B–B5H);
- terms and conditions that become, or stop being, effective with the passage of time (paragraph 30F);
- the potential dilution of ordinary shares (paragraphs 30G–30H and B5I–B5L); and
- instruments that include obligations to purchase the entity's own equity instruments (paragraph 30J).
Paragraphs BC170–BC245 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with the proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
A51Overall, we welcome the proposals. We consider they will enhance the quality of disclosure on financial instruments with characteristics of equity.
A52We welcome aspects of these proposals. However, we have concerns about the overall volume and cost of the additional disclosures, in addition to the specific issues explained below.
A53Under the Basel Pillar 3 regulations, many banks and building societies are already making disclosures in many of these areas. It would be helpful to align similar requirements as far as possible in order to minimise confusion for users.
A54We note that EFRAG is carrying out extensive field testing on the operability and costs and benefits of these disclosure requirements. In the light of the results of the EFRAG field testing, the IASB may wish to consider We recommend that the IASB consider undertaking further field testing before finalising the disclosures.
Priority on liquidation
A55Stakeholders have indicated that it may be impracticable for groups to establish the priority of instruments on liquidation, as ED IFRS 7 paragraph 30B(a)(ii) requires, as claims are made against individual legal entities. In addition, as claims within one legal entity are not subordinated to those in any other, consolidating such claims could be misleading. For example, although a parent company can call in its debt from a subsidiary, under these proposals, intra-group debt would not be disclosed unless an entity made the disclosure on a disaggregated basis.
A56For groups including entities based in different countries with different legal frameworks governing liquidation, this may prove even more challenging. Stakeholders have told us that that this information is not currently routinely collected at a group level, and that there could be significant costs associated with collecting and auditing the information required for these disclosures.
A57Stakeholders have also told us that information on the priority of instruments on liquidation may be of limited relevance in regulated financial sectors, in which regulatory resolution may be a more likely outcome than liquidation. Entities in those sectors would have to highlight that liquidation is one possible outcome among several.
A58Overall, this feedback suggests that a consolidated disclosure requirement may not provide useful information.
A59We recommend that the IASB remove paragraphs 30A and 30B, as we believe the disclosure objectives set out in paragraph 30A of IFRS 7 will be more effectively met by the requirement to disclose the terms and conditions of compound financial instruments in paragraph 17A, and the terms and conditions of financial instruments with financial liability and equity characteristics in paragraphs 30C to 30E.
A60Stakeholders also questioned whether entities would be able to disclose how significant uncertainty about laws or regulations could affect priority on liquidation (ED paragraph 30E(c)) without disclosing sensitive legal advice. We recommend removing this paragraph.
Question 8—Presentation of amounts attributable to ordinary shareholders (paragraphs 54, 81B and 107–108 of IAS 1)
The IASB proposes to amend IAS 1 to require an entity to provide additional information about amounts attributable to ordinary shareholders. The proposed amendments are that:
- the statement of financial position shows issued share capital and reserves attributable to ordinary shareholders of the parent separately from issued share capital and reserves attributable to other owners of the parent (paragraph 54);
- the statement of comprehensive income shows an allocation of profit or loss and other comprehensive income attributable to owners of the parent between ordinary shareholders and other owners of the parent (paragraph 81B);
- the components of equity reconciled in the statement of changes in equity include each class of ordinary share capital and each class of other contributed equity (paragraph 108); and
- dividend amounts relating to ordinary shareholders are presented separately from amounts relating to other owners of the entity (paragraph 107).
Paragraphs BC246–BC256 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposed requirement to allocate issued share capital and reserves between ordinary shareholders and other owners of the parent give rise to any practical difficulties? If so, please describe those practical difficulties and specify areas in which further guidance would be helpful.
A61We welcome the proposals in this area, as they increase the visibility of complex capital structures for users.
Question 9—Transition (paragraphs 97U–97Z of IAS 32)
The IASB proposes to require an entity to apply the proposed amendments retrospectively with the restatement of comparative information (a fully retrospective approach). However, to minimise costs, the IASB proposes not to require the restatement of information for more than one comparative period, even if the entity chooses or is required to present more than one comparative period in its financial statements.
For an entity already applying IFRS Accounting Standards, the IASB proposes:
- to require the entity to treat the fair value at the transition date as the amortised cost of the financial liability at that date if it is impracticable (as defined in IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors) for the entity to apply the effective interest method in IFRS 9 Financial Instruments retrospectively (paragraph 97X);
- not to require the entity to separate the liability and equity components if the liability component of a compound financial instrument with a contingent settlement provision was no longer outstanding at the date of initial application (paragraph 97W);
- to require the entity to disclose, in the reporting period that includes the date of initial application of the amendments, the nature and amount of any changes in classification resulting from initial application of the amendments (paragraph 97Z);
- to provide transition relief from the quantitative disclosures in paragraph 28(f) of IAS 8 (paragraph 97Y); and
- no specific transition requirements in relation to IAS 34 Interim Financial Reporting for interim financial statements issued within the annual period in which the entity first applies the amendments.
For first-time adopters, the IASB proposes to provide no additional transition requirements.
Paragraphs BC262–BC270 of the Basis for Conclusions explain the IASB's rationale for these proposals.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why.
Would the proposal to apply the proposed amendments retrospectively give rise to any other cases in which hindsight would be necessary? If so, please describe those cases and the circumstances in which the need for hindsight would arise.
A62We are generally supportive of the proposals of full retrospective adoption, as we recognise this leads to greater comparability of issued instruments across different reporting periods.
A63However, it is important that sufficient lead time is available to entities to prepare for transition, especially if the proposal for full retrospective application is retained. While classification outcomes may not ultimately change in many cases, this will not be clear until entities have been able to assess fully the final amendments. Understanding, preparing for, and communicating the outcome of transition may be challenging and expensive for some entities. Field testing of disclosure requirements, as recommended at A52, may also help inform the IASB's decision on an effective date.
A64Stakeholders have raised concerns about the particular complexities of retrospective adoption of the proposals relating to obligations to redeem own equity associated with previous business combinations. Full retrospective application could require both remeasurement of those obligations and consequential remeasurement of acquisition-date goodwill arising. In regulated sectors, this could adversely affect regulatory capital ratios.
A65Concerns have furthermore been raised by representatives of small- and medium-sized accounting firms, and private equity investors, that costs may exceed the benefits. These stakeholders tell us that, for such entities, complex financial instruments are relatively commonplace, and that full retrospective restatement could lead to significant additional costs with no clear benefit. Many entities would have to engage professional advisers to assist with application of the new requirements.
A66Private equity investors, for example, would have to review a significant volume of bespoke structures, typically a number of years old, at significant expense., as they may hold interests in entities via financial instruments with characteristics of equity. They expect that such costs would be required to be passed on to investors in their funds. They generally did not consider that there would be any significant benefit to them as users of the financial statements in these cases, as, generally, classification outcomes were not expected to change.
A67Change in classification as a result of retrospective application of the requirements may present particular challenges in relation to hedge accounting. For entities which have previously applied hedge accounting in respect of a liability which is required to be restated as equity, which cannot be hedged, early termination of hedge accounting may result in additional cost and work. Equally, if entities reclassify an equity instrument as a financial liability, hedge accounting could have been applied in the past and now may need to be applied in the future. Sufficient lead time will be required to enable entities to prepare for transition. A68If instruments were required to be retrospectively reclassified from equity to a financial liability, it would be necessary to measure their fair value at inception, which could also prove onerous and difficult to perform without hindsight.
A69Owing to the possibility that the cost of transition may outweigh the benefits of implementing these proposals for some companies, we recommend that consideration should be given to providing transitional relief from full retrospective application where this would require undue cost or effort, as permitted under IFRS 9 paragraph 7.2.18 in relation to impairment.
A70We recommend that if financial instruments have been extinguished at the date of initial application, they should not be required to be restated. This is especially important for financial instruments including obligations to redeem own equity and contingent settlement provisions measured on the proposed new basis.
A71We also recommend that the IASB consider an across-the-board transition relief from restating comparatives, which would permit entities to assess classification at the date of initial application, similar to the proposals in the Classification and Measurement of Financial Instruments ED paragraph 7.2.48. We suggest this is done on the basis of the facts and circumstances at that date, including an assessment only of features that have not expired at that date. These adopt a proportionate approach that we consider would also be appropriate for these amendments.
Question 10—Disclosure requirements for eligible subsidiaries (paragraphs 54, 61A–61E and 124 of [IFRS XX])
The IASB proposes amendments to the draft Accounting Standard [IFRS XX Subsidiaries without Public Accountability: Disclosures], which will be issued before the proposals in the Exposure Draft are finalised.
[IFRS XX] will permit eligible subsidiaries to apply the recognition, measurement and presentation requirements in IFRS Accounting Standards with reduced disclosures.
The IASB's proposals select appropriate disclosure requirements from those proposed for IFRS 7, based on the IASB's agreed principles for reducing disclosures.
Paragraphs BC257–BC261 explain the IASB's rationale for the selected disclosures.
Do you agree with these proposals? Why or why not? If you disagree with any of the proposals, please explain what you suggest instead and why, taking into consideration the reduced disclosure principles described in BC258.
A72The application of the IFRS Accounting Standard Subsidiaries without Public Accountability: Disclosures (forthcoming standard) in the UK is conditional on the endorsement of the standard by the UKEB. The UKEB has not yet begun its endorsement assessment and the following comments should be viewed in that context.
A73We welcome the IASB's identification of consequential amendments to the forthcoming standard in this ED. We think this is an efficient approach that should ensure disclosure requirements for eligible subsidiaries keep pace with the development of IFRS Accounting Standards for the parent entity's consolidated financial statements.
A74We support the application of the IASB's agreed principles for reducing disclosures for the forthcoming standard to the full set of disclosures proposed in this ED. Consequently, we broadly agree with the proposed reduced disclosures for eligible subsidiaries. However, the concerns raised above on the full set of proposed disclosures apply equally to eligible subsidiaries, where applicable.
A75We are, however, concerned that the cost-benefit considerations of the proposed reduced disclosures for eligible subsidiaries are not clearly laid out in this ED. We draw your attention to our recommendation in paragraph A47A52 that in the light of the results of the EFRAG field testing on the full disclosure requirements, the IASB may wish to consider undertaking further field testing before finalising the disclosures. We recommend that the IASB reconsider the cost-benefit considerations of the proposed reduced disclosures for eligible subsidiaries arising from this ED in the light of such field testing.
Financial Instruments with Characteristics of Equity: Amendments to IAS 32, IFRS 7 and IAS I
Final Comment Letter (FCL) 28 March 2024
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The comment letter to which this feedback statement relates forms part of those influencing activities and is intended to contribute to the IFRS Foundation's due process.
The views expressed by the UKEB in its comment letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
- Executive Summary
- Appendices
- Background
- Feedback Statement
- Due Process Compliance Statement (DPCS)
- Next steps
- Timeline
- Appendix A: Feedback received during the consultation period
- Appendix B: Final Comment Letter – clean copy
- Reclassification
- Obligations to redeem an entity's own equity instruments
- Contingent settlement provisions
- Fixed-for-fixed
- Disclosures
- Transition
- Laws and regulations
- Appendix A: Questions on ED Financial Instruments with Characteristics of Equity – Proposed amendments to IAS 32, IFRS 7 and IAS I
- Additional Tier 1 (AT1) and Restricted Tier 1 (RT1) Instruments
- Question 2—Settlement in an entity's own equity instruments (paragraphs 16, 22, 22B–22D, AG27A and AG29B of IAS 32)
- Question 3—Obligations to purchase an entity's own equity instruments (paragraphs 23 and AG27B–AG27D of IAS 32)
- Net settlement at the election of the issuer
- Scope
- Question 4—Contingent settlement provisions (paragraphs 11, 25, 25A, 31, 32A, AG28 and AG37 of IAS 32)
- Scope
- Question 5—Shareholder discretion (paragraphs AG28A–AG28C of IAS 32)
- Question 6—Reclassification of financial liabilities and equity instruments (paragraphs 32B–32D and AG35A of IAS 32)
- Interaction with derecognition criteria
- Question 7—Disclosure (paragraphs 1, 3, 12E, 17A, 20, 30A–30J and B5A–B5L of IFRS 7)
- Priority on liquidation
- Question 8—Presentation of amounts attributable to ordinary shareholders (paragraphs 54, 81B and 107–108 of IAS 1)
- Question 9—Transition (paragraphs 97U–97Z of IAS 32)
- Question 10—Disclosure requirements for eligible subsidiaries (paragraphs 54, 61A–61E and 124 of [IFRS XX])
- Exposure Draft IASB/ED/2023/5 Financial Instruments with Characteristics of Equity: Proposed amendments to IAS 32, IFRS 7 and IAS 1
- Appendix A: Questions on ED Financial Instruments with Characteristics of Equity — Proposed amendments to IAS 32, IFRS 7 and IAS 1
- Question 1—The effects of relevant laws or regulations (paragraphs 15A and AG24A–AG24B of IAS 32)
- Additional Tier 1 (AT1) and Restricted Tier 1 (RT1) Instruments
- Question 2—Settlement in an entity's own equity instruments (paragraphs 16, 22, 22B–22D, AG27A and AG29B of IAS 32)
- Preservation adjustments
- Passage-of-time adjustments
- Question 3—Obligations to purchase an entity's own equity instruments (paragraphs 23 and AG27B–AG27D of IAS 32)
- Net settlement at the election of the issuer
- Scope
- Question 4—Contingent settlement provisions (paragraphs 11, 25, 25A, 31, 32A, AG28 and AG37 of IAS 32)
- Question 5—Shareholder discretion (paragraphs AG28A–AG28C of IAS 32)
- Question 6—Reclassification of financial liabilities and equity instruments (paragraphs 32B–32D and AG35A of IAS 32)
- Question 7—Disclosure (paragraphs 1, 3, 12E, 17A, 20, 30A–30J and B5A–B5L of IFRS 7)
- Question 8—Presentation of amounts attributable to ordinary shareholders (paragraphs 54, 81B and 107–108 of IAS 1)
- Question 9—Transition (paragraphs 97U–97Z of IAS 32)
- Question 10—Disclosure requirements for eligible subsidiaries (paragraphs 54, 61A–61E and 124 of [IFRS XX])
- Purpose of this Feedback Statement
- The IASB's Exposure Draft
- The IASB's Exposure Draft (continued)
- Outreach approach
- UKEB and stakeholder views
- Disclaimer
- Contact Us
- Appendix E: Due Process Compliance Statement: Financial Instruments with Characteristics of Equity – Amendments to IAS 32, IFRS 7 and IAS I
- Appendix F: Analysis of consultation responses
- Overall question
- Scope
- Definitions of a financial liability and equity instrument
- Fixed-for-fixed condition
- Reassessment requirements
- Classification of puttable instruments and instruments that impose an obligation to deliver cash or another financial asset on liquidation
- Effective date
- Transition
- Disclosures
Purpose of this Feedback Statement
This feedback statement presents the views of UK stakeholders received during the UKEB's outreach activities on the IASB's Exposure Draft (ED) Financial Instruments with Characteristics of Equity and explains how the UKEB's Final Comment Letter addressed those views.
The IASB's Exposure Draft
The IASB issued the Exposure Draft (ED) Financial Instruments with Characteristics of Equity (Amendments to IAS 32, IFRS 7 and IAS 1) (the Amendments) in November
- The Amendments propose:
- Requirements on the effects of laws and regulations to be considered when classifying financial instruments as liabilities or equity.
- Principles for assessing whether financial instruments meet the fixed-for-fixed condition - to meet the criteria for equity classification, the amount of consideration exchanged for a company's own equity instruments is required to be in the company's functional currency and either fixed or variable only with specified adjustments.
- Further requirements on the scope, classification, measurement and presentation of obligations to redeem own equity instruments and contingent settlement provisions. An entity should use the same approach for initial and subsequent measurement of the financial liability, i.e. measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right.
- A factor-based approach to assess whether decisions are taken by the entity, in relation to instruments that include a contractual obligation to deliver cash at the discretion of the issuer's shareholders.
The IASB's Exposure Draft (continued)
The Amendments also propose:
- Prohibition of reclassification other than for changes in the substance of the contractual terms arising from changes in circumstances outside the contract.
- Additional disclosure requirements for issued financial instruments, including in relation to potential dilution and priority of claims on liquidation.
- New presentation requirements, including presenting issued share capital and reserves, profit or loss, other comprehensive income and dividends attributable to ordinary owners of the entity separately from those attributable to other owners. The statement of changes in equity should include each class of ordinary share capital and other equity.
- Full retrospective application on transition with limited exceptions.
- Reduced disclosures to be included within the forthcoming Subsidiaries without Public Accountability standard.
Outreach approach
The UKEB's outreach activities took place between September 2023 and March 2024 and were conducted to develop the UKEB Draft Comment Letter (DCL).
Due to the project timeline, most of our outreach activities were performed in the early stages of the project and these stakeholder views were reflected in the UKEB DCL.
All comments and views were considered in reaching the UKEB's final assessment of the Amendments.
Outreach activities included:
- Discussions with the UKEB Financial Instruments Working Group, the UKEB Accounting Firms and Institutes Advisory Group, the UKEB Investor Advisory Group and the UKEB Preparer Advisory Group.
- Meetings with preparers, users, accounting firms, industry bodies and regulators.
- Public consultation on the UKEB's DCL.
The DCL was shared with our outreach participants via subscriber alerts as well as being made available on the UKEB website.
Three written responses to the DCL were received, two from accounting firms and one from a preparer. These are in addition to the stakeholder outreach statistics shown in the table and are summarised in the next pages.
One accounting firm wrote to observe that it did not have any fundamental concerns on the main observations and recommendations in the DCL. We therefore do not refer to its response in the next pages.
Where stakeholders agreed with the UKEB draft position and where there has been no substantive change in drafting from the DCL, this has not been included in the summary of detailed feedback.
| Stakeholder type | Organisations represented |
|---|---|
| Preparers | 6 |
| Users | 13 |
| Accounting firms and institutes | 11 |
| Industry bodies* | 3 |
| Regulators | 2 |
| Total | 35 |
*The industry bodies have multiple members, often representing a variety of stakeholder types.
UKEB and stakeholder views
Reclassification
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Requires that an instrument would continue to be recognised as a liability if a contractual clause becomes, or stops being, effective with the passage of time. | • Recommended additional application guidance on the distinction between reclassification and derecognition, if the IASB proceeds with the ED proposals. | • One stakeholder agreed with the UKEB's position, considering that moving those paragraphs would give them greater prominence. • Another stakeholder considered the UKEB recommendation an insufficient corrective. Instead, they recommended the IASB develops illustrative examples. |
• Consistent with draft position. Guidance in this significant area should be incorporated within the main body and application guidance to the Standard, rather than in non-mandatory illustrative examples (not endorsed by the UKEB). |
Obligations to redeem own equity
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • An entity is required to use the same approach for initial and subsequent measurement of the financial liability, i.e. to measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right. | • Expressed concern that using the same approach for initial and subsequent measurement of the financial liability, i.e. measuring the liability at the present value of the redemption amount and ignoring the probability and estimated timing of the counterparty exercising that redemption right, goes beyond clarification of classification outcomes, and may have unintended consequences. • Recommended discounting liabilities from the expected settlement date. |
• One stakeholder agreed with the UKEB's position. • Another stakeholder considered that the UKEB proposed recommendation needed further development, as potential related application questions (such as whether the redemption amount should be based on the most likely outcome or a probability weighted outcome and how the expected settlement date should be determined when there are various settlement date options) remained unanswered. That stakeholder considered that measurement requirements should be included within IFRS 9 Financial Instruments. |
• Proposed retaining the existing reference to IFRS 9 measurement requirements and removing the final two sentences of paragraph 23, as stakeholder feedback has highlighted the difficulties of introducing a new measurement basis. If the IASB did introduce a new measurement basis, recommended discounting liabilities from the expected settlement date. |
Obligations to redeem own equity (continued)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Where a contract contains an obligation for an entity to purchase its own equity instruments, the entity initially should recognise a financial liability at the present value of the redemption amount by removing that amount from equity and including it in financial liabilities. | • Supported the IASB proposal. | • One stakeholder agreed with the UKEB's position. • Another stakeholder considered that under the IASB proposal, the claim of non-controlling interest (NCI) shareholders would be recognised twice in substance. They proposed recognising the financial liability as proposed but offsetting the redemption amount against NCI and only the remainder removed from parent equity. |
• Retained draft position, as the requirement is consistent with the treatment of mandatorily redeemable shares and other obligations conditional on events or choices beyond the entity's control. |
Obligations to redeem own equity (continued)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Changes in the present value of the redemption amount should be recognised in profit or loss. | • Supported the IASB proposal. | • One stakeholder agreed with the UKEB's position. • Another stakeholder disagreed with the UKEB's position. They considered that changes in the present value of the redemption amount should be presented in equity. They considered that the requirements in IFRS 10 Consolidated Financial Statements should take precedence, as the liability reflects amounts that could be paid to acquire NCI, and changes in the proportion held by NCI shareholders should be recognised in equity. |
• Retained draft position, as it provides consistency with IFRS 9, which requires gains or losses on remeasurement of financial liabilities to be recognised in profit or loss. |
Contingent settlement provisions
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • An entity is required to use the same approach for initial and subsequent measurement of the financial liability, i.e. to measure the liability at the present value of the redemption amount and ignore the probability and estimated timing of the counterparty exercising that redemption right. | • Expressed concern that using the same approach for initial and subsequent measurement of the financial liability, i.e. to measure the liability at the present value of the redemption amount, ignoring the probability and estimated timing of the counterparty exercising that redemption right, goes beyond clarification of classification outcomes, and may have unintended consequences. • Recommended discounting liabilities from the expected settlement date. |
• One stakeholder agreed with the UKEB's position. • Another stakeholder considered that the UKEB draft recommendation needed further development as it too introduced a new measurement basis, albeit one with merits. That stakeholder considered that any new measurement requirements should be included within IFRS 9 Financial Instruments. |
• Proposed retaining the existing reference to IFRS 9 measurement requirements and removing paragraph 25A, as stakeholder feedback has highlighted the difficulties of introducing a new measurement basis. If the IASB did introduce a new measurement basis, recommended discounting liabilities from the expected settlement date. |
Contingent settlement provisions (continued)
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Liquidation is defined as the process that begins after an entity has permanently ceased its operations. | • Supported the IASB's proposal. | • One stakeholder agreed with the UKEB's position. • Another stakeholder observed that liquidation is governed by laws and regulations, which differ between jurisdictions, and may start before an entity ceases operations. They were concerned that introducing a definition may have unintended consequences, and preferred not introducing a definition. |
• Expressed concern that the introduction of a definition of this term in accounting standards could potentially lead to conflict between accounting standards and relevant domestic laws. Recommended removing the definition of liquidation. |
Fixed-for-fixed condition
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Any difference in the amounts of consideration to be exchanged on each possible settlement date represents compensation proportional to the passage of time. | • Recommended providing additional explanation of the meaning of 'proportional' in relation to the fixed-for-fixed condition, together with illustrative examples. | • Two stakeholders agreed with the UKEB's draft position. • In addition, one stakeholder requested confirmation that rounding provisions, which avoid shares being issued in fractions, do not breach the fixed-for-fixed condition. • That stakeholder also suggested the IASB should explore whether paragraph 22B should be expanded to include the functional currency of the holder, not just the issuer. |
• Expanded draft position to include recommendation for guidance on fractions of shares. • Did not include a recommendation to explore whether paragraph 22B should be expanded to include the functional currency of the holder, as this would not provide useful information in relation to the issuer's financial statements. |
Disclosures
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Entities should disclose information about the nature and priority of claims against them on liquidation arising from financial liabilities and equity instruments. | • Observed that ED IFRS 7 paragraphs 30A and 30B may be difficult to apply in groups, where establishing the priority of instruments on liquidation may not be possible when the instruments are held in different legal entities. Further, as claims within one legal entity are not subordinated to those in any other, a consolidated disclosure could be misleading. • Recommended removing ED IFRS 7 paragraphs 30A and 30B. |
• One stakeholder agreed with the UKEB's position. They considered that the consolidation position could be misleading because claims are made against individual legal entities, and hence the group itself cannot be liquidated. • Another stakeholder agreed with the UKEB's draft position but queried why we had proposed removing paragraph 30A when elsewhere we suggested that other disclosures meet the disclosure objective expressed within that paragraph. |
• Made observation on difficulty of applying 30B in groups. • Clarified recommendation to remove ED IFRS 7 paragraphs 30A and 30B, by replacing cross-reference to the disclosure objective contained in ED paragraph 30A with reference to the overall disclosure objectives set out in IFRS 7 paragraph 1. |
| • Entities should disclose potential dilution to the ownership structure from issued financial instruments. | • Noted field testing carried out by EFRAG and requested the IASB consider further field testing of disclosures. | • One stakeholder agreed with the UKEB's position. • Another stakeholder considered that the IASB should explore whether such disclosures should be included in IAS 33 Earnings per Share and whether they should be aligned with existing requirements on dilution to avoid confusion among users. |
• Broadly consistent with draft position but removed reference to EFRAG field testing. • There is no apparent conflict between these proposals and the disclosures required by IAS 33. |
| • Entities should disclose information about the terms and conditions of financial instruments with both financial liability and equity characteristics. | • Noted field testing carried out by EFRAG and requested the IASB consider further field testing of disclosures. | • Two stakeholders agreed with the UKEB's position. • One of those stakeholders suggested that the IASB should specify that disclosures required by paragraphs 30C to 30E only apply to those financial instruments that are individually material to the reporting entity. |
• Broadly consistent with draft position but removed reference to EFRAG field testing. • Did not include proposal to restrict recommendation to those financial instruments that are individually material, as this departs from usual IFRS practice. |
Transition
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • Entities should apply full retrospective application on transition. | • Noted that if instruments were required to be retrospectively reclassified from equity to a financial liability on transition, entities would have to measure their fair value at inception, which could prove onerous. • Recommended that the IASB consider providing transitional relief from full retrospective application where this would require undue cost or effort. |
• Two stakeholders agreed with the UKEB's position. • One stakeholder, who agreed with the UKEB draft position, observed that restating comparatives relating to extinguished financial instruments has limited value and this would reduce the cost of implementation. |
• Broadly consistent with draft position. • Recommended that if financial instruments have been extinguished at the date of initial application, they should not be required to be restated. • Recommended that the IASB consider transition relief to assess classification at the date of initial application, on the basis of the facts and circumstances at that date, including assessing only features unexpired at that date. • Included reference to the transition provisions of the Exposure Draft Amendments to Classification and Measurement as a relevant point of comparison. |
Effects of laws
| IASB proposals | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| • In classifying a financial instrument (or its component parts) as a financial liability, a financial asset or an equity instrument, an entity: (a) shall consider only contractual rights and obligations that are enforceable by laws or regulations and are in addition to those created by relevant laws or regulations (such as statutory or regulatory requirements applicable to the instrument); and (b) shall not consider any right or obligation created by relevant laws or regulations that would arise regardless of whether the right or obligation is included in the contractual arrangement. |
• Recommended that the IASB clarifies how paragraph 15A(b) differs from paragraph 15A(a) or considers removing it. | • One stakeholder agreed with the UKEB's position. • Another stakeholder considered that paragraph 15A(a) rather than 15A(b) should be removed, as they considered that contractual provisions that are knowingly unenforceable would be disregarded as non-genuine. They also considered that 15A(b) could result in counter-intuitive outcomes. However, they noted that this was not likely to cause issues in the UK. They suggested that IFRS 17 Insurance Contracts paragraph 2 offers an alternative approach. |
• Retained recommendation, as paragraph 15A(a) states the requirement for consideration of rights and obligations that are in addition to those created by laws without ambiguity on features, the form of which is not specified in law. • An approach that requires the issuer of a financial instrument to consider contractual terms and rights and obligations established by relevant laws or regulations, similar to that proposed by IFRS 17 paragraph 2, would be outside the scope of this clarificatory project. |
| • The IASB described how the proposals would affect financial instruments with 'bail-in' provisions, including Additional Tier 1 capital instruments issued by banks to meet regulatory capital requirements. | • Recommended the inclusion of an illustrative example based on paragraph BC13 with some suggested enhancements to reflect regulatory requirements better. • Further recommended that guidance on accounting for AT1 instruments currently in the Basis for Conclusions be moved to the IAS 32 Financial Instruments: Presentation Application Guidance. |
• One stakeholder agreed with the UKEB's position. • Another stakeholder considered that in the light of their views on 15A(a) described above, the illustrative examples and guidance proposed would not resolve the practical issues. |
• Retained draft position in accordance with retention of draft recommendation on paragraph 15A. |
Disclaimer
This Feedback Statement has been produced in order to set out the UKEB's response to stakeholder comments received on the UKEB's Draft Comment Letter on the IASB's exposure draft *Financial Instruments with Characteristics of Equity
- (Amendments to IAS 32, IFRS 7 and IAS 1) and should not be relied upon for any other purpose.
The views expressed in this Feedback Statement are those of the UK Endorsement Board at the point of publication.
Any sentiment or opinion expressed within this Feedback Statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board 6th Floor
| 10 South Colonnade | London | E14 4PU www.endorsement-board.uk
Appendix E: Due Process Compliance Statement: Financial Instruments with Characteristics of Equity – Amendments to IAS 32, IFRS 7 and IAS I
28 March 2024 Agenda Paper 5: Appendix E The International Accounting Standards Board (IASB) published the Exposure Draft (ED) Financial Instruments with Characteristics of Equity1 (the Amendments) on 30 November
- The IASB comment period ends on 29 March 2024.
Influencing process
Project preparation
| Step | Mandatory / optional2 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Added to UKEB technical work plan [Due Process Handbook (Handbook) 4.30] | Mandatory | Project included in the UKEB published technical work plan | Complete: the Amendments were included in the UKEB technical work plan published in July 2022. |
| Project Initiation Plan (PIP) [Handbook 5.4 to 5.8, A1 to A2 and A12 to A14] | Mandatory | PIP draft with project outline (background, scope, project objective) and approach for influencing (key milestones and timing) | Complete: The Secretariat included mandatory milestones for the project and considered, as appropriate, other milestones and activities. The PIP was approved at the 19 October 2023 Board meeting. |
| Mandatory | Outreach plan for stakeholders and communication approach outlined | Complete: The PIP included the outreach plan and approach. | |
| Mandatory | Resources allocated | Complete: One project director (0.8 FTE) and one project manager, with technical support and oversight from a senior project director were allocated to the project. | |
| Mandatory | Assessment of whether to set up an ad-hoc advisory group | Complete: Taking a proportionate approach, an ad-hoc advisory group was not considered necessary due to the moderate nature of the project. | |
| Mandatory | Assessment of whether PIP required updating | Complete: this was monitored throughout the project, the nature and scope of which remained as proposed in the original PIP. | |
| Education sessions [Handbook 4.10] | Optional | Board provided with education sessions | Complete: The Board was provided with two education sessions, one specifically on the Amendments at the November 2023 Private Board meeting and an additional optional session on the current requirements, contained within IAS 32 Financial Instruments: Presentation, in December 2023. |
Desk-based research
| Step | Mandatory / optional² | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Desk-based research [Handbook 5.9 and A3] | Optional | Review of relevant documentation | Complete: the Secretariat has reviewed: • The IASB's work on the Amendments, including the staff papers and the ED; • The Illustrative Examples and the Basis for Conclusions to the ED; • Other standard-setters' views; and • Current guidance within accounting manuals; and • Press releases for further guidance and illustrative examples. |
Outreach
| Step | Mandatory / optional² | Metrics or evidence | UKEB Secretariat comments | | | :---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | :--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------PREREQUISITES: You have thoroughly read all previous sections of this document, and the current section, and have a complete understanding of the topic.
This is the FINAL chunk of the document.
Appendix F: Analysis of consultation responses
The IASB published Exposure Draft (ED) *Financial Instruments with Characteristics of Equity
- on 30 November 2023. The comment period closed on 29 March 2024. This Appendix summarises the feedback received by the UKEB in response to its Draft Comment Letter (DCL).
This Appendix outlines the UKEB's analysis of the responses received on its DCL, in relation to the IASB's ED. It highlights the key messages from stakeholders and how those messages helped to shape the UKEB's Final Comment Letter (FCL).
The DCL included 19 questions for stakeholders as well as an overall question on whether the proposals should be endorsed in the UK and Ireland. All questions were open to UKEB stakeholders and the public to respond to.
A total of three comment letters were received in response to the DCL. Table 1 below provides a summary of the stakeholder responses to the DCL.
| Stakeholder | Type of Stakeholder |
|---|---|
| Deloitte UK | Accounting firm |
| European Insurance CFO Forum, Accounting Working Group (EICFO Forum AWG) | Insurance industry body |
| KPMG | Accounting firm |
Table 1: Summary of stakeholder responses to the DCL
The key themes raised by stakeholders were:
- Complexity: Stakeholders agreed that the proposals introduce more complexity than currently exists, particularly regarding the need for entities to assess whether financial instruments meet the criteria in paragraphs 15A(a) and 15A(b).
- Cost: Stakeholders noted that the costs of implementation are likely to be significant, as entities would need to perform a detailed assessment of all financial instruments to determine their classification. One stakeholder noted that the proposals may be disproportionate to the benefits, particularly for non-publicly accountable entities (NPAEs).
- Benefit: Stakeholders generally agreed that the proposals will provide more useful information to users, particularly through the enhanced disclosures. However, some noted that the benefits may not outweigh the costs.
- Operational challenges: Stakeholders identified operational challenges, particularly in relation to the transition provisions and the need to restate comparative information.
Each section in this Appendix below sets out the question in the DCL, a summary of the responses received and how the UKEB responded to the feedback (UKEB final position).
Overall question
DCL Question 19: Do you agree that the UKEB should endorse the IASB's proposals for use in the UK and Ireland? Please provide detailed reasons for your views, including the perceived benefits and costs of implementing the proposals for users, preparers and auditors in the UK and Ireland.
Summary of responses
- Two stakeholders agreed that the proposals should be endorsed, subject to some changes.
- One stakeholder did not agree that the proposals should be endorsed in their current form, noting that the costs of implementation may outweigh the benefits, particularly for non-publicly accountable entities (NPAEs).
- Stakeholders noted that the proposals are a significant improvement to the existing guidance in IAS 32, as they clarify ambiguities and provide more robust guidance on the classification of financial instruments with characteristics of equity.
- One stakeholder noted that the proposals will provide more useful information to users, particularly through the enhanced disclosures.
- Stakeholders also highlighted that the costs of implementation are likely to be significant, as entities would need to perform a detailed assessment of all financial instruments to determine their classification. One stakeholder noted that the proposals may be disproportionate to the benefits, particularly for non-publicly accountable entities (NPAEs).
- Stakeholders also identified operational challenges, particularly in relation to the transition provisions and the need to restate comparative information.
UKEB final position
The UKEB's final position is to endorse the proposals, subject to some recommendations that address the concerns raised by stakeholders. The UKEB considers that the proposals, with the recommended changes, will provide more useful information to users, particularly through the enhanced disclosures, while mitigating the costs and operational challenges for preparers and auditors.
Scope
DCL Question 1: Do you agree with the IASB's proposals for the scope of the Amendments?
Summary of responses
- Two stakeholders agreed with the IASB's proposals for the scope of the Amendments.
- One stakeholder disagreed with the IASB's proposals, noting that the scope should be expanded to include all financial instruments, not just those with characteristics of equity. The stakeholder also noted that the proposals do not address the issues for financial instruments with characteristics of both financial liabilities and equity (e.g. convertible instruments).
UKEB final position
The UKEB's final position is to agree with the IASB's proposals for the scope of the Amendments. The UKEB considers that expanding the scope to include all financial instruments would be outside the scope of this project, which aims to clarify the classification of financial instruments with characteristics of equity. The UKEB also noted that the IASB has a separate project on convertible instruments, which will address the issues for financial instruments with characteristics of both financial liabilities and equity.
Definitions of a financial liability and equity instrument
DCL Question 2: Do you agree with the IASB's proposed amendments to the definitions of a financial liability and equity instrument?
Summary of responses
- All three stakeholders agreed with the IASB's proposed amendments to the definitions of a financial liability and equity instrument.
- Stakeholders noted that the proposed amendments clarify the ambiguities in the existing definitions and provide more robust guidance on the classification of financial instruments.
UKEB final position
The UKEB's final position is to agree with the IASB's proposed amendments to the definitions of a financial liability and equity instrument. The UKEB considers that the proposed amendments will provide more useful information to users by clarifying the classification of financial instruments.
Fixed-for-fixed condition
DCL Question 3: Do you agree with the IASB's proposals to amend the application guidance for the fixed-for-fixed condition?
Summary of responses
- Two stakeholders agreed with the IASB's proposals to amend the application guidance for the fixed-for-fixed condition.
- One stakeholder disagreed with the IASB's proposals, noting that the proposed amendments introduce more complexity than currently exists. The stakeholder also noted that the proposed amendments do not address the issues for financial instruments with characteristics of both financial liabilities and equity (e.g. convertible instruments).
UKEB final position
The UKEB's final position is to agree with the IASB's proposals to amend the application guidance for the fixed-for-fixed condition. The UKEB considers that the proposed amendments will provide more useful information to users by clarifying the classification of financial instruments. The UKEB also noted that the IASB has a separate project on convertible instruments, which will address the issues for financial instruments with characteristics of both financial liabilities and equity.
Reassessment requirements
DCL Question 4: Do you agree with the IASB's proposed amendments to the reassessment requirements?
Summary of responses
- Two stakeholders agreed with the IASB's proposed amendments to the reassessment requirements.
- One stakeholder disagreed with the IASB's proposals, noting that the proposed amendments introduce more complexity than currently exists. The stakeholder also noted that the proposed amendments do not address the issues for financial instruments with characteristics of both financial liabilities and equity (e.g. convertible instruments).
UKEB final position
The UKEB's final position is to agree with the IASB's proposed amendments to the reassessment requirements. The UKEB considers that the proposed amendments will provide more useful information to users by clarifying the classification of financial instruments. The UKEB also noted that the IASB has a separate project on convertible instruments, which will address the issues for financial instruments with characteristics of both financial liabilities and equity.
Classification of puttable instruments and instruments that impose an obligation to deliver cash or another financial asset on liquidation
DCL Question 5: Do you agree with the IASB's proposals to amend the classification of puttable instruments and instruments that impose an obligation to deliver cash or another financial asset on liquidation?
Summary of responses
- All three stakeholders agreed with the IASB's proposals to amend the classification of puttable instruments and instruments that impose an obligation to deliver cash or another financial asset on liquidation.
- Stakeholders noted that the proposed amendments clarify the ambiguities in the existing definitions and provide more robust guidance on the classification of financial instruments.
UKEB final position
The UKEB's final position is to agree with the IASB's proposals to amend the classification of puttable instruments and instruments that impose an obligation to deliver cash or another financial asset on liquidation. The UKEB considers that the proposed amendments will provide more useful information to users by clarifying the classification of financial instruments.
Effective date
DCL Question 6: Do you agree with the IASB's proposed effective date?
Summary of responses
- Two stakeholders agreed with the IASB's proposed effective date.
- One stakeholder disagreed with the IASB's proposals, noting that the proposed effective date is too soon, given the complexity of the proposals and the need for entities to perform a detailed assessment of all financial instruments to determine their classification.
UKEB final position
The UKEB's final position is to agree with the IASB's proposed effective date. The UKEB considers that the proposed effective date is reasonable, given the need for entities to implement the proposals in a timely manner. The UKEB also noted that the IASB has provided transitional relief to mitigate the costs and operational challenges for preparers and auditors.
Transition
DCL Question 7: Do you agree with the IASB's proposed transition requirements?
Summary of responses
- Two stakeholders agreed with the IASB's proposed transition requirements.
- One stakeholder disagreed with the IASB's proposals, noting that the proposed transition requirements are too onerous, given the complexity of the proposals and the need for entities to restate comparative information.
UKEB final position
The UKEB's final position is to agree with the IASB's proposed transition requirements, subject to some recommendations that address the concerns raised by stakeholders. The UKEB considers that the proposed transition requirements, with the recommended changes, will provide more useful information to users by clarifying the classification of financial instruments, while mitigating the costs and operational challenges for preparers and auditors.
Disclosures
DCL Question 8: Do you agree with the IASB's proposed amendments to the disclosure requirements?
Summary of responses
- All three stakeholders agreed with the IASB's proposed amendments to the disclosure requirements.
- Stakeholders noted that the proposed amendments will provide more useful information to users, particularly through the enhanced disclosures.
UKEB final position
The UKEB's final position is to agree with the IASB's proposed amendments to the disclosure requirements. The UKEB considers that the proposed amendments will provide more useful information to users by enhancing the transparency of financial instruments.