5 Annual Improvements to IFRS Accounting Standards – Volume 11
14 December 2023 Agenda Paper 5
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Narrow-scope |
Purpose of the paper
The purpose of this paper is to obtain the Board's:
- approval for the issue of a Final Comment Letter (FCL) on the International Accounting Standards Board (IASB)'s Exposure Draft (ED) Annual Improvements to IFRS Accounting Standards – Volume 11;
- approval for the publication of the Feedback Statement (FS); and
- feedback on and approval of the draft Due Process Compliance Statement (DPCS).
Summary of the Issue
As part of its Annual Improvements cycle, the International Accounting Standards Board (IASB) issued the ED which included eight proposed amendments on 12 September 2023.
The UKEB's Draft Comment Letter (DCL) was published for UK stakeholder comment on 19 October 2023, concluding that the ED improved the consistency and understandability of the IFRS Accounting Standards concerned. The consultation closed on 20 November 2023. The only response to the DCL was supportive of the UKEB's messages.
Further outreach since publication of the DCL has not identified any significant concern with the proposals in the ED. As such, the FCL presented at the Appendix A remains unchanged from the DCL.
Decisions for the Board
Subject to any amendments arising at this meeting, does the Board approve:
- the FCL (Appendix A) for issue to the IASB and publication on the UKEB website?
- the FS (Appendix B) for publication on the UKEB website?
- the draft DPCS (Appendix C)?
Recommendation
The Secretariat recommends that, subject to any amendments agreed at this meeting, the Board approved the FCL, FS for issuance and publication and approves the [draft] DPCS.
Appendices
Appendix A Final Comment Letter Appendix B Feedback Statement Appendix C [Draft] Due Process Compliance Statement
Background
1As part of its Annual Improvements cycle, the IASB issued the ED of Annual Improvements to IFRS Accounting Standards – Volume 11 (Annual Improvements) which included eight proposed amendments on 12 September 2023. The IASB's comment period ends on 11 December 2023. The Board was provided with a summary of the proposed amendments in Annex A of the Project Initiation Plan.
2Annual improvements are limited to changes that either clarify the wording in an IFRS Accounting Standard, or correct relatively minor unintended consequences, oversights or conflicts between requirements of the Accounting Standards. 1 The proposed improvements are packaged and exposed together in one document.
3The Secretariat conducted desk-based research and discussed the IASB's proposals with stakeholders in September and October 2023 to inform the Draft Comment Letter (DCL).
4The DCL was approved at the October 2023 UKEB meeting and published on the UKEB website on 19 October 2023, with a consultation period ending on 20 November 2023. The DCL was supportive of the IASB's proposal on the basis that the amendments are expected to improve the consistency and understandability of the IFRS Accounting Standards concerned. UKEB news alerts and LinkedIn posts were used to raise awareness of the publication of the DCL.
Outreach and feedback on the DCL
5Following the publication of the DCL, the Secretariat conducted further outreach activities to inform the FCL. This involved discussions with the Preparer Advisory Group (PAG) and the Accounting Firms and Institutes Advisory Group (AFIAG) in October and November 2023. One written response to the DCL was received and has been published on the UKEB website. No significant concern has been identified during the outreach or in the written response received.
Comment letter, feedback statement and due process
6The draft FCL is attached at Appendix A. Given the feedback received, it remains unchanged from the DCL.
7The draft feedback statement (FS) is attached at Appendix B and reflects the limited feedback received.
8The draft DPCS is attached at Appendix C for consideration. A final version will be brought to the 30 January 2024 meeting for noting once the final project steps are complete.
Questions for the Board
1Subject to any amendments arising at this meeting, does the Board approve:
- the FCL (Appendix A) for issuance to the IASB and publication on the UKEB website?
- the FS (Appendix B) for publication on the UKEB website?
- the draft DPCS (Appendix C)?
Next steps
9The FCL will be submitted to the IASB following this meeting. The FCL together with the FS will be published on the UKEB website. The DPCS will be updated to reflect the final project steps and presented to the 30 January 2024 meeting for the Board's noting.
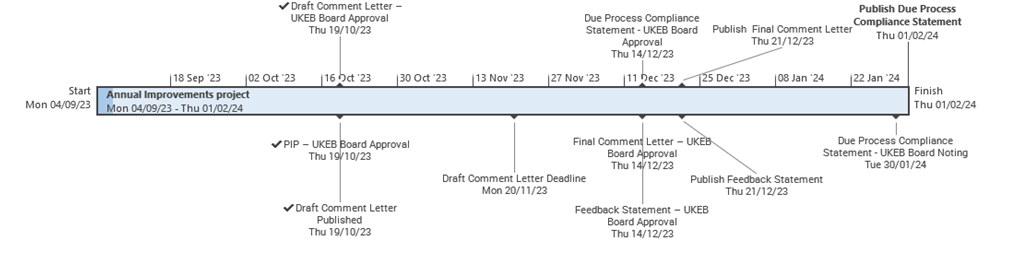
Annual Improvements to IFRS Accounting Standards – Volume 11 Timeline
| Milestone – Brief description | Status |
|---|---|
| Influencing | |
| 12 September 2023 | The IASB publishes the Exposure Draft |
| 19 October 2023 | Board: Approves the Project Initiation Plan (PIP) and Draft Comment Letter (DCL) for publication |
| 19 October 2023 | DCL published, comment period 32 days |
| October – November 2023 | Outreach with UKEB advisory groups as described in the PIP |
| 14 December 2023 | Board: [Approves] Final Comment Letter, Feedback Statement and draft Due Process Compliance Statement (DPCS) |
| 30 January 2024 | Board: Final DPCS for the Board's noting |
Timeline
Final Comment Letter (Appendix A)
Dr Andreas Barckow Chairman International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
[14 December 2023]
Dear Dr Barckow
Exposure Draft Annual Improvements to IFRS Accounting Standards – Volume 11
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS. 1 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option. 2
3We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB) Exposure Draft (ED) Annual Improvements to IFRS Accounting Standards–Volume 11. In developing this letter, we have consulted
4with stakeholders in the UK, including preparers of accounts, accounting firms and institutes and a regulator.
5We support the proposals in the ED as they are expected to improve the consistency and understandability of the IFRS Accounting Standards concerned. For detailed responses to the questions in the ED please see Appendix A.
If you have any questions about this response, please contact the project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Questions on ED Annual Improvements to IFRS Accounting Standards – Volume II
IFRS 1 First-time Adoption of International Financial Reporting Standards
Hedge Accounting by a First-time Adopter
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A1We agree with the IASB's proposals to align the terminology in the requirements of hedge accounting in IFRS 1 with IFRS 9 Financial Instruments and to add the cross-referencing to the relevant IFRS 9 paragraphs.
A2We agree these proposed amendments would improve the accessibility and understandability of the hedge accounting requirements for first-time adopters that are required to apply IFRS 9 instead of IAS 39.
IFRS 7 Financial Instruments: Disclosures
Gain or loss on derecognition
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A3We agree with the IASB's proposals to update the obsolete cross-reference in paragraph B38 of IFRS 7 and to streamline the wording in the last sentence of the paragraph in accordance with IFRS 13.
A4We agree these proposed amendments would improve the accessibility and understandability of the disclosure requirements on the gain or loss on derecognition relating to financial assets in which the entity has continuing involvement.
IFRS 7 Financial Instruments: Disclosures
Disclosure of deferred difference between fair value and transaction price
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A5We agree with the IASB's proposal to align the wording in paragraph IG14 of IFRS 7 with the wording in paragraph 28 of IFRS 7.
A6The illustrative example in paragraph IG14 of IFRS 7 is associated with the disclosure requirements in paragraph 28 of IFRS 7 therefore we agree the proposed amendments would improve the understandability of the disclosure requirements on the deferred difference between fair value and transaction price of financial instruments.
IFRS 7 Financial Instruments: Disclosures
Introduction and credit risk disclosures
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A7We agree with the IASB's proposal to add a statement in the introductory paragraph of the Implementation Guidance accompanying IFRS 7 and to remove the disclaimer in paragraph IG20B of IFRS 7.
A8We agree the proposed amendments would improve the understandability by clarifying that the illustrative examples in the Implementation Guidance do not illustrate all the requirements in the accompanying accounting standard.
A9We observe the disclaimer statement only appears in some illustrative examples (IEs) and implementation guidance (IG) accompanying IFRS Accounting Standards therefore we suggest the IASB to take into consideration the consistency of the disclaimer language across IEs and IG when drafting new IFRS Accounting Standards or amending existing ones.
IFRS 9 Financial Instruments
Transaction price
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A10We agree with the IASB's proposals to remove the reference to the IFRS 15's definition of the term 'transaction price' from Appendix A of IFRS 9 and to revise the wording around the term in paragraph 5.1.3 of IFRS 9.
A11We agree the proposed amendments would improve the understandability by maintaining only one meaning of “transaction price” within IFRS 9.
IFRS 9 Financial Instruments
Derecognition of lease liabilities
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A12We agree with the IASB's proposal to add a cross-reference to paragraph 3.3.3 of IFRS 9 in paragraph 2.1(b)(ii) of IFRS 9 which states the requirements of lessee accounting upon the derecognition of lease liabilities.
A13We agree the proposed amendments would improve the understandability and accessibility because the addition of the cross-reference explicitly states the application requirements of the derecognition of lease liabilities.
IFRS 10 Consolidated Financial Statements
Determination of a 'de facto' agent
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A14We agree with the IASB's proposals to address the inconsistency between paragraphs B73 and B74 by clarifying the requirements in paragraph B74.
A15We agree the proposed amendments would improve the understandability of the requirements of the assessment of de facto agency relationships and its interaction with the assessment of control.
IAS 7 Statement of Cash Flows
Cost method
Do you agree with the IASB's proposals to amend the IFRS Accounting Standards and accompanying guidance in the manner described in this Exposure Draft?
If not, why not? If you disagree with these proposals, please explain what you would suggest instead and why.
A16We agree with the IASB's proposal to replace the term 'cost method', which is no longer defined in IFRS Accounting Standards, with the term 'at cost'.
A17We agree the proposed amendment would improve understandability around the measurement requirement of an associate, a joint venture of a subsidiary by removing a term that is no longer defined.
Feedback Statement
IASB Exposure Draft Annual Improvements to IFRS Accounting Standards – Volume II December 2023
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The comment letter to which this feedback statement relates forms part of those influencing activities and is intended to contribute to the IFRS Foundation's due process. The views expressed by the UKEB in its comment letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
- Executive Summary
- Summary of the Issue
- Decisions for the Board
- Recommendation
- Appendices
- Background
- Outreach and feedback on the DCL
- Comment letter, feedback statement and due process
- Questions for the Board
- Next steps
- Annual Improvements to IFRS Accounting Standards – Volume 11 Timeline
- Timeline
- Appendix A: Questions on ED Annual Improvements to IFRS Accounting Standards – Volume II
- IFRS 1 First-time Adoption of International Financial Reporting Standards
- IFRS 7 Financial Instruments: Disclosures
- IFRS 7 Financial Instruments: Disclosures
- IFRS 7 Financial Instruments: Disclosures
- IFRS 9 Financial Instruments
- IFRS 9 Financial Instruments
- IFRS 10 Consolidated Financial Statements
- IAS 7 Statement of Cash Flows
- Feedback Statement
- Appendix C: DRAFT Due Process Compliance Statement: Annual Improvements to IFRS Accounting Standards – Volume II
Purpose of this feedback statement
This feedback statement presents the views of UK stakeholders received during the UKEB's outreach activities on the IASB's Exposure Draft (ED) Annual Improvements to IFRS Accounting Standards–Volume 11 and explains how the UKEB's Final Comment Letter addressed those views.
The IASB's Exposure Draft
In September 2023 the IASB issued the ED IASB/AI/ED/2023/1 Annual Improvements to IFRS Accounting Standards – Volume 11 (Annual Improvements). The ED included eight proposed amendments which are summarised on the next two pages.
The IASB issues amendments to international accounting standards as part of its continuous effort to maintain and improve IFRS Standards and to support consistent application.
Annual improvements are limited to changes that either clarify the wording in an IFRS Accounting Standard, or correct relatively minor unintended consequences, oversights or conflicts between requirements of the Accounting Standards.
Transaction price (IFRS 9*)
- Revise the wording in paragraph 5.1.3 of IFRS 9; and
- Delete the reference to 'transaction price' and the associated references to IFRS 15 from Appendix A.
Derecognition of lease liabilities (IFRS 9*)
- Add a cross-reference to paragraph 3.3.3 of IFRS 9 in paragraph 2.1(b)(ii) of IFRS 9.
Hedge accounting by a first-time adopter (IFRS 1*)
- Add cross-references to paragraph 6.4.1 of IFRS 9 in paragraphs B5 and B6 of IFRS 1; and
- Replace the word 'conditions' with 'qualifying criteria' in paragraph B6 of IFRS 9.
Cost method (IAS 7*)
- Replace the term 'cost method', which is no longer defined in IFRS Accounting Standards, with 'at cost'.
* IFRS 9 Financial Instruments; IFRS 1 First-time Adoption of International Financial Reporting Standards; IAS 7 Statement of Cash Flows
Gain or loss on derecognition (IFRS 7*)
- Replace the reference to paragraph 27A of IFRS 7, which no longer exists, with a reference to paragraphs 72–73 of IFRS 13; and
- Replace the phrase 'inputs that were not based on observable market data' with 'unobservable inputs'.
Disclosure of deferred difference between fair value and transaction price (Implementation Guidance accompanying IFRS 7*)
- Propose an amendment to paragraph IG14 to improve its consistency with paragraph 28 of IFRS 7 which it illustrates.
Introduction and credit risk disclosures (Implementation Guidance accompanying IFRS 7*)
- Add a statement that the implementation guidance accompanying IFRS 7 does not illustrate all the requirements in IFRS 7 in paragraph IG1 of IFRS 7; and
- Simplify the wording in paragraph IG20B of IFRS 7.
Determination of a 'de facto agent' (IFRS 10*)
- Clarify the requirements in paragraph B74 of IFRS 10.
*IFRS 7 Financial Instruments: Disclosures; IFRS 10 Consolidated Financial Statements
Outreach approach & comment letter assessment
The UKEB's outreach activities took place between September and November 2023 and were conducted to assist the UKEB in developing its Comment Letter.
The outreach approach was underpinned by the UKEB's guiding principles of thought leadership, transparency, independence and accountability.
As the IASB's ED related to targeted improvements to the IFRS Accounting Standards, the Board took a proportionate approach to outreach on the IASB proposals and the UKEB's Draft Comment Letter (DCL).
Outreach activities included:
- discussion with the UKEB's Preparer Advisory Group and Accounting Firms & Institutes Advisory Group; and
- public consultation on the UKEB's DCL.
One written response to the UKEB's Invitation to Comment on its DCL was received and was supportive of the UKEB's DCL.
No substantive comments were received from the UKEB's Advisory Groups and UK stakeholders on the proposed amendments.
Therefore, our final comment letter is supportive of the IASB's ED on Annual Improvements.
All comments and views received were considered in reaching the UKEB final views on the proposals.
Disclaimer
This feedback statement has been produced in order to set out the UKEB's response to stakeholder comments received on the UKEB's project responding to the IASB's Exposure Draft Annual Improvements to IFRS Accounting Standards –Volume 11 and should not be relied upon for any other purpose.
The views expressed in this feedback statement are those of the UKEB at the point of publication.
Any sentiment or opinion expressed within this feedback statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board
6th Floor | 10 South Colonnade | London | E14 4PU
Appendix C: DRAFT Due Process Compliance Statement: Annual Improvements to IFRS Accounting Standards – Volume II
The International Accounting Standards Board (IASB) published Annual Improvements to IFRS Accounting Standards -Volume 11 1 Exposure Draft (ED) on 12 September 2023. The IASB comment period ends on 11 December 2023.
Influencing process
Project preparation
| Step | Mandatory / optional 2 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Added to UKEB technical work plan [Due Process Handbook (Handbook) 4.28 to 4.30] | Mandatory | Project is included in the UKEB published technical work plan. | Complete: The Annual Improvements to IFRS Accounting Standards –Volume 11 (Annual Improvements) were included in the UKEB technical work plan published in September 2023. |
| Project Initiation Plan (PIP) [Handbook 5.4 to 5.8] | Mandatory | PIP draft with project outline (background, scope, project objective) and approach for influencing (key milestones and timing) | Complete: The Secretariat included mandatory milestones for the project and considered, as appropriate, other milestones and activities. The PIP was approved at the 19 October 2023 Board meeting. |
| Mandatory | Outreach plan for stakeholders and communication approach outlined | Complete: The PIP (referred to above) included the outreach plan and approach. | |
| Mandatory | Resources allocated | Complete: One Project Manager supported by one Assistant Project Manager, with oversight from a Project Director. | |
| Project Initiation Plan (PIP) [Handbook 5.4 to 5.8] (continued) | Optional | Assessment of whether to set up of an ad-hoc advisory group | Complete: Taking a proportionate approach, an ad-hoc advisory group was not considered necessary due to the narrow-scope nature of the Amendments. |
| Mandatory | Assessment of whether PIP required updating | Complete: We monitored this throughout the project, whose nature and scope remained as proposed in the original PIP. | |
| Mandatory | UKEB Board public meeting held to approve PIP | Complete: The PIP was approved at the 19 October 2023 Board meeting. | |
| Education sessions [Handbook 4.10] | Optional | Board provided with education sessions | Complete: No education session was provided but the updates on the project were included in the agenda papers for UKEB March 2023 and June 2023 meetings. In addition, education material was shared with the Board in the 19 October 2023 meeting pack. |
Desk-based research
| Step | Mandatory / optional 1 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Desk-based research [Handbook 5.9] | Optional | Review of relevant documentation. | Complete: The Secretariat has reviewed: - the IASB's work on the ED (mainly staff papers); - the Basis for Conclusions to the ED; - relevant material produced by other parties, including accounting firms; - IFRS Interpretations Committee Agenda Decisions; and - other standard-setters' views. |
Outreach
| Step | Mandatory / optional 1 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Outreach activities [Handbook 5.10 to 5.12] | Mandatory | Evidence of consultation | Complete: Due to the narrow-scope nature of the proposed amendments, consultation activities were focused on obtaining responses to the Draft Comment Letter and consultation with the UKEB advisory groups: Accounting Firms & Institutes Advisory Group (AFIAG) and Preparer Advisory Group (PAG). Given most of the proposed amendments in the ED are to IFRS 7 and IFRS 9, we drew the Financial Instruments Working Group (FIWG) members' attention to Annual Improvements and asked them to contact the project team if they had any feedback. No feedback was received from the FIWG members. The UKEB received one comment letter. The comment letter received was published on the UKEB website. |
Draft Comment Letter (DCL)
| Step | Mandatory / optional 3 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| DCL published for comment (generally mandatory) [Handbook paragraphs 5.13 to 5.17] | Mandatory | The UKEB sets comment period for responses to DCL | Complete: The DCL was published for consultation for 32 days on 19 October 2023 (comment period deadline: 20 November 2023). |
| Mandatory 3 | Review and approval at a UKEB public meeting | Complete: The DCL was reviewed and approved at the Board meeting on 19 October 2023. | |
| Mandatory 3 | DCL published on website for public consultation | Complete: The DCL was published for consultation for 32 days on 19 October 2023 (comment period deadline: 20 November 2023). | |
| Optional | News Alert to announce publication | Complete: Two news alerts were published on 19 October 2023 and on 15 November 2023 calling for comments. A link to the DCL was included in the meeting packs for the October 2023 PAG meeting and the November 2023 AFIAG meeting. |
Project finalisation and project closure
| Step | Mandatory / optional 1 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| FCL [Handbook paragraph 5.18] | Mandatory | Public responses to DCL assessed and published on website | Complete: The UKEB received one comment letter which was published on the UKEB website. All responses were assessed, reflected as appropriate in the final comment letter and summarised in the Feedback Statement. |
| Mandatory | FCL approved by the UKEB in public meeting | To be completed: [A draft of the final comment letter was presented for approval to the Board at its 14 December 2023 public meeting. [The Board approved the final comment letter, subject to suggested amendments]. ] | |
| Mandatory | FCL submitted to the IASB and posted on UKEB website | To be completed: [The FCL was submitted to the IASB on [XX December 2023] and posted on UKEB website on [XX December 2023] The Board decided at its 19 October 2023 meeting 4 to have a 30-day consultation period for the DCL, acknowledging that the FCL would be submitted to the IASB [x days] after its submission deadline.] |
|
| Optional | News alert published to announce publication | To be completed: [A News Alert announcing publication of the FCL was published on [XX December 2023].] |
Feedback Statement
| Step | Mandatory / optional 1 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Feedback Statement [Handbook 5.19 to 5.22] | Mandatory | Feedback Statement approved by the UKEB in a public meeting | To be completed: [A draft of the Feedback Statement was presented for approval to the Board at its 14 December 2023 public meeting. [The Board approved the Feedback Statement, subject to suggested amendments].] |
| Mandatory | Feedback Statement posted on the UKEB website | To be completed: [The Feedback Statement was published on the UKEB website on [XX December 2023].] | |
| Optional | News alert published to announce publication | To be completed: [A News Alert announcing publication of the Feedback Statement was published on [XX December 2023].] | |
| Due Process Compliance Statement (DPCS) [Handbook 5.23 to 5.26] | Mandatory | DPCS approved by the UKEB in public meeting | To be completed: [A [draft] DPCS was presented for approval to the Board at its 14 December 2023 public meeting. A final DPCS was presented for noting at the Board's 30 January 2024 meeting.] |
| Mandatory | DPCS published on the UKEB website | To be completed: [The final DPCS was published on the UKEB website after the January 2024 Board meeting.] |
Ongoing communications
| Step | Mandatory / optional 1 | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Public board meetings [Handbook 4.10] | Mandatory | UKEB public meetings held to discuss technical project | Complete: The Board received an overview of the project in October 2023. The Board approved the PIP and DCL at its meeting on 19 October 2023 and [FCL at its meeting on 14 December 2023]. |
| Secretariat papers [Handbook 4.20] | Mandatory | Board meeting papers made available on the UKEB website usually no later than five working days before a Board meeting | Complete: The UKEB's meeting papers were published on the UKEB website 5 working days before the relevant public meetings. Meeting minutes and recordings were made publicly available via the UKEB website. Subscribers were notified via UKEB news alerts. |
Conclusion
This document sets out the main due process activities performed as part of the UKEB's due process to issue its comment letter in response to the IASB's ED.
This project complies with the applicable due process steps, as set out in the UKEB Due Process Handbook at the time of writing.
Footnotes
-
The IASB and IFRS Interpretations Committee Due Process Handbook (paragraphs 6.10 to 6.15) – Exposing annual improvements, August 2020 ↩↩↩↩↩↩↩↩
-
UKEB calculation based on London Stock Exchange Group (LSEG) and Eikon data, May 2023. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩↩
-
UKEB estimate based on FAME (company information in the UK and Ireland produced by Bureau Van Dijk, a Moody's analytics company), Company Watch financial analytics and other proprietary data. ↩↩↩
-
The IASB Exposure Draft Annual Improvements to IFRS Accounting Standards -Volume 11 can be accessed here. ↩
-
In accordance with the Due Process Handbook. ↩
-
In accordance with the UK Endorsement Board Due Process Handbook (paragraphs 5.13 to 5.17), a draft comment letter is issued in all circumstances unless impracticable. ↩
-
Paragraphs 4(c) and 4(d) in the Minutes of UKEB Public Meeting 19 October 2023 ↩