4 Lack of Exchangeability – Project Initiation Plan (PIP)
Executive Summary
| Project Type | Endorsement and Adoption |
| Project Scope | Narrow-scope |
| Purpose of the paper | This paper provides the Board with a proposed Project Initiation Plan (PIP) for the project to assess whether to adopt for use in the UK the narrow-scope amendments Lack of Exchangeability (Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates) issued by the IASB in August 2023.The Amendments have an effective date of 1 January 2025. |
| Summary of the Issue | The proposed PIP sets out the approach and timeline for the project to assess the amendments against the statutory adoption criteria1. The project plan proposes that the UKEB’s endorsement and adoption of the amendments will be completed following the June 2024 Board meeting. This should allow sufficient time for UK entities to be able to use them by the IASB’s effective date. |
| Decisions for the Board | The Board is asked whether it approves the proposed PIP. |
| Recommendation | The Secretariat recommends that the Board approves the proposed PIP. |
| Appendices | Appendix A Project Initiation Plan (Draft) |
Appendix A: Project Initiation Plan
| 1. Project Type | Endorsement and adoption |
| 2. Project Scope | Narrow-scope |
Purpose
A1This paper sets out the plan to assess whether to adopt for use in the UK1 the narrow-scope amendments Lack of Exchangeability (Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates) issued by the IASB in August 2023. These amendments contain guidance to specify when a currency is exchangeable and how to determine the exchange rate when it is not.
A2The Amendments have an effective date of 1 January 2025, with earlier application permitted (subject to the UKEB endorsement in the UK).
A3The Board actively influenced the development of these Amendments by submitting a Comment Letter3 in September 2021 in response to the IASB’s Exposure Draft ED/2021/4 - Lack of Exchangeability4.
A4The UKEB’s statutory functions mean that it must consider the Amendments against the statutory adoption criteria before their formal adoption for use in the UK. The Board’s aim would be to ensure adoption is completed in good time to permit UK entities to use the amendments on the IASB mandated effective date of 1 January 2025.
Background
A5The IFRS Interpretations Committee received a submission about the determination of the exchange rate when there is a long-term lack of exchangeability as IAS 21 The Effects of Changes in Foreign Exchange Rates does not include explicit requirements on the exchange rate an entity uses when the spot exchange rate is not observable.
A6To address this matter the IASB issued an Exposure Draft (ED) in April 2021 that proposed narrow scope amendments to IAS 21 Lack of Exchangeability. The amendments were intended to address diversity in practice and improve the usefulness of the information provided to the investors. The amendments required companies to use a consistent approach in assessing if there is lack of exchangeability between currencies, and when there is, the exchange rate to use and the related disclosures.
A7The final published amendments are generally consistent with the ED proposals. A summary of the main changes is included in Annex A of this paper.
Description of the Amendments to IAS 21
A8A brief description of the Amendments to IAS 21 is shown in the table below.
| Amendments to IAS 21 | |
| Issued for public comment | Exposure Draft ED/2021/4 Lack of Exchangeability (proposed amends to IAS 21)—issued for public comment in April 2021 (comment period ended on 1 September 2021)6. |
| Title and issue date of final amendments | Lack of Exchangeability (Amendments to IAS 21) issued in August 20237. |
| Origin | See Background on p.4 of the ED and the July 2021 UKEB Meeting, Agenda Paper 88 paragraphs 1–5 for further detail. |
| What has changed? | Amendments to IAS 21 The Effects of Changes in Foreign Exchange Rates |
| - Amend paragraph 8 and add paragraphs 8A and 8B to clarify that a currency is exchangeable when an entity is able to exchange it for another currency through markets or exchange mechanisms that create enforceable rights | |
| - and obligations without undue delay, at the measurement date and for a specified purpose. A currency is not exchangeable if an entity can only obtain an insignificant amount of the other currency. | |
| - Add paragraph 19A to make clear that when a currency is not exchangeable, an entity estimates the spot exchange rate that would have been applied to an orderly transaction between market participants at the measurement date and that would faithfully reflect the prevailing economic conditions. | |
| - Amend paragraph 26 to make clear that if there are multiple exchange rates available at the reporting date, the rate to use is that at which the future cash flows representing the transaction would be settled as if those cash flows have occurred at the measurement date. | |
| - Add paragraph 57A which requires disclosure of information about how a currency, not exchangeable into another currency, affects the entity’s financial position, financial performance and cash flows. This includes disclosing the nature and financial effects of the lack of exchangeability; spot exchange rates used; estimation process; and the risks entity is exposed because of the lack of exchangeability. | |
| - Add paragraph 57B that direct the entity to paragraphs A18-A20 for applying paragraph 57A. | |
| Appendix A Application guidance (for amendments to IAS 21) | |
| - Add Appendix A Application guidance as an integral part of IAS 21 to help entities assess whether a currency is exchangeable into another currency and to estimate the spot exchange rate when a currency is not exchangeable. | |
| Consequential amendments to IFRS 1 First-time Adoption of International Financial Reporting Standards | |
| - Amend paragraphs 31C (Use of deemed cost after severe hyperinflation) and D27 (Appendix D Exemptions from other IFRSs - Severe hyperinflation) and add paragraph 39AI (Effective date) to the IFRS 1 First-time Adoption of International Financial Reporting Standards to align the requirements related to severe hyperinflation to the amended IAS 21. | |
| Transition requirements | An entity shall apply those amendments for annual reporting periods beginning on or after 1 January 2025. If an entity applies the Amendments for an earlier period, it shall disclose that fact. |
| The entity shall not restate the comparative information when applying Lack of Exchangeability. Instead, the entity is required to translate the affected amounts at estimated spot exchange rates at the date of initial application, with an adjustment to either the retained earnings (if between foreign and functional currency) or the reserve for cumulative translation differences (if between functional and presentation currency). |
Project plan
A9The following factors have been considered when developing the project plan.
The Amendments are narrow in scope
A10The Amendments are focussed on clarifying how an entity can assess exchangeability, the exchange rate to use when the currency is not exchangeable, and additional disclosures to provide in those circumstances. Based on research and initial stakeholder feedback (see paragraphs A14-A15 and A29), this issue is relevant to only a few companies in the UK with operations in the countries where currencies are exposed to a long-term lack of exchangeability.
The Amendments have been subject to public consultation
A11The Amendments were issued for public comment as an Exposure Draft in 2021. They were considered by the UKEB, and the Board issued a comment letter to the IASB9.
A12Generally, feedback to the IASB from UK and international stakeholders (including the UKEB) supported the proposals, though many suggested various minor wording changes. The final amendments were published in 2023 and are not substantially different from those in the 2021 ED.
Proportionality
A13The UKEB Due Process Handbook, paragraph 3.710 notes that “the activities undertaken to achieve the milestones for each project should be proportionate to the significance, urgency, complexity (i.e., nature or scope), size, expected timeline and expected interest or controversy attached to the project”. The following assessment of factors suggests that these amendments are not complex, are largely consistent with current practice and will only affect a limited number of UK entities. Therefore, a limited set of activities are proposed.
The significance of the amendments
Prevalence in the UK/Size
A14Preliminary desk-based research and initial stakeholder feedback has indicated that only a few currencies or countries are expected to be subject to a lack of exchangeability.
- Venezuela has been specifically identified as a country where there is a lack of exchangeability.
- It has also been suggested that the Zimbabwe dollar may be subject to longer-term lack of exchangeability 11.
- Other countries noted as an example in the comment letters to the IASB ED were Argentina, Lebanon, Sudan, Malawi, and Mozambique.
A15The number of UK companies with operations in these areas is limited. Based on the limited research undertaken, we have identified the following UK companies that have operations in countries identified above:
- Venezuela: Shell, British American Tobacco, GlaxoSmithKline, AstraZeneca, Aggreko, Diageo, BT, and Unilever.
- Zimbabwe: Anglo American, Unilever, Standard Chartered Bank, Barclays Bank, Shell, Rio Tinto and British American Tobacco.
- Over 100 UK companies have a permanent presence in Argentina 12. This includes 20 FTSE 100 companies including BT, GSK, HSBC and Unilever, and a range of small and medium sized UK businesses.
A16Based on the evidence from this research, the Secretariat do not believe the amendments relate to a matter that is prevalent in the UK. Whilst, a number of UK companies that will be impacted, the size of the impact is not expected to be material.
Importance to Users
A17Information about assets and holdings subject to a lack of exchangeability could have a material impact on users’ understanding of the financial statements and therefore the decisions they make about allocation of their scarce resources.
A18We are not aware of significant concerns among users about the current accounting where there is a lack of exchangeability for UK entities.
A19The amendments appear to support enhanced consistency and disclosure that will be useful to users that are making decisions about entities with interests in impacted entities.
Impact on Preparers
A20For the preparers affected by the lack of exchangeability requirements limited outreach suggests that the amendments are largely consistent with current practice by UK entities.
A21The enhanced disclosure could require additional work for entities. However, it seems reasonable to expect the disclosures address factors they are already considering and should not place an unreasonable burden on those entities.
Need to Influence/Ability to adopt the amendments
A22Limited outreach and desk-based research has not identified significant concerns with the amendments that would suggest a technical issue that is likely to impact the ability of the UKEB to adopt the amendments.
Complexity of Topic
A23The nature of the amendments is not technically complex. The focus of the amendments is on the identification of circumstances where a currency lacks exchangeability. The amendments impact two IASB standards:
- IAS 21:
- amend paragraphs 8 and 26,
- add paragraphs 8A-8B, 19A, 57A-57B, 60L-60M and a new Appendix A (paragraphs A1-A20); and
- add illustrative examples (paragraphs IE1-IE18).
- IFRS 1:
- amend paragraphs 31C and Appendix D (paragraph D27); and
- add paragraph 39AI.
Expected Timeline/Urgency
A24The effective date is 1 January 2025, with early application permitted by the IASB. So far, there have not been any calls13 to accelerate the adoption for use in the UK.
Expected Interest/Sensitivity
A25We are not aware of wider political or other concerns in relation to this project.
Research, plan for outreach, and initial stakeholder feedback
A26We have used desk-based research such as accounting manuals, publications from the accounting bodies and communications with other national standard setter and limited stakeholder discussions to inform the development of the PIP.
A27Considering the factors outlined above, the Secretariat plans to conduct limited outreach for the development of draft Endorsement Criteria Assessment (DECA), in line with the UKEB Due Process Handbook (DPH). The minimum due process required by paragraph 6.21 of the DPH is:
As a minimum, Regulation 8 of SI 2019/685 requires the UKEB to consult with a representative range of stakeholders before adopting an international accounting standard. Publication of the DECA on the UKEB website and notifying UK stakeholders is expected to be sufficient in the following situations:
- When amendments to international accounting standards are minor and meet the criteria for annual improvements or for narrow-scope amendments.
A28In view of the assessment in paragraphs A14-A25, the Secretariat propose the following outreach:
- Pre-DECA publication
- an email to the companies specifically identified in paragraph A15, major accounting firms and the UK regulator in Q4 2023, without follow up.
- consultation with the UKEB’s Accounting Firms & Institutes Advisory Group (AFIAG), Investor Advisory Group (IAG) and Preparer Advisory Group (PAG); and
- Post-DECA publication
- announcement of DECA consultation through the usual channels. But no further additional stakeholder outreach.
A29Some preliminary outreach with affected UK stakeholders highlighted that they believe these amendments provide a significant improvement to IAS 21and have not noted any major concerns.
Project milestones
A30In line with the proposed proportionate approach, the table below provides a brief description of the work focused on the mandatory milestones listed in paragraph 6.11 of the DPH14.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Project initiation activities | ||
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30 (d)] | Added to UKEB technical work plan. | Completed. |
| Education session (optional) [Handbook 4.10] | Not proposed in light of UKEB’s previous influencing activities. | To be confirmed. |
| Project Initiation Plan (mandatory) [Handbook 6.11] | This paper. | - |
| Desk-based research [Handbook 6.17] | The Secretariat has reviewed: | Completed. |
| - The IASB’s work on the Amendments (mainly staff papers, ED feedback) and the Basis for Conclusions | ||
| - Comment letters on the ED from UK stakeholders | ||
| - Previous work done by the UKEB (early desk-based research, comment letters on our DCL, discussions with IASB) | ||
| - Relevant material produced by other parties, including accounting firms15 | ||
| Other mandatory milestones | ||
| Issue of a DECA (mandatory) [Handbook 6.23–6.26] | The Secretariat will develop a draft Endorsement Criteria Assessment (DECA) to assess whether the Amendments meet the UK’s statutory requirements for adoption. | To be completed. We expect to bring the DECA for discussion to the January 2024 meeting. |
| Minimum activities (mandatory) [Handbook 6.18 - 6.22] | Reach out directly to affected UK stakeholders already identified. Consultation with the UKEB Advisory groups, as appropriate. Publish DECA for stakeholder comment on the UKEB website. | To be completed. DECA publication for comment expected in early February 2024. Targeted outreach activities are ongoing and will continue during the DECA comment period. |
| Consultation period for the DECA [Handbook 6.28] | The DECA will be issued for comment for 90 days. | To be completed. DECA comment period expected to be early February 2024 - May 2024. |
| Project closure [Handbook 6.30] | The project closure comprises the following mandatory steps: | To be completed. Adoption Package for discussion and approval |
| - Preparation of an ‘adoption package’ by | the Secretariat comprising: the Final Endorsement Criteria Assessment (ECA), Feedback Statement, the Adoption Statement and a Due Process Compliance Statement for the project; and | |
| - Voting on the adoption of the Amendments. |
Resources allocated
A31On the basis of this project plan, we consider that a project team consisting of one Project Manager with oversight from a Project Director should be sufficient to ensure the project timelines are achievable.
A32In addition, we plan to obtain input from the economics team to assist in developing the contents of the economic impact assessment.
Setting-up an ad-hoc advisory group is not necessary
A33Given the narrow-scope nature of the Amendments and initial feedback, it is not considered necessary to set up a separate, ad-hoc advisory group specific for this project.
Project timeline
Endorsement and adoption stage
A34The plan proposes a final endorsement decision in July 2024. This allows for flexibility in preparing material for the Board for endorsement, sufficient time for stakeholder feedback (at a time that is likely to be more convenient to them) and leaves sufficient time for preparers to implement the amendments.
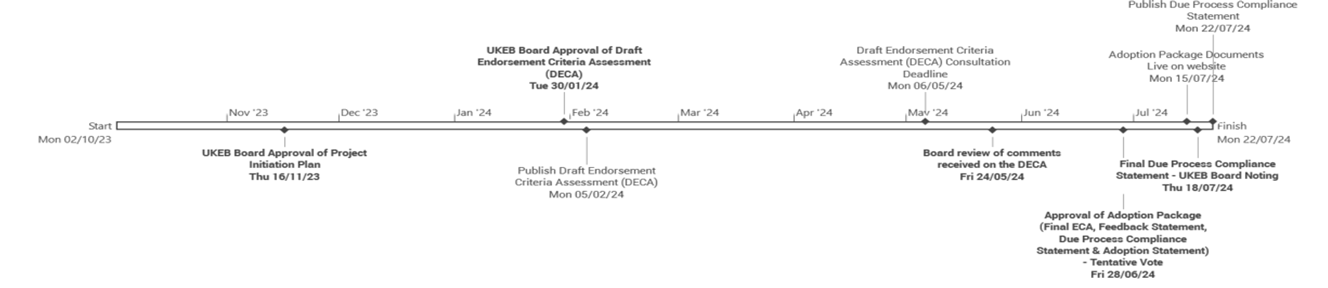
A35The proposed high-level project timeline is as follows:
| Date | Milestones |
|---|---|
| 16 November 2023 | Presentation of Project Initiation Plan (PIP) for approval |
| 30 January 2024 | Draft Endorsement Criteria Assessment (DECA) for approval |
| DECA consultation period (90 days): 5 February – 6* May 2024 | |
| 24 May 2024 | Board review of comments received on the DECA |
| 28 June 2024 | Consideration of Adoption Package |
| Early July | Board members provide a tentative vote |
| Mid of July | Voting form is sent to board members |
| 18 July 2024 | Publication of voting outcome and Adoption Package on the UKEB website |
| Due Process Compliance Statement for noting |
*TBC
Narrow-scope amendments to IAS 21: Lack of Exchangeability (effective date 1 January 2025) – Proposed timeline
Annex A: Summary of main changes to the ED
| Proposals in the ED | Stakeholder feedback | Final standard (main changes) |
|---|---|---|
| Definition of Exchangeability and factors for assessment16 | ||
| Definition of Exchangeability (Paragraph 8) | ||
| This paragraph adds a definition of 'exchangeable', which states: A currency is exchangeable into another currency when an entity is able to exchange that currency for the other currency. | Many respondents agreed with the proposed definition of ‘exchangeable’ and the factors an entity is required to consider in assessing whether a currency is exchangeable. Except few respondents who sought clarification on factors used to assess exchangeability. | The IASB clarified the guidance around the factors where stakeholders noted concerns. |
| Factors to consider (Paragraph A2-A11) | ||
| To make the definition proposed in paragraph 8 operational and to help entities apply that definition consistently, the Board proposed to specify when an entity is able (and thus unable) to exchange a currency for another currency by setting out five factors an entity considers in assessing exchangeability and to specify how those factors affect the assessment. | ||
| The five factors for assessing exchangeability are: | Based on feedback received, the IASB decided to clarify two of the five factors for assessing exchangeability. These are: | |
|
|
|
| Markets or exchange mechanisms (Paragraph A7) | (Paragraph A5 and A17) | |
| The Exposure Draft proposed adding requirements in paragraph A7 to state: In assessing whether a currency is exchangeable into another currency, an entity shall consider only markets or exchange mechanisms in which a transaction to exchange the currency for the other currency would create enforceable rights and obligations. Enforceability is a matter of law. Whether an exchange transaction in a market or exchange mechanism would create enforceable rights and obligations depends on facts and circumstances. |
|
The IASB on markets or exchange mechanisms:
|
| Ability to obtain only limited amounts of the other currency (Paragraph A11) | (Paragraph A10) | |
| The Exposure Draft proposed adding requirements in paragraph A11 to state: An entity may be able to obtain only limited amounts of the other currency. For example, an entity with a liability denominated in a foreign currency (FC1,000) may be able to obtain only FC50 to settle that liability. In such circumstances, a currency is not exchangeable into another currency when, for a purpose specified in paragraph A9, an entity is able to obtain no more than an insignificant amount of the other currency. An entity shall assess the significance of the amount of the other currency it is able to obtain for a specified purpose by comparing that amount with the total amount of the other currency required for that purpose. | Some respondents requested additional guidance on how to apply ‘no more than an insignificant amount’ and others commented that how to apply the aggregate model is unclear. | The IASB developed the following example of the 'aggregate method' as part of the application guidance. An entity with a functional currency of LC has liabilities denominated in currency FC. The entity assesses whether the total amount of FC it can obtain for the purpose of settling those liabilities is no more than an insignificant amount compared with the aggregated amount (the sum) of its liability balances denominated in FC. |
| Holistic consideration of factors when assessing exchangeability. | Feedback indicates that some respondents read the proposals to say that, in assessing exchangeability, each of the factors would be considered individually or separately, instead of holistically. | While the IASB clarified in its discussions that an entity is required to consider all factors when assessing exchangeability, and that the absence of one factor would indicate a lack of exchangeability, no |
| Appendix A Application guidance (Paragraph A1) | Noted above | additional material was added to the final standard. (Paragraph A1) The IASB simplified the diagram to make it easier to apply the requirements. |
| Determining the spot exchange rate when exchangeability is lacking17 | ||
| Objective (Paragraph 19A) | (Paragraph 19A) | |
| This paragraph states: When exchangeability between two currencies is lacking—that is, when a currency is not exchangeable into another currency (as described in paragraphs A2–A11) at a measurement date—an entity shall estimate the spot exchange rate at that date. The estimated spot exchange rate shall meet the following conditions assessed at the measurement date: (a) a rate at which an entity would have been able to enter into an exchange | Some respondents suggested revising the proposal to specify that the conditions are objectives an entity aims to meet when estimating the spot exchange rate, rather than requirements to be met. A few respondents said, when exchangeability is lacking, meeting the conditions in proposed paragraph 19A may be impracticable. | The IASB amended this paragraph to state that ‘an entity’s objective in estimating the spot exchange rate is to reflect at the measurement date the rate at which an orderly exchange transaction would take place between market participants under prevailing economic conditions. |
| transaction had the currency been exchangeable into the other currency; (b) a rate that would have applied to an orderly transaction between market participants; and (c) a rate that faithfully reflects the prevailing economic conditions. | ||
| Use of observable exchange rate (Paragraph 19B) | (Paragraph A11-A17) | |
| In estimating the spot exchange rate as required by paragraph 19A, an entity may use an observable exchange rate as the estimated spot exchange rate when that observable exchange rate meets the conditions in paragraph 19A and is either: (a) a spot exchange rate for a purpose other than that for which the entity assesses exchangeability; or (b) the first exchange rate at which an entity is able to obtain the other currency after exchangeability of the currency is restored (first subsequent exchange rate). | Some respondents noted the wording in paragraph 19B is unclear, other respondents including EEG and IFRIC members noted to require but not to permit the use of an observable exchange as the estimated spot exchange rate. | The IASB removed paragraph 19B and provided choices for estimating the exchange rate as part of the implementation guidance, not mandating the use of observable exchange rates in estimating the spot exchange rate. |
| Appendix A Application guidance (Paragraph A1) | Noted above | (Paragraph A1) The IASB simplified the diagram to make it easier to apply the requirements. |
Footnotes
-
The statutory adoption criteria are in Regulation 7 of The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 no. 685 (the Regulations, or SI 2019/685) ↩↩
-
IASB Final amendments – Lack of Exchangeability IAS 21 ↩
-
UKEB Final Comment Letter – Lack of Exchangeability (Proposed Amendments to IAS 21).pdf ↩
-
IASB Exposure Draft: Lack of Exchangeability IAS 21 ↩
-
IFRIC meeting June 2018 – Project IAS 21 Extreme long-term lack of exchangeability (agenda ref:2) ↩
-
IASB Exposure Draft: Lack of Exchangeability IAS 21 ↩
-
IASB Lack of Exchangeability Amendments to IAS 21 ↩
-
Paper 8: Lack of Exchangeability – UKEB Project Initiation Plan (Influencing) 20 July 2021 ↩
-
Feedback Statement - Lack of Exchangeability ↩
-
UKEB Due Process Handbook (December 2022) ↩
-
Guidance by the Institute of Chartered Accountants of Zimbabwe (ICAZ) on IAS 21 amendments: Lack of Exchangeability ↩
-
Department for Business & Trade - Exporting guide to Argentina ↩
-
The Secretariat asked the PAG and AFIAG explicitly if they were aware of any call from entities for early adoption of the amendments in the UK. Both indicated that they did not believe it was a concern in the UK. ↩
-
Due Process Handbook ↩
-
For example: BDO Bulletin - IASB issues amendments to IAS 21 – Lack of Exchangeability and Deloitte Lack of exchangeability Final amendments address when and how to estimate a spot rate (24 August 2023) ↩
-
IASB Staff paper: 12 A Topic: Assessing exchangeability between two currencies (December 2022) ↩
-
IASB staff paper: 12B Topic: Determining the spot exchange rate when exchangeability is lacking (December 2022) ↩