6 PIR of IFRS 15 RFI - Final Comment Letter
Executive Summary
| Project Type | Influencing—Post-implementation review |
|---|---|
| Project Scope | Moderate |
| Purpose of the paper |
The purpose of this paper is to obtain Board approval:
- of a Final Comment Letter (FCL) to the IASB on its Post-implementation Review (PIR) of IFRS 15 Revenue from Contracts with Customers;
- to publish the Feedback Statement; and
- of the draft Due Process Compliance Statement (DPCS).
Summary of the Issue
The IASB is undertaking a PIR of IFRS 15 to assess whether the new requirements are working as intended. The Request for Information (RFI) is seeking feedback on the IFRS 15 core principle and the five-step revenue recognition model, including the benefits to users of financial statements and the costs for preparers. Depending on responses, the IASB will consider what, if any, further action is required. The UKEB's Draft Comment Letter (DCL), was published for UK stakeholder comment on 27 July
- This consultation closed on 5 October 2023.
Further outreach since publication of the DCL has highlighted some additional issues, summarised in this paper.
Decisions for the Board
1.Which option does the Board choose relating to whether or not the FCL should include a recommendation to the IASB to consider a narrow-scope amendment to IFRS 3 Business Combinations, similar to the recent FASB amendment [ASU 2021-08], whereby the accounting for contract assets acquired and contract liabilities assumed in a business combination are required to be measured, on acquisition, in accordance with Topic 606 Revenue from Contracts with Customers?
2.Subject to any amendments arising at this meeting, does the Board approve:
- the FCL for issuance to the IASB and publication on the UKEB website?
- the Feedback Statement for publication on the UKEB website?
- the [draft] DPCS?
Recommendation
The Secretariat recommends that, subject to any amendments agreed at this meeting, the Board approves the FCL and Feedback Statement for issue and publication and approves the [draft] DPCS.
Appendices
- Appendix A Final Comment Letter
- Appendix B Feedback Statement
- Appendix C [Draft] Due Process Compliance Statement
Background
1.The IASB issued its RFI on the Post-implementation Review (PIR) of IFRS 15 Revenue from Contracts with Customers on 29 June 2023. The comment period ends on 27 October 2023.
2.The background to IFRS 15 can be found in the PIP. An education session on the PIR of IFRS 15 was provided to the Board during its private meeting in April 2023. The Secretariat conducted desk-based research, discussed the PIR with UKEB Advisory Groups, hosted a preparer roundtable and held one-to-one meetings with various stakeholders, including investor organisations.
3.The DCL was approved at the 13 July 2023 UKEB meeting and published on the UKEB website on 27 July 2023, with a comment deadline of 5 October 2023. The DCL noted that the standard is generally working as intended and included comments and recommendations on a few areas of concern raised by UK stakeholders that could potentially be resolved or improved by standard setting activity. UKEB news alerts and LinkedIn posts were used to raise awareness of the publication of the DCL.
Outreach on the DCL
4.Following publication of the DCL the Secretariat conducted further outreach activities to inform the FCL. This involved public consultation on the DCL, outreach meetings with stakeholders, and feedback from the Accounting Firms and Institutes Advisory Group (AFIAG) was sought in July 20231. Three written responses to the DCL were received and have been uploaded to the UKEB website. This number was not unexpected given the number of in-person meetings held to seek feedback on this project and the small number of concerns raised.
5.A summary of the feedback received during the consultation period and resulting changes to the comment letter can be seen in the Feedback Statement at Appendix B to this document. To assist board member review significant changes (excluding formatting and edits for clarity/brevity) have been highlighted in grey in the proposed FCL at Appendix A to this paper.
6.Two key issues that emerged subsequent to the issuance of the DCL are worth noting in a little more detail. These relate to ongoing costs from use of the standard and convergence with US GAAP.
Ongoing costs
7.Mixed views were received following the publication of the DCL regarding the ongoing costs to preparers. However, one accounting firm noted during our one-to-one that the involvement of experts to support preparers with the application of IFRS 15 can be costly. They provided a number of examples where ongoing costs remain significant. These included, companies with complex contracts, product offerings that change regularly or those with emerging business models. The companies with such contracts and business models that do not have the time and/or expertise to review new contracts in house call on external expertise at additional cost.
8.The draft FCL has been amended to include this additional stakeholder feedback. However, as this was part of the contextual information requested by the IASB, no specific proposals in relation to abating these costs in the future have been included.
Convergence with US GAAP
9.Whilst the IASB and FASB jointly developed the revenue recognition standards, FASB has subsequently made some changes which has meant that a degree of divergence between the requirements in US GAAP and IFRS has crept in.
Recent changes to US GAAP: Accounting for Revenue contracts acquired in a business combination
10.In October 2021, FASB issued the Accounting Standards Update (ASU) No. 2021-08 – Business Combinations (Topic 805) Accounting for Contract Assets and Contract Liabilities from Contracts with Customers. The amendment creates an exception to the general recognition and measurement principles of Topic 805 Business Combinations and requires an acquirer of a business to recognise and measure an acquiree’s contract assets and contract liabilities in a business combination on acquisition in accordance with Topic 606 – Revenue from Contracts with Customers. The amendment is effective for fiscal years beginning after 15 December 2022 or later2.
11.The change means that UK companies with dual listing, when reporting under US GAAP will no longer account for contract assets acquired and contract liabilities assumed in a business combination at fair value on the date of acquisition. Instead, those contract assets and liabilities will be accounted for as if the acquiring entity had entered into the contracts themselves, using the principles set out in the revenue recognition standard. These adjustments could affect both the amount of goodwill recognised on acquisition and the amounts of revenue that will be recognised on these contracts with customers in the future.
12.The FASB's intention in making the change to US GAAP is to have consistent and comparable accounting for contract assets and contract liabilities, regardless of whether an entity is acquired in a business combination. The amendment is intended to:
- avoid the complexities in valuing contract assets and contract liabilities at fair value and to address the diversity in accounting practice.
- improve comparability for users of financial statements prepared under US GAAP:
- making the post-acquisition reporting of cash-flows and revenue by the acquirer comparable to the pre-acquisition reporting by the acquiree, and
- between revenue contracts acquired in a business combination and those originated by the acquirer.
13.Further details of the FASB amendments are set out here.
Rfl on IFRS 15
14.In the RFI3, the IASB noted that initial feedback suggested that sometimes the difference between the measurement principles in IFRS 3 Business Combinations (based on fair value) and those in IFRS 15 (based on the transaction price) might create difficulties for entities when measuring contract assets and contract liabilities acquired as part of a business combination. Some stakeholders suggested that the IASB could consider resolving the difference between the requirements for measuring contract assets and contract liabilities in IFRS 15 and on acquisition under IFRS 3, noting the recent changes made by FASB.
15.Although, it was suggested that this matter is not pervasive and that the difference in requirements between IFRS 15 and IFRS 3 does not create significant issues for users of financial statements, the IASB is seeking stakeholders' feedback on whether the differences between the requirements in IFRS 3 and IFRS 15 lead to significant fair value adjustments on acquisition, the pervasiveness of the matter, the impact on entities' financial statements and the usefulness of the resulting information to users of financial statements.
16.We received limited feedback on this issue during our outreach. Other than accounting firms, no other UK stakeholders highlighted any concerns with the interaction of IFRS 15 and IFRS 3 or IFRS 13 Fair Value Measurement and none specifically mentioned the recent change to US GAAP or that they had any concerns. Two accounting firms noted that most of the time, for most acquisitions, the resulting difference in valuation methods (fair value versus transaction price) would not be material. The only example identified where a significant difference may arise was for a large acquisition where a large variable consideration constraint had been applied in measuring the revenue of a contract. Only one accounting firm requested that IASB maintain convergence with the FASB in this instance.
17.Currently there are only 26 UK listed companies with a dual listing in the US that are in turn required to file annual reports with the S.E.C. This number has been steadily declining over recent years.
18.The majority of UK companies preparing accounts under IFRS may be negatively impacted by a change to IFRS if they undertook a business combination; such a change would require those companies to account for contract assets acquired and contract liabilities assumed under that business combination at transaction price (using the principles of IFRS 15) on acquisition, as opposed to fair value, whilst other assets acquired/liabilities assumed would be accounted for at fair value. The acquirer cannot simply carry over the acquiree's balances, but rather it needs to assess how the acquiree applied Topic 606 to identify differences with the acquirer's accounting policies, estimates and judgments, as well as any errors in the acquiree's accounting.
19.The table below sets out the pros and cons of the two possible recommendations to the IASB – either to amend the requirements of IFRS 3 to ensure consistency with US GAAP, or not amend:
| Option A: No amendments to IFRS 3 | Option B: A narrow-scope amendment to IFRS 3 |
|---|---|
| Pros | Pros |
| - No concern raised in the UK in relation to any inconsistency between IFRS 3 and IFRS 15. The PIR of IFRS 3 concluded that fair value remains the best approach4 | - Maintains convergence with US GAAP. |
| - There is no call for a change in position from other international users of IFRS – feedback on the March 2020 Discussion paper Business Combinations— Disclosures, Goodwill and Impairment5 did not highlight new information that would suggest the IASB needs to reopen this question as part of its Goodwill and Impairment project. | - Improves comparability for users of financial statements prepared under US GAAP and IFRS. |
| - Conceptually, under IFRS contract assets and liabilities acquired in a business combination are required to be measured at fair value at the acquisition date and there is no difference between contract assets/liabilities and any other asset/liability acquired in a business combination. | - UK companies with dual listings in the US will not be required to prepare a reconciliation to reflect this difference in the instance that they undertake a transaction that leads to a material difference as identified above. |
| Cons | Cons |
| - Fair value adjustments related to acquiree assets and liabilities show that the entity has acquired these assets and liabilities rather than creating them and so entity's performance is depicted differently. | - An amendment would not improve the accounting for business combinations under IFRS. |
| - Leads to divergence between IFRS and US GAAP. | - An amendment to IFRS would not meet the objective of financial reporting6 of providing more decision-useful information - financial statements should provide information that is useful in assessing not only an entity's prospects for future net cash inflows, but also “how efficiently and effectively the entity's management and governing board have discharged their responsibilities to use the entity's economic resources”. |
| - Fair value adjustments related to acquiree assets and liabilities can distort the depiction of an entity's performance as it is depicted differently depending on whether growth has occurred organically or via a business combination. | - Measuring contract assets acquired and contract liabilities assumed in a business combination under the revenue standard, eliminates key decision-useful fair value information that is necessary to evaluate the soundness of managers' business acquisition decisions. |
| - Simply carrying over the acquiree's pre-acquisition measures of contract assets and liabilities to the post-acquisition financial statements of an acquirer, does not faithfully represent the economics of a business acquisition transaction and could result in an overstatement of post-acquisition revenues and income7. | |
| - Potential overstatement of post-acquisition revenues and income by the acquirer resulting from carrying over the acquiree's basis may create perverse incentives for entities to "buy revenues”8. | |
| - An increase in contract liabilities9 (related to the application of carryover basis measurement), as opposed to fair value measurement often will produce an offsetting increase in goodwill. | |
| - The resulting effects of an amendment to IFRS on post-acquisition revenues and income may be immaterial and/or will not be transparent to investors and other users of the financial statements. | |
| - The change may impose additional cost for UK companies with no listings in the US, for no clear additional benefit. |
Options
20.On balance, the Secretariat do not consider that the Board should propose an amendment to the IASB to maintain convergence with US GAAP in this instance. This is based on the fact that no significant concerns were raised by IASB's stakeholders in relation to these proposals, in spite of the opportunities provided on three different recent consultations, the fact that the change will lead to a brand new inconsistency with the Conceptual Framework and that the resulting effects are only likely to occur in exceptional circumstances and, when they do occur, their effects will not be transparent or decision-useful to investors.
21.The suggested paragraphs to be included in the FCL (Appendix A) are included in that document and highlighted in grey and in brackets.
Questions for the Board
1.Which option would the Board like to reflect in the final comment letter?
Final Comment Letter (FCL)
22.The FCL is attached at Appendix A for consideration and, subject to any amendments at the meeting, approval for issuance to the IASB and publication on the UKEB website.
Feedback Statement
23.The Feedback Statement is attached at Appendix B for consideration and, subject to any amendments at the meeting, approval for publication on the UKEB website.
Due Process Compliance Statement (DPCS)
24.The [draft] DPCS is attached at Appendix C for consideration and, subject to amendments agreed by the Board, approval. A final version for noting will be brought to the 16 November 2023 meeting once the final project steps are complete.
Questions for the Board
2.Subject to any amendments agreed at this meeting, does the Board approve:
- The FCL for issue to the IASB and publication on the UKEB website?
- The Feedback Statement for publication on the UKEB website?
- The [draft] DPCS for the project?
Next steps
25.The FCL will be submitted to the IASB by 27 October 2023. The FCL together with the Feedback Statement will be published on the UKEB website. The DPCS will be updated to reflect the final project steps and presented to the 16 November 2023 meeting for noting.
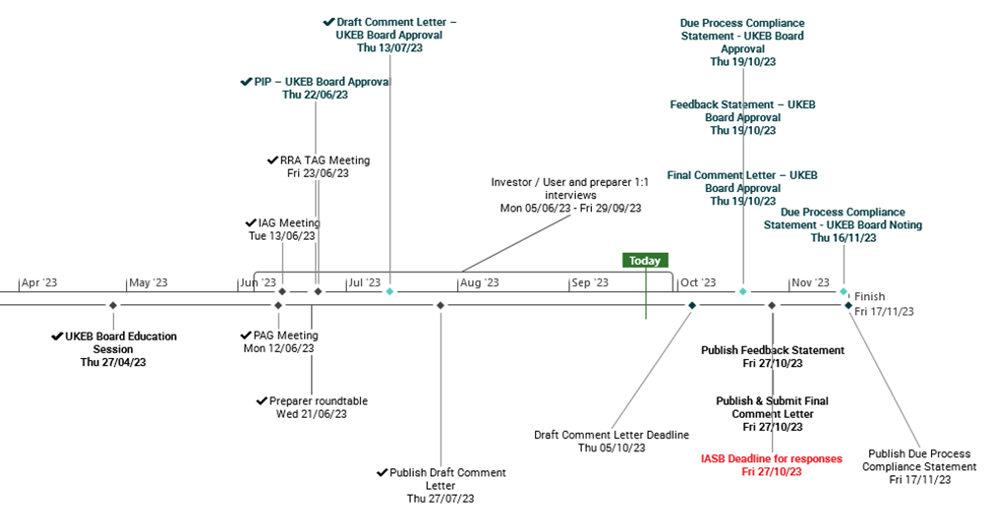
PIR of IFRS 15 Revenue from Contracts with Customers Timeline
| Influencing | Milestone – Brief description | Status |
|---|---|---|
| November 2022 | Outreach with UKEB Accounting Firms and Institutes Advisory Group (AFIAG) | Completed |
| 27 April 2023 | Board: Education session | Completed |
| June 2023 | Outreach with UKEB advisory/working groups | Completed |
| 22 June 2023 | Board: Approves the Project Initiation Plan (PIP) | Completed |
| 29 June 2023 | IASB publishes Request for Information | Completed |
| June – September 2023 | Further outreach as described in the PIP | Completed |
| 13 July 2023 | Board: Approves Draft Comment Letter (DCL) for publication | Completed |
| 27 July 2023 | DCL published, comment period 70 days | Completed |
| 19 October 2023 | Board: Considers and approves the Final Comment Letter (FCL), Feedback Statement, draft Due Process Compliance Statement (DPCS) Secretariat: Revises documents for any Board comments and submits FCL to the IASB by 27 October 2023 |
This meeting |
| 16 November 2023 | Board: Approves final Due Process Compliance Statement. | To be completed |
Timeline
Dr Andreas Barckow Chair International Accounting Standards Board Columbus Building 7 Westferry Circus Canary Wharf London E14 4HD
27 October 2023
Dear Dr Barckow
Invitation to Comment: Request for Information – Post-implementation Review of IFRS 15 Revenue from Contracts with Customers
1.The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2.There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.10 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.11
3.We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Request for Information-Post-implementation Review: IFRS 15 Revenue from Contracts with Customers (RFI). In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts. 10 South Colonnade
| London | E14 4PU [email protected]
Footnotes
Invitation to Comment: Request for Information – Post-implementation Review of IFRS 15 Revenue from Contracts with Customers
1The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
2There are currently approximately 1,500 entities with equity listed on the London Stock Exchange that prepare their financial statements in accordance with IFRS.10 In addition, UK law allows unlisted companies the option to use IFRS and approximately 14,000 such companies currently take up this option.11
3We welcome the opportunity to provide comment on the International Accounting Standards Board (IASB)'s Request for Information-Post-implementation Review: IFRS 15 Revenue from Contracts with Customers (RFI). In developing this letter, we have consulted with stakeholders in the UK, including preparers, accounting firms and institutes, and users of accounts.
4Based upon the work undertaken we conclude the following:
- The feedback we have received is consistent with the IASB's statement in the RFI that 'initial feedback suggests that IFRS 15 has achieved its objective and is working well, though some stakeholders still find applying aspects of the requirements challenging'.
- The implementation of the standard was costly for companies in some industries, (e.g. telecommunications, aerospace). In addition, the ongoing costs of applying IFRS 15 in those industries continue to be significant (see Appendix A paragraph A4).
- Overall users highlight a notable improvement in the usefulness of company disclosure about revenue subsequent to the implementation of IFRS 15.
- The transition requirements in IFRS 15 achieved an appropriate balance between reducing costs for preparers of financial statements and providing useful information to users of financial statements.
- Preparers, particularly UK groups with US listings, and users of their financial statements, support retaining the current level of convergence between IFRS 15 and Topic 606.
5Our recommendations are limited to the areas set out below:
- regarding determining the transaction price, we recommend that the IASB clarify the guidance on consideration payable to a customer to reduce the diversity in accounting practice as to when consideration payable, including negative revenue, is netted against revenue and when it is presented as an expense (see Appendix A paragraphs A8-A9);
- regarding principal versus agent considerations, we recommend that the IASB:
- expand the indicators of control in assessing if an entity is a principal (IFRS 15 paragraph B37) to cover indicators that are more relevant to services and intangibles; and
- elevate paragraph B385H from the Basis for Conclusions to the application guidance of the standard to note the importance of the primary assessment of transfer control and that the indicators of control are secondary in the assessment;
- [see paragraphs 9-21 of cover paper and Appendix A paragraph A29 for options]
- we recommend that the IASB and the FASB continue to work together to ensure that there are no significant differences between the two standards (see Appendix A paragraphs A30-A33).
6For detailed responses to the questions in the IASB's RFI, please see Appendix A.
7If you have any questions about this response, please contact the project team at [email protected].
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix A: Questions on Request for Information: Post-implementation Review IFRS 15 Revenue from Contracts with Customers
Overall assessment of IFRS 15
| Question 1—Overall assessment of IFRS 15
| Question 1—Overall assessment of IFRS 15 |
|------------------------------------------|
| |
</div>
19 October 2023
Agenda Paper 6: Appendix A
### Convergence with Topic 606 {: #convergence-with-topic-606 }
<div class="table-container" markdown="1">
| Question 10—Convergence with Topic 606 |
|----------------------------------------|
| a) How important is retaining the current level of convergence between IFRS 15 and Topic 606 to you and why? |
</div>
<a class="section__global-number" href="#paragraph-A30" id="paragraph-A30">A30</a>The requirements in both standards are substantially converged given that they were developed jointly by the IASB and FASB. There have been a small number of amendments since their publication.
<a class="section__global-number" href="#paragraph-A31" id="paragraph-A31">A31</a>During our outreach, preparers from UK groups with listings in the US supported retaining the current level of convergence between IFRS 15 and Topic 606. Acknowledging the existing level of divergence, one preparer stakeholder noted that further convergence should occur only if the result provides better information to users of the financial statements.
<a class="section__global-number" href="#paragraph-A32" id="paragraph-A32">A32</a>Users who assess US companies and companies reporting under IFRS are in favour of retaining the existing level of convergence between IFRS and US GAAP, as it ensures better comparability of revenue recognition between US companies and companies in other jurisdictions.
<a class="section__global-number" href="#paragraph-A33" id="paragraph-A33">A33</a>We recommend that the IASB and the FASB continue to work together to ensure that there are no significant differences between the two standards.
### Other matters {: #other-matters }
<div class="table-container" markdown="1">
| Question 11—Other matters |
|---------------------------|
| a) Are there any further matters that you think the IASB should examine as part of the post-implementation review of IFRS 15? If yes, what are those matters and why should they be examined? |
| Please explain why those matters should be considered in the context of this post-implementation review and the pervasiveness of any matter raised. Please provide examples and supporting evidence. |
</div>
<a class="section__global-number" href="#paragraph-A34" id="paragraph-A34">A34</a>We have not identified any further matters in the UK that we think the IASB should examine.
IASB Post-implementation Review (PIR)
IFRS 15 Revenue from Contracts with Customers
October 2023
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
The comment letter to which this feedback statement relates forms part of those influencing activities and is intended to contribute to the IFRS Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended international accounting standards undertaken by the UKEB.
[TOC]
## Purpose of this feedback statement
This feedback statement presents the views of UK stakeholders received during the UKEB's outreach activities on the IASB's Post-implementation Review (PIR) of IFRS 15 Revenue from Contracts with Customers and explains how the UKEB's Final Comment Letter addressed those views.
## The IASB's Post-implementation Review
In June 2023, the IASB published the Request for Information on the Post-implementation Review (PIR) of IFRS 15.
The PIR assesses whether the standard is meeting its objectives, can be applied consistently, provides useful information to users, and implementation costs are as expected. The IASB's possible actions following the PIR are to:
<ol markdown="1" type="a">
<li markdown="1">produce educational materials;</li>
<li markdown="1">conduct follow-up research work for possible standard setting; or</li>
<li markdown="1">take no action</li>
</ol>
The IASB's Request for Information (RFI) identified nine areas of the revenue requirements in IFRS 15 on which it was seeking feedback. The UKEB comment letter was responsive to UK stakeholder feedback and focused only on those areas where UK stakeholders expressed particular concerns.
## UKEB Outreach approach
The UKEB's outreach activities took place between June and October 2023 and were conducted to assist the UKEB in developing its Comment Letter.
The outreach approach was underpinned by the UKEB's guiding principles of thought leadership, transparency, independence and accountability.
Due to the project timeline most outreach activities were performed in the early stages of the project and the stakeholder views reflected in the DCL.
Outreach activities included:
* meetings with preparers, users, accounting firms and regulators, including discussions with the UKEB Advisory Groups and UKEB Rate-regulated Activities Technical Advisory Group;
* a roundtable event with preparers; and
* public consultation on the UKEB's draft comment letter.
Three written responses to the UKEB's Invitation to Comment on its DCL were received. These are included in the stakeholder outreach statistics shown in the table.
All comments and views were considered in reaching the UKEB final views on the questions raised.
<div class="table-container" markdown="1">
| Stakeholder type | Stakeholders | Organisations represented |
|--------------------------|--------------|---------------------------|
| Preparers | 17 | 11 |
| Auditors & Accounting firms | 8 | 5 |
| Regulators/ Standard setters | 5 | 3 |
| Users | 3 | 2 |
| Academics | - | - |
| Professional bodies / committees* | 1 | 8 |
</div>
*Those committees have multiple members, representing a variety of stakeholder types.
Note: UKEB Advisory Groups are not included in the above table, although one-to-one meetings with, or written responses from, members are included.
## 1. IFRS 15's overall assessment {: #section-1-ifrs-15-overall-assessment }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| Stakeholders noted that the Standard was generally working as intended and did not contain any “fatal flaws”. The IFRS 15 requirements were an improvement on the previous revenue requirements. | Noted the Standard is working as intended, did not contain “fatal flaws” and the core principles result in useful information about an entity's revenue from contract with customers. | Consistent with initial views. | Consistent with draft position. |
| | Highlighted a number of benefits for companies resulting from the implementation of IFRS 15 e.g. improved internal controls. | | |
| Views were mixed on improving the understandability and accessibility of the Standard. Whilst some preparers said the IASB should provide education materials and flowcharts explaining the links between the requirements, others were of the view that, given the standard has been applied for a number of years, the usefulness of such education materials is limited. | Noted mixed views on improving the understandability and accessibility of the Standard but did not recommend education materials. | Views were mixed: whilst a few stakeholders thought further illustrative examples would be helpful to improve understanding of specific areas of the standard, most agreed with the UKEB draft position. | Consistent with draft position. |
| Views were mixed regarding the ongoing costs and benefits of applying the requirements in IFRS 15. Whilst a preparer from the telecommunications industry indicated that the ongoing costs of applying IFRS 15 are significantly greater than expected for the benefits of the resulting information to users, others said the ongoing costs are not significant for their companies given the relatively simple business model. | Noted that preparers in some industries (e.g. telecommunications and aerospace) expressed the view that the ongoing costs of applying IFRS 15 continue to be significant. | Mixed views. Some stakeholders emphasised the significant ongoing costs of applying IFRS 15. In particular, these costs are relevant for companies with large volumes of contracts or complex contracts and for emerging business models. | Consistent with the draft position, but added text to provide further information on the nature of companies impacted by increased on-going costs. |
| | | Some other stakeholders noted that whilst implementation was a costly exercise, the ongoing cost is not significant. | |
</div>
## 2. Identifying performance obligations in a contract {: #section-2-identifying-performance-obligations-in-a-contract }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|---------------------------------|---------------------------------|
| Stakeholders noted that identifying performance obligations in a contract is an area of the Standard that involves significant judgement, in particular applying the concept of 'distinct' to determine whether a separate performance obligation exists. | Noted that overall IFRS 15 provides a clear and sufficient basis to identify performance obligations. | Consistent with initial views. | Consistent with draft position. |
| Overall, most stakeholders thought the guidance in the Standard is sufficient and the challenges raised result from the need to apply judgement to complex contracts. | Observed a number of challenges associated with identifying performance obligations for certain contracts, specifically identifying a 'distinct' good or service (or a bundle of services). | | |
</div>
## 3. Determining the transaction price {: #section-3-determining-the-transaction-price }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|-----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| A few stakeholders who provided feedback noted that IFRS 15 provides a clear and sufficient basis to determine the transaction price in a contract. | Noted that overall IFRS 15 provides a clear and sufficient basis to determine the transaction price in a contract. | Further Stakeholder feedback observed that the guidance on consideration payable to a customer can be difficult to apply and recommended the IASB clarify the guidance to reduce diversity in practice. Particular examples provided were on an amount payable to a customer not treated as consideration payable to a customer and the presentation of net 'negative' revenue as part of revenue or expense. | Updated the draft position, suggesting clarification to the guidance on consideration payable to a customer and presentation of 'negative' revenue, given the diversity in practice. |
| | Noted that little feedback was received on this topic. | | |
| The UK regulator observed that preparers find the language used in the Standard on constraining estimates of variable consideration unnecessarily complicated. | Noted the language used in the Standard on constraining estimates of variable consideration is unnecessarily complicated. | Stakeholders did not provide examples where the requirements for constraining estimates of variable consideration are unclear. | Consistent with draft position. |
</div>
## 4. Determining when to recognise revenue {: #section-4-determining-when-to-recognise-revenue }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|-----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------|---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| Stakeholders explained that it was challenging to make an initial assessment of whether revenue should be recognised over time or at a point in time, in particular in the software development and utility industries and for long term, developmental contracts or complex contracts. | Noted that significant judgement is required to identify whether control passes to the customer over time or at a point in time. | Consistent with initial views. | Enhanced the draft position to add an example to clarify the diversity in practice and a conclusion that UKEB is unable to ascertain how widespread the diversity is or whether users are concerned about it. |
</div>
## 5. Principal versus agent considerations {: #section-5-principal-versus-agent-considerations }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| Stakeholders indicated that this area of the standard is inherently challenging and judgemental to apply in practice. | Noted that stakeholders clearly identified principal versus agent considerations as an area of IFRS 15 that is challenging and requires significant judgement. | Stakeholders suggested certain paragraphs in the Basis for Conclusion, on the Standard relating to the primacy of the assessment of the transfer of control principle, be incorporated in application guidance in the Standard. | Builds upon the draft position to expand the indicators. The final letter:<ul markdown="1"><li markdown="1">provides examples of possible additional indicators</li><li markdown="1">requests certain paragraphs in the Basis for Conclusion, on the primacy of the assessment of the transfer of control principle, be incorporated in the Standard.</li></ul> |
| Stakeholders noted the lack of indicators for identifying a principal relating to intangibles, such as media content, with inventory risk being less relevant in intangible and service-based industries. | Recommended the IASB considers expanding the indicators of control in assessing if an entity is a principal, to cover indicators that are more relevant to services and intangibles. | Other stakeholders agreed with UKEB recommendation to expand the indicators of control. | |
| Some preparers were concerned that any changes to the requirements relating to principal versus agent consideration might result in companies reassessing their previous judgements. | | Two accounting firms noted that the current guidance should be unchanged, raising concern on cost of changes for stakeholders and the risk of unintended consequences. | |
| One accounting firm indicated challenges in the gaming industry in applying the requirements on principal versus agent considerations when identifying the customer. | This topic related to an application issue that was not included in the draft comment letter given that other stakeholders in our outreach did not comment on this issue. | One stakeholder from the pharmaceuticals industry emphasised that identifying the customer can be challenging for some arrangements. | Consistent with draft position. |
</div>
## 6. Licensing {: #section-6-licensing }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|------------------------------------------------------------------------------------------------------------------------------------------------------------------------|-------------------------------------------------------------------------------------------------------------------------------|-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| Stakeholders indicated that overall the guidance on licensing in IFRS 15 is useful and the guidance on the 'right to use' and 'right to access' is clear and sufficient. | Noted the Standard provides a clear and sufficient basis for accounting for contracts involving licences. | One stakeholder from the pharmaceuticals industry further observed a few application challenges on transition to the Standard in applying the requirements for licensing, in particular the criteria to determine whether the nature of a licence is to provide a right to access or a right to use the entity's intellectual property (IP). That preparer further noted IFRS 15 led to different accounting for economically the same transactions - sales-based royalties versus legal asset divestment. Feedback from some accounting firms noted the lack of guidance on licence renewals and suggested minor amendments to the guidance to cover licence renewals, to specifically require revenue to be deferred until the renewal period begins, not when the renewal is agreed. This would reduce diversity in practice. | Further stakeholder feedback identified application issues. We have included these examples in the UKEB comment letter. No amendments were proposed on licence renewals as this point was not raised by other stakeholders. |
</div>
## 7. Disclosure requirements {: #section-7-disclosure-requirements }
<div class="table-container" markdown="1">
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|-----------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|-----------------------------|---------------------------------|
| Generally, users and regulators noted improvement in the usefulness of information disclosed about revenue under IFRS 15. | Noted that some users of financial statements, regulators and accounting firms observed some improvement in the usefulness of information entities disclosed about revenue after IFRS 15 was implemented. | Consistent with initial views | Consistent with draft position |
| Some preparers found some disclosures onerous (e.g. the contract asset and contract liabilities reconciliation, and remaining performance obligations) and questioned the relevance of these disclosures to users. | This topic was not included in the draft comment letter given the usefulness of these disclosures for users. | Consistent with initial views | Consistent with draft position |
</div>
8. Transition requirements
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Preparers supported the choice in transition methods allowed under the Standard. | Noted that the modified retrospective method and practical expedients were commonly applied on the transition to IFRS 15. | Limited feedback on transition. | Consistent with draft position. |
| Most preparers indicated they used the modified retrospective method, and that the practical expedients reduced the cost and burden of transition to IFRS 15. | Noted that whilst users would prefer a full retrospective method, they did not have significant concerns with companies using the modified retrospective method. | ||
| A few preparers indicated the full retrospective method was used given the availability of data. | |||
| Users said a full retrospective method is always preferable for their analysis but did not express any concern with the modified retrospective method. |
9. Applying IFRS 15 with other IFRS Accounting Standards
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position | |:--------------------------------------------------------------|:-------------------------------------------------------------------------------------------------------------------------------------------|:-------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|:---------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------- | Initial views | Draft position | Consistent with initial views | Consistent with draft position | | The IFRS 15 PIR does not contain any evidence or findings about the impact of the Standard on capital allocation decisions. | The comment letter did not include any comments on capital allocation. | Consistent with initial views | Consistent with draft position | | A few stakeholders, mostly preparers, found that the application guidance in IFRS 15 was helpful when implementing the Standard. | Noted that some preparers found the application guidance helpful. | Consistent with initial views | Consistent with draft position | | Some stakeholders, including some accounting firms, observed that auditors applied IFRS 15 robustly which improved the quality of information disclosed about revenue. | Noted that auditors applied IFRS 15 robustly, improving the quality of information disclosed about revenue. | Consistent with initial views | Consistent with draft position |
10. Convergence with Topic 606
| Initial stakeholder views | UKEB draft position | Further stakeholder views | UKEB final position |
|---|---|---|---|
| Some stakeholders commented on the importance of convergence with Topic 606 e.g. improved comparability of revenue recognition across entities, industries, jurisdictions and capital markets. | Recommended that the IASB and the FASB continue to work together to ensure that there are no significant differences between the two standards | Stakeholders further emphasised the importance of convergence with Topic 606. | [Consistent with draft position.] |
| A few stakeholders thought the IASB should consider amending IFRS 15 to converge with US GAAP only if the amendment would significantly improve consistency of application and the usefulness of the resulting information. |
Disclaimer
1This feedback statement has been produced in order to set out the UKEB's response to stakeholder comments received on the UKEB's project responding to the IASB's Request for Information Post-implementation Review IFRS 15 Revenue from Contracts with Customers and should not be relied upon for any other purpose.
2The views expressed in this feedback statement are those of the UK Endorsement Board at the point of publication.
3Any sentiment or opinion expressed within this feedback statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board 6th Floor
| 10 South Colonnade | London
| E14 4PU | United Kingdom
Appendix C: [Draft] Due Process Compliance Statement: Post-implementation Review of IFRS 15 Revenue from Contracts with Customers
IASB's due process document
| Request for Information Post-implementation Review of IFRS 15 Revenue from Contracts with Customers | Published: 29/06/2023 |
|---|---|
| Comment deadline: 27/10/2023 |
General UKEB requirements: The UKEB adopts international accounting standards for use within the UK, in accordance with SI 2019/685 and applies its own processes before it decides to endorse and adopt a new or amended international accounting standard.
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Work plan | |||
| Technical project added to UKEB technical work plan [Due Process Handbook (DPH) [4.29] | Mandatory | Project is included in the UKEB published technical work plan. | Complete: The Post-implementation review (PIR) was included in the UKEB technical work plans from October 2022. |
1 In accordance with the Due Process Handbook.
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments |
|---|---|---|---|
| Project preparation [Handbook 5.4 to 5.8] | |||
| Project Initiation Plan (PIP) [DPH 5.4 to 5.8] | Mandatory | PIP draft with project outline (background, scope, project objective) and approach to influencing (key milestones and timing) proportionate to the project | Complete: taking a proportionate approach, the Secretariat included mandatory milestones for the project and considered, as appropriate, other milestones and activities. |
| Mandatory | Outreach plan for stakeholders and communication approach outlined | Complete: this plan was outlined in the PIP. In addition the Secretariat published a project webpage on the UKEB website. | |
| Mandatory | Resources allocated | Complete: One project director supported by one project manager, with communications and oversight from a Senior Project Director, as described in the PIP. | |
| Mandatory | Assessment of whether to set up an ad-hoc advisory group | Complete: Given the scope and nature of the project, it was not considered necessary to set up a separate, ad-hoc advisory group as the existing UKEB Advisory Groups are well placed to provide feedback on this project. | |
| Mandatory | UKEB Board public meeting held to approve PIP | Complete: The PIP was approved at the 22 June 2023 Board meeting. |
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments | Initial Initial views | | UKEB response to topics related to the PIR of IFRS 15 | | UKEB response | | Some preparers noted that a few topics in IFRS 15 were difficult to implement and required extensive use of judgement (e.g. identifying separate performance obligations, revenue recognition for variable consideration, the recoverability assessment of contract assets). | Noted that some topics in IFRS 15 were difficult to implement and required extensive use of judgement (e.g. identifying separate performance obligations, revenue recognition for variable consideration, the recoverability assessment of contract assets). | Consistent with initial views | Consistent with draft position | | Some users observed that entities applied IFRS 15 consistently, which improved the comparability of information disclosed about revenue. | Noted that some users observed that entities applied IFRS 15 consistently, which improved the comparability of information disclosed about revenue. | Consistent with initial views | Consistent with draft position | | Generally, users and regulators noted improvement in the usefulness of information disclosed about revenue under IFRS 15. | Noted that some users of financial statements, regulators and accounting firms observed some improvement in the usefulness of information entities disclosed about revenue after IFRS 15 was implemented. | Consistent with initial views | Consistent with draft position | | Some preparers found some disclosures onerous (e.g. the contract asset and contract liabilities reconciliation, and remaining performance obligations) and questioned the relevance of these disclosures to users. | This topic was not included in the draft comment letter given the usefulness of these disclosures for users. | Consistent with initial views | Consistent with draft position | | The IFRS 15 PIR does not contain any evidence or findings about the impact of the Standard on capital allocation decisions. | The comment letter did not include any comments on capital allocation. | Consistent with initial views | Consistent with draft position | | A few stakeholders, mostly preparers, found that the application guidance in IFRS 15 was helpful when implementing the Standard. | Noted that some preparers found the application guidance helpful. | Consistent with initial views | Consistent with draft position | | Some stakeholders, including some accounting firms, observed that auditors applied IFRS 15 robustly which improved the quality of information disclosed about revenue. | Noted that auditors applied IFRS 15 robustly, improving the quality of information disclosed about revenue. | Consistent with initial views | Consistent with draft position |
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments | | UKEB Education Session or Initial Assessment | | Project preparation (continued) [Handbook 5.4 to 5.8] | | Education sessions [DPH 4.10] | Optional | UKEB education or initial assessment | Complete: An education session on the proposals was presented at the 27 April 2023 Private Board meeting covering background information on IFRS 15 and the PIR. | | Desk-based research [DPH 5.9] | Optional | Identify relevant research sources and documents | Complete: The Secretariat has reviewed:
- The IASB's work on the Rfl (staff papers, draft Rfl);
- Accounting manuals and press releases for guidance and illustrative examples;
- IFRS Interpretations Committee Agenda Decisions relating to IFRS 15; and
- FRC thematic reviews of IFRS 15 disclosures undertaken in 2018, 2019, and 2020.
22 June 2023: the Board approved the PIP.
13 July 2023: the Board discussed and approved the Draft Comment Letter (DCL) for consultation. |
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments |
| Communications (continued) | | |
| Outreach activities [DPH 5.11] | Mandatory | Gather input from users, preparers and accounting firms and institutes, as outlined in the PIP. | Complete: Around 40 stakeholders, representing users of financial statements, preparers of financial statements, accounting firms and regulators were consulted during the project. Further detail can be found in the Feedback statement.
The UKEB received three comment letters which are published on the UKEB website. |
| Preparation of documents for public comment | | |
| UKEB response to topics related to the PIR of IFRS 15 | Noted that some topics in IFRS 15 were difficult to implement and required extensive use of judgement (e.g. identifying separate performance obligations, revenue recognition for variable consideration, the recoverability assessment of contract assets). | Consistent with initial views | Consistent with draft position |
| Noted that some users observed that entities applied IFRS 15 consistently, which improved the comparability of information disclosed about revenue. | Consistent with initial views | Consistent with draft position |
| Noted that some users of financial statements, regulators and accounting firms observed some improvement in the usefulness of information entities disclosed about revenue after IFRS 15 was implemented. | Consistent with initial views | Consistent with draft position |
| This topic was not included in the draft comment letter given the usefulness of these disclosures for users. | Consistent with initial views | Consistent with draft position |
| The comment letter did not include any comments on capital allocation. | Consistent with initial views | Consistent with draft position |
| Noted that some preparers found the application guidance helpful. | Consistent with initial views | Consistent with draft position |
| Noted that auditors applied IFRS 15 robustly, improving the quality of information disclosed about revenue. | Consistent with initial views | Consistent with draft position |
Influencing process
| Step | Mandatory/ optional¹ | Metrics or evidence | UKEB Secretariat comments | | UKEB - IFRS 15 Post-Implementation Review Timeline - April 2023 to November 2023 | Key Milestones: | | UKEB response to topical elements in the PIR of IFRS 15 | | Education sessions (continued) [DPH 4.10] |
Footnotes
-
UKEB Accounting Firms and Institutes Advisory Group members were contacted by email to request feedback on the DCL. Subsequently one-to-one meetings were held with two separate "Big 4" accounting firms and two written responses were received from the other two "Big 4" accounting firms. Feedback received was prior to any formal "global firm" response provided to the IASB. ↩
-
For public business entities, the amendments in this Update are effective for fiscal years beginning after December 15, 2022, including interim periods within those fiscal years. For all other entities, the amendments are effective for fiscal years beginning after December 15, 2023, including interim periods within those fiscal years. The amendments in this Update should be applied prospectively to business combinations occurring on or after the effective date of the amendments. Early adoption of the amendments is permitted, including adoption in an interim period. An entity that early adopts in an interim period should apply the amendments (1) retrospectively to all business combinations for which the acquisition date occurs on or after the beginning of the fiscal year that includes the interim period of early application and (2) prospectively to all business combinations that occur on or after the date of initial application. ↩
-
See the IASB's Rfl for the PIR of IFRS 15, Spotlight 9.1 - IFRS 3 Business Combinations. ↩
-
In the PIR of IFRS 3, the IASB asked a question about the extent to which the information derived from the fair value measurements is relevant and whether there are any deficiencies. Some respondents highlighted concerns that fair value information does not facilitate a comparison of trends between entities that grow organically and those that grow through acquisitions. In addition, some respondents said upward revaluations of acquired inventory to fair value reduce profitability in the first period following the business combination. In the IFRS 3 PIR Report and Feedback Statement, the IASB acknowledged respondents’ concerns related to fair value adjustments but concluded that fair value remains the best approach for measuring the assets acquired and the liabilities assumed in a business combination. See page 18 of IASB's Report and Feedback Statement on the Post-implementation review of IFRS 3 Business combinations published on 17 June 2015. ↩
-
A few respondents to the IASB's March 2020 Discussion paper Business Combinations— Disclosures, Goodwill and Impairment said fair value adjustments made to assets acquired and liabilities assumed in a business combination affect the financial performance of the reporting entity in future periods. One respondent highlighted a conflict between the measurement principles in IFRS 3 (based on fair value) and in IFRS 15 Revenue from Contracts with Customers (based on the transaction price) that in its view should be addressed. In summarising the feedback to the DP, IASB noted that the Basis for Conclusions of IFRS 3 explains why, in the IASB's view, recognising assets acquired and the liabilities assumed at their acquisition date fair values provides useful information. ↩
-
Paragraph 1.2 of the IFRS Conceptual Framework says "the objective of general-purpose financial reporting is to provide financial information about the reporting entity that is useful to existing and potential investors, lenders and other creditors in making decisions relating to providing resources to the entity". Paragraph 1.4 says "to make the assessments described in paragraph 1.3, existing and potential investors, lenders and other creditors need information about: (a) the economic resources of the entity, claims against the entity and changes in those resources and claims (see paragraphs 1.12–1.21); and (b) how efficiently and effectively the entity's management and governing board have discharged their responsibilities to use the entity's economic resources (see paragraphs 1.22–1.23)". ↩
-
This concern is not new; it was raised in the basis for conclusions in FASB Statement No. 141 (revised 2007), Business Combinations, which stated in part that "by recording assets and liabilities at the carrying amounts of predecessor entities, post combination revenues may be overstated (and expenses understated) as the result of embedded gains that were generated by predecessor entities but not recognized by them" (paragraph B38). ↩
-
The availability of greater future revenue recognition, under the new guidance, may encourage acquirers to shop for contracts where there are advance payments that exceed the performance of the contract (i.e. buy revenues), in order to augment future revenue recognition, resulting from the derecognition of the higher contract liability balance, measured in accordance with the revenue standard, as opposed to at the fair value measurement. ↩
-
The fair value amount measured by the acquirer is often less than the amount recorded by the acquiree under the revenue recognition principles of IFRS 15 before acquisition. The fair value reflects the amount that would be paid to a third party to assume the contract liability, and therefore would exclude the costs to enter into the contract (e.g. selling costs) that have already been incurred by the acquiree. This reduction in value or fair value adjustments is often referred to as a 'haircut'. due to the 'haircut'; the subsequent amount of revenue recognised by the acquirer after the acquisition is therefore less than would have been recorded by the acquiree had it not been acquired. ↩
-
UKEB calculation based on LSEG and Eikon data, May 2023. This calculation includes companies listed on the Main market as well as on the Alternative Investment Market (AIM). ↩↩
-
UKEB estimate based on FAME, Company Watch and other proprietary data. ↩↩