5 FICE PIP
19 October 2023 Agenda Paper 5
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
| Purpose of the paper | This paper provides the Board with a Project Initiation Plan (PIP) for the project relating to the IASB's proposed amendments to IAS 32 Financial Instruments: Presentation. |
Summary of the Issue
Following stakeholder feedback on the IASB's 2018 Discussion Paper on this topic, the IASB decided to make clarificatory amendments to IAS 32 to improve understanding of its principles and the consistency of application. The Board has been monitoring the relevant IASB tentative decisions to-date on this topic, listed on the project webpage.
The IASB expects to issue an Exposure Draft (ED) setting out its proposed amendments during November 2023, either close to or after the UKEB's November 2023 meeting. The IASB is likely to propose a 120-day comment period. As a result of the timing of Board meetings, the window for the Board to consider the key proposals of the published ED could be very brief. Whilst the Board will have already considered key IASB decisions that will be reflected in the ED, past experience has shown that the review of the proposed amendments in a published ED provides clarity on their consequences. The Secretariat therefore asks the Board to consider two potential options for the timing of the publication of its DCL.
- Publication of a UKEB Draft Comment Letter (DCL) in January 2024 for a 30-day comment period; or
- Publication of the DCL in December 2023 for a comment period of up to 45 days.
Decisions for the Board
- Does the Board agree with the Secretariat's recommendation that the project timeline should follow option one?
- Subject to that decision, does the Board approve the PIP?
Recommendation
The Secretariat recommends that the Board:
- approves option one – to publish the DCL in January 2024 for a 30-day comment period.
- approves the PIP.
Appendices
Appendix A [Draft] Project Initiation Plan
Purpose
1This paper provides the Board with a Project Initiation Plan (PIP) for the influencing phase of the project relating to the IASB's proposed amendments to IAS 32 Financial Instruments: Presentation.
Background
2Following stakeholder feedback on the 2018 Discussion Paper, the IASB tentatively decided to scope the project as clarifying some principles within IAS 32 and providing additional application guidance to IAS 32, in order to reduce diversity in practice, and further developing some presentation and disclosure requirements.
3The UKEB has been actively monitoring the decisions taken by the IASB to inform the ED as part of its IASB General Update papers, which are also listed on the project webpage. The relevant UKEB papers are:
- June 2022 Contingent settlement provisions and effects of laws and regulations.
- July 2022 Reclassifications.
- September and October 2022 Obligations to redeem own equity instruments.
- January 2023 Presentation of equity instruments and financial liabilities,
- March 2023 Sweep issues, classification of financial instruments with a contractual obligation to deliver cash at the discretion of the entity's shareholders and additional disclosures to ensure that amounts attributable to ordinary shareholders are more visible in the accounts.
- May 2023 Disclosures in IFRS 7 and IAS 1.
- June 2023 Consequential Amendments to the project Subsidiaries without Public Accountability and Due Process Steps and Permission to Ballot.
4The Board also received an education session on the IASB's project in November 2022.
5The Financial Instruments Working Group discussed four of the topics at its September 2023 meeting. It will discuss the remaining topics at its November 2023 meeting. Further planned outreach is included in the PIP.
Project Initiation Plan (PIP)
6The draft PIP is attached at Appendix A for the Board's consideration and approval.
7The IASB is currently expected to issue the ED during November 2023, either close to or after the UKEB's November 2023 meeting. The IASB is likely to propose a 120-day comment period. The timing of Board meetings makes it difficult to analyse the proposals, conduct meaningful outreach and incorporate the results of that outreach in the DCL while still adhering to the IASB's expected comment deadline. Whilst the Board will have already considered key IASB decisions that will be reflected in the ED, past experience has shown that the review of the proposed amendments in a published ED provides clarity on their consequences. The Secretariat therefore asks the Board to consider two potential options for the timing of the publication of its DCL. These are:
- To issue a DCL following the 30 January 2024 Board meeting for a public comment period of 30 days (option one); or
- Issue a DCL following the December 2024 Board meeting for a public comment period of a minimum of 30 days, for example, 45 days (option two).
8Option one means that the Board will discuss the key technical issues at its December 2023 meeting, followed by consideration of a DCL at the 30 January 2024 Board meeting, with the DCL published for stakeholder comment in early February 2024. This option permits additional time for outreach with stakeholders following the publication of the ED, which can then be incorporated in the DCL for the Board to consider at the January 2024 meeting. The Board discussion of the key technical issues relating to the ED could therefore also be reflected in the DCL.
9However, depending on exact timings, option one may result in the Final Comment Letter (FCL) being delivered a few days1 after the IASB comment period ends. From previous discussions with IASB staff, they have confirmed that a slightly late submission can be accepted and included in their analysis.
10Option two would mean a DCL developed and included in the UKEB's agenda papers for the 14 December 2023 Board meeting (expected to be published on 7 December 2023). This would only permit a week to develop the draft for Board's consideration after the ED is issued. This option would result in the UKEB's FCL being delivered on time. However, the short timeframe between the publication of the ED and the DCL would compromise the ability to analyse the ED proposals or engage meaningfully with stakeholders. As a result, the DCL would likely have limited coverage of the key technical points at issue. In addition, the DCL being published after 15 December 2023 means that it will coincide with the winter holiday period for a lot of stakeholders, leaving little time to interact with stakeholders until early in January 2024 when they return from annual leave.
11Whilst neither option is ideal, on balance, the Secretariat recommends option one. This option allows additional time to:
- engage with stakeholders early on the ED proposals, rather than the IASB's tentative decisions;
- discuss the technical issues with the Board;
- prepare the DCL; and
- take stakeholder feedback fully into account in the DCL.
Questions for the Board
- Does the Board agree with the Secretariat's recommendation that the project timeline should follow option one?
- Subject to that decision, does the Board approve the PIP?
Appendix A: Financial Instruments with Characteristics of Equity - Project Initiation Plan
| Project Type | Influencing |
|---|---|
| Project Scope | Moderate |
Purpose
A1This paper sets out the plan to influence the proposed Amendments Financial Instruments with Characteristics of Equity to IAS 32 Financial Instruments: Presentation (the Amendments), which are expected to be published by the IASB in November 2023.
Background
A2Following stakeholder feedback on the IASB's 2018 Discussion Paper on this topic, the IASB decided to make clarificatory amendments to IAS 32 to improve understanding of its principles and the consistency of its application.
A3The IASB expects to issue an Exposure Draft (ED) for this project in November 2023.
A4From May 2021 to May 2023, the IASB has taken tentative decisions which suggest that the ED will make the following clarifications:
- It will introduce principles for assessing whether financial instruments meet the fixed-for-fixed condition.2
- It will prohibit reclassification other than for changes in the substance of the contractual terms arising for changes in circumstances outside the contract.
- It will specify further recognition, classification and measurement requirements for contingent settlement provisions as well as clarifying the meaning of certain terms in that context.
- It will clarify certain requirements on the scope, classification, remeasurement and presentation of obligations to redeem own equity instruments.
- In relation to instruments that have a contractual obligation to deliver cash at the discretion of the issuer's shareholders, it will introduce a factor-based approach to assess whether a decision of shareholders is a decision of the entity.
- It will specify the effects of laws to be taken into account when classifying financial instruments as liabilities or equity.
- It will introduce additional disclosure requirements for issued financial instruments, including in relation to potential dilution and priority of claims.
Project plan rationale
A5The following considerations have shaped the project plan.
The scope of the IASB project is to make amendments clarifying IAS 32
A6Following stakeholder feedback on the 2018 Discussion Paper, the IASB tentatively decided to scope the project as clarifying some principles within IAS 32 and providing additional application guidance to IAS 32, in order to reduce diversity in practice, and further developing some presentation and disclosure requirements.
A7The Amendments are therefore not expected to change the principles of IAS 32. However, existing practice may change, if the Amendments specify requirements in areas in which entities considered they had a choice of accounting policy. The project may also result in some additional presentation or disclosure requirements.
A8The Amendments may affect any entity that has issued capital instruments. However, we expect they may be of particular interest to entities subject to regulatory capital requirements.
Initial engagement with UK stakeholders suggests they welcome the project in this important area
A9At its September 2023 meeting, the Financial Instruments Working Group (the FIWG) considered the first four topics (A4 (a) to (d) above) in relation to which the IASB has proposed amendments and will be considering the remaining ones at its November 2023 meeting. Overall, the FIWG welcomed the IASB's project to make clarifying amendments to IAS 32. Nonetheless, together with our desk-based research, their initial feedback has highlighted areas where the wording of the ED will require especially close review.
Setting up an ad-hoc advisory group is not necessary
A10The Financial Instruments Working Group is well placed to provide feedback on this project, so it is not considered necessary to set up a separate ad-hoc advisory group specific for this project.
[Project timelines]
A11[We have set out below two options for the timeline for the influencing phase. The Board is asked to decide its preferred timeline. Text pertaining to the two options is in square brackets throughout this document as we will publish the PIP with the approved option only.]
Project milestones
A12A proportionate approach is proposed, incorporating mandatory milestones listed in paragraph 5.3 of the UKEB's Due Process Handbook (Handbook). The table below provides a brief description of the work we have done and that we intend to do as part of this project.
A13Future dates are based on current expectations and are, therefore, subject to subsequent modification. The Board will be alerted to any significant changes.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30(b)] | Added to UKEB technical work plan. | Completed. |
| Education session on IASB proposals on FICE (optional) [Handbook 4.10] | An education session on the FICE project was provided to the board in November 2022. A further education session on the anticipated ED proposals will be provided to the Board at a future meeting. | First session completed in November 2022. A second session is currently planned for the November 2023 Board meeting. |
| Desk-based research (optional) [Handbook 5.9] | The Secretariat has begun its programme of desk-based research, to include review of IASB staff papers, publications from regulators, accounting firms and other relevant sources including accounting manuals as well as the ED when published. | In progress. |
| Outreach activities (mandatory) [Handbook 5.11] | We have already begun to engage with the Financial Instruments Working Group and will continue to engage with the members in its November 2023 and January 2024 meetings. |
In addition, we plan to seek feedback from:
- the Accounting Firms and Institutes Advisory Group;
- the Preparers' Advisory Group;
- the Investors' Advisory Group; and
- Relevant industry bodies and regulators drawn from sectors in which we understand these issues regularly arise.
| In progress. | | Project Initiation Plan (PIP) (mandatory) [Handbook 5.4 to 5.8] | This paper | To be brought to October 2023 Board meeting, ahead of the IASB's publication of the ED. | | Draft comment letter (DCL) published for comment (generally mandatory) [Handbook paragraphs 5.13 to 5.17] |
The Secretariat will publish the approved DCL for public comment for 30 days following the January 2024 Board meeting. The Secretariat will bring a preparatory technical paper to the December 2023 Board meeting for discussion.]
[Option Two
The Secretariat will publish the approved DCL for public comment for a minimum of 30 days (and up to 45 days) following the December 2023 Board meeting.]
As soon as possible after the January 2024 Board meeting.]
[Option Two
As soon as possible after the December 2024 Board meeting.]
The IASB comment period is expected to close at the end of March 2024, either before or on the same day as the UKEB meeting. The Secretariat will submit the FCL to the IASB as soon as possible following approval at the 28 March 2024 UKEB meeting.]
[Option Two
UKEB submits FCL to the IASB before the comment period ends.]
As soon as possible after the March 2024 Board meeting.]
[Option Two
As soon as possible after the February 2024 Board meeting.]
Resources allocated
A14On the basis of this project plan, we consider that a project team consisting of one Project Director (0.8 FTE), one Project Manager and technical support and oversight from a Senior Project Director should ensure the project timelines are achievable. Input from the economics team and communications support will be obtained as appropriate.
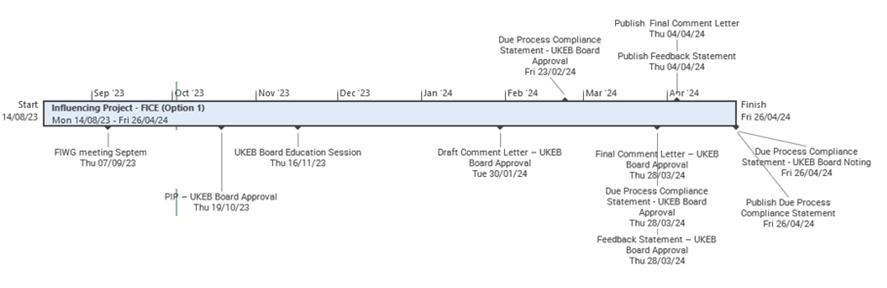
Detailed project timeline [- Option One: DCL published in January 2024]
| Date | Milestone |
|---|---|
| October to November 2023 | Preliminary analysis and outreach before publication of Exposure Draft |
| 19 October 2023 | Board: Discusses and approves Project Initiation Plan (this document). |
| 16 November 2023 | Board: Education session on proposed topics for Amendments. |
| November 2023 | IASB publishes ED with 120-day comment period. |
| November 2023 to January 2024 | Secretariat: Outreach with advisory groups, FIWG and relevant industry groups. |
| 7 December 2023 | Secretariat: Submits technical paper to Board. |
| 14 December 2023 | Board: Discusses technical paper. |
| 30 January 2024 | Board: Discusses and approves DCL. |
| 6 February 2024 | Secretariat: Alerts key stakeholders to publication of DCL. |
| 6 February to 5 March 2024 | 30-day comment period. |
| 28 March 2024 | Board: Discusses and approves Final Comment Letter (FCL), Feedback Statement and Due Process Compliance Statement. |
| As soon as possible after Board discussion | Secretariat: Submits FCL to IASB and publishes FCL on website. |
| 26 April 2024 | Board: Notes Due Process Compliance Statement. |
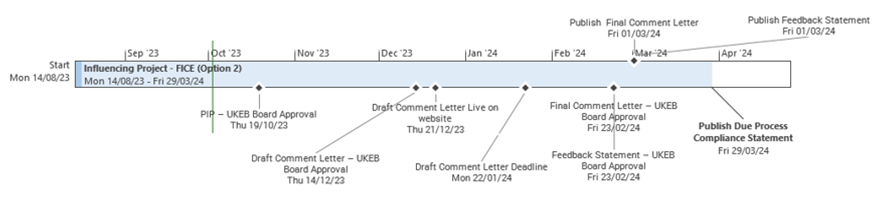
[Option Two: DCL published in December 2024]
| Date | Milestone |
|---|---|
| October to November 2023 | Preliminary outreach before publication of Exposure Draft |
| 19 October 2023 | Board: Discusses and approves Project Initiation Plan (this document). |
| 16 November 2023 | Board: Education session on proposed topics for Amendments. |
| November 2023 | IASB publishes ED with 120-day comment period. |
| November 2023 to January 2024 | Secretariat: Outreach with advisory groups, FIWG and relevant industry groups. |
| 7 December 2023 | Secretariat: Submits DCL to Board. |
| 14 December 2023 | Board: Discusses and approves DCL. |
| Shortly after 14 December 2023 | Secretariat: Alerts key stakeholders to publication of DCL. |
| December 2023 to late January 2024 or early February 2024 | 45-day comment period. |
| 23 February 2024 | Board: Discusses and approves FCL, Feedback Statement and Due Process Compliance Statement. |
| As soon as possible after Board discussion | Secretariat: Submits FCL to IASB and publishes FCL on website. |
| 28 March 2024 | Board: Notes Due Process Compliance Statement. |
Footnotes
-
The exact timing depends on when the IASB publishes the ED. If the ED is published on 30 November 2023, the IASB comment period would end on 29 March 2024. Assuming the UKEB comment letter is submitted on 1 April 2024, it would be submitted three days late. If the ED is published on 15 November 2023, the IASB comment period would end on 14 March 2024. Assuming the UKEB comment letter is submitted on 1 April 2024, it would be submitted 18 days late. ↩
-
IAS 32.16 (b) sets out requirements for classification as an equity instrument, which include "...a derivative that will be settled only by the issuer exchanging a fixed amount of cash or another financial asset for a fixed number of its own equity instruments." ↩