8 Connectivity – UKEB Staff Paper Fair Value Measurement
18 May 2023 Agenda Paper 8
| Project Type | Monitoring |
|---|---|
| Project Scope | Significant |
Executive Summary
Purpose of the paper
This is the third staff paper in a series of preparatory papers, focusing on connectivity between the International Sustainability Standards Board (ISSB) [draft] IFRS Sustainability Disclosure Standards and International Accounting Standards Board (IASB) Accounting Standards.
The aim of the series of papers is to enable the UKEB to consider the key matters related to connectivity and to develop its own position. This paper focuses on connectivity regarding fair value measurement.
Summary of the Issue
The ISSB has issued a Request for Information (Rfl) to inform its initial two-year work plan. One of the four proposed projects included in the Rfl relates to integration in reporting.
This project includes a research project on integration in reporting to support integrated disclosures beyond the requirements on connected information in the financial statements and sustainability-related financial disclosures, that are included in S1 and S2.
In parallel, the IASB has activated a project named 'Climate-related Risks in the Financial Statements' which seeks to address stakeholder feedback it received on its Third Agenda Consultation. This relates to the potential for inconsistent application of IFRS Accounting Standards in relation to climate-related risks in financial statements.
This staff paper contains two appendices:
Appendix A – Potential connectivity issues between Sustainability Disclosure Standards and Accounting Standards: Fair Value Measurement (Staff paper)
This paper discusses areas of potential overlap or misalignment from a user's perspective in relation to fair value measurement and includes possible solutions together with illustrative examples.
Appendix B: Connectivity Background
Due to the common background for all the topics in this series, a separate background paper has been prepared [Appendix B] to avoid repetition. The first section of this paper explains the interaction of the preparatory paper series with the UKEB Due Process. The paper then comments on the nature of ‘connected information', relationship between the IASB and ISSB standards and requirements, implications for issuing new standards and next steps.
Decisions for the Board
The Board is not asked to make any decisions.
In relation to Appendix A, does the Board have any comments or additional areas to those noted in the paper?
Recommendation
The Board to consider and discuss the potential connectivity issues in relation to the fair value measurement.
Appendices
Appendix A Potential connectivity issues between Sustainability Disclosure Standards and Accounting Standards: Fair Value Measurement (Staff paper) Appendix B Connectivity Background
Potential connectivity issues between Sustainability Disclosure Standards and Accounting Standards: Fair Value Measurement (Staff paper)
Introduction
1This is the third staff paper in a series of preparatory papers, focusing on connectivity between the International Sustainability Standards Board (ISSB) [draft] IFRS Sustainability Disclosure Standards and International Accounting Standards Board (IASB) IFRS Accounting Standards.
2The objective of these papers is to support the UKEB's consideration of the key matters related to connectivity and to develop its own position in relation to these matters. This paper focuses on potential connectivity issues with respect to fair value measurements.
3There are three appendices to this paper and, where relevant, have been referenced to in the paper:
- Annex 1 to this paper contains relevant examples from annual reports of the UK's FTSE 350 companies.
- Annex 2 contains a summary of the relevant requirements of IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information (S1) and [draft] IFRS S2 Climate-related Disclosures (S2).
- Annex 3 contains extracts from the associated Accounting Standards relating to fair value measurements.
4The first draft of this staff paper has also been shared with the members of the UKEB Sustainability Working Group (SWG) and the National Standards Setters Sustainability Forum.
5Once feedback has been received from these groups and from this discussion with the UKEB, this staff paper will be revised and presented to the Board for noting. Relevant comments will be incorporated into the Draft Comment Letter (DCL) on the ISSB's Request for Information (Rfl) on Consultation on Agenda Priorities.
Areas of potential overlap or misalignment
Overview of themes identified
6The table below contains themes identified from a range of stakeholders of perceived current disconnects between the requirements of the Task Force for Climate-related Financial Disclosures (TCFD) and the financial statement disclosures related to fair value measurement in FTSE 350 Annual Reports.
7These themes are explored in more detail in the paper, with referencing to the relevant sections provided in the final column of the table.
8The high-level examples relate to entities with exposure to climate-related risks and seek to illustrate perceived current disconnects between TCFD (as an approximate proxy for S2 requirements1) and disclosures in the financial statements.
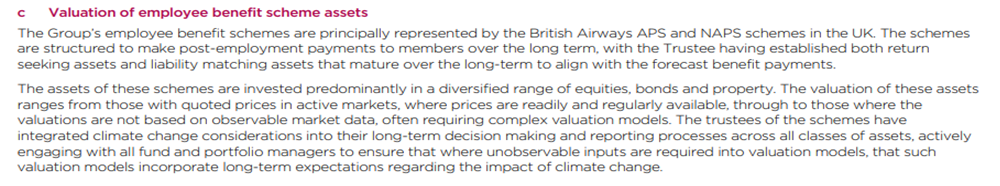
| Narrative reporting e.g., TCFD disclosures | Financial Statement fair value measurement and disclosures | User connectivity questions | Reference to detailed discussion | |
|---|---|---|---|---|
| Assumptions and sensitivity analysis in fair value measurement | Prominent descriptions of material climate risks (transition and physical), impacting the entity, including uncertainty concerning commodity prices or regulation | Limited or no disclosure of the consideration of climate-related impacts on key assumptions and sensitivity analysis | Were potential impacts material in the current period? If so, to what extent have they been reflected, if not, when are they likely to impact? | Paragraph 28-40 |
| Fair value less costs of disposal in impairment testing | Disclosure of the entity's strategy to address the impact of short, medium, and long-term physical or transition risks. Intention to replace material emission-heavy assets in a Cash Generating Unit (CGU) | The note disclosure does not comment on whether and how the climate mitigation strategy has been considered in determining the fair value of the CGU. | To what extent have climate-related matters been considered in the calculation of fair value less costs of disposal? | Paragraph 41-49 |
| Narrative reporting e.g., TCFD disclosures | Financial Statement fair value measurement and disclosures | User connectivity questions | Reference to detailed discussion | |
|---|---|---|---|---|
| Disclosure of assumptions and inputs in fair value measurement | Significant disclosures of medium to long term climate-related targets and transition plans. Intention to restructure existing assets and terminate assets | Limited disclosure regarding how climate change has been included in the fair value measurements or inputs used. On acquisition, limited disclosure of impacts on goodwill. | To what extent have climate-related matters, including the relevant inputs been factored into current fair value measurements? What inputs have been used? | Paragraph 50-62 |
Detailed discussion
Current and anticipated financial effects
IFRS Sustainability Disclosure Standards
9Once the ISSB Standards are adopted for use in a jurisdiction, entities will be required to provide disclosures about the current and anticipated financial effects of sustainability-related risks and opportunities, as set out in the paragraphs below.
10Paragraph 222 of S1 stipulates that entities will be required to disclose information that will enable users of general-purpose financial reporting3 to understand the effects of significant sustainability-related risks and opportunities on its financial position, financial performance and cash flows for the reporting period, and the anticipated effects over the short, medium, and long term. This includes information on how sustainability-related risks are included in the entity's financial planning.
11In the first instance, entities will be required to disclose quantitative information either as a value or range of values, unless unable to do so in which case qualitative disclosure will be required.
12Paragraph 22(a) of S1 sets out that entities would be required to disclose the effect of significant sustainability-related risks and opportunities on the entity's most recently reported financial position, financial performance and cash flows.
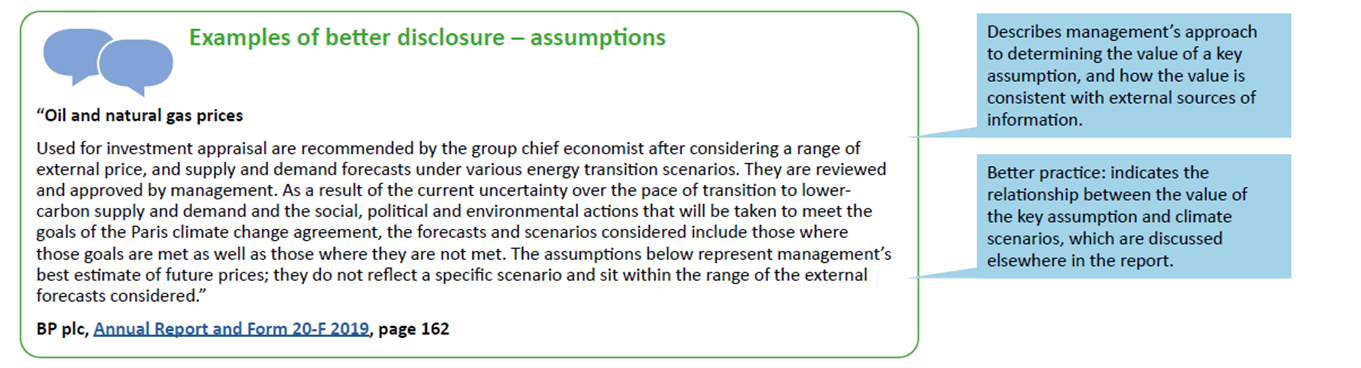
13Entities will also need to disclose information on those sustainability-related risks and opportunities for which there is a significant risk that there will be a material adjustment to the carrying amounts of assets and liabilities reported in the financial statements, within the next financial year (S1 paragraph 22(b)).
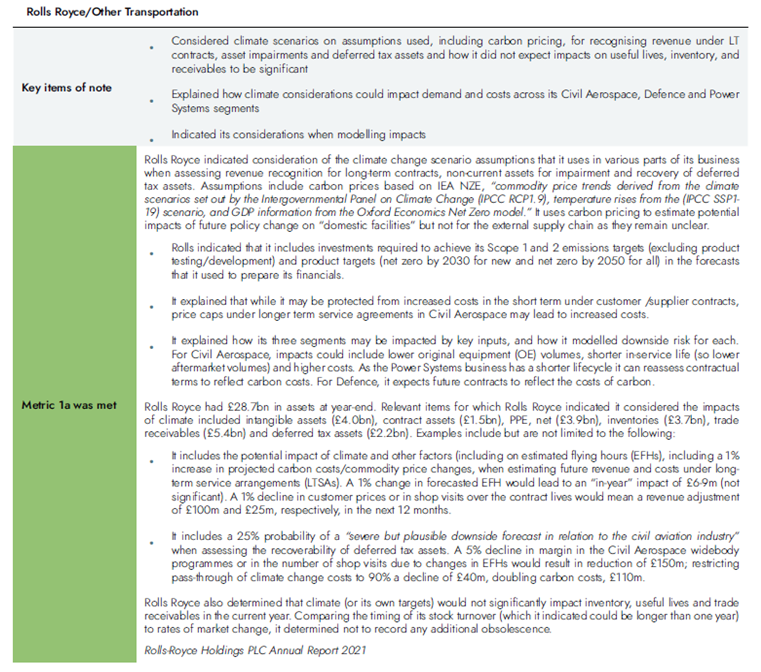
14In addition, S1 (paragraph 80) requires that financial data and assumptions used in sustainability disclosures are consistent with the corresponding financial data and assumptions in the financial statements, to the extent possible. This is also reflected under Metrics and Targets in S2 paragraph 22(b).4
IFRS Accounting Standards
15The fair value of certain assets and liabilities may be affected by material climate-related risks or opportunities, such as assumptions regarding potential changes in commodity prices or the timing of regulations that may penalise negative environmental behaviour. In these situations, market participants' perspectives on valuation may change and users' expectation of impacts on the financial statements may be heightened.
16Assets and liabilities typically subject to fair value measurement under IFRS Accounting standards are:
- IFRS 3 Business Combinations
- IFRS 9 Financial Instruments
- IAS 16 Property, Plant and Equipment
- IAS 19 Employee Benefits
- IAS 36 Impairment of Assets
- IAS 38 Intangibles
- IAS 40 Investment Property
17IFRS 13 Fair Value Measurement therefore applies to those IFRSs that require or permit fair value measurements or disclosures and provides a single IFRS framework for measuring fair value and requires disclosures about fair value measurement.
18The standard defines fair value as 'the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date'. It also applies when another IFRS Accounting Standard requires or permits fair value measurements or disclosures regarding fair value measurements (paragraph 9).
19Paragraph 11 of IFRS 13 states that a fair value measurement for a particular asset or liability and an entity should consider the characteristics of the asset or liability if market participants would take those characteristics into account when pricing the asset or liability at the measurement date. Such characteristics include, for example, the condition and location of the asset and restrictions, if any, on the sale or use of the asset.
20More detail about the scope and requirements of IFRS 13 has been included in Annex 3 to this paper.
21In addition, IAS 1 Presentation of Financial Statements requires an entity to “Disclose information about the assumptions it makes about the future, and other major sources of estimation uncertainty at the end of the reporting period, that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities within the next financial year “(paragraph 125).
Fair Value Measurement
Market participants
22IFRS 13 paragraph 22 states that an entity is required to measure the fair value of an asset or a liability using the assumptions that market participants would use when pricing the asset or liability, assuming that market participants act in their economic best interest.
The price
23According to paragraph 15 and 16 of IFRS 13, a fair value measurement assumes that the asset or liability is exchanged in an orderly transaction between market participants to sell the asset or transfer the liability at the measurement date under current market conditions, in the principal or (if no principal market) the most advantageous market.
24If there is no observable market, the entity will need to assume that a transaction takes place at the measurement date as this establishes a basis for estimating a price (paragraph 21).
Valuation techniques (refer Annex 3, paragraphs A20 - A22)
25When determining the fair value, the standard sets out the valuation techniques in paragraph 61. It stipulates the requirement to use valuation techniques that are appropriate in the circumstances and for which sufficient data is available to measure fair value. There are three techniques in the standard, namely market approach, cost approach and income approach.
Inputs to valuation techniques (refer Annex 3, paragraph A23)
26When performing the valuation, the entity should use valuation techniques that are appropriate in the circumstances maximising the use of observable inputs and minimising the use of unobservable inputs.
Fair Value Hierarchy (refer Annex 3, paragraph A23)
27Paragraphs 72 – 90, set out the three-level hierarchy, based on the type of inputs to the valuation techniques used (set out in more detail in Annex 3). Level 1 inputs are unadjusted quoted prices in active markets for items identical to the asset or liability being measured. As with current IFRS standards, if there is a quoted price in an active market, an entity uses that price without adjustment when measuring fair value.
markets or supported by market data). Level 3 inputs are inputs which must be developed to reflect the assumptions that market participants would use when determining an appropriate price for the asset or liability, for example, cash flow forecasts.
Assumptions and sensitivity analysis in fair value measurement
Assumptions in fair value measurement
Context
28With respect to the use of assumptions made by the entity when establishing the inputs into valuation models, the entity should consider the potential impact of sustainability-related risks and opportunities.
29Users may expect that these risks would affect inputs into valuation models such as adjustments to cash flows or discount rates used in a discounted cash flow calculation, or to prices when applying the market approach.
30If the sustainability disclosures contain information about the financial effect of a significant sustainability risk with the potential to cause a material adjustment to the carrying amounts of assets and liabilities, users may expect to see something about this in the financial statements.
Potential reasons for a disconnect
31From an accounting perspective, there may be valid explanations for why non-disclosure may be appropriate. For example, the sustainability risk may have been assessed but not considered to have high enough estimation certainty or probability of occurrence to impact fair values in the financial statements. However, without a disclosure to this effect, users may perceive that the information is disconnected.
32Another possibility may be that the entity had assessed the risk and concluded that it did not meet the definition of material5 information and therefore was not relevant or required for disclosure in the financial statements. However, this perspective may not fully take into consideration that climate-related risks and opportunities are increasing in importance and relevance to users.
Solution considerations
33The IASB may wish to consider providing additional guidance relating to materiality to communicate the importance of climate-related risks to users and to emphasise the application of qualitative elements in relation to sustainability
topics. This may include highlighting its Education Material on Effects on climate related matters on financial statements, which was published in November 2020.
34The IASB could also consider emphasising that users need to understand if climate-related risks and opportunities have been considered in the preparation of the financial statements and consequently, if any material impacts on valuations were identified.
35This could align with S1 (paragraph 80) and S2 (paragraph 22(b)) regarding consistency between the financial data and assumptions used in sustainability disclosures and the corresponding financial data and assumptions in the financial statements.
Sensitivity analysis in fair value measurement
Context
36Due to inherent uncertainties regarding the future impact of climate-related matters on the industry, market or entity, a range of possible scenarios may be required to determine possible impacts on fair value measurements.
37Users may struggle to comprehend which scenario was considered the most relevant or whether any of the scenarios disclosed in the sustainability disclosures of the annual report were used to prepare the valuations in the financial statements.
Potential reasons for a disconnect
38In preparing its financial statements, an entity may have the view that the scenarios disclosed in the sustainability disclosures of the annual report were not relevant (or maybe not relevant yet) for the valuations in the financial statements or that any one scenario is most relevant for the valuations.
Solution considerations
39When an entity's scenario analysis provides a range of possible outcomes the ISSB may consider emphasising in S2 that preparers should indicate which scenario was considered the most likely. The IASB may wish to consider whether disclosure about how the risks from multiple scenarios discussed in sustainability disclosures should be considered for determining fair value in the financial statements.
40An example of disclosure to this effect can be seen in Annex 1, paragraph A1 relating to the valuation of the employee benefit scheme assets. IAS 19 requires
the plan assets for a defined benefit scheme to be valued at fair value (paragraph 113).
Fair value less costs of disposal in impairment testing
Context
41Climate-related risks and opportunities, as well as targets and transition plans may be possible indicators of impairment of assets and consequently reduce the recoverable amount of the relevant assets.
42When performing impairment reviews to determine the recoverable amount, entities can use value-in-use or fair value less cost of disposal or a combination of both.
43When the fair value less costs of disposal method is used in impairment testing under IAS 36 Impairment of Assets, the effect of a restructuring is relevant to a fair value calculation if, and only if, a third-party purchaser would factor that into the price they would be willing to pay for the asset or cash-generating unit (CGU) whereas the entity's own intentions are not directly relevant and should not be considered. This is relevant if there is an expectation that a market participant would undertake the restructuring.
44In addition, where an entity calculates the recoverable amount of a CGU as its fair value less costs of disposal, expenditure to enhance the asset may be included in the calculation.
45The interpretation of what may constitute enhancement expenditure, is often considered to be a grey area and lead to diversity in practice. For example, when an entity incurs costs on an asset to comply with new regulations, it may be considered maintenance and not enhancement, even if the asset's productive capacity is enhanced.
Potential impacts
46If a significant sustainability-related or climate-related risk has been disclosed indicating that there may be a material adjustment to the carrying amount of an asset within the next financial year (S2 paragraph 14(b)) a user may be unclear as to whether this has been identified as an impairment indicator and whether an impairment review has been carried out. This is especially true if an impairment did not actually take place, as there will be no disclosure on this in the financial statements.
47Given the fact that future restructuring costs are typically prohibited from being considered in fair value calculations (IAS 36 paragraph 44), it is possible that entities may not apply the correct accounting treatment.
48The additional complexity around interpreting whether costs incurred are enhancement costs or maintenance costs may lead to inconsistency in accounting treatment and comparability issues.
Solution considerations
49The IASB may also wish to consider providing guidance to support preparers to disclose whether and how the costs of restructuring or enhancement of assets due to material climate-related risks and opportunities have been considered in determining fair value less costs of disposal.
Disclosure of assumptions and inputs in fair value measurement (refer Annex 3, paragraphs A24 - A26)
Assumptions and inputs
Context
50As set out in Annex 3, paragraphs A24-A26, an entity is required to disclose, amongst other things, the valuation techniques and inputs used in measuring fair values of assets and liabilities. If using Level 3 inputs, it would include assumptions made about future cash flows and risk adjusted discount rates used.
Potential impacts
51Due to their inherent uncertainty, medium- and longer-term material climate-related matters may be categorised as unobservable inputs at Level 3 (paragraphs 86-90f IFRS 13) of the fair value hierarchy.
52IFRS 13 requires that these inputs reflect the assumptions that market participants would use when pricing requires disclosure of the inputs used in fair value measurements. This may result in a high level of judgment as entities will have to estimate the market impact of unobservable inputs such as future commodity prices e.g., wheat prices will change in relation to the level of supply and demand. Supply and demand will in turn, be impacted by various factors such as, for example, short-term factors like the war in Ukraine and long-term factors such as the impact of climate change on wheat supply in the future.
Solution considerations
53While the impact of discounting over the medium- and longer-term is likely to reduce the materiality of the inputs, the IASB may wish to consider providing guidance on how the existing disclosures on Level 1, 2 or 3 inputs can be amended to reflect the climate-related inputs, to the extent they are relevant.
54An example of disclosures relating to key assumptions can be seen in Annex 1, paragraph A2. The example shows what the entity has disclosed around key assumptions and how disclosure could be improved.
55Another example of how climate-change has been considered in assumptions made can be seen in Annex 1, paragraph A3.
Disclosure of reasonably possible changes in key assumptions
Context
56In the case of CGUs containing goodwill (or intangible assets with indefinite useful lives), paragraph 134 (f) of IAS 36, requires disclosure if a reasonably possible change in a key assumption on which management has based its determination of a CGU's recoverable amount would erode the headroom. In that case, the entity should disclose the following:
- the amount by which the GCU's recoverable amount exceeds its carrying amount;
- the value assigned to the key assumption;
- the amount by which the value assigned to the key assumption must change, after incorporating any consequential effects of that change on the other variables used to measure recoverable amount, in order for the CGU's recoverable amount to be equal to its carrying amount.
Potential impacts
57While entities may not realise this, the uncertainty around climate-related matters and the possible change to assumptions may very well trigger this disclosure.
Solution considerations
58The IASB may wish to consider if further guidance is required to explain the use of headroom and sensitivity to changes in key assumptions around climate-related matters affecting the entity's fair value measurements. This may need to include providing guidance to support preparers to disclose whether and how the costs of restructuring or enhancement of assets due to material climate-related risks and opportunities have been considered in determining fair value less costs of disposal.
Disclosure timeframe
Context
59While both the IFRS Sustainability standards (S1 and S2) and the IFRS Accounting standards (IAS 1) contain the text 'within the next financial year' entities may incorrectly assume that this restricts their ability to disclose relevant climate-related risks or opportunities occurring in the medium- to long-term.
Potential impact
60Entities may assume that they are restricted from disclosing any financial effects on valuations from medium- or longer-term climate change targets and transition plans in the financial statements.
61At the UKEB March Preparers Advisory Group meeting7 some members noted that, 'as accounting standards require an outlook over the next 12 months, this made reporting a multi-year impact more challenging.'
Solution considerations
62The IASB may wish to consider providing guidance to clarify how materiality applies independent of timeframe.
Next Steps
63Following feedback from the members of the UKEB Sustainability Working Group (SWG) and the National Standards Setters Sustainability Forum and the UKEB Board, this staff paper will be revised and presented to the Board for noting at a future Board meeting. Relevant comments will be incorporated into the Draft Comment Letter (DCL) on the ISSB's Request for Information (Rfl) on Consultation on Agenda Priorities.
Question for the Board
1In relation to Appendix A, does the Board have any comments or additional areas to those noted in the paper?
Annex 1: Fair value measurement and disclosure examples
Disclosure examples
A1The International Airline Group noted in their Annual Report 20228 that climate change matters were taken into consideration in measuring the fair value of its employee benefit scheme assets.
A2The FRC noted in their Climate thematic report 20209 that BP had disclosed management's approach to determining the value of a key assumption in their investment appraisal methodology.
A3The extract below from Carbon tracker report: Still Flying blind 2022 stated that Rolls Royce have considered the impact of climate in asset valuation and changes in its costs.
Annex 2: IFRS Sustainability Disclosure Standards
Financial effects of sustainability-related risks and opportunities
A4S1 requires the disclosure of material information about sustainability-related financial risks and opportunities and sets out general reporting requirements. S2 is a thematic standard specific to climate-related risks and opportunities.
A5The relevant sections of these draft standards relevant to aspects of fair value measurement are set out below.
[draft] IFRS S1
A6Paragraph 22 of S1 requires an entity to provide quantitative disclosures of the impact on its most recently reported financial position, financial performance and cash flows. And for these risks and opportunities identified, paragraph 22(b) requires information where there is a significant risk of material adjustment to the carrying amounts of assets and liabilities reported in the financial statements within the next financial year.
Financial position
A7Paragraph 22(c) goes on to stipulate that the entity is required to disclose how it expects its financial position to change over time (considering its definition of the short, medium and long term as required by paragraph 9(b)) when considering its strategy to address the significant sustainability-related risks and opportunities it has identified.
A8This includes its current and committed investment plans and their anticipated financial effects on the financial position. Examples may include capital expenditure, major acquisitions and divestments, joint ventures, business transformation, innovation, new business areas and asset retirements.
Financial performance
A9Paragraph 22(d) requires the entity to disclose how it expects its financial performance to change over time (considering its definition of the short, medium and long term as required by paragraph 16(b)) when considering its strategy to address the significant risks and opportunities. Examples may include increases or decreases in revenue or costs of products and services aligned or not aligned with a lower-carbon economy; consistent with the latest international agreement on climate change; physical damage to assets from climate events; and the cost of climate adaptation or mitigation.
A10Paragraphs 42 to 44 of S1 set out the requirements for 'connected information' and note that sustainability information may also need to be linked to the financial statements. This includes providing information to enable users of general-purpose financial reporting to assess the connections between the sustainability-related risks and opportunities, and to assess how information about these risks and opportunities is linked to information in the general-purpose financial statements.
A11S1 also requires a description of the relationships between different disclosures, which includes the requirement to connect narrative information on governance, strategy and risk management to related metrics and targets.
A12To promote alignment with the financial statements, the ISSB has specified requirements to enable users to connect the disclosures where required. S1 proposes that sustainability-related financial disclosures:
- Are prepared for the same reporting entity and reporting period as the related financial statements (paragraph 66);
- Are provided at the same time as the financial statements and within the general-purpose financial report (paragraph 66);
- Include financial data and assumptions that are consistent with the corresponding financial data and assumptions in the financial statements, to the extent possible (paragraph 80) [redeliberation – ‘considering IFRS Accounting Standards'];
[draft] IFRS S2
A13When specifically considering climate-related matters, S2 (paragraph 14), requires an entity to disclose:
- how climate-related risks and opportunities have affected its most recently reported financial position, financial performance and cash flows;
- information about the climate-related risks and opportunities identified in (a) for which there is a significant risk that there will be a material adjustment to the carrying amounts of assets and liabilities reported in the financial statements within the next financial year;
- how it expects its financial position to change over time, given its strategy to address significant climate-related risks and opportunities, reflecting:
- its current and committed investment plans and their anticipated effects on its financial position (for example, capital expenditure, major acquisitions and divestments, joint ventures, business transformation, innovation, new business areas and asset retirements);
- its planned sources of funding to implement its strategy; and
- how it expects its financial performance to change over time, given its strategy to address significant climate-related risks and opportunities; and
- if the entity is unable to disclose quantitative information for paragraph 14(a)-(d), an explanation of why that is the case.
A14The ISSB also requires that an entity would need to explain the connections between those risks and opportunities and their current and anticipated financial effects. In addition, it would need to provide quantitative information about the financial effects unless it is unable to do so, in which case it would provide qualitative information.
A15S2 requires entities to disclose climate-related targets, including performance against and progress towards those targets. Entities are also required to disclose their transition plans, which include actions planned to transition toward a lower-carbon economy.
Annex 3: IFRS Accounting Standards
IFRS 13 Fair Value Measurement
Definition
A16IFRS 13 Fair Value Measurement defines fair value as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date (paragraph 9).
A17Circumstances in which IFRS 13 does not specify the measurement and disclosure requirements are, for example:
- Share-based payment transactions (IFRS 2)
- Leases (IFRS 16)
- Impairment of assets (IAS 38)
- Inventories (IAS 2)
- IFRS 13 also does not establish disclosure requirements for fair values related to employee benefits and retirement plans (IAS 19).
The asset or the liability
A18Paragraph 11 states that a fair value measurement for a particular asset or liability and an entity should consider the characteristics of the asset or liability if market participants would take those characteristics into account when pricing the asset or liability at the measurement date. Such characteristics include, for example, the condition and location of the asset and restrictions, if any, on the sale or use of the asset.
Market participants
A19Paragraph 22 states that an entity is required to measure the fair value of an assets or a liability using the assumptions that market participants would use when pricing the asset or liability, assuming that market participants act in their economic best interest.
Valuation techniques
A20When determining the fair value, the standard sets out the valuation techniques in paragraph 61. It stipulates the requirement to use valuation techniques that are appropriate in the circumstances and for which sufficient data are available to
measure fair value, maximising the use of relevant observable inputs and minimising the use of unobservable inputs.
A21According to paragraph 62, the objective of using a valuation technique is to estimate the price at which an orderly transaction to sell the asset or to transfer the liability would take place between market participants at the measurement date under current market conditions.
A22Three widely used valuation techniques are:
- the market approach,
- the cost approach, and
- the income approach
Fair value hierarchy
A23Paragraphs 72 – 90, set out the three-level hierarchy, based on the type of inputs to the valuation techniques used, as follows:
- Level 1 inputs are unadjusted quoted prices in active markets for items identical to the asset or liability being measured. As with current IFRS standards, if there is a quoted price in an active market, an entity uses that price without adjustment when measuring fair value.
- Level 2 inputs are inputs other than the quoted prices determined in level 1 that are directly or indirectly observable for that asset or liability. They are likely to be quoted assets or liabilities for similar items in active markets or supported by market data. For example, interest rates, credit spreads or yields curves. Adjustments may be needed to level 2 inputs and, if this adjustment is significant, then it may require the fair value to be classified as level 3.
- Level 3 inputs are unobservable inputs. These inputs should be used only when it is not possible to use Level 1 or 2 inputs. The entity should maximise the use of relevant observable inputs and minimise the use of unobservable inputs. However, situations may occur where relevant inputs are not observable and therefore these inputs must be developed to reflect the assumptions that market participants would use when determining an appropriate price for the asset or liability. The general principle of using an exit price remains and IFRS 13 does not preclude an entity from using its own data. For example, cash flow forecasts may be used to value an entity that is not listed. Each fair value measurement is categorised based on the lowest level input that is significant to it.
Disclosure
A24According to paragraph 91, the disclosures required are such that it would help users to assess the following:
- For assets and liabilities (on a recurring or non-recurring basis) measured at fair value, the valuation techniques and the inputs used to develop those measures.
- For recurring fair value measurements using significant unobservable inputs (Level 3), the effect of the measurements on profit or loss or other comprehensive income for the period.
A25Further disclosures required are set out in paragraph 93 and include:
- information about the hierarchy level into which fair value measurements fall,
- transfers between levels 1 and 2,
- methods and inputs to the fair value measurements and changes in valuation techniques, and
- additional disclosures for level 3 measurements that include a reconciliation of opening and closing balances, and quantitative information about unobservable inputs and assumptions used.
A26In its Educational Material10 published in November 2020, the IASB highlighted the possibility of disclosure of the assumptions on climate-related risk specifically for the unobservable input for Level 3.
Conceptual Framework
Measurement
A27The Conceptual Framework (CF) specifies the concept of measurement (paragraph F 4.54) as involving the assigning of monetary amounts at which the elements of the financial statements are to be recognised and reported.
IAS 1 Presentation of Financial Statements
Disclosure
A28IAS 1 Presentation of Financial Statements requires certain disclosures in relation to significant judgements and sources of estimation uncertainty as follows:
A29Paragraph 122 requires disclosure of judgements, apart from those involving estimation, that have the most significant effect on the amounts disclosed in the financial statements.
A30Paragraph 125 requires disclosure of information about those assumptions or sources of estimation uncertainty that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities in the next financial year, including details of the nature of those assets and liabilities and their carrying amount.
A31Paragraph 129 provides examples of the type of disclosures that may be required to address the requirements of paragraph 125. This includes examples of the nature of the assumption or estimation uncertainty, sensitivity disclosures and explanation of changes to past assumptions.
Appendix B: Connectivity Background
Context and interaction with UKEB due process
Context
B1The ISSB has issued a Request for Information (RFI), to inform their initial two-year work plan. One of the four projects includes a project that focusses on integration in reporting. That project includes a discussion of the requirements in IFRS S1 and IFRS S2 in relation to connected information in the financial statements.
B2Due to the timeframe of the publication of the ISSB RFI it is critical that the UKEB develop a fuller understanding of this new area so that it can provide a meaningful and evidence-based response to the ISSB.
B3In addition, the IASB agreed, at its March 2023 meeting for a project to commence on 'Climate-related Risks in the Financial Statements'. This project has commenced due to the fact that the ISSB has completed its deliberations on its first two Standards, Draft IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information (S1) and IFRS S2 Climate-related Disclosures, so the IASB has a stable set of decisions to inform their project.
B4The scope of the UKEB work1 is to assess the overlap and connectivity between the requirements of IFRS Sustainability Disclosure Standards and those of IFRS Accounting Standards, as well as the information that results from the application of the two sets of standards. We will consider the content of the two ISSB Exposure Drafts2 and any practical needs for connectivity arising from their application via a series of papers for discussion by the UKEB Board.
B5The UKEB Secretariat are therefore developing a series of preparatory papers which consider the connectivity themes between the ISSB [draft] IFRS Sustainability Disclosure Standards and IFRS Accounting Standards for consideration and discussion by the UKEB. It is intended that this work will be of benefit to both the ISSB and the IASB as they develop their work plans.
UKEB Due Process
B6As this work is preparatory, fact finding in nature and does not seek to form any policy positions, a Project Initiation Plan (PIP) is not required. Stakeholder
feedback will be sought from UKEB Advisory and Working Groups to help inform the Board discussion and enrich feedback to the ISSB and IASB.
B7In accordance with the UKEB Due Process, a formal PIP relating to the ISSB RFI will be presented to the UKEB at the June meeting for consideration.
Connected information
B8Draft IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information (S1) contains a section regarding ‘connected information’3 which proposes that an entity will be required to provide users of general-purpose financial reporting with information that enables them to assess the connections between:
- various sustainability-related risks and opportunities;
- the governance, strategy and risk management related to those risks and opportunities, along with metrics and targets; and
- sustainability-related risks and opportunities and other information in general purpose financial reporting, including the financial statements.
B9The IASB has communicated4 that accounting standards adequately cater for all material risks, including those arising from sustainability-related issues.
B10However, there is a growing concern and demand from stakeholders in the UK to improve the connectivity between the narrative reporting on sustainability related financial effects with the associated impacts on the financial statements. Examples of studies carried out and reports issued are those by Carbon Tracker5 and the FRC's Thematic Review6.
B11Stakeholder views will be sought from UKEB Advisory and Working Groups as well as other National Standard Setters (NSS) and presented for discussion meetings of the International Forum of National Standard Setters (IFASS). When the ISSB RFI project on connectivity is issued, formal outreach with UK stakeholders will be conducted as part of the response to the ISSB.
B12We consider interoperability i.e., alignment between IFRS Sustainability Disclosure Standards and other jurisdictional sustainability initiatives (e.g., EFRAG's ESRS and the climate related disclosures proposed by the SEC) to be out of scope.
Relationship between the IASB and ISSB Standards
B13A key relationship between the IASB and ISSB standards is that they are intended to provide information about an entity for the same reporting period and at the same time. They aim to primarily provide relevant and timely information to meet investors requirements. However, it is unclear how investors will be able to connect the two types of information and understand the impact on the entity's profitability or financial position.
B14In the UK, the working assumption is that the information will be presented in the Annual Report as entities are required to incorporate Task Force on Climate-Related Financial Disclosures (TCFD) in their Strategic Report.
B15From a practical operational perspective, preparers will need to ensure there is adequate communication between internal ESG reporting teams (who may be unfamiliar with accounting standards) and financial reporting teams (who may be unfamiliar with sustainability standards) to ensure connectivity within the Annual Report. As the information will be required at the same time, for the same financial period and across an entity's value chain, there will also be implications and connectivity requirements for data, systems, processes, and controls.
Differences and similarities between the standards
B16There are several differences between proposed IFRS Sustainability Disclosure Standards and the current IFRS Accounting Standards. Due to the forward-looking nature and longer time frames of sustainability risks and opportunities, the ISSB standards will likely require reporting entities to provide descriptions, numbers, or ranges of numbers in the narrative disclosures that won't necessarily connect directly to the financial statements.
B17As the information is prepared on a different basis, it is unlikely to be identical. However, users still need to be able to make connections, where appropriate, and understand the financial effects of sustainability matters, both in the narrative disclosures as well as in the financial statements, to the extent relevant.
B18Key differences identified so far include:
- Timeframe - sustainability disclosures require the disclosure of the financial effects over the short, medium, and long term but do not define those periods. IAS 1 Presentation of Financial Statements requires management to look at least 12 months from the end of the reporting period and requires the distinction to be made between current and non-current assets and liabilities.
- Perspective - while accounting standards consider forward looking information such as with impairment testing and useful economic lives, the
amounts generally reflect historic cost values7. Sustainability disclosures are forward looking in nature and use scenarios, assumptions and estimates to forecast a range of possible future outcomes.
- Scope - sustainability disclosures require material information about sustainability-related risks and opportunities across a company's 'value chain'. The value chain is defined as the 'full range of activities, resources and relationships related to a company's business model and the external environment in which it operates'. Accounting standards have a narrower definition of scope related to the legal reporting entity or group of companies.
- Recognition – Reporting levels of greenhouse gas emissions require measurement and there is an increased focus on emissions and emission rights which may lead to an expectation around recognition of related assets or liabilities. This would not necessarily lead to an immediate recognition of an asset or liability in the financial statements8 but may lead to their recognition in a later period.
- Assurance - IFRS financial statements are typically subject to independent audit by an established network of experienced audit professionals. It is yet to be determined what level of assurance will be required for sustainability disclosures or who might undertake that work.
- Adapted from IFRS Accounting Standards – primarily IAS 1 Presentation of Financial Statements and IAS 8 Accounting Policies, Changes in Accounting Estimates and Errors. The ISSB has also redeliberated to use concepts from IFRS Accounting Standards. For example, entities are required to use information that is 'reasonable and supportable and available without undue cost or effort' which is consistent with IFRS 9 Financial Instruments.
- Materiality - the ISSB redeliberated and tentatively agreed to use the same definition of material as IFRS Accounting Standards to ensure investors understand sustainability risks and opportunities i.e. ‘Information is material if omitting, misstating or obscuring it could reasonably be expected to influence investor decisions.’
- Publication and reporting period – entities are required to disclose sustainability-related financial information as a part of general-purpose financial reporting. This is intended to ensure that financial statement information and sustainability-related financial disclosures can be considered together.
- Fair presentation (para. 17) and Materiality and aggregation (para. 31): 'provide additional disclosures when compliance with the specific requirements in IFRSs is insufficient to enable users to understand the impact of particular transactions, other events and conditions on the entity's financial position and financial performance.'
- Structure of the notes (para. 112c): The notes shall: ... '(c) provide information that is not presented elsewhere in the financial statements but is relevant to an understanding of any of them.'
- Accounting policy information (para. 117): 'disclose material accounting policy information – i.e., when considered together with other information included in an entity's financial statements, it can reasonably be expected to influence decisions that the primary users of general-purpose financial statements make on the basis of those financial statements.'
- Judgements (para. 122): 'judgements that management has made in the process of applying the entity's accounting policies and that have the most significant effect on the amounts recognised in the financial statements.'
- Sources of estimation uncertainty: a further requirement (paras. 125, 129) to: 'disclose information about the assumptions [the company] makes about the future, and other major sources of estimation uncertainty at the end of the reporting period, that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities within the next financial year.'
- Financial impacts: how significant climate-related risks and opportunities have affected its most recently reported financial position, financial performance and cash flows.
- Quantitative and qualitative: if the entity is unable to disclose quantitative information, an explanation of why that is the case is required and qualitative disclosures are required.
- Material risk: for information identified in (a) above for which there is a significant risk that there will be a material adjustment to the carrying amounts of assets and liabilities reported in the financial statements within the next financial year.
- Changes in financial position: how the entity expects its financial position to change over time, given its strategy to address significant climate-related risks and opportunities, reflecting:
- its current and committed investment plans and their anticipated effects on its financial position (for example, capital expenditure, major acquisitions and divestments, joint ventures, business transformation, innovation, new business areas and asset retirements); and,
- its planned sources of funding to implement its strategy.
- Timeframe: how an entity expects its financial performance to change over the short, medium and long terms, given its strategy to address significant climate-related risks and opportunities (for example, increased revenue from or costs of products and services aligned with a lower-carbon economy, consistent with the latest international agreement on climate
- change; physical damage to assets from climate events; and the costs of climate adaptation or mitigation).
- Reporting Boundary – disclosures are required regarding significant climate-related risks and opportunities in an entity's value chain and where in that chain the significant climate-related risks and opportunities are concentrated.
- Assets:
- Recognition.
- Measurement (depreciation and revaluation models).
- Impairment.
- Expected credit losses related to financial assets.
- Liabilities and provisions:
- Confidential and commercially sensitive information.
- Recognition.
- Fair value measurement.
- Disclosures:
- Purpose and objectives of sustainability disclosures.
- Scope of estimation uncertainty.
- Communicating levels of uncertainty – hierarchy of disclosures.
- Risk disclosures relating to financial assets, non-financial assets and liabilities.
- Sustainability policy disclosures.
- Reporting of outcomes against previously disclosed plans.
- Internal transfer pricing vs internal carbon pricing.
- Other considerations
- Scope of consolidated information.
- Control.
- Exemption from disclosure.
- Conceptual Framework and materiality: Implications for the Conceptual Framework.
Next steps
B27The topics of future papers are shown in the table below. They are based on the themes noted above and identified in the UKEB staff paper presented at the January 2023 meeting of IFASS.
UKEB meeting Connectivity Topics Status March Asset recognition, measurement, and impairment Complete April Liabilities and provisions Complete May Fair value and measurement In progress July Other considerations September Conceptual Framework Footnotes
-
Draft IFRS S2, when finalised is likely to be more granular than TCFD. This link illustrates the proposed differences. ↩↩
-
Paragraph 22 of S1 is a proxy for paragraph 14 in S2, the latter being limited to climate-related risks and opportunities. ↩↩
-
As set out to in the Conceptual Framework, paragraph 1.2, the terms 'financial reports' and 'financial reporting' refer to general purpose financial reports and general purpose financial reporting unless specifically indicated otherwise. This term is also used in [draft] S1, paragraph 1 which sets out that the objective of the standard is to provide disclosures about sustainability-related risks and opportunities that is useful to the primary users of general purpose financial reporting. ↩↩
-
The ISSB redeliberated this sentence to now include 'to the extent possible with IFRS Accounting Standards'. ↩↩
-
Information is material if omitting, misstating, or obscuring it could reasonably be expected to influence the decisions that the primary users of general-purpose financial statements make on the basis of those financial statements, which provide financial information about a specific reporting entity. (IASB definition) ↩↩
-
IASB Educational Material: Effects of climate-related matters on financial statements – November 2020 ↩
-
International Airline Group (IAG) Annual Report 2022 page 208 ↩↩
-
FRC Climate Thematic Reporting – How are companies developing their reporting on climate-related challenges? November 2020 ↩
-
IASB Educational Material: Effects of climate-related matters on financial statements – November 2020