4 Supplier Finance Arrangements Amendments to IAS 7 and IFRS 7 – Project Initiation Plan
18 May 2023 Agenda Paper 4
Executive Summary
| Project Type | Endorsement and Adoption |
|---|---|
| Project Scope | Narrow-scope |
Purpose of the paper
This paper provides the Board with a draft Project Initiation Plan (PIP) for the project to consider the International Accounting Standards Board (IASB)'s narrow-scope amendments Supplier Finance Arrangements (Amendments to IAS 7 and IFRS 7) (the Amendments) for adoption for use in the UK. The Amendments are expected to be issued by the IASB later in May 2023, with an effective date of 1 January 2024.
Summary of the Issue
The UKEB must consider the Amendments against the statutory adoption criteria1 before UK entities are able to apply them. This paper presents a draft PIP setting out the proposed approach and timeline for the UKEB's project to assess whether the Amendments are suitable for adoption in the UK.
Decisions for the Board
The Board is asked to approve the draft PIP.
Recommendation
The Secretariat recommends that the Board approves the draft PIP.
Appendices
| Appendix A | Draft Project Initiation Plan (PIP) |
|---|---|
18 May 2023 Agenda Paper 4: Appendix A
Appendix A: Draft Project Initiation Plan
| Project Type | Endorsement and adoption |
|---|---|
| Project Scope | Narrow-scope |
Purpose
A1This paper sets out the plan to assess whether to adopt1 the narrow-scope amendments Supplier Finance Arrangements: Amendments to IAS 7 and IFRS 7 (the Amendments), expected to be issued by the IASB in May 2023, with an effective date of 1 January 2024 (with earlier application permitted by the IASB).
A2This Project Initiation Plan is presented to the Board ahead of the publication of the Amendments by the IASB as the IASB's accelerated effective date of 1 January 2024 results in an unusually short timeline for the UKEB endorsement work.
A3The IASB's proposals were set out in Exposure Draft ED/2021/10 Supplier Finance Arrangements: Proposed amendments to IAS 7 and IFRS 7 (the ED). The Board actively influenced the development of the Amendments, submitting its Final Comment Letter on the ED to the IASB on 28 March 20222.
A4The UKEB must consider the Amendments against the statutory adoption criteria before they can be formally adopted for use in the UK. The Amendments cannot be used by UK entities until formal adoption has taken place. The Board's aim would be to ensure an adoption decision is reached before the expected effective date of the Amendments of 1 January 2024.
Background
A5The IFRS Interpretations Committee (the Committee) considered a question about the information an entity is required to provide in its financial statements about supply chain finance (reverse factoring) arrangements. In response to that
18 May 2023 Agenda Paper 4: Appendix A
A6question, in December 2020 the Committee published the Agenda Decision Supply Chain Financing Arrangements – Reverse Factoring to explain the applicable requirements in IFRS Standards.
A7Feedback received on the draft Agenda Decision, including from investors and analysts, suggested that the information an entity is required to provide about this form of financing falls short of meeting user information needs. Users of financial statements want to understand the effects of these arrangements on an entity's liabilities and cash flows, as well as on liquidity risk and risk management.
A8The Amendments are intended to complement existing disclosure requirements in IFRS Accounting Standards that apply to supplier finance arrangements3. The Amendments to IAS 7 Statement of Cash Flows and IFRS 7 Financial Instruments: Disclosures require entities to disclose additional information in the notes about those arrangements.
A9The Amendments aim to provide users of financial statements with the information that enables them to assess the effect of supplier finance arrangements on an entity's liabilities and cash flows, as well as on its liquidity risk and risk management.
Description of the Amendments to IAS 7 and IFRS 7
A10The Amendments are expected to be published by the IASB in May 2023. A brief description of the expected Amendments to IAS 7 and IFRS 7, as proposed in the IASB's ED and subsequently re-deliberated by the IASB4, is shown in the table below.
| Amendments to IAS 7 and IFRS 7 – Supplier Finance Arrangements |
|---|
| Issued for public comment |
| Expected title and issue date of final amendments |
| Origin |
| What is the expected change? |
18 May 2023 Agenda Paper 4: Appendix A
| Amendments to IAS 7 and IFRS 7 – Supplier Finance Arrangements |
|---|
| Transition requirements |
Exclusions
A11The Amendments are expected to update existing guidance on implementing IFRS 76. That guidance accompanies, but is not an integral part of, IFRS 7. The UKEB's project does not address the guidance on implementing IFRS 7 as UK-adopted International Accounting Standards comprises only the mandatory sections of the standards7.
Project plan
A12The project plan is guided by the following factors.
18 May 2023 Agenda Paper 4: Appendix A
The Amendments are narrow in scope
A13The Amendments are part of the IASB's activities on maintenance and consistent application of IFRS Accounting Standards.
A14The Amendments are intended to complement the existing requirements in IFRS Accounting Standards that apply to supplier finance arrangements. They will not propose changes to classification or measurement requirements applicable to supplier finance arrangements but would be limited to requiring entities to disclose additional information in the notes to the financial statements about those arrangements.
The Amendments have been subject to public consultation
A15The Amendments were exposed for public comment as Exposure Draft ED/2021/10 Supplier Finance Arrangements: Proposed amendments to IAS 7 and IFRS 7.
A16The Board actively influenced the development of the Amendments. The UKEB considered the proposed amendments and consulted with UK stakeholders8 ahead of the submission of its final comment letter to the IASB. The UKEB submitted its Final Comment Letter on the ED to the IASB on 28 March 20229.
A17The IASB considered the comments from UK stakeholders, including the UKEB, in developing the final Amendments. In instances when the IASB decided not to take forward some of the suggestions made, it provided the rationale for its decisions (i.e. in IASB staff papers discussing the specific amendments and deliberations). Agenda Paper 610 of the December 2022 UKEB meeting summarises the main proposals in the ED, the UKEB response in its Final Comment Letter and the actions taken by the IASB in finalising the Amendments.
Initial stakeholder feedback
A18Ahead of the publication of the Amendments, the Secretariat gathered preliminary views of the UKEB's Accounting Firms & Institutes Advisory Group (AFIAG), the Investor Advisory Group (IAG) and the Preparers Advisory Group (PAG). Overall, the increased transparency on the use of supplier finance arrangements was welcomed, particularly by the IAG, albeit with some potential application challenges highlighted by the PAG and the AFIAG.
18 May 2023 Agenda Paper 4: Appendix A
Project milestones
A19A proportionate approach is proposed, incorporating the mandatory milestones listed in paragraph 6.11 of the UKEB's Due Process Handbook (Handbook)11. The table below provides a brief description of the work we have done and/or that we intend to do as part of this project.
A20Future dates are based on current expectations and are, therefore, subject to subsequent modification. The Board will be alerted to any significant changes.
| Milestone/activity | Brief description | Status |
|---|---|---|
| Project initiation activities | ||
| Technical project added to UKEB technical work plan (mandatory) [Handbook 4.30 (d)] | Added to UKEB technical work plan. | Added to work plan (to be approved by the Board at this meeting - May 2023). |
| Board Education session (optional) [Handbook 4.10] | The Board had an education session on the Exposure Draft of the Amendments in December 2021. In December 2022, the Board was provided with an update on the IASB's redeliberations. | Completed at December 2021 and December 2022 Board meetings. |
| Project Initiation Plan (mandatory) [Handbook 6.11] | This paper. | - |
| Desk-based research [Handbook 6.17] | The Secretariat has reviewed:
|
To be completed once the Amendments are published by the IASB |
18 May 2023 Agenda Paper 4: Appendix A
| Milestone/activity | Brief description | Status |
|---|---|---|
| The Secretariat will review the Amendments, once published, to assess whether there are any significant changes compared to the proposals in the ED and to the IASB's redeliberations that would require consideration. | ||
| Other mandatory milestones | ||
| Issue of a DECA (mandatory) [Handbook 6.23-6.26] | The Secretariat will develop a draft Endorsement Criteria Assessment (DECA) to assess whether the Amendments meet the UK's statutory requirements for adoption. | To be completed. Subject to timely publication of the Amendments by the IASB, we expect to bring the DECA for discussion to the July 2023 meeting. |
| Minimum outreach activities (mandatory) [Handbook 6.18 - 6.22] |
|
To be completed. Subject to timely publication of the Amendments by the IASB, DECA publication for comment expected in July 2023. Targeted outreach activities are ongoing and will continue during the DECA comment period. |
18 May 2023 Agenda Paper 4: Appendix A
| Milestone/activity | Brief description | Status |
|---|---|---|
| Consultation period for the DECA (mandatory) [Handbook 6.28] | The DECA will be issued for comment for 90 days. | To be completed. Subject to timely publication of the Amendments, DECA comment period expected to be late July – October 2023. |
| Project closure [Handbook 6.30] | The project closure process for endorsement projects will comprise the following mandatory steps.
|
To be completed. Subject to timely publication of the Amendments by the IASB, we expect to bring the Adoption Package for discussion and approval to the November 2023 meeting. The final Due Process Compliance Statement is expected to be brought for noting to the December 2023 meeting. |
18 May 2023 Agenda Paper 4: Appendix A
Resources allocated
A21On the basis of the project plan set out above, we consider that a project team consisting of one Project Director supported by a Project Manager, with oversight provided by one Senior Project Director, should be sufficient to ensure the project timelines are achievable.
A22In addition, we plan to obtain input from the economics team to develop the contents of the economic impact assessment and the legal team, if such issues arise during the course of this project.
Setting-up an ad-hoc advisory group is not necessary
A23Given the narrow-scope nature of the Amendments and initial feedback, it is not considered necessary to set up a separate, ad-hoc advisory group specific for this project. Instead, the existing UKEB Advisory Groups have already been consulted at the influencing stage, and will be further consulted on the adoption criteria assessment, as appropriate.
Project timeline
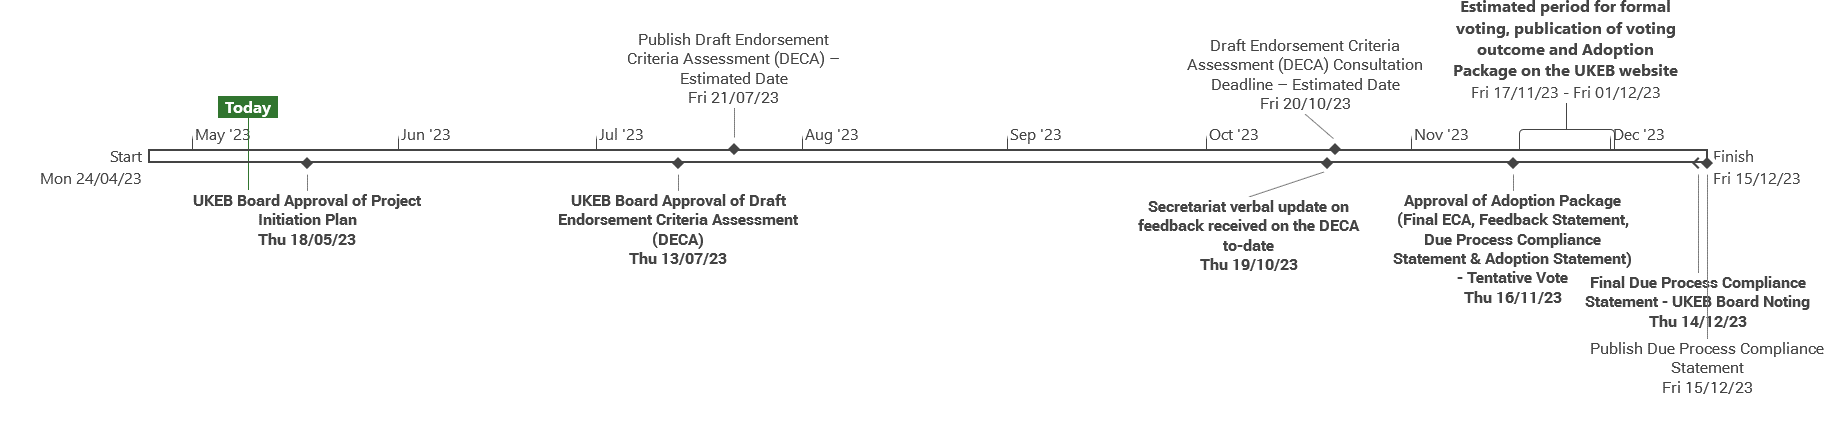
A24The proposed high-level project timeline, based on current expectations and subject to timely publication of the Amendments by the IASB, is as follows:
| Date | Milestones |
|---|---|
| 18 May 2023 | Presentation of Project Initiation Plan for approval |
| 13 July 2023 | Presentation of Draft Endorsement Criteria Assessment (DECA) for approval |
| DECA consultation period (90 days): Late July – October 2023 | |
| 19 October 2023 | Verbal update to the Board on feedback received on the DECA up to that date. (The DECA consultation period is not expected to have finished by then). |
| 16 November 2023 | Consideration of Adoption Package |
| Board members provide a tentative vote | |
| Mid-November – early December 2023 | Estimated period for formal voting, publication of voting outcome and Adoption Package on the UKEB website |
| 14 December 2023 | Due Process Compliance Statement for noting |
19 January 2023 Agenda Paper 4: Appendix A
Footnotes
-
The statutory adoption criteria are in Regulation 7 of The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 no. 685 (the Regulations, or SI 2019/685) ↩↩
-
Also often referred to as supply chain finance, payables finance or reverse factoring arrangements. ↩
-
A table comparing the IASB proposals in the ED and the IASB's tentative decisions made in November 2022 is presented in Appendix A to IASB Agenda Paper 12A (February 2023) here. ↩
-
Guidance on implementing IFRS 7 paragraph IG18. ↩
-
Non-mandatory guidance includes bases for conclusions, dissenting opinions, implementation guidance and illustrative examples, together with the IFRS practice statements. This categorisation is set out in the introduction to the IASB yearly Bound Volumes. ↩
-
UKEB Dec. 2022, Agenda Paper 6, General IASB update, paragraphs 17-29. ↩