10 Approval of Due Process Handbook – Feedback Statement
14 December 2022 Agenda Paper 10
Executive Summary
| Project Type | UKEB Set-up |
| Project Scope | N/A |
This paper presents a feedback statement on the UKEB's consultation on its Due Process Handbook (Handbook) for Board approval.
Summary of the Issue
The Handbook was issued for comment on 21 February 2022 and was open for comment until 6 June 2022. The Board discussed the comments received at its July and September 2022 meetings and approved a revised version of the Handbook at its October 2022 meeting. The Secretariat addressed all comments in the final version of the Handbook.
The Due Process Handbook feedback statement summarises the main issues raised by respondents during the UKEB's public consultation of the draft Due Process Handbook and explains how those issues have been addressed.
Decisions for the Board
Board members are asked, subject to any comments made at the meeting, whether they approve the Due Process Handbook feedback statement for publication.
Recommendation
We recommend that, subject to any amendments at the meeting, the Board approves the Due Process Handbook feedback statement for publication.
Appendices
Appendix A Due Process Handbook Feedback Statement
Foreword
"The UK Endorsement Board is pleased to present a summary of the feedback received from stakeholders on the UKEB Due Process Handbook (Handbook).
The Handbook sets out the due process the Board applies to its activities, enabling it to uphold its guiding principles of accountability, independence, transparency and thought leadership when fulfilling its statutory functions.
We are grateful for the constructive and insightful views from UK stakeholders in the development of this Handbook".
Pauline Wallace, Chair, UK Endorsement Board
Function of the UK Endorsement Board
The UKEB is responsible for endorsement and adoption of IFRS for use in the UK and is therefore the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation on the development of new standards, amendments and interpretations.
Purpose
-
This feedback statement summarises the main issues raised by respondents during the UKEB's public consultation of the draft Due Process Handbook (Handbook) and explains how those issues have been addressed.
-
The Handbook sets out the due process that the UKEB follows in carrying out its statutory functions, which consist of:
- The Handbook also describes additional due process steps that the UKEB follows for carrying out its other activities (thought leadership, research programme, post-implementation reviews (PIR); and setting up and operating advisory groups).
Visual representation of the "Due Process Handbook" cover with text: "Due Process Handbook UK Endorsement Board December 2022". This is a supporting visual, not part of the main text flow.
Background
The draft Handbook was published for public consultation on 21 February 2022 and was open for comment until 6 June 2022 (for 105 days).
During the consultation period, the UKEB and its Secretariat promoted awareness of the Handbook and encouraged stakeholders to respond through News Alerts and advertising through the usual channels.
All stakeholder comments were considered in finalising the Handbook.
Stakeholder submissions received were made public on the UKEB website.
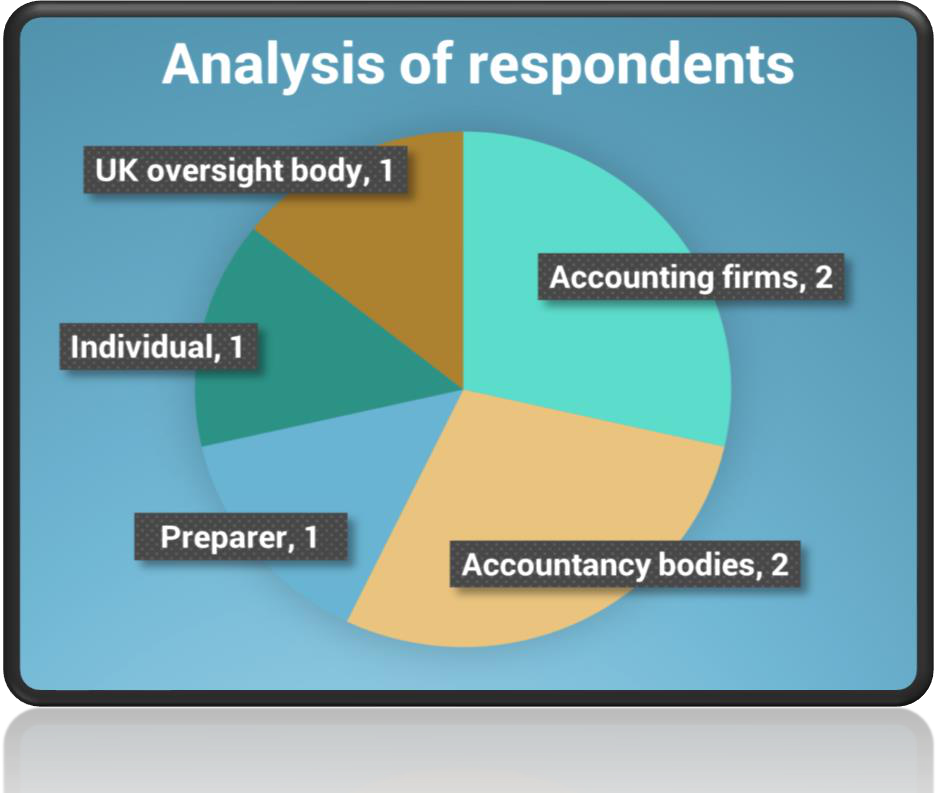
The Board received six comment letters.
The UK oversight body (FRC) provided additional feedback.
Overall assessment
Respondents thought that the processes described in the Handbook provide an adequate framework for the UKEB's due process activities and were generally supportive of these processes.
Respondents raised detailed comments and suggestions.
The FRC's feedback was similar in nature to the other respondents' comments and was addressed as part of the Secretariat's analysis.
At its July and September 2022 meetings, the Board reviewed and provided comments on the Secretariat's preliminary assessment of the comments received and planned drafting amendments on the issues identified by respondents.
The Board subsequently discussed and approved a revised version of the Handbook at its October 2022 meeting.
The next sections in this feedback statement summarise the main issues raised by respondents during the UKEB's public consultation of the Handbook and explain how those issues were addressed.
Substantive issues identified
Section 3: Terms of Reference and Guiding Principles
- Application of the proportionate approach
- Review of the quality and effectiveness of the UKEB's activities and "lessons learnt"
Section 4: Governance activities
- Voting process for reviewing the Handbook and request to add the UKEB complaints policy
- Process regarding the UKEB's ability not to adopt a standard in full
- Requirements for prioritising projects in the UKEB workplan
Section 5: Influencing process
- Process for monitoring activities
- Milestones
- Shortening the comment period of a draft comment letter
Section 6: Endorsement process
- Minimum outreach activities
- DECA content and situations for shortening the comment period of a DECA
Section 7: Thought leadership and research programme
- Timing and frequency of engagement with UK stakeholders
- Milestones for research projects and situations for shortening the comment period of a research document that invites comments
- Whether the UKEB will issue interpretive guidance
Section 8: Post-implementation reviews (PIRs)
- Objective and process for carrying out PIRs
- Definition of "significant change in accounting practice"
Comments by respondents and final revisions
Section 3—Terms of Reference (ToR) and Guiding Principles
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Application of the proportionate approach | ||
| Specified that non-mandatory milestones may also be considered, as appropriate, to achieve an overall approach to the project that is proportionate to the significance and complexity (i.e. nature or scope) of the project (i.e. relevant standard or amendment), size of the issue and the expected timeline. | One respondent observed that considering whether to pursue a non-mandatory milestone should not be optional and the Board should explain why an optional milestone will not be pursued. In addition, this respondent observed that 'nature or scope' can be related to the significance of the project but not to its complexity and suggested additional edits to clarify the application of the proportionate approach. |
The Board confirmed its view that non-mandatory milestones may only be considered as appropriate and if undertaken, will be reflected in the project initiation plan. Some further revisions were made to indicate that the Board may decide not to undertake a 'mandatory milestone' for a particular project and to explain the application of a proportionate approach (i.e. the activities undertaken should be proportionate to the significance, urgency, complexity (nature or scope), size, expected timeline and expected interest or controversy attached to the project. |
| Review of the quality and effectiveness of the UKEB's activities and “lessons learnt” | ||
| Did not include a requirement to undertake a review of the quality and effectiveness of the UKEB's influencing and endorsement activities. | Many respondents observed that the Handbook should include a new requirement to undertake a review of the quality and effectiveness of the UKEB's influencing and endorsement activities and that this review could assess, for example, whether there are “lessons to be learned” from projects and other engagements. | A new paragraph was included in the Handbook to highlight that the UKEB may decide to undertake a review of a project after its completion so that any "lessons learnt” can be incorporated into the process for future projects. |
Section 4—Governance activities
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Voting process for reviewing the Handbook and request to add the UKEB complaints policy | ||
| Did not include requirements for approving or reviewing the Handbook or described the UKEB complaints process. | Respondents suggested clarifying:
|
The following was added in response to the comments received:
|
| Process regarding the UKEB's ability not to adopt a standard in full | ||
| Described the voting process requirements for adopting a new or amended standard in line with the UKEB ToR. | Some respondents suggested creating additional steps to ensure standards are always endorsed in full by the UKEB. | The Board observed that the UKEB has a statutory obligation to consider whether adoption is appropriate, not to ensure there is always full adoption. Consequently, no revisions were made to the Handbook in this respect. |
| Requirements for adding and prioritising projects in the UKEB Workplan that are important to UK stakeholders | ||
| Explained that the UKEB's technical workplan is driven by the IASB's workplan. The UKEB then prioritises and allocates resources to projects based on their priority in the UK. | One respondent suggested the UKEB to be proactive in identifying UK-specific issues either by bringing them to the IASB's attention or by adding them to its work plan. Two respondents suggested adding "the need to align with the IASB effective date of a new or amended standard” or the "size of UK entities affected" as factors for prioritising technical projects. |
The Board observed that individual projects that are important to UK stakeholders and that impact UK entities are already being prioritised, so no revisions were made to the Handbook in this respect. The following paragraphs were added in response to the respondents' suggestions:
|
Section 5—Influencing process
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Process for monitoring activities | ||
| Did not include references to the UKEB's monitoring activities. | One respondent suggested the inclusion of a "monitoring" stage of influencing projects in Section 5 ("Influencing processes") of the Handbook. | In response to the comments received, a reference was included in Section 5 of the Handbook that the Secretariat will be proactively monitoring projects being undertaken by the IASB and IFRS Interpretations Committee and will be providing the Board with regular updates. |
| Milestones | ||
| The following milestones were not considered mandatory: a draft comment letter (DCL) outreach activities and a feedback statement. | Some respondents observed that following milestones should be made mandatory: a 'draft comment letter' (DCL), 'outreach activities' and a 'feedback statement' (if the UKEB issues a DCL for public comment). | In response to the comments received the Handbook now clarifies that:
|
| Situations for shortening the comment period of a draft comment letter | ||
| The consultation period of a DCL could be shortened to a period of less than 30 days where amendments are minor and meet the criteria for annual improvements or for narrow-scope amendments and where there is limited time to consult. | Respondents observed that:
|
The length of the shortened comment period of a DCL was not modified. The only situation where the comment period for a DCL can be shortened is when there is limited time to consult. |
Section 6—Endorsement process
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Minimum outreach activities | ||
| Described the situations in which the UKEB carries out minimum outreach activities(i.e. when amendments are minor and when there is limited time consult). | Respondents suggested adding:
|
A rebuttable presumption is not needed because the Board clarified that the UKEB will always undertake some type of outreach activity to gather feedback on the DECA. No amendment was made to limit the amount of outreach based on previous success at the influencing stage since the endorsement process requires different considerations. |
| DECA content and situations for shortening the comment period of a DECA | ||
| Described the processes for conducting a formal assessment of whether the new or amended standard met the endorsement criteria in line with the requirements in SI 2019/685 and the situations for shortening the length of the consultation period of a DECA to not less than 14 days. | Some respondents suggested:
|
The Board observed that the requirements in the Handbook are in line with SI 2019/685 (and are separate from the IASB's Conceptual Framework). Some further revisions were made to the Handbook to clarify that the DECA should also consider:
* Where a Board member does not support the adoption of a new or amended standard, this should be reflected in the DECA, in the Board discussions and consequently in the Board member's vote. |
Section 7—Thought leadership and research programme
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Timing and frequency of engagement with UK stakeholders | ||
| Explained how the UKEB carries out its thought leadership objectives. | One respondent suggested explaining in addition, the timing and frequency of the UKEB's engagement with UK stakeholders. | No further revisions were made to the Handbook as the Board observed that the level of engagement with UK stakeholders will be project-specific and will depend on the nature, scope or complexity of the project. |
| Milestones for research projects and situations for shortening the comment period of a research document that invites comments | ||
| The following milestones were not considered mandatory: 'identification of issues for research', 'outreach activities' and a 'feedback statement'. | Some respondents observed that following milestones should be made mandatory: 'identification of issues for research', 'outreach activities' and a 'feedback statement' (if a research document invites stakeholder comments). | The Board agreed with the respondents' suggestions but observed that ‘outreach activities' is not a mandatory activity for research projects (e.g. research may just include desk-based research). The Handbook additionally clarifies that:
|
| Whether the UKEB will issue interpretive guidance as part of its research activities | ||
| Explained that in leading the UK debate the UKEB develops 'its own views' and that UKEB's research may have a 'problem-solving orientation'. | A few respondents observed that the UKEB developing “its own views" and the UKEB research having a "problem-solving orientation” are statements that are ambiguous and potentially misleading as they may imply that the UKEB will be interpreting Standards. | The Board considered that the statements in the Handbook highlighted by those respondents are not ambiguous and do not lead to the UKEB issuing technical advice and/or interpretations of the Standards. Consequently no further revisions were made to the Handbook in this respect. |
Section 8—Post-implementation reviews (PIRs)
| Draft Handbook requirements | Stakeholder views | UKEB final revisions to the Handbook |
|---|---|---|
| Objective and process for carrying out post-implementation reviews | ||
| Described the processes for undertaking post-implementation reviews in line with the requirements in Regulation 11 in SI 2019/685. | One respondent suggested clarifying:
|
In response, revisions were made to Section 8 of the Handbook to clarify the different processes applicable to post-implementation reviews of standards adopted under different regulations (i.e. standards adopted under Regulations 4 and 6 and subsequent reviews) and to clarify the processes that will be followed if:
|
| Definition of 'significant change in accounting practice' | ||
| Defined a 'significant change in accounting practice' as usually occurring when a new standard was issued by the IASB and when it had a widespread effect on many entities or a material effect on a few entities. | Some respondents observed that:
|
In response to the comments received, the definition of “significant change in accounting practice” was revised. A "significant change in accounting practice” will usually depend on the number of entities affected and the impact on those entities. Assessment of an amendment or standard as leading to a "significant change in accounting practice” may require judgement and will usually occur when a new standard is issued by the IASB. |
Disclaimer
- This feedback statement has been produced in order to set out the UKEB response to stakeholder comments received on the draft Due Process Handbook and should not be relied upon for any other purpose.
- The views expressed in this feedback statement are those of the UKEB at the point of publication.
- Any sentiment or opinion expressed within this feedback statement will not necessarily bind the conclusions, decisions, endorsement or adoption of any new or amended IFRS by the UKEB.
Contact Us
UK Endorsement Board
1 Victoria Street | London | SW1H 0ET | United Kingdom