5.0 Research Project on Intangibles – Draft Report, amended PIP and response to EFRAG
Executive Summary
| Project Type | Thought Leadership |
|---|---|
| Project Scope | Significant |
| Purpose of the paper |
This paper provides sections of the draft report of the Qualitative Research Project on Intangibles currently being conducted, an amended Project Initiation Plan (PIP) and a proposed response to the EFRAG report Better Reporting on Intangibles based on our research findings to date.
Summary of the Issue
Subsequent to the Project Initiation Plan (PIP) approval at the April 2022 UKEB meeting, the project team has been working on developing a report into stakeholder views on accounting for intangibles, drawing on qualitative research based on in-depth interviews with a range of stakeholders. A draft of the first half of the report is attached as Appendix 1.
The PIP has been amended to better reflect the nature of research as previously agreed with Board and to better reflect current [draft] due process. Specifically, and contrary to previous expectations, no draft report with an invitation to comment will be published. These amendments are reflected and explained in proposed amended PIP (see Appendix 2). This change will only impact interim milestones but the final report will be published according to the same expected deadlines. Therefore, the UKEB's ability to influence the IASB project is not expected to be impacted.
Appendix 3 is a draft response to the EFRAG report Better Reporting on Intangibles. The response reflects the research findings from the stakeholder interviews previously discussed with the Board.
Decisions for the Board
The Board is asked to:
- provide comments on the draft report;
- approve the amended PIP; and
- approve the response to EFRAG.
Recommendation
We recommend the Board approve the amended PIP and response to EFRAG
Appendices
| Appendix 1 | Draft Qualitative Research Report: UK Stakeholder Views on Accounting for Intangibles |
| Appendix 2 | Amended Project Initiation Plan |
| Appendix 3 | Response to EFRAG Report: Better Reporting on Intangibles |
Background
1In one of his first public statements the then new chair of the IASB, Dr Andreas Barckow, stated that “the rise of self-generated intellectual property and its non-addressal in the accounts" was one of the biggest challenges and opportunities facing the IASB. This reflected growing stakeholder concerns about the accounting for intangibles
2In April 2022, the IASB confirmed that a research project on intangible items would be one of three projects to be added to their work plan after the completion of the third agenda consultation.
3The IASB staff paper presented at the time stated that:
"[an intangibles] project should aim to comprehensively review IAS 38. Although developing enhanced disclosure requirements (such as disclosures about unrecognised intangible assets) would help to address user information needs, feedback indicates that other aspects of IAS 38 also should be reviewed. For example, respondents said that IAS 38 is an old Accounting Standard in need of modernising to reflect the increasing importance of intangible assets in today's business models.”
4The IASB website currently states that, “This project will aim comprehensively to review the accounting requirements for intangible assets. Initial research will seek to identify the scope of the project and how best to stage work on this topic to deliver timely improvements to IFRS Accounting Standards.” To date no specific timeline is provided.
5In early 2022, the UKEB agreed to undertake a multi-output, proactive research project that would contribute to the international debate on Intangible items. The research is to focus on how the accounting for, and reporting of, Intangible items could be improved to provide investors with more useful general purpose financial statements to assist them to make better informed decisions.
6The initial phase of the research is focused on understanding stakeholder views (particularly investors) of the accounting for, and reporting of, intangibles in the UK. This involves three outputs:
- A report drawing primarily on qualitative research based on in-depth interviews with a range of stakeholders, supported by a review of key literature. This report is the focus of the current board paper and discussed in more detail in the next section.
- An analysis of Intangibles Reporting in the UK, focused on estimating the prevalence and economic relevance of intangible items among UK reporters, an analysis of current practices among listed UK companies using IFRS standards, including capitalisation and expensing, along with associated disclosures. An analysis of whether and how current reporting practices affects economic outcomes may also be conducted.
- A report, and recommendations, based on more comprehensive investor outreach, further developing the learnings from the early qualitative research. The primary research will be based on outreach with investors, including interviews and a survey.
Draft Qualitative Research Report: UK Stakeholder Views on Accounting for Intangibles
7As set out in the Project Initiation Plan (PIP) approved in April 2022, the UKEB project team has been working on a report into stakeholder views on the accounting for intangibles, drawing primarily on qualitative research based on in-depth interviews with a range of stakeholders, supported by a review of key literature. The research is explorative by design. Its aim is to provide a better understanding of UK stakeholders' perspectives on the accounting for, and reporting of, intangibles in the UK, and the potential economic outcomes arising from the existing accounting framework. The report will form the basis for later research that will provide more explicit recommendations to the IASB. This research will also be brought to the attention of EFRAG in response to its Better Reporting on Intangibles project, together with a dedicated response to their questions on the topic.
8The primary focus of the intangibles research has been:
- Finding and assessing relevant literature on the topic both in the fields of accounting and economics.
- Conducting quantitative analyses to estimate the prevalence of intangible capital/assets in the UK, using both companies' and macroeconomic data.
- Developing interview questions: the review of the literature provided context for the design of a semi-structured interview approach.
- Identifying and approaching potential interviewees as well as undertaking interviews. We have identified and approached stakeholders directly through established network links and LinkedIn searches, as well as through calls in the UKEB news alert, an open call on our website, LinkedIn posts and snowballing1.
- In June the Board asked the project team to increase the number of interviews conducted, and in particular to identify additional users of financial statements to interview. As shown in table 1 below we were able to double the number of interviewees.
### Table 1: Overview of Interviewed Stakeholder Background
| Stakeholder background | Number of interviewees end May | Number of interviewees end July | |------------------------|--------------------------------|---------------------------------| | User | 4 | 13 | | Preparer | 4 | 6 | | Auditor | 2 | 2 | | Standard Setter | 2 | 2 | | Academic | 3 | 6 | | Other | 1 | 4 | | | 16 | 32 |
- The additional interviews have enhanced the research by allowing us to engage with more perspectives on accounting for intangibles. However, this meant that the team had to analyse a substantially increased amount of data to be incorporated into the final report.
- In June the Board asked the project team to increase the number of interviews conducted, and in particular to identify additional users of financial statements to interview. As shown in table 1 below we were able to double the number of interviewees.
### Table 1: Overview of Interviewed Stakeholder Background
- The report is comprised of the following sections:
- Executive summary
- Introduction (see Appendix 1)
- The economics of intangible capital (see Appendix 1)
- Economics literature on the topic
- Economic prevalence of intangible assets
- Stakeholders' views – summary of the results
- Main issues with IAS 38 (see Appendix 1)
- Suggestions on how to improve IAS 38 (draft in November)
- Specific issues, including materiality (draft in November)
- Conclusions (draft in November)
- Report Appendices
- Methodology (See Appendix 1)
- References
10Board member feedback on the content of the draft sections as well as on the style and tone are welcome.
11As this is a draft, some content is still to be finalised, including cross-referencing (currently highlighted) and additional “boxed” content that will be added in limited cases as additional detail on specific topics. This content will be provided in November.
12The stakeholders' views on how to improve IAS 38, other specific matters raised, and conclusions will be submitted at the November Board meeting.
13During Q4 2022 the project team intend to discuss this research with two of the Board's advisory groups: the Preparers Advisory Group (PAG) in October, and the Accounting Firms & Institutes Advisory Group (AFIAG) in November. Their views will bolster our research findings and are expected to be incorporated as appropriate in subsequent drafts of the report.
Questions for the Board
14Does the Board have any comments on:
- The contents of:
- The introductory section?
- The economics section?
- The stakeholder concerns with IAS 38 section?
- Overall tone and style of the report?
- Any other comments or suggestions?
Amended Project Initiation Plan (PIP)
15The intangibles project is the first significant pro-active research project undertaken by the Secretariat and Board. Given this project has been on-going in parallel with the development of the Board's due process handbook (the Handbook), it has necessitated revisions of the original April PIP to ensure alignment with the Handbook. We believe going forward the need for revision will be reduced as we incorporate lessons learned from this and the Goodwill research projects into future projects.
16However, by their nature research projects, especially large ones, evolve over time. The Secretariate have taken an approach that uses footnotes to date-stamp changes over time; feedback from the Board on this approach is welcome.
17The most substantive changes in the October 2022 PIP relate to the removal of the Invitation to Comment and changes to the timetable for outputs.
Amendments to Due Process
18In April and July 2022, the PIP had classified the first output, the qualitative research report, as a discussion paper. At that time, the [Draft] Due Process Handbook required a discussion paper to be accompanied by an Invitation to Comment. As a result, the PIP proposed a 30-day consultation period. In July 2022, this was amended to a 90-day consultation period to be consistent with the [Draft] Handbook requirements. Subsequently, the Board has discussed the due process for research projects, resulting in a number of amendments, including clarifying when an Invitation to Comment is necessary (para 7.12) and noting (para 7.11(e)) that research studies may now be quantitative, qualitative or survey based.
19This qualitative research report will summarise the feedback received during outreach undertaken but will not include preliminary or final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, under the current [Draft] Handbook (paragraph 7.11(e)) this report better fits as a research study that summarises the input received from a qualitative study, removing the need for an invitation to comment or comment period when this report is published (consistent with [Draft] Handbook para 7.12.
Amendments to Timetable of Outputs
20The following table presents the timings for outputs proposed in the April, July and October 2022 PIPs. There have been substantial changes proposed in response to a number of factors:
- Feedback from the Board on the project.
- Lessons learned from both the current research project and the goodwill research project.
- Ensuring time to engage with advisory groups during development and analysis phases of research.
- Reflections on resources (staff and Board) including other projects being undertaken.
- Allowing Board time to engage with research across the life of the project, and having adequate time to review draft reports.
- Incorporating sufficient time to gather and analyse stakeholder feedback given level of interest in the project.
21It is particularly evident that the April PIP was ambitious, as noted by the Board at the time.
Table 2: Amended Project Milestone Timings
| Key Milestone | April PIP | July PIP | Oct. PIP |
|---|---|---|---|
| Qualitative Research Report | |||
| Complete Interviews | May 2022 | July 2022 | July 2022 |
| First Draft | July 2022 | Sep. 2022 | Oct. 2022 |
| Final Report | Sep. 2022 | Jan. 2022 | Jan. 2022 |
| Quantitative Research Report | |||
| Complete Research | Sep. 2022 | Nov. 2022 | Apr. 2023 |
| First Draft | Oct. 2022 | Dec. 2022 | May.2023 |
| Final Report | Dec. 2022 | Mar. 2023 | July 2023 |
| User Survey | |||
| Complete Survey | Oct. 2022 | Jan 2023 | Aug. 2023 |
| First Draft | Dec. 2022 | Apr. 2023 | Dec. 2023 |
| Final Report | Feb. 2023 | Jun. 2023 | Mar. 2024 |
22Based on this we propose amending the project PIP as shown at Appendix 2. The key amended text is highlighted in grey in that document, and we have included footnotes where appropriate to date-stamp and explain changes.
Questions for the Board
23Does the Board:
- have any comments on the amended PIP; and
- approve the amended PIP?
Response to EFRAG Report Better Reporting on Intangibles
24The Secretariat believe there is an opportunity to respond the EFRAG Report Better Reporting on Intangibles. Using the summaries of findings already presented to the Board at previous meetings we have prepared a response to the specific questions asked by EFRAG. See Appendix 3.
25This is in addition to the ongoing conversations the UKEB have had with EFRAG staff about our research, and the public board papers they have had access to and have discussed with the team.
Questions for the Board
26Does the Board:
- have any comments on the draft response to EFRAG; and
- approve finalisation and submission of the response to EFRAG?
Intangible items and IFRS Accounting
Introduction
“The biggest challenge I see is to remain relevant in an ever-changing environment. While I think that our literature has generally stood the test of time, there have been changes in the environment that clearly could not have been anticipated when the Standards were developed. I am thinking of economies becoming more service than manufacturing oriented... as well as the rise of self-generated intellectual property and its non-addressal in the accounts"
Chair of the IASB Andreas Barckow1
1Following the results of the Third Agenda Consultation completed in July 2022, the International Accounting Standards Board (IASB) has announced that it expects to review the accounting requirements for intangibles within the next few years2. While the nature and scope of the project are yet to be finalised, the project has been positioned as a “comprehensive review”3.
2The IASB noted that many stakeholders responding to the Third Agenda Consultation "highlighted deficiencies in the reporting of intangible assets ...relating to all aspects of IAS 38, including its scope, its recognition and measurement requirements ...and the adequacy of [disclosures]"4.
3The IASB acknowledged that any project on intangibles will likely be large and complex for both the IASB and its stakeholders. They also noted that the project should "aim to address intangibles more broadly”, focusing not just on "assets", but also including intangible items currently expensed.
4In anticipation of an IASB review of intangible items the UK Endorsement Board (UKEB) decided to initiate a research project focussed on understanding UK stakeholders' views on the accounting for intangibles5. The UKEB wanted to understand the concerns with the current approach to the accounting for, and reporting on, intangibles, particularly under IAS 38 Intangible Assets, as well as possible ways in which these could be improved. To obtain a better understanding of the landscape, this report considers both the economics of intangible items alongside the accounting treatment.
5The report takes a qualitative approach, drawing from over thirty one-to-one interviews conducted with a diverse range of stakeholders. The approach provided an opportunity to understand different perspectives from stakeholders across the accounting landscape compared with other methods. The views heard are contrasted with findings from relevant reports and academic papers, in particular contributions focusing on the UK.
6This report draws out some common themes that point to specific attributes stakeholders are looking for in any solution aimed at addressing the accounting for intangibles. The report also provides useful background to inform further research by the UKEB on the topic, with the purpose of eventually supporting its engagement with the IASB's own project on intangibles.
Background
Terminology: Intangibles Assets, Intangible Expenditure, Intangible Items or Intangible Capital?
“In a legal, economic or business-related circumstance, there are many different terms that follow [the] intangible concept: intangibles, intangible assets, intangible values, intellectual capital, intellectual property, knowledge assets, invisible assets. They either characterize a particular area of intangibles or are used interchangeably to designate the intangible vision, in general."7
7To understand stakeholder concerns with the current accounting for intangible items and their views on how to improve it necessitates defining what is meant by "intangibles".
8At its simplest from an accounting perspective the key distinguishing characteristic of intangible items is that they lack physical substance (IAS 38, para 8). This can be contrasted with expenditure on items with physical substance, such as the purchase, or development of, property, plant, equipment, inventory, agricultural items etc.
9As a general rule, the international accounting for intangibles is set out in IAS 38 Intangible Assets, a catch-all standard that is the main focus of this report. However, several other accounting standards address expenditure on specific items that lack physical substance. These are explicitly identified in IAS 38 (para 2-3) to include:
- Financial Assets (IASs 32 and 39, IFRSs 7 and 9)
- Certain assets arising from the exploration and evaluation of mineral resources (IFRS 6)
- Intangible items held for sale in the ordinary course of business (IAS 2)
- Deferred tax assets (IAS 12)
- Lease of intangible assets (IFRS 16)
- Goodwill acquired in a business combination (IFRS 3)
- Insurance contracts (IFRS 17)
- Assets arising from contracts with customers (IFRS 15)
10These items are in general outside the scope of this report, unless otherwise noted.
11In this report we generally use the term “Intangible Assets”, to refer to intangible items specifically recognised in IAS 38, or when quoting stakeholders' responses verbatim. This is because the term "asset” has a general meaning under the Conceptual Framework for Accounting, while the term “intangible asset” has a specific, and potentially different meaning under IAS 38 as is discussed later in this report8.
12We will generally use the term “intangible item” or “intangible expenditure” depending on the context when considering the accounting aspects of recognising, measuring and disclosing information relevant to intangibles. In the economic sections we will use instead the expression “intangible capital”, more common in this literature9.
13IAS 38 also distinguishes between “internally generated” and “purchased” intangibles, with a distinction also captured by academic research10. We will discuss this distinction further in paragraphs XX-XX.
Intangibles under International Accounting Standards – IAS 38
14IAS 38 defines an intangible asset as “an identifiable non-monetary asset without physical substance” (IAS 38, para 8). 'Identifiable' means the asset must be separable or arise from contractual or other legal rights (separable assets can be sold, transferred, licensed, etc.) 'Non-monetary' excludes intangible items that are money held or assets to be received in fixed or determinable amounts of money. In most instances monetary items would be captured by IFRS 9 Financial Instruments.
15The Basis for Conclusions11 for IAS 38 provides the following example of items that can be recognised as intangible assets: “computer software, patents, copyrights, motion picture films, customer lists, mortgage servicing rights, fishing licences, import quotas, franchises, customer or supplier relationships, customer loyalty, market share and marketing rights.”
16Goodwill acquired in a business combination is accounted for in accordance with IFRS 3 and is outside the scope of IAS 38 (see paragraph X). Internally generated goodwill is identified as being within the scope of IAS 38 but is explicitly excluded from recognition as an asset (IAS 38, para 48) because "it is not an identifiable resource" (IAS 38, para 49).
17An intangible asset can only be recognised if:
- the item is controlled by the entity (IAS 38, para 13),
- it is probable that the expected future economic benefits that are attributable to the asset will flow to the entity (IAS 38, para 21)12.
18In addition to these general principles of recognition, IAS 38 explicitly prohibits the recognition of internally generated brands, mastheads, publishing titles, customer lists and similar items as intangible assets. The reason given is that “the cost of generating an intangible asset internally is often difficult to distinguish from the cost of maintaining or enhancing the entity's operations or goodwill.”
19Any other internally generated intangibles are classified as to whether they arise in a research or development phase. According to the Standard, research expenditure must be recognised as an expense. Development expenditure that meets specified criteria can be recognised as an intangible asset at cost.
20These recognition criteria are widely considered as particularly restrictive in the academic literature and industry practice13. This high bar has historically led to relatively few internally generated intangible assets being recognised in financial statements (see paragraphs XX-XX). This, in turn, has triggered discussions as to whether IAS 38 leads to a true and fair view of companies' underlying value14.
21It should be noted that IFRS 3 Business Combinations allows the recognition of all identifiable intangibles in a business acquisition. IFRS 3 does not require an explicit assessment of control or probability of future benefits, nor does it prohibit the recognition of certain types of intangibles, thus imposing a lower threshold for the recognition of intangibles identified in a business combination. This “may result in recognising some assets and liabilities that the acquiree had not previously recognised as assets and liabilities in its financial statements.” (IFRS 3, para 13)15,16.
22Intangible assets that meet the recognition criteria are usually measured at cost (IAS 38, para 24). If an intangible is acquired through a business combination then its fair value is deemed to be its cost (IAS 38, para 33).
23After initial recognition, an entity usually measures an intangible asset at cost less accumulated amortisation (IAS 38, para 74). It may choose to measure the asset at fair value when fair value can be determined by reference to an active market, though this is expected to be "uncommon” (IAS 38, para 78). If the recognition of intangible assets happens in a business combination, they are measured at fair value on the acquisition date (IFRS 3, para 18).
24At initial recognition, an entity must also assess whether an intangible asset has a finite or indefinite life. Some intangibles that may be considered to have indefinite lives include brands and licenses granted in perpetuity. A finite useful life is amortised and is subject to impairment testing. An intangible asset with an indefinite useful life is not amortised but is tested annually for impairment.
25IAS 38, at paragraph 118, includes a number of disclosure requirements, including for each class of intangible assets:
- distinction between internally generated and other intangible assets;
- information on useful lives;
- additions, indicating separately assets arising from internal development, assets acquired separately, and assets acquired through business combinations.
The responses to the IASB Third Agenda Consultations
26Calls for the IASB to address intangibles became much more explicit in response to the Third Agenda Consultation, undertaken in 2021.17,18,19
27For the third agenda consultation, the IASB received 124 comment letters.20 The focus of respondents' concerns was:
- The current standard needs comprehensive review by the IASB as it was published in the 1990s with a focus on manufacturing businesses with primarily tangible assets. The recent shift towards service-oriented businesses is not accommodated properly by the standard;
- Due to the limitation in requirements in IAS 38, accounting for new emerging assets (e.g., emission trading rights, cloud-based computing arrangements and crypto-currencies) and transactions remains challenging;
- Some respondents believe the IASB should revisit the reasons for the differences in the recognition criteria for internally generated intangibles and those acquired separately;
- Many respondents supported the requirement to improve the disclosures of intangibles not recognised as assets;
- A few respondents asked the IASB to consider the potential overlap of sustainability with the intangible items as these are key drivers of sustainable business development and sustainability reporting.
28The UKEB comment letter21 recommended a comprehensive review of IAS 38. Noting that the any IASB review should address:
- The extent to which IAS 38 captures relevant information on intangibles, including those which are becoming more prevalent, such as cryptocurrencies, pollutant pricing mechanisms, software, and development costs, and;
- Whether separate standards addressing non-financial assets would provide more relevant information where intangibles such as crypto-currencies and emissions trading rights are held for investment and trading.
29Other respondents argued that revisiting the recognition and measurement criteria of intangibles could improve comparability, prevent loss of useful information, and better reflect the importance of intangibles.
30Also respondents noted that entities' value creation in the modern era relies significantly on intangible items. Human capital may be the most critical source in the modern knowledge-based economy (see paragraphs XX-XX), but other important intangible items include big data, brand, efficient business processes and customer relationships. Disaggregation of such information about an entity's value creation activities would be helpful for users as it provides insight into an entity's ability to generate future profits and cash flows.
31In April 2022 the IASB confirmed the addition of a research project on intangible items to its work plan.22
32In the UK, debates about the accounting for intangibles calls for an improved accounting standards for intangibles are not new.
33For example in the early 1990s there was
"no shortage of suggestions on how the information flow on R&D between industry and the City (London's financial community) can be improved. For example, valuable recommendations have been made (on the measurement, accounting treatment and disclosure of R&D) in reports by the House of Lords Select Committee on Science and Technology (1991), the Institutional
dMany respondents supported the requirement to improve the disclosures of intangibles not recognised as assets; eA few respondents asked the IASB to consider the potential overlap of sustainability with the intangible items as these are key drivers of sustainable business development and sustainability reporting.
28The UKEB comment letter21 recommended a comprehensive review of IAS 38. Noting that the any IASB review should address:
- The extent to which IAS 38 captures relevant information on intangibles, including those which are becoming more prevalent, such as cryptocurrencies, pollutant pricing mechanisms, software, and development costs, and;
- Whether separate standards addressing non-financial assets would provide more relevant information where intangibles such as crypto-currencies and emissions trading rights are held for investment and trading.
29Other respondents argued that revisiting the recognition and measurement criteria of intangibles could improve comparability, prevent loss of useful information, and better reflect the importance of intangibles.
30Also respondents noted that entities' value creation in the modern era relies significantly on intangible items. Human capital may be the most critical source in the modern knowledge-based economy (see paragraphs XX-XX), but other important intangible items include big data, brand, efficient business processes and customer relationships. Disaggregation of such information about an entity's value creation activities would be helpful for users as it provides insight into an entity's ability to generate future profits and cash flows.
31In April 2022 the IASB confirmed the addition of a research project on intangible items to its work plan.22
32In the UK, debates about the accounting for intangibles calls for an improved accounting standards for intangibles are not new.
33For example in the early 1990s there was
"no shortage of suggestions on how the information flow on R&D between industry and the City (London's financial community) can be improved. For example, valuable recommendations have been made (on the measurement, accounting treatment and disclosure of R&D) in reports by the House of Lords Select Committee on Science and Technology (1991), the Institutional Shareholders' Committee (1992), the Accounting Practices Group of the Chartered Institute of Management Accountants (1992) and the International Accounting Standards Committee (1993)."23
34The FRC, in its role as national standard setter, has undertaken two major projects on Intangible Assets.
35. FRC ARP Staff Research Report: Investor Views on Intangible Assets and their Amortisation (March 2014)
36In 2014, the FRC undertook a research project: 'Investor Views on Intangible Assets and their Amortisation' to understand the investors' views on intangible assets and whether the reporting requirements in IAS 38 provided useful and reliable information. Overall, investors had mixed views. The paper highlighted several concerns with the accounting for intangibles, especially when acquired in business combinations. The main findings were:
- Half of the respondents wanted different accounting treatment to those required by IAS 38;
- Some investors distinguished intangible assets into two types: 'wasting intangible assets' (i.e. with a defined useful life) and 'organically replaced intangible assets' (i.e. with no defined useful life) and suggested amortisation of wasting intangible asset and an impairment only model for organically replaced intangible assets;
- Others suggested an impairment review rather than periodic amortisation for all intangible assets acquired in business combination;
- With regard to internally generated intangible assets:
- most respondents agreed with capitalising development costs for internally generated assets in line with IAS 38;
- a few suggested capitalising research costs whilst others suggested to expense all R&D, even at development stage. The most common reason given was the quality of disclosures and lack of consistent application for capitalisation of assets.
- More respondents favoured the periodic amortisation of these assets than those acquired in business combination.
- In contrast many investors expressed views that the separately acquired intangible assets should be capitalised and amortised annually.
37Ultimately, most investors were dissatisfied with the quality of disclosures, especially as the information about the objective of business combinations and the purpose of intangible assets acquired was not always provided, and then used to perform post-acquisition reviews.
38. Business Reporting of Intangibles: Realistic proposals A Discussion Paper prepared by staff of the UK Financial Reporting Council (February 2019)
39The FRC issued the paper 'Business Reporting of Intangibles: Realistic proposals' was published in 2019 to add to the international debate and gather stakeholders' views to influence the IASB. The objective of this paper was to explore reasons why intangibles are not fully reflected in financial statements and to develop practical proposals to improve business reporting.
40The report concluded that the definition of assets and recognition criteria in the Conceptual Framework restricted the recognition of many intangibles. Given the revision of the Conceptual framework during 2018, the paper considered that the reporting of intangibles could be enhanced within the new framework, especially the information about the value of internally generated intangibles. It also considered the possibility of addressing the reporting of intangibles outside of the financial statements e.g. in narrative reporting.
41Disclosures about expenditure on intangibles were highlighted as an important area of improvement. The report noted that there was poor disclosure about 'future oriented intangibles' which are expensed in current period with a view to drive benefit in subsequent accounting periods. Better disclosure would go some way to address the issue of earnings management as there is a time lag between incurring expenditure on intangibles and return received from it in future.
42In addition to the above, narrative reporting in management commentary section of an annual report was identified as another way to enable provision of information on unrecognised intangibles, focusing on those intangibles that are relevant to entity's business model, requiring common metrics and agreed definitions and calculations to promote comparability of information on intangibles over several periods and within the same industry.
Conclusion
43Concerns about the accounting for intangible items are not new. Recognition, measurement and disclosure all were identified as areas of concern. This has led, both internationally and in the UK, to calls for a different approach.
44At the heart of these concerns is that the accounting does not reflect the economics when it comes to Intangible items. This is a key concern. The Conceptual Framework of Accounting posits that “Financial reports represent economic phenomena in words and numbers. To be useful, financial information must not only represent relevant phenomena, but it must also faithfully represent the substance of the phenomena that it purports to represent." (para 2.12, emphasis added).
45Similar concerns arose during stakeholders' interviews. The results are discussed in a subsequent section of this report (paragraphs XX-XX).
46The next section examines the economics of intangible items to provide the reader with a framework to better understand both the current accounting practices, the concerns stakeholders have about them, and any potential solutions proposed in other papers and by our interviewees.
Intangibles: economic context
47This section considers intangible capital from an economic perspective. Specifically, it focuses on its absence from national accounts and contribution to growth at a national level (macroeconomics), its contribution to companies' performance and KPIs (microeconomics), and its effect on companies' returns and price informativeness (financial economics).27 It then considers the prevalence of intangible capital in the UK economy, focusing on both individual companies' and national accounts.
48Economic information is aimed at helping contextualise the current accounting treatment of intangibles, the problems associated with the accounting, and any solutions proposed by other literature and stakeholders.
49We show that intangible assets have grown in importance over the last 15 years, but that their prevalence is largely understated due to the current individual and national accounting rules.
Intangible capital: features and economic consequences for firms
50Intangibles have always been a key drive to the innovation of products and processes, productivity, and economic growth. However, in the current state of the economy, commonly labelled as “knowledge economy”, intangible capital plays a bigger and more pervasive role than ever before.28
51The expression “knowledge economy”, was introduced by Drucker (1969), but the real rise of the knowledge economy occurred with the emergence of the “service economy", i.e. an economy skewed towards services and its reduced reliance on manufacturing.29 The transition to the knowledge economy was underpinned by the fast spread of information and communication technology (ICT)30. With respect to the past, the knowledge economy is characterised:
- Greater importance of knowledge-based service sectors;
- A higher proportion of skilled to unskilled workers;
- A greater relevance of research-steered innovation;
- Importantly, a higher reliance on intangible capital for value creation.
52This report refers to the definition of knowledge economy found in Powell and Snellman (2004): "production based on knowledge-intensive activities that contribute to an accelerated pace of technological and scientific advance as well as equally rapid obsolescence. The key components of a knowledge economy include a greater reliance on intellectual capabilities than on physical inputs or natural resources, combined with efforts to integrate improvements in every stage of the production process, from the R&D lab to the factory floor to the interface with customers. These changes are reflected in the increasing relative share of the gross domestic product that is attributable to intangible capital” (emphasis added).
53The economics literature has long recognised the contribution of intangible capital31, broadly understood as “skills, organizational structures and processes, culture, and other factors”32, to firms' productivity and growth, as well as their influence on stock prices.
54However, because of its inherent characteristics, economists have shied away from providing prescriptive definitions for it, besides recognising that to be called "assets" they should be a resource the economic benefits of which are reaped over the long-term.33
55Intangible and tangible capital share some common features: they both have a durable impact on the companies' performance and their returns are reaped over future periods of time. In addition, the value of both tangible and intangible capital depletes over time34.
56Besides these characteristics, economists have identified features that distinguish intangible capital from physical one, the most common and relevant of which are35:
- Invisible: intangible capital lacks physical substance and needs a storage medium36;
- Tacit: intangible capital may be implicit knowledge embedded in people;
- Non-rivalrous: intangible capital can be used simultaneously by multiple users without depleting the asset or reducing its usefulness;
- Partially excludable: property rights over intangible capital cannot always be easily defined or enforced;
- Non-tradable or traded in imperfect markets: intangibles are often internally generated and are often non-fungible and therefore non-tradeable. When they are traded, they are typically traded in imperfect markets;
- Non-separable: intangible capital often cannot be separated from the business where it is created without loss of value; and
- Complementary: intangible capital often adds value in conjunction with other types of capital, either tangible or intangible, and labour.
57These features have important economic consequences commonly found across companies, industries and economies that invest more in intangible capital:
- Higher productivity: because of their complementarity with other capital and the synergies they create within the organisation, intangible capital is found to enhance productivity37;
- Spillover effects (externalities)38: intangible capital is found to have sizable positive spillover effects, and positively to contribute to productivity, salaries, training and enhance skills and human capital well-beyond the boundaries of the firms that invest in them39;
- Network externalities: because of their non-rivalrous and invisible nature, intangible capital is often a main contributor to network effects, which arise when "the value of a good or service increases for both new and existing users as more customers use it; the more existing users there are on a network, the more attractive it becomes for newcomers"40;
- Sunk costs: because investment in intangibles is neither separable from the firm, nor tradeable it is often non-recoverable41;
- Risks and uncertainty: intangible capital is difficult to liquidate, which makes assessing its recoverable value more complicated and lending to companies that invest in intangibles possibly riskier42; and
- Lack of measurability: intangible assets are also notoriously difficult to measure, which makes companies' valuation by equity investors trickier43.
58These characteristics and their economic consequences make the identification and measurement of intangible assets tricky – something that underpins the accounting for intangibles prescribed by IAS 38. Box XX focuses on these issues in greater detail.
Intangible assets in macroeconomics
59The contribution of intangible investment to macroeconomic growth, and the issues of recognising and measuring intangible investment in national accounts, from which they are largely absent, are all heavily researched.
60In its simplest form, the output of a closed economy (that is ignoring international trade) can be described as the sum of three items:
- consumption by households
- investment in productive goods
- government expenditure
61In their seminal contributions, Corrado, Hulten and Sichel (2005, 2006; we refer to their framework as CHS) noted that intangible capital had historically not been considered as an input of production in economic models, where only labour and physical capital were typically introduced. This led to intangible capital being neglected both as investment of productive goods and output itself in national accounts. As a consequence, investment in intangible capital was not accounted for at a national level, with large swathes of GDP and related economic growth being consequently neglected in most economies44.
62Since its publication, the CHS framework has influenced both national and international accounting systems, so that R&D is considered a component of investment in many national accounts45. Unfortunately though many other intangible items (such as brand, training or design) are still not widely accounted for at a national level (see Martin, 2019), though some statistics offices (including the UK ONS) calculate experimental statistics for intangible investment not officially accounted for (see paragraphs XX-XX)46.
63According to the CHS framework, intangible items can be bucketed into three categories47:
- Computerised information: mainly computer software;
- Innovative property: broadly corresponding to R&D
- Economic competencies: comprising brand equity, training and human capital, and organisational capital.
64With reference to the UK, Goodridge, Haskel and Wallis (2014) apply the CHS framework to estimate UK intangible investment at a national level and its contribution to economic growth. While the paper's results are now dated (the most recent set of results displayed in the paper dates back to 2009), the importance of their findings is unaltered. The paper found that, as of 2009, national intangible investment had surpassed tangible investment, and was amounting £124 billion (tangible investment was £94 billion)48. Of these, 70% were internally generated investments. Organisation capital was the largest category, accounting for 21% of the investment, followed by software (18%), design (12%) and R&D (11%).
65Importantly, the authors also estimate that intangible investment positively contributed to national productivity in the UK. According to the authors, during the period 2000-2009 intangible assets accounted for 26% of the growth in value added per hour worked. The joint contribution of intangible capital and tangible investment in ICT (computer and telecommunication) accounted for 45% of the growth in value added per hour worked.
66In separate contributions, these authors have estimated whether unmeasured intangible assets can help explain the UK productivity puzzle, that is an observed slowdown in both labour productivity (output per hour) and total factor productivity observed after the financial crisis (see The Economist, 2022). In a recent paper (Goodridge and Haskel, 2022) the authors estimate that in 2019 the difference between what productivity was and what it would have been following the pre-crisis trend was 28 percentage points, of which roughly 5% could be explained by unaccounted intangible assets. These results confirm previous estimations (Goodridge, Haskel and Wallis, 2013), which suggests that, using the authors' own words, "unmeasured intangibles are part of the explanation of the productivity puzzle, but not all of it". For example, Goodridge, Haskel and Wallis (2016) estimate that 35% of the puzzle could be attributed by slow total factor productivity growth in the oil and gas and financial sector industries.49,50
Intangible assets in microeconomics
67The microeconomics literature has extensively studied the relationship between investment in intangible capital and firm-level outcomes51.
68Many contributions focus their attention on the relationship between intangible capital and firm productivity. With reference to the UK, Riley and Robinson (2011) estimate the impact of the three types of intangible capital identified in the CHS framework on firm-level output and find that they are positively associated with firms' output. The paper emphasises sectorial differences, with intangible capital linked to higher productivity more in the services than in the manufacturing sectors.
69A paper by Marrocu, Paci and Pontis (2011) estimates the relationship between intangible capital and production (measured as value added) at a country level using firm-level and regional data from six European countries, including the UK.52 The paper finds a positive correlation between intangible capital and value added considering all countries together. This relation is stronger when the model is estimated for the United Kingdom only.
70More recent contributions focusing on other countries also establish a positive relation between intangible capital and productivity. See footnote for further details.53
71Other firm-level outcomes have been discussed in the literature. Focusing on UK firms Nemlioglu and Mallick (2017) [summarise paper here]
72Focusing on other countries, Villalonga (2004) finds that intangible capital allows positively affects companies' competitive advantage in the United States; Montresor and Vezzani (2014) using EU data shows a positive relation between intangible capital and productivity; Di Cintio, Ghosh and Grassi (2017) find that intangible capital is associated with more exports and economic growth in Italy54. [summarise paper on intangible assets and credit constraints].
Intangible assets and capital markets outcomes
73Research has shown that firms that invest more in intangible assets are associated with better stock price performance and other positive market outcomes, consistently with the fact that intangible assets are associated with higher profitability and better firms' performance.55
74One empirical regularity in financial economics traditionally explained by the lack of recognition of intangible assets is the market-to-book value puzzle (Lev, 2001), i.e. evidence, largely based on US data, that the market-to-book ratio for value stocks has been disproportionately high for XX years. Lev (2001) suggests that unrecognised intangible assets can largely explain the phenomenon. Hulton and Hao (2008) attempt to solve the puzzle by adjusting book values for intangible. The authors find... [Summarise findings].
75Some recent contributions explore the relation between intangibles and stock prices. Bongaerts, Kang and Van Dijk (2022) find that companies with higher shares of intangible assets outperform companies that invest less in intangibles, generating an economically significant average return of 4.6% per annum. The results hold when excluding big tech firms (Amazon, Apple, Facebook, Google, Microsoft, Netflix and Tesla)56. Eisfeldt, Kim and Papanikolau (2021) note that the tendency of stocks characterised by high market-to-book ratios (“value” stocks) to outperform stocks characterised by low market-to-book ratios (“growth” stocks”) has weakened over the last ten years and attribute this evidence to intangible assets being largely absent from book values.57
76Oswald, Simpson and Zarowin (2020) exploit the transition from UK GAAP to IFRS in 2004/2005 to estimate whether the capitalisation of R&D expenses, mandatory under IFRS, impounds information into stock prices. Using the transition as a natural experiment, they find that capitalisation of R&D information adds relevant information to stock prices. Importantly, they find that pre-IFRS adoption the market could not infer what portion of R&D expenses constituted investment, suggesting that explicit requirements to capitalise intangibles convey relevant information to users of financial statements.
New intangibles
77Both academics and industry practitioners have identified several new intangible asset classes risen to prominence largely as a result of development by US and Chinese tech-firms.58 These intangibles, which could be broadly categorised as “digital assets”, are by and large related to the spread of artificial intelligence (AI) algorithms used by tech companies for different purposes, such as to commercialise their products, enhance user experience, or improve their own decision making.
78Digital capital. A 2020 paper focusing on the US showed that listed firms have become more digital capital-intensive over the last 20 years. The stock of digital capital is disproportionately bigger in firms in the largest decile of market capitalisation, which includes "superstar” tech firms. The authors estimate that digital capital positively contributes to firms' productivity.59
79Big data. Thanks to recent technological advancements, and especially developments in AI technology, (some) companies are now able to collect, store and analyse large amounts of data (including personal data) on an unprecedented scale (hence the name "big data", popularised by the computer scientist John Mashey in the 1990s). This data is used both for commercial purposes and to enhance internal decision-making processes60. Because of big data's increasing importance as a driver of productivity and source of competitive advantage, some contributions have discussed whether personal data can effectively be considered as a stand-alone asset class, and if so, how to measure it.
80A 2021 paper analyses US tech firms' governance practices to infer what constitutes an asset in relation to the economic exploitation of personal data. They conclude that it's not ownership (personal data can't be owned) or access right to the data per se to constitute an asset, but rather the interaction between access rights and technology used to convert that very same data into user metrics to track, record and measure user engagement on their platforms61.
81A 2022 paper62 analyses the issues of classification, recognition and measurement of big data from a more canonical accounting perspective. Although data is usually stored in servers or USB, the authors establish that it is without a physical substance, it is separable and identifiable and therefore meet the requirements of IAS 38 of intangible asset (including controllability, and generation of future economic benefits). The authors assess alternative methods for recognition and measurement: at cost, using net present value and at fair value. The cost approach appears to be the most prudent in their opinion. However, they deem the fair value approach potentially suitable if there are enough of data users and collectors to measure the fair value of data assets, such as the data users accessing data trading centres.
82AI technology and algorithms. (Haskel's paper) on recognition of AI – insert summary here
Crypto-assets
83Crypto-assets. Crypto-assets are [insert definition]. From an economic perspective, most crypto-assets are more akin to financial than intangible assets [PUT REF]. However, the IASB IFRS Interpretation Committee (IFRIC) in March 2019 issued a final agenda decision stating that crypto-assets are to be classified as intangible assets within the IFRS framework. Stakeholders are however not fully satisfied by the agenda decision, as classifying crypto-assets as intangibles does not reflect their underlying economics, as also noted in several academic papers. The debate is open though and some academic contributions endorse IFRIC's view instead. Box XX discusses economics, economic prevalence and accounting treatment of crypto-assets in greater detail.
Economic prevalence
84This section looks at the economic prevalence of intangible assets in the UK economy (using national data) and among UK companies (using individual companies' data). The purpose is twofold:
- To assess whether intangible assets have grown in importance over the last 15 years
- To assess the extent to which intangible assets are missing from both national accounts and companies' balance sheets.
Intangibles in national accounts and economic statistics
85As noted in paragraphs XX-XX, intangible assets have traditionally been absent from national accounts, in the UK and internationally. However, based on the CSH framework (see paragraph XX), and thanks to the work of a group of UK academics as well as ONS economists and statisticians63, R&D was first introduced into UK national accounts in 2014.
86The Bean review, a 2016 independent review of UK economic statistics, emphasised the importance of intangible assets for the UK economy, and the need for a more comprehensive measurement of intangible assets in UK national accounts. While a large portion of intangible investments is not yet included in official UK national account statistics, the Office for National Statistics (ONS) calculates and publishes estimates of investment in intangibles at a national level for the market sector (the so called "experimental statistics”).64,65
87National and experimental data on intangible assets are calculated by surveying representative samples of UK companies, as well as using administrative data such as VAT forms and PAYE records.66 National surveys are large and complex to respond to, therefore responses typically involve several staff members, including accountants. For national statistics purposes large companies are broken into different reporting units based on the nature of their business (say, the retail, petrol and insurance divisions of TESCO may be surveyed separately) and geography. This would not happen however for smaller businesses: therefore, in most instances the company in and of itself is the reporting unit.
88For our purposes, the existence of these data is important for two main reasons:
- They provide an estimate of the prevalence of intangible assets in the United Kingdom and can therefore be used to infer the extent to which these are absent from companies' balance sheets
- As emerged in relevant literature and in interviews on the topic with the ONS and an academic, because national data is calculated based on surveys of private companies:
- The challenges faced by national statisticians in measuring intangible assets are in many instances similar to the ones faced by individual companies (see Box XX)
- Wider recognition of intangible assets at a company level may lead to more comprehensive and consistent statistics at the national level67
89Figure 1 below displays the trend in tangible and intangible investment for the 1997-2019 period according to ONS experimental statistics.
Figure 1: Trend in tangible and intangible assets investment 1997-2019

Source: ONS, Investment in intangible assets in the UK by industry: 2019.
90As noted in Martin (2019) and other publications, annual investment in intangible assets is estimated to be roughly equal to investment in tangible assets68, a largely "unaccounted half" (see Figure 2) amounting to roughly 7.5% of the country GDP.69 As of 2019, intangibles investment was nearly £170 billion. Figure 3 provides a breakdown of 2019 investment among different assets (both accounted and unaccounted for).
Figure 2: Intangible assets investment, share of total national investment

Source: UKEB calculations on ONS, Investment in intangible assets in the UK by industry: 2019
Figure 3: 2019 intangible assets investment, by asset class

Source: UKEB calculations on ONS, Investment in intangible assets in the UK by industry: 2019. Assets accounted for in national statistics: research and development, software, artistic originals, mineral exploration.
Financial statements information
FTSE 350 companies
91We calculated the prevalence of intangible assets among FTSE 350 companies using Reuters-Eikon data.
92We firstly look at the trend in the amount of intangible assets included on companies' balance sheets for the period 2008-202170. Figure 4 shows the trend in intangible assets against market capitalisation. We compare these two indicators as several academic studies71 suggest that intangible assets are a driver to stock prices/market value:
Figure 3: 2019 intangible assets investment, by asset class
Pie Chart Breakdown: - Research and Development: 19.03% - Software: 15.83% - Artistic Originals: 5.65% - Organisational capital: 1.72% - Training: 18.21% - Financial product innovation: 14.25% - Mineral Exploration: 3.69% - Branding: 0.47% - Design: 21.15%
Accounted for: 36.62% of the total
Source: UKEB calculations on ONS, Investment in intangible assets in the UK by industry: 2019. Assets accounted for in national statistics: research and development, software, artistic originals, mineral exploration.
Financial statements information
FTSE 350 companies
91We calculated the prevalence of intangible assets among FTSE 350 companies using Reuters-Eikon data.
92We firstly look at the trend in the amount of intangible assets included on companies' balance sheets for the period 2008-202170. Figure 4 shows the trend in intangible assets against market capitalisation. We compare these two indicators as several academic studies71 suggest that intangible assets are a driver to stock prices/market value:
Figure 4: trend in intangible assets, FTSE 350 companies
Bar Chart showing Intangibles (£ billion) and Market Cap (£ trillion) from 2008 to 2021. - Intangibles trend from £115.40 billion (2008) to £330.00 billion (2021). - Market capitalisation trend (right axis) shown to be generally higher.
Source: Reuters-Eikon. Intangible assets figure exclude goodwill.
93As evident from the graph, over the period 2008-202172, intangible assets of FTSE 350 companies show a growing trend, amounting to roughly £330 billion as of 2021 year-end. Between 2008 and 2021 intangibles tripled in value, from £115 to £330 billion (+185% over the period). By comparison, over the same period total assets increased by 60.6% (from £7.1 to £11.5 trillion), PPE increased by 76.3% (from £500 to £879 billion), and market capitalisation increased by 88.5% from 200973 (from £1.3 to £2.4 trillion). This suggests that intangible assets grew at a faster pace than assets overall, physical assets and market capitalisation.
94This is reflected in intangible assets share of total assets increasing over the period, as shown in Figure 5:
Figure 5: intangible assets as a share of total assets, FTSE 350 companies
Bar Chart showing percentage of intangible assets as a share of total assets from 2008 to 2021. - Percentages range from 1.52% (2009) to 3.01% (2019), ending at 2.87% (2021).
Source: Reuters-Eikon. Intangible assets figures exclude goodwill.
95The rise in intangible assets is even more evident when excluding the financial sector (banks, insurance companies and financial services firms), characterised by hefty balance sheets. Excluding the financial sector, over the 2008-2021 period intangible assets as a share of total assets nearly doubled, from 6.73% to 12.2% (see Figure 6).
Figure 6: intangible assets over total assets, FTSE 350 companies (excluding financial sector)
Bar Chart showing percentage of intangible assets over total assets for FTSE 350 companies (excluding financial sector) from 2008 to 2021. - Percentages range from 6.73% (2008) to 12.19% (2021).
Source: Reuters-Eikon. Intangible assets figures exclude goodwill.
96In fact, there are significant sector differences in the prevalence of intangible assets (see Figure 7). The graph plots the amount of intangibles on the balance sheet in £ billions against their share of total assets. The sector characterised by the highest amount of intangibles, both in absolute and relative terms, is Food, Beverages and Tobacco; this is largely attributable to the British American Tobacco (BAT) 2017
Figure 7: Intangible assets by industry
Scatter plot showing Share of intangibles over total assets (%) versus Intangibles (£ billion). - Food, Bev. and Tob. (38.04% share) is an outlier in the top right, with high intangible assets in £ billion. - Health Care (31.22% share) and Automobiles (28.15% share) show high percentage shares. - Other industries are plotted across the chart including Technology (24.81%), Personal Care (20.36%), Media (13.65%), Chemicals (13.62%), Telecommunications (12.91%), Industrials (9.70%), Travel and Leisure (8.83%), Consumer Pr. and Ser. (4.53%), Energy (4.53%), Construction (2.11%), Financial Services (0.46%), Insurance (0.47%), Banks (0.22%), Real Estate (0.00%), Utilities (2.79%).
Source: Reuters-Eikon. Industry classification: ICB (Super-sector).
97These figures show that intangible assets are increasingly important on companies' balance sheets. However, and as discussed in paragraphs XX-XX, under the current accounting framework companies can only capitalise a relatively limited number of internally generated intangible assets. By contrast, capitalising intangible assets arising from a business combination is much easier, suggesting that intangible assets are under-recognised on companies' balance sheets.
98In addition, the IFRS intangible assets classification does not currently cater for assets that have emerged in recent years (such as big data or AI algorithms: see paragraphs XX-XX) or requires the expensing of others (such as training, advertising, human capital). As a consequence, the number of intangibles on companies' balance sheets should be interpreted as a “lower bound”, both in absolute terms and as a share of the total.
99Analyses of financial statement information and additional data from Reuters-Eikon provided evidence suggesting that intangible assets are potentially missing from companies' balance sheets.
100More in detail, we analysed FTSE 350 annual reports to look for evidence of granular information on intangible expenses. As discussed later in paragraphs XX-XX, a problem flagged by UK stakeholders about IAS 38 is the fact that the standard does not require detailed disclosures about expenses that may relate to intangibles. The analysis revealed that a majority of FTSE 350 companies do not disclose granular information about intangible expenses, such as R&D, advertising, software development and training costs76. Using Reuters-Eikon data and individual financial statements, we found the following examples of such expenditures:
- Unilever, a customer goods company, in 2021 expensed over £6 billion in advertising costs77;
- Diageo plc, a food and beverage company, expenses roughly £2 billion per year on advertising78;
- 33 companies on the FTSE 350 expensed training costs, for a total amount of £406 million.
- XX FTSE 350 companies in 2021 expensed over £22 billion in R&D.
101It can be argued that at least part of those intangible expenses is likely to be investments that companies are not allowed to capitalise under current IFRS requirements.
102The academic literature uses the Perpetual Inventory Method (PIM)79 to capitalise intangible expenses. Using the PIM for a selected number of companies to estimate the extent to which intangible assets are likely to be missing from companies' balance sheets (data was taken from Reuters-Eikon) showed the following:
- Capitalised R&D costs for two major pharmaceutical companies, AstraZeneca (AZ) and GlaxoSmithKline (GSK), are likely higher in value that what is currently written on their balance sheets:
- Over the 2011-2020 period, AstraZeneca spent over £5 billion on average in R&D. R&D expenses hiked to over £8 billion during 2021 in connection to the Covid-19 vaccine development. Using 2001-2021 data we estimate that, was AZ to capitalise these expenses, they would amount to over £37 billion in 2021 (not taking into account any potential impairment losses).
- Over the 2011-2021 period, GSK spent over £3.8 billion on average in R&D. Using 2001-2021 data we estimate that, was GSK to capitalise these expenses, they would amount to nearly £26 billion in 2021 (not taking into account any potential impairment losses).
- We capitalised training costs for Vodafone, a telecommunications company. Over the 2011-2021 period, Vodafone spent over £49 million on average in training. Using 2001-2021 data we estimate that, was Vodafone to capitalise these expenses, they would amount to roughly £715 million in 2021 (not taking into account any potential impairment losses).
- We capitalised advertising costs for Unilever, a consumer goods company. Over the 2012-2021 period, Unilever spent over £7.3 billion on average in advertising. Using 2012-2021 data we estimate that, was Unilever to capitalise these expenses, they would amount to almost £16 billion in 2021 (not taking into account any potential impairment losses).
103Additional analysis of Reuters-Eikon data and individual financial statements revealed that some companies recognise customer relations arising from business combinations. For example, the London Stock Exchange Group has recognised £8.7 billion in customer relationships following their acquisition of Refinitiv and Tradeweb in 2021.
104These figures and analyses suggest that potentially large swathes of intangible assets are likely missing from companies' balance sheets, and that, at a minimum, more granular information about intangible expenses could help users obtain better estimates of the size of intangible assets held by companies.
Unlisted companies
105We also estimated the prevalence of intangible assets in a sample of 28 large unlisted companies applying IFRS80. An analysis of companies' financial statements has revealed that as of 2020 year-end these companies had £4.7 billion in intangible assets (excluding goodwill). Total assets for these companies totalled nearly £300 billion (£126 billion excluding two life insurance companies that did not hold any intangible assets), suggesting that the share of intangible over total assets was a mere 1.6% (3.7% excluding financial companies).
106The lower share of intangible over total assets than the one found for listed companies (see paragraphs XX-XX) may be attributable to the lower degree of M&A activity taking place among private companies.
Comparison between national and companies' data
107A comparison between FTSE 350 companies' and macroeconomic data shows that a significant number of intangible assets are unaccounted for in individual companies' accounts.
108Using the same method used in paragraphs 100-105, we capitalised intangible investment at a national level. Assuming a 22% depreciation rate (the rate used for a "generic" intangible in the literature, see Villalonga, 2004) we estimate that as of 2019 year-end the stock of intangible capital at the UK level was just above £670 billion.
109As reported in Figure X, as of 2019 year-end intangible assets on FTSE 350 companies' balance sheets amounted to roughly £293 billion. This represents 43% of the estimated the stock of intangible capital based on ONS experimental data. FTSE 350 companies are a subset of UK firms, but as the largest and most competitive companies in the country, and a fundamental contributor to the real economy81, their stock of intangible assets should be a significant, if note the largest, share of the country's stock of intangible capital. As noted, intangible assets on our sample of 30 large unlisted companies were less than £5 billion, a far cry from what the 28 largest listed companies report (£XXX billion). As a consequence, the reporting gap is likely to be in the range of the hundreds of billions.
Summary of stakeholders' views
110The following sections summarise the key themes emerging from more than 30 in person interviews with stakeholders. Appendix XX discusses the methodology used to conduct our research and reports a breakdown of the respondents. When appropriate, stakeholders' views are compared and contrasted with the relevant literature in accounting and economics.
111We will firstly focus on the problems with IAS 38 identified by stakeholders and then discuss opportunities for improvement flaggeds by the respondents. Some issues (materiality, prudence, relevance and reliability) are discussed in a separate section.
What's wrong with IAS 38: a literature-informed summary of stakeholders' views
112In this section we summarise the concerns stakeholders raised with the current accounting for intangible items. We also consider the reasons why current accounting may be difficult to change, or even perceived as favourable by some stakeholders. These concerns lay a foundation for the following section that considers opportunities for improvement in the accounting for intangible items.
IAS 38 Intangibles is an “Old Standard”
“I do think IAS 38 has problems. The main problem is that it is an old Standard, based on an old conception of R&D. It doesn't help to deal with many intangibles that exist today.” (Academic)
“IAS 38 is an old standard, it is too general”. (Preparer)
113IAS 38 was originally issued by the International Accounting Standards Committee in September 1998 (see paragraphs XX-XX). That Standard replaced IAS 9 Research and Development Costs, issued in 1993, which itself replaced an earlier version, Accounting for Research and Development Activities that had been issued in July 1978. As a consequence, the current standard in fact retains large sections originally written in the 1970s.
114When asked what is wrong with intangibles, a common refrain from stakeholders was that "IAS 38 is an old standard" (Preparer). On its own the age of a standard is not a valid criticism, but this view seems to be underpinned by two specific concerns, that IAS 38 is dated when considered in light of:
- the advances in technology and the economic changes experienced since the standard was developed and implemented for use by companies in the UK (see paragraphs XX-XX); and,
- the recent developments in the Conceptual Framework underpinning international accounting standards.
115The first concern is that IAS 38 has not kept pace with advances in technology. This is closely linked to the increasing importance of intangible capital in the economy, as evidenced in paragraphs XX-XX and to newly emerged intangible assets classes, as noted in paragraphs XX-XX82. On this issue one interviewee commented that "something needs to be done. The status quo is not acceptable. It is not a reflection of economic reality and not relevant to the value of the business. The economy will become more intangible over time.” (Auditor)
116IAS 38 references specific intangible items, that were relevant at the time the standard and subsequent amendments were published. While, in principle, the standard allows for the development of new types of intangibles, the recognition criteria for internally developed intangibles are very restrictive and grounded in the accounting for research and development (see paragraphs XX-XX). These criteria have proven difficult to apply to intangibles of well recognised importance (such as brands and human capital) and are likely to be equally difficult to apply to emerging intangibles, such as artificial intelligence, algorithms and big data. This often leads companies to expensing all such investing for financial reporting purposes.
117The second concern refers to changes in the conceptual framework that underpins the development of accounting standards, and a mismatch between how assets are treated in the conceptual framework (revised in 2018) and in the standard itself. As one stakeholder noted “The [current] Conceptual Framework definition of an asset does seem to capture a lot more intangibles than are generally recognised under IAS 38.” (Standard Setter)83
118IAS 38 was based on a Conceptual Framework developed in 1989. The definitional characteristics and recognition criteria in IAS 38, particularly the concepts of control and probability, are embedded from that Conceptual Framework. However, the Conceptual Framework revisions in 2018 are particularly relevant to these concerns, as they were partly driven by shareholder feedback during the second agenda consultation about the application of the conceptual framework to intangibles (discussed in paragraphs XX-XX).
119The 1989 Conceptual Framework defined an asset as "A resource controlled by the entity as a result of past events and from which future economic benefits are expected to flow to the entity”. This definition is repeated in IAS 38, paragraph 8. The definition of an asset was changed in the 2018 Conceptual Framework to “A present economic resource controlled by the entity as a result of past events. An economic resource is a right that has the potential to produce economic benefits" (emphasis added).
120Two changes to the language used in the Conceptual Framework to define an asset are of particular relevance for intangibles.
- The first is that in the new framework assets are based on economic resources, which manifest as rights. Of course, rights are themselves intangible, emphasising that intangibility is at the core of such assets.
- The second the deletion of 'expected flow' from the definition of an asset, which emphasises that the economic benefit does not need to be certain, or even likely, in order to meet the definition of an asset.
121The change in b. in particular echoes one of our stakeholder's views on intangible assets: "Intangibles are value drivers of firms. In fact, often the company may be making losses from an accounting perspective. But value is being created in things like employees, corporate culture, resources the company devotes into delivering future growth such as spending on R&D, Software, brand names, even CapEx (more broadly defined). All these have the potential to deliver value in the long run”. (Academic)
122The removal of the requirement for an expected flow from the conceptual framework now means that it clashes with the recognition criteria of IAS 38: “An intangible asset shall be recognised if, and only if: (a) it is probable that the expected future economic benefits that are attributable to the asset will flow to the entity" (para. 21). With the reference to "probable”, understood in accounting to mean “more likely than not” (IFRS 5, Appendix A).
123By contrast, the current Conceptual Framework refers to an asset having:
"the potential to produce economic benefits. For that potential to exist, it does not need to be certain, or even likely, that the right will produce economic benefits. It is only necessary that the right already exists and that, in at least one circumstance, it would produce for the entity economic benefits beyond those available to all other parties (para 4.14)...
A right can meet the definition of an economic resource, and hence can be an asset, even if the probability that it will produce economic benefits is low (para 4.15, emphasis added).
124The revised conceptual framework also made amendments to the concept of control, so that the IAS 38 definition is now out of line with the new conceptual framework definition. IAS 38 states that “An entity controls an asset if the entity has the power to obtain the future economic benefits flowing from the underlying resource and to restrict the access of others to those benefits.” (IAS 38, para 13). While this definition is similar to that found in the Conceptual Framework definition (para 4.20), IAS 38 goes on to heavily emphasise the need for legal rights to protect the intangible asset (see IAS 38 paras 14 and 15). This latter focus on legal rights is now out of step with the new Conceptual Framework, which notes that “control can also arise if an entity has other means of ensuring that it, and no other party, has the present ability to direct the use of the economic resource and obtain the benefits that may flow from it. For example, an entity could control a right to use know-how that is not in the public domain if the entity has access to the know-how and the present ability to keep the know-how secret, even if that know-how is not protected by a registered patent.” (Para 4.22).
125Technology has seen rapid developments in the business environment with the introduction of brand-new business models as well as revolutionalising the way business is conducted (see paragraphs XX-XX). These advances in technology and the recent changes to the conceptual framework form the foundation for concerns that IAS 38 takes too limited an approach to recognition of intangibles.
126“I am nervous about having too many rules and trying to create bright lines. A principle based approach is better. If you set a bright line people find ways to bend the rules. Principles usually leads to greater discipline in the accounting. I would prefer something that is more aligned with the conceptual framework. Is there really an asset here? Then we can think about the appropriate measurement?" (Investor)
Three Specific Problems
127Interviewees' main concerns about IAS 38 coalesce around three clear issues with the current accounting:
- Limited recognition of intangibles assets
- Inconsistent accounting, whether for:
- different types of intangibles, e.g. research versus exploration;
- internally generated vs purchased intangibles; or
- intangibles versus other assets.
- disclosure, for both capitalised and expensed intangible items.
128It is worth noting that stakeholders did not identify the gap between book value and market value of companies (see paragraphs XX-XX) as a key concern. As noted in paragraphs XX-XX, this has however been a significant area of note among academics, particularly Baruch Lev who has authored a number of books and articles focussed on this matter.
129Even when asked, few interviewees identified this as a primary issue. For example, an academic noted: “I am not a fan of the theory that the gap between Book Value and Market Value is driven by intangibles. I do not believe perfect measuring of intangibles would lead to a perfect match between Book Value and Market Value.” (Academic)
Limited recognition
“We need to get behind the initiative to change IAS 38. The most important assets are missing from the balance sheet. The idea being that it is hard to say you are relevant when all the information on Intangibles is missing". (Auditor)
"Intangibles are an increasing component of the assets of modern firms. They include knowledge assets acquired through research and development, human capital developed by investing in employees, the value in supply chains and product distribution systems, brands, software investments, and the organisation of the business. Few of these intangibles appear as assets on balance sheets, leading to increasing calls for reform" (Barker et al. 2020, pg. 2)
130Many stakeholders interviewed reflected concerns that IAS 38 rarely leads to recognition of internally generated intangibles, an issued also widely commented on in the literature on the topic84.
131Almost all stakeholders commented that the prohibition on capitalisation of expenditures that could otherwise be deemed as contributing to an intangible asset, fails to capture useful information about many intangible items.85
132We heard a range of comments that support this concern from different stakeholders, for example:
- "The current accounting standard is not fit for purpose. There are lots of intangibles that should also be captured. There are "real" intangibles that are ignored in the financial statements even before you think about "brand" and "reputation" (Preparer)
- "Genuine investment is being expensed." (Standard Setter)
- "Requirements to expense marketing and workforce are problematic. If they meet the definition of an asset they should be capitalised.” (Auditor)
- "We aren't capturing good assets on the balance sheet” (Preparer)
133Besides those in the production chain, users also noted the lack of recognition of many intangibles. One analyst for example commented: “accounting is okay at dealing with intangibles that have strong rights associated with them. Where the accounting system fails is insights into how the entity is developing intangibles, e.g. the ability of the workforce or the building of brands. Insight into these internal intangibles would be useful. That information is lacking in accounting.” (Analyst)
134In addition to these concerns a preparer noted that the requirement to generally expense spending on internally generated intangibles fails to distinguish between "good spending” (i.e. money spent on profitable projects) and “bad spending” (i.e. money spent on non-profitable ones). They also linked this to IAS 36 Impairment of Assets, arguing that even for capitalised expenditure companies were slow to write off under-performing assets.
"The intangibles and impairment standards are slightly broken, we need to come back to the users' needs. Bad news can be hidden as you expense as you go. We would like to see a developed narrative on ongoing costs, and some of this captured as an asset.” (Preparer)
135There is concern about the inability for IAS 38 to account for more recent innovations such as algorithms, cryptocurrency or artificial intelligence, all of which may already, or could in the future, represent significant intangible value.
"There has been a rise in intangibles, resilience, networks, brand value etc, and the accounting is bad at capturing this, along with the creative process. This problem will grow as the economy continues to move towards intangibles. If you want accounting to remain relevant there should be a solution." (User)
136Given the pace of innovation in the intangible space it is hard to know what specific items will be relevant in the future. However, when explicitly asked, most interviewees from all stakeholder types agreed that “new intangibles” such as algorithms, big data and tech capital deserve recognition, as it is evident that they are allowing some companies to reap future economic benefits.
137Stakeholders identified a range of intangibles they thought deserved recognition:
- "Trademarks and brands: IP business models are different. If you have a strong registered trademark portfolio. They are accessible and protectable. Core brands that are protected.” (Academic)
- "Virtually all our brands are missing from the balance sheet because they weren't acquired. And most of our value is now focussed on looking forward to developing the next generation products which has to expensed. But that is just the way the accounting is. We don't see analysts seeing this as a problem, but obviously this creates inconsistency between organic growth and inorganic growth. Comparisons of companies is more difficult.” (Preparer)
- "There is clearly a need for capturing more intangibles assets, things like carbon emissions rights.” (Academic)
- For high-tech companies cloud computing is a key asset that is not being captured. (Academic)
138Even when expenditures on intangibles do meet the definition of intangible asset, recognition of internally generated intangibles under IAS 38 is limited to the development phase (see paragraphs XX-XX). Some stakeholders considered that the criteria for entering the development phase are somewhat arbitrary and open to significant interpretation leading to substantially different accounting outcomes for different entities, even in the same industry. “Determining technical and commercial feasibility is always difficult". (Preparer)
139Stakeholders overall agreed that this lack of recognition leads to some fundamental problems. As noted by an investor, “the definition of value is broken. The value factor has underperformed since 2008. It is due to the rise of intangibles. Intangible-heavy companies look expensive based on a Price to Earning ratio. People are updating the value definition that adds back research and development. They change the earnings and get a better value measure."
Inconsistent accounting
140As noted in paragraphs XX_XX, there are significant differences between the accounting for internally generated intangible assets (frequently expensed), purchased intangible assets (recognised at cost) and intangible assets acquired through a business combination (recognised at fair value).
141Many stakeholders commented that these different recognition criteria lead to significant differences in the accounting for otherwise comparable companies, dependant on whether they have grown organically or via acquisition.
142A sample of feedback from stakeholders include:
- "We need to level the playing field with IFRS 3 Business Combinations [which allows capitalisation of a much wider range of intangibles]; IAS 38 should expand to capture key intangibles”. (Academic)
- "A good place to start with this question could be with those intangibles that are only recognised through a business combination [IFRS 3]. Should these be recognised irrespective of whether they have been acquired or developed internally?" (Standard Setter)
- "There is disparity [in the accounting for] acquisition growth and organic growth. I don't think it changes decision making, but it can lead to confusion”. (Analyst)
143The academic literature has also focused on this issue:
"Intangible assets from an acquisition such as brands, customer lists, research and even goodwill are indeed currently recognised. Why not those from firms investing internally to develop their brands, customer relations, and research?" (Barker et al. 2020, pg. 2)
144Stakeholders noted that there are also substantial differences in the accounting if the intangible item is captured by a different standard. IFRS 6 Exploration for and Evaluation of Mineral Resources permits many research costs to be capitalised. By contrast, IAS 38 research costs must always be expensed even though “there is a high degree of similarity between E&E and R&D". (Auditor).Another stakeholder noted "Extractive industries provide an interesting contrast to accounting for intangibles generally, and certainly contradicts the approach taken to R&D. There is no reluctance to impair and the model seems to work there." (Accountant)86
145Even where the accounting for intangibles is relatively clear, as is the case for research and development, there is evidence of inconsistent accounting between companies. A 2019 academic paper87 observed with regard to the accounting treatment for research and development that companies in their sample hardly adopt a consistent approach, with the majority of companies either fully or partly expensing, raising concerns about the usefulness of reporting. In addition, the authors noted that, in their interviewees' opinion, the current framework leads to little comparability between companies growing organically and externally.
Limited disclosure
“We need better disclosure about both capitalisation and expensing” (Academic)
146While there are a substantial number of disclosure requirements for recognised intangible assets under IAS 38, stakeholders expressed some dissatisfaction towards the rules governing these disclosures. As one stakeholder put it: “Current IAS 38 disclosure requirements are a confused mix" (Auditor). Another one stated that "If management think it is important they should be disclosing. But users are getting cynical, they want better information, and have got fed up asking for it. I think that accountants are supposed to make accounting understandable to the ordinary person. We shouldn't need experts to help understand the organisation.” (Investor)
147Our Stakeholders had two main issues with the disclosures related to intangible expenditure:
- first, they noted that there are virtually no requirements to disaggregate and provide granular information about intangible expenses. One interviewee for example indicated that “at the moment so much to do with intangibles is lumped together and this is problematic. Investors are trying to strip out the value of the information on intangibles from the financial statements. At the very least Cash flow provides you with the best starting information” (Investor). Given that most internal expenditure on intangibles is currently required to be expensed, we heard numerous comments that the current disclosure requirements are inadequate. For example:
- "Even if you continue to expense (but balance sheet recognition would be better) there isn't enough granularity in the disclosures. (Preparer)
- "The expenses are not disaggregated enough. You might see R&D and advertising. You won't see training." (Auditor)
- "If they expense you don't get information about why they expensed. Why were expenses not capitalised?" (Academic)
- Second, stakeholders also indicated a range of additional disclosures beyond granular expenses' information that they believe would enhance the usefulness of information about intangibles. These enhanced disclosures reflect the perceived importance of intangibles as drive of productivity and competitiveness (see paragraphs XX-XX) but also the uncertainty around their value to the organisation.
148Some stakeholders called for added disclosures if not in the notes to financial statements, then in other reports, such as the management report.
- “At the very least additional disclosure in either management reporting or another specific report is important, this may be a better idea than disrupting the current system. But people are interested in additional disclosure.” (Academic)
149The need for more information about future cash-flow uncertainty, as well as information on the portfolio of projects/investments taken on by companies. For example:
- "We can see what you have invested, but we need more information on the relationship between expectation.” (Investor)
- "Internal management struggle with managing IP. Investors want to know about the portfolio of patents and trademarks, but they also want to know how the board is managing these key assets, who has responsibility. There is a strong link to stewardship." (Academic)
- "Pharmaceutical companies are interesting, we are interested in pipelines of drugs. However, these are not something we assess from the balance sheet. We get lots of discussion from the company and we can verify this with side sources that feel more independent.” (Analyst)
150Another theme that emerged is separability, as there are no requirements to disclose the thresholds companies use to capitalise expenses. For example:
- "Goodwill is a significant asset for serial acquirers. We tend to remove it to focus on the operating performance on the entity. Other intangibles seems to be a big bucket of unknown stuff. We don't have a lot of clarity on when things are being capitalised and when they are not, what decisions are they making, what valuation methodology are they using to value the item on the balance sheet. The amortisation tends to be clearer.” (Investor)
- "It is difficult to ascertain the policies that entities are using for recognition of intangibles. Sales, general and administrative expenses is a claimed investment but we don't get clarity. There is no one size fits all.” (Investor)
151Many of these themes have also been discussed in the academic literature.
- For example Barker et al. (2020) note that “IAS 38 also requires the disclosure of additional information about research and development activities. However, entities must disclose the aggregate amount of research and development expenditure recognised as an expense during the period. This is a mixture of research expense, development amortisation and any impairment expense."
- Qualitative research by Mazzi et al. (2019), also based on stakeholders' interviews, noted that “there was general agreement that mandatory disclosure in IAS 38 is minimal and often boiler-plated disclosure on R&D expense and capitalisation. There is a desire for greater disclosure, which would underpin any capitalisation decision based on the six criteria."
148 Some stakeholders called for added disclosures if not in the notes to financial statements, then in other reports, such as the management report.
-
“At the very least additional disclosure in either management reporting or another specific report is important, this may be a better idea than disrupting the current system. But people are interested in additional disclosure.” (Academic)
149 The need for more information about future cash-flow uncertainty, as well as information on the portfolio of projects/investments taken on by companies. For example:
-
"We can see what you have invested, but we need more information on the relationship between expectation.” (Investor)
-
"Internal management struggle with managing IP. Investors want to know about the portfolio of patents and trademarks, but they also want to know how the board is managing these key assets, who has responsibility. There is a strong link to stewardship." (Academic)
-
"Pharmaceutical companies are interesting, we are interested in pipelines of drugs. However, these are not something we assess from the balance sheet. We get lots of discussion from the company and we can verify this with side sources that feel more independent.” (Analyst)
150 Another theme that emerged is separability, as there are no requirements to disclose the thresholds companies use to capitalise expenses. For example:
-
"Goodwill is a significant asset for serial acquirers. We tend to remove it to focus on the operating performance on the entity. Other intangibles seems to be a big bucket of unknown stuff. We don't have a lot of clarity on when things are being capitalised and when they are not, what decisions are they making, what valuation methodology are they using to value the item on the balance sheet. The amortisation tends to be clearer.” (Investor)
-
"It is difficult to ascertain the policies that entities are using for recognition of intangibles. Sales, general and administrative expenses is a claimed investment but we don't get clarity. There is no one size fits all.” (Investor)
151 Many of these themes have also been discussed in the academic literature.
- For example Barker et al. (2020) note that “IAS 38 also requires the disclosure of additional information about research and development activities. However, entities must disclose the aggregate amount of research and development expenditure recognised as an expense during the period. This is a mixture of research expense, development amortisation and any impairment expense."
- Qualitative research by Mazzi et al. (2019), also based on stakeholders' interviews, noted that “there was general agreement that mandatory disclosure in IAS 38 is minimal and often boiler-plated disclosure on R&D expense and capitalisation. There is a desire for greater disclosure, which would underpin any capitalisation decision based on the six criteria."
- They also note that “We find that references to R&D-related terms are, in general, minimal in company annual reports, ... [and] varies significantly in length and location in the annual report. The interviews ...confirm a demand for more disclosure, especially when development costs are capitalised. Thus... companies are encouraged to provide clearer and greater levels of disclosure than that currently provided." (Mazzi et al., 2019, pg 9 – summary of stakeholders' views, 16 interviewees)
152 The call for added disclosures should not go unheard. Not only does it come from all stakeholders' categories, but also it emerged that it has driven stakeholders' (and users in particular) away from financial disclosures, hunting for the information they need elsewhere:
-
Now accounting researchers tend to look for information outside of the annual report, to find relevant material information that can't be found in the annual report. (Academic)
-
Users that we spoke to indicated that they sourced information on intangibles from other sources, with one noting that “Users looking at smaller companies may feel they get an advantage from private information". (User)
153 All of this adds up to a general lack of information leading to dissatisfaction with the accounting for intangibles.
“What is missing is to the extent that things are happening [but] nothing is captured when it comes to intangibles. You don't have trends.” (Auditor)
Support for the current approach
154 Even though most stakeholders were generally in favour of change, some identified reasons why there may be support for maintaining the current approach to accounting for intangibles under IAS 38.
155 Some stakeholders observed that the current accounting was not particularly problematic for users, with a common theme that information could be obtained from other sources88
-
"On one level there is not a problem. Investors use financial information along with other information to form their positions. The investment market takes a sceptical view of accounting information, it is the product of a range of assumptions and also incomplete. When you are valuing a company you do not start with a balance sheet, and in many ways the market is already coping." (User)
156 Others felt that any changes to the standard/current accounting would be too difficult or lengthy to implement.
-
"Intangibles are intrinsically linked to so many other parts of the business and it is very hard to untangle them." (User)
-
"I think that the current approach is fairly decent. Say Coke, marketing will bolster its value, but it will make the accounts very messy and investors would just strip it out. Return on assets is a good measure." (User)
-
“Developing a new standard on Intangibles is likely to take 20 years” (Auditor)
157 While the majority of studies finds a significant positive association between intangibles disclosure and the financial performance or the market value of a firm, there are also more ambiguous results in regard to this set of relationships.89
Management's stewardship
158 Some interviewees suggested that companies may show some resistance to changing the status quo as under the current accounting model preparers can enhance companies' KPIs while at the same time investing in intangible items without the management being generally accountable for their investment decisions over the longer term (as most investments are expensed).
159 When expenditure on intangibles is expensed as incurred the future earnings will not have to be matched with the related amortisation of those costs. This inflates future profitability, admittedly at the cost of current profitability. But often management can argue (and users accept) that the expenditure on intangibles is not "real expense” or at the very least is a “one-off” and should be ignored.
160 The expensing of intangibles also causes a number of important profitability measures to be inflated. Specifically measures tied to return on assets and return of equity. This is because the investment in intangibles that is expensed (probably in previous periods) is missing from the denominator.
161 These arguments are reflected in stakeholders' comments:
-
"Companies are not interested in capitalising, life is easier, no need to impairment test." (Accountant)
-
"Results are the most important measure. Preparers want to present this in the best possible light. The current standard allows organisations to choose how much to spend (expense) on R&D etc. By not capitalising Return on Investment looks better and there are no shocks from impairment. Also you can smooth income." (Preparer)
162 One academic also noted that auditors may also have an incentive to maintain the status quo in order not to incur higher costs:
-
"Auditors are conservative. Even if a company might want to capitalise auditors don't have the resources and expertise to test the capitalisation, so they push towards expense. And it is even worse the more “exotic” the intangibles. It is all very well to think about prepares and users, but auditors are an important part of the process.” (Academic)
163 Similar arguments appear in the academic literature on the topic. For example, Baruch Lev in his book “Intangibles – Management, Measurement and Reporting” (2001), observes that there are reasons both managers and users of financial statements might prefer the "US GAAP-mandated expensing of practically all investments in intangibles" (pg 88). His arguments are equally relevant to the IFRS Accounting Standard environment where the majority of expenditure on internally generated intangibles is expensed.
164 Finally Lev (2001) turns his attention to users (analysts), who he argues often believe that they obtain from managers (and presumably other private sources) sufficient information about a firms' innovation activities. “In fact, public disclosure in financial reports of such information may strip them of privileged information" (pg. 91).
Appendix 1: Research Methodology
165 This research is qualitative in nature. We conducted in-person or Microsoft Teams interviews with over 30 stakeholders, using a semi-structured interview approach and approaching stakeholders of different types (preparers, users, auditors, academics) to obtain a diverse sample. Interviews lasted between 60 and 90 minutes depending on the interviewee. The interview questions were developed jointly by the technical accounting and economics teams and the UKEB. They draw from the accounting and economics literature on the topic and leverage prior research work and expertise of those involved in the project.
166 Semi-structured interviews are an interview type widely used in qualitative research. It involves guiding the interviewee through a set of previously written open questions, the order of which might or might not vary. Researchers can occasionally add questions if needed, but overall follow the interview structure. Semi-structured interviews are typically used when interviewers cannot access the interviewee more than once, and typically last between 30 and 60 minutes. For a concise reference, see Jamshed (2014) (link: https://www.ncbi.nlm.nih.gov/pmc/articles/PMC4194943/#ref6), and references therein.
167 Interviews broadly covered the following topics:
- Does the current accounting for intangibles work? What problems does the interviewee see with IAS 38?
- Classification: does the current classification work? Are there intangible assets that should are economically important, should be recognised but currently don't appear on balance sheets?
- Initial recognition: how to separate intangible expenses from investment? How to define control?
- Subsequent measurement: what is the best model to account for intangibles?
- Organic versus external growth: does the fact that intangibles are more easily recognised when purchased or in a business combination lead to a fair representation of the balance sheets of companies that grow internally?
- Solutions: does IAS 38 need improvement or replacement? What solutions does the interviewee propose to improve IAS 38?
- Economic consequences: are there unintended economic consequences springing from the current accounting practices, such as effects on companies' valuations, or incentives to companies' management to grow by acquisitions as oppose to organically?
168 Following the tenets of qualitative research methods (and in particular, grounded theory), we aimed to obtain a diverse sample of interviewees, to enable us to obtain a variety of insights. We therefore decided to interview different investor types investing in regions around the world. We drew up the list of potential interviewees in the following way:
- The UKEB team conducted some initial research to identify stakeholder categories of interest
- A number of interviewees were secured using personal pre-existing contacts
- Several interviewees were contacted using cold calling/messaging
- Some interviewees were reached out thanks to the suggestion of other interviewees (snowballing)
169 Speaking directly with different types of stakeholders afforded the UKEB the opportunity to gain insight beyond what could be collected via a standard survey format. Particularly this allowed us to:
- Understand the main problems related to the current accounting framework, and whether problems were perceived differently by different stakeholder types
- Identify solutions that can be adopted to improve the current accounting framework, using a balanced view that takes into account the needs of different types of UK stakeholders
- Take a multi-disciplinary approach to the issue, interviewing largely accountants, but also marketing/communication specialists, lawyers, economists, and statisticians
170 We collected observations till we reached 'theoretical saturation', that is, until it was evident that interviewing an additional investor was unlikely to generate any additional insights/themes (Aldiabat & Le Navenec, 2018; Charmaz, 2006). To encourage participation and frank discussion we committed to keeping responses anonymous. To analyse the data, we extracted common and divergent themes that emerged from the interviews using thematic analysis (Bryman, 2016, pages 586-9). We adopted this approach rather than one based on grounded theory (Charmaz, 2006; Strauss & Corbin, 1991; Thornberg & Charmaz, 2014), as the purpose of the research is not to create new theory.
Appendix 2: Project Initiation Plan: Intangibles Research
| Project Type | Thought Leadership |
|---|---|
| Project Scope | Significant |
Overview
1 The UKEB delegated functions include responsibility for “participating in and contributing to the development of a single set of international accounting standards.” Undertaking pro-active thought leadership activities is key to the UKEB's ability to effectively deliver this statutory function.
2 The UKEB's Terms of Reference (ToR) further explain that with regard to thought leadership, the UKEB shall:
- Lead the UK debate on international accounting standards and reporting.
- Represent UK views in international fora with the aim of influencing debate.
- Engage with accounting and reporting and endorsement and adoption bodies in other jurisdictions, in order to improve influence and understand best practice.
- Proactively participate in the development of new global accounting standards, for example by undertaking research.
3 We believe that a project on intangibles, as described below, clearly supports the UKEB meeting these responsibilities.
4 The increasing importance of intangibles to the modern economy is ubiquitously acknowledged, as demonstrated by the numerous academic papers1 and books2 written on this topic. As noted by CPA Ontario “Today, intangible assets are recognized as the key source of innovation and growth, an economic golden goose"3.
5 At the same time there is significant discussion about the shortfalls of IFRS Standards4 in relation to accounting for intangibles. EFRAG has published a comprehensive report, outlining a range of concerns with current accounting for intangible assets and possible approaches to improving their reporting.5
6 Concerns about the accounting for and reporting of intangibles are not only confined to academic discussions and national standard setters. Steve Cooper6, an independent analyst, co-author of The Footnotes Analyst blog, and former IASB Board Member, has stated that, "the current inconsistent and limited recognition of intangible assets causes analytical challenges for investors... We think that investors would greatly benefit from improvements to both the narrative reporting and financial statement data regarding intangibles."
7 These concerns have been echoed in surveys of users. For example:
- In 2019 the FRC published a consultation “Business Reporting of Intangibles: Realistic Proposals”7. They noted when reporting the feedback received from UK investors that they “were unanimous in their support for improving the quality of reporting on intangibles” 8
- Research currently being funded by ICAS has noted that 93% of users surveyed thought that "financial reporting is lacking adequate information on intangible assets", though they also note that this view was only shared by 61% of preparers surveyed.9
- A worldwide survey of 170 senior investment decision makers commissioned by Columbia Threadneedle Investments concluded that, “There is agreement that analysis of intangibles provides a competitive advantage to investors, and recognition that intangible research is increasingly important in analytical work. However, while investors find information about intangibles readily available, they believe that it is often unreliable, incomplete or inaccurate.”10
8 The IASB has acknowledged these concerns about intangibles. In one of his first public statements the new chair of the IASB, Dr Andreas Barckow, stated that "the rise of self-generated intellectual property and its non-addressal in the accounts” was one of the biggest challenges and opportunities facing the IASB.11
9 Staff papers presented to the IASB summarising the feedback it received on its Third Agenda Consultation12 indicated that most respondents rated intangible assets as a high priority area.13 Respondents believed any review should:
- modernise IAS 38 Intangible Assets, to better reflect the ever-increasing importance of intangible assets in today's business models, particularly for unrecognised internally generated assets;
- address new types of intangible assets, which were not envisaged when IAS 38 was developed (such as cryptocurrencies and emission rights) to ensure it results in useful information to users of financial statements; and
- improve comparability between companies that grow organically and those that grow through acquisitions.
10 Based on that feedback we expect intangibles to form a key part of the IASB's agenda for the next five-year period.
11 A pro-active thought leadership project on intangibles will enable the UKEB to fulfil its responsibility to proactively participate in the development of high-quality accounting standards by leading the UK debate on accounting and reporting of intangibles as well as contributing to and actively participating in the international debate on a timely basis.
Objective of the project
12 Given the significance of intangibles to the UK and global economies in the twenty-first century, and the expectation that a project on accounting for such items will form a key part of the IASB's agenda in the future, it is important that the UKEB pro-actively contributes to this significant area of standard development.
13 "Intangibles” encompasses a wide range of possible topics and avenues for research. The UKEB believes that it is well placed to focus on elements of investor needs when it comes to accounting and reporting of intangibles. This will act as a useful starting point for, and input into, the accounting solutions to be devised by the IASB.
14 The context for the research is:
How could the accounting for, and reporting of, Intangible Items be improved to provide investors with more useful general purpose financial statements to assist them to make better informed decisions?
15 Key elements of this context are:
- Accounting and reporting14: The context for any research will be accounting and reporting in accordance with IFRS Accounting Standards, and the annual financial statements. Specifically, the research will consider elements of classification, recognition, measurement, and disclosure of intangible items. This does not necessarily mean that the current approach of the IFRS Accounting Standards should constrain possible solutions. It may be that new or expanded standards need to be developed to capture useful information.
- Intangible Items: This term is a placeholder for a broad range of non-physical items that are not within the scope of IFRS 9: Financial Instruments, and is not necessarily intended to be the same as defined in IAS 38: Intangible Assets. Part of the research would seek to identify what investors consider the most relevant intangible items, and whether current definitions adequately capture the extent and nature of these items.
- Investors: The Conceptual Framework for Financial Reporting15 identifies the primary users of financial reports as existing and potential investors, lenders and other creditors that cannot require reporting entities to provide information directly to them. We believe that a focus on investors who rely on General Purpose Financial Statements (GPFS) will provide useful information while helping limit the extent of research that will need to be undertaken. These users make key decisions that involve buying, selling or holding equity instruments; or exercising rights to vote on, or otherwise influence, management's actions that affect the use of the entity's economic resources.
16 Within this context we will focus on exploring with investors the areas they see as deficient in the current reporting for intangible items under IFRS Accounting Standards and possible solutions that they believe would address these concerns. This will include examining current reporting practices for intangibles in the UK.
17 The research could be extended later to engage with investors to explore new ways of thinking about the issue of accounting for and reporting on intangibles. A pre-requisite for this would be to consider with other stakeholders, such as academics and preparers (especially in sectors that have intangible items identified as particularly relevant by investors) possible alternative approaches that may not have been considered and which could meet investors' information needs. We would want to facilitate discussions between key stakeholders to develop solutions.
18 The research would be based on a bottom-up or inductive approach. In the initial phase, research would build from investors' needs and observations of practice to develop proposals. This can be contrasted with the top-down or deductive approach that would start with the conceptual framework and develop solutions rooted in accounting theory.
19 This approach will allow us to contribute to and reflect on the work being done by others in this area, such as EFRAG and the AASB. By building on our links with investors we believe we will be able to provide an important perspective on any solutions proposed by others.
20 It will also build on previous work in the UK by the FRC, for example, the FRC's 2019 consultation "Business Reporting of Intangibles: Realistic Proposals”.
Key planning assumptions, constraints and timeline
Project timeline and resource capacity
21 As noted below this project is split into two phases, each with a number of milestones, and an overall expected duration of up to 3 years. The immediate focus is on understanding the reporting landscape for intangible assets in the UK and investors' views. Later work could extend this research into developing more comprehensive proposals to address those findings.
22 This timeline would fit into the IASB's expected review of intangible assets, that is likely to be a long-term project commencing later in 2023. Therefore, we believe that the first phase of research could feed into the IASB's preliminary thinking by describing current reporting practice and investors' concerns. The second phase of the research could feed directly into an IASB project on Intangibles in 2024 or 2025.
23 We currently expect that the project would require input from the following technical staff:
- 40-50% of one accounting specialist project director on a consistent basis;
- up to 40% of a member of the economics team at various stages to support specific outputs; and
- 25% of a project manager on a consistent basis to support the project.
24 Production of regular outputs is important to retaining interest and momentum in the project over its lifetime, and is factored into the resource allocation. For example, one early output proposed is a paper addressing questions asked in EFRAG's Discussion Paper: Better Reporting on Intangibles. This will require significant activity in the first half of 2022.
25 It is also important to acknowledge that additional research opportunities and outputs could be identified or emerge while the project is underway. Any significant changes to the research outputs or timetable will be presented to the Board.
Assumptions
26 Once established, the UKEB's user and academic advisory groups will form a key part of any outreach. We may also be able to utilise the IASB's Investor contacts, along with the knowledge of our liaison IASB Board Member.
27 We do not plan on setting up an ad hoc external group at this point in time. However, a sub-group of UKEB Board members to provide ongoing advice would be useful. We believe a group of three or four Board members, including an investor and academic representative would be appropriate. They would be regularly consulted and appraised of progress on the project and would provide an important link back to the Board.
28 We will look to academics to support the research, in particular during Phase Two, to help identify alternative approaches to addressing the accounting for intangible assets. As noted, a future academic advisory group will play a key role in supporting engagement with academics. We would also look to bring academics and users together as part of some of the outputs discussed below and may consider commissioning empirical research, if appropriate.
29 It is expected that a number of the activities to be undertaken as part of this project will have synergistic opportunities to collaborate with and contribute to other UKEB projects. For example, there is overlap with the Goodwill and Impairment research currently being undertaken. We will actively look for ways to incorporate cross-sectional thinking and help ensure maximum impact for this thought leadership project.
30 We also see this project as an opportunity to engage with other NSS and international stakeholders (including the IASB). We will actively look to collaborate with others to enhance the research activities being undertaken and increase the impact of the work being done. Some of these opportunities are noted below, others will emerge over time.
Risks
31 Traditionally, it has been difficult to engage with investors. Though provision of information to investors is the focus of accounting information, the time scales involved in development of accounting standards makes it difficult to engage with this key stakeholder group as they are more focussed on what they are seeing today in financial statements.
32 Maintaining the momentum, consistency and quality of the project over a long period of time can be difficult. We intend to mitigate this by allocating a lead project director to the project with responsibility for coordinating the ongoing involvement of other members of the team at appropriate junctures.
33 The IASB's specific plans regarding the scope and timing of the intangibles project may not be known for some time. We are planning on the assumption we will be able to contribute to the early stages of the project. The UKEB project timelines and milestones will need to remain flexible in order to respond to developments at the IASB to ensure the UKEB outputs are timely and have maximum impact on the activities of the IASB.
Outputs
34 The research project is currently framed around two phases. Subsequent outputs are expected to build on preceding ones. Phase two would be subject to a review of the preceding research, and any expectations around the timing and nature of the IASB's plans with regards to Intangible Assets. This would be an opportunity to develop additional or alternative outputs.
35 The phase one outputs focus on evidence gathering, assisting the UKEB to understand the current state of reporting on intangibles in the UK through a review of the existing academic literature, considering the economic indicators and understanding stakeholder views on the extant accounting for Intangibles. Phase two will focus on the development of preliminary/final Board views. The nature and timing of the research will be affected by the IASB's plans with regards to Intangible Items.16
Phase One
Major Output 1 - Qualitative Research Report: UK Stakeholder Views on Accounting for Intangibles17 (QI 2022 QI 2023)
36 In 2022 we will develop a research paper drawing primarily on qualitative research based on in-depth interviews with a range of stakeholders, supported by a review of key literature. The research is explorative by design. It will provide a better understanding of UK stakeholders' perspectives on the accounting for, and reporting of, Intangibles in the UK, and the economic outcomes arising from the existing accounting framework.18
37 The work will be based primarily on qualitative research involving gathering feedback from a range of interested stakeholders. This is expected to include both detailed discussions with interested individuals and broader survey type research. However, we also expect it to be informed by the initial qualitative work being undertaken as part of output 3 discussed below.
38 The IASB have requested that the UKEB contribute to their research on making material judgements19. This project provides an ideal opportunity to contribute the views of UK stakeholders and there is a clear link between the accounting for intangible items and the role of materiality. By their nature intangibles necessitate greater consideration of qualitative factors when assessing their materiality. We have explored this issue with stakeholders in interviews and the IASB has already expressed interest in seeing our findings.20
39 We will seek to work with EFRAG on some outreach with stakeholders, including investors. For example, we are considering joint roundtables on specific elements of the EFRAG report.
40 We expect to discuss a draft report on the outreach with the Board in Q4 2022, with Board approval of the final report in January 2023. This is a research study that summarises the input received from a qualitative study ([Draft] Due Process Handbook, paragraph 7.11(e)). The report will summarise the feedback received as a result of the outreach undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.21
Major Output 2 Analysis of Intangible Reporting in the UK (QI 2022 H2 2023)22
41 In parallel with the other major outputs we would also undertake an analysis of the reporting of intangible items in the annual financial statements of UK companies.
42 To better understand the current reporting on intangible items we will undertake a review of the nature and extent of current reporting in the UK. An analysis of current practices among listed UK companies using IFRS standards would allow examination of the accounting for intangibles (including capitalisation and expensing), along with associated disclosures. The analysis may also gather data that is useful for other projects being undertaken by the UKEB, including on goodwill and impairment.
43 This may also be an opportunity to engage with UK academics to support and enhance this research, for example by commissioning targeted empirical analysis. The UKEB may consider funding research through a competitive grant process to encourage and support appropriate research.
44 A multi-functional Secretariat team – including economist, academic and accounting technical – is likely to be needed for this work given the need to gather quantitative information which would then require comprehensive analysis.
45 We intend to publish a report in H2 2023 that summarises the findings of the research. This is a research study that summarises the input received from a quantitative study (Draft Due Process Handbook, paragraph 7.11(e)). The report will summarise the research findings as a result of the research undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.23
Major Output 3 – Investor Outreach (Q1 2022 – QI 2024)
46 In 2022 a key focus will be engaging with investors to better understand their perspectives on the reporting of intangibles in the financial statements. This will take the form of a range of outreach activities including developing and administering an investor survey.
47 The focus of the outreach will be on understanding investors' information needs and practices. It will seek to examine:
- the intangibles investors consider as most important to their decision making;
- how well their information needs about intangibles are currently served; and
- investor views on the opportunities for improvement to the accounting for, and reporting of, intangibles in general purpose financial statements.
- some additional questions relevant to other UKEB projects that overlap with this work.
48 The survey development and analysis will be supported by the UKEB economics team and we will also explore opportunities to work with the FRC Financial Reporting Lab. We will also engage with the Academic Advisory Group and the Investor Advisory Group to advise on the survey instrument and engagement with users.24
49 We will take a proactive approach to engaging with investors in the UK as we consider this a great opportunity to build connections with them.
50 We plan to publish a report summarising the key findings from the outreach in early 2024. This is a research study that summarises the input received from a survey based study (Draft Due Process Handbook, paragraph 7.11(e)). The report will summarise the feedback received as a result of the survey undertaken but will not include preliminary/final views from the Board on specific approaches to addressing accounting for Intangibles. Therefore, in line with the current [Draft] Due Process Handbook (paragraph 7.12) the report will not include an invitation to comment.25
Phase Two26
51 Phase Two would be subject to a new PIP to be presented to the Board in mid-2023. It is expected that additional outputs would be proposed, particularly in 2023 that would support the ongoing project, and any IASB activity in this area.
52 We also plan to engage directly with other National Standard Setters including EFRAG and the Australian Accounting Standards Board who are also planning to undertake extended research projects on the accounting for intangibles. This may provide the opportunity to develop collaborative research proposals.
53 Phase two research will build on the research studies undertaken as part of phase one of this research project. It is expected that some phase two outputs would include Board views, and therefore would include Invitation(s) to Comment.27
Other Minor Outputs
54 In addition to the primary outputs highlighted above, we expect to publish other minor outputs that utilise work already being undertaken. These will be of varying degrees of formality and size and will be intended to publicise and maintain interest in the research work. Examples could include:
- Short articles on the UKEB Website and in other media.
- Podcasts and videos highlighting aspects of research undertaken.
- Regular short posts on UKEB social media.
- Hosting and/or co-hosting topic specific events with a range of stakeholders.
- Participation in events run by others in both the academic and user communities.
- Contributions to research being undertaken by other National Standards Setters.
- Supporting and contributing to a special issue in an Academic Journal.
55 These outputs would be expected to involve to varying degrees both the Secretariat and UKEB Board members. We will continue to explore other opportunities to collaborate with interested parties. We are aware of a number of organisations that are currently undertaking research, or considering undertaking research, in this area. In addition to the NSS activities already discussed, work being undertaken by Professional Bodies and others will also be relevant avenues for collaboration.
Project closure
56 Each output will comply with the expected due process requirements appropriate to the nature of the output.
| The Footnotes Analyst
| ICAS
55These outputs would be expected to involve to varying degrees both the Secretariat and UKEB Board members. We will continue to explore other opportunities to collaborate with interested parties. We are aware of a number of organisations that are currently undertaking research, or considering undertaking research, in this area. In addition to the NSS activities already discussed, work being undertaken by Professional Bodies and others will also be relevant avenues for collaboration.
Project closure
56Each output will comply with the expected due process requirements appropriate to the nature of the output.
Project timeline
57The proposed high-level project timeline is as follows (a graphical representation is included on the next page). Note that dates are indicative only, and subject to revision as the project develops28:
| Date | Milestones |
|---|---|
| 2022 | |
| PHASE 1 | |
| January | Project Initiation Plan |
| February | Commence Output 1 – Qualitative Research Report |
| Commence Output 3 - Investor Outreach | |
| March | Commence Output 2 - Analysis of Intangible Reporting in the UK |
| 2023 | |
| PHASE 1 – Cont. | |
| Jan Board | Approve Final Report – Output 1 |
| Q3 Board | Approve Final Paper – Output 2 |
| Q3 Board | Phase 2 Project Initiation Plan |
| 2024 | |
| PHASE 1 – Cont. | |
| Q1 Board | Approve Final Report – Output 3 |
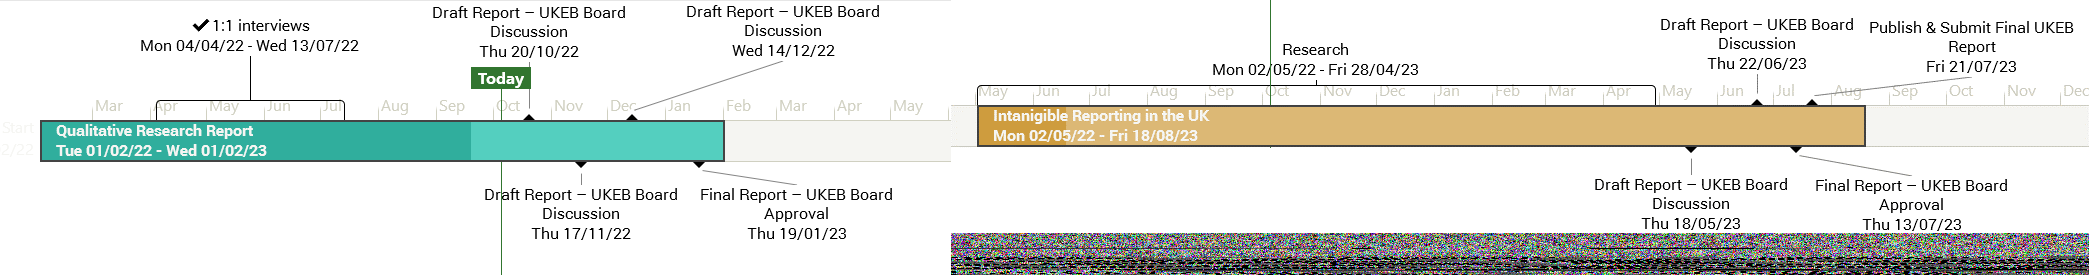
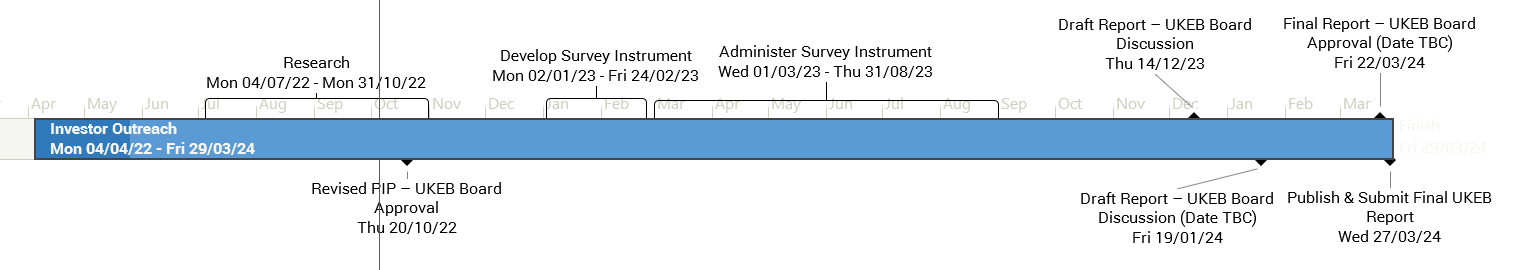
Annex A
Work being undertaken by others
National Standard Setters
1The Australian Accounting Standards Board (AASB) is looking at the current requirements of IAS 38, with a focus on improved disclosure29.
2Given the focus of this research is on current requirements of IFRS Standards, and restricted to IAS 38, we expect limited overlap in any research project undertaken by the UKEB. While some of their findings may help inform our thinking, we expect to look much more widely at the issue.
3EFRAG is undertaking a much larger project termed “Better Information on Intangibles”30. It has published a 70-page Discussion Paper outlining current issues and possible avenues for improvements of measurement and disclosure of intangible assets. The paper notes that the value relevance of financial statements is decreasing, which could be due to missing information about intangible assets. It considers three approaches for better information on intangibles:
- Recognition and measurement in the primary financial statements;
- Information on specific intangibles in the notes to the financial statements or in the management report; and
- Information on future-oriented expenses and risk/opportunity factors that may affect future performance in the notes to the financial statements or in the management report.
4The scope of EFRAG's discussions goes beyond the existing definition of assets in financial reporting and also covers sources of possible economic benefits that would not be controlled by an entity.
5The work being undertaken by EFRAG is likely to be directly relevant to any UKEB research project. Given their focus on better information on intangibles it would be expected that this work may help inform proposals for alternative accounting presented to stakeholders for discussion.
6We will also be able to utilise some of the background work EFRAG have already undertaken, such as their literature review.
Academic and other research
7There are a significant number of research papers looking at intangible assets. Presented here is a sample of a few of the studies that will contribute to this research project.
- Amir Amel-Zadeh, Martin Glaum & Thorsten Sellhorn (2021): Empirical Goodwill Research: Insights, Issues, and Implications for Standard Setting and Future Research, European Accounting Review. This paper reviews the empirical literature on the determinants and decision usefulness of goodwill reporting.
- Barker, Richard & Lennard, Andrew & Penman, Stephen & Teixeira, Alan. (2021). Accounting for intangible assets: suggested solutions. Accounting and Business Research. 1-30. 10.1080/00014788.2021.1938963. Drawing on relevant research, we evaluate solutions for intangible asset accounting that contrast with balance sheet recognition, and we compare these with current practice under IFRS.
- Chalmers, Keryn & Clinch, Greg & Godfrey, Jayne & Wei, Zi. (2010). Intangible Assets, IFRS, and Analysts' Earnings Forecasts. Accounting and Finance. 52. 10.1111/j.1467-629X.2011.00424.x. We investigate whether the adoption of IFRS in 2005 by Australian firms has been associated with a loss of potentially useful information about intangible assets.
- CPA Ontario (2021). You can't touch this: The intangible assets debate.
- EFRAG (2020). A Literature Review on the Reporting of Intangibles.
- Financial Reporting Council (2019). Business Reporting of Intangibles: Realistic Proposals.
- Financial Reporting Council (2021). Feedback Statement: Business Reporting of Intangibles: Realistic Proposals.
- ICAS (forthcoming). The Production and Consumption of Information on Intangibles: An Empirical Investigation of CFOs and Investors
- Nichita, Mirela. (2019). Intangible assets -insights from a literature review. Journal of Accounting and Management Information Systems. 18. 10.24818/jamis.2019.02004. Research Question: How do researchers address the definition, measurement, recognition and potential of intangible assets to generate future economic benefits when a formal structure for reporting them is highly controversial?
- Nwogugu, Michael. (2019). Intangibles Accounting Regulations and the “Global Intangibles Economy”: Belief-Revision, Enforcement Theory and Financial Stability. 10.1057/978-1-137-44704-3_5.
EFRAG 35 Square de Meeûs B-1000 Brussels Belgium
Dear EFRAG members,
Better Information on Intangibles (DP/2021/8)
The UK Endorsement Board (UKEB) welcomes the opportunity to provide a response to the questions asked in EFRAG's Discussion Paper: Better Information on Intangibles – Which is the best way to go?
The UKEB is responsible for endorsement and adoption of IFRS Accounting Standards for use in the UK and therefore is the UK's National Standard Setter for IFRS Accounting Standards. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. It should be noted the UKEB has not yet developed its own views on the accounting for intangibles. The answers provided below reflect the views heard from stakeholders during interviews undertaken as part of the UKEB's own qualitative research project on intangibles (described below) commenced Spring
- The UKEB expects to continue its research and may arrive at different conclusions for current and future projects, including any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
In early 2022, the UKEB began a proactive research project that would contribute to the international debate on Intangible items. The research focuses on how the accounting for, and reporting of, Intangible items could be improved to provide investors with more useful general purpose financial statements to assist them to make better informed decisions. This complements EFRAG's research work in this area and we look forward to exploring other opportunities for collaboration in the future.
The initial phase of the UKEB's research is focused on understanding UK stakeholder views (particularly investors) on the accounting for, and reporting of, intangibles. The first project is a report drawing on qualitative research based on in-depth interviews with over 30 stakeholders from a range of backgrounds, supported by a review of key literature. The research is explorative by design. It will provide a better understanding of UK stakeholders' perspectives as well as the economic outcomes arising from the existing accounting framework. It will also form the basis for later research that will provide more explicit recommendations to the IASB. A more detailed report presenting the views from these interviews is expected to be published early in 2023, and we look forward to sharing this with EFRAG at that time.
If you have any questions about this response, please contact the project team at [email protected]
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
If you have any questions about this response, please contact the project team at [email protected]
[The questions from the report are reproduced in bold. A summary of relevant points from the EFRAG report helpful to understanding the context of the question are included in a grey box. The UKEB Response is included in the numbered paragraphs]
Appendix 1: Questions on Better Information on Intangibles (DP/2021/8)
Question I – Issues with the current information
Do you think the issues listed are relevant and valid? Are there additional issues with the current information on intangibles that are not listed? If so, what are these issues?
We list here for the Board the issues identified in the report:
- Financial statements lack the drivers of value for intangible intensive businesses such as big data, customer relationships, brand, efficient business processes and/or the dynamic capability of a workforce being important parts of how businesses create value.
- Comparability challenges between internally generated assets and acquired assets.
- Distorted performance measures as return on assets ratios do not provide useful information, expenses not correctly matched, statement of performance is hit twice when acquired intangibles are replaced by internally generated intangibles.
- Different interpretations of intangibles that are not well defined or defined at all. For example the extent to which an activity is research or development.
- Measurement issues at cost and fair value.
- Disclosures alone cannot solve the problem due to commercial sensitivity and no general agreement on how to report on intangibles.
These issues are affecting company's market value and financial position, capital allocation and investment decision, access to finance, and stewardship assessment.
A1From the interviews with UK stakeholders we have heard concerns that are broadly consistent with the issues raised in chapter two of the EFRAG report.
Limited recognition
A2Many stakeholders identified inconsistencies in recognition between IAS 38 Intangible Assets and the Conceptual Framework which has been updated a number of times since IAS 38 was first issued. Specifically, IAS 38 requires expenditure to meet a definition of "asset” and “control” that is no longer consistent with the revised Conceptual Framework. This means that the standard no longer reflects current thinking on what constitutes an asset and therefore does not adequately capture key intangibles that are relevant to some entities. This is consistent with issue 'i' listed above.
A3IAS 38 requires many specific types of internally generated intangibles to be expensed. These include marketing expenditures, internally generated brands, training, customer lists and similar. Almost all stakeholders commented that this prohibition from capitalisation of expenditure that could otherwise be deemed as contributing to an intangible asset fails to capture useful information about many intangible items. This is consistent with issues 'i' and 'iv' listed above.
A4For those items that do meet the definition of intangible asset, recognition of internally generated intangibles under IAS 38 is limited to the “development phase". It was suggested that the criteria for entering the development phase could be considered somewhat arbitrary and open to significant interpretation leading to substantially different accounting outcomes for different entities, even in the same industry. This is consistent with issues 'iv' and 'v' listed above.
Limited consistency
A5There are significant differences between the accounting for internally generated intangible assets (frequently expensed), acquired intangible assets (which use a cost model) and intangible assets acquired through a business combination (which use a fair value model).
A6Stakeholders commented that this leads to significant differences in the accounting for otherwise comparable companies, dependent on whether they have grown organically or through acquisitions. This is consistent with issue ‘ii' listed above. This has led users to acquire their information from other sources in order to compare companies that grown externally and companies that grow organically, in order to be able to compute comparable KPIs and performance indicators. This is consistent with issue 'iii' listed above.
Limited disclosure
A7While there are a substantial number of disclosure requirements for recognised intangible assets under IAS 38, there are virtually no requirements related to intangible expenses. Given that most internal expenditure on intangibles is currently required to be expensed, we heard numerous comments that the current requirements are inadequate. This is consistent with issue ‘vi’ listed above.
Question 2 – Which way to go?
Do you think there is room for improvement regarding information on intangibles in financial reporting? If so:
- Do you think the different approaches described could be combined in a manner that could meet (most of) the needs of users and for which the benefits would exceed the costs? If so, please describe such a combination.
- If you do not think the different approaches described in the Discussion Paper could be combined in a manner that would meet (most of) the needs of users, which (if any) of the described approaches do you think could be worth investigating further with the objective of getting better information on intangibles: * Amending existing recognition and measurement requirements for intangibles (see Chapter 3); * Providing disclosures on specific intangibles (see Chapter 4); * Providing disclosures on future-oriented expenses and risk/opportunity factors that may affect future performance (see Chapter 5); or * An approach other than those described in the Discussion Paper (please explain this approach)?
A8Many of our stakeholders indicated a desire for enhancing the accounting for intangibles and suggested a number of approaches to improving the information on intangibles. A minority of stakeholders suggested or supported either getting rid of specific requirements for intangibles altogether, folding them in with other standards, such as property plant and equipment, or developing specific standards for specific intangibles.
A9However, most stakeholders suggested incremental approaches consistent with those outlined in the EFRAG report.
A10As will be discussed in more detail below, generally stakeholders wanted enhancements to the standard with regard to recognition and measurement. In addition, they wanted better disclosure, both about recognised intangibles and expenses that are related to intangible items. These views are consistent with the ones mentioned above with reference to Chapters 3-5.
Question 3 – Recognition
Chapter 3 considers whether and how internally generated intangibles could be recognised and measured in the financial statements and the benefits and limitations of the proposed approaches. In doing so, consideration is being given to the asset recognition in the statement of financial position but also to the effects in the statement of financial performance.
Do you consider that IAS 38 Intangible Assets should be amended to permit the recognition of certain internally generated intangible assets (in addition to development costs)? (Please explain your answer).
A11According to the research, most stakeholders wanted any new standard for intangibles to recognise and capitalise a greater range of expenditures, potentially including research, training, and certain marketing expenditure in some circumstances
A12Many stakeholders argued that the Conceptual Framework definition of an asset introduced in 2018 should form the basis for recognising intangible items (as opposed to the older definition reflected in IAS 38).
If your answer to this question is 'yes', please also answer sub-questions 1 to 3 below.
1Paragraph 3.26 of this Discussion Paper explains that IAS 38 currently includes an explicit prohibition to recognise some types of internally generated intangible assets such as internally developed brands, mastheads, publishing titles, customer lists and similar items, staff training and marketing. Do you consider that the explicit prohibition to recognise some types of intangible assets that exists in IAS 38 should be removed? (Please explain your answer).
A13A number of stakeholders explicitly identified these prohibitions as problematic. Some noted that the prohibitions seemed to exclude items that otherwise could meet the Conceptual Framework definition of an asset. Also, it was suggested that these prohibitions represent a rule-based approach to accounting that is inconsistent with a desire for principle-based standards.
2Paragraphs 3.10 to 3.71 of this Discussion Paper explore four possible approaches regarding the recognition of internally generated intangibles. Which of the following approaches would you support?
- Recognise (as an asset) all defined intangibles; with no specified conditions or thresholds (see paragraphs 3.15 - 3.35 of this Discussion Paper);
A14Many stakeholders appeared to favour an approach that was based on recognition of intangible assets that met the revised Conceptual Framework definition of an asset.
- Threshold for recognition of an asset (see paragraphs 3.36 - 3.48 of this Discussion Paper);
A15Some stakeholders identified certain recognition thresholds beyond those in the Conceptual Framework (discussed below).
- Conditional recognition of an asset (see paragraphs 3.49 - 3.59 of this Discussion Paper);
A16No stakeholders interviewed advocated for a conditional recognition approach that could allow recapitalisation onto the balance sheet once certain conditions are met.
- No recognition (that is, expensing all internally generated intangibles) (see paragraphs 3.60 - 3.67 of this Discussion Paper); and
A17No stakeholders interviewed advocated for a total prohibition on recognising internally generated intangible assets.
- None of the above or other suggestions (please explain).
A18N/A
3If you support ‘Conditional recognition of an asset' or 'Threshold for recognition of an asset' in the previous sub-question, which criteria would you consider for recognition:
- Criteria based on the level of (un)certainty about the outcome of the intangibles (that is, the probability of expected benefit and the pattern of consumption of these future benefits);
A19A number of stakeholders identified probability of economic inflow greater than 50% as a possible threshold for conditional recognition.
- Criteria based on the identifiability of the expenditure related to the intangibles;
A20A number of stakeholders raised concerns about the allocation of expenditure to specific intangibles given the perceived difficulty in separating out the resultant benefits from other assets used by the organisation.
- Criteria based on the technical or commercial feasibility of the intangibles considered at inception of the development;
A21No stakeholders specifically discussed these criteria.
- Criteria based on separability of the assets, that is, the existence of a legal right and/or the ability to sell, transfer, licence or pledge the asset;
A22A number of stakeholders identified legal or equivalent rights over benefits as a matter that should be considered as a possible threshold for conditional recognition.
- All or a combination of the above depending on the nature of the intangibles (please explain);
- Other suggestions (please specify).
A23N/A
Question 4 – Possible Measurement Bases
If you think that IAS 38 should be amended to permit the recognition of certain internally generated intangible assets (in addition to development costs), which of the following suggested measurement approaches would you support:
- Initial and subsequent measurement at amortised cost with impairment ('Cost model');
- Initial measurement at cost and subsequent measurement at fair value ('Revaluation model');
- Initial and subsequent measurement at fair value (‘Fair value model');
- Initial measurement at fair value (as deemed cost) and subsequent measurement at amortised cost with impairment (‘IFRS 3 model')?
A24Many stakeholders were generally comfortable with capitalisation of many types of costs associated with intangibles, particularly where there were clearly identifiable rights attached to the associated intangible item. They view this as an important step in addressing the issues of standard inconsistency and differences between organic and acquisitive growth.
A25During discussions, most stakeholders agreed that accrual accounting, which would not only capitalise costs but would also require amortisation (dependent on the determination of a reasonable useful economic life) and impairment, would provide more relevant and reliable information.
A26A number of stakeholders who identified as users of financial statements were wary of over-capitalisation of internally generated intangible assets, particularly where there were no clear legal rights that provided certainty over the existence of an asset.
A27Feedback on use of fair value for measurement purposes was more mixed. Some stakeholders thought there should be more fair value measurement of intangibles. However, there was a general acknowledgement that this would increase variability in the financial statements, as valuations of intangibles are likely to become more volatile.
Question 5 – Information relating to specific intangibles
Chapter 4 discusses an approach under which information on specific intangibles, that are key to an entity's business model, is provided to help users assess the contribution of the intangible to the value of the entity.
1To the extent that information relating to specific intangibles should be provided, do you agree that the information should be limited to the intangibles that are key to an entity's business model? If not, why?
A28While stakeholders did mention the importance of enhancing disclosure about intangibles that are central to an entity's business model, there was no suggestion from stakeholders that disclosure should be limited to only these assets.
2Preliminary feedback received from some users of financial reports indicates that an entity's fair value estimate of a specific intangible would generally not be particularly relevant information. Do you agree that disclosing the fair value of an intangible is less helpful for users than disclosure of quantitative and qualitative information that could assist them in forming their own views on the value for an entity of the specific intangible?
A29Users of financial statements were concerned that fair value would make it more difficult to understand the financial statements, particularly where markets were less active or non-existent. Preparers were concerned that users of financial statements would over-react to such fluctuations.
A30However there was an awareness that fair value can be useful when it can be measured based on appropriate information. This could be a case-by-case assessment and take account of the enhancement in information, markets and techniques over time.
3Do you agree with the advantages and disadvantages of information relating to specific intangibles as identified in Chapter 4 compared to recognition and measurement (see Chapter 3) and information on future-oriented expenses (see Chapter 5)? If not, which aspects do you disagree with and/or which additional advantages and disadvantages have you identified?
A31N/A
Question 6 – Information on future-oriented expenses
Chapter 5 proposes various elements of information on expenses recognised in a period that could be considered to relate to benefits that will be recorded in future periods ('future-oriented expenses').
Chapter 5 discusses the approach on providing information on future oriented expense. The purpose is not to assess the value of individual assets, but to assess the financial performance of a period and for predicting future financial performance. Information: Information on whether the costs of the period have been incurred to generate income in the period or in future periods. Two general measures in which this information can be provided: i) By entity's management in the notes to the financial statements / on face of SOFP or ii) In a way that help users to make distinction between expenses related to current and future period.
Additional information to understand an entity's business model, provide additional contextual information about costs (e.g., number of employees and employee costs per function, per segment and region). Example of information if the distinction should be made by users: * Expenses related to patents; * Marketing expenses (including information on spending on trademarks/brands); * Staff training expenses (not included in research and development costs or sales and marketing costs).
1Do you consider that requiring such information could be useful? If so:
- Should the information mainly complement information on specific intangibles (see Chapter 4) or should requirements on future-oriented expenses be introduced instead of requirements on information on specific intangibles?
- Should the information mainly:
- Reflect the views of the entity's management by disclosing the recognised expenses the management considers relate to the benefits of future periods)? Or
- Help users perform their own assessments on the recognised expenses that relate to benefits of future periods, by providing further specifications and breakdown of the expenses of a period?
A32A majority of stakeholders observed that disclosure requirements related to intangible expenditures that are not capitalised must be enhanced. They want more granular information about the nature of expenditure, including but not limited to specific information on marketing, information technologies, training, and research.
A33Stakeholders want to understand the relationship between such expenditure and the organisation's business model. Further, they request information on whether the entity is expecting relevant expenditures to maintain or enhance future cash flows.
A34For many investors (as opposed to stakeholders more generally) improved disclosures was their primary recommendation with regard to accounting for intangibles. However, when the possible alternative approaches were discussed, there was often agreement that more could be done to improve the accounting in terms of recognition, measurement and disclosure for intangible items. Only a few thought that enhancing disclosure alone was sufficient.
A35The following quotes from stakeholders interviewed summarise the main views that emerged on disclosures:
-
Better disclosures are needed for both capitalised and unrecognised intangibles (Academic)
-
Although there are substantial disclosure requirements for recognised intangible assets under IAS 38, these are often confusing. (Auditor)
- There is an issue with no requirements to disaggregate and provide granular information about intangible expenses [under IAS 38] (Investor)
- Reasons for expensing items and why were these not capitalised is lacking from the annual report (Academic)
- Do you consider that requiring such information could be useful? If so:
- Should the information mainly complement information on specific intangibles (see Chapter 4) or should requirements on future-oriented expenses be introduced instead of requirements on information on specific intangibles?
- Should the information mainly:
- Reflect the views of the entity's management by disclosing the recognised expenses the management considers relate to the benefits of future periods)? Or
- Help users perform their own assessments on the recognised expenses that relate to benefits of future periods, by providing further specifications and breakdown of the expenses of a period?
A32A majority of stakeholders observed that disclosure requirements related to intangible expenditures that are not capitalised must be enhanced. They want more granular information about the nature of expenditure, including but not limited to specific information on marketing, information technologies, training, and research.
A33Stakeholders want to understand the relationship between such expenditure and the organisation's business model. Further, they request information on whether the entity is expecting relevant expenditures to maintain or enhance future cash flows.
- Do you agree with the advantages and disadvantages of information on future-oriented expenses identified in Chapter 5? If not, which aspects do you disagree with and/or which additional advantages and disadvantages have you identified?
Advantages: * A fixed terminology to distinguish between different intangibles is not necessary but needed for types of expenses. * Can take account of intangibles that do not create value on their own but together with other assets. * Do not require specific intangibles to be identified hence no measurement issues. * Less costly to providing information on specific intangibles or recognising intangibles.
Disadvantages: * No information on key intangibles is required. * Effectiveness of investment in intangibles is not taken into account. * Difficult to match revenue with previous future-oriented expenses. * Less useful for assessment of stewardship. * Less granular information on intangibles. * Information can be commercially sensitive. * Require guidance on different types of recognised expenses. * Splitting recognised expenses related to current and future period can be subjective. * Not solve the issue of different accounting of acquired and internally generated intangibles. * Costly than providing information on specific intangibles. * IFRS performance measure will still be distorted.
A36While the specific items identified were not explicitly discussed with stakeholders, the advantages and disadvantages identified would appear to be consistent with comments heard from stakeholders.
Question 7– Information on risk/opportunity factors affecting intangibles
Chapter 5 proposes that information included in the financial reports on factors affecting intangibles should be limited to disclosing risk/opportunity factors linked to the key intangibles (whether or not specified) according to the entity's business model. The disclosure should include a description of the risk/opportunity, relevant measures reflecting the risk/opportunity, if relevant (for example, KPI's used to measure it), and how the risk is managed and mitigated. It should include an assessment of the materiality of the risk/opportunity factors based on the probability of their occurrence and the expected magnitude of their impact.
Do you agree with this proposal? If not, what information on risk/opportunity factors affecting intangibles should be provided?
Risk/opportunity factors affecting intangibles – the approach suggested is: * Limited to information that is material and specific to the entity. * Limited to information material for the primary users of financial reports. * Include a description of the risk/ opportunity factors that could affect (the contribution of) both recognised and unrecognised intangibles, how it affects the entity (would also require the entity to describe its business model) relevant measures if relevant and how the risk/ opportunity is managed and mitigated or taken advantage of.
Examples of risk/opportunity factors on which information could be provided (if relevant) * Environmental impact/dependence. * Ability to attract people with the right skills. * Functioning of management control systems. * Customer concentration. * Supplier relationships. * Quality of work of oversight committees. * Respect for human rights. * Anti-corruption and bribery.
A37Many stakeholders talked about the need for enhanced disclosure on risks associated with capitalised intangibles to compensate for the greater uncertainty about their value.
A38They also believed there could be more information linking intangibles to related Key Performance Indicators (KPIs). This would help address concerns about over-capitalisation. For example, management could link useful life and impairment directly to the drivers of value that intangibles are expected to provide. As one user noted:
“Key drivers of value for intangibles would be useful to disclose. For example, employee churn by division, or customer satisfaction (net promoter score).”
A39A number of stakeholders thought that information on these key drivers would be central to future ESG reporting, and that these relationships would be important to highlight and would provide particularly useful information.
A40The issue of materiality was raised in many interviews. Most stakeholders interviewed wanted increased granularity of disclosure. It was observed that intangibles are important drivers of value, but carry increased risk and uncertainty, and so greater disclosure and finer detail would be required to help users of financial statements assess their impact.
A41Stakeholders were asked how this could be balanced with concerns about information overload. Most felt that for intangibles when assessing materiality qualitative factors are more important than quantitative ones. These qualitative factors are likely to be derived from the relationship between the intangible item and its importance to the business model.
Question 8– Issues to be Considered
Chapter 6 discusses challenges and issues to be considered when finding a manner to provide better information on intangibles. It mentions that it could be beneficial to introduce a common terminology on intangibles and that preparers of financial statements should not be required to disclose information on intangibles that would be (very) commercially sensitive.
Issues discussed in chapter 6 are: * Terminology: No fixed terminology to describe intangibles, different words can be used for same intangible, helpful to provide guidance on how to classify different type of expenses * Sensitivity of the information provided: allowing entity not to disclose commercially sensitive information and consider alterative information to be presented * Placement of information: covered below * Relevant and comparable information: it is challenging to make requirements that would result in comparable information and information relevant to a particular entity * Potential effects on the ability to receive finance: consideration should be given to whether recognising some assets can affect the entity's ability to receive finance e.g., research and development in pipeline, brand reputation and customer loyalty might be accepted as collateral, whereas goodwill would not * Removal of some of the current requirements: to assess whether reporting requirements such as how to account for acquired intangibles can be costly for preparers could be removed
- Do you consider that it would be useful to introduce a common terminology on intangibles?
A42A small minority of stakeholders mentioned broad categories of intangibles. However, this particular aspect was neither explicitly explored nor has it emerged as a theme from the interviews we conducted.
- Do you agree that preparers of financial statements should not be required to disclose information on intangibles that would be (very) commercially sensitive?
A43Some stakeholders expressed concerns about commercial sensitivity, but again stakeholders identified materiality as the overriding factor.
- Are there additional issues than those listed in Chapter 6 you think should be taken into account when considering how to provide better information on intangibles?
A44N/A
Question 8– Placement of the information
Chapter 6 presents an approach under which information discussed in Chapter 4 and Chapter 5 would be placed in the notes to the financial statements if the information is related to an item that meets the definition of an asset or to an item recognised in the statement of financial performance. In other cases, the information would be placed in the management report. However, it is noted that such an approach would result in information about intangibles to be spread between the notes to the financial statements and the management report.
Where do you think the different types of information that would follow from the approaches discussed in Chapter 4 and Chapter 5 should be placed? Should they be placed all in the same section or in different sections of the financial report and why?
Regarding the placement of information on intangibles, this paper suggest: * Information on specific intangibles (chapter 4) should be placed in the notes to the financial statements if those specific intangibles meet the definition of an assets, if not, then should be disclosed in the management report. For approach suggested in chapter 5, this means that additional information on future oriented expenses would be included in notes and disclosures about risk/opportunity factors would be included in the management report.
Argument against this approach: * Users have to consult two different sources/parts in the financial report. * Content of the management report and whether these should be prepared depend on local requirements.
A45Stakeholders commented that having the information in the financial statements (including the notes) as opposed to in management commentary gives the information greater prominence, and because it will then have to be audited it will give users greater confidence in the information reported.
Footnotes
-
See appendix 2 for examples of publications on intangible assets. ↩↩↩
-
See for example Haskel and Westlake (2018), "Capitalism without Capital: The Rise of the Intangible Economy" Princeton University Press ↩↩
-
Ontario CPA Insight (2021), “You Can't Touch This: The Intangible Assets Debate", https://www.cpaontario.ca/intangibles ↩↩
-
See for example Barker, Richard & Lennard, Andrew & Penman, Stephen & Teixeira, Alan. (2021), "Accounting for intangible assets: suggested solutions". Accounting and Business Research. ↩↩
-
EFRAG Discussion Paper: Better Reporting on Intangibles 6: Missing intangible assets distorts return on capital ↩↩
-
For simplicity the rest of the report uses the term "accounting for intangibles" to mean both accounting on and reporting of intangibles. ↩↩
-
Feedback-Statement-FINAL.pdf (frc.org.uk), para 6. 9: The production and consumption of information on intangibles: an analysis of some preliminary results ↩↩
-
The IASB has also started to use similar terminology (i.e. intangible items) for similar reasons. In the IASB's April 2022 paper suggesting they undertake an intangibles project they acknowledge that "although this paper refers to a project on intangible assets... one key issue to consider in such a project is whether it should be limited to accounting for and disclosing information about financial statement elements intangible assets and expenses arising from expenditure on intangible items-or whether the project should aim to address intangible items more broadly" (para 36). ↩↩↩
-
Intangible Assets, note it is unclear whether this was exclusively in the context of GAAP requirements, though they are similar to IFRS in many ways. ↩↩
-
https://www.ifrs.org/projects/work-plan/2020-agenda-consultation/ ↩↩
-
AP24D: Feedback summary-Potential projects (part 1) (ifrs.org) ↩↩
-
The remainder of this proposal will use the term "accounting for intangible assets" to include both accounting and reporting. ↩↩
-
See Chapter 2: Objective, usefulness and limitations of general purpose financial reporting ↩↩
-
[This paragraph was added in October 2022 to explicitly state the nature of the research in each phase] ↩↩
-
[Title amended in October 2022 to better reflect nature of research as had previously been agreed with Board] ↩↩
-
[Paragraph amended in October 2022 to better reflect nature of research as had previously been agreed with Board]. ↩↩
-
IFRS - IASB call for research on Making Materiality Judgements ↩↩
-
[Paragraph added in July 2022 to reflect discussion with the IASB] ↩↩
-
[Paragraph replaced in October 2022 to reflect Board's discussion and subsequent amendments to the [Draft] Due Process Handbook]. ↩↩↩
-
[In October 2022 the order of Major Output 2 and 3 were swapped to better reflect the relationship between the outputs and their timing] ↩↩↩
-
[Amended in July 2022 to reflect our understanding of the due process at that time. Amended in October 2023 to adjust publication date from early 2023 to H2 2023 and for subsequent amendments to the [Draft] Due Process Handbook]. ↩↩
-
[Amended in October 2022 to reflect the intended engagement with the Advisory Groups] ↩
-
[Added in July 2022 to reflect our understanding of the due process. Amended in October 2023 to adjust publication date from mid-2023 to early 2024 and for subsequent amendments to the [Draft] Due Process Handbook] ↩
-
[In July 2022 the more comprehensive original proposals for Phase 2 were removed in acknowledgement that it would be better at this stage to reassess proposals in light of the IASB plan and findings from first phase of research] ↩
-
[Added in October 2022 to reflect Board's discussion and subsequent amendments to the [Draft] Due Process Handbook]. ↩↩
-
A phenomenon in turn labelled post-industrialism or post-Fordism, see Bell, 1973. ↩↩
-
We herein use the expression intangible capital to distinguish it from the expression "intangible asset" which in this report we use in a strict sense as defined in IAS 38. To avoid repetition, we may use the term "intangibles" within this section. ↩
-
Brynjolfsson, Hitt and Young, 2002; (emphasis added) ↩
-
See Thum-Thysen, Voigt, Bilbao-Osorio, Maier and Ognyanova (2017). ↩
-
Both defining features of assets: see Thum-Thysen et al., 2019; Crouzet, Eberly, Eisfeldt and Papanikolau, 2022. ↩
-
The below list is distilled from Crouzet, Eberly, Eisfeldt and Papanikolau, 2022; Haskel and Westlake (2017); Andrews and de Serres (2012); Villalonga (2004). ↩
-
See the pioneering theoretical framework of Crouzet et al. (2022) in particular, where the need for a storage medium is emphasised as one of the two defining characteristics of intangibles alongside with being non-rivalrous. ↩
-
Brynjolfsson, Hitt and Young (2002); B. Hall (1993a); Griliches (1981); Lev and Sougiannis (1996); Bresnahan, Brynjolfsson, and Hitt (1999, 2002). ↩
-
Spillovers or externalities are situations in which the activities of one agent in the market induce external effects (either positive or negative) on other agents in that market. ↩
-
See Department of Business, Innovation and Skills (2012), and in particular Tables 16 and 20; see Goodridge, Haskel and Wallis (2017). ↩
-
Quote from Morningstar (2017); see also Intermede (2020). ↩
-
See Hölzl (2005) and literature therein. ↩
-
Thum-Thysen et al. (2017). Andrews and de Serres (2012). ↩
-
See Martin and Baybutt (2021), Martin (2019) and Box XX. ↩
-
See also Nakamura, 2003; 2010. ↩
-
For example the UN System of National Accounts (SNA) and the European System of Accounts (ESA). ↩
-
This literature is relevant to our report for two reasons: firstly, the issues faced by national accountants and statistician when dealing with the recognition and measurement of intangible investment and assets are (unsurprisingly) very similar to the ones faced by standard setters and companies' accountants. Secondly, correctly recognising and measuring intangible assets at a company level is important to help measure national output and therefore contribution of private investment to the long-term public good. See Corrado, Hulten and Sichel (2006), Pages 16 and following and Table 1. ↩
-
For more recent estimates by the ONS see paragraphs XX-XX. ↩
-
This would be a desirable outcome from the long-term public good perspective. ↩
-
Other UK-focused contributions extend the CHS framework to account for additional types of intangible capital. For example, Corrado, O'Mahoney and Samek (2021) develop a model to incorporate formal education/schooling into the national production function, thus treating national spending in education as an investment rather than as consumption (as it's currently accounted for).. O'Mahoney and Samek (2021) develop a framework to incorporate health into human capital stocks at a national level. The authors show that, on average, poor health reduces human capital stock by 12% in the United Kingdom. ↩
-
Outside of the United Kingdom, Corrado, Haskel, Ionni, Jona-Lasinio, Mas and O'Mahoney (2018) apply the CHS framework to EU countries, finding that in the EU14 over the 2000-2013 period the share of intangibles over GDP was lower than that of tangibles: 7.2% against 9.4%. The authors however found that northern and non-German speaking continental countries were characterised by higher investment in intangible capital than Mediterranean and German-speaking continental countries. Elnasri and Fox (2017) apply the CHS framework to Australia, showing that in 2015 intangible investment was ASD 82 billion, well-below the ASD 227 billion invested in tangible capital. This suggests that, as expected, reliance on intangible capital tends to differ between countries. ↩
-
Firm-level capital market outcomes are discussed separately in the following section. ↩
-
The paper differentiates between intangible capital, measured at a firm level, and human, social, technological and public capita, measured at a regional level We refer to the paper itself for more detailed definitions of these capitals. ↩
-
Roth, Sen and Rammer (2021), focusing on Germany, find a positive relationship between intangible capital and firm-level productivity, which stronger magnitudes for services firms (as opposed to manufacturing). Crass and Peters (2014) also focus on Germany. Following the framework introduced in Corrado et al. (2005), their paper differentiates intangible capital into Innovative capital (IC), Branding capital (BC), Human capital (HC) and Organisational capital (OC). The authors find that the R&D component of IC to be strongly and positively related to firms' total factor productivity, as well as all components of BC (marketing, trademarks) and HC (training, high skilled labour). The authors find mixed results with respect to OC. The seminal Bontempi and Mairesse (2015) study the contribution of intangible capital to production, using Italian firm-level data. They find that intangible capital positively and strongly contributes to output, and the result is robust to the estimation of different production functions. They break down intangible capital into Intellectual capital (IK) and Customer capital (CK), and find that the marginal productivity of CK is higher than that of IK. Takizawa (2015) studies the effect of intangibles play in labour productivity growth in the US and Japan. They find that intangibles are positively related to labour productivity growth in the US, but not in Japan, though investment in both tangible and intangible assets was found to have a positive relation with labour productivity growth in both countries. Lin and Lo (2015) study the determinants of intangible investment in Taiwan, as well as the relation between intangibles and productivity. ↩
-
More in detail: Villalonga (2004) discusses how intangible assets can affect long-term competitive advantage, measured as profits persistence. Using US listed companies' data, the author finds that intangible capital are a determinant of a firm's long term profitability and henceforth the source of competitive advantage in most industries. However their results show that intangible assets can also "lock in" competitive disadvantage. Montresor and Vezzani (2014) study the impact of intangible assets on innovation at a firm level. Using pan-European firm-level data for the year 2013, the authors find that internally generated intangibles explain firm-level innovation more than externally generated intangibles. In addition, "technological intangibles" (whether internally generated or not) also have a significant influence on companies' ability to innovate. Di Cintio, Ghosh and Grassi (2017) look at the relation between investment in R&D, firms' export and firms' growth using a sample of Italian SMEs. Using a convincing empirical strategy, the authors show that R&D is associated with both more exports and more growth, though firms that export tend to grow less as a result of R&D. The authors did not find any direct effect of exports on companies' growth. ↩
-
These are discussed in a separate section as the economic theory, the empirical techniques and the data utilised to estimate the empirical models are substantially different from the ones used in microeconomics. ↩
-
The authors extend a traditional Fama and French 5-factor asset pricing model (Fama and French, 2015) to include an "intangible intensity" factor capturing the share own-generated intangible assets over total assets. Their factor excludes goodwill. For their estimations, the authros use returns on the Russel 3000 constituents for the 1989-2020 period. ↩
-
Focusing on the econometrics, the authors create an intangibles-adjusted HML factor (which captures the performance of value stocks) that outperforms the traditional Fama and French (2015) HML factor by 2.11% annually. Park (2019) conducts a similar exercise and obtains comparable results. ↩
-
See Autor, Dorn, Katz, Patterson and Van Reenen, 2017; Tambe, Hitt, Rock and Brynjolfsson, 2020. ↩
-
Tambe, Hitt, Rock and Brynjolfsson (2020) estimate prevalence and impact on productivity of "digital capital", understood as "factors of production that are complementary to recorded investments in IT assets (such as hardware and software), but that are not otherwise recorded on a firm's balance sheet". The authors estimate the prevalence of digital capital among US publicly listed companies, showing that this has increased dramatically over the last 20 years, largely because of an actual accumulation of capital (the authors estimate that the price of digital capital has roughly remained constant after the dot-com bubble, so growth can't be attributed to prices). ↩
-
There is vast literature showing that Big Data Analytics (BDA) is a driver of competitive advantage (see Corte-Real, Oliveira, Ruivo, 2016, and references therein; see Wamba et al., 2017) and innovation (Ghasemaghei and Calic, 2020). ↩
-
Birch, Cochrane and Ward (2021). ↩
-
Xiong, Xie, Zhao, Lin and Fan (2022). ↩
-
We would like to mention the work of Jonathan Haskel, Peter Goodridge, Gavin Wallis, Mary O'Mahoney, Josh Martin, Richard Heys, among others, as of particular relevance for the recognition of intangibles in national accounts. ↩
-
See most recent ONS bulletin: https://www.ons.gov.uk/economy/economicoutputandproductivity/productivitymeasures/articles/experimentalestimatesofinvestmentinintangibleassetsintheuk2015/2018#measuring-the-data ↩
-
The market sector is defined by the ONS as "the part of the economy that charges economically meaningful prices for its output, and as such operates for profit. Includes all profit-making corporations, whether privately or publicly funded, and excludes non-profit institutions serving households (such as charities) and general government". See https://www.ons.gov.uk/economy/economicoutputandproductivity/publicservicesproductivity/methodologies/howtocompareandinterpretonsproductivitymeasures ↩
-
See link to the Annual Business Survey questions, through which R&D data is estimated: https://www.ons.gov.uk/surveys/informationforbusinesses/businesssurveys/latestquestionsfortheannualbusinesssurveyabsrespondents ↩
-
This would be a desirable outcome from the long-term public good perspective. ↩
-
See also Roth, Sen and Rammer (2021) who find a similar result using German firm-level data; Peters and Taylor (2017) who estimate the stock of intangible capital to be nearly half of total capital for US firms. ↩
-
As of 2019, roughly £60 billion were accounted for, of which half could be attributed to R&D, suggesting that total accounted investment (tangible and intangible) was in the ballpark of £230 billion, which is consistent with national account estimates. ↩
-
We have chosen this time span due to data availability/reliability. ↩
-
We compared 2021 year-end market valuations with 2009 as in 2008 they were negatively affected by the financial crisis. ↩
-
See BAT 2017 financial statements, pages 132 and following ↩
-
The analysis was conducted using Reutiers Eikon, Fame, Companies Watch and companies' financial statements. ↩
-
See Unilever 2021 financial statement, page 123. ↩
-
Put link to Diageo financial statements ↩
-
See Villalonga, 2004; Peters and Taylor, 2017; Bongaerts, Kang and Van Dijk (2022) [other papers]. [Describe methodology] ↩
-
The sample is: Arnold Clark Automobiles, Arup, Bestway, CDS Superstores, Domestic and general, Edrington Group, Euro Garages Ltd, Heathrow Airport Holdings Limited, INEOS Group Holdings, ISG, John Lewis PLC, KCA Deutag Alpha Limited, Matalan, Motor fuel group, Morson group, Nando's Group Holdings, Neptune Energy Group LTD, New look retail holdings Ltd, Pertemps Network Group Limited, Pension Insurance Corporation PLC, Reed, Rothesay Life Plc, Stonegate pub company, John swire & sons limited, Kemble Water Finance Ltd, The very group, THG, Vue International Bidco PLC. ↩
-
As of end of 2021 their combined income after taxes was £XXXX billion (XX% of the GDP), they employed XXXX million people (XX% of the workforce). ↩
-
Since the publication of IAS 38 in 1998, nearly 25 years ago, there have been significant developments in the world. To put this in context consider just a few of the technologies become mainstream in the last two decades: - Smartphones (the first Apple iPhone was released in 2007) - The rise of Artificial Intelligence, increasing reliance on algorithms and Big Data - Easily accessible video calling (Skype launched in 2003) - Video streaming (YouTube launched on 2005) - Social media (Facebook launched in 2004) - 3D printing - Internet usage has grown from virtually 0 to over 50% of the world population - The mainstreaming of hybrid and electric transportation. Many of these changes relate directly to intangible items. ↩
-
The Conceptual Framework for Financial Reporting is a fundamental element of International Accounting Standards. While not a Standard itself: "The Conceptual Framework sets out the fundamental concepts for financial reporting that guide the Board in developing IFRS Standards. It helps to ensure that the Standards are conceptually consistent and that similar transactions are treated the same way, so as to provide useful information for investors, lenders and other creditors. The Conceptual Framework also assists companies in developing accounting policies when no IFRS Standard applies to a particular transaction, and more broadly, helps stakeholders to understand and interpret the Standards." IFRS Conceptual Framework for Financial Reporting. ↩
-
[add an additional reference from academic literature] ↩
-
noted, to be recognised as an intangible asset IAS 38 requires expenditure to meet a different definition of "asset" and "control" from that in the Conceptual Framework. Even then, many internally generated assets must simply be expensed without further consideration under the current IAS 38 requirements, as IAS 38 requires many specific types of internally generated intangibles to be expensed. These include marketing expenditures, internally generated brands, training, customer lists and similar. ↩
-
This point is also picked up by Barker et al (2020) "Another example of conditional capitalization is observable in the extractives sector. An entity developing an oil field or a mine is allowed to recognise exploration costs as an asset... In contrast, an entity that develops a new drug generally cannot recognise an asset until much later in the process (because of the six additional criteria in IAS 38). Yet both activities are about exploring for a product." (Barker et al. 2020, pg. 22) ↩
-
Mazzi et al. (2019), a paper that uses a similar methodology to this report. ↩
-
We are grouping these stakeholders' views here as opposed to the previous section as these stakeholders expressed a generally favourable view of the status quo. However, we note that the mere fact of having to seek information elsewhere is in and of itself a hint that the accounting does not provide the required level of information, a point already emphasised in paragraphs XX-XX. ↩
-
See Zambon et al, 2020. ↩