6.0 Subsidiaries without Public Accountability Disclosures Approve Draft Comment Letter
UK ENDORSEMENT BOARD 9 DECEMBER 2021 AGENDA PAPER 6
Executive Summary
| Project Type | Influencing |
| Project Scope | Significant |
Purpose of the paper
The purpose of this paper is to:
- obtain Board feedback on Draft Comment Letter and accompanying invitation to comment questions on the IASB's ED Subsidiaries without Public Accountability: Disclosures; and
- ask whether the Board agrees to include in the Draft Comment Letter the recommendation for the IASB to consider not requiring eligible subsidiaries to produce a statement cash flows.
Summary of the Issue
IASB's Exposure Draft ED/2021/7 Subsidiaries without Public Accountability: Disclosures seeks to develop an accounting standard that permits eligible subsidiaries to apply the recognition, measurement and presentation requirements in IFRS Standards accompanied by a reduced disclosure regime.
Our initial stakeholder outreach has indicated support for the proposals in the ED. However, some concerns were identified, mainly relating to proposed disclosures that did not seem necessary.
The UKEB Draft Comment Letter highlights these concerns. The Invitation to Comment (questions at the end of the DCL) will focus on determining the appetite of UK stakeholders to use the draft Standard and identifying other significant issues with the proposed disclosure requirements. We intend to publish the DCL on the website for a 30 day consultation period.
Decisions for the Board
The Board is asked to:
- Approve the Draft Comment Letter and Invitation to Comment questions for stakeholder consultation.
- Consider whether it wishes to recommend not requiring eligible subsidiaries to produce a statement of cash flows in its response to the IASB.
Recommendation
We recommend the Board approve the Draft Comment Letter and Invitation to Comment questions for stakeholder consultation.
Appendices
Appendix 1 Draft comment Letter – Subsidiaries without Public Accountability: Disclosures and Proposed Invitation to Comment Questions
Background
1The IASB's Exposure Draft (ED) Subsidiaries without Public Accountability: Disclosures¹ was published on 26 July 2021. It seeks to develop an accounting standard that would permit eligible subsidiaries to apply reduced disclosure requirements so long as they apply the recognition, measurement and presentation requirements in IFRS Standards. The IASB's comment deadline is 31 January 2022.
2The IASB added the reduced-disclosure IFRS Standard project to its agenda in response to feedback from stakeholders (mainly preparers) on the Request for Views—2015 Agenda Consultation. It specifically responds to the feedback that groups would prefer their subsidiaries, that do not have public accountability to prepare their individual financial statements in accordance with IFRS Standards, but with reduced disclosure requirements.
3In the UK, FRS 101 Reduced Disclosure Framework sets out an optional reduced disclosure framework which addresses the financial reporting requirements and disclosure exemptions for the individual financial statements of subsidiaries and ultimate parents that otherwise apply the recognition, measurement and disclosure requirements of UK-adopted international accounting standards.
UK Stakeholder feedback
4To date, we have received limited feedback from stakeholders. Outreach to date has included conducting a roundtable with 4 accounting firms, 3 preparers, discussions with HMRC, ACCA and the Financial Reporting Council. A survey was published on 2 November 2021 and the deadline for completion of the survey is 10 January 2022.
5The stakeholder feedback so far is that:
- Most stakeholders supported IASB's proposed scope in the ED i.e. limited only to subsidiaries without public accountability. However, a few stakeholders supported expanding the scope to all entities. In their view, the IASB used the disclosure requirements in the IFRS for SMEs Standard as a starting point and these disclosures are not designed solely for subsidiaries.
- Stakeholders strongly supported (maintaining FRS 101) and allowing the use of the draft Standard as an alternative choice to FRS 101.
- Stakeholders indicated some concern with IASB's 'bottom-up approach' to developing the proposed disclosure requirements i.e. starting with the disclosure requirements in the IFRS for SMEs Standard and then compare the recognition and measurement requirements in IFRS Standards and, when the recognition and measurement requirements differed between IFRS Standards and the IFRS for SMEs Standard, address the disclosures to align with the requirements in the IFRS Standards. They note that this approach would require a lot of effort from preparers in terms of determining the required disclosures compared to the disclosure requirements in full IFRS Standards. Preparers of subsidiary financial statements may not be familiar with
the IFRS for SMEs Standard. Therefore, in their view, this approach does not achieve the objective of reducing costs for subsidiaries.
- Stakeholders noted that the proposed disclosure requirements for IFRS 2 Share-based Payment, IFRS 7 Financial Instruments: Disclosures, IFRS 13 Fair value Measurement and IAS 24 Related Party Disclosures are burdensome. They recommend these proposed disclosures be removed in the draft Standard. The specific issues are set-out in the DCL.
- Stakeholders indicated that in their experience entities that issue insurance contracts within the scope of IFRS 17 Insurance Contracts that could be eligible to apply the draft Standard are mainly subsidiaries that insure only the risks of its parent or its fellow subsidiaries (sometimes called a 'captive insurer'), and is not otherwise publicly accountable, might be eligible to apply the draft Standard. They noted that 'captive insurers' are unlikely to be prevalent in the UK. In addition, some stakeholders support the IASB's approach to propose reduced disclosure requirements only after entities have applied IFRS 17. However, our preferred approach would be for the IASB to propose the reduced disclosures for subsidiaries without public accountability as part of the package of the exposure drafts for any new or amended standards.
Draft Comment Letter and ITC
6The draft comment letter (included as Appendix 1 to this paper):
- supports IASB's effort to develop a reduced-disclosure IFRS Standard for eligible subsidiaries;
- recommends the IASB extend the scope so that ultimate parent of a group may take advantage of the reduced-disclosure IFRS Standard in its individual financial statements; and
- suggests that the draft Standard be closely aligned with FRS 101 to the extent possible.
7The Invitation to Comment questions ask stakeholders whether they would consider moving from FRS 101 to the reduced-disclosure IFRS Standard and their feedback on the proposed disclosure requirements.
Questions for the Board
8Do Board members approve the Draft Comment Letter and Invitation to Comment questions for release for stakeholder consultation?
Other considerations – statement of cash flows exemption
9Under FRS 101, qualifying entities are not required to prepare a statement of cash flows because FRS 101 exempts a qualifying entity from the requirements of IAS 7 Statement of Cash Flows.
10By contrast, the IASB's ED does not change the current recognition, measurement and presentation requirements in IFRS Standards. Therefore, the requirements of IAS 7 apply to eligible subsidiaries that opt to apply the draft Standard. The ED does require reduced disclosures for the statement of cash flows compared to those in IAS 7.
11In addition, paragraph 130 of the ED requires an entity to disclose a reconciliation between the opening and closing balances in the statement of financial position for liabilities arising from financing activities which should include:
- changes from financing cash flows;
- changes arising from obtaining or losing control of subsidiaries or
- other businesses;
- the effect of changes in foreign exchange rates;
- changes in fair values; and
- other changes.
12The proposed requirement in paragraph 130 of the ED is a simplified version of the requirements in paragraphs 44A–44E of IAS 7 for changes in liabilities arising from financing activities.
13Initial outreach with stakeholders indicated that one of the main benefits of FRS 101 is the exemption to prepare a statement of cash flows. They noted that exemption from producing a statement of cash flows is a significant cost saving.
14The UKEB could recommend the IASB consider a similar exemption. We note that strictly speaking this is outside the scope of the ED, which does not change the current recognition, measurement and presentation requirements in IFRS Standards. However, reflecting on the experience of FRS 101 and stakeholder feedback we believe this could be brought into the scope of the ED.
Question for the Board
15Does the Board wish to comment on exemption from the requirements of IAS 7 Statement of Cash Flows in its response to the ED?
Next Steps
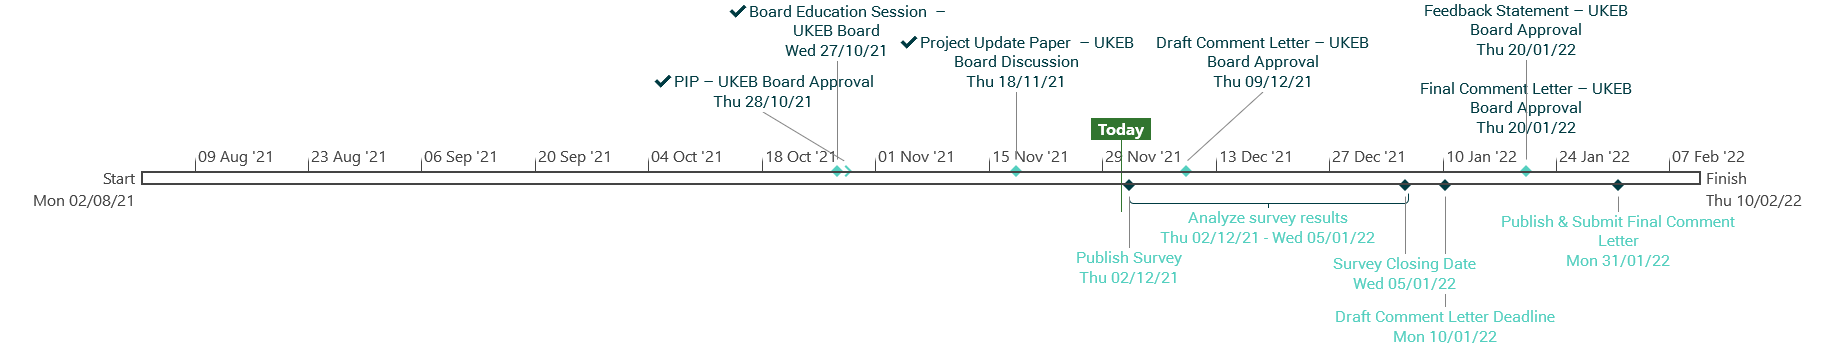
16The next project milestones are as follows:
| Date | Milestone | Complete |
|---|---|---|
| 26 July 2021 | IASB Publish ED | ✔ |
| 28 October 2021 | Approve PIP | ✔ |
| 02 November 2021 | Publish stakeholder survey | ✔ |
| 09 December 2021 | Board Meeting Approve Draft Comment Letter | |
| 13 December 2021 | Publish Draft Comment Letter. Deadline for responses 05 January 2022. | |
| 20 January 2022 | Board Meeting Approve Final Comment Letter | |
| 31 January 2022 | Approve Feedback Statement Submit Comment Letter to IASB Publish Feedback Statement on website. |
Dr. Andreas Barckow Chairman International Accounting Standards Board 7 Westferry Circus Canary Wharf London E14 4HD
[Date]
Dear Dr Barckow
Appendix 1: Invitation to Comment: Exposure Draft ED/2021/7 Subsidiaries without Public Accountability: Disclosures
The UK Endorsement Board (UKEB) is responsible for endorsement and adoption of IFRS for use in the UK and therefore is the UK's National Standard Setter for IFRS. The UKEB also leads the UK's engagement with the IFRS Foundation (Foundation) on the development of new standards, amendments and interpretations. This letter is intended to contribute to the Foundation's due process. The views expressed by the UKEB in this letter are separate from, and will not necessarily affect the conclusions in, any endorsement and adoption assessment on new or amended International Accounting Standards undertaken by the UKEB.
There are currently approximately 1,500 entities with equity listed on London Stock Exchange using IFRS Standards¹. In addition, unlisted companies have the option to use IFRS and a significant number take up this option.
We welcome the opportunity to provide comment on the IASB's Exposure Draft ED/2021/7 Subsidiaries without Public Accountability: Disclosures. To develop our draft response our work to-date has included in-house research and some initial outreach at our stakeholders' roundtables. Our work on these matters continues and will inform our final comment letter. Our high-level comments from our initial work are as follows:
1We support IASB's efforts to develop an IFRS Standard that would permit eligible subsidiaries to apply recognition and measurement requirements in IFRS Standards, but with a reduced set of disclosure requirements. It should be noted that subsidiaries without public accountability usually have few users of their financial statements, primarily parent entities, tax authorities and providers of credit such as bank credit departments. These users can request additional information from management and therefore financial statements are not their single source of information. We see merit in the draft Standard in terms of anticipated cost savings and reductions in complexity for preparers of eligible subsidiaries that report to a parent applying IFRS Standards in its consolidated financial statements. Other benefits of the draft Standard include disclosures tailored to the needs of users of these financial
statements and reduced audit work, compared to applying the requirements of IFRS Standards in full.
2Whilst we broadly agree with the proposed scope set out in the ED, that the draft Standard would be available only to subsidiaries without public accountability. However, we recommend the IASB to extend the scope so that ultimate parent of a group may take advantage of the reduced-disclosure IFRS Standard in its individual financial statements. Users of individual financial statements have less information requirements than users of consolidated financial statements. In addition, the draft Standard used the disclosure requirements in the IFRS for SMEs Standard as a starting point and these disclosures are not designed solely for subsidiaries.
3Initial consultation with stakeholders has identified possible further reductions to some of the disclosures set out in paragraphs 22 to 213 of the draft Standard for eligible subsidiaries. Two main areas suggested by UK stakeholders include the disclosure requirements of IFRS 7 Financial Instruments: Disclosures and IFRS 13 Fair Value Measurement. More information on these issues can be found in the appendix to this letter.
4We are aware of entities in the UK that issue insurance contracts within the scope of IFRS 17 Insurance Contracts and could be eligible to apply the draft Standard, these are mainly 'captive insurers'. However, some stakeholders indicated that the latter are unlikely to be prevalent in the UK. We have reservations about supporting full IFRS 17 disclosure requirements for subsidiaries eligible, which are not publicly accountable, to use the draft Standard on the grounds of undue costs for preparers and users' information needs. We are also concerned that this could create a precedent for any new IFRS Standards it issues in the future. Our preferred approach would be for the IASB to propose the reduced disclosures for subsidiaries without public accountability as part of the package of the exposure drafts for any new or amended standards.
In the UK FRS 101 Reduced Disclosure Framework, provides a reduced disclosure framework for qualifying entities. In particular, it allows subsidiaries of groups preparing consolidated financial statements in accordance with UK-adopted international accounting standards to apply accounting policies consistent with the group accounts, but to take advantage of disclosure exemptions to reduce the cost of preparing financial statements. FRS 101 can be applied in the individual financial statements of subsidiaries and ultimate parents. Our desk-based research and initial outreach with stakeholders clearly identified the wide use of FRS 101 in the UK and the positive impact of the FRS 101 regime on the cost-effectiveness of the preparation of the financial statements. The cost of producing full UK-adopted international accounting standards disclosure for individual group entities would be disproportionate to the use made of subsidiary financial statements, which often have few users that are external to the group. FRS 101 offers a cost saving due to the reduced number of disclosures that require preparing and auditing. We therefore recommend the IASB closely align the proposed disclosure requirements in the draft Standard with FRS 101 to the extent possible. Our recommendation is based on the positive impact of FRS 101 on financial reporting.
If you have any questions about this response, please contact the project team at [email protected]
Yours sincerely
Pauline Wallace Chair UK Endorsement Board
Appendix Questions on ED/2021/7 Subsidiaries without Public Accountability: Disclosures.
Appendix: Questions on ED/2021/7 Subsidiaries without Public Accountability: Disclosures
Objective
Question 1: Objective
Paragraph 1 of the draft Standard proposes that the objective of the draft Standard Subsidiaries without Public Accountability: Disclosures is to permit eligible subsidiaries to apply the disclosure requirements in the draft Standard and the recognition, measurement and presentation requirements in IFRS Standards.
Do you agree with the objective of the draft Standard? Why or why not? If not, what objective would you suggest and why?
A1We support IASB's effort to develop an IFRS Standard that would permit eligible subsidiaries to apply IFRS Standard with reduced disclosure requirements.
A2It should be noted that subsidiaries without public accountability usually have few users of their financial statements, primarily parent entities, tax authorities and providers of credit such as bank credit departments. These users can request additional information from management and therefore financial statements are not their single source of information.
A3The objective of the ED is similar to those in FRS 101 Reduced Disclosure Framework, which sets out an optional reduced disclosure framework for the individual financial statements of subsidiaries and ultimate parent entities that otherwise apply the recognition, measurement and disclosure requirements of UK-adopted international accounting standards.
A4Feedback from stakeholders indicated the use of FRS 101 in the UK has led to significant cost saving and we would expect similar benefits in general for entities that opt to use the draft Standard given that both Standards have similar scope.
A5Initial outreach with preparers indicated that groups with overseas subsidiaries are those most likely to consider adopting the draft Standard. Such groups can see a number of benefits from aligning the financial reporting framework of their subsidiaries worldwide, including consistency of reporting to the parent for the purposes of preparing the consolidated financial statements and resulting cost savings for both parents and subsidiaries.
Scope
Question 2: Scope
Paragraphs 6–8 of the draft Standard set out the proposed scope. Paragraphs BC12–BC22 of the Basis for Conclusions explain the Board's reasons for that proposal.
Do you agree with the proposed scope? Why or why not? If not, what approach would you suggest and why?
A6We broadly agree with the proposed scope which is in line with the objective of the project which respond to requests from stakeholders—mainly preparers—to the Request for Views—2015 Agenda Consultation to provide disclosure relief for subsidiaries whose parent prepares consolidated financial statements applying IFRS Standards.
A7However, we recommend the IASB to extend the scope so that ultimate parent of a group may take advantage of the reduced-disclosure IFRS Standard in its individual financial statements. Users of individual financial statements have less information requirements than users of consolidated financial statements and draft Standard used the disclosure requirements in the IFRS for SMEs Standard as a starting point and these disclosures are not designed solely for subsidiaries.
Developing the proposed disclosure requirements
Question 3: Approach to developing the proposed disclosure requirements
In developing the proposed disclosure requirements, the Board used the disclosure requirements from the IFRS for SMEs Standard, with minor tailoring, when the recognition and measurement requirements in IFRS Standards and the IFRS for SMEs Standard were the same. When the recognition and measurement requirements differed between IFRS Standards and the IFRS for SMEs Standard, the Board:
- added disclosure requirements for topics or accounting policy options that are addressed in IFRS Standards but omitted from the IFRS for SMEs Standard. To do so, the Board applied (to the disclosure requirements in IFRS Standards for that topic or policy option) the principles it used when developing the disclosure requirements in the IFRS for SMEs Standard.
- deleted disclosure requirements relating to accounting policies available in the IFRS for SMEs Standard but not in IFRS Standards.
The Board applied this approach so the disclosure requirements proposed in the draft Standard would be sufficient to meet the needs of users of the financial statements. After applying that approach, the Board reviewed the outcome and in a limited number of cases, proposed some exceptions.
Paragraphs BC23–BC39 of the Basis for Conclusions explain the Board's reasons for its approach to developing the proposed disclosure requirements.
Do you agree with that approach? Why or why not? If not, what approach would you suggest and why?
A8Initial outreach with stakeholders has indicated some concern with IASB's 'bottom-up approach' to developing the proposed disclosure requirements i.e. start with the disclosure requirements in the IFRS for SMEs Standard and then compared the recognition and measurement requirements in IFRS Standards and, when the recognition and measurement requirements differed between IFRS Standards and the IFRS for SMEs Standard, address the disclosures to align with the requirements in the IFRS Standards. They note that this approach would require a lot of efforts from preparers in terms of determining the required disclosures compared to the disclosure requirements in full IFRS Standards. Preparers of subsidiary financial statements may not be familiar with the IFRS for SMEs Standard. Therefore, in their view this approach does not achieve the objective of reducing costs for subsidiaries.
A9By contrast, stakeholder also indicated that a ‘top-down approach' similar to FRS 101, which started with the full IFRS Standards disclosure requirements and provided disclosure exemptions to those disclosures is a better approach and easier to apply. In addition, this approach would result in consistency of language between the draft Standard and full IFRS Standards which would be helpful when transitioning to the draft Standard.
A10We do not see IASB's 'bottom-up approach' as a major concern because although this approach starts with the disclosure requirements in the IFRS for SMEs Standard, the IASB has tailored the disclosure requirements in the IFRS for SMEs Standard to align for terms and language with IFRS Standards. We therefore do not see major inconsistencies between the disclosure requirements in the ED and in IFRS Standards. In addition, we see benefits as the ED sometimes uses simpler language.
A11In addition, we also support the principles the IASB used to assess the needs of users of financial statements as we agree that these users are likely to be focussed on information about short-term cash flows, obligations, commitments or contingencies, liquidity, solvency, measurement uncertainties, accounting policy choices and disaggregations of amounts in the financial statements.
Exceptions to the approach
Question 4: Exceptions to the approach
Paragraphs BC40–BC52 of the Basis for Conclusions explain the Board's reasons for the exceptions to its approach to developing the proposed disclosure requirements. Exceptions (other than paragraph 130 of the draft Standard) relate to:
- disclosure objectives (paragraph BC41);
- investment entities (paragraphs BC42–BC45);
- changes in liabilities from financing activities (paragraph BC46);
- exploration for and evaluation of mineral resources (paragraphs BC47–BC49);
- defined benefit obligations (paragraph BC50);
- improvements to disclosure requirements in IFRS Standards (paragraph BC51); and
- additional disclosure requirements in the IFRS for SMEs Standard (paragraph BC52).
- Do you agree with the exceptions? Why or why not? If not, which exceptions do you disagree with and why? Do you have suggestions for any other exceptions? If so, what suggestions do you have and why should those exceptions be made?
- Paragraph 130 of the draft Standard proposes that entities disclose a reconciliation between the opening and closing balances in the statement of financial position for liabilities arising from financing activities. The proposed requirement is a simplified version of the requirements in paragraphs 44A–44E of IAS 7 Statement of Cash Flows.
- Would the information an eligible subsidiary reports in its financial statements applying paragraph 130 of the draft Standard differ from information it reports to its parent (as required by paragraphs 44A–44E of IAS 7) so that its parent can prepare consolidated financial statements? If so, in what respect?
- In your experience, to satisfy paragraphs 44A–44E of IAS 7, do consolidated financial statements regularly include a reconciliation between the opening and closing balances in the statement of financial position for liabilities arising from financing activities?
A12We broadly agree with the exceptions to the approach to developing the disclosure requirements. However, in some cases we recommend the rationale for making for exceptions be more clearly explained and justified. For instance, the rationale for the exception to the approach relating to improvements to disclosure requirements in IFRS Standards from IFRS 7 Financial Instruments: Disclosures and IFRS 13 Fair Value Measurement are not clear.
A13Our initial outreach with preparers suggests that the ED's requirement to include in a subsidiary's financial statements a reconciliation between the opening and closing balances in the statement of financial position for liabilities arising from financing activities would not differ from information it would report to its parent in order to comply with paragraphs 44A–44E of IAS 7 Statement of Cash Flows.
A14In addition, preparers indicated they would find this reconciliation easier to prepare compared to preparing a statement of cash flows for a subsidiary and wondered whether users would find this reconciliation more useful than the requirement to prepare a full statement of cash flows.
A15In addition, preparers also indicated that the information required by the reconciliation are collected from each subsidiary in the group for the purpose of disclosing the reconciliation in the consolidated financial statements.
The proposed reduced disclosure requirements
Question 5: Disclosure requirements about transition to other IFRS Standards
Any disclosure requirements specified in an IFRS Standard or an amendment to an IFRS Standard about the entity's transition to that Standard or amended Standard would remain applicable to an entity that applies the Standard.
Paragraphs BC57–BC59 of the Basis for Conclusions explain the Board's reasons for this proposal.
Do you agree with this proposal? Why or why not? If not, what approach would you suggest and why?
A16We support IASB's proposal that any disclosure requirements specified in an IFRS Standard about the entity's transition to that Standard would remain applicable to an entity that applies the reduced-disclosure IFRS Standard. We believe such transition disclosures would provide useful information to users of subsidiaries' financial statements. In addition, such disclosures requirements are not recurrent and therefore no significant ongoing cost would be incurred. On balance, we think the benefits of the information to users would outweigh the one-off cost of providing the transition disclosures.
Question 6: Disclosure requirements about insurance contracts
The draft Standard does not propose to reduce the disclosure requirements of IFRS 17 Insurance Contracts. Hence an entity that applies the Standard and applies IFRS 17 is required to apply the disclosure requirements in IFRS 17. Paragraphs BC61–BC64 of the Basis for Conclusions explain the Board's reasons for not proposing any reduction to the disclosure requirements in IFRS 17.
- Do you agree that the draft Standard should not include reduced disclosure requirements for insurance contracts within the scope of IFRS 17? Why or why not? If you disagree, from which of the disclosure requirements in IFRS 17 should an entity that applies the Standard be exempt? Please explain why an entity applying the Standard should be exempt from the suggested disclosure requirements.
- Are you aware of entities that issue insurance contracts within the scope of IFRS 17 and are eligible to apply the draft Standard? If so, please say whether such entities are common in your jurisdiction, and why they are not considered to be publicly accountable.
Disclosure requirements about insurance contracts
A17Whilst we are aware of entities in the UK that issue insurance contracts within the scope of IFRS 17 and could be eligible to apply the draft Standard, we do not think this is prevalent in the UK.
A18We have reservations about supporting full IFRS 17 disclosure requirements for subsidiaries eligible to use the draft Standard on the grounds of undue costs for preparers and users' information needs, which are entities that are not publicly accountable. We are also concerned that the reasons why the IASB decided not to propose reduced disclosure
requirements for IFRS 17 could create a precedent for any recently issued IFRS Standards which is not yet effective.
Question 7: Interaction with IFRS 1 First-time Adoption of International Financial Reporting Standards
Paragraphs 23–30 of the draft Standard propose reduced disclosure requirements that apply to an entity that is preparing its first IFRS financial statements and has elected to apply the Standard when preparing those financial statements.
If a first-time adopter of IFRS Standards elected to apply the draft Standard, the entity would:
- apply IFRS 1, except for the disclosure requirements in IFRS 1 listed in paragraph A1(a) of Appendix A of the draft Standard; and
- apply the disclosure requirements in paragraphs 23–30 of the draft Standard.
This approach is consistent with the Board's proposals on how the draft Standard would interact with other IFRS Standards.
However, IFRS 1 differs from other IFRS Standards—IFRS 1 applies only when an entity first adopts IFRS Standards and sets out how a first-time adopter of IFRS Standards should make that transition.
- Do you agree with including reduced disclosure requirements for IFRS 1 in the draft Standard rather than leaving the disclosure requirements in IFRS 1?
Paragraphs 12–14 of the draft Standard set out the relationship between the draft Standard and IFRS 1.
- Do you agree with the proposals in paragraphs 12–14 of the draft Standard? Why or why not? If not, what suggestions do you have and why?
Interaction with IFRS 1
A19We support IASB's proposal for reduced disclosure requirements for IFRS 1. We believe this approach is proportionate and practical and take into consideration user's information needs of eligible subsidiaries which are non-publicly accountable entities.
A20We also welcome IASB's clarification of the interaction of the draft Standard with IFRS 1. We find the guidance on electing or revoking an election to apply the draft Standard helpful and clear.
Question 8: The proposed disclosure requirements
Paragraphs 22–213 of the draft Standard set out proposed disclosure requirements for an entity that applies the Standard. In addition to your answers to Questions 4 to 7:
- Do you agree with those proposals? Why or why not? If not, which proposals do you disagree with and why?
- Do you recommend any further reduction in the disclosure requirements for an entity that applies the Standard? If so, which of the proposed disclosure requirements should be excluded from the Standard and why?
- Do you recommend any additional disclosure requirements for an entity that applies the Standard? If so, which disclosure requirements from other IFRS Standards should be included in the Standard and why?
The proposed reduced disclosure requirements
A21Our stakeholder outreach and research work clearly indicated that the proposed disclosure requirements set out in paragraph 22 to 213 of the ED are extensive. We include below disclosure requirements which we recommend to be removed and our rationale [This is an initial view—stakeholders please see Question 5 in the Invitation to Comment]:
| Disclosure requirements in the ED | IASB's rationale for adding the disclosures into the draft Standard | UKEB's rationale to remove the disclosure requirements in the draft Standard |
|---|---|---|
| IFRS 2 Share-based Payment | These disclosures are required by IFRS for SMEs Standard. | FRS 101 requires only a description of each type of share-based payment transaction. The other disclosures of IFRS 2 are exempted, provided that the entity is:
We believe the disclosure requirements in the draft Standard for share-based payment arrangements are disproportionate and burdensome. Stakeholders shared similar concerns. We recommend the draft Standard to follow the approach of FRS 101. |
| Disclosure requirements in the ED | IASB's rationale for adding the disclosures into the draft Standard | UKEB's rationale to remove the disclosure requirements in the draft Standard |
|---|---|---|
| IFRS 7 Financial Instruments: Disclosures FRS 13 Fair Value Measurement |
Users of subsidiaries' financial statements could benefit from these disclosure requirements and their inclusion in the draft Standard is supported by the principles used to develop the disclosure requirements in the IFRS for SMEs Standard. These disclosures are not required by IFRS for SMEs Standard. | FRS 101 provides disclosure exemption from IFRS 7 and 13, except financial institutions, provided that equivalent disclosures are included in the consolidated financial statements of the group in which the entity is consolidated. We note that the disclosure requirements for IFRS 7 and 13 in the draft Standard is more extensive than the IFRS for SMEs Standard which are disproportionately burdensome and add little value to users of subsidiaries' financial statements which often have few users that are external to the group. For example, a specific concern raised by stakeholders is that most groups would have a central treasury function which are dealt with by the parent and requiring subsidiaries to separately disclose its inter-group hedging would be onerous, costly to produce and unlikely to be useful to users of its financial statements. We recommend a similar approach to FRS 101. We consider that this approach is consistent with the scope of the draft Standard i.e. subsidiaries without public accountability. |
| IAS 24 Related Party Disclosures | These disclosures are required by IFRS for SMEs Standard. | FRS 101 exempts qualifying entities from the requirements in IAS 24 to disclose:
The exemptions from the requirements in IAS 24 in FRS 101 was well received and we recommend the draft Standard to follow the approach of FRS 101. |
Question 9: Structure of the draft Standard
Paragraphs 22–213 of the draft Standard set out proposed disclosure requirements for an entity that applies the Standard. These disclosure requirements are organised by IFRS Standard and would apply instead of the disclosure requirements in other IFRS Standards that are listed in Appendix A. Disclosure requirements that are not listed in Appendix A that remain applicable are generally indicated in the draft Standard by footnote to the relevant IFRS Standard heading. Paragraphs BC68–BC70 explain the structure of the draft Standard.
Do you agree with the structure of the draft Standard, including Appendix A which lists disclosure requirements in other IFRS Standards replaced by the disclosure requirements in the draft Standard? Why or why not? If not, what alternative would you suggest and why?
Structure of the draft Standard
A22We find the structure of the draft Standard, where the disclosure requirements are organised by IFRS Standard to be sufficiently clear. We also find Appendix A of the ED to be helpful which list down the disclosure requirements in full IFRS Standards that do not apply to entity that applies the draft Standard.
A23However, we find the presentation requirements of the draft Standard unhelpful. The ED includes those disclosure requirements that remain applicable by footnote to eight IFRS Standard headings. For instance, for IFRS 16 Leases, a footnote is appended to state that in addition to the disclosure required by the draft Standard, paragraph 47 of IFRS 16 which uses the word 'disclose' remains applicable. These footnotes can be confusing when determining the disclosure requirements of the draft Standard. To improve the accessibility of the draft Standard we recommend these footnotes are replaced with a comprehensive list of disclosure requirements. This approach would be more helpful and make the draft Standard a stand-alone document. This would make it easier to understand as it would avoid the need for users to refer back to other IFRS Standards.
Other comments
Question 10: Other comments
Do you have any other comments on the proposals in the draft Standard or other matters in the Exposure Draft, including the analysis of the effects (paragraphs BC92–BC101 of the Basis for Conclusions)?
A24IAS 1 Presentation of Financial Statements, paragraph 17(c) requires an entity to provide additional disclosures when compliance with the specific requirements in IFRS Standards is insufficient to enable users to understand the impact of particular transactions, other events and conditions on the entity's financial position and financial performance. The ED states in footnote 8 that the requirements of IAS 1 paragraph 17(c) remain applicable. Those requirements refer to the additional disclosures to be provided when compliance with the required disclosures does not lead to fair presentation of the underlying transactions. Stakeholders found it difficult to understand how they would apply those requirements in the context of a reduced disclosure regime. We recommend additional guidance on how to apply this requirement in the context of the ED, for example, in the light of the principles used to assess the needs of users of financial statements which are likely to be focussed on information about short-term cash flows, obligations, commitments or contingencies, liquidity, solvency, measurement uncertainties, accounting policy choices and disaggregations of amounts in the financial statements in order to achieve fair presentation as required by IAS 1 paragraph 15.
A25We strongly support identification of consequential amendments to the draft Standard when the IASB publishes an exposure draft of a new or amended IFRS Standard. We believe this is a more efficient approach that would ensure the reduced disclosure requirements for eligible subsidiaries keep pace with standard development for the parent entity's consolidated financial statements.
Appendix 2: Questions for the Invitation to Comment
1Do you agree with the proposed scope which is limited only to subsidiaries without public accountability? Do support extending the scope to individual financial statements of ultimate parent of a group? Please explain your rationale.
2Do you agree with the initial feedback at paragraph A17 that subsidiaries in the UK issuing insurance contracts within the scope of IFRS 17 Insurance Contracts, which could be eligible to apply the draft Standard, are mainly 'captive insurers' and unlikely to be prevalent? Can you provide other examples of entities that issue insurance contracts within the scope of IFRS 17 and that could be eligible to apply the draft Standard?
3If the reduced-disclosure IFRS Standard is adopted in the UK, would you consider changing from FRS 101 to the draft Standard? Please explain why.
4Do you agree that any disclosure requirements specified in an IFRS Standard about the entity's transition to that Standard should remain applicable to an entity that applies the reduced-disclosure IFRS Standard?
5Do you agree with UKEB's analysis at paragraph A21 regarding the disclosure requirements that should be excluded from the draft Standard? Do you think further reduction in the disclosure requirements in needed? Please explain your rationale and provide examples if relevant.
6In your opinion are the proposals likely to provide long terms benefits to financial reporting that exceed the costs? Can you provide any information on likely costs (qualitative or quantitative)?
7Do you have any other comments on the exposure draft?
A link to the ED can be found here.
Footnotes
-
The ED and Basis for Conclusions can be accessed here: https://www.ifrs.org/projects/work-plan/subsidiaries-smes/#published-documents ↩
-
UKEB calculations based on LSEG and Eikon data. ↩