6.0 Research on Subsequent Measurement of Goodwill - Project Implementation Plan
| Project Type | Research |
|---|---|
| Project Scope | Limited scope |
Executive Summary
Purpose of the paper
This paper provides the Board with a Project Initiation Plan (PIP) for a research project to analyse the potential impact of transitioning to an amortisation model for the subsequent measurement of goodwill.
Summary of the Issue
The IASB has begun redeliberating the preliminary views in its DP 2020/1 Business Combinations: Disclosures, Goodwill and Impairment (the Discussion Paper).
In the Discussion Paper, the IASB supported retaining the impairment-only model for the subsequent measurement of goodwill. Responses to this view in the DP were mixed. The UKEB Secretariat's response advocated a hybrid model for the subsequent measurement of goodwill. In the hybrid model, an annual amortisation charge would be supported by impairment testing.
As a result of an initial discussion of the responses received on its DP, the IASB directed staff to undertake further work on the implications of transitioning to a hybrid model for the subsequent measurement of goodwill. The IASB project team has reached out to national standard setters, including the UKEB, to help support this additional research.
The proposed UKEB goodwill measurement research project will address the following topics:
- Potential impact on financial position, debt covenants, tax, and ability to meet legal and regulatory requirements if historic goodwill balances were adjusted on transition.
- How the useful life of goodwill is determined for amortisation purposes under UK GAAP.
- How a hybrid model can provide information that is useful for users.
- The cost implications of a hybrid model.
Decisions for the Board
The Board is asked:
- Whether it is content with the work planned to respond to the research questions, and
- To approve the PIP for this project.
Recommendation
We recommend the Board approves planned work and the PIP.
Appendices
- Appendix 1 Project initiation plan: goodwill measurement
| Project Type | Research |
|---|---|
| Project Scope | Limited scope |
Overview
1The IASB has begun redeliberating the preliminary views in its DP 2020/1 Business Combinations: Disclosures, Goodwill and Impairment (the Discussion Paper). In the Discussion Paper, the IASB supported retaining the impairment-only model for the subsequent measurement of goodwill. Responses to this preliminary view were mixed: some respondents supported maintaining the impairment-only model whereas others recommended the reintroduction of amortisation.1 The UKEB secretariat's response advocated a hybrid model for the subsequent measurement of goodwill. In the hybrid model, an annual amortisation charge is supported by impairment testing.
2The proposed project responds to and expands on a request from IASB staff. The IASB discussed its plan for redeliberations on this project at its September 2021 meeting. It agreed that further work would be prioritised to support redeliberation on goodwill measurement. To inform the Board's redeliberation on this topic IASB staff identified two specific areas of analysis that they intended to carry out with support from national standard setters. These areas were:
- How the useful life of goodwill is determined for amortisation purposes under national GAAP; and
- The potential impacts of transitioning to an amortisation model.
3We have identified two further areas for analysis that we anticipate will be useful to the IASB in its ongoing redeliberation. These areas are:
- How a hybrid model can provide information that is useful for users.
- Cost implications of a hybrid model.
4The proposed project contributes to the influencing activities delegated to the UKEB in SI/2019/685(5)(b).2
5The IASB currently plans to vote on the Discussion Paper's proposals in Q1 2022.
6Undertaking the project is relevant for the UKEB and its stakeholders because:
- Goodwill represents approximately 18% of total assets for UK FTSE 350 entities; and,
- M&A activity by IFRS reporters in the UK is expected to increase in the immediate and medium term.3
7We anticipate that undertaking the project will deliver the following benefits for the UKEB:
- Timely engagement with the IASB: the project provides an opportunity to support the IASB in a timely manner.
- Profile building: the project provides an opportunity to contribute new, UK-specific evidence to the ongoing international debate on goodwill.
- Stakeholder engagement: the outreach on this project will contribute to building relationships with UK preparers, users, auditors, and regulators.
Project objectives, scope and output
8The IASB's objective in undertaking this project is to assemble relevant evidence to underpin their redeliberations on subsequent measurement of goodwill.
9The UKEB's objectives in undertaking this project are to:
- Build the UKEB's reputation as a significant and positive participant in the development of global accounting standards; and
- Demonstrate the UKEB guiding principle of thought-leadership by anticipating IASB's information needs and contributing UK-specific evidence to the international debate on goodwill; and
- Demonstrate the UKEB guiding principle of accountability through outreach to UK stakeholders.
10The intended outputs of the project are:
- A comprehensive analysis in response to the IASB's request and the further questions identified by UKEB staff; and
- A feedback statement summarising stakeholder views from outreach activities (as specified in the draft Due Process Handbook).
11Once the results of the analysis highlighted above are known, the UKEB may wish to consider expanding the research or developing an informal paper or report for
publication. We intend to consult with the Board on any additional research or development of an informal paper for publication before commencement of any work.
Approach
12The project approach will comprise desk-based research and stakeholder outreach.
13The table in appendix 1 outlines the proposed questions, initial findings and proposed further work. Secretariat will provide updates to the Board as necessary throughout the project.
Key milestones and proposed timeline
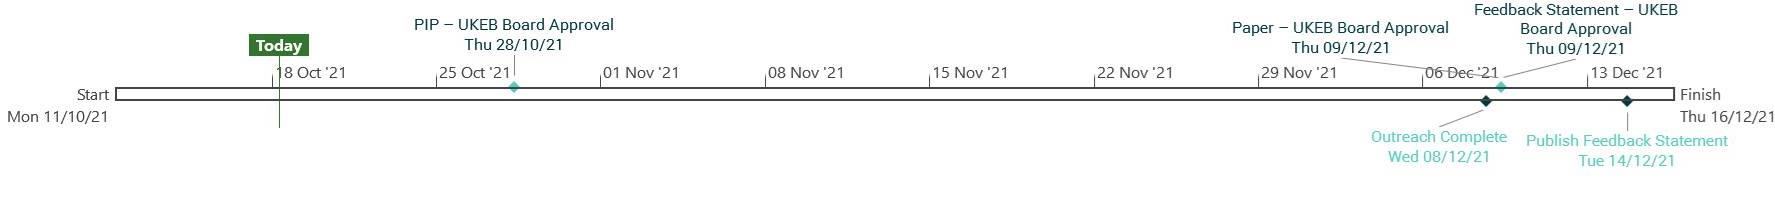
14The proposed high-level project timeline is as follows:
| Month | Activity / Milestone |
|---|---|
| October | Board meeting: approval of PIP |
| October - November | Desk-based research |
| November | Outreach activities |
| December | Board meeting: approve analysis for submission to IASB |
| Board meeting: approve feedback statement | |
| December | Share analysis with IASB |
The timeline is shown below:
Project closure
15At project close, a feedback statement and a statement of compliance with due process will be prepared. The feedback statement will summarise stakeholder views from outreach activities and will be submitted to the Board for approval for publication.
Assumptions
16We have made the following assumptions in developing this project initiation plan:
- Planned further research will result in sufficient depth and breadth of analysis (planned further research is shown in appendix 1).
- There are no significant changes to project scope.
- The resource allocated to the project does not change.
- IASB timelines do not change.
- Any emerging UKEB governance requirements will not impose significant additional steps or necessitate significant increase in the resource allocated to the project.
Next Steps
Subject to Board approval, we will commence the research and analysis activities outlined in Appendix 1.
Appendix 1: Summary of areas for analysis, initial findings and proposed further research
| Question | Initial Findings | Further Research Proposed |
|---|---|---|
| Section a: Analyses requested by IASB | ||
| 1 If IASB decides to reintroduce goodwill amortisation and the transition requires adjusting historical goodwill balances, what are the potential effects of writing-off significant amounts of historic goodwill on transition and amortising the remaining historic goodwill balances on: | ||
| a Financial position | Goodwill exceeded net assets for approximately 11% of FTSE 350 entities in 2019. The proportion of FTSE 350 entities whose goodwill exceeds net assets has remained broadly constant at approximately 11% between 2005 and 2019. | Update analysis for 2020 year-ends. Extend sample to other listed entities outside FTSE 350. Analyse trends by sector and size of entity. Numerical example illustrating potential impacts of transitioning to an amortisation model. Analyse age profile of goodwill for a sample of UK IFRS reporters to ascertain the value of goodwill that would need to be written off on transition. Research different possible treatments of goodwill on transition. |
| b Debt covenants | There is no standard approach to the treatment of goodwill in debt covenants. Some include goodwill as an asset when assessing credit and when setting covenant terms whilst others do not. | Survey to lenders and preparers to establish: - Whether covenant terms typically include or exclude goodwill. - How a change in subsequent measurement of goodwill could impact existing covenants. |
| c Distributable profits, dividend payments, and capital maintenance | Under the Companies Act 2006 and UK common law, distributions are made by individual companies and not by groups. The group accounts are therefore not relevant for the purpose of determining a company's profits available for distribution, dividend payments or capital maintenance. Amortisation or impairment of goodwill arising on consolidation has no direct impact on distributable profits, dividend payments or capital maintenance. | How a change in subsequent measurement of goodwill could impact existing covenants. |
| d Listing requirements | An initial review of the UK Listing Rules has not identified any specific requirements regarding financial position. | Further review of relevant sources to identify whether transitioning to an amortisation model would lead to breaches of listing rules and other related requirements. |
| e Tax | There is tax relief for some kinds of goodwill under current UK legislation. | Numerical example to illustrate any impact on current and deferred tax of transitioning to an amortisation model. |
| f Other legal and regulatory requirements | - | Further review of relevant sources to identify whether transitioning to an amortisation model would lead to breaches of other regulatory requirements. |
| 2 In national GAAP: | ||
| a Is a default period provided? What are the reasons for setting a default period and how was that default period determined? | UK GAAP requires amortisation of goodwill on a systematic basis over its useful life. Management should make a reliable estimate of the useful life of goodwill. If, in exceptional cases, an entity is unable to make a reliable assessment of the useful life of goodwill, the life shall not exceed 10 years. Earlier UK GAAP contained a rebuttable presumption that the maximum useful economic life of goodwill was 20 years. |
Explore why 10 years was set as the cap in current UK GAAP. Analyse arguments for and against a default period, including review of relevant FASB papers. |
| b Can entities deviate from a default period based on specific facts and circumstances (rebuttable presumption) and, if so, whether in practice entities tend to rebut that presumption and deviate from the default period, and what evidence is provided to support any deviation? | Our initial sample of large private UK companies has found entities which either: - Voluntarily report under IFRS Or - Do not have goodwill |
Extend sample of large private UK companies to identify UK GAAP reporters with goodwill. Outreach to UK GAAP preparers, auditors and regulator to analyse: - How a reliable estimate of the useful life of goodwill is made - Whether it is assessed separately for each acquisition - Cost and resource implications of the assessment - Frequency with which the default period is deviated from - Frequency with which the estimate of the useful life of goodwill is revised and reasons why |
| c Is useful life established on the basis of management's best estimate and, if so, whether a list of indicators/factors to be considered is provided (for example: cash flow streams, synergies, payback period), how entities are making these estimates and whether auditors and regulators can, and do, challenge these assumptions? | Experience of auditing estimates of useful life of goodwill | |
| Section B: UKEB staff proposed questions | ||
| 1 How can a hybrid model provide useful information for users? | Investor contributions to the international debate suggest that amortisation does not provide useful information, and in fact reduces the decision-usefulness of the financial statements. However, these views are often based on the assumptions that: 1. An amortisation-only model would be introduced. 2. The useful life of goodwill for amortisation purposes would be determined by reference to a default or cap. 3. Disclosures relating to the impairment test would be lost. |
Further analysis of user responses to IASB's DP and to FASB's goodwill measurement consultation. Survey to users in the UK to assess how: - A hybrid model could meet information needs - Allowing management to estimate the useful life of goodwill would provide relevant information The IASB DP's proposed disclosures on business combinations could provide relevant information |
| 2 Cost implications of a hybrid model. | International debate has identified concerns that introducing a hybrid model would create an additional cost burden for entities, given it would require amortisation in addition to impairment testing. | Outreach to preparers, auditors and users to assess cost implications of preparing and auditing amortisation supported by indicator-only impairment testing compared to costs of an impairment-only model. |
Footnotes
-
UK EB staff analysis estimates that a marginal majority of respondents advocated the reintroduction of amortisation. ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019: https://www.legislation.gov.uk/uksi/2019/685/made ↩
-
Source - Lexis Nexis market tracker trend report: Trends in UK Public M&A in 2020 ↩