12.0 Disclosure Requirements in IFRS Standards – A Pilot Approach. Updated Project Implementation Plan
Executive Summary
| Project Type | Influencing |
|---|---|
| Project Scope | Significant |
Purpose of the paper
This paper provides the Board with an updated Project Initiation Plan (PIP) for the IASB's ED/2021/3 Disclosure Requirements in IFRS Standards – A Pilot Approach 1 for approval. In response to stakeholder requests, IASB has now extended the deadline from 21 October 2021 to 12 January 2022.
The PIP was previously approved by the Board on 20 July 2021, and at that time it was noted that IASB would likely extend the timeline for this project. The updated PIP reflects the new IASB timeline and allows for additional time to complete project tasks previously identified in the PIP. In particular, we intend to use the additional time to offer a wider range of field-testing dates to potential volunteer companies in the UK, and to extend the stakeholder comment period on the UKEB's draft comment letter.
Summary of the Issue
This IASB ED seeks to address the “disclosure problem” and proposes four actions:
- Creates Guidance for IASB's use when developing and drafting disclosure requirements. This proposes to largely replace mandatory disclosure items with an objectives-based regime.
- Applies this Guidance to IFRS 13 Fair Value Measurement and proposes amendments to this standard developed by using the new Guidance.
- Applies this Guidance to IAS 19 Employee Benefits and proposes amendments to this standard developed by using the new Guidance.
- Proposes consequential amendments to IAS 34 Interim Financial Reporting and IFRIC 17 Distribution of Non-cash Assets to Owners.
Decisions for the Board
The Board is asked to approve the updated PIP.
Recommendation
We recommend the Board approves the updated PIP.
Appendices
Appendix 1 PIP: Disclosure Requirements in IFRS Standards – A Pilot Approach
Draft Project initiation plan: Disclosure Requirements in IFRS Standards – A Pilot Approach.
Project Implementation Plan
| Project Type | Influencing |
|---|---|
| Project Scope | Significant |
Overview
1SI/2019/685(5)(b) 2 requires the UKEB to be responsible for “participating in and contributing to the development of a single set of international accounting standards.” The proposed project contributes to this work.
2The IASB's Exposure Draft ED Disclosure Requirements in IFRS Standards – A Pilot Approach 3 ("the Disclosure Pilot”) seeks to address the “the disclosure problem" of financial statements containing irrelevant information, insufficient relevant information, ineffective communication of the information provided and a checklist approach to disclosure used by some entities.
3This project forms part of IASB's Disclosure Initiative, a portfolio of projects exploring how to improve the effectiveness of disclosures in financial reporting. The IASB's ED was published on 25 March 2021 and, following an extension, the comment deadline is now 12 January 2022.
4The ED proposes four actions.
- Creates Guidance for IASB to use when developing and drafting disclosure requirements. This proposes to largely replace mandatory disclosure items with an objectives-based regime where entities can provide disclosure that satisfies the disclosure objectives.
- Applies this Guidance to IFRS 13 Fair Value Measurement and proposes amendments to this standard developed using the new Guidance.
- Applies this Guidance to IAS 19 Employee Benefits and proposes amendments to this standard created using the new Guidance
- Proposes consequential amendments to IAS 34 Interim Financial Reporting and IFRIC 17 Distribution of Non-cash Assets to Owners.
5The ED notes that in addition to the proposed amendments to IFRS 13 and IAS 19, the guidance may potentially be used in the future development of new standards and changes to existing IFRS standards.
6Given the importance placed on disclosure by users of financial statements, the ED's proposals are expected to affect a large number of UK stakeholders, including IFRS preparers, users, auditors and relevant regulators. Ensuring the IASB has the opportunity to consider views of UK stakeholders during the standard's development is key to minimising new concerns being identified during the endorsement and adoption assessment process
Objective of the project
7As noted above this project forms part of IASB's Disclosure Initiative, a portfolio of projects exploring how to improve the effectiveness of disclosures in financial reporting. It seeks to address the “the disclosure problem” of financial statements containing too much irrelevant information, not enough relevant information, ineffective communication of the information provided and some entities taking a checklist approach to disclosure.
8The ED aims to improve the IASB's approach to developing and drafting disclosure requirements in IFRS standards and to help stakeholders improve the usefulness of disclosures for the primary users of financial statements.
The Guidance for IASB
9To achieve the above the ED creates Guidance for IASB to use when developing and drafting disclosure requirements.
10IASB identified a number of barriers to better disclosure based on stakeholder feedback and considered ways to addressing these which would also potentially help improve the disclosure problem. Those barriers and IASB's proposed remedies are as follows:
- Stakeholders have said to IASB that the easiest way to achieve compliance can be to apply disclosure requirements like a checklist. To remedy this IASB propose that companies to comply with disclosure objectives that can only be met by applying judgement.
- Stakeholders have said to IASB that complying with high volumes of prescriptive requirements does not leave time to apply materiality judgements. To remedy this IASB proposes minimising the requirements to disclose particular items of information, thus removing a perceived compliance burden.
- Preparers may not always understand why information is useful, and therefore find it difficult to make effective judgements regarding its disclosure. To remedy this IASB proposes to engage users earlier in the standard setting process, set objectives based on user needs, and explain to preparers how the users are likely to use the information provided.
11The proposed Guidance would lead to mandatory lists of disclosure items in accounting standards being replaced with:
- Overall disclosure objectives – these describe the overall information needs of investors for a particular IFRS Standard and require companies to provide information in the Notes sufficient to meet these needs.
- Specific disclosure objectives – these describe the detailed information needs of investors within an IFRS Standard. These include an explanation of what investors may do with the information. Companies are required to provide information in the Notes sufficient to ensure these needs are met.
- Items of information – provide examples of items of information a company may disclose to satisfy each disclosure objective. In some cases providing this information will be mandatory. These are intended to help companies apply judgement and determine how to satisfy particular disclosure objectives.
12IASB then proceeded to applying the disclosure Guidance to IFRS 13 and IAS 19 with the twin aims of: improving the usefulness of disclosures of financial statements prepared applying those standards; and testing and improving the proposed Guidance itself.
Amendments to IFRS 13 and IAS 19
13The IASB's application of the proposed Guidance to IFRS 13 and IAS 19 results in the lists of mandatory disclosure items in these Standards being replaced with a General Objective, a number of Specific Objectives, descriptions of how users are likely to use the information, and multiple lists of Items of Information.
14The amendments to IFRS 13 and IAS 19 (and consequential changes to IAS 34 and IFRIC 17) arising from this exercise form part of the exposure draft and may be finalised as amendments to these standards when this consultation is finalised.
Consequences of finalising the ED
15If the proposals in the ED are finalised in full then:
- The proposed amendments to IFRS 13 and IAS 19 (and consequential changes to IAS 34 and IFRIC 17) would be enacted with immediate effect;
- The proposed Guidance will be used in standard setting activities in future; and
- The proposed Guidance may be applied to amend other existing IFRS Standards, subject to the normal due process for amendment to a Standard.
Initial identification of issues
16Our initial desk-based review of the standard and feedback from user, preparer, auditor and regulator roundtables has identified the following initial issues with the proposals.
Comparability
17A tension between relevance and comparability arises under these proposals. Companies may disclose different information to meet the same disclosure objective depending on their circumstances. This may result in relevant disclosure but may make comparability between companies more challenging.
Digital reporting
18Reduced consistency in disclosure may make it more difficult for users of digital reporting (or their models which consume financial data) to draw meaningful comparisons between companies and ensure that complete data sets have been received due to the lack of uniformity in reporting.
Application of judgement
19IASB identified that some companies currently struggle to make good judgements and apply materiality correctly when considering disclosure. The proposals increase reliance on judgement, which may exacerbate this problem.
20The Items of Information (some of which are mandatory) continue to be visually presented in a checklist style in the test standards. Behavioural change is complex and it is possible this this may encourage companies who prefer to use a “safe” checklist approach to use the Items of Information in this manner, which would not achieve the desired change.
Audit & enforceability
21The auditability of the proposals needs to be considered. In addition, companies will need to consider their processes to make Boards and Audit Committees comfortable with judgement-based disclosures compared to the previous perceived “safe” lists of mandatory disclosure.
22Regulators will need to ensure the proposals are satisfactory for their needs, and adapt their processes not to query disclosure only because it is different to that of similar companies, if the overall disclosure objectives are met. Regulators have told us working with an objectives based regime can be successful, but is resource intensive. Scaling this approach across more standards has resourcing implications for both regulators and companies. Some stakeholders have suggested that a company's assessment of materiality may need to be disclosed to allow regulators to adequately assess the completeness and effectiveness of reporting.
IFRS 13 amendments
23Based on our initial analysis we do not support the proposed amendments to IFRS 13. We understand that IFRS 13 was chosen for the disclosure pilot as it provided a good example of a standard requiring a high level of materiality judgement. However, we note that the PIR of IFRS 13 concluded that the information required by IFRS 13 is useful to users of financial statements. Further, stakeholders consulted by IASB during this project confirmed that “fair value measurement disclosures applying IFRS 13 generally contain information that meets the needs of users of financial statements”. (BC 59). Given the significant amount of change and consultation in recent months we cannot support significant amendments to a disclosure regime that stakeholders say is working adequately.
Context of amendments
24Based on our initial analysis we have reservations about supporting amendments to either IFRS 13 or IAS 19 without first understanding whether the Guidance described in the ED will be adopted and applied to other IASB projects. If the methodology is not used elsewhere, it will lead to inconsistent principles for disclosures being applied within IFRS.
Key planning assumptions, constraints and timeline
25We have commenced activities related to this project and will provide stakeholders a longer than usual comment period to maximise responses in what is a very busy consultation period for both UKEB and our stakeholders.
Assumptions
26We have made the following assumptions in developing this project plan:
- The work will be combination of desk based analysis and outreach with stakeholders.
- That a draft comment letter will be presented for Board approval at the 20 July meeting. The IASB extension to the project timeline has allowed us to extend our comment deadline from the originally planned 1 October 2021 to 1 November 2021. This extended consultation period should allow stakeholders the maximum time to engage. A final comment letter will be presented to the Board at the December 2021 meeting.
Outreach
UK stakeholders
27The ED approach to disclosure is likely to impact a wide range of stakeholders including users and preparers of financial statements, auditors and relevant regulators. To ensure feedback is received from each these communities we have leveraged the recent Agenda Consultation roundtables to also obtain feedback on the ED. These views will be used to inform our draft comment letter, which provides stakeholders a further opportunity for feedback. During the period that the draft comment letter is open to consultation, we plan further interviews with UK regulators and will conduct further individual stakeholder interviews as opportunities arise.
28In addition to the roundtables and draft comment letter, we propose to create a series of educational videos produced jointly with IASB exploring key elements of the proposals. The purpose of these is to educate UK stakeholders and to raise awareness of the proposals and the opportunity to comment.
29We will advertise for volunteers to participate in IASB's field test exercise, and to the extent UK volunteers participate, will conduct this as a joint exercise with IASB. The extension of the deadline for this project to 12 January 2022 should allow for greater flexibility in dates for companies interested in volunteering for field testing, though we recognise that half year and quarterly reporting commitments will still need to be worked around.
International stakeholders
30We are already in touch with the IASB's project team and have plans in place to record a joint series of educational videos on the ED, which will be hosted on the UKEB website.
31EFRAG issued its draft comment letter on the IASB's ED on 11 May 2021 and has a comment deadline of 15 October 2021 (subsequently extended to 4 January 2022). The Australian Accounting Standards Board (AASB) issued its draft comment letter in April 2021 with a comment deadline of 16 August 2021 (subsequently extended to 15 October 2021). We plan to reach out to both project teams to understand their key areas of concern. We also aim to reach out to the staff of the Accounting Standards Board of Canada (AcSB) and as we understand from previous conversations that the proposals in the ED are of particular interest to them. This outreach should help us obtain further insight into those jurisdictions' views of the requirements proposed in the ED and whether there are overlaps with UK views.
32UKEB outreach work is planned to occur between June and October.
Project closure
33Consistent with the proposals in the draft Due Process Handbook, the Feedback statement should be approved by the board at the same time as the comment letter.
Project timeline
34The proposed high-level project timeline is as follows:
| Date (2021) | Board meeting | Milestones |
|---|---|---|
| 20 July | Board meeting | Approve PIP |
| 20 July | Board meeting | Approve draft comment letter |
| As soon as possible thereafter | Publish draft comment letter | |
| August - October | Field testing takes place. | |
| 17 September | Board meeting | Approve updated PIP |
| 1 November | Deadline for draft comment letter responses | |
| 9 December | Board meeting | Approve final comment letter & feedback statement |
| As soon as possible thereafter | Submit final comment letter to IASB (IASB deadline 12 January 2022) |
Project timeline
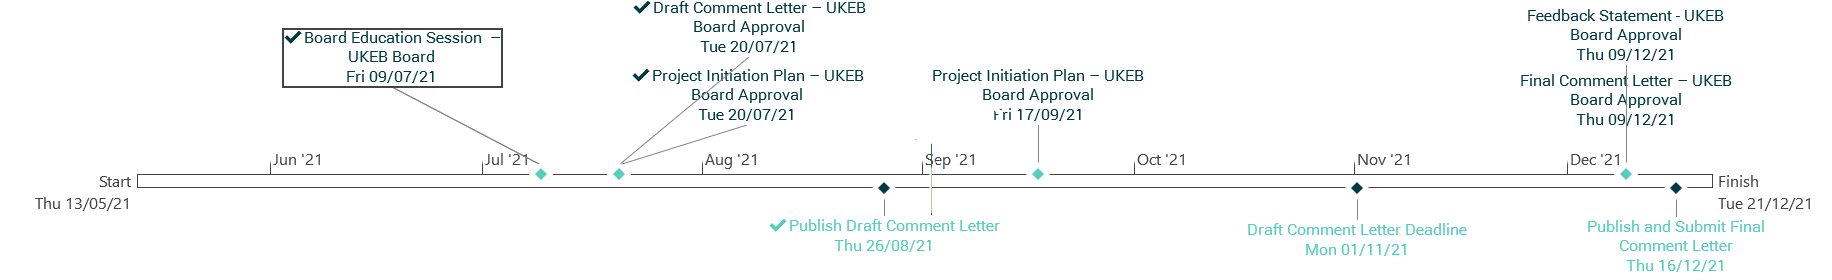
The timeline illustrates the following key milestones and dates:
- Start: Thu 13/05/21
- Board Education Session - UKEB Board: Fri 09/07/21
- Draft Comment Letter - UKEB Board Approval: Tue 20/07/21
- Project Initiation Plan - UKEB Board Approval: Tue 20/07/21
- Publish Draft Comment Letter: Thu 26/08/21
- Draft Comment Letter Deadline: Mon 01/11/21
- Feedback Statement - UKEB Board Approval: Thu 09/12/21
- Final Comment Letter - UKEB Board Approval: Thu 09/12/21
- Publish and Submit Final Comment Letter: Thu 16/12/21
- Finish: Tue 21/12/21
Footnotes
-
Exposure Draft ED/2021/3 Disclosure Requirements in IFRS Standards – A Pilot Approach The ED, Basis for Conclusions and Illustrative Examples can be accessed here. ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019: https://www.legislation.gov.uk/uksi/2019/685/made ↩
-
The ED, Basis for Conclusions and Illustrative Examples can be accessed here: https://www.ifrs.org/projects/work-plan/standards-level-review-of-disclosures/exposure-draft-and-comment-letters/ ↩