Project Initiation Plan - Climate-related Matters
| Project Type | Thought Leadership |
|---|---|
| Project Scope | Limited scope |
Overview
1The UKEB Regulatory Strategy 2023/24 (draft) includes a research project entitled 'Reporting climate-related matters in financial statements' in the workplan. This paper provides the Board with a draft PIP for a project to consider the reporting of climate-related matters in the financial statements.
2The UKEB delegated functions include responsibility for “participating in and contributing to the development of a single set of international accounting standards." Undertaking pro-active thought leadership activities is key to the UKEB's ability to effectively deliver this statutory function. The UKEB's Terms of Reference (ToR) further explain that regarding thought leadership, it shall proactively participate in the development of new global accounting standards, for example by undertaking research.
3In August 2022, the Department for Business, Energy, and Industrial Strategy (BEIS) requested1 the UKEB carry out work to consider the overlap or impact of the proposed International Sustainability Standards Board (ISSB) Sustainability Disclosure Standards with those issued by the International Accounting Standards Board (IASB).
4The IASB has added a pipeline project 'Climate-related Risks in the Financial Statements', after noting in its Feedback Statement on the Third Agenda Consultation that stakeholders had commented on inconsistent application of IFRS Accounting Standards to climate-related risks; and that there was insufficient information disclosed about climate-related risks in the financial statements2.
5While IASB staff noted, at the time, that underlying causes of any deficiencies in reporting were unclear, they also observed that, “...the ISSB's work on climate-related disclosures (and sustainability-related financial information more broadly) could provide the IASB with helpful insights about potential improvements to the information provided in the financial statements about climate-related risks3”.
6In response, to the feedback the IASB added a pipeline project ‘Climate-related Risks in the Financial Statements’4 and noted three objectives:
- research the causes of stakeholders' concerns about inconsistent application and insufficient information.
- research whether the IFRS Foundation's educational material on the Effects of climate-related matters on financial statements and the application of the ISSB's future standard on climate-related disclosures help to address these concerns; and
- consider whether and, if so, what narrow-scope actions might be needed.
7In March 2023, the IASB moved the project from the maintenance project pipeline to the maintenance project workplan.
8The ISSB is currently developing a Request for Information (RFI) to inform its initial two-year work plan. As at March 2023 the IFRS Foundation website indicated that the ISSB RFI will be issued in May 2023. The approach will include both foundational work, which will build on draft IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information (S1) and draft IFRS S2 Climate-related Disclosures (S2), and potential research and standard setting projects.
9The ISSB has tentatively agreed that one of the projects in the RFI will be on integration in reporting. This will include a discussion of the requirements in IFRS S1 and S2 in relation to connected information which is intended to provide context for the potential project. This project is intended to be an ISSB project that could be pursued jointly with the IASB, rather than as a formal joint project with the IASB.
10Stakeholders appear to be giving increasing importance to connectivity, as demonstrated by several recent studies and reports in the UK highlighting the disconnect between Task Force on Climate-related Financial Disclosures5 (TCFD) disclosures on climate-related risks to companies' business models in the front half of companies' Annual Reports and information disclosed in their financial statements6. As both S1 and S2 use TCFD as its basis, the TCFD-based research is an appropriate proxy for the proposed ISSB Standards and their expected connectivity with IASB standards. For example:
- Carbon Trackers October 2022 report ‘Still Flying Blind: The Absence of Climate Risk in Financial Reporting' noted,” Most of the companies reviewed7 did not provide sufficient evidence that their financial statements included the impacts of material climate-related matters. The failure to provide this information raises questions about whether companies are reflecting the financial consequences of climate risk and the energy transition within their financial statements”.
- The FRC Corporate Reporting Review (CRR)'s July 2022 thematic8 review assessed both TCFD disclosures and climate-related reporting in the financial statements of 25 carbon intensive, large premium listed companies in the UK. The FRC noted,” Some companies did not provide sufficient detail in their financial statement disclosures to provide meaningful information to users, especially when compared to extensive disclosures about climate-related risks and opportunities in the strategic report." In addition, that,” Only a small portion of companies disclosed the impact of climate change on amount recognised in the financial statements".
- PWC's April 2022 report ‘The green shoots of TCFD reporting'9 found that only 8% of the first 50 published annual reports by FSTE 350 companies in 2021 quantified the estimated financial impact of climate risks in their strategic report. They noted that when financial information was disclosed in the financial statements it was often a brief statement that climate change was not material.
- ACCA and the Adam Smith Business School Research Report 'Companies' readiness to adopt IFRS S2 climate-related disclosures'10 focussed on the
100 companies with the highest average GHG emissions over the three-year period 2018-2020 in the construction materials and chemicals industries (50 from each industry) worldwide, which provided annual reports in English. The report noted that, “there is a low level of climate-related disclosure pertinent to an entity's financial position, performance, and cash flows” and that “this finding is of particular interest as these disclosures refer to the integration of the 'front-end' of companies' annual reports with the 'back-end' (i.e., financial statements)".
Objective of the project
11A research project on reporting climate-related matters in financial statements is consistent with the UKEB's statutory functions as well as the request for additional work on connectivity by the Government. In addition, the evidence gathered will help the UKEB to obtain insight on the UK companies' existing experience of reporting on climate-related matters. This will help the UKEB provide evidence-based responses to both the IASB, on its project on climate-related risks in financial statements, and to the ISSB, on its RFI on its future agenda setting.
12The objective of the research is to develop a body of evidence, using FTSE 350 annual reports to identify disconnects between TCFD and SECR narrative disclosures in the front half of the annual report and the disclosure of the associated financial effects in the financial statements.
13The project will also document the process, to ensure the research could be repeated to gauge the level of improvements in connectivity over time. To avoid duplication and repetition, the research approach will seek to build upon existing TCFD-based research. In particular, the approach will seek to reference previous work in the UK by other organisations.
14When the ISSB issue the RFI a separate PIP will be prepared which would include formal stakeholder outreach however, as this is preparatory research, outreach will be limited to the UKEB working and advisory groups.
15The deliverables of the research project are to:
- Understand the current issues already identified regarding the reporting of climate-related matters in financial statements.
- Assess the areas of disconnect between the TCFD and SECR disclosures and the financial statements, seek initial stakeholder perspectives and to consider the potential impact of draft ISSB disclosure requirements.
16For each deliverable a description of the objectives, proposed methodology for gathering of evidence, the expected outcomes, timing, and resources required are set out below.
Deliverable One: Assessment of current research
Objective
17To understand the current issues already identified regarding the reporting of climate-related matters in financial statements. This will enable the UKEB to be aware of research already completed and to identify areas of further investigation.
Methodology
18Identify and assess current UK focussed and global TCFD based research, identify key themes and potential causes.
Outcome
19A reference document containing a high-level summary of the key findings from recent research regarding issues identified in the reporting of climate-related risks in financial statements. The document will also identify potential further areas for focussed UKEB research.
Timing and resources
20This activity could be started immediately by a Project Manager and is likely to require between one to two months to complete.
Deliverable Two: Analysis of 2022 FTSE annual reports
Objective
21To determine the nature of connectivity gaps, to assess the extent to which the cause may be incongruence between accounting standards and the requirements of TCFD and to assess the potential impact of ISSB standards on those gaps.
Methodology
22The assessment will initially focus on a sample of nine annual reports from the FTSE 350 and focus on entities from a range of industries. The sample will be weighted towards industries considered to be heavier carbon emitters but also seek to include companies from a range of industries.
23The assessment will help inform the amount of time taken and provide an indication as to whether a review of a larger sample may be feasible within the timeframe and resource constraints. The Board will be updated on progress, the available options and recommended next steps on a regular basis.
24The deep dives will be desktop-based and will compare TCFD and SECR narrative disclosures in the front half of annual reports to the financial effects reported in the financial statements based on IFRS Accounting Standards and consider whether any disconnects identified would be addressed by the adoption of S1 and S2.
25The analysis will consider the following areas for climate-related risk and opportunity disclosures in the Strategic Report:
- Materiality for the company based on externally accessible factors such as industry, entity's business model, etc.
- A principle or embedded risk
- Specific metrics and targets
- Quantification
26The analysis will compare across the following areas for climate-related risk disclosures in the financial statements:
- Were climate-related matters mentioned
- What disclosures were provided and how they were linked with the disclosures in the Strategic Report
- Were any financial effects quantified
27We will seek to consider other organisations research as it is published in this area where relevant.
Outcome
28A report including the following:
- an analysis of the connectivity gaps identified and the extent to which the cause may be due to incongruence between accounting standards and the requirements of TCFD.
- the potential impact of the adoption of draft S1 and S2 on those gaps.
- a summary of stakeholder views obtained from UKEB working and advisory groups.
Timing and resources
29The financial reporting analysis will be conducted primarily by the external researcher13 with part time support of a UKEB Project Manager and Director.
30A majority of UK listed companies have December year-ends and tend to start publishing their annual reports from end of February onwards. As a result, the work is expected to commence fully from mid-March 2023. Once commenced the work is estimated to take between three to four months to complete.
Key planning assumptions, constraints, and timeline
Key planning assumptions and constraints
31Given the limited resource available within the UKEB Secretariat, the immediate focus will be on-boarding an external researcher, with an investment background, to work alongside UKEB staff to review the approach and design of the desktop research. The initial activity will consist of an assessment of the existing TCFD based research.
32It is expected that several of the activities to be undertaken as part of this project will result in opportunities to collaborate with, and contribute to, other UKEB projects. For example, there is a potential overlap with the Intangibles research project. We will actively look for ways to incorporate cross-sectional thinking and help ensure maximum impact for this thought leadership project.
33Once the project has concluded, there may be an opportunity to work with academics and academic journals using the final report to support further research. The UKEB Academic Advisory Group would play a key role in considering whether to recommend any further research in this area to the UKEB.
Stakeholder outreach
34Investor focus: The Conceptual Framework for Financial Reporting14 identifies the primary users of financial reports as existing and potential investors, lenders and other creditors that cannot require entities to provide information directly to them. The project will, therefore, focus primarily on investors' requirements, as they rely on General Purpose Financial Statements (GPFS) to provide useful information.
35Stakeholder outreach: Formal stakeholder outreach will not be conducted as part of this research project. The UKEB is in the process of establishing both a Sustainability Working Group (SWG) and, at the Secretariat level, a National Standard Setters (NSS) Sustainability Forum. These groups will be the main form of outreach on draft project deliverables. The UKEB will also seek to engage UKEB Advisory Groups, as appropriate, but this is expected to be less frequent as the members of the SWG will be drawn from existing UKEB Advisory Groups.
Resource
36In addition to outreach and technical support from the UKEB SWG and Advisory Groups, the project currently expects the following level of input from the technical staff:
- 0.75 FTE project director [0.5 FTE of a project director on a consistent basis and 0.25 of a project director to support key deliverables];
- 0.25 FTE project manager to support research and contribute to specific deliverables on a consistent basis; and
- External researcher: two days a week, initially for three months
37It is also important to acknowledge that additional research opportunities and outputs could emerge, or be identified, while the project is underway. Any significant changes to the research approach, outputs, timetable, or costs will be presented to the Board.
Risks
38While the ISSB has taken tentative decisions regarding issuing the RFI in May and the number and scope of the four proposed projects they remain subject to change until the ISSB make a formal decision.
39The ISSB Staff were granted the option from the Due Process Oversight Committee (DPOC) for the ISSB to use an exception to reduce the minimum consultation period from 120 days to 90 days. The ISSB will consider this option at the April 2023 board meeting. If the consultation period was reduced to 90 days this would present a due process challenge in terms of ensuring UK stakeholders had 30 days to consider a UKEB Draft Comment Letter to provide their feedback and space on the UKEB Board agenda to agree the Final Comment Letter during the August holiday period.
40While we are aware that the IASB's ‘Climate risk reporting in financial statements' project will be started in 2023 the detailed timing has not yet to be confirmed.
41The method and approach to the initial deep dives will be discussed with the researcher once onboard. The scope or approach to the deep dive may be subject to change based on their assessment of effort and recommendations on approach.
42The UKEB project timelines and milestones will need to remain flexible to respond to developments at the ISSB and IASB to ensure the UKEB outputs are timely and have maximum impact on the activities of both boards.
Project closure
43Each output will comply with the expected due process requirements appropriate to the nature of the output.
Project timeline
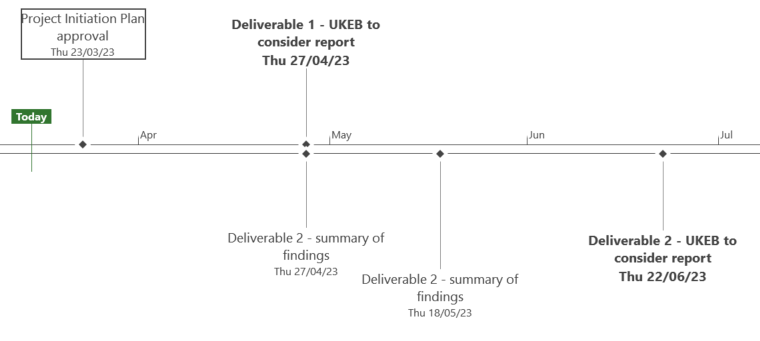
44The proposed high-level project timeline is as follows (a graphical representation is included on the next page). Note that dates are indicative only, and subject to revision by the Board as the project develops:
| Expected Date | Summary of current connectivity research | Analysis of 2022 annual reports |
|---|---|---|
| March 2023 | Project Initiation Plan approval | |
| March 2023 | Commencement of work | |
| April 2023 | UKEB to consider report | Update for the Board |
| May 2023 | n/a | Update for the Board |
| June 2023 | n/a | UKEB to consider report |
High-level timeline
Footnotes
-
Letter from Lord Callanan to the International Sustainability Standards Board (1 August 2022). On 7 February 2023, the Government announced a machinery of government update creating a new Department for Business and Trade (DBT). The UKEB is now a partner body to DBT. ↩
-
Third Agenda Consultation - Projects to add to the work plan ↩
-
IASB Agenda paper Ref 24A, April 2022 para 24 (c) ↩
-
IASB Maintenance project pipeline ↩
-
TCFD requires all large listed, unlisted and LLPs to report on a mandatory basis, within the Strategic Report Financial for years beginning on or after 6 April 2022. Metrics and target require the disclose of Scope 1, Scope 2 and, if appropriate, Scope 3 greenhouse gas (GHG) emissions, and the related risks. ↩
-
SECR is the principal regulatory regime for reporting emissions and associated information and is intended to complement the TCFD disclosures. SECR requires businesses to include their greenhouse gas emissions, energy consumption and energy efficiency action by quoted and large unquoted companies in their annual Directors' report (for companies) or the Energy and Carbon Report (for large LLPs) for financial years beginning on or after 1 April 2019. ↩
-
Financial Conduct Authority (FCA), via its listing rules, requires that certain UK premium listed companies and standard listed companies include a statement in their annual financial report which sets out whether they have made disclosures consistent with the TCFD's framework. These rules came into force for accounting periods beginning on or after 1st January 2022. ↩
-
Still Flying Blind: The Absence of Climate Risk in Financial Reporting (October 2022) ↩
-
134 carbon-exposed companies that are key to "driving the global net zero emissions transition" and include those companies that contribute to up to 80% of global industrial greenhouse gas emissions. ↩
-
CRR Thematic review of TCFD disclosures and climate in the financial statements (July 2022) ↩
-
The green shoots of TCFD reporting: An analysis of the first 50 companies to report under the Listing Rules (April 2022) ↩
-
Companies' readiness to adopt IFRS S2 climate-related disclosures (August 2022) ↩
-
Note - this and all other assumptions regarding estimated researcher effort are subject to change as the researcher will need to validate once on boarded to the project team. ↩
-
See Chapter 2: Objective, usefulness and limitations of general purpose financial reporting ↩