Project Initiation Plan - ISSB Exposure Drafts IFRS S1 and IFRS S2
| Project Type | Project Scope |
|---|---|
| Influencing | Significant |
Background
1In November 2021, the IFRS Foundation announced the formation of a new International Sustainability Standards Board (ISSB)1 to develop a comprehensive global baseline of high-quality sustainability disclosure standards to meet investors' information needs.
Current ESG Reporting Landscape
2There is currently a proliferation of voluntary framework for companies to use when reporting their Environmental, Social and Governance (“ESG”) information but there is no single framework covering the full range of issues which fall under the heading of Sustainability.
3The Companies Act 2006 requires UK registered entities to report on ESG matters within their annual reports. Most other jurisdictions do not require such disclosures, although companies operating globally may choose to report this information on a voluntary basis.
4Local jurisdictions across the globe are all in the early stages of considering the implications of the standards and grappling with the same difficulties and questions: What legislative mechanisms are necessary to allow/require companies to use the standards? Who should have responsibility for assessing these standards for adoption within those jurisdictions? Which stakeholders are impacted and have an interest in this area as well as how can they be identified? Who should be carrying out the assessment of the Exposure Drafts (“EDs”) before any decisions regarding remit are made?
5As a result, this is a time of major regulatory and policy change across jurisdictions. In the EU, EFRAG's Project Task Force for Environmental Sustainability Reporting Standards2 (ESRS) has published several sustainability working papers across multiple topics. The EFRAG Sustainability Reporting Board is expected to publish these as EDs in April 2022. In March 2022, the US Securities Exchange Commission (SEC)3 opened a public consultation on its proposed rule for the enhancement and standardisation of climate-related disclosures.
6The UK is several reporting cycles ahead of most other jurisdictions in this space as UK Companies Act 2006 already requires reporting on ESG matters. However, even here the introduction of mandatory reporting under ISSB issued standards will require a significant step change. The UK legislative landscape and corporate reporting framework is likely to change to enable UK companies to use these standards in a consistent and comparable way. We expect these changes to the landscape to continue during the course of our work on this project, and we will be monitoring to ensure that they reflect the needs of our stakeholders.
7The Department for Business, Energy and Industrial Strategy (BEIS) sets the reporting requirements, both financial and non-financial (ESG matters) for UK registered entities under Company Law. For the UK to adopt under ISSB issued standards and for UK registered entities to be required to report under them, changes to both the primary and secondary legislation may be required. BEIS has committed to carrying out the associated public consultation on any proposals. Consultations are expected in relation to the adoption mechanism for ISSB issued standards, as well as the scope and location of disclosures.
8However, currently no single UK organisation has been delegated a statutory function to consider and adopt these standards for use in the UK. As a result, UK market regulators will be considering their strategies and systems to take account of reporting under the new standards and that the standards appropriate for the entities they regulate. This will require consultation with their respective stakeholders.
9The UKEB is the UK's standard setter for international accounting standards. The functions of the Secretary of State, under Chapter 3 of Part 2 of the principal Regulations4. Section 5(b) of the principal Regulations include the responsibility for “participating in and contributing to the development of a single set of international accounting standards” have been delegated to the UKEB. The UKEB's mission, set out in the UKEB Regulatory Strategy5, is to serve the UK public good by leading in the development and synthesis of UK views on financial reporting and representing them in the international arena. The UKEB is also required, by its Terms of Reference6, to influence the development of IFRS, consult with stakeholders to obtain their views, and highlight concerns to the IASB.
10Following guidance from BEIS, the Board agreed to assist the Government by carrying out work in this area to consider the suitability of these standards for use in the UK. The Board agreed to commence a project looking at the overlap between IASB and ISSB issued standards, develop a communications strategy, and actively engage with UK stakeholders (including government departments and regulators) and other national standard setters.
The ISSB Exposure Drafts
11The ISSB currently consists of a Chair and Vice Chair and recruitment for the other Board members is currently underway. The IFRS Foundation Trustees granted special powers to the ISSB Chair and Vice Chair to enable the publication of the EDs before the ISSB Board was quorate. Their aim was to balance the need to advance the urgent work of the ISSB with the requirement to obtain stakeholder views. The Trustees noted that this was a transitional measure and provided for under the IFRS Foundation's Constitution, published in November 2021.
12In March 2022, the International Sustainability Standards Board (ISSB) issued two Exposure Drafts (“EDs”), IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information” (“IFRS S1”)7 and IFRS S2 Climate Related Disclosures ("IFRS S2")8. These are the first EDs published by the ISSB.
13The EDs are based on the prototypes developed by the IFRS Foundation's Technical Readiness Working Group9 (TRWG). Those prototypes were developed with reference to the IASB frameworks and standards, recommendations from the Task Force on Climate-Related Financial Disclosures (TCFD) and incorporated the industry-based standards of the Sustainability Accounting Standards Board (SASB)10. The prototypes were released publicly at the COP 2611 conference in November 2021.
14The comment period has been set for 120 days, concluding on 29 July 2022. The ISSB will then review the feedback in the second half of 2022 and intends to issue the final standards by the end of the year. The EDs will be redeliberated once the Board has recruited six additional members12. The IFRS Foundation's Due Process Oversight Committee was consulted on the approach13 and raised no objections.
15IFRS S1 sets out the proposed general reporting requirements for the disclosure of sustainability-related financial information14. The information is intended to enable primary users of the entity's general purpose financial reporting to assess the entity's enterprise value to determine whether to provide resources to it. The ED has been adapted from IAS 1 Presentation of Financial Statements15 and is intended to perform a similar function for ISSB Standards. That is, IFRS S1 requirements are not limited to climate-related matters and are intended to provide a framework for all future ISSB issued Standards.
16IFRS S2 is a thematic disclosure standard and sets out the proposed requirements for identifying, measuring and disclosing climate-related risks and opportunities16. The proposed requirements are designed to enable users of general-purpose financial reporting to assess an entity's exposure to, and management of, climate-related risks and opportunities, across markets, to facilitate capital allocation and stewardship decisions.
17The ISSB Basis for Conclusions for IFRS S217 notes that IFRS Accounting and Sustainability Standards are intended to be complementary. It also notes that the ED does not 'negate requirements to consider the effects of climate, when material, in applying IFRS Accounting Standards18' and specifies that the application of the ED is not a substitute for applying the requirements of IFRS Accounting Standards.
18It is intended that the standards will apply prospectively, and that entities will have relief from disclosing comparatives in the first year of application. An effective date will be set when the standards are finalised.
The UKEB project and identification of potential issues
19The UKEB project is currently expected to include desk-based analysis and stakeholder consultation to develop comment letters on both19 ISSB EDs, to the extent that they overlap with IASB issued standards. A single project will cover both EDs due to their close alignment and the UKEB project scope.
20The global lack of experience and knowledge means that there are no pre-existing sources of information in this area. Other jurisdictions are also starting similar projects, which removes another potential consultation source. This adds to the extensive number of domestic and international uncertainties in this area.
21As mentioned above, in the UK, there is a developed framework for ESG reporting which allows reporting under existing voluntary frameworks. The disclosures made by companies in their annual reports have increased and improved since ESG reporting was mandated for UK quoted companies, in 2013. As many other jurisdictions do not currently require any type of ESG disclosures, UK entities are well placed to provide examples of 'best practice' that can be shared internationally. However, this is not straightforward and time is required to enable appropriate review of annual reports and field-testing of the proposed standards.
22Internationally, it is a varied picture. Whilst many jurisdictions do not require ESG disclosures, multi-nationals which operate across jurisdictions do report on these issues. However, the consistency of application varies.
23The initial stage of the project will involve the following desk-based research:
- A high level ‘top down' review of the standards' principles and concepts followed by a detailed 'bottom up' review comparing between the ISSB EDs and relevant IASB standards;
- A review of the structures of the EDs in comparison with IASB standards to ensure any differences are easily identifiable;
- Comparison and consideration of overlap between the EDs and the disclosure requirements in IASB issued standards; and
- As part of our review of annual reports to identify reporting on ESG matters in financial statements, be alive to any current sustainability reporting ‘best practice' examples by UK companies. These examples could be shared with the ISSB to illustrate the highest level of current expertise and knowledge in the UK.
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information
Interaction with IASB Standards
24We note that the Basis for Conclusions for IFRS S1 states20 that sustainability-related financial information disclosure requirements are intended to complement the information currently disclosed in general purpose financial reporting. The objective is that all information disclosed is prepared consistently, where appropriate, and can be connected in general purpose financial reports. The ISSB has applied the qualitative characteristics in the IASB Conceptual Framework to aid consistency21.
25The ED has been based on IASB's Conceptual Framework for Financial Reporting, IAS 1 Presentation of Financial Statements, IAS 8 Accounting Polices, Changes in Accounting Estimates and Errors and with reference to IFRS Practice Statement 2 Making Materiality Judgements, where applicable. From an initial review, the requirements and definitions used appear to be consistent with those standards and guidance.
26The Basis for Conclusions also notes22 that 'the requirements and guidance from IAS 1 and IAS 8 have been changed only to refer to sustainability-related financial disclosures, with two exceptions – location of information, and special application of sources of estimation and outcome uncertainty and errors.
27In relation to the location of information, an entity would be required to report sustainability-related financial disclosures at the same time as it publishes its related financial statements. While this is not an overlap with IASB Standards, it may present an operational and cultural change for financial reporting and ESG teams as their information would need to be integrated and connected for reporting purposes. This would require the alignment of sustainability and accounting data, systems, process, and controls within the financial reporting teams working day timetable.
28In relation to corrections, errors would be corrected by restating the comparative amounts for the prior period. Under IAS 8 changes in estimates are recognised prospectively i.e. in the period of change. The ISSB notes23 that some sustainability metrics will require a significant level of estimation and that, as they are not part of the double entry accounting model, restatement would not impact the financial statements.
29The proposals are also intended to act as a global baseline, that are interoperable with the range of jurisdictional laws and regulations, while meeting the needs of capital markets24. In addition, an entity could apply IFRS Sustainability Disclosure Standards whether their financial statements are prepared using IFRS or another accounting framework i.e. local GAAP. However, UK and other national legislation will determine whether this will be acceptable to global jurisdictions..
30From an initial review of IFRS S1, variations from current IASB standards do not appear to be significant but, those that exist may cause operational challenges for financial reporting teams. We will seek further feedback on any overlaps through outreach on IFRS S1 with UK stakeholders.
Structure of Standard
31The Core Content25 of the standard proposes that disclosure is provided about relevant governance, strategy, risk management and metrics/targets. The standard then describes what is required to meet each of these requirements. We expect an entity's governance and organisational strategy for sustainability would address both the financial and non-financial aspects of sustainability. If so, it may be better to provide requirements for governance and strategy in a separate, over-arching, standard that addresses sustainability disclosure for both financial and non-financial information. Otherwise, these requirements will need to be duplicated (and maintained) in standards addressing the disclosure of non-financial information, in addition to these proposals for the disclosure of financial information in IFRS S1.
32The standard does not define “sustainability”26. Instead, it refers to information “useful to users...assessment of enterprise value27”including forward looking information and suggests that sustainability risks and opportunities arise from dependencies/impacts on resources28. A number of suggestions29 are then made as to matters to consider in sustainability disclosures including consideration of industry based standards, pronouncements of other standard setting bodies and disclosures made by other relevant entities. While we understand the need for a broad definition which is flexible for future events, the absence of definition risks activity unrelated to sustainability being subject to the ISSB disclosure regime, and increases the risk of overlap with existing IASB standards.
33The above points need to be analysed further as desk based research continues and stakeholder outreach commences.
IFRS S2 Climate Related Disclosures
34We note that IASB standards do not explicitly refer to climate-related risks and opportunities. However, entities are required to consider climate-related risks when applying IFRS if their effect is 'material in the context of the financial statements taken as a whole30.
35The IFRS S2 Basis for Conclusions31 notes that the ED requirements are 'consistent with and complement those in [draft] IFRS S1. These include the core content areas, conceptual elements, and general features e.g. materiality, reporting entity, connected information and the location of information.
36The standard is structured around the TCFD four core elements of governance, strategy, risk management, and metrics and targets. A potential area of overlap with IFRS may be the strategy and decision-making disclosure requirements.
37The Strategy and decision-making section32 require the disclosure of anticipated future effects of significant climate-related risks and opportunities that could impact an entity's business model and strategy. The requirements include disclosure of current and anticipated effects ‘on the entity's financial position, financial performance and cash flows for the reporting period, and the anticipated effects over the short, medium, and long term.' This also includes reflecting how these risks and opportunities are included in the entity's financial plans. This appears to complement the going concern assumption in IAS 1 where management are required to consider all relevant information for at least 12 months post balance sheet date.
38From an initial review of IFRS S2, variations from current IASB standards do not appear to be significant. However, we will seek further feedback on any overlaps through outreach on IFRS S2 with UK stakeholders.
Economic assessment
39To support the response to the ISSB, and to help explain the potential economic impacts on UK stakeholders, the economics team will produce an estimate of:
- the prevalence of climate/ESG reporting among UK listed companies, i.e., how many UK listed companies are already reporting some form of sustainability/climate disclosures, which frameworks are used (TCFD, SASB, GRI, other) and whether there are industry differences. This exercise will involve Reuters/Eikon, engagement with the London Stock Exchange for additional data/information, and a review of companies' 2019 annual reports.
- how many UK listed companies have listed subsidiaries in the EU and USA that already use or may be in scope of proposed sustainability/climate standards or frameworks33.
- an assessment, via outreach, of any potential one-off and/or ongoing costs and benefits from any overlaps with IFRS.
Outreach
40The desk-based research will determine the scope of the outreach and form the basis of supporting materials provided to stakeholders.
UK stakeholders
41Given the likely widespread impact of these proposals, the Secretariat would like to hear from a range of preparers of financials statements as well as users of those financial statements, to understand the extent of any overlap and the potential impacts.
42Based upon the scope determined above, we propose to:
- Conduct interviews with users and preparers of financial statements to explore how they think the reporting will work in practice, whether the disclosures will be useful and comparable, and to identify any areas of concern or difficulty.
- Issue the Draft Comment Letter for public consultation.
- Host and broadcast a joint half day event, such as a webinar, in late June, to help stakeholders understand the disclosure requirements and areas of overlap with IASB Standards. The event would involve a panel discussion and be interactive with Q&A from the attendees. The panel could feature representatives from the ISSB and IASB, alongside UK preparers, users and regulators. It could include UKEB Board Members and speakers from BEIS to highlight the UK reporting landscape, any likely changes to it and the UKEB's work in this area.
- Engage with preparers and users to identify examples of ‘best-practice' reporting in this area, which could be shared with the ISSB.
- Conduct field-testing to identify any unintended consequences of, or difficulties with, reporting under the proposed standards. Such testing will also help to clarify the system changes preparers may require and what the costs of introducing reporting under ISSB issued standards may be. This is, however, unlikely to be possible within the current 120 day consultation period.
- Work in coordination with government bodies and regulators to ensure feedback takes the issues and concerns of all UK stakeholders into account.
43The proposed outreach events have not been set up yet. The organisations in question may have multiple demands on their time from other UK bodies seeking feedback on the various aspects of these proposals. Therefore, we request the assistance of Board Members in encouraging stakeholder involvement in outreach events, particularly in the user community.
International stakeholders
44We are in contact with both the IASB and ISSB project teams and are having preliminary discussions about a joint event, such as the proposed webinar.
45During the project we will reach out to staff at other national standard setters. This will allow us to understand the views of other jurisdictions on the requirements proposed in the EDs and whether there are any areas of concern in common with the UK.
Planning Assumptions
46We have made the following assumptions in developing the project plan:
- There will be significant to moderate overlap between the ISSB EDs and IFRS. The IFRS Foundation has developed the ISSB EDs with the intention of achieving consistency and comparability between accounting and sustainability standards but, as discussed, this is a complex and evolving landscape.
- We will need to be cognisant of any forthcoming legislative changes, due to the implications for ISSB and IASB issued standards, and the UK company reporting landscape in which they operate.
- Work will need to be carried out to determine areas of overlap, fully assess the EDs, support stakeholders understanding of the requirements, obtain relevant stakeholder feedback, and reflect the findings in the final comment letter. This work all needs to be carried out within a condensed timeframe to ensure the UKEB provides its response to the ISSB on a timely basis.
- We therefore estimate that at least 2 Project Directors and a Project Associate will be required over the duration of the project.
- We have currently set the scope of this project as significant. We expect to revise the scope and workplan in this PIP as more clarity develops in these areas. Material changes will result in a revised Project Initiation Plan (PIP) being submitted to the board for approval.
Constraints
47As other jurisdictions have also published sustainability standards and are seeking feedback in parallel with the ISSB, stakeholders may have very limited availability to engage.
48Stakeholders may also require a significant level of education on the EDs before they can comment. Due to the short consultation timeframe they may be unable to provide comprehensive responses which would impact the quality of the UK feedback to the ISSB34.
49The uncertainty around proposals regarding the adoption of ISSB issued standards for use in the UK could make it difficult for stakeholders to be able to respond confidently and constructively.
Project closure
50It is intended that a Feedback Statement and Due Process Compliance Statement will be presented at the July UKEB Board meeting, with the Final Comment Letter.
Key Milestones
51The proposed high-level project timeline
| Date | Milestones |
|---|---|
| 21 April 2022 | Approval of Project Initiation Plan (PIP) |
| Board meeting | |
| May / June 2022 | Stakeholder outreach and webinar |
| 19 May 2022 | Approval of Draft Comment Letter(s) |
| Board meeting | |
| 18 July 2022 | Approval of Final Comment Letter(s), Feedback Statement and draft Due Process Compliance Statement. |
| Board meeting | |
| 22 July 2022 | Submission of Final Comment Letter(s) to the ISSB |
| 23 September | Due Process Compliance Statement for noting. |
| Board meeting |
Project Plan
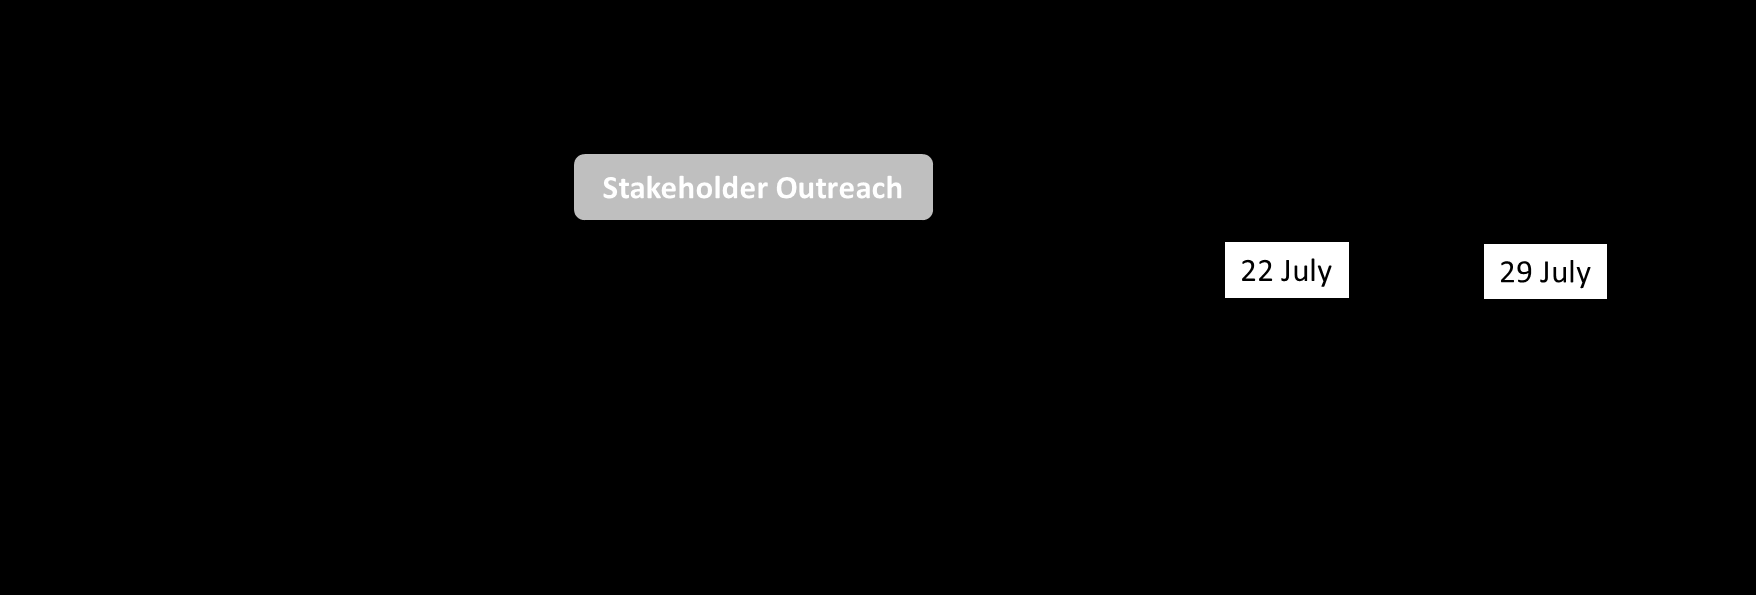
This diagram illustrates the project plan timeline, showing key activities and their sequencing:
Phases: * Project Initiation Plan (PIP) Approval * Update on progress (Technical Update) * Final Comment Letter(s) Submission to ISSB
Timeline with UKEB Meetings: * 21 April: UKEB meetings * 19 May: UKEB meetings, Draft Comment Letter(s) * 23 June: UKEB webinar * 18 July: UKEB meetings, Final Comment letter(s), Draft Feedback Statement, Draft Due Process Compliance Statement * 22 July: UKEB meetings * 29 July: ISSB Comment Letter deadline
The "Stakeholder Outreach" activity spans from around mid-May to early July, encompassing the UKEB webinar.
Footnotes
-
IFRS Foundation announces formation of new Sustainability Standards Board ↩
-
PROJECT TASK FORCE ON EUROPEAN SUSTAINABILITY REPORTING STANDARDS (PTF-ESRS) ↩
-
SEC The Enhancement and Standardization of Climate-Related Disclosures for Investors ↩
-
The International Accounting Standards and European Public Limited-Liability Company (Amendment etc.) (EU Exit) Regulations 2019 (2019/685) ↩
-
UKEB 2022-2023 Regulatory Strategy - '#26 IFRS and International Sustainability Standards Board's (ISSB) standards - overlap' ↩
-
Terms of Reference para 3.1 (a) Roles and Responsibilities 'Influencing the development of IFRS, including, but not limited to, following, and contributing to debates on the IASB's projects, having oversight of consultations with UK stakeholders to obtain their views, and highlighting concerns to the IASB, as and when appropriate, including the development of the IASB's agenda and post-implementation reviews ↩
-
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information ↩
-
IFRS S2 Climate Related Disclosures ↩
-
IFRS Foundation Technical Readiness Working Group ↩
-
According to IFAC The State of Play in Sustainability Assurance (June 2021) of the UK entities surveyed approximately 40% under made sustainability disclosures under TCFD, 35% under GRI Standards, 15% under SASB Standards. ↩
-
IFRS Foundation announces ISSB and publication of prototype disclosure requirements ↩
-
The ISSB has advised that these six appointments are expected by the end of Q2, 2022 and a further six appointments are expected by the end of Q3, 2022. ↩
-
IFRS Foundation Due Process Oversight Committee Summary of meeting held on 21 March 2022 ↩
-
ISSB note that these proposals are in response to demand from users of general-purpose financial reporting for more consistent, complete, comparable, and verifiable sustainability-related financial information, to help them assess an entity's enterprise value. Enterprise value reflects expectations of the amount, timing, and certainty of future cash flows over the short, medium, and long term and the value of those cash flows in the light of the entity's risk profile, and its access to finance and cost of capital. The proposals require an entity to disclose material information about all significant sustainability-related risks and opportunities to which it is exposed ↩
-
Basis for Conclusions IFRS S1 para BC18, page 8 ↩
-
The ISSB note that an entity's relationship with the environment has become increasingly important. Climate change presents significant risks for all entities, their activities, and their economic sectors. The proposals in the exposure draft are intended to facilitate the provision of comparable information on this topic for global capital markets. ↩
-
Basis for Conclusions IFRS 2 para BC195, page 58 ↩
-
Basis for Conclusions IFRS 2 para BC196, page 58 ↩
-
If it is determined that there is limited overlap with the IFRS S2, a single letter will be submitted the ISSB on IFRS S1, incorporating any relevant areas from IFRS S2. ↩
-
Basis for Conclusions IFRS S1 para BC14, page 7 ↩
-
Basis for Conclusions IFRS S1 para BC60, page 19. Qualitative characteristics of useful sustainability-related financial information have also been provided in Appendix C of the Exposure Draft for guidance. ↩
-
Basis for Conclusions IFRS S1 para BC48, page 14 ↩
-
Basis for Conclusions IFRS S1 para BC82, page 24 ↩
-
This has been designed through a 'building block' approach where IASB standards are the base block and the ISSB standards are added to create a global baseline to meet the needs of primary users of general-purpose financial reporting. Local public policy requirements, or other sustainability frameworks, can then be added to this baseline to meet the needs of wider stakeholders. ↩
-
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information paragraph 11 ↩
-
The Basis for Conclusions IFRS S1 B30 notes that the concept of sustainability is frequently linked to sustainable development and notes the UN definitions including climate change, biodiversity etc. However it does not adopt this as a definition for this standard nor reflect the UN wording in the body of the standard or defined terms. ↩
-
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information Appendix A ↩
-
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information paragraph 17 ↩
-
IFRS S1 General Requirements for Disclosure of Sustainability-related Financial Information paragraph 51 ↩
-
IFRS Foundation 'Effects of climate-related matters on financial statements' - November 2020 ↩
-
Basis for Conclusions IFRS 2 para BC17, page 9 ↩
-
IFRS S2 paragraph 14, page 36 ↩
-
This will be dependent on the availability of a reliable source of complete data. ↩
-
The UKEB recommended the ISSB consider a 6-9-month consultation period to allow for a more comprehensive consideration and field testing of the proposals. ↩