Project Initiation Plan - Non-Current Liabilities with Covenants (Proposed Amendments to IAS 1)
Project Type: Influencing Project Scope: Limited (Narrow Scope Amendment)
Background
1SI/2019/685(5)(b) requires the UKEB to be responsible for “participating in and contributing to the development of a single set of international accounting standards.” The proposed project contributes to this work.
2In January 2020, the International Accounting Standards Board (IASB) issued an amendment to IAS 1 Presentation of Financial Statements (IAS 1) on Classification of Liabilities as Current or Non-current (2020 amendments). It was aimed at clarifying how to classify debt and other financial liabilities as current or non-current in particular circumstances.
3In 2021, stakeholder concerns led to consideration by the IFRS Interpretations Committee (IFRIC) of the application of the 2020 amendments. Specifically, this was centred on classification when a company's right to defer settlement is subject to compliance with covenants within 12 months of the reporting date and the company is not compliant with such covenants at the reporting date. This led to an IFRIC tentative agenda decision (TAD) which stated that as the company would not have a right to defer settlement of the liability and it would present the related liability as a current liability in its balance sheet. Respondents to the TAD were critical of the conclusion and highlighted unintended consequences arising from the 2020 amendment and the TAD which had not been considered when developing the amendments.
4The IASB's response was a tentative decision to amend IAS 1 with respect to classification (as current or non-current), presentation and disclosures of liabilities where an entity's right to defer settlement for at least 12 months is subject to the entity complying with conditions after the reporting period. This was subsequently published as IASB Exposure Draft (ED) Non-current Liabilities with Covenants in November 2021 with a comment deadline of 21 March 2022.
5In the ED, the IASB proposes to amend IAS 1 to specify that “specific conditions”, with which a company must comply after the reporting date, do not affect the classification of a liability as current or non-current at that date. Instead, a company would be required to:
- present non-current liabilities with covenants separately on the face of its balance sheet; and
- disclose information in the notes about the covenants with which it must comply within 12 months of the reporting date.
6Two IASB Board Members have provided an “alternative view” to the ED. Specifically they disagree with the proposal to require an entity to present separately, in its statement of financial position, non-current liabilities subject to such conditions. They also disagree with some of the additional note disclosures proposed in the ED.
Initial identification of issues
7Our initial desk-based review of the standard and feedback from stakeholder discussions have identified a number of concerns with the proposals. We believe that the exposure draft, though narrow in scope, could have a significant impact on financial reporting in the UK. We also spoke with the IASB project team to ensure that our concerns did not arise from any misunderstanding of the requirements of the proposals.
8We have also undertaken some preliminary outreach, having spoken informally to representatives of a number of accounting firms, all of whom appear to reinforce our initial views on the IASB proposals. These are outlined in our Draft Comment Letter (see Appendix 2 of this paper).
9We have discussed the EFRAG draft response with their project team. Their letter raises similar concerns to our own.
Key planning assumptions, constraints and timeline
Comment deadline and resource capacity
10As noted, the IASB's ED was published in November 2021, with a 21 March 2022 comment deadline.
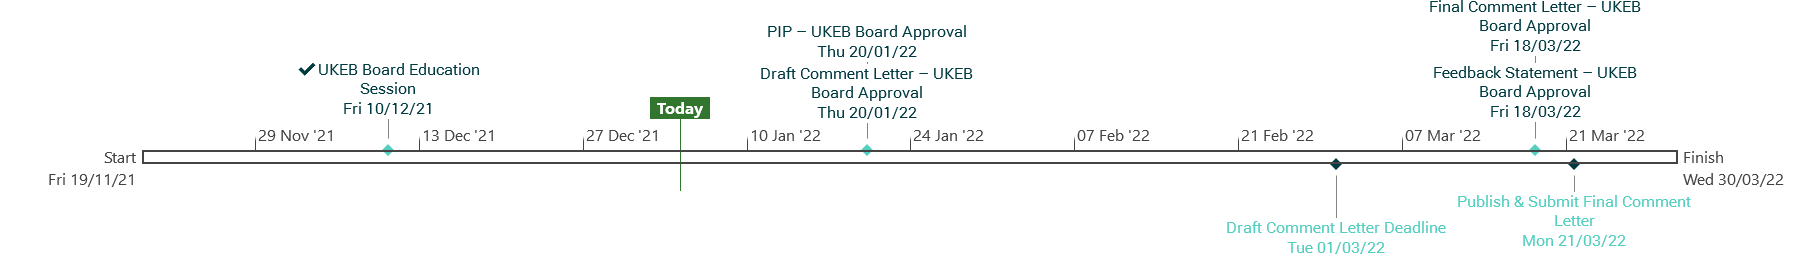
11Given the short deadline, we have included a Draft Comment Letter for Board consideration at this meeting. Subject to Board approval, we plan to publish the draft comment letter in the week following the Board meeting and it will be open for stakeholder comment until about 1 March 2022, ensuring that the comment period is no shorter than 28 days.
12The Final Comment Letter will be circulated to the Board for the 18 March Board Meeting, followed by submission to the IASB on 21 March, subject to Board approval.
13As outlined below we believe that time should be invested in undertaking active outreach with potentially affected stakeholders, including prepares and users. We estimate that 20% of a Project Director's time will be required to obtain the stakeholder feedback and reflect it in the final comment letter.
Assumptions
14We have made the following assumptions in developing this project plan:
- the impact of the amendments is expected to be widespread.
- It is likely that many stakeholders have not identified the impact of these changes, and given the short timeline, which has run over the Christmas holiday period, it is probable they have not fully engaged with the proposals.
- We would invest some time into raising awareness and actively reaching out to stakeholders to solicit feedback on the Draft Comment Letter.
Outreach
15Staff believe that given this is a narrow scope amendment, albeit with the potential for significant impact on the financial statements, a proportionate response is to raise general awareness of the IASB proposals and our Draft Comment Letter as well as undertaking additional targeted outreach with potentially affected stakeholders, including preparers and users.
UK stakeholders
16We have already reached out to a number of accounting firms and have either spoken to, or expect to speak with, most in the coming weeks.
17We have also reached out to potentially affected stakeholders, including preparers and users, who we believe could have an interest in this topic.
18We believe that the publication of the draft comment letter will provide an opportunity to raise specific concerns with stakeholders directly.
International stakeholders
19As noted, we are already in touch with the IASB's project team but we do not propose any joint outreach as it would be disproportionate to the size of the amendment itself.
20Also as noted, we are already discussing this issue with the EFRAG's project team and plan to continue sharing views.
21Once the Draft Comment Letter is published, we will reach out to staff of the Accounting Standards Board of Canada (AcSB), Australian Accounting Standards Board (AASB), and Malaysian Accounting Standards Board (MASB). This will allow us to understand their view of the requirements proposed in the ED and whether there are overlaps with issues we identify for UK entities.
Project closure
22It is intended that the Feedback Statement and Due Process Compliance Statement will be provided to the UKEB at the same meeting as the Final Comment Letter.
Project timeline
23The proposed high-level project timeline is as follows:
| Date | Milestones |
|---|---|
| 21 Jan Board meeting | Approve PIP and draft comment letter |
| 25 Jan | Publish draft comment letter |
| 1 March | Deadline for responses to draft comment letter (more than 28 Days from publishing) |
| 11 March for / 18 March Board meeting | Circulate Final Comment Letter, Feedback Statement and Due Process Compliance Statement for Board Approval (at 18 March meeting) |
| 21 March | Submit Final Comment Letter to IASB |